
- Home
- »
- Electronic & Electrical
- »
-
Tankless Water Heater Market Size Report, 2026-2033GVR Report cover

Tankless Water Heater Market (2026 - 2033)
Size, Share & Trends Analysis Report By Product (Electric, Gas), By Application (Residential, Commercial), By Region (North America, Europe, APAC, Latin America, MEA), And Segment Forecasts
Market Size, 2025
$4.3BMarket Estimate, 2026
$4.7BMarket Forecast, 2033
$9.4BCAGR, 2026–2033
10.4%Tankless Water Heater Market Summary
The global tankless water heater market size was valued at USD 4.3 billion in 2025 and is projected to grow from USD 4.7 billion in 2026 to USD 9.4 billion by 2033, growing at a CAGR of 10.4% from 2026 to 2033. Europe dominated the market with the largest revenue share of 33.3% in 2025. The tankless water heater market is primarily driven by the rising demand for energy-efficient, on-demand hot water systems that reduce utility costs.
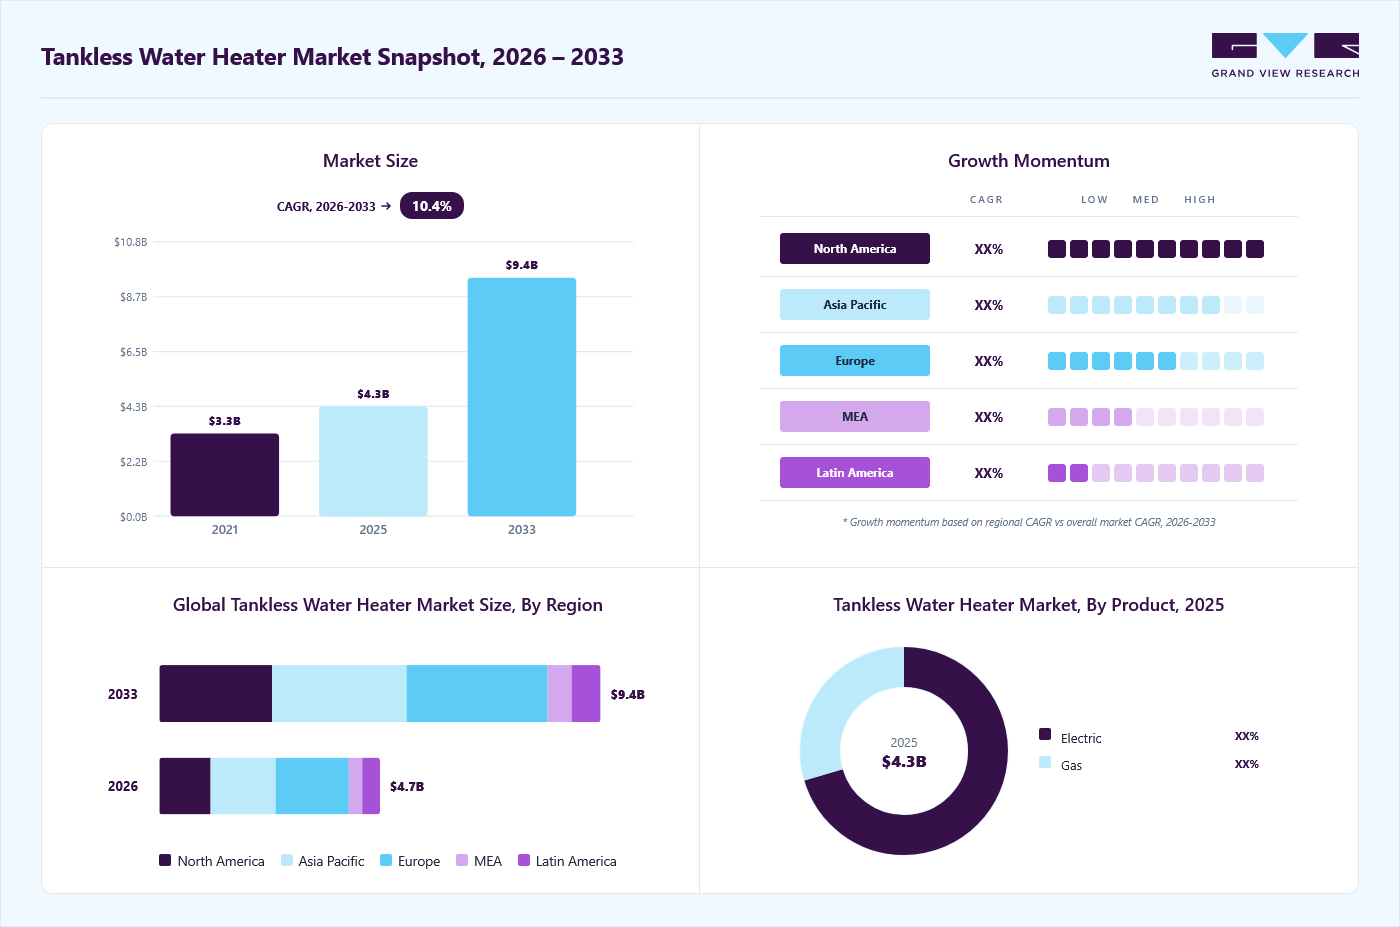 Source: Grand View Research, IR Documents, Primary Interviews, Paid DatabasesTo learn more about this report,
 Download Free Sample Report
Key Market Trends & Insights
- By product: Electric tankless heaters held the largest revenue share of 70.5% in 2025.
- By application: Residential segment dominated the market, with a revenue share of 73.5% in 2025.
Regional Highlights
- Largest regional market: Europe (33.3% revenue share, 2025)
- Fastest-growing regional market: North America (highest CAGR, 2026-2033)
- By country: The U.S. held the largest market share in 2025.
Market Size & Forecast
- Market size in 2025: USD 4.3 Billion
- Estimated market size in 2026: USD 4.7 Billion
- Projected market size by 2033: USD 9.4 Billion
- CAGR (2026-2033): 10.4%
Three ways to get this report
Buy it, customize it, or ask a question.Ask an Analyst
Analyst response in 1 business day
- AccessReport author, directly
- Reply timeWithin 1 working day
- No sales callDirect answer only
- FormatEmail reply
- CostFree, no cost
Get the Full Report
What the study covers
- FormatsPDF · Excel · Dashboard
- Timeline2026–2033 annual, 2025 base
- Coverage20+ countries, 5 regions
- Companies10+ key players profiled
Customize the Report
20% free customization
- IncludeCountries, segments, points
- TailorTo your product definition
- ExtendDeeper competitor detail
- OrA fully bespoke study
- Turnaround5–10 working days
The tankless water heater market is primarily driven by advancements in heating technologies that offer improved performance and longevity. Growing environmental awareness is pushing consumers toward eco-friendly alternatives to traditional water heaters. Government incentives and rebates for energy-efficient appliances are also encouraging adoption. Moreover, the compact design of tankless systems makes them ideal for urban housing with limited space.The increasing preference for smart home integration and remote-control features primarily drives the tankless water heater market. Rising disposable incomes and changing lifestyles are leading consumers to invest in premium home appliances. The hospitality industry's demand for continuous hot water supply is also fueling market growth. Furthermore, the need to replace aging traditional water heaters is accelerating the shift toward tankless alternatives.
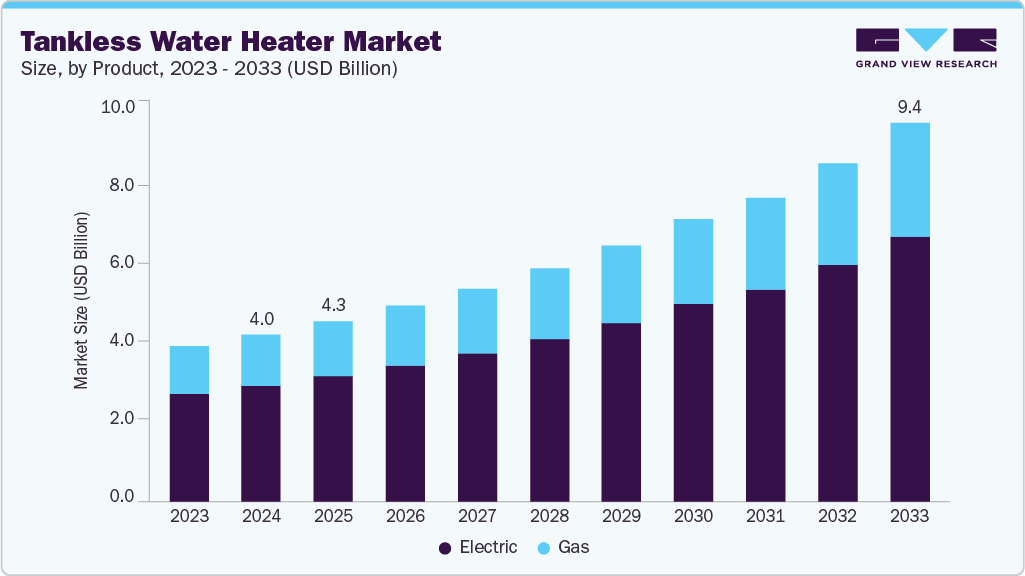 To learn more about this report, Download Free Sample Report
The tankless water heater market is primarily driven by growing awareness of water conservation and the need for sustainable living solutions. Rapid urbanization and the expansion of residential infrastructure in developing economies are creating new market opportunities. Technological innovations enabling faster heating and better temperature control are attracting tech-savvy consumers. In addition, rising energy costs are pushing both households and businesses to seek more cost-effective water heating options.
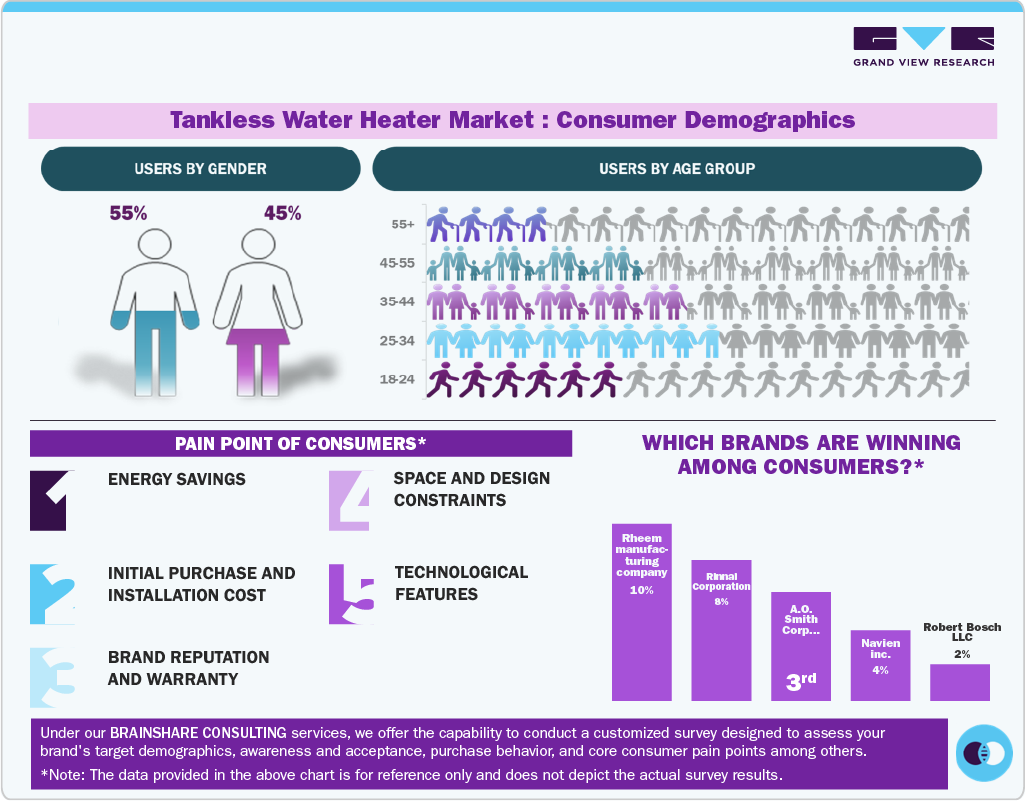 To learn more about this report, Download Free Sample Report
Market Dynamics
The tankless water heater market is driven by rising demand for energy-efficient, compact, and on-demand water heating solutions across residential, commercial, and hospitality sectors. These systems eliminate standby heat loss associated with storage water heaters, thereby improving energy efficiency and reducing long-term operating costs. Rapid urbanization, increasing construction of space-constrained housing units, and growing renovation activities are further accelerating product adoption. Additionally, stringent energy efficiency regulations, decarbonization targets, and government incentives promoting low-emission appliances are encouraging the replacement of conventional heating systems. Technological advancements such as smart temperature controls, digital monitoring systems, and integration with smart home ecosystems are further enhancing product performance and consumer adoption globally.
The increasing focus on energy conservation and operational cost reduction is significantly driving demand for tankless water heaters. Traditional storage water heating systems consume higher energy due to continuous reheating of stored water, whereas tankless systems provide hot water instantly, eliminating standby energy losses. Rising electricity and fuel prices across major economies are further pushing consumers and commercial users toward efficient alternatives. Additionally, rapid urbanization and the expansion of high-density residential infrastructure, particularly in emerging economies, are increasing demand for compact heating solutions that optimize space utilization. The growing shift toward sustainable building practices and green certification standards in residential and commercial construction is further strengthening the adoption of tankless water heating technologies.
Despite strong efficiency benefits, the tankless water heater market is restrained by high initial purchase and installation costs compared to conventional storage systems. Installation often requires modifications to existing gas lines, electrical infrastructure, or ventilation systems, which increases overall system cost and limits retrofit adoption. In developing and price-sensitive markets, consumers continue to prefer traditional water heaters due to lower upfront investment, despite higher long-term energy savings. Additionally, lack of skilled installation professionals and limited awareness in rural and semi-urban regions further hinder market penetration. These challenges collectively slow down adoption, particularly in cost-sensitive residential segments.
The increasing adoption of smart home technologies and IoT-enabled appliances presents significant growth opportunities for the tankless water heater market. Manufacturers are increasingly focusing on connected water heating systems that allow users to control temperature settings, track energy consumption, and optimize usage through mobile applications. The integration of artificial intelligence and predictive maintenance capabilities is further enhancing system efficiency and reducing operational downtime. Rising consumer preference for automated, energy-efficient, and environmentally sustainable home solutions is expected to accelerate demand for advanced tankless systems. Furthermore, the expansion of green buildings and net-zero energy housing initiatives globally is creating a favorable environment for the adoption of intelligent and low-emission water heating technologies.
Analyst Perspective
The tankless water heater market sits at the intersection of structural drivers few home appliance categories match rising urban density, accelerating electrification of heating systems, and strong regulatory push toward energy efficiency. The core competitive advantage will lie with players that integrate high-efficiency, smart-enabled systems with seamless retrofit compatibility across diverse infrastructure conditions, converting a traditionally replacement-driven category into a continuous upgrade cycle supported by sustainability mandates and long-term cost savings.
Product Insights: Electric tankless water heaters dominated the market, supported by electrification trends, while gas models gained momentum with demand for high-efficiency heating
Based on product, the electric segment led the market with the largest revenue share of 70.5% in 2025 and is expected to grow at the fastest CAGR over the forecast period. The electric tankless water heater market is driven by factors such as the increasing shift toward cleaner energy sources and the phasing out of gas-based systems in many regions. Rising electricity access in remote and developing areas is expanding the customer base for electric models. Consumers are also drawn to their lower installation costs and minimal maintenance compared to gas units. Supportive government policies promoting electrification and energy efficiency are further accelerating adoption. In addition, advancements in smart thermostats and digital controls enhance user convenience, fueling market growth. Companies such as Bosch and A. O. Smith offer electric tankless water heaters for commercial & residential use.
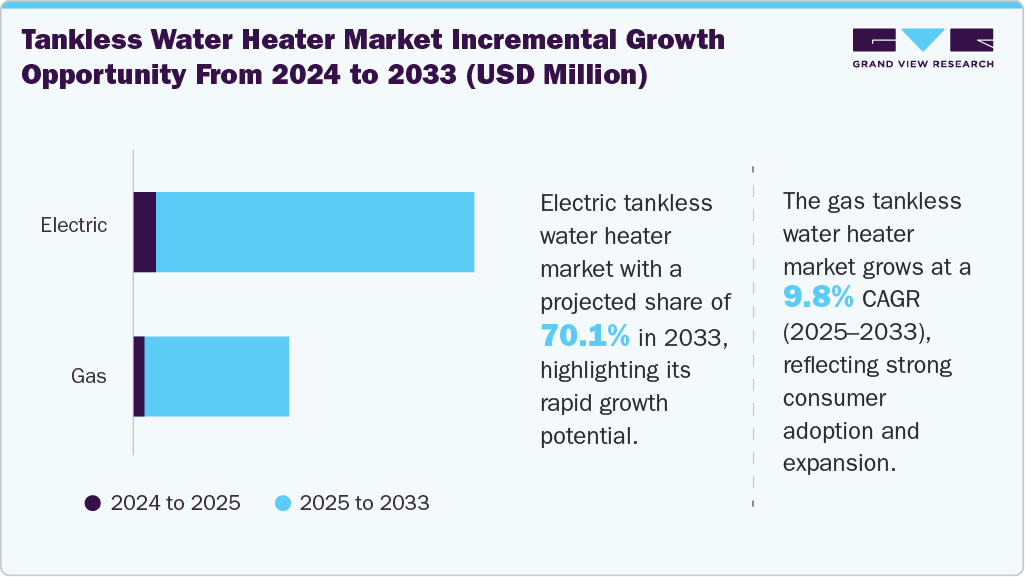 To learn more about this report, Download Free Sample Report
The gas tankless water heater market is projected to grow at the fastest CAGR of 9.9% from 2026 to 2033. The gas tankless water heater market is driven by high heating efficiency and faster water flow rates that appeal to larger households and commercial users. In regions with low natural gas prices, these systems offer a cost-effective alternative to electric models. The durability and long lifespan of gas units also make them a preferred choice for long-term investments. Growing infrastructure development in colder climates, where high-capacity heating is essential, supports demand. Moreover, innovations in low-NOx and condensing technologies are making gas models more environmentally friendly and compliant with stricter emission regulations.
Application Insights: Residential applications lead market demand as commercial adoption accelerates
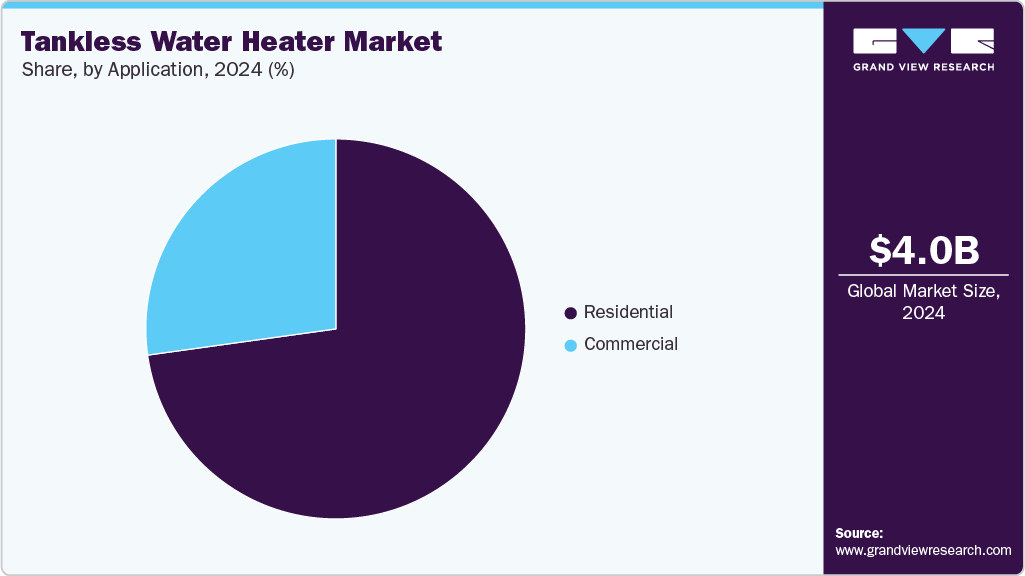
Based on application insights, the residential segment led the market with the largest revenue share of 73.5% in 2025. The residential application of the tankless water heater market is driven by the growing trend toward space-saving appliances in modern homes and apartments. Homeowners increasingly value the continuous supply of hot water for simultaneous use in multiple bathrooms and kitchens. Rising awareness of long-term cost savings on energy bills is influencing purchasing decisions. The increasing popularity of home improvement and remodeling projects also boosts demand for upgraded water heating systems. In addition, aesthetic preferences for sleek, wall-mounted designs contribute to their appeal in contemporary residential settings.
 To learn more about this report, Download Free Sample Report
The residential market of tankless water heaters is projected to grow at a significant CAGR of 10.5% from 2026 to 2033. The commercial application of the tankless water heater market is driven by the need for reliable, high-volume hot water in sectors such as hospitality, healthcare, and food service. Businesses prioritize systems that reduce downtime and ensure consistent performance during peak usage. The scalability of tankless systems allows for customized solutions based on specific operational demands. Increasing regulations on energy efficiency in commercial buildings are also encouraging the shift from traditional heaters. Furthermore, the focus on reducing operational costs and carbon footprints supports wider adoption in commercial settings.
Regional Insights
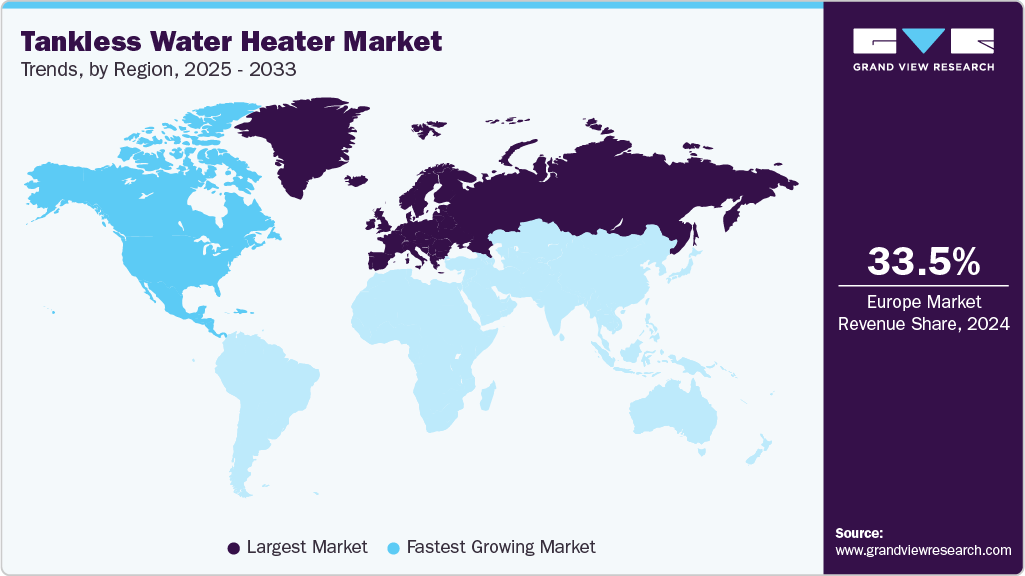
North America accounted for the market share of 22.9% in 2025. In North America, rising investments in smart grid infrastructure and energy management systems are supporting the adoption of tankless water heaters. Consumers are increasingly attracted to app-controlled and Wi-Fi-enabled models that offer real-time usage monitoring. The aging housing stock presents a large retrofit market for efficient water heating solutions. Environmental certifications and eco-labeling influence consumer preferences across the region. Moreover, the shift toward electrification in line with decarbonization goals is pushing manufacturers to innovate.
U.S. Tankless Water Heater Market Trends
The U.S. led the North American tankless water heater market in 2025, holding the largest market share with 78.3% of the region’s total revenue. In the U.S., aggressive marketing by utility companies and manufacturers is raising awareness about the benefits of tankless systems. Regional building codes are gradually incorporating efficiency standards that favor tankless technologies. Tax incentives and utility rebates in several states are significantly boosting consumer adoption. A growing DIY culture also makes compact, easy-to-install systems more appealing. In addition, high demand for hot water in large suburban homes creates a strong market for high-capacity models.
Europe Tankless Water Heater Market Trends
Europe dominated the tankless water heater market with the largest revenue share of 33.3% in 2025. In Europe, the tankless water heater market is driven by stringent EU directives focused on emissions reduction and energy conservation. The popularity of decentralized heating systems in multi-family housing supports localized tankless solutions. Cultural emphasis on sustainable living is increasing demand for low-consumption appliances. Renovation of old buildings under green initiatives is accelerating the replacement of traditional boilers. In addition, rising electricity costs across many EU nations are prompting a shift toward more efficient water heating options.
 To learn more about this report, Download Free Sample Report
UK Tankless Water Heater Market Trends
In the UK, the push to phase out gas boilers by 2035 under the government’s net-zero carbon strategy is propelling interest in alternatives such as tankless heaters. Compact home sizes and space constraints make tankless models more practical compared to bulky tanks. The increased adoption of underfloor heating systems complements tankless solutions for hot water supply. Public funding for low-carbon home upgrades is expanding consumer access. Moreover, a growing rental housing market is demanding quick, cost-efficient heating upgrades.
Asia Pacific Tankless Water Heater Market Trends
The Asia Pacific accounted for a market share of 29.3% in 2025. In Asia Pacific, rapid urbanization and rising middle-class income levels are fueling demand for modern home appliances, including tankless water heaters. The region's high population density and smaller living spaces favor compact heating systems. Government initiatives promoting energy-efficient housing, especially in countries such as Japan, South Korea, and China, are key market drivers. Increasing awareness of hygiene and hot water availability post-COVID-19 is influencing consumer behavior. In addition, domestic manufacturing growth is making tankless units more affordable and accessible.
Key Tankless Water Heater Company Insights
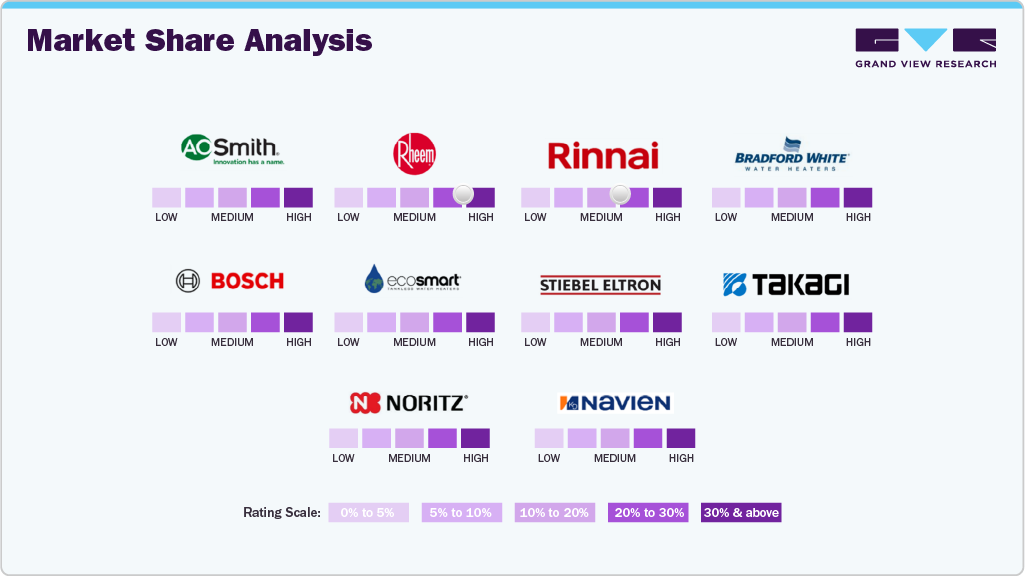
Many brands in the tankless water heater market have recognized untapped opportunities in their product portfolios and are actively working to capitalize on them. This includes launching innovative designs, expanding customization options, and tailoring marketing strategies to align with evolving consumer tastes and cultural trends. By addressing niche segments and emerging preferences, these brands aim to increase their market share and strengthen their competitive positioning worldwide.
 To learn more about this report, Download Free Sample Report
 To learn more about this report, Download Free Sample Report
Key Tankless Water Heater Companies:
The following key companies have been profiled for this study on the tankless water heater market.
-
Robert Bosch LLC
Competitive Benchmarking
Category
Operating Strategies
Competitive Edge
Weakness
Established Players (Rinnai Corporation, Rheem Manufacturing, A. O. Smith, Bosch Thermotechnology, Navien Inc.)
- Expand product portfolios with high-efficiency condensing and electric tankless systems; invest in smart IoT-enabled water heaters; strengthen partnerships with residential builders, contractors, and utility companies; focus on energy-efficient and regulation-compliant product lines; expand geographically in North America, Europe, and Asia-Pacific
- Strong global brand recognition, extensive distribution networks, high contractor loyalty, and large installed base; advanced R&D capabilities in energy-efficient and smart heating technologies; diversified product portfolios covering residential and commercial segments
- High manufacturing and compliance costs due to strict energy efficiency and environmental regulations; slower adoption in price-sensitive emerging markets; high installation complexity and dependency on skilled labor
Emerging Players (EcoSmart Green Energy Products, Eemax, Ariston Holding, Takagi, Midea Group, regional manufacturers)
- Focus on cost-effective electric tankless solutions; target niche segments such as small apartments, point-of-use systems, and retrofit installations; expand through e-commerce and direct-to-consumer channels; emphasize affordability and compact design innovations
- Faster innovation cycles in electric and compact tankless systems; ability to serve price-sensitive and emerging markets; flexible production and regional customization capabilities
- Limited global brand recognition; weaker contractor and installer networks; lower R&D budgets compared to established players; challenges in scaling across regulated markets
Recent Developments
-
In September 2024, A.O. Smith introduced a new Point-Of-Use (POU) Electric Tankless Water Heater designed for quick installation in light commercial and residential settings. This compact unit requires no venting and includes features like dry fire protection, leak detection with audible alarms, and integrated scale detection to enhance durability and performance.
-
In January 2023, Bosch Thermotechnology launched the Tronic 4000 C and Tronic 6100 C electric tankless water heaters, designed for point-of-use and whole-house applications, respectively. These models offer compact designs, high energy efficiency, and consistent on-demand hot water delivery, catering to both residential and light commercial needs.
Tankless Water Heater Market Report Scope
Report Attribute
Details
Market size in 2025
USD 4.3 billion
Estimated Market size in 2026
USD 4.7 billion
Projected Market size by 2033
USD 9.4 billion
Growth rate
CAGR of 10.4% from 2026 to 2033
Base year for estimation
2025
Historical data
2021 - 2024
Forecast period
2026 - 2033
Quantitative units
Revenue in USD million/billion and CAGR from 2026 to 2033
Report coverage
Revenue forecast, company ranking, competitive landscape, growth factors, and trends
Segments covered
Product, application, region
Regional scope
North America; Europe; Asia Pacific; Latin America; MEA
Country scope
U.S.; Canada; Mexico; Germany; UK; France; Italy; Spain; China; Japan; India; South Korea; Australia & New Zealand; Brazil; Argentina; South Africa;
Key companies profiled
A. O. Smith; Rheem Manufacturing Company; Rinnai Corporation; Bradford White Corporation; Robert Bosch LLC; EcoSmart Green Energy Products, Inc.; Stiebel Eltron Inc.; Takagi; Noritz America Corp.; Navien Inc.
Customization scope
Free report customization (equivalent up to 8 analysts' working days) with purchase. Addition or alteration to country, regional & segment scope.
Pricing and purchase options
Avail customized purchase options to meet your exact research needs. Explore purchase options
Global Tankless Water Heater Market Report - Table of Contents
Chapter 1. Methodology and Scope
1.1. Market Segmentation & Scope
1.2. Market Definition
1.3. Information Procurement
1.3.1. Purchased Database
1.3.2. GVR’s Internal Database
1.3.3. Secondary Materials & Third-Party Perspectives
1.3.4. Primary Research
1.4. Information Analysis
1.4.1. Data Analysis Models
1.5. Market Formulation & Data Visualization
1.6. Data Validation & Publishing
Chapter 2. Executive Summary
2.1. Market Snapshot
2.2. Product Outlook
2.3. Application Outlook
2.4. Regional Outlook
2.5. Competitive Landscape Snapshot
Chapter 3. Tankless Water Heater Market Variables and Trends
3.1. Market Introduction
3.2. Industry Value Chain Analysis
3.2.1. Raw Material Trends & Outlook
3.2.2. Retail/Sales Channel Analysis
3.3. Market Dynamics
3.3.1. Market Driver Analysis
3.3.2. Market Restraint Analysis
3.3.3. Market Opportunities
3.3.4. Market Challenges
3.4. Industry Analysis Tools
3.4.1. Porter’s Five Forces Analysis
3.5. Market Entry Strategies
Chapter 4. Tankless Water Heater Market: Consumer Behavior Analysis
4.1. Demographic Analysis
4.2. Consumer Trends & Preferences
4.3. Factors Affecting Buying Decisions
4.4. Consumer Product Adoption
4.5. Observations & Recommendations
Chapter 5. Tankless Water Heater Market: Product Estimates & Trend Analysis
5.1. Tankless Water Heater Market, By Product: Key Takeaways
5.2. Product Movement Analysis & Market Share, 2025 & 2033
5.3. Market Estimates & Forecasts by Product, 2021 - 2033 (USD Million)
5.3.1. Electric
5.3.1.1. Market estimates and forecast, 2021 - 2033 (USD Million)
5.3.2. Gas
5.3.2.1. Market estimates and forecast, 2021 - 2033 (USD Million)
Chapter 6. Tankless Water Heater Market: Application Estimates & Trend Analysis
6.1. Tankless Water Heater Market, By Application: Key Takeaways
6.2. Application Movement Analysis & Market Share, 2025 & 2033
6.3. Market Estimates & Forecasts, by Application, 2021 - 2033 (USD Million)
6.3.1. Residential
6.3.1.1. Market estimates and forecast, 2021 - 2033 (USD Million)
6.3.2. Commercial
6.3.2.1. Market estimates and forecast, 2021 - 2033 (USD Million)
Chapter 7. Tankless Water Heater Market: Regional Estimates & Trend Analysis
7.1. Regional Movement Analysis & Market Share, 2025 & 2033
7.2. North America
7.2.1. U.S.
7.2.1.1. Key country dynamics
7.2.1.2. Market estimates and forecast, 2021 - 2033 (USD Million)
7.2.2. Canada
7.2.2.1. Key country dynamics
7.2.2.2. Market estimates and forecast, 2021 - 2033 (USD Million)
7.2.3. Mexico
7.2.3.1. Key country dynamics
7.2.3.2. Market estimates and forecast, 2021 - 2033 (USD Million)
7.3. Europe
7.3.1. UK
7.3.1.1. Key country dynamics
7.3.1.2. Market estimates and forecast, 2021 - 2033 (USD Million)
7.3.2. Germany
7.3.2.1. Key country dynamics
7.3.2.2. Market estimates and forecast, 2021 - 2033 (USD Million)
7.3.3. France
7.3.3.1. Key country dynamics
7.3.3.2. Market estimates and forecast, 2021 - 2033 (USD Million)
7.3.4. Italy
7.3.4.1. Key country dynamics
7.3.4.2. Market estimates and forecast, 2021 - 2033 (USD Million)
7.3.5. Spain
7.3.5.1. Key country dynamics
7.3.5.2. Market estimates and forecast, 2021 - 2033 (USD Million)
7.4. Asia Pacific
7.4.1. China
7.4.1.1. Key country dynamics
7.4.1.2. Market estimates and forecast, 2021 - 2033 (USD Million)
7.4.2. India
7.4.2.1. Key country dynamics
7.4.2.2. Market estimates and forecast, 2021 - 2033 (USD Million)
7.4.3. Japan
7.4.3.1. Key country dynamics
7.4.3.2. Market estimates and forecast, 2021 - 2033 (USD Million)
7.4.4. Australia & New Zealand
7.4.4.1. Key country dynamics
7.4.4.2. Market estimates and forecast, 2021 - 2033 (USD Million)
7.4.5. South Korea
7.4.5.1. Key country dynamics
7.4.5.2. Market estimates and forecast, 2021 - 2033 (USD Million)
7.5. Latin America
7.5.1. Brazil
7.5.1.1. Key country dynamics
7.5.1.2. Market estimates and forecast, 2021 - 2033 (USD Million)
7.6. Middle East & Africa
7.6.1. South Africa
7.6.1.1. Key country dynamics
7.6.1.2. Market estimates and forecast, 2021 - 2033 (USD Million)
Chapter 8. Tankless Water Heater Market: Competitive Analysis
8.1. Recent Developments & Impact Analysis by Key Market Participants
8.2. Company Categorization
8.3. Participant’s Overview
8.4. Financial Performance
8.5. Product Benchmarking
8.6. Company Market Share Analysis, 2025 (%)
8.7. Company Heat Map Analysis, 2025
8.8. Strategy Mapping
8.9. Company Profiles
8.9.1. A. O. Smith
8.9.1.1. Company Overview
8.9.1.2. Financial Performance
8.9.1.3. Product Portfolios
8.9.1.4. Strategic Initiatives
8.9.2. Rheem Manufacturing Company.
8.9.2.1. Company Overview
8.9.2.2. Financial Performance
8.9.2.3. Product Portfolios
8.9.2.4. Strategic Initiatives
8.9.3. Rinnai Corporation
8.9.3.1. Company Overview
8.9.3.2. Financial Performance
8.9.3.3. Product Portfolios
8.9.3.4. Strategic Initiatives
8.9.4. Bradford White Corporation.
8.9.4.1. Company Overview
8.9.4.2. Financial Performance
8.9.4.3. Product Portfolios
8.9.4.4. Strategic Initiatives
8.9.5. Robert Bosch LLC.
8.9.5.1. Company Overview
8.9.5.2. Financial Performance
8.9.5.3. Product Portfolios
8.9.5.4. Strategic Initiatives
8.9.6. EcoSmart Green Energy Products, Inc.
8.9.6.1. Company Overview
8.9.6.2. Financial Performance
8.9.6.3. Product Portfolios
8.9.6.4. Strategic Initiatives
8.9.7. Stiebel Eltron Inc.
8.9.7.1. Company Overview
8.9.7.2. Financial Performance
8.9.7.3. Product Portfolios
8.9.7.4. Strategic Initiatives
8.9.8. Takagi
8.9.8.1. Company Overview
8.9.8.2. Financial Performance
8.9.8.3. Product Portfolios
8.9.8.4. Strategic Initiatives
8.9.9. Noritz America Corp.
8.9.9.1. Company Overview
8.9.9.2. Financial Performance
8.9.9.3. Product Portfolios
8.9.9.4. Strategic Initiatives
8.9.10. Navien Inc.
8.9.10.1. Company Overview
8.9.10.2. Financial Performance
8.9.10.3. Product Portfolios
8.9.10.4. Strategic InitiativesList of Tables
Table 1 Global Tankless water heater market - Key market driver analysis
Table 2 Global Tankless water heater market - Key market restraint analysis
Table 3 Global Tankless water heater market estimates & forecast, by Product (USD Million)
Table 4 Global Tankless water heater market estimates & forecast, by application (USD Million)
Table 5 U.S. macro-economic outlay
Table 6 U.S.Tankless water heater market estimates and forecast, 2021 - 2033 (USD Million)
Table 7 U.S. Tankless water heater market estimates & forecast, by Product (USD Million)
Table 8 U.S. Tankless water heater market estimates & forecast, by application (USD Million)
Table 9 Canada macro-economic outlay
Table 10 Canada Tankless water heater market estimates and forecast, 2021 - 2033 (USD Million)
Table 11 Canada Tankless water heater market estimates & forecast, by Product (USD Million)
Table 12 Canada Tankless water heater market estimates & forecast, by application (USD Million)
Table 13 Mexico macro-economic outlay
Table 14 Mexico Tankless water heater market estimates and forecast, 2021 - 2033 (USD Million)
Table 15 Mexico Tankless water heater market estimates & forecast, by Product (USD Million)
Table 16 Mexico Tankless water heater market estimates & forecast, by application (USD Million)
Table 17 U.K. macro-economic outlay
Table 18 U.K. Tankless water heater market estimates and forecast, 2021 - 2033 (USD Million)
Table 19 U.K. Tankless water heater market estimates & forecast, by Product (USD Million)
Table 20 U.K. Tankless water heater market estimates & forecast, by application (USD Million)
Table 21 Germany macro-economic outlay
Table 22 Germany Tankless water heater market estimates and forecast, 2021 - 2033 (USD Million)
Table 23 Germany Tankless water heater market estimates & forecast, by Product (USD Million)
Table 24 Germany Tankless water heater market estimates & forecast, by application (USD Million)
Table 25 France macro-economic outlay
Table 26 France Tankless water heater market estimates and forecast, 2021 - 2033 (USD Million)
Table 27 France Tankless water heater market estimates & forecast, by Product (USD Million)
Table 28 France Tankless water heater market estimates & forecast, by application (USD Million)
Table 29 Italy macro-economic outlay
Table 30 Italy Tankless water heater market estimates and forecast, 2021 - 2033 (USD Million)
Table 31 Italy Tankless water heater market estimates & forecast, by Product (USD Million)
Table 32 Italy Tankless water heater market estimates & forecast, by application (USD Million)
Table 33 Spain macro-economic outlay
Table 34 Spain Tankless water heater market estimates and forecast, 2021 - 2033 (USD Million)
Table 35 Spain Tankless water heater market estimates & forecast, by Product (USD Million)
Table 36 Spain Tankless water heater market estimates & forecast, by application (USD Million)
Table 37 China macro-economic outlay
Table 38 China Tankless water heater market estimates and forecast, 2021 - 2033 (USD Million)
Table 39 China Tankless water heater market estimates & forecast, by Product (USD Million)
Table 40 China Tankless water heater market estimates & forecast, by application (USD Million)
Table 41 India macro-economic outlay
Table 42 India Tankless water heater market estimates and forecast, 2021 - 2033 (USD Million)
Table 43 India Tankless water heater market estimates & forecast, by Product (USD Million)
Table 44 India Tankless water heater market estimates & forecast, by application (USD Million)
Table 45 Japan macro-economic outlay
Table 46 Japan Tankless water heater market estimates and forecast, 2021 - 2033 (USD Million)
Table 47 Japan Tankless water heater market estimates & forecast, by Product (USD Million)
Table 48 Japan Tankless water heater market estimates & forecast, by application (USD Million)
Table 49 Australia & New Zealand macro-economic outlay
Table 50 Australia & New Zealand Tankless water heater market estimates and forecast, 2021 - 2033 (USD Million)
Table 51 Australia & New Zealand Tankless water heater market estimates & forecast, by Product (USD Million)
Table 52 Australia & New Zealand Tankless water heater market estimates & forecast, by application (USD Million)
Table 53 South Korea macro-economic outlay
Table 54 South Korea Tankless water heater market estimates and forecast, 2021 - 2033 (USD Million)
Table 55 South Korea Tankless water heater market estimates & forecast, by Product (USD Million)
Table 56 South Korea Tankless water heater market estimates & forecast, by application (USD Million)
Table 57 Brazil macro-economic outlay
Table 58 Brazil Tankless water heater market estimates and forecast, 2021 - 2033 (USD Million)
Table 59 Brazil Tankless water heater market estimates & forecast, by Product (USD Million)
Table 60 Brazil Tankless water heater market estimates & forecast, by application (USD Million)
Table 61 South Africa macro-economic outlay
Table 62 South Africa Tankless water heater market estimates and forecast, 2021 - 2033 (USD Million)
Table 63 South Africa Tankless water heater market estimates & forecast, by Product (USD Million)
Table 64 South Africa Tankless water heater market estimates & forecast, by application (USD Million)
Table 65 Recent developments & impact analysis by key market participants
Table 66 Company market share, 2025
Table 67 Company heat map analysis
Table 68 Companies undergoing key strategies
List of FiguresFig. 1 Global Tankless Water Heater Market Segmentation
Fig. 2 Information procurement
Fig. 3 Primary research pattern
Fig. 4 Primary research approaches
Fig. 5 Primary research process
Fig. 6 Market snapshot
Fig. 7 Product snapshot
Fig. 8 Application snapshot
Fig. 9 Regional snapshot
Fig. 10 Competitive landscape snapshot
Fig. 11 Global Tankless water heater market size (USD Million)
Fig. 12 Global Tankless water heater market size, 2018 to 2033 (USD Million)
Fig. 13 Global Tankless water heater market: Penetration & growth prospect mapping
Fig. 14 Global Tankless water heater market: Value chain analysis
Fig. 15 Global Tankless water heater market: Profit margin analysis
Fig. 16 Global Tankless water heater market: Market dynamics
Fig. 17 Global Tankless water heater market: Porter's five forces analysis
Fig. 18 Factors influencing buying decisions for tankless water heater
Fig. 19 Global Tankless water heater market: Product Movement Analysis, 2025 & 2033 (%)
Fig. 20 Electric market estimates and forecast, 2021 - 2033 (USD Million)
Fig. 21 Gas market estimates and forecast, 2021 - 2033 (USD Million)
Fig. 22 Global Tankless water heater market: Application Movement Analysis, 2025 & 2033 (%)
Fig. 23 Residential Tankless water heater market estimates and forecast, 2021 - 2033 (USD Million)
Fig. 24 Commercial Tankless water heater market estimates and forecast, 2021 - 2033 (USD Million)
Fig. 25 Global Tankless water heater market: Regional outlook, 2025 & 2033 (USD Million)
Fig. 26 Regional marketplace: Key takeaways
Fig. 27 North America market estimates and forecast, 2021 - 2033 (USD Million)
Fig. 28 US market estimates and forecast, 2021 - 2033 (USD Million)
Fig. 29 Canada market estimates and forecast, 2021 - 2033 (USD Million)
Fig. 30 Mexico market estimates and forecast, 2021 - 2033 (USD Million)
Fig. 31 Europe Tankless water heater market estimates and forecast, 2021 - 2033 (USD Million)
Fig. 32 UK Tankless water heater market estimates and forecast, 2021 - 2033 (USD Million)
Fig. 33 Germany Tankless water heater market estimates and forecast, 2021 - 2033 (USD Million)
Fig. 34 France Tankless water heater market estimates and forecast, 2021 - 2033 (USD Million)
Fig. 35 Italy Tankless water heater market estimates and forecast, 2021 - 2033 (USD Million)
Fig. 36 Spain Tankless water heater market estimates, 2021 - 2033 (USD Million)
Fig. 37 China market estimates and forecast, 2021 - 2033 (USD Million)
Fig. 38 India market estimates and forecast, 2021 - 2033 (USD Million)
Fig. 39 Japan market estimates and forecast, 2021 - 2033 (USD Million)
Fig. 40 Brazil market estimates and forecast, 2021 - 2033 (USD Million)
Fig. 41 South Africa market estimates and forecast, 2021 - 2033 (USD Million)
Fig. 42 Key company categorization
Fig. 43 Company market share analysis, 2025
Fig. 44 Strategic framework of the tankless water heater marketResearch Methodology
The tankless water heater market figures in this report are based on a proven research process that combines executive interviews with secondary research from proprietary databases, company filings, and recognized regulatory and institutional sources. Market size is built through value-chain sizing - reconciling supply-side and demand-side estimates - and triangulated with bottom-up and top-down approaches. Every estimate passes multiple levels of expert validation before publication, with each tankless water heater segment quantified using the revenue-capture definitions in the table below.
Segment Definition
Segment - Type
Revenue capture definition
Electric
This segment covers the revenues generated through the sales of electric tankless water heaters that heat water instantly using high-powered electrical heating elements without the need for storage tanks. These systems are widely used in residential apartments, small homes, and point-of-use applications where space efficiency and easy installation are key requirements. Electric tankless systems eliminate standby heat loss and provide on-demand hot water with improved energy efficiency. Real-life examples include point-of-use bathroom heaters, under-sink instant water heaters, and whole-house electric systems used in compact urban apartments, smart homes, and energy-efficient housing projects.
Gas
This segment covers the revenues generated through the sales of gas tankless water heaters that heat water instantly using natural gas or propane burners instead of electricity, providing high-capacity hot water supply on demand. These systems are commonly used in large residential households, commercial buildings, hotels, and hospitality facilities where higher hot water flow rates are required. Gas tankless water heaters are known for their ability to deliver continuous hot water supply for multiple outlets simultaneously while maintaining lower operating costs in gas-available regions. Real-life examples include wall-mounted condensing gas water heaters, whole-home systems installed in villas and hotels, and commercial-grade units used in restaurants, laundries, and healthcare facilities.
Estimation Model
Layer Name
Key Question
Description
Demand / Need Layer
Who requires water heating solutions?
Total population requiring residential, commercial, and institutional hot water solutions globally.
Infrastructure & Access Layer
Who can technically adopt tankless systems?
Population with reliable electricity, gas supply, and installation-ready infrastructure.
Behavioural Layer
Who actively adopts tankless water heaters?
Users preferring energy-efficient, space-saving, and on-demand heating systems.
Monetisation Layer
How much revenue is generated?
Revenue generated through product sales, installation, maintenance, and service contracts.
Delivered Customizations
This report has been delivered with the following In-depth customizations
CLIENT REQUEST
CUSTOMIZATION DELIVERED
VALUE ADDS
Product, Application, and Regional Growth
Evaluated growth across electric and gas tankless water heaters, residential and commercial applications, and key regions including Europe, North America, and Asia Pacific.
Helps stakeholders identify high-growth segments, evaluate adoption drivers, and assess commercialization opportunities in energy-efficient water heating systems.
Energy Efficiency and Smart Home Adoption
Assessed demand for compact, on-demand, and energy-efficient water heating solutions, including Wi‑Fi-enabled and smart-controlled models.
Supports product positioning and innovation strategies by highlighting consumer preferences for convenience, sustainability, and lower utility costs.
Competitive and Opportunity Assessment
Reviewed the competitive landscape, key companies, recent product launches, and the opportunities created by electrification, retrofits, and regulatory support.
Supports investment and expansion strategies by identifying underserved markets, technology shifts, and long-term growth opportunities in the heating equipment sector.
Frequently Asked Questions About This Report
The global tankless water heater market size was valued at USD 4.3 billion in 2025 and is expected to reach USD 4.7 billion in 2026.
The electric tankless heaters market accounted for a revenue share of 70.5% in 2025, driven by factors such as the increasing shift toward cleaner energy sources and the phasing out of gas-based systems in many regions.
Some key players operating in the tankless water heater market include A. O. Smith, Rheem Manufacturing Company, Rinnai Corporation, Bradford White Corporation, Robert Bosch LLC, EcoSmart Green Energy Products, Inc., Stiebel Eltron Inc., Takagi, Noritz America Corp., and Navien Inc.
Key factors driving growth in the tankless water heater market include increasing demand for energy-efficient and space-saving appliances, rising construction of residential and commercial buildings, and growing consumer awareness about sustainable technologies. Technological advancements, such as Wi-Fi-enabled smart controls, also boost adoption. Government incentives for eco-friendly products further support market expansion. Additionally, longer lifespan and lower operational costs attract more consumers.
North America is the fastest-growing region over the forecast period.
The residential application segment leads the market with 73.5% in 2025.
The Europe region dominated the market with 33.3% revenue share in 2025.
The global tankless water heater market is expected to grow at a compound annual growth rate (CAGR) of 10.4% from 2026 to 2033 to reach USD 9.4 billion by 2033.
The electric product segment is the fastest-growing segment over the forecast period.
About the Author(s)
Electronic & Electrical Research Team
Consumer Goods · Electronic & ElectricalThis report was authored by the electronic & electrical research team at Grand View Research - comprising two research analysts, one senior research analyst, and one industry expert - with specialized expertise in the electronic & electrical segment of the consumer goods industry. All findings are based on proprietary consumer goods databases, executive interviews, and regulatory analysis, subject to internal peer review prior to publication.
Last Updated:
Speak to Analyst

Customize this report to your needs - add regions, segments, or data points, with 20% free customization.
Or view our licence options:


ISO 9001:2015 & 27001:2022 Certified
We are GDPR and CCPA compliant! Your transaction & personal information is safe and secure. For more details, please read our privacy policy.


