
- Home
- »
- Healthcare IT
- »
-
Telerehabilitation Market Size, Share & Trends Report, 2033GVR Report cover

Telerehabilitation Market (2026 - 2033)
Size, Share & Trends Analysis Report By Component (Hardware, Software), By Services (Clinical Assessment, Clinical Therapy), By Therapy, By Application, By End-use, By Region, And Segment Forecasts
Market Size, 2025
$4.0BMarket Estimate, 2026
$4.9BMarket Forecast, 2033
$16.0BCAGR, 2026–2033
18.5%Telerehabilitation Market Summary
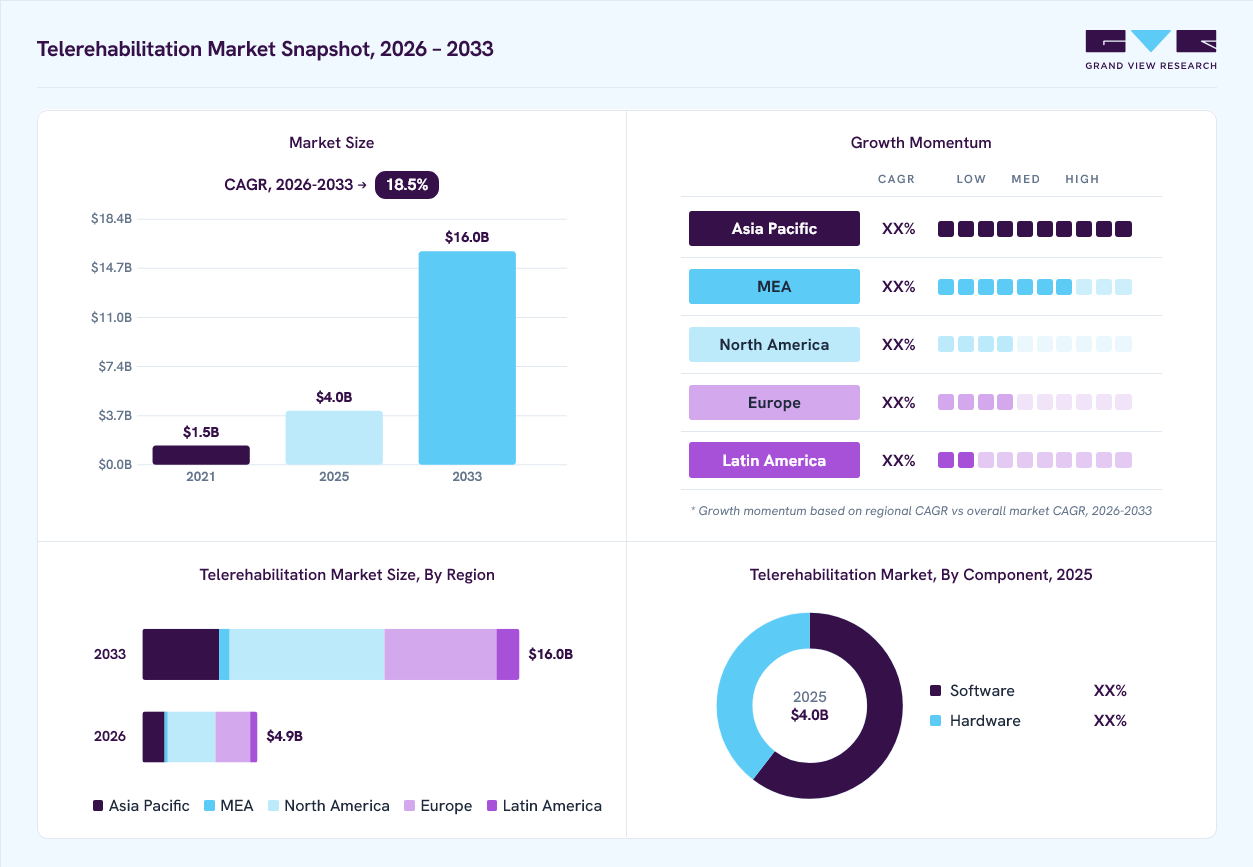
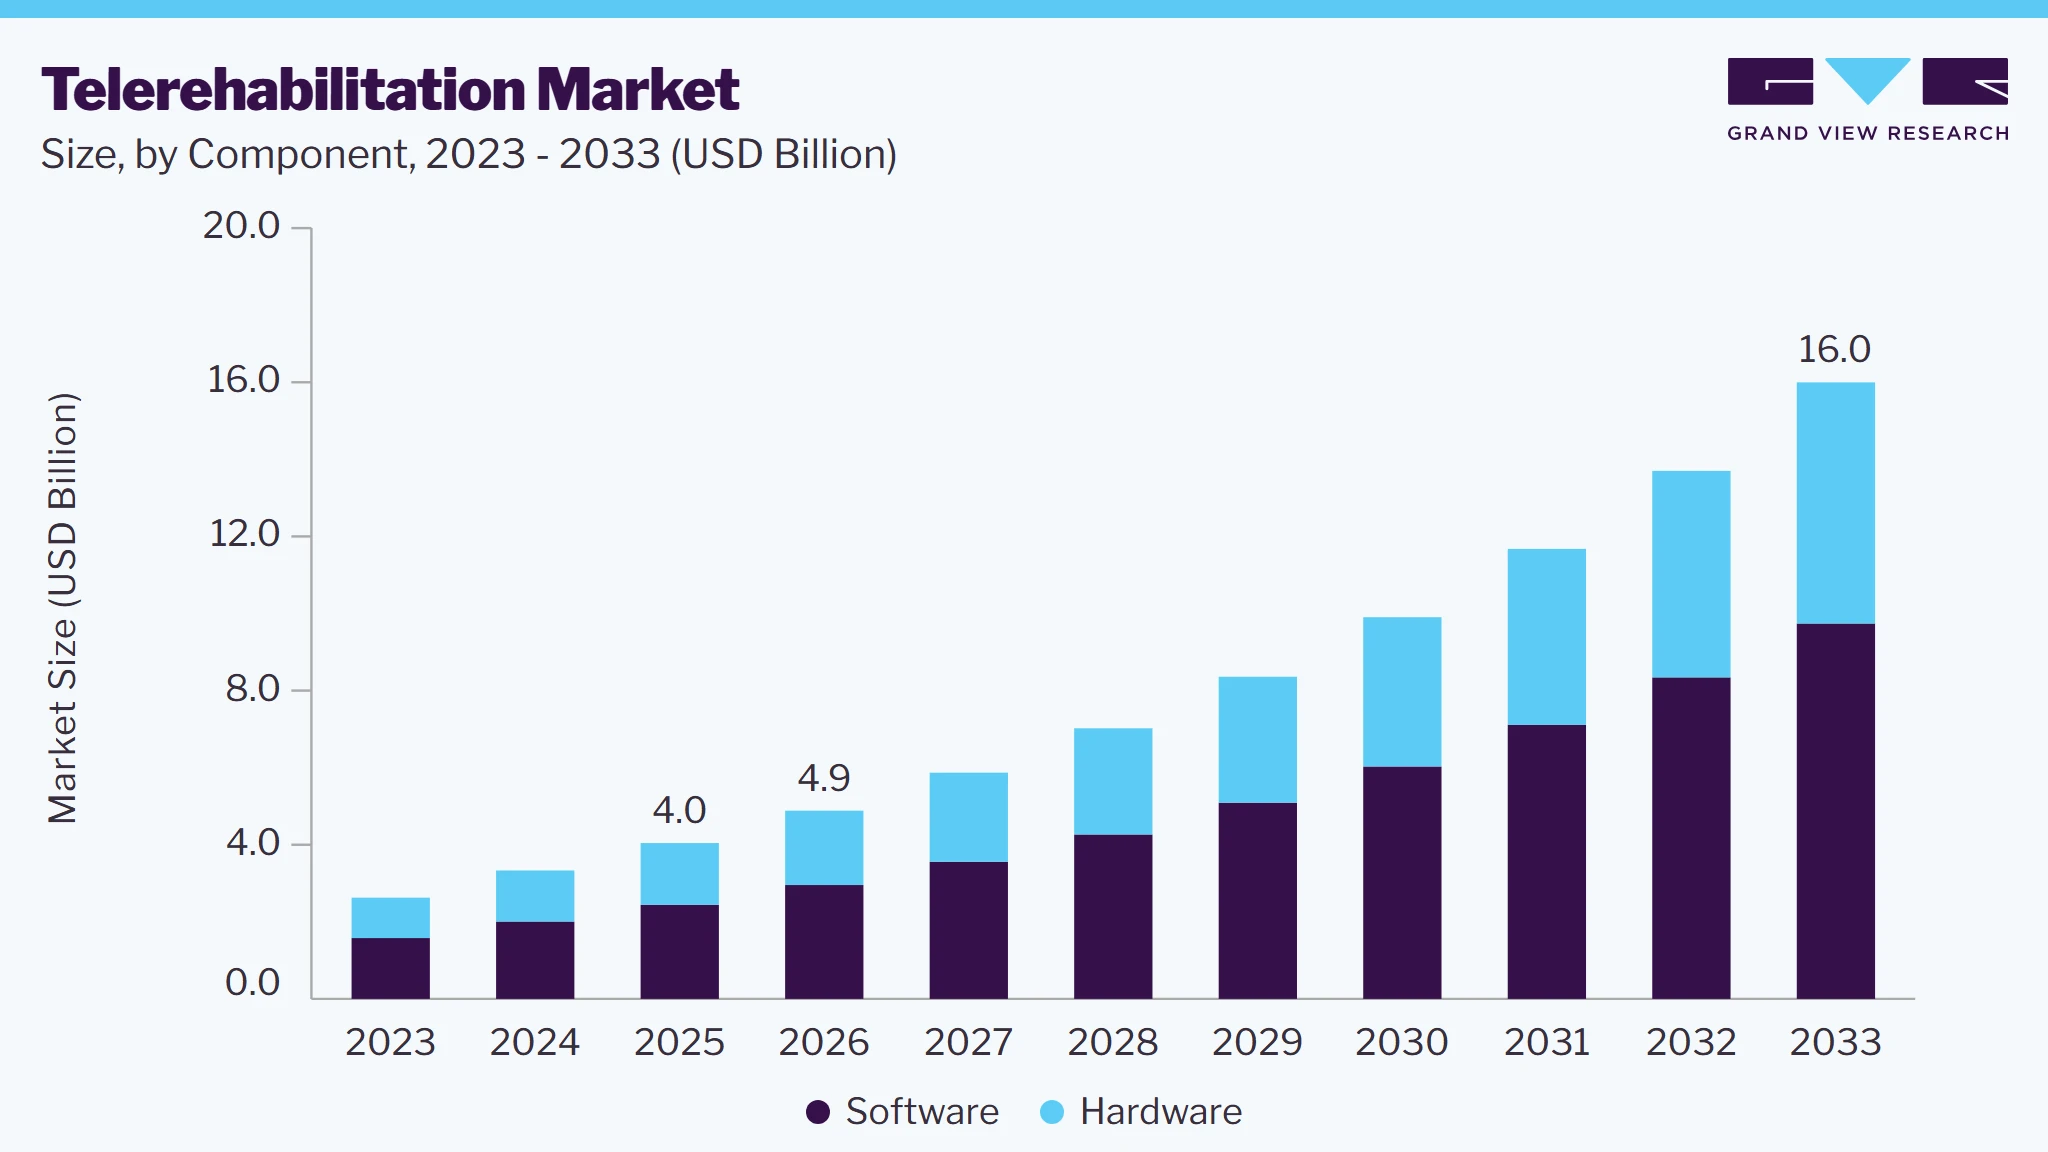
The global telerehabilitation market size was valued at USD 4.0 billion in 2025 and is projected to grow from USD 4.9 billion in 2026 to USD 16.0 billion by 2033, growing at a CAGR of 18.5% from 2026 to 2033. North America dominated the market, accounting for the largest global share of 41.5% in 2025. Increased instances of various disorders such as traumatic brain injury, cerebrovascular accidents, and developmental delays in the pediatric population are some of the factors expected to increase the demand for telerehabilitation services globally.
 Source: Grand View Research, IR Documents, Primary Interviews, Paid DatabasesTo learn more about this report,
 Download Free Sample Report
Key Market Trends & Insights
- By component: the software segment dominated the market with the largest revenue share in 2025.
- By services: the clinical therapy segment dominated the market with the largest revenue share in 2025.
- By therapy: the physical therapy segment dominated the market with a revenue share of 42.9% in 2025.
- By application: the orthopedic segment dominated the market with a share of 31.8% in 2025.
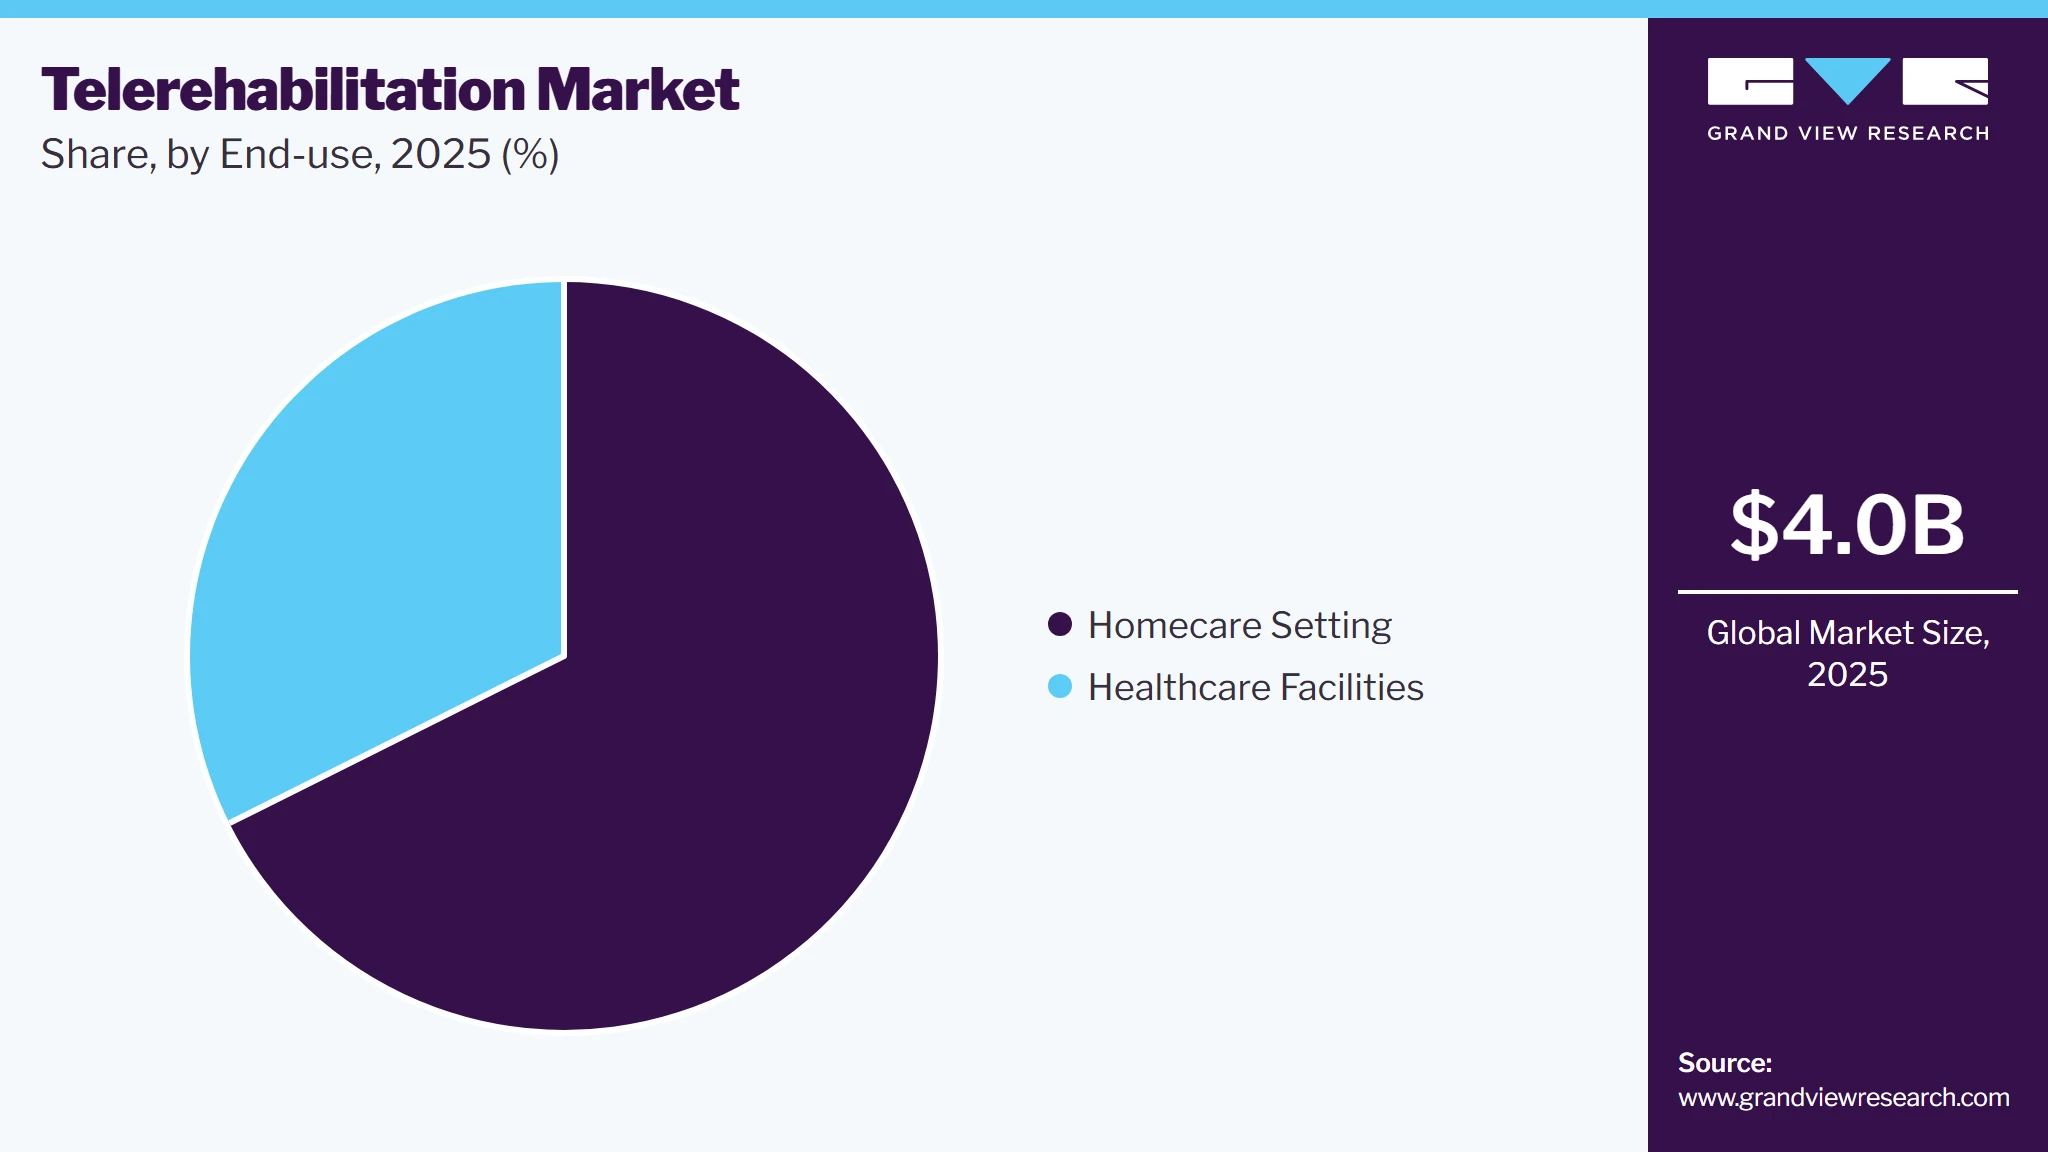
- By end-use: the homecare setting segment dominated the market with the largest share of 67.6% in 2025.
Regional Highlights
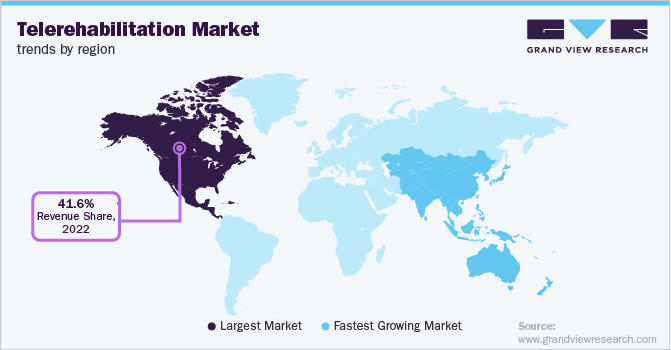
- Largest regional market: North America (41.5% revenue share, 2025)
- Fastest-growing regional market: Asia Pacific (fastest CAGR, 2026-2033)
- By country: The U.S. held the largest share of North America in 2025.
Market Size & Forecast
- Market size in 2025: USD 4.0 Billion
- Estimated market size in 2026: USD 4.9 Billion
- Projected market size by 2033: USD 16.0 Billion
- CAGR (2026-2033): 18.5%
Three ways to get this report
Buy it, customize it, or ask a question.Ask an Analyst
Analyst response in 1 business day
- AccessReport author, directly
- Reply timeWithin 1 working day
- No sales callDirect answer only
- FormatEmail reply
- CostFree, no cost
Get the Full Report
What the study covers
- FormatsPDF · Excel · Dashboard
- Timeline2026–2033 annual, 2025 base
- Coverage20+ countries, 5 regions
- Companies10+ key players profiled
Customize the Report
20% free customization
- IncludeCountries, segments, points
- TailorTo your product definition
- ExtendDeeper competitor detail
- OrA fully bespoke study
- Turnaround5–10 working days
These conditions hamper the patient's physical movement, increasing the demand for these services. For instance, according to an article published by JAMA Network Open in November 2024, pediatric traumatic brain injury accounts for nearly 500,000 emergency department visits and more than 7000 fatalities annually in the U.S. Telerehabilitation, or e-rehabilitation, provides rehabilitation services through a telecommunication network and the Internet. Medical professionals remotely communicate with patients using telerehabilitation services and diagnose the patients & administer therapy. Physical therapy, speech-language, occupational therapy, audiology, audiology, and psychology are medical specialties that use telerehabilitation. For instance, Bio-sensing Solutions SL. (DyCare), a Spain-based telerehabilitation platform offering ReHub, a telerehabilitation tool for physiotherapists, hospitals, and clinics.
 To learn more about this report, Download Free Sample Report
Furthermore, telerehabilitation allows patients to receive rehabilitation services from the comfort of their homes, overcoming geographical barriers and enabling continuous care for those with limited access. For instance, NeoRehab introduced a new eHAB platform to meet the demand of patients with chronic pain who reside in remote locations.
Moreover, the rising adoption of digital technologies in the healthcare industry and the increasing penetration of smartphones and the internet globally are expected to drive the market. In addition, various initiatives are undertaken by both public and private institutions. For instance, the American Telemedicine Association's Telemedicine Special Interest Group Special is a key resource for rehabilitation professionals who want to incorporate information and communication technologies into clinical best practices, advocacy, and the delivery of rehabilitation services. These initiatives are credited with increasing awareness of telerehabilitation services, which is expected to drive market growth.
With the advancement of telecommunication technologies, patients can now access rehabilitation services remotely, reducing the need for in-person visits and making therapy more convenient and accessible. This shift particularly benefits individuals in rural or underserved areas, allowing them to receive high-quality rehabilitation care without geographical constraints. The proliferation of telerehabilitation platforms and tools reflects the broader trend towards digital health solutions, enhancing the overall accessibility and efficiency of rehabilitation services. As technology advances, these innovations are set to drive further growth in the rehabilitation equipment market, offering new possibilities for improving patient care and recovery.
Market Dynamics
The telerehabilitation market is growing due to the increasing prevalence of chronic diseases, neurological and musculoskeletal disorders, sports injuries, and age-related disabilities requiring ongoing rehabilitation. Rising adoption of telehealth, AI-enabled rehabilitation platforms, wearable devices, and remote monitoring technologies are supporting market growth. In addition, increasing healthcare expenditure, expanding digital health infrastructure, and the growing need for accessible, cost-effective rehabilitation services are driving demand. The focus on improving patient outcomes, reducing hospital readmissions, and expanding access to rehabilitation in remote areas continues to create significant growth opportunities in the market.
Telerehabilitation, or e-rehabilitation, provides rehabilitation services through a telecommunication network and the internet. Medical professionals remotely communicate with patients using telerehabilitation services and diagnose the patients & administer therapy. Physical therapy, speech-language, occupational therapy, audiology, audiology, and psychology are medical specialties that use telerehabilitation. For instance, Bio-sensing Solutions SL. (DyCare), a Spain based telerehabilitation platform offering ReHub, a telerehabilitation tool for physiotherapists, hospitals, and clinics.
Furthermore, telerehabilitation allows patients to receive rehabilitation services from the comfort of their homes, overcoming geographical barriers and enabling continuous care for those with limited access. For instance, NeoRehab introduced a new eHAB platform to meet the demand of patients with chronic pain who reside in remote locations.
Case Study Published by Springer Nature in May 2024: Acceptance and Adoption of Telerehabilitation Among Physiotherapists in Nigeria
Background:
Nigeria, like many low- and middle-income countries (LMICs), has experienced relatively slow adoption of telerehabilitation despite growing global acceptance of remote rehabilitation services. The COVID-19 pandemic accelerated interest in virtual physiotherapy, creating an opportunity to evaluate healthcare professionals' willingness to integrate tele-rehabilitation into routine clinical practice. A 2024 mixed-method study assessed the level of acceptance, adoption, key facilitators, and barriers among Nigerian physiotherapists.
Implementation and Key Findings:
• The study surveyed 331 licensed physiotherapists across Nigeria and conducted in-depth interviews with 12 clinicians to evaluate tele-rehabilitation adoption and acceptance.
• Before the COVID-19 lockdown, only 18.7% of physiotherapists provided tele-rehabilitation services.
• During the national lockdown, adoption increased to 34.4%, highlighting how the pandemic accelerated the implementation of digital rehabilitation services.
• After lockdown restrictions were lifted, continued utilization declined, with only 21.8% of physiotherapists maintaining tele-rehabilitation services, indicating challenges in sustaining virtual care beyond emergency situations.
• Smartphone-based applications were the most widely used delivery platform, adopted by 46.8% of respondents, demonstrating the importance of mobile technology in low-resource healthcare settings.
• Tele-rehabilitation was primarily used for:
- • Patient education
- • Management of musculoskeletal disorders
- • Exercise prescription and follow-up consultations
• The study found that age and years of clinical experience significantly influenced tele-rehabilitation adoption, with younger physiotherapists demonstrating higher levels of digital technology utilization.
• Key facilitators supporting tele-rehabilitation adoption included:
- • Training programs for physiotherapists
- • Availability of evidence-based clinical guidelines
- • Access to telehealth software and hardware
- • Increased patient awareness and acceptance of remote care
• Major barriers limiting adoption included:
- • Limited digital and telecommunications infrastructure
- • Poor internet connectivity
- • Financial constraints
- • Lack of institutional and hospital management support
- • Insufficient information and communication technology (ICT) skills among healthcare professionals
Market Impact:
• Growing clinical acceptance: The study indicates that physiotherapists increasingly recognize the value of telerehabilitation, creating a favorable environment for future market expansion in emerging economies.
• Infrastructure remains a key growth constraint: Limited digital infrastructure, inconsistent internet connectivity, and inadequate technological resources continue to restrict large-scale adoption despite growing interest.
• COVID-19 demonstrated market potential: The rise in tele-rehabilitation usage during the pandemic highlighted strong latent demand for remote rehabilitation services when access to in-person care is disrupted.
• Opportunities for affordable digital solutions: Vendors can capitalize on demand by developing cost-effective, mobile-first telerehabilitation platforms that are accessible in low-resource settings.
• Increasing demand for clinician training: The need for digital competency and telehealth training creates opportunities for education providers, healthcare institutions, and technology companies offering implementation support.
• Expansion of cloud-based rehabilitation platforms: The findings support growing demand for cloud-enabled rehabilitation software that facilitates remote patient monitoring, virtual consultations, and digital exercise management.
• Need for localized technology solutions: Market growth will be driven by platforms designed to address local language requirements, affordability, connectivity limitations, and region-specific clinical workflows.
• Policy and reimbursement will accelerate adoption: Government investment in digital health infrastructure, supportive reimbursement frameworks, and standardized tele-rehabilitation guidelines will be essential for sustained market growth.
• Significant opportunity in emerging markets: Africa and other low- and middle-income countries represent high-growth markets where improving digital healthcare ecosystems can substantially expand the adoption of telerehabilitation services.
Strategic Insight:
This case study highlights that technology availability alone is insufficient to drive sustained telerehabilitation adoption. Long-term market growth depends on strengthening digital infrastructure, enhancing clinician competencies, establishing regulatory frameworks, and integrating tele-rehabilitation into routine healthcare delivery. Vendors that combine user-friendly platforms with clinical training, technical support, and evidence-based implementation strategies are likely to achieve greater success in emerging healthcare markets, where digital rehabilitation demand is expected to continue growing.
Effective telerehabilitation services depend on reliable high-speed internet connectivity, access to smartphones, tablets, or computers, and secure digital platforms for video consultations and remote patient monitoring. However, many patients and healthcare providers continue to face challenges such as unstable internet connections, limited access to digital devices, frequent power outages, and inadequate IT infrastructure, reducing the effectiveness and continuity of virtual rehabilitation sessions. According to WHO's Global Strategy on Digital Health, many low- and middle-income countries continue to face challenges such as inadequate broadband connectivity, fragmented digital health ecosystems, and shortages of trained healthcare professionals, limiting the implementation and scalability of telehealth services, including telerehabilitation.
In addition, varying levels of digital literacy among patients, elderly populations, and healthcare professionals further limit the adoption of telerehabilitation services. Healthcare providers may also encounter difficulties integrating telehealth platforms with existing electronic health record (EHR) systems, while concerns regarding data privacy, cybersecurity, and regulatory compliance add complexity to implementation. These technological and operational barriers increase deployment costs, slow provider adoption, and restrict access to remote rehabilitation services, particularly in underserved regions. Overcoming these infrastructure and accessibility challenges will require investments in broadband expansion, affordable digital technologies, healthcare workforce training, and supportive government policies to enable widespread and sustainable adoption of telerehabilitation.
The integration of AI into telerehabilitation platforms presents a significant growth opportunity for the market. AI-powered solutions can analyze patient performance in real time, personalize rehabilitation exercises based on individual progress, and provide automated feedback, enabling more effective remote care. Combined with wearable sensors, motion-tracking technology, and computer vision, these platforms allow clinicians to monitor patient adherence, assess movement quality, and modify treatment plans without requiring frequent in-person visits. As healthcare providers increasingly prioritize value-based care and seek scalable solutions to address workforce shortages and rising rehabilitation demand, AI-enabled telerehabilitation platforms can improve clinical outcomes while reducing healthcare costs.
Furthermore, expanding internet connectivity, greater adoption of digital health technologies, and supportive government initiatives promoting virtual healthcare are expected to accelerate the deployment of intelligent telerehabilitation solutions across hospitals, rehabilitation centers, and home healthcare settings globally.
Market Concentration & Characteristics
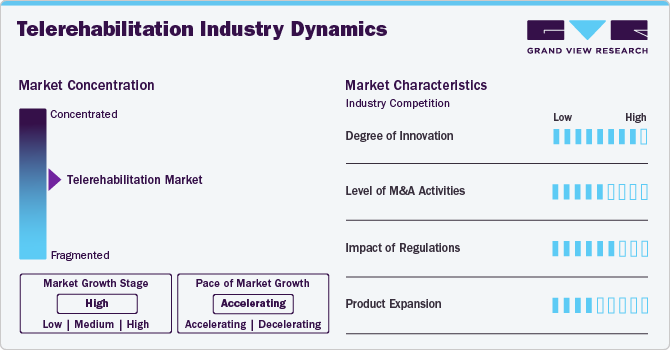
The telerehabilitation industry is characterized by a high degree of innovation owing to dynamic market trends and technological advancements, such as integrating AI and ML in software and hardware. Real-time telerehabilitation may positively affect treatment session attendance and exercise program compliance.
The telerehabilitation industry is characterized by a medium level of merger and acquisition (M&A) activity, facilitating access to complementary technologies and expertise to capture a larger market share. Furthermore, companies desire to expand their business to cater to the growing demand for orthopedic implants and maintain a competitive edge.
 To learn more about this report, Download Free Sample Report
Regulations, such as the 1996 Health Insurance Portability and Accountability Act (HIPAA) and its amendments under the Health Information Technology for Economic and Clinical Health (HITECH) Act, positively impact market growth. These regulations play a crucial role in safeguarding digital health information's secure management and privacy, shaping telemedicine services' operational framework and compliance standards, particularly in the U.S.
Key market players are adopting various strategies, such as new partnerships, collaborations, and geographical expansions.Several market players are expanding their business by launching new solutions to expand their product portfolio.
Analyst Perspective
The telerehabilitation market is witnessing rapid growth due to the increasing prevalence of chronic diseases, aging populations, rising telehealth adoption, and growing demand for convenient home-based rehabilitation. Advancements in AI, wearable devices, remote patient monitoring, and virtual rehabilitation technologies are further improving patient outcomes and expanding access to care. Companies offering secure, AI-enabled, and interoperable telerehabilitation platforms with personalized therapy, seamless virtual care, and strong partnerships with healthcare providers will gain a competitive advantage by enhancing patient engagement, improving clinical outcomes, and expanding market reach.
Component Insights
Based on component, the software segment dominated the market with the largest revenue share in 2025 and is anticipated to witness the fastest CAGR growth over the forecast period. The adoption of various software has significantly increased due to assistance from healthcare systems. Furthermore, market players are developing software applications to help physicians diagnose and treat patients more efficiently. For instance, in 2021, HI launched Open Tele Rehab software in Vietnam to provide rehabilitation services to isolated populations. Similarly, Rehametrics digital rehabilitation software is designed to improve the outcomes obtained from rehabilitation and facilitate rehabilitation professionals' daily work. Such an initiative is expected to propel the segment’s growth over the forecast period.
Hardware is anticipated to witness significant CAGR growth over the forecast period. The growth is attributed to the widespread adoption of various medical peripheral devices, microphones, audio equipment, video conferencing, and display screen devices used to facilitate telerehabilitation. Moreover, a study published by NIH reported that a telerehabilitation program using virtual reality video games improves postural control and balance in multiple sclerosis patients. For instance, the Oculus is a virtual reality (VR) system used for telerehabilitation services.
Services Insights
Based on services, the clinical therapy segment dominated the market with the largest revenue share in 2025 and is anticipated to witness the fastest CAGR growth over the forecast period. Physical, speech, occupational, behavioral, neurological, and cognitive rehabilitation therapies are among the clinical therapies provided by telerehabilitation. Moreover, the demand for drug and alcohol addiction treatment is anticipated to rise over the forecast period, thereby driving segment growth. For instance, according to the 2023 National Survey on Drug Use and Health (NSDUH) conducted by the National Institute on Alcohol Abuse and Alcoholism (NIAAA), 28.9 million individuals ages 12 and above had alcohol use disorder.
Clinical assessment is anticipated to witness a significant CAGR over the forecast period. The primary purpose of clinical assessment in telerehabilitation is to help the rehabilitation counselor, and consumers obtain essential and relevant information. Telerehabilitation eliminates the need for patients to travel, which is beneficial for people with mobility issues, chronic conditions, or those residing in rural or remote areas. This leads to improved patient engagement and treatment adherence. Moreover, this segment offers evidence to support the development of a rehabilitation plan tailored to the client's needs, circumstances, and goals and enables accurate assessment. Such beneficial factors are anticipated to boost the market growth over the forecast period.
Therapy Insights
Based on therapy, the physical therapy segment dominated the market with a revenue share of 42.9% in 2025. The increasing number of people participating in fitness programs and the rising number of outdoor or sports endeavors drive demand for physical therapy. With the help of telerehabilitation, physical therapists discuss with patients online and specify their physical activities. Moreover, the growing acceptance of telerehabilitation among physiotherapists is further propelling segment growth. For instance, Ambitions, a therapy center in the U.S., reported that more than 50 million Americans seek physical therapy services.
Occupational therapy is anticipated to witness the fastest CAGR over the forecast period. Occupational therapy helps patients suffering from cognitive, physical, and sensory problems regain independence in all aspects of their daily activities. The rise in the prevalence of people suffering from various disorders, such as dementia, Alzheimer's disease, amputations, etc., is expected to drive demand for these software solutions during the forecast period. In addition, occupational therapists are adopting electronic information and telecommunication technologies to offer services to patients remotely. Thus, such factors are expected to boost segment growth. For instance, according to the Alzheimer's Society, currently, an estimated 982,000 individuals live with dementia in the UK, and is anticipated to rise to 1.4 million by 2040.
Application Insights
Based on application, the orthopedic segment dominated the market with a share of 31.8% in 2025 and is anticipated to witness the fastest CAGR growth over the forecast period. The rising number of people suffering from osteoarthritis, bone fractures due to road accidents, and sports injuries are driving the demand for telerehabilitation. For instance, according to Stanford University, in the U.S., annually, more than 3.5 million children suffer from sports injuries. Thus, sports-induced injury is anticipated to drive the demand for telerehabilitation services in the orthopedic industry. Moreover, various software solutions are being developed that permit monitoring exercise time, local temperature, and the biomechanics of active movements of patients who underwent orthopedic surgery. This is expected to drive the market.
The cardiovascular segment is anticipated to witness the fastest CAGR over the forecast period. Moreover, various software solutions are being developed that permit monitoring exercise time, local temperature, and the biomechanics of active movements of patients who underwent orthopedic surgery. This is expected to drive the market. In addition, telephysiotherapy treatments modulate physiological signals such as pulse rate, oxygen levels, electrocardiograms (ECG), and joint motion frequency for individuals with cardiorespiratory disorders. Such factors boost the segment growth.
End-use Insights
Based on end-use, the homecare setting segment dominated the market with the largest revenue share in 2025 and is anticipated to witness the fastest CAGR growth over the forecast period. One primary driver is the increasing preference for home-based care among patients, especially the elderly and those suffering from chronic diseases. Home care allows patients to maintain their independence and receive personalized care tailored to their specific needs, which is particularly important for those undergoing long-term rehabilitation. In addition, government initiatives and insurance providers increasingly support home care services, understanding the cost benefits and the positive impact on patient well-being.
 To learn more about this report, Download Free Sample Report
The healthcare facilities segment is anticipated to witness significant CAGR over the forecast period, owing to an increasing focus on patient-centered care and the rise in chronic diseases and age-related conditions. Hospitals and clinics are investing in advanced telerehabilitation technologies to improve patient outcomes and enhance recovery processes. This trend is driven by the need for more effective treatments and rehabilitation solutions for conditions such as stroke, orthopedic injuries, and neurological disorders.
Regional Insights
North America dominated the women’s health app market with the largest revenue share of 41.5% in 2025. The rising prevalence of chronic diseases and well-developed healthcare infrastructure fuel the market growth in this region. In addition, technological advancements in rehabilitation and rising public awareness of remote patient monitoring contribute to the market expansion. Market players are focusing on improving the quality of telerehabilitation services to improve the overall patient experience.
 To learn more about this report, Download Free Sample Report
U.S. Telerehabilitation Market Trends
The telerehabilitation market in the U.S. held the largest share in the North America region in 2025. Factors such as the growing need for remote patient consultation and the launch of virtual physiotherapist services boost market growth. For instance, in August 2022, Orbit Telehealth, a virtual care platform, introduced a platform enabling over 300,000 brick-and-mortar Physical Therapy providers to provide hybrid virtual care.
Europe Telerehabilitation Market Trends
The telerehabilitation market in Europe is anticipated to register a considerable growth rate during the forecast period. The rising prevalence of chronic diseases, such as heart disease, and obesity, is one of the primary market drivers in this region. For instance, according to the UK Government, approximately 63.8% of adults in England 18 years and above were living with obesity.
Spain telerehabilitation market is anticipated to register a considerable growth rate during the forecast period. Factors such as rising demand for telerehabilitation services among athletes and fitness enthusiasts, and a growing number of smartphone users fuel the telerehabilitation industry in the country. For instance, in October 2022, DyCare, a Spain-based provider of telerehabilitation services, launched telerehabilitation services for insurance companies.
Asia Pacific Telerehabilitation Market Trends
The telerehabilitation market in Asia Pacific is anticipated to register the fastest growth over the forecast period. There is huge investment potential in providing telerehabilitation services in emerging nations such as India and China, where healthcare infrastructure is expanding, and the physician-to-patient ratio is low. Moreover, various government initiatives are undertaken to promote digital health technologies, thereby boosting market growth in the region.
India telerehabilitation market is anticipated to register a considerable growth rate during the forecast period. Factors such as favorable government initiatives and growing investment drive the market growth. For instance, in October 2024, the Indian government launched a telerehabilitation center to offer crucial sound therapy for children post-cochlear implant surgery.
Latin America Telerehabilitation Market Trends
The telerehabilitation market in Latin America is witnessing steady growth. The market is driven by an increasing elderly population, rising prevalence of chronic diseases, and growing awareness of rehabilitation services. Market players are focusing on improving the quality of telerehabilitation services to improve the overall patient experience.
Argentina telerehabilitation market is anticipated to register considerable growth during the forecast period. Argentina's telerehabilitation equipment market is rapidly evolving, driven by increasing investments in healthcare and a growing awareness of the importance of rehabilitation in improving quality of life. The Argentine government has been focusing on expanding access to rehabilitation services through various public health programs and collaborations with private-sector players.
Middle East & Africa Telerehabilitation Market Trends
The telerehabilitation market in the Middle East and Africa is experiencing lucrative growth, owing to growth in the rehabilitation equipment sector. This growth is driven by an increasing prevalence of chronic diseases and an aging population, technological advancements, and rising awareness about the benefits of telerehabilitation.
Saudi Arabia telerehabilitation market is anticipated to register a considerable growth rate during the forecast period. The rising adoption of various strategies to improve the rehabilitation market, with substantial investments in healthcare facilities and rehabilitation centers, boosts the market growth. For example, the Saudi Vision 2033 plan emphasizes enhancing the quality of healthcare services, including rehabilitation, which has led to the establishment of new centers equipped with the latest rehabilitation technology.
Key Telerehabilitation Company Insights
Key participants in the telerehabilitation industry are focusing on developing innovative business growth strategies, such as expanding their product portfolios, partnerships and collaborations, mergers and acquisitions, and business footprints.
Key Telerehabilitation Companies:
The following key companies have been profiled for this study on the telerehabilitation market.
-
American Well
-
Doctor On Demand, Inc.
-
Koninklijke Philips N.V
-
Hinge Health, Inc.
-
Cisco Systems, Inc.
-
NeoRehab
-
C3O TelemedicineTM
-
Bosch Healthcare Solutions GmbH
-
Physio Cloud Software
-
Ludica Health Inc. (Jintronix.com)
Competitive Benchmarking
Category
Operating Strategies
Competitive Edge
Weakness
Established Players (e.g., Philips Healthcare, Medtronic, Oracle Health (Cerner), Teladoc Health, Hinge Health)
- Expand comprehensive digital rehabilitation platforms through AI integration, remote patient monitoring, strategic acquisitions, partnerships with hospitals and health systems, and geographic expansion. Invest in interoperable telehealth ecosystems, wearable technologies, and evidence-based clinical programs.
- Strong brand recognition, extensive healthcare provider networks, strong R&D capabilities, broad digital health portfolios, established payer relationships, and global market presence.
- High implementation and maintenance costs, lengthy procurement cycles, integration challenges with legacy healthcare systems, and dependence on reimbursement policies and regulatory approvals.
Emerging Players (e.g., Sword Health, Kaia Health, Reflexion Health, RecoveryOne, XRHealth)
- Focus on AI-powered personalized rehabilitation, virtual reality (VR)-based therapy, computer vision, motion-tracking technologies, and home-based rehabilitation programs. Emphasize subscription-based models, employer partnerships, and rapid product innovation.
- Agile business models, rapid innovation cycles, cost-effective cloud-based platforms, personalized patient engagement, scalable remote care solutions, and strong user experience.
- Limited global brand recognition, smaller customer base, constrained financial resources, lower market penetration, and challenges in scaling across diverse regulatory and reimbursement environments.
Recent Developments
- In July 2024, the Federation Physiotherapy Virtual Care Clinic(FPVCC) launched the first satellite hubs across the Latrobe Valley, which provides access to their physiotherapy telehealth appointments.
Telerehabilitation Market Report Scope
Report Attribute
Details
Market size value in 2025
USD 4.0 billion
Market size value in 2026
USD 4.9 billion
Revenue forecast in 2033
USD 16.0 billion
Growth rate
CAGR of 18.5% from 2026 to 2033
Historical data
2021 - 2025
Forecast period
2026 - 2033
Quantitative units
Revenue in USD million/billion, and CAGR from 2026 to 2033
Report coverage
Revenue forecast, company ranking, competitive landscape, growth factors, and trends
Segments covered
Component, services, therapy, application, end-use, region
Regional scope
North America; Europe; Asia Pacific; Latin America; MEA
Country scope
U.S., Canada, Mexico, Germany, UK, Spain, Italy, France, Norway, Denmark, Sweden, Japan, China, India, Australia, Thailand, South Korea, Brazil, Argentina, South Africa, Saudi Arabia, UAE, Kuwait
Key companies profiled
American Well, Doctor On Demand, Inc., Koninklijke Philips N.V, Hinge Health, Inc., Cisco Systems, Inc., NeoRehab, C3O TelemedicineTM , Bosch Healthcare Solutions GmbH, Physio Cloud Software, Ludica Health Inc. (Jintronix.com)
Customization scope
Free report customization (equivalent up to 8 analysts' working days) with purchasse. Addition or alteration to country, regional & segment scope.
Pricing and purchase options
Avail customized purchase options to meet your exact research needs. Explore purchase options
Global Telerehabilitation Market Report Segmentation
This report forecasts revenue growth at global, regional, and country levels and provides an analysis of industry trends in each of the sub-segments from 2021 to 2033. For this study, Grand View Research, Inc. has segmented the global telerehabilitation market report based component, services, therapy, application, end-use, and region:
-
Component Outlook (Revenue, USD Million, 2021 - 2033)
-
Hardware
-
Software
-
-
Services Outlook (Revenue, USD Million, 2021 - 2033)
-
Clinical Assessment
-
Clinical Therapy
-
-
Therapy Outlook (Revenue, USD Million, 2021 - 2033)
-
Physical Therapy
-
Occupational Therapy
-
Others
-
-
Application Outlook (Revenue, USD Million, 2021 - 2033)
-
Cardiovascular
-
Orthopedic
-
Neurology
-
Pediatric
-
Others
-
-
End-use Outlook (Revenue, USD Million, 2021 - 2033)
-
Healthcare Facilities
-
Homecare Setting
-
-
Regional Outlook Revenue, USD Million, 2021 - 2033)
-
North America
-
U.S.
-
Canada
-
Mexico
-
-
Europe
-
Germany
-
UK
-
Spain
-
Italy
-
France
-
Denmark
-
Norway
-
Sweden
-
-
Asia Pacific
-
Japan
-
China
-
India
-
Australia
-
Thailand
-
South Korea
-
-
Latin America
-
Brazil
-
Argentina
-
-
MEA
-
South Africa
-
Saudi Arabia
-
UAE
-
Kuwait
-
-
Research Methodology
The telerehabilitation market figures in this report are based on a proven research process that combines executive interviews with secondary research from proprietary databases, company filings, and recognized regulatory and institutional sources. Market size is built through value-chain sizing-reconciling supply-side and demand-side estimates-and triangulated with bottom-up and top-down approaches. Every estimate passes multiple levels of expert validation before publication, with each telerehabilitation segment quantified using the revenue-capture definitions in the table below.
Segment Definition
Segment - Component
Revenue capture definition
Software
Includes telehealth platforms, mobile applications, cloud-based rehabilitation systems, AI-enabled therapy software, and remote patient monitoring solutions that facilitate virtual rehabilitation, patient engagement, and clinical data management.
Hardware
Comprises the physical devices required for telerehabilitation, including smartphones, tablets, computers, webcams, wearable sensors, motion-tracking systems, rehabilitation robots, and connected medical devices used for remote therapy delivery.
Segment - Service
Revenue capture definition
Physical Therapy
Focuses on restoring movement, strength, balance, and physical function through remotely supervised exercise programs and rehabilitation interventions for musculoskeletal, orthopedic, and post-surgical conditions.
Occupational Therapy
Helps patients regain the ability to perform daily living, self-care, and work-related activities through virtual interventions that improve motor, cognitive, and functional abilities.
Others
Includes speech and language therapy, cognitive rehabilitation, respiratory rehabilitation, psychological rehabilitation, and other specialized therapies delivered through telecommunication technologies.
Segment - Application
Revenue capture definition
Orthopedic
Covers telerehabilitation services for musculoskeletal injuries, fractures, arthritis, joint replacement recovery, sports injuries, and other orthopedic conditions requiring remote rehabilitation.
Cardiovascular
Includes remote cardiac rehabilitation programs focused on exercise training, lifestyle modification, patient education, and continuous monitoring following cardiovascular diseases or surgical procedures.
Neurology
Encompasses rehabilitation services for neurological disorders such as stroke, Parkinson's disease, multiple sclerosis, spinal cord injuries, and traumatic brain injuries through virtual therapy platforms.
Pediatric
Includes remote rehabilitation services designed for infants, children, and adolescents with developmental disorders, congenital conditions, neurological impairments, or physical disabilities.
Others
Covers rehabilitation for pulmonary disorders, oncology recovery, geriatric care, chronic pain management, vestibular disorders, and other specialized rehabilitation applications.
Segment - End Use
Revenue capture definition
Homecare Setting
Represents revenue from telerehabilitation services delivered directly to patients in their homes, enabling continuous therapy, remote monitoring, and improved accessibility with reduced travel requirements.
Healthcare Facilities
Includes hospitals, rehabilitation centers, outpatient clinics, specialty care centers, and long-term care facilities that deploy telerehabilitation platforms to extend rehabilitation services beyond conventional in-person care.
Estimation Model
Model Details
This research methodology outlines the process for estimating the size of the global telerehabilitation market for the period from 2021 to 2033. The study covers key market segments, including software, hardware, clinical therapy, clinical assessment, physical therapy, occupational therapy, orthopedic rehabilitation, cardiovascular rehabilitation, neurological rehabilitation, pediatric rehabilitation, homecare settings, and healthcare facilities across major geographic regions including North America, Europe, Asia Pacific, Latin America, and the Middle East & Africa.
The objective is to develop a strong and defensible market estimate through a combination of bottom-up and top-down approaches supported by primary industry validation.
A triangulated market sizing approach was used, combining:
-
Bottom-Up Analysis from the number of telerehabilitation consultations, virtual therapy sessions, software platform subscriptions, hardware deployments, healthcare provider adoption, and average revenue per session.
-
Top-Down Checks using digital health expenditure, rehabilitation service demand, prevalence of chronic diseases and disabilities, aging population, internet and smartphone penetration, telehealth adoption rates, and healthcare infrastructure.
-
Primary Research with telerehabilitation platform providers, hospitals, rehabilitation centers, physiotherapists, occupational therapists, healthcare IT vendors, payers, healthcare administrators, and industry experts.
Step-by-Step Market Estimation Process
Telerehabilitation Service Utilization Model
This model estimates market size by evaluating the number of patients utilizing remote rehabilitation services and the associated annual spending.
Step 1: Country-level data for telerehabilitation utilization, rehabilitation patient populations, prevalence of chronic diseases and disabilities, digital health adoption, and internet accessibility for 2021–2025 was collected from government agencies, healthcare organizations, telehealth associations, public health databases, and company reports.
Step 2: Telerehabilitation utilization rates were applied to estimate the percentage of rehabilitation patients receiving virtual care annually. Utilization rates were derived from healthcare surveys, telehealth registries, reimbursement databases, published clinical studies, and primary interviews.
Step 3: Average annual spending per telerehabilitation patient was estimated using consultation fees, therapy session charges, software subscription costs, reimbursement rates, provider billing data, and platform pricing.
Step 4: Market size was calculated by multiplying:
Number of Telerehabilitation Patients × Average Annual Spending per Patient
Step 5: Calculations were performed at the country level and subsequently aggregated to regional and global levels.
Step 6: Historical and forecast growth rates were incorporated based on increasing telehealth adoption, rising chronic disease prevalence, aging populations, improving broadband connectivity, favorable reimbursement policies, and growing acceptance of remote rehabilitation.
Telerehabilitation Platform Revenue Extrapolation Model
This model estimates market size using revenues generated by telerehabilitation solution providers and healthcare organizations offering virtual rehabilitation services.
Step 1: The number of active telerehabilitation software providers, hospitals offering virtual rehabilitation, rehabilitation clinics, outpatient therapy centers, home healthcare providers, and digital health platforms by country was identified through healthcare registries, company disclosures, industry associations, and proprietary databases.
Step 2: Average annual revenue per provider/platform was estimated using company financial reports, subscription pricing, licensing models, provider interviews, reimbursement data, and market intelligence.
Step 3: Revenues were adjusted for regional differences in software pricing, reimbursement structures, patient volumes, deployment models (cloud/on-premise), and healthcare spending.
Step 4: Country-level market size was calculated by multiplying:
Number of Telerehabilitation Providers/Platforms × Adjusted Average Annual Revenue per Provider
Step 5: Regional and global market values were generated through aggregation of country-level estimates.
Step 6: Annual adjustments were incorporated to reflect increasing software adoption, AI integration, wearable device utilization, expansion of remote monitoring services, regulatory support, and investments in digital healthcare infrastructure.
Virtual Therapy Session Volume and Pricing Model
This model estimates market size based on the volume of virtual rehabilitation services delivered and average pricing across therapy categories.
Step 1: Virtual therapy session volume data was collected from hospitals, rehabilitation centers, telehealth platforms, outpatient clinics, healthcare databases, industry publications, and primary interviews.
Step 2: Services were categorized into:
-
Physical Therapy
-
Occupational Therapy
-
Clinical Assessment
-
Orthopedic Rehabilitation
-
Cardiovascular Rehabilitation
-
Neurological Rehabilitation
-
Pediatric Rehabilitation
-
Other Telerehabilitation Services
Step 3: Average pricing per virtual consultation, therapy session, remote assessment, and rehabilitation program was established using provider pricing data, reimbursement schedules, telehealth claims databases, and expert interviews.
Step 4: Revenue generated by each service category was calculated by multiplying:
Number of Virtual Therapy Sessions/Programs × Average Revenue per Session/Program
Step 5: Category-level revenues were aggregated to determine country, regional, and global market sizes.
Step 6: Forecast assumptions incorporated increasing demand for home-based rehabilitation, technological advancements such as AI-powered rehabilitation platforms, wearable sensors, motion tracking, virtual reality (VR), remote patient monitoring, and expanding reimbursement coverage for telehealth services.
Software and Hardware Adoption Model
This model estimates market size based on the adoption of telerehabilitation software platforms and supporting hardware solutions.
Step 1: Data on deployments of telerehabilitation software, remote monitoring systems, wearable rehabilitation devices, motion capture technologies, tablets, smartphones, and connected rehabilitation equipment collected across healthcare facilities and homecare settings.
Step 2: Adoption rates were analyzed across hospitals, rehabilitation centers, outpatient clinics, and homecare providers based on digital maturity and telehealth implementation.
Step 3: Average software licensing revenue, subscription fees, hardware pricing, maintenance contracts, and implementation services were estimated through company reports and industry benchmarking.
Step 4: Revenue was calculated by multiplying:
Number of Software/Hardware Deployments × Average Revenue per Deployment
Step 5: Country-level estimates were aggregated into regional and global market values.
Step 6: Forecast assumptions considered increasing cloud adoption, interoperability improvements, AI integration, cybersecurity investments, and growing demand for connected rehabilitation ecosystems.
Market Validation and Forecasting
The estimates derived from the telerehabilitation service utilization model, platform revenue extrapolation model, virtual therapy session volume and pricing model, and software and hardware adoption model were cross validated using data triangulation.
The findings were further verified through primary interviews with telerehabilitation platform providers, rehabilitation specialists, physiotherapists, occupational therapists, hospitals, digital health companies, healthcare administrators, insurers, payers, and industry experts.
Final market forecasts were developed by evaluating digital health adoption trends, healthcare expenditure growth, aging demographics, prevalence of chronic diseases and disabilities, expansion of home healthcare, reimbursement developments, regulatory support for telehealth, broadband infrastructure improvements, and continued technological advancements in AI, wearable devices, virtual reality, and remote patient monitoring that are shaping the global telerehabilitation market.
Delivered Customizations
This report has been delivered with the following In-depth customizations
Client Request
Customization Delivered
Value Adds
Telerehabilitation Adoption & Patient Engagement Analysis
Conducted a patient-centric assessment of virtual rehabilitation journeys from referral and onboarding through therapy completion and follow-up. Evaluated patient engagement, therapy adherence, platform utilization, dropout rates, satisfaction levels, and clinical outcomes across home-based rehabilitation programs.
Provides actionable insights to improve patient retention, optimize virtual care pathways, enhance therapy adherence, reduce patient attrition, and improve overall telerehabilitation effectiveness.
Telerehabilitation Platform Pricing & Reimbursement Benchmarking Study
Evaluated platform subscription models, virtual therapy pricing, reimbursement policies, payer coverage, licensing strategies, and regional pricing variations across software, hardware, and telehealth-enabled rehabilitation services.
Supports pricing optimization, reimbursement strategy development, competitive benchmarking, profitability analysis, payer negotiations, and market expansion planning.
Digital Rehabilitation Outcomes & Value-Based Care Assessment
Assessed remote patient monitoring metrics, digital therapy outcomes, patient-reported outcome measures (PROMs), value-based reimbursement models, clinician productivity, and quality performance indicators across telerehabilitation programs.
Helps stakeholders demonstrate clinical and economic value, improve patient outcomes, strengthen payer relationships, support value-based care initiatives, and enhance competitive positioning in the telerehabilitation market.
Frequently Asked Questions About This Report
The clinical therapy segment dominated the market with the largest revenue share in 2025 and is anticipated to witness the fastest CAGR growth over the forecast period.
The physical therapy segment dominated the market with a revenue share of 42.9% in 2025
The orthopedic segment dominated the market with a share of 31.8% in 2025 and is anticipated to witness the fastest CAGR growth over the forecast period
The homecare setting segment dominated the market with the largest revenue share in 2025 and is anticipated to witness the fastest CAGR growth over the forecast period.
The global telerehabilitation market was valued at USD 4.0 billion in 2025 and is estimated at USD 4.9 billion in 2026.
The global telerehabilitation market is expected to grow at a compound annual growth rate (CAGR) of 18.5% from 2026 to 2033 to reach USD 16.0 billion by 2033.
The software segment dominated the market with the largest revenue share in 2025. The adoption of various software has significantly increased owing to the assistance provided to healthcare systems. In addition, the software helps to achieve greater engagement and improves the outcomes.
Increased instances of various disorders such as traumatic brain injury, cerebrovascular accidents, and developmental delays in the pediatric population are some of the factors expected to increase the demand for telerehabilitation services globally.
Some of the key market players of telerehabilitation market include American Well, Doctor On Demand, Inc., Koninklijke Philips N.V, Hinge Health, Inc., Cisco Systems, Inc., NeoRehab, C3O TelemedicineTM , Bosch Healthcare Solutions GmbH, Physio Cloud Software, Ludica Health Inc. (Jintronix.com).
About the Author(s)
Healthcare IT Research Team
Healthcare · Healthcare ITThis report was authored by the healthcare it research team at Grand View Research - comprising two research analysts, one senior research analyst, and one industry expert - with specialized expertise in the healthcare it segment of the healthcare industry. All findings are based on proprietary healthcare databases, executive interviews, and regulatory analysis, subject to internal peer review prior to publication.
Last Updated:
Speak to Analyst

Customize this report to your needs - add regions, segments, or data points, with 20% free customization.
Or view our licence options:


ISO 9001:2015 & 27001:2022 Certified
We are GDPR and CCPA compliant! Your transaction & personal information is safe and secure. For more details, please read our privacy policy.


