
- Home
- »
- Clinical Diagnostics
- »
-
Thrombosis & Hemostasis Biomarkers Market Report, 2033GVR Report cover

Thrombosis And Hemostasis Biomarkers Market (2026 - 2033)
Size, Share & Trends Analysis Report By Product (Analyzers, Reagents & Consumables), By Test Location, By Test Type, By Application, By End Use, By Region, And Segment Forecasts
Market Size, 2025
$5.8BMarket Estimate, 2026
$6.2BMarket Forecast, 2033
$9.9BCAGR, 2026–2033
6.9%Thrombosis & Hemostasis Biomarkers Market Summary
The global thrombosis and hemostasis biomarkers market size was valued at USD 5.8 billion in 2025 and is projected to grow from USD 6.2 billion in 2026 to USD 9.9 billion by 2033, at a CAGR of 6.9% from 2026 to 2033. North America dominated the market, accounting for a revenue share of 37.0% in 2025. The market growth is attributable to the increasing prevalence of chronic diseases such as pancreatic cancer, the expanding base of the geriatric population, the growing demand for personalized medicines, and overall advancements in technology.
Key Market Trends & Insights
- By product: The reagents & consumables segment held the largest market share of approximately 65.5% in 2025.
- By test location: The clinical laboratory test segment held the largest market share of over 62.0% in 2025.
- By test type: The post-thrombin (PT) test segment held the largest market share of over 17.5% in 2025.
- By application: The deep vein thrombosis (DVT) segment held the largest market share of over 40.5% in 2025.
- By end-use: The diagnostic centers segment held the largest market share of approximately 44.5% in 2025.
Regional Highlights
- Largest regional market: North America (37.0% revenue share, 2025)
- Fastest-growing regional market: Asia Pacific (Highest CAGR, 2026-2033)
Market Size & Forecast
- Market size in 2025: USD 5.8 Billion
- Estimated market size in 2026: USD 6.2 Billion
- Projected market size by 2033: USD 9.9 Billion
- CAGR (2026-2033): 6.9%
Prism AI by Grand View Research Free to tryAsk a question about the thrombosis and hemostasis biomarkers marketTry asking✓Every figure cited from GVR research Prefer the report? Download free sample →
These biomarkers are very vital for the diagnosis of coagulation disorders, thrombotic events, and clinical decision making for diseases such as deep vein thrombosis, stroke, and pulmonary embolism. The rise in the recognition of preventive medicine and the use of more sophisticated diagnostic devices will drive growth within the market.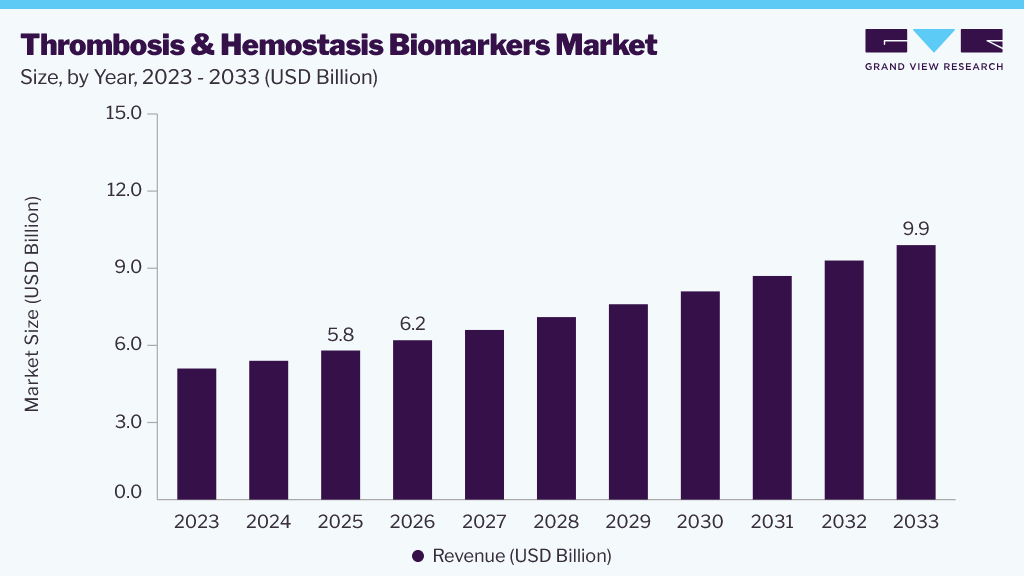 Source: Grand View Research, IR Documents, Primary Interviews, Paid DatabasesTo learn more about this report,
 Download Free Sample Report
In July 2025, the WHO highlighted cardiovascular diseases as the leading cause of global mortality, including complications linked to thrombosis such as stroke and pulmonary embolism. It emphasizes the pressing need for early screening and ongoing risk assessment, and will lead to increased use of coagulation and thrombosis biomarkers in medical diagnosis. The increased focus on early detection has boosted the demand for biomarker testing globally.
The increasing demand for personalized medicines is projected to drive the thrombosis and hemostasis biomarkers industry. The biomarkers allow healthcare providers to develop personalized treatment plans that are more effective and safer for every individual. Personalized medicines work on the principle of tailoring medical treatment to individuals with unique genetic makeup and medical history; thereby, thrombosis and hemostasis biomarkers help identify patients at increased risk of blood clots.
Building on the promise of biomarkers and personalized medicine, the British Heart Foundation has funded research in the area to transform heart treatments. According to its publication, new funding in personalized medicine can transform heart treatment in 4 key ways. These include creating digital hearts to predict treatment success, designing personalized pacemakers, preventing heart attacks & strokes with personalized medicine, and predicting the impact of chemotherapy on the heart.
Novel technologies are being built to curate more sensitive and specific biomarkers that can detect small changes in the clotting and hemostasis systems. For instance, mass spectrometry and other high-throughput proteomics technologies have evolved, allowing to identify new, previously undetectable biomarkers.
New technologies are enabling the development of more sensitive and specific biomarkers that can detect small changes in the clotting & hemostasis systems. For instance, the use of mass spectrometry and other high-throughput proteomics technologies has led to the identification of previously undetectable biomarkers, providing more comprehensive information about a patient's clotting and hemostasis status.
Analyst Perspective
The thrombosis and hemostasis biomarkers industry is experiencing steady growth, driven by the increasing prevalence of cardiovascular disorders, rising incidence of clotting abnormalities, and growing demand for early and accurate diagnostic tools. There is increased adoption of the use of biomarker tests among healthcare professionals, as it allows them to assess the risk and make timely interventions to help patients suffering from ailments such as deep vein thrombosis, pulmonary embolism, and stroke. Increased adoption of personalized medicine, along with advances in molecular diagnostics and lab technology, is expected to help market growth.
In addition, increasing clinical research activities and the development of novel biomarker panels are improving diagnostic precision and reliability. With continued demand for faster, less invasive, and highly sensitive diagnostic solutions, organizations that can deliver innovations, develop assays, and conduct clinical validation are poised for significant opportunities in the future.
Product Insights
The reagents & consumables segment led the market with the largest revenue share of approximately 65.5% in 2025. The dominant segment share can be attributed to the growing prevalence of bleeding and coagulation disorders, high demand for diagnostic tools, and new product launches. The dominant segment share can be attributed to the growing prevalence of bleeding and coagulation disorders, high demand for diagnostic tools, and new product launches.
The increasing adoption of thrombosis and hemostasis biomarker assays in clinical diagnostics is contributing to the high demand for reagents and consumables. In addition, advancements in the field of biomarker assays and the increasing need for fast, efficient, and less invasive diagnosis solutions are likely to contribute to future market growth. The expansion of hospital and laboratory facilities in emerging countries is contributing to increased use of consumables in diagnostic processes.
The analyzer segment is expected to grow at the fastest CAGR over the forecast period. The segment’s growth can be attributed to the increasing prevalence of bleeding disorders and coagulation disorders, and technological advancements in diagnostic tools. Advancements in this area continue to make way in the industry. The use of advanced technology in automated and high-throughput analyzers is enabling more efficiency in the process of diagnosis in laboratories.
In addition, the increasing demand for fast and accurate test results is driving the use of analyzer systems. Furthermore, continuous innovations in biomarker-based testing platforms are enhancing workflow integration in healthcare settings. The growing focus on early disease detection and personalized medicine is further driving the demand for analyzer systems in thrombosis and hemostasis diagnostics.
Test Location Insights
The clinical laboratory test segment led the market with the largest revenue share of over 62.0% in 2025. Clinical laboratory tests help identify abnormalities within the blood clotting process, determine the severity of the condition, and guide treatment decisions. Moreover, the increasing investment in healthcare infrastructure, particularly in emerging economies, is also driving the growth of the clinical laboratory tests segment.
Furthermore, the increasing prevalence of cardiovascular and thrombotic disorders is also contributing to the demand for regular coagulation testing. In addition, advancements in laboratory automation and high-throughput testing technologies are improving diagnostic accuracy and turnaround time. Increasing awareness about the importance of early detection of diseases is promoting the use of laboratory testing.
The point-of-care tests segment is expected to grow at the fastest CAGR over the forecast period. Point-of-care test segment growth can be attributed to the convenience it offers healthcare providers, as POC tests deliver results within minutes.
POCT allows diagnostic tests to be performed in settings outside traditional clinical laboratory settings, such as doctors' offices, emergency rooms, or even in patients' homes, thereby driving the thrombosis and hemostasis biomarkers industry. In addition, the increasing demand for rapid decision-making in critical care and emergency situations is further accelerating the adoption of POCT solutions.
Test Type Insights
The post-thrombin (PT) segment led the market with the largest revenue share of over 17.5% in 2025. The test allows for monitoring the effectiveness of anticoagulant medications, such as warfarin, used to prevent blood clots. It is also utilized as a diagnostic tool to identify bleeding disorders or liver diseases. Blood plasma typically takes approximately 11 to 13.5 seconds to clot for individuals not taking blood-thinning medications. PT tests are often reported as an International Normalized Ratio (INR), which typically ranges from 0.9 to 1.1. For people with warfarin, the target INR range is usually between 2 and 3.5, which is higher than the normal range.
The fibrin/ fibrinogen segment is expected to grow at the fastest CAGR over the forecast period. The test is performed to manage and assess medical conditions such as blood clot formation, which include DVT, PE, and other thrombotic disorders. Furthermore, it is also useful in detecting deficiencies in fibrinogen levels, caused by genetic or hereditary factors. Different types of fibrinogen deficiencies include Afibrinogenemia, Hyperfibrinogenemia, and Dysfibrinogenemia. Afibrinogenemia is a rare disease affecting only 1 in every 1 million people and is characterized by a complete absence of fibrinogen in the blood.
Application Insights
The deep vein thrombosis segment led the market with the largest revenue share of approximately 40.5% in 2025. Deep vein thrombosis is a serious and underdiagnosed disease that involves the formation of a blood clot in a deep vein, most commonly in the pelvis, lower leg, thigh, or arm. DVT cases are estimated at 1-2 cases per 1,000 people annually. It affects people from all ethnicities, genders, and ages, but certain people remain at higher risk. This includes factors such as people with a history of blood clots, family history, obesity, cancer, and other chronic diseases.
The pulmonary embolism segment is expected to grow at the fastest CAGR over the forecast period. Pulmonary embolism is a disease caused by blood clots in the blood vessels in the lungs, which can also occur in other body parts, such as arms or legs. PE is one of the most common heart diseases, ranking only behind stroke and heart attack. For instance, in January 2023, according to the American Lung Association, PE affects nearly 900,000 people in the U.S. annually. Pulmonary embolism can be diagnosed via a D-dimer test, computed tomography angiogram, ultrasound, and V/Q scan. In addition, the increasing incidence of deep vein thrombosis (DVT) and related cardiovascular complications is further driving the demand for accurate diagnostic biomarkers. Furthermore, rising awareness regarding early detection and timely treatment of thrombotic conditions is supporting segment growth across healthcare settings.
End Use Insights
The diagnostic centers segment led the market with the largest revenue share of approximately 44.5% in 2025. The share can be attributed to hospitals' greater reliance on diagnostic laboratories for testing & evaluation, which further accelerates the segment's growth. Another major factor expected to drive segment growth is the increase in government initiatives to provide various facilities, such as compensation for diagnostic tests. Moreover, several healthcare institutions are working with laboratories to incorporate different clinical tests, such as thrombosis & hemostasis biomarker testing. For instance, in May 2023, Labcorp entered into a strategic agreement with Jefferson Health, under which the former will acquire the latter’s laboratory services outreach. In addition, with this strategic move, Jefferson will be able to expand its specialty lab testing.
The hospitals and clinics segment is expected to grow at the fastest CAGR over the forecast period. Constant changes in the healthcare industry have increased the need for hospitals with improved diagnostic services. The increase in healthcare spending globally has significantly contributed to the segment's growth. As hospitals collect and maintain data on disease frequency, regulatory bodies often collaborate with hospitals for disease surveillance. The need for hospitals with advanced facilities has increased with ongoing changes in the healthcare industry. The rise in the number of hospitals and diagnostic laboratories has also led to high growth in the segment.
Regional Insights
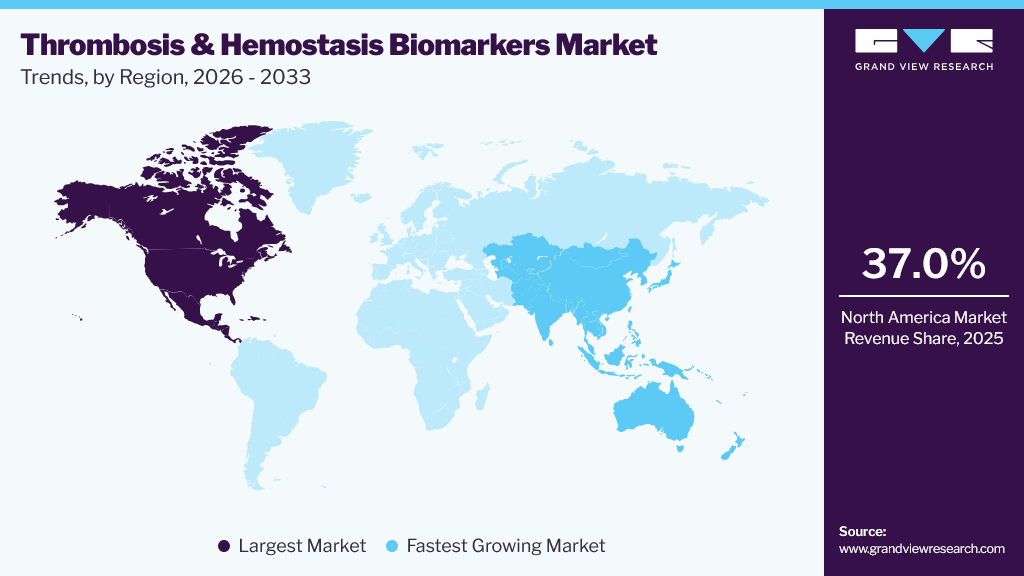
North America dominated the global thrombosis and hemostasis biomarkers market with the largest revenue share of approximately 37.0% in 2025. It can be attributed to an increasing prevalence of thrombosis and hemostasis disorders, advancements in technology, and consistent R&D efforts in thrombosis and hemostasis biomarkers, which are key factors driving the market in the region. The regional dominance is attributed to the high prevalence of thrombotic disorders, advanced healthcare infrastructure, strong presence of leading diagnostic companies, and continuous innovation in coagulation testing technologies. The increasing adoption of automated laboratory systems and biomarker-based diagnostic solutions is further supporting market growth in the region. For instance, in April 2024, Siemens Healthineers and Sysmex expanded their integrated hemostasis testing portfolio in North America, strengthening access to automated coagulation analyzers and laboratory workflow solutions. The partnership helps the laboratories test coagulation parameters, such as D-dimer, among others, that are associated with the process of hemostasis.
 To learn more about this report, Download Free Sample Report
Asia Pacific Thrombosis and Hemostasis Biomarkers Market
The thrombosis and hemostasis biomarkers market in the Asia Pacific is expected to grow at the fastest CAGR over the forecast period. The growth is attributed to the local presence of leading companies and increased R&D investment. In addition, the growing geriatric population susceptible to diseases and the rising prevalence of cardiovascular diseases and blood-clotting disorders are anticipated to propel the Asia Pacific regional market. For instance, in July 2024, a study published in The Lancet Regional Health – Western Pacific projected that the burden of cardiovascular disease across Asia will continue to rise substantially between 2025 and 2050 due to population growth, population aging, and increasing exposure to cardiovascular risk factors. The anticipated increase in ischemic heart disease, stroke, and other thrombotic conditions is expected to drive demand for early diagnosis and monitoring through thrombosis and hemostasis biomarkers such as D-dimer, coagulation factors, and platelet-related markers.
Key Thrombosis and Hemostasis Biomarkers Company Insights
The key players in the thrombosis & hemostasis biomarkers industry are continually developing and refining existing technologies to enhance patient outcomes and significantly improve the effectiveness and efficiency of healthcare.
Key Thrombosis and Hemostasis Biomarkers Companies
The following key companies have been profiled for this study on the global thrombosis and hemostasis biomarkers market:
-
bioMérieux SA
-
F. Hoffmann-La Roche Ltd.
-
Biomedica Diagnostics
-
Siemens Healthcare Private Limited
-
Abbott
-
HORIBA Ltd.
-
Werfen
-
Quidel Corporation
-
Diazyme Laboratories, Inc.
-
Thermo Fisher Scientific, Inc.
Recent Developments
-
In March 2025, Werfen commercially launched its flagship ACL TOP Family 70 Series Hemostasis Testing Systems and expanded innovation investments at its Bedford, Massachusetts, technology center. The launch strengthens Werfen’s hemostasis diagnostics portfolio by improving laboratory efficiency, standardization, and testing capacity for coagulation and thrombosis-related biomarkers.
-
In April 2024, Thermo Fisher Scientific entered a strategic distribution agreement with Bio-Techne to expand access to immunoassays, proteins, antibodies, enzymes, and diagnostic reagents across Europe. The collaboration enhances the availability of biomarker research and diagnostic tools that support cardiovascular, coagulation, and disease-monitoring applications.
Thrombosis And Hemostasis Biomarkers Market Report Scope
Report Attribute
Details
Market size in 2025
USD 5.8 billion
Estimated market size in 2026
USD 6.2 billion
Projected market size by 2033
USD 9.9 billion
Growth rate
CAGR of 6.9% from 2026 to 2033
Base year for estimation
2025
Historical data
2021 – 2024
Forecast period
2026 – 2033
Quantitative units
Revenue in USD million/billion, and CAGR from 2026 to 2033
Report coverage
Revenue forecast, company ranking, competitive landscape, growth factors, and trends
Segments covered
Product, test location, test type, application, end use, region
Regional scope
North America; Europe; Asia Pacific; Latin America; Middle East & Africa
Country scope
U.S.; Canada; Germany; UK; France; Italy; Spain; Denmark; Sweden; Norway; Rest of Europe; China; Japan; India; Australia; South Korea; Thailand; Brazil; Mexico; Argentina; South Africa; Saudi Arabia; UAE; Kuwait
Key companies profiled
bioMérieux SA; F. Hoffmann-La Roche Ltd.; Biomedica Diagnostics; Siemens Healthcare Private Limited; Abbott; HORIBA Ltd.; Werfen; Quidel Corporation; Diazyme Laboratories, Inc.; Thermo Fisher Scientific, Inc.
Customization scope
Free report customization (equivalent up to 8 analysts working days) with purchase. Addition or alteration to country, regional & segment scope.
Pricing and purchase options
Avail of customized purchase options to meet your exact research needs. Explore purchase options
Global Thrombosis And Hemostasis Biomarkers Market Report Segmentation
This report forecasts revenue growth at the global, regional, and country levels and provides an analysis of the latest industry trends and opportunities across each sub-segment from 2021 to 2033. For this study, Grand View Research has segmented the global thrombosis and hemostasis biomarkers market report by product, test location, test type, application, end-use, and region:
-
Product Outlook (Revenue, USD Billion, 2021 - 2033)
-
Analyzers
-
Reagents & Consumables
-
-
Test Location Outlook (Revenue, USD Billion, 2021 - 2033)
-
Clinical Laboratory Tests
-
Point-of-Care Tests
-
-
Test Type Outlook (Revenue, USD Billion, 2021 - 2033)
-
D-Dimer
-
Anti-Thrombin III
-
Plasminogen
-
Soluble Fibrin
-
Selectins
-
Factor VIII
-
PT
-
APTT
-
Fibrinogen
-
Others
-
-
Application Outlook (Revenue, USD Billion, 2021 - 2033)
-
Deep Vein Thrombosis (DVT)
-
Pulmonary Embolism (PE)
-
Disseminated Intravascular Coagulation (DIC)
-
Others
-
-
End Use Outlook (Revenue, USD Billion, 2021 - 2033)
-
Hospitals & Clinics
-
Academic & Research Institutes
-
Diagnostic Centers
-
Others
-
-
Regional Outlook (Revenue, USD Billion, 2021 - 2033)
-
North America
-
U.S.
-
Canada
-
-
Europe
-
UK
-
Germany
-
France
-
Italy
-
Spain
-
Denmark
-
Sweden
-
Norway
-
-
Asia Pacific
-
Japan
-
China
-
India
-
Australia
-
South Korea
-
Thailand
-
-
Latin America
-
Brazil
-
Mexico
-
Argentina
-
-
Middle East and Africa
-
South Africa
-
Saudi Arabia
-
UAE
-
Kuwait
-
-
Frequently Asked Questions About This Report
The global thrombosis and hemostasis biomarkers market size was valued at USD 5.8 billion in 2025 and is estimated at USD 6.2 billion for 2026.
The global thrombosis and hemostasis biomarkers market is expected to grow at a CAGR of 6.9% from 2026 to 2033, reaching USD 9.9 billion.
North America dominated with an approximately 37.0% revenue share in 2025.
The reagents & consumables segment accounted for the largest revenue share of approximately 65.5% in 2025.
Key players in the market include bioMérieux SA, F. Hoffmann-La Roche Ltd., Biomedica Diagnostics, Siemens Healthcare Private Limited, Abbott, HORIBA Ltd., Werfen, Quidel Corporation, Diazyme Laboratories, Inc., Thermo Fisher Scientific, Inc. and others.
About the Author(s)
Clinical Diagnostics Research Team
Healthcare · Clinical DiagnosticsThis report was authored by the clinical diagnostics research team at Grand View Research - comprising two research analysts, one senior research analyst, and one industry expert - with specialized expertise in the clinical diagnostics segment of the healthcare industry. All findings are based on proprietary healthcare databases, executive interviews, and regulatory analysis, subject to internal peer review prior to publication.
Last Updated:
Speak to Analyst

Customize this report to your needs - add regions, segments, or data points, with 20% free customization.
Or view our licence options:


ISO 9001:2015 & 27001:2022 Certified
We are GDPR and CCPA compliant! Your transaction & personal information is safe and secure. For more details, please read our privacy policy.


