
- Home
- »
- Medical Devices
- »
-
Tonometer Market Size, Growth Report, 2026-2033GVR Report cover

Tonometer Market (2026 - 2033)
Size, Share & Trends Analysis By Type (Applanation Tonometer, Rebound Tonometer), By Portability (Desktop, Handheld), By End Use (Hospitals), By Region, And Segment Forecasts
Market Size, 2025
$468.1MMarket Estimate, 2026
$497.2MMarket Forecast, 2033
$757.5MCAGR, 2026–2033
6.2%Tonometer Market Summary
The global tonometer market size was valued at USD 468.1 million in 2025 and is projected to grow from USD 497.2 million in 2026 to USD 757.5 million in 2033, at a CAGR of 6.2% from 2026 to 2033. North America dominated the market, accounting for a revenue share of 43.0% in 2025. This growth is attributable to the increasing incidence of glaucoma. Tonometers are used to diagnose and evaluate patients at risk of developing chronic eye conditions.
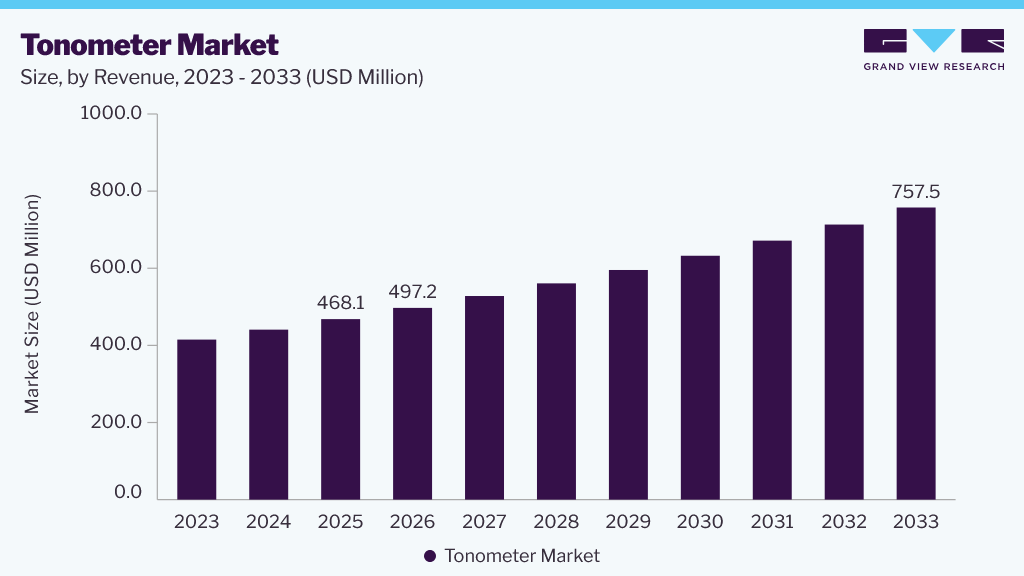 Source: Grand View Research, IR Documents, Primary Interviews, Paid DatabasesTo learn more about this report,
 Download Free Sample Report
Key Market Trends & Insights
- By type: The applanation tonometers segment held the largest market share of around 46.0% in 2025.
- By end use: The ophthalmic centers segment held the largest market share of over 56.0% in 2025.
- By portability: The handheld segment held the largest market share at around 57.0% in 2025.
Regional Highlights
- Largest regional market: North America (43.0% revenue share, 2025)
- Fastest-growing regional market: Europe (highest CAGR, 2026-2033)
Market Size & Forecast
- Market size in 2025: USD 468.1 Million
- Estimated market size in 2026: USD 497.2 Million
- Projected market size by 2033: USD 757.5 Million
- CAGR (2026-2033): 6.2%
Prism AI by Grand View Research Free to tryAsk a question about the tonometer market✓Every figure cited from GVR research Prefer the report? Download free sample →In addition, the rising geriatric population, coupled with the prevalence of diabetes, has significantly contributed to the market growth. Both geriatric and diabetic patients are more susceptible to eye-related disorders, including glaucoma. This has led to a surge in demand for tonometers, as regular IOP monitoring becomes crucial for preventing vision loss. Moreover, these devices are widely used in hospitals, eye clinics, and ophthalmic centers to assess patients’ eye health.
Furthermore, the market witnessed significant shifts owing to the heightened patient awareness about the benefits of regular IOP monitoring and early glaucoma diagnosis. Patients have increasingly recognized the importance of preventive measures to safeguard their vision. As a result, eye checkup camps and glaucoma screening programs have become more prevalent, encouraging people to seek timely evaluations.
Analyst Perspective
The global tonometer market is being driven by the rising prevalence of glaucoma, an aging population, and increasing emphasis on early diagnosis through routine intraocular pressure (IOP) monitoring. The growing adoption of handheld and rebound tonometers is improving accessibility to glaucoma screening across hospitals, ophthalmic centers, and community eye care settings due to their portability, ease of use, and patient comfort. Manufacturers are focusing on innovations such as calibration-free rebound tonometry, automated non-contact systems, and integrated ophthalmic diagnostic platforms to improve workflow efficiency and diagnostic accuracy. In addition, expanding glaucoma awareness campaigns, screening initiatives, and continued investments in ophthalmic diagnostic technologies are supporting long-term market growth.
Type Insights
By type, the applanation tonometers segment held the largest market share, at around 46.0% in 2025, due to their high accuracy and long-standing acceptance as the clinical standard for intraocular pressure (IOP) measurement. Goldmann applanation tonometers are widely used in hospitals and ophthalmic clinics because they provide reliable and repeatable measurements essential for glaucoma diagnosis and management. Their widespread availability, established clinical validation, and integration into routine ophthalmic examinations continue to support their dominance in the segment.
Rebound tonometers are projected to grow at the fastest CAGR during the forecast period owing to increasing demand for portable, anesthesia-free, and patient-friendly intraocular pressure (IOP) measurement devices across hospitals, ophthalmic centers, and community screening programs. Their ability to provide quick, accurate, and repeatable measurements without topical anesthesia or fluorescein makes them particularly suitable for pediatric, geriatric, and home healthcare settings. The growing emphasis on early glaucoma detection, expanding outreach eye care programs, and increasing adoption of point-of-care diagnostic devices are further supporting segment growth. Furthermore, manufacturers continue to introduce advanced rebound tonometers that enhance workflow efficiency and measurement consistency. For instance, in April 2025, iCare (Revenio Group) highlighted the development of the iCare ST500, the world's first slit lamp-mounted rebound tonometer designed to provide fast, calibration-free, anesthesia-free, and repeatable IOP measurements while improving clinical workflow efficiency.
End Use Insights
By end use, the ophthalmic centers segment held the largest market share, over 56.0%, in 2025, driven by the increasing prevalence of eye-related diseases, including glaucoma and ocular hypertension. These centers specialize in eye care; hence, they have actively participated in glaucoma screening programs and used tonometers to obtain accurate IOP measurements, emphasizing preventive measures. Regular IOP assessments using tonometers allowed the timely identification of patients at risk. By detecting elevated IOP early, these centers contributed to better management and reduced vision loss associated with glaucoma.
Hospitals are expected to grow substantially as the fastest CAGR during the forecast period. As primary care facilities, hospitals have actively participated in glaucoma screening programs, including increased adoption of tonometers. In addition, government initiatives have led to the implementation of schemes that encourage hospitals and clinics to adopt tonometers. Such financial incentives facilitated the integration of tonometry into routine eye examinations and glaucoma screenings within healthcare facilities.
Portability Insights
By portability, the handheld segment held the largest market share at around 57.0% in 2025 because it offers enhanced patient comfort. Despite their smaller size, they offer ease of use and precise IOP readings. Such portable devices are particularly valuable in busy clinical settings as they are ideal for routine IOP assessments. Their ergonomic design ensures patient comfort during examinations. Moreover, handheld devices such as rebound tonometers, the Perkins tonometer, and the Tono-Pen are commercially available. This caters to patients' growing awareness of the importance of early glaucoma diagnosis, thereby driving market growth.
Desktop tonometers are expected to see significant growth during the forecast period, driven by rising demand for high-precision ophthalmic diagnostic equipment in hospitals, specialty eye clinics, and comprehensive eye care centers. These systems provide reliable intraocular pressure measurements while supporting high patient throughput and standardized clinical assessments. The growing preference for integrated ophthalmic workstations that combine multiple diagnostic functions into a single platform is improving examination efficiency, reducing testing time, and optimizing clinical workflows. In addition, continuous product innovation and the commercialization of multifunctional ophthalmic diagnostic systems are supporting market expansion. For instance, in November 2025, Topcon Healthcare announced the U.S. FDA 510(k) clearance and commercial launch of the TRK-3 OMNIA, integrating objective refraction, keratometry, non-contact tonometry, and pachymetry into a single compact desktop platform for streamlined ophthalmic examinations
Regional Insights
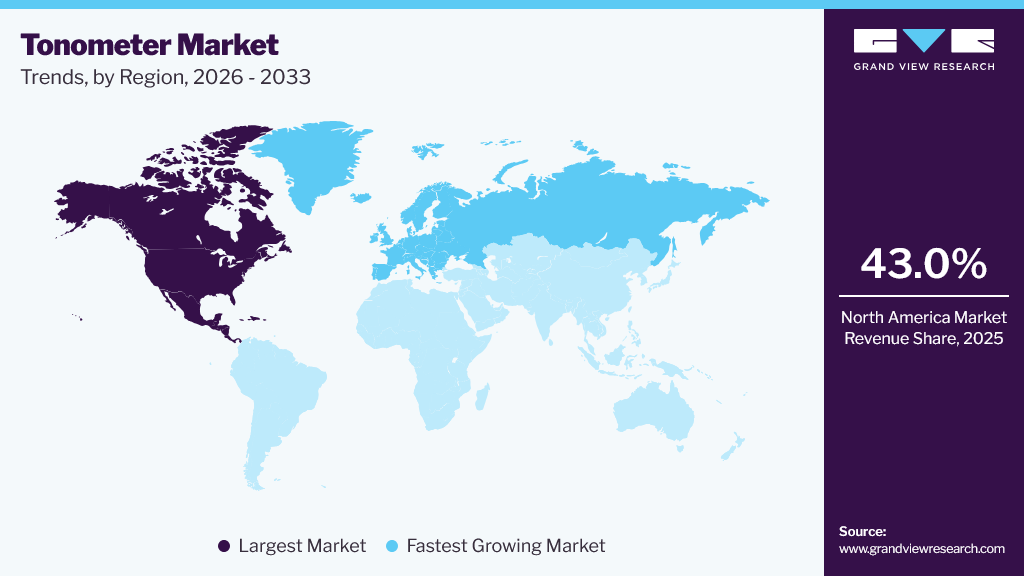
North America dominated the market with a revenue share of approximately 43.0% in 2025, owing to the high prevalence of glaucoma, well-established ophthalmic healthcare infrastructure, and widespread adoption of advanced diagnostic technologies. The presence of leading ophthalmic device manufacturers, favorable reimbursement policies, and increasing emphasis on preventive eye care have accelerated the adoption of next-generation tonometry systems across hospitals, ophthalmic centers, and ambulatory care facilities. Furthermore, continuous product innovation and the commercialization of advanced diagnostic devices are improving clinical workflow and expanding access to accurate intraocular pressure measurement. For instance, in May 2024, Reichert Technologies (AMETEK) expanded U.S. commercialization of its Tono-Vera Tonometer, featuring objective rebound tonometry technology and the patented ActiView Positioning System to improve the accuracy of intraocular pressure measurements and workflow efficiency.
 To learn more about this report, Download Free Sample Report
U.S. Tonometer Market Trends
The U.S. tonometer market was propelled by the rapidly increasing geriatric population. People aged 60 and above are at a higher risk of developing glaucoma, and this risk escalates each year after the age of 40. As a result, tonometers played a crucial role in assessing IOP and preventing vision loss with glaucoma. Moreover, ongoing technological innovations in the country have increasingly focused on enhancing tonometry devices.
Europe Tonometer Market Trends
The Europe tonometer market accounted for a significant market share in 2025 and is expected to grow at the significant CAGR during the forecast period, owing to the region's aging population, increasing prevalence of glaucoma, and well-developed ophthalmic healthcare infrastructure. Growing emphasis on early disease detection, routine eye examinations, and community-based vision screening programs is driving demand for accurate and portable tonometry devices across hospitals, specialty eye clinics, and primary healthcare settings. In addition, continuous product innovation and the availability of advanced ophthalmic diagnostic technologies are supporting the modernization of eye care services across the region. For instance, in December 2025, Haag-Streit UK relaunched the Perkins Mk3 hand-held applanation tonometer, expanding access to portable intraocular pressure measurement for pediatric, bedridden, wheelchair-bound, and community-based patients.
Asia Pacific Tonometer Market Trends
The Asia Pacific tonometer market accounted for a significant market share in 2025 owing to the rising prevalence of glaucoma, rapidly expanding geriatric population, and improving access to ophthalmic healthcare services across emerging economies. Growing investments in healthcare infrastructure, increasing awareness of preventive eye care, and expanding glaucoma screening initiatives are driving the adoption of advanced tonometry devices throughout hospitals, ophthalmic centers, and community healthcare facilities. Furthermore, rising healthcare expenditure, the expansion of specialty eye hospitals, and improving availability of advanced ophthalmic diagnostic technologies are supporting wider deployment of tonometers across the region. These factors continue to strengthen the Asia Pacific's position as an important market for ophthalmic diagnostic equipment.
Key Tonometer Company Insights
The tonometer market is moderately fragmented, with established manufacturers focusing on product innovation, strategic partnerships, regulatory approvals, geographic expansion, and acquisitions to strengthen their product portfolios and expand their presence across hospitals, ophthalmic centers, and community eye care settings.
Key Tonometer Companies
The following key companies have been profiled for this study on the tonometer market:
-
Keeler Ltd.
-
Topcon Corporation
-
Icare Finland Oy
-
AMETEK Inc.
-
Reichert, Inc.
-
OCULUS
-
Kowa American Corporation
-
NIDEK CO., LTD
-
Ziemer Ophthalmic Systems
Recent Developments
-
In March 2026, Haag-Streit USA introduced the Reliance Optometry Workplace in the U.S., integrating the AT 870 Goldmann applanation tonometer into a comprehensive examination lane solution. The launch strengthens the company's ophthalmic diagnostic portfolio by improving clinical workflow, examination efficiency, and access to accurate intraocular pressure measurement in optometry practices.
-
In August 2024, iCare, a subsidiary of Revenio Group, launched the iCare ST500, the world's first slit-lamp-mounted rebound tonometer. The device provides fast, calibration-free, anesthesia-free, and repeatable intraocular pressure measurements while improving examination efficiency, expanding the company's rebound tonometry portfolio for ophthalmic clinics and hospitals.
Tonometer Market Report Scope
Report Attribute
Details
Market size in 2025
USD 468.1 million
Estimated market size in 2026
USD 497.2 million
Projected market size by 2033
USD 757.5 million
Growth rate
CAGR of 6.2% from 2026 to 2033
Base year for estimation
2025
Historical data
2021 – 2024
Forecast period
2026 – 2033
Quantitative units
Revenue in USD million, and CAGR from 2026 to 2033
Report coverage
Revenue forecast, company ranking, competitive landscape, growth factors, and trends
Segments covered
Type, portability, end use, and region
Regional scope
North America; Europe; Asia Pacific; Central & South America; Middle East & Africa
Country scope
U.S.; Canada; Mexico; UK; Germany; France; Italy; Spain; China; India; Japan; Australia & New Zealand; South Korea; Brazil; Argentina; South Africa; UAE
Key companies profiled
Keeler Ltd.; Topcon Corporation; Icare Finland Oy; AMETEK Inc.; Reichert, Inc.; OCULUS; Kowa American Corporation; NIDEK CO., LTD; Ziemer Ophthalmic Systems
Customization scope
Free report customization (equivalent up to 8 analysts working days) with purchase. Addition or alteration to country, regional & segment scope.
Pricing and purchase options
Avail of customized purchase options to meet your exact research needs. Explore purchase options
Global Tonometer Market Report Segmentation
This report forecasts revenue growth at global, regional, and country levels and provides an analysis of the latest industry trends and opportunities in each of the sub-segments from 2021 to 2033. For this study, Grand View Research has segmented the global tonometer market report based on type, portability, end use, and region:
-
Type Outlook (Revenue, USD Million, 2021 - 2033)
-
Applanation Tonometer
-
Rebound Tonometer
-
Indentation Tonometer
-
Pascal Dynamic Contour Tonometer
-
-
Portability Outlook (Revenue, USD Million, 2021 - 2033)
-
Desktop
-
Handheld
-
-
End Use Outlook (Revenue, USD Million, 2021 - 2033)
-
Hospitals
-
Ophthalmic Centers
-
Others
-
-
Regional Outlook (Revenue, USD Million, 2021 - 2033)
-
North America
-
U.S.
-
Canada
-
Mexico
-
-
Europe
-
UK
-
Germany
-
France Italy
-
Spain
-
Denmark
-
Sweden
-
Norway
-
-
Asia Pacific
-
Japan
-
China
-
India
-
Australia
-
South Korea
-
Thailand
-
-
Latin America
-
Brazil
-
Argentina
-
-
Middle East and Africa (MEA)
-
South Africa
-
Saudi Arabia
-
UAE
-
Kuwait
-
-
Frequently Asked Questions About This Report
North America dominated with a 43.0% revenue share in 2025.
The global tonometer market size was valued at USD 468.1 million in 2025 and is estimated at USD 497.2 million for 2026.
The global tonometer market is expected to grow at a CAGR of 6.2% from 2026 to 2033, reaching USD 757.5 million.
Key players in the market include Keeler Ltd.; Topcon Corporation; Icare Finland Oy; AMETEK Inc.; Reichert, Inc.; OCULUS; Kowa American Corporation; NIDEK CO., LTD; Ziemer Ophthalmic Systems, and others.
The applanation tonometer segment accounted for the largest revenue share at around 46.0% in 2025.
About the Author(s)
Medical Devices Research Team
Healthcare · Medical DevicesThis report was authored by the medical devices research team at Grand View Research - comprising two research analysts, one senior research analyst, and one industry expert - with specialized expertise in the medical devices segment of the healthcare industry. All findings are based on proprietary healthcare databases, executive interviews, and regulatory analysis, subject to internal peer review prior to publication.
Last Updated:
Speak to Analyst

Customize this report to your needs - add regions, segments, or data points, with 20% free customization.
Or view our licence options:


ISO 9001:2015 & 27001:2022 Certified
We are GDPR and CCPA compliant! Your transaction & personal information is safe and secure. For more details, please read our privacy policy.


