
- Home
- »
- Pharmaceuticals
- »
-
Topical Drugs Market Size & Share Report, 2025-2030GVR Report cover

Topical Drugs Market (2026 - 2033)
Size, Share & Trends Analysis Report By Route Of Administration (Dermal, Ophthalmic, Rectal, Vaginal, Nasal), By Type (Semi-solid, Transdermal), By End-use (Home Care Settings, Hospitals & Clinics, Burn Centers), By Region, And Segment Forecasts
Market Size, 2025
$201.4BMarket Estimate, 2026
$213.0BMarket Forecast, 2033
$323.5BCAGR, 2026–2033
6.2%Topical Drugs Market Summary
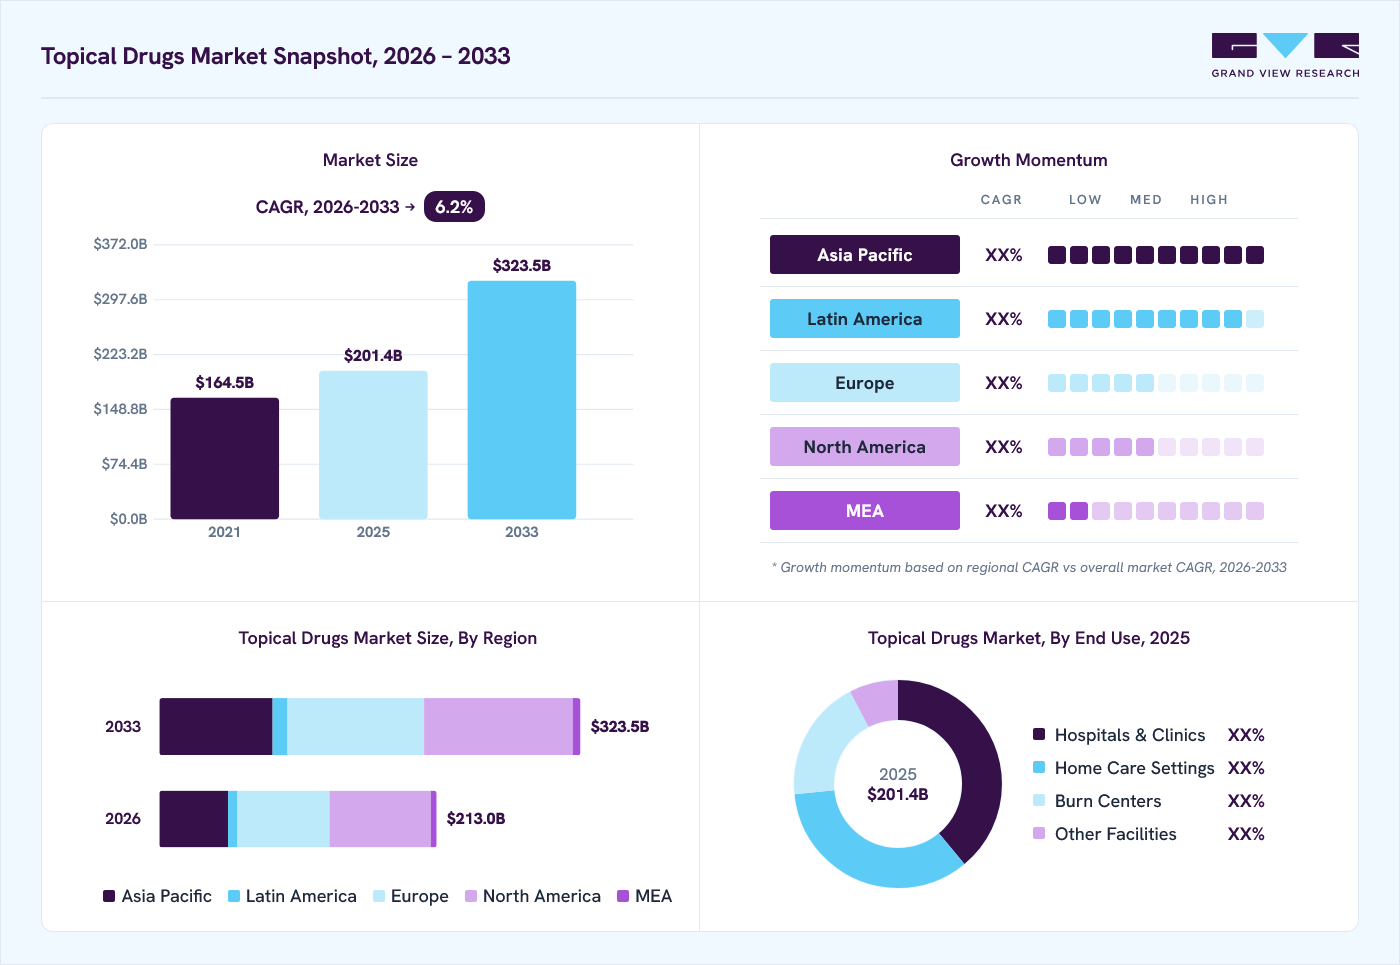
The global topical drugs market size was valued at USD 201.4 billion in 2025 and is projected to grow from USD 213.0 billion in 2026 to USD 323.5 billion by 2033, growing at a CAGR of 6.2% from 2026 to 2033. North America dominated the market, accounting for the largest global share of 36.7% in 2025. The market growth is increasingly influenced by the rising prevalence of skin conditions and chronic diseases globally.
 Source: Grand View Research, IR Documents, Primary Interviews, Paid DatabasesTo learn more about this report,
 Download Free Sample Report
Key Market Trends & Insights
- By type: Semi-solid formulations segment held the largest revenue share of 62.3% in 2025.
- By route of administration: Dermal drug delivery segment held the largest share of 54.2% in 2025.
- By end-use: Hospitals & clinics segment held the largest revenue share of 38.9% in 2025.
Regional Highlights
- Largest regional market: North America (36.7% revenue share, 2025)
- Fastest-growing regional market: Asia pacific (fastest CAGR, 2026-2033)
- By country: The U.S. held the largest share of North America in 2025.
Market Size & Forecast
- Market size in 2025: USD 201.4 Billion
- Estimated market size in 2026: USD 213.0 Billion
- Projected market size by 2033: USD 323.5 Billion
- CAGR (2026-2033): 6.2%
Three ways to get this report
Buy it, customize it, or ask a question.Ask an Analyst
Analyst response in 1 business day
- AccessReport author, directly
- Reply timeWithin 1 working day
- No sales callDirect answer only
- FormatEmail reply
- CostFree, no cost
Get the Full Report
What the study covers
- FormatsPDF · Excel · Dashboard
- Timeline2026–2033 annual, 2025 base
- Coverage20+ countries, 5 regions
- Companies10+ key players profiled
Customize the Report
20% free customization
- IncludeCountries, segments, points
- TailorTo your product definition
- ExtendDeeper competitor detail
- OrA fully bespoke study
- Turnaround5–10 working days
According to the American Academy of Dermatology Association, skin issues such as acne, along with eczema and psoriasis, affect approximately 50 million individuals in the U.S. annually. In India, surveys indicate that 41.7 per 1,000 people suffer from skin complaints, with allergies being the most common. Similarly, about 20% of adults in Germany experience chronic dermatological conditions, while in Saudi Arabia, 34% of respondents report diverse skin issues. This widespread incidence of skin disorders has catalyzed a growing demand for effective topical treatments, further invigorating the market.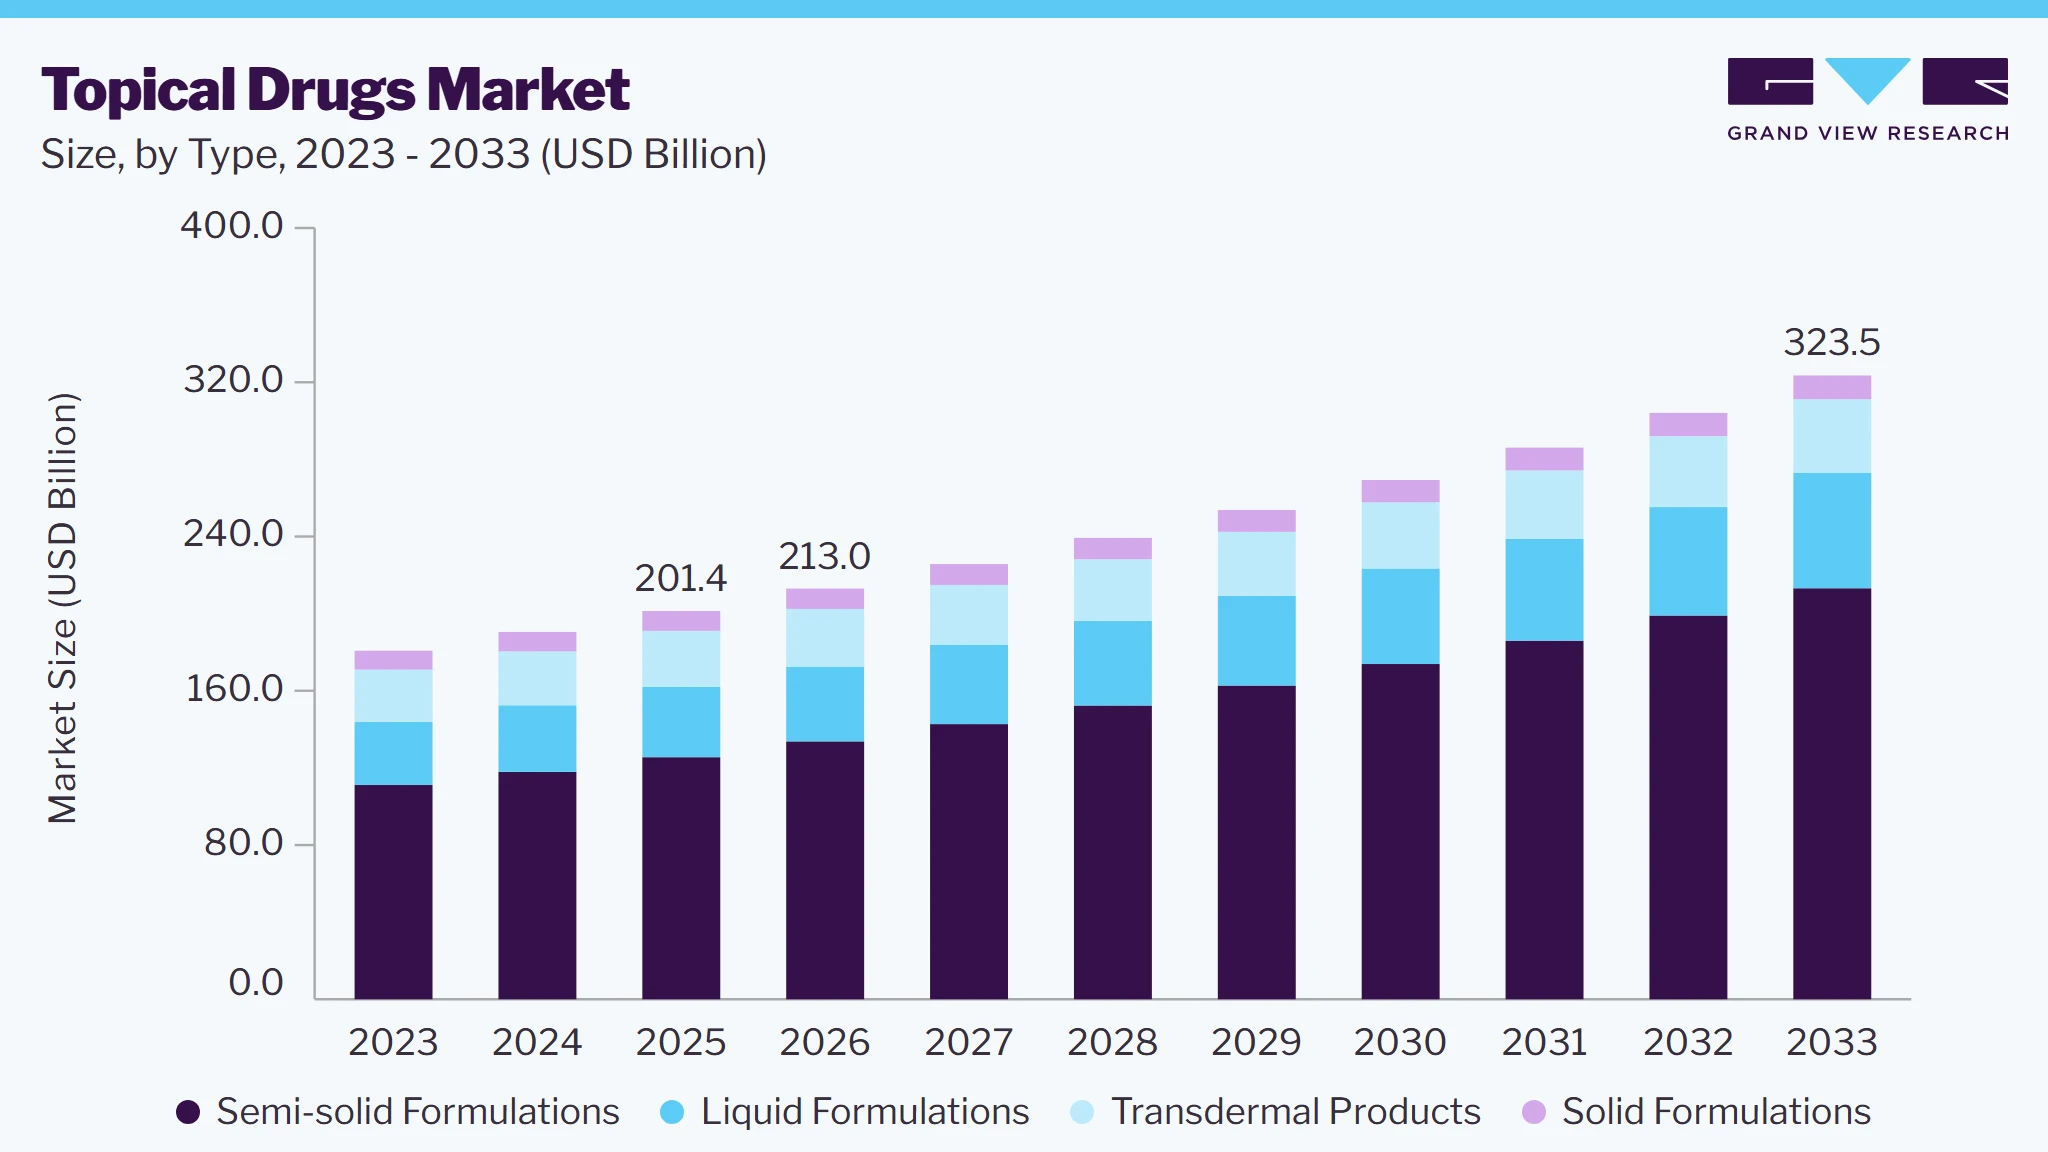 To learn more about this report, Download Free Sample Report
The increasing prevalence of diabetes also amplifies the need for topical solutions, particularly for managing skin complications associated with the disease. The International Diabetes Federation has forecasted that an estimated 643 million individuals worldwide are projected to have diabetes by 2030, highlighting the urgency for innovative management strategies. In markets such as Mexico, around 12 million people currently live with diabetes, necessitating effective dermatological care. As diabetes management becomes a critical public health concern, the demand for topical treatments that address conditions such as neuropathic pain and foot ulcers is set to grow, influencing the diabetes management market significantly.
Technological advancements in drug delivery systems are revolutionizing treatment efficacy and enhancing patient compliance in the topical drugs market. Innovations, including transdermal patches and nanotechnology, facilitate improved skin permeation and controlled drug release. The increasing consumer preference for non-invasive aesthetic treatments further supports this trend, with over 60% of patients in North America favoring topical therapies for their ease of use. This preference is echoed in emerging markets such as China and India, where healthcare reforms are streamlining access to innovative treatments, supporting the growth of the compounded topical drugs market that offers tailored formulations for diverse patient needs.
Regulatory reforms in India and China are crucial in bolstering the market landscape for topical drugs. For instance, in India, proposed amendments to the Drugs Rules, 1945, in July 2024 seek to enhance drug transparency and safety, while a recent waiver on clinical trials for specific drug categories expedites the introduction of innovative therapies. Likewise, China’s healthcare reforms, propelled by the National Healthcare Security Administration, allow for faster drug approvals and expanded health insurance coverage, enhancing access to essential medications. These initiatives are instrumental in ensuring that populations in both countries have access to advanced topical solutions for treating various skin disorders, thereby fueling the overall expansion of the topical drugs market.
Market Dynamics
The topical drugs market is supported by the increasing prevalence of dermatological disorders, rising demand for noninvasive treatment options, and growing adoption of targeted drug delivery systems. Topical formulations are widely used for the treatment of skin diseases, pain management, ophthalmic conditions, and infections due to their ability to deliver therapeutic effects directly to the affected site while minimizing systemic exposure. Market growth is further driven by advancements in formulation technologies that enhance drug absorption, efficacy, and patient compliance. The expanding geriatric population, increasing incidence of chronic wounds and burns, and greater consumer awareness regarding self-care treatments are contributing to sustained demand. In addition, the growing availability of over-the-counter products and the expansion of retail and online pharmacy channels are improving access to topical therapies across various regions. Pharmaceutical companies continue to focus on developing innovative formulations and transdermal delivery platforms to address unmet clinical needs. However, regulatory requirements, generic competition, and formulation complexity remain important factors influencing market development.
The topical drugs market is primarily driven by the increasing prevalence of dermatological disorders and the growing preference for localized treatment approaches. Conditions such as atopic dermatitis, psoriasis, acne, fungal infections, and chronic wounds continue to create substantial demand for topical formulations due to their ability to deliver therapeutic agents directly to the affected area while minimizing systemic exposure. Advancements in formulation technologies, increasing awareness of skin health, and the availability of targeted therapies are further supporting market growth. In addition, the expanding pediatric and geriatric populations are contributing to the adoption of topical treatments because of their favorable safety and convenience profiles. As healthcare providers increasingly emphasize patient adherence and noninvasive treatment options, the role of topical drugs across dermatology and related therapeutic areas continues to expand. For instance, in September 2025, Reuters reported that the U.S. FDA had approved Incyte's Opzelura (ruxolitinib) cream for pediatric patients aged 2 to 11 years with atopic dermatitis. The approval expanded the product's indication beyond patients aged 12 years and older. According to the report, atopic dermatitis affected approximately 2 million to 3 million children aged 2 to 11 years and more than 21 million individuals aged 12 years and older in the United States. The approval increased access to topical treatment options for a substantial patient population and reflected the growing demand for targeted dermatological therapies.
A major challenge affecting the topical drugs market is the complex regulatory framework governing product development and approval. Topical formulations require extensive evaluation of safety, efficacy, stability, skin permeation characteristics, and manufacturing consistency before receiving regulatory authorization. The development process is particularly demanding for semi solid formulations and advanced transdermal systems, where formulation variations can significantly influence therapeutic performance. Regulatory agencies continue to require comprehensive clinical evidence, product characterization data, and long term stability assessments, which can increase development timelines and costs. These requirements may delay commercialization and create barriers for smaller manufacturers seeking market entry. Furthermore, maintaining consistent product quality across large scale manufacturing operations remains a critical requirement throughout the product lifecycle. For instance, in February 2026, the U.S. FDA approved Adquey (difamilast) ointment 1% for the topical treatment of mild to moderate atopic dermatitis in adults and pediatric patients aged 2 years and older. The approval followed a comprehensive regulatory review process that included clinical efficacy assessments, manufacturing evaluations, labeling reviews, and pediatric study requirements. The FDA approval documentation specified a 36 month shelf life for 27 g and 85 g tubes and an 18 month shelf life for 3 g physician sample tubes. The extensive review process highlighted the regulatory complexity and development requirements associated with bringing new topical therapies to market.
The growing focus on dermatology innovation and inflammatory skin disease management presents a significant opportunity for the topical drugs market. Pharmaceutical companies are increasingly investing in novel therapeutic approaches that offer improved efficacy, longer treatment duration, and enhanced patient convenience. Advances in drug delivery technologies, coupled with a deeper understanding of inflammatory pathways, are enabling the development of more targeted treatments for chronic skin conditions. The increasing burden of atopic dermatitis, psoriasis, and other immune mediated skin disorders continues to encourage research activity and strategic collaborations across the industry. In addition, the expansion of clinical development programs and pipeline candidates is expected to broaden future treatment options and support market growth. For instance, in June 2026, Reuters reported that AbbVie had entered into an agreement to acquire Apogee Therapeutics to strengthen its immunology pipeline for inflammatory diseases including atopic dermatitis. The transaction included Apogee's lead candidate, zumilokibart, which was being evaluated with dosing intervals of every 3 months or every 6 months, compared with currently available therapies that often require administration every 2 weeks. The development highlighted increasing industry focus on innovative treatments for chronic inflammatory skin conditions and demonstrated continued investment in expanding therapeutic options for dermatology patients.
Analyst Perspective
The topical drugs market is characterized by a balance between multinational pharmaceutical companies with diversified product portfolios and specialized players focused on formulation innovation and drug delivery technologies. Established companies continue to leverage strong regulatory expertise, global distribution networks, and brand recognition to maintain market leadership, particularly in dermatology, ophthalmology, and pain management applications. Meanwhile, emerging and specialized manufacturers are gaining traction through differentiated topical formulations, transdermal systems, and cost competitive offerings. Future competition is expected to center on advanced drug delivery platforms, patient adherence improvements, lifecycle management strategies, and the development of targeted therapies for chronic and underserved conditions.
Route Of Administration Insights
Based on route of administration, the dermal drug delivery segment led the market with the largest revenue share of 54.2% in 2025, fueled by its capacity to offer targeted treatment, user-friendly application, and improved patient compliance. Patients increasingly favor non-invasive topical solutions over injections, contributing to the heightened adoption of these therapies for the effective management of skin disorders.
Ophthalmic drug delivery is expected to grow lucratively over the forecast period, owing to the growing prevalence of eye disorders, including glaucoma and age-related macular degeneration. Furthermore, advancements in drug delivery technologies improve therapeutic efficacy while reducing systemic side effects, rendering these treatments more attractive to patients. For instance, in April 2024, Eyenovia provided updates on Mydcombi and Clobetasol Propionate, reporting positive Phase IV results highlighting efficacy and tolerability, positioning these innovations favorably for topical ophthalmic drugs.
Type Insights
Based on type, the semi-solid formulations segment led the market with the largest revenue share of 62.3% in 2025 due to their versatility, ease of use, and effectiveness in delivering active ingredients directly to the skin. Formulations such as creams, gels, and ointments improve patient compliance and offer targeted treatment for various dermatological conditions.
Liquid formulations are expected to register significant growth over the forecast period. Liquid formulations, including solutions and suspensions, facilitate precise dosing and rapid skin absorption. Their non-invasive characteristics enhance patient compliance, making them highly effective for treating various dermatological conditions. Furthermore, advancements in formulation technologies improve product stability and efficacy.
End Use Insights
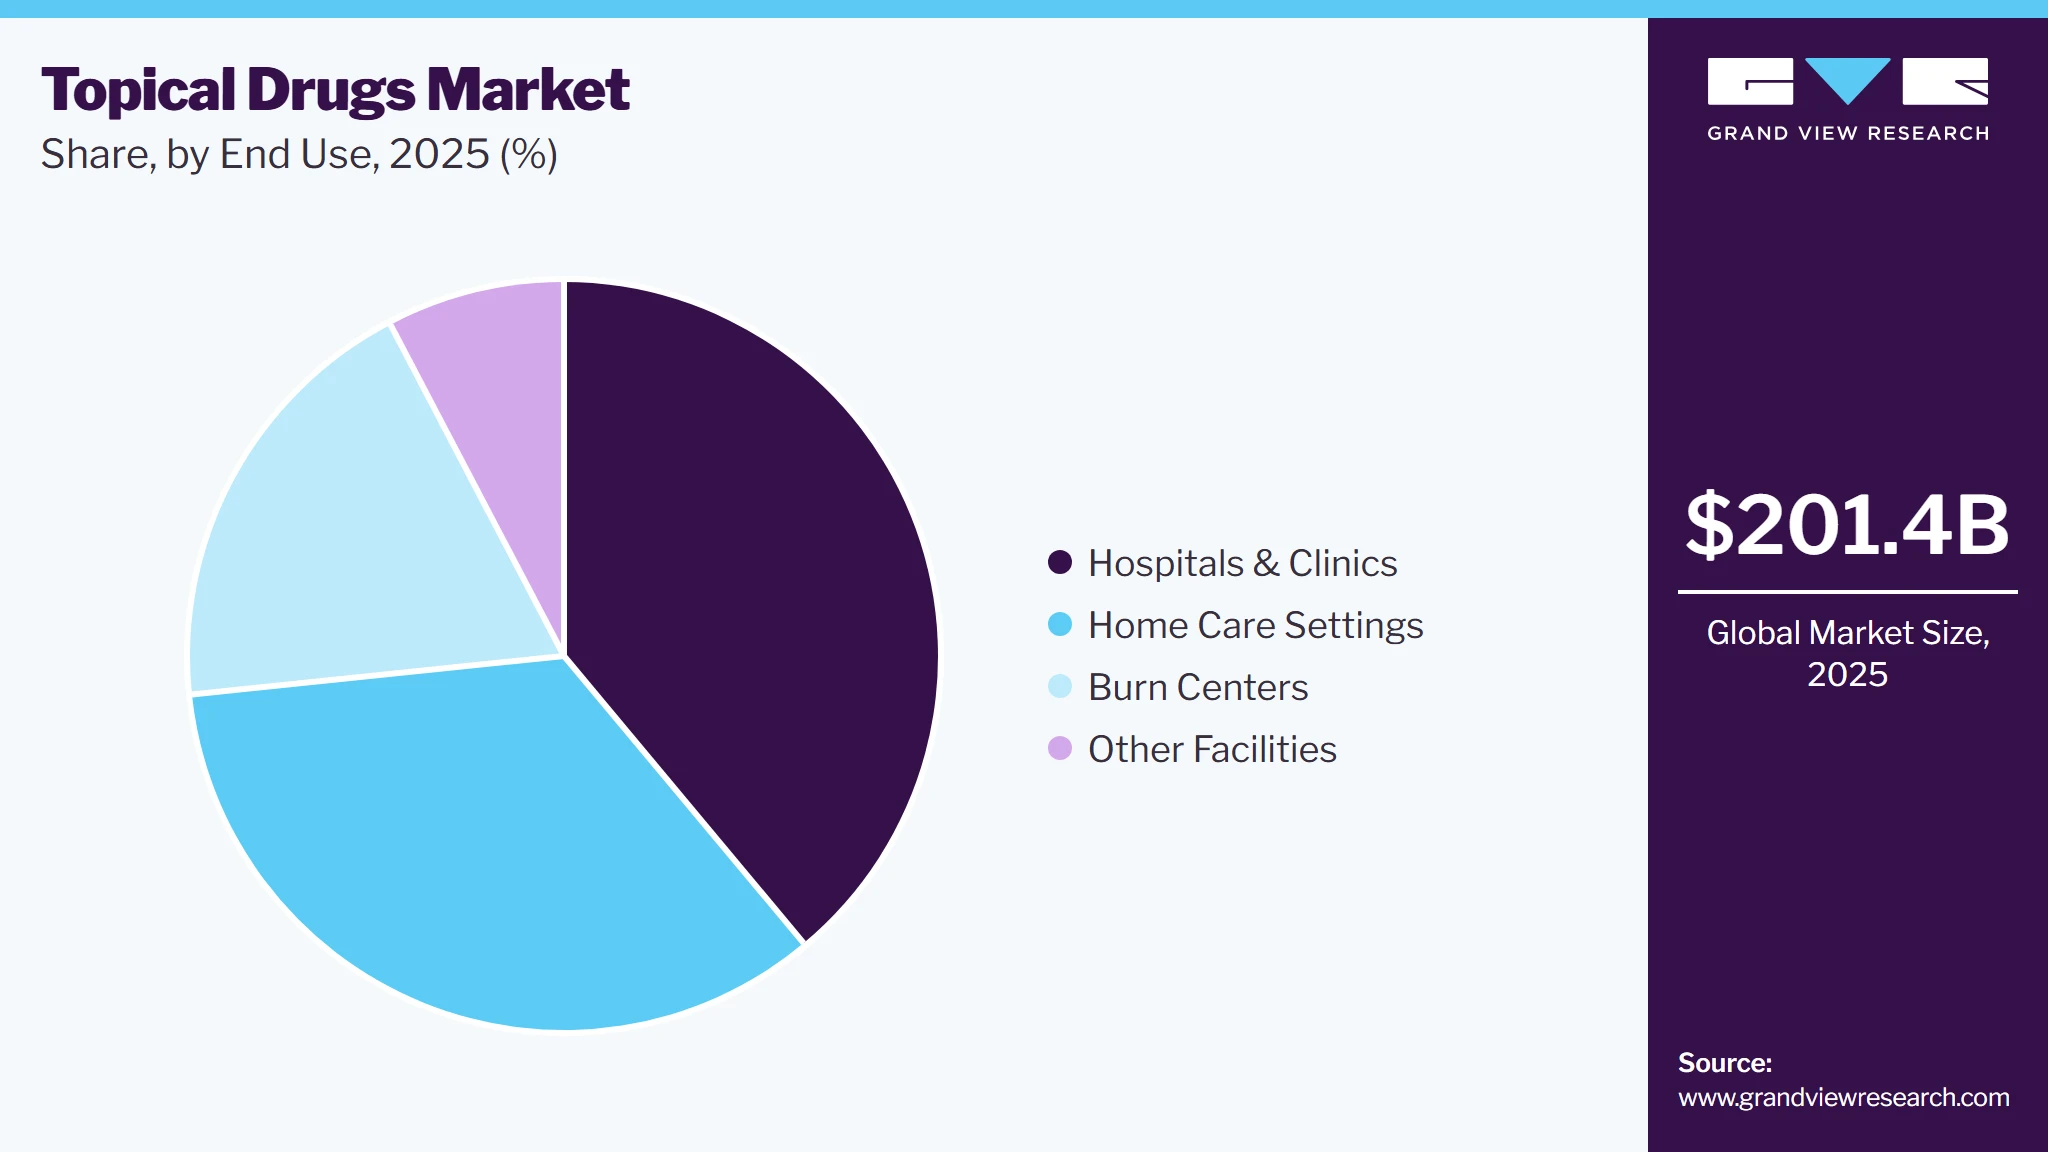
Based on end-use, the hospitals & clinics segment led the market with the largest revenue share of 38.9% in 2025, driven by the growing prevalence of skin disorders and chronic diseases necessitating professional intervention. These facilities offer specialized care, ensuring effective management of conditions through advanced topical therapies, which cultivates patient trust and promotes adherence to prescribed treatment regimens.
 To learn more about this report, Download Free Sample Report
Burn centers are projected to experience rapid growth over the forecast period. Burn centers are increasingly utilizing a diverse array of topical medications to enhance wound management and scar healing, as tailored treatments are essential for effective care. This trend is driven by advancements in burn care practices and an increased awareness of the significance of effective topical therapies in managing complex burn cases.
Regional Insights
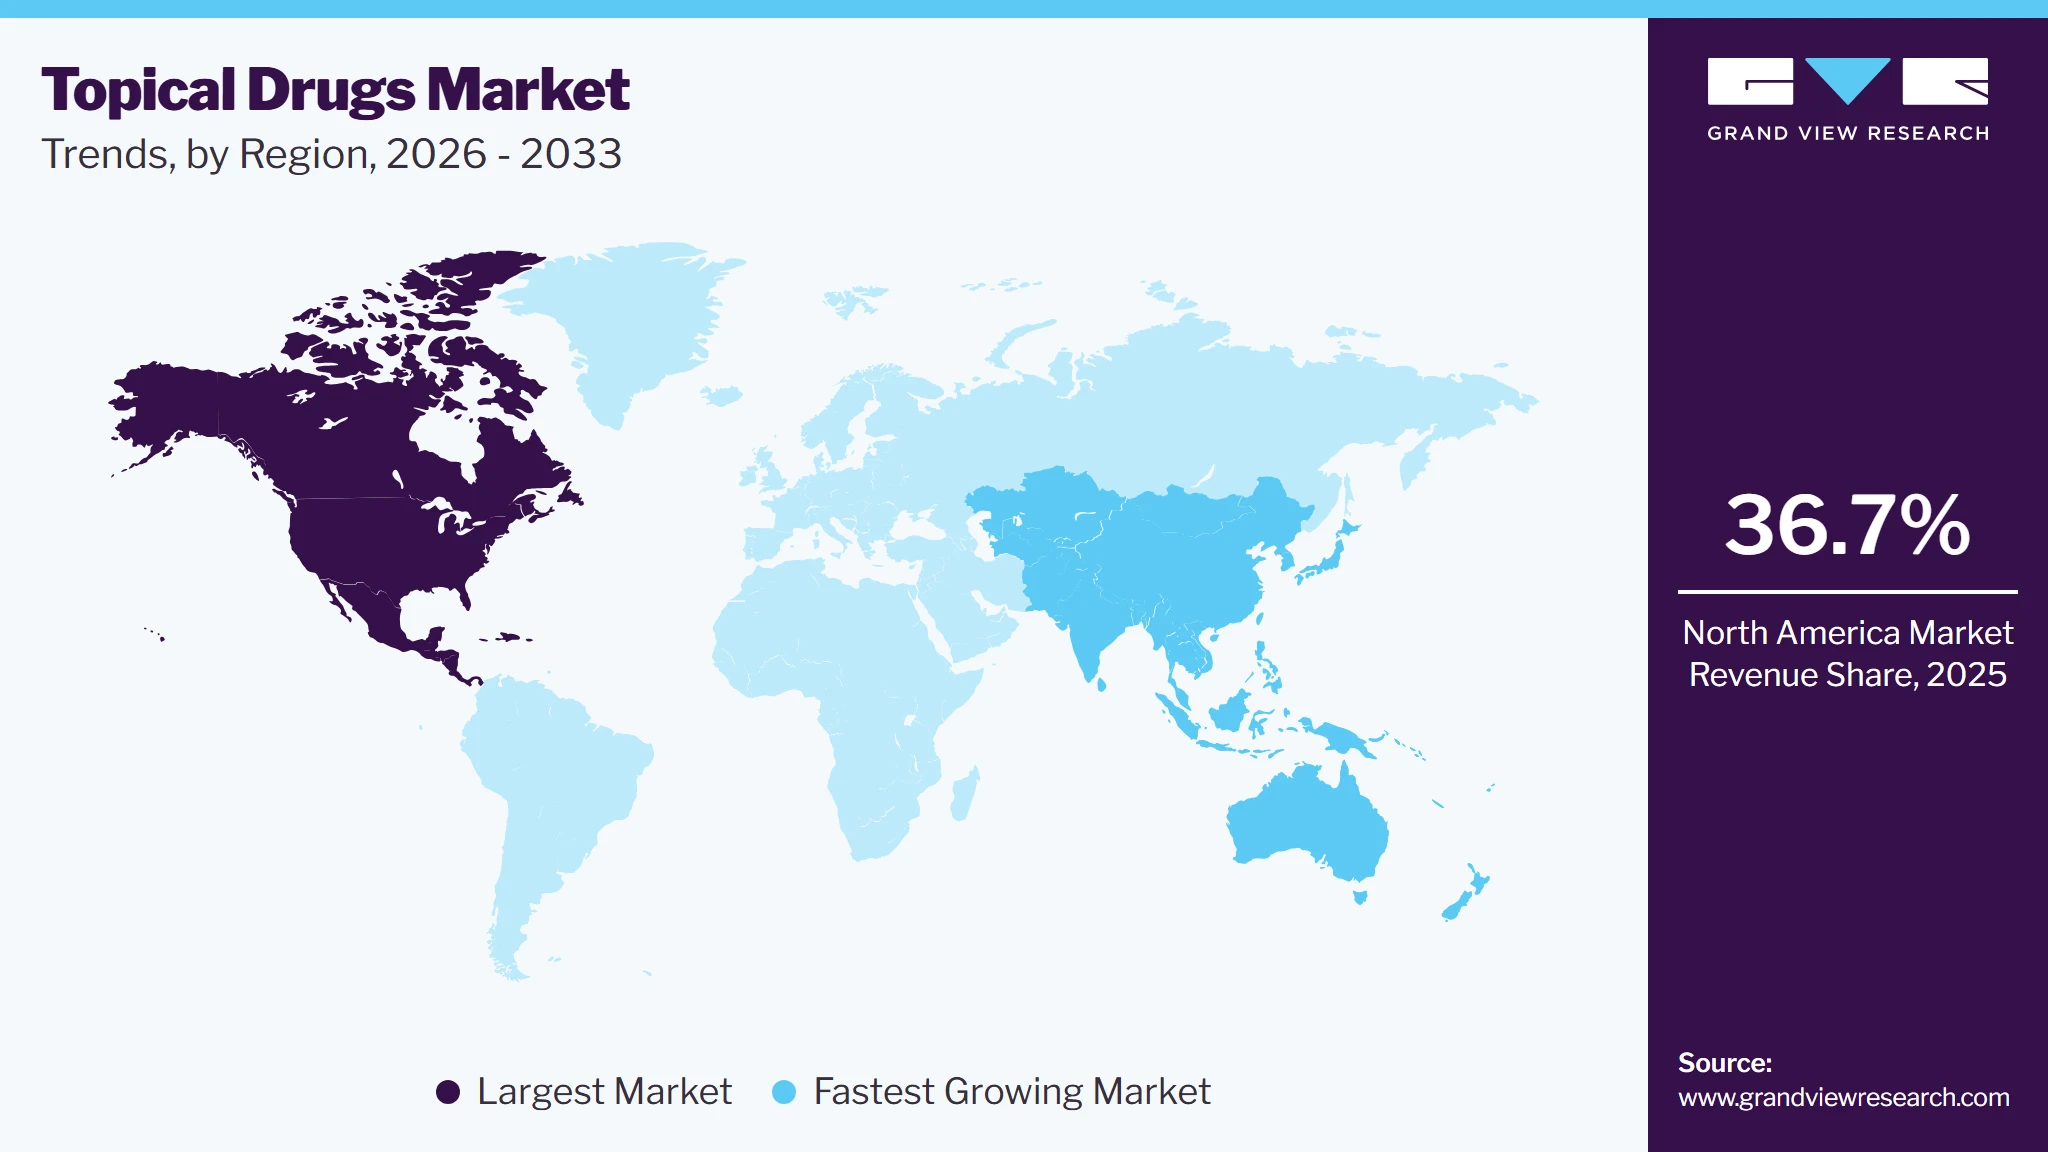
North America dominated the topical drugs market with the largest revenue share of 36.7% in 2025, driven by a high prevalence of skin disorders, advanced healthcare infrastructure, and robust investments in research and development. The presence of major pharmaceutical companies and a strong consumer emphasis on skincare bolster the region’s growth potential.
 To learn more about this report, Download Free Sample Report
U.S. Topical Drugs Market Trends
The topical drugs market in the U.S. held the largest share in the North America region in 2025. The U.S. boasts a sophisticated pharmaceutical industry, cutting-edge drug delivery technologies, and substantial healthcare expenditure. The presence of leading manufacturers and contract development organizations promotes research and development, while strong consumer demand for effective topical treatments stimulates market growth for a range of dermatological products.
Europe Topical Drugs Market Trends
Europe topical drugs market held a substantial market share in 2025, aided by heightened awareness of skin health, increasing dermatological conditions, and a rising demand for advanced therapies. For instance, in November 2024, Dupixent received EU approval as the first medicine for young children with eosinophilic esophagitis. Strong regulatory frameworks and a focus on innovation in drug formulations further enhance the region’s competitive edge in the global market.
The topical drugs market in Germany is expected to grow over the forecast period, supported by its robust healthcare system, substantial investments in pharmaceutical research and development, and a large patient population suffering from chronic skin conditions. In October 2024, Germany became the first country to launch LEO Pharma’s Anzupgo (delgocitinib) cream, specifically indicated for adults with moderate to severe Chronic Hand Eczema, following European Commission approval. The nation’s strong emphasis on quality control and regulatory compliance bolsters consumer trust and stimulates demand for effective topical therapies.
Asia Pacific Topical Drugs Market Trends
Asia Pacific topical drugs market is expected to register the fastest CAGR of 7.4% over the forecast period, driven by rising healthcare expenditures, a higher prevalence of skin disorders, and enhanced awareness of dermatological health. Moreover, rapid urbanization, improving healthcare infrastructure, and a growing middle-class population are further boosting demand for effective topical treatments in the region.
The topical drugs market in India is expected to register the fastest growth in the Asia Pacific market over the forecast period. India’s topical drugs market is experiencing significant growth, driven by its vast population suffering from skin diseases, improved healthcare accessibility, and rising disposable incomes. The government’s emphasis on enhancing healthcare infrastructure and regulatory reforms that expedite drug approvals present substantial opportunities for topical therapies. For instance, in November 2024, Clariant unveiled eight high-performing excipients at CPHI India 2024, thereby advancing its portfolio for effective pharmaceutical formulations.
Key Topical Drugs Company Insights
Some key companies operating in the market include Bayer AG, Cipla, GSK plc, Johnson & Johnson Services, Inc., and Novartis AG. The market is distinguished by notable innovation and strategic partnerships, with companies investing in advanced formulation technologies and personalized medicine to enhance product offerings and expand their geographical reach.
-
Bayer AG’s consumer health division provides diverse topical products for pain relief, skincare, and wound healing, prioritizing innovative formulations that enhance patient compliance and effectively address various dermatological conditions.
-
Bausch Health Companies Inc. focuses on topical pharmaceuticals in dermatology and ophthalmology. It offers both prescription and over-the-counter products for conditions such as acne and psoriasis, emphasizing innovation and efficacy in topical drug delivery solutions.
Key Topical Drugs Companies:
The following key companies have been profiled for this study on the topical drugs market.
- Bayer AG
- Cipla
- GSK plc
- Johnson & Johnson Services, Inc.
- Novartis AG
- Bausch Health Companies Inc.
- Hisamitsu Pharmaceuticals Co., Inc.
- Merck KGaA
- GLENMARK PHARMACEUTICALS LTD.
- MedPharm Ltd.
Competitive Benchmarking
Category
Operating Strategies
Competitive Edge
Weakness
Established Players (Bayer AG, GSK plc, Johnson & Johnson Services, Inc., Novartis AG, Merck KGaA, Bausch Health Companies Inc.)
- Focus on expanding topical drug portfolios through product innovation, lifecycle management, strategic acquisitions, and indication expansion across dermatology, ophthalmology, pain management, and infectious disease applications. Strengthen market presence through extensive clinical research, regulatory approvals, physician engagement programs, and broad distribution partnerships across hospital, retail, and online pharmacy channels.
- Strong global brand recognition and established credibility among healthcare professionals and patients. Extensive research and development capabilities, diversified product portfolios, robust manufacturing infrastructure, and broad commercial networks support large scale market penetration and regulatory compliance across multiple geographies.
- High research, development, and regulatory costs associated with novel topical formulations and transdermal technologies. Large organizational structures may result in longer product development timelines and slower response to emerging therapeutic trends and niche market opportunities.
Emerging and Specialized Players (Cipla, Hisamitsu Pharmaceuticals Co., Inc., Glenmark Pharmaceuticals Ltd., MedPharm Ltd.)
- Focus on developing differentiated topical formulations, generic alternatives, transdermal drug delivery systems, and specialty dermatology products. Emphasize cost effective manufacturing, contract development services, and partnerships with pharmaceutical companies to support formulation innovation and market expansion.
- Greater flexibility in addressing niche therapeutic areas and emerging patient needs. Strong expertise in formulation science, topical drug delivery technologies, and specialty product development enables faster innovation and targeted market positioning. Competitive pricing strategies support adoption in cost sensitive and emerging markets.
- Limited financial resources and narrower product portfolios compared with multinational pharmaceutical companies. Smaller commercial footprints and distribution capabilities may restrict market reach, while dependence on partnerships and licensing agreements can increase business and commercialization risks.
Recent Developments
-
In September 2024, Mankind Pharma entered the topical analgesic market with the launch of Nimulid Strong, featuring a unique 2X diclofenac formulation aimed at alleviating neck pain and enhancing consumer flexibility with gel and spray options.
-
In April 2024, Cipla Health Limited acquired Ivia Beaute Private Limited’s cosmetics and personal care distribution business, enhancing its portfolio with established brands and strengthening its position in India’s growing beauty market.
-
In April 2024, Bausch Health announced public drug plan listings for PrUCERIS aerosol foam in five Canadian provinces, improving access for ulcerative colitis patients.
Topical Drugs Market Report Scope
Report Attribute
Details
Market size value in 2025
USD 201.4 billion
Market size value in 2026
USD 213.0 billion
Revenue forecast in 2033
USD 323.5 billion
Growth rate
CAGR of 6.2% from 2026 to 2033
Historical data
2021 - 2024
Forecast period
2026 - 2033
Quantitative units
Revenue in USD million/billion, and CAGR from 2026 to 2033
Report coverage
Revenue forecast, company ranking, competitive landscape, growth factors, and trends
Segments covered
Type, route of administration, end-use, region
Regional scope
North America; Europe; Asia Pacific; Latin America; MEA
Country scope
U.S.; Canada; Mexico; UK; Germany; France; Italy; Spain; Denmark; Norway; Sweden; Japan; China; India; South Korea; Australia; Thailand; Brazil; Argentina; South Africa; Saudi Arabia; UAE; Kuwait.
Key companies profiled
Bayer AG; Cipla; GSK plc; Johnson & Johnson Services, Inc.; Novartis AG; Bausch Health Companies Inc.; Hisamitsu Pharmaceuticals Co., Inc.; Merck KGaA; GLENMARK PHARMACEUTICALS LTD.; MedPharm Ltd.
Customization scope
Free report customization (equivalent up to 8 analysts' working days) with purchase. Addition or alteration to country, regional & segment scope.
Pricing and purchase options
Avail customized purchase options to meet your exact research needs. Explore purchase options
Global Topical Drugs Market Report Segmentation
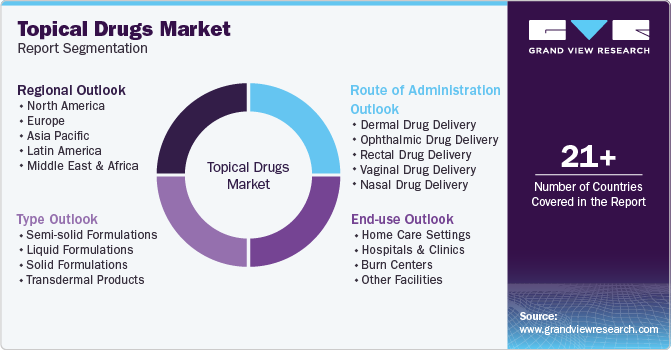
This report forecasts revenue growth at global, regional, and country levels and provides an analysis of the latest industry trends in each of the sub-segments from 2021 to 2033. For this study, Grand View Research has segmented the global topical drugs market report based on route of administration, type, end use, and region:
 To learn more about this report, Download Free Sample Report
-
Route of Administration Outlook (Revenue, USD Million, 2021 - 2033)
-
Dermal Drug Delivery
-
Ophthalmic Drug Delivery
-
Rectal Drug Delivery
-
Vaginal Drug Delivery
-
Nasal Drug Delivery
-
-
Type Outlook (Revenue, USD Million, 2021 - 2033)
-
Semi-solid Formulations
-
Creams
-
Ointments
-
Lotions
-
Gel
-
Pastes
-
-
Liquid Formulations
-
Suspensions
-
Solutions
-
-
Solid Formulations
-
Powders
-
Suppositories
-
-
Transdermal Products
-
Transdermal Patches
-
Transdermal Semi-Solids
-
-
-
End Use Outlook (Revenue, USD Million, 2021 - 2033)
-
Home Care Settings
-
Hospitals & Clinics
-
Burn Centers
-
Other Facilities
-
-
Regional Outlook (Revenue, USD Million, 2021 - 2033)
-
North America
-
U.S.
-
Canada
-
Mexico
-
-
Europe
-
UK
-
Germany
-
France
-
Italy
-
Spain
-
Denmark
-
Sweden
-
Norway
-
-
Asia Pacific
-
Japan
-
China
-
India
-
Australia
-
South Korea
-
Thailand
-
-
Latin America
-
Brazil
-
Argentina
-
-
Middle East & Africa
-
South Africa
-
Saudi Arabia
-
UAE
-
Kuwait
-
-
Research Methodology
The topical drugs market figures in this report are based on a proven research process that combines executive interviews with secondary research from proprietary databases, company filings, and recognized regulatory and institutional sources. Market size is built through value-chain sizing - reconciling supply-side and demand-side estimates - and triangulated with bottom-up and top-down approaches. Every estimate passes multiple levels of expert validation before publication, with each topical drugs segment quantified using the revenue-capture definitions in the table below.
Segment Definition
Segment - Type
Revenue capture definition
Semi-solid Formulations
Revenue generated from topical drugs marketed in semi-solid dosage forms, including creams, ointments, lotions, gels, and pastes used for dermatological, ophthalmic, rectal, vaginal, nasal, and transdermal applications. All sales derived from semi-solid topical formulations are included exclusively within this segment, regardless of therapeutic indication, active ingredient, or distribution channel.
Liquid Formulations
Revenue generated from topical drugs formulated as liquid dosage forms, including solutions and suspensions intended for dermal, ophthalmic, nasal, rectal, or vaginal administration. Revenue associated with all liquid topical products is classified solely within this segment and excluded from other formulation categories.
Solid Formulations
Revenue generated from topical drugs available in solid dosage forms, including powders and suppositories used for localized therapeutic applications. All sales attributed to these products are captured exclusively within this segment irrespective of therapeutic use, patient population, or care setting.
Transdermal Products
Revenue generated from transdermal drug delivery products, including transdermal patches and transdermal semi-solid formulations designed to deliver active pharmaceutical ingredients through the skin for local or systemic therapeutic effects. Revenue from all transdermal products is included exclusively within this segment and excluded from conventional topical formulation categories.
Segment - Route of Administration
Revenue capture definition
Dermal Drug Delivery
Revenue generated from topical drugs administered directly onto the skin for the treatment of dermatological conditions, wound care, pain management, infections, and other localized disorders. All sales associated with skin-based topical administration are included exclusively within this segment regardless of formulation type or therapeutic indication.
Ophthalmic Drug Delivery
Revenue generated from topical drugs administered to the eye for the treatment of ocular disorders, infections, inflammation, glaucoma, dry eye disease, and related conditions. Revenue from all ophthalmic topical products is classified solely within this segment.
Rectal Drug Delivery
Revenue generated from topical drugs administered through the rectal route, including formulations intended for hemorrhoids, inflammatory bowel conditions, infections, pain management, and other anorectal disorders. All related sales are captured exclusively within this segment.
Vaginal Drug Delivery
Revenue generated from topical drugs administered through the vaginal route for the treatment of infections, hormonal disorders, inflammation, and other gynecological conditions. Revenue from all vaginal topical therapies is included solely within this segment.
Nasal Drug Delivery
Revenue generated from topical drugs administered through the nasal cavity for the treatment of allergies, congestion, infections, inflammatory conditions, and other nasal disorders. All sales associated with nasal topical administration are classified exclusively within this segment.
Segment - End Use
Revenue capture definition
Home Care Settings
Revenue generated from topical drugs purchased and utilized by patients in home care environments, including prescription and over-the-counter products used without direct institutional supervision. All sales associated with self-administered topical therapies are included exclusively within this segment.
Hospitals & Clinics
Revenue generated from topical drugs administered, dispensed, or prescribed within hospitals, specialty clinics, outpatient centers, and physician offices. Revenue from institutional healthcare settings is classified solely within this segment.
Burn Centers
Revenue generated from topical drugs used in specialized burn treatment facilities for wound healing, infection prevention, pain management, and skin regeneration therapies. All sales associated with burn care applications are captured exclusively within this segment.
Others
Revenue generated from topical drugs utilized in healthcare facilities not classified under hospitals, clinics, or burn centers, including rehabilitation centers, long-term care facilities, nursing homes, and ambulatory care centers. Revenue from these settings is included solely within this segment.
Estimation Model
 To learn more about this report, Download Free Sample Report
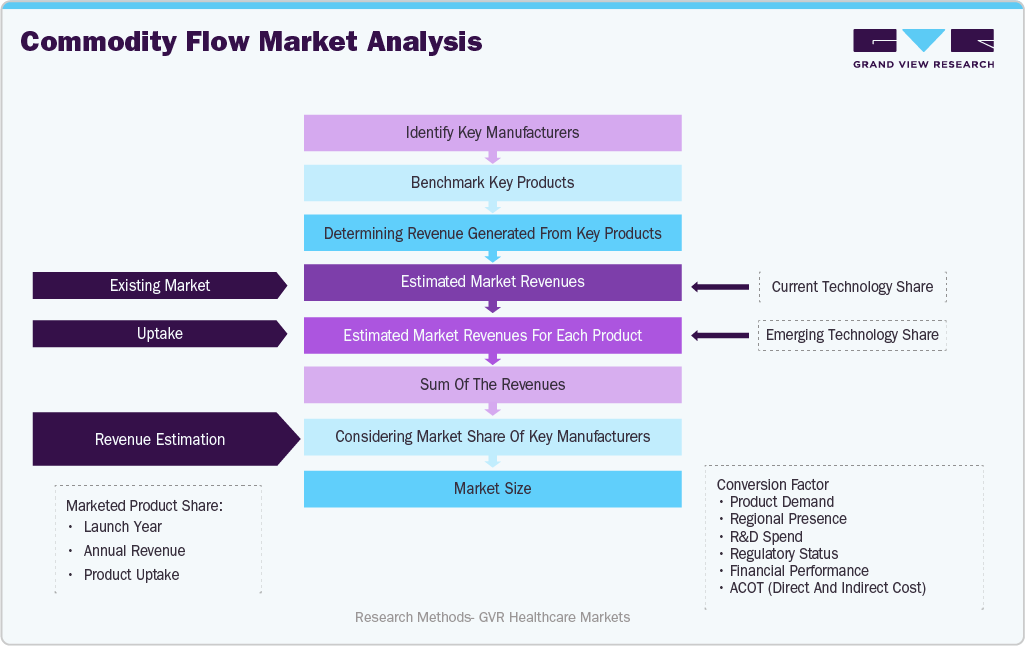
The topical drugs market was estimated using a combination of bottom-up and top-down approaches. The methodology began with identifying key manufacturers and benchmarking marketed products across semi-solid formulations, liquid formulations, solid formulations, and transdermal products. Product-level revenues were assessed through company reports, regulatory filings, prescription trends, and healthcare utilization data. Revenue contributions were mapped across dermal, ophthalmic, rectal, vaginal, and nasal drug delivery routes. Market sizing incorporated disease prevalence, treatment rates, product adoption, and end-use demand across home care settings, hospitals and clinics, burn centers, and other healthcare facilities. Market shares of leading companies were evaluated to validate competitive positioning and revenue distribution. Forecast estimates were developed by analyzing product demand, pipeline developments, regulatory approvals, technological advancements in topical and transdermal delivery systems, healthcare expenditure trends, reimbursement scenarios, and regional market dynamics. Final market estimates were validated through data triangulation, primary interviews, and secondary research sources.
Delivered Customizations
This report has been delivered with the following In-depth customizations
Client Request
Customization Delivered Value Adds Topical Drugs Market Competitive Landscape & Portfolio Assessment
Conducted a comprehensive assessment of the global topical drugs market, evaluating approved products, formulation technologies, therapeutic applications, pipeline developments, and competitive positioning. The study analyzed key participants including Bayer AG, GSK plc, Johnson & Johnson Services, Inc., Novartis AG, Bausch Health Companies Inc., Cipla, Hisamitsu Pharmaceuticals Co., Inc., Merck KGaA, Glenmark Pharmaceuticals Ltd., and MedPharm Ltd. across dermatology, ophthalmology, pain management, wound care, and transdermal drug delivery segments.
Helped the client identify high-growth therapeutic areas, benchmark competitor product portfolios, assess market positioning, and evaluate expansion opportunities across topical and transdermal drug delivery markets. Supported strategic decision making related to product development, licensing opportunities, and market entry strategies.
Topical Drug Delivery Technology & Formulation Benchmarking Study
Delivered a detailed benchmarking analysis of topical drug delivery technologies, including semi-solid formulations, liquid formulations, transdermal systems, and advanced penetration enhancement platforms. The assessment compared formulation performance, delivery efficiency, patient compliance, manufacturing capabilities, intellectual property positioning, and commercialization potential across leading industry participants.
Enabled the client to assess formulation competitiveness, identify technology gaps, benchmark innovation strategies, and prioritize investments in next-generation topical and transdermal drug delivery platforms. Supported product differentiation and long-term innovation planning.
Topical Drugs Manufacturing & Commercialization Feasibility Assessment
Conducted a strategic evaluation of the topical drugs manufacturing ecosystem, including formulation development capabilities, excipient sourcing, contract manufacturing networks, regulatory requirements, quality control processes, packaging technologies, and commercial scale production infrastructure. The study also assessed regional manufacturing capabilities, outsourcing opportunities, and supply chain resilience supporting global commercialization.
Supported manufacturing strategy development by identifying qualified production partners, evaluating supply chain risks, optimizing outsourcing models, and strengthening commercialization readiness. Enabled efficient scale-up planning and enhanced operational flexibility across regional and global markets.
Frequently Asked Questions About This Report
The market growth is increasingly influenced by the rising prevalence of skin conditions and chronic diseases globally.
The dermal drug delivery segment led with a 54.2% revenue share in 2025.
The semi-solid formulations segment led with a 62.3% revenue share in 2025.
The hospitals & clinics segment led with a 38.9% revenue share in 2025.
The global topical drugs market size was valued at USD 201.4 billion in 2025 and is estimated at USD 213.0 billion for 2026.
The global topical drugs market is expected to grow at a CAGR of 6.2% from 2026 to 2033, reaching USD 323.5 billion by 2033.
North America dominated with a 36.7% revenue share in 2025.
Asia pacific is the fastest-growing region over the forecast period.
Key players include Some key players operating in the topical drugs market include Bayer AG; Cipla; GSK plc; Johnson & Johnson Services, Inc.; Novartis AG; Bausch Health Companies Inc.; Hisamitsu Pharmaceuticals Co., Inc.; Merck KGaA; GLENMARK PHARMACEUTICALS LTD.; MedPharm Ltd.
About the Author(s)
Pharmaceuticals Research Team
Healthcare · PharmaceuticalsThis report was authored by the pharmaceuticals research team at Grand View Research - comprising two research analysts, one senior research analyst, and one industry expert - with specialized expertise in the pharmaceuticals segment of the healthcare industry. All findings are based on proprietary healthcare databases, executive interviews, and regulatory analysis, subject to internal peer review prior to publication.
Last Updated:
Speak to Analyst

Customize this report to your needs - add regions, segments, or data points, with 20% free customization.
Or view our licence options:


ISO 9001:2015 & 27001:2022 Certified
We are GDPR and CCPA compliant! Your transaction & personal information is safe and secure. For more details, please read our privacy policy.


