
- Home
- »
- Medical Devices
- »
-
U.S. Academic Medical Center Market Size Report, 2033GVR Report cover

U.S. Academic Medical Center Market (2026 - 2033)
Size, Share & Trends Analysis Report By Ownership, By Therapeutic Area (Oncology, Cardiovascular Diseases), By Bed Capacity (Less than 300 beds, 300-500 beds, 501-800 beds, More than 800 beds), By Region, And Segment Forecasts
Market Size, 2025
$1,110.9BMarket Estimate, 2026
$1,175.9BMarket Forecast, 2030
$1,983.2BCAGR, 2026–2030
7.8%U.S. Academic Medical Center Market Summary
The U.S. academic medical center market was valued at USD 1,110.9 billion in 2025 and is projected to grow from USD 1,175.9 billion in 2026 to reach USD 1,983.2 billion by 2033, at a CAGR of 7.8% from 2026 to 2033. Northeast market is anticipated to register the fastest growth rate during the forecast period.
Key Market Trends & Insights
- By ownership: The private AMC segment held the largest revenue share of 56.3% in 2025.
- By therapeutic area: The oncology segment held a significant share of 24.9% in 2025.
- By bed capacity: The more than 800 beds segment held a significant share of 42.5% in 2025.
Market Size & Forecast
- Market size in 2025: USD 1,110.9 Billion
- Estimated market size in 2026: USD 1,175.9 Billion
- Projected market size by 2033: USD 1,983.2 Billion
- CAGR (2026-2033): 7.8%
Three ways to get this report
Buy it, customize it, or ask a question.Ask an Analyst
Analyst response in 1 business day
- AccessReport author, directly
- Reply timeWithin 1 working day
- No sales callDirect answer only
- FormatEmail reply
- CostFree, no cost
Get the Full Report
What the study covers
- FormatsPDF · Excel · Dashboard
- Timeline2026–2030 annual, 2025 base
- Coverage20+ countries, 5 regions
- Companies10+ key players profiled
Customize the Report
20% free customization
- IncludeCountries, segments, points
- TailorTo your product definition
- ExtendDeeper competitor detail
- OrA fully bespoke study
- Turnaround5–10 working days
The market is driven by increasing federal and private investments in biomedical research, rising demand for specialized tertiary and quaternary care, and growing clinical trial activity across leading academic health systems. The expanding adoption of precision medicine, artificial intelligence, and digital health technologies is further strengthening research capabilities and improving patient outcomes. For instance, in October 2025, Mayo Clinic launched the Mayo Clinic Platform Accelerate to support healthcare AI startups, reinforcing the role of AMC in advancing healthcare innovation.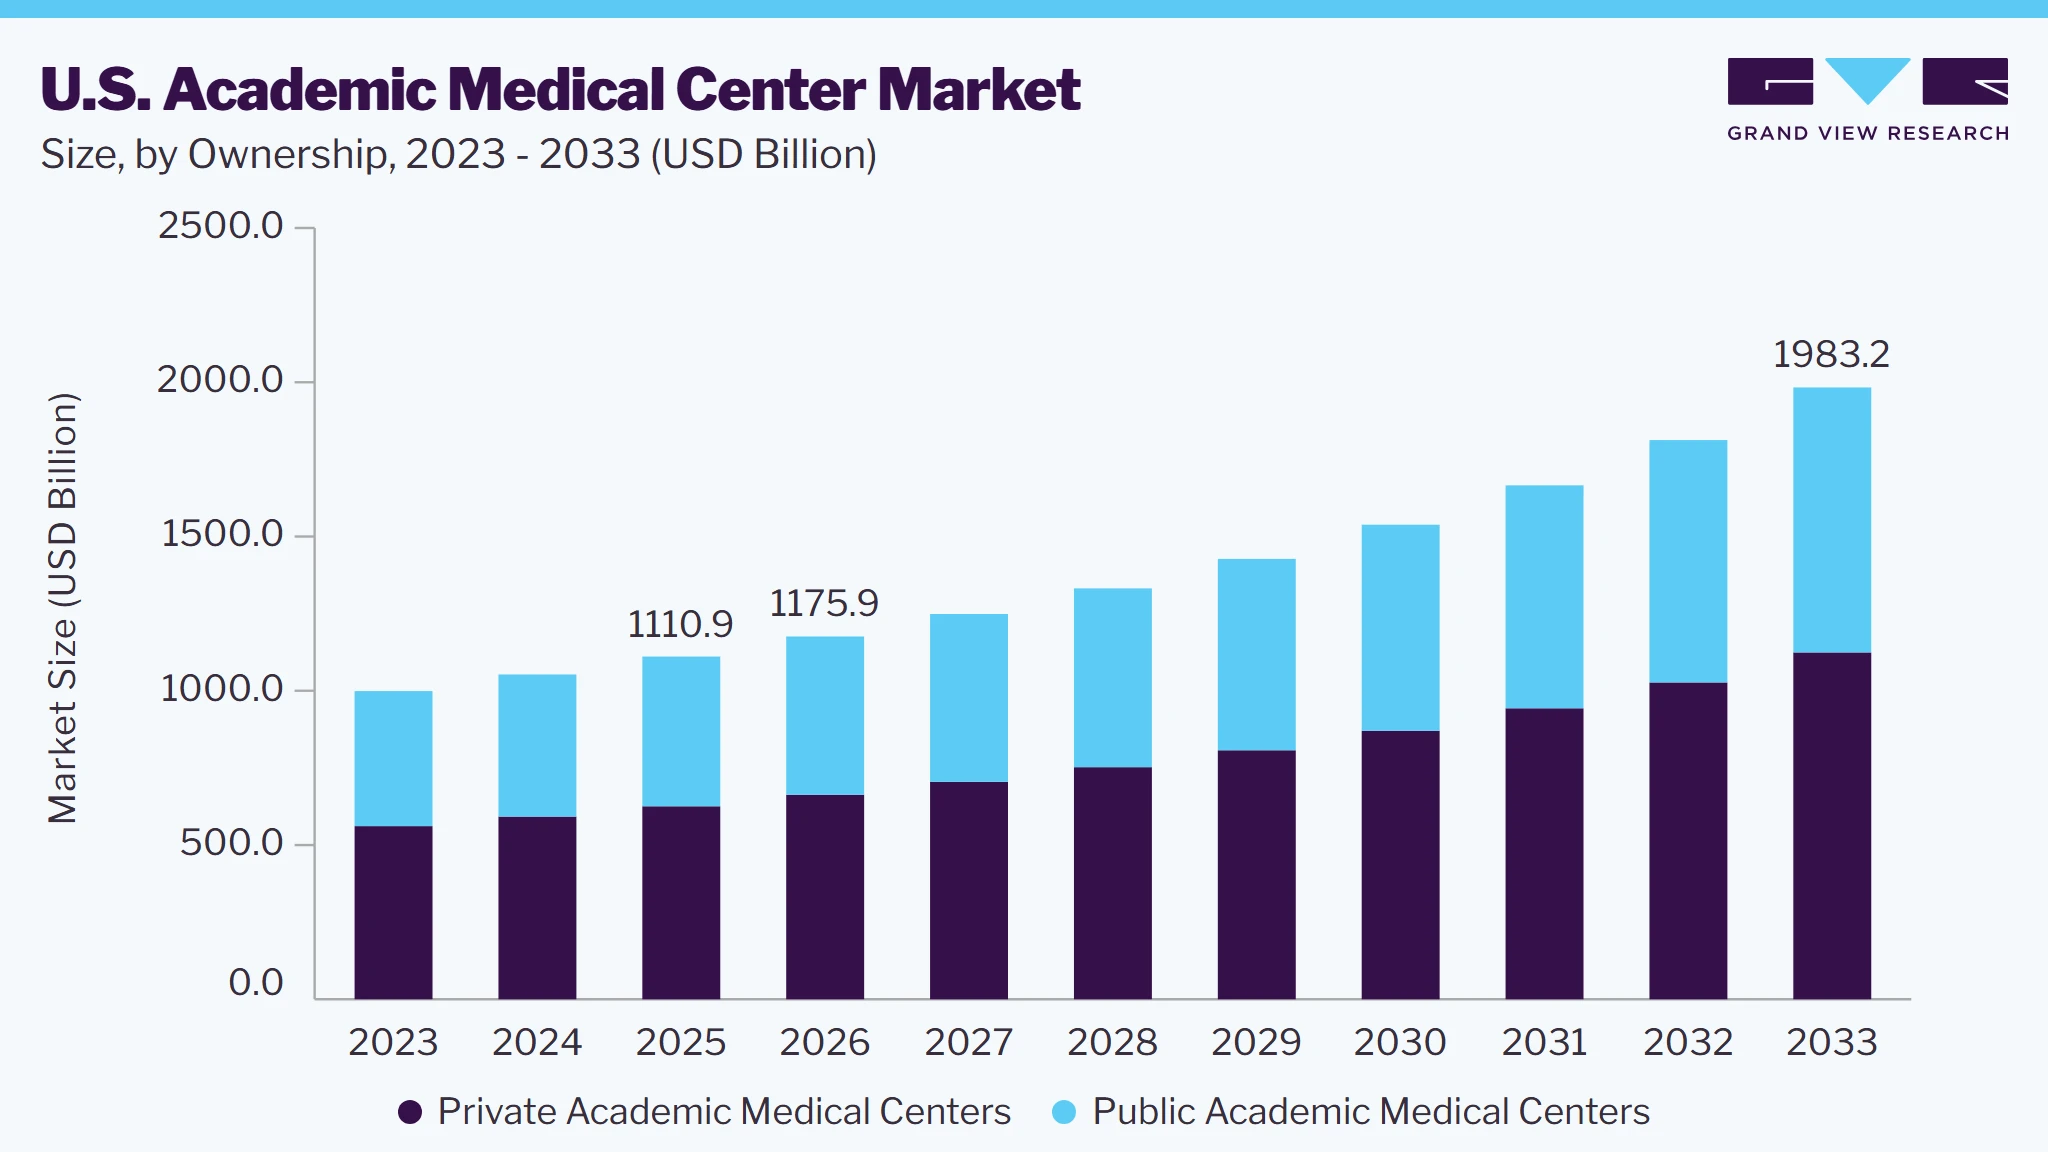 Source: Grand View Research, IR Documents, Primary Interviews, Paid DatabasesTo learn more about this report,
 Download Free Sample Report
The section below outlines the key factors driving the growth of the market, highlighting the rising incidence of road accidents, sports injuries, fractures, and orthopedic trauma cases across the region. It also examines increasing healthcare investments, expanding access to advanced orthopedic care, growing adoption of minimally invasive trauma fixation technologies, and the rising presence of international medical device manufacturers supporting market expansion.
Market Dynamics
As the primary recipients of competitive research funding from federal agencies, AMC use these investments to expand research infrastructure, accelerate clinical trials, adopt advanced technologies, and translate scientific discoveries into innovative patient care. These investments also strengthen their ability to deliver specialized healthcare services, support precision medicine, attract top physician-scientists, and commercialize new therapies. As the U.S. healthcare system continues to prioritize research-driven innovation and multidisciplinary care, maintaining federal funding is expected to enhance the clinical, educational, and research capabilities, thereby supporting long-term market growth.
In April 2026, Michael and Susan Dell committed USD 750 million to the University of Texas at Austin to establish the UT Dell Medical Center and the UT Dell Campus. The investment will support the development of the first AI-native academic medical center in the U.S., integrating artificial intelligence across patient care, hospital operations, biomedical research, and medical education. The project, developed in collaboration with MD Anderson Cancer Center, is expected to accelerate AI-enabled diagnostics, personalized treatment planning and predictive analytics, while strengthening the nation's and research infrastructure.
The academic medical center market is facing a material restraint due to federal reductions in National Institutes of Health (NIH) research funding and proposed changes to indirect cost reimbursement policies. Community hospitals and AMCs rely on NIH support for both direct research activities and the overhead costs associated with maintaining laboratories, compliance systems, core facilities, data management, and administration. In early 2025, the NIH proposed capping indirect cost reimbursement at 15%, down from a historical average of approximately 27-28%, while also terminating more than 1,100 NIH grants. According to the Association of American Medical Colleges (AAMC), these actions disrupted research programs across dozens of institutions and contributed to the cancellation of at least 160 clinical trials in oncology, HIV/AIDS, mental health, substance use, and chronic disease. By year-end, terminated grants reached 1,183, and funding cuts approached USD 2 billion, with the indirect cost policy implying annual support reductions of more than USD 4 billion. The result has been a direct deterioration in AMC operating leverage, as institutions are forced to absorb fixed research costs with fewer federal dollars, thereby constraining expansion, innovation, and long-term competitiveness.
This restraint is reflected in institutional actions. Vanderbilt University Medical Center (VUMC), one of the largest academic health systems in the Southeast, initially planned a USD 250 million budget reduction in March 2025, later increasing the target to USD 300 million as federal funding pressures grew. The institution then announced up to 650 layoffs, primarily in research, administrative, and support roles. This example shows that NIH funding instability affects grant portfolios and also leads to immediate workforce reductions and diminished research capacity. For AMCs such as Vanderbilt, these cuts weaken the ability to sustain translational science, support investigator-initiated studies, and maintain the infrastructure necessary for high-impact academic medicine.
Baylor College of Medicine in Houston announced 122 layoffs due to uncertainty about federal support for academic medicine. The reductions affected staff in administration, research, clinical operations, and education, underscoring the broad financial impact. Baylor’s leadership described the layoffs as a last resort, citing the difficulty of sustaining core missions during sudden funding changes. The impact extended to MD Anderson Cancer Center, which implemented a partial hiring freeze to maintain fiscal stability. This regional response demonstrates how federal funding uncertainty can disrupt interconnected health systems, restricting budgets, research collaboration, clinical trials, and specialized cancer care.
A significant growth opportunity in the market is the rise of AI-native hospitals. These facilities integrate artificial intelligence into infrastructure, clinical workflows, and digital systems from the outset, rather than incorporating AI after construction. Traditional hospitals that adopt AI via isolated software differ from AI-native AMCs, which are designed around enterprise-wide AI ecosystems that unify electronic health records, medical imaging, genomics, clinical decision support, databases, and operational systems. This model enables continuous data-driven care, improves efficiency, and advances personalized medicine.
The growing availability of large philanthropic investments is accelerating this transformation. Instead of funding only research programs, donors are increasingly financing next-generation healthcare campuses that combine advanced computing, artificial intelligence, biomedical engineering, and clinical care within a single ecosystem. This model creates new revenue opportunities for AMCs through industry collaborations, AI technology commercialization, precision medicine programs, and expanded federal and private research funding.
For instance, in April 2026, Michael and Susan Dell committed USD 750 million to the University of Texas at Austin to establish the UT Dell Medical Center and the UT Dell Campus. The initiative was designed to create the first AI-native academic medical center in the U.S., with artificial intelligence embedded across patient care, hospital operations, and medical education. Developed in collaboration with MD Anderson Cancer Center, the campus will integrate expertise in oncology and advanced computing to advance AI-enabled diagnostics, personalized treatment planning, predictive analytics, and biomedical innovation.
Market Impact:
The emergence of AI-native AMC is expected to create long-term opportunities for healthcare AI vendors, cloud computing providers, medical device manufacturers, and pharmaceutical companies by increasing demand for enterprise AI platforms, digital infrastructure, precision medicine technologies, and collaborative research programs. It also enables AMCs to diversify revenue beyond patient care through technology commercialization, industry-sponsored research, and innovation partnerships, strengthening their competitive position in the evolving U.S. healthcare ecosystem.
AMC depends heavily on funding from the National Institutes of Health to support clinical trials, physician-scientist training, and advanced laboratory infrastructure. However, recent federal funding uncertainty, including grant terminations, delayed awards, and proposed reductions in NIH indirect cost reimbursements, has placed significant financial pressure on AMCs. As a result, several leading academic institutions have implemented hiring freezes, workforce reductions, delayed research projects, and budget controls to offset funding shortfalls. For Instance, in March 2025, Johns Hopkins University announced layoffs affecting more than 2,000 employeesfollowing the loss of approximately USD 800millionin federal research funding. Harvard University imposed hiring freezes and scaled back spending amid federal funding disputes, while Stanford University introduced budget restrictions and paused recruitment for research positions amid uncertainty about NIH funding. These developments threaten the core mission of AMC by slowing scientific innovation, reducing clinical trial activity, and constraining long-term financial sustainability across the market.
Market Concentration & Characteristics
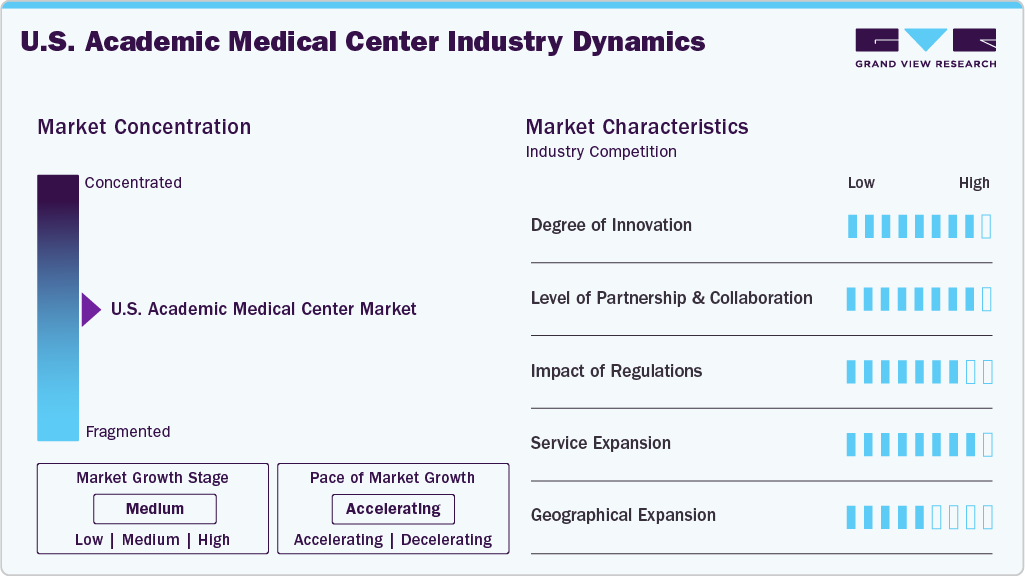
The chart below represents the relationship between industry concentration, industry characteristics, and industry participants. The market is moderately consolidated, with academic health systems competing across specialized care, precision medicine, and medical education. The industry is characterized by a high degree of innovation, high regulatory influence, high partnerships and collaborations, high service expansion, and moderately high regional expansion. Growing investments in AI and digital health continue to reshape the competitive landscape.
The market is witnessing a high level of innovation driven by artificial intelligence, precision medicine, digital health and genomics. Institutions are increasingly integrating AI into clinical decision support, diagnostics, and medical research to improve patient outcomes. In November 2024, Mount Sinai Health System opened the Hamilton and Amabel James Center for Artificial Intelligence and Human Health, dedicated to advancing AI-powered healthcare delivery, and medical education. This reflects the growing role of AI-enabled innovation in transforming academic healthcare.
Strategic collaborations between AMC, technology companies, pharmaceutical firms, and government agencies continue to accelerate education and clinical innovation. These partnerships support AI implementation and precision medicine, while expanding access to advanced healthcare. In September 2024, UTHealth Houston partnered with OpenAI to deploy ChatGPT Edu across healthcare and medical education to adopt generative AI at an enterprise scale.
 To learn more about this report, Download Free Sample Report
The market operates under stringent regulatory frameworks governing AI-enabled medical technologies, patient privacy, and healthcare quality. Compliance with FDA, NIH, HIPAA, and CMS regulations is essential for research funding and clinical implementation. In March 2024 , leading academic health systems formed the Trustworthy & Responsible AI Network (TRAIN) to establish governance standards for the safe, ethical, and compliant adoption of AI in healthcare, reflecting the increasing regulatory focus on responsible AI deployment.
The market is rapidly expanding beyond traditional tertiary care by integrating precision medicine, genomic testing, virtual care, AI-assisted diagnostics, and multidisciplinary specialty programs. These expanded services improve patient access while accelerating the translation of research into clinical practice. In November 2024, Mount Sinai expanded its AI-enabled clinical services through its dedicated AI center, supporting precision medicine, predictive analytics, and clinical decision support across multiple specialties.
The market continues to expand through the establishment of new campuses, satellite hospitals, digital health networks, and regional research collaborations to improve access to specialized care. For instance, in November 2024, the Mount Sinai Health System announced the opening of the Hamilton and Amabel James Center for AI and Human Health in New York City. The new center was established to advance healthcare delivery through the development and application of innovative AI technologies, while further strengthening Mount Sinai’s academic research capabilities and expanding access to advanced, technology-enabled patient care across the region.
Analyst Perspective
The market is evolving toward integrated academic health systems that combine advanced clinical care, medical education, research, and specialized treatment capabilities. The rising prevalence of chronic and complex diseases, an aging population, and the growing demand for tertiary and quaternary care are supporting market growth. Academic medical centers are increasingly investing in oncology, cardiovascular care, neuroscience, transplantation, precision medicine, advanced diagnostics, and outpatient specialty services while expanding hospital and physician networks. The competitive landscape is increasingly shaped by clinical expertise, research capabilities, medical school affiliations, adoption of advanced technology, and regional network strength. Investments in AI-enabled diagnostics, robotic surgery, digital health, precision medicine, and clinical research, along with strategic acquisitions, affiliations, and partnerships, are expected to strengthen the market position of prominent academic medical centers across the U.S.
Ownership Insights
Based on ownership, the private AMC segment held the largest revenue share of 56.3% in 2025. The segment's dominance is driven by strong financial resources, allowing them to continuously expand advanced clinical infrastructure, adopt next-generation technologies, and strengthen research capabilities through philanthropic funding and industry partnerships. Their ability to invest in complex specialty care and precision medicine, while attracting nationally recognized physicians further supports higher patient volumes and revenue growth. For instance, in July 2025, Thomas Jefferson University and Jefferson Health received a USD 28 million philanthropic gift from Sidney and Caroline Kimmel to support the expansion and modernization of the emergency department at Thomas Jefferson University Hospital and accelerate clinical and translational research at Sidney Kimmel Medical College.
The public AMC segment accounted for a substantial share of the market in 2025 and is expected to grow steadily over the forecast period. The segment's growth is supported by increasing state investments in healthcare infrastructure and physician training, along with its critical role in providing specialized care to underserved populations. Public AMCs continue to modernize facilities, expand patient capacity, and strengthen programs to meet rising healthcare demand. For instance, in June 2025, University Hospital and Rutgers Health launched the first phase of a major redevelopment project in Newark to construct a new patient-care tower and modernize the academic health campus, expanding access to high-quality care while enhancing academic medicine and clinical training.
Therapeutic Area Insights
Based on the therapeutic area, the oncology segment held a significant share of 24.9% in 2025.The segment's dominance is driven by the high burden of cancer, increasing demand for multidisciplinary cancer care, and the concentration of advanced oncology services. U.S. AMCs serve as leading hubs for precision oncology, immunotherapy, CAR-T cell therapy, and early-phase clinical trials, attracting referrals for complex cancer cases. In addition, substantial federal funding continues to strengthen academic institutions' oncology capabilities. For instance, the National Cancer Institute (NCI) allocated approximately USD 346.5 million in FY 2025 through 75 NCI-Designated Cancer Centers, supporting cancer research infrastructure, clinical trials, and translational medicine.
The cardiovascular diseases segment is expected to grow at a significant CAGR of 8.6% during the forecast period. This growth is attributed to the rising prevalence of heart disease, increasing demand for complex structural heart procedures, and rapid adoption of minimally invasive cardiovascular interventions at AMC. These institutions are also expanding dedicated cardiovascular research programs and integrating multidisciplinary specialties such as cardio-oncology to manage the growing number of cancer patients experiencing cardiovascular complications. For instance, in February2025, the National Heart, Lung, and Blood Institute (NHLBI) highlighted its continued investment in cardio-oncology research, supporting AMC in developing innovative approaches to prevent and treat cardiovascular complications associated with advanced cancer therapies.
Bed Capacity Insights
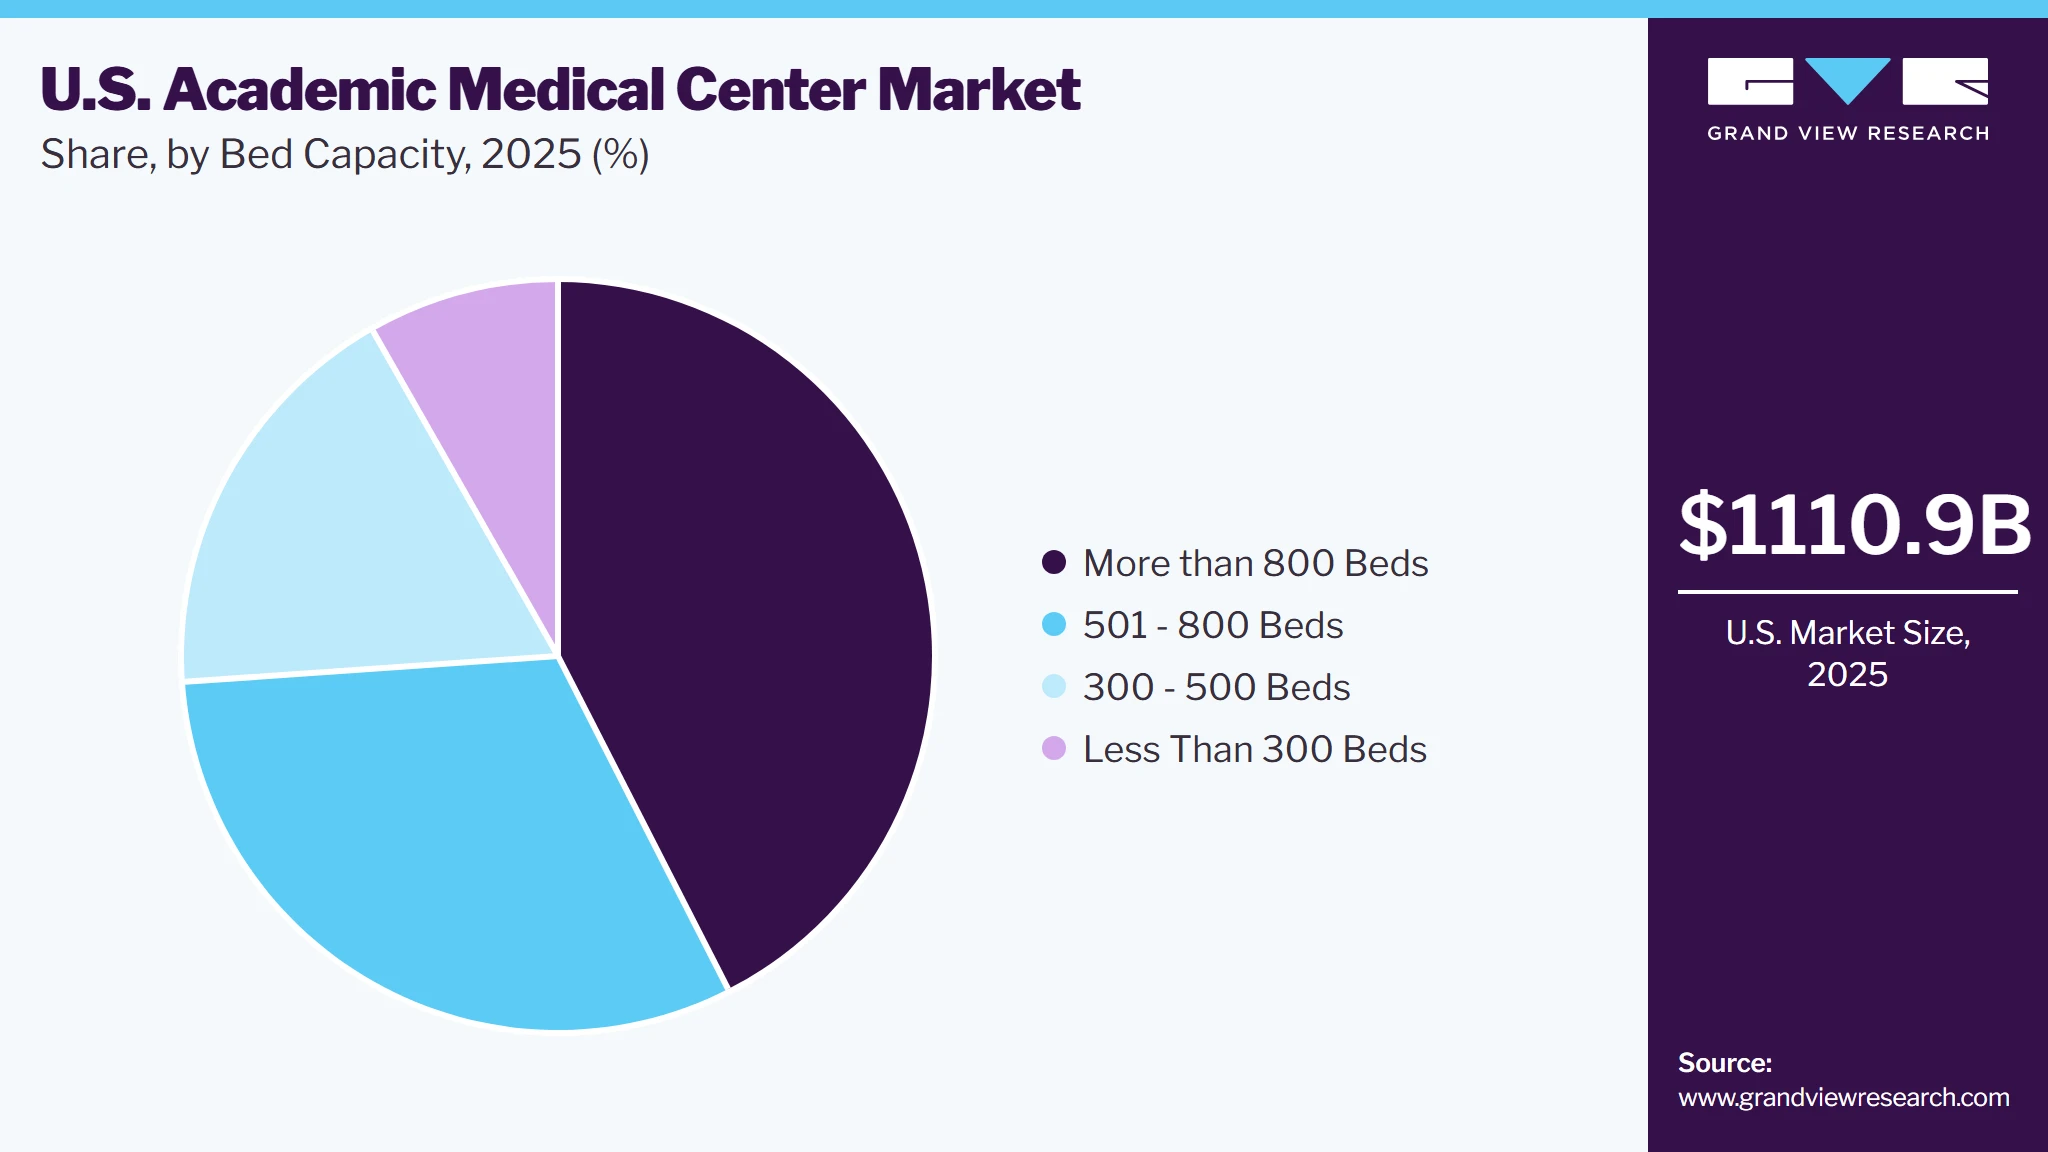
Based on bed capacity, the more than 800 beds segment held a significant share of 42.5% in 2025. The segment's dominance is driven by the concentration of highly specialized tertiary and quaternary care services, Level 1 trauma centers, and comprehensive teaching facilities within large AMC. These institutions manage the highest volume of complex referrals, organ transplants, cancer care, and advanced cardiovascular and neurological procedures while receiving substantial federal research funding. For instance, in September 2025, Vanderbilt University Medical Center began opening the new Jim Ayers Tower, adding six inpatient floors with 30 private patient rooms per floor as part of its largest campus expansion. The tower increases inpatient capacity and supports growing demand for complex patient care and medical education.
 To learn more about this report, Download Free Sample Report
The less than 300 beds segment is expected to grow to a significant CAGR during the forecast period. This growth is attributed to increased investments in smaller regional academic hospitals and satellite campuses, which improve access to specialty care closer to patients' communities. Health systems are expanding these facilities to reduce pressure on large tertiary hospitals while supporting outpatient services, medical education, and community-based clinical research. For instance, in February 2025, Sutter Health announced a major East Bay expansion that includes a new academic-affiliated medical center with an initial capacity of up to 200 beds, along with specialty clinics, ambulatory surgery centers, and physician recruitment to improve regional access to advanced healthcare services.
Region Insights
The Northeast dominated the market in 2025, accounting for the largest revenue share of 31.0%. The region's leadership is driven by the high concentration of nationally ranked AMC, leading medical schools, and NIH-funded institutions. States such as Massachusetts, New York, and Pennsylvania are home to renowned institutions, including Mass General Brigham, NewYork-Presbyterian, NYU Langone Health, and Penn Medicine, which provide highly specialized tertiary and quaternary care while leading clinical research and physician training. The region also benefits from strong federal funding, established healthcare infrastructure, and a high volume of complex patient referrals. For instance, in April 2025, Penn Medicine broke ground on the USD 270 million Penn Medicine Montgomeryville, a four-story multispecialty outpatient center in Pennsylvania that will expand access to advanced healthcare services across Montgomery and Bucks counties. The facility will offer comprehensive cancer care, primary care, cardiovascular, orthopedic, neuroscience, and women's health services, further strengthening the Northeast's academic healthcare infrastructure and improving access to specialized care closer to patients' communities.
Southwest Academic Medical Center Market Trends
The Southwest is expected to register the fastest CAGR of 8.0% during the forecast period. This growth is attributed to rapid population growth, increasing healthcare investments, and the expansion of academic health systems across Arizona, Texas, and neighboring states. AMCs in the region are investing heavily in new hospitals and specialty care programs to address rising demand for advanced healthcare services while expanding medical education and physician training. For instance, in November 2025, The University of Texas MD Anderson Cancer Center launched its historic USD 2.5 billion "Only Possible Here" campaign, the largest fundraising initiative in the institution's history. The campaign has already secured more than USD 1.9 billion during its silent phase and aims to advance cancer research, expand clinical programs, accelerate innovation, and strengthen academic and research infrastructure, further reinforcing the Southwest's position as a rapidly growing hub for academic healthcare and biomedical research.
Key U.S. Academic Medical Center Company Insights
The U.S. academic medical centers market is competitive, with key players focusing on acquisitions, strategic partnerships, network expansion, and investments in specialty care to strengthen their market presence. For instance, in February 2026, Vanderbilt Health completed the acquisition of Tennova Healthcare-Clarksville Hospital and related physician clinics from Community Health Systems. The acquisition added a270-bed hospital, a freestanding emergency department, physician clinics, and outpatient services to Vanderbilt Health’s network, strengthening its presence across Middle Tennessee. Prominent players in the market include Cleveland Clinic, Weill Cornell Medicine, Vanderbilt University Medical Center, University Hospitals, Massachusetts General Hospital, Stanford Health Care, UAB Health System, Mayo Clinic, Icahn School of Medicine at Mount Sinai, Cedars-Sinai, Johns Hopkins University, and UC San Diego Health.
Key U.S. Academic Medical Center Companies:
-
Cleveland Clinic
-
Weill Cornell Medicine
-
Vanderbilt University Medical Center
-
University Hospitals
-
The General Hospital Corporation (Massachusetts General Hospital)
-
Stanford Health Care
-
UAB Health System
-
Mayo Foundation for Medical Education and Research (Mayo Clinic)
-
Icahn School of Medicine at Mount Sinai
-
Cedars-Sinai
-
Johns Hopkins University
-
UC San Diego Health
Competitive Benchmarking
Operating Strategies
Competitive Edge
Weaknesses
Mature Players: Cleveland Clinic, Mayo Foundation for Medical Education and Research (Mayo Clinic), The General Hospital Corporation (Massachusetts General Hospital), The Johns Hopkins University,
- Invest in precision medicine, AI, and advanced specialty care.
- Expand clinical research and NIH-funded programs.
- Strengthen partnerships with pharmaceutical, biotech, and medical device companies.
- Grow outpatient networks and international patient services.
- Strong global reputation and trusted brand.
- Extensive research funding and clinical expertise.
- Advanced infrastructure and comprehensive specialty services.
- Strong financial resources and industry collaborations.
- High operating and research costs.
- Workforce shortages and rising labor costs.
- Complex organizational structures slow decision-making.
Emerging Players: Weill Cornell Medicine, Vanderbilt University Medical Center, University Hospitals, UAB Health System
- Expand specialty care and regional referral networks.
- Increase investments in digital health, AI, and telehealth.
- Strengthen clinical trials and academic collaborations.
- Develop precision medicine and translational research programs.
- Agile adoption of new technologies.
- Strong regional reputation and academic affiliations.
- Growing research capabilities and specialty care programs.
- Ability to expand rapidly in high-growth clinical areas.
- Lower brand recognition than leading AMCs.
- Greater competition for research funding and talent.
- Limited financial resources for large-scale expansion.
- Increasing reimbursement and capital investment pressures
Recent Developments
-
In November 2025, the University of Minnesota Physicians and Fairview Health Services announced the strategic partnership for Minnesota’s Healthcare Future, a 10-year framework designed to strengthen academic medicine, expand patient access, advance medical education, and accelerate clinical research across the state’s academic health system. The partnership is expected to ensure long-term stability for the University of Minnesota Medical Center and preserve its integrated academic, research, and clinical mission.
This partnership ensures continuity of care while strengthening our shared commitment to advancing medical education, research, and patient care for Minnesotans. - Leadership statement from University of Minnesota Physicians and Fairview Health Services.
-
In September 2025, Florida State University and Tallahassee Memorial HealthCare approved a landmark partnership to establish a new academic health center in North Florida. The collaboration aims to expand quaternary care services, increase biomedical research capacity, enhance physician training programs, and improve regional healthcare access by integrating academic medicine with community-based care.
By uniting TMH’s longstanding commitment to community care with FSU’s mission of academic excellence and service, we are seizing an extraordinary opportunity to shape the long-term future of health care in North Florida and beyond. - Joint statement from FSU President Richard McCullough and TMH CEO Mark O’Bryant.
U.S. Academic Medical Center Market Report Scope
Report Attribute
Details
Market size in 2025
USD 1,110.9 billion
Estimated market size in 2026
USD 1,175.9 billion
Projected market size by 2033
USD 1,983.2 billion
Growth rate
CAGR of 7.8% from 2026 to 2033
Actual data
2021 - 2025
Forecast data
2026 - 2033
Quantitative units
Revenue in USD /billion and CAGR from 2026 to 2033
Report coverage
Revenue forecast, million company ranking, competitive landscape, growth factors, and trends
Segments covered
Ownership, therapeutic area, bed capacity, region
Country scope
U.S.
Regional Scope
Northeast, Southeast, Southwest, Midwest, West
Key companies profiled
Cleveland Clinic; Weill Cornell Medicine; Vanderbilt University Medical Center; University Hospitals; The General Hospital Corporation (Massachusetts General Hospital); Stanford Health Care; UAB Health System; Mayo Foundation for Medical Education and Research (Mayo Clinic); Icahn School of Medicine at Mount Sinai; Cedars-Sinai; The Johns Hopkins University; UC San Diego Health
Customization scope
Free report customization (equivalent up to 8 analysts working days) with purchase. Addition or alteration to country, regional & segment scope.
Pricing and purchase options
Avail customized purchase options to meet your exact research needs. Explore purchase options
U.S. Academic Medical Center Market Report Segmentation
This report forecasts revenue growth, region level and provides an analysis of the latest industry trends in each of the sub-segments from 2021 to 2033 For this study, Grand View Research has segmented the U.S. academic medical center market report based on ownership, therapeutic area, bed capacity, and region:
-
Ownership Outlook (Revenue, USD Million, 2021 - 2033)
-
Public Academic Medical Centers
-
Private Academic Medical Centers
-
-
Therapeutic area Outlook (Revenue, USD Million, 2021 - 2033)
-
Oncology
-
Cardiovascular Diseases
-
Neurology & Neurosciences
-
Orthopedics
-
Gastroenterology
-
Others
-
-
Bed Capacity Outlook (Revenue, USD Million, 2021 - 2033)
-
Less than 300 Beds
-
300-500 Beds
-
501-800 Beds
-
More than 800 Beds
-
-
Region Outlook (Revenue, USD Million, 2021 - 2033)
-
Northeast
-
Southeast
-
Southwest
-
Midwest
-
West
-
Research Methodology
The U.S. academic medical center market figures in this report are based on a proven research process that combines executive interviews with secondary research from proprietary databases, company filings, and recognized regulatory and institutional sources. Market size is built through value-chain sizing-reconciling supply-side and demand-side estimates-and triangulated with bottom-up and top-down approaches. Every estimate passes multiple levels of expert validation before publication, with each U.S. academic medical center segment quantified using the revenue-capture definitions in the table below.
Segment Definition
Segment
Revenue capture definition
By Ownership
Public Academic Medical Centers
Academic medical centers owned or operated by government or public institutions, combining advanced patient care with medical education, physician training, and clinical research.
Private Academic Medical Centers
Privately governed academic medical centers that provide specialized and advanced healthcare services while supporting medical education, residency programs, and clinical research.
By Therapeutic Area
Oncology
Covers revenue generated from cancer diagnosis, treatment, and management, including medical oncology, surgical oncology, radiation therapy, advanced diagnostics, and specialized cancer care.
Cardiovascular Diseases
Covers revenue from the diagnosis and treatment of heart and vascular diseases, including cardiology, cardiac surgery, interventional procedures, electrophysiology, and related services.
Neurology & Neurosciences
Includes revenue from the diagnosis and treatment of neurological conditions through neurology, neurosurgery, stroke care, epilepsy treatment, and other specialized neuroscience services.
Orthopedics
Includes revenue generated from the diagnosis and treatment of bone, joint, spine, and musculoskeletal disorders, including joint replacement, orthopedic surgery, trauma, and sports medicine.
Gastroenterology
Covers revenue from the diagnosis and treatment of gastrointestinal, liver, pancreatic, and digestive disorders, including endoscopy, hepatology, and other specialized GI procedures.
Others
Includes revenue from other therapeutic specialties such as nephrology, pulmonology, urology, endocrinology, rheumatology, infectious diseases, and other clinical departments.
By Bed Capacity
Less than 300 Beds
Includes smaller academic medical centers with fewer than 300 inpatient beds, generally providing focused specialty care, teaching programs, and selected research activities.
300-500 Beds
Includes medium-sized academic medical centers with 300-500 beds that provide a broad range of inpatient, specialty, teaching, and clinical research services.
501-800 Beds
Includes large academic medical centers with 501-800 beds, typically offering extensive tertiary care, multiple specialty departments, medical training, and advanced research programs.
More than 800 Beds
Includes large-scale academic medical centers with over 800 beds, typically serving as major referral hubs for complex tertiary and quaternary care, education, and clinical research.
Estimation Model
Model Details
This research methodology outlines the process for estimating the size of the U.S. academic medical centers market from 2021 to 2033. The study covers key ownership segments, including Public Academic Medical Centers and Private Academic Medical Centers. It also evaluates major therapeutic areas, including Oncology, Cardiovascular Diseases, Neurology & Neurosciences, Orthopedics, Gastroenterology, and Others, along with bed-capacity segments comprising Less than 300 Beds, 300-500 Beds, 501-800 Beds, and More than 800 Beds.
The objective is to develop a robust and defensible market estimate by combining bottom-up and top-down approaches, supported by primary industry validation.
A triangulated market sizing approach was used, combining:
-
Bottom-Up Analysis based on the number of academic medical centers, patient volumes, inpatient admissions, outpatient visits, procedures, bed capacity, utilization rates, average revenue per patient, and facility-level revenues.
-
Top-Down Analysis using U.S. hospital expenditure, healthcare utilization, hospital revenues, medical education and research activity, disease burden, healthcare infrastructure, population growth, and overall healthcare spending.
- Primary Research with academic medical center executives, hospital administrators, physicians, department heads, healthcare consultants, researchers, financial professionals, and other industry experts.
Step-by-Step Market Estimation Process
Academic Medical Center Patient Volume and Revenue Model
This model estimates the market size based on the number of patients receiving care at academic medical centers and the average revenue generated from patient care activities.
Step 1: Facility-level data on academic medical centers operating in the U.S. from 2021 to 2025 were collected from hospital databases, academic health system disclosures, medical school affiliations, government healthcare databases, annual reports, and industry sources.
Step 2: Annual patient volumes were estimated using inpatient admissions, outpatient visits, emergency encounters, surgical procedures, hospital utilization statistics, health system disclosures, and primary interviews.
Step 3: Average revenue per patient was estimated using hospital financial disclosures, reimbursement data, payer mix, service intensity, procedure mix, and facility-level benchmarks.
Step 4: Market size was calculated using:
Number of Patient Encounters × Average Revenue per Patient Encounter
Step 5: Facility-level estimates were aggregated to calculate regional and national market values.
Step 6: Historical and forecast growth rates were incorporated based on patient volume growth, increasing prevalence of complex diseases, expansion of specialty services, healthcare expenditure, reimbursement trends, and academic health system expansion.
Academic Medical Center Facility Revenue Extrapolation Model
This model estimates the market size based on revenues generated by academic medical centers across the U.S.
Step 1: The number of active public and private academic medical centers was identified using hospital databases, medical school affiliations, health system disclosures, government databases, and industry sources.
Step 2: Average annual revenue per academic medical center was estimated using hospital and health system financial statements, annual reports, facility-level benchmarks, patient volumes, and primary interviews.
Step 3: Facility revenues were adjusted based on differences in bed capacity, patient volume, ownership structure, geographic location, payer mix, specialty mix, case complexity, and utilization rates.
Step 4: Market size was calculated using:
Number of Academic Medical Centers × Adjusted Average Annual Revenue per Center
Step 5: Facility-level estimates were aggregated to determine the overall U.S. academic medical centers market size.
Step 6: Annual adjustments were applied to account for health system expansion, hospital mergers and acquisitions, capacity additions, changes in reimbursement, specialty program expansion, and growth in patient demand.
Therapeutic Area Revenue Model
This model estimates market size based on patient volumes and revenues generated across major therapeutic areas within academic medical centers.
Step 1: Therapeutic area data were collected from academic medical centers, hospital systems, healthcare databases, clinical departments, government sources, payer data, and industry publications.
Step 2: Services were categorized into:
-
Oncology
-
Cardiovascular Diseases
-
Neurology & Neurosciences
-
Orthopedics
-
Gastroenterology
-
Others
Step 3: Patient volumes and average revenue per patient or procedure were estimated for each therapeutic area using hospital utilization data, reimbursement benchmarks, procedure volumes, payer data, and primary interviews.
Step 4: Revenue generated by each therapeutic area was calculated using:
Therapeutic Area Patient Volume × Average Revenue per Patient / Procedure
Step 5: Therapeutic area revenues were aggregated and reconciled with total academic medical center revenues to determine the overall market size.
Step 6: Forecast assumptions incorporated disease prevalence, aging population, increasing complexity of care, growth in cancer and cardiovascular treatment, expansion of neuroscience programs, adoption of advanced procedures, and increasing demand for specialized tertiary and quaternary care.
Ownership-Based Market Estimation
The market was further assessed based on the ownership structure of academic medical centers.
Step 1: Academic medical centers were classified into:
-
Public Academic Medical Centers
- Private Academic Medical Centers
Step 2: The number of centers, patient volumes, and associated revenues for each ownership category were estimated using hospital databases, health system disclosures, government records, financial reports, and industry research.
Step 3: Average revenue per facility and average revenue per patient were calculated separately for public and private academic medical centers.
Step 4: Segment revenue was calculated using:
Segment Patient Volume × Average Revenue per Patient
or
Number of Centers in Segment × Average Revenue per Center
Step 5: Ownership-level estimates were cross-checked against the total academic medical centers market to ensure consistency and avoid double counting.
Bed Capacity-Based Market Estimation
This model estimates market revenues based on the bed capacity of academic medical centers.
Step 1: Academic medical centers were classified into:
-
Less than 300 Beds
-
300-500 Beds
-
501-800 Beds
- More than 800 Beds
Step 2: The number of centers within each bed-capacity category was estimated using hospital databases, health system reports, facility disclosures, and healthcare infrastructure data.
Step 3: Average occupancy rates, inpatient admissions, outpatient volumes, and revenue per facility were estimated for each bed-capacity category.
Step 4: Segment revenue was calculated using:
Number of Academic Medical Centers by Bed Capacity × Adjusted Average Revenue per Center
Step 5: Adjustments were made for differences in bed utilization, case complexity, specialty mix, patient volumes, geographic location, and tertiary and quaternary care capabilities.
Step 6: Bed-capacity segment estimates were reconciled with the overall market value to maintain consistency across the market model.
Market Validation and Forecasting
The estimates derived from the patient volume and revenue model, facility revenue extrapolation model, therapeutic area revenue model, ownership-based model, and bed capacity-based model were cross-validated through data triangulation.
Findings were further verified through primary interviews with academic medical center executives, hospital administrators, physicians, department heads, healthcare consultants, researchers, and other industry experts.
Final market forecasts were developed by evaluating U.S. healthcare expenditure, patient volumes, population growth, aging demographics, disease burden, hospital utilization, reimbursement trends, healthcare workforce availability, medical infrastructure investment, and academic health system expansion.
Forecast assumptions also considered the increasing demand for complex tertiary and quaternary care, oncology services, cardiovascular procedures, neuroscience care, advanced surgical procedures, transplantation services, precision medicine, and technology-enabled healthcare delivery. The model further considered academic medical center capacity expansion, consolidation among health systems, growth in outpatient specialty services, and continued investment in advanced clinical capabilities through 2033.
Delivered Customizations
This report has been delivered with the following In-depth customizations
Client Request
Customization Delivered
Value Adds
Academic Medical Center (AMC) Benchmarking Analysis
Comprehensive benchmarking of leading U.S. academic medical centers based on research funding (NIH grants), clinical specialties, hospital capacity, faculty strength, medical education programs, research infrastructure, patient care capabilities, strategic partnerships, innovation initiatives, and regional presence. Compared institutional performance across key operational and research metrics to identify market leaders and emerging competitors.
Provides comprehensive benchmarking of leading AMCs, identifies institutional strengths and competitive gaps, supports strategic collaborations, partnership evaluation, investment decisions, and market expansion planning across the U.S. academic healthcare ecosystem.
Research Funding & Clinical Trial Activity Analysis
Detailed assessment of NIH funding distribution, sponsored research programs, clinical trial activity, translational research output, patient enrollment, and commercialization initiatives across leading academic medical centers. Evaluated funding trends by therapeutic area, research productivity, investigator-initiated studies, and industry-sponsored collaborations.
Supports opportunity assessment for research partnerships, clinical trial site selection, investment prioritization, commercialization planning, and long-term market forecasting based on institutional research strength.
Technology & Innovation Analysis
Assessment of emerging technologies adopted by U.S. academic medical centers, including AI-enabled clinical decision support, precision medicine, genomic sequencing, digital pathology, robotic-assisted surgery, telehealth platforms, advanced imaging, and electronic health record (EHR) integration. Evaluated innovation ecosystems, startup collaborations, technology commercialization, and translational medicine initiatives across major AMCs.
Helps identify future growth drivers, innovation leaders, technology adoption trends, commercialization opportunities, and competitive differentiation while supporting strategic partnerships and investment decisions.
Frequently Asked Questions About This Report
The U.S. academic medical centers market size was estimated at USD 1,110.9 billion in 2025 and is expected to reach 1,175.9 billion in 2026.
The U.S. academic medical centers market is expected to grow at a compound annual growth rate of 7.8% from 2026 to 2033 to reach USD 1,983.2 billion by 2033.
Some key players operating in the U.S. academic medical centers market include Weill Cornell Medicine, Cleveland Clinic, Vanderbilt University Medical Center, University Hospitals, The General Hospital Corporation (Massachusetts General Hospital), Stanford Health Care, UAB Health System, Mayo Foundation for Medical Education and Research (Mayo Clinic), Cedars-Sinai, The Johns Hopkins University, UC San Diego Health, Icahn School of Medicine at Mount Sinai.
Key factors that are driving the U.S. academic medical centers market growth include rising funding for academic & research programs, a growing shortage of physicians across the U.S., and an increasing number of AMCs.
Private AMC segment held the largest revenue share of 56.3% in 2025.
The more than 800 beds segment held a significant share of 42.5% in 2025.
The oncology segment held a significant share of 24.9% in 2025, while cardiovascular diseases is fastest growing segment.
About the Author(s)
Medical Devices Research Team
Healthcare · Medical DevicesThis report was authored by the medical devices research team at Grand View Research - comprising two research analysts, one senior research analyst, and one industry expert - with specialized expertise in the medical devices segment of the healthcare industry. All findings are based on proprietary healthcare databases, executive interviews, and regulatory analysis, subject to internal peer review prior to publication.
Last Updated:
Speak to Analyst

Customize this report to your needs - add regions, segments, or data points, with 20% free customization.
Or view our licence options:


ISO 9001:2015 & 27001:2022 Certified
We are GDPR and CCPA compliant! Your transaction & personal information is safe and secure. For more details, please read our privacy policy.


