
- Home
- »
- Medical Devices
- »
-
U.S. Acute Care Procedure Chair Market Size Report, 2033GVR Report cover

U.S. Acute Care Procedure Chair Market (2026 - 2033) Size, Share & Trends Analysis Report By Product (Powered Chairs, Manual Chairs), By Application (Multi-functional Treatment Chairs, Stretcher Chairs, General Procedure Chairs), By End Use, And Segment Forecasts
U.S. Acute Care Procedure Chair Market Summary
The U.S. acute care procedure chair market size was estimated at USD 103.19 million in 2025 and is projected to reach USD 182.38 million by 2033, growing at a CAGR of 7.37% from 2026 to 2033. This growth can be attributed to the rising volume of outpatient and emergency procedures, increasing demand for workflow-efficient patient handling solutions, expanding adoption of ergonomically advanced chairs in ambulatory surgery centers and hospital emergency departments, and growing emphasis on infection-control-compliant, multifunctional equipment that supports rapid patient turnover and improved clinical outcomes.
Key Market Trends & Insights
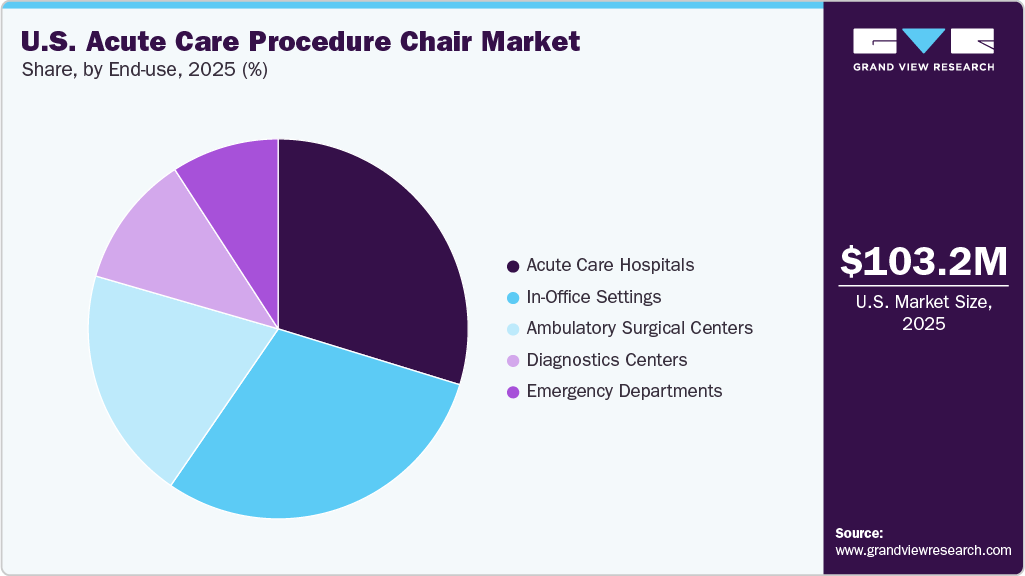
- By end use, the in-office setting segment led the market with the largest revenue share of 29.82% in 2025.
- By product, the powered segment is anticipated to grow at the fastest CAGR during the forecast period.
- By application, the gynecological chairs segment is anticipated to grow at the fastest CAGR during the forecast period
Market Size & Forecast
- 2025 Market Size: USD 103.19 Million
- 2033 Projected Market Size: USD 182.38 Million
- CAGR (2026-2033): 7.73%
Prism AI by Grand View Research Free to tryAsk a question about the U.S. acute care procedure chair marketTry asking✓Every figure cited from GVR research Prefer the report? Download free sample →
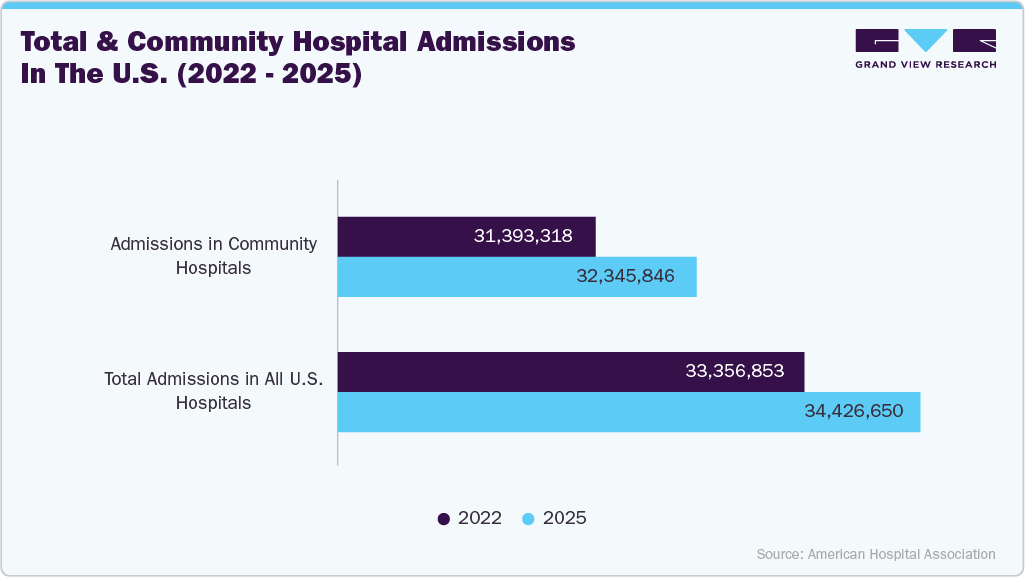
Rising hospitalization rates in the U.S. are driving up demand for acute care procedure chairs. The growing burden of diseases, surgical interventions, and age-related health conditions has led to more patients requiring inpatient care. As hospitals experience higher patient volumes, the need for efficient, adaptable, and comfortable procedure chairs increases to support examinations, treatments, and routine clinical workflows. This trend is expected to strengthen market growth in the years to come.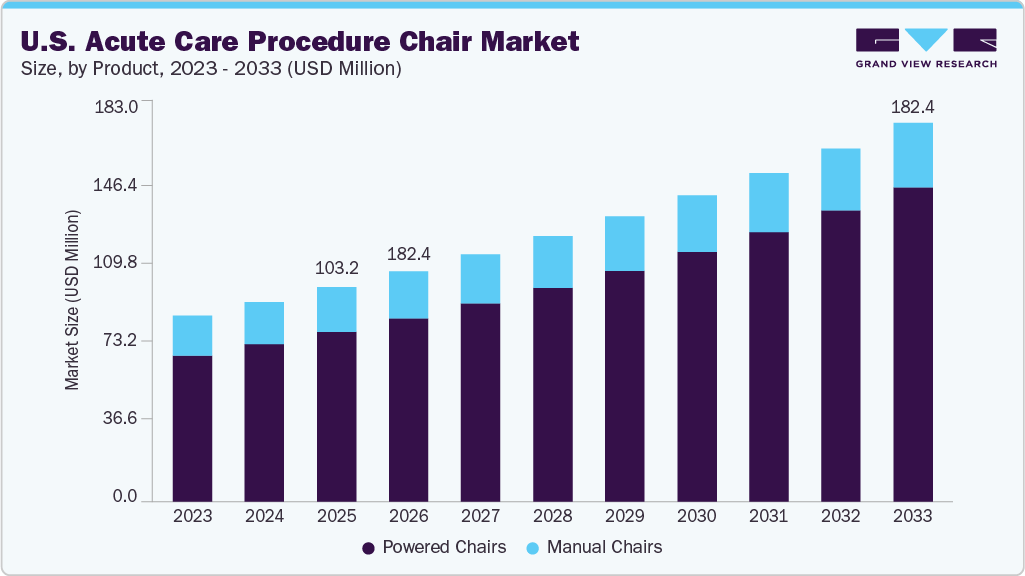 Source: Grand View Research, IR Documents, Primary Interviews, Paid DatabasesTo learn more about this report,
 Download Free Sample Report
In recent years, the country has experienced growth in admissions to community hospitals and other healthcare facilities.
 To learn more about this report, Download Free Sample Report
Thus, the rise in hospital admissions across the U.S. increases the number of patients requiring examinations, treatments, and short-term care, as a result strengthening the demand for acute care procedure chairs and supporting market growth as healthcare facilities manage higher patient volumes.
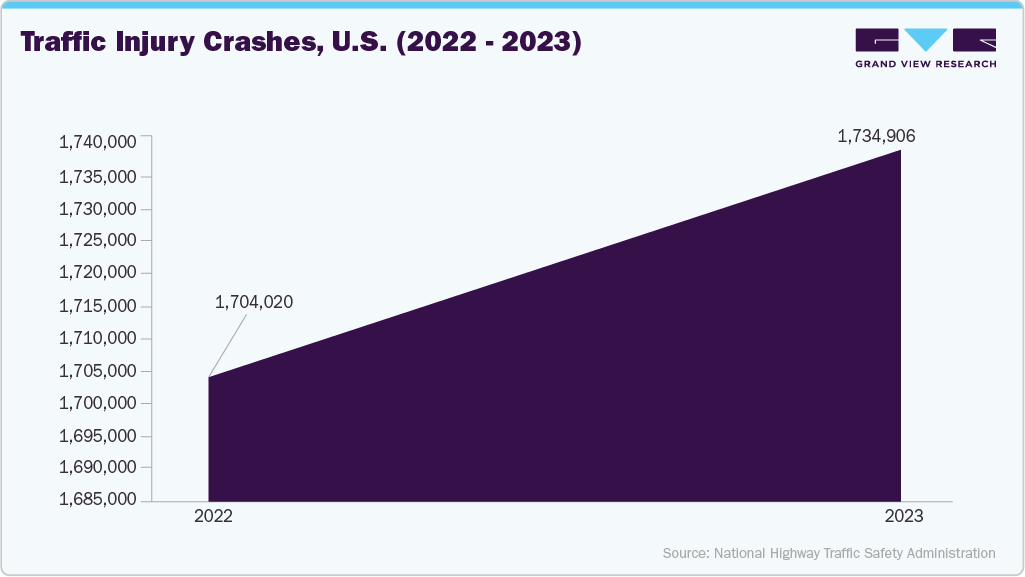
Moreover, the rising burden of road accidents and sports injuries is expected to drive growth in the U.S. acute care procedure chair industry. These incidents often require surgical procedures, increasing demand for multifunctional treatment and stretcher chairs. According to the National Safety Council, approximately 46,027 individuals died in motor vehicle crashes in the U.S. in 2022 and medically consulted injuries from such incidents totaled 5.2 million that year.
According to the National Safety Council, about 3.7 million people were treated in emergency departments for injuries related to recreational and sports equipment in 2023. The Council also reports that sports and recreational injuries rose by 20% in 2021, 12% in 2022, and 2% in 2023. As a result, demand for acute care procedure chairs is expected to increase. In addition, the National Highway Traffic Safety Administration reported a 1.8% rise in injury crashes from 2022 to 2023.
 To learn more about this report, Download Free Sample Report
State-By-State Motor Vehicle Crash Fatalities And Fatalities Per 100,000 Population, 2023
State
Deaths
Deaths per 100,000 population
Alabama
974
19.1
Alaska
60
8.2
Arizona
1,304
17.5
Arkansas
596
19.4
California
4,061
10.4
Colorado
720
12.2
Connecticut
308
8.5
Delaware
135
13.1
District of Columbia
44
6.5
Florida
3,396
15.0
Georgia
1,615
14.6
Hawaii
93
6.5
Idaho
275
14.0
Illinois
1,241
9.9
Indiana
898
13.1
Iowa
377
11.8
Kansas
387
13.2
Kentucky
814
18.0
Louisiana
811
17.7
Maine
135
9.7
Maryland
621
10.0
Massachusetts
343
4.9
Michigan
1,094
10.9
Minnesota
409
7.1
Mississippi
732
24.9
Missouri
991
16.0
Montana
208
18.4
Nebraska
227
11.5
Nevada
389
12.2
New Hampshire
130
9.3
New Jersey
606
6.5
New Mexico
437
20.7
New York
1,114
5.7
North Carolina
1,561
14.4
North Dakota
106
13.5
Ohio
1,242
10.5
Oklahoma
718
17.7
Oregon
587
13.9
Pennsylvania
1,211
9.3
Rhode Island
71
6.5
South Carolina
1,047
19.5
South Dakota
140
15.2
Tennessee
1,323
18.6
Texas
4,291
14.1
Utah
280
8.2
Vermont
69
10.7
Virginia
913
10.5
Washington
810
10.4
West Virginia
260
14.7
Wisconsin
583
9.9
Wyoming
144
24.7
U.S. total
40,901
12.2
Source: Insurance Institute for Highway Safety, Highway Loss Data Institute
As a result, the substantial number of individuals affected by road-traffic accidents and sports-related injuries is expected to drive demand for acute care procedure chairs in the coming years.
Market Concentration & Characteristics
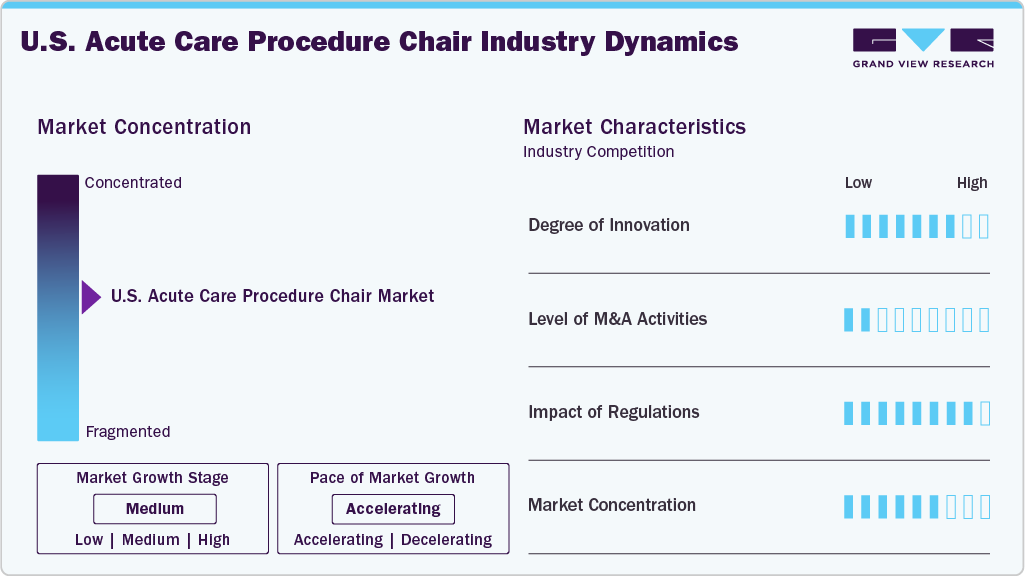
The U.S. acute care procedure chair industry is expanding steadily as hospitals, outpatient centers, and emergency departments increasingly adopt ergonomic, workflow-efficient chairs that enhance patient handling, reduce clinician strain, and support high procedural throughput. Growth is fueled by rising hospitalization rates, increasing volumes of outpatient and emergency procedures, a shift toward minimally invasive treatments, and a widening adoption of powered, multi-position chairs across care settings.
Innovation is high in U.S. acute care procedure chair industry, shaped by rapid upgrades in powered motion systems, ADA-compliant design, advanced ergonomics, and integrated safety technologies. Manufacturers are adding low-entry heights, programmable positioning, Active Sensing Technology, wider transfer surfaces, and hygiene-centric materials. New powered chairs and compact multifunctional systems are improving clinical efficiency across ophthalmic, ENT, gynecologic, emergency, and outpatient settings. Expansion of programmable, fully electric systems and broader use of premium materials and modular accessories continue to elevate product sophistication.
 To learn more about this report, Download Free Sample Report
M&A activity in U.S. acute care procedure chair industry is moderate, primarily focused on expanding product portfolios, enhancing manufacturing capabilities, and strengthening distribution within surgical and outpatient care segments. Strategic collaborations-such as exclusive distribution agreements and facility expansions-remain more prevalent than large-scale acquisitions. Manufacturers partner with international chair specialists to introduce advanced multifunctional, powered, and specialty-specific procedure chairs to the U.S., reflecting targeted consolidation aimed at accelerating market penetration.
Regulatory influence is significant. Procedure chairs fall under FDA 21 CFR 880.6140 and must meet Class I device requirements. New U.S. Access Board standards effective September 2024 mandate 17-inch low seat heights for accessible medical diagnostic equipment, influencing product redesigns and accelerating adoption of ADA-compliant models. Compliance with safety, structural, and ergonomic standards, plus facility accreditation and reimbursement frameworks (MS-DRG for inpatient, APC/OPPS for outpatient), increases design complexity and lengthens validation timelines. These regulatory obligations are driving manufacturers toward safer, more standardized, and accessibility-focused innovations.
The U.S. acute care procedure chair industry is moderately concentrated, driven by a mix of established medical furniture manufacturers and specialized procedure-chair producers. Key players include Stryker, Midmark, MTI, Champion Manufacturing, UMF Medical, Haag-Streit Group, Infinium Medical, GF Health Products, and others. High-volume demand for powered chairs strengthens the position of firms offering advanced ergonomic systems, while diversified portfolios across ophthalmic, ENT, gynecological, and multifunctional treatment chairs allow leaders to maintain share across multiple clinical environments. Competition is shaped by innovation speed, regulatory compliance, facility partnerships, and the ability to provide durable, ADA-compliant, multi-specialty solutions.
Product Insights
The powered chairs segment accounted for the largest market revenue share in 2025. This dominance can be attributed to the growing demand for technologically advanced seating systems that enhance workflow efficiency and patient comfort in acute care settings. Powered procedure chairs offer superior adjustability, automated positioning, and smooth mobility, allowing clinicians to perform examinations and minor procedures with greater precision and reduced physical strain. Their ability to support rapid height adjustments, tilt functions, and multi-position configurations significantly improves patient accessibility, especially for individuals with limited mobility.
The manual chairs segment is expected to register at the fastest CAGR during the forecast period. The manual chairs segment is expanding as facilities prioritize reliable, low-maintenance equipment that supports high patient turnover and cost-efficient operations. Hospitals, emergency departments, and outpatient centers continue to adopt manual systems to reduce servicing needs and simplify workflow. Growth is supported by budget-constrained procurement cycles, increased use in routine procedures, and wider availability of ADA-aligned designs that improve accessibility. New product introductions focused on operational efficiency further strengthen demand and sustain segment momentum.
Application Insights
The multi-functional treatment chairs segment accounted for the largest market revenue share in 2025. This dominance can be attributed to the growing preference for versatile equipment that enables healthcare facilities to perform a wide range of procedures, including examinations, diagnostics, minor surgeries, and outpatient treatments, all on a single, adaptable platform. Multi-functional chairs enable transitions between various positions, reducing the need for multiple devices and helping hospitals optimize space, lower equipment costs, and enhance workflow efficiency. Their ergonomic design, advanced adjustability, and integration of features such as electronic controls, safety locks, and enhanced patient support systems also contribute to improved patient comfort and caregiver convenience.
The gynecological chairs segment is expected to register the fastest CAGR during the forecast period, driven by rising patient volumes for screening, diagnosis, and routine women’s health procedures. The increasing incidence of gynecological conditions and growing utilization of outpatient and hospital-based services are driving procurement. Providers are standardizing equipment to enhance positioning consistency, improve room turnover, and ensure workflow compliance. Expansion of specialty clinics and broader use of procedure-focused setups further strengthen segment demand.
End Use Insights
The in-office setting care hospitals segment led the market with the largest revenue share of 29.82% in 2025. This dominance can be attributed to the high patient inflow in hospital-based acute care departments, the rising number of surgical and minimally invasive procedures, and the greater emphasis on efficient patient handling and safety protocols. Acute care hospitals rely heavily on advanced procedure chairs to support rapid patient turnover, precise positioning, and seamless workflow integration across various departments. The availability of higher budgets in hospitals compared to other care settings also enables greater adoption of technologically advanced, powered, and ergonomic chair systems.
 To learn more about this report, Download Free Sample Report
The ambulatory surgical centers segment is expected to register at the fastest CAGR during the forecast period, as procedure volumes continue shifting from inpatient to outpatient settings. ASCs are scaling capacity to manage higher surgical throughput, driving demand for procedure chairs that support efficient turnover and multi-specialty use. Expansion of Medicare-certified centers and broader adoption of same-day surgical models are increasing procurement. Standardization of equipment across new and existing facilities further supports sustained growth in this segment.
Key U.S. Acute Care Procedure Chair Company Insights
Key players in the U.S. acute care procedure chair industry are expanding product portfolios, upgrading manufacturing capacity, and strengthening distribution reach across hospital, ASC, and outpatient settings. Companies such as Stryker, Champion Manufacturing, Midmark, MTI, UMF Medical, Infinium Medical, GF Health Products, Haag-Streit, and others are advancing powered-motion systems, improving ADA-aligned accessibility features, and integrating safety and workflow-support technologies. Firms are also investing in regulatory compliance, facility partnerships, and production expansions to support broader adoption across clinical specialties and high-throughput care environments.
Key U.S. Acute Care Procedure Chair Companies:
- Stryker
- Champion Manufacturing Inc.
- Midmark Corporation
- MTI Medical Technology Industries, Inc.
- Zimed Healthcare LLC
- United Metal Fabricators, Inc. (UMF Medical)
- Infinium Medical (Lemi MD Brusaferri & C. srl)
- GF Health Products, Inc.
- Wy’East Medical
- Hill Laboratories Company
- IOA Healthcare Furniture
- Digiterm Ltd.
Recent Developments
-
In August 2025, UMF Medical introduced the LibertyPRO, a next-generation procedure chair series designed for versatility, durability, and enhanced patient comfort. Engineered with a 650 lb weight capacity to support a broad range of patient needs, LibertyPRO also offers optional TruComfort+ Support Rails with integrated blood pressure positioning to improve stability and help ensure more accurate vitals collection during procedures.
-
In May 2025, Midmark Corp., a medical solutions provider committed to enhancing clinical environments and improving care delivery, introduced the Midmark 631 Procedure Chair as the first and only U.S. Access Board (USAB) compliant procedure chair. Designed to address growing accessibility needs in modern healthcare settings, the chair supports safer, more inclusive patient experiences while improving workflow efficiency for caregivers.
-
In April 2025, UMF Medical introduced the FusionFREEDOM Exam Chair, designed to enhance accessibility for patients with mobility challenges and support more inclusive care environments. The chair features a low 17-inch seat height, optional TruComfort Support Rails to facilitate safe and secure transfers, and an ADA-compliant design, making it well-suited for practices prioritizing patient safety, comfort, and accessibility.
U.S. Acute Care Procedure Chair Market Report Scope
Report Attribute
Details
Market size value in 2026
USD 110.88 million
Revenue forecast in 2033
USD 182.38 million
Growth rate
CAGR of 7.37% from 2026 to 2033
Base year for estimation
2025
Historical data
2021 - 2024
Forecast period
2026 - 2033
Quantitative units
Revenue in USD million/billion and CAGR from 2026 to 2033
Report coverage
Revenue forecast, company ranking, competitive landscape, growth factors, and trends
Segments covered
Product, application, end use
Country scope
U.S.
Key companies profiled
Stryker; Champion Manufacturing Inc.; Midmark Corporation; MTI Medical Technology Industries Inc.; Zimed Healthcare LLC; United Metal Fabricators Inc. (UMF Medical); Infinium Medical (Lemi MD Brusaferri & C. srl); GF Health Products Inc.; Wy’East Medical; Hill Laboratories Company; IOA Healthcare Furniture; Digiterm Ltd.
Customization scope
Free report customization (equivalent up to 8 analyst’s working days) with purchase. Addition or alteration to country, & segment scope.
Pricing and purchase options
Avail customized purchase options to meet your exact research needs. Explore purchase options
U.S. Acute Care Procedure Chair Market Report Segmentation
This report forecasts revenue growth at country levels and provides an analysis of the latest industry trends in each of the sub-segments from 2021 to 2033. For this study, Grand View Research has segmented the U.S. acute care procedure chair market report based on product, application, and end use:
-
U.S. Acute Care Procedure Chair Product Outlook (Revenue, USD Million, 2021 - 2033)
-
Powered Chairs
-
Manual Chairs
-
-
U.S. Acute Care Procedure Chair Application Outlook (Revenue, USD Million, 2021 - 2033)
-
Multi-functional Treatment Chairs
-
Stretcher Chairs
-
General Procedure Chairs
-
Ophthalmic Chairs
-
Gynecological Chairs
-
ENT Chairs
-
Plastic Surgeries
-
-
U.S. Acute Care Procedure Chair End Use Outlook (Revenue, USD Million, 2021 - 2033)
-
Acute Care Hospitals
-
In-office Settings
-
Ambulatory Surgical Centers
-
Diagnostic Centers
-
Emergency Departments
-
Frequently Asked Questions About This Report
The U.S. acute care procedure chair market size was valued at USD 103.19 million in 2025 and is expected to reach USD 110.88 million in 2026.
The U.S. acute care procedure chair market is expected to grow at a compound annual growth rate of 7.37% from 2025 to 2033 to reach USD 182.38 million by 2033.
Powered chairs segment held the largest revenue share in 2025. This dominance can be attributed to the growing demand for technologically advanced seating systems that enhance workflow efficiency and patient comfort in acute care settings.
Companies such as Stryker, Champion Manufacturing, Midmark, MTI, UMF Medical, Infinium Medical, GF Health Products, Haag-Streit, and others are advancing powered-motion systems, improving ADA-aligned accessibility features, and integrating safety and workflow-support technologies.
Rising volume of outpatient and emergency procedures, increasing demand for workflow-efficient patient handling solutions, expanding adoption of ergonomically advanced chairs in ambulatory surgery centers and hospital emergency departments, and growing emphasis on infection-control-compliant, multifunctional equipment that supports rapid patient turnover and improved clinical outcomes are the key factors driving growth.
About the Author(s)
Medical Devices Research Team
Healthcare · Medical DevicesThis report was authored by the medical devices research team at Grand View Research - comprising two research analysts, one senior research analyst, and one industry expert - with specialized expertise in the medical devices segment of the healthcare industry. All findings are based on proprietary healthcare databases, executive interviews, and regulatory analysis, subject to internal peer review prior to publication.
Last Updated:
Speak to Analyst

Customize this report to your needs - add regions, segments, or data points, with 20% free customization.
Or view our licence options:


ISO 9001:2015 & 27001:2022 Certified
We are GDPR and CCPA compliant! Your transaction & personal information is safe and secure. For more details, please read our privacy policy.


