
- Home
- »
- Consumer F&B
- »
-
U.S. Canned Food Market Size & Share Report, 2026-2033GVR Report cover

U.S. Canned Food Market (2026 - 2033)
Size, Share & Trends Analysis Report By Product (Meat, Seafood, Fruits, Vegetables), By Can Size (No. 1, No. 2, No.10, No.300, No. 2 ½), By Country (New York, Pennsylvania, Washington, D.C., New Jersey), By Segment Forecasts
Market Size, 2025
$72.1BMarket Estimate, 2026
$75.0BMarket Forecast, 2033
$102.9BCAGR, 2026–2033
4.6%U.S. Canned Food Market Summary
The U.S. canned food market size was valued at USD 72.1 billion in 2025 and is expected to grow from USD 75.0 billion in 2026 to USD 102.9 billion in 2033, at a CAGR of 4.6% from 2026 to 2033. The increasing demand for convenient, long-lasting, ready-to-eat food products primarily drives the market's growth. Busy lifestyles, increasing urbanization, and the need for affordable meal options encourage consumers to choose canned foods. Additionally, advancements in food preservation and rising demand for nutritious packaged foods continue to support market growth.
Key Market Trends & Insights
- By product: Canned seafood segment held the largest market share of 29.8% in 2025
- By can size: No. 300 size segment held the largest market share of 34.0% in 2025
Market Size & Forecast
- Market Size in 2025: USD 72.1 Billion
- Estimated Market Size in 2026: USD 75.0 Billion
- Projected Market Size by 2033: USD 102.9 Billion
- CAGR (2026-2033): 4.6%
Three ways to get this report
Buy it, customize it, or ask a question.Ask an Analyst
Analyst response in 1 business day
- AccessReport author, directly
- Reply timeWithin 1 working day
- No sales callDirect answer only
- FormatEmail reply
- CostFree, no cost
Get the Full Report
What the study covers
- FormatsPDF · Excel · Dashboard
- Timeline2026–2033 annual, 2025 base
- Coverage20+ countries, 5 regions
- Companies10+ key players profiled
Customize the Report
20% free customization
- IncludeCountries, segments, points
- TailorTo your product definition
- ExtendDeeper competitor detail
- OrA fully bespoke study
- Turnaround5–10 working days
The U.S. canned food industry is also supported by strong retail distribution through supermarkets, grocery stores, and online platforms. Consumers increasingly prefer canned fruits, vegetables, seafood, and soups because they are easy to store and reduce food waste. Furthermore, innovations in sustainable packaging and healthier product offerings are creating new growth opportunities for manufacturers.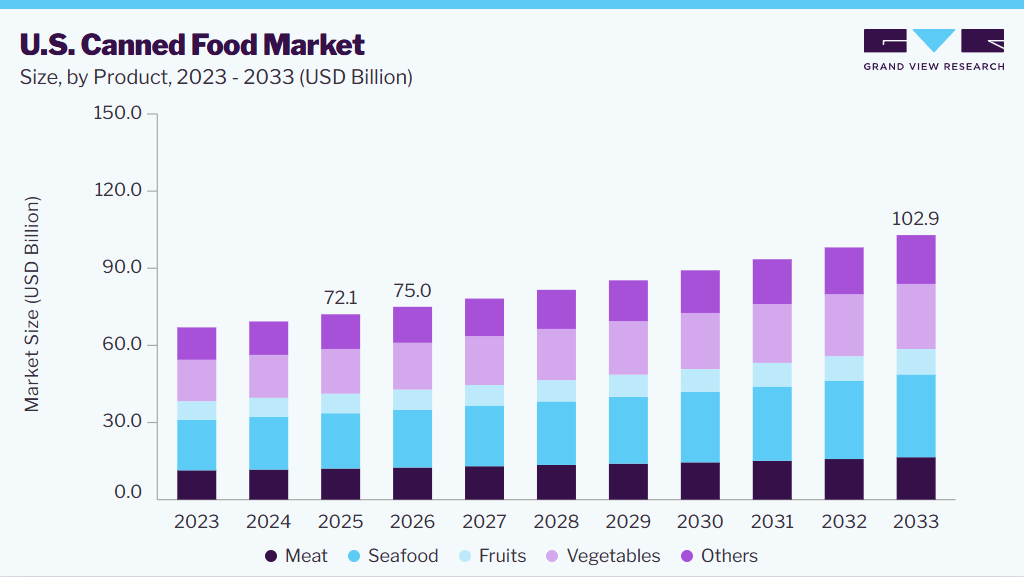 Source: Grand View Research, IR Documents, Primary Interviews, Paid DatabasesTo learn more about this report,
 Download Free Sample Report
The industry also benefits from strong domestic agricultural production, which ensures a steady supply of raw materials for food processing. Rising exports of canned food products have expanded market opportunities for U.S. manufacturers in international markets. Moreover, continuous investments in automation and advanced processing technologies are improving production efficiency and product quality.
Market Dynamics
Consumers are increasingly choosing foods that can be stored for extended periods without refrigeration, making canned products a practical option for households and institutions. This trend is supported by the need for reliable pantry staples during emergencies and changing consumption habits. Shelf-stable foods also help retailers manage inventory more efficiently by reducing spoilage losses. According to the data published in September 2025, 24% of tinned fish consumers select canned seafood specifically for its convenience, highlighting how strongly ease-of-use influences purchasing decisions in this category. As a result, manufacturers continue to expand their canned food portfolios to meet evolving demand.
Canned food manufacturers must comply with rigorous standards covering processing, labeling, packaging, and product quality. Meeting these requirements requires continuous investment in quality assurance systems, testing, and documentation. Any regulatory changes or non-compliance can lead to product recalls, financial penalties, and reputational damage. In May 2025, Hormel Foods issued a recall of more than 256,000 pounds of its canned “Dinty Moore Beef Stew” after reports from consumers of foreign matter, specifically wood pieces, in the product. The U.S. Department of Agriculture’s Food Safety and Inspection Service (FSIS) announced a recall impacted distribution across the country and advised customers to either dispose of or return the affected cans for safety reasons. These compliance obligations increase operational complexity and production costs across the industry.
Analyst Perspective
The U.S. canned food market is characterized by strong consumer preference for convenience, affordability, and products that can be stored for extended periods. From an analyst perspective, canned foods remain relevant as practical pantry staples that require minimal preparation and offer flexibility across everyday meals. The market is also evolving as consumers increasingly seek healthier ingredients, cleaner labels, and greater product variety. Competition from fresh and frozen alternatives creates pressure on manufacturers to differentiate through quality, nutrition, packaging, and innovation.
Product Insights
The canned seafood market segment accounted for the largest revenue share of 29.8% in 2025. The seafood segment is driven by strong consumer demand for protein-rich foods that offer convenience and consistent availability throughout the year. Canned seafood provides an economical alternative to fresh varieties while maintaining nutritional value and versatility in meal preparation. Growing interest in healthy eating has also increased the consumption of products such as tuna, salmon, and sardines. In addition, product innovations, including flavored and premium offerings, are attracting a wider consumer base. According to the data published in March 2026, Fishwife is expanding its retail presence through Costco, bringing its premium tinned seafood products to a wider customer base. The move highlights the growing mainstream demand for high-quality, sustainable seafood options and gives the brand greater visibility among Costco’s large membership audience.
The canned vegetable market segment is projected to grow significantly at a CAGR of 4.9% from 2026 to 2033. The canned vegetables segment is supported by increasing demand for convenient ingredients that require minimal preparation in home and foodservice kitchens. Year-round availability of seasonal vegetables ensures a consistent supply regardless of harvest cycles or weather conditions. Consumers also value canned vegetables for their affordability and ability to reduce food waste through their longer shelf life. Expanding product varieties, including low-sodium and organic options, are further strengthening demand across the U.S. canned food market.
Can Size Insights
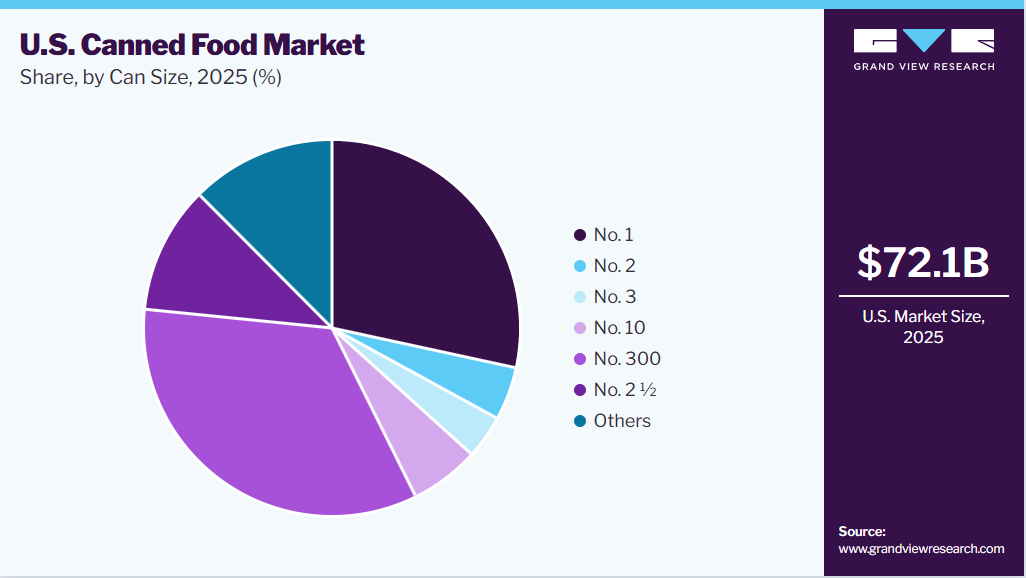
The No. 300 can size dominated the U.S. canned food industry, accounting for the largest revenue share of 34.0% in 2025. The No. 300 can size is widely used in the U.S. canned food market because it offers a practical balance between portion size, consumer convenience, shelf stability, and manufacturing efficiency. Demand is driven by household consumption, ready-to-eat meal trends, foodservice applications, and the need for standardized packaging across products such as vegetables, fruits, beans, and sauces. Its relatively compact size also supports easy storage, transportation, and retail shelf merchandising.
 To learn more about this report, Download Free Sample Report
The No.10 can size market segment is projected to grow at the fastest CAGR of 4.9% from 2026 to 2033. The No. 10 can size segment is primarily supported by demand from restaurants, catering services, and institutional food providers requiring larger quantities. Its high-volume capacity helps reduce packaging waste and improve operational efficiency in commercial kitchens. The format is preferred for bulk food preparation due to its cost-effectiveness and convenience in large-scale meal production. Growing foodservice activity in the U.S. continues to contribute to the growth of the U.S. canned food industry.
Country Insights
The U.S. canned food market’s growth is driven by increasing demand for convenient meal solutions that fit into fast-paced lifestyles. Growing awareness of food availability and emergency preparedness is encouraging consumers to maintain stored food supplies. Expansion of private-label products and improved product formulations are attracting price-conscious and health-focused buyers. Additionally, advancements in packaging designs and distribution networks are helping manufacturers reach a broader consumer base.
New York Canned Food Market Trends
The New York region held the largest share of the U.S. canned food market in 2025, at 11.1%. The canned food market in New York is supported by a large urban population with diverse dietary preferences and high demand for convenient meal options. The presence of extensive retail networks and foodservice establishments creates strong opportunities for canned food suppliers. Growing interest in ethnic cuisines also drives the availability of a wider range of canned ingredients and specialty products. Additionally, the state’s developed logistics infrastructure helps ensure efficient product movement across distribution channels.
Texas Canned Food Market Trends
The Texas canned food market is expected to grow at the fastest CAGR of 5.9% over the forecast period. The canned food market in Texas is driven by its expanding population and strong demand from households, restaurants, and institutional buyers. The state’s well-established agricultural sector provides access to key raw materials used in canned food production. Increasing investments in food processing facilities and supply chain capabilities are strengthening regional market growth. Furthermore, the growing presence of supermarkets and wholesale distributors supports wider product accessibility across the state.
Key U.S. Canned Food Company Insights
The U.S. canned food industry is characterized by the presence of several established manufacturers competing across multiple product categories. Major companies maintain their market positions through extensive distribution networks, strong brand recognition, and diverse product portfolios. Private-label brands are also gaining traction by offering affordable alternatives to consumers through major retail chains.
The U.S. canned food market remains moderately competitive, with companies focusing on product innovation, packaging improvements, and strategic partnerships to strengthen their presence. Regional players continue to contribute by catering to specific consumer preferences and local demand patterns.
Key U.S. Canned Food Companies
-
Bumble Bee Seafoods
-
StarKist Co
-
ICICLE SEAFOODS, INC.
-
LDH (La Doria) Ltd
-
Thai Union Group PCL
-
American Tuna, Inc.
-
Tri Marine Group
-
NIPPON SUISAN KAISHA, LTD
-
Conagra Brands, Inc.
-
Connors Bros. Ltd.
Competitive Benchmarking
Category
Operating Strategies
Competitive Edge
Weakness
Established Players (StarKist Co.; ICICLE SEAFOODS, INC.; LDH (La Doria) Ltd)
Scale production, strengthen branded and private-label portfolios, optimize distribution, and expand across retail and foodservice channels.
Strong brand recognition, extensive distribution networks, established retailer relationships, and large-scale processing capabilities.
Higher operating costs, complex supply chains, and exposure to commodity and input-cost fluctuations.
Emerging Players (American Tuna, Inc.)
Target niche segments, introduce premium and health-oriented products, emphasize product innovation, and build direct-to-consumer channels.
Greater agility, faster innovation, differentiated offerings, and stronger focus on emerging consumer preferences.
Smaller production scale, limited distribution reach, and lower bargaining power with major retailers.
Recent Developments
-
In February 2025, several canned tuna products from major brands such as Genova, Trader Joe’s, and Van Camp’s were voluntarily recalled due to a potential risk of Clostridium botulinum contamination, linked to a manufacturing defect in can seals.
-
In January 2025, 100 Mistérios expanded into the U.S. market with the launch of 100 Misterios USA LLC, bringing its premium Portuguese canned seafood products to American consumers. The move highlights growing demand for gourmet tinned seafood and supports the broader trend of premiumization in the U.S. shelf-stable food market.
U.S. Canned Food Market Report Scope
Report Attribute
Details
Market size in 2025
USD 72.1 billion
Estimated market size in 2026
USD 75.0 billion
Projected market size by 2033
USD 102.9 billion
Growth rate
CAGR of 4.6% from 2026 to 2033
Actuals
2021 - 2025
Forecast period
2026 - 2033
Quantitative units
Revenue in USD million/billion, volume in million units, and CAGR from 2026 to 2033
Report coverage
Revenue forecast, volume forecast, company ranking, competitive landscape, growth factors, and trends
Segments covered
Product, can size, and region
Country scope
U.S.
Key companies profiled
Bumble Bee Seafoods; StarKist Co; ICICLE SEAFOODS, INC.; LDH (La Doria) Ltd; Thai Union Group PCL; American Tuna, Inc.; Tri Marine Group; NIPPON SUISAN KAISHA, LTD; Conagra Brands, Inc.; Connors Bros. Ltd.
Customization scope
Free report customization (equivalent up to 8 analysts’ working days) with purchase. Addition or alteration to country, regional & segment scope.
Pricing and purchase options
Avail customized purchase options to meet your exact research needs. Explore purchase options
U.S. Canned Food Market Report Segmentation
This report forecasts revenue & volume growth at the regional and country levels and provides an analysis of the latest industry trends and opportunities in each of the sub-segments from 2021 to 2033. For this study, Grand View Research has segmented the U.S. canned food market report based on product, can size, and country:
-
Product Outlook (Volume, Million Units; Revenue, USD Million/Billion, 2021 - 2033)
-
Meat
-
Seafood
-
Fruits
-
Vegetables
-
Others
-
-
Can Size Outlook (Volume, Million Units; Revenue, USD Million/Billion, 2021 - 2033)
-
No. 1
-
No. 2
-
No. 3
-
No. 10
-
No. 300
-
No. 2 ½
-
Others
-
-
Regional Outlook (Volume, Million Units; Revenue, USD Million/Billion, 2021 - 2033)
-
New York
-
Pennsylvania
-
Washington, D.C.
-
New Jersey
-
Ohio
-
Massachusetts
-
Texas
-
California
-
Illinois
-
Research Methodology
The U.S. canned food market figures in this report are based on a proven research process that combines executive interviews with secondary research from proprietary databases, company filings, and recognized regulatory and institutional sources. Market size is built through value-chain sizing—reconciling supply-side and demand-side estimates—and triangulated with bottom-up and top-down approaches. Every estimate passes multiple levels of expert validation before publication, with each U.S. canned food segment quantified using the revenue-capture definitions in the table below.
Segment Definition
Segment - Product
Revenue capture definition
Meat
Canned meat generates revenue by providing convenient, shelf-stable protein for household meals, quick preparation, and foodservice use. Suppliers capture value through meat quality, formulation, portioning, and product positioning. Revenue is realized through retail cans, multipacks, institutional supply, and foodservice channels.
Seafood
Canned seafood generates revenue by offering ready-to-eat protein with convenient storage and preparation. Value is differentiated through species selection, sourcing, preparation style, pack size, and product quality. Revenue is captured through branded and private-label retail products, multipacks, and foodservice distribution.
Fruits
Canned fruits generate revenue by delivering convenient fruit formats with extended storage suitability for household consumption and food preparation. Suppliers capture value through fruit variety, cut style, packing medium, quality, and presentation. Revenue is primarily generated through retail packaging, multipacks, and institutional or foodservice sales.
Vegetables
Canned vegetables generate revenue by providing convenient, ready-to-use vegetable options for everyday cooking and meal preparation. Suppliers capture value through vegetable selection, cut format, preparation method, pack size, and quality positioning. Revenue is generated through household retail products, private-label offerings, bulk packs, and foodservice channels.
Others
Other canned food products generate revenue across specialized categories that serve specific consumption, culinary, or convenience needs. Suppliers capture value through formulation, ingredient combinations, functionality, packaging, and differentiated positioning. Revenue is realized through retail products, specialty offerings, institutional sales, and foodservice distribution.
Estimation Model
Each layer progressively narrows the population pool and applies a conversion rate to arrive at addressable revenue.
01
02
03
04
Consumption Universe Layer
Access & Availability Layer
Purchase & Usage Layer
Revenue Conversion Layer
Who consumes canned food in the U.S.?
Who can access canned food?
Who regularly purchases canned food?
How is revenue generated from canned food consumers?
Covers U.S. consumers using canned food across household meals, snacks, cooking, and food preparation.
Covers consumers reached through supermarkets, mass retailers, club stores, convenience stores, e-commerce, and foodservice channels.
Focuses on consumers purchasing canned food for everyday meals, convenience, pantry stocking, and cooking.
Captures monetization across canned meat, seafood, fruits, vegetables, and other canned food products.
Delivered Customizations
This report has been delivered with the following In-depth customizations
CLIENT REQUEST
CUSTOMIZATION DELIVERED
VALUE ADDS
U.S. Canned Food Consumer & Category Demand Analysis
Assessed U.S. consumer demand across canned soups, vegetables, fruits, beans, meat/seafood, sauces, and ready meals, with emphasis on usage occasions, convenience needs, meal preparation habits, health perceptions, value sensitivity, and evolving portion preferences.
Identifies the highest-potential consumption occasions and product categories, helping prioritize innovation, pack architecture, claims, price points, and consumer targeting.
U.S. Canned Food Competitive & Brand Landscape
Benchmarked major branded and private-label players across assortment breadth, pricing architecture, pack formats, channel presence, brand positioning, promotional intensity, innovation pipelines, and premium/value strategies.
Pinpoints competitive pressure points and market white spaces, enabling sharper differentiation, portfolio optimization, and stronger positioning across retail and e-commerce channels.
U.S. Canned Food Supply, Manufacturing & Cost Outlook
Evaluated key agricultural inputs, processing capacity, canning and packaging economics, seasonal sourcing patterns, freight exposure, inventory dynamics, import dependencies, and factors influencing production costs and availability.
Supports sourcing and margin planning by identifying cost sensitivities, supply vulnerabilities, procurement opportunities, and areas where packaging or manufacturing efficiencies can improve competitiveness.
Frequently Asked Questions About This Report
The canned vegetables market is projected to grow at the fastest CAGR of 4.9% from 2026 to 2033.
The No.300 size led the market with a 34.0% revenue share in 2025.
The No.10 can size is projected to grow at a CAGR of 4.9% from 2026 to 2033.
Key players include Bumble Bee Seafoods, StarKist Co, ICICLE SEAFOODS, INC., LDH (La Doria) Ltd, Thai Union Frozen Products, American Tuna, Inc., Tri Marine Group, NIPPON SUISAN KAISHA, LTD, Conagra Brands, Inc., and Connors Bros. Ltd.
Key factors driving the U.S. canned food market include growing demand for affordable pantry staples, increased home meal preparation, emergency food stockpiling, and product innovations such as low-sodium, organic, and preservative-free options.
The U.S. canned food market size was valued at USD 72.1 billion in 2025 and is estimated at USD 75.0 billion for 2026.
The canned seafood market led with a 29.8% revenue share in 2025.
The U.S. canned food market is expected to grow at a CAGR of 4.6% from 2026 to 2033, reaching USD 102.9 billion by 2033.
About the Author(s)
Consumer F&B Research Team
Consumer Goods · Consumer F&BThis report was authored by the consumer f&b research team at Grand View Research - comprising two research analysts, one senior research analyst, and one industry expert - with specialized expertise in the consumer f&b segment of the consumer goods industry. All findings are based on proprietary consumer goods databases, executive interviews, and regulatory analysis, subject to internal peer review prior to publication.
Last Updated:
Speak to Analyst

Customize this report to your needs - add regions, segments, or data points, with 20% free customization.
Or view our licence options:


ISO 9001:2015 & 27001:2022 Certified
We are GDPR and CCPA compliant! Your transaction & personal information is safe and secure. For more details, please read our privacy policy.


