
- Home
- »
- Homecare & Decor
- »
-
U.S. Helicopter Tourism Market Size & Share Report, 2033GVR Report cover

U.S. Helicopter Tourism Market (2026 - 2033)
Size, Share & Trends Analysis Report By Tourism Type (Sightseeing & Scenic & Luxury & Private Tourism), By Destination Type (Urban, Coastal, Mountain), By Booking Channel Type (Direct / Operator, Online Travel Platforms), And Segment Forecasts
Market Size, 2025
$448.6MMarket Estimate, 2026
$464.5MMarket Forecast, 2033
$592.5MCAGR, 2026–2033
3.5%U.S. Helicopter Tourism Market Summary
The U.S. helicopter tourism market size was valued at USD 448.6 million in 2025 and is projected to grow from USD 464.5 million in 2026 to USD 592.5 million by 2033, at a CAGR of 3.5% from 2026 to 2033. The market growth is driven by rising demand for experiential and adventure-based travel, increasing tourist interest in aerial sightseeing, and the popularity of helicopter tours across destinations such as the Grand Canyon, Las Vegas, Hawaii, Alaska, and New York City.
Key Market Trends & Insights
- By tourism type: Sightseeing & scenic tourism segment held the largest market share of 50.4% in 2025.
- By destination type: Urban segment held the largest market share of 36.4% in 2025.
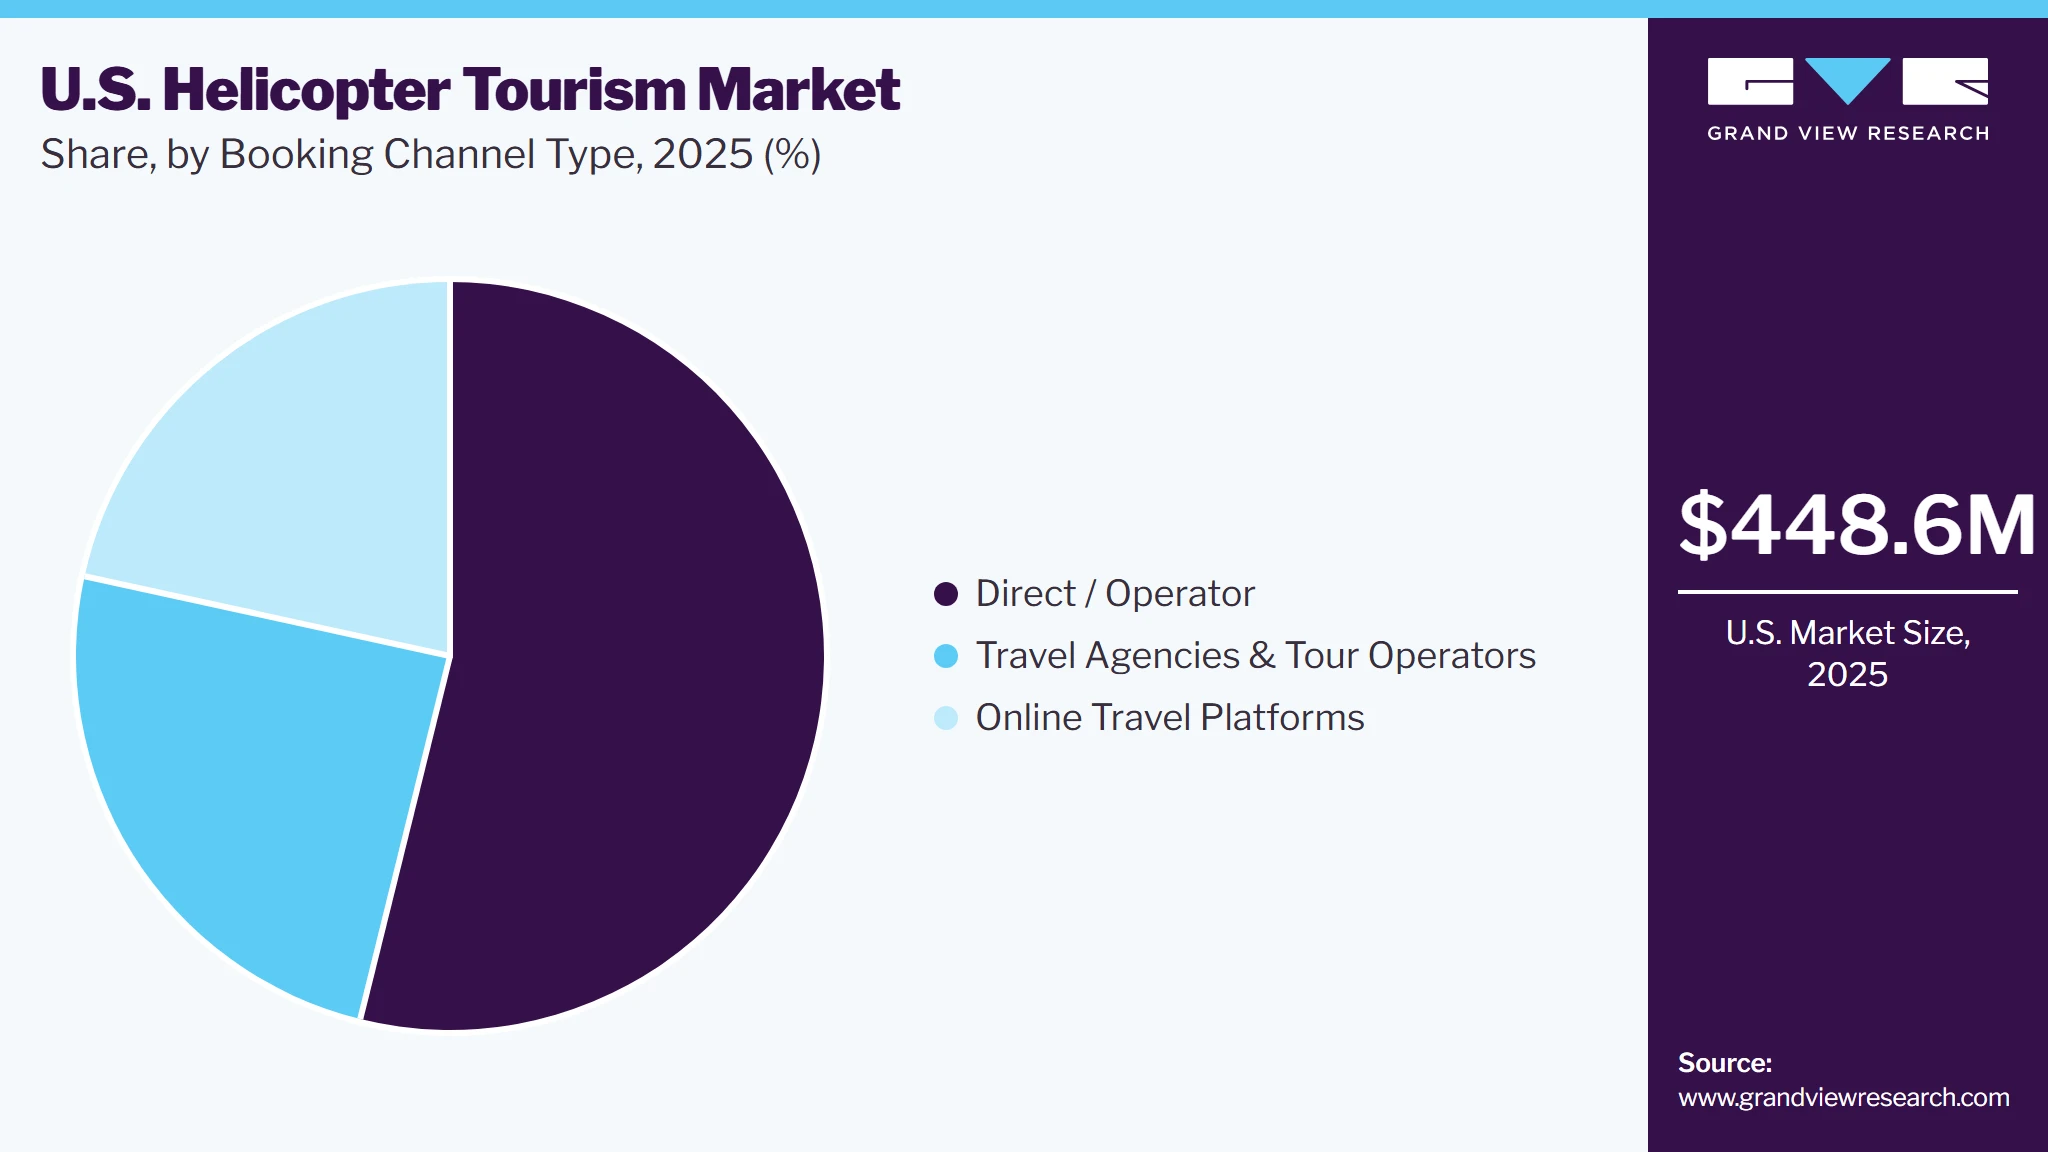
- By booking channel type: Direct / operator segment held the largest market share of 53.8% in 2025.
Market Size & Forecast
- Market size in 2025: USD 448.6 Million
- Estimated market size in 2026: USD 464.5 Million
- Projected market size by 2033: USD 592.5 Million
- CAGR (2026-2033): 3.5%
Prism AI by Grand View Research Free to tryAsk a question about the U.S. helicopter tourism marketTry asking✓Every figure cited from GVR research Prefer the report? Download free sample →
Growth of the U.S. helicopter tourism industry is further supported by the expansion of private and customized sightseeing experiences, growing preference for premium travel activities, and increasing adoption of online booking platforms that provide convenient access to helicopter tour packages. The market also benefits from the strong U.S. tourism infrastructure, high domestic and international tourist arrivals, and growing consumer interest in unique ways to experience major landmarks and scenic destinations. In addition, operators are expanding customized flight options, sunset tours, private charters, and destination-specific experiences, supporting broader adoption of helicopter-based tourism services.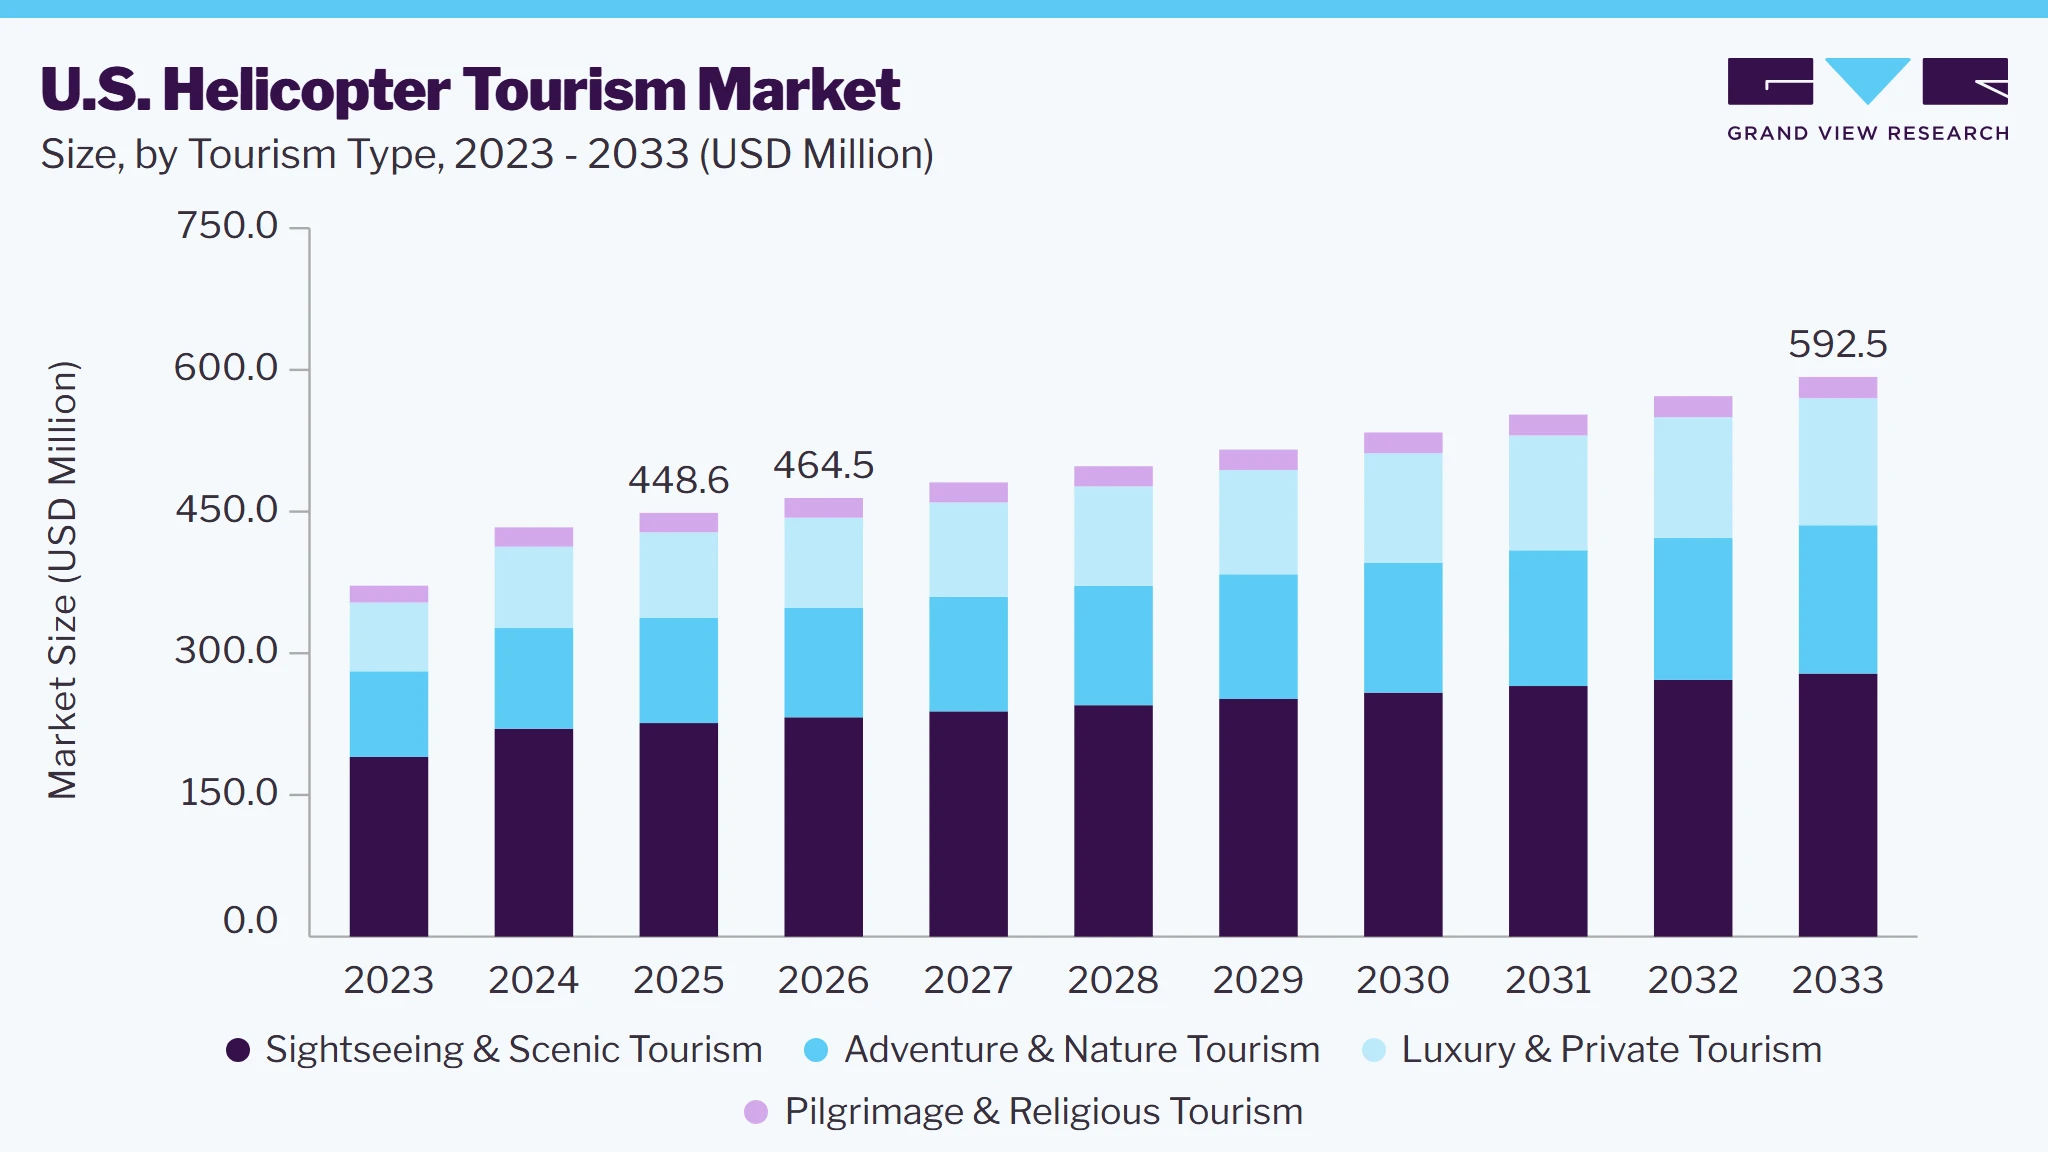 Source: Grand View Research, IR Documents, Primary Interviews, Paid DatabasesTo learn more about this report,
 Download Free Sample Report
The U.S. helicopter tourism market is increasingly supported by the development of premium, customized, and destination-specific aerial experiences, allowing tourists to combine sightseeing with landing experiences, private transfers, dining, and other activities. For instance, in 2026, Maverick Helicopters continues to offer experiences from Las Vegas and the Grand Canyon, including its Wind Dancer Grand Canyon landing tour priced from USD 599, as well as Neon & Nature tours from Las Vegas starting at USD 249. The company also promotes helicopter experiences for the 2026 Pacific Airshow, including VIP helicopter transfers and coastal flyovers.
In Hawaii, operators are expanding experiences beyond conventional sightseeing. Magnum Helicopters currently offers a private Oahu helicopter experience with a private ridge landing, accommodating up to four passengers and combining aerial sightseeing with an exclusive landing at a location accessible by helicopter.
The market is also supported by consumers' increasing willingness to allocate spending toward unique, memorable, and customized travel experiences. Hawaii represents a particularly important destination for helicopter tourism because of its volcanic landscapes, coastlines, waterfalls, and mountainous terrain. According to Hawaii's Department of Business, Economic Development & Tourism, the state recorded 9.64 million visitors and USD 21.75 billion in visitor spending in 2025, with visitor spending increasing 5.7% despite a slight decline in arrivals. This spending environment creates opportunities for helicopter operators to promote sightseeing flights, private experiences, and destination-focused aerial tours as higher-value additions to conventional vacations.
The development of the U.S. helicopter tourism market is closely linked to the regulatory framework governing commercial air tours. The Federal Aviation Administration (FAA) oversees commercial air-tour operations under applicable Part 91, Part 135, and Part 136 requirements, with specific oversight for air tours conducted near National Park Service units and in Hawaii. The FAA also maintains an updated database of certificated Part 135 operators, enabling customers and industry participants to verify whether operators and aircraft are authorized for charter operations.
Market Dynamics
The U.S. helicopter tourism market is benefiting from the large visitor base at major scenic and leisure destinations, where experiential tourism encourages travelers to allocate spending toward distinctive sightseeing activities. In 2025, U.S. national parks recorded 323.0 million recreation visits, while the Grand Canyon National Park alone received 4.43 million visitors, creating a substantial addressable customer base for aerial sightseeing and related Helicopter Services. Las Vegas, another major helicopter-tour hub, welcomed 38.5 million visitors in 2025.
Increasing aviation-safety requirements, airspace controls, and environmental restrictions can constrain the expansion of helicopter services and increase operational complexity for tourism operators. Commercial air tours operating over national parks are subject to FAA and National Park Service oversight, with management frameworks that can specify routes, altitudes, flight frequency, aircraft types, and operating periods. The FAA and NPS continue to develop and implement Air Tour Management Plans and voluntary agreements for areas with commercial air-tour activity. The regulatory focus intensified during 2025 as the FAA's Commercial Air Tour Aviation Rulemaking Committee worked toward a more consistent national safety framework. The committee's November 2025 recommendations proposed a National Air Tour Safety Standard and a comprehensive revision of 14 CFR Part 136 to harmonize safety requirements across commercial air-tour operations.
The increasing adoption of technology for flight monitoring, operational control, and safety management presents an opportunity for the U.S. helicopter tourism market to improve the reliability and safety of helicopter services. In January 2026, the Federal Aviation Administration (FAA) issued Advisory Circular AC 136-5, titled Enhanced Flight Following Center (EFFC) for Commercial Air Tour Operators. Issued on January 23, 2026, the guidance recommends the development and integration of enhanced flight-following procedures to improve operational control and the ability to locate and monitor commercial air-tour flights.
Analyst Perspective
The U.S. helicopter tourism market is evolving from conventional sightseeing flights toward a broader experiential tourism ecosystem centered on personalized, adventure-oriented, and premium travel experiences. Demand is increasingly supported by tourists seeking unique aerial access to national parks, canyons, coastlines, and major attractions, while operators are differentiating their helicopter services through private flights, scenic landings, sunset tours, customized itineraries, and destination-specific packages. The market is also benefiting from digital booking platforms and technology-enabled flight monitoring, while safety compliance, airspace restrictions, and environmental considerations remain important factors shaping future growth.
Consumer Insights
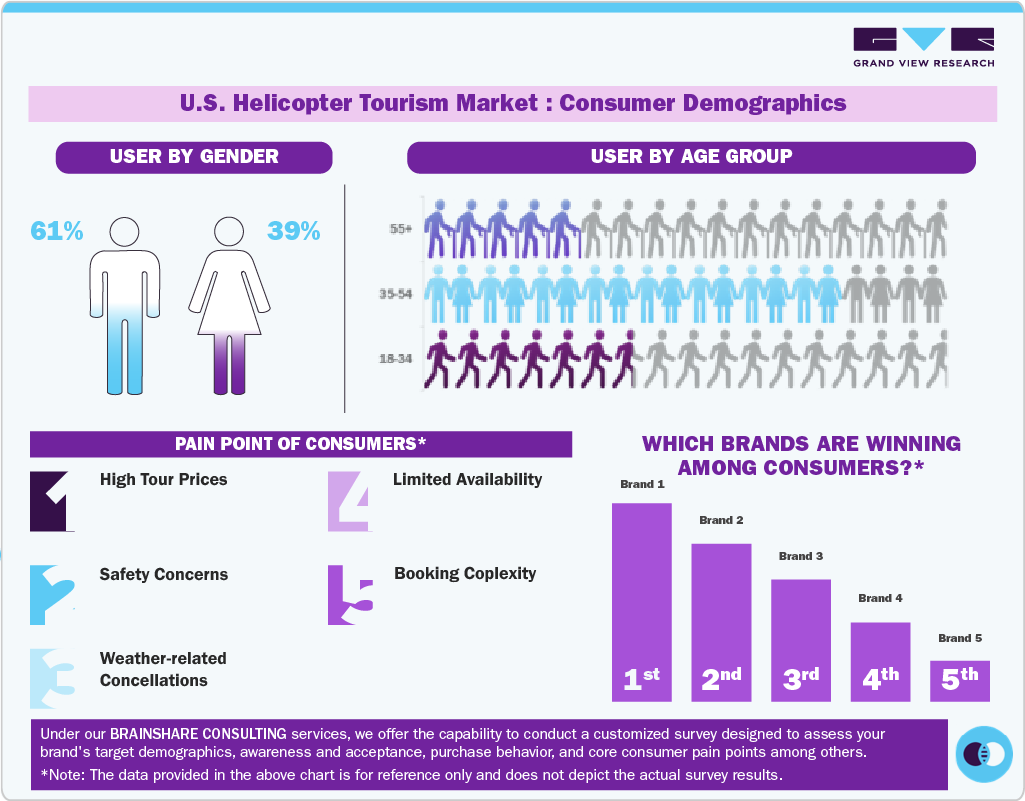
Consumer demand in the U.S. helicopter tourism industry is primarily influenced by gender, age, income, travel preferences, and willingness to spend on memorable and exclusive experiences, with purchasing decisions increasingly shifting toward experiential tourism that provides convenience, personalization, and unique destination experiences.
 To learn more about this report, Download Free Sample Report
-
Male consumers account for the larger share of the helicopter-interest audience at an estimated 61.0%, while female consumers account for approximately 39.0%. Male demand is supported by a stronger interest in adventure, outdoor, and aviation-related experiences, whereas female demand is increasingly associated with leisure sightseeing, couples' experiences, celebrations, and special-occasion travel. These figures represent a directional audience indicator rather than confirmed helicopter-tour passenger bookings.
Consumers in the U.S. helicopter tourism market commonly encounter several pain points and challenges during booking and travel planning.
-
High ticket prices remain a major barrier, particularly for younger and price-sensitive travelers who may consider helicopter tourism an occasional rather than a routine travel activity.
-
Weather cancellations can disrupt planned itineraries, as helicopter operations are highly dependent on visibility, wind, rainfall, and other weather conditions.
-
Limited availability during peak tourism periods can make preferred flight schedules difficult to secure, particularly at popular destinations and during holidays and major tourism seasons.
-
Safety concerns can influence purchase decisions, particularly among first-time passengers who may have limited familiarity with helicopter operations and may evaluate operator safety records, aircraft condition, and pilot qualifications.
-
Booking complexity can arise when helicopter experiences are offered through multiple operators and booking platforms, making it difficult for consumers to compare schedules, prices, routes, inclusions, and cancellation policies.
These consumer insights reflect purchasing behavior within the helicopter tourism segment only. As a result, operators are increasingly focusing on flexible booking options, transparent pricing, digital reservation systems, clear safety communication, shared-flight options, and customized helicopter services to attract a broader consumer base while strengthening the role of experiential tourism in the U.S. market.
Tourism Type Insights
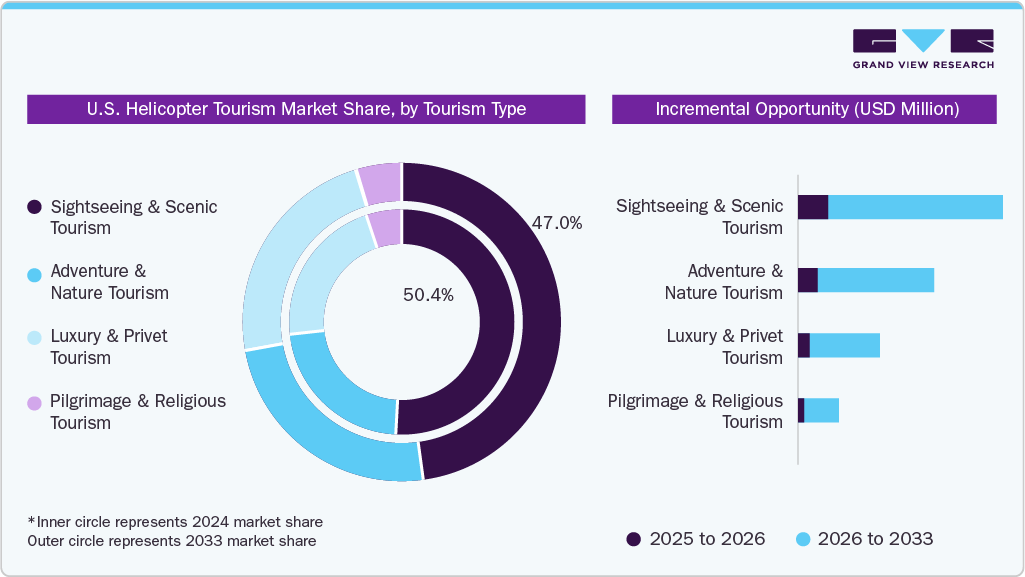
Sightseeing & scenic tourism dominated the U.S. helicopter tourism industry, accounting for the largest revenue share of 50.4% in 2025, supported by travelers seeking aerial access to coastlines, waterfalls, volcanic landscapes, mountains, and other natural landmarks that provide a different perspective from conventional sightseeing. Blue Hawaiian Helicopters currently offers its Oahu Air Adventure, a 50-minute sightseeing experience departing from Turtle Bay and covering the North Shore, Waianae Mountains, Pearl Harbor, Waikiki, Diamond Head, and Hanauma Bay. This demonstrates how operators are packaging multiple scenic attractions into a single aerial experience, supporting Experiential Tourism and demand for sightseeing-focused helicopter services.
 To learn more about this report, Download Free Sample Report
The luxury & private tourism segment is expected to grow at a CAGR of 5.1% from 2026 to 2033, driven by travelers seeking exclusive flights, privacy, customized itineraries, and premium sightseeing experiences. Private Helicopter Services are particularly relevant for couples, families, special occasions, and affluent travelers seeking personalized destination experiences. For instance, Papillon Grand Canyon Helicopters offers private Grand Canyon tours from Las Vegas for groups of up to six passengers, including the Private Grand Celebration Tour, which features a private helicopter, a 3,200-foot descent to the Grand Canyon floor, a champagne toast, and a light picnic overlooking the Colorado River. This illustrates how operators are combining exclusivity, customized experiences, and premium amenities to strengthen experiential tourism within the U.S. market.
Destination Type Insights
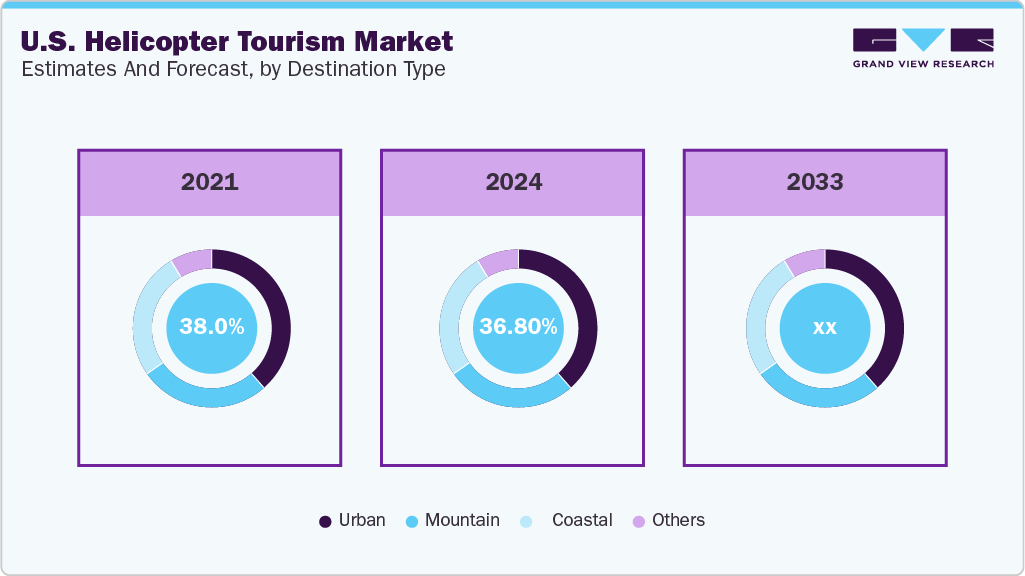
Urban destination accounted for the largest revenue share of 36.4% in 2025, supported by tourists seeking elevated views of iconic skylines, entertainment districts, beaches, celebrity neighborhoods, and architectural landmarks within densely developed cities. Unlike conventional sightseeing, helicopter tours allow visitors to cover multiple urban attractions within a short flight while avoiding road congestion and providing a distinctive perspective of the destination. Los Angeles is a strong example, with the city attracting 49.5 million visitors in 2025, including 43.1 million domestic and 6.4 million international visitors. For instance, Group 3 Aviation currently offers dedicated Los Angeles helicopter tours ranging from 35 to 65 minutes, including its “Hooray For Hollywood” tour covering the Hollywood Sign, Universal Studios, downtown Los Angeles, and Dodger Stadium, as well as its “Hollywood & The Beaches” tour combining Hollywood landmarks with the Santa Monica and Malibu coastline. This demonstrates how urban helicopter services can combine multiple high-density attractions into a single experiential tourism activity and appeal to visitors seeking convenient, premium ways to explore major U.S. cities.
 To learn more about this report, Download Free Sample Report
The mountain destination segment is expected to grow at a CAGR of 4.5% from 2026 to 2033, supported by travelers seeking access to high-altitude landscapes, glaciers, rugged peaks, alpine valleys, and remote areas that are difficult to reach through conventional ground-based tourism. Demand is particularly relevant in Alaska, the Rocky Mountains, and other mountainous regions, where Helicopter Services can combine aerial sightseeing with glacier landings, wildlife viewing, hiking, and adventure activities. In November 2025, Sweetwater Heli announced the launch of California's first active heli-skiing operation, with commercial trips planned for the winter 2026 season in the remote Sweetwater Mountains between Lake Tahoe and Yosemite National Park. The company secured U.S. Forest Service permits and planned trips at approximately USD 1,800 per person, including 6–8 ski runs from high-elevation mountain terrain. This development expands helicopter-based adventure tourism into a new California mountain destination and creates opportunities for experiential tourism through specialized mountain-access helicopter services.
Booking Channel Type Insights
Direct / operator booking channel dominated the U.S. helicopter tourism industry, accounting for a revenue share of 53.8% in 2025, as travelers increasingly use operators’ websites to check tour availability, compare flight options, select preferred schedules, and customize sightseeing or private experiences. This channel is particularly relevant for helicopter services that require passengers to select specific tour durations, passenger capacity, departure locations, or additional experiences. In November 2025, helicopter travel platform hoper launched its international booking platform, with Los Angeles included among its initial U.S. destinations, enabling travelers to compare helicopter options, view availability, access pricing information, and book flights online. The launch demonstrates the increasing digitalization of helicopter-tour bookings and the growing role of online platforms in improving accessibility and convenience within experiential tourism.
 To learn more about this report, Download Free Sample Report
Online travel platforms booking channel is expected to grow at a CAGR of 5.4% from 2026 to 2033, as digital platforms make helicopter experiences easier to discover and book alongside other travel services. For instance, in September 2025, Uber announced a partnership with Joby Aviation to integrate Blade’s helicopter and seaplane services into the Uber app as early as 2026, allowing customers to book helicopter flights to destinations including JFK, Newark, and the Hamptons directly through the Uber platform. Blade had carried more than 50,000 passengers in 2024, primarily in the New York metropolitan area and Southern Europe. The development demonstrates how integration with large-scale online travel and mobility platforms can expand digital access to helicopter services, simplify booking, and connect helicopter experiences with broader experiential tourism journeys.
Key U.S. Helicopter Tourism Company Insights
The U.S. helicopter tourism market is characterized by competition among established helicopter-tour operators with strong presence in major tourism destinations, including the Grand Canyon, Las Vegas, and Hawaii. Selected companies compete primarily through destination coverage, tour variety, safety credentials, aircraft capabilities, customized itineraries, landing experiences, and customer service. Because reliable public company-level revenue or passenger market-share data are limited, the companies below are presented as key market participants rather than ranked by verified market share.
-
Grand Canyon & Las Vegas Helicopter Tour Operators: Maverick Helicopters maintains a strong presence across Las Vegas and the Grand Canyon, offering sightseeing, landing, sunset, and customized experiences. Its current Grand Canyon portfolio includes the Wind Dancer, Wind Dancer Sunset, Skywalk Odyssey, Indian Territory, and Western Journey tours, with listed prices ranging from USD 549 to USD 739 for several experiences. The operator differentiates through destination variety, landing experiences, and integration with Las Vegas tourism.
-
Grand Canyon Scenic Tourism Specialists: Papillon Grand Canyon Helicopters competes through its extensive Grand Canyon tour portfolio and long-established destination presence. The company states that it has operated Grand Canyon tours since 1965 and offers flights from both the Grand Canyon and Las Vegas, including aerial sightseeing, canyon-floor landing experiences, private aircraft options, and combination tours. Its focus on sightseeing-oriented aircraft, customized experiences, and multiple tour formats strengthen its position in destination-based experiential tourism.
-
Hawaii Helicopter Tourism Specialists: Blue Hawaiian Helicopters has a strong presence across Hawaii, providing helicopter services across the Big Island, Maui, Oahu, Kauai, and Lanai. Its portfolio includes scenic, nature, private, landing, and customized tours. For example, its Oahu portfolio includes tours covering Pearl Harbor, Diamond Head, North Shore, waterfalls, and other attractions, while its Kauai services focus on otherwise difficult-to-access scenic areas such as the Na Pali Coast and Waimea Canyon.
-
Premium & Customized Helicopter Experiences: Blue Hawaiian also differentiates through private charter and customized itineraries. Its current Hawaii offerings include private tours and charter options, while selected experiences combine helicopter sightseeing with exclusive landing opportunities. For instance, its Lanai experience is offered as a private-style extended aerial experience covering Maui, Molokai, and Lanai.
 To learn more about this report, Download Free Sample Report
Key U.S. Helicopter Tourism Companies
-
Maverick Helicopters
-
Papillon Grand Canyon Helicopters
-
Blue Hawaiian Helicopters
-
Sundance Helicopters
-
Liberty Helicopters
-
Air Maui
-
Safari Helicopters
-
5 Star Helicopter Tours
-
HeliNY
-
Grand Canyon Helicopters
Competitive Benchmarking
Category
Operating Strategies
Competitive Edge
Weakness
Established Players: Maverick Helicopters; Papillon Grand Canyon Helicopters; HeliNY; Liberty Helicopters
- Focus on operating across high-demand tourism destinations and offering diversified experiences, including city sightseeing, Grand Canyon excursions, private charters, sunset flights, and customized experiences.
- Established operators also invest in specialized sightseeing fleets, safety programs, strategic departure locations, and partnerships with hotels, travel operators, and destination tourism networks.
- Maverick operates across Nevada, Arizona, Hawaii, and California, while Papillon combines helicopter tours with broader ground and adventure experiences.
- Strong brand recognition, extensive operating experience, established tourism infrastructure, larger fleets, and access to major tourist destinations.
- Papillon has operated since 1965 and maintains a broad fleet and destination network, while Maverick operates more than 45 helicopters across multiple U.S. locations.
- HeliNY has operated New York sightseeing tours since 1994, providing a strong position in the urban aerial tourism segment.
- High operating and maintenance costs, dependence on tourism volumes, and significant exposure to weather-related cancellations.
- Larger operators also face regulatory restrictions, particularly around operating routes, noise, and heliport access in densely populated destinations.
- Maintaining large fleets and extensive physical infrastructure can further increase fixed costs during periods of weaker tourism demand.
Emerging / Specialized Players: Wild West Helicopters; Sundance Helicopter Tours; 5 Star Helicopter Tours
- Focus on differentiated and location-specific experiences rather than nationwide or multi-destination scale. Strategies include specialized Grand Canyon routes, smaller-group experiences, themed flights, exclusive landing locations, and direct online booking.
- Wild West Helicopters, for example, differentiates through its cowboy-ranch departure location and Grand Canyon West Rim experience, while regional operators can tailor products around specific tourist attractions.
- Greater operational flexibility and the ability to develop highly differentiated experiences for specific destinations or customer segments.
- Smaller operators can compete through unique routes, personalized service, niche experiences, and potentially lower organizational complexity than large multi-location companies.
- Comparatively lower brand awareness, smaller fleets, and limited geographic coverage can restrict passenger volumes and marketing reach.
- These operators may also be more dependent on a single tourism destination, making them particularly vulnerable to localized weather disruptions, changes in visitor flows, operational restrictions, or increased competition from larger established companies.
Recent Developments
-
In September 2025, Joby Aviation announced plans to bring Blade's helicopter and seaplane passenger services to the Uber app as early as 2026, following its acquisition of Blade's passenger business for up to $125 million. Blade transported more than 50,000 passengers in 2024, primarily across the New York metropolitan area and other high-traffic destinations. The planned integration expands digital access to helicopter-based passenger services and creates a potential new distribution channel for urban Experiential Tourism and premium aerial travel.
-
In 2026, Maverick Helicopters also expanded its destination experience portfolio with offerings such as Neon & Nature, combining Las Vegas sightseeing with aerial views of the surrounding landscape, alongside Grand Canyon experiences including Wind Dancer, Skywalk Odyssey, and Indian Territory. The portfolio illustrates the industry's shift toward differentiated, destination-specific tourism packages rather than basic point-to-point sightseeing flights.
-
In April 2025, MyFlight Tours broke ground on a USD 4 million, 12,000-square-foot new headquarters and helicopter-tour facility at Coleman A. Young International Airport in Detroit. The facility was designed to include a larger passenger lobby, lounge area with food and beverage services, event space, and offices, strengthening the company's tourism infrastructure and enhancing the passenger experience. MyFlight had already been operating helicopter tours in Detroit since 2021 and offered tours starting at approximately USD 55 per person, highlighting the expansion of accessible Helicopter Services and Experiential Tourism in the U.S. market. The facility was expected to open by the end of 2025.
U.S. Helicopter Tourism Market Report Scope
Report Attribute
Details
Market size in 2025
USD 448.6 million
Estimated market size in 2026
USD 464.5 million
Projected market size by 2033
USD 592.5 million
Growth rate
CAGR of 3.5% from 2026 to 2033
Base year
2025
Actuals
2021 - 2024
Forecast period
2026 - 2033
Quantitative units
Revenue in USD million and CAGR from 2026 to 2033
Report coverage
Revenue forecast, company ranking, competitive landscape, growth factors, and trends
Segments covered
Tourism type, destination type, and booking channel type
Key companies profiled
Maverick Helicopters; Papillon Grand Canyon Helicopters; Blue Hawaiian Helicopters; Sundance Helicopters; Liberty Helicopters; Air Maui; Safari Helicopters; 5 Star Helicopter Tours; HeliNY; Grand Canyon Helicopters
Customization scope
Free report customization (equivalent up to 8 analysts’ working days) with purchase. Addition or alteration to country, regional & segment scope.
Pricing and purchase options
Avail customized purchase options to meet your exact research needs. Explore purchase options
U.S. Helicopter Tourism Market Report Segmentation
This report forecasts revenue growth at the country level and provides an analysis of the latest trends and opportunities in each of the sub-segments from 2026 to 2033. For this study, Grand View Research has segmented the U.S. helicopter tourism market report based on tourism type, destination type, and booking channel type:
-
Tourism Type Outlook (Revenue, USD Million; 2021 - 2033)
-
Sightseeing & Scenic Tourism
-
Adventure & Nature Tourism
-
Pilgrimage & Religious Tourism
-
Luxury & Private Tourism
-
-
Destination Type Outlook (Revenue, USD Million; 2021 - 2033)
-
Urban
-
Coastal
-
Mountain
-
Other
-
-
Booking Channel Type Outlook (Revenue, USD Million, 2021 - 2033)
-
Direct / Operator
-
Travel Agencies & Tour Operators
-
Online Travel Platforms
-
Research Methodology
The U.S. helicopter tourism market figures in this report are based on a proven research process that combines executive interviews with secondary research from proprietary databases, company filings, and recognized regulatory and institutional sources. Market size is built through value-chain sizing-reconciling supply-side and demand-side estimates-and triangulated with bottom-up and top-down approaches. Every estimate passes multiple levels of expert validation before publication, with each U.S. helicopter tourism segment quantified using the revenue-capture definitions in the table below.
Segment Definition
Tourism Type
Revenue capture definition
Sightseeing & Scenic Tourism
Revenue from helicopter flights primarily undertaken to view landscapes, landmarks, cityscapes, coastlines, mountains, waterfalls, and other tourist attractions from the air, including shared sightseeing flights and scheduled scenic tours. Excludes helicopter transportation undertaken primarily for point-to-point travel, emergency services, or non-tourism purposes.
Adventure & Nature Tourism
Revenue from helicopter experiences associated with adventure, outdoor, and nature-based tourism, including helicopter-supported mountain tours, glacier or wilderness experiences, aerial wildlife viewing, heli-skiing, and helicopter access to adventure destinations. Excludes conventional sightseeing flights where the primary purpose is general scenic viewing.
Pilgrimage & Religious Tourism
Revenue from helicopter services used primarily to access religious and pilgrimage destinations, including helicopter transfers to temples, shrines, monasteries, and other religious sites, as well as pilgrimage packages incorporating helicopter transportation. Excludes general tourism flights that only incidentally visit religious landmarks.
Luxury & Private Tourism
Revenue from private or premium helicopter tourism experiences, including exclusive sightseeing flights, private charters, customized aerial tours, luxury hotel or resort transfers, destination-wedding services, and other personalized helicopter experiences. Excludes standard shared sightseeing flights and routine point-to-point transportation not positioned as a premium tourism experience.
Estimation Model
Layer Name
Key Question
Description
Target Consumer Layer
Who needs and uses helicopter tourism services?
Demand comes from leisure travelers, tourists, couples, families, adventure seekers, and luxury travelers seeking sightseeing and unique aerial experiences.
Market Accessibility Layer
What determines customer access and willingness to purchase?
Market access depends on tourist destinations, operator availability, tour pricing, seasonality, booking convenience, and regulatory requirements.
Purchase Behavior Layer
What drives product/service differentiation?
Operators differentiate through scenic routes, flight duration, private tours, customized itineraries, special-event packages, safety, and enhanced passenger experiences.
Monetization Layer
How are helicopter tourism services monetized?
Revenue is generated through sightseeing tickets, private tours, customized flights, special-occasion packages, charter services, and partnerships with hotels, resorts, and travel agencies.
Delivered Customizations
This report has been delivered with the following In-depth customizations
Client Request
Customization Delivered
Value Adds
U.S. Helicopter Tourism Consumer Preferences & Buying Behavior Analysis
Conducted a detailed assessment of U.S. tourist preferences for helicopter sightseeing, aerial tours, adventure flights, private charters, and customized experiences, covering traveler type, trip purpose, booking behavior, spending preferences, destination choices, and demand for personalized.
Helps stakeholders identify high-demand customer segments, understand preferences and develop targeted tour packages, pricing strategies, and personalized aerial experiences.
U.S. Helicopter Tourism Product Innovation, Customization & Market Trends Analysis
Evaluated innovation across helicopter tourism offerings, including scenic sightseeing routes, private and customized tours, adventure experiences, special-event flights, luxury charters, digital booking solutions, and technology-enabled safety and flight-following services, while assessing emerging trends.
Provides insights into evolving traveler expectations and service innovation, supporting differentiation through customized itineraries, enhanced passenger experiences, digital convenience, safety features, and technology-enabled.
U.S. Helicopter Tourism Distribution & Market Opportunity Assessment
Assessed growth opportunities across direct operator bookings, online travel platforms, travel agencies, hotel and resort partnerships, concierge services, and tourism packages, while analyzing regional tourism hotspots, destination demand, individual and group travelers, and emerging opportunities.
Supports investment and expansion decisions by identifying high-potential destinations, distribution channels, tourism partnerships, and customer segments, enabling operators to expand reach and capture demand for sightseeing, adventure, and customized helicopter experiences.
Frequently Asked Questions About This Report
The U.S. helicopter tourism market size was valued at USD 448.6 million in 2025 and is estimated at USD 464.5 million for 2026.
The U.S. helicopter tourism market is expected to grow at a CAGR of 3.5% from 2026 to 2033, reaching USD 592.5 million by 2033.
By tourism type, the sightseeing & scenic tourism accounted for the largest revenue share of 50.4% in 2025.
The U.S. helicopter tourism market is driven by growing demand for experiential and adventure travel, as tourists seek unique aerial views of iconic destinations. Additionally, rising demand for luxury, private, and customized travel experiences supports market growth.
Key players in the U.S. Helicopter Tourism Market include Maverick Helicopters, Papillon Grand Canyon Helicopters, Blue Hawaiian Helicopters, Liberty Helicopters, Sundance Helicopters, Air Maui Helicopters, HeliNY, and Zip Aviation. These operators serve major tourism destinations such as the Grand Canyon, Las Vegas, Hawaii, and New York City.
By destination type, urban accounted for the largest revenue share of 36.4% in 2025.
By booking channel type, the direct / operator accounted for the largest revenue share of 53.8% in 2025.
Luxury & private tourism type is projected to register the fastest CAGR of 5.1% in the U.S. helicopter tourism market.
Emerging trends in the U.S. helicopter tourism market include the growing demand for private and customized aerial experiences, digital/online booking, and luxury travel packages. The market is also moving toward quieter and more sustainable aviation technologies, including eVTOL aircraft, which could reshape future aerial tourism experiences.
About the Author(s)
Homecare & Decor Research Team
Consumer Goods · Homecare & DecorThis report was authored by the homecare & decor research team at Grand View Research - comprising two research analysts, one senior research analyst, and one industry expert - with specialized expertise in the homecare & decor segment of the consumer goods industry. All findings are based on proprietary consumer goods databases, executive interviews, and regulatory analysis, subject to internal peer review prior to publication.
Last Updated:
Speak to Analyst

Customize this report to your needs - add regions, segments, or data points, with 20% free customization.
Or view our licence options:


ISO 9001:2015 & 27001:2022 Certified
We are GDPR and CCPA compliant! Your transaction & personal information is safe and secure. For more details, please read our privacy policy.


