
- Home
- »
- Medical Devices
- »
-
U.S. Physical Therapy Services Market Size Report, 2033GVR Report cover

U.S. Physical Therapy Services Market (2026 - 2033)
Size, Share & Trends Analysis Report By Application (Orthopedic Therapy, Neurological Therapy), By Settings (Outpatient Clinics, Hospitals), By Payer (Public Insurance, Private Insurance), By Region, And Segment Forecasts
Market Size, 2025
$52.3BMarket Estimate, 2026
$54.6BMarket Forecast, 2033
$76.6BCAGR, 2026–2033
4.9%U.S. Physical Therapy Services Market Summary
The U.S. physical therapy services market size was valued at USD 52.3 billion in 2025 and is projected to grow from USD 54.6 billion in 2026 to USD 76.6 billion by 2033, at a CAGR of 4.9% from 2026 to 2033. The market is driven by several factors, such as an aging population, rising prevalence of musculoskeletal and chronic conditions, increasing sports-related injuries, growing preference for nonsurgical and preventive rehabilitation, and technological advancements in physical therapy services.
Key Market Trends & Insights
- By application: Orthopedic segment held the largest market share of 59.1% in 2025
- By settings: Outpatient clinics segment held the largest revenue share of 51.2% in 2025.
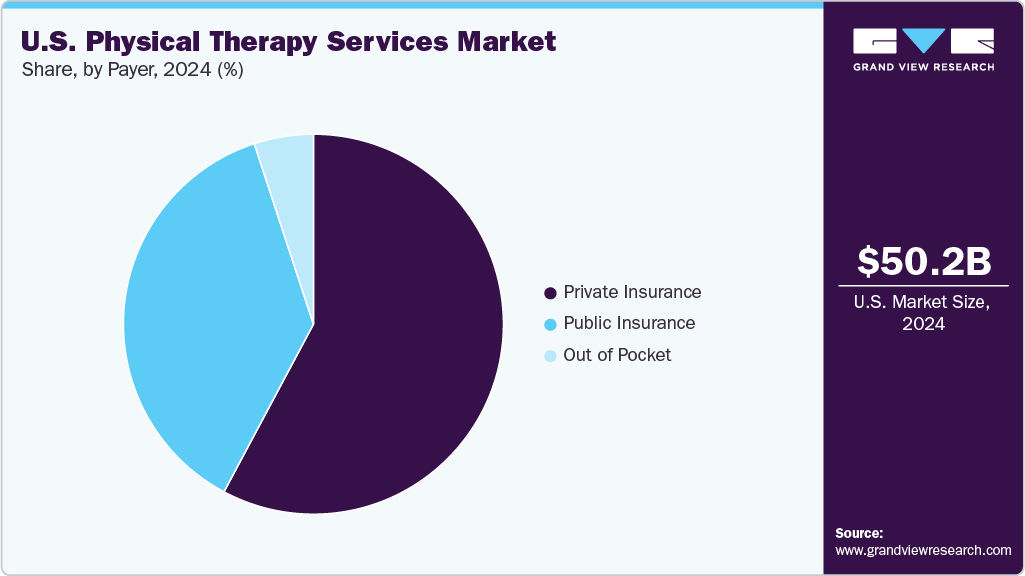
- By payer: Private health insurance segment held the largest revenue share of 57.9% in 2025.
Market Size & Forecast
- Market size in 2025: USD 52.3 Billion
- Estimated market size in 2026: USD 54.6 Billion
- Projected market size by 2033: USD 76.6 Billion
- CAGR (2026-2033): 4.9%
Three ways to get this report
Buy it, customize it, or ask a question.Ask an Analyst
A direct answer, usually in 1 working day
- AccessReport author, directly
- Reply timeWithin 1 working day
- No sales callDirect answer only
- FormatEmail reply
- CostFree, no cost
Get the Full Report
What the study covers
- FormatsPDF · Excel · Dashboard
- Timeline2026–2033 annual, 2025 base
- Coverage20+ countries, 5 regions
- Companies10+ key players profiled
Customize the Report
20% free customization
- IncludeCountries, segments, points
- TailorTo your product definition
- ExtendDeeper competitor detail
- OrA fully bespoke study
- Turnaround5–10 working days
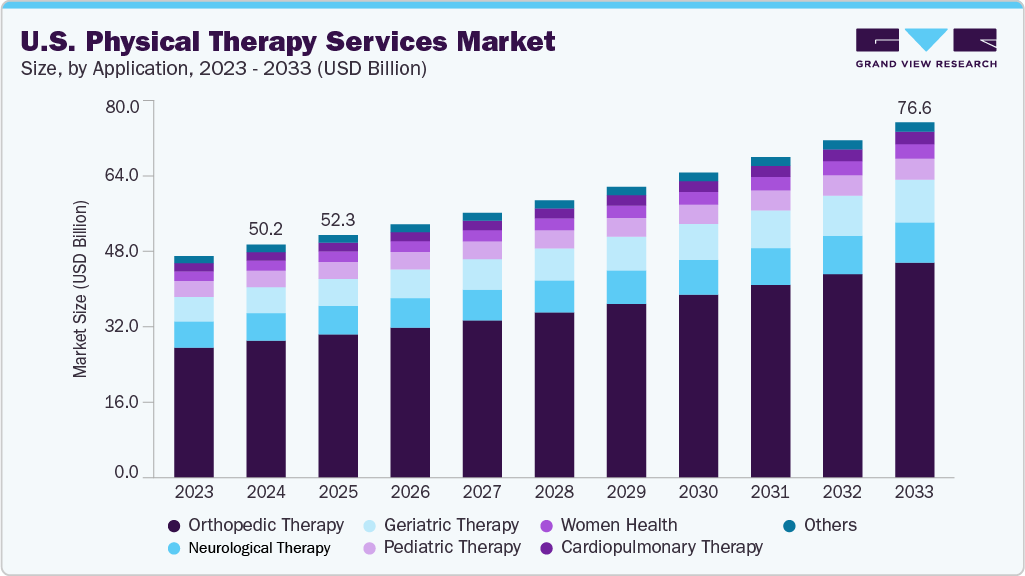 Source: Grand View Research, IR Documents, Primary Interviews, Paid DatabasesTo learn more about this report,
 Download Free Sample Report
Market Dynamics
The U.S. physical therapy services market is undergoing structural changes as providers expand outpatient and home-based care, adopt digital and AI-enabled rehabilitation solutions, and develop more personalized treatment models. Consolidation through acquisitions and strategic partnerships is also reshaping provider networks and supporting broader service diversification. M&A activity and strategic partnerships are further supporting clinic expansion and service diversification. However, therapist shortages, reimbursement pressure, and operating costs remain key challenges.
Increasing global sports participation has intensified competition within the sports industry, creating significant financial opportunities, particularly for athletes pursuing elite professional status. Hence, injured athletes frequently encounter considerable pressure from personal expectations and team management to resume competition quickly, as extended recovery periods can risk their position within the team. In October 2024, Project Play released its State of Play 2024 report, highlighting youth sports trends in the U.S., noting that in 2023, approximately 27.3 million children aged 6-17 participated in organized sports, representing 55.4% of that age group. The report emphasized the rising incidence of serious knee injuries among teen athletes and called for increased awareness and preventive measures. Early intervention, personalized care, and prevention-focused strategies are essential to facilitating effective recovery and a safe return to competition.Physical therapy is critical in sports medicine, particularly in managing injuries during major international events. Sports physiotherapists' primary responsibilities include injury treatment, rehabilitation, and performance support through strategies for injury prevention, maintenance, and recovery. Athletes value sports physiotherapists who demonstrate expertise, possess strong personal attributes, communicate effectively, and show a genuine interest in their well-being. In 2024, according to the National Safety Council, sports and recreational injuries in the U.S. increased by 17%, with 4.4 million people treated in emergency departments, primarily from exercise, cycling, and basketball. The highest injury rates were observed among 15- to 24-year-olds, with males affected more than females, and most patients (90%) were treated and released.Athletes often have a narrow understanding of the responsibilities of sports physiotherapists, primarily viewing them as injury-focused. The four key themes regarding the role of sports physiotherapists are:- Treatment of injuries
- Injury prevention
- Rehabilitation
- Enhancement of athletic performance
 To learn more about this report,Furthermore, physical therapy offers numerous advantages for pain management, contributing to its growing popularity among individuals with chronic pain. It can enhance flexibility and range of motion, facilitate movement, and reduce the risk of injury. In addition, physical therapy may reduce reliance on medications, helping patients avoid potential side effects and improve overall health. Promoting increased physical activity also supports a healthier lifestyle, countering the negative effects of a sedentary routine. In November 2025, a USD 75,000 donation was made to establish a fund supporting the operations of Pennsylvania College of Technology’s Physical Therapy Clinic. The clinic provides care to uninsured or underinsured patients while giving students hands-on clinical experience under faculty supervision. Download Free Sample Report
Financial constraints and limited access remain significant challenges for physical therapy utilization in the U.S. High out-of-pocket costs, including copayments, deductibles, and session fees, can discourage patients from initiating or completing treatment. For instance, in March 2025, Physical Therapy Billing reported that copayments for physical therapy visits under high-deductible health plans could reach USD 75 per session, increasing the financial burden on patients and potentially delaying care. Access challenges are also pronounced in rural and underserved areas, where patients may face limited clinic availability, longer travel distances, and fewer specialized providers. Similarly, in January 2026, Pew Research Center reported that 71% of rural U.S. adults had home broadband subscriptions, based on a 2025 survey, indicating that nearly three in ten rural adults lacked a home broadband subscription and highlighting a persistent digital access barrier for telehealth and tele-rehabilitation services.
The expansion of AI-enabled, technology-driven physical therapy is a significant opportunity in the U.S. market, as providers increasingly adopt digital solutions to improve access, personalization, and operational efficiency. For instance, in March 2026, the American Physical Therapy Association (APTA) submitted recommendations to the U.S. Department of Health and Human Services on the strategic implementation of AI in healthcare, highlighting AI’s potential to improve access, support clinical decision-making, reduce administrative workload, and enhance the delivery of physical therapy. This creates opportunities to integrate AI into assessment, treatment planning, documentation, and patient monitoring.
The opportunity is further supported by the growing demand for convenient and accessible rehabilitation. In December 2025, Martin Army Community Hospital launched a virtual physical therapy pilot using SWORD Health’s digital platform, which uses motion-tracking technology and artificial intelligence to track exercise performance and enable remote clinical oversight. The model enables physical therapy to be delivered outside the clinic, helps address scheduling and geographic access barriers, and allows therapists to monitor patients remotely and adjust treatment plans based on movement data.
Market Characteristics & Concentration
The chart below illustrates the relationship between market concentration, characteristics, and participants. The market is fragmented, with many small players entering the market and launching new innovative services. The degree of innovation is moderate to high, the level of M&A activities is high, the impact of regulations is medium, service expansion is medium, and the impact of partnerships & collaborations is medium.
The degree of innovation in the U.S. physical therapy services industry is moderate to high, supported by the increasing adoption of AI, wearables, virtual care, and data-driven rehabilitation. For instance, in July 2025, APTA highlighted AI-driven diagnostics, wearable technologies, and emerging care delivery models as key innovations to reshape rehabilitation and physical therapy practice. Traditional approaches, including therapeutic exercise and manual therapy, remain fundamental, while technology-enabled solutions are increasingly being integrated to improve personalization, monitoring, and accessibility.
 To learn more about this report, Download Free Sample Report
The level of M&A activity in the U.S. market is high, driven by provider consolidation, geographic expansion, and diversification of rehabilitation services. Key players are acquiring established practices to expand clinic networks and strengthen their presence across outpatient and home-based care. For instance, in July 2026, U.S. Physical Therapy, Inc. acquired a 67% equity interest in a Twelve-clinic physical therapy practice, with existing owners retaining 33%. The acquired practice generates approximately 112,000 annual visits and USD 12 million in annual revenue, strengthening U.S. Physical Therapy’s outpatient clinic network. Similarly, in August 2025, U.S. Physical Therapy, Inc. acquired a three-clinic physical therapy practice, taking a 60% ownership stake while the founders retained 40%, adding approximately USD 5.3 million in annual revenue and 28,000 visits to its outpatient network.
The impact of regulations on the U.S. market is medium, as regulatory frameworks facilitate and constrain growth. Medicare reimbursement policies are essential to determine the financial viability of physical therapy, affecting how services are delivered and compensated. However, the regulatory environment remains stable, with periodic adjustments rather than extensive reforms, allowing providers to operate within established guidelines while seeking compliance.
Service expansion within the market is medium, with many providers exploring opportunities to broaden their offerings beyond traditional physical therapy. This includes developing specialized programs targeting pediatrics, geriatrics, or sports rehabilitation populations. For instance, in February 2024, UPMC Children’s Hospital of Pittsburgh expanded its pediatric rehabilitation services to UPMC Jameson in New Castle, Pennsylvania, establishing a dedicated outpatient rehabilitation facility offering pediatric physical therapy and speech therapy, with occupational therapy planned. The expansion broadens UPMC’s physical therapy service portfolio to include specialized pediatric rehabilitation and brings these services closer to families in surrounding communities.
The impact of partnerships and collaborations in the U.S. market is moderate to high, as providers collaborate with healthcare systems, technology companies, and academic institutions to expand service capabilities, improve clinical education, and strengthen care delivery. For instance, in October 2025, Athletico Physical Therapy partnered with Exxat to implement the Exxat One platform across its 900+ clinics, centralizing student placements and onboarding while expanding hands-on learning opportunities for future rehabilitation professionals.
Analyst Perspective
Market development is increasingly shaped by the shift toward distributed care models, provider consolidation, digital rehabilitation, and specialization across orthopedic, geriatric, and sports therapy. While these trends are expanding service capacity, workforce availability, reimbursement economics, and operating costs will influence how quickly providers can scale. Providers are expanding clinic networks, pursuing partnerships and acquisitions, and adopting technology-enabled care models. AI-enabled platforms, virtual physical therapy, and remote patient monitoring are also gaining traction. However, therapist shortages, reimbursement constraints, and rising operating costs remain key challenges. Continued demand for outpatient rehabilitation and personalized care is expected to create growth opportunities. Geographic expansion and the adoption of digital care are likely to further support market development over the forecast period.
Application Insights
The orthopedic therapy segment led the market with the largest revenue share of 59.1% in 2025. The rising prevalence of MSK conditions, including arthritis, and the growing preference for nonsurgical rehabilitation. According to CDC data reported in 2025, 21.3% of U.S. adults aged 18 years and older had diagnosed arthritis in 2024, while arthritis and osteoarthritis accounted for a substantial number of physician visits. Growing awareness of physical therapy for pain management, mobility improvement, and recovery from orthopedic surgery is further supporting demand. In July 2025, Rothman Orthopedic Institute highlighted advanced physical therapy techniques, including early mobility, Blood Flow Restriction Therapy, and Neuromuscular Electrical Stimulation, to improve post-surgical recovery. These advances, along with rising rates of sports-related injuries, are expected to drive the adoption of targeted, noninvasive orthopedic rehabilitation services.
The geriatric therapy segment is expected to grow at the fastest CAGR over the forecast period. Growth of the segment can be attributed to the growing elderly population and the rising incidence of age-related conditions, such as arthritis, osteoporosis, Alzheimer’s disease, cancer, balance & gait disorders, neurological disorders, and mobility impairments. Moreover, technological advancements and the trend toward preventive healthcare & nonsurgical interventions have increased the demand for physical therapy as a preferred approach to managing age-related health decline. For instance, in July 2025, Siskin Hospital for Physical Rehabilitation, in collaboration with the University of Tennessee at Chattanooga, launched a new geriatric physical therapy residency program to develop therapists specializing in the care of older adults. The program provides advanced education, mentorship, and clinical experience focused specifically on geriatric physical therapy, reflecting the growing need for specialized rehabilitation services for the aging population.
Settings Insights
The outpatient clinics segment led the market with the largest revenue share of 51.2% in 2025 and is anticipated to grow at the fastest CAGR during the forecast period. This dominance is due to the patient’s preference for flexible, convenient, and personalized rehabilitation without hospitalization. Outpatient clinics serve a broad range of needs, including post-surgical rehabilitation, chronic pain management, mobility improvement, and sports injury recovery. In July 2025, Cigna introduced a new site-of-care review for outpatient hospital PT/OT services, aimed at ensuring medical necessity and potentially shifting therapy services toward lower-cost outpatient settings. Increasing availability of personalized care, flexible scheduling, and expanded outpatient networks is expected to further support segment growth.
The home healthcare segment is expected to grow at a significant CAGR over the forecast period, driven by the aging U.S. population, increasing preference for care at home, and rising demand for personalized and cost-effective rehabilitation. Advances in telehealth and portable therapy technologies are further enabling physical therapists to deliver care remotely or directly in patients’ homes. For instance, in April 2025, U.S. Physical Therapy, Inc. expanded its home-based services by acquiring a physical, occupational, and speech therapy practice through its subsidiary, MSO Metro, LLC, extending access to therapy in patients’ homes and supporting continuity of care. These developments, along with growing adoption of technology-enabled home therapy, are expected to support segment growth.
Payer Insights
The private insurance segment led the market with the largest revenue share of 57.9% in 2025 and is anticipated to grow at the fastest CAGR during the forecast period. The segment's growth can be attributed to the supported by increasing collaboration among private health insurers, employers, and healthcare providers. Employer-sponsored health plans frequently include coverage for physical therapy, improving access to rehabilitation services, and encouraging patients to seek treatment earlier. According to the U.S. Census Bureau, as of September 2025, private health insurance covered 66.1% of the U.S. population in 2024, while employment-based insurance remained the most common type, covering 53.8% of the population. This broad private insurance coverage supports greater utilization of physical therapy services and strengthens demand for preventive and rehabilitative care.
 To learn more about this report, Download Free Sample Report
The public insurance segment is expected to grow at a significant CAGR over the forecast period. This is supported by the large beneficiary base of Medicare and Medicaid, particularly among older adults and low-income populations requiring rehabilitation services. In November 2024, CMS finalized the 2025 Medicare Physician Fee Schedule, introducing changes such as general supervision of physical therapist assistants and simplified outpatient therapy plan-of-care certifications, helping improve access and reduce administrative burden. Rising chronic disease prevalence also supports demand; the CDC reported in April 2025 that 76.4% of U.S. adults had at least one of 12 selected chronic conditions in 2023, representing approximately 194 million adults, while 93.0% of adults aged 65 years and older had at least one chronic condition. The substantial chronic-disease burden, particularly among older adults, supports continued demand for long-term disease management and rehabilitation services, including physical therapy.
Key U.S. Physical Therapy Services Company Insights
Facility expansion, strategic partnerships, and increased emphasis on inorganic growth initiatives are critical strategies these players use to strengthen their market position. In addition, other competitors are continually engaging in strategic expansion projects to build their footholds in new markets. Some of the notable emerging players are Ivy Rehab, CORA Health Services, Inc., and Enhabit Home Health & Hospice.
Key U.S. Physical Therapy Services Companies:
The following key companies have been profiled for this study on the U.S. physical therapy services market.
-
Select Physical Therapy
-
U.S. Physical Therapy, Inc.
-
ATI Physical Therapy
-
Athletico Physical Therapy
-
Drayer Physical Therapy Institute
-
Professional Physical Therapy
-
CORA Health Services, Inc.
-
PT SOLUTIONS
-
Boston Children's Hospital
-
ApexNetwork Physical Therapy
-
Hinge Health, Inc.
-
Kaia Health (Sword Health, Inc.)
-
Limber Health, Inc. (Net Health)
-
Kins Health Inc (Wysa Ltd.)
-
BetterHealthcare
-
Omada Health Inc.
Competitive Benchmarking
Category
Operating Strategies
Competitive Edge
Weakness
Established Players (Select Medical, U.S. Physical Therapy, Athletico Physical Therapy, ATI Physical Therapy, CORA Physical Therapy)
Focus on expanding outpatient clinic networks, acquisitions, hospital partnerships, specialized rehabilitation services, and technology-enabled patient care to strengthen geographic reach and service capabilities.
Extensive clinic networks, established brand recognition, broad therapist base, strong referral relationships, and diversified rehabilitation services.
High operating and staffing costs, dependence on therapist availability, reimbursement pressures, and challenges in maintaining consistent service quality across large networks.
Emerging Players (Hinge Health, Sword Health, Omada Health, ApexNetwork Physical Therapy)
Focus on virtual physical therapy, AI-enabled rehabilitation, and technology-driven patient engagement to improve accessibility and personalize care.
Flexible digital delivery models, technology-enabled care, personalized rehabilitation programs, and lower dependence on traditional clinic infrastructure.
Limited physical clinic presence, dependence on technology adoption and reimbursement acceptance, and relatively smaller market presence compared with established providers.
Recent Developments
-
In July 2026, Drayer Physical Therapy Institute, a U.S. outpatient rehabilitation provider with 84 clinics, is acquired by GS Capital Partners and Drayer management from Linden Capital Partners, aiming to accelerate growth while maintaining patient-focused care.
-
In April 2025, U.S. Physical Therapy, Inc. acquired an outpatient home care practice offering physical, occupational, and speech therapy, acquiring 80% ownership while the existing owners retained 20%, extending its homecare services in the northeast.
-
In September 2024, Athletico Physical Therapy partnered with Limber Health to enhance hybrid musculoskeletal care. This collaboration integrates Limber’s technology in over 900 clinics across 24 states and D.C., aiming to improve patient outcomes in orthopedic rehabilitation.
-
In September 2024, NextGen Healthcare, Inc. renewed its partnership with Athletico Physical Therapy to implement NextGen Enterprise EHR and PM systems, enhancing clinical and financial efficiency across Athletico’s expanded service areas.
-
For instance, in July 2024, Select Medical and Cedars-Sinai introduced a specialized spine care initiative in Greater Los Angeles.
-
In March 2024, ATI Physical Therapy, Inc. formed a two-year exclusive partnership with the McDonald’s All-American Games, becoming the Official Physical Therapy Partner for this annual event in March, which showcases top high school basketball talent.
-
In June 2024, Select Medical donates USD 5 million over five years to Harrisburg University to establish the Select Medical Physical Therapy and Movement Institute.
U.S. Physical Therapy Services Market Report Scope
Report Attribute
Details
Market size in 2025
USD 52.3 billion
Estimated market size in 2026
USD 54.6 billion
Projected market size by 2033
USD 76.6 billion
Growth rate
CAGR of 4.9% from 2026 to 2033
Base year for estimation
2025
Historical data
2021 - 2024
Forecast data
2026 - 2033
Quantitative units
Revenue in USD billion and CAGR from 2026 to 2033
Report coverage
Revenue forecast, company ranking, competitive landscape, growth factors, and trends
Segments covered
Application, settings, payer, region
Country scope
U.S.
Region scope
West; Midwest; Southeast; Northeast; Southwest
Key companies profiled
Select Physical Therapy; U.S. Physical Therapy; Inc.; ATI Physical Therapy; Athletico Physical Therapy; Drayer Physical Therapy Institute; Professional Physical Therapy; CORA; PT SOLUTIONS; Boston Children's Hospital; ApexNetwork Physical Therapy; Hinge Health, Inc.; Sword Health, Inc. (Kaia Health); Limber Health, Inc. (Net Health); Kins Health Inc (Wysa Ltd.); BetterHealthcare; Omada Health Inc.
Customization scope
Free report customization (equivalent to up to 8 analyst’s working days) with purchase. Addition or alteration to country, regional & segment scope.
Pricing and purchase options
Avail customized purchase options to meet your exact research needs. Explore purchase options
U.S. Physical Therapy Services Market Report Segmentation
This report forecasts revenue growth at the country and regional level and provides an analysis of the latest industry trends in each of the sub-segments from 2021 to 2033. For this study, Grand View Research has segmented the U.S. physical therapy services market report based on application, settings, payer, and region:
-
Application Outlook (Revenue, USD Billion, 2021 - 2033)
-
Orthopedic Therapy
-
Neurological Therapy
-
Geriatric Therapy
-
Pediatric Therapy
-
Women Health
-
Cardiopulmonary Therapy
-
Others
-
-
Settings Outlook (Revenue, USD Billion, 2021 - 2033)
-
Outpatient Clinics
-
Hospitals
-
Home Healthcare
-
Others
-
-
Payer Outlook (Revenue, USD Billion, 2021 - 2033)
-
Public Insurance
-
Private Insurance
-
Out of Pocket
-
-
Region Outlook (Revenue, USD Billion, 2021 - 2033)
-
West
-
Midwest
-
Southeast
-
Northeast
-
Southwest
-
Research Methodology
The U.S. physical therapy services marketfigures in this report are based on a proven research process that combines executive interviews with secondary research from proprietary databases, company filings, and recognized regulatory and institutional sources. Market size is built through value-chain sizing-reconciling supply-side and demand-side estimates-and triangulated with bottom-up and top-down approaches. Every estimate passes multiple levels of expert validation before publication, with each U.S. physical therapy services segment quantified using the revenue-capture definitions in the table below.
Segment Definition
Segment - Application
Revenue capture definition
Orthopedic Therapy
Revenue is generated from physical therapy services focused on the assessment, treatment, and rehabilitation of musculoskeletal conditions, including joint disorders, fractures, arthritis, sports injuries, and post-surgical orthopedic conditions.
Neurological Therapy
Revenue is generated from physical therapy services designed to improve movement, balance, coordination, strength, and functional abilities among patients with neurological conditions such as stroke, Parkinson’s disease, multiple sclerosis, and spinal cord injuries.
Geriatric Therapy
Revenue is generated from physical therapy services focused on age-related mobility limitations, balance disorders, fall prevention, strength improvement, and functional rehabilitation among older adults.
Pediatric Therapy
Revenue is generated from physical therapy services addressing developmental, congenital, neurological, orthopedic, and movement-related conditions in infants, children, and adolescents.
Women’s Health
Revenue is generated from physical therapy services addressing women-specific health conditions, including pelvic floor dysfunction, pregnancy-related musculoskeletal conditions, postpartum rehabilitation, and pelvic pain.
Cardiopulmonary Therapy
Revenue is generated from physical therapy and rehabilitation services that focus on improving cardiovascular and respiratory function, endurance, mobility, and exercise capacity in patients with cardiopulmonary conditions.
Others
Revenue is generated from physical therapy services that fall outside the defined application categories, including rehabilitation for selected chronic conditions, balance disorders, vestibular conditions, and general functional impairments.
Segment - Settings
Revenue capture definition
Outpatient Clinics
Revenue is generated from physical therapy services delivered at independent or affiliated outpatient rehabilitation clinics, where patients receive scheduled assessment, treatment, and rehabilitation without inpatient admission.
Hospitals
Revenue is generated from physical therapy services provided within hospitals, including inpatient rehabilitation, acute-care physical therapy, and outpatient therapy services operated by hospital systems.
Home Healthcare
Revenue is generated from physical therapy services delivered at patients’ homes, primarily for individuals with mobility limitations, chronic conditions, post-surgical needs, or limited ability to access clinic-based care.
Others
Revenue is generated from physical therapy services delivered through settings outside outpatient clinics, hospitals, and home healthcare, including skilled nursing facilities, rehabilitation centers, schools, sports facilities, and other specialized care settings.
Segment - Payer
Revenue capture definition
Public Insurance
Revenue is generated from physical therapy services reimbursed through government-funded insurance programs, including Medicare, Medicaid, and other federal or state public health insurance programs.
Private Insurance
Revenue is generated from physical therapy services reimbursed by commercial health insurance providers, employer-sponsored plans, managed care organizations, and other private payers.
Out-of-Pocket
Revenue is generated directly from patients who pay for physical therapy services using personal funds, including self-pay visits, deductibles, copayments, coinsurance, and services not covered by insurance.
Estimation Model
Category
Methodology
Description
Top-Down
Commodity Flow Analysis
Market size was estimated by analyzing revenues generated by leading U.S. physical therapy service providers, supported by company annual reports, SEC filings, investor presentations, industry databases, and provider-level information. Revenue contributions from private providers were assessed using industry sources and validated through primary research to derive the overall market value.
Parent Market
Parent Market & Penetration-Based Analysis
The U.S. physical therapy services market was evaluated within the broader global physical therapy services and rehabilitation services landscape. Patient volumes, physical therapy utilization, prevalence of musculoskeletal and neurological conditions, treatment frequency, referral patterns, and healthcare expenditure were assessed to estimate the addressable market and U.S. market opportunity.
Validation
Data Triangulation & Validation Model
Market estimates were validated by triangulating provider revenues, patient and visit volumes, reimbursement and payer data, government healthcare statistics, industry databases, company disclosures, and primary interviews to ensure consistency across applications, settings, payers, and the overall U.S. market.
Forecasting
Forecasting & CAGR Modeling
Market forecasts were developed using historical growth patterns, aging population trends, MSK disease prevalence, sports-related injuries, therapy utilization, healthcare spending, reimbursement trends, outpatient care expansion, and adoption of virtual physical therapy. Trend and scenario-based modeling were applied to project market growth and CAGR.
Customization Table
Client Request
Customization Delivered
Value Adds
Competitive landscape, benchmarking & market share analysis of U.S. players
Provided a comprehensive competitive landscape and benchmarking analysis of leading U.S. physical therapy service providers, covering market positioning, service portfolios, geographic presence, clinic networks, business models, and strategic initiatives.
Enabled identification of market leaders, competitive strengths, expansion strategies, and whitespace opportunities to support strategic planning and competitive intelligence.
Pricing and reimbursement analysis
Delivered an analysis of physical therapy service pricing across outpatient clinics, specialty services, virtual therapy models, payer types, and reimbursement structures in the U.S.
Supported evaluation of pricing strategies, reimbursement dynamics, cost benchmarking, and revenue optimization opportunities for physical therapy providers.
Market opportunity assessment
Identified growth opportunities across outpatient rehabilitation, orthopedic therapy, and technology-enabled rehabilitation services.
Enabled strategic planning, service expansion, investment prioritization, and identification of high-growth opportunities within the U.S. physical therapy services industry.
Frequently Asked Questions About This Report
The U.S. physical therapy services market size was valued at USD 50.3 billion in 2025 and is estimated at USD 54.6 billion in 2026.
Key factors that are driving the U.S. physical therapy services market growth attributed to the market is driven by several factors such as, including the aging population, increased prevalence of chronic conditions, increased awareness of preventive care, and technological advancements. These drivers will increase the demand for these services, by changing both patient behavior and the strategic direction of healthcare providers.
The outpatient clinics segment led the market with the largest revenue share of 51.2% in 2025 and is the fastest-growing segment.
The private insurance segment led the market with the largest revenue share of 57.9% in 2025 and is the fastest-growing segment.
The U.S. physical therapy services market is expected to grow at a CAGR of 4.9% from 2026 to 2033, reaching USD 76.6 billion by 2033.
The orthopedic therapy segment led the market with the largest revenue share of 59.1% in 2025, while geriatric therapy segment is the fastest-growing segment.
Key players include Select Physical Therapy; U.S. Physical Therapy, Inc.; ATI Physical Therapy; Athletico Physical Therapy; Drayer Physical Therapy Institute; Professional Physical Therapy; CORA; PT SOLUTIONS; Boston Children's Hospital; ApexNetwork Physical Therapy; Hinge Health, Inc.; Sword Health, Inc.; Kaia Health; Limber Health, Inc. (Net Health); Kins Health Inc (Wysa Ltd.); BetterPT (HealthBus); Omada Health Inc.
About the Author(s)
Medical Devices Research Team
Healthcare · Medical DevicesThis report was authored by the medical devices research team at Grand View Research - comprising two research analysts, one senior research analyst, and one industry expert - with specialized expertise in the medical devices segment of the healthcare industry. All findings are based on proprietary healthcare databases, executive interviews, and regulatory analysis, subject to internal peer review prior to publication.
Last Updated:
Speak to Analyst

Customize this report to your needs - add regions, segments, or data points, with 20% free customization.
Or view our licence options:


ISO 9001:2015 & 27001:2022 Certified
We are GDPR and CCPA compliant! Your transaction & personal information is safe and secure. For more details, please read our privacy policy.


