
- Home
- »
- Paints, Coatings & Printing Inks
- »
-
Waterborne Coatings Market Size, Growth Report, 2026-2033GVR Report cover

Waterborne Coatings Market (2026 - 2033)
Size, Share & Trends Analysis Report By Resin (Acrylic, Polyurethane, Epoxy, Polyester), By Application (Architectural, Automotive OEM), By Region (North America, Asia Pacific, Europe), And Segment Forecasts
Market Size, 2025
$76.9BMarket Estimate, 2026
$80.4BMarket Forecast, 2033
$115.3BCAGR, 2026–2033
5.3%Waterborne Coatings Market Summary
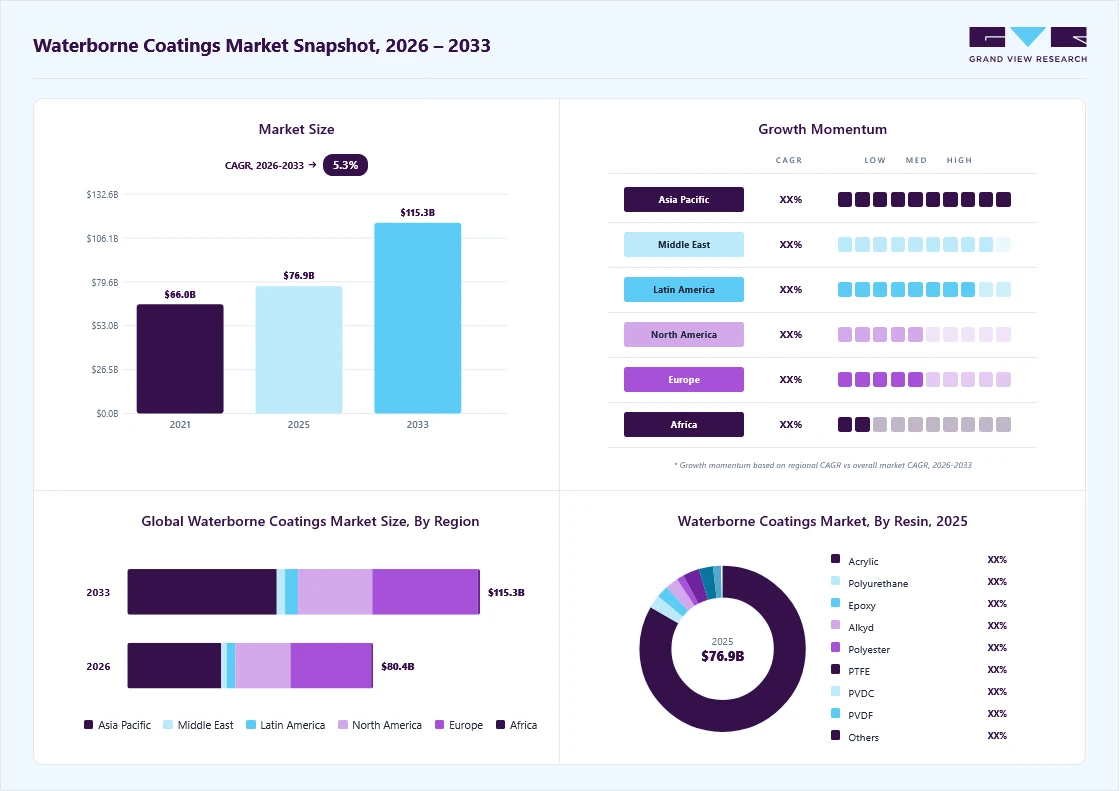
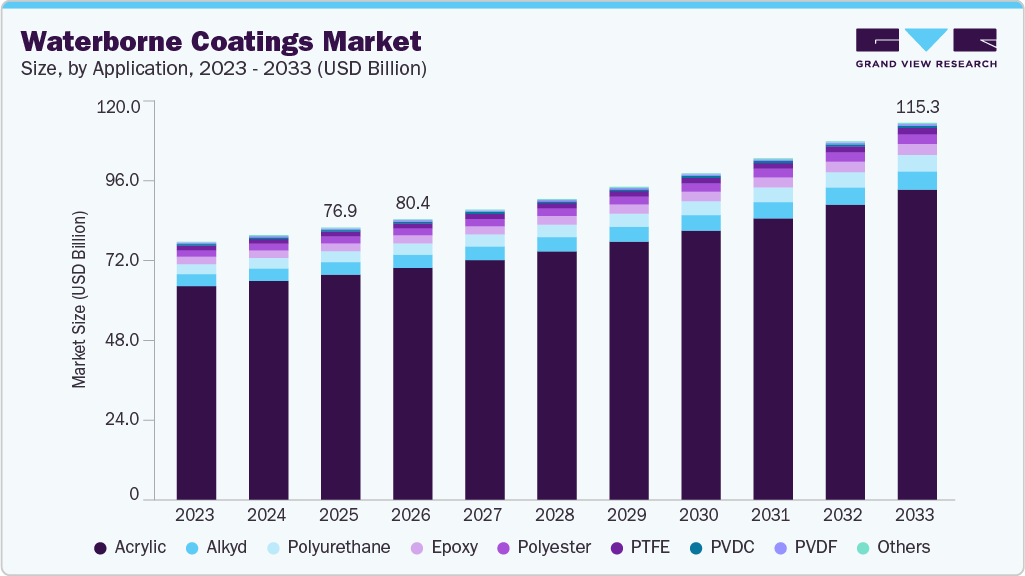
The global waterborne coatings market size was valued at USD 76.9 billion in 2025 and is projected to grow from USD 80.4 billion in 2026 to USD 115.3 billion by 2033, at a CAGR of 5.3% from 2026 to 2033. Asia Pacific dominated the global market, accounting for the largest revenue share of 37.6% in 2025.. The market is driven by a combination of environmental regulations, sustainability trends, and industrial growth.
 Source: Grand View Research, IR Documents, Primary Interviews, Paid DatabasesTo learn more about this report,
 Download Free Sample Report
Key Market Trends & Insights
- By Resin: Polyurethane segment is expected to record a CAGR of 7.6% from 2026 to 2033.
- By application: Marine segment is likely to grow at the highest CAGR of 7.2% during the assessment period.
Regional Highlights
- Largest regional market: Asia Pacific (37.6% revenue share, 2025)
- By country: The Japan waterborne coatings industry is a major contributor to the global market.
Market Size & Forecast
- Market size in 2025: USD 76.9 Billion
- Estimated market size in 2026: USD 80.4 Billion
- Projected market size by 2033: USD 115.3 Billion
- CAGR (2026-2033): 5.3%
Three ways to get this report
Buy it, customize it, or ask a question.Ask an Analyst
Analyst response in 1 business day
- AccessReport author, directly
- Reply timeWithin 1 working day
- No sales callDirect answer only
- FormatEmail reply
- CostFree, no cost
Get the Full Report
What the study covers
- FormatsPDF · Excel · Dashboard
- Timeline2026–2033 annual, 2025 base
- Coverage20+ countries, 5 regions
- Companies10+ key players profiled
Customize the Report
20% free customization
- IncludeCountries, segments, points
- TailorTo your product definition
- ExtendDeeper competitor detail
- OrA fully bespoke study
- Turnaround5–10 working days
Governments across several regions have implemented strict controls on Volatile Organic Compound (VOC) emissions, encouraging industries to shift from solvent-based coatings to waterborne alternatives with lower environmental impact. Increasing awareness regarding environmental protection and health safety has also led companies and end users to prefer eco-friendly coatings that reduce air pollution and improve workplace safety.
 To learn more about this report, Download Free Sample Report
Rapid industrialization and urbanization across the world are driving construction activities, which are expected to significantly boost demand for waterborne coatings over the forecast period. Furthermore, the market shift from solvent-based coatings with high or moderate volatile organic compound (VOC) content to low-emission, solvent-free waterborne alternatives is supporting this growth, particularly in residential and commercial applications.
Interior and exterior wall paints predominantly use waterborne formulations, which are typically based on acrylate or styrene dispersions. Alkyd-based waterborne coatings are gaining popularity among interior designers due to their ease of application, glossy finish, and better adaptability to varying climatic conditions during application and drying. In the automotive sector, rising production levels, along with increasing focus on design innovation and aesthetics, are key growth drivers.
Market Concentration & Characteristics
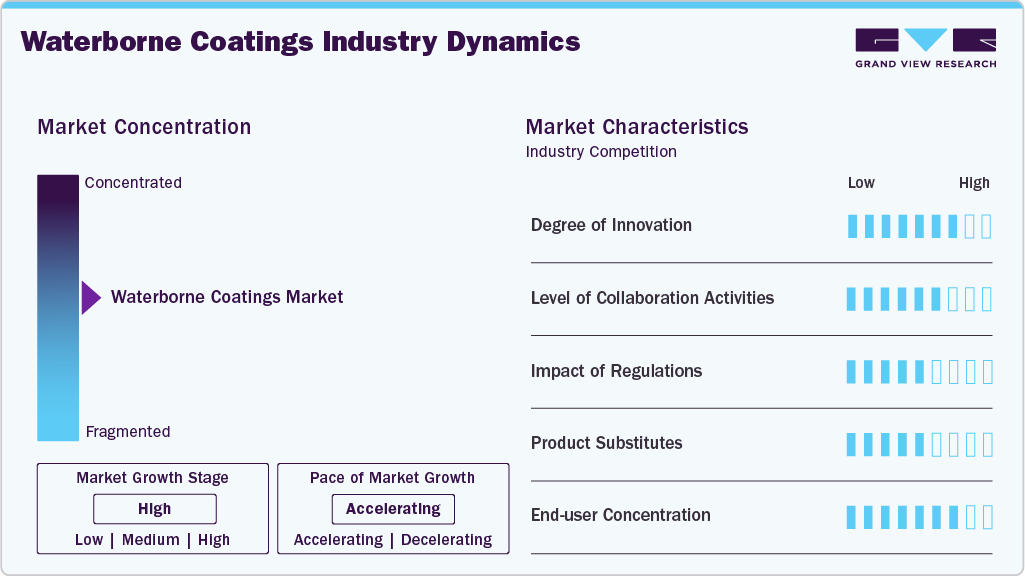
The global waterborne coatings market exhibits a moderately consolidated competitive structure, with the presence of several large multinational coating and chemical companies alongside a growing base of regional and specialty manufacturers. Key players such as AkzoNobel, PPG Industries, The Sherwin-Williams Company, and Axalta Coating Systems LLC dominate the market with their strong global distribution networks, extensive product portfolios, and continuous investment in research and development. These companies are benefiting from advanced formulation capabilities that enable them to develop high-performance, low-VOC coatings that comply with increasingly strict environmental regulations.
 To learn more about this report, Download Free Sample Report
The market is characterized by increasing fragmentation at the regional level, with numerous mid-sized and local manufacturers competing by offering cost-effective and application-specific solutions. The competitive landscape is further shaped by increasing demand for environmentally sustainable coatings across end-use industries, including construction, automotive, and industrial manufacturing. Key characteristics of the market include strong regulatory influence, a clear shift toward eco-friendly formulations, and continuous innovation in resin technologies and performance additives. Furthermore, companies are focusing on strategic initiatives such as mergers & acquisitions, capacity expansions, and partnerships to strengthen their technological capabilities and expand their presence in emerging markets.
Resin Insights
The acrylic segment dominated the global waterborne coatings market, accounting for 83.2% of revenue in 2025. The market is driven by cost efficiency and compliance with stringent environmental regulations. The expansion of the construction and renovation sector further supports the growth, as acrylic formulations are used in interior and exterior paints. In addition, the well-established supply chain and ease of formulation of acrylic resins enable manufacturers to scale production more efficiently than with other resin systems. Furthermore, key companies in the coatings industry, such as AkzoNobel, PPG Industries Inc., The Sherwin-Williams Company, Nippon Paint, BASF, and Kansai Paint, are strengthening their acrylic waterborne portfolios through continuous innovation and capacity expansion. These players are focusing on developing advanced acrylic hybrid systems, including acrylic-polyurethane blends, to enhance performance characteristics, such as abrasion resistance and flexibility. Collectively, these efforts are supporting the growth of the acrylic segment in the global waterborne coatings market.
The polyurethane segment is projected to record the fastest CAGR of 7.6% from 2026 to 2033, driven by increasing environmental regulations and the surging demand for high-performance, low-VOC coating solutions. Waterborne polyurethane coatings offer superior properties, including excellent abrasion resistance, flexibility, adhesion, and durability, making them suitable for demanding applications across the automotive, construction, and industrial sectors. Furthermore, the shift toward sustainable, eco-friendly materials, along with expanding construction activities and industrialization, is driving market growth. In addition, innovations such as bio-based polyurethane systems, hybrid formulations, and fast-curing technologies are further enhancing product adoption.
Application Insights
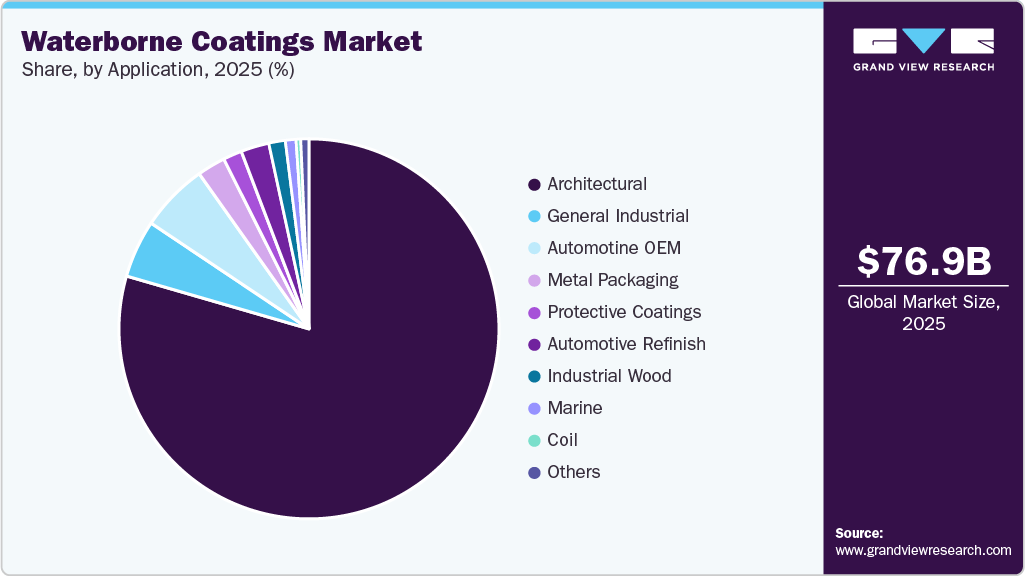
The architectural segment dominated the market in 2025. The segment growth is driven by increasing demand for sustainable construction materials. Strict rules on volatile organic compound (VOC) emissions are encouraging the use of water-based coatings as they are safer and have a lower environmental impact. In addition, rapid urbanization, growth in residential and commercial construction, and expanding infrastructure activities are boosting the demand for wall paints and decorative coatings. The segment is seeing increased demand due to rising renovation and repainting activities, where waterborne coatings are preferred for their low odor, quick drying, and ease of application. The growing adoption of green building practices and eco-friendly materials in construction is further strengthening the demand for waterborne coatings in architectural applications globally.
 To learn more about this report, Download Free Sample Report
The marine segment is projected to record the fastest CAGR from 2026 to 2033. Increasing global shipping activities and surging demand for corrosion-resistant and biofouling-resistant coatings are accelerating the adoption of waterborne technologies in shipbuilding and maintenance. In particular, cargo ships and passenger vessels are using low-VOC and eco-friendly coatings to comply with IMO emission norms while improving fuel efficiency and hull performance. The next-generation biofouling-resistant coatings and low-VOC marine systems are preferred for new ship builds and dry-docking maintenance programs to extend vessel life and reduce maintenance cycles. These trends are supported by rising global shipbuilding activity.
Regional Insights
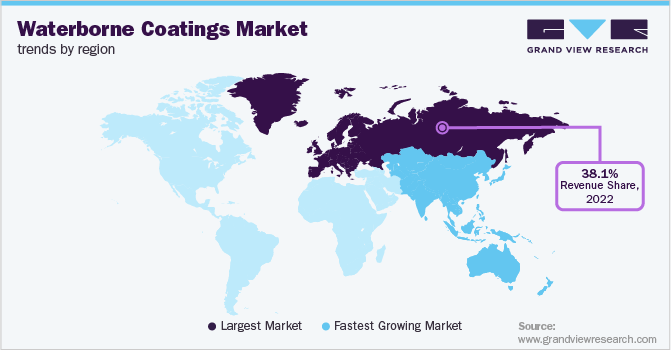
Asia Pacific dominated the global waterborne coatings market with a revenue share of 37.6% in 2025. Companies in the waterborne coatings market in the Asia Pacific region are focusing on collaboration and new product development to stay competitive. Many manufacturers are forming partnerships with technology providers, raw material suppliers, and automotive companies to improve coating performance, reduce emissions, and enhance application efficiency. In addition, companies are launching new waterborne coating products with better durability, faster drying time, and lower environmental impact. Overall, partnerships and product innovation are helping companies strengthen their presence and meet evolving customer requirements in the region. For instance, in March 2025, PPG launched a waterborne automotive coatings manufacturing facility in Thailand with an annual production capacity of approximately 2,000 tons. The plant is expected to strengthen production capabilities and support the increasing demand for sustainable coating solutions in the market.
 To learn more about this report, Download Free Sample Report
Japan Waterborne Coatings Market Trends
Japan is expected to grow at the fastest CAGR of 8.0% in the Asia Pacific waterborne coatings market during the forecast period. The country has strict environmental regulations that limit VOC emissions, encouraging industries to adopt eco-friendly waterborne coatings instead of solvent-based products. Furthermore, the country’s strong manufacturing base in automotive and electronics is driving the demand for these coatings due to their performance and compliance benefits. Ongoing construction, renovation, and infrastructure development drive the need for architectural coatings. Japan also emphasizes sustainability and innovation, with companies investing in advanced, low-emission coating technologies. Overall, regulatory support, industrial demand, and technological advancements are supporting market growth.
Europe Waterborne Coatings Market Trends
Europe accounted for a significant market share in 2025. Rising volatility in petrochemical and solvent prices is encouraging manufacturers to shift toward cost-effective waterborne alternatives. Increasing investments in rail and infrastructure development are supporting the adoption of durable and environmentally compliant coatings. Advancements in application technologies have improved product performance, making waterborne coatings more efficient and widely acceptable across industries.
The waterborne coatings market in Germany is expected to grow at a significant pace over the forecast period, on account of a strong automotive manufacturing base and an increasing focus on sustainable production. Regulatory frameworks such as EU REACH and VOC emission limits are encouraging industries to shift from solvent-based to waterborne systems. The country’s advanced automotive sector is also a key driver, as manufacturers are using waterborne coatings in OEM paint lines to reduce emissions. In addition, strong research and development capabilities are leading to continuous innovation in high-performance coatings.
North America Waterborne Coatings Market Trends
The growth of waterborne coatings market in North America is primarily driven by the expansion of electric vehicle (EV) and battery manufacturing facilities in the U.S. and Canada, where OEMs prefer waterborne systems for high-performance, controlled production environments. Large-scale infrastructure renewal programs, such as road, bridge, and public building upgrades, are also boosting the adoption of these coatings. Contractors are increasingly preferring low-odor, fast-drying coatings that are suitable for occupied or high-traffic sites.
The U.S. dominated the North American market, supported by a highly developed manufacturing base, strong R&D capabilities, and rapid adoption of low-VOC and sustainable coating technologies across key end-use industries. Active participation from major coatings manufacturers and continuous product innovations are also favoring the market. Increasing investments in advanced applications, such as automotive OEM, construction, and industrial equipment, are further driving the commercialization and large-scale deployment of waterborne coatings in the country.
Middle East & Africa Waterborne Coatings Market Trends
The waterborne coatings market in the Middle East and Africa is expected to grow significantly over the forecast period, due to increasing construction activities and the development of large infrastructure projects. Furthermore, the surging demand for eco-friendly and low-VOC coatings is fueling market growth. Harsh climatic conditions also support durable formulations. In addition, global players are introducing innovative products and expanding regional presence, further boosting market growth.
Latin America Waterborne Coatings Market Trends
The waterborne coatings market in Latin America is expected to grow due to increasing environmental regulations that encourage the use of low-VOC, eco-friendly products. Furthermore, rapid urbanization and rising construction activities in countries such as Brazil and Mexico are driving demand for these coatings in architectural applications. In addition, growth in the automotive and industrial sectors is also supporting market expansion, as manufacturers shift toward safer and more sustainable coating solutions. The increasing awareness of health and environmental impacts, along with steady renovation and maintenance activities, is further boosting the adoption of waterborne coatings across the region.
Key Waterborne Coatings Company Insights
Some of the key players operating in the market include The Sherwin-Williams Company and PPG Industries, Inc.
- PPG Industries Inc. is a global manufacturer of paints, coatings, and specialty materials. It offers architectural paints, automotive OEM and refinish coatings, industrial and protective coatings, marine solutions, powder coatings, and specialty chemicals and glass products. The company focuses on innovation, sustainability, and high-performance solutions, offering products that protect surfaces and enhance aesthetics.
Nippon Paint Holdings Company Ltd. and Kansai Paint Co. are emerging market participants.
- Nippon Paint Holdings Co., Ltd. is a global paint and coatings company operating across decorative, automotive, industrial, marine, and protective coating segments. The company focuses on delivering innovative, high-performance coating solutions that address evolving customer needs and environmental requirements. Its offerings include architectural paints, refinish coatings, and industrial solutions, aimed at enhancing durability, aesthetics, and sustainability across various applications.
Key Waterborne Coatings Companies:
The following key companies have been profiled for this study on the waterborne coatings market.
- Akzo Nobel N.V.
- BASF
- Axalta Coating Systems Ltd.
- Berger Paints India
- Kansai Paint Co., Ltd.
- Nippon Paint Holdings Co., Ltd.
- PPG Industries, Inc.
- RPM International Inc.
- The Sherwin-Williams Company
- Valspar
- Tikkurila
Recent Developments
-
In April 2025, Amcor completed an advanced healthcare packaging coating facility in Malaysia, expanding its manufacturing footprint in Southeast Asia. The plant introduces air-knife and waterborne coating technologies for medical packaging applications. The investment strengthens regional supply chain resilience, enhances local production capabilities, and supports growing demand for sterile, high-performance healthcare packaging solutions.
-
In February 2025, AkzoNobel introduced RUBBOL WF 3350, a new waterborne wood coating featuring 20% bio-based content, at its site in Sweden. The solution enhances sustainability by using renewable raw materials while maintaining high durability and performance standards.
-
In February 2024, Covestro launched waterborne UV coating solutions. The solutions focus on high-performance industrial applications such as cabinetry, building products, and wood furniture.
Waterborne Coatings Market Report Scope
Report Attribute
Details
Market size in 2025
USD 76.9 billion
Estimated Market size in 2026
USD 80.4 billion
Projected Market size by 2033
USD 115.3 billion
Growth rate
CAGR of 5.3% from 2026 to 2033
Base year for estimation
2025
Historical data
2021 - 2024
Forecast period
2026 - 2033
Quantitative units
Revenue in USD million/billion, volume in kilotons, and CAGR from 2026 to 2033
Report coverage
Revenue forecast, company ranking, competitive landscape, growth factors, and trends
Segments covered
Resin, Application, and Region
Regional scope
North America; Europe; Asia Pacific; Central & South America; Middle East ; Africa
Country scope
U.S.; Canada; Mexico, UK; Germany; France; Netherlands; Belgium; Spain; Poland; Sweden; China; India; Japan; South Korea; Malaysia; Indonesia; Vietnam; Australia; New Zealand; Brazil; Argentina; Colombia; Chile; Saudi Arabia; Iran; Oman; UAE; Qatar; Kuwait; South Africa; Angola; Nigeria
Key companies profiled
Akzo Nobel N.V.; BASF; Axalta Coating Systems Ltd.; Berger Paints India.; Kansai Paint Co. Ltd.; Nippon Paint Holdings Co., Ltd.; PPG Industries, Inc.; RPM International Inc.; The Sherwin-Williams Company; Valspar; and Tikkurila
Customization scope
Free report customization (equivalent to up to 8 analysts’ working days) with purchase. Addition or alteration to country, regional & segment scope.
Pricing and purchase options
Avail customized purchase options to meet your exact research needs. Explore purchase options
Global Waterborne Coatings Market Report Segmentation
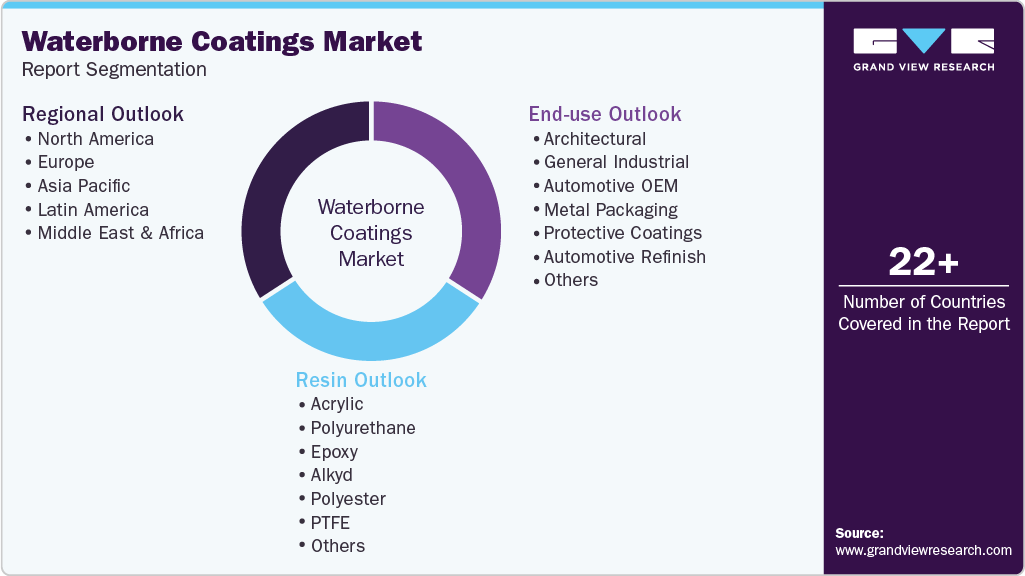
This report forecasts revenue growth at the global, regional, and country levels and provides an analysis of the latest industry trends in each of the sub-segments from 2021 to 2033. For this study, Grand View Research has segmented the global waterborne coatings market report based on resin, application, and region:
 To learn more about this report, Download Free Sample Report
-
Resin Outlook (Volume, Kilotons; Revenue, USD Million; 2021 - 2033)
-
Acrylic
-
Polyurethane
-
Epoxy
-
Alkyd
-
Polyester
-
PTFE
-
PVDC
-
PVDF
-
Others
-
-
Application Outlook (Volume, Kilotons; Revenue, USD Million; 2021 - 2033)
-
Architectural
-
General Industrial
-
Automotive OEM
-
Metal Packaging
-
Protective Coatings
-
Automotive Refinish
-
Industrial Wood
-
Marine
-
Coil
-
Others
-
-
Regional Outlook (Volume, Kilotons; Revenue, USD Million; 2021 - 2033)
-
North America
-
U.S.
-
Canada
-
Mexico
-
-
Europe
-
Germany
-
France
-
UK
-
Spain
-
Belgium
-
Sweden
-
Netherlands
-
Poland
-
-
Asia Pacific
-
China
-
India
-
Japan
-
South Korea
-
Malaysia
-
Indonesia
-
Vietnam
-
Australia
-
New Zealand
-
-
Latin America
-
Brazil
-
Argentina
-
Colombia
-
Chile
-
-
Middle East
-
Saudi Arabia
-
Iran
-
Oman
-
UAE
-
Qatar
-
Kuwait
-
-
Africa
-
South Africa
-
Angola
-
Nigeria
-
-
Frequently Asked Questions About This Report
The global waterborne coatings market size was valued at USD 76.9 billion in 2025 and is estimated at USD 80.4 billion for 2026.
The global waterborne coatings market is expected to grow at a CAGR of 5.3% from 2026 to 2033, reaching USD 115.3 billion by 2033.
Asia Pacific dominated with a 37.6% revenue share in 2025.
The architectural segment held the largest revenue share in 2025, while marine is the fastest-growing application.
Key players include Akzo Nobel N.V.; BASF; Axalta Coating Systems Ltd.; Berger Paints India.; Kansai Paint Co. Ltd.; Nippon Paint Holdings Co., Ltd.; PPG Industries, Inc.; RPM International Inc.; The Sherwin-Williams Company; Valspar; and Tikkurila.
The acrylic segment dominated the market with an 83.2% revenue share in 2025, primarily due to its strong balance of performance, cost efficiency, and environmental compliance. Acrylic-based waterborne coatings offer excellent durability, UV resistance, fast drying time, and low VOC emissions, which make them suitable for architectural, automotive, and industrial applications. The growth of this category is further supported by stricter environmental regulations and the global shift toward sustainable and eco-friendly coating systems.
The market is driven by increasing environmental regulations that restrict VOC emissions and promote low-toxicity solutions. Rising demand for sustainable and eco-friendly coatings across automotive, construction, and industrial sectors is another key driver. Growing urbanization, infrastructure development, and expanding automotive production, especially in Asia Pacific, are further supporting market expansion.
About the Author(s)
Paints, Coatings & Printing Inks Research Team
Bulk Chemicals · Paints, Coatings & Printing InksThis report was authored by the paints, coatings & printing inks research team at Grand View Research - comprising two research analysts, one senior research analyst, and one industry expert - with specialized expertise in the paints, coatings & printing inks segment of the bulk chemicals industry. All findings are based on proprietary bulk chemicals databases, executive interviews, and regulatory analysis, subject to internal peer review prior to publication.
Last Updated:
Speak to Analyst

Customize this report to your needs - add regions, segments, or data points, with 20% free customization.
Or view our licence options:


ISO 9001:2015 & 27001:2022 Certified
We are GDPR and CCPA compliant! Your transaction & personal information is safe and secure. For more details, please read our privacy policy.


