
- Home
- »
- Electronic Devices
- »
-
Webcam Market Size, Share & Trends Report, 2026-2033GVR Report cover

Webcam Market (2026 - 2033)
Size, Share & Trends Analysis Report By Technology (Analog, Digital), By Product (USB, Wireless), By Distribution Channel (Brick & Mortar, E-commerce), By End Use, By Region, And Segment Forecasts
Market Size, 2025
$10.0BMarket Estimate, 2026
$10.7BMarket Forecast, 2033
$17.2BCAGR, 2026–2033
7.1%Webcam Market Summary
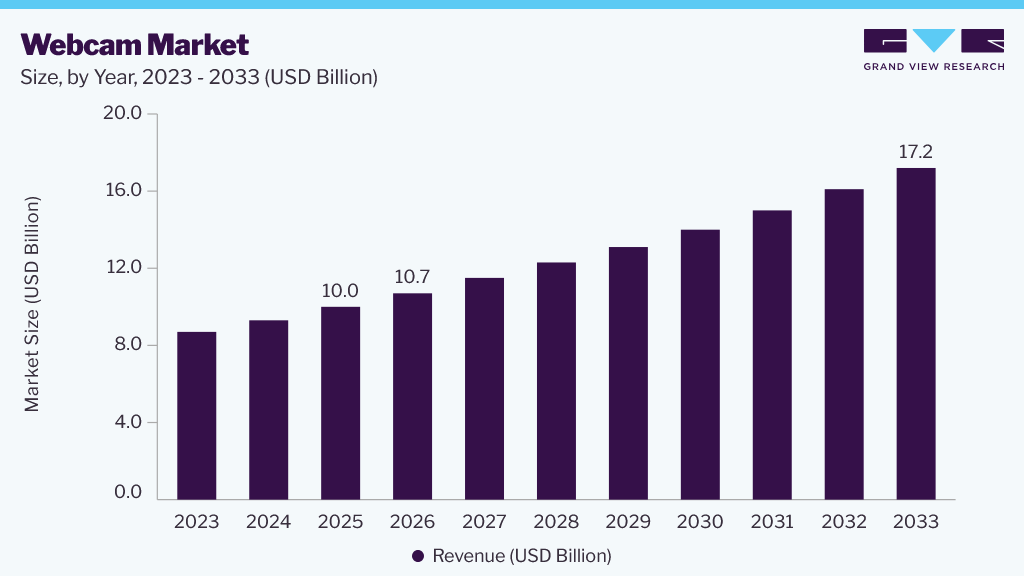
The global webcam market size was valued at USD 10.0 billion in 2025 and is projected to grow from USD 10.7 billion in 2026 to USD 17.2 billion by 2033, at a CAGR of 7.1% from 2026 to 2033. North America dominated the market, accounting for 45.0% of revenue in 2025. The global webcam industry is witnessing sustained growth, with digital communication, hybrid work, remote collaboration, and online content consumption becoming increasingly embedded across professional and consumer environments.
 Source: Grand View Research, IR Documents, Primary Interviews, Paid DatabasesTo learn more about this report,
 Download Free Sample Report
Key Market Trends & Insights
- By product: USB webcams segment held the largest market share of around 63.0% in 2025.
- By technology: Digital segment held the largest share of around 72.0% in 2025.
- By distribution channel: E-Commerce segment held the largest share of about 61.0% in 2025.
- By end use: Video conferencing segment held the largest revenue share of around 32.0% in 2025.
Regional Highlights
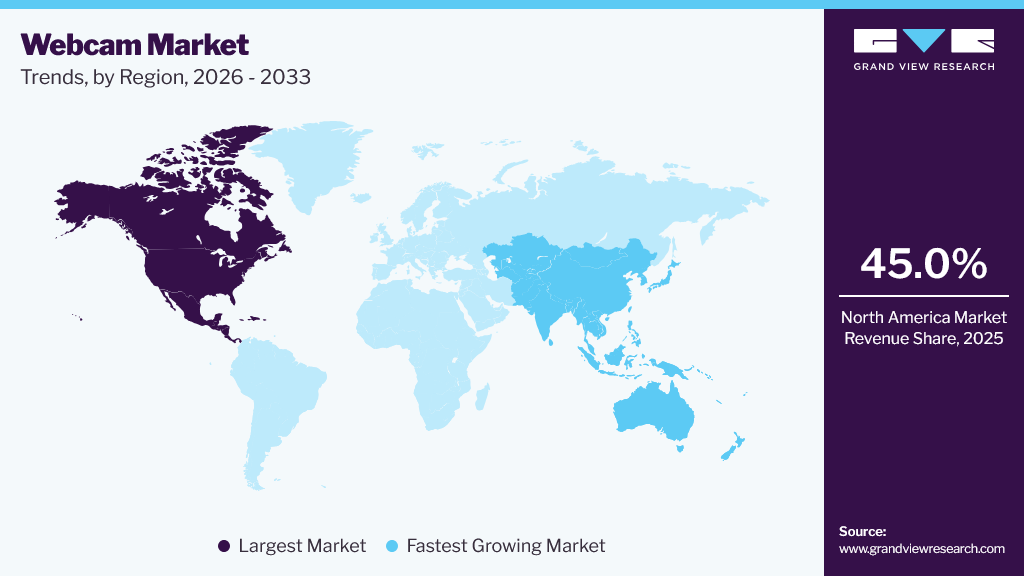
- Largest regional market: North America (45.0% revenue share, 2025)
- Fastest-growing regional market: Asia Pacific (fastest CAGR of over 8.6%, 2026-2033)
Market Size & Forecast
- Market size in 2025: USD 10.0 Billion
- Estimated market size in 2026: USD 10.7 Billion
- Projected market size by 2033: USD 17.2 Billion
- CAGR (2026-2033): 7.1%
Three ways to get this report
Buy it, customize it, or ask a question.Ask an Analyst
Analyst response in 1 business day
- AccessReport author, directly
- Reply timeWithin 1 working day
- No sales callDirect answer only
- FormatEmail reply
- CostFree, no cost
Get the Full Report
What the study covers
- FormatsPDF · Excel · Dashboard
- Timeline2026–2033 annual, 2025 base
- Coverage20+ countries, 5 regions
- Companies10+ key players profiled
Customize the Report
20% free customization
- IncludeCountries, segments, points
- TailorTo your product definition
- ExtendDeeper competitor detail
- OrA fully bespoke study
- Turnaround5–10 working days
The global webcam industry is witnessing sustained growth as digital communication, hybrid work, remote collaboration, and online content consumption become increasingly embedded across professional and consumer environments. While video conferencing remains a core application, demand is expanding across livestreaming, gaming, e-learning, telehealth, virtual events, customer engagement, and content creation. Enterprises are increasingly deploying webcams as part of modern collaboration infrastructure, particularly as distributed teams and flexible working arrangements continue to shape workplace communication. In parallel, the growing popularity of video-based social media and creator platforms is encouraging consumers and professionals to invest in higher-quality imaging solutions.Technological advancements are further transforming the webcam landscape. Manufacturers are increasingly integrating artificial intelligence (AI)-based features such as automatic framing, facial tracking, background enhancement, gesture recognition, and intelligent exposure adjustment to improve the user experience. The adoption of high-resolution 4K webcams, HDR imaging, improved low-light performance, beamforming microphones, and autofocus capabilities is also supporting demand for premium products. These developments are enabling webcams to compete not only as peripheral devices but also as intelligent communication and content-creation tools.
The healthcare sector remains an important application area, with webcams supporting telemedicine consultations, remote patient interactions, virtual specialist appointments, and healthcare communication. Growing digital healthcare infrastructure and improved broadband connectivity are facilitating the use of video-enabled services across developed and emerging markets. Similarly, educational institutions are expanding the use of webcams for virtual classrooms, blended learning, online assessments, and instructor-student interaction, creating additional avenues for market expansion.
Enterprise demand is also evolving beyond basic video conferencing. Organizations are increasingly seeking webcams that offer enhanced security, privacy shutters, plug-and-play connectivity, platform compatibility, and centralized device management. The growing adoption of unified communications and collaboration platforms is encouraging businesses to standardize video hardware across offices and home-based employees. At the same time, rising consumer interest in livestreaming, podcasting, gaming, and professional video production is creating demand for webcams with studio-quality imaging and audio capabilities.
Evolving user expectations, rapid advancements in imaging technology, and increasing internet penetration are compelling manufacturers to differentiate through intelligent features, superior image quality, privacy, and seamless software integration. Competitive dynamics are consequently shifting from resolution-focused offerings toward AI-enabled functionality, user experience, design, connectivity, and ecosystem compatibility. As webcam applications continue to diversify across enterprise, healthcare, education, and creator markets, ongoing product innovation and the integration of intelligent imaging technologies are expected to remain key factors shaping the future development of the market.
Market Dynamics
The webcam market is undergoing a structural shift driven by AI-enabled intelligence and expanding use cases. Growth is propelled by the integration of automated framing, noise suppression, and high-resolution imaging that elevate virtual collaboration and creator workflows. However, heightened privacy concerns and cybersecurity vulnerabilities associated with connected hardware pose adoption challenges, compelling manufacturers to embed physical shutters and implement robust encryption. Simultaneously, surging demand across remote work, education, and digital content creation unlocks lucrative opportunities for differentiated, multi-functional 4K devices.
The increasing integration of artificial intelligence into webcams is emerging as a key driver of market growth. Modern webcams are increasingly equipped with AI-enabled capabilities such as automatic framing, subject tracking, exposure adjustment, background optimization, and noise suppression, enabling users to maintain consistent video quality across diverse environments. The growing prevalence of hybrid work and virtual collaboration is further increasing demand for cameras capable of delivering professional-quality communication without requiring complex setups. The global video conferencing market is also expected to expand steadily through 2033, supported by continued adoption of remote and hybrid work models across enterprises and other end-use sectors. Recent product launches demonstrate the industry's shift toward intelligent cameras, with manufacturers incorporating AI-based tracking and image optimization into both mainstream and premium webcam models. Consequently, AI functionality is expected to enhance product differentiation and support replacement demand for conventional webcams.
Growing concerns about unauthorized access to cameras and the handling of visual data may restrain the expansion of the webcam market, particularly across business, healthcare, education, and home environments. Connected cameras can introduce additional privacy and cybersecurity considerations when video feeds, microphones, device permissions, or associated cloud services are compromised. Recent cybersecurity discussions continue to highlight vulnerabilities in internet-connected cameras, raising user awareness of camera access and data protection. At the same time, the growing incorporation of AI-based functions, including facial tracking and automated framing, may increase sensitivity around the processing of visual information. Manufacturers are therefore increasingly incorporating physical privacy shutters, camera indicators, and software-based controls into products to address these concerns. Recent webcam models from major vendors illustrate this trend through the inclusion of hardware privacy mechanisms alongside intelligent imaging capabilities. Nevertheless, concerns surrounding unauthorized surveillance, data handling, and device security could influence purchasing decisions and increase compliance and development costs.
The growing use of webcams beyond conventional video conferencing presents significant opportunities for market participants. Demand is expanding toward content creation, online education, livestreaming, virtual presentations, telehealth, and professional communications, creating opportunities for manufacturers to develop specialized products with higher resolution and enhanced imaging capabilities. Current products increasingly offer 4K video, improved low-light performance, autofocus, wider fields of view, and intelligent framing, allowing a single device to address multiple use cases. The expansion of hybrid collaboration is also supporting investment in video-enabled workspaces, while advances in AI are enabling webcams to automatically adjust framing and image characteristics during presentations and meetings. Furthermore, the availability of feature-rich webcams across different price points is lowering the entry barrier for individual creators, students, and small businesses. This convergence of professional communication and digital content creation is expected to create new avenues for product differentiation and market penetration.
Analyst Perspective
The global webcam market is positioned for steady growth as hybrid work, remote learning, livestreaming, telehealth, and digital collaboration sustain demand. Market development is shifting toward higher-value products featuring 4K resolution, AI-powered auto-framing, noise reduction, low-light optimization, and enhanced privacy controls. Competitive differentiation will increasingly depend on combining image quality with intelligent software, security, and seamless compatibility across conferencing and content-creation platforms. Growing adoption of professional-grade webcams among enterprises, creators, educators, and home users will support demand. Declining sensor costs and expanding broadband connectivity are also expected to broaden adoption across emerging markets. Overall, AI integration, design, ease of installation, ecosystem compatibility, and evolving user expectations will increasingly shape competition beyond resolution alone.
Product Insights
USB webcams dominated the market with a share of around 63.0% in 2025. Their ongoing popularity is underpinned by seamless cross-platform compatibility across Windows, Mac, and Linux operating systems. Modern iterations incorporate advanced thermal management profiles and optimized form factors that enable efficient heat dissipation while offering plug-and-play flexibility for diverse user setups. This reliability makes them a primary staple for desk-bound professionals and daily communication needs.
The wireless segment is anticipated to grow at the fastest CAGR of over 8.5% during the forecast period, as they are versatile in application, compatible, and provide higher resolution. These cable-free units leverage integrated image sensor chips that transmit visual packets over Wi-Fi, Bluetooth, or Ethernet, eliminating physical wear, infrastructure constraints, and security vulnerabilities associated with exposed cabling. They offer exceptional deployment flexibility, proving especially valuable when monitoring complex commercial premises or dynamic flexible spaces, which is further expected to favor the segment growth in the coming years.
Technology Insights
The digital technology segment dominated the webcam industry, with a share of around 72.0% in 2025, and is expected to grow at the fastest CAGR of around 9.0% over the forecast period. Digital webcams leverage advanced Charge-Coupled Device (CCD) or Complementary Metal-Oxide-Semiconductor (CMOS) sensors to convert optical data into high-definition pixels, backed by enhanced firmware encryption and high-grade cybersecurity protocols that far surpass traditional analog alternatives. These digital architectures ensure superior image fidelity and enable real-time processing capabilities such as autofocus and exposure correction. As modern enterprise networks demand stringent data protection standards, digital models continue to replace legacy analog systems across critical corporate and institutional environments.
The analog technology segment represents a legacy foundation within the market, catering to specialized setups that prioritize conventional closed-circuit workflows. Traditional analog webcams transmit continuous wave signals via physical coaxial cabling directly to digital video recorders (DVRs) or display monitors. While these systems are valued for their straightforward installation and predictable hardware budgets, they typically provide lower maximum resolutions and lack native network intelligence. Consequently, their adoption is increasingly confined to localized, cost-sensitive surveillance niches where advanced remote processing and high-definition data streaming are not primary requirements.
Distribution Channel Insights
The e-commerce segment led the webcam market with a revenue share of about 61.0% in 2025. The mega-giants in the e-commerce industry are taking measures against fake and counterfeit product suppliers to instill confidence in their customers while offering discounts on product purchases. This shift in consumer preferences from offline to online purchasing is expected to support the growth of the e-commerce segment during the forecast period. E-commerce platforms enable consumers to purchase products directly, reducing the involvement of intermediaries and distributors and potentially offering products at lower prices. This digital shift is further supported by convenient home delivery options and exhaustive online product reviews. Detailed comparison tools and bundle deals hosted on web platforms also empower buyers to evaluate specifications effortlessly, shifting brand preference toward direct online orders.
The brick & mortar segment is expected to grow over the forecast period as in-person channels remain favored by risk-conscious buyers seeking to avoid counterfeit hardware and verify build quality firsthand. Physical retail also allows consumers to evaluate camera form factors, weight, and privacy shutter mechanisms directly before committing to a purchase. Furthermore, the availability of products in-store directly supports enterprise clients experiencing urgent equipment breakdowns who require same-day replacements without waiting for shipping windows.
End Use Insights
The video conferencing segment captured the largest revenue share, at around 32.0% in 2025, driven by the widespread adoption of hybrid work models and cloud-based unified communication platforms. This strong market standing is largely driven by the ongoing adoption of cloud-enabled communication platforms. Rather than relying on standard built-in laptop cameras, organizations are increasingly equipping remote personnel and huddle spaces with standalone, high-definition hardware featuring 4K resolution, dynamic lighting adjustments, and AI-driven auto-framing. As enterprises standardize meeting environments around platforms like Microsoft Teams, Zoom, and Cisco Webex, recurring procurement across corporate offices, home setups, and satellite hubs continues to strengthen video conferencing as the primary revenue generator for the industry.
The security and surveillance segment is expected to grow at the fastest CAGR of over 9.0% during the forecast period. The growth is driven by heightened demand for intelligent commercial and residential monitoring solutions across retail storefronts, hospitality hubs, and corporate complexes to mitigate inventory shrinkage, vandalism, and security risks. The integration of smart analytics into these monitoring tools further maximizes site safety and operational transparency. Automated motion triggers and low-light sensor enhancements enable round-the-clock threat detection with minimal human supervision. These systems now securely connect to centralized mobile dashboards, providing facility managers with instant alerts and high-resolution playback from any remote location.
Regional Insights
The North America webcam market accounted for the largest global revenue share of over 45.0% in 2025, serving as the primary revenue-generating region worldwide. This sustained regional leadership is heavily driven by an exceptionally mature corporate IT infrastructure, widespread acceptance of hybrid and remote working models, and an early-adopter consumer base that rapidly embraces advanced smart hardware. Across the region, rapid enterprise digitization and massive investments in cloud-enabled unified communications have fundamentally transformed high-definition webcams from auxiliary accessories into core productivity infrastructure.
 To learn more about this report, Download Free Sample Report
Furthermore, the robust growth of the local digital creator economy, alongside stringent corporate requirements for secure visual communications, has accelerated replacement cycles toward premium intelligent hardware. Market participants across the region continuously focus on launching advanced models equipped with embedded AI capabilities, automated facial tracking, and studio-grade noise-canceling arrays to meet the high expectations of enterprise buyers. Heightened consumer emphasis on home security solutions, automated remote surveillance, and high-frequency live streaming has helped maintain robust demand across both consumer electronics and specialized retail distribution channels. Regulatory compliance mandates focusing on data protection and hardware-level encryption further dictate product development cycles, ensuring that privacy-centric designs remain a key purchase driver for regional corporate buyers.
U.S. Webcam Market Trends
The U.S. is the undisputed economic powerhouse and the largest market in North America. Propelled by a massive corporate ecosystem, a high concentration of remote technology workforces, and pervasive smart home integration, the U.S. market is projected to expand robustly over the forecast period. Demand in the region is intensely driven by corporate tech upgrades, widespread educational e-learning rollouts, and a massive base of digital content creators demanding ultra-HD 4K streaming tools. Strategic shifts toward flexible office spaces and decentralized enterprise teams ensure that the country remains the primary testing ground and revenue driver for high-end wireless and AI-enhanced webcam technologies.
Asia Pacific Webcam Market Trends
The Asia Pacific webcam industry is projected to expand at the fastest CAGR of over 8.6% during the forecast period. The rapid expansion is primarily driven by the surging digital infrastructure across emerging economies, the mass adoption of hybrid work environments, and the rapid expansion of the digital creator economy throughout East and South Asia. China, Taiwan, and Japan remain the global nerve centers for hardware manufacturing and optical sensor production.
Local OEMs and component suppliers (such as Lenovo, Xiaomi, and Insta360) are driving down average selling prices (ASPs) while introducing high-spec 4K and AI-enabled webcams directly into the regional market. Content creators, micro-influencers, and online retailers are continuously upgrading from standard integrated laptop webcams to high-performance standalone 4K and PTZ webcams with dynamic tracking, a trend expected to further favor market growth over the coming years.
Europe Webcam Market Trends
The Europe webcam industry demonstrates steady, resilient expansion, with a projected CAGR of over 6.3% from 2026 to 2033. European demand characteristics are uniquely shaped by rigorous regional data privacy frameworks, such as the General Data Protection Regulation (GDPR), which compel both enterprise clients and hardware manufacturers to prioritize top-tier cybersecurity protocols, encrypted local data handling, and physical privacy mechanisms. The region's accelerated transition toward sustainable digital workplaces, combined with strong adoption across public administration, telehealth, and academic institutions, provides a stable baseline for long-term deployment of commercial hardware.
Moreover, while traditional USB plug-and-play devices remain prevalent in standard corporate desk setups, wireless and IP-connected options are gaining momentum rapidly due to their flexibility in modern modular office environments. Furthermore, steady investments in automated security infrastructure across retail and industrial hubs continue to stimulate regional adoption of digital surveillance cameras. As European enterprises increasingly demand sustainable, energy-efficient electronics with robust compliance credentials, manufacturers are refining their supply chains to align with strict environmental compliance directives and consumer protection standards across the continent.
Germany is the largest and most influential market in Europe as of 2025, characterized by an extensive industrial manufacturing base, deep-rooted enterprise digitalization initiatives, and a strict adherence to workplace data security. Germany represents a highly lucrative ecosystem for advanced webcam technologies. The country's strong corporate emphasis on secure remote collaboration, combined with widespread adoption of industrial automation and smart commercial monitoring, ensures continuous commercial procurement of high-resolution digital and wireless camera systems across enterprises.
Key Webcam Company Insights
Key players in the market are actively expanding their product portfolios by intensifying research and development efforts in AI-integrated visual hardware and offering high-spec devices at competitive price points. To capture burgeoning market demand and strengthen regional footprint, leading manufacturers are partnering with local distributors, IT integrators, and third-party software platforms to deepen customer reach and lock in enterprise accounts. For instance, Cisco Systems has continually updated its smart video ecosystems with advanced enterprise devices, such as the Cisco Room Vision PTZ Camera, launched in mid-2025, and the Cisco Room Kit Pro G2, introduced at ISE 2026, designed to optimize AI-driven speaker tracking, video-over-IP, and hybrid workspace collaboration. Continuous innovation in onboard processing, automated framing, and secure endpoint communication remains pivotal for companies seeking to consolidate market share.
Key Webcam Companies
The following key companies have been profiled for this study of the webcam market.
-
Canon Inc.
-
10moons
-
Cisco Systems Inc.
-
Koninklijke Philips N.V.
-
Lenovo
-
Microsoft
-
Logitech International S.A. (Logitech)
-
D-Link Systems Inc.
-
Razer Inc.
-
Xiaomi
-
Sony Corporation
Recent Developments
-
In January 2026, Logitech International S.A. introduced the Logitech Rally AI Camera Pro during CES 2026. Built with onboard neural processing units (NPUs), the enterprise camera automates real-time multi-speaker tracking, gesture controls, and telemetry analytics connected to the Logitech Sync cloud infrastructure.
-
In October 2025, Razer Inc released the Razer Kiyo V2 and Kiyo V2 X streaming webcams to strengthen its position within the digital creator and gaming markets. The flagship lineup features integrated Sony STARVIS sensors and built-in Reincubate Camo AI tools, enabling auto-framing, intelligent exposure adjustments, and background isolation without requiring host CPU overhead.
-
In June 2025, Cisco Systems, Inc. launched the Cisco Room Vision PTZ Camera at InfoComm 2025. The deployment expanded Cisco’s visual hardware portfolio with an AI-driven video-over-IP tracking camera featuring 4K Ultra HD imaging, automated multi-subject framing, and integrated Power over Ethernet (PoE+) capabilities for enterprise conference spaces.
Webcam Market Report Scope
Report Attribute
Details
Market size in 2025
USD 10.0 billion
Estimated market size in 2026
USD 10.7 billion
Projected market size by 2033
USD 17.2 billion
Growth rate
CAGR of 7.1% from 2026 to 2033
Base year for estimation
2025
Historical data
2021 - 2024
Forecast period
2026 - 2033
Quantitative units
Revenue in USD million/billion, volume in million units, CAGR from 2026 to 2033
Report coverage
Revenue forecast, company ranking, competitive landscape, growth factors, trends
Segments covered
Technology, product, distribution channel, end use, region
Regional scope
North America; Europe; Asia Pacific; Latin America; MEA
Country scope
U.S.; Canada; UK; Germany; China; India; Japan; Brazil
Key companies profiled
Canon Inc.; 10Moons; Cisco Systems Inc.; Koninklijke Philips N.V.; Lenovo; Microsoft; Logitech; D-Link Systems Inc.; Razer Inc.; Xiaomi; Sony Corporation
Customization scope
Free report customization (equivalent to 8 analyst’s working days) with purchase. Addition or alteration to country, regional & segment scope
Pricing and purchase options
Avail customized purchase options to meet your exact research needs. Explore purchase options
Global Webcam Market Report Segmentation
This report forecasts revenue & volume growth at the global, regional & country levels and provides an analysis of the latest industry trends in each of the sub-segments from 2021 to 2033. For this study, Grand View Research has segmented the global Webcam Market report based on technology, product, distribution channel, end use, and region:
- Technology Outlook (Volume, Million Units; Revenue, USD Million/Billion, 2021 - 2033)
- Analog
- Digital
- Product Outlook (Volume, Million Units; Revenue, USD Million/Billion, 2021 - 2033)
- USB
- Wireless
- Distribution Channel Outlook (Volume, Million Units; Revenue, USD Million/Billion, 2021 - 2033)
- Brick & Mortar
- E-commerce
- End Use Outlook (Volume, Million Units; Revenue, USD Million/Billion, 2021 - 2033)
- Security and Surveillance
- Entertainment
- Video Conferencing
- Live Events
- Visual Marketing
- Others
- Regional Outlook (Volume, Million Units; Revenue, USD Million/Billion, 2021 - 2033)
- North America
- U.S.
- Canada
- Europe
- Germany
- UK
- Asia Pacific
- China
- India
- Japan
- Latin America
- Brazil
- Middle East & Africa
- North America
Frequently Asked Questions About This Report
The global webcam market size was estimated at USD 10.0 billion in 2025 and is expected to reach USD 10.7 billion in 2026.
The global webcam market is expected to grow at a compound annual growth rate of 7.1% from 2026 to 2033, reaching USD 17.2 billion by 2033.
The USB segment dominated the webcam market with a share of over 63.0% in 2025.
North America dominated with a 45.0% revenue share in 2025.
Key players include Canon Inc., 10Moons, Cisco Systems Inc., Koninklijke Philips N.V., Lenovo, Microsoft, Logitech International S.A. (Logitech), D-Link Systems Inc., Razer Inc., Xiaomi, and Sony Corporation.
About the Author(s)
Electronic Devices Research Team
Semiconductors & Electronics · Electronic DevicesThis report was authored by the electronic devices research team at Grand View Research - comprising two research analysts, one senior research analyst, and one industry expert - with specialized expertise in the electronic devices segment of the semiconductors & electronics industry. All findings are based on proprietary semiconductors & electronics databases, executive interviews, and regulatory analysis, subject to internal peer review prior to publication.
Last Updated:
Speak to Analyst

Customize this report to your needs - add regions, segments, or data points, with 20% free customization.
Or view our licence options:


ISO 9001:2015 & 27001:2022 Certified
We are GDPR and CCPA compliant! Your transaction & personal information is safe and secure. For more details, please read our privacy policy.


