
- Home
- »
- Medical Devices
- »
-
Wireless Cardiac Monitoring Systems Market Size, Growth Report, 2026-2033GVR Report cover

Wireless Cardiac Monitoring Systems Market (2026 - 2033)
Size, Share & Trends Analysis Report, By Type (Implantable Cardiac Monitors, Patch-Type Monitor, Mobile Cardiac Telemetry System), By End-User, By Region, And Segment Forecasts
Market Size, 2025
$4.1BMarket Estimate, 2026
$4.6BMarket Forecast, 2033
$9.7BCAGR, 2026–2033
11.4%Wireless Cardiac Monitoring Systems Market Summary
The global wireless cardiac monitoring systems market size was valued at USD 4.1 billion in 2025 and is projected to grow from USD 4.6 billion in 2026 to USD 9.7 billion by 2033, at a CAGR of 11.4% from 2026 to 2033. The North America dominated the market, accounting for a revenue share of 45.0% in 2025. Wireless cardiac monitoring systems are remote healthcare devices that track heart activity for medical analysis.
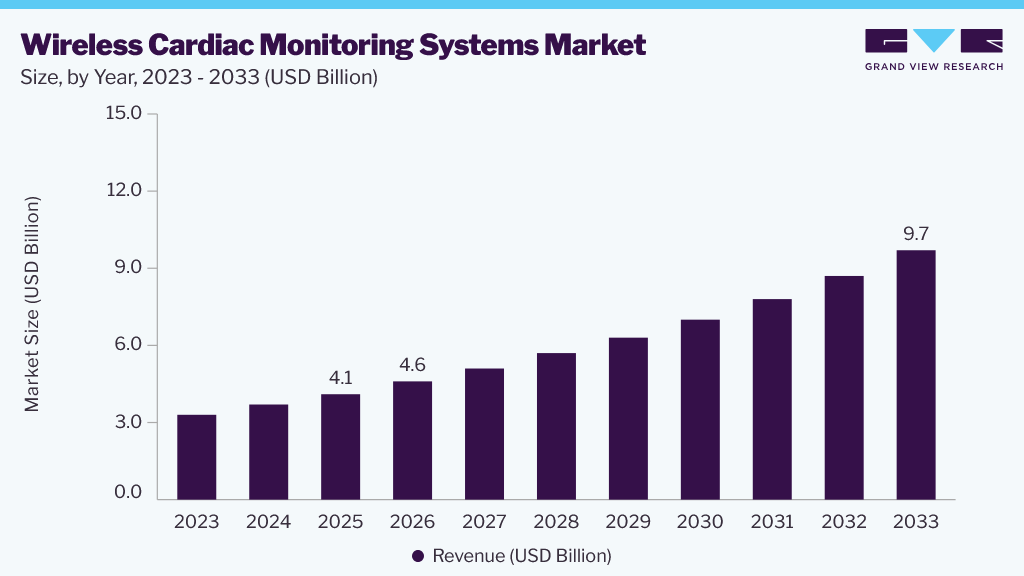 Source: Grand View Research, IR Documents, Primary Interviews, Paid DatabasesTo learn more about this report,
 Download Free Sample Report
Key Market Trends & Insights
- By type: The mobile cardiac telemetry systems segment led the market with the largest revenue share of over 35.0% in 2025.
- By end-use: The hospitals & clinics segment accounted for the highest market share of over 46.0% in 2025.
Regional Highlights
- Largest regional market: North America (45.0% revenue share, 2025)
- Fastest-growing regional market: Asia-Pacific (highest CAGR, 2026-2033)
Market Size & Forecast
- Market size in 2025: USD 4.1 Billion
- Estimated market size in 2026: USD 4.6 Billion
- Projected market size by 2033: USD 9.7 Billion
- CAGR (2026-2033): 11.4%
Three ways to get this report
Buy it, customize it, or ask a question.Ask an Analyst
Analyst response in 1 business day
- AccessReport author, directly
- Reply timeWithin 1 working day
- No sales callDirect answer only
- FormatEmail reply
- CostFree, no cost
Get the Full Report
What the study covers
- FormatsPDF · Excel · Dashboard
- Timeline2026–2033 annual, 2025 base
- Coverage20+ countries, 5 regions
- Companies10+ key players profiled
Customize the Report
20% free customization
- IncludeCountries, segments, points
- TailorTo your product definition
- ExtendDeeper competitor detail
- OrA fully bespoke study
- Turnaround5–10 working days
The market is expected to grow due to several factors, such as a growing geriatric population susceptible to cardiovascular diseases (CVDs), technological advancements in remote monitoring technologies, and increasing product approvals in developed economies. In 2025, the OECD reported that the proportion of individuals aged 65 years and older in the European Union increased from 18% in 2000 to 22% in 2024 and is projected to reach 29% by 2050. The report highlighted that population aging is expected to place greater pressure on healthcare systems and contribute to a substantial increase in the prevalence of cardiovascular diseases across Europe over the coming decades.
The advancements in remote patient monitoring technology are expected to boost the market. A growing number of industry players are entering into strategic alliances, such as funding and collaboration, to develop vendor-neutral cardiac data management platforms that allow companies to monitor medical information from implantable cardiac monitors (ICMs), wearable devices, consumer ECG devices, and other sources.
In addition, Technological advancements in remote patient monitoring and connected cardiac care platforms are expected to support market growth. Industry participants are increasingly investing in vendor-neutral cardiac data management systems that integrate data from implantable cardiac monitors, wearable devices, consumer ECG systems, and hospital-based monitoring solutions. The integration of artificial intelligence into these platforms is improving workflow efficiency through automated data analysis, prioritization of critical events, and enhanced clinical decision-making. For instance, in September 2025, Royal Philips partnered with Optum Healthcare to expand access to mobile cardiac telemetry (MCOT) and extended Holter monitoring solutions, supporting broader adoption of remote cardiac monitoring technologies and connected cardiac care services.
Analyst Perspective
The wireless cardiac monitoring systems market is evolving from episodic cardiac assessment toward continuous, data-driven patient management. Growing adoption of remote monitoring technologies, wearable cardiac devices, and AI-enabled analytics is enabling earlier detection of arrhythmias and improving long-term cardiovascular care. Healthcare providers are increasingly prioritizing connected monitoring solutions that reduce hospital visits while supporting proactive clinical intervention. The market is also benefiting from expanding reimbursement support and rising demand for home-based healthcare services. Companies that successfully integrate device connectivity, automated data interpretation, and scalable remote monitoring platforms are expected to strengthen their competitive position over the forecast period.
Type Insights
By type, mobile cardiac telemetry systems dominated the market, accounting for over 35.0% of revenue in 2025. These systems continuously monitor cardiac activities, improving diagnosis and patient compliance. In addition, medical professionals are actively integrating telemedicine into general practice, enabling them to analyze long-term heart rhythm data and deliver patient-centric solutions via mobile cardiac telemetry.
The patch-type monitor segment is expected to grow at the fastest CAGR during the forecast period. Patch-type monitors are non-invasive and attached to the patient’s skin with adhesive. In addition, these devices are more discreet and convenient than traditional holter devices. A growing player participation in this category is expected to drive the growth of wireless cardiac monitoring systems. For instance, in August 2024, iRhythm Technologies launched its Zio Cardiac Arrhythmia Monitoring Service in Austria, the Netherlands, Switzerland, and Spain. The service includes the Zio wearable electrocardiogram (ECG) patch along with the artificial intelligence-driven ZEUS analytics platform. enabling up to 14 days of continuous cardiac rhythm monitoring and supporting improved arrhythmia detection.
End-Use Insights
By end-use, hospitals & clinics dominated the market, accounting for over 46.0% of revenue in 2025. The share is attributable to the hospital and clinic’s ability to manage patients who often require continuous cardiac monitoring because of their critical conditions. Moreover, these healthcare providers are equipped with nuanced medical equipment and specialized staff who facilitate the usage and diagnosis of wireless cardiac monitoring systems.
The diagnostic centers segment is anticipated to grow during the forecast period. The growing focus on outsourcing monitoring activities to independent facilities aids segment growth. For example, independent diagnostic testing facilities (IDTF) are specialized facilities with expertise in diagnostic testing, including cardiac monitoring. In addition, these facilities are increasing their collaboration with healthcare providers, further strengthening their growth. For instance, in December 2024, SmartCardia acquired Cardiomedix, a U.S.-based Independent Diagnostic Testing Facility (IDTF). The acquisition enabled SmartCardia to offer an integrated cardiac monitoring service that combines wearable monitoring devices, AI-driven analytics, clinician reporting, and accredited diagnostic testing within a unified platform.
Regional Insights
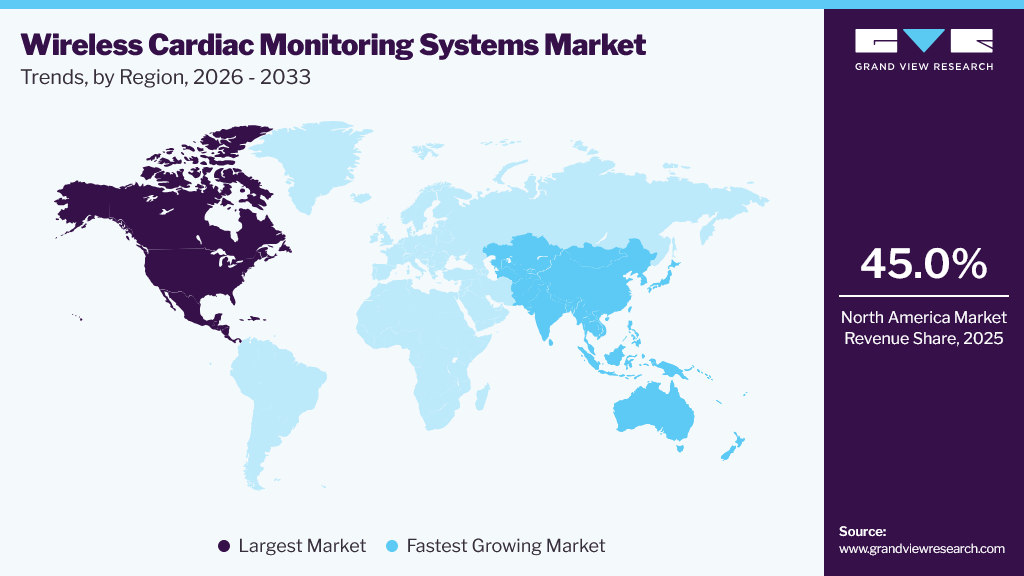
North America dominated the market, accounting for a revenue share of 45.0% of the market in 2025. The share is attributed to the advanced healthcare infrastructure, high prevalence of cardiovascular diseases, high healthcare expenditure, and a growing geriatric population. The growing burden of cardiovascular diseases and the rising aging population are driving demand for advanced cardiac monitoring solutions across the region.
 To learn more about this report, Download Free Sample Report
Advancements in wearable devices, mobile health applications, artificial intelligence, and cloud computing platforms have increased the precision and effectiveness of wireless cardiac monitoring devices. In 2024, the American Heart Association (AHA) projected that over 61.0% of U.S. adults might have some form of cardiovascular disease by 2050, highlighting the growing need for long-term cardiac monitoring and disease management solutions.
Asia Pacific Wireless Cardiac Monitoring Systems Market Trends
Asia-Pacific is expected to witness the fastest CAGR during the forecast period, driven by the growing prevalence of cardiovascular diseases, increasing healthcare infrastructure, healthcare expenditure, and growing adoption of telehealth and remote patient monitoring solutions across countries such as China, Japan, India, and South Korea. The increasing use of wearable cardiac monitoring devices, artificial intelligence-enabled diagnostics, and cloud-based healthcare platforms is improving access to continuous cardiac care and supporting early disease detection.
In February 2025, AliveCor introduced the Kardia 12L ECG System in India. The device combines a compact form factor with AI-enabled ECG analysis and is designed to support assessment of multiple cardiac abnormalities, including heart rhythm disorders and signs of myocardial infarction. Its simplified single-cable configuration allows ECG acquisition in a range of clinical care environments. The initiative improved access to mobile cardiac monitoring technologies and digital arrhythmia detection tools, supporting the adoption of connected cardiac care solutions across the region.
Key Wireless Cardiac Monitoring Systems Company Insights
The market is highly competitive, with many manufacturers. The market players are focusing on strategic initiatives such as new product launches, geographical expansion, mergers and acquisitions, collaborations, product upgrades, and partnerships.
Key Wireless Cardiac Monitoring Systems Companies
The following key companies have been profiled for this study on the wireless cardiac monitoring systems market:
-
Koninklijke Philips N.V.
-
Abbott Laboratories
-
Medtronic plc
-
BIOTRONIK SE & Co. KG
-
Boston Scientific Corporation
-
Asahi Kasei Corporation
-
iRhythm Technologies, Inc.
-
Avertix Medical, Inc.
-
Baxter International Inc.
-
OSI Systems, Inc. (Spacelabs Healthcare)
Recent Developments
-
In September 2025, Masimo announced an expanded multi-year strategic partnership with Philips to accelerate the integration of Masimo monitoring technologies into Philips patient monitoring platforms. The collaboration integrates wearable monitoring solutions and next-generation multi-parameter monitoring technologies used in wireless patient and cardiac monitoring applications.
-
In July 2025, Royal Philips announced a collaboration with Epic to integrate Philips’ ambulatory cardiac monitoring and diagnostic services with Epic’s Aura platform. The collaboration focuses on improving workflow connectivity and streamlining access to cardiac monitoring data across healthcare systems.
Wireless Cardiac Monitoring Systems Market Report Scope
Report Attribute
Details
Market size in 2025
USD 4.1 billion
Estimated Market size in 2026
USD 4.6 billion
Projected Market size by 2033
USD 9.7 billion
Growth Rate
CAGR of 11.4% from 2026 to 2033
Base year for estimation
2025
Actual data
2021 – 2025
Forecast period
2026 – 2033
Quantitative units
Revenue in USD Billion, and CAGR from 2026 to 2033
Report coverage
Revenue forecast, company ranking, competitive landscape, growth factors, and trends
Segments covered
Type, end-use, region
Regional Scope
North America, Europe, Asia Pacific, Latin America, Middle East & Africa
Country scope
U.S.; Canada; Mexico; UK; Germany; France; Italy; Spain; China; India; Japan; Australia & New Zealand, South Korea; Brazil; Argentina; South Africa; UAE
Key companies profiled
Koninklijke Philips N.V.; Abbott Laboratories; Medtronic plc; BIOTRONIK SE & Co. KG; Boston Scientific Corporation; Asahi Kasei Corporation; iRhythm Technologies, Inc.; Avertix Medical, Inc.; Baxter International Inc.; OSI Systems, Inc. (Spacelabs Healthcare).
Customization scope
Free report customization (equivalent up to 8 analysts working days) with purchase. Addition or alteration to country, regional & segment scope.
Pricing and purchase options
Avail of customized purchase options to meet your exact research needs. Explore purchase options
Global Wireless Cardiac Monitoring Systems Market Report Segmentation
This report forecasts revenue growth at the regional and country levels and provides an analysis of the latest industry trends and opportunities in each sub segment from 2021 to 2033. For this study, Grand View Research has segmented global wireless cardiac monitoring systems market report on the basis of type, end-use, and region.
Type (Revenue in USD Billion, 2021 - 2033)
-
Implantable Cardiac Monitors (ICM)
-
Patch-Type Monitor
-
Mobile Cardiac Telemetry System
-
Others
End-use (Revenue in USD Billion, 2021 - 2033)
-
Hospitals & Clinics
-
Diagnostic Centers
-
Others
-
Regional Outlook (Revenue in USD Billion 2021 - 2033)
-
North America
-
U.S.
-
Canada
-
-
Europe
-
UK
-
Germany
-
France
-
Italy
-
Spain
-
Sweden
-
Norway
-
Denmark
-
-
Asia Pacific
-
China
-
Japan
-
India
-
Australia
-
Thailand
-
South Korea
-
-
Latin America
-
Brazil
-
Mexico
-
Argentina
-
-
Middle East and Africa
-
Saudi Arabia
-
South Africa
-
UAE
-
Kuwait
-
-
Frequently Asked Questions About This Report
The global wireless cardiac monitoring systems market size was valued at USD 4.1 billion in 2025 and is estimated at USD 4.6 billion for 2026.
The global wireless cardiac monitoring systems market is expected to grow at a CAGR of 11.4% from 2026 to 2033, reaching USD 9.7 billion.
North America dominated with a revenue share of approximately 45.0% in 2025.
Key players in the market include Koninklijke Philips N.V., Abbott Laboratories, Medtronic plc, BIOTRONIK SE & Co. KG, Boston Scientific Corporation, Asahi Kasei Corporation, iRhythm Technologies, Inc., Avertix Medical, Inc., Baxter International Inc., and OSI Systems, Inc. (Spacelabs Healthcare). and others
The mobile cardiac telemetry systems segment accounted for the largest revenue share of over 35.0% in 2025.
About the Author(s)
Medical Devices Research Team
Healthcare · Medical DevicesThis report was authored by the medical devices research team at Grand View Research - comprising two research analysts, one senior research analyst, and one industry expert - with specialized expertise in the medical devices segment of the healthcare industry. All findings are based on proprietary healthcare databases, executive interviews, and regulatory analysis, subject to internal peer review prior to publication.
Last Updated:
Speak to Analyst

Customize this report to your needs - add regions, segments, or data points, with 20% free customization.
Or view our licence options:


ISO 9001:2015 & 27001:2022 Certified
We are GDPR and CCPA compliant! Your transaction & personal information is safe and secure. For more details, please read our privacy policy.


