
- Home
- »
- Digital Media
- »
-
Wireless In-Flight Entertainment Market Size Report, 2033GVR Report cover

Wireless In-Flight Entertainment Market (2026 - 2033)
Size, Share & Trends Analysis Report By Aircraft Type (Narrow-body, Wide-body), By Fitment Type (Retrofit, Line fit), By Hardware (Antennas, WAPs, Modems), By Technology, By Region And Segment Forecasts
Market Size, 2025
$2.9BMarket Estimate, 2026
$3.5BMarket Forecast, 2033
$4.1BCAGR, 2026–2033
15.5%Wireless In-Flight Entertainment Market Summary
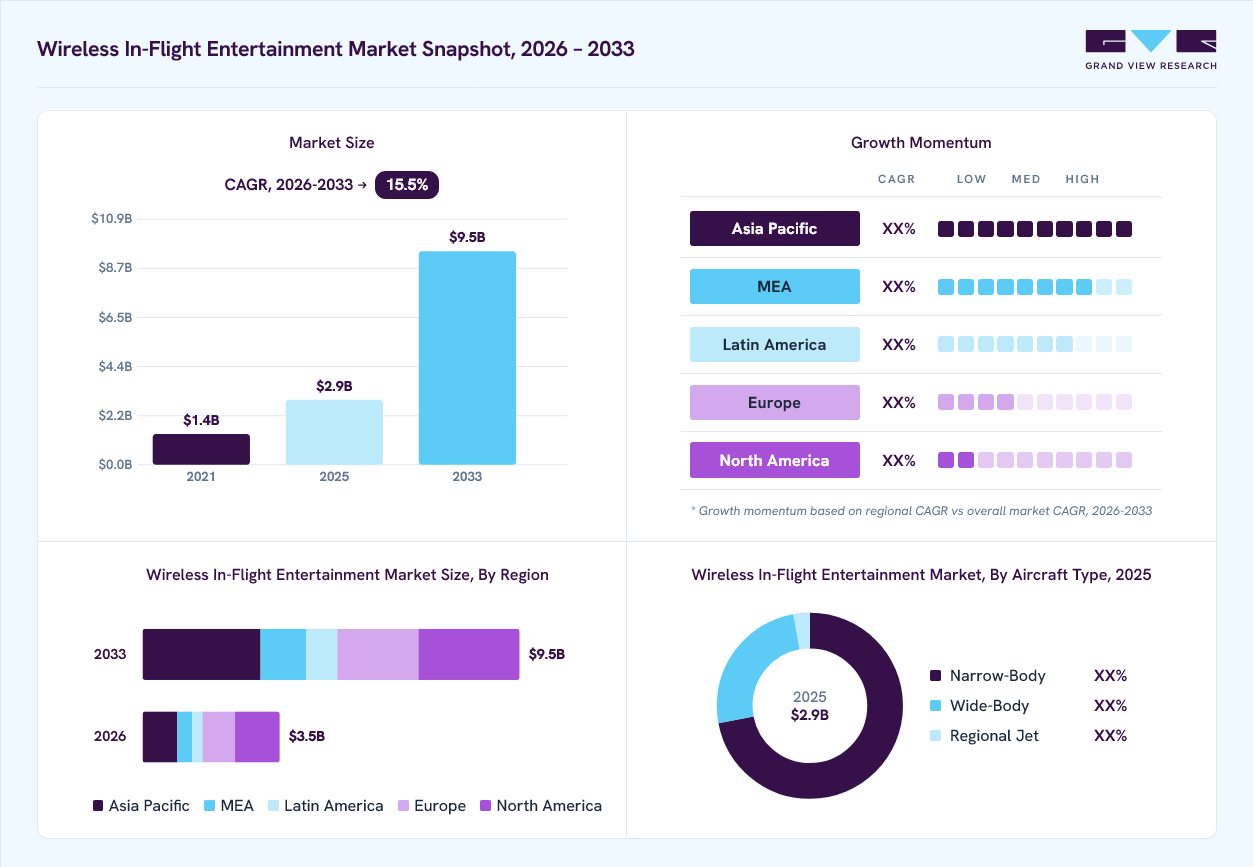
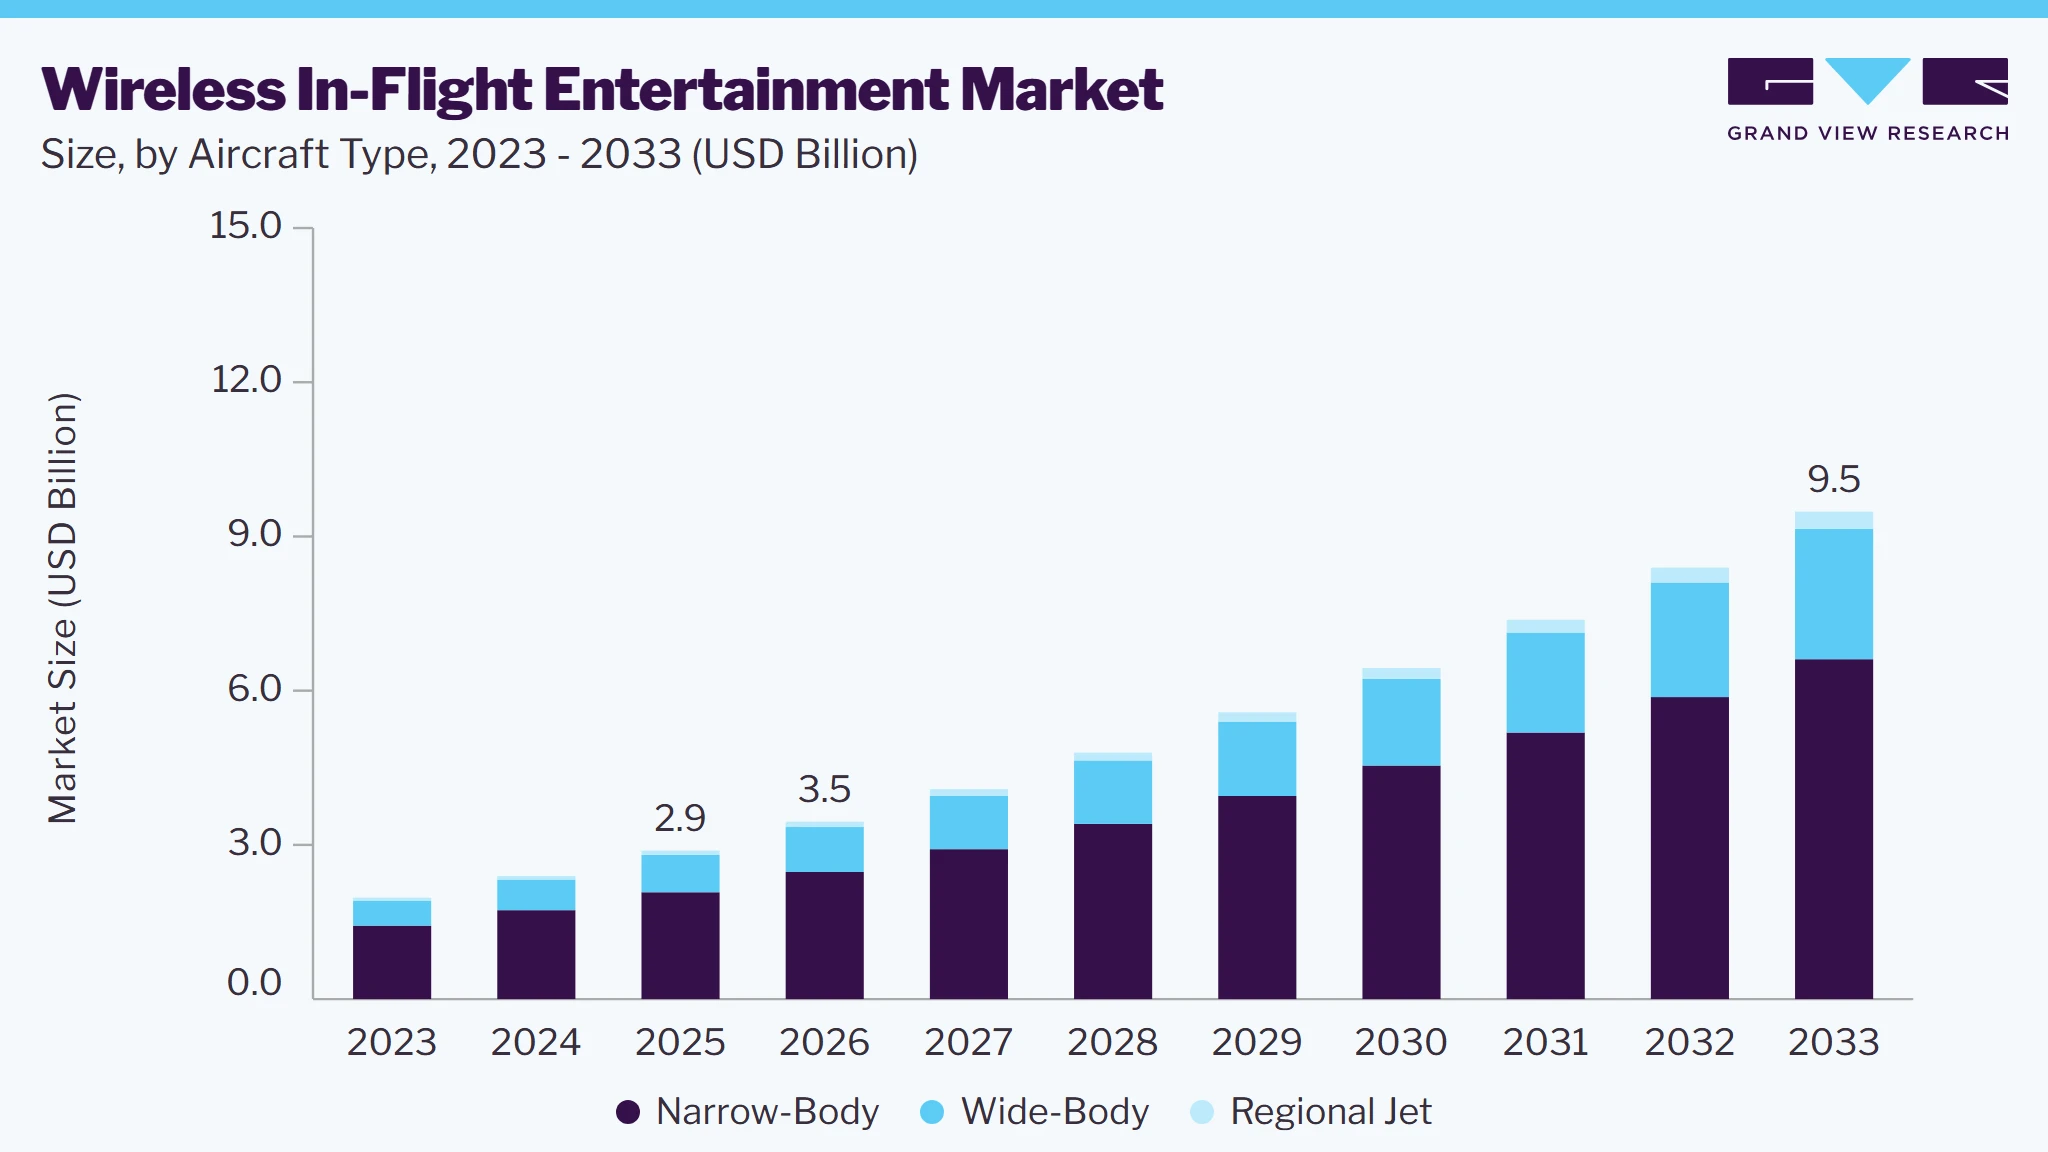
The global wireless in-flight entertainment market size was valued at USD 2.9 billion in 2025 and is projected to grow from USD 3.5 billion in 2026 to USD 9.5 billion by 2033, at a CAGR of 15.5% from 2026 to 2033. North America dominated the market, accounting for a revenue share of 33.4% in 2025. The wireless in-flight entertainment market is driven by the increasing demand for seamless onboard digital entertainment, the growing adoption of Bring Your Own Device (BYOD) strategies by airlines, and the rising integration of high-speed wireless connectivity and cloud-based content delivery solutions into modern aircraft.
 Source: Grand View Research, IR Documents, Primary Interviews, Paid DatabasesTo learn more about this report,
 Download Free Sample Report
Key Market Trends & Insights
- By aircraft type: The narrow-body segment dominated the market, with a share of 71.9% in 2025.
- By fitment type: The retrofit segment accounted for the largest market share of 84.3% in 2025.
- By hardware: The antenna development segment dominated the market in 2025.
- By technology: The ATG segment held the largest market share in 2025.
Regional Highlights
- Largest regional market: North America (33.4% revenue share in 2025)
- Fastest growing regional market: Asia Pacific (highest CAGR 19.1%, 2026-2033)
- By Country: The U.S. held the largest market share in 2025.
Market Size & Forecast
- Market size in 2025: USD 2.9 Billion
- Estimated market size in 2026: USD 3.5 Billion
- Projected market size by 2033: USD 9.5 Billion
- CAGR (2026-2033): 15.5%
Three ways to get this report
Buy it, customize it, or ask a question.Ask an Analyst
Analyst response in 1 business day
- AccessReport author, directly
- Reply timeWithin 1 working day
- No sales callDirect answer only
- FormatEmail reply
- CostFree, no cost
Get the Full Report
What the study covers
- FormatsPDF · Excel · Dashboard
- Timeline2026–2033 annual, 2025 base
- Coverage20+ countries, 5 regions
- Companies10+ key players profiled
Customize the Report
20% free customization
- IncludeCountries, segments, points
- TailorTo your product definition
- ExtendDeeper competitor detail
- OrA fully bespoke study
- Turnaround5–10 working days
The expanding deployment of wireless streaming platforms, onboard Wi-Fi networks, content management systems, digital passenger engagement applications, and real-time flight information services is significantly accelerating the adoption of wireless in-flight entertainment solutions across commercial and business aviation. These advancements are improving passenger satisfaction, increasing airline operational efficiency, and creating significant growth opportunities in the wireless in-flight entertainment market. The market growth is attributed to consumers' increasing inclination to utilize personal electronic devices while in flight, which has complemented the rising adoption of wireless in-flight entertainment and connectivity services.The increased proliferation of personal devices, such as laptops, smartphones, and tablets, has prompted airlines to start offering wireless in-flight connectivity & entertainment services to passengers, thereby providing them access to a wide spectrum of stored as well as streaming entertainment content and other connectivity services on their personal devices.
 To learn more about this report, Download Free Sample Report
Furthermore, passengers’ personal devices or portable/embedded media interface devices provided by the airline can readily access these services. Both airlines and passengers can benefit from installing W-IFE systems in aircraft, and these tools can help airlines boost their revenue and increase return on investment. The combination of the In-Flight Connectivity (IFC) and In-Flight Entertainment (IFE) segments has opened up numerous opportunities under the W-IFE umbrella, including the live streaming of movies and other audio-visual content. The growing penetration of portable electronic devices and portable digital media tablets remains prominent in the BYOD era.
The aviation industry witnessed a major impact of COVID-19 pandemic. The global supply chains and logistics were suddenly affected during the initial worldwide lockdowns. Airline operators' sales for in-flight entertainment and connectivity system were affected by the drop in commercial aircraft deliveries caused by the coronavirus outbreak. This factor is anticipated to limit market expansion during the forecast period. However, a number of key players are focusing and working on implementing new strategies and tactics to overcome the pandemic's impact.
The aviation sector began to recover slowly from the pandemic in 2021, which led to an increase in aircraft deliveries. The improvement in the overall in-flight travel experience of passengers continues to drive airlines and aircraft operators to upgrade new cabin entertainment systems. This rebound in the aviation sector and aircraft deliveries is fueling the investments. For instance, in May 2022, Air France introduced their new long-haul business seat, which is expected to offer the highest level of comfort with redesigned iconic seat features.
Passengers now anticipate having access to both consistent connectivity and high-definition content owing to the growing demand for streaming services. Airlines now provide customers Wi-Fi connectivity so they can access in-flight and other entertainment content on their devices. For instance, the Emirates Group offers more than 5,00 channels of TV shows, music, movies, and games, all on demand in multiple languages, along with Wi-Fi connectivity for uninterrupted communications.
Market Dynamics
The wireless in-flight entertainment market is experiencing significant growth owing to the increasing emphasis on enhancing passenger experience, the rapid advancement of onboard wireless connectivity technologies, and the growing demand for personalized digital entertainment across commercial and business aviation. Rising air passenger traffic, increasing investments in aircraft cabin modernization, and the expansion of connected aircraft initiatives are encouraging airlines and aircraft operators to deploy advanced wireless in-flight entertainment solutions across both new and existing fleets. The advancements in satellite communication, high-speed air-to-ground connectivity, content personalization, artificial intelligence-based recommendation engines, edge computing, and data analytics are enabling seamless content delivery, enhancing passenger satisfaction, improving operational efficiency, reducing aircraft weight and maintenance requirements, and strengthening airline competitiveness, thereby creating substantial opportunities for long-term market growth.
The increasing expectation for seamless digital experiences during air travel is becoming a primary factor encouraging airlines to invest in wireless in-flight entertainment solutions. Modern passengers prefer uninterrupted access to movies, television shows, music, games, flight information, and destination-related content on their personal smartphones, tablets, and laptops. Wireless entertainment platforms support these expectations by delivering personalized content without requiring traditional seatback displays, improving convenience while enhancing overall passenger satisfaction.
Airlines are increasingly adopting Bring Your Own Device (BYOD) strategies to reduce aircraft weight, simplify cabin configurations, and minimize maintenance associated with seatback entertainment systems. Wireless in-flight entertainment platforms also enable faster content updates, multilingual programming, targeted promotional services, and real-time passenger communication. These capabilities strengthen customer engagement, improve service quality, and help airlines differentiate their onboard experience while optimizing operational efficiency across short-haul and long-haul flights.
Maintaining consistent wireless connectivity throughout an entire flight remains a significant challenge for airlines deploying wireless in-flight entertainment systems. Service interruptions can occur due to varying satellite coverage, limited air-to-ground network availability, adverse weather conditions, or aircraft operating across remote oceanic and polar regions. Such inconsistencies may affect streaming quality, increase buffering, and reduce passenger confidence in onboard digital entertainment services.
Airlines must also invest in advanced communication infrastructure, redundant network systems, and continuous software optimization to improve service reliability. Integrating wireless entertainment with existing aircraft communication equipment while complying with aviation certification requirements further increases implementation complexity. These technical and operational challenges can delay deployments, increase ownership costs, and limit adoption among airlines operating older aircraft fleets or serving geographically challenging routes.
The increasing availability of artificial intelligence, cloud computing, and advanced passenger analytics is creating new opportunities for highly personalized wireless entertainment experiences. Airlines can leverage passenger preferences, travel history, language selection, and viewing behavior to recommend customized entertainment, destination information, shopping offers, and onboard services directly through wireless portals. Such personalization enhances passenger engagement while improving the perceived value of onboard digital services.
The integration of wireless entertainment platforms with e-commerce, loyalty programs, food ordering, premium content subscriptions, and destination-based travel services is expanding the functionality of onboard digital ecosystems. Airlines can generate additional ancillary revenue through targeted advertising, retail partnerships, and premium entertainment offerings while delivering more relevant experiences to travelers. These innovations support stronger customer relationships and improve the commercial value of wireless entertainment investments.
Market Concentration & Characteristics
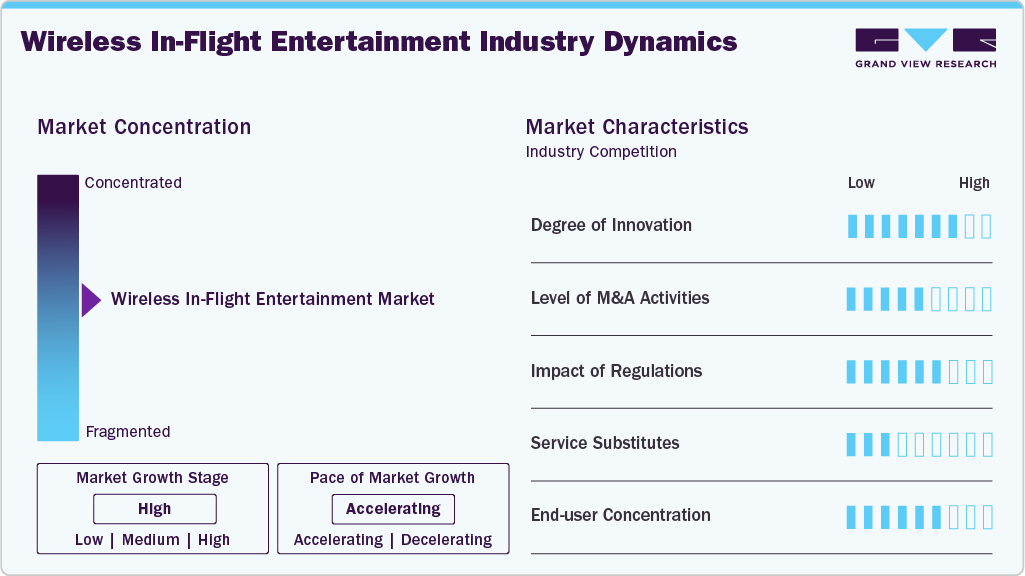
The Wireless In-Flight Entertainment Market is moderately concentrated, with leading aircraft connectivity providers, cabin technology companies, in-flight entertainment solution providers, satellite communication companies, and software developers competing across wireless content streaming, onboard connectivity, passenger engagement platforms, content management systems, and cabin digitalization solutions. Rising demand for enhanced passenger experiences, increasing aircraft modernization programs, and the growing adoption of connected aircraft technologies are driving market expansion. Companies are strengthening their competitive positions through strategic partnerships, acquisitions, cloud-based platform development, and continuous investments in next-generation wireless connectivity and digital entertainment solutions.
 To learn more about this report, Download Free Sample Report
The market is characterized by a high degree of innovation, supported by rapid advancements in satellite communications, high-speed onboard Wi-Fi, cloud-based content delivery, artificial intelligence-driven content personalization, and wireless streaming technologies. Merger and acquisition activity remains moderately high as companies expand connectivity capabilities and strengthen digital aviation portfolios. Regulatory impact is significant due to stringent aviation certification requirements, cybersecurity standards, passenger data privacy regulations, and aircraft safety compliance. The threat of substitutes remains moderate because traditional seatback entertainment systems and passengers' pre-downloaded offline content continue to serve as alternatives, although they offer lower flexibility and personalization than modern wireless in-flight entertainment solutions.
Analyst Perspective
The wireless in-flight entertainment market is experiencing significant expansion, driven by increasing airline investments in enhancing the passenger experience, rapid advancements in onboard wireless connectivity technologies, and the growing adoption of connected aircraft, Bring Your Own Device (BYOD) platforms, and cloud-based entertainment solutions across commercial and business aviation. The growing adoption of high-speed satellite communications, wireless streaming platforms, artificial intelligence-driven content personalization, advanced content management systems, and real-time passenger engagement applications is improving onboard service quality, operational efficiency, and customer satisfaction. Airlines are increasingly prioritizing cabin digitalization, seamless onboard connectivity, and ancillary revenue opportunities through personalized digital services. Technology providers are well-positioned to capitalize on emerging opportunities, thereby reinforcing long-term market expansion and sustainable revenue generation across the global aviation ecosystem.
Aircraft Type Insights
Based on aircraft type, the narrow-body segment led the market with the largest revenue share of 71.9% in 2025 and is expected to grow at a considerable CAGR over the forecast period. The strong growth of the segment is driven by the surge in demand for short-haul flights as well as the opening of new airports and travel routes. These aircraft are more appealing since they outperform their rivals in terms of ergonomics and fuel efficiency. Some of the major airlines are presently replacing their fleet of old, inefficient narrow-body aircraft with newer, more fuel-efficient ones to offer substantial growth opportunities during the forecast period.
The regional jet segment is projected to grow at the highest CAGR of 20.0% from 2023 to 2030. Airlines are modernizing and upgrading their fleets of smaller planes with portable electronic devices, entertainment systems, and Wireless In-Flight Connectivity (W-IFEC) across the globe. Airlines are also forging strategic partnerships with connectivity providers in order to improve their systems. For instance, in January 2022, Asiana Airlines Inc. partnered with Anuvu Operations LLC, a provider of high-speed connectivity and entertainment solutions, to serve as Content Service Provider (CSP) for the company.
Fitment Type Insights
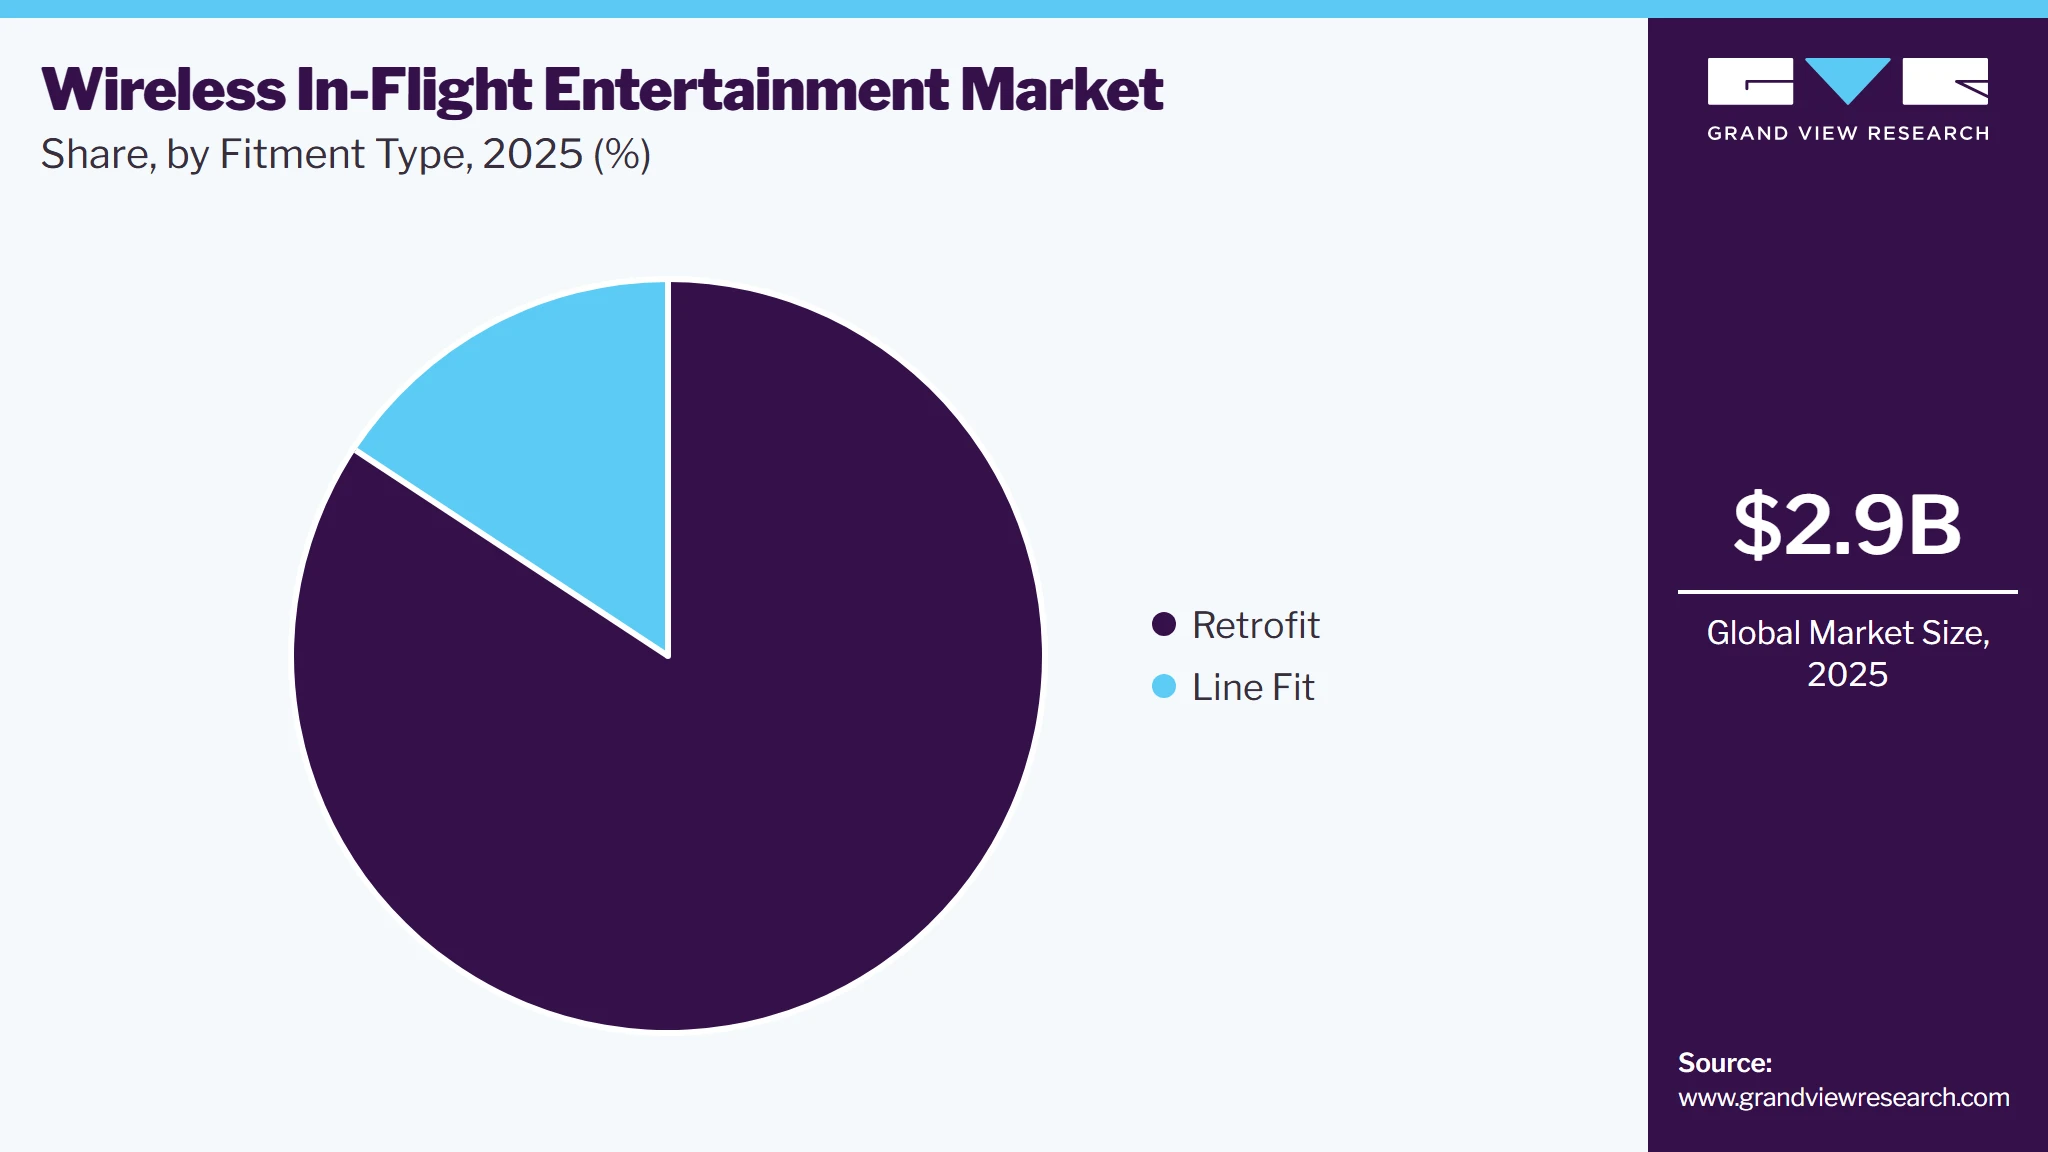
Based on fitment type, the retrofit segment dominated the market with the largest revenue share of 84.3% in 2025. This can be attributed to the ongoing advancement in aviation industries and revitalizing the cabin with advanced technologies to offer a better in-flight experience to passengers. Additionally, airlines have begun retrofitting wireless in-flight technology to reduce overall weight, enhance the passenger experience, and boost profit margins on each trip, which is expected to drive the growth further.
 To learn more about this report, Download Free Sample Report
The line fit segment is anticipated to grow at the highest CAGR of about 20% over the forecast period. Connection providers and hardware suppliers are increasingly stepping into the line fit segment to assess their system offerings and provide uniform W-IFE solutions in their fleet by creating strategic alliances with aircraft manufacturers. For instance, Embraer SA, a global aerospace company, and Viasat Inc., a global communication company, partnered into an agreement of Buyer-Furnished Equipment (BFE) to offer Viasat's cutting-edge In-Flight Connectivity (IFC) technology as line-fit option on E2 aircraft of Embraer’s aircraft family.
Hardware Insights
Based on hardware, the antennas segment led the market with the largest revenue share of 47.6% in 2025. The segment's growth can be attributed to the rising demand for antennas in the aviation sector for better connectivity. For instance, in April 2019, Viasat Inc., a global communication company, introduced its second-generation antenna. This dual-band system is expected to keep crew members as well as passengers connected, irrespective of their destination globally
The modem segment is predicted to register the fastest CAGR of around 19% from 2023 to 2030. This can be attributed to the emergence of next-generation Airborne Network (AN) and Airborne Internet (AI) systems as it uses a combination of satellite and terrestrial wireless technologies to provide coverage across the globe. Moreover, advancement in modem technology to offer uninterrupted connectivity and enhanced in-flight experience is projected to further boost the growth.
Technology Insights
Based on technology, the ATG segment dominated the market with a revenue share of 42.1% in 2025. The use of Ku-Band for high-speed applications such as video, computer-to-computer data communications, voice, and SCADA and mainframe workstations is expected to drive the segment growth during the forecast period. Additionally, compared to the Ka-Band frequency spectrum, Ku-Band is less vulnerable to rain fade, making it more effective for certain geographic locations, resulting in market growth during the forecast period.
The Ka-Band segment is projected to grow at the highest CAGR of 20.2% from 2023 to 2030. This can be attributed to its usage and support in several revenue streams, such as stationary and mobile equipment, including airborne and marine systems, satellite gateways, and others. Additionally, it allocates more spectrum for applications such as internet access and 5G connectivity, as it has higher bandwidth than any other bands used in the segment. Hence, the segment is expected to witness significant market growth.
Regional Insights
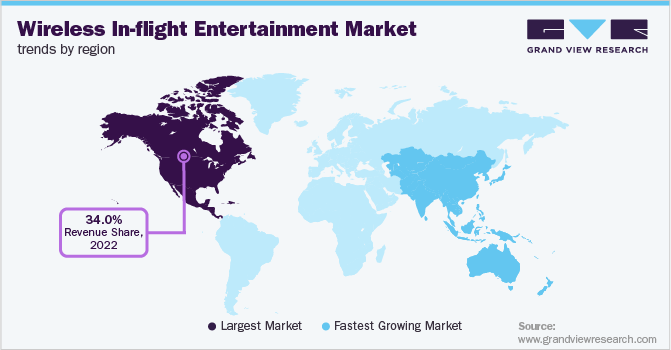
North America dominated the wireless in-flight entertainment market with the largest revenue share of 33.4% in 2025. Regional airlines in wealthy nations are anticipated to use W-IFE technologies more frequently, which is anticipated to propel the regional industry growth. Some well-known entertainment and communication companies, such as Viasat Inc. and Panasonic Avionics Corporation, always attempt to offer passengers innovative technologies in the region.
 To learn more about this report, Download Free Sample Report
U.S. Wireless In-Flight Entertainment Market Trends
The wireless in-flight entertainment market in the U.S. held the largest share in the North America region in 2025.
For instance, in August 2021, Panasonic Avionics Corporation launched the world’s first full cabin in-flight entertainment 4k ultra-HD system in association with Cathay Pacific Airways. Passengers on Cathay Pacific can use their own Bluetooth-enabled headphones to experience the latest Hollywood content in 4K on the screen, which supports Bluetooth audio streaming. This is expected to propel the regional growth over the forecast period.
The Asia Pacific region is expected to grow at a significant CAGR of around 21.0% during the forecast period. This can be attributed to the rising passenger traffic and demand for aircraft equipped with the region's next-generation communication and entertainment systems. For instance, in February 2022, Thai Airways partnered with Stellar Entertainment Group, an in-flight entertainment company, to work as a new content service partner for the airline group.
The company is expected to offer a range of in-flight entertainment services, including production services, television, and audio content, strategic curation and licensing of all film, account management, technical assistance, and content delivery. This, in turn, is expected to fuel the industry growth across the region.
Key Companies & Market Share Insights
Key players in the wireless in-flight entertainment market are offering and expanding their product portfolios by investing in product research & development and delivering competitive pricing, which furthers market rivalry. It is anticipated that these investments would eventually help airlines better meet passengers' demands for in-flight media and improve the connectivity experience by creating a digital environment, which is very similar to that at work or home.
The competition in this market is high. Moreover, technological advancements are allowing companies to save time and cost while increasing their efficiency and effectiveness, creating an incentive to gain a competitive edge. Constant research and development are leading to the industry becoming more common and standard even if it requires some investment. Due to globalization, the wireless in-flight entertainment trend is present in global markets over boundaries. Some prominent players in the global wireless in-flight entertainment market include:
Key Wireless In-Flight Entertainment Companies
The following key companies have been profiled for this study on the wireless in-flight entertainment market.
-
BAE Systems plc
-
Bluebox Aviation Systems Ltd.
-
Gogo LLC
-
Inflight Dublin, Ltd.
-
Lufthansa Systems GmbH
-
Panasonic Avionics Corporation
-
Rockwell Collins Inc.
-
SITAONAIR
-
Thales Group SA
-
Zodiac Aerospace SA
Competitive Benchmarking
Category
Operating Strategies
Competitive Edge
Weakness
Established Players (BAE Systems plc, Rockwell Collins Inc., Thales Group SA)
- Focus on expanding integrated wireless connectivity ecosystems through partnerships with satellite, software, and aircraft manufacturers.
- Invest heavily in R&D and cabin digitalization to deliver globally scalable, aircraft-certified entertainment solutions.
- Strong global airline relationships, certified technologies, and extensive deployment experience support market leadership.
- Ability to provide reliable, end-to-end wireless entertainment, connectivity, and content management solutions across fleets.
- Dependence on legacy onboard systems can slow migration toward next-generation wireless entertainment platforms.
- Large organizational structures may reduce deployment agility and delay innovation compared to emerging technology providers.
Emerging Players (Panasonic Avionics Corporation, Rockwell Collins Inc., SITAONAIR)
- Emerging players focus on developing cloud-native wireless entertainment platforms through partnerships in connectivity and software technologies.
- Invest in agile product development to deliver cost-effective, passenger-centric digital cabin solutions for airlines.
- Flexible technology platforms enable rapid innovation and faster deployment across diverse aircraft configurations.
- Ability to deliver customized wireless entertainment solutions with competitive pricing for regional airline operators.
- Limited global deployment experience may restrict large-scale contracts with major international airline fleets.
- Smaller financial resources can constrain technology investments, certifications, and long-term customer support capabilities.
Wireless In-flight Entertainment Market Report Scope
Report Attribute
Details
Market size in 2025
USD 2.9 Billion
Estimated market size in 2026
USD 3.5 Billion
Projected market size by 2033
USD 9.5 Billion
Growth rate
CAGR of 15.5% from 2026 to 2033
Base year for estimation
2025
Historical data
2021 - 2024
Forecast period
2026 - 2033
Quantitative units
Revenue in USD Million, and CAGR from 2026 to 2033
Report coverage
Revenue forecast, company ranking, competitive landscape, growth factors, and trends
Segments covered
Aircraft type, fitment type, hardware, technology, region
Regional scope
North America; Europe; Asia Pacific; Latin America; MEA
Country scope
U.S.; Canada; Mexico; U.K.; Germany; France; China; Japan; India; South Korea; Australia; Brazil; Saudi Arabia; UAE; South Africa
Key companies profiled
BAE Systems plc; Bluebox Aviation Systems Ltd.; Gogo LLC; Inflight Dublin, Ltd.; Lufthansa Systems GmbH; Panasonic Avionics Corporation; Rockwell Collins Inc.; SITAONAIR; Thales Group SA; Zodiac Aerospace SA
Customization scope
Free report customization (equivalent up to 8 analysts' working days) with purchase. Addition or alteration to country, regional & segment scope.
Pricing and purchase options
Avail customized purchase options to meet your exact research needs. Explore purchase options
Global Wireless In-Flight Entertainment Market Segmentation
This report forecasts revenue growth at global, regional, and country levels and provides an analysis of the latest industry trends in each of the sub-segments from 2021 to 2033. For this study, Grand View Research has segmented the global wireless in-flight entertainment market report based on aircraft type, fitment type, hardware, technology, and region:
-
Aircraft Type Outlook (Revenue, USD Million, 2021 - 2033)
-
Narrow-body
-
Wide-body
-
Regional Jet
-
-
Fitment Type Outlook (Revenue, USD Million, 2021 - 2033)
-
Retrofit
-
Line fit
-
-
Hardware Outlook (Revenue, USD Million, 2021 - 2033)
-
Antennas
-
WAPs
-
Modems
-
Others
-
-
Technology Outlook (Revenue, USD Million, 2021 - 2033)
-
ATG
-
Ku-Band
-
L-Band
-
Ka-Band
-
-
Regional Outlook (Revenue, USD Million, 2021 - 2033)
-
North America
-
U.S.
-
Canada
-
Mexico
-
-
Europe
-
Germany
-
U.K.
- France
-
-
Asia Pacific
-
China
-
Japan
-
India
-
South Korea
-
Australia
-
-
Latin America
-
-
Brazil
-
-
Middle East and Africa
-
Saudi Arabia
-
UAE
-
South Africa
-
-
Research Methodology
The wireless in-flight entertainment market figures in this report are based on a proven research process that combines executive interviews with secondary research from proprietary databases, company filings, and recognized regulatory and institutional sources. Market size is built through value-chain sizing - reconciling supply-side and demand-side estimates - and triangulated with bottom-up and top-down approaches. Every estimate passes multiple levels of expert validation before publication, with each wireless in-flight entertainment segment quantified using the revenue-capture definitions in the table below.
Segment Definition
Segment - Aircraft Type
Revenue capture definition
Narrow-body
Revenue is generated through wireless in-flight entertainment solutions installed in narrow-body aircraft operating short- and medium-haul routes. This segment is driven by increasing fleet expansion, high passenger volumes, and growing airline investments in connected cabin experiences.
Wide-body
Revenue is generated through wireless entertainment systems deployed in wide-body aircraft serving long-haul and international routes. This segment is driven by greater passenger demand for premium onboard entertainment, high-speed connectivity, and enhanced digital travel experiences.
Regional Jet
Revenue is captured through wireless in-flight entertainment platforms integrated into regional jets operating short-distance routes. This segment is driven by the increasing adoption of cost-effective cabin connectivity solutions among regional airlines to improve passenger satisfaction.
Segment - Fitment Type
Revenue capture definition
Retrofit
Revenue is generated through the installation of wireless in-flight entertainment systems on existing aircraft fleets during maintenance and cabin upgrade programs. This segment is driven by airlines seeking to modernize cabins, improve passenger services, and extend aircraft operational life.
Line fit
Revenue is generated through factory-installed wireless in-flight entertainment solutions integrated into newly manufactured aircraft before delivery. This segment is driven by growing demand for connected aircraft and increasing collaboration between airlines, aircraft manufacturers, and system providers.
Segment - Hardware
Revenue capture definition
Antennas
Revenue is generated through aircraft-mounted antennas that enable communication with satellite or air-to-ground networks for wireless entertainment and onboard connectivity. This segment is driven by increasing deployment of high-speed broadband communication technologies.
WAPs
Revenue is generated through wireless access points that distribute onboard Wi-Fi connectivity to passengers' personal devices throughout the aircraft cabin. This segment is driven by rising adoption of Bring Your Own Device (BYOD) entertainment platforms.
Modems
Revenue is generated through onboard modems that manage data transmission between aircraft communication systems and external satellite or ground networks. This segment is driven by growing demand for reliable, high-capacity wireless communication infrastructure.
Others
Revenue is captured through supporting hardware components, including onboard servers, network switches, storage devices, power distribution units, and communication interfaces required for wireless in-flight entertainment systems. This segment is driven by continuous aircraft connectivity upgrades and cabin digitalization initiatives.
Segment - Technology
Revenue capture definition
ATG
Revenue is generated through air-to-ground communication technology that delivers wireless connectivity using terrestrial cellular networks during flight. This segment is driven by cost-effective connectivity requirements for domestic and short-haul airline operations.
Ku-Band
Revenue is generated through Ku-band satellite communication systems that provide high-speed wireless internet and entertainment services on commercial aircraft. This segment is driven by widespread global coverage and increasing airline demand for reliable onboard broadband connectivity.
L-Band
Revenue is generated through L-band satellite communication technology that supports essential onboard connectivity, operational communications, and limited passenger data services. This segment is driven by its high reliability, consistent signal performance, and ability to maintain connectivity under challenging weather conditions.
Ka-Band
Revenue is generated through Ka-band satellite communication systems offering high-capacity broadband connectivity for streaming, real-time entertainment, and internet services. This segment is driven by increasing demand for faster data speeds, greater bandwidth efficiency, and next-generation connected aircraft solutions.
Estimation Model
Layer Name
Key Question
Description
Airline Adoption Layer
Who are the potential adopters?
Identifies the primary adopters of wireless in-flight entertainment solutions, including commercial airlines, low-cost carriers, full-service airlines, business aviation operators, charter airlines, government and VIP aircraft operators, and aircraft leasing companies seeking to enhance passenger experience, improve onboard connectivity, reduce aircraft weight, and increase ancillary revenue opportunities.
Connectivity Infrastructure Layer
Who can deploy wireless entertainment solutions?
Deployment depends on the availability of aircraft-certified wireless access points, satellite communication systems, air-to-ground connectivity, onboard servers, antennas, cloud-based content management platforms, cybersecurity solutions, cabin network infrastructure, and certified installation and maintenance capabilities supporting uninterrupted onboard digital entertainment services.
Passenger Experience Application Layer
Where are wireless entertainment solutions actively utilized?
Wireless in-flight entertainment solutions are deployed across narrow-body aircraft, wide-body aircraft, regional jets, business aircraft, commercial passenger cabins, premium cabins, economy cabins, and connected aircraft platforms to provide streaming entertainment, onboard shopping, flight information, passenger engagement services, and internet connectivity through passengers' personal devices.
Revenue Generation Layer
How is revenue generated?
Revenue is generated through wireless in-flight entertainment platforms, onboard connectivity hardware, satellite communication services, software licensing, cloud-based content management systems, content licensing agreements, aircraft retrofit and line-fit installations, maintenance services, technical support contracts, advertising platforms, premium internet access, and ancillary digital passenger services.
Delivered Customizations
This report has been delivered with the following In-depth customizations
Client Request
Customization Delivered
Value Adds
Wireless Connectivity Performance Optimization & Passenger Experience Assessment
Conducted detailed evaluation of onboard wireless connectivity across commercial, regional, and business aircraft, integrating satellite communication, wireless access points, content delivery platforms, and passenger analytics to optimize entertainment performance and connectivity reliability.
Improves passenger satisfaction, enhances connectivity reliability, optimizes onboard services, increases operational efficiency, and strengthens airline competitiveness.
BYOD Entertainment Platform Deployment & Cabin Digitalization Strategy
Assessed deployment of Bring Your Own Device (BYOD) entertainment platforms across narrow-body, wide-body, and regional aircraft, integrating cloud-based content management, wireless streaming technologies, and aircraft cabin networks to improve digital passenger engagement.
Enhances cabin digitalization, improves content accessibility, reduces operating costs, increases passenger engagement, and supports fleet modernization.
AI-Driven Content Personalization & Ancillary Revenue Optimization Strategy
Evaluated implementation of artificial intelligence-powered recommendation engines, passenger behavior analytics, personalized content delivery, targeted advertising platforms, and onboard retail integration to improve entertainment experiences and maximize ancillary revenue opportunities.
Enables personalized entertainment, improves ancillary revenues, enhances passenger engagement, supports data-driven decisions, and increases service differentiation.
Frequently Asked Questions About This Report
The global wireless in-flight entertainment market size was estimated at USD 2.9 billion in 2025 and is expected to reach USD 3.5 billion in 2026.
The global wireless in-flight entertainment market is expected to grow at a compound annual growth rate of 15.5% from 2026 to 2033 to reach USD 9.5 billion by 2033.
Some key players operating in the wireless in-flight entertainment market include Gogo LLC, BAE Systems PLC, Panasonic Avionics Corporation, Rockwell Collins, Inc., SITAOnAir, and Thales Group SA.
Key factors that are driving the wireless in-flight entertainment market growth include the increasing prominence of wireless connectivity and the growing adoption of the Bring Your Own Device (BYOD) trend among the general public and growing inclination toward the use of personal electronic device onboard has supplemented the surging adoption of wireless in-flight entertainment and connectivity services.
The Asia Pacific is the fastest-growing region with a CAGR from 2026 to 2033.
The retrofit segment dominated the market with a share of 84.3% in 2025.
The antennas segment accounted for the largest revenue share in 2025.
The narrow-body segment dominated with a 71.9% revenue share in 2025.
North America dominated the wireless in-flight entertainment market with a share of 33.4% in 2025.
About the Author(s)
Digital Media Research Team
Technology · Digital MediaThis report was authored by the digital media research team at Grand View Research - comprising two research analysts, one senior research analyst, and one industry expert - with specialized expertise in the digital media segment of the technology industry. All findings are based on proprietary technology databases, executive interviews, and regulatory analysis, subject to internal peer review prior to publication.
Last Updated:
Speak to Analyst

Customize this report to your needs - add regions, segments, or data points, with 20% free customization.
Or view our licence options:


ISO 9001:2015 & 27001:2022 Certified
We are GDPR and CCPA compliant! Your transaction & personal information is safe and secure. For more details, please read our privacy policy.


