
- Home
- »
- Healthcare IT
- »
-
Women’s Health App Market Size & Share Report 2026-2033GVR Report cover

Women’s Health App Market (2026 - 2033)
Size, Share & Trends Analysis Report By Type (Fitness & Nutrition, Menstrual Health, Pregnancy Tracking & Postpartum Care, Menopause, Disease Management), By Modality (Smartphone, Tablet), By Region, And Segment Forecasts
Market Size, 2025
$5.3BMarket Estimate, 2026
$6.3BMarket Forecast, 2033
$23.4BCAGR, 2026–2033
20.5%Women’s Health App Market Summary
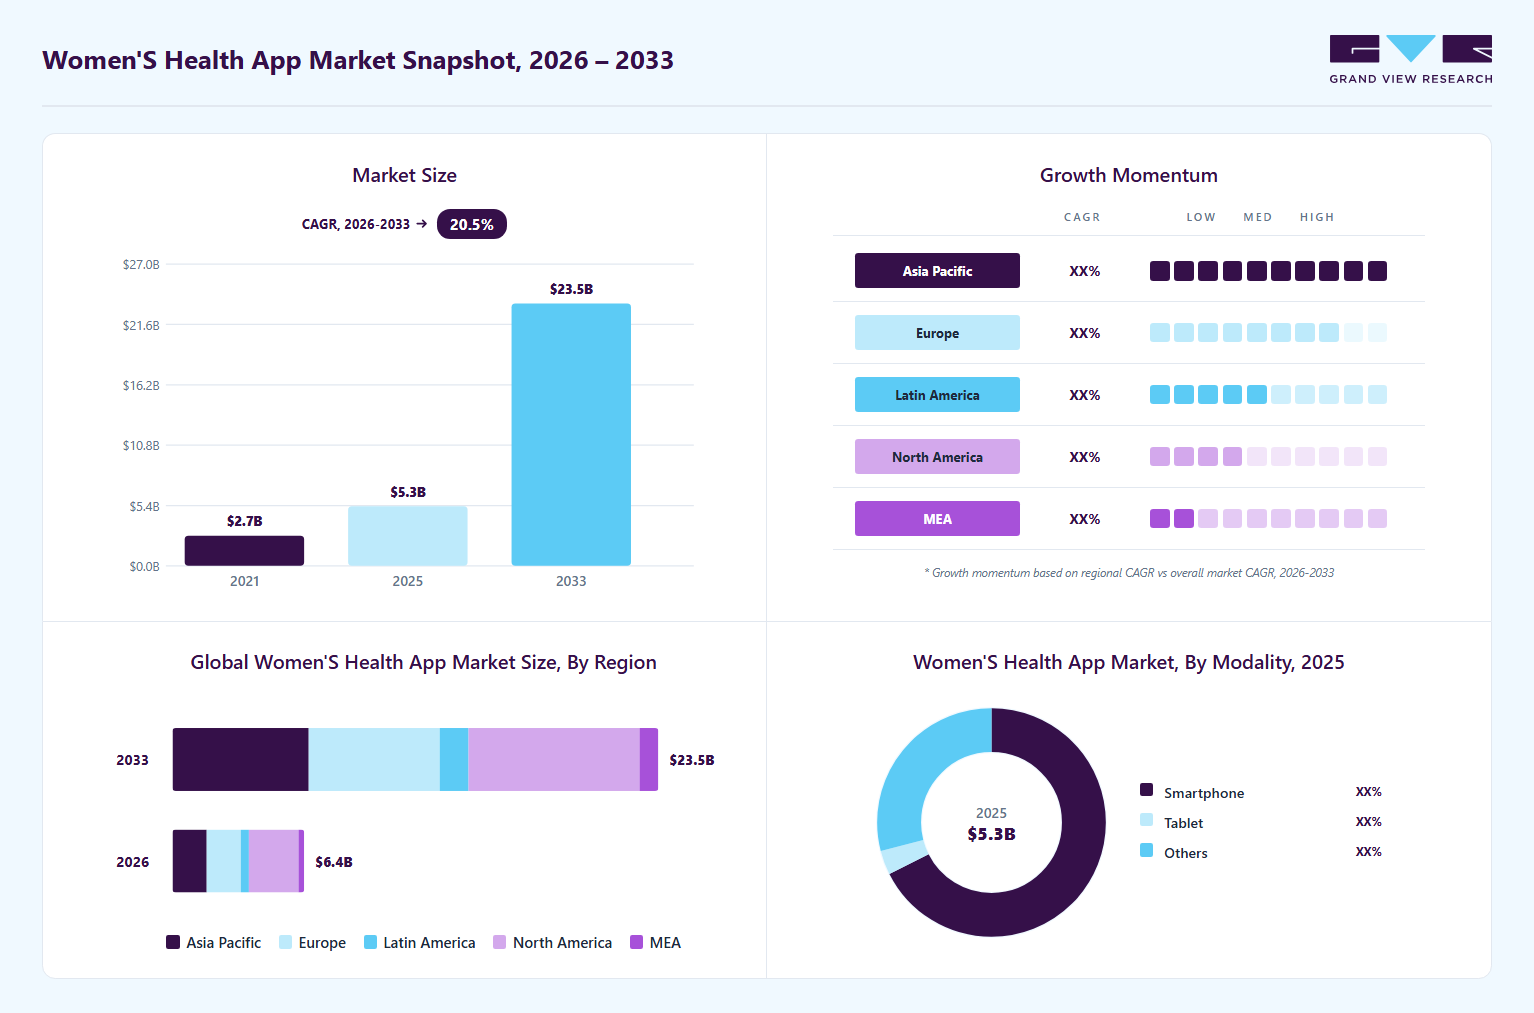
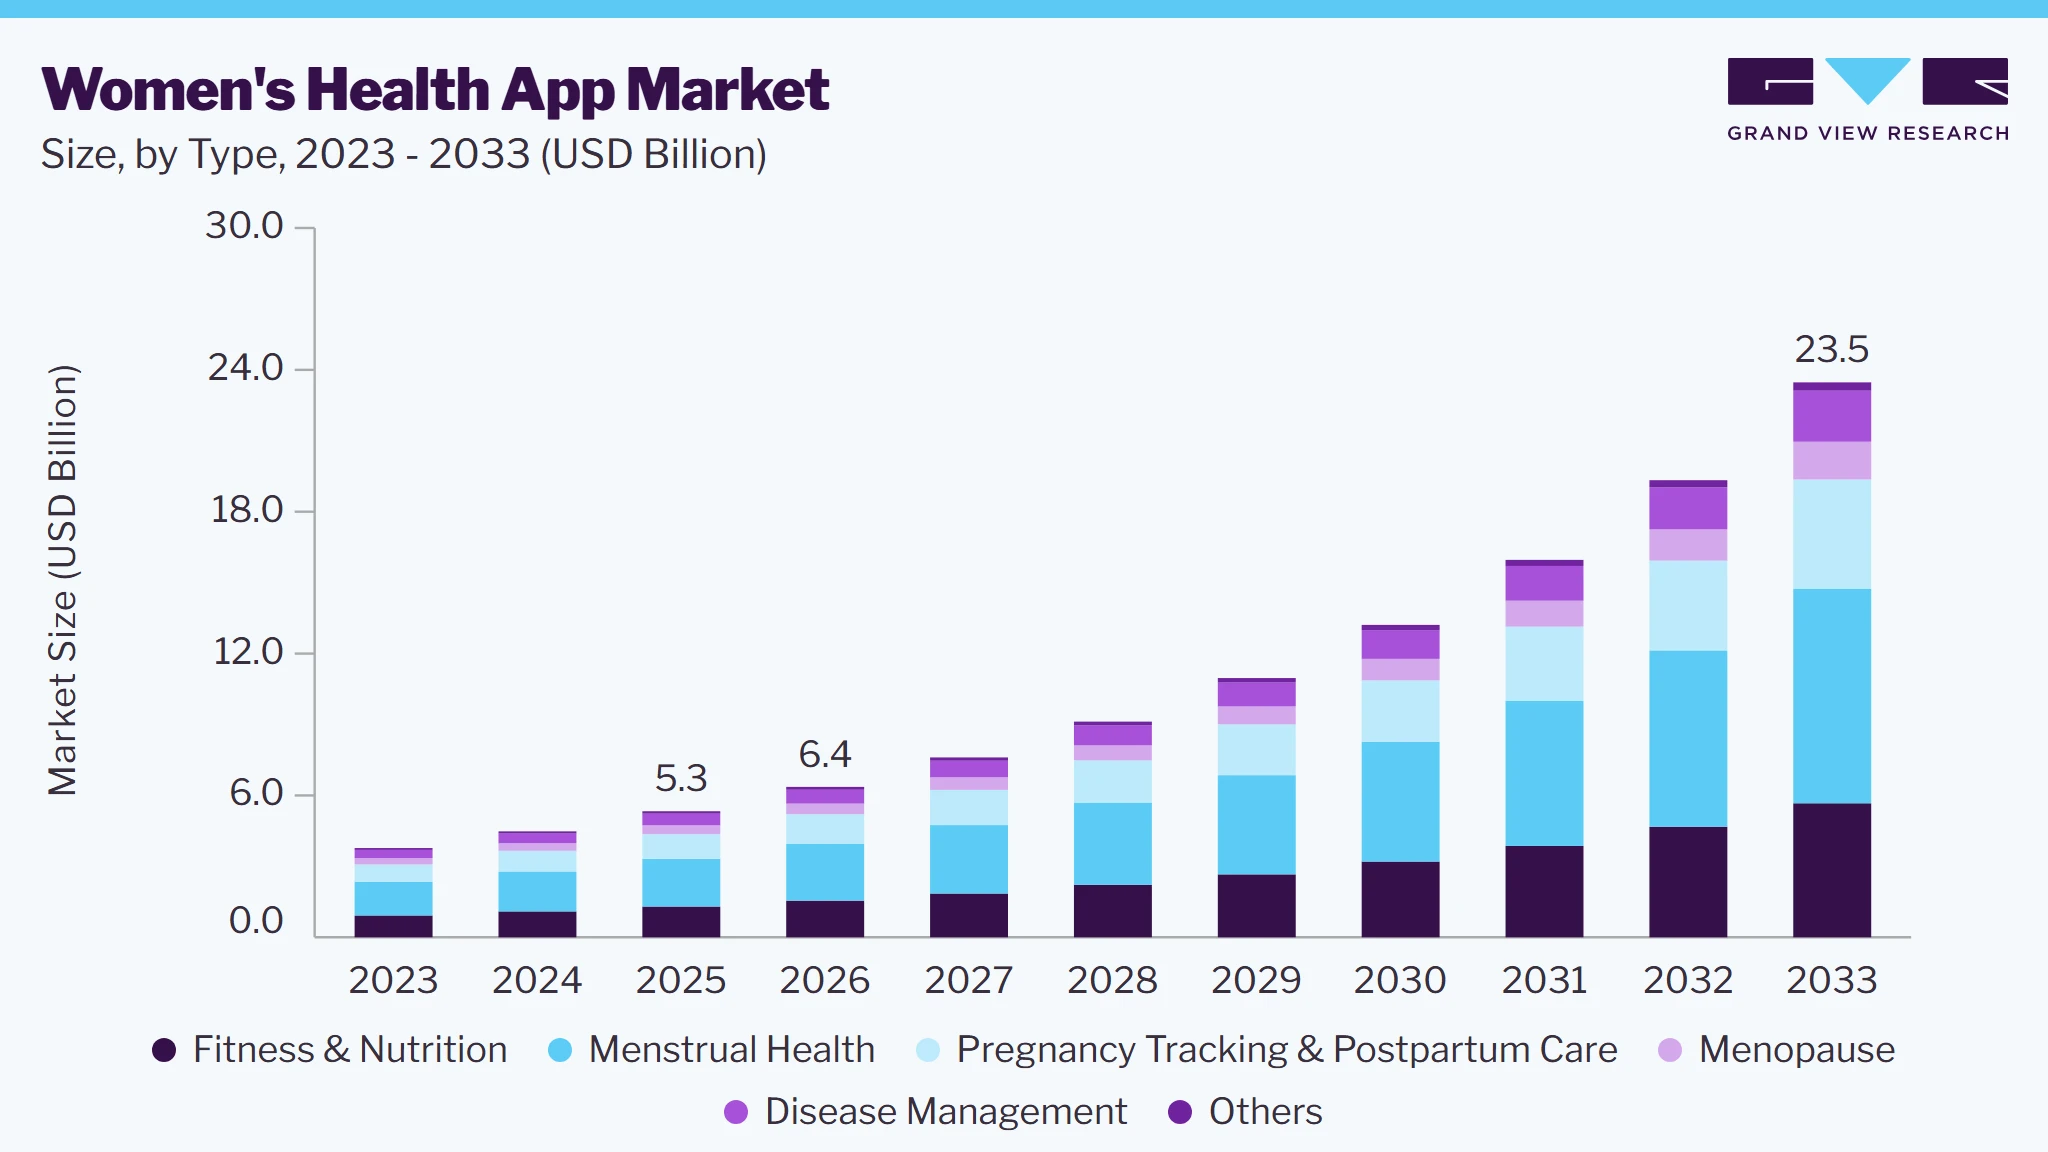
The global women’s health app market size was valued at USD 5.3 billion in 2025 and is projected to grow from USD 6.3 billion in 2026 to USD 23.4 billion by 2033, growing at a CAGR of 20.5% from 2026 to 2033. North America dominated the women’s health app market with the largest revenue share of 38.0% in 2025. Changes in diet, stress, and consumption of alcohol play significant roles in leading to hormonal disparities in women.
 Source: Grand View Research, IR Documents, Primary Interviews, Paid DatabasesTo learn more about this report,
 Download Free Sample Report
Key Market Trends & Insights
- By type: Menstrual health segment led the market with the largest revenue share of 37.8% in 2025 and is expected to grow at the fastest CAGR over the forecast period.
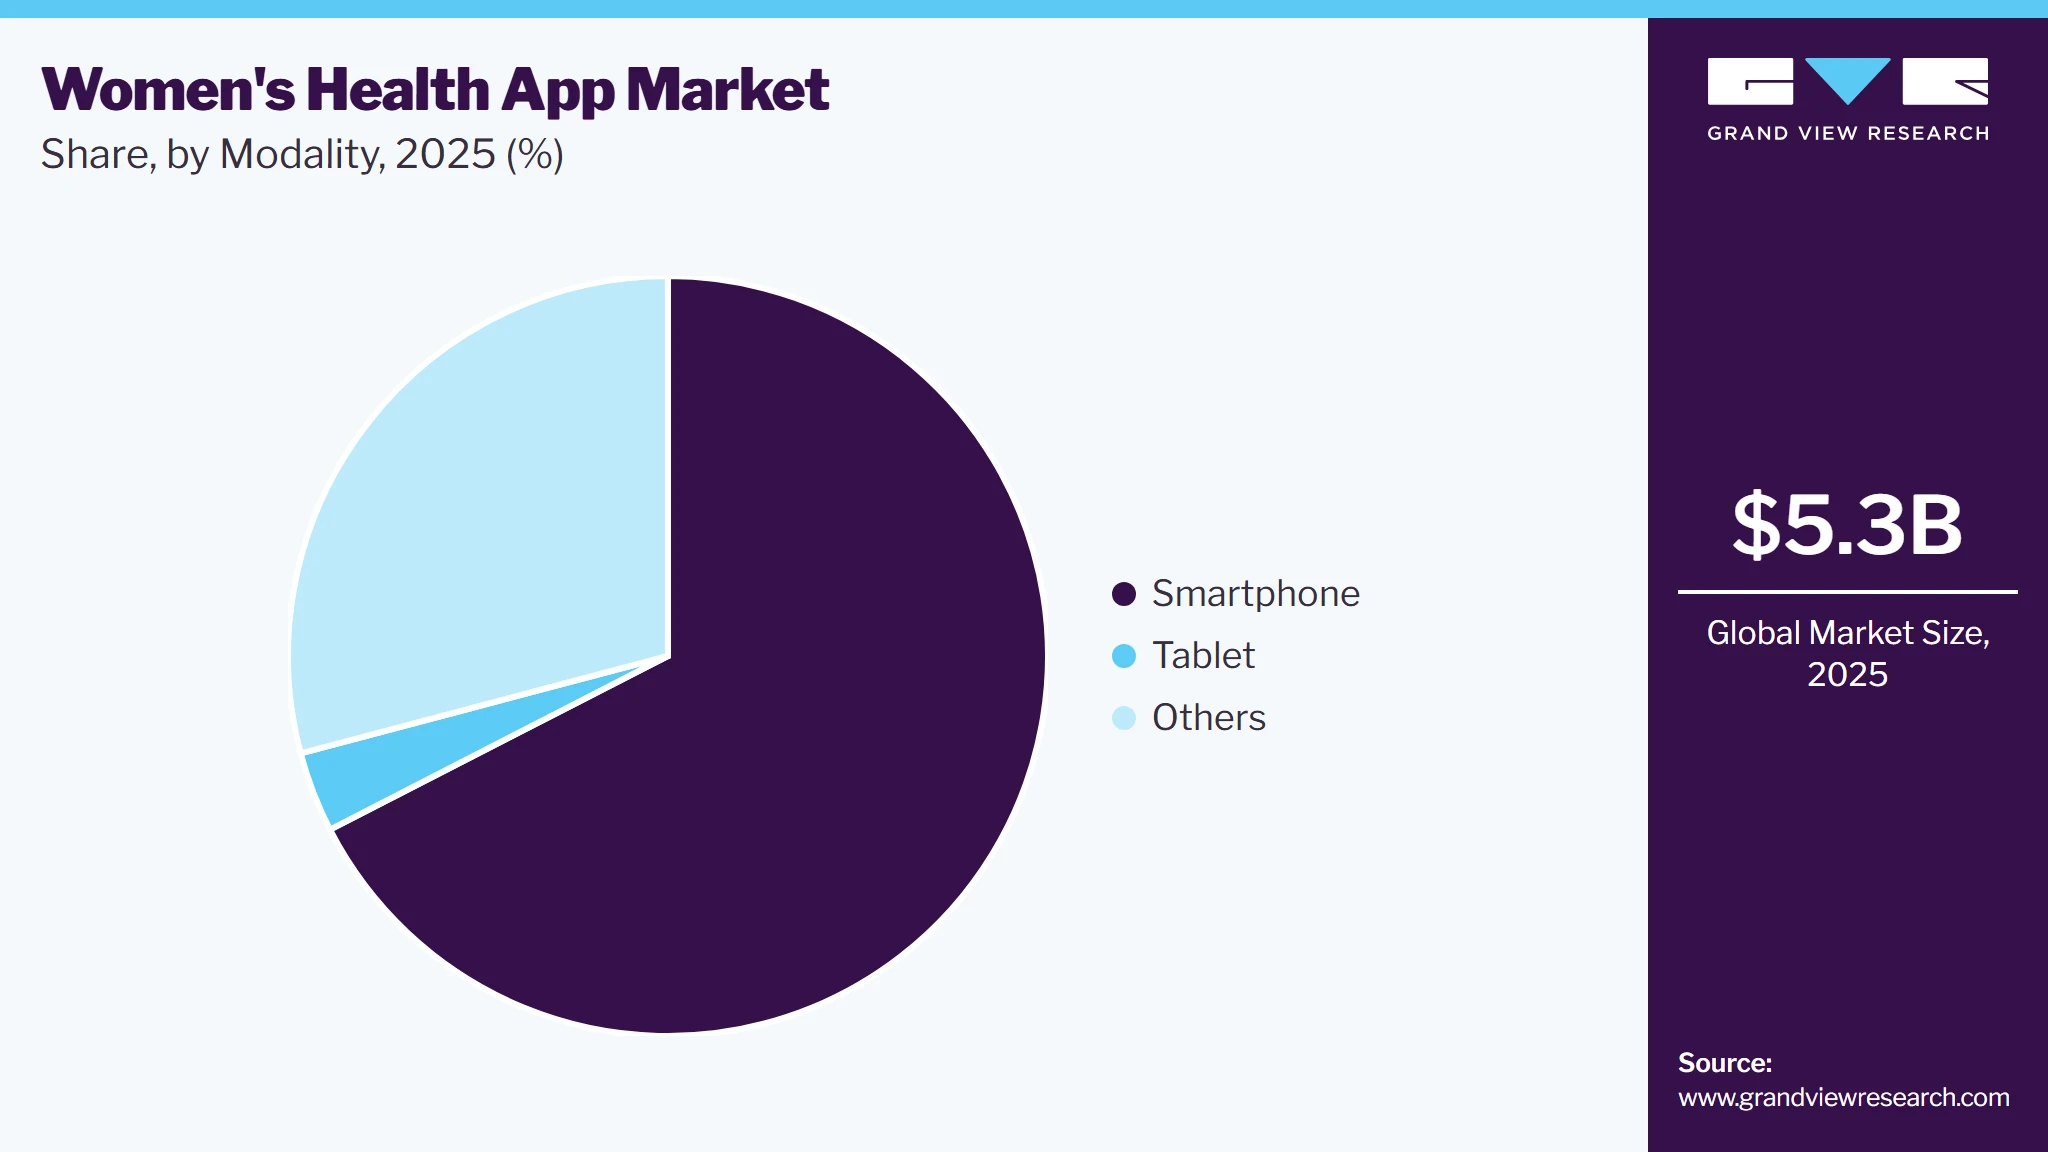
- By modality: Smartphone segment led the market with the largest revenue share of 68.6% in 2025.
Regional Highlights
- Largest regional market: North America (38.0% revenue share, 2025)
- By country: The U.S. held the largest market share in 2025
Market Size & Forecast
- Market size in 2025: USD 5.3 Billion
- Estimated market size in 2026: USD 6.3 Billion
- Projected market size by 2033: USD 23.4 Billion
- CAGR (2026-2033): 20.5%
Three ways to get this report
Buy it, customize it, or ask a question.Ask an Analyst
Analyst response in 1 business day
- AccessReport author, directly
- Reply timeWithin 1 working day
- No sales callDirect answer only
- FormatEmail reply
- CostFree, no cost
Get the Full Report
What the study covers
- FormatsPDF · Excel · Dashboard
- Timeline2026–2033 annual, 2025 base
- Coverage20+ countries, 5 regions
- Companies10+ key players profiled
Customize the Report
20% free customization
- IncludeCountries, segments, points
- TailorTo your product definition
- ExtendDeeper competitor detail
- OrA fully bespoke study
- Turnaround5–10 working days
These hormonal imbalances are susceptible to various diseases post-menopause, including osteoarthritis (OA), anemia, obesity, abnormal menstrual cycles, depression, and fibromyalgia. As the aging population and incidence of obesity increase, the prevalence of OA is expected to increase. According to the World Health Organization, in July 2023, approximately 73% of individuals diagnosed with osteoarthritis are over the age of 55, and around 60% of these patients are women.Anemia continues to affect millions of women around the world. According to the WHO, the prevalence of anemia was 29.9% among females of reproductive age, which is equivalent to nearly half a billion females aged 15-49 years, In December 2023, Hearst UK (The National Magazine Company Ltd.) launched an app for Women’s Health UK, enhancing its Women’s Health Collective membership. This comprehensive app offers exclusive access to expert training plans, wellness advice, and the latest health news, aiming to help women achieve their best health and fitness levels. It features content from leading global experts and top UK writers.
 To learn more about this report, Download Free Sample Report
The expected rise in arthritis among women is anticipated to stimulate the market. Developing regular healthy habits and altering daily routines can mitigate the effects of arthritis. In October 2022, the DigiPrevent project, aimed at developing digital tools to prevent rheumatoid arthritis, received funding of USD 3.43 million. This funding, primarily provided by EIT Health, a network created by the European Institute of Innovation and Technology, supports the efforts of researchers at Karolinska Institutet and their partners.
Increasing investments from both government and private sectors are facilitating the uptake of software aimed at enhancing women's welfare. For instance, in January 2024, the World Economic Forum reported that the Global Alliance for Women’s Health had received support from 42 organizations, with a total commitment of USD 55 million to improve global women’s health outcomes.
Market Dynamics
Women’s health apps are gaining traction as they offer personalized features such as menstrual cycle tracking, nutrition monitoring, fitness management, medication reminders, mental wellness support, sleep tracking, and symptom analysis. These applications enable users to better manage their overall health through real-time monitoring, behavioral insights, and data-driven recommendations. The growing focus on preventive healthcare, coupled with increasing awareness regarding women-centric wellness management, is expected to continue driving growth in the women’s health apps market.
The increasing prevalence of hormonal imbalances, lifestyle-related disorders, and chronic musculoskeletal conditions among women is significantly driving demand for women’s health applications. Factors such as unhealthy dietary habits, sedentary lifestyles, chronic stress, obesity, smoking, and alcohol consumption have contributed to rising incidences of conditions including menstrual disorders, polycystic ovary syndrome (PCOS), osteoporosis, obesity, depression, fibromyalgia, and osteoarthritis (OA). Women, particularly during and after menopause, are more susceptible to these conditions due to hormonal and metabolic changes associated with aging.
The growing burden of osteoarthritis and related chronic conditions further supports the adoption of digital health solutions. According to the World Health Organization (WHO), approximately 528 million people globally were living with osteoarthritis in 2019, with women accounting for nearly 60.0% of cases. Additionally, the increasing aging female population and rising obesity prevalence are expected to accelerate disease incidence over the coming years. As a result, women are increasingly turning to mobile health applications for preventive care, symptom tracking, and chronic disease management.
Concerns regarding data privacy, cybersecurity, and regulatory compliance remain major restraints for the women’s health apps market. Women’s health applications frequently collect highly sensitive personal information, including menstrual cycles, fertility data, pregnancy records, hormonal health metrics, sexual wellness information, and mental health data. Growing consumer awareness regarding misuse of health data, combined with tightening global data protection regulations such as GDPR in Europe and HIPAA in the U.S., has increased scrutiny on digital health platforms. In recent years, concerns surrounding reproductive health data privacy have intensified following changes in abortion regulations in several countries, leading users to question how their personal health information is stored and shared. According to recent cybersecurity studies, healthcare continues to be one of the most targeted sectors for data breaches globally, creating hesitation among users regarding adoption of digital health platforms. These concerns may limit consumer trust and slow the adoption of women’s health applications, particularly in regions with limited digital health regulations and cybersecurity infrastructure.
The integration of artificial intelligence (AI), predictive analytics, and wearable device connectivity is creating substantial growth opportunities in the women’s health apps market. Consumers are increasingly seeking personalized and preventive healthcare solutions that provide real-time insights into fertility, pregnancy, hormonal balance, menopause management, mental wellness, and chronic disease monitoring. AI-enabled women’s health applications can analyze user behavior, biometric data, sleep patterns, nutrition, and menstrual health trends to deliver customized recommendations and early risk assessments. The rapid expansion of digital health adoption further supports this opportunity. According to industry trends, global digital health funding and femtech investments continue to grow steadily, driven by increasing awareness of women-specific healthcare needs and rising smartphone penetration. Additionally, growing adoption of wearable devices such as smartwatches and fitness trackers is enhancing app functionality through continuous health monitoring and integration with telehealth services. These advancements are expected to accelerate user engagement and expand the role of women’s health apps in preventive and personalized healthcare management.
Market Concentration & Characteristics
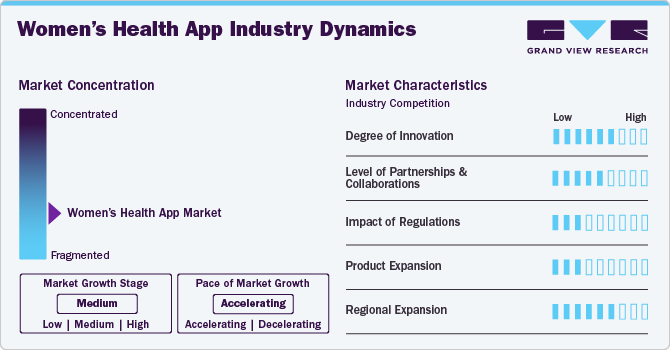
The degree of innovation is high in the market due to features such as menstrual tracking, fertility monitoring, pregnancy guidance, and mental health support, enhanced by AI and machine learning. These apps focus on personalized care and remote monitoring, reflecting a commitment to improving global women's health outcomes.
To improve their standing in the market, various firms engage in mergers and acquisitions. These endeavors increase their market knowledge, expand their range of products, and improve their capabilities. In May 2024, Keleya and Kinderheldin merged as Keleya and integrated their services, including introducing AI-driven 24/7 midwife support. The merger secures a significant market presence with partnerships across 65 German health insurers, covering 65% of the insured population.
 To learn more about this report, Download Free Sample Report
Regulations influence aspects such as data privacy, security, accuracy of information, and overall quality of healthcare services provided through these apps. Regulatory frameworks such as GDPR in Europe and HIPAA in the U.S. set standards for protecting user data and ensuring compliance with healthcare regulations. These regulations enhance consumer trust and drive innovation by encouraging app developers to meet stringent requirements.
In the global market, the presence of product substitutes is medium. While various women’s health apps that cater to specific needs, such as period tracking, pregnancy monitoring, and overall wellness, are available, the level of direct substitutes that offer identical features and functionalities may not be as high as in some other industries.
The increasing awareness about women’s health and the growing demand for personalized healthcare solutions led to a surge in the adoption of women’s health apps worldwide. Companies operating in this market are actively expanding their presence in different regions to cater to the diverse needs of women across the globe. This expansion is driven by factors such as technological advancements, rising investments in digital health solutions, and the emphasis on preventive healthcare measures.
Analyst Perspective
The women's health app market sits at a rare intersection of structural tailwinds few digital health verticals can match - a clinically underserved female population, a rapidly expanding menopausal cohort, and a B2B monetisation channel through insurer and employer contracts that is largely insulated from consumer price sensitivity. The central competitive moat, however, will belong to the player that consolidates condition coverage across menstrual health, pregnancy, menopause, and disease management into a single longitudinal record - converting episodic app usage into a durable, lifelong health relationship that commands the premium the underlying epidemiology clearly justifies.
Type Insights
Based on type, the menstrual health segment led the market with the largest revenue share of 37.8% in 2025 and is expected to grow at the fastest CAGR over the forecast period. The growth is attributed to an increasing awareness among women about the importance of hygiene during menstrual periods. The widespread use of apps for tracking menstrual cycles, combined with the introduction of new products and features by leading companies, is contributing to the expansion of this market segment. In October 2023, Titan Smart Wearables partnered with Elda to innovate in women's healthcare, marking a step towards creating an integrated wellness ecosystem focused on enriching user experiences and empowering health management.
The pregnancy tracking and postpartum care segment is anticipated to grow at a considerable CAGR over the forecast period. The surge in the use of pregnancy-related applications designed to support the health of both the mother and the baby is driving the growth of this segment. In October 2023, the local hospital trust and the University of Leicester launched the Janam app, a free pregnancy guide for South Asian women in Leicestershire, available in six languages. Featuring visual aids such as diagrams and videos, this app aims to empower users with the knowledge to make informed choices about pregnancy, childbirth, and postnatal care.
Modality Insights
Based on modality, the smartphone segment led the market with the largest revenue share of 68.6% in 2025. The smartphone market is growing due to increasing awareness of women's health, demand for accessible healthcare, and the convenience of tracking health metrics. The widespread use of smartphones, advancements in technology such as AI and wearables integration, and the push from COVID-19 towards digital healthcare have all significantly contributed to the popularity and functionality of these apps. In May 2023, Bonatra Healthcare Pvt. Limited acquired women's health and wellness firm MyAva, to widen its holistic healthcare solutions and offer a comprehensive platform for managing chronic conditions. This move is part of Bonatra's plan to launch new IoMT devices, like a smart ring, to enhance its integration of medical and data science with technology.
 To learn more about this report, Download Free Sample Report
Other segment is expected to grow at the fastest CAGR over the forecast period. The market is growing with innovation beyond smartphones and tablets, and it includes wearable devices, virtual reality (VR) technology, and telemedicine platforms emerging as key drivers. Wearables such as smartwatches offer convenient health tracking, including menstrual cycles and fertility, while VR technology provides immersive ways to manage pain and improve mental health. Telemedicine platforms enable remote consultations for prenatal care and other health concerns, offering accessible healthcare solutions for women.
Regional Insights
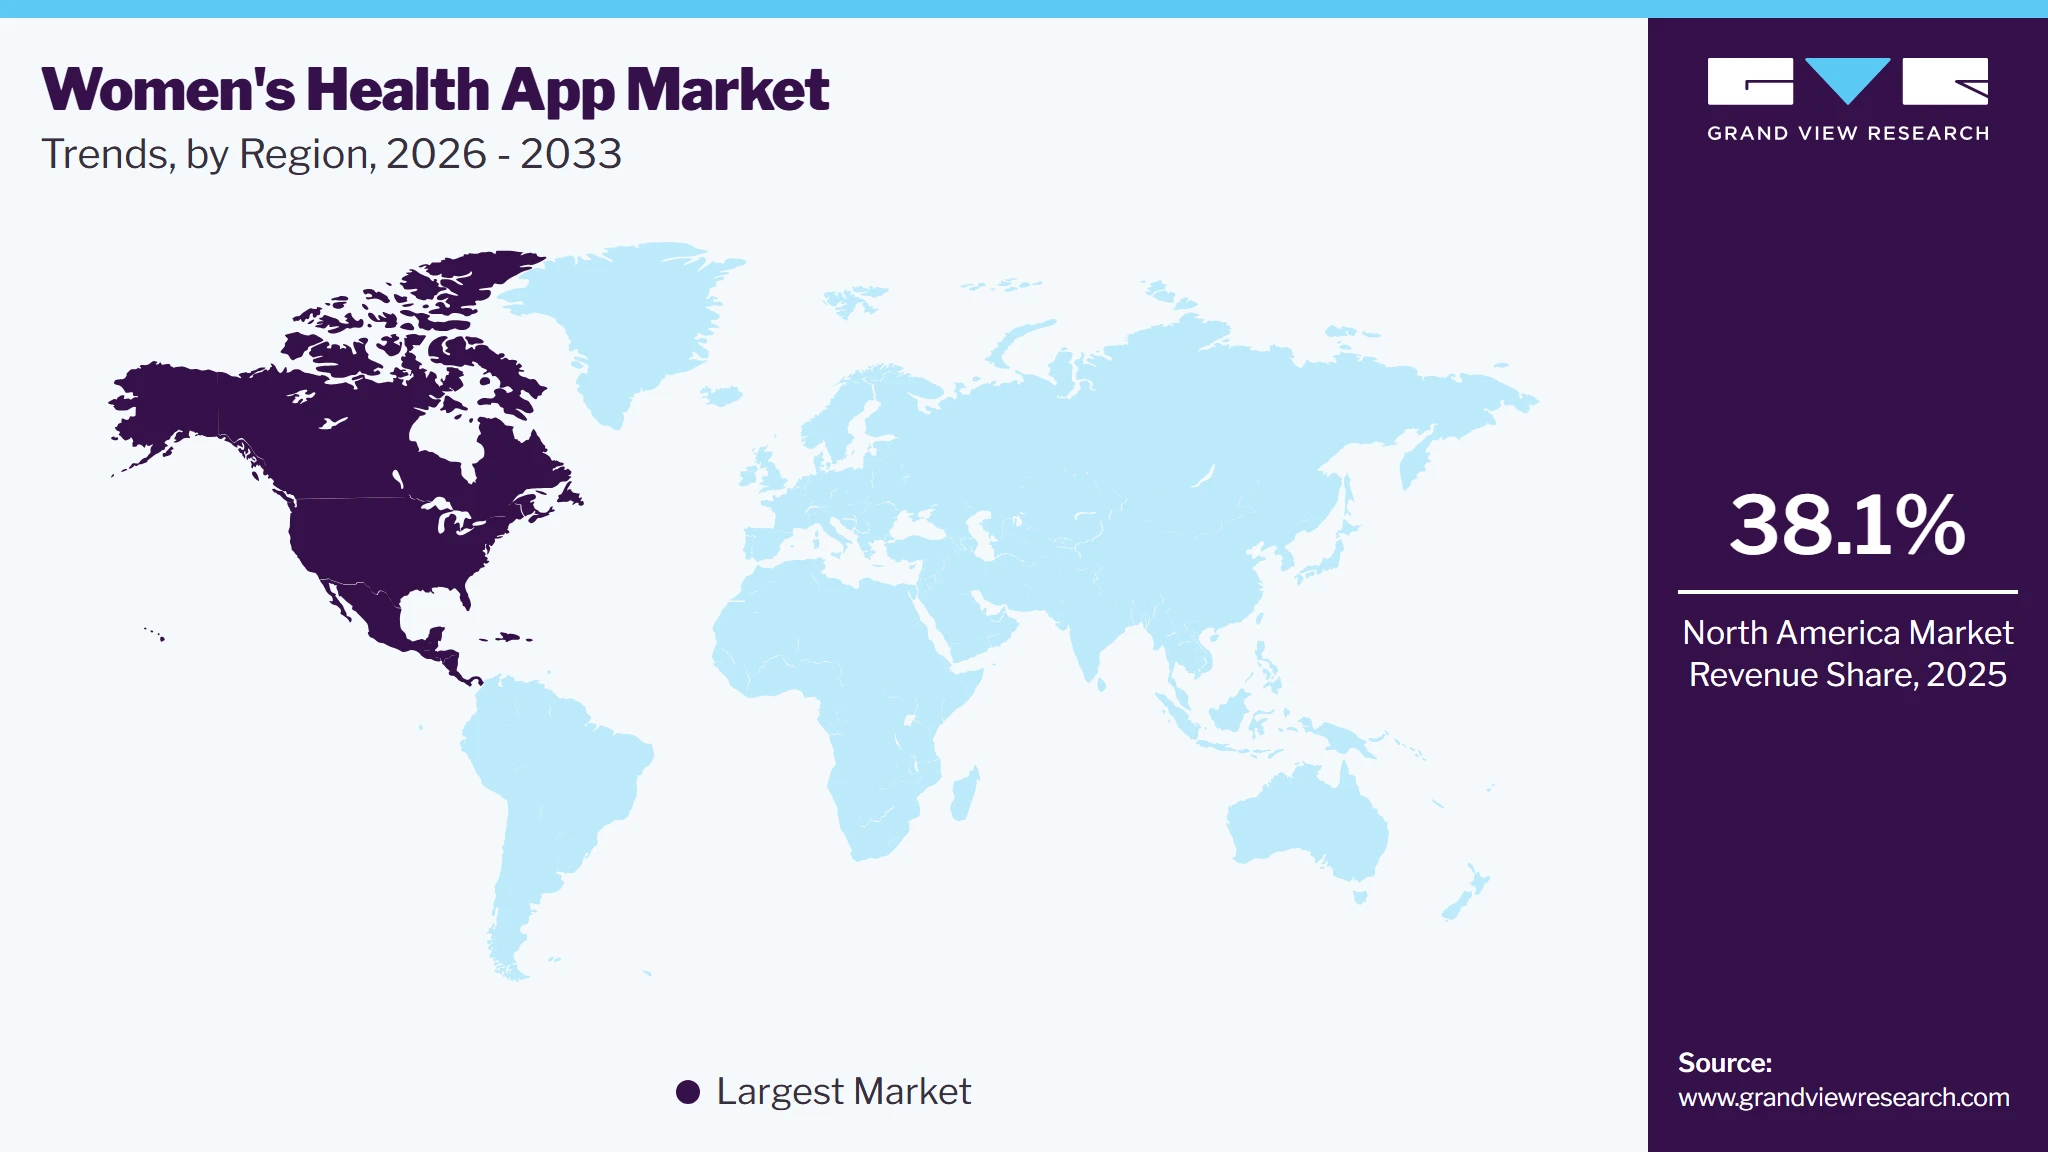
North America dominated the women’s health app market with the largest revenue share of 38.0% in 2025. This is due to the increasing adoption of smartphones and rising government interest in reducing healthcare costs. In addition, the high adoption of technologically advanced products and regulatory reforms for approval and usage of mobile-based applications are contributing to the growth of the market in the region.
 To learn more about this report, Download Free Sample Report
U.S. Women’s Health App Market Trends
The women’s health app market in the U.S. held the largest share in the North America region in 2025. Several key factors are driving the market growth in U.S. The increasing awareness and focus on women’s health and wellness have led to a growing demand for digital solutions that cater specifically to women’s needs. The rise of wearable technology and smartphones made it easier for women to track their health metrics, menstrual cycles, fertility, pregnancy, and overall well-being through apps. In addition, the convenience and accessibility of these apps have made them popular among women of all ages. In July 2022, Lisa Health launched Midday, an innovative app designed to assist women through menopause. By integrating AI, sensor tech, and digital therapeutics, Midday offers personalized support highlighting physical and emotional changes during menopause. This app, developed in collaboration with Mayo Clinic, merges Lisa Health's technology with expert medical advice for comprehensive menopause symptom management.
The Canada women’s health app market is expected to grow at the fastest CAGR over the forecast period. The market growth in Canada is driven by several factors. An increased awareness of women's health issues, coupled with the widespread use of smartphones and digital technologies among Canadian women, is fostering a demand for health-focused apps. The COVID-19 pandemic further accelerated this trend by boosting the need for telemedicine and virtual healthcare services. Governmental support for digital health solutions and investments in healthcare technology also play vital roles. Recent data shows a surge in the use of women’s health apps, evidenced by rising download numbers and user engagement across various age demographics, underscoring the critical role these digital tools play in supporting women's health.
Europe Women’s Health App Market Trends
The women’s health app market in Europe is expected to grow at the fastest CAGR over the forecast period, owing to the increasing government investment in IT infrastructure and the growing number of digital startups in the region. Increasing awareness about reproductive health, rising prevalence of OA, and improving internet access are propelling the market in Europe.
The UK women's health app market is governed by GDPR, which ensures the protection of sensitive user data, and the NHS Digital Health Technology Standard that mandates quality and safety standards. These regulations are key drivers in the development and innovation of such apps. Recent trends indicate a significant increase in the usage of women's health apps for tracking menstrual cycles, fertility, pregnancy, and overall well-being among UK females.
The women’s health app market in Germany is growing significantly, driven by strict data privacy laws such as the Federal Data Protection Act and GDPR, which build user trust by ensuring the protection of sensitive health information. In addition, public healthcare institutions actively promote these digital solutions, and the German Federal Joint Committee recognized some apps as eligible for reimbursement, providing a financial incentive for use. Cultural factors contribute, with German women showing a higher preference for using digital tools for health management compared to their European peers. This combination of regulatory support, financial incentives, and cultural openness fostered innovation and adoption in the sector.
The Spain women’s health app market is shaped by specific regulations and trends. Key among these is the data protection laws such as the GDPR, which are critical for apps handling women's sensitive health information. The country is experiencing an increased focus on women's health, fueling the demand for digital health solutions. As awareness around health and wellness grows, there's a notable increase in the development and usage of apps designed for women's health needs, ranging from period tracking to pregnancy support. Recent data indicates a growing reliance on these apps among Spanish women to manage their health care.
Asia Pacific Women’s Health App Market Trends
The women’s health app market in Asia-Pacific is expected to grow at a significant CAGR over the forecast period, due to the high number of smartphone users in China and India, increasing internet penetration, and growing demand for effective healthcare technologies. In addition, increasing government focus on women’s wellness is favoring the market growth. For instance,the Indian government launched the Swasthya Samiksha app that enables the members of the parliament to track maternal and reproductive health data and indicators of their respective constituencies.
The Japan women’s health app market is anticipated to grow at the fastest CAGR over the forecast period. The healthcare sector is strictly controlled, which applies to the market for women's health applications. The Japanese government enforces tight regulations to guarantee the safety and effectiveness of health-oriented technologies, such as apps focusing on women's health. These apps typically undergo extensive evaluation and must gain approval prior to their market release. Moreover, Japan has rigid data privacy regulations, particularly concerning sensitive health data, which additionally influence the creation and functioning of women’s health applications within the nation.
Latin America Women’s Health App Market Trends
The women’s health app market in Latin America is expected to grow at a rapid CAGR during the forecast period. In Latin America, the market is influenced by specific regulations related to data privacy and protection. Countries such as Brazil, Mexico, and Argentina implemented data protection laws that impact how health apps collect, store, and use the personal health information of users. Compliance with these regulations is crucial for companies operating in this sector to ensure the security and confidentiality of sensitive data. In addition, some countries have specific regulations governing telemedicine services, which often intersect with women’s health apps that offer virtual consultations or remote monitoring feature
The Brazil women’s health app market is strictly regulated under the Brazilian General Data Protection Law (LGPD), which mandates strict adherence to data privacy and security practices, essentially for sensitive health information. This compliance is vital for businesses in the sector to maintain user trust. In addition, the country's cultural focus on health, beauty, and wellness significantly influences the demand for digital health solutions tailored to women's needs, from menstrual tracking to mental health support.
MEA Women’s Health App Market Trends
The women’s health app market in MEA was identified as a lucrative region in this industry. In the MEA region, regulatory frameworks are pivotal in driving the market growth. Initiatives by the Saudi Ministry of Health and the Egyptian government aim to boost the adoption of e-health and telemedicine services. Cultural factors, notably gender segregation in countries such as Iran and Saudi Arabia, shape demand for women-centric health apps that offer features such as women-only communities and private consultations with female doctors. In addition, the increasing health awareness among women in the region, acknowledging the role of technology in health management, is fueling the market. Women are leveraging these apps for a range of needs, from tracking menstrual cycles to managing pregnancies and monitoring chronic conditions, enhancing the scope of virtual healthcare.
The Saudi Arabia women’s health app market is anticipated to grow at the fastest CAGR during the forecast period. Saudi society's conservative nature plays a significant role in shaping the market. Due to cultural restrictions on gender interactions, promoting and accessing women's health apps in the country may be challenging. In addition, regulations related to women's data and security are stringent in Saudi Arabia, impacting how women's health apps collect, store, and utilize user data. In April 2024, recent data disclosed by the Communications, Space, and Technology Commission (CST) highlighted remarkable levels of internet accessibility in Saudi Arabia, with 99% of the population now online. The Saudi Internet Report 2023 indicates that each person, on average, uses 44 GB of mobile data every month, showcasing the swift progress in the country's digital infrastructure.
Key Women’s Health App Company Insights
The market is highly fragmented with presence of various software companies. Collaborations for software development, incorporation of latest technologies, new product launch, and regional expansion in emerging markets are some of the key strategies used by companies to gain competitive edge. For instance,in October 2023, Flo introduced Flo for Partners, a feature that helps partners better understand their significant others' menstrual and reproductive health. This update includes push notifications, period and pregnancy information, symptom explanations, supportive tips, and quizzes, enabling partners to offer more informed support during their significant others' cycles.
Key Women’s Health App Companies
The following key companies have been profiled for this study on the women’s health app market.
-
Flo Health, Inc.
-
Clue
-
Glow, Inc.
-
Withings
-
Google, Inc
-
Fitbit, Inc.
-
Natural Cycles USA Corp
-
Apple Inc.
-
Wildflower Health
-
HelloBaby, Inc.
-
Ovia Health
Competitive Benchmarking
Category
Operating Strategies
Competitive Edge
Weakness
Established Players (Apple Inc., Google, Inc, Fitbit, Inc., Withings)
- Expand integrated digital ecosystems through partnerships with healthcare providers, insurers, and wearable device companies
- Invest in AI-driven personalization, subscription models, and multilingual platform expansion
- Strong brand credibility, large user base, and high customer retention
- Advanced data analytics capabilities with diversified women’s health service portfolios
- Higher operational and compliance costs due to global regulatory requirements Slower innovation cycles and limited agility in addressing niche women’s health needs
Emerging Players (Flo Health, Inc., Clue, Glow, Inc., Wildflower Health)
- Focus on niche segments such as fertility, menopause, mental wellness, or PCOS management
- Leverage social media marketing, community-led engagement, and freemium pricing strategies
- Faster product innovation and ability to address underserved women’s health categories
- Agile technology integration with personalized and user-centric experiences
- Limited financial resources and challenges in scaling user acquisition profitably
- Lower consumer trust and weaker clinical validation compared to established platforms
Recent Developments
-
In January 2024, Femtech Canada announced its network focused to empowering tech firms focused on women’s health, having gathered over 120 Canadian startups and partners. After more than two years in development, the initiative supports health solutions for women, girls, non-binary, trans individuals, and those assigned female at birth.
-
In February 2024, Rosy Wellness expanded its platform to address a wider array of women's health issues for individuals aged 17 to 91. Under the guidance of founder and CEO Lyndsey Harper, Rosy attracted USD 5 million in funding from supporters such as True Wealth Ventures and Portfolia. Notably founded by a physician, the platform introduced new features such as ‘Quickies’ to broaden its reach and offerings in women's health.
-
In January 2023, Mamahood, a femtech app, was launched to support women in the Middle East and North Africa through fertility, pregnancy, and motherhood. It offers health-tracking tools, educational content, and a community platform for support. A key feature is its on-demand live chat, which allows 24/7 access to healthcare advisors for immediate, professional guidance.
-
In March 2024, Dialogue Health Therapeutics, a Canadian virtual health company, enhanced its services by acquiring assets from Koble Care, a digital women's health platform. This acquisition comprises of all of Koble's content, software, and intellectual property. Koble's specialized content will be incorporated into Dialogue’s Integrated Health Platform (IHP), and Koble’s CEO, Swati Matta, will join the Dialogue team as the head of women’s health.
Women’s Health App Market Report Scope
Report Attribute
Details
Market size value in 2025
USD 5.3 billion
Market size value in 2026
USD 6.3 billion
Revenue forecast in 2033
USD 23.4 billion
Growth rate
CAGR of 20.5% from 2026 to 2033
Base year for estimation
2025
Historical data
2021 - 2024
Forecast period
2026 - 2033
Quantitative units
Revenue in USD million/billion and CAGR from 2026 to 2033
Report coverage
Revenue forecast, company ranking, competitive landscape, growth factors, and trends
Segments covered
Type, modality, region
Regional scope
North America; Europe; Asia Pacific; Latin America; MEA
Country scope
U.S.; Canada; Mexico; Germany; UK; France; Italy; Spain; Norway; Denmark; Sweden; Russia; Iceland; Finland; China; Japan; India; South Korea; Australia; Thailand; Singapore; Brazil; Argentina; Saudi Arabia; South Africa; UAE; Kuwait; Israel
Key companies profiled
Flo Health, Inc.; Clue; Apple Inc.; Glow, Inc.; Withings; Google, Inc.; Natural Cycles USA Corp; Wildflower Health; HelloBaby, Inc.; Ovia Health
Customization scope
Free report customization (equivalent up to 8 analysts' working days) with purchase. Addition or alteration to country, regional & segment scope.
Pricing and purchase options
Avail customized purchase options to meet your exact research needs. Explore purchase options
Global Women’s Health App Market Report Segmentation
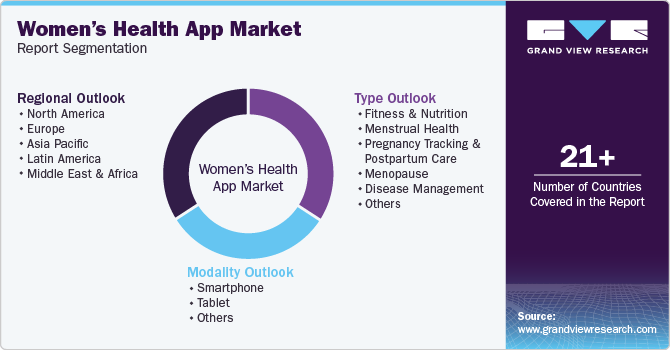
This report forecasts revenue growth at global, regional, and country levels and provides an analysis of the latest industry trends in each of the sub-segments from 2021 to 2033. For this study, Grand View Research has segmented the global women’s health app market report based on:
 To learn more about this report, Download Free Sample Report
-
Type Outlook (Revenue, USD Million, 2021 - 2033)
-
Fitness & Nutrition
-
Menstrual Health
-
Pregnancy Tracking & Postpartum Care
-
Menopause
-
Disease Management
-
Others
-
-
Modality Outlook (Revenue, USD Million, 2021 - 2033)
-
Smartphone
-
Tablet
-
Others
-
-
Regional Outlook (Revenue, USD Million, 2021 - 2033)
-
North America
-
U.S.
-
Canada
-
Mexico
-
-
Europe
-
UK
-
Germany
-
Spain
-
France
-
Italy
-
Norway
-
Denmark
-
Sweden
-
Russia
-
Iceland
-
Finland
-
-
Asia Pacific
-
China
-
Japan
-
India
-
South Korea
-
Thailand
-
Australia
-
Singapore
-
-
Latin America
-
Brazil
-
Argentina
-
-
Middle East & Africa
-
South Africa
-
Saudi Arabia
-
UAE
-
Kuwait
-
Israel
-
-
Research Methodology
Segment Definition
Segment - Type
Revenue capture definition
Fitness & Nutrition
Revenue is generated through freemium-to-premium subscription conversions and in-app purchases for personalised workout plans, macro/calorie tracking, and dietary guidance designed around women's hormonal and physiological cycles. B2B employer wellness contracts represent a growing secondary channel.
Menstrual Health
As the largest type segment, revenue is primarily captured through tiered subscription models (free cycle-tracking with premium fertility/hormone insights) and, increasingly, through payer/insurer reimbursement partnerships that cover period and ovulation monitoring for reproductive planning.
Pregnancy Tracking & Postpartum Care
Revenue flows from one-time purchases and subscription upgrades for apps supporting fetal development monitoring, birth planning, and postpartum recovery; a rising share is captured via hospital system partnerships and maternity benefit programmes offered by insurers and employers.
Menopause
Revenue is earned through direct-to-consumer premium subscriptions and digital therapeutics licensing agreements with healthcare providers, covering symptom tracking (hot flashes, mood, sleep) and AI-driven personalised guidance - with reimbursement recognition emerging in markets like Germany.
Disease Management
Revenue is predominantly B2B, captured through enterprise contracts with insurers, employers, and hospital networks for apps managing women-specific chronic conditions such as PCOS, endometriosis, osteoarthritis, and anemia, often combined with remote monitoring and care-coordination modules.
Others
This residual segment captures revenue from mental wellness, sexual health, pelvic floor therapy, and general women's preventive care apps that do not fit the primary classifications, monetised through a mix of subscriptions, one-time purchases, and community membership fees.
Segment - Modality
Revenue capture definition
Smartphone
The dominant revenue channel, capturing income through Apple App Store and Google Play subscription billing, in-app purchase flows, and freemium conversion funnels on iOS and Android; COVID-19-accelerated digital adoption and IoMT device integrations (smart rings, CGMs) have further deepened smartphone-led monetisation.
Tablet
Revenue is generated through the same subscription and premium-tier models as smartphones but via tablet-optimised app experiences that offer richer data visualisations, expanded health dashboards, and enhanced content consumption - particularly relevant for pregnancy and disease management use cases.
Others
This segment - comprising smartwatches, smart rings, VR platforms, and telemedicine systems - is the fastest-growing modality, capturing revenue through device-bundled software licensing, SaaS telemedicine subscriptions, and virtual consultation fees as women's health functionality expands beyond handheld screens.
Estimation Model
Epidemiology Layer
Digital Access Layer
Behavioural Layer
Monetisation Layer
Who has a relevant condition?
Who can be reached digitally?
Who actively uses health apps?
How much revenue is generated?
Identify disease prevalence rates among the global female population-anemia, PCOS, menopause, pregnancy, endometriosis-to define the clinically motivated user pool.
Apply region-specific smartphone penetration rates to the eligible population, filtered by gender-adjusted internet access, to derive the digitally reachable addressable market.
Apply health app adoption rates (~37%) and freemium-to-premium conversion benchmarks (~17%) from Rock Health and IQVIA data to convert reachable users into active, paying subscribers.
Multiply paying users by blended consumer ARPU (USD 15-25/year) and add B2B/institutional revenue from insurer, employer, and hospital contracts (USD 5-15 per covered life/year).
Output: Eligible User Pool
Output: Digitally Reachable Market
Output: Active & Paying Users
Output: Addressable Revenue
Delivered Customizations
This report has been delivered with the following In-depth customizations
Client Request
Customization Delivered
Value Adds
Menstrual Health, Fertility & Pregnancy Tracking Trends
Conducted a focused analysis of women’s health apps covering menstrual tracking, fertility monitoring, pregnancy management, hormonal health, AI-enabled symptom tracking, wearable integration, and digital wellness adoption trends.
Helps stakeholders identify high-growth application areas, evaluate user engagement trends, and assess commercialization opportunities in AI-driven women’s healthcare platforms.
Digital Wellness & Preventive Healthcare Adoption Trends
Evaluated adoption trends for menopause management, mental wellness, fitness, nutrition, and chronic disease management apps, including wearable integration, subscription models, and preventive healthcare features.
Provides insights into emerging wellness trends, unmet consumer needs, and commercially attractive app segments to support product positioning and innovation strategies.
FemTech Infrastructure & Personalized Healthcare Opportunity Assessment
Assessed demand for AI-powered women’s health platforms, remote monitoring, virtual care, and personalized wellness solutions, along with data privacy, regulatory, and interoperability challenges.
Supports investment and expansion strategies by identifying underserved markets, evaluating technology readiness, and strengthening long-term growth opportunities in preventive healthcare.
Frequently Asked Questions About This Report
The global women's health app market size was estimated at USD 5.3 billion in 2025 and is expected to reach USD 6.3 billion in 2026.
The global women's health app market is expected to grow at a compound annual growth rate of 20.5% from 2026 to 2033 to reach USD 23.4 billion by 2033.
Some key players operating in the women's health app market are Flo Health, Inc.; Clue; Apple Inc.; Glow, Inc.; Withings; Fitbit, Inc.; Natural Cycles; Wildflower Health; HelloBaby, Inc.; and Ovia Health
Key factors that are driving the women's health app market growth include increased mobile phone penetration, changes in dietary habits, and rising stress among the working women population.
The menstrual health segment led with a 37.8% revenue share in 2025.
North America dominated with a 40.1% revenue share in 2025.
Smartphone held the largest revenue share 68.6% in 2025, while other segment is the fastest-growing area.
About the Author(s)
Healthcare IT Research Team
Healthcare · Healthcare ITThis report was authored by the healthcare it research team at Grand View Research - comprising two research analysts, one senior research analyst, and one industry expert - with specialized expertise in the healthcare it segment of the healthcare industry. All findings are based on proprietary healthcare databases, executive interviews, and regulatory analysis, subject to internal peer review prior to publication.
Last Updated:
Speak to Analyst

Customize this report to your needs - add regions, segments, or data points, with 20% free customization.
Or view our licence options:


ISO 9001:2015 & 27001:2022 Certified
We are GDPR and CCPA compliant! Your transaction & personal information is safe and secure. For more details, please read our privacy policy.


