
- Home
- »
- Renewable Energy
- »
-
Wood Chips Market Size, Share & Growth Report, 2026-2033GVR Report cover
![Wood Chips Market (2026 - 2033)Report]()
Wood Chips Market (2026 - 2033)
Size, Share & Trends Analysis Report By Product Type (Softwood, Hardwood), By Application (Wood-Based Panels, Landscaping & Mulch), By End Use (Pulp & Paper Industry), By Distribution Channel, By Region, And Segment Forecasts
Market Size, 2025
$15.8BMarket Estimate, 2026
$16.5BMarket Forecast, 2033
$25.9BCAGR, 2026–2033
6.6%Wood Chips Market Summary
The global wood chips market size was valued at USD 15.8 billion in 2025 and is projected to grow from USD 16.5 billion in 2026 to USD 25.9 billion in 2033, at a CAGR of 6.6% from 2026 to 2033. Europe dominated the global market, accounting for the largest revenue share of 34.0% in 2025. The market is experiencing steady growth, driven by rising demand for renewable feedstocks across the pulp and paper, biomass energy, and engineered wood sectors.
Key Market Trends & Insights
- By product type: The softwood segment held the largest market share of around 60.0% in 2025.
- By application: The pulp manufacturing segment held the largest market share of around 34.0% in 2025.
- By end use: The pulp & paper industry segment held the largest market share of around 42.0% in 2025.
- By distribution channel: The offline segment held the largest market share of around 91.0% in 2025.
Regional Insights
- Largest regional market: Europe (34.0% revenue share, 2025)
- Fastest-growing regional market: Asia Pacific (highest CAGR, 2026-2033)
Market Size & Forecast
- Market size in 2025: USD 15.8 Billion
- Estimated market size in 2026: USD 16.5 Billion
- Projected market size by 2033: USD 25.9 Billion
- CAGR (2026-2033): 6.6%
Three ways to get this report
Buy it, customize it, or ask a question.Ask an Analyst
A direct answer, usually in 1 working day
- AccessReport author, directly
- Reply timeWithin 1 working day
- No sales callDirect answer only
- FormatEmail reply
- CostFree, no cost
Get the Full Report
What the study covers
- FormatsPDF · Excel · Dashboard
- Timeline2026–2033 annual, 2025 base
- Coverage20+ countries, 5 regions
- Companies10+ key players profiled
Customize the Report
20% free customization
- IncludeCountries, segments, points
- TailorTo your product definition
- ExtendDeeper competitor detail
- OrA fully bespoke study
- Turnaround5–10 working days
The growing emphasis on sustainable resource utilization, decarbonization, and circular economy practices is accelerating the adoption of wood chips as a cost-effective, environmentally friendly raw material. The expanding pulp production, rising consumption of paper-based packaging, and increasing deployment of biomass-fired power plants and combined heat and power (CHP) facilities are collectively driving the market demand. Additionally, greater utilization of forestry residues and sawmill by-products is strengthening supply efficiency while supporting waste minimization and sustainable forest management initiatives.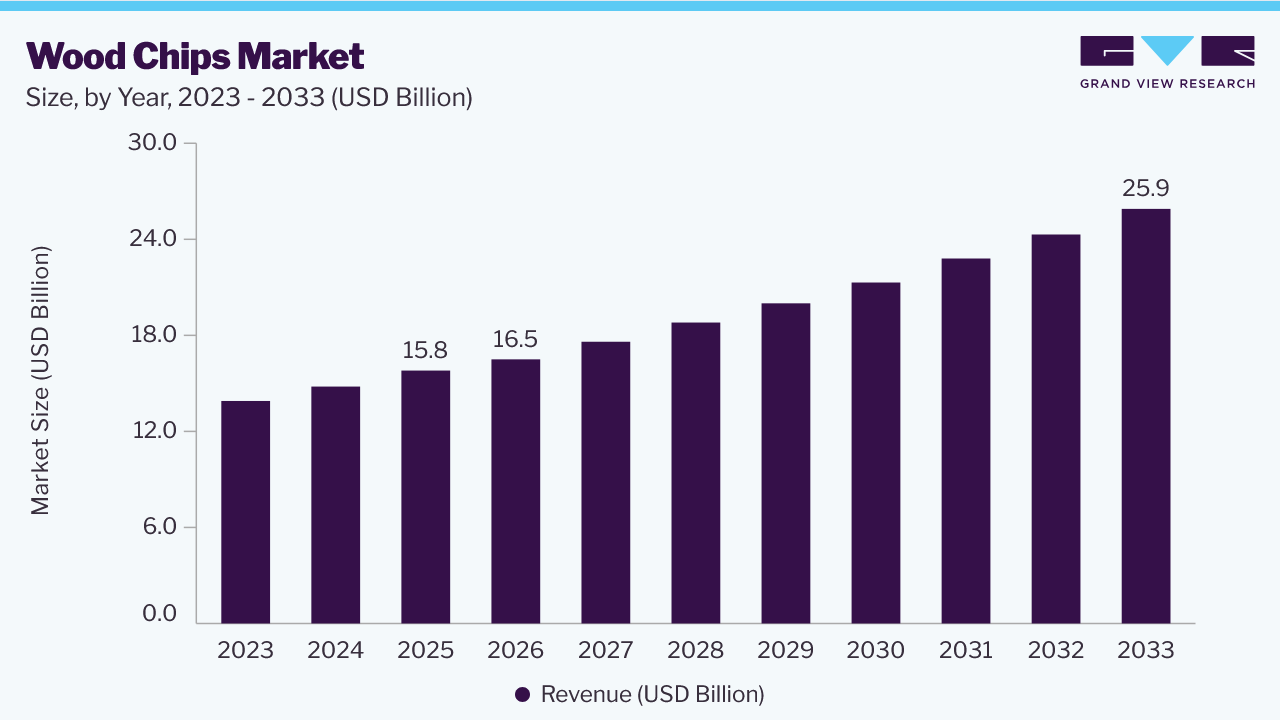
The market is further benefiting from favorable government policies that promote renewable energy generation, carbon emissions reduction, and the substitution of fossil fuels with biomass-based alternatives. Increasing investments in biomass infrastructure, district heating networks, and industrial bioenergy projects are creating sustained demand for wood chips, particularly in developed economies. At the same time, expanding construction activities and growing demand for engineered wood products are supporting consumption in wood-based panel applications. However, a major challenge for the market is the fluctuation in raw material availability caused by changing forestry regulations, weather conditions, and supply chain constraints.
The market continues to present strong opportunities as governments and industries invest in cleaner energy solutions and sustainable forest management. Growing focus on reducing carbon emissions and increasing the use of renewable fuels is expected to support long-term demand for wood chips. In addition, ongoing investments in biomass energy projects and advanced wood processing technologies are likely to create new growth opportunities across industrial and energy applications.
Analyst Perspective
The market for wood chips is expected to benefit from continued investments in renewable energy, sustainable forestry, and advanced wood processing technologies. The growing commercialization of biomass energy projects, the increasing demand for low-carbon industrial fuels, and the expanding applications of wood chips in construction, agriculture, and landscaping are expected to create significant long-term growth opportunities. As industries increasingly prioritize sustainable raw materials and governments strengthen climate and energy policies, the global wood chips market is projected to maintain a growth trajectory throughout the forecast period.
Products Type Insights
The softwood segment held the largest revenue share in 2025, driven by its wide use in pulp and paper production and biomass energy. Softwoods such as pine and spruce produce long fibers that enhance paper strength and quality, making them well-suited for paper manufacturing. It is also commonly used as biomass fuel because of its steady supply and consistent quality from managed forests. Strong production infrastructure and established supply chains further support its availability. Continuous demand from the paper packaging and renewable energy industries has helped the segment maintain its leading position in the market.
The hardwood segment is expected to register robust growth during the forecast period, driven by increasing demand for hardwood chips across pulp manufacturing, biomass energy, and value-added wood product applications. Hardwood chips are gaining greater prominence in applications requiring short fibers and superior surface smoothness, particularly in the production of printing, writing, tissue, and specialty papers. Rising emphasis on sustainable sourcing practices and the efficient utilization of mixed-species forests is further supporting the adoption of hardwood chips. Additionally, growing investments in biomass energy infrastructure, expanding production of engineered wood products, and continuous advancements in wood processing technologies are expected to further accelerate the growth of this segment throughout the forecast period.
Application Insights
The pulp manufacturing segment held the largest share, accounting for around 34.0% of the global wood chips demand in 2025. Wood chips remain the primary raw material for pulp manufacturing, making them requisite to paper producers worldwide. Growing demand for packaging products, driven by the expansion of e-commerce and the food & beverage industry, is increasing the need for high-quality wood chips. Additionally, the rising adoption of sustainable paper-based packaging as an alternative to plastics is supporting long-term market demand. Stable production capacity, coupled with continuous investments in pulp manufacturing facilities, is expected to reinforce the segment's dominant position throughout the forecast period.
The combined heat & power (CHP) segment is expected to register the fastest growth, driven by the increasing use of biomass as a renewable energy source. Wood chips are widely used as fuel in CHP plants because they can generate both electricity and heat with higher energy efficiency than conventional power systems. Governments and industries are increasingly adopting biomass-based energy solutions to reduce carbon emissions and improve energy security. In addition, growing investments in renewable energy infrastructure and favorable environmental policies are encouraging the installation of biomass-powered CHP facilities. The availability of forestry residues and wood waste further supports the use of wood chips as a reliable and sustainable fuel source for energy generation.
End Use Insights
The pulp & paper industry segment held the largest share, accounting for around 34.0% of the global wood chips demand in 2025. This dominance is attributed to its consistent requirement for high volumes of wood-based raw materials. Wood chips are processed into pulps to produce printing paper, tissue, packaging materials, and a wide range of specialty paper grades. Sustained growth in demand for corrugated packaging from the retail, e-commerce, and logistics sectors continues to drive wood chip consumption. Furthermore, the industry's emphasis on renewable feedstock and sustainable manufacturing practices supports long-term demand. Ongoing modernization of pulp mills, capacity expansions, and stable production levels further reinforce the segment's leading position in the global wood chips market.
The energy & utilities segment is witnessing the fastest growth, supported by the increasing adoption of biomass for renewable power and heat generation. Wood chips are widely used in biomass power plants, district heating systems, and industrial boilers as an alternative to fossil fuels. Growing efforts to reduce greenhouse gas emissions and diversify energy sources are encouraging utilities to expand biomass-based energy projects. Furthermore, supportive government incentives for renewable energy adoption, coupled with the abundant availability of forest residues, are expected to significantly accelerate the utilization of wood chips across power generation and industrial energy applications. With investments in green energy projects expected to accelerate in the coming years, the segment is projected to maintain a strong growth trajectory over the forecast period.
Distribution Channel Insights
The offline segment accounted for the largest share of the wood chips market, owing to its bulk-purchasing nature. Bulk purchasers include pulp mills, biomass power plants, and other wood processors who mostly obtain wood chips through long-term contracts with vendors, distributors, and forestry firms. Through offline purchases, buyers can effectively inspect quality, maintain continuity of supplies, and arrange for delivery. The good connections established between manufacturers and industrial clients play an important role in maintaining supply contracts. Given that wood chips are mostly sold in bulk, offline distribution remains the predominant channel.
The online distribution channel is experiencing the fastest growth as digital procurement platforms are increasingly adopted across industrial supply chains. Online channels enable buyers to compare suppliers, review product specifications, and place orders more efficiently, reducing procurement time and improving transparency. Small and medium-sized businesses are increasingly using digital platforms to source wood chips for heating, landscaping, and biomass applications. Additionally, developments in logistics management and digital supply chain solutions are making online procurement more convenient for businesses. Therefore, the online sales channel is expected to gain share over the forecasted period.
Regional Insights
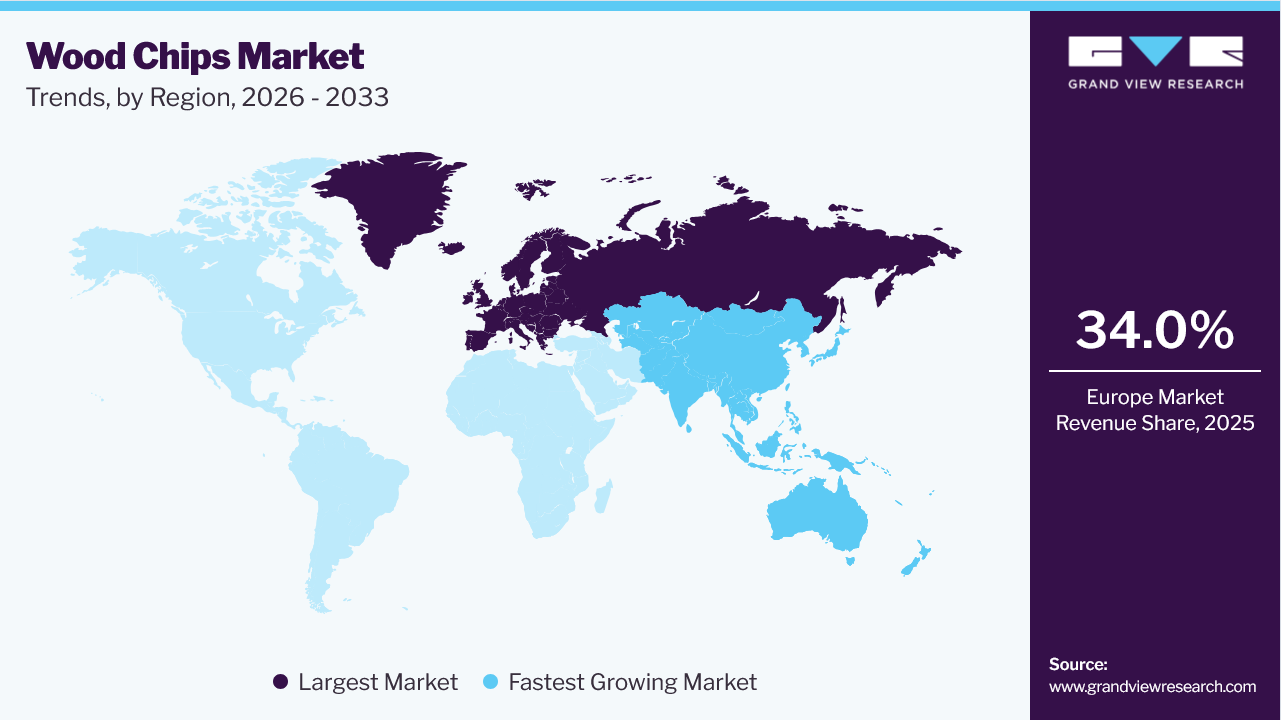
Europe accounted for the largest share of the global wood chips market, driven by its well-established biomass energy sector, advanced forestry management practices, and strong pulp and paper industry. The region has witnessed widespread adoption of wood chips as a renewable feedstock for combined heat and power (CHP) plants, district heating systems, and industrial biomass boilers, supported by stringent carbon-reduction targets and favorable renewable-energy policies. In addition, the presence of sustainably managed forests, efficient wood processing infrastructure, and high demand for wood-based panels and paper products continue to strengthen market growth. Ongoing investments in bioenergy facilities, circular economy initiatives, and the utilization of forestry residues are expected to reinforce Europe's leading position in the global wood chips market throughout the forecast period.
Asia Pacific Wood Chips Market Trends
Asia Pacific is expected to register the fastest growth during the forecast period, driven by expanding pulp and paper production, increasing deployment of biomass energy, and rising demand for engineered wood products. Rapid industrialization, growing consumption of paper-based packaging, and increasing investments in renewable energy infrastructure are accelerating the adoption of wood chips across the region. Furthermore, abundant forestry resources in several countries, coupled with expanding plantation forestry and greater utilization of forestry residues, are strengthening feedstock availability. Government initiatives promoting clean energy, sustainable forest management, and bio-based industries are also supporting market expansion. Continued investments in pulp manufacturing capacity, biomass power projects, and advanced wood processing technologies are expected to sustain the region's strong growth trajectory throughout the forecast period.
Key Wood Chips Company Insights
The wood chips market is characterized by the presence of several global, regional, and local participants, resulting in a highly competitive landscape. Leading companies are actively pursuing strategies such as partnerships, collaborations, mergers, acquisitions, and strategic agreements to strengthen their market position, expand their geographic footprint, enhance production capabilities, and broaden their product portfolios. In addition, market participants are investing in capacity expansions, sustainable sourcing initiatives, and advanced wood-processing technologies to improve operational efficiency and meet the growing demand for renewable wood-based feedstocks.
Key Wood Chips Companies
The following key companies have been profiled for this study on the wood chips market.
-
Marubeni Corporation.
-
Weyerhaeuser Company
-
West Fraser Timber Co.
-
International Woodchip Corporation
-
Oji Holdings Corporation.
-
Interfor Corporation
-
Metsa Group
-
Mitsui & Co., Ltd.
-
Sojitz Corporation
Recent Developments
-
In July 2025, the U.S. Forest Service announced USD 80 million in Wood Innovation Grants to support wood products manufacturing, promote active forest management, and advance energy innovation in timber-producing regions across the U.S. The initiative is expected to strengthen the wood supply chain, expand markets for wood-based feedstocks, and support long-term demand for wood chips across pulp, bioenergy, and wood products applications.
-
In July 2025, Sumitomo Forestry completed the acquisition of Teal Jones Louisiana Holdings, expanding its timber processing operations in the United States. The acquisition increased wood-processing capacity and strengthened vertical integration within the timber value chain, while enhancing the availability of wood residues, including wood chips, for pulp, biomass energy, and other value-added wood-product applications. The company also announced plans to utilize wood chips and sawmill residues for biomass power generation and future biorefinery projects.
Wood Chips Market Report Scope
Report Attribute
Details
Market size in 2025
USD 15.8 billion
Estimated market size in 2026
USD 16.5 billion
Projected market size by 2033
USD 25.9 billion
Growth rate
CAGR of 6.6% from 2026 to 2033
Base year for estimation
2025
Historical data
2021 - 2024
Forecast period
2026 - 2033
Quantitative units
Revenue in USD billion, and CAGR from 2026 to 2033
Report coverage
Revenue forecast, company ranking, competitive landscape, growth factors, and trends
Segments covered
Product type, application, end use, distribution channel, region
Regional Scope
North America; Europe; Asia Pacific; Latin America; Middle East & Africa
Country Scope
U.S.; Canada; Mexico; UK; Germany; France; China; Japan; India; Australia; South Korea; Brazil; Argentina; South Africa; Saudi Arabia; UAE
Key companies profiled
Marubeni Corporation; Weyerhaeuser Company; West Fraser Timber Co.; International Woodchip Corporation; Oji Holdings Corporation; Interfor Corporation; Metsa Group; Mitsui & Co., Ltd; Sojitz Corporation
Customization scope
Free report customization (equivalent up to 8 analysts working days) with purchase. Addition or alteration to country, regional & segment scope.
Pricing and purchase options
Avail of customized purchase options to meet your exact research needs. Explore purchase options
Global Wood Chips Market Report Segmentation
This report forecasts revenue growth at the global, regional, and country levels and provides an analysis of the latest industry trends and opportunities across each sub-segment from 2021 to 2033. For the purpose of this study, Grand View Research has segmented the global wood chips market report based on product type, application, end use, distribution channel, and region:
-
Product Type Outlook (Revenue, USD Billion, 2021 - 2033)
-
Softwood
-
Hardwood
-
Others
-
-
Application Outlook (Revenue, USD Billion, 2021 - 2033)
-
Pulp Manufacturing
-
Residential & Commercial Heating
-
Combined Heat & Power (CHP)
-
Wood-Based Panels
-
Landscaping & Mulch
-
Playground Surfacing
-
Animal Bedding
-
Biofuels & Bioenergy
-
Others
-
-
End Use Outlook (Revenue, USD Billion, 2021 - 2033)
-
Pulp & Paper Industry
-
Energy & Utilities
-
Construction & Building Materials
-
Agriculture & Horticulture
-
Municipal & Public Infrastructure
-
Industrial Manufacturing
-
Others
-
-
Distribution Channel Outlook (Revenue, USD Billion, 2021 - 2033)
-
Offline
-
Online
-
-
Regional Outlook (Revenue, USD Billion, 2021 - 2033)
-
North America
-
U.S.
-
Canada
-
Mexico
-
-
Europe
-
UK
-
Germany
-
France
-
-
Asia Pacific
-
China
-
Japan
-
India
-
Australia
-
South Korea
-
-
Latin America
-
Brazil
-
Argentina
-
-
Middle East and Africa (MEA)
-
South Africa
-
Saudi Arabia
-
UAE
-
-
About the Author(s)
Renewable Energy Research Team
Energy & Power · Renewable EnergyThis report was authored by the renewable energy research team at Grand View Research - comprising two research analysts, one senior research analyst, and one industry expert - with specialized expertise in the renewable energy segment of the energy & power industry. All findings are based on proprietary energy & power databases, executive interviews, and regulatory analysis, subject to internal peer review prior to publication.
Last Updated:
Speak to Analyst


Customize this report to your needs - add regions, segments, or data points, with 20% free customization.
Or view our licence options:


ISO 9001:2015 & 27001:2022 Certified
We are GDPR and CCPA compliant! Your transaction & personal information is safe and secure. For more details, please read our privacy policy.


