
- Home
- »
- Medical Devices
- »
-
Wound Dressing Market Size And Share Report, 2026-2033GVR Report cover

Wound Dressing Market (2026 - 2033)
Size, Share & Trends Analysis Report By Product (Traditional Dressing, Advanced Dressing), By Application (Chronic Wounds, Acute Wounds), By End-use, By Region, And Segment Forecasts
Market Size, 2025
$16.0BMarket Estimate, 2026
$16.7BMarket Forecast, 2033
$22.4BCAGR, 2026–2033
4.3%Wound Dressing Market Summary
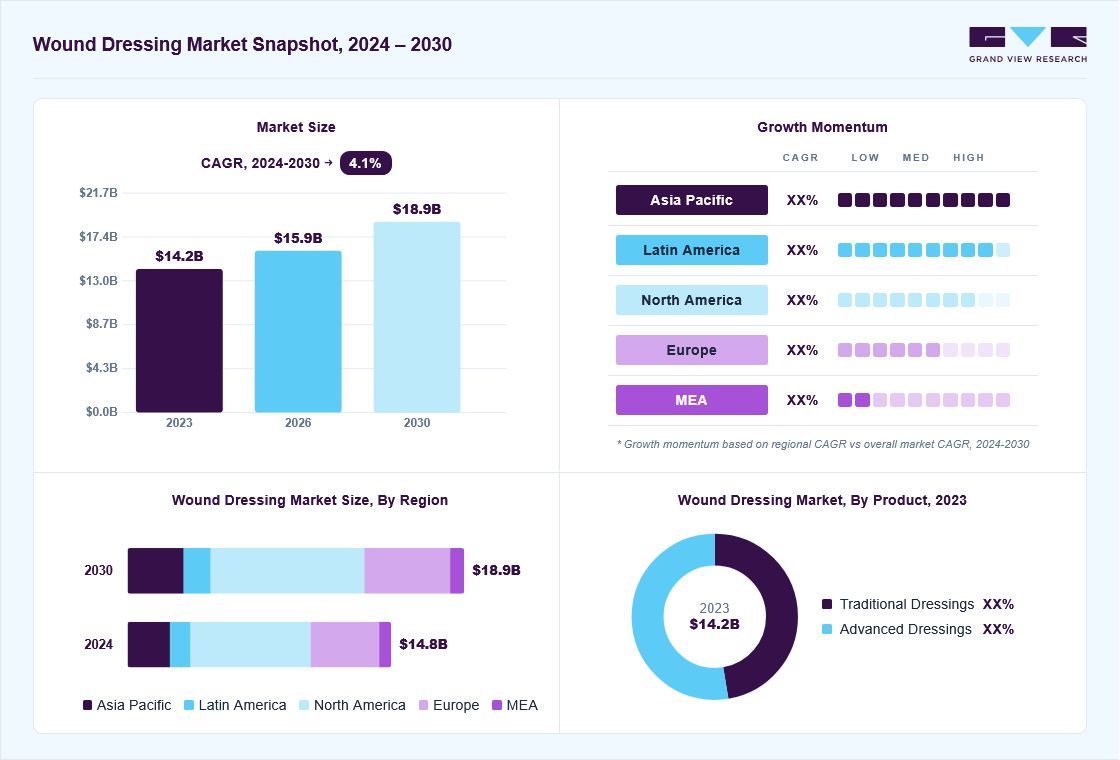
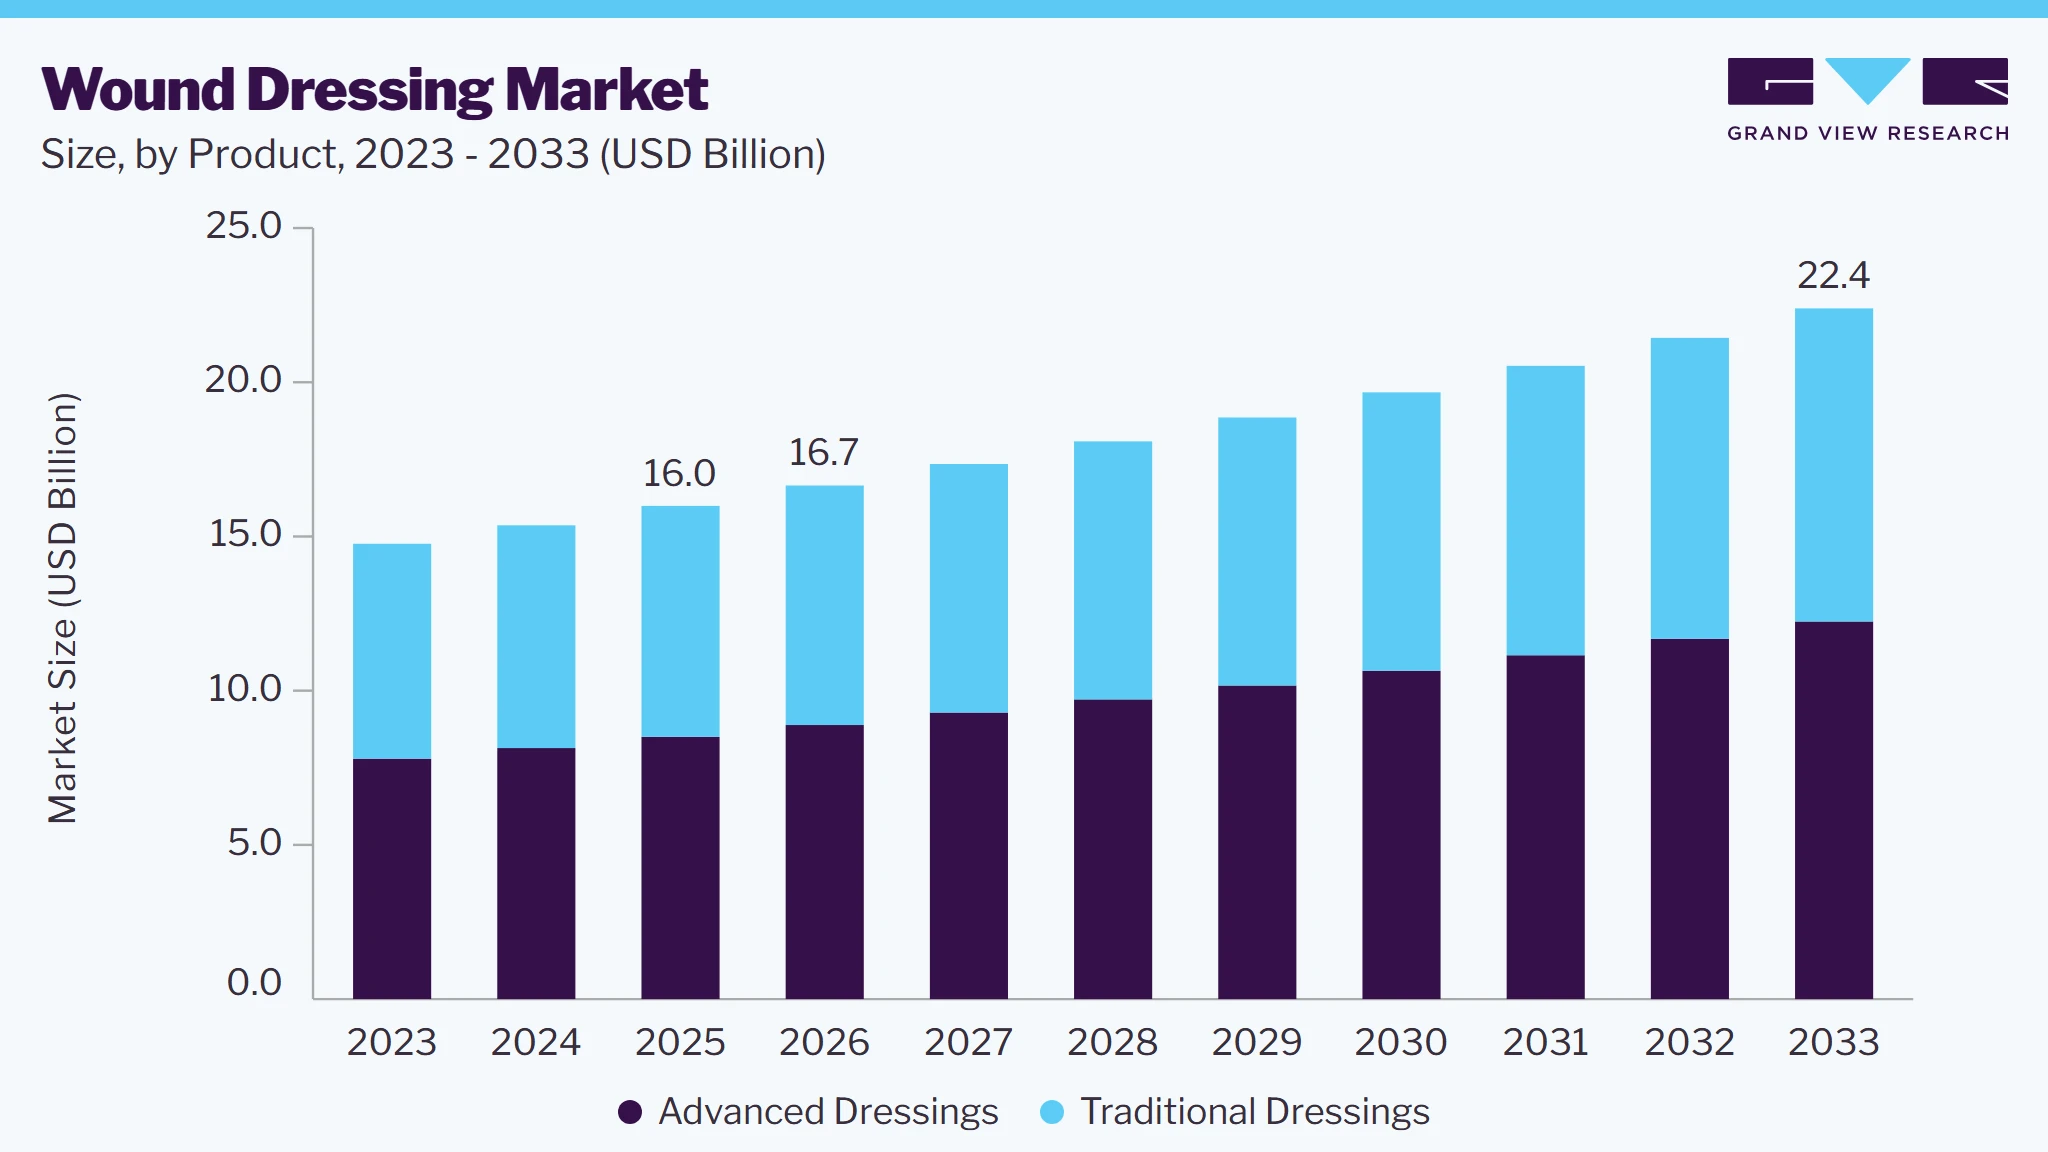
The global wound dressing market size was valued at USD 16.0 billion in 2025 and is projected to grow from USD 16.7 billion in 2026 to USD 22.4 billion by 2033, at a CAGR of 4.3% from 2026 to 2033. The market in North America dominated with a revenue share of 45.5% in 2025. The increasing prevalence of diverse wounds, including pressure ulcers and surgical site wounds, coupled with a growing aging population and a rise in traumatic accidents globally, is anticipated to drive the growth of the market.
 Source: Grand View Research, IR Documents, Primary Interviews, Paid DatabasesTo learn more about this report,
 Download Free Sample Report
Key Market Trends & Insights
- By product: Advanced dressing segment held the largest market share of 53.2% in 2025.
- By application: Chronic wounds segment held the largest market share of 59.8% in 2025.
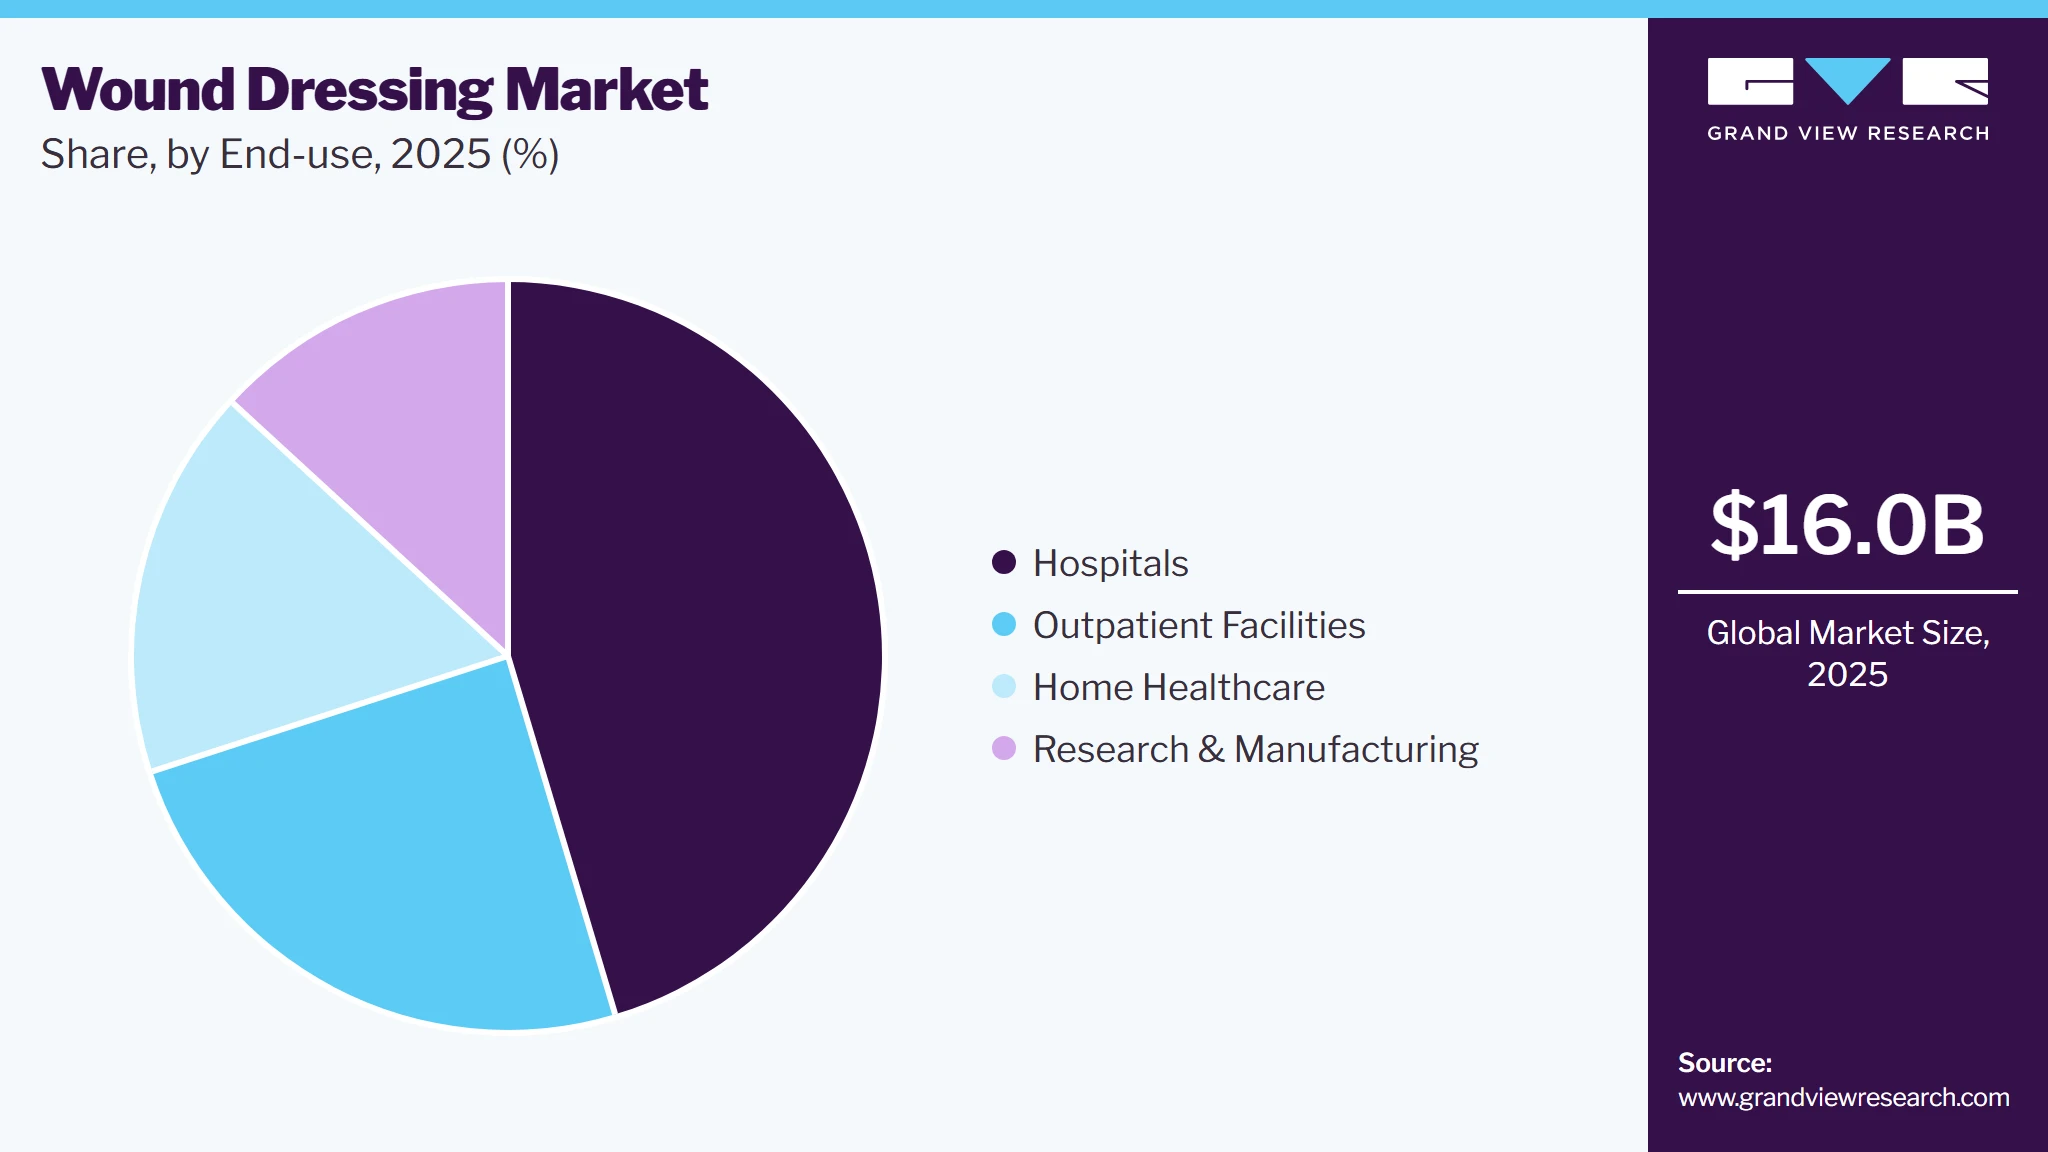
- By end-use: Hospitals segment held the largest market share of 45.4% in 2025.
Regional Highlights
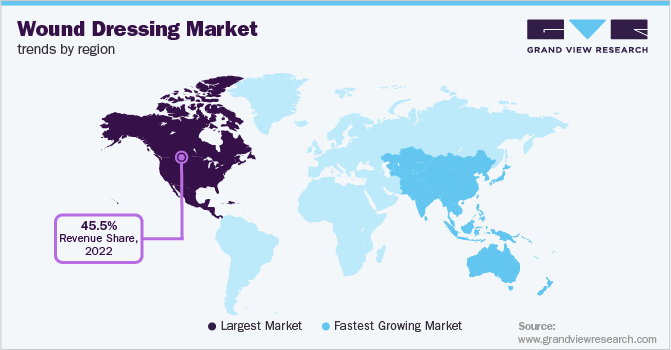
- Largest regional market: North America (45.5% revenue share, 2025)
- Fastest-growing regional market: Asia Pacific (highest CAGR, 2026-2033)
- By country: The U.S. held the largest market share in 2025.
Market Size & Forecast
- Market size in 2025: USD 16.0 Billion
- Estimated market size in 2026: USD 16.7 Billion
- Projected market size by 2033: USD 22.4 Billion
- CAGR (2026-2033): 4.3%
Three ways to get this report
Buy it, customize it, or ask a question.Ask an Analyst
Analyst response in 1 business day
- AccessReport author, directly
- Reply timeWithin 1 working day
- No sales callDirect answer only
- FormatEmail reply
- CostFree, no cost
Get the Full Report
What the study covers
- FormatsPDF · Excel · Dashboard
- Timeline2026–2033 annual, 2025 base
- Coverage20+ countries, 5 regions
- Companies10+ key players profiled
Customize the Report
20% free customization
- IncludeCountries, segments, points
- TailorTo your product definition
- ExtendDeeper competitor detail
- OrA fully bespoke study
- Turnaround5–10 working days
According to the WHO report published in June 2022, about 1.3 million people die each year as a result of road accidents. These factors are expected to boost market growth over the forecast period. The global incidence of chronic wounds, such as venous leg ulcers and diabetic foot ulcers, is on the rise. For instance, in January 2023 report from NCBI revealed that approximately 6.5 million people in the United States are grappling with various chronic wounds. In addition, the growing diabetic population is expected to play a pivotal role in driving the expansion of the market. For instance, as per CDC, in October 2022, approximately 38.4 million people in the U.S. have been diagnosed with diabetes, which comprises around 11.6% of the total U.S. population. In addition, diabeticfootonline.com reported in 2021 that up to 34% of people with diabetes are susceptible to developing diabetic foot ulcers. Consequently, due to these factors, the increasing demand for wound dressing is anticipated to foster the growth of the market.
 To learn more about this report, Download Free Sample Report
The elderly population is particularly prone to wounds, and the increasing number of older individuals is anticipated to drive the growth of the market. For instance, according to the European Parliament, Japan holds the distinction of being the fastest-aging country worldwide, with approximately 28.7% of its population aged 65 years and above. Moreover, according to the same source, it is anticipated that by 2036, one-third of the Japanese population will be aged 65 years and above. In addition, as highlighted by NCBI, the aging process can impact wound healing, underscoring the need for wound dressing in the geriatric population to facilitate the healing of wounds and thereby drive the growth of the market.
The surge in the incidence of global traumatic accidents. For instance, based on statistics released by WHO in June 2022, approximately 1.3 million individuals die due to road crashes annually, while an additional 20 to 50 million people endure non-fatal injuries. Similarly, according to the Economic Times, India recorded 554,796 road accident cases in the year 2020. These accidents often lead to considerable blood loss and various injuries, demanding swift medical intervention, and in some cases, necessitating surgical procedures to provide immediate relief to the affected individuals. Consequently, the increasing frequency of accidents is expected to drive the need for wound dressing products, contributing to significant growth in the market over the forecast period.
The outbreak of COVID-19 pandemic was expected to lower the use of advanced wound dressing, as they require healthcare advice, thereby restricting the growth of the market. However, post-pandemic, the market is anticipated to grow at a significant growth rate over the forecast duration. This can be attributed to initiatives such as partnership, research and development, geographic expansion, and launch of technologically advanced products by major market players. For instance, in September 2021, Coloplast Corp. inaugurated a factory in Central America, which was intended to support the global growth of the company. Similarly, in October 2021, Medline Industries announced an investment of USD 77.5 million to build a new distribution center in Kansas. Thus, due to the aforementioned factors, the market is expected to boost over the post-pandemic period.
Market Dynamics
The wound dressing market is driven by the rising prevalence of chronic wounds, increasing surgical procedures, an aging population, and growing awareness of effective wound management. Healthcare providers are increasingly adopting advanced dressings that promote faster healing, reduce infection risk, and lower overall treatment costs, supporting market expansion. However, pricing pressures, reimbursement limitations in certain regions, and the availability of low-cost conventional dressings continue to influence purchasing decisions. Ongoing product innovation, expansion of home healthcare, and increasing demand for value-based wound care are expected to sustain long-term market growth.
The wound dressing market is primarily driven by the growing prevalence of chronic wounds, including diabetic foot ulcers, pressure ulcers, and venous leg ulcers, alongside the increasing number of surgical procedures and traumatic injuries worldwide. The expanding elderly population and rising incidence of diabetes further increase the demand for effective wound management solutions. In addition, the shift toward advanced wound dressings that accelerate healing, reduce infection risk, and minimize hospital stays is supporting sustained market growth.
According to European Wound Management Association (EWMA),
- Chronic wounds affect approximately 2.2 individuals per 1,000 population, highlighting a significant healthcare burden across Europe.
- The point prevalence of venous leg ulcers is estimated at 0.33%-1.01% of the population, contributing substantially to the global burden of chronic wound management.
The wound dressing market faces challenges due to the high cost of advanced wound dressings compared with traditional alternatives, which limits their adoption in price-sensitive healthcare systems. In many developing countries, limited reimbursement coverage and constrained healthcare budgets further restrict the use of premium wound care products. Additionally, pricing pressure from hospital procurement and competitive tender-based purchasing can impact manufacturers’ profit margins and market penetration.
The growing shift toward home healthcare and outpatient wound management presents a significant opportunity for the wound dressing market. The increasing demand for easy-to-use, long-wearing, and infection-resistant advanced dressings is driving product innovation and adoption beyond hospital settings. Additionally, expanding healthcare access in emerging economies and the rising focus on value-based care are creating new growth opportunities for manufacturers across both developed and developing markets.
Market Characteristics
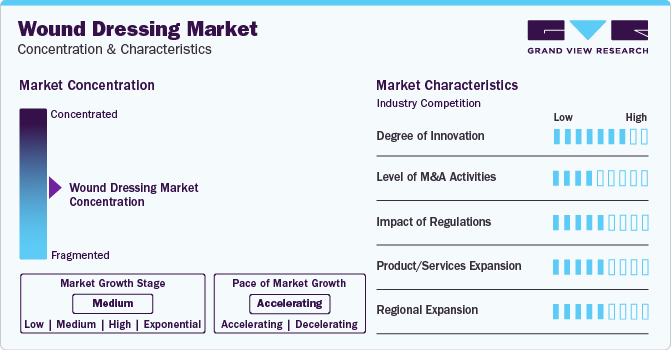
The wound dressing market is driven by continuous technological advancements and innovations, focusing on product enhancement and development to meet evolving market demands. Development of advanced wound care technologies, such as, bioengineered allogeneic cellular therapies, stem cell therapies, xenograft cellular matrices, and growth factors. Thus, market players are investing in innovative technologies and procedures to keep up with the demand.
 To learn more about this report, Download Free Sample Report
Several market players such as 3M; Coloplast Corp.; Medline Industries; Smith & Nephew; ConvaTec Group PLC; Derma Sciences (Integra LifeSciences); Ethicon (Johnson & Johnson); Baxter International; Molnlycke Health Care AB and others, indicating a concerted effort towards strategic collaborations and geographical expansion to address the growing demand and capitalize on market opportunities.
Regulatory standards, such as FDA (Food and Drug Administration) approvals in the United States or CE marking in the European Union, are essential, demanding comprehensive preclinical and clinical assessments, stringent manufacturing practices, and documentation to gain market approval.
The market expansion is driven by the development of innovative wound dressing. More than 3000 products have been developed with the goal of treating various wound types and targeting different points of the healing cascade. Wound dressings have developed from crude applications of natural products, including plant herbs, animal fat, and honey, to tissue-engineered scaffolds. This product expansion is expected to continue, benefiting patients, surgeons, and healthcare providers.
Analyst Perspective
The wound dressing market is experiencing significant growth, driven by the rising prevalence of chronic wounds, increasing surgical procedures, an aging population, and greater awareness of advanced wound management. While traditional dressings continue to account for a significant share due to their affordability and widespread use, advanced dressings are gaining market share as healthcare providers prioritize faster healing, infection prevention, and shorter hospital stays. Continued product innovation, favorable reimbursement for selected advanced wound care products, and the expansion of home healthcare services.
Product Insights
Based on product, the advanced dressing segment dominated the wound dressing market with a market share of 53.2% in 2025 and are expected to grow at the fastest CAGR during the forecast period. This can be attributed to rising cases of obesity and venous leg ulcers. For instance, as per a study by Sage Journals in 2020, the prevalence rate of obesity in India is 40.3%. Similarly, according to a WHO report published in 2022, 19.0% of the population in Germany is classified as obese. Individuals with obesity are at a heightened risk of developing venous leg ulcers, indicating that the increasing prevalence of obesity within the population is likely to contribute to the dominance of the advanced dressing segment in the forecast period.
Traditional dressing is expected to witness a considerable CAGR over the forecast period. Traditional dressings are most commonly used to treat burn cases, thus, rising number of burn cases is expected to boost the traditional dressing segment. For instance, according to WHO in October 2023, about 180,000 deaths were caused due to burns every year. Moreover, in India, around 1,000,000 people are moderately or severely burnt each year. Similarly, as per CDC in the U.S., approximately, 4,500 burn victims die annually & 10,000 die due to burn-related infections. These factors are boosting the segment growth.
Application Insights
Based on application, the chronic wounds segment dominated the wound dressing market with a market share of 59.8% in 2025. This can be attributed to the increasing incidence of chronic diseases and geriatric population globally. For instance, as per Ageing Asia, in Indonesia, in 2019, the population aged above 60 stood at 27,524,000, and it is anticipated to surge to 69,792,000 by the year 2050. Similarly, there has been an increase in number of people suffering from diabetes & diabetic foot ulcers. For instance, as per ScienceDirect, diabetic foot ulcers may impact 25% of the diabetic population, and approximately 20% of those affected may face the risk of amputation. Furthermore, according to a CDC report, in November 2023, approximately 38.4 million individuals in the U.S. were diagnosed with diabetes, and this figure is expected to triple by 2060, as indicated by BMC Population Health Metrics. Thus, these factors are boosting the segment growth over the forecast period.
The acute wounds segment is expected to witness the fastest growth of CAGR over the forecast period. This can be accredited to the rising number of surgical wounds and surgical site infections worldwide. For instance, as per a study by Wound International, the incidence rate of surgical site infections in general surgery was found to be 11.7%. Similarly, rising incidence of traumatic accidents is expected to impel the segment growth. For instance, as per an article by Brady United Organization, in July 2021, around 316 people in the U.S. are shot every day, leading to acute wounds, which require wound dressing to heal. Thus, due to abovementioned factors, the market is expected to impel over the forecast years.
End-use Insights
Based on end-use, the hospitals segment dominated the wound dressing market with a market share of 45.4% in 2025. This can be credited to rising surgical procedures and an increasing number of hospitals. For instance, as per a 2020 study published by NCBI, an estimated 310 million surgical procedures occur worldwide annually, with 40 to 50 million taking place solely in the U.S. Furthermore, there's been a notable rise in the global count of hospitals and hospitalizations. According to the Australian Institute of Health & Welfare, hospitalizations in Australia have seen a significant increase. In the 2019-2020 period, 11.1 million individuals in Australia underwent hospitalization. Consequently, these trends are expected to elevate the prominence of the hospital segment within the end-use market.
 To learn more about this report, Download Free Sample Report
The home healthcare segment is expected to witness the fastest growth of CAGR over the forecast period. The prevalence of home healthcare settings is on the rise globally, with an increasing number of countries adopting this approach. In addition, numerous surgical procedures necessitate an extended recovery period, resulting in frequent wound dressing changes. The preference for home healthcare settings is particularly notable among the geriatric and bariatric populations. The growing numbers within these demographics are expected to contribute to the expansion of the home healthcare segment. For instance, according to WHO's June 2021 report, worldwide obesity has tripled since 1975. Similarly, the same source notes that in 2020, 39 million children under the age of five were classified as overweight or obese. These factors are poised to drive the growth of the home healthcare segment throughout the forecast period.
Regional Insights
North America dominated the wound dressing market with the largest revenue share of 45.5% in 2025. The prevalence of dominance in the North America region within the market can be attributed to its well-established healthcare infrastructure, rising awareness, and the presence of key industry players. Furthermore, an anticipated increase in the volume of surgeries in North America is poised to propel the growth of the market in the region. For instance, in August 2022, according to the New Jersey Department of Health, around 7,398 open-heart surgeries were conducted in New Jersey during the 2019-2020 period. Similarly, in 2020, approximately 40,000 children in the U.S. underwent congenital heart surgery, as reported by AHA Journals. As such surgeries take time to heal, and wound dressing products help in healing these wounds in quick duration. Hence, wound dressing is preferred post-surgery, thereby impelling the market in the North America region.
 To learn more about this report, Download Free Sample Report
The wound dressing market in the U.S. held the largest share in the North America region in 2025. The growth of the market is driven by factors such as a robust healthcare infrastructure, rising awareness of the use of advanced wound care products, and the presence of several leading market players. In addition, the rise in orthopedic procedures due to the high incidence of sports injuries is expected to further propel the market. Hence, such factors are anticipated to propel the market growth in the U.S. over the forecast period.
However, Asia Pacific is estimated to witness the fastest CAGR over the forecast period. This can be accredited to the rising diabetic population in the region. For instance, according to the Down to Earth organization, as of December 2021, India had 74.2 million diabetic populations which were aged 20 – 79. Moreover, this number is anticipated to increase and reach 124.8 million by 2045. As diabetic people are more prone to diabetic foot ulcers, therefore, an increase in diabetic population may help the market grow in the Asia Pacific region.
China accounted for Asia Pacific largest share of the market in 2025. The regulatory process for product approvals is relatively less stringent in China, facilitating the easy entry of advanced products into the market. In addition, the availability of resources enables technological advancements at lower costs, contributing to a rise in the number of manufacturing facilities in the country. Furthermore, China has introduced Order 650 (formerly Order 276), known as the Regulations for the Supervision and Administration of Medical Devices, which aims to restrict foreign investment in the country, primarily to safeguard local medical device manufacturing companies. As a result, an anticipated increase in the number of local wound dressing manufacturers is expected to drive market growth over the forecast period.
Key Companies & Market Share Insights
Smith & Nephew plc, 3M, ConvaTec Inc., Coloplast Corp. Molnlycke Health Care AB, B. Braun Melsungen AG, Cardinal Health, are some of the dominant players operating in the wound dressing industry.
-
3M develops, manufactures, & markets a range of products and services globally. The company functions across four reportable segments: transportation & electronics; safety & industrial; healthcare; and consumer goods.
-
Smith & Nephew is a medical technology company engaged in developing, manufacturing, marketing, and selling medical services & devices. The company provides its services in orthopedics, sports medicine & ENT, and advanced wound care management.
-
Coloplast Corp. is a Danish manufacturing and marketing company. It has a distribution network spread across 53 countries. Its product range includes ostomy, urology, continence, wound care, and skin care verticals.
Imbed Biosciencesa, Kerecis, are some of the emerging market players functioning in wound dressings market.
-
Imbed Biosciencesa is a provider of nanotech-based wound care products. The company has developed technologies for embedding bioactive molecules in wound dressings and surgical implants. The products are based on the Microlyte Matrix technology platform. The company also offers antibacterial, anti-biofilm, and analgesic wound dressings.
-
Kerecis is engaged in the development of MariGen Omega3 acellular dermal matrix technology for applications in addressing chronic wounds, hernia repair, breast reconstruction, and abdominal wall reconstruction. Their proprietary acellular fish skin-derived material enhances existing human and porcine technologies through enhanced economic benefits superior clinical performance, and decreased disease transmission risks.
Key Wound Dressing Companies
The following key companies have been profiled for this study on the wound dressing market.
-
Smith+Nephew
-
Mölnlycke Health Care AB
-
Convatec Group PLC
-
Ethicon (Johnson & Johnson)
-
Coloplast Corp.
-
URGO
-
Coloplast Corp.
-
3M
-
Integra LifeSciences
-
PAUL HARTMANN AG
-
DR.AUSBÜTTEL (DRACO)
-
Integra LifeSciences
-
Medline Industries, Inc.
-
Brightwake Ltd.
Competitive Benchmarking
Category
Operating Strategies
Competitive Edge
Weakness
Established Players (3M, Coloplast Corp., Medline, Smith+Nephew)
• Expand advanced dressing portfolios through R&D and acquisitions.
• Strengthen hospital contracts and group purchasing organization (GPO) partnerships.
• Strong brand recognition and clinician trust.
• Broad product portfolios covering traditional and advanced dressings.
• Higher product pricing compared to local brands.
• Slower innovation cycles due to large organizational structures.
Emerging Players (Datt Mediproducts Private Limited, Advanced Medical Solutions Group plc, DermaRite Industries, LLC)
• Develop niche products with antimicrobial, bioactive, or sustainable materials.
• Target underserved regional markets and outpatient settings.
• Faster product innovation and agility.
• Competitive pricing strategies.
• Limited brand awareness and clinician adoption.
• Smaller sales and distribution networks.
Recent Developments
-
In June 2023, JeNaCell introduced the epicite balancing wound dressing to the German market. The dressing is especially well-suited and adapted for the management of chronic wounds with low to medium levels of exudation, including soft tissue lesions, diabetic foot ulcers, venous leg ulcers, and arterial leg ulcers.
-
In January 2023, Convatec Group PLC launched Convafoam, an advanced foam dressing in the U.S. The product is designed to fulfill the needs of patients and healthcare providers. It can be used for various types of wounds at any stage of the wound, which makes it the simple dressing choice for skin protection and wound management.
-
In October 2022, Healthium Medtech introduced a new line of wound dressings "Theruptor Novo". For the treatment of persistent sores such as diabetic foot ulcers and leg ulcers.
Wound Dressing Market Report Scope
Report Attribute
Details
Market size in 2025
USD 16.0 billion
Estimated market size in 2026
USD 16.7 billion
Projected market size by 2033
USD 22.4 billion
Growth rate
CAGR of 4.3% from 2026 to 2033
Historical data
2021 - 2024
Forecast period
2026 - 2033
Quantitative units
Revenue in USD million/billion and CAGR from 2026 to 2033
Report coverage
Revenue forecast, company ranking, competitive landscape, growth factors, and trends
Segments covered
Product, application, end-use, region
Regional scope
North America; Europe; Asia Pacific; Latin America; MEA
Country scope
U.S.; Canada; Mexico; Germany; UK; France; Italy; Spain; Norway; Denmark; Sweden; Russia; Iceland; Finland; China; Japan; India; South Korea; Australia; Thailand; Singapore; Brazil; Argentina; Saudi Arabia; South Africa; UAE; Kuwait; Israel
Key companies profiled
3M, Coloplast Corp., Medline, Smith+Nephew, Convatec Inc., Integra LifeSciences Corporation, Ethicon (Johnson & Johnson), Mölnlycke AB, MedWay Group, Cardinal Health, PAUL HARTMANN AG, Datt Mediproducts Private Limited, Advanced Medical Solutions Group plc, B. Braun SE, DermaRite Industries, LLC.
Customization scope
Free report customization (equivalent up to 8 analysts' working days) with purchase. Addition or alteration to country, regional & segment scope.
Pricing and purchase options
Avail customized purchase options to meet your exact research needs. Explore purchase options
Global Wound Dressing Market Report Segmentation
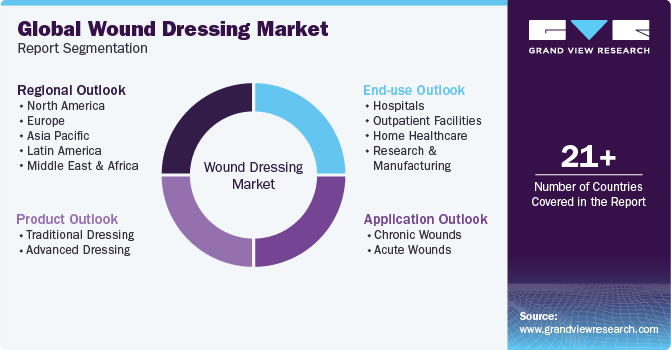
This report forecasts revenue growth at global, regional & country levels and provides an analysis of the industry trends in each of the sub-segments from 2021 to 2033. For this study, Grand View Research has segmented the global wound dressing market report based on product, application, end-use, and region:
 To learn more about this report, Download Free Sample Report
-
Product Outlook (Revenue, USD Million, 2021 - 2033)
-
Traditional Dressing
-
Gauze
-
Tape
-
Bandages
-
Cotton
-
Others
-
-
Advanced Dressing
-
Moist Dressing
-
Foam Dressing
-
Hydrocolloid Dressing
-
Film Dressing
-
Alginate Dressing
-
Hydrogel Dressing
-
Collagen Dressing
-
Other Advanced Dressing
-
-
Antimicrobial Dressing
-
Silver Dressing
-
Non-silver Dressing
-
-
Active Dressing
-
Biomaterials
-
Skin-substitute
-
-
-
-
Application Outlook (Revenue, USD Million, 2021 - 2033)
-
Chronic Wounds
-
Diabetic Foot Ulcers
-
Pressure Ulcers
-
Venous Leg Ulcers
-
Other Chronic Wounds
-
-
Acute Wounds
-
Surgical & Traumatic Wounds
-
Burns
-
-
-
End-use Outlook (Revenue, USD Million, 2021 - 2033)
-
Hospitals
-
Outpatient Facilities
-
Home Healthcare
-
Research & Manufacturing
-
-
Regional Outlook (Revenue, USD Million, 2021 - 2033)
-
North America
-
U.S.
-
Canada
-
-
Europe
-
UK
-
Germany
-
France
-
Italy
-
Spain
-
Denmark
-
Sweden
-
Norway
-
-
Asia Pacific
-
Japan
-
China
-
India
-
Australia
-
Thailand
-
South Korea
-
-
Latin America
-
Brazil
-
Mexico
-
Argentina
-
-
Middle East & Africa
-
South Africa
-
Saudi Arabia
-
UAE
-
Kuwait
-
-
Research Methodology
The wound dressing market figures in this report are based on a proven research process that combines executive interviews with secondary research from proprietary databases, company filings, and recognized regulatory and institutional sources. Market size is built through value-chain sizing - reconciling supply-side and demand-side estimates - and triangulated with bottom-up and top-down approaches. Every estimate passes multiple levels of expert validation before publication, with each wound dressing segment quantified using the revenue-capture definitions in the table below.
Segment Definition
Segment - Product
Revenue capture definition
Traditional Dressings
Revenue is captured from the sale of traditional wound dressings including gauze, cotton dressings, adhesive bandages, absorbent pads, bandages, and wound packing materials used for basic wound protection and management. It includes sales across hospitals, clinics, pharmacies, and home healthcare settings, while excluding advanced wound dressings, NPWT systems, skin substitutes, biologics, and wound closure devices.
Film Dressings
Revenue is captured from the sale of advanced wound dressings, including foam, hydrocolloid, hydrogel, alginate, collagen, antimicrobial, silicone, transparent film, and superabsorbent dressings used to manage acute and chronic wounds. It includes sales across hospitals, clinics, ambulatory surgical centers, and home healthcare settings, while excluding traditional dressings, NPWT systems, skin substitutes, and wound closure devices.
Estimation Model
Stage
Description
Bottom-Up
Procedure Volume
Modeling
Estimates the wound dressing market by analyzing the prevalence and incidence of acute wounds (surgical wounds, traumatic injuries, burns) and chronic wounds (diabetic foot ulcers, pressure ulcers, venous leg ulcers) across key countries. The model incorporates dressing utilization rates, dressing change frequency, average treatment duration, and care settings (hospitals, ambulatory surgical centers, wound care clinics, and home healthcare) to calculate market revenues.
Top-Down
Revenue
Triangulation
Assesses market revenues generated by leading wound dressing manufacturers such as Smith+Nephew, Mölnlycke Health Care, ConvaTec, Solventum (3M), Coloplast, Medline, and Integra LifeSciences, along with regional players. Company revenues are segmented by traditional and advanced wound dressings using annual reports, product portfolio analysis, financial disclosures, pricing data, and regional sales trends to estimate the total addressable market and segment shares.
Demand-Side
Care-Setting
Modeling
Evaluates purchasing behavior and procurement patterns across hospitals, specialty wound care centers, ambulatory surgical centers, long-term care facilities, pharmacies, and home healthcare providers. The approach incorporates reimbursement policies, institutional purchasing contracts, wound management protocols, adoption of advanced dressings, average selling prices (ASP), and utilization by wound type to validate demand and refine market estimates.
Delivered Customizations
This report has been delivered with the following In-depth customizations
Client Request
Customization Delivered
Value Adds
Product-level pricing, ASP by dressing type (traditional and advanced) across key countries
Detailed ASP benchmarking, pricing trends, and revenue estimates by product category and region.
Supports pricing strategy, revenue forecasting, and competitive positioning decisions.
Competitive landscape and portfolio benchmarking
Company-wise analysis covering product portfolio, market positioning, innovation pipeline, regulatory approvals, and strategic initiatives.
Helps identify market gaps, benchmark competitors, and evaluate partnership or acquisition opportunities.
Country-level demand and procurement analysis
Assessment of wound prevalence, procedure volumes, reimbursement landscape, purchasing patterns, and distribution channels across major markets.
Enables region-specific market entry, sales prioritization, and investment planning.
Frequently Asked Questions About This Report
North America dominated the wound dressing market with the largest revenue share of 45.5% in 2025.
Key factors include the increasing prevalence of diverse wounds, including pressure ulcers and surgical site wounds, coupled with a growing aging population and a rise in traumatic accidents.
Asia Pacific is the fastest-growing region over the forecast period.
The advanced dressings segment dominated the wound dressing market with a market share of 53.2% in 2025.
The chronic wounds segment dominated the wound dressing market with a market share of 59.8% in 2025.
The hospitals segment dominated the wound dressing market with a market share of 45.4% in 2025.
The global wound dressing market size was valued at USD 16.0 billion in 2025 and is estimated at USD 16.7 billion for 2026.
The global wound dressing market is expected to grow at a CAGR of 4.3% from 2026 to 2033, reaching USD 22.4 billion by 2033.
Key players include 33M, Coloplast Corp., Medline, Smith+Nephew, Convatec Inc., Integra LifeSciences Corporation, Ethicon (Johnson & Johnson), Mölnlycke AB, MedWay Group, Cardinal Health, PAUL HARTMANN AG, Datt Mediproducts Private Limited, Advanced Medical Solutions Group plc, B. Braun SE and DermaRite Industries, LLC.
About the Author(s)
Medical Devices Research Team
Healthcare · Medical DevicesThis report was authored by the medical devices research team at Grand View Research - comprising two research analysts, one senior research analyst, and one industry expert - with specialized expertise in the medical devices segment of the healthcare industry. All findings are based on proprietary healthcare databases, executive interviews, and regulatory analysis, subject to internal peer review prior to publication.
Last Updated:
Speak to Analyst

Customize this report to your needs - add regions, segments, or data points, with 20% free customization.
Or view our licence options:


ISO 9001:2015 & 27001:2022 Certified
We are GDPR and CCPA compliant! Your transaction & personal information is safe and secure. For more details, please read our privacy policy.


