
- Home
- »
- Medical Devices
- »
-
Competitive Landscape: Top 20 Contract Sales OrganizationsGVR Report cover
![Competitive Landscape: Top 20 Contract Sales OrganizationsReport]()
Competitive Landscape: Top 20 Contract Sales Organizations
Report Overview
Our healthcare portfolio has been developing since our inception in 2014, wherein we have tracked numerous sub-domains and their R&D activities. We have actively been tracking the life science outsourcing space and have seen the evolution of these players from just a handful to now over 200 companies. To help understand and highlight their development journey, we have made this special study that focuses on the top contract sales organization in the healthcare industry.
Increasing number of CSOs globally
The number of contract sales organizations (CSOs) is growing steadily, and their operating models are evolving rapidly to meet the changing demands of the pharmaceutical industry. These organizations are no longer limited to traditional field sales functions, instead, they are transforming into tech-enabled, multichannel engagement partners. This shift is largely driven by the increasing adoption of virtual healthcare interactions, e-detailing, tele-representation, and advanced CRM platforms. In addition, many CSOs are embracing a hybrid engagement model that blends face-to-face interactions with digital outreach strategies. By leveraging predictive analytics, AI-driven representative targeting, and real-time, on-demand physician engagement, CSOs are optimizing salesforce efficiency and improving engagement outcomes in a more data-driven and scalable manner. For instance, IQVIA has enhanced its CSO capabilities by integrating enriched behavioral and claims data with AI-driven “Integrated Field Alerts.” In a 2024 oncology case study, this approach increased predictive precision by 8%, allowing field teams to identify high-value HCPs more effectively.
Top 20 Contract Sales Organizations
Competitive Landscape: Top 20 Contract Sales Organizations
Market Outlook
Company Categorization
Company Position Matrix
Service Offering Matrix
List of Key CSOs by Region
Company Overview
Key Service Offerings
Financial Reporting
Recent Strategic Developments
SWOT Analysis
In addition, as drug pipelines become more complex, especially in specialty areas like oncology, immunology, neurology, and rare diseases, pharmaceutical companies are demanding that CSOs provide representatives with deeper scientific literacy. Unlike traditional generalist reps, modern CSOs are investing heavily in therapeutic-area-specific training, clinical background screening, and continuous education programs. This is essential to ensure that field teams can hold meaningful conversations with specialists, communicate clinical value, and adhere to promotional compliance. For instance, Syneos Health has built dedicated salesforces for oncology and autoimmune conditions, including access to nurse educators and medical science liaisons. This trend is strengthened by increasing payor scrutiny and physician demand for evidence-backed conversations rather than product pitches. The result is a more qualified, compliant, and clinically relevant sales interface.
Countries such as India, Brazil, Mexico, Vietnam, and parts of Sub-Saharan Africa are witnessing accelerated growth in pharmaceutical sales. However, launching operations in these geographies often involves regulatory, linguistic, and infrastructure challenges. CSOs provide the necessary local knowledge, access to established HCP networks, and fast operational scaling without requiring a physical presence from the sponsor. For instance, in India, domestic and multinational firms regularly engage regional CSOs to deploy trained salesforces across tier-2 and tier-3 cities, helping them reach semi-urban and rural prescriber bases. This approach reduces launch timelines and costs while ensuring cultural relevance and regulatory adherence. As emerging markets continue to expand access to medicines, CSOs remains essential partners for localization and go-to-market execution.
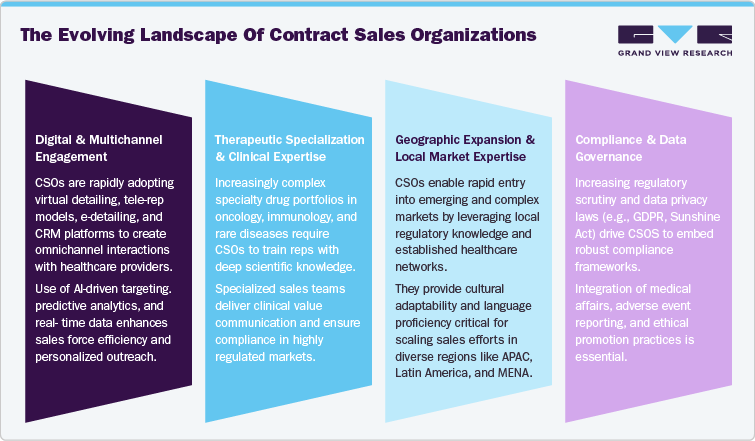
The landscape of pharmaceutical contract sales organizations is undergoing a significant transformation driven by the rapid advancement of digital technologies, shifting commercial strategies, and the increasing complexity of drug portfolios. Traditionally, CSOs operated primarily as external field force providers, offering pharmaceutical companies flexible, scalable sales teams to supplement or replace in-house sales representatives. However, evolving market demands have propelled these organizations to adopt tech-enabled, multichannel engagement models that incorporate virtual detailing, tele-representative solutions, advanced Customer Relationship Management (CRM) systems, and predictive analytics powered by artificial intelligence (AI). These innovations enable CSOs to deliver highly targeted, data-driven outreach that enhances physician engagement and improves overall sales effectiveness. Furthermore, the rising prominence of specialty pharmaceuticals, particularly in areas such as oncology, immunology, and rare diseases, has necessitated deeper scientific and clinical expertise among CSO personnel, driving investment in specialized training and compliance programs.
Competitive Analysis of Contract Sales Organization:

The Contract Sales Organization (CSO) market is defined by intensifying competition among a diverse group of players that bring varying levels of specialization, scale, and digital capability. Global companies like IQVIA and Syneos Health are dominating due to their ability to offer end-to-end commercial solutions, combining deep therapeutic knowledge with advanced digital tools and analytics. Their scale enables them to win large, multinational contracts and support complex product launches. Companies like Thermo Fisher Scientific and Inizio are becoming more assertive in this space by leveraging their operational networks and integrating commercial services with data platforms, though their strategic depth in pure CSO offerings is still maturing.
Company Profile: IQVIA
Headquartered: U.S.
Establishment Year: 2016
Company Overview: IQVIA provides comprehensive support across the drug development and commercialization lifecycle, including clinical trial management, real-world evidence, regulatory affairs, and CSO services. Its CSO service offering stands out due to the integration of predictive analytics, AI-powered targeting, and multi-channel engagement strategies through platforms like Orchestrated Customer Engagement (OCE). With a presence in over 100 countries and a strong client base that includes major pharmaceutical and biotechnology firms, IQVIA enables data-driven field force deployment, tele-representation, and compliant promotional programs tailored for specialty and primary care markets.
Financial Performance
Key Financials
Revenue (in USD Million)
As of dated 31st December
2024
2023
2022
Total Revenue
15,405.0
14,984.0
14,410.0
Operating Income
2,202.0
1,977.0
1,799.0
Working Capital
-1,128.0
-895.0
-597.0
EBIT
1,669.0
1,459.0
1,363.0
EBITA
3,458.0
3,256.0
2,897.0
Net Income
1,373.0
1,358.0
1,091.0
Cash from operating activities
2,716.0
2,149.0
2,260.0
Cash used in investing activities
1,444.0
1,603.0
2,006.0
Income tax paid
301.0
101.0
260.0
Asset Turnover
57.3%
56.2%
56.9%
Quick ratio
70.5%
73.3%
74.1%
Debt/Equity Ratio
324.9%
336.5%
339.5%
Current Ratio
83.8%
86.2%
89.3%
ROE
21.7%
22.2%
18.9%
ROA
5.1%
5.1%
4.3%
Earnings/share
7.6
7.4
5.8
Price to earnings ratio
27.7
48.5
35.5
Service Offerings:

SWOT Analysis:
IQVIA: SWOT Analysis
STRENGTH
WEAKNESS
- IQVIA operates across 100+ countries, offering unmatched reach and deployment capacity for CSO programs.
- Strong use of AI, predictive analytics, and proprietary platforms (e.g., OCE – Orchestrated Customer Engagement) gives IQVIA a clear edge in targeting and engagement.
- IQVIA’s advanced platforms and global operations come at a premium, making them less accessible for smaller biotech or mid-cap pharma clients.
- Integrated service models can sometimes lack agility, making customization slower compared to smaller, specialized CSOs.
OPPORTUNITY
THREAT
- Post-pandemic shift toward virtual engagement plays directly to IQVIA’s digital strengths.
- Complex therapeutic areas require highly trained reps and integrated engagement, which IQVIA can deliver.
- Local CSOs in Asia, LATAM, and MENA offer cheaper models with deep market familiarity.
- Some pharma companies are shifting from integrated providers to a modular outsourcing model, which may bypass IQVIA’s bundled services.
An in-depth analysis shall be provided for below listed 20 Contract Sales Organization:
-
IQVIA, Inc.
-
Syneos Health
-
CMIC HOLDINGS Co., Ltd.
-
Axxelus
-
EPS Corporation
-
UDG Healthcare plc
-
ICON Plc
-
Thermo Fisher Inc.
-
Medpace
-
Celerion
-
LabCorp
-
QFR Solutions
-
MaBico
-
Mednext Pharma Pvt. Ltd.
-
Promoveo Health
-
Peak Pharma Solutions Inc.
-
Celerion
-
MARVECS GmbH
-
GTS Solution
-
Sales Focus, Inc


Customize this report to your needs - add regions, segments, or data points, with 20% free customization.
Or view our licence options:


ISO 9001:2015 & 27001:2022 Certified
We are GDPR and CCPA compliant! Your transaction & personal information is safe and secure. For more details, please read our privacy policy.


