
- Home
- »
- Medical Devices
- »
-
Operating Room Equipment Market Size Report, 2026-2033GVR Report cover

Operating Room Equipment Market (2026 - 2033)
Size, Share & Trends Analysis Report By Product (Anesthesia, Endoscopes, Electro Surgical Devices, Surgical Imaging), By End Use (Hospitals, Ambulatory Surgery Centers), By Region, And Segment Forecast
Market Size, 2025
$50.8BMarket Estimate, 2026
$53.9BMarket Forecast, 2033
$92.8BCAGR, 2026–2033
8.1%Operating Room Equipment Market Summary
The global operating room equipment market size was valued at USD 50.8 billion in 2025 and is projected to grow from USD 53.9 billion in 2026 to USD 92.8 billion by 2033, at a CAGR of 8.1% from 2026 to 2033. The market in North America dominated with a revenue share of 36.0% in 2025. The growth of the market is attributed to factors such as the rising number of hospitals & ambulatory surgery centers, the growing incidence of chronic diseases requiring surgeries, and technological innovations in medical devices.
 Source: Grand View Research, IR Documents, Primary Interviews, Paid DatabasesTo learn more about this report,
 Download Free Sample Report
Key Market Trends & Insights
- By product: Anesthesia segment held the largest market share of 29.6% in 2025.
- By end use: Hospitals & clinics segment held the largest market share of 74.5% in 2025.
Regional Highlights
- Largest regional market: North America (36.0% revenue share, 2025)
- By country: The U.S. held the largest market share in 2025
Market Size & Forecast
- Market size in 2025: USD 50.8 Billion
- Estimated market size in 2026: USD 53.9 Billion
- Projected market size by 2033: USD 92.8 Billion
- CAGR (2026-2033): 8.1%
Three ways to get this report
Buy it, customize it, or ask a question.Ask an Analyst
Analyst response in 1 business day
- AccessReport author, directly
- Reply timeWithin 1 working day
- No sales callDirect answer only
- FormatEmail reply
- CostFree, no cost
Get the Full Report
What the study covers
- FormatsPDF · Excel · Dashboard
- Timeline2026–2033 annual, 2025 base
- Coverage20+ countries, 5 regions
- Companies10+ key players profiled
Customize the Report
20% free customization
- IncludeCountries, segments, points
- TailorTo your product definition
- ExtendDeeper competitor detail
- OrA fully bespoke study
- Turnaround5–10 working days
 To learn more about this report, Download Free Sample Report
In addition, healthcare infrastructure, rising healthcare expenditures, increase in the number of surgeries and rising demand for minimally invasive surgeries are contributing to the growth of the market. The number of surgical procedures performed globally are rising due to the growing and aging population. Surgical care is vital for the management of various medical conditions such as injuries, cardiovascular diseases, cancers, obstructed labor, malignancy, infections, cerebrovascular diseases, mental illnesses, and many others. According to an article published in the MEDIRES journal in January 2024, around 234.2 million surgical procedures are performed globally annually. The changing lifestyle and unhealthy diet have led to an increase in the prevalence of various chronic diseases that increases the demand for surgical procedures worldwide. In addition, injuries account for a large amount of disease burden and are expected to rise in the coming years.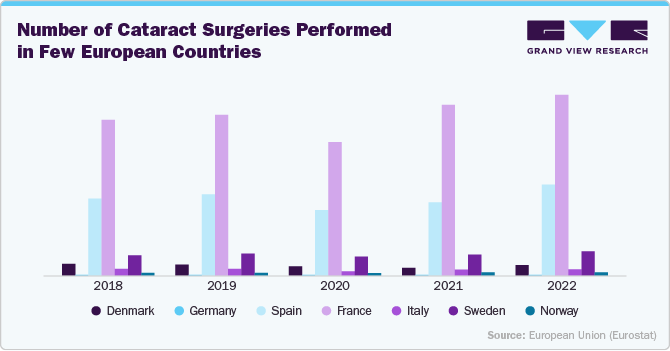 To learn more about this report, Download Free Sample Report
Furthermore, rising investments in the development of operating-room equipment are expected to drive market growth over the forecast period through the launch of innovative products. For instance, in August 2024, Getinge launched two innovative products aimed at enhancing surgical efficiency and safety: the Maquet Corin operating table and the Maquet Ezea surgical light. The launch of these products represents Getinge's commitment to improving operational efficiency in healthcare settings while prioritizing patient safety and ease of use for medical professionals. These innovations are expected to significantly enhance workflow in operating rooms across various clinical environments. Stéphane Le Roy, President Surgical Workflows at Getinge, said:
“Maquet Corin advances crucial aspects for surgical teams. Its flexibility and user-friendly design save time by enhancing communication and cooperation among staff. Additionally, its smart sensor-based safety features protect both OR personnel and equipment.”
Worldwide Establishment of New Operating Rooms/Surgical Centers
Country
Year
Month
Event
U.S.
2025
February
The HCA Florida Mercy Hospital unveiled four new operating rooms to leverage its capacity to serve new patients. Three of these new operating rooms are established for orthopedic procedures, and the fourth room is a state-of-the-art hybrid room designed for cardiac and vascular procedures.
Philippines
2025
February
The Manila Doctors Hospital upgraded its existing operating rooms and expanded its capacity by constructing four new operating rooms, bringing the total number of ORs to 14.
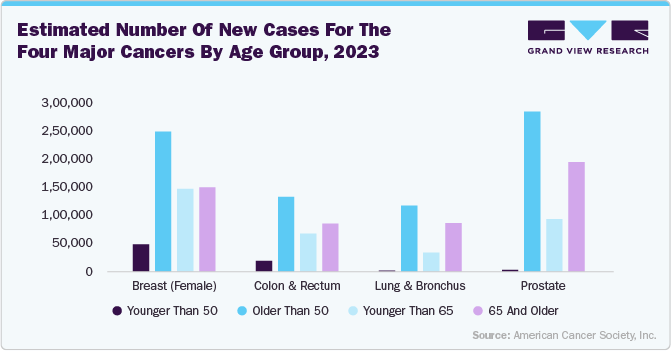
Furthermore, according to the U.S. Department of Health and Human Services, it was estimated, an estimated 2,001,140 new cases of cancer will be diagnosed in the U.S. and 611,720 people will die from the disease in 2024. In the U.S., breast cancer cases affect women at a rate of 264,000 each year, while cases in men stand at around 2,400 as per The Centers for Disease Control and Prevention (CDC). The number of surgeries being performed to treat these diseases is expected to result in high demand for operating room equipment.
 To learn more about this report, Download Free Sample Report
Moreover, governments and private organizations are investing in healthcare infrastructure improvements, including operating room technologies. These funding initiatives aim to modernize healthcare facilities and support the adoption of OR equiment that can be used to perform complex surgical procedures. In January 2025, VitVio, a London-based healthcare technology startup, successfully raised USD 2.05 million in pre-seed funding aimed at developing AI-powered operating rooms for hospitals. This funding round was led by LDV Capital, with participation from Bek Ventures, Tiny Supercomputer Investment Company, and various angel investors. The investment reflects growing confidence in the potential of artificial intelligence to enhance surgical efficiency and patient outcomes.
The industry is driven by the growing pressure on hospitals to manage costs while delivering high-quality care. Integrated operating room solutions present substantial cost-saving opportunities by enhancing resource utilization, shortening operation times, and decreasing surgical complications. This economic motivation encourages hospitals to invest in advanced technological devices. Solutions such as ENDOALPHA from Olympus Corporation contribute to reduced surgical durations, enhanced patient safety, and expedited recovery. As the complexity of advanced surgeries escalates, hospitals are increasingly adopting technological innovations in the operating room, including innovative and advanced surgical instruments, digital imaging diagnostics, robotic 3D imaging, surgical robots, and virtual reality technologies.
Market Dynamics
The operating room equipment market is experiencing steady growth, driven by the rising volume of surgical procedures, increasing prevalence of chronic diseases, expanding healthcare infrastructure, and growing demand for advanced surgical care. Operating room equipment plays a critical role in enabling safe, efficient, and precise surgical interventions by supporting a wide range of procedures across specialties including general surgery, orthopedics, cardiovascular surgery, neurosurgery, gynecology, and minimally invasive surgery. The growing burden of age-related conditions, trauma cases, cancer, and cardiovascular disorders, coupled with an expanding elderly population requiring surgical treatment, is significantly contributing to market expansion.
The number of surgical procedures performed globally are on a rise owing to the growing and aging population. Surgical care is vital for management of various medical conditions such as injuries, cardiovascular diseases, cancers, obstructed labor, malignancy, infections, cerebrovascular diseases, mental illnesses and many others. According to an article published in the MEDIRES journal in January 2024, around 234.2 million surgical procedures are performed globally annually. The changing lifestyle and unhealthy diet have led to an increase in the prevalence of various chronic diseases that increase the demand for surgical procedures worldwide. In addition, injuries account for the large amount of disease burden and are expected to rise in the coming years. The chart below highlights the number of cataract surgeries performed across selected European countries, reflecting the growing demand for ophthalmic surgical procedures. Higher surgical volumes are contributing to increased utilization of operating room equipment, supporting market growth across the region.
The volume of cataract surgeries across the European Union remained high in 2023, with just over 5.0 million procedures performed, equivalent to 1,118 surgeries per 100,000 population. The large number of procedures reflects the growing burden of age-related cataracts driven by Europe's aging population, increasing awareness of vision restoration, and widespread availability of advanced ophthalmic surgical services.
Countries such as Portugal, Spain, Estonia, Sweden, Ireland, Finland, and Malta perform nearly all cataract procedures as day cases, whereas Slovenia, Czechia, Italy, Germany, and the Netherlands predominantly utilize outpatient treatment models. Conversely, Romania and Bulgaria continue to rely more heavily on inpatient admissions, suggesting opportunities to improve healthcare efficiency through greater adoption of ambulatory surgical pathways.
Cataract Surgery Statistics in Europe, 2023
Parameter
Statistics / Findings
Total cataract surgeries performed
Over 5.0 million procedures
EU average surgery rate
1,118.0 per 100,000 population
Highest surgery rate
Luxembourg - 1,627.3 per 100,000
Second highest
France - 1,598.7 per 100,000
Third highest
Estonia - 1,506.8 per 100,000
Lowest surgery rate
Romania - 389.4 per 100,000
Second lowest
Poland - 628.8 per 100,000
Third lowest
Bulgaria - 745.8 per 100,000
In-patient procedures
6.4%
Day-patient procedures
55.8%
Out-patient procedures
37.8% (24 reporting countries)
The operating room equipment market faces restraint due to the high capital investment and operational costs associated with establishing and maintaining advanced oncology infrastructure. Cancer treatment facilities require significant expenditure on radiotherapy systems, surgical equipment, molecular diagnostic laboratories, imaging technologies, and specialized oncology professionals, making them difficult to develop and sustain, particularly in low- and middle-income regions. In addition, the high cost of innovative therapies, including immunotherapies, targeted therapies, and CAR-T cell therapies, can limit patient access and increase the financial burden on healthcare systems. In November 2024, Stryker launched the Oculan Lighting Platform, a next-generation surgical lighting solution designed to enhance visualization and illumination in operating rooms. The platform incorporates advanced technologies such as Fly Eye optical architecture, Auto Lux, Microspot, and SHD Mode to improve tissue differentiation, minimize shadows and glare, and support greater surgical precision.
The increasing adoption of AI-enabled operating room platforms that automate clinical documentation, operative reporting, workflow coordination, and data analytics presents a significant growth opportunity for the operating room equipment market. Intelligent OR ecosystems capable of integrating surgical devices, patient monitoring systems, imaging equipment, and hospital information systems can improve operating room efficiency, reduce clinician administrative workload, enhance documentation accuracy, and support data-driven decision-making.In June 2026, Moon Surgical and Uncovr [SK1] deployed AI-powered automated operative reporting on the Maestro platform across the first 20 clinical laparoscopic procedures. The integration generated structured operative reports from intraoperative video within minutes, enhancing documentation efficiency, workflow optimization, and reimbursement accuracy while validating AI-enabled intelligent operating room capabilitiesMarket Concentration & Characteristics
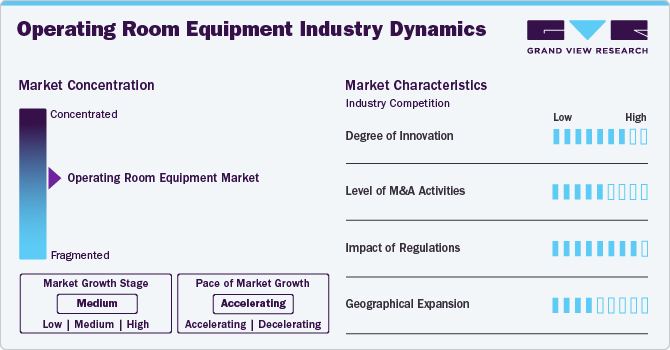
The chart below illustrates the relationship between industry concentration, industry characteristics, and industry participants. The x-axis represents the level of industry concentration, ranging from low to high. The y-axis represents various industry characteristics, including industry competition, degree of innovation, impact of regulations, level of merger & acquisition activities, and geographic expansion.
The degree of innovation is notably high, driven by continuous technological advancements, growing patient demand for minimally invasive procedures, and the need for improved diagnostic accuracy and therapeutic outcomes. Companies are investing heavily in research and development to introduce equipment integrated with digital solutions. For instance, in April 2024, the MOLLI OncoPen is a minimal invasive surgical tool designed by MOLLI Surgical to enhance precision in breast cancer surgery. It resembles a pen and integrates with the MOLLI 2 System. The OncoPen helps surgeons accurately target and remove cancerous lesions by using a small MOLLI Marker placed near the tumor beforehand. During surgery, it offers real-time 3D guidance on the MOLLI Tablet to locate the lesion precisely.
 To learn more about this report, Download Free Sample Report
Several key market players are devising business growth strategies in the form of mergers and acquisitions. Through M&A activity, these companies can expand their business. For instance, In April 2024, Stryker Corporation announced the completion of its acquisition of mfPHD. This strategic move is aimed at enhancing Stryker's offerings in modular wall systems for healthcare facilities, specifically hospitals and ambulatory surgery centers. The acquisition aligns with Stryker's broader enterprise strategy to expand its product offerings while emphasizing turn-key operating room (OR) initiatives.
The industry is regulated by a variety of national and international standards, such as those set by the FDA in the U.S. and the EMA in Europe. Manufacturers must demonstrate compliance with safety and performance criteria, often through clinical testing, to ensure their medical devices are safe and effective before they can be marketed.
Several market players are expanding their business by entering new geographical regions to strengthen their market position and expand their product portfolio. In June 2023, STERIS announced its acquisition of surgical instrumentation assets from Becton, Dickinson and Company (BD) for a total consideration of USD 540 million. This strategic move is aimed at expanding STERIS's portfolio in the healthcare sector, particularly in surgical instruments, which are critical for various medical procedures.
Analyst Perspective
The operating room equipment market is experiencing growth, driven by the increasing volume of surgical procedures worldwide, the rising adoption of minimally invasive and robotic-assisted surgeries, and continuous investments in modern healthcare infrastructure. Hospitals and ambulatory surgical centers are increasingly upgrading to integrated operating rooms equipped with advanced surgical imaging, anesthesia workstations, patient monitoring systems, and digital workflow solutions to improve clinical efficiency and patient outcomes. In addition, the growing demand for hybrid operating rooms, AI-enabled surgical technologies, and real-time intraoperative imaging is further fueling technological innovation across the market.
Product Insights
Based on product, the anesthesia segment led the market with the largest revenue share of 29.6% in 2025. Anaesthesia is essential for surgeries across all disciplines-from general and cardiovascular surgery to orthopaedics, oncology, and neurosurgery. Every operating room must be equipped with anaesthesia workstations, ventilators, gas delivery systems, and patient monitoring tools. Moreover, a growth in the number of Ambulatory Surgical Centers (ASCs) and outpatient surgeries has increased the demand for compact and portable anaesthesia systems. Furthermore, companies are launching new products to expand their global footprint. For instance, in April 2025, Dräger launched the Atlan A100 anesthesia workstation in India, aimed at enhancing perioperative care. This system incorporates advanced lung protective ventilation, low-flow anesthesia capabilities, and measures to prevent infections, representing a notable advancement in anesthesia technology for healthcare providers.
The endoscopes segment is expected to grow at the fastest CAGR over the forecast period. Increasing awareness regarding earlier detection of diseases through minimally invasive surgical procedures, the adoption of various distribution strategies, and the growing prevalence of chronic disorders are some of the major factors driving market growth. Furthermore, technological advancements significantly impacted the field of disposable endoscopic devices, driving innovation and improving patient care.
These advancements have led to developing more advanced and sophisticated disposable endoscopes, offering enhanced imaging capabilities, improved maneuverability, and ease of use. For instance, in September 2024, Olympus Corporation received U.S. FDA 510(k) approval for its CADDIE computer-aided detection (CADe) device, a cloud-based AI technology developed to help gastroenterologists during colonoscopy procedures to detect colorectal polyps.
End Use Insights
Based on end use, the hospitals & clinics segment led the market with the largest revenue share of 74.5% in 2025, owing to its wide applications in ORs. Hospitals are emphasizing upgrading operation theatres because they are one of the greatest revenue-generating sources. Growth is also anticipated to be fueled by the rising geriatric population, increase in the burden of diseases, increase in healthcare expenditures, demand for hybrid operating rooms, and rising investments in infrastructure and cutting-edge technologies for effective results.
 To learn more about this report, Download Free Sample Report
For instance, in January 2023, the Galilee Medical Center announced the opening of a smart room for managing inventory in OR through a partnership between Autonomi Company and Israeli group purchasing organization Sarel. Furthermore, in February 2022, Canada’s Alberta province government invested USD63.5 million for 11 new operating rooms at Calgary's Foothills hospital. The 11 new operating rooms are in addition to the 32 existing operating rooms at the northwest Calgary hospital. They will allow up to 7,000 more surgeries each year.
The ambulatory surgical centers segment is expected to grow at the fastest CAGR over the forecast period. Ambulatory surgery is being increasingly performed in developed countries. The shortage of beds in hospitals and scarce economic resources are expected to boost the growth of this segment. However, the high initial and maintenance cost of OR equipment is hampering segment growth. The development of various medical devices that aid in performing minimally invasive surgeries is allowing physicians to carry out a greater number of surgical procedures on a day-care basis. The availability of technologically advanced I-ORs has contributed largely to the improvement of day-care surgery.
Regional Insights
North America dominated the operating room equipment market with the largest revenue share of 36.0% in 2025. This growth is attributed to the increasing demand for surgical automation. Major factors attributed to the market growth are the rise in demand for efficient healthcare services, an increase in the need to reduce healthcare expenditure, and effective EHR implementation by healthcare organizations. Furthermore, the presence of established players in the market, technologically advanced HCIT, and funding to improve OR infrastructure are other factors propelling the market growth.
 To learn more about this report, Download Free Sample Report
U.S. Operating Room Equipment Market Trends
The market in the U.S. held the largest share in the North America region in 2025 due to technological advancements and recent approvals received for technological devices. Manufacturers are investing in R&D to obtain approvals for new products for commercialization. For instance, in October 2024, Olympus Corporation announced a strategic partnership with Proximie, a global health technology company, aimed at revolutionizing the digitization of operating rooms. This collaboration is significant as it seeks to enhance patient care and improve clinical practices through advanced telecollaboration technologies.
Europe Operating Room Equipment Market Trends
Europe operating room equipment market is expected to register considerable growth during the forecast period. UK, Germany, Italy, France, and Spain are the main markets in this region. The increasing geriatric population in developed countries, such as the UK, Germany, Italy, and France, is one of the factors expected to drive growth over the forecast period.
Germany operating room equipment market is anticipated to register a significant growth rate during the forecast period. Factors such as increasing adoption of minimally invasive surgeries, introduction of advanced products, and other business activities, such as mergers & acquisitions, are expected to contribute to growth of the market in Germany. For instance, in March, 2024, Eurazeo announced that it had signed an agreement to sell all the share capital of Peters Surgical to Advanced Medical Solutions Group plc (AMS). The agreement entails a complete transfer of ownership of Peters Surgical, which specializes in surgical products and has a strong market presence in Europe and beyond. The sale is part of Eurazeo's strategy to optimize its portfolio by divesting from certain assets while focusing on others that align more closely with its long-term investment goals.
Asia Pacific Operating Room Equipment Market Trends
Asia Pacific operating room equipment market is anticipated to be the significantly growing region. Healthcare spending in the region has significantly increased, enabling investments in advanced medical technologies and improvements in infrastructure. This trend is particularly evident in countries such as China and India, where rising economic strength and government initiatives are promoting the adoption of operating room equipment. The integration of advanced technologies such as robotic surgery and telemedicine further supports this growth by improving surgical precision and reducing recovery times.
Japan operating room equipment market held the largest share in 2024. This is attributed to technological advancements, rising inclination for minimally invasive surgeries, increasing penetration for treatment & diagnosis, investment by global players, ongoing R&D, and presence of key manufacturers. For instance, in November 2024, Stille AB launched the imagiQ3, a next-generation C-arm table, during the Radiological Society of North America (RSNA) conference. This innovative product represents a significant advancement in surgical imaging technology, building on the legacy of its predecessors while introducing new features designed to enhance operational efficiency and patient safety.
Latin America Operating Room Equipment Market Trends
Latin America operating room equipment market is expected to register significant growth during the forecast period. The primary driver is the increasing demand for advanced healthcare technologies, which is spurred by a growing prevalence of chronic diseases and a rising number of surgical procedures across the region. As hospitals strive to improve patient outcomes and operational efficiency, they are increasingly adopting operating room products that facilitate better communication, data management, and workflow optimization. Furthermore, government initiatives aimed at improving healthcare services and funding for health information technology (HCIT) infrastructure are also contributing to the robust development of the ORI market in Latin America.
Brazil operating room equipment market accounted for a major share of Latin America in 2024. A large population suffering from chronic diseases, coupled with rapid development of technologically advanced devices, is expected to increase the market penetration of operating room equipment in the coming years. In September 2024, Purple Surgical, launched its operations in Brazil. This strategic move is aimed at expanding the company's presence in the Latin American market, which is increasingly recognized for its growing healthcare sector and demand for high-quality medical supplies.
Middle East And Africa Operating Room Equipment Market Trends
MEA operating room equipment market is expected to register considerable growth during the forecast period. There is a significant increase in healthcare expenditure across the region, with countries such as Kuwait, Saudi Arabia, and the UAE investing heavily in advanced healthcare technologies to improve patient outcomes and operational efficiency. This investment is largely fueled by a rising geriatric population and an increasing prevalence of chronic diseases, which necessitate more surgical procedures.
The operating room equipment market in UAEis experiencing significant growth during the forecast period. This growth is primarily driven by the growing product innovations and improvements. For instance, in January 2025, RAIN Technology ME LTD announced a significant leadership transition with the appointment of Abbes Seqqat as the new CEO. This change is part of RAIN's strategic efforts to enhance its presence in the UAE and globally launch its innovative surgical voice assistant, Orva. Seqqat succeeds Nithya Thadani, who has led the company since 2017 and will continue to contribute as a member of the Board of Directors.
Key Operating Room Equipment Company Insights
The market is fairly competitive owing to the presence of a large number of multinational as well as local market players. The market players are adopting various strategies, such as partnerships & collaborations, regional expansion, and service launches, to gain higher market shares. For instance, in August 2022, Affera, Inc. was acquired by Medtronic, an international leader in healthcare technology. Similarly, in December 2021, Baxter International Inc. announced it has completed its acquisition of Hillrom. Some of the prominent players in the operating room equipment market include:
Key Operating Room Equipment Companies:
The following are the leading companies in the operating room equipment market.
- Koninklijke Philips N.V
- Medtronic
- Getinge AB
- Stryker Corporation
- Siemens Healthineers AG
- GE HealthCare
- Steris
- Skytron, LLC
- Drägerwerk AG & Co. KGaA,
- Baxter International Inc.
Competitive Benchmarking
Category
Operating Strategies
Competitive Edge
Weakness
Established Players (e.g., Koninklijke Philips N.V., Medtronic, Getinge AB, Stryker Corporation, Siemens Healthineers AG, GE HealthCare, Steris, Baxter International Inc., Olympus Corporation, Karl Storz)
- Focus on expanding comprehensive operating room portfolios through continuous product innovation, strategic acquisitions, and partnerships with healthcare providers. Invest in integrated operating room solutions, surgical imaging, endoscopy, anesthesia systems, patient monitoring, operating tables and lights, and AI-enabled digital operating room technologies to improve surgical efficiency and patient outcomes.
- Strong global presence, diversified product portfolios, extensive hospital and healthcare provider relationships, well-established distribution networks, strong R&D investments, and significant regulatory expertise. Their ability to provide end-to-end operating room solutions, long-term service agreements, and integrated digital platforms strengthens customer loyalty and market leadership.
- High R&D and manufacturing costs, lengthy regulatory approval processes, dependence on hospital capital expenditure and procurement cycles, and increasing pricing pressure from healthcare providers. Large organizational structures also reduce flexibility in responding quickly to emerging technologies and niche market demands.
Specialized Players (e.g., Skytron, LLC and Drägerwerk AG & Co. KGaA)
- Focus on specialized operating room equipment including surgical tables, operating room lights, anesthesia workstations, patient monitoring systems, and operating room integration solutions. Emphasize product innovation, ergonomic designs, workflow optimization, equipment reliability, and customized solutions for hospitals and surgical centers.
- Strong expertise in niche operating room technologies, faster product innovation, high product quality, customized solutions, and strong customer service. Their focused portfolios enable them to develop specialized equipment that addresses specific clinical and operational requirements.
- Smaller global footprint, narrower product portfolios, and comparatively limited financial resources than diversified multinational competitors. Greater dependence on specific product categories and regional distribution networks limit scalability and reduce competitiveness in large integrated operating room projects.
Recent Developments
-
In May 2025, the Olympus Corporation, a global medical technology company, has recently demonstrated its new AI endoscopy solution, OLYSENSE Platform, at the Digestive Disease Week (DDW) annual meeting. The platform features the CADDIE computer-aided detection device, which uses cloud-based AI technology to aid gastroenterologists in suspected polyp detection during colonoscopy procedures.
-
In October 2025, Olympus Corporation announced that it has received CE (Conformité Européenne) approval for three cloud-based artificial intelligence (AI) medical devices. This approval is crucial as it allows these devices to be marketed and used within the European Economic Area, ensuring they meet stringent safety and efficacy standards set by European regulators.
-
In January 2025, JUNE MEDICAL and Aspen Surgical announced a strategic partnership aimed at expanding access to the Galaxy II surgical retractor system across the U.S. market. This collaboration is significant as it combines JUNE MEDICAL's innovative medical devices with Aspen Surgical's extensive distribution network, enhancing the availability of advanced surgical tools in hospitals and surgery centers nationwide.
-
In July 2024, Philips collaborated with the University of Zurich to develop a Visual Patient Avatar to address cognitive overload in operating rooms, enhancing patient safety. This innovative tool displays vital information clearly, helping anesthesiology providers make quicker, more informed decisions, ultimately reducing the risk of errors and improving situational awareness during procedures.
-
In March 2023, Baystate Medical Center (BMC) announced the launch of its latest operating rooms and interventional suites, which are equipped with advanced technological features aimed at enhancing surgical precision and patient care. This initiative is part of BMC's ongoing commitment to improving healthcare delivery through innovation.
Operating Room Equipment Market Report Scope
Report Attribute
Details
Market size in 2025
USD 50.8 billion
Estimated market size in 2026
USD 53.9 billion
Projected market size by 2033
USD 92.8 billion
Growth rate
CAGR of 8.1% from 2026 to 2033
Historical data
2021 - 2025
Forecast period
2026 - 2033
Quantitative units
Revenue in USD billion and CAGR from 2026 to 2033
Report coverage
Revenue forecast, company ranking, competitive landscape, growth factors, and trends
Segments covered
Product, end use, and region
Regional scope
North America; Europe; Asia Pacific; Latin America; MEA
Country scope
U.S.; Canada; Mexico; Germany; UK; France; Italy; Spain; Norway; Denmark; Sweden; China; Japan; India; South Korea; Australia; Thailand; Brazil; Argentina; Saudi Arabia; South Africa; UAE; Kuwait
Key companies profiled
Koninklijke Philips N.V., Medtronic, Getinge AB, Stryker Corporation, Siemens Healthineers AG, GE HealthCare, Steris, Skytron, LLC, Drägerwerk AG & Co. KGaA, Baxter International Inc., Olympus Corporation, Karl Storz.
Customization scope
Free report customization (equivalent up to 8 analysts' working days) with purchasse. Addition or alteration to country, regional & segment scope.
Pricing and purchase options
Avail customized purchase options to meet your exact research needs. Explore purchase options
Global Operating Room Equipment Market Report Segmentation
This report forecasts revenue growth at global, regional, and country levels and provides an analysis on industry trends in each of the sub segments from 2021 to 2033. For this study, Grand View Research Inc. has segmented the operating room equipment market report based on product, end use, and region:
 To learn more about this report, Download Free Sample Report
-
Product Outlook (Revenue, USD Million, 2021 - 2033)
-
Anaesthesia
-
Endoscopes
-
Electro Surgical Devices
-
Surgical Imaging
-
OR Tables
-
OR Lights
-
Patient Monitoring
-
Others
-
-
End Use Outlook (Revenue, USD Million, 2021 - 2033)
-
Hospitals
-
Ambulatory Surgery Centers
-
-
Regional Outlook (Revenue, USD Million, 2021 - 2033)
-
North America
-
U.S.
-
Canada
-
Mexico
-
-
Europe
-
Germany
-
UK
-
Spain
-
Italy
-
France
-
Denmark
-
Norway
-
Sweden
-
-
Asia Pacific
-
Japan
-
China
-
India
-
Australia
-
Thailand
-
South Korea
-
-
Latin America
-
Brazil
-
Argentina
-
-
MEA
-
South Africa
-
Saudi Arabia
-
UAE
-
Kuwait
-
-
Research Methodology
The operating room equipment market figures in this report are based on a proven research process that combines executive interviews with secondary research from proprietary databases, company filings, and recognized regulatory and institutional sources. Market size is built through value-chain sizing - reconciling supply-side and demand-side estimates - and triangulated with bottom-up and top-down approaches. Every estimate passes multiple levels of expert validation before publication, with each operating room equipment segment quantified using the revenue-capture definitions in the table below.
Segment Definition
Segment - Product
Revenue capture definition
Anesthesia
This segment includes anesthesia machines, anesthesia workstations, ventilators, vaporizers, gas delivery systems, and associated monitoring equipment used to administer and regulate anesthetic agents during surgical procedures.
Endoscopes
The endoscopes segment comprises rigid and flexible endoscopic systems used for minimally invasive diagnostic and therapeutic procedures. It includes endoscopes, camera systems, visualization processors, light sources, and related accessories that enable surgeons to visualize internal organs.
Electro Surgical Devices
This segment includes electrosurgical generators, pencils, electrodes, bipolar and monopolar instruments, vessel sealing devices, and radiofrequency-based surgical systems.
Surgical Imaging
The surgical imaging segment includes intraoperative imaging systems such as mobile C-arms, hybrid operating room imaging equipment, fluoroscopy systems, surgical navigation systems, and other real-time imaging technologies.
OR Tables
Operating room (OR) tables include electrically or hydraulically powered surgical tables designed to support and position patients during a wide variety of surgical procedures.
OR Lights
This segment includes ceiling-mounted, wall-mounted, and mobile surgical lighting systems that provide bright, shadow-free illumination of the operative field.
Patient Monitoring
The patient monitoring segment comprises multiparameter monitoring systems that continuously measure and display vital physiological parameters such as electrocardiography (ECG), blood pressure, oxygen saturation (SpO₂), respiratory rate, temperature, cardiac output, and end-tidal carbon dioxide (EtCO₂).
Others
This category includes additional operating room equipment such as surgical booms, operating room integration systems, medical-grade display monitors, insufflators, suction and smoke evacuation systems, fluid management devices, patient warming systems, surgical power tools, and other accessories that support efficient operating room workflow and surgical performance.
Segment - End Use
Revenue capture definition
Hospitals & Clinics
Hospitals and clinics represent the largest end-use segment, utilizing comprehensive operating room equipment for inpatient and outpatient surgical procedures across specialties such as general surgery, orthopedics, cardiovascular surgery, neurosurgery, gynecology, urology, and oncology.
Ambulatory Surgical Centers (ASCs)
Ambulatory Surgical Centers (ASCs) are specialized healthcare facilities that perform same-day surgical procedures without requiring overnight hospitalization. These centers utilize compact, efficient, and technologically advanced operating room equipment optimized for minimally invasive and outpatient surgeries
Estimation Model
Research Methodology
Market estimates were developed through a combination of secondary research, primary interviews, company financial analysis, regulatory publications, hospital procurement data, and validation with surgeons, anesthesiologists, operating room managers, hospital administrators, medical device manufacturers, distributors, and industry experts.
Market Sizing Approach
The market size was estimated using a triangulation approach comprising surgical procedure volumes, operating room infrastructure, healthcare expenditure, hospital capital investments, equipment replacement cycles, average selling prices (ASPs), and company revenue benchmarking to validate the overall market value.
Procedure Volume Model
The addressable market was estimated by evaluating the annual volume of surgical procedures across major specialties, including general surgery, orthopedic, cardiovascular, neurosurgical, gynecological, urological, and minimally invasive procedures. The number of operating rooms, equipment utilization rates, and replacement demand were then used to estimate product adoption across healthcare facilities.
Revenue Estimation Model
Market revenue was calculated using the installed base of operating room equipment, annual procurement volumes, average selling prices (ASPs), maintenance and service revenues, equipment replacement cycles, and purchasing patterns across hospitals, ambulatory surgical centers (ASCs), and specialty clinics.
Company Revenue Validation
The estimated market size was cross validated using publicly available revenues, product portfolios, annual reports, investor presentations, regional sales, procurement contracts, and strategic initiatives of leading operating room equipment manufacturers and healthcare technology providers.
Forecast Development
Forecasts were developed based on increasing surgical procedure volumes, rising adoption of minimally invasive and robotic-assisted surgeries, expansion of healthcare infrastructure, technological advancements in integrated operating rooms, growing demand for hybrid operating rooms, increasing healthcare expenditure, and replacement of legacy surgical equipment with advanced digital systems.
Segmentation Methodology
Market segmentation was established using a weighted index based on product type, surgical procedure volume, equipment utilization rates, healthcare facility type, procurement trends, pricing patterns, technological adoption, and regional healthcare infrastructure and investment levels.
Scope & Assumptions
The market is measured in USD and includes operating room equipment used across hospitals, clinics, and ambulatory surgical centers worldwide. The study covers anesthesia equipment, endoscopes, electrosurgical devices, surgical imaging systems, operating room tables, operating room lights, patient monitoring systems, and other supporting operating room equipment. Market estimates include revenues generated from new equipment sales and associated service revenues where applicable, across both developed and emerging healthcare markets.
Customization Table
Client Request
Customization Delivered
Value Adds
Operating Room Infrastructure
& Surgical Capacity AnalysisDeveloped a comprehensive assessment of global operating room infrastructure, surgical procedure volumes, healthcare facility expansion, and accessibility to advanced operating room equipment across developed and emerging markets. The study evaluated operating room capacity, equipment penetration, capital investment trends, procurement patterns, and regional disparities in surgical infrastructure.
Enables stakeholders to identify high-growth regions, evaluate operating room infrastructure gaps, prioritize capital investments, and develop strategies to improve surgical capacity, operational efficiency, and patient access to advanced surgical care.
Surgical Workflow & Equipment Utilization Analysis
Conducted an end-to-end evaluation of the surgical workflow, including preoperative preparation, anesthesia management, intraoperative imaging, patient monitoring, surgical visualization, and postoperative recovery. The study also assessed equipment utilization rates, replacement cycles, procurement strategies, hospital purchasing behavior, and adoption trends across hospitals and ambulatory surgical centers (ASCs).
Provides actionable insights for optimizing operating room efficiency, improving equipment utilization, reducing procedure turnaround time, enhancing patient safety, and supporting strategic purchasing and investment decisions for healthcare providers and medical device manufacturers.
Advanced Operating Room Technologies & Competitive Assessment
Conducted an in-depth evaluation of emerging operating room technologies, including AI-enabled operating room integration systems, robotic-assisted surgery platforms, hybrid operating rooms, advanced surgical imaging, smart patient monitoring, and connected digital operating room solutions. The study benchmarked technology adoption, product innovation, regulatory developments, competitive positioning, and investment trends across leading operating room equipment manufacturers.
Helps stakeholders identify technology investment opportunities, accelerate adoption of next-generation operating room solutions, strengthen competitive positioning, and capitalize on emerging trends in digital surgery, integrated operating rooms, and intelligent surgical ecosystems.
Frequently Asked Questions About This Report
Some key players operating in the operating room equipment market include Koninklijke Philips N.V, Medtronic, Getinge AB, Stryker, Siemens Healthineers AG, GE HealthCare, Steris, Skytron, LLC, Drägerwerk AG & Co. KGaA, and Baxter International Inc.
The growth of the market is attributed to factors such as the rising number of hospitals & ambulatory surgery centers, the growing incidence of chronic diseases requiring surgeries, and technological innovations in medical devices.
Asia Pacific is the fastest-growing region over the forecast period due to expanding healthcare infrastructure, increasing surgical procedure volumes, rising investments in hospital modernization, and growing adoption of advanced operating room technologies.
Hospitals & clinics segment dominated with a share of 74.5% in 2025 due to the high volume of surgical procedures, increasing investments in operating room infrastructure, and widespread adoption of advanced surgical equipment, while ASCs is the fastest growing segment.
The global operating room equipment market size was valued at USD 50.8 billion in 2025 and is estimated at USD 53.9 billion for 2026.
The global operating room equipment market is expected to grow at a CAGR of 8.1% from 2026 to 2033, reaching USD 92.8 billion by 2033.
The anesthesia devices segment dominated the global operating room equipment market with a share of 29.6% in 2025 due to their essential role in ensuring safe anesthesia delivery and patient monitoring across a wide range of surgical procedures, while endoscopes is the fastest growing segment.
North America dominated with a 36.0% revenue share in 2025.
About the Author(s)
Medical Devices Research Team
Healthcare · Medical DevicesThis report was authored by the medical devices research team at Grand View Research - comprising two research analysts, one senior research analyst, and one industry expert - with specialized expertise in the medical devices segment of the healthcare industry. All findings are based on proprietary healthcare databases, executive interviews, and regulatory analysis, subject to internal peer review prior to publication.
Last Updated:
Speak to Analyst

Customize this report to your needs - add regions, segments, or data points, with 20% free customization.
Or view our licence options:


ISO 9001:2015 & 27001:2022 Certified
We are GDPR and CCPA compliant! Your transaction & personal information is safe and secure. For more details, please read our privacy policy.


