
- Home
- »
- Next Generation Technologies
- »
-
Virtual Reality Market Size And Share Report, 2026-2033GVR Report cover

Virtual Reality Market (2026 - 2033)
Size, Share & Trends Analysis Report By Device (HMD, GTD, PDW), By Technology (Semi & Fully Immersive, Non-immersive), By Component (Hardware, Software), By Application (Aerospace & Defense, Consumer, Healthcare), By Region, And Segment Forecasts
Market Size, 2025
$129.0BMarket Estimate, 2026
$164.5BMarket Forecast, 2033
$901.2BCAGR, 2026–2033
27.5%Virtual Reality Market Summary
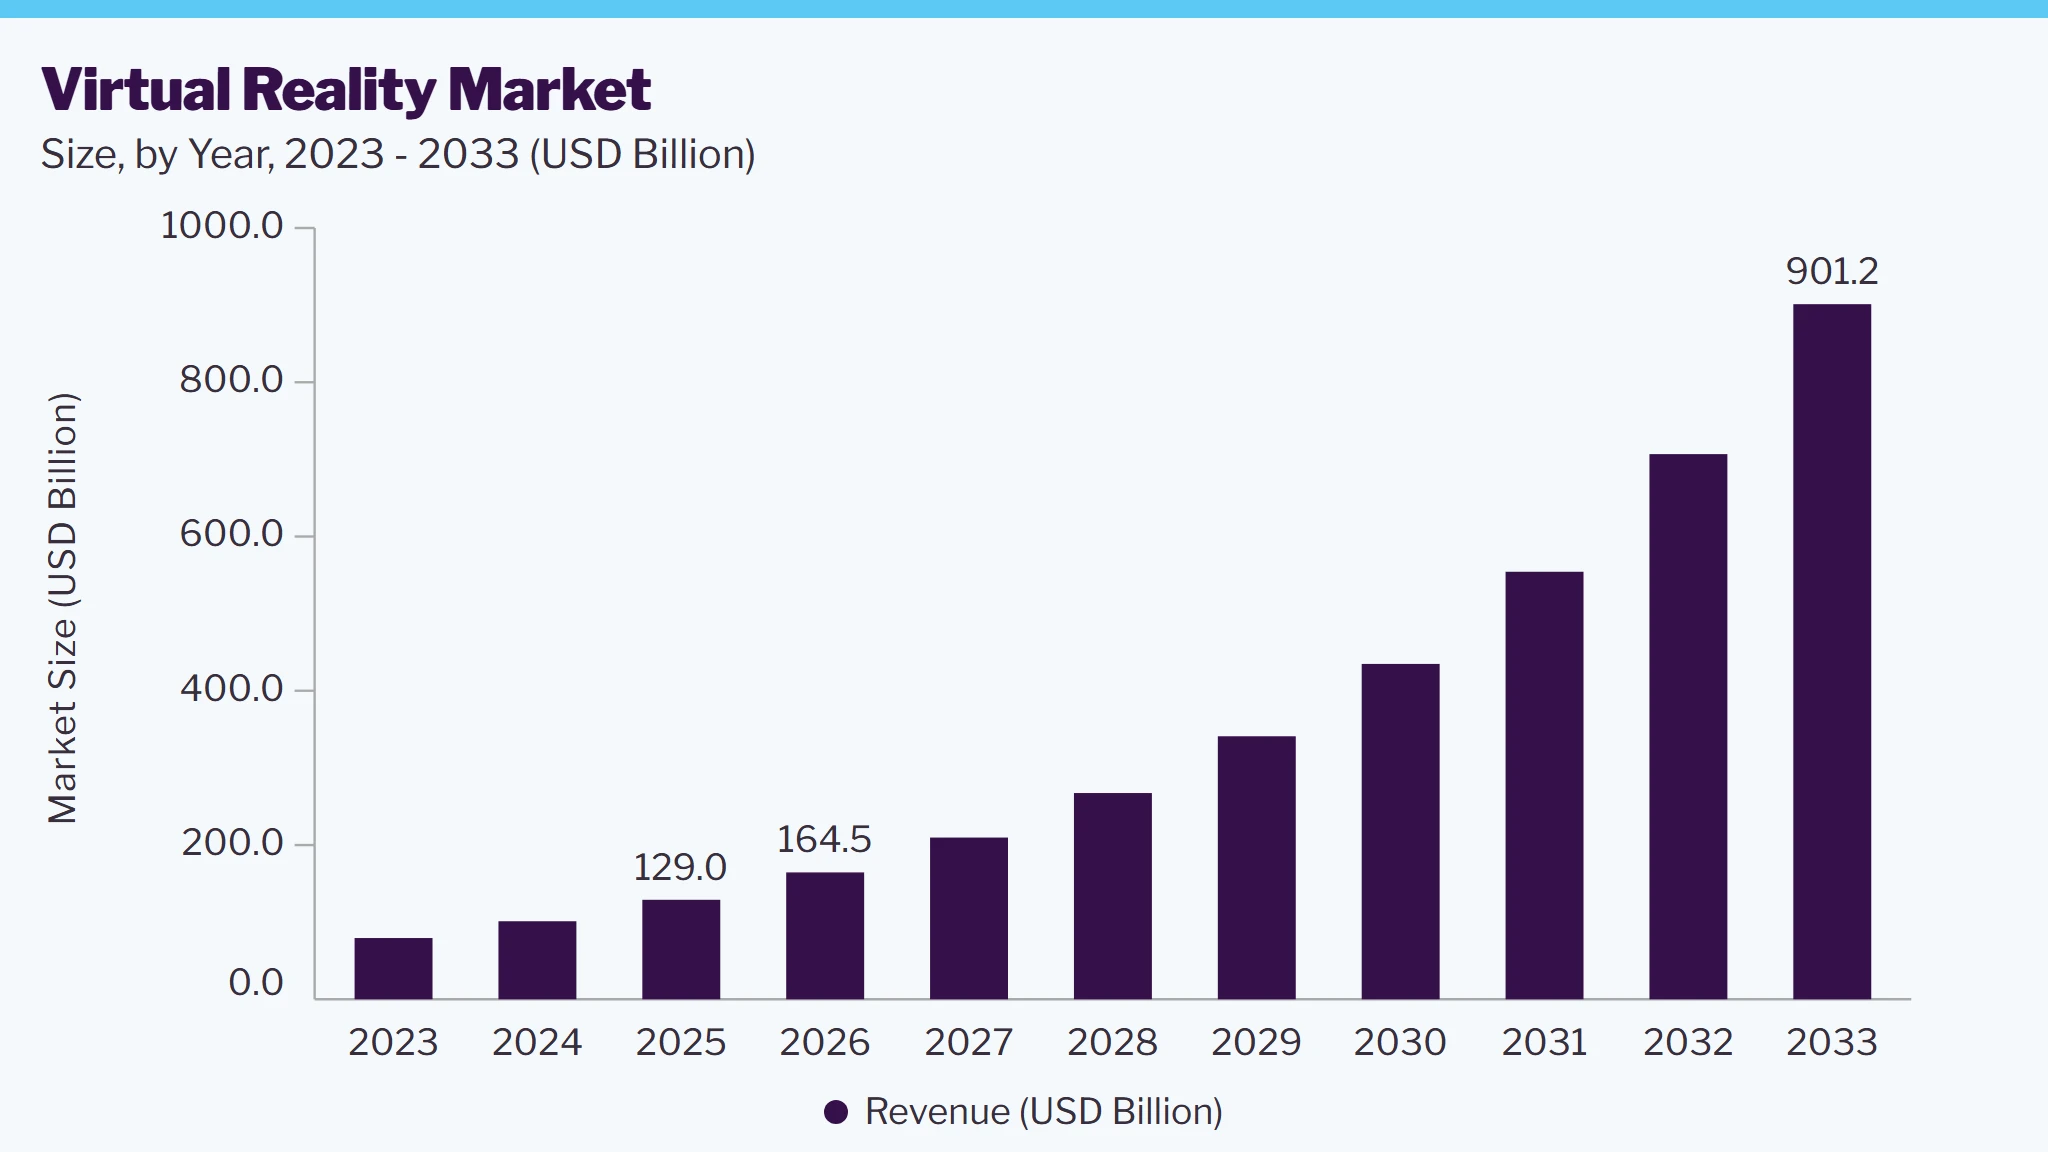
The global virtual reality market size was valued at USD 129.0 billion in 2025 and is projected to grow from USD 164.5 billion in 2026 to USD 901.2 billion by 2033, at a CAGR of 27.5% from 2026 to 2033. Asia Pacific accounted for the largest global revenue share of over 38.3% in 2025. The continuous developments in hardware and software technologies are encouraging the widespread use of virtual reality across different applications. The use of virtual reality for training and entertainment is gaining momentum, helping the market grow.
Key Market Trends & Insights
- By device: Head-mounted display device held the largest revenue share of over 62.5% in 2025.
- By technology: Semi & fully immersive segment held the largest revenue share of approximately 85.4% in 2025.
- By application: Commercial segment held the largest revenue share of 56.9% in 2025.
- By component: Hardware segment held the largest revenue share of 65.2% in 2025.
Regional Highlights
- Largest regional market: Asia Pacific (38.3% revenue share, 2025)
- Fastest-growing regional market: Europe (fastest CAGR, 2026-2033)
Market Size & Forecast
- Market size in 2025: USD 129.0 Billion
- Estimated market size in 2026: USD 164.5 Billion
- Projected market size by 2033: USD 901.2 Billion
- CAGR (2026-2033): 27.5%
Three ways to get this report
Buy it, customize it, or ask a question.Ask an Analyst
Analyst response in 1 business day
- AccessReport author, directly
- Reply timeWithin 1 working day
- No sales callDirect answer only
- FormatEmail reply
- CostFree, no cost
Get the Full Report
What the study covers
- FormatsPDF · Excel · Dashboard
- Timeline2026–2033 annual, 2025 base
- Coverage20+ countries, 5 regions
- Companies10+ key players profiled
Customize the Report
20% free customization
- IncludeCountries, segments, points
- TailorTo your product definition
- ExtendDeeper competitor detail
- OrA fully bespoke study
- Turnaround5–10 working days
Virtual reality (VR) technology creates immersive and interactive experiences through devices such as VR headsets, glasses, controllers, gloves, and haptic-enabled wearables. These technologies simulate digital environments and enable users to interact with virtual content in increasingly realistic ways, transforming applications across gaming, entertainment, training, and simulation. The growing adoption of VR for instructional and workforce training is also supporting market expansion, particularly among field workers, engineers, mechanics, pilots, defense personnel, and technicians. By providing realistic and controlled training environments, VR can help organizations improve skill development, reduce training-related risks, and enhance operational preparedness.
 Source: Grand View Research, IR Documents, Primary Interviews, Paid DatabasesTo learn more about this report,
 Download Free Sample Report
The adoption of VR is expanding across industries such as automotive, healthcare, manufacturing, and aerospace, supported by its ability to enhance visualization, simulation, collaboration, and product development. In the automotive industry, for instance, VR enables engineers to evaluate vehicle designs, identify potential issues, and make modifications during the early stages of development, helping reduce reliance on costly physical prototypes. Automotive manufacturers are also integrating mixed reality (MR), combining augmented reality (AR) and VR, into vehicle engineering and development workflows. In healthcare, VR is gaining traction in applications such as medical training, surgical simulation, rehabilitation, and exposure-based therapies, creating additional opportunities for market growth. Furthermore, travel and tourism companies are increasingly leveraging VR to provide virtual tours of monuments, iconic destinations, museums, parks, and other attractions, allowing potential travelers to explore destinations remotely and supporting more engaging pre-travel experiences.
Market Dynamics
The virtual reality (VR) market is being driven by increasing adoption across gaming, entertainment, healthcare, education, automotive, manufacturing, and enterprise applications. Advancements in head-mounted displays (HMDs), spatial computing, motion tracking, haptic technologies, and wireless connectivity are enhancing immersive experiences and expanding the range of VR use cases. Integration with artificial intelligence (AI), digital twins, and cloud technologies is further enabling applications such as simulation, virtual training, product design, and remote collaboration. However, the high costs of advanced hardware, specialized software, and supporting infrastructure remain a key restraint, particularly for enterprise-grade deployments. At the same time, declining hardware costs, growing availability of standalone VR devices, and increasing investments by technology companies are creating new opportunities for market expansion. The continued development of immersive content and enterprise applications is expected to support sustained market growth.
Virtual reality (VR) emerges as an important technology across a broad range of commercial applications, including training, immersive experiences, entertainment, simulation, and real-time inspection. VR-based training enables organizations to create realistic, controlled environments without the logistical requirements of physical training facilities, potentially reducing training costs while maintaining an interactive learning experience. In addition, virtual simulations allow employees to practice complex or hazardous procedures in a controlled setting, helping minimize exposure to on-site risks in industries such as construction, aerospace & defense, manufacturing, and other safety-critical sectors.
VR is also gaining increasing adoption across healthcare and medical applications. Medical students and healthcare professionals can use VR-based simulations to practice complex procedures, improve clinical skills, and enhance procedural preparedness in controlled environments. In addition, VR-based interventions are being explored for pain and anxiety management, rehabilitation, and behavioral health applications. VR exposure therapy (VRET), for instance, provides controlled and gradual exposure to simulated environments and is being used to support the management of conditions such as post-traumatic stress disorder (PTSD), phobias, and anxiety. VR-based rehabilitation is also gaining traction as an approach for supporting motor function recovery and improving patient engagement during physical therapy.
Furthermore, VR is expanding across media & entertainment, tourism & hospitality, gaming, and other commercial applications. In gaming, VR enables highly interactive and immersive experiences by allowing users to engage with digitally simulated environments. Tourism and hospitality companies are also leveraging VR to offer virtual tours of destinations, hotels, attractions, and cultural sites, allowing potential customers to explore these experiences remotely. The expanding application of VR across diverse commercial and enterprise use cases, coupled with ongoing advancements in hardware, software, and immersive technologies, is expected to support continued market growth over the coming years.
The high cost of hardware, software, and supporting infrastructure remains a significant restraint for the adoption of immersive technologies such as augmented reality (AR) and virtual reality (VR). While consumer-oriented VR devices have become increasingly accessible, commercial and enterprise-grade VR systems often require sophisticated, durable hardware, specialized software, training platforms, and licensing, resulting in substantially higher implementation costs. For instance, medical training VR systems can range from several thousand dollars to more than USD 300,000, depending on the hardware, software, training platforms, and licensing requirements. Similarly, VR gaming setups can range from approximately USD 350 to more than USD 3,000, making advanced systems relatively expensive for individual consumers. According to a consumer survey published by PatentPC, 65% of consumers identified high prices as a major barrier to VR adoption, compared with 45% for commercial adoption. These cost considerations can discourage consumers and organizations from investing in VR systems, particularly when the expected benefits do not justify the initial expenditure.
Market participants are increasingly working to improve affordability through advancements in hardware design, component integration, and manufacturing efficiency. Companies such as Meta and Apple offer VR headsets across a broad price range, from approximately USD 300 to USD 3,500, catering to different consumer and enterprise needs. However, despite the increasing availability of lower-priced devices, the upfront investment associated with VR hardware, software, accessories, and supporting infrastructure remains a key barrier to widespread adoption. High initial costs, particularly for advanced and enterprise-grade systems, are therefore expected to continue constraining market growth in price-sensitive segments.
The integration of virtual reality (VR) with emerging technologies such as digital twins and immersive remote collaboration is creating significant opportunities for market expansion. These capabilities are particularly relevant to engineering, manufacturing, and other industrial organizations adopting Industry 4.0 frameworks. VR enables companies to create realistic virtual representations of industrial environments and processes, supporting applications such as inventory management, design validation, predictive maintenance, workforce training, and production planning. By enabling teams to visualize and evaluate processes in simulated environments before implementing changes in physical facilities, VR can help improve decision-making, reduce development risks, and optimize operational workflows. For instance, the BMW Group partnered with NVIDIA to develop a VR-enabled digital twin of a virtual factory, allowing the company to design, test, and optimize production processes and factory layouts before implementing the corresponding physical infrastructure.
VR also presents significant opportunities across the hospitality and tourism industry by enabling hotels and travel companies to offer immersive experiences beyond traditional photographs and videos. Virtual tours allow prospective guests to explore hotel rooms, amenities, facilities, and surrounding environments remotely, providing a more detailed understanding of the experience before making a booking. This can enhance customer engagement and support more informed purchasing decisions. For instance, Marriott Hotels introduced a virtual reality experience using Samsung Gear VR headsets that offered guests 360-degree virtual experiences of destinations, including an ice cream shop in Rwanda, the Andes Mountains in Chile, and the streets of Beijing. The growing adoption of immersive visualization across industrial, commercial, hospitality, and tourism applications is expected to create new use cases and support the continued expansion of the VR market.
Analyst Perspective
The virtual reality (VR) market is evolving from a primarily consumer-focused technology into an increasingly important enterprise tool across industries. Advancements in hardware and software, declining device costs, and integration with AI and digital twins are improving VR accessibility, functionality, and business value. Healthcare, hospitality, manufacturing, construction, aerospace and defense, media and entertainment, and education are adopting VR for training, design, simulation, collaboration, and operational workflows. Continued investments by major technology companies are accelerating headset, immersive content, and supporting technology development. As VR solutions become more capable, affordable, and integrated with broader digital ecosystems, enterprise adoption is expected to expand, supporting long-term market growth.
Device Insights
The head-mounted display (HMD) segment dominated the virtual reality industry, accounting for a revenue share of 62.5% in 2025, and is expected to maintain its leading position through 2033. Segment growth is primarily driven by the increasing adoption of VR headsets across consumer and commercial applications, supported by the availability of diverse HMD configurations, including tethered, hybrid, and wireless devices. HMDs are increasingly being used for training, simulation, and visualization across industries such as research, aerospace, engineering, military, and healthcare. In addition, manufacturers are continually enhancing HMD capabilities by improving display resolution, tracking, ergonomics, and connectivity, while strategic partnerships are advancing the development of more immersive, application-specific VR solutions.
The gesture-tracking device (GTD) segment is projected to grow at the fastest CAGR of 29.9% during the forecast period. Growth is being driven by increasing demand for advanced gesture-tracking capabilities that enable more intuitive, immersive, and natural interactions within virtual environments. GTD-based VR systems incorporate technologies such as sensors, processors, VR projectors, large displays, and multi-screen projection systems to capture and interpret user movements with greater precision. Furthermore, ongoing advancements in sensor and processor technologies are improving tracking accuracy, responsiveness, and system performance, enabling more realistic interactions and enhancing the overall immersive experience across VR applications.
Technology Insights
The semi & fully immersive segment accounted for the largest revenue share of 85.4% in 2025, and is expected to grow at the fastest CAGR over the forecast period. Growth is primarily supported by increasing demand for immersive VR head-mounted displays (HMDs) across educational, industrial, training, and simulation applications. Semi- and fully immersive systems recreate real-world environments in virtual settings, enabling users to visualize complex scenarios, conduct simulations, and support planning and decision-making. These systems typically incorporate advanced simulators, high-performance computing systems, and high-resolution displays to deliver realistic and interactive experiences. In education, immersive VR is gaining traction as it enables students to engage in interactive learning activities, including simulations and practical exercises that may be difficult or impractical to conduct in conventional classroom environments.
Non-immersive VR technology provides users with a computer-generated environment accessed through conventional workstations, computers, or gaming consoles rather than a fully immersive virtual experience. Its relatively lower infrastructure requirements, accessibility, and efficient network management make it suitable for a range of applications. Non-immersive systems are used in areas such as design, gaming, visualization, and medical support, although their predominantly two-dimensional interaction limits the scope of certain applications. These systems typically rely on conventional input devices, including controllers, keyboards, mice, and displays, allowing users to access VR-based applications without requiring specialized immersive hardware. The ability to leverage existing computing infrastructure can reduce the need for significant investments in new systems, thereby supporting adoption in cost-sensitive applications.
Application Insights
The commercial segment dominated the virtual reality market, accounting for a revenue share of 56.9% in 2025, supported by the increasing adoption of VR headsets and immersive experience centers across applications such as real estate, automotive showrooms, and retail. Businesses are increasingly leveraging VR to showcase properties, demonstrate products, simulate real-world experiences, and engage potential customers through interactive and immersive environments. In addition, the growing penetration of smartphones, tablets, and other connected handheld devices is improving access to VR content and supporting broader adoption across commercial applications. Companies are also using VR as a tool for product launches, marketing, customer engagement, and virtual demonstrations, creating additional opportunities for segment growth.
The healthcare segment is projected to grow at the fastest CAGR of 32.2% over the forecast period, driven by the expanding use of VR for medical education, clinical training, treatment support, disease awareness, and operational planning. Hospitals, medical institutions, and universities are increasingly adopting VR-based solutions to provide students and healthcare professionals with realistic, controlled environments for practicing procedures and developing clinical skills. VR-enabled surgical simulation can also allow physicians to rehearse complex procedures and evaluate different approaches before performing interventions on patients, potentially improving preparedness and reducing procedural risks. Furthermore, the growing adoption of remote collaboration and simulation technologies in healthcare is expected to create additional opportunities for VR applications, supporting continued segment expansion.
Component Insight
The hardware segment accounted for the largest revenue share of 65.2% in 2025, supported by the widespread adoption of smartphones, tablets, and other advanced handheld electronic devices. The increasing integration of VR-compatible features across consumer electronics is expanding the ecosystem of devices that support immersive applications. The segment encompasses a broad range of components, including input and output devices, controllers, sensors, and VR consoles, which are increasingly being adopted as part of complete VR setups. Furthermore, the growing deployment of VR headsets across commercial applications, theme and amusement parks, training facilities, and entertainment venues is creating opportunities for original equipment manufacturers (OEMs) to expand their presence in the VR hardware ecosystem.
The software segment is projected to grow at the fastest CAGR of 29.7% during the forecast period, driven by the increasing demand for software solutions capable of processing inputs, generating interactive feedback, analyzing data, and managing VR environments. VR software plays a critical role in creating realistic three-dimensional environments that enable users to interact with digital content, making it valuable for applications such as product design and prototyping. In addition, VR software is increasingly being deployed for training and simulation, virtual tool development, application development, gaming, and immersive learning platforms. Continued advancements in graphics, spatial computing, artificial intelligence (AI), and real-time data processing are further enhancing software capabilities and supporting segment growth.
Regional Insights
The Asia Pacific virtual reality market accounted for the largest global revenue share of 38.3% in 2025, supported by the region’s strong manufacturing ecosystem, expanding technology infrastructure, and increasing adoption of immersive technologies across industrial and consumer applications. Countries such as China, Japan, and South Korea have established electronics and hardware manufacturing capabilities, supporting the production and supply of VR headsets, components, and related devices. In addition, the presence of a large industrial base and growing adoption of automation are encouraging enterprises to integrate VR into applications such as employee training, product design, simulation, maintenance, and remote collaboration.
 To learn more about this report, Download Free Sample Report
Furthermore, growing smartphone penetration, improving digital connectivity, and increasing availability of VR-enabled consumer devices are broadening access to immersive experiences across the region. Growing investments in extended reality (XR), artificial intelligence (AI), gaming, and digital content ecosystems are also supporting the development of the regional VR market. These factors, combined with continued technological advancements and expanding enterprise applications, are expected to sustain market growth across Asia Pacific.
Europe Virtual Reality Market Trends
The Europe virtual reality (VR) market is projected to be among the fastest-growing regional markets during the forecast period, driven by the growing adoption of immersive technologies across gaming, automotive, healthcare, manufacturing, education, and other industries. The region’s well-established automotive and industrial sectors are increasingly leveraging VR for product design, prototyping, simulation, employee training, and remote collaboration, creating new opportunities for market expansion. In addition, the growing integration of VR into enterprise applications is broadening its use beyond traditional entertainment and gaming applications.
Europe’s large and established gaming community continues to support demand for advanced VR headsets and immersive gaming experiences. Ongoing advancements in display quality, motion tracking, processing capabilities, and wireless connectivity are improving VR hardware performance and enhancing user experiences. Furthermore, increasing investments in immersive content, gaming ecosystems, and extended reality (XR) technologies are encouraging the development and commercialization of next-generation VR solutions across European markets. These developments are expected to support continued regional market growth over the forecast period.
Key Virtual Reality Companies Insights
Key market players are adopting strategies such as partnerships, acquisitions, joint ventures, product innovations, research and development (R&D), and geographical expansion to strengthen their market presence and competitive position. Companies are also focusing on enhancing their product portfolios to address evolving user requirements and maintain competitiveness. For instance, Meta Platforms, Inc. acquired Within Unlimited, Inc. to strengthen its virtual reality (VR) capabilities and gain access to its popular VR fitness application, Supernatural.
Furthermore, leading companies are expanding their product portfolios through new product launches and significant enhancements to existing offerings. The rapid pace of technological advancements in the VR industry is encouraging market participants to regularly introduce products with improved features, capabilities, and tools. For instance, HTC Corporation launched the VIVE XR Elite, a virtual reality and augmented reality headset equipped with a high-resolution display designed to deliver an immersive user experience. These product developments enable companies to differentiate their offerings and address the evolving requirements of VR users.
Key Virtual Reality Companies
The following key companies have been profiled for this study on the virtual reality market.
-
Alphabet Inc.
-
Sensics, Inc.
-
Sixense Enterprises, Inc. (Penumbra, Inc.)
Recent Developments
-
In June 2026, engineers from Binghamton University developed a digital twin synchronized with real-world sensors to provide a virtual tour of a greenhouse with the help of VR headsets. The system was developed for older farmers, farmers with limited mobility, and agricultural students who lack access to greenhouses and labs.
-
In October 2025, Microsoft and Meta collaborated to launch the Windows 11 update for Meta Quest 3. This update provides immersive remote desktop capabilities for Meta Quest devices. The update introduces multi-monitor streaming, an ultrawide immersive mode, and new workspace customization tools. The integration allows users to mirror high-resolution desktop displays inside Meta's headset environment.
Virtual Reality Market Report Scope
Report Attribute
Details
Market size in 2025
USD 129.0 billion
Estimated market size in 2026
USD 164.5 billion
Projected market size by 2033
USD 901.2 billion
Growth rate
CAGR of 27.5% from 2026 to 2033
Base year for estimation
2025
Historical data
2021 - 2024
Forecast period
2026 - 2033
Quantitative units
Revenue in USD billion and CAGR from 2026 to 2033
Report coverage
Revenue forecast, company market position analysis, competitive landscape, growth factors, and trends
Segments covered
Device, technology, component, application, and region
Regional scope
North America; Europe; Asia Pacific; South America; Middle East & Africa
Country scope
U.S.; Canada; Mexico; UK; Germany; France; Italy; China; Japan; India; South Korea; Brazil; Argentina; South Africa; Saudi Arabia
Key companies profiled
Alphabet Inc.; Barco NV; CyberGlove Systems, Inc.; Meta Platforms Inc.; HTC Corporation; Microsoft Corporation; Samsung Electronics Co., Ltd.; Sensics, Inc.; Sixense Enterprises, Inc. (Penumbra, Inc.); Ultraleap Ltd.
Customization scope
Free report customization (equivalent to up to 8 analysts working days) with purchase. Addition or alteration to country, regional & segment scope.
Pricing and purchase options
Avail of customized purchase options to meet your exact research needs. Explore purchase options
Global Virtual Reality Market Report Segmentation
This report forecasts revenue growth at the global, regional & country levels and provides an analysis of the latest industry trends in each of the sub-segments from 2021 to 2033. For this study, Grand View Research has segmented the global virtual reality market report based on device, technology, component, application, and region:
-
Device Outlook (Revenue, USD Billion, 2021 - 2033)
-
Head-Mounted Display (HMD)
-
Gesture-Tracking Device (GTD)
-
Projectors & Display Wall (PDW)
-
-
Technology Outlook (Revenue, USD Billion, 2021 - 2033)
-
Semi & Fully Immersive
-
Non-immersive
-
-
Component Outlook (Revenue, USD Billion, 2021 - 2033)
-
Hardware
-
Software
-
-
Application Outlook (Revenue, USD Billion, 2021 - 2033)
-
Aerospace & Defense
-
Consumer
-
Commercial
-
Enterprise
-
Healthcare
-
Others
-
-
Regional Outlook (Revenue, USD Billion, 2021 - 2033)
-
North America
-
U.S.
-
Canada
-
Mexico
-
-
Europe
-
UK
-
Germany
-
France
-
Italy
-
-
Asia Pacific
-
China
-
Japan
-
India
-
South Korea
-
-
South America
-
Brazil
-
Argentina
-
-
Middle East & Africa
-
South Africa
-
Saudi Arabia
-
-
Frequently Asked Questions About This Report
The global virtual reality market size was valued at USD 129.0 billion in 2025 and is expected to reach USD 164.5 billion in 2026.
The global virtual reality (VR) market is expected to grow at a compound annual growth rate of 27.5% from 2026 to 2033 to reach USD 901.2 billion by 2033.
Semi & fully immersive segment accounted for the largest revenue share of 83.0% in 2025.
Asia Pacific accounted for the largest revenue share of over 40.0% in 2025.
Some key players operating in the virtual reality market include Alphabet Inc.; Barco NV; CyberGlove Systems, Inc.; Meta Platforms Inc.; HTC Corporation; Microsoft Corporation; Samsung Electronics Co., Ltd.; Sensics, Inc.; Sixense Enterprises, Inc. (Penumbra, Inc.); Ultraleap Ltd.
About the Author(s)
Next Generation Technologies Research Team
Technology · Next Generation TechnologiesThis report was authored by the next generation technologies research team at Grand View Research - comprising two research analysts, one senior research analyst, and one industry expert - with specialized expertise in the next generation technologies segment of the technology industry. All findings are based on proprietary technology databases, executive interviews, and regulatory analysis, subject to internal peer review prior to publication.
Last Updated:
Speak to Analyst

Customize this report to your needs - add regions, segments, or data points, with 20% free customization.
Or view our licence options:


ISO 9001:2015 & 27001:2022 Certified
We are GDPR and CCPA compliant! Your transaction & personal information is safe and secure. For more details, please read our privacy policy.


