
- Home
- »
- Consumer F&B
- »
-
100% Juice Market Size, Share And Trends Report, 2033GVR Report cover

100% Juice Market (2026 - 2033)
Size, Share & Trends Analysis Report By Product (Fruits, Vegetables), By Category (Private Label, Branded), By Type, By Packaging, By Distribution Channel, By Region, And Segment Forecasts
Market Size, 2025
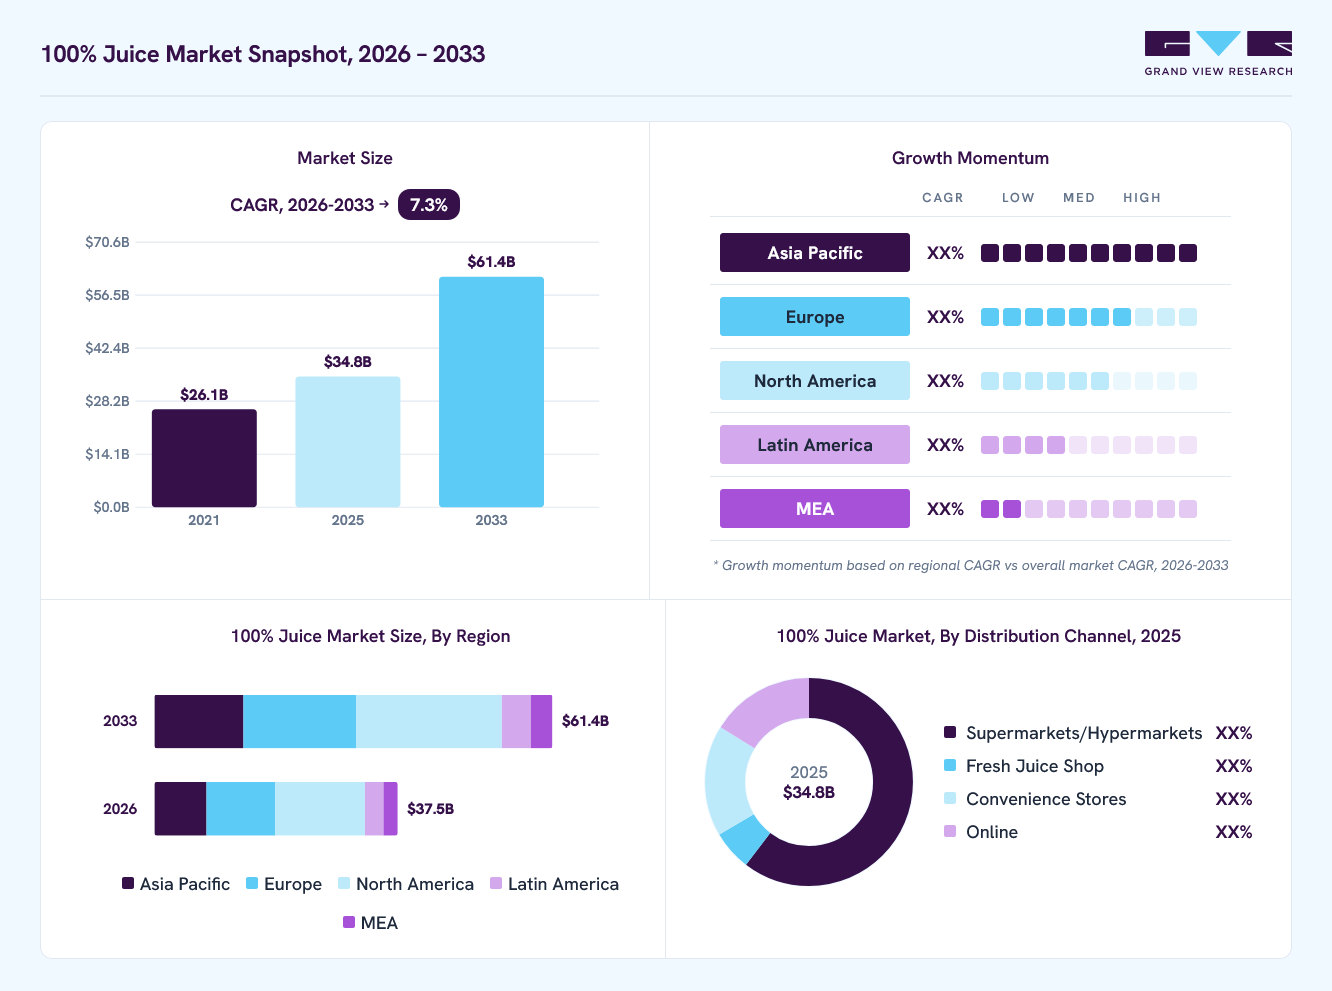
$34.8BMarket Estimate, 2026
$37.5BMarket Forecast, 2033
$61.4BCAGR, 2026–2033
7.3%100% Juice Market Summary
The global 100% juice market size was valued at USD 34.8 billion in 2025 and is projected to grow from USD 37.5 billion in 2026 to USD 61.4 billion by 2033, at a CAGR of 7.3% from 2026 to 2033. North America dominated the market, accounting for a revenue share of 36.9% in 2025. The rise in health consciousness among consumers is a significant trend.
 Source: Grand View Research, IR Documents, Primary Interviews, Paid DatabasesTo learn more about this report,
 Download Free Sample Report
Key Market Trends & Insights
- By product: 100% fruit juice segment led the market with the largest revenue share of 90.3% in 2025.
- By type: Not From Concentrate (NFC) segment led the market with the largest revenue share of 74.1% in 2025.
- By category: Private label segment led the market with the largest revenue share of 42.2% in 2025.
- By packaging: Carton packaging segment led the market with the largest revenue share of 59.0% in 2025.
Regional Highlights
- Largest regional market: North America (44.2% revenue share, 2025)
- Fastest-growing regional market: Asia Pacific (highest CAGR, 2026-2033)
- By country: The U.S. held the largest market share in 2025.
Market Size & Forecast
- Market size in 2025: USD 34.8 Billion
- Estimated market size in 2026: USD 37.5 Billion
- Projected market size by 2033: USD 61.4 Billion
- CAGR (2026-2033): 7.3%
Three ways to get this report
Buy it, customize it, or ask a question.Ask an Analyst
Analyst response in 1 business day
- AccessReport author, directly
- Reply timeWithin 1 working day
- No sales callDirect answer only
- FormatEmail reply
- CostFree, no cost
Get the Full Report
What the study covers
- FormatsPDF · Excel · Dashboard
- Timeline2026–2033 annual, 2025 base
- Coverage20+ countries, 5 regions
- Companies10+ key players profiled
Customize the Report
20% free customization
- IncludeCountries, segments, points
- TailorTo your product definition
- ExtendDeeper competitor detail
- OrA fully bespoke study
- Turnaround5–10 working days
Increasing awareness of the health benefits associated with consuming natural, nutrient-rich juices is boosting demand for the market. The rise of functional beverages, which offer additional health benefits, has led to a surge in demand for 100% packaged juice products enriched with vitamins, minerals, and probiotics. Consumers are increasingly looking for juices that boost immunity, enhance digestion, and provide energy.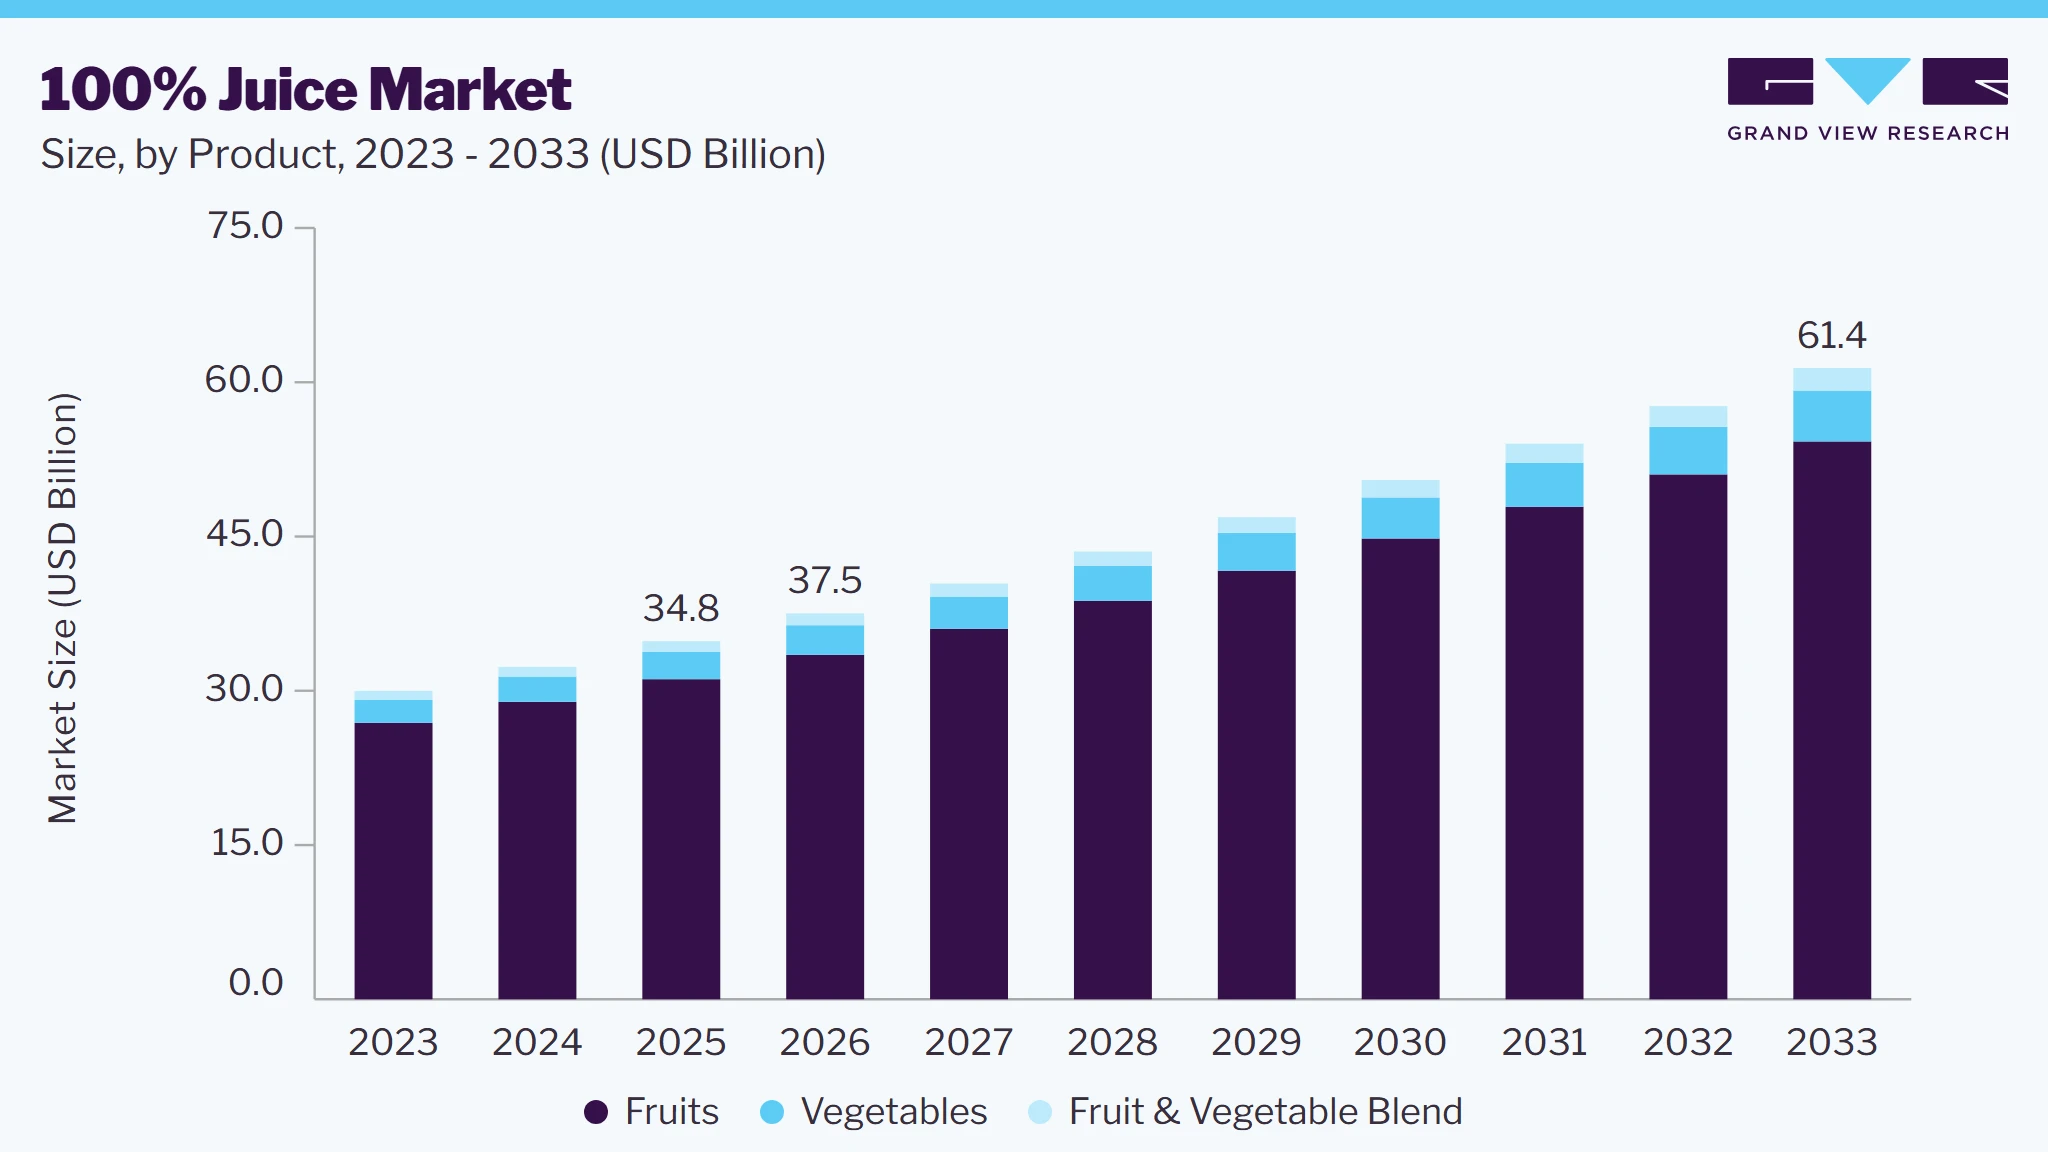 To learn more about this report, Download Free Sample Report
With an increasing focus on sustainability, consumers are more inclined toward products that adopt environmentally friendly practices. Brands that emphasize sustainably sourced ingredients and eco-friendly packaging are witnessing greater consumer loyalty. Manufacturers are constantly experimenting with new flavor profiles and blends, moving beyond traditional orange and apple juices to exotic fruit combinations and blends that include superfoods. This innovation caters to a diverse palate and encourages trialing among consumers.
An increasing number of consumers are transitioning away from carbonated drinks and sugary beverages in favor of healthier, natural options. The perception of 100% packaged juice as a premium, healthful element of a balanced diet bolsters its appeal. Younger generations, who are highly health-conscious, are a driving force in the market. They prioritize clean-label products, which are perceived to be free from artificial ingredients.
Leading juice manufacturers are expanding their product lines to include functional juices, organic offerings, and blends featuring superfoods like turmeric or ginger. This diversification caters to evolving consumer preferences. Companies are increasingly positioning their products as organic, non-GMO, and free from artificial additives to cater to health-conscious consumers.
Globally, wellness centers have increasingly advocated for the adoption of healthier diets to enhance both physical and mental well-being. One of the emerging trends among consumers is detoxification, a practice aimed at cleansing the body, in which fruit juices play a crucial role. These juices not only aid in detoxification but also support weight loss. In response, juice manufacturers have begun launching products specifically designed to fit seamlessly into detox programs. For example, Pressed, a California-based company, introduced new detox juice offerings segmented into specific programs, such as the Cleanse 1 program and Cleanse 2 program, each featuring different juice products.
In addition, veganism has become a popular dietary trend, with widespread adoption globally. These juice products, which can easily be incorporated into a vegan diet, provide essential vitamins and minerals, driving their growing demand among consumers. To cater to this market segment, companies are launching such products in various flavors and innovative packaging to attract health-conscious consumers.
The 100% juice market is set for sustained growth, driven by innovations in product formulations, campaigns, and collaboration activities, strategic marketing efforts, and expanding distribution networks. Manufacturers and stakeholders in this sector have significant opportunities to capitalize on changing consumer trends and strengthen their positions in the global market.
Market Dynamics
Growing consumer demand for clean-label and minimally processed beverages is encouraging manufacturers to emphasize natural ingredients and transparent sourcing practices. Product innovation through the introduction of exotic fruit blends, functional formulations, and fortified juice variants is helping brands attract health-conscious consumers. In addition, increasing investments in sustainable packaging solutions and environmentally responsible production methods are strengthening brand differentiation in a competitive marketplace. The expansion of premium and organic juice offerings, coupled with rising consumer interest in wellness-oriented lifestyles, is further contributing to the market's development and long-term growth potential.
The growing consumer preference for beverages made with recognizable, minimally processed ingredients is driving demand for 100% juice products. Buyers increasingly seek drinks that align with wellness-focused lifestyles, favoring options free from artificial additives, preservatives, and synthetic flavors. This shift is encouraging manufacturers to emphasize ingredient transparency and simple formulations. In May 2026, Austria Juice launched a new reduced-sugar fruit juice concentrate range that cuts sugar and calories by at least 30% using a proprietary yeast fermentation process while maintaining authentic fruit flavor and a clean-label formulation. As a result, 100% juice is gaining appeal as a naturally derived beverage choice that supports clean-label consumption trends.The production of 100% juice relies heavily on consistent supplies of high-quality fruit, making manufacturers vulnerable to fluctuations in agricultural output and raw material availability. Weather-related disruptions, crop diseases, and seasonal variations can affect fruit yields, creating challenges in maintaining stable production volumes. In addition, strict quality requirements often limit sourcing flexibility, increasing operational complexity for producers. According to the USDA data published in January 2026, weather-driven disruptions and uneven citrus harvests in major producing regions are tightening the supply of juice-grade fruit, especially oranges used in 100% juice production. These factors can place pressure on profit margins and constrain the ability of manufacturers to offer competitively priced products across diverse consumer segments.Increasing consumer inclination toward wellness-driven drinking habits is encouraging brands to develop more enriched and purpose-led juice offerings. Demand for beverages perceived as natural and beneficial for daily health routines is prompting innovation in formulations and ingredient combinations. Growing retail modernization and digital grocery platforms are improving reach and product discoverability across wider consumer segments. This environment is enabling manufacturers to strengthen brand differentiation through enhanced sensory appeal and convenient packaging solutions.Analyst Perspective
The 100% juice market is experiencing steady growth, supported by rising consumer demand for natural, nutrient-rich, and minimally processed beverage options. Increasing health consciousness and preference for beverages perceived as wholesome alternatives to carbonated drinks are encouraging higher adoption across age groups. Expanding interest in immunity support and daily wellness nutrition is further strengthening consumption patterns.
Product Insights
Based on product, the 100% fruit juice segment led the market with the largest revenue share of 90.3% in 2025. The 100% fruit juice is favored by consumers for its natural sweetness, derived entirely from fruits without added sugars or artificial sweeteners. This aligns with the growing preference for natural and healthier beverages. 100% packaged fruit juices are often marketed as part of a balanced diet, associated with various health benefits, including improved immune function, better digestion, and reduced risk of chronic diseases. This health association boosts their popularity. Many well-established juice brands have built their portfolios around 100% fruit juices, investing in extensive marketing campaigns that emphasize the purity, natural taste, and health benefits of their products. This has helped cement fruit juice's dominance in the market.
The 100% fruit & vegetable blend segment is expected to grow at a CAGR of 8.8% from 2026 to 2033. As consumers become more health-conscious, they are increasingly seeking beverages that offer a balanced nutritional profile. Blending fruits and vegetables creates juices that are lower in natural sugars while being rich in essential vitamins, minerals, and fiber. This combination appeals to consumers looking for healthier beverage options. The combination of fruits and vegetables offers a wider range of flavors and textures, appealing to consumers who are adventurous with their taste preferences. This diversity allows manufacturers to create unique blends that stand out in a crowded market, attracting consumers who seek variety in their diets.
Type Insights
Based on type, the Not From Concentrate (NFC) segment led the market with the largest revenue share of 74.1% in 2025. NFC juices are widely perceived by consumers as being of higher quality and closer to the natural taste of freshly squeezed juice. Unlike juice from concentrate, which undergoes multiple processing steps, including concentration and reconstitution, NFC juice retains more of the natural flavors and nutrients of the original fruit or vegetable. This perception of freshness and purity makes NFC juice more appealing to consumers who prioritize quality. Many established juice brands have built strong consumer loyalty around their NFC product lines. These brands often invest heavily in marketing and product innovation, reinforcing their market leadership and ensuring that NFC juices remain the preferred choice for a large segment of consumers.
The from concentrate segment is expected to grow at a CAGR of 8.0% from 2026 to 2033. Juices made from concentrate are generally more affordable than their "not from concentrate" counterparts. The concentration process reduces the volume and weight of the juice, making it cheaper to transport and store, which translates to lower costs for consumers. This affordability makes concentrate juices an attractive option, especially in price-sensitive markets and among budget-conscious consumers. The concentration process removes much of the water content, reducing the likelihood of spoilage and making these juices easier to store for extended periods.
Category Insights
Based on category, the private label segment led the market with the largest revenue share of 42.2% in 2025. Consumers often prefer well-known brands that they trust, particularly when it comes to products like 100% juice, which is associated with health and wellness. Established brands have built a reputation for quality, consistency, and safety, leading to strong consumer loyalty. This trust in branded products drives higher sales and market share. Major juice brands invest heavily in marketing and advertising campaigns that emphasize the purity, health benefits, and superior taste of their products. These efforts create strong brand recognition and reinforce the value proposition of branded juices, attracting a large consumer base.
The private label segment is expected to grow at a CAGR of 7.9% from 2026 to 2033. The perception of private-label products has significantly improved over the years. Many retailers have invested in enhancing the quality of their private label offerings, ensuring they meet or even exceed the standards of branded products. This shift has led to increased consumer trust and acceptance of private-label 100% juices. Retailers are increasingly promoting their private label products, giving them prominent shelf space and visibility. With the rise of supermarket chains and e-commerce platforms, private-label juices are becoming more widely available, making it easier for consumers to choose them over branded options.
Packaging Insights
Based on packaging, the carton packaging segment led the market with the largest revenue share of 59.0% in 2025. Carton packaging is widely preferred by consumers for its convenience, ease of use, and portability. It is easy to store, pour, and reseal, making it an ideal choice for both home use and on-the-go consumption. This broad consumer appeal contributes to its dominant market share. They are less expensive to produce and transport compared to other packaging materials like glass. This cost efficiency allows juice producers to offer their products at competitive prices, which attracts more consumers and drives higher sales volumes.
The plastic segment is expected to grow at a CAGR of 8.0% from 2026 to 2033. Plastic bottles and containers are lightweight and durable, making them convenient for consumers to carry and handle. This portability is particularly appealing for on-the-go lifestyles, as plastic bottles are less likely to break compared to glass and are easier to transport in various settings. The lower production and transportation costs associated with plastic packaging make it an attractive option for manufacturers, which can lead to more competitive pricing for consumers.
Distribution Channel Insights
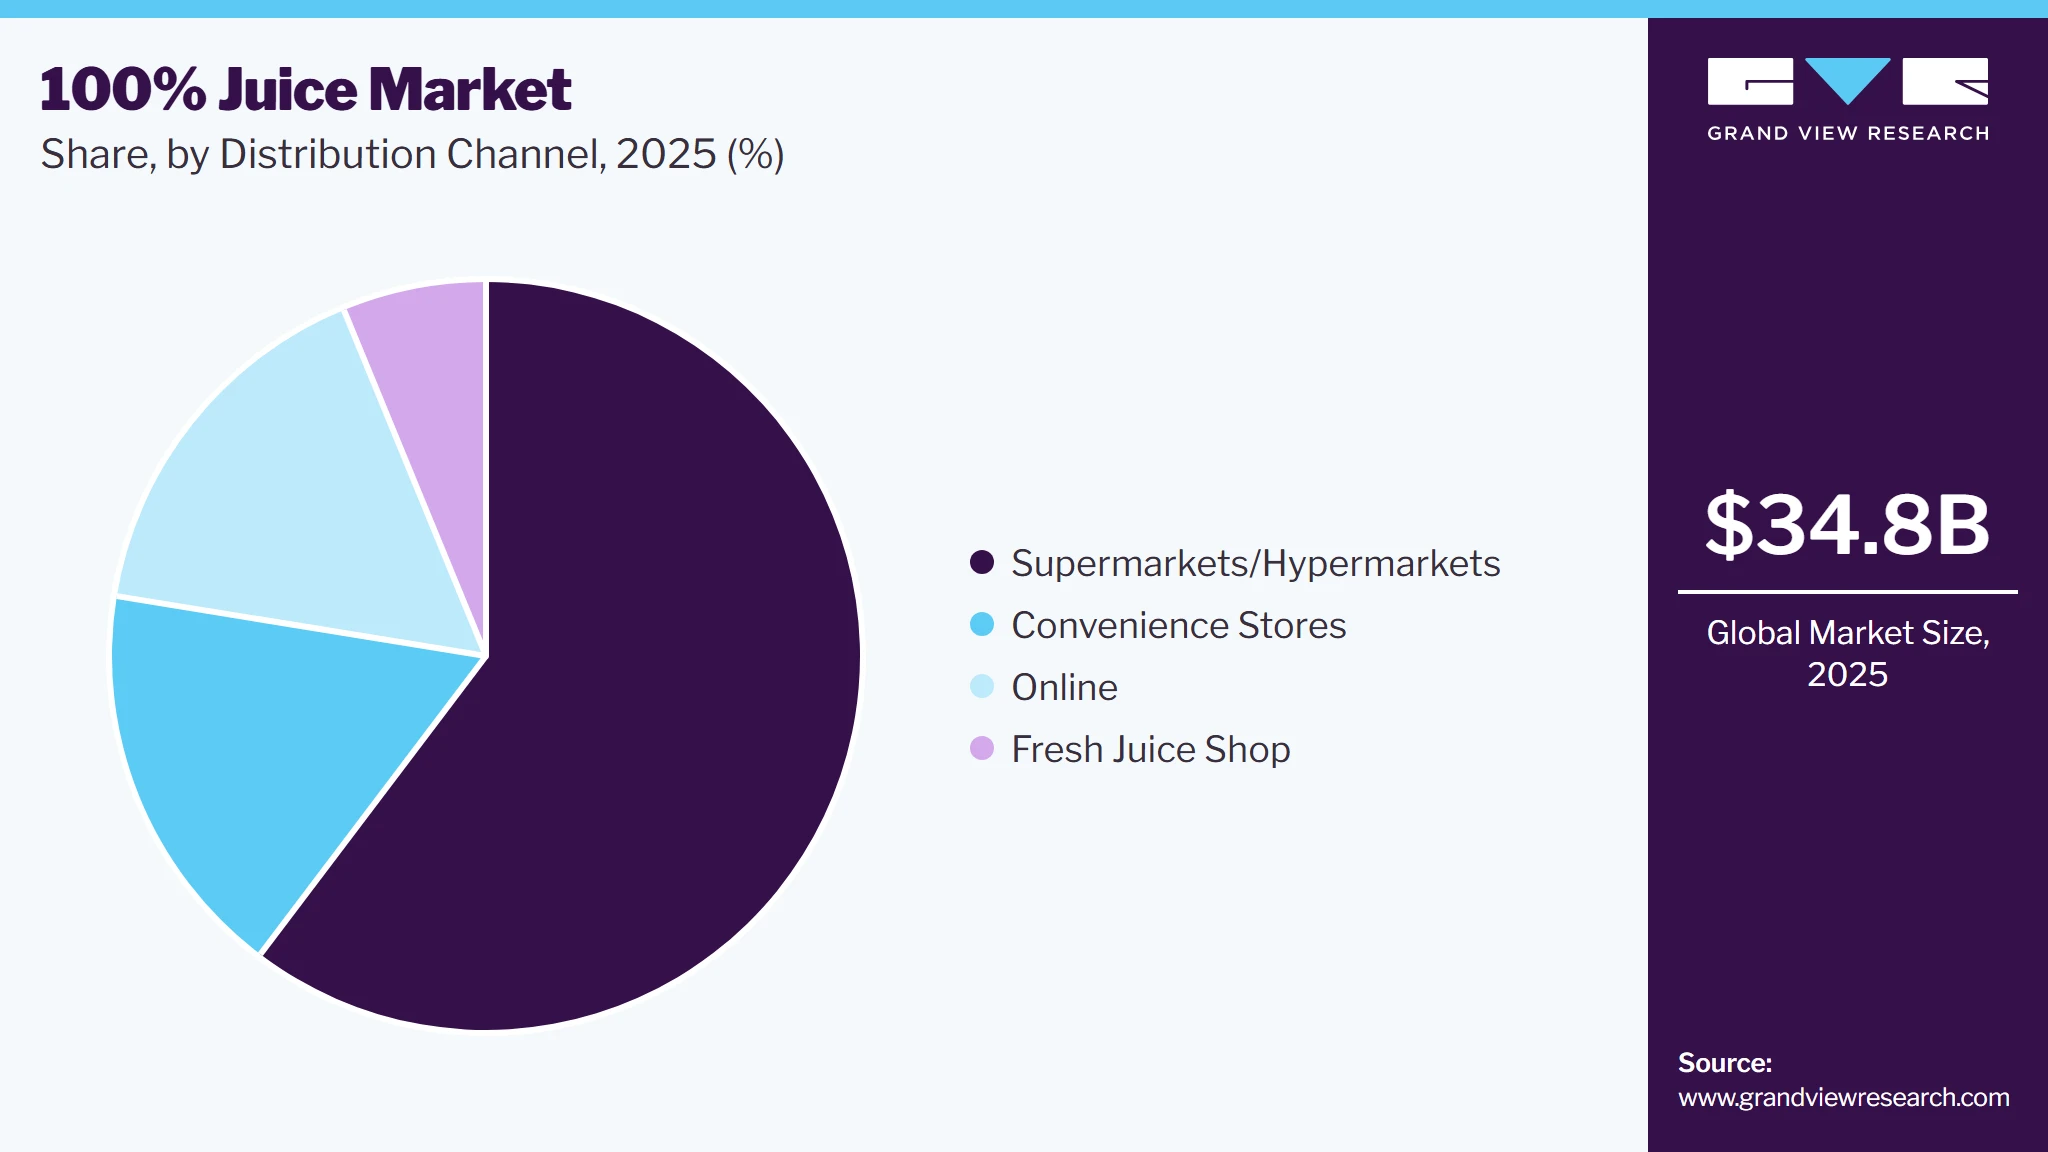
Based on the distribution channel, the supermarkets & hypermarkets segment led the market with the largest revenue share of 60.3% in 2025. These retail formats offer a one-stop shopping experience, where consumers can purchase all their grocery needs, including 100% juice, in a single trip. The convenience of picking up juice along with other household essentials boosts sales through these channels. Supermarkets and hypermarkets typically offer an extensive range of 100% juice products, including various brands, flavors, and packaging sizes. This vast selection attracts a broad customer base, allowing consumers to find exactly what they are looking for, which drives higher sales volumes.
 To learn more about this report, Download Free Sample Report
The sales of 100% juice through online channels are expected to grow at a CAGR of 9.0% from 2026 to 2033. Juice manufacturers are increasingly investing in direct-to-consumer (D2C) online channels, bypassing traditional retail intermediaries. This approach allows brands to build stronger relationships with consumers, offer customized products, and collect valuable data on consumer preferences, all of which drive sales growth. Moreover, online platforms often utilize algorithms to provide personalized recommendations based on a consumer’s past purchases and preferences. This personalization encourages repeat purchases and increases the likelihood of trying new products, driving higher sales in the online segment.
Regional Insights
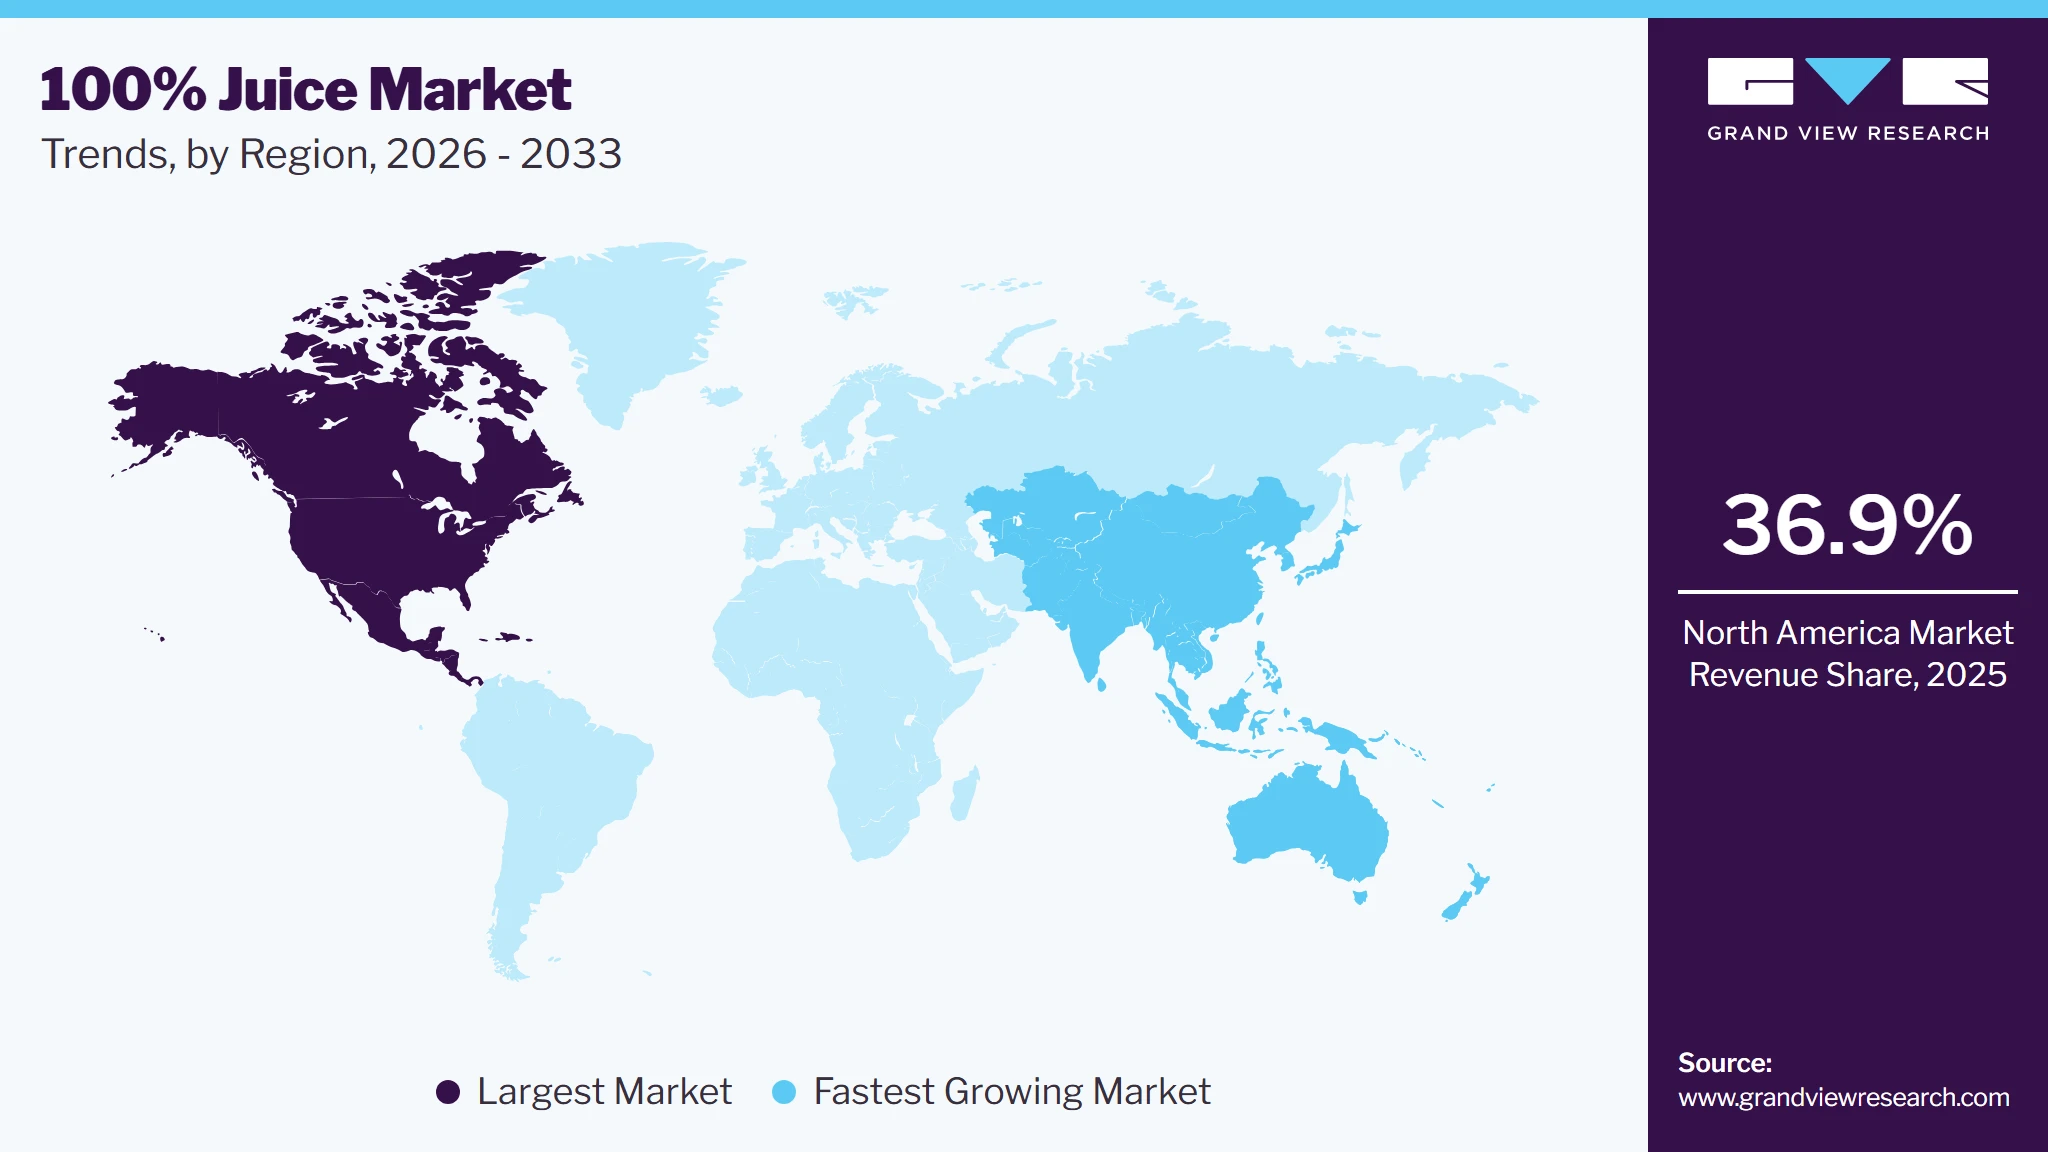
North America dominated the 100% juice market with the largest revenue share of 36.9% in 2025. The market is evolving beyond traditional flavors such as orange, apple, and grape juice. Manufacturers are increasingly experimenting with exotic fruits, blends, and even functional additives like probiotics and vitamins to cater to the adventurous palate of modern consumers. This innovation not only attracts health-conscious individuals but also younger audiences who seek unique beverage experiences. Many juice brands have enhanced their online presence and optimized e-commerce channels, making it easier for consumers to access their favorite products.
 To learn more about this report, Download Free Sample Report
U.S. 100% Juice Market Trends
The 100% juice market in the U.S. held the largest share in the North America region in 2025. The market in the U.S. is experiencing robust growth, fueled by increasing consumer awareness of its health benefits, the rise of wellness trends, and a growing preference for natural and healthy beverages. The preference for clean-label products is rising, and 100% juice made from roasted barley grains without additives fits this trend perfectly.
Europe 100% Juice Market Trends
The 100% juice market in Europe is expected to grow at a CAGR of 7.8% from 2026 to 2033. European consumers are increasingly prioritizing health and wellness, leading to a strong preference for natural, clean-label products. 100% juice, with no added sugars, preservatives, or artificial ingredients, aligns well with this trend. Consumers are particularly interested in juices that offer health benefits, such as those high in vitamins, antioxidants, and other nutrients. Juice manufacturers are increasingly adopting recyclable, biodegradable, and reduced-plastic packaging options to meet consumer expectations and comply with stringent European Union regulations. Cartons made from renewable resources and glass bottles are gaining popularity.
Asia Pacific 100% Juice Market Trends
The 100% juice market in Asia Pacific is expected to witness a CAGR of 8.4% from 2026 to 2033. Consumers in Asia Pacific are increasingly focused on health and wellness, driving demand for 100% packaged juices that are natural and free from added sugars, preservatives, and artificial ingredients. The health benefits associated with consuming pure fruit juices, such as boosting immunity and providing essential nutrients, are key factors in this trend. As consumers become more aware of the potential health risks associated with pesticides and GMOs, there is a rising demand for organic 100% juices. This trend is particularly strong among urban populations in countries such as China, Japan, and Australia, where organic products are increasingly seen as premium and healthier options.
Key 100% Juice Company Insights
The market is characterized by competitive dynamics shaped by a combination of factors, including product innovation, regional production capabilities, and evolving consumer preferences. Leading manufacturers invest in R&D and technological advancements to provide cost-effective and quality products.
Market players are entering into joint ventures, partnerships, mergers, agreements, and acquisitions to strengthen their market position and expand their geographical reach. Key manufacturers in the 100% packaged juice market utilize their expansive distribution networks and robust brand recognition to sustain a substantial market presence. They prioritize quality, innovation, and regional preferences, thereby reinforcing their leadership in international markets that embrace 100% packaged juice.
Key 100% Juice Companies:
The following key companies have been profiled for this study on the 100% juice market.
-
Del Monte Foods, Inc.
-
Suntory Beverage & Food
-
The Hain Celestial Group, Inc.
-
Ocean Spray Cranberries, Inc.
-
Welch Foods Inc.
-
Juice Master Ltd.
-
SUJA LIFE, LLC
-
7-ELEVEN, Inc.
-
Greenhouse Juice Co.
-
Pulp & Press Juice Co.
Competitive Benchmarking
Category
Operating Strategies
Competitive Edge
Weakness
Established Players (Del Monte Foods, Inc., The Hain Celestial Group, Inc., Welch Foods Inc.)
- Strong global retail presence across supermarkets, hypermarkets, convenience stores, and foodservice channels with large-scale cold-chain distribution.
- High brand trust, extensive product portfolios, strong supply chain networks, and heavy marketing investment.
- High competition within packaged beverages, price sensitivity in mass markets, and limited differentiation in basic juice offerings.
Emerging Players (Juice Master Ltd., Greenhouse Juice Co., Pulp & Press Juice Co.)
- Focus on e-commerce, health stores, organic retail outlets, and direct-to-consumer channels with niche positioning in natural/clean-label juices.
- Strong alignment with wellness trends, product innovation in cold-pressed and organic variants, and flexible go-to-market strategies.
- Limited global reach, lower brand recall, and dependence on niche or premium consumer segments.
Recent Developments
-
In April 2024, Tropicana expanded its portfolio by introducing a new line called Tropicana Special Start, along with two additional flavors in its Tropicana Multivit Boost range. The new Tropicana Special Start line features three 100% pure pressed fruit juices: Pink Grapefruit, Sanguinello Blood Orange, and Pineapple. These fruits are sourced from regions chosen for their exceptional taste and color, such as the foothills of Mount Etna, where Tropicana's Sanguinello Blood Orange is harvested.
-
In January 2024, Revl Fruits debuted as a premium juice brand under the name 'Revl Fruits.' Their 100% juice lineup is crafted for enjoyment at any time, whether chilled or blended into your favorite beverages. The collection features four distinct flavors: Boldly Cran, Tart Cherry, Berry Wild, and Truly Tropical.
100% Juice Market Report Scope
Report Attribute
Details
Market size in 2025
USD 34.8 billion
Estimated market size in 2026
USD 37.5 billion
Projected market size by 2033
USD 61.4 billion
Growth rate
CAGR of 7.3% from 2026 to 2033
Base year for estimation
2025
Historical data
2021 - 2024
Forecast period
2026 - 2033
Quantitative units
Revenue in USD million/billion and CAGR from 2026 to 2033
Report coverage
Revenue forecast, company ranking, competitive landscape, growth factors, and trends
Segments covered
Product, type, category, packaging, distribution channel, region
Regional scope
North America; Europe; Asia Pacific; Latin America; MEA
Country scope
U.S.; Canada; Mexico; Germany; UK; France; Italy; Spain; China; India; Japan; Australia & New Zealand; South Korea; Brazil; South Africa
Key companies profiled
Del Monte Foods, Inc.; Suntory Beverage & Food; The Hain Celestial Group, Inc.; Ocean Spray Cranberries, Inc.; Welch Foods Inc.; Juice Master Ltd.; SUJA LIFE, LLC; 7-ELEVEN, Inc.; Greenhouse Juice Co.; and Pulp & Press Juice Co.
Customization scope
Free report customization (equivalent up to 8 analysts' working days) with purchase. Addition or alteration to country, regional & segment scope.
Pricing and purchase options
Avail customized purchase options to meet your exact research needs. Explore purchase options
Global 100% Juice Market Report Segmentation
This report forecasts revenue growth at the global, regional, and country levels and provides an analysis of the latest industry trends and opportunities in each of the sub-segments from 2021 to 2033. For this study, Grand View Research has segmented the global 100% juice market report based on product, type, category, packaging, distribution channel, and region:
-
Product Outlook (Revenue, USD Million, 2021 - 2033)
-
Fruits
-
Orange
-
Apple
-
Grape
-
Mixed Fruit
-
Others
-
-
Vegetables
-
Fruit & Vegetable Blend
-
-
Type Outlook (Revenue, USD Million, 2021 - 2033)
-
Not From Concentrate
-
From Concentrate
-
-
Category Outlook (Revenue, USD Million, 2021 - 2033)
-
Private Label
-
Branded
-
-
Packaging Outlook (Revenue, USD Million, 2021 - 2033)
-
Carton
-
Plastic
-
Glass
-
Others
-
-
Distribution Channel Outlook (Revenue, USD Million, 2021 - 2033)
-
Supermarkets/Hypermarkets
-
Fresh Juice Shop
-
Convenience Stores
-
Online
-
-
Regional Outlook (Revenue, USD Million, 2021 - 2033)
-
North America
-
U.S.
-
Canada
-
Mexico
-
-
Europe
-
UK
-
France
-
Germany
-
Spain
-
Italy
-
-
Asia Pacific
-
China
-
Japan
-
India
-
Australia & New Zealand
-
South Korea
-
-
Central & South America
-
Brazil
-
-
Middle East & Africa
-
South Africa
-
-
Research Methodology
The 100% juice market figures in this report are based on a proven research process that combines executive interviews with secondary research from proprietary databases, company filings, and recognized regulatory and institutional sources. Market size is built through value-chain sizing - reconciling supply-side and demand-side estimates - and triangulated with bottom-up and top-down approaches. Every estimate passes multiple levels of expert validation before publication, with each 100% juice segment quantified using the revenue-capture definitions in the table below.
Segment Definition
Segment - Category
Revenue capture definition
Private Label
Private label 100% juice products are manufactured by third-party producers and sold under a retailer’s own brand name. They are typically positioned as affordable alternatives while still maintaining essential quality standards and are widely used by supermarkets and large retail chains.
Branded
Branded 100% juice products are marketed under established company names with strong identity, packaging, and positioning. They focus on product differentiation, trust, and consistent quality perception to attract loyal consumers and support premium pricing.
Estimation Model
Layer
Guiding Question
Description
Consumption Universe Layer
Who consumes 100% juice (globally)?
Represents the global population consuming beverages in daily diets, including individuals seeking refreshing fruit‑based drinks as part of hydration habits and general wellness routines.
Access & Availability Layer
Who can access 100% juice?
Includes consumers who can easily purchase 100% juice through supermarkets, grocery stores, convenience outlets, online grocery platforms, and foodservice channels.
Purchase & Usage Layer
Who regularly purchases 100% juice?
Covers consumers who actively buy and regularly consume 100% juice as part of meals, breakfast routines, or on‑the‑go refreshment occasions.
Revenue Conversion Layer
How is revenue generated from 100% juice consumers?
Represents monetization through packaged juice sales across varied pack sizes, premium fruit blends, functional juice variants, and value packs.
Delivered Customizations
This report has been delivered with the following In-depth customizations
Client Request
Customization Delivered
Value Adds
100% Juice Market Consumption & Lifestyle Trends
Analyzed rising preference for natural, no-added-sugar, and minimally processed fruit beverages driven by health-conscious routines, daily hydration needs, and reduced intake of carbonated drinks.
Supports understanding of shifting consumer behavior toward wholesome beverage choices and increasing demand for clean-label refreshment alternatives.
100% Juice Product Innovation & Premiumization Trends
Evaluated advancements in cold-pressed juices, functional fruit blends, reduced-sugar formulations, and premium exotic fruit variants supported by sustainable sourcing and packaging innovations.
Identifies opportunities for differentiation, premium positioning, and alignment with evolving demand for natural yet value-added juice offerings.
100% Juice Health & Functional Benefit Positioning
Examined increasing focus on immunity support, vitamin enrichment, and antioxidant-rich formulations as key drivers shaping product positioning strategies in the beverage space.
Reveals opportunities for functional claim-based differentiation and stronger alignment with wellness-oriented consumer expectations.
Frequently Asked Questions About This Report
The global 100% juice market size was valued at USD 34.8 billion in 2025 and is estimated at USD 37.5 billion for 2026.
North America dominated with a 36.9% revenue share in 2025.
Asia Pacific is the fastest-growing region over the forecast period.
The 100% fruit juice segment led with a 90.3% revenue share in 2025.
The Not From Concentrate (NFC) segment led the market with the largest revenue share of 74.1% in 2025.
Private label segment led the market with the largest revenue share of 42.2% in 2025.
Key players include Del Monte Foods, Inc.; Suntory Beverage & Food; The Hain Celestial Group, Inc.; Ocean Spray Cranberries, Inc.; Welch Foods Inc.; Juice Master Ltd.; SUJA LIFE, LLC; 7-ELEVEN, Inc.; Greenhouse Juice Co.; and Pulp & Press Juice Co.
The global 100% juice market is expected to grow at a CAGR of 7.3% from 2026 to 2033, reaching USD 61.4 billion by 2033
Key factors include growing consumer awareness of health and wellness, increasing demand for natural and nutrient-rich beverages, and a preference for clean-label, preservative-free products.
About the Author(s)
Consumer F&B Research Team
Consumer Goods · Consumer F&BThis report was authored by the consumer f&b research team at Grand View Research - comprising two research analysts, one senior research analyst, and one industry expert - with specialized expertise in the consumer f&b segment of the consumer goods industry. All findings are based on proprietary consumer goods databases, executive interviews, and regulatory analysis, subject to internal peer review prior to publication.
Last Updated:
Speak to Analyst

Customize this report to your needs - add regions, segments, or data points, with 20% free customization.
Or view our licence options:


ISO 9001:2015 & 27001:2022 Certified
We are GDPR and CCPA compliant! Your transaction & personal information is safe and secure. For more details, please read our privacy policy.


