
- Home
- »
- Medical Devices
- »
-
3D Medical Imaging Devices Market Size Report, 2026-2033GVR Report cover

3D Medical Imaging Devices Market (2026 - 2033)
Size, Share & Trends Analysis Report By Device Type (Hardware, Software), By Application (Oncology, Cardiology), By End Use (Hospitals, Diagnostic Imaging Centers), By Region, And Segment Forecasts
Market Size, 2025
$10.7BMarket Estimate, 2026
$11.4BMarket Forecast, 2033
$17.3BCAGR, 2026–2033
6.2%3D Medical Imaging Devices Market Summary
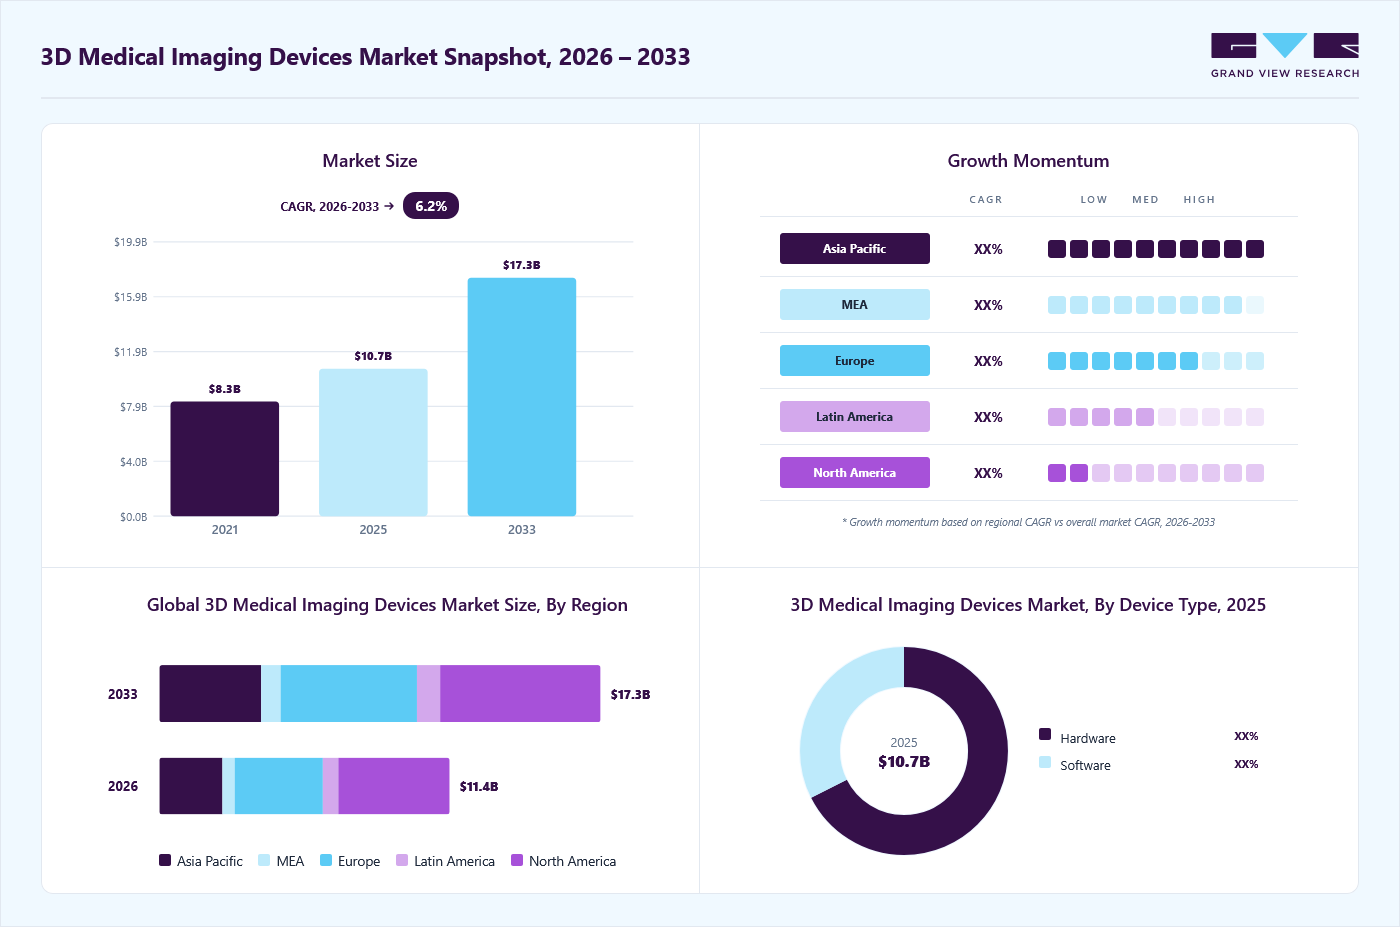
The global 3D medical imaging devices market size was valued at USD 10.7 billion in 2025 and is projected to grow from USD 11.4 billion in 2026 to USD 17.3 billion by 2033, at a CAGR of 6.2% from 2026 to 2033. North America dominated the global market with the largest revenue share of 38.6% in 2025. The rising prevalence of chronic disorders, an increasing preference for minimally invasive procedures, technological advancements and the growing aging population are the major factors contributing to the overall 3D medical imaging devices industry growth.
 Source: Grand View Research, IR Documents, Primary Interviews, Paid DatabasesTo learn more about this report,
 Download Free Sample Report
Key Market Trends & Insights
- By device type: Hardware segment led the market with the largest revenue share of 67.5% in 2025.
- By application: Oncology segment led the market with the largest revenue share of 33.1% in 2025.
- By end use: Hospitals segment led the market with the largest revenue share of 48.3% in 2025.
Regional Highlights
- Largest regional market: North America (38.6% revenue share, 2025)
- By country: The U.S. held the largest market share in 2025.
Market Size & Forecast
- Market size in 2025: USD 10.7 Billion
- Estimated market size in 2026: USD 11.4 Billion
- Projected market size by 2033: USD 17.3 Billion
- CAGR (2026-2033): 6.2%
Prism AI by Grand View Research Free to tryAsk a question about the 3D medical imaging devices marketTry asking✓Every figure cited from GVR research Prefer the report? Download free sample →
The growing prevalence of chronic disorders such as CVDs, Cancer, Neurological conditions and many others are further contributing to the 3D medical imaging devices industry growth. According to the data published by the International Agency for Research on Cancer, approximately 19,976,499 cancer cases were identified worldwide in 2022. These conditions frequently necessitate accurate and detailed imaging for early detection, diagnosis, and treatment planning. Medical 3D imaging technologies, including MRI and CT scans, provide healthcare professionals with three-dimensional views of anatomical structures and abnormalities, enhancing decision-making and improving patient care.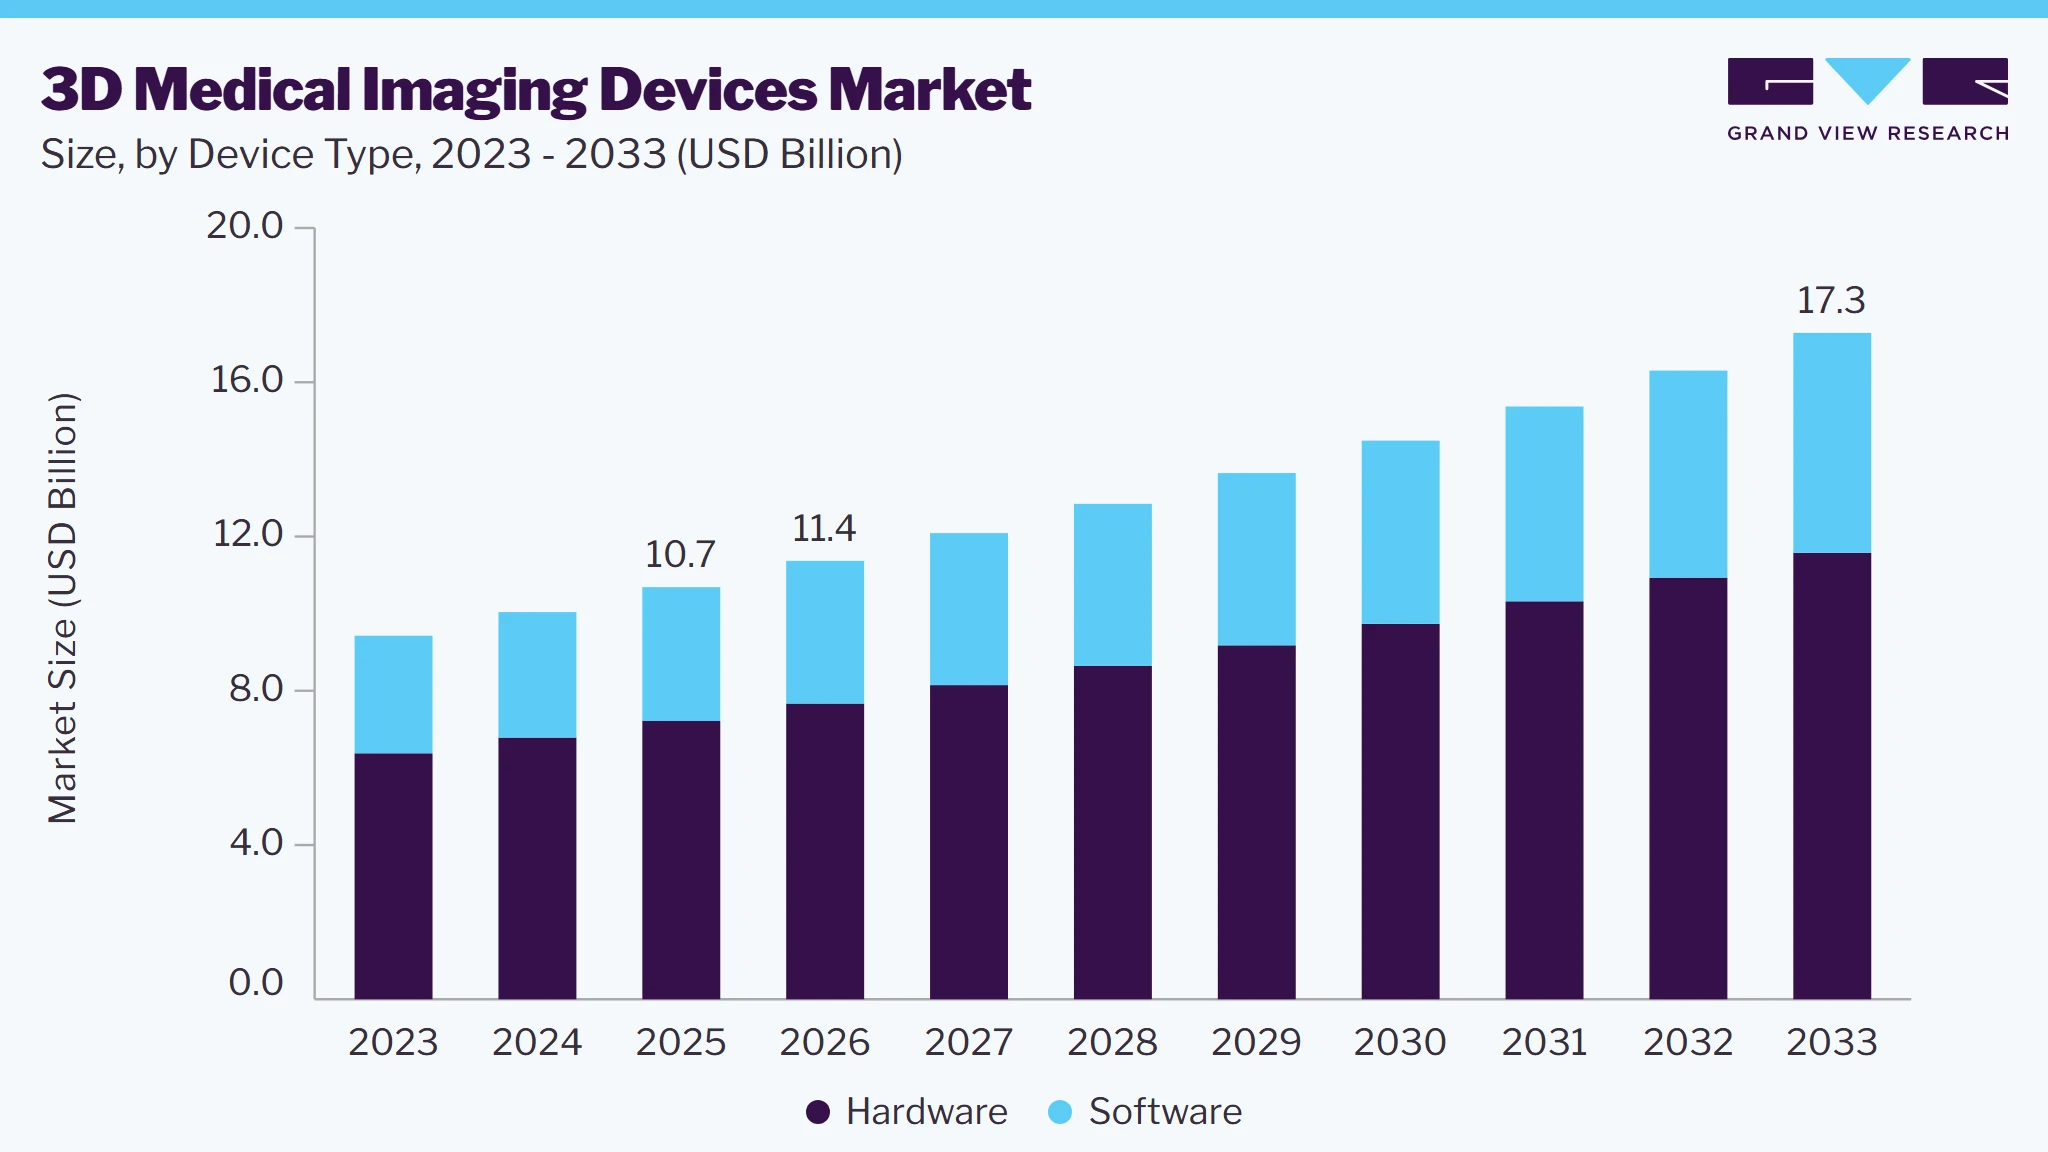 To learn more about this report, Download Free Sample Report
The evolution of 3D medical imaging has improved its efficiency, providing healthcare professionals with better tools for accurate diagnosis and treatment planning. These technologies allow for detailed visualization of anatomical structures, aiding in the detection and management of complex conditions. Furthermore, continuous advancements, such as improved imaging quality, integration of AI, and enhanced device capabilities, are further supporting the growth of the market. These innovations not only improve diagnostic accuracy but also streamline processes, making 3D imaging an increasingly essential part of modern healthcare.
The growing preference for minimally invasive procedures is further driving the adoption of 3D imaging technologies in surgical and interventional settings. These advanced imaging devices provide detailed and accurate visualization of complex anatomical structures, enabling surgeons and interventional radiologists to plan procedures more effectively. By using 3D images, they can navigate challenging areas with greater precision, ensuring that treatment is accurately targeted while minimizing damage to surrounding tissues. This approach not only enhances the safety and efficacy of procedures but also contributes to shorter recovery periods, reduced risks of complications, and improved overall patient outcomes. As the advantages of minimally invasive techniques become important to healthcare providers, the 3D medical imaging devices is expected to grow further.
Market Dynamics
3D medical imaging devices market solutions are gaining significant traction as they enable hospitals, academic medical centers, and specialized diagnostic clinics to address, treat, and optimize patient care through advanced volumetric visualization platforms. These solutions integrate technologies such as multi-row photon-counting detectors, high-throughput hybrid configurations, deep learning image reconstruction architectures, smart radiation dose-optimization algorithms, and AI-driven clinical dashboards to provide real-time control over scan parameters, multi-planar anatomical structures, automated lesion detection, and quantitative treatment efficacy. 3D medical imaging platforms help healthcare providers and radiology practitioners address the rising global demand for early and precise chronic disease management by supporting personalized surgical pre-planning, targeted oncological staging, advanced myocardial perfusion imaging, and proactive neurodegenerative disease tracking.
The rapidly expanding global geriatric population serves as a primary catalyst for the growth of the 3D medical imaging devices market. Aging is naturally accompanied by biological vulnerability, creating an increased risk for complex, age-related chronic conditions such as cardiovascular disease, progressive cancers, musculoskeletal degeneration, and neurodegenerative disorders like Alzheimer’s disease. Underscoring this demographic push, data from the United Nations Population Division projects that the global population of individuals aged 65 and older is on track to double within the next 30 years, reaching an estimated 1.6 billion by 2050. Similarly, the World Health Organization (WHO) outlines that the global segment of people aged 60 and older will scale up from 1 billion to 1.4 billion by 2030. Moreover, traditional 2D planar imaging often falls short in providing the depth and structural resolution required to safely diagnose or navigate treatments in fragile, elderly patients. Consequently, there is a surging clinical reliance on high-dimensional 3D medical imaging modalities such as 3D Computed Tomography (CT), 3D Magnetic Resonance Imaging (MRI), and Cone Beam CT (CBCT) which deliver precise spatial resolution, multi-planar anatomical tracking, and clearer tissue differentiation.
The high capital acquisition and operational costs associated with advanced 3D medical imaging devices act as a significant restraint on the growth of the global market. Procuring top-tier 3D-capable systems, such as premium multi-slice CT scanners, high-field MRI units, and advanced hybrid configurations, requires a massive upfront capital expenditure (CapEx) that often strains the budgets of mid-sized hospitals, outpatient centers, and facilities in emerging economies. Beyond the initial purchase price, healthcare providers must absorb substantial ongoing operational expenses (OpEx), including specialized facility renovation for radiation shielding, complex software licensing fees, high energy consumption, and premium long-term service maintenance contracts. Additionally, the need for specialized training for radiologic technologists and biomedical engineers to operate and maintain these sophisticated volumetric platforms further escalates the total cost of ownership. Consequently, these compounding financial barriers delay equipment replacement cycles, limit widespread clinical adoption, and widen the technological gap between well-funded urban medical centers and resource-constrained rural or public healthcare facilities.
Market Concentration & Characteristics
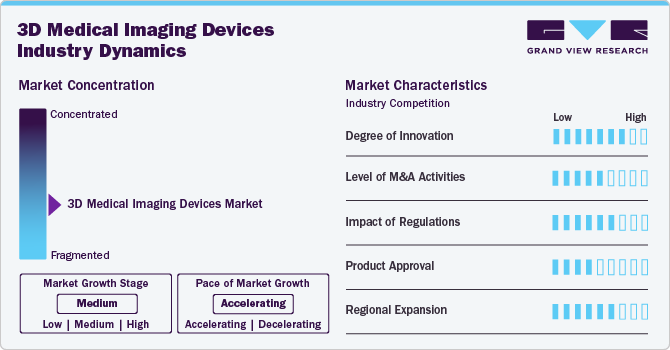
The 3D medical imaging devices industry is growing at a significant rate. This is because of the increasing need for advanced diagnostics. These devices allow healthcare professionals to view detailed, three-dimensional images of anatomical structures, offering greater clarity and precision. This detailed visualization is particularly useful in surgical planning, where accurate imaging helps doctors navigate complex areas of the body, reducing the risk of complications and improving patient outcomes. The ability to see structures in 3D enhances diagnostic accuracy, which is essential for detecting and treating a wide range of conditions. As the demand for more precise and effective diagnostic technologies rises, the adoption of 3D medical imaging devices continues to expand, making them an essential part of modern healthcare.
Companies in the 3D medical imaging devices industry are increasingly focusing on strategic product launches as a key approach to securing a significant share. By introducing innovative and advanced products, these companies aim to meet the growing demand for high-quality diagnostic tools that offer greater precision and efficiency. In November 2023, Boston Imaging, the U.S. division of Samsung's digital radiography and ultrasound business, announced the launch of the V6, a new ultrasound system offering advanced imaging capabilities in 2D, 3D, and color, specifically designed for Women's Health and Urology.
 To learn more about this report, Download Free Sample Report
The 3D medical imaging devices industry is marked by a high degree of innovation, fueled by technological advancements and the increasing need for more precise and efficient diagnostic solutions. As healthcare demands increase, there is a continuous push to develop imaging systems that offer superior resolution, enhanced accuracy, and faster processing times.
Industry players in the 3D medical imaging devices industry are actively engaging in mergers and acquisitions (M&A) as part of their strategy to strengthen their position, expand their product portfolios, and enhance technological capabilities. In July 2024, GE HealthCare announced that it has reached an agreement to acquire the clinical artificial intelligence (AI) software business of Intelligent Ultrasound Group PLC for a total of approximately USD 51 million.
Regulations have a significant impact on 3D medical imaging devices, as they ensure these technologies are safe, effective, and of high quality. Regulatory organizations like the U.S. Food and Drug Administration (FDA), the European Medicines Agency (EMA), and other national health authorities set strict standards for the development, testing, and approval of medical imaging devices.
Manufacturers are introducing new products in the industry as part of their efforts to remain competitive in an increasingly dynamic industry. For instance, in September 2024, PIUR IMAGING, a provider of tomographic 3D ultrasound technology, announced that its product, PIUR tUS Infinity, had received FDA approval. This approval is a major milestone, allowing the company’s advanced ultrasound technology to be introduced to the U.S. for the first time.
The geographical reach of the 3D medical imaging devices industry is steadily growing, driven by the increasing demand for advanced healthcare solutions, the expansion of healthcare infrastructure, and a greater awareness of the benefits of 3D imaging technologies. Adoption of these devices is notably rising in regions such as Asia Pacific, Latin America, and the Middle East, as these areas experience significant improvements in healthcare facilities and access to advanced diagnostic devices.
Analyst Perspective
The 3D medical imaging devices market is positioned at the intersection of several long-term healthcare and life science industry trends, including the growing demand for precision medicine, an increasing clinical focus on high-dimensional diagnostic accuracy, and continuous advancements in multi-row, energy-sensitive detector technologies. Rising global incidences related to oncological malignancies, complex cardiovascular conditions, and musculoskeletal or neurodegenerative disorders are creating significant opportunities for 3D medical imaging equipment manufacturers and healthcare infrastructure developers, as clinicians seek definitive, non-invasive volumetric imaging solutions to map complex spatial anatomical features and structural anomalies with extreme precision. In addition, the expanding adoption of advanced 3D platforms across multi-specialty hospitals, standalone diagnostic imaging chains, and academic research institutions coupled with core technological innovations such as multi-row photon-counting detectors, high-throughput hybrid configurations, and AI-driven deep learning image reconstruction architectures is significantly improving diagnostic sensitivity, reducing patient radiation or contrast exposure, and optimizing pre-surgical planning and therapeutic tracking workflows.
Device Type Insights
Based on device type, the hardware segment led the market with the largest revenue share of 67.5% in 2025. Hardware components are an essential part of any medical imaging device, serving as the foundation for technologies like MRI machines, CT scanners, and ultrasound devices. These essential components play a significant role in medical imaging, and healthcare institutions are making substantial investments in hardware to ensure optimal patient outcomes. As the use of 3D imaging increases, along with its various benefits, the segment is expected to experience further growth. The presence of major market players such as Koninklijke Philips N.V., Siemens Healthcare GmbH, GE Healthcare, and Shenzhen Mindray Bio-Medical Electronics Co., Ltd, all of which offer extensive portfolios of these devices, is a key factor driving segment growth.
The software is expected to grow at a fastest CAGR of 8.3% over the forecast period. Software plays an important role in improving the quality and functionality of images produced by hardware devices such as MRI, CT scanners, and ultrasound machines. These software solutions utilize advanced algorithms and image processing techniques to create detailed 3D reconstructions, enhance image contrast, and eliminate noise. As the demand for more accurate and detailed diagnostics continues to grow, healthcare providers are increasingly relying on these software tools to extract valuable insights from imaging data, driving the demand for advanced software solutions. The growth of this segment is supported by the presence of major industry players, such as GE Healthcare. For example, GE Healthcare's Innova 3D software generates 3D images from angiography, aiding in the visualization of complex vasculature. Similarly, Philips offers quantification software like QLAB for general imaging analysis. These factors are expected to contribute to the continued growth and strong market presence of the software segment over the forecast period.
Application Insights
Based on application, the oncology segment led the market with the largest revenue share of 33.1% in 2025. This is driven by the rising incidence of cancer worldwide, which has led to an increasing demand for advanced diagnostic and treatment tools. 3D medical imaging devices, including CT, MRI, and PET-CT scanners, are essential in oncology as they provide detailed, accurate images of tumors and the surrounding tissues. These technologies are critical for cancer diagnosis, staging, treatment planning, and ongoing monitoring, making them a key component in the effective management of cancer patients.
The cardiology segment is projected to witness the fastest CAGR of 8.4% during the forecast period. Cardiac interventions, including catheter-based procedures, minimally invasive surgeries, and structural heart interventions, have become more complex. Cardiologists now require detailed 3D images of the heart and its vasculature to effectively plan and guide these procedures. Devices such as 3D echocardiography and cardiac CT/MRI offer the critical anatomical information needed, enhancing the precision and safety of these interventions. The rising incidence of cardiac conditions, such as heart attacks, cardiac arrest, and other cardiovascular diseases, is expected to drive the growing use of 3D imaging. For instance, the American Heart Association reports that over 356,000 cases of total cardiac arrest occur annually in the U.S.
End Use Insights
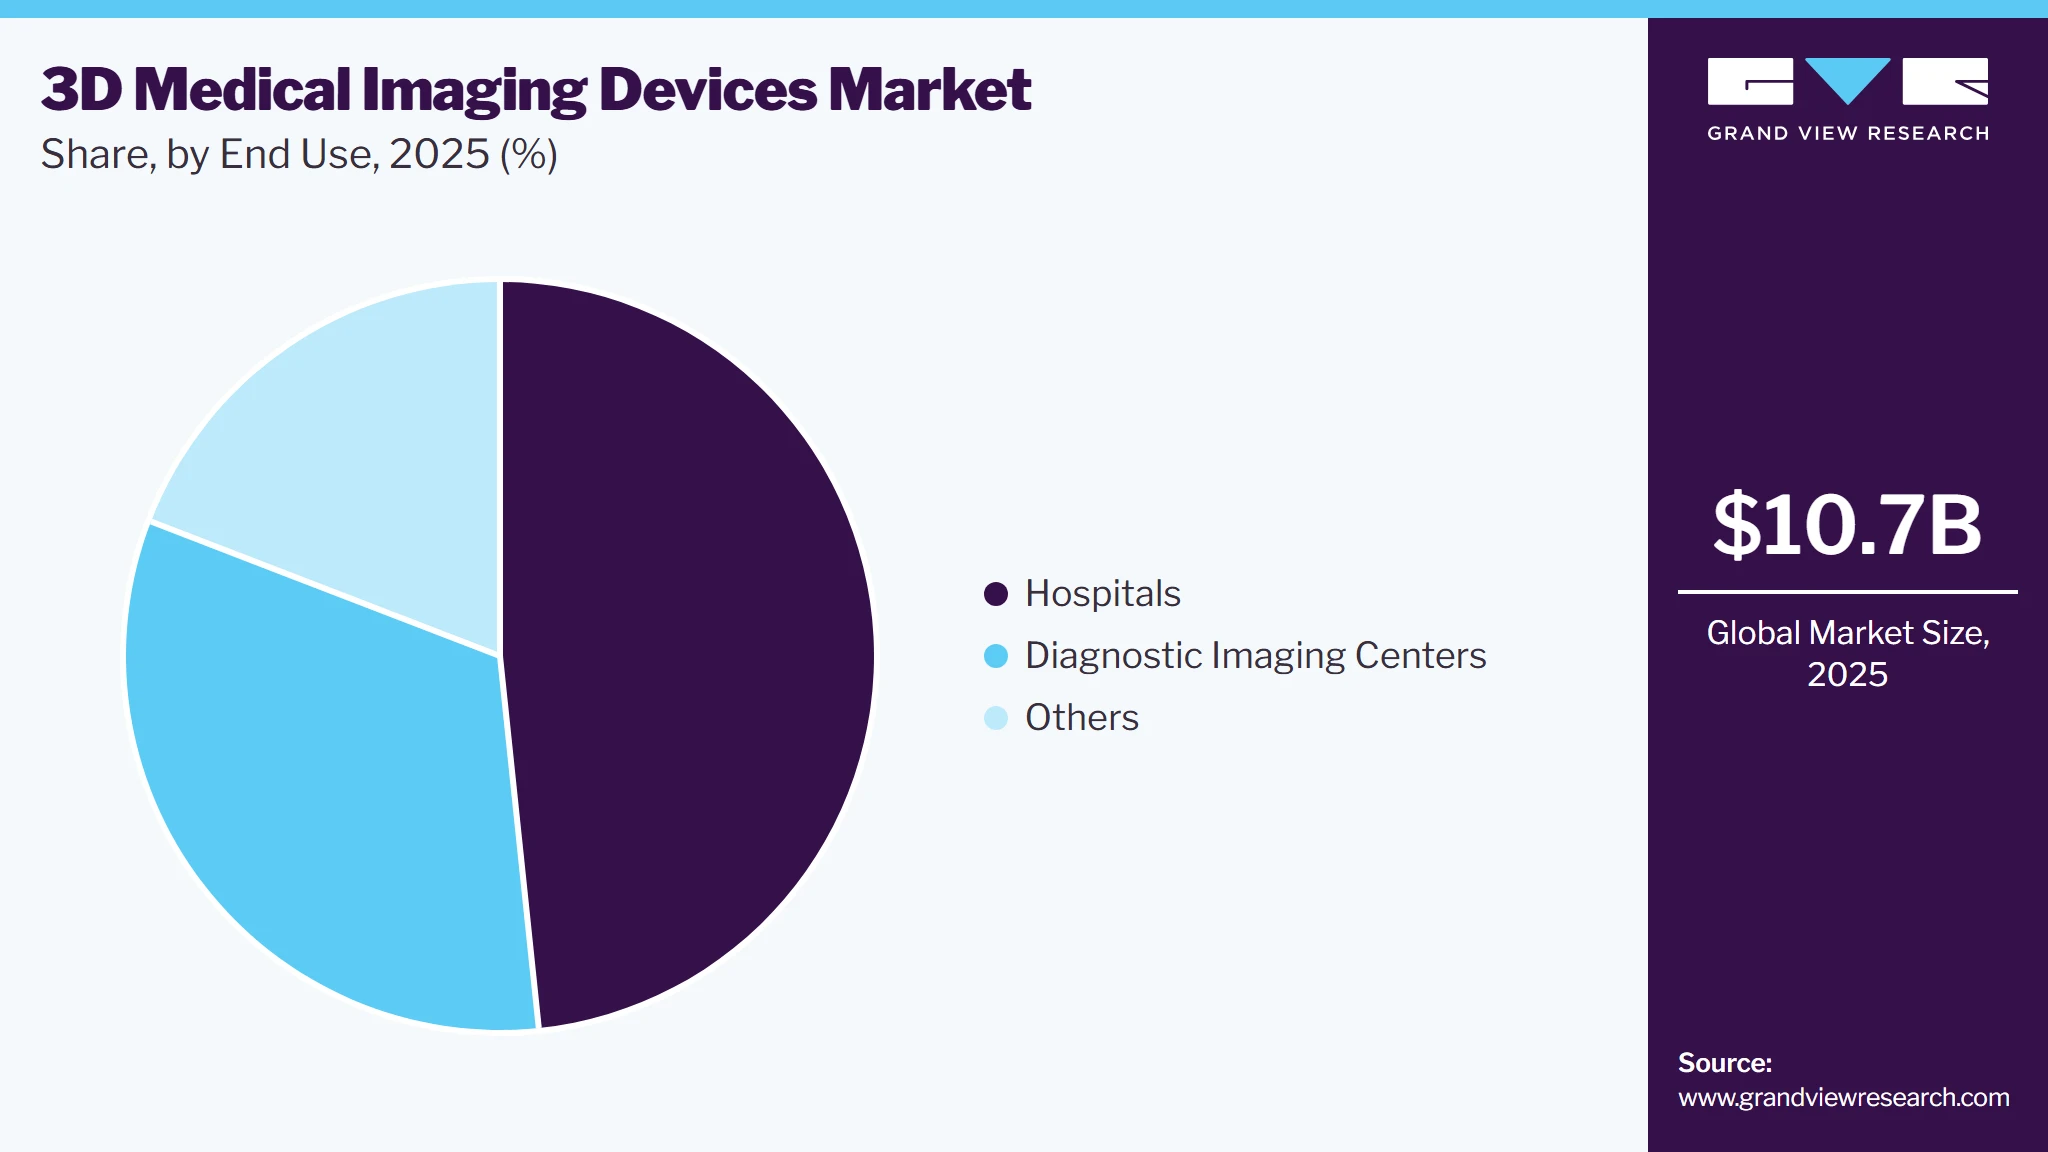
Based on end use, the hospitals segment led the market with the largest revenue share of 48.3% in 2025. This is because it offers a wide range of diagnostic, therapeutic, and surgical services, which makes them the primary users of 3D medical imaging devices. These devices are essential for diagnosing and monitoring various medical conditions, from cancer and cardiovascular diseases to orthopedic and neurological disorders, allowing hospitals to offer a complete spectrum of healthcare services. Moreover, the hospitals segment is expected to witness growth due to several factors such as high adoption of image-guided therapy systems in hospitals, high volume of surgeries undertaken at hospitals, and hospitals being considered as primary health systems in several countries. Moreover, the installation of image-guided therapy systems at hospitals has demonstrated several positive results in terms of cost-effectiveness and optimization of clinical workflows. Furthermore, large hospitals usually have in-house medical imaging facilities, which is estimated to propel segment growth.
 To learn more about this report, Download Free Sample Report
The diagnostic imaging centers segment is projected to witness the fastest CAGR of 8.4% during the forecast period. These centers provide faster appointments and shorter wait times for patients compared to hospitals. This quick access to diagnostic services is especially attractive for individuals needing non-emergency imaging, such as routine screenings, preventive check-ups, and follow-up studies. As healthcare trends increasingly focus on efficiency and convenience, diagnostic imaging centers are well-positioned to meet these needs. In many cases, these centers also serve as disease detection hubs, providing physicians with results that support further diagnosis and treatment. As awareness grows and technology continues to advance, the segment is expected to experience significant growth.
Regional Insights
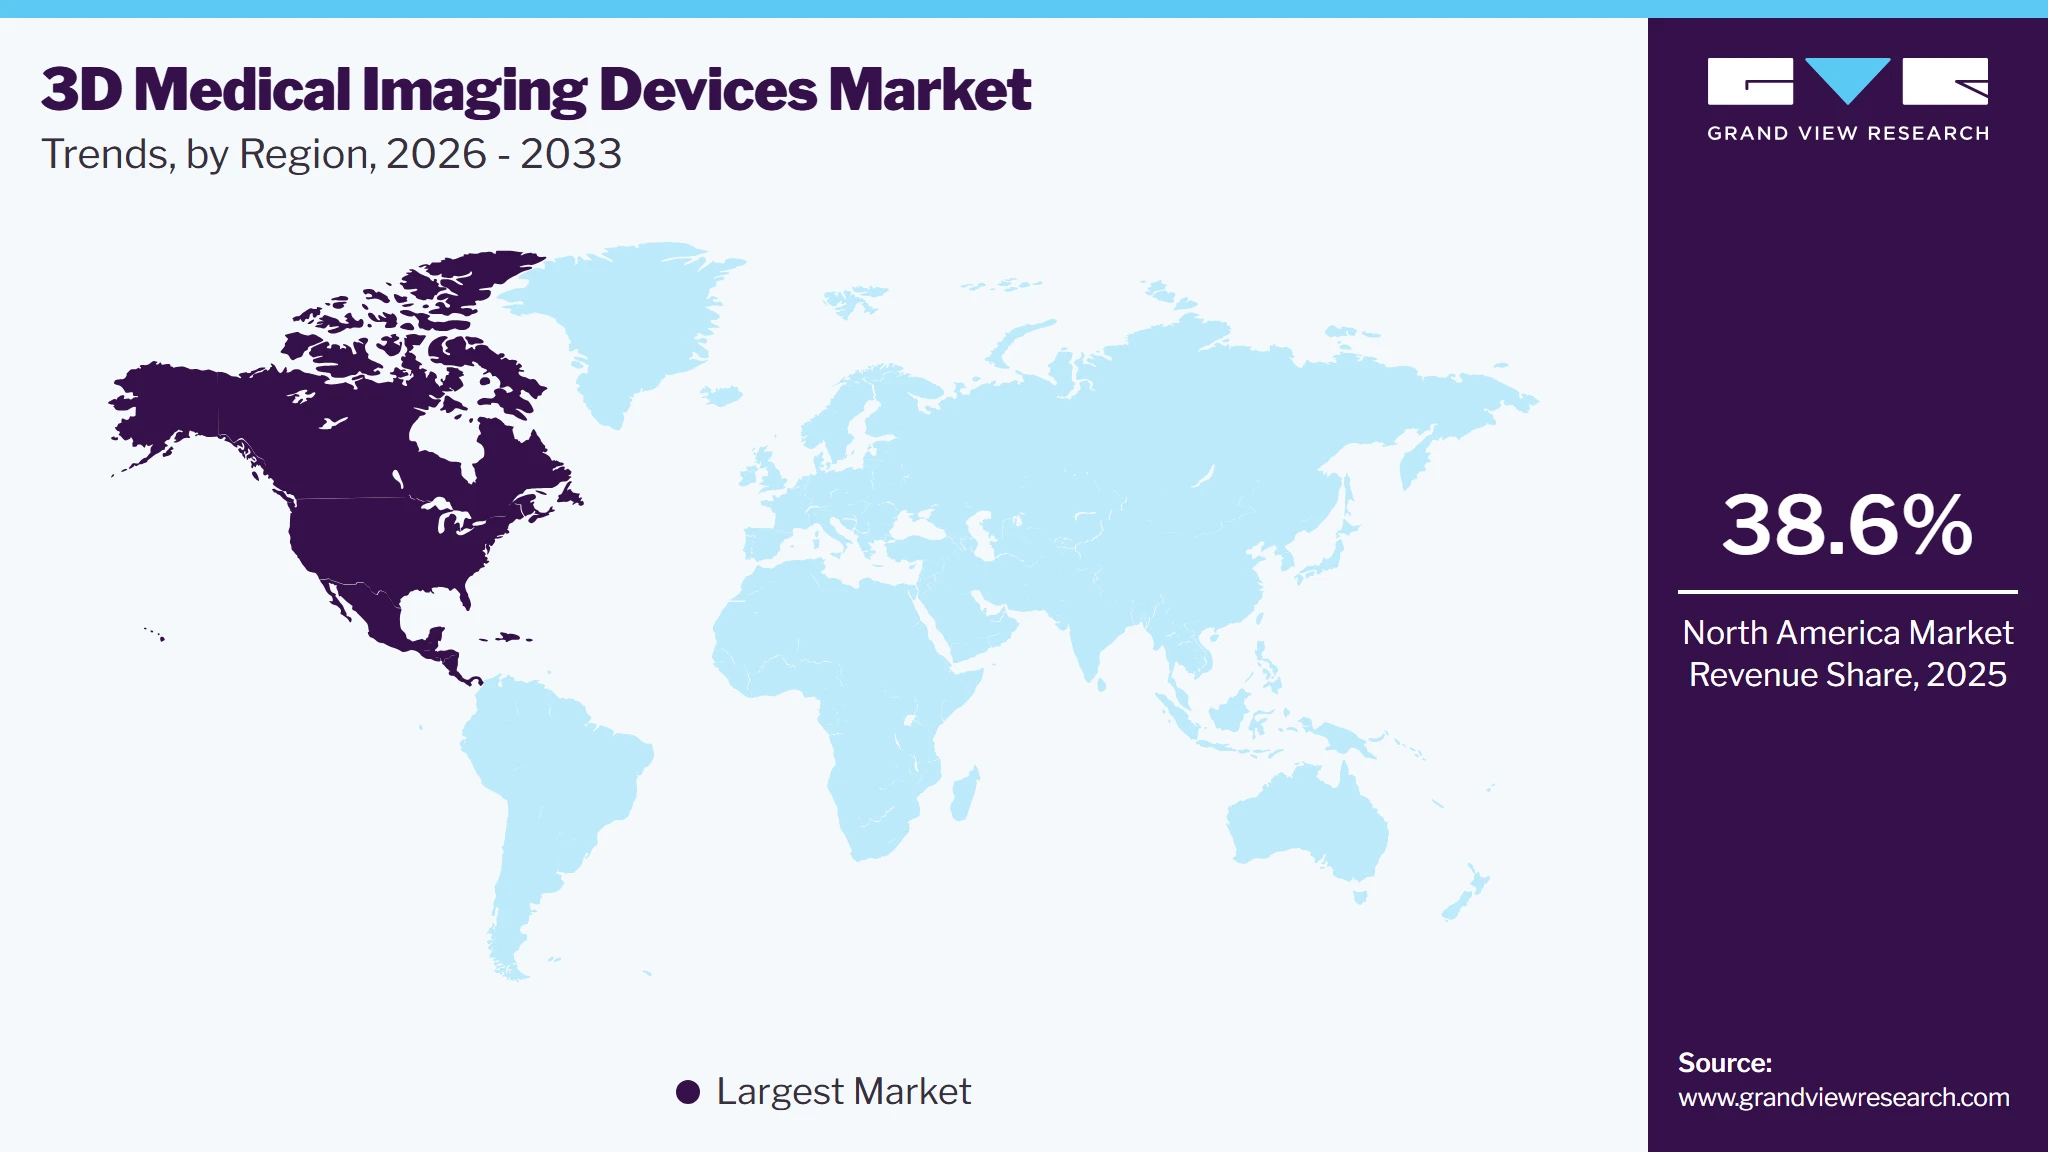
North America dominated the 3D medical imaging devices market with the largest revenue share of 38.6% in 2025. This is owing to the presence of major market players, the increasing prevalence of chronic conditions such as cancer, diabetes, cardiovascular diseases (CVDs), and the expanding geriatric population. Major players in the market contribute to the development of innovative 3D medical imaging technologies, enhancing diagnostic capabilities and improving patient outcomes.
 To learn more about this report, Download Free Sample Report
U.S. 3D Medical Imaging Devices Market Trends
The 3D medical imaging devices market in the U.S. held the largest share in the North America region in 2025. This is attributed to the presence of key manufacturers that ensure the availability of advanced products and technologies in the country. In addition, these companies are continuously innovating and integrating various technologies to stay competitive. For instance, in June 2023, GE HealthCare announced the FDA approval and product launch of Sonic DL, a deep learning-based technology designed to significantly speed up image acquisition in Magnetic Resonance Imaging (MRI).
Europe 3D Medical Imaging Devices Market Trends
Europe 3D medical imaging devices market held a significant market share in 2024, this is owing to the presence of key market players and the strategic initiatives they are undertaking in the region, such as product introductions and technological innovations. For instance, in February 2024,PIUR IMAGING, a European provider of independent tomographic 3D ultrasound solutions, introduced the PIUR tUS Infinity 4 for Thyroid. This technology marks a major leap forward in tomographic 3D ultrasound imaging, establishing new industry benchmarks for speed, accuracy, and overall user experience.
UK 3D medical imaging devices market is experiencing significant growth, driven by the adoption of advanced technologies in this country. In April 2024, plans were unveiled to construct the UK's most powerful MRI scanner in Nottingham, aimed at addressing conditions like Alzheimer's disease.MRI creates 3D internal images of the body by utilizing strong magnetic fields and radio waves. According to the University of Nottingham, the new MRI machine will operate at temperatures as low as -270°C and be 1,000 times more powerful than the machines first developed in the 1970s. The advanced scanner is expected to be operational by late 2026 or early 2027.
The France 3D medical imaging devices market is expected to grow over the forecast period. The rising prevalence of chronic disorders in the country is becoming a significant healthcare concern. As a result, there is growing awareness among the population about available treatment and diagnostic options. This growing awareness is expected to drive the growth of the market.
Germany 3D medical imaging devices marketis experiencing significant growth, driven by the increasing initiatives undertaken by major market players in this country. For instance, in October 2024, GE HealthCare has announced a collaboration with University Medicine Essen in Germany to create a new Theranostics Centre of Excellence. The centre will focus on integrating theranostics into clinical practice and advancing research into more personalized cancer care approaches. As part of the partnership, GE HealthCare will supply equipment for the university's new radiotracer development centre.
Asia Pacific 3D Medical Imaging Devices Market Trends
Asia Pacific 3D medical imaging devices market is expected to witness the fastest growth of CAGR 8.5% over the forecast period. This growth is primarily driven by the increasing prevalence of chronic disorders and the rising demand for advanced medical devices. In addition, growing awareness among the population about the benefits of these devices, coupled with improvements in healthcare infrastructure and better access to advanced technologies, is further accelerating the adoption of 3D medical imaging devices in the region.
Japan 3D medical imaging devices market is significantly driven by growing initiatives in the country. In September 2024, Clarius Mobile Health, a provider of high-definition handheld ultrasound systems, has entered into a new distribution agreement with Marubun Corporation, electronics trading company listed on the Tokyo Prime Market in Japan. Under this agreement, Marubun is authorized to sell Clarius wireless ultrasound scanners to hospitals and specialty clinics across Japan.
China 3D medical imaging devices market is expected to grow over the forecast period. This growth is primarily driven by the increasing prevalence of chronic diseases, rising healthcare spending, and advancements in medical technology. In addition, the expanding healthcare infrastructure, greater awareness of advanced diagnostic tools, and the growing demand for more precise and efficient imaging solutions are also contributing to the market's expansion.
Latin America 3D Medical Imaging Devices Market Trends
Latin America 3D medical imaging devices market is expected to grow owing to the rising demand for advanced diagnostic tools and increasing awareness among the population. As healthcare providers strive to deliver more accurate and timely diagnoses, there is a growing emphasis on utilizing advanced imaging technologies such as 3D medical imaging to improve patient outcomes. The increasing prevalence of chronic diseases, such as cancer, cardiovascular diseases, and diabetes, further fuels the need for advanced diagnostic devices.
Middle East & Africa 3D Medical Imaging Devices Market Trends
Middle East & Africa 3D medical imaging devices market is experiencing notable growth, driven by factors such as increasing healthcare investments, advancements in medical technology, and growing awareness about the benefits of 3D imaging. Rising rates of chronic diseases and an aging population are further fueling the demand for more accurate and efficient diagnostic tools. In addition, improvements in healthcare infrastructure, along with expanding access to advanced medical devices in both urban and rural areas, are contributing to the adoption of 3D medical imaging technologies. The region's focus on enhancing healthcare quality and expanding diagnostic capabilities is expected to continue driving the growth of the 3D medical imaging devices industry.
Key 3D Medical Imaging Devices Company Insights
Key players in the 3D medical imaging devices industry are adopting several strategic initiatives to mark their market presence and drive growth. These include significant investments in research and development aimed at innovating and enhancing product offerings, expanding their portfolios to include a broader range of imaging solutions, strategic collaborations, partnerships, and acquisitions to increase their reach, access new markets, and leverage complementary technologies. These efforts are helping to meet the evolving needs of healthcare providers, while simultaneously contributing to the continued expansion of the 3D medical imaging devices industry.
Key 3D Medical Imaging Devices Companies
The following key companies have been profiled for this study on the 3D medical imaging devices market.
-
Siemens Healthineers
-
Esaote SpA
-
Koninklijke Philips N.V.
-
GE Healthcare Ltd.
-
Canon Medical Systems
-
Hitachi Medical Systems
-
Shimadzu Corporation
-
DigiRad Corporation
-
Del Medical Systems Inc
Competitive Benchmarking
Category
Operating Strategies
Competitive Edge
Weakness
Established Players (Siemens Healthineers, Esaote SpA, Koninklijke Philips N.V.)
- Focus on expanding high-tier, multi-modality 3D imaging hardware portfolios including photon-counting 3D CT, high-field (3T and 7T) MRI, and matrix-transducer 4D ultrasound systems tailored for complex anatomical visualization, oncology staging, and micro-structural diagnostics.
- Emphasize strategic enterprise integrations with multi-specialty hospital networks, academic medical centers, and large-scale diagnostic imaging chains through multi-year capital procurement agreements and unified PACS/cloud-based software subscriptions to strengthen global market share.
- Strong global brand equity, deeply entrenched institutional footprints, fully established worldwide distribution networks, and premium field-service engineering teams that guarantee minimal scanner downtime across major healthcare markets.
- Advanced institutional R&D capabilities coupled with proprietary deep learning image reconstruction (DLIR) engines, allowing for photorealistic cinematic rendering, ultra-low radiation dose profiles, and unmatched spatial resolution.
- Staggering product development costs, prolonged regulatory compliance timelines (e.g., FDA 510(k), EU MDR), and high upfront capital expenditure requirements that slow down agility in price-sensitive emerging economies.
- Intensifying pricing pressure and market commoditization in mid-tier and legacy 2D/3D configuration segments, where standard diagnostic requirements create pushback against high-premium capital equipment investments.
Emerging Players (DigiRad Corporation, Del Medical Systems Inc, Shimadzu Corporation)
- Focus on niche, cost-competitive, and application-specific 3D systems such as dental Cone Beam CT (CBCT), orthopedic-specific extremity scanners, and ultra-portable, handheld 3D point-of-care ultrasound (POCUS) devices targeting outpatient clinics and ambulatory surgical centers (ASCs).
- Prioritize software-driven innovation by developing vendor-neutral, AI-powered advanced visualization applications that seamlessly overlay onto existing legacy hardware to automate organ segmentation and lesion tracking with enhanced diagnostic longevity.
- Accelerated product innovation cycles and highly flexible commercialization frameworks enabling rapid responses to fast-moving healthcare IT trends and specific radiology workflows.
- Aggressive, competitive pricing strategies that dismantle barriers to entry, enabling faster adoption among standalone imaging facilities, smaller community clinics, and rural hospital systems with restricted capital budgets.
- Constrained financial runways, lower baseline brand awareness, and highly localized or single-region distribution networks when measured against multi-billion-dollar global medical equipment conglomerates.
- Persistent hurdles regarding multi-region regulatory clearances, lack of decades-long longitudinal clinical data, and lower physician familiarity, which can collectively trigger long sales cycles and slow down widespread clinical adoption.
Recent Developments
-
In October 2024, GE HealthCare announced the launch of the Versana Premier, the newest addition to its Versana ultrasound family. This advanced system is designed to offer a combination of reliability, affordability, ease of use, and versatility, making it a valuable tool for a wide range of clinical applications.
-
In October 2024, GE HealthCare announced the establishment of a new AI Innovation Lab, aimed at accelerating early-stage AI innovations within the company. This initiative is part of GE HealthCare's broader AI and digital strategy, which focuses on integrating artificial intelligence into medical devices and developing AI applications that enhance decision-making throughout the care journey and various disease states.
-
In September 2024, Siemens Healthineers announced the FDA has granted premarket approval (PMA) for the Mammomat B.brilliant, a tomosynthesis or three-dimensional breast imaging technology. This approval includes new 3D image acquisition and reconstruction technology, further enhancing the system's capabilities. In addition to its previous clearance for full-field digital mammography (2D imaging), breast biopsy, and titanium contrast-enhanced mammography, the new features enable more advanced breast imaging.
3D Medical Imaging Devices Market Report Scope
Report Attribute
Details
Market size in 2025
USD 10.7 billion
Estimated market size in 2026
USD 11.4 billion
Projected market size by 2033
USD 17.3 billion
Growth rate
CAGR of 6.2% from 2026 to 2033
Historical data
2021 - 2024
Forecast period
2026 - 2033
Quantitative units
Revenue in USD million/billion and CAGR from 2026 to 2033
Report coverage
Revenue forecast, company ranking, competitive landscape, growth factors, and trends
Segments covered
Device type, application, end use, region
Regional scope
North America; Europe; Asia Pacific; Latin America; MEA
Country scope
U.S.; Canada; Mexico; Germany; UK; France; Italy; Spain; Norway; Denmark; Sweden; China; Japan; India; South Korea; Australia; Thailand; Brazil; Argentina; Saudi Arabia; South Africa; UAE; Kuwait;
Key companies profiled
Siemens Healthineers; Esaote SpA; Koninklijke Philips N.V.; GE Healthcare Ltd.; Canon Medical Systems; Hitachi Medical Systems; Shimadzu Corporation; DigiRad Corporation; Del Medical Systems Inc.
Customization scope
Free report customization (equivalent up to 8 analysts' working days) with purchase. Addition or alteration to country, regional & segment scope.
Pricing and purchase options
Avail customized purchase options to meet your exact research needs. Explore purchase options
Global 3D Medical Imaging Devices Market Report Segmentation
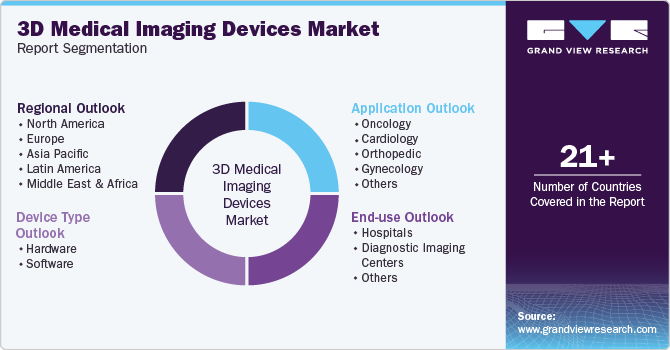
This report forecasts revenue growth at global, regional, and country levels and provides an analysis of the latest industry trends in each of the sub-segments from 2021 to 2033. For the purpose of this study, Grand View Research has segmented the global 3D medical imaging devices market report on the basis of device type, application, end use and region:
 To learn more about this report, Download Free Sample Report
-
Device Type Outlook (Revenue, USD Million, 2021 - 2033)
-
Hardware
-
X-ray Devices
-
CT Devices
-
Ultrasound Systems
-
MRI Equipment
-
-
Software
-
-
Application Outlook (Revenue, USD Million, 2021 - 2033)
-
Oncology
-
Cardiology
-
Orthopedic
-
Gynecology
-
Others
-
-
End Use Outlook (Revenue, USD Million, 2021 - 2033)
-
Hospitals
-
Diagnostic Imaging Centers
-
Others
-
-
Regional Outlook (Revenue, USD Million, 2021 - 2033)
-
North America
-
U.S.
-
Canada
-
-
Europe
-
UK
-
Germany
-
France
-
Italy
-
Spain
-
Denmark
-
Sweden
-
Norway
-
-
Asia Pacific
-
Japan
-
China
-
India
-
Australia
-
Thailand
-
South Korea
-
-
Latin America
-
Brazil
-
Mexico
-
Argentina
-
-
Middle East & Africa
-
South Africa
-
Saudi Arabia
-
UAE
-
Kuwait
-
-
Research Methodology
Segment Definition
Segment - Device Type
Revenue capture definition
Hardware
Revenue is generated through the direct sale or leasing of physical 3D-enabled medical imaging modalities, including 3D Ultrasound, CT scanners, MRI systems, and Tomosynthetic Mammography units. Manufacturers derive income from initial equipment capital sales, multi-year post-warranty service and maintenance contracts, physical component upgrades (such as high-density detector arrays or advanced gantry assemblies), and specialized hardware accessories like specialized imaging coils and transducers.
Software
Revenue is captured through the commercialization of advanced 3D image reconstruction, post-processing, and visualization software platforms. Market participants generate revenue through multi-user enterprise licenses, subscription-based Software-as-a-Service (SaaS) models, cloud-based PACS/VNA rendering plugins, AI-driven automated segmentation software upgrades, and annual maintenance agreements that provide ongoing technical support and regulatory algorithm updates.
Segment - Application
Revenue capture definition
Oncology
Revenue flows from 3D imaging hardware configurations and specialized software modules optimized for cancer detection, multi-planar tumor volume staging, and radiation therapy planning. Income is driven by the deployment of high-resolution 3D CT/MRI packages, automated lesion-tracking software, and advanced 3D visualization tools used to delineate tumor margins and guide stereotactic interventional biopsies.
Cardiology
Revenue is generated through the deployment of systems specialized for advanced cardiovascular diagnostics, such as 3D Echocardiography and Cardiac CT Angiography. Manufacturers capture value from specialized cardiac gating hardware, multi-dimensional ventricular volume analysis software licenses, and automated 3D modeling tools utilized to visualize complex coronary artery anomalies, structural heart diseases, and myocardial perfusion.
Orthopedic
Revenue is derived from 3D medical imaging solutions tailored for musculoskeletal assessments, joint reconstruction modeling, and spinal intervention mapping. Income is earned from the sale of specialized orthopedic hardware (such as weight-bearing 3D Cone Beam CT scanners), robotic-assisted surgery planning software integrations, and multi-planar biomechanical modeling applications used to map complex bone fractures and guide implant positioning.
Gynaecology
Revenue flows from 3D imaging equipment utilized across obstetrics and women’s health settings, primarily dominated by premium 3D/4D ultrasound systems and digital breast tomosynthesis (DBT). Providers capture revenue through high-end ultrasound console sales, specialized matrix array volume probes, fetal anomaly screening software expansions, and premium spatial-resolution imaging upgrades.
Others
Revenue is captured from 3D imaging configurations allocated across secondary clinical applications, including neurology (e.g., 3D brain mapping), gastroenterology (e.g., virtual colonoscopy), and urology. Market participants capture revenue through general-purpose 3D software licenses, versatile multi-specialty hardware configurations, and variable clinical application packages.
Segment - End Use
Revenue capture definition
Hospitals
Revenue is generated through the high-volume procurement, leasing, or institutional tendering of 3D medical imaging infrastructure to multi-specialty medical centers and hospital networks. This segment drives substantial capital inflows from premium tier, multi-modality 3D hardware acquisitions, enterprise-wide software deployments across radiology departments, and long-term, high-margin preventive maintenance contracts.
Diagnostic Imaging Centers
Revenue is derived from the acquisition of 3D imaging technologies by standalone imaging networks and outpatient radiology clinics. Revenue in this segment is driven heavily by high-throughput, versatile 3D systems (such as mid-to-high tier 3D ultrasound and CT) optimized for fast patient turnaround, flexible financing or operational leasing models, and scalable software upgrades designed to maximize operational return on investment (ROI).
Others
Revenue flows from secondary end-users, including ambulatory surgical centers (ASCs), specialized research and academic institutes, military medical facilities, and independent point-of-care clinics. Manufacturers capture revenue via low-footprint or mobile 3D imaging system sales, targeted ambulatory surgical planning software licenses, and basic ad-hoc technical support service models.
Delivered Customizations
This report has been delivered with the following In-depth customizations
CLIENT REQUEST
CUSTOMIZATION DELIVERED
VALUE ADDS
Technological Advancement Analysis
Conducted a comprehensive technology assessment of the global 3D medical imaging devices market, focusing on advancements across high-dimensional modalities including 3D Computed Tomography (3D CT), 3D Magnetic Resonance Imaging (3D MRI), 3D Ultrasound, and Cone Beam Computed Tomography (CBCT). The study further assessed the impact of these innovations on diagnostic accuracy across key clinical spaces (Oncology, Cardiology, Orthopedics, and Dental/Maxillofacial Surgery) as a segment, efficiency, patient outcomes, and clinical workflow integration. Additionally, reviewed ongoing R&D activities, the next regulatory approvals (FDA 510(k) clearances and CE markings), potential funding, and investments in next-generation spatial compound mixed-reality (XR/AR) imaging systems.
This analysis enables stakeholders to understand evolving technology trends across the 3D medical imaging hardware and advanced visualization software segments, highlighting high-growth innovation opportunities. The study identifies emerging 3D imaging and XR/AR system trends, competitive advantages, and future investment opportunities. The insights support strategic software-as-a-service (SaaS) integration planning for market positioning across the global diagnostic imaging ecosystem.
Competitive Analysis
Conducted a detailed competitive assessment of leading 3D medical imaging equipment manufacturers and specialized software developers based on Product Portfolios & Modality Breadth, Software Ecosystem, Key Differentiators, and Commercial Go-to-Market strategies. The analysis examined competitive positioning across core radiology segments while tracking strategic mergers, acquisitions, AI vendor collaborations, and hospital network partnerships that are altering vendor concentration and market share dynamics.
This analysis enables stakeholders to evaluate competitive intensity, benchmark key market participants against peers, and identify emerging leaders in the global 3D medical imaging market. The study provides a detailed business-mapping related to product differentiation, software integration, and flexible deployment strategies, allowing early defense planning and targeted account acquisition costs to help penetrate healthcare markets and rapidly expanding hospital systems.
Geographic Expansion
Conducted a detailed assessment of regional and country-level dynamics within the global 3D medical imaging devices market across North America, Europe, Asia-Pacific, Latin America, and the Middle East & Africa. The analysis evaluated localized market-readiness variables by examining healthcare infrastructure readiness, specifically looking at the density of advanced imaging centers, tertiary hospitals, and ambulatory surgical centers (ASCs) capable of utilizing heavy 3D data workloads. It also tracked adoption and replacement cycles, assessed current installation trends of high-end imaging, 3D portable/edge systems, vendor deals, legacy 2D installations, etc. Furthermore, the study navigated complex regulatory and reimbursement frameworks, analyzing region-specific standards for 3D image reconstruction, technical component billing, and strict evolving government regulations regarding medical radiation exposure.
This analysis enables stakeholders to understand regional growth opportunities across the global 3D medical imaging ecosystem. It helps identify high-growth regions and contributors to capital equipment expansion, regulatory evolution, and reimbursement changes. Furthermore, it provides seamless insights into localized regulatory barriers, reimbursement health economics, and adoption hurdles, helping clients plan their geographic expansion and market penetration strategies.
Frequently Asked Questions About This Report
The global 3D medical imaging devices market size was estimated at USD 10.7 billion in 2025 and is expected to reach USD 11.4 billion in 2026.
The global 3D medical imaging devices market is expected to grow at a compound annual growth rate of 6.2% from 2026 to 2033 to reach USD 17.3 billion by 2033.
The hardware segment dominated the 3D medical imaging devices type market with a share of 67.5% in 2025. This is attributable to the high demand for imaging devices globally.
Some key players operating in the 3D medical imaging devices market include GE Healthcare; Siemens Healthineers AG; Philips Healthcare; Canon Medical Systems Corporation; Mindray; FUJIFILM SonoSite, Inc.; Esaote; ContextVision; EOS imaging; Intelerad; Able Software Corp.; and Axial3D
Key factors that are driving the market growth include growing incidence of chronic disorders and technological advancements.
Hospitals held the largest revenue share in 2025, while diagnostic imaging centers is the fastest-growing area.
North America accounted for 38.6% of revenue in 2025.
Oncology held the largest revenue share in 2025, while cardiology is the fastest-growing area.
About the Author(s)
Medical Devices Research Team
Healthcare · Medical DevicesThis report was authored by the medical devices research team at Grand View Research - comprising two research analysts, one senior research analyst, and one industry expert - with specialized expertise in the medical devices segment of the healthcare industry. All findings are based on proprietary healthcare databases, executive interviews, and regulatory analysis, subject to internal peer review prior to publication.
Last Updated:
Speak to Analyst

Customize this report to your needs - add regions, segments, or data points, with 20% free customization.
Or view our licence options:


ISO 9001:2015 & 27001:2022 Certified
We are GDPR and CCPA compliant! Your transaction & personal information is safe and secure. For more details, please read our privacy policy.


