
- Home
- »
- Next Generation Technologies
- »
-
5G Devices Market Size, Share And Trends Report, 2033GVR Report cover

5G Devices Market (2026 - 2033)
Size, Share, & Trends Analysis Report By Form Factor (Phones, CPE, Modules, Hotspots, Switches & Routers, Laptop, Tablets), By Spectrum (Sub-6 GHz, MmWave), By Region, And Segment Forecasts
Market Size, 2025
$269.2BMarket Estimate, 2026
$350.6BMarket Forecast, 2033
$2,322.2BCAGR, 2026–2033
31.0%5G Devices Market Summary
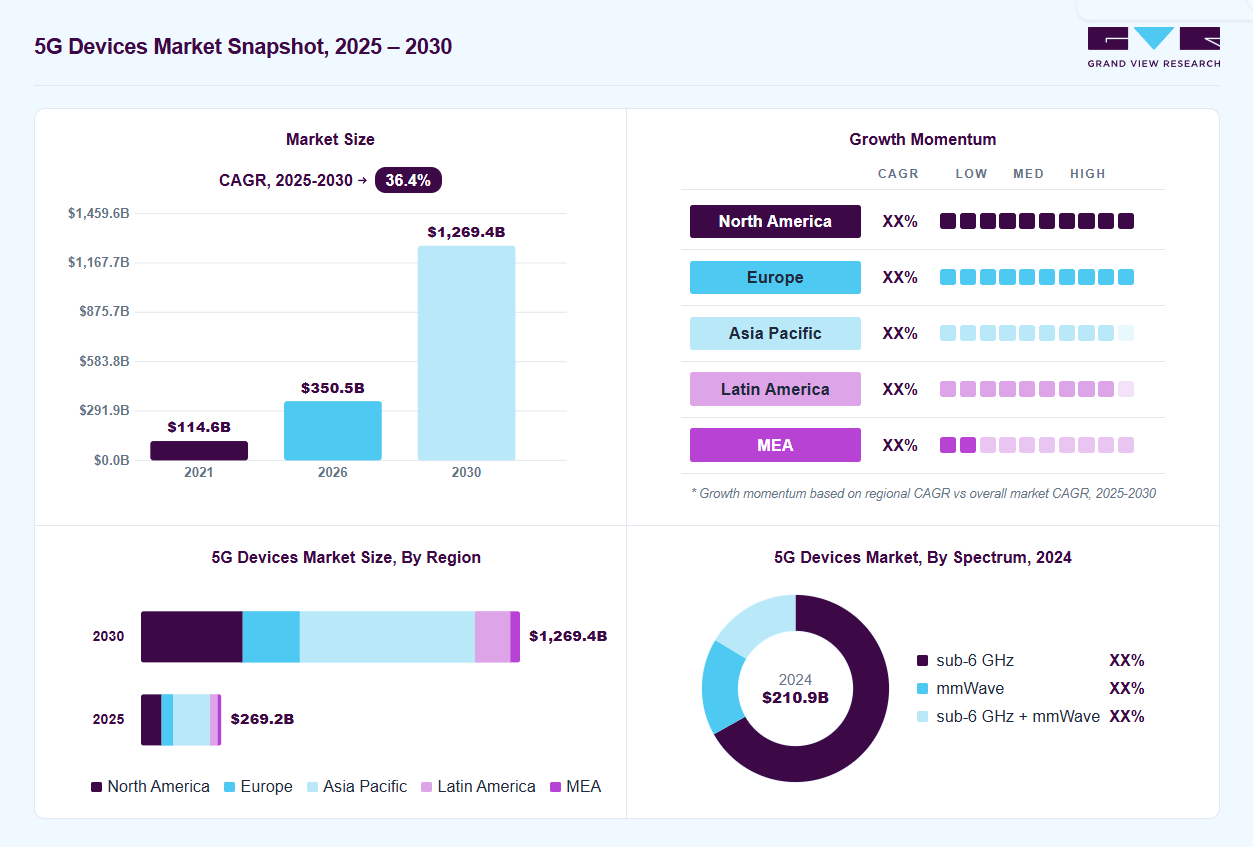
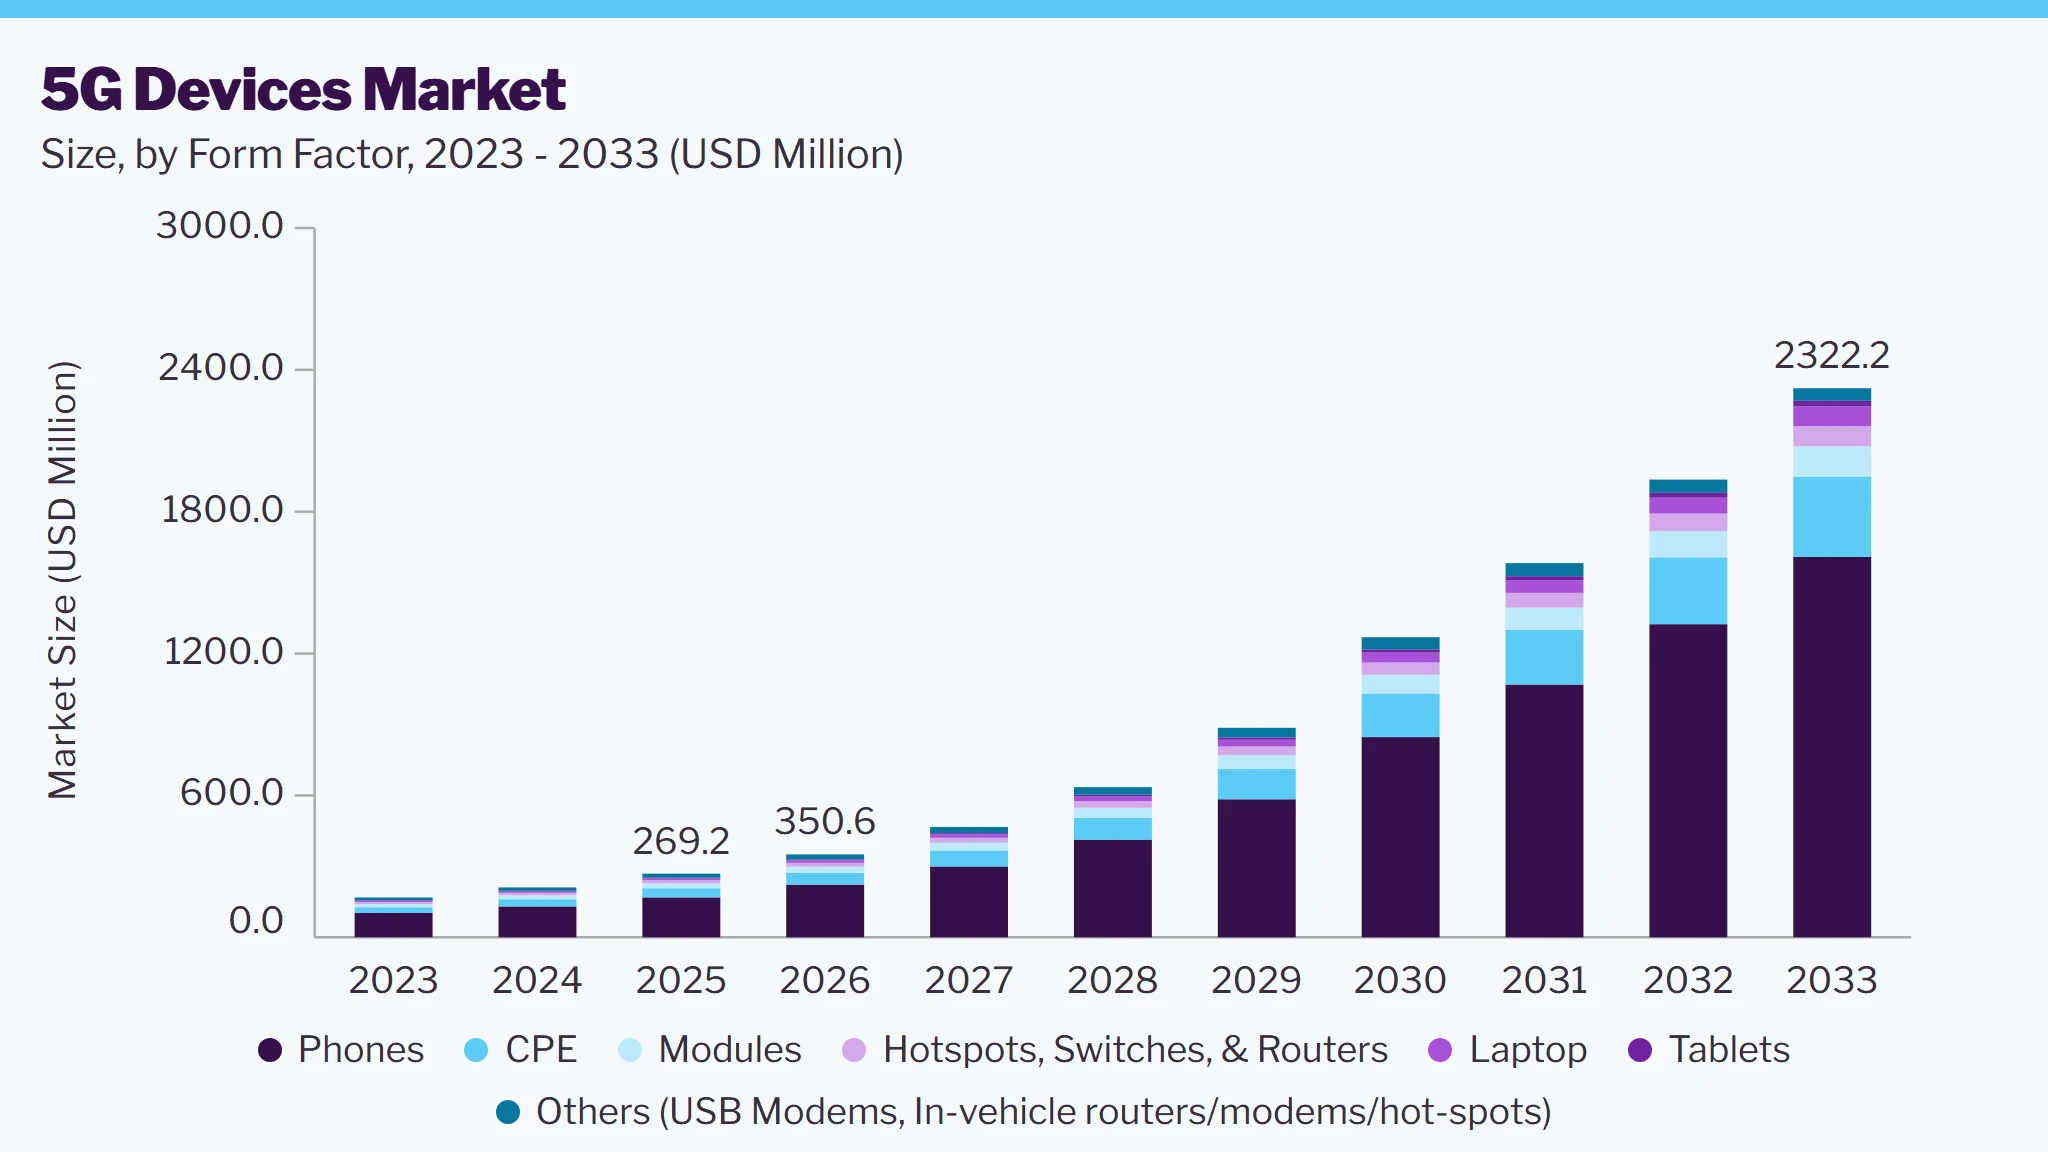
The global 5G devices market size was valued at USD 269.2 billion in 2025 and is projected to grow from USD 350.6 billion in 2026 to USD 2,322.2 billion by 2033, at a CAGR of 31.0% from 2026 to 2033. Asia Pacific dominated the global market with the largest revenue share of 46.0% in 2025. One of the primary drivers propelling the market is the continuous expansion of 5G network infrastructure.
 Source: Grand View Research, IR Documents, Primary Interviews, Paid DatabasesTo learn more about this report,
 Download Free Sample Report
Key Market Trends & Insights
- By form factor: Phones segment dominated the market, with a revenue share of 62.7% in 2025.
- By spectrum: Sub-6 GHz segment held the largest market share in 2025.
Regional Highlights
- Largest regional market: Asia Pacific (46.0% revenue share, 2025)
- Fastest-growing regional market: North America (highest CAGR, 2026-2033)
- By country: The China held the largest market share in 2025.
Market Size & Forecast
- Market size in 2025: USD 1.3 Billion
- Market size in 2025: USD 269.2 Billion
- Estimated market size in 2026: USD 350.6 Billion
- Projected market size by 2033: USD 2,322.2 Billion
- CAGR (2026-2033): 31.0%
Prism AI by Grand View Research Free to tryAsk a question about the 5G devices marketTry asking✓Every figure cited from GVR research Prefer the report? Download free sample →Telecommunication companies and governments worldwide are investing heavily in rolling out 5G networks, increasing coverage and capacity. As these networks become more accessible, the demand for 5G devices such as smartphones, tablets, and IoT gadgets naturally rises. This expansion is enabling faster data speeds, lower latency, and greater connectivity, which appeals to both consumers and businesses.
Another significant driver of the market is the increasing consumer demand for high-speed connectivity. As people rely on their devices for an array of activities, from streaming high-definition content to online gaming, there is a growing need for quicker and more reliable connections. 5G technology caters to this demand by offering unparalleled data speeds and reduced lag, enhancing the overall user experience. This surge in consumer demand is pushing device manufacturers to produce more 5G-compatible products.
 To learn more about this report, Download Free Sample Report
The substantial increase in the number of announced and commercially available 5G devices, as cataloged by GSA, is a strong driving force behind the growth of the market. The remarkable surge of 62% in announced 5G devices and a staggering 76% growth in 5G phones from the beginning of 2022 indicate the rapid pace of innovation within the industry. Consumers, as well as businesses and industries, are witnessing an expanding array of options in the market, catering to diverse needs and preferences. With over 1,650 commercially available 5G devices, reflecting a remarkable annual growth of more than 66%, this market transformation is extending the accessibility of 5G technology. This proliferation of 5G devices is translating into faster network adoption, improved connectivity, and enhanced user experiences, propelling the overall market forward.
The proliferation of the Internet of Things (IoT) and the advent of Industry 4.0 are also contributing to the growth of the market. These trends involve connecting various devices and sensors to the internet for data collection and automation. The low latency and high bandwidth of 5G networks are crucial for IoT and Industry 4.0 applications, as they enable real-time data transfer and decision-making. This is driving the development and adoption of 5G-compatible devices in sectors like manufacturing, healthcare, transportation, and smart cities.
One notable restraint in the 5G devices industry is the relatively higher cost associated with adopting this advanced technology. The deployment of 5G infrastructure and the production of compatible devices involve substantial investments. Consequently, this can drive up the cost of 5G devices, making them less affordable for some consumers or enterprises. To overcome this restraint, manufacturers and service providers need to focus on cost-effective solutions and foster competition in the market.
Market Dynamics
The 5G devices market is shaped by accelerating global 5G network rollouts, rising data-intensive applications, and increasing convergence of connectivity across consumer and enterprise environments. Technological advancements in semiconductor design, radio frequency components, and device integration are enabling broader adoption of 5G-enabled form factors beyond smartphones. The market is transitioning from early consumer-led demand toward diversified enterprises, industrial, and fixed wireless use cases, positioning 5G devices as foundational hardware for next-generation digital ecosystems.
The primary driver for the 5G devices market is the rapid expansion of commercial 5G networks across developed and emerging economies. Mobile network operators are investing heavily in spectrum acquisition and infrastructure upgrades to support higher data speeds, lower latency, and massive device connectivity. This network expansion creates a direct requirement for compatible end-user devices, as legacy 4G hardware cannot leverage advanced 5G capabilities.
5G devices address this driver by integrating advanced modems, antennas, and chipsets capable of operating across diverse spectrum bands. Smartphones, customer premises equipment (CPE), and modules are increasingly optimized for both sub-6 GHz and mmWave environments, enabling seamless user experiences. As network coverage improves, device replacement cycles accelerate, directly translating infrastructure investments into sustained hardware demand and market growth.
A key restraint in the 5G devices market is the relatively high cost of 5G-enabled components and end devices compared to 4G alternatives. Advanced chipsets, RF front-end complexity, and power management requirements increase bill-of-material costs, particularly for mmWave-capable devices. This pricing premium limits adoption among price-sensitive consumers and small enterprises.
The impact of this restraint is most pronounced in emerging markets and entry-level device segments, where affordability strongly influences purchasing decisions. Form factors such as laptops, industrial routers, and specialized modules experience slower penetration due to higher upfront costs. As a result, market growth remains uneven across geographies, with mature markets adopting faster while cost constraints delay volume expansion elsewhere.
An emerging opportunity lies in the growing use of 5G devices across enterprise and industrial environments. Private 5G networks, Industry 4.0 initiatives, and edge computing deployments are driving demand for 5G-enabled routers, modules, and gateways. These applications require reliable, low-latency connectivity that legacy wireless technologies cannot consistently deliver.
The growth potential is significant for vendors with strong portfolios in CPE, modules, and networking hardware. Enterprise-focused device manufacturers and module suppliers are well positioned to capture this opportunity by offering scalable, certified, and application specific solutions. As enterprises increasingly adopt 5G for mission critical operations, non-smartphone device categories are expected to contribute a rising share of overall market revenue.
Analyst Perspective
The 5G devices market is moving beyond its initial smartphone-centric phase toward a broader, multi-form-factor ecosystem. Network densification and enterprise adoption are reshaping demand patterns, particularly for CPE, modules, and industrial-grade devices. Ongoing advancements in chipset integration and power efficiency are gradually improving device affordability and performance. Investment activity is expected to shift toward enterprise connectivity solutions and private network hardware. Competitive dynamics increasingly favor vendors with diversified portfolios spanning both consumer and infrastructure-adjacent devices.
Form Factor Insights
Based on form factor, the phones segment led the market with the largest revenue share of 62.7% in 2025. Mobile phones have become an integral part of modern life, with millions of users globally. The transition to 5G not only promises faster and more reliable data speeds but also unlocks the potential for various applications, such as Augmented Reality (AR), Virtual Reality (VR), and the Internet of Things (IoT), which are best experienced on mobile devices. In addition, phone manufacturers have recognized the immense market potential and have been actively investing in 5G technology integration, thus further propelling the segment’s growth in the 5G devices market.
The laptop segment is anticipated to register significant growth over the forecast period. Laptops are essential tools for various professional and personal tasks, making them indispensable in modern life. The integration of 5G connectivity into laptops opens up new possibilities, enabling users to access high-speed internet on the go without the limitations of Wi-Fi hotspots. Laptops with 5G capabilities offer a compelling solution for remote work, as they provide reliable connectivity, ensuring professionals stay productive regardless of their location. The combination of 5G's low latency and high-speed internet access facilitates seamless video conferencing, cloud computing, and data-intensive tasks, further driving the appeal of 5G-enabled laptops.
Spectrum Insights
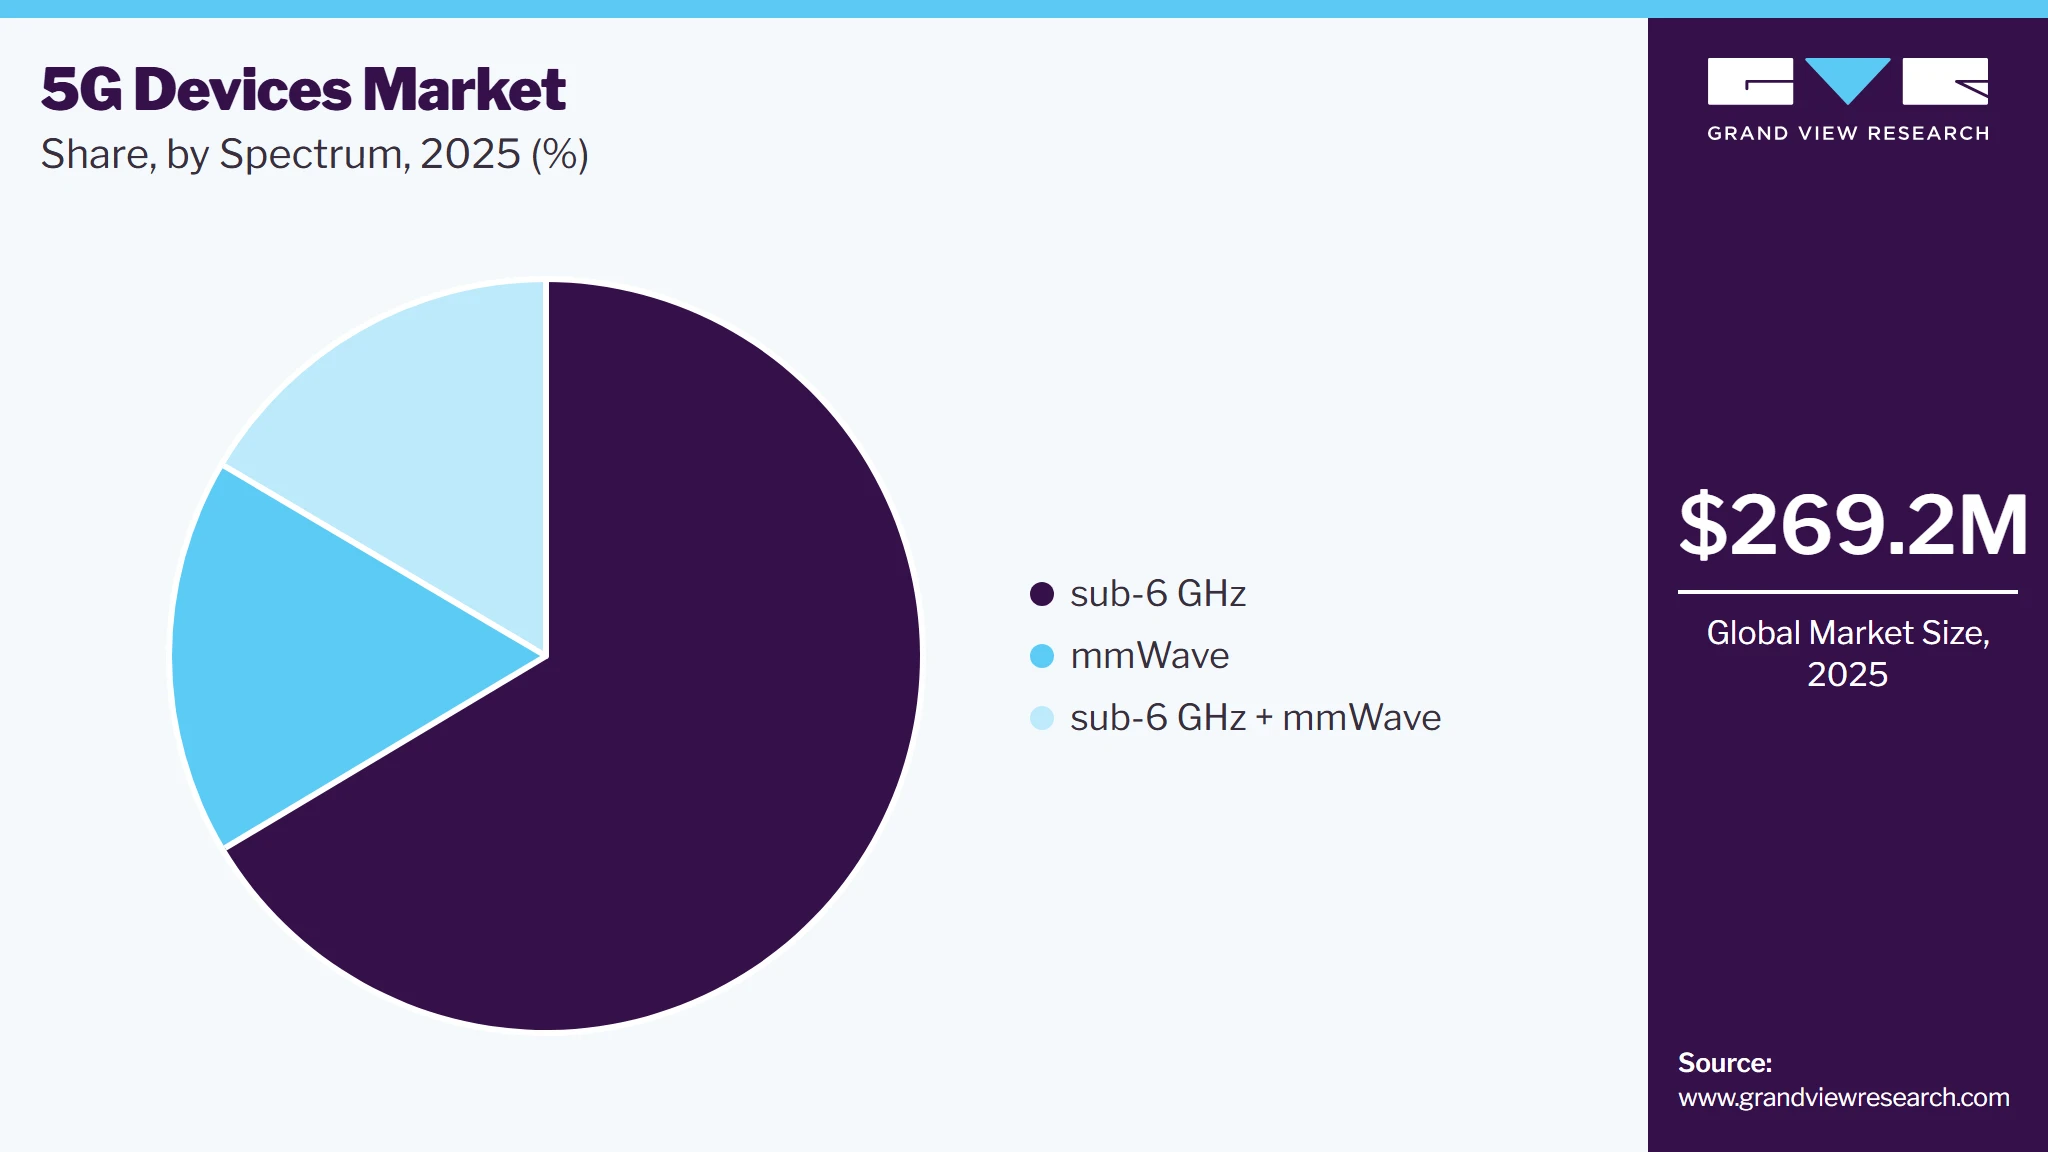
Based on spectrum, the sub-6 GHz segment led the market with the largest revenue share of 66.4% in 2025. The sub-6 GHz frequencies offer a balanced mix of coverage and capacity. This means that devices operating in this frequency range can provide wide area coverage while also delivering impressive data speeds, making them suitable for both urban and rural areas. The sub-6 GHz 5G devices are also more widespread and accessible, as they are part of the initial phase of 5G deployments.
 To learn more about this report, Download Free Sample Report
The mmWave segment is anticipated to register the fastest CAGR over the forecast period. Its emergence can be attributed to its unique capabilities and the growing demand for high-speed, low-latency connectivity. MmWave technology operates at extremely high frequencies, offering significantly faster data speeds compared to sub-6 GHz counterparts. As consumers and industries increasingly rely on bandwidth-intensive applications like AR, VR, and high-definition video streaming, mmWave's ability to deliver multi-gigabit data rates becomes a crucial selling point.
Regional Insights
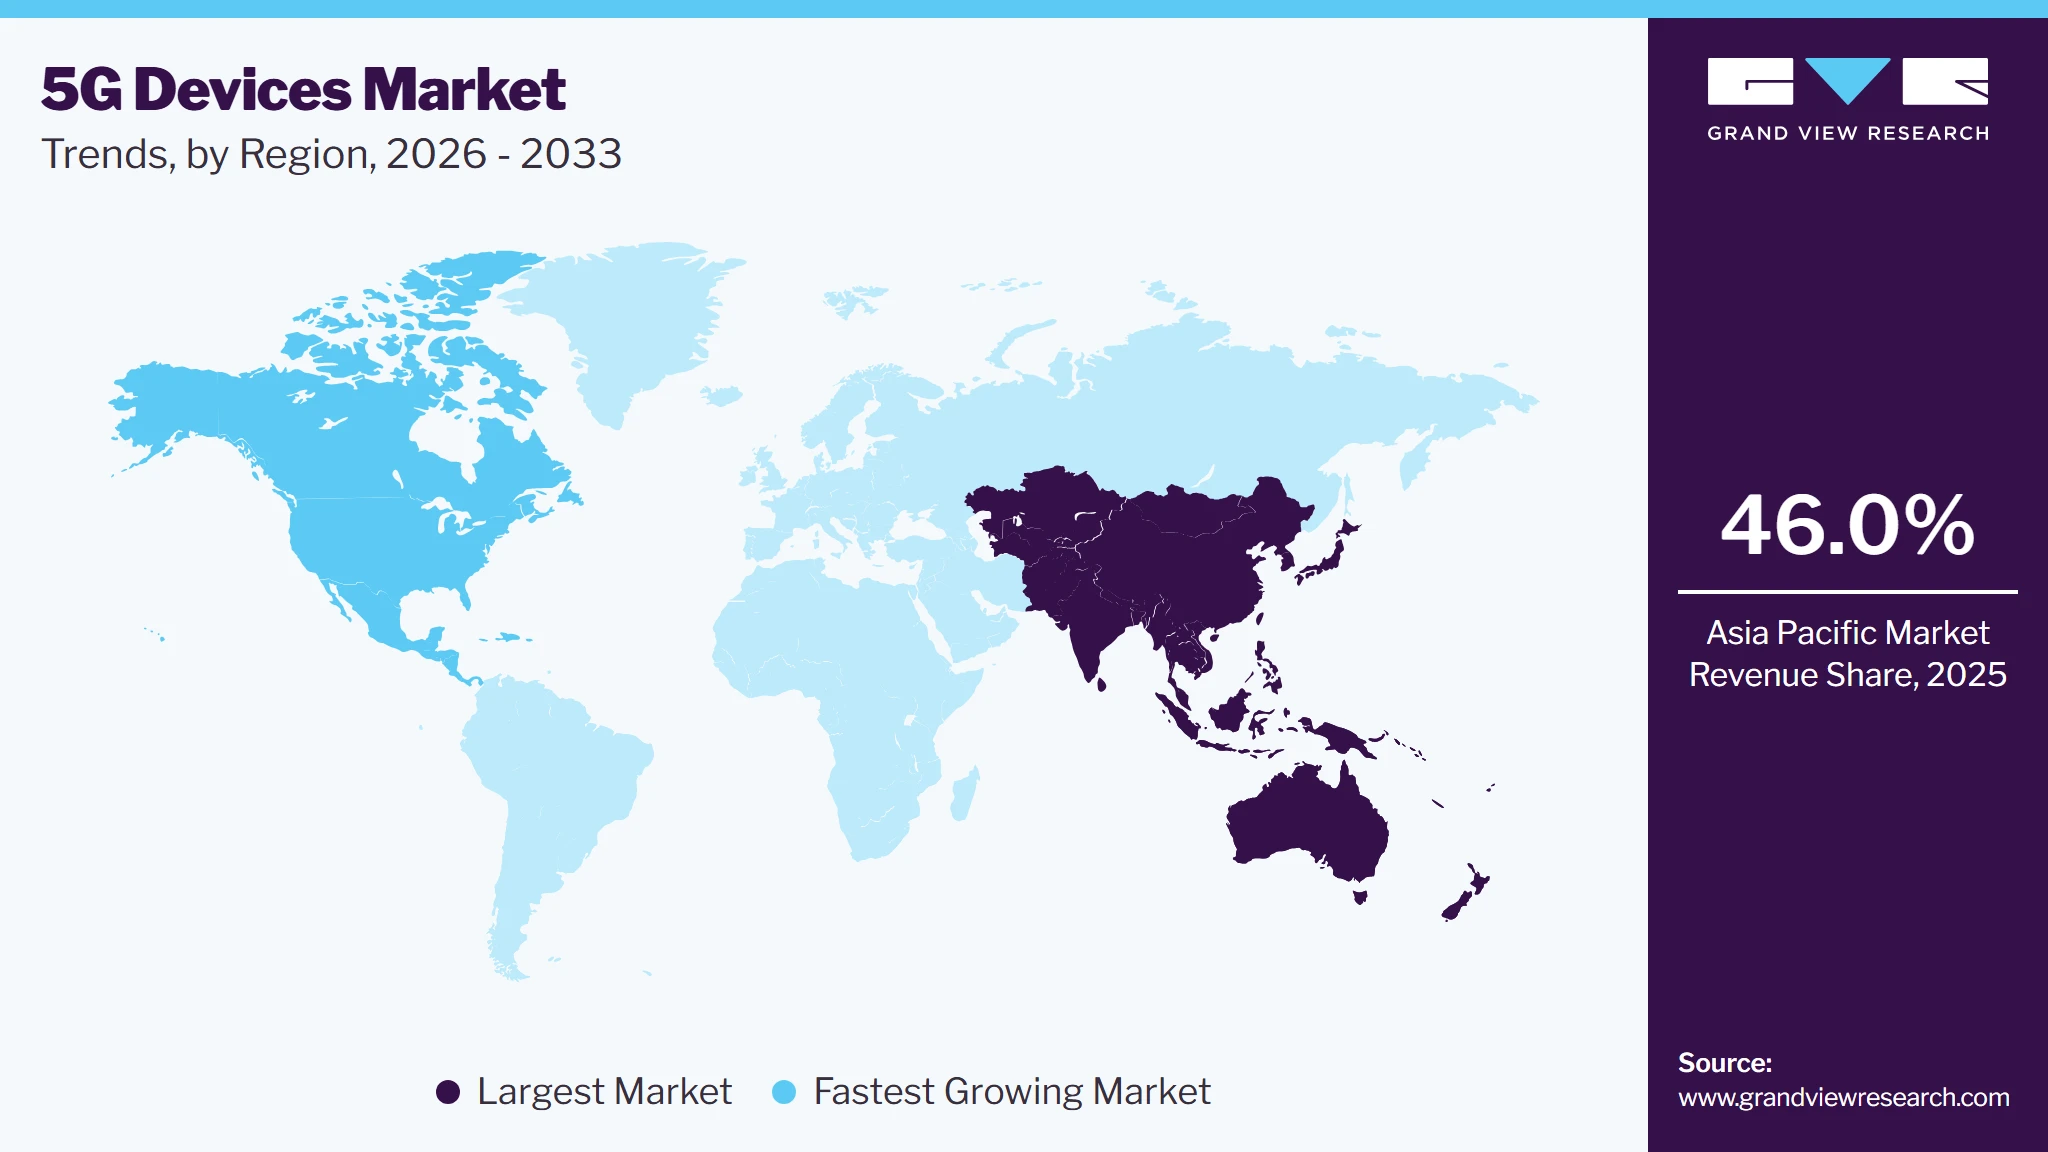
The North America regional market is anticipated to emerge as the fastest-growing market from 2025 to 2033. North America, particularly the U.S., is home to some of the world's largest tech giants and innovators in the telecommunications industry. The region has been at the forefront of 5G network deployments, with extensive coverage and a strong focus on advancing the adoption of 5G technology. Moreover, North America boasts a tech-savvy consumer base that eagerly embraces the latest technological advancements. Growing demand for advanced technology, 5G network coverage, and investments in 5G networks are driving the regional market’s growth.
U.S. 5G Devices Market Trends
The growing demand for faster, more reliable internet connectivity, particularly as consumers and businesses increasingly rely on data-heavy applications such as streaming, gaming, and cloud computing. This is further supported by the expansion of 5G networks across urban and rural areas, ensuring broader coverage. Additionally, advancements in 5G technology, including improvements in speed, latency, and energy efficiency, have spurred the development of new devices, such as smartphones, IoT devices, and wearables, all of which require 5G connectivity to function optimally. The push for smart cities and connected ecosystems is also a significant driver, as 5G enables more efficient traffic management, health monitoring, and public safety systems.
Asia Pacific 5G Devices Market Trends
Asia Pacific dominated the global 5G devices market with the largest revenue share of 46.0% in 2025. The region's vast population, particularly in countries like China and India, has fueled a tremendous demand for 5G devices. With growing urbanization and increasing smartphone adoption, consumers are eager to access the benefits of high-speed 5G networks. Furthermore, Asia Pacific hosts some of the world's largest manufacturers of 5G devices, including leading smartphone makers and network equipment providers. These local companies are well-positioned to deliver a wide range of 5G devices, catering to diverse consumer preferences and price points. In addition, Asian countries, including China and South Korea, were at the forefront of 5G network launches, which further propelled the region’s growth.
 To learn more about this report, Download Free Sample Report
The 5G devices market in the China held the largest share in the Asia Pacific region in 2025. With the world’s one of the prominent 5G subscriber base, China is pioneering the adoption of 5G-enabled smartphones, IoT devices, and industrial applications. The government's strong commitment to digital transformation and smart city initiatives has spurred demand for devices that leverage 5G’s high-speed, low-latency capabilities. Additionally, the integration of 5G into sectors like manufacturing, healthcare, and transportation is fostering innovation and economic growth. As a hub for 5G device production and consumption, China continues to shape the global 5G landscape, driving connectivity and technological advancements.
Europe 5G Devices Market Trends
The increasing demand for advanced connectivity among consumers in the region drives growth of the 5G devices market in Europe. The demand is largely driven by activities such as high-definition video streaming, online gaming, and virtual reality applications, all of which are optimized with 5G technology. Companies are introducing affordable 5G devices to cater to the increasing demand. For instance, in September 2022, Deutsche Telekom launched the T Phone, a smartphone designed to provide users with an affordable and feature-rich 5G experience across nine European countries. The T Phone is equipped with a 6.52-inch IPS TFT display featuring a resolution of 720 x 1600 pixels and a refresh rate of 60 Hz, ensuring decent visual quality for everyday tasks. Such initiatives make 5G technology more accessible to a broader customer base and accelerate the adoption of 5G devices across the European market, thereby fueling the growth of the market.
UK 5G devices market is witnessing shift toward remote work and online education drives growth in the UK. Remote work became a prominent trend in the UK, with companies adopting hybrid or fully remote models to enhance flexibility and productivity. Employees working from home rely heavily on uninterrupted internet access for video conferencing, cloud-based collaboration tools, and data-intensive applications. 5G devices such as smartphones, laptops, and mobile hotspots provide faster speeds and lower latency compared to traditional broadband solutions, ensuring seamless virtual communication and workflow continuity. Businesses have also invested in 5G-enabled routers and dongles to equip their remote workforce with reliable connectivity, further boosting demand for such devices.
5G devices market in Germany is experiencing growth due to adoption of 5G in automotive applications. One of the key benefits of 5G in the automotive sector is its ability to enable seamless vehicle-to-everything communication. This technology allows vehicles to communicate with each other, with infrastructure, and with pedestrians, enhancing safety and efficiency on the roads. 5G’s ultra-low latency and high data transfer rates are critical for real-time decision-making in autonomous vehicles, requiring 5G-enabled modules, sensors, and onboard communication devices. The growing adoption of these devices by automakers in Germany is significantly contributing to the expansion of the 5G devices market.
Key 5G Devices Company Insights
Some of the key companies in the 5G devices market include ZTE Corporation, Xiaomi, Samsung, Sony Group Corporation, D-Link, Huawei, and others. The competitive landscape among device manufacturers in the market has ignited a flurry of innovation and fueled the continuous release of an array of advanced 5G devices. In the race to secure a strong market presence, companies are actively engaged in a relentless pursuit of excellence. This fervor for market share and customer loyalty is the driving force behind a relentless cycle of development and improvement in the 5G product domain.
-
Xiaomi is a technology company specializing in the design, development, and manufacturing of smartphones, smart home devices, and other consumer electronics. The company offers smartphones, smart TVs, fitness bands, air purifiers, and more. The company's offerings in the market include 5G smartphones, such as the Xiaomi MIX Flip, Xiaomi 14T Pro, and POCO C75, laptops, tablets and others. Xiaomi's products are available in over 100 countries and regions worldwide. In August 2024, the company earned a spot on the Fortune Global 500 list for the sixth consecutive year.
-
Samsung is a provider of technology and consumer electronics. The company operates across diverse sectors, including consumer electronics, information technology, mobile communications, and device solutions. Its extensive product portfolio encompasses smartphones, televisions, home appliances, semiconductors, and display panels. Samsung offers a range of 5G devices, including smartphones, tablets, laptops, and wearable technology. The company operates in over 76 countries and employs more than 260,000 people globally. In addition to consumer electronics, it also provides solutions across various sectors, such as healthcare, finance, and transportation.
Key 5G Devices Companies
The following key companies have been profiled for this study on the 5G devices market.
-
ZTE Corporation
-
Xiaomi
-
Samsung
-
Sony Group Corporation
-
D-Link
-
Huawei
-
Nokia Corporation
-
Fibocom Wireless, Inc.
-
Inseego Corp
-
Askey Computer Corp.
-
HTC Corporation
Recent Developments
-
In September 2024, Samsung Electronics launched the Galaxy S24 FE, a flagship smartphone that combines advanced features with user-friendly performance. The device boasts a 6.7-inch Dynamic AMOLED 2X display with a resolution of 1080 x 2340 pixels and a smooth 120 Hz refresh rate, enhancing visual experiences for gaming and multimedia consumption. The Galaxy S24 FE is powered by the Exynos 2400e chipset, offering robust processing capabilities alongside 8GB of RAM and storage options of 128GB, 256GB, or 512GB. The smartphone aims to deliver an exceptional balance of performance and style to meet the needs of modern users.
-
In July 2023, Ericsson and Intel unveiled a strategic partnership aimed at harnessing Intel's cutting-edge 18A process and manufacturing technology to bolster Ericsson's forthcoming next-generation optimized 5G infrastructure. Within the framework of this collaboration, Intel is set to produce tailor-made 5G SoCs (system-on-chip) to empower Ericsson in crafting highly distinctive, top-tier products for the future landscape of 5G infrastructure. Beyond this, the collaboration extends to the optimization of 4th Gen Intel Xeon Scalable processors with Intel vRAN Boost for Ericsson's Cloud RAN solutions. The core goal is to empower communication service providers with amplified network capacity, heightened energy efficiency, and enhanced scalability and flexibility:
5G Devices Market Report Scope
Report Attribute
Details
Market size in 2025
USD 269.2 billion
Estimated market size in 2026
USD 350.6 billion
Projected market size by 2033
USD 2,322.2 billion
Growth rate
CAGR of 31.0% from 2026 to 2033
Base year for estimation
2025
Historical data
2021 - 2024
Forecast period
2026 - 2033
Quantitative units
Revenue in USD billion and CAGR from 2026 to 2033
Report coverage
Revenue forecast, company market share, competitive landscape, growth factors, and trends
Segments covered
Form factor, spectrum, region
Regional scope
North America; Europe; Latin America; MEA; Asia Pacific
Country scope
U.S.; Canada; Mexico; Germany; U.K.; France; China; Japan; India; South Korea; Australia; Brazil; Saudi Arabia; UAE; South Africa
Key companies profiled
ZTE Corporation; Xiaomi; Samsung; Sony Group Corporation; D-Link; Huawei; Nokia Corporation; Fibocom Wireless, Inc.; HTC Corporation; Inseego Corp.; Askey Computer Corp.
Customization scope
Free report customization (equivalent up to 8 analysts' working days) with purchase. Addition or alteration to country, regional & segment scope.
Pricing and purchase options
Avail customized purchase options to meet your exact research needs. Explore purchase options
Global 5G devices Market Report Segmentation
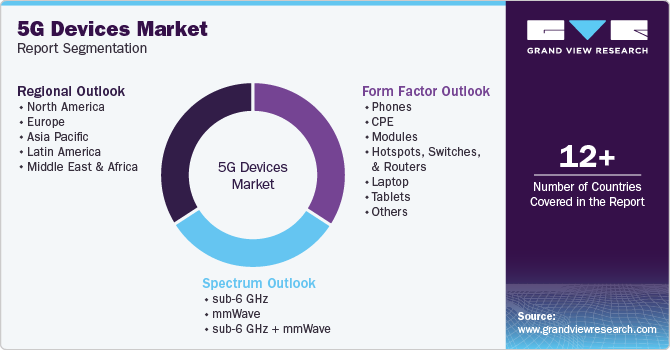
The report forecasts revenue growth at global, regional, and country levels and provides an analysis of the latest industry trends in each of the sub-segments from 2021 to 2033. For this study, Grand View Research has segmented the global 5G devices market report based on form factor, spectrum, and region.
 To learn more about this report, Download Free Sample Report
-
Form Factor Outlook (Revenue, USD Billion, 2021 - 2033)
-
Phones
-
CPE
-
Modules
-
Hotspots, Switches, & Routers
-
Laptop
-
Tablets
-
Others
-
-
Spectrum Outlook (Revenue, USD Billion, 2021 - 2033)
-
sub-6 GHz
-
mmWave
-
sub-6 GHz + mmWave
-
-
Regional Outlook (Revenue, USD Billion, 2021 - 2033)
-
North America
-
U.S.
-
Canada
-
Mexico
-
-
Europe
-
UK
-
Germany
-
France
-
-
Asia Pacific
-
China
-
India
-
Japan
-
South Korea
-
Australia
-
-
Latin America
-
Brazil
-
-
Middle East & Africa
-
Kingdom of Saudi Arabia (KSA)
-
UAE
-
South Africa
-
-
Research Methodology
The 5G devices market figures in this report are based on a proven research process that combines executive interviews with secondary research from proprietary databases, company filings, and recognized regulatory and institutional sources. Market size is built through value-chain sizing - reconciling supply-side and demand-side estimates - and triangulated with bottom-up and top-down approaches. Every estimate passes multiple levels of expert validation before publication, with each 5G devices segment quantified using the revenue-capture definitions in the table below.
Segment Definition
Segment - Form Factor
Revenue capture definition
Phones
Revenue generated from the sale of 5G-enabled smartphones, including unlocked retail devices, carrier-bundled models, and enterprise-grade handsets sold through direct and indirect distribution channels.
CPE
Revenue derived from fixed wireless access to customer premises equipment, such as indoor and outdoor 5G gateways supplied to residential, commercial, and enterprise customers, including operator-subsidized and standalone device sales.
Modules
Revenue captured from the sale of embedded 5G communication modules to original equipment manufacturers for integration into industrial equipment, automotive systems, smart devices, and IoT hardware platforms.
Commercial Vehicle
Revenue from portable 5G hotspots, enterprise routers, and networking switches with integrated 5G connectivity, including devices sold for temporary, mobile, and fixed enterprise networking use cases.
Hotspots, Switches, & Routers
Revenue generated from always connected 5G enabled laptops and notebooks with integrated cellular modems, sold to consumer, commercial, and enterprise end users.
Laptop
Revenue was captured from the sale of consumer and commercial tablets supporting 5G connectivity, including Wi-Fi + cellular models sold through retail and enterprise procurement channels.
Tablets
Revenue from emerging and specialized 5G device categories, such as wearables, cameras, industrial terminals, point-of-sale devices, and customized communication hardware.
Others
Revenue generated from the sale of 5G-enabled USB dongles and plug-and-play modems for laptops and desktops, as well as in-vehicle routers, embedded modems, and mobile hotspots supplied to automotive OEMs, fleet operators, and aftermarket channels for connected vehicles, telematics, infotainment, and mobile broadband applications.
Segment - Spectrum
Revenue capture definition
Sub-6 GHz
Revenue generated from sales of 5G devices designed to operate on low- and mid-band spectrum, including smartphones, CPE, modules, tablets, laptops, and routers optimized for wide-area coverage and mass-market consumer and enterprise deployments.
mmWave
Revenue generated from sales of 5G devices supporting high-frequency millimeter-wave spectrum, including premium smartphones, enterprise-grade routers, hotspots, and fixed wireless access equipment deployed in dense urban, indoor, and high-capacity environments.
sub-6 GHz + mmWave
Revenue generated from sales of multi-band 5G devices capable of operating across both sub-6 GHz and mmWave spectrum, including flagship smartphones, advanced CPE, and enterprise networking devices requiring flexible performance across diverse network conditions.
Estimation Model
Layer Name
Key Question
Description
Network Readiness Layer
Where is 5G commercially available?
This layer assesses global and regional 5G network coverage, spectrum allocation, and operator readiness. It establishes the addressable geography for 5G device adoption. Network maturity directly influences device replacement cycles and form factor demand.
Device Penetration Layer
Which device categories are adopting 5G?
This layer evaluates penetration rates across smartphones, CPE, modules, and computing devices. It captures adoption differences between consumer and enterprise segments. The analysis reflects factor-specific replacement and upgrade patterns.
Pricing and ASP Layer
What revenue is generated per device?
This layer analyzes average selling prices across device categories and spectrum capabilities. It accounts for cost differentials between sub-6 GHz and mmWave-enabled devices. ASP trends significantly shape total market value.
Vendor Supply Layer
Who is capturing device revenue?
This layer maps vendor shipments, portfolio breadth, and channel strategies. It links device volumes and pricing to company-level revenue capture. Competitive positioning determines market share distribution.
Delivered Customizations
This report has been delivered with the following In-depth customizations
Client Request
Customization Delivered
Value Adds
Regional 5G Devices Market Opportunity Assessment
- Country/region-wise market sizing and forecasts
- Analysis of demand, adoption trends, and regulatory landscape
- Identification of high-growth regions and investment hotspots
- Identified region-specific growth opportunities
- Supported expansion and go-to-market strategy
- Enabled informed regional investment decisions
Cross-Segmentation Analysis for the 5G Devices Market
- Criss-cross market analysis by form factor and spectrum
- Demand and adoption assessment across key segments
- Segment attractiveness and growth potential benchmarking
- Identified high-potential market segments
- Supported targeted product positioning and marketing strategy
- Improved customer and segment prioritization
Competitive Benchmarking and Strategic Positioning in the 5G Devices Market
- Benchmarking of key competitors across products, pricing, partnerships, and innovation
- Comparative assessment of market share, capabilities, and strategies
- Analysis of competitive strengths, gaps, and differentiation areas
- Identified competitive white spaces and growth gaps
- Supported strategic positioning and differentiation
- Enabled data-driven competitive strategy development
Frequently Asked Questions About This Report
The global 5g devices market size was valued at USD 269.2 billion in 2025 and is estimated at USD 350.5 billion for 2026.
Phones segment dominated the market, with a revenue share of 62.7% in 2025. The transition to 5G not only promises faster and more reliable data speeds but also unlocks the potential for various applications, such as Augmented Reality (AR), Virtual Reality (VR), and the Internet of Things (IoT), which are best experienced on mobile devices.
The continuous expansion of 5G network infrastructure, the increasing consumer demand for high-speed connectivity, and proliferation of the Internet of Things (IoT) and the advent of Industry 4.0 are driving the 5G devices market’s growth.
The global 5g devices market is expected to grow at a CAGR of 31.0% from 2026 to 2033, reaching USD 2,322.2 billion by 2033.
Asia Pacific dominated with a 46.0% revenue share in 2025.
The China held the largest market share in 2025.
Sub-6 GHz segment held the largest market share in 2025.
Some key players operating in the 5G devices market include ZTE Corporation, Xiaomi, Samsung, Sony Group Corporation, D-Link, Huawei, Nokia Corporation, Fibocom Wireless, Inc., HTC Corporation, Inseego Corp., and Askey Computer Corp.
About the Author(s)
Next Generation Technologies Research Team
Technology · Next Generation TechnologiesThis report was authored by the next generation technologies research team at Grand View Research - comprising two research analysts, one senior research analyst, and one industry expert - with specialized expertise in the next generation technologies segment of the technology industry. All findings are based on proprietary technology databases, executive interviews, and regulatory analysis, subject to internal peer review prior to publication.
Last Updated:
Speak to Analyst

Customize this report to your needs - add regions, segments, or data points, with 20% free customization.
Or view our licence options:


ISO 9001:2015 & 27001:2022 Certified
We are GDPR and CCPA compliant! Your transaction & personal information is safe and secure. For more details, please read our privacy policy.


