
- Home
- »
- Medical Devices
- »
-
Actigraphy Device Market Size, Share & Trends Report, 2033GVR Report cover

Actigraphy Device Market (2026 - 2033)
Size, Share & Trends Analysis Report By Application (Sleep Disorders, Physical Activity Monitoring, Chronic Disease Management), By End-use (Healthcare Providers, Research Institutions), By Region, And Segment Forecasts
Market Size, 2025
$3.3BMarket Estimate, 2026
$4.2BMarket Forecast, 2033
$19.7BCAGR, 2026–2033
24.6%Actigraphy Device Market Summary
The global actigraphy device market size was valued at USD 3.3 billion in 2025 and is projected to grow from USD 4.2 billion in 2026 to USD 19.7 billion by 2033, at a CAGR of 24.6% from 2026 to 2033. North America dominated the market, accounting for a revenue share of 35.0% in 2025. The rising prevalence of sleep disorders such as insomnia, sleep apnea, and restless legs syndrome drives the market growth.
Key Market Trends & Insights
- By application: Sleep disorders segment held the largest market share of over 50.0% in 2025.
- By end use: Healthcare providers segment held the largest market share of around 45.0% in 2025
Regional Highlights
- Largest regional market: North America (35.0% revenue share, 2025)
- Fastest-growing regional market: Asia Pacific (highest CAGR, 2026-2033)
Market Size & Forecast
- Market size in 2025: USD 3.3 Billion
- Estimated market size in 2026: USD 4.2 Billion
- Projected market size by 2033: USD 19.7 Billion
- CAGR (2026-2033): 24.6%
Prism AI by Grand View Research Free to tryAsk a question about the actigraphy device marketTry asking✓Every figure cited from GVR research Prefer the report? Download free sample →
The aging population, with its increased susceptibility to sleep disturbances, further fuels market growth. Technological advancements, such as the development of more accurate, user-friendly devices with enhanced data analysis capabilities, are also significantly driving market expansion. The increasing prevalence of sleep disorders such as insomnia, sleep apnea, and restless legs syndrome is significantly driving the growth of the actigraphy device industry. According to the National Sleep Foundation's 2025 Sleep in America Poll, nearly 4 in 10 U.S. adults received a 'D' or 'F' grade for overall sleep health, while 60% of adults reported experiencing at least one sleep-related problem every week. The growing prevalence of poor sleep quality is driving demand for continuous sleep-monitoring technologies, including actigraphy devices, to support early diagnosis and long-term sleep assessment.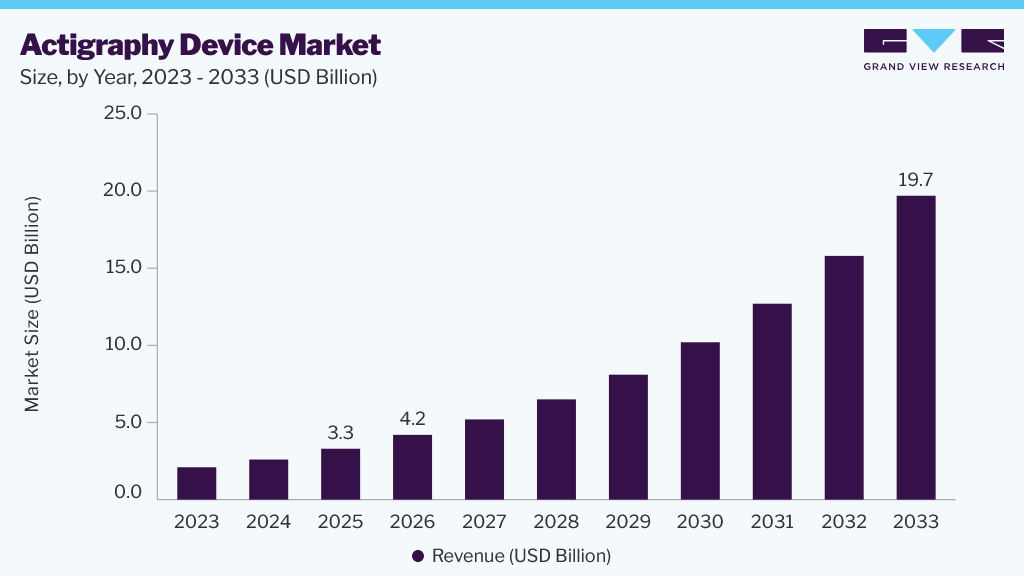 Source: Grand View Research, IR Documents, Primary Interviews, Paid DatabasesTo learn more about this report,
 Download Free Sample Report
As more individuals seek effective ways to monitor and manage their sleep patterns, actigraphy devices, which track and analyze sleep behavior, have gained popularity among both healthcare professionals and consumers. These disorders often require consistent and precise monitoring, and actigraphy devices offer a non-invasive, cost-effective solution for tracking sleep cycles and disturbances. As awareness of sleep health continues to rise and demand for personalized healthcare tools grows, the market for actigraphy devices is expected to expand, offering improved outcomes for individuals with sleep disorders.
Public awareness of the importance of sleep for overall health and well-being is growing. This increased awareness is driving demand for sleep-monitoring tools, including actigraphy devices, as individuals seek to understand better and manage their sleep patterns. For instance, the American Academy of Sleep Medicine (AASM) has launched the "Act on Actigraphy" campaign to promote the use of actigraphy testing in diagnosing and managing sleep disorders. The campaign emphasizes the value of actigraphy as an evidence-based tool for patient-centered sleep care and advocates for insurance coverage of this essential medical service to ensure patient access.
The rising geriatric population is significantly contributing to the market growth. For instance, according to UN population projections, the global population aged 65 and over is rapidly aging. Between 1974 and 2024, this demographic doubled, rising from 5.5% to 10.3% of the global population. By 2074, this figure is projected to double again, reaching 20.7%. As individuals age, they often experience sleep-related issues such as insomnia, fragmented sleep, and other disorders that can impact their overall health and quality of life.
Actigraphy devices, which provide a convenient, non-invasive way to monitor sleep patterns, are becoming increasingly valuable in managing these sleep disturbances among older adults. Healthcare providers are leveraging these devices to assess better sleep conditions, tailor treatments, and monitor the effectiveness of interventions in elderly patients. With the global aging population on the rise, the demand for solutions to improve sleep quality and manage related health issues is expected to fuel continued growth in the actigraphy device market.
Market Concentration & Characteristics
The market growth stage is high, and growth is accelerating. The market is characterized by the rising prevalence of sleep disorders, an aging population, a growing emphasis on personalized medicine, and increasing awareness of sleep health.
The actigraphy device industry exhibits a moderate degree of innovation. While advancements in sensor technology, data analytics, and integration with other health metrics are ongoing, truly novel biomaterials or fundamental shifts in the core technology are less frequent. However, the increasing prevalence of neurological conditions and increasing remote patient monitoring adoption are expected to drive further innovation in actigraphy devices over the forecast period.
Regulatory bodies play a significant role in shaping the market. Compliance with standards set by agencies such as the FDA and EMA is crucial for product approval and market access. These regulations, while ensuring safety and efficacy, can pose challenges due to the need for rigorous testing and documentation, potentially slowing innovation and time-to-market.
The level of M&A activity in the market is moderate. Companies pursue mergers and acquisitions to expand market presence, diversify product portfolios, expand regionally, and gain access to new technologies or research capabilities. This consolidation trend is expected to continue as companies seek competitive advantages in this growing market.
The threat of product substitutes in the market is moderate. While traditional methods such as polysomnography (PSG) remain the gold standard for sleep diagnosis, they are often more expensive and time-consuming, and they require a clinical setting. Actigraphy offers a more accessible and convenient alternative, particularly for long-term monitoring and at-home use, mitigating the threat from PSG to some extent. However, other wearable health trackers with some sleep-tracking features pose a moderate substitute threat, though typically with less precision than dedicated actigraphy devices.
A moderate level of end-user concentration characterizes the actigraphy device market. Key end users include hospitals, sleep clinics, research institutions, and, increasingly, individual consumers for personal health tracking. While hospitals and clinics represent a significant segment, the growing direct-to-consumer market is diversifying the user base and influencing product development.
Analyst Perspective
The actigraphy device market is growing as healthcare providers adopt wearables to track sleep, circadian rhythms, and activity. These non-invasive devices enable long-term monitoring and are used in sleep medicine, research, and disorder management. Greater awareness of sleep health, rising disorder rates, and sensor advances fuel demand. Manufacturers are creating smaller, more accurate, connected devices with stronger analytics and remote monitoring. Companies with reliable sensors and data platforms, plus healthcare partnerships, may gain market share. Future growth will depend on innovation, clinical adoption, data accuracy, and integration with digital health and remote monitoring systems.
Application Insights
The sleep disorders segment dominated the market in 2025, owing to the critical role these devices play in diagnosing and managing various sleep-related conditions. Actigraphy offers a convenient, cost-effective, and objective method for monitoring sleep patterns over extended periods, aiding in the identification of issues such as insomnia, sleep apnea, and circadian rhythm disorders. The increasing prevalence of these disorders, coupled with growing awareness of sleep health, fuels demand for actigraphy devices, as both healthcare professionals and individuals seek reliable tools for assessment and intervention. This widespread use in sleep medicine solidifies the dominance of the sleep disorders segment.
The chronic disease management segment is expected to experience the fastest growth during the forecast period, driven by growing recognition of the interconnectedness among sleep, activity, and chronic conditions. Actigraphy devices provide valuable data on patients' sleep and activity, empowering healthcare providers to remotely monitor and manage individuals with conditions such as diabetes, cardiovascular disease, and obesity. Tracking these key metrics allows for personalized treatment plans, assessment of intervention effectiveness, and early identification of potential complications. The growing adoption of remote patient monitoring and telehealth, combined with the rising prevalence of chronic diseases, fuels this segment's expansion as healthcare systems prioritize proactive, personalized care.
End-use Insights
The healthcare providers segment dominated the market in 2025, owing to their central role in patient care and diagnosis. These institutions utilize actigraphy for a variety of purposes, including sleep disorder diagnosis, pre-and post-surgical patient monitoring, and research. The high volume of patients requiring sleep and activity assessments within these settings, coupled with the established integration of actigraphy into clinical workflows, makes Healthcare providers the largest end-user segment. Moreover, the growing integration of telehealth and remote patient monitoring into healthcare systems further solidifies the segment's dominance.
The homecare settings segment is expected to witness the fastest growth over the forecast period. A growing preference for remote patient monitoring, coupled with the rising prevalence of chronic conditions requiring long-term care, is fueling rapid expansion in the homecare settings segment. These devices enable convenient, continuous monitoring of sleep and activity at home, facilitating early detection of health issues and personalized interventions. Focus on cost-effective healthcare delivery to further drive demand. This shift toward home-based care is projected to sustain the segment's rapid growth over the forecast period.
Regional Insights
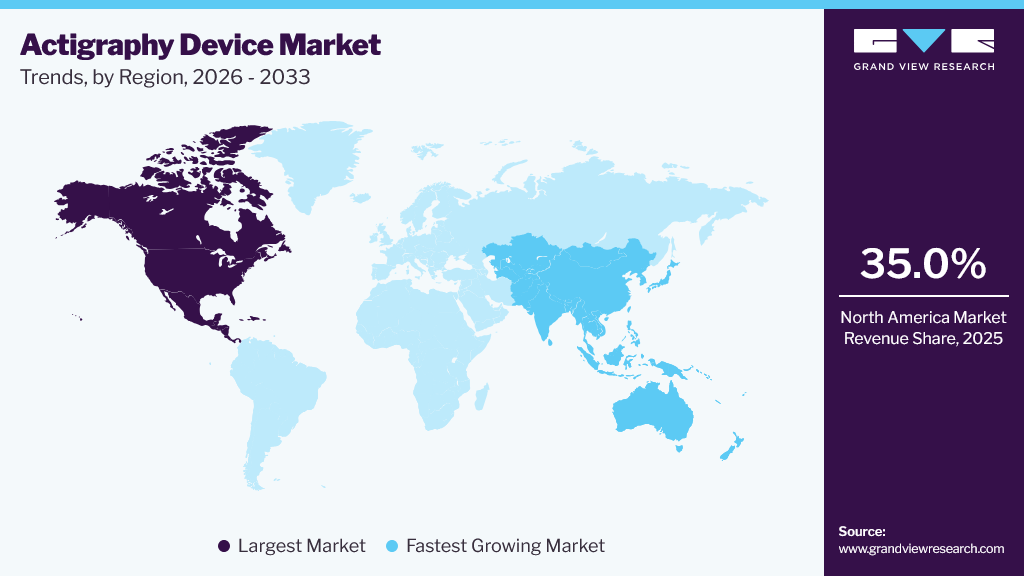
The North America actigraphy device market is dominated, with a share of around 35.0% in 2025. This can be attributed to the combination of factors including the high prevalence of sleep disorders, an aging population, and well-established healthcare infrastructure. The region's strong emphasis on technological advancements and personalized medicine further fuels market growth. The presence of key market players and easy access to advanced actigraphy devices contribute to the market's maturity in this region.
 To learn more about this report, Download Free Sample Report
U.S. Actigraphy Device Market Trends
The actigraphy device industry in the U.S. held a significant market share in 2025, owing to high healthcare expenditure, a large geriatric population, and a growing preference for home-based healthcare solutions. The increasing adoption of telehealth and remote patient monitoring further strengthens the market.
Canada actigraphy device market is experiencing steady growth fueled by an aging population, rising awareness of sleep disorders, and increasing adoption of advanced healthcare technologies. In recent years, Canada has experienced a rise in sleep disorders, such as insomnia, sleep apnea, and restless legs syndrome. For instance, according to the report by Elsevier B.V. in December 2024, Insomnia disorder affected an estimated 16.3% of the population of Canada, with women experiencing higher rates.
Asia Pacific Actigraphy Device Market Trends
The Asia Pacific actigraphy device industry is anticipated to grow at the fastest CAGR over the forecast period. Several factors, such as a large and growing population, increasing awareness of sleep disorders, and improving healthcare infrastructure, contribute to the growth of the sleep disorder market. In recent years, countries such as Japan, China, and India have seen a growing demand for actigraphy devices, driven by an aging population. Moreover, rising disposable incomes and increasing access to healthcare drive the region’s growth.
The actigraphy device market in China is expected to grow significantly over the forecast period. China's market is experiencing rapid growth due to increasing healthcare expenditure, a large geriatric population, and rising awareness of sleep health. The expanding healthcare infrastructure and increasing adoption of advanced medical technologies are further driving market growth.
Key Actigraphy Device Market Company Insights
The actigraphy device market is characterized by global, regional, and niche solution providers competing through technological innovation, strategic partnerships, acquisitions, and product portfolio expansion. Key market players are adopting various strategies, such as product launches, approvals, and other measures, to increase their market presence and gain a competitive advantage. These advancements in the actigraphy device industry are anticipated to boost market growth over the forecast period.
Key Actigraphy Device Companies
The following key companies have been profiled for this study on the actigraphy device market:
-
Ametris (formerly ActiGraph, LLC.)
-
Fibion Inc.
-
Koninklijke Philips N.V.,
-
CamNtech Ltd
-
Empatica Inc.
-
ActivInsights Ltd
-
Neurocare Group AG
Recent Developments
-
In June 2025, ActiGraph rebranded as Ametris to reflect its evolution into a global digital health solutions provider, expanding its capabilities in wearable technologies, AI-driven analytics, and integrated clinical trial platforms while continuing to support medical-grade actigraphy solutions for clinical research.
-
In June 2025, Empatica launched EmbraceMini, a wrist-worn actigraphy device designed for clinical trials and healthcare research, enabling continuous monitoring of sleep, physical activity, and circadian rhythms.
-
In October 2024, ActiGraph partnered with Indivi to integrate wearable and smartphone-based data into precision medicine research, supporting the use of digital biomarkers and remote monitoring in neuroscience clinical development.
Actigraphy Device Market Report Scope
Report Attribute
Details
Market size in 2025
USD 3.3 billion
Estimated market size in 2026
USD 4.2 billion
Projected market size by 2033
USD 19.7 billion
Growth rate
CAGR of 24.6% from 2026 to 2033
Base year for estimation
2025
Historical data
2021 - 2024
Forecast period
2026 - 2033
Quantitative units
Revenue in USD billion, and CAGR from 2026 to 2033
Report coverage
Revenue forecast, company ranking, competitive landscape, growth factors, and trends
Segments covered
Application, end-use, region
Regional scope
North America; Europe; Asia Pacific; Latin America; MEA
Country scope
U.S.; Canada; Mexico; UK; Germany; France; Italy; Spain; Denmark; Sweden; Norway; Japan; China; India; Australia; South Korea; Thailand; Brazil; Argentina; South Africa; Saudi Arabia; UAE; Kuwait
Key companies profiled
Ametris (formerly ActiGraph, LLC.); Fibion Inc.; Koninklijke Philips N.V.; CamNtech Ltd; Empatica Inc.; ActivInsights Ltd; Neurocare Group AG
Customization scope
Free report customization (equivalent to 8 analyst working days) with purchase. Addition or alteration to country, regional & segment scope.
Pricing and purchase options
Avail of customized purchase options to meet your exact research needs. Explore purchase options
Global Actigraphy Device Market Report Segmentation
This report forecasts revenue growth at the global, regional, and country levels and provides an analysis of the latest industry trends and opportunities across each sub-segment from 2021 to 2033. For this study, Grand View Research has segmented the global actigraphy device market report based on application, end-use, and region:
- Application Outlook (Revenue, USD Billion, 2021 - 2033)
- Sleep Disorders
- Physical Activity Monitoring
- Chronic Disease Management
- End-use Outlook (Revenue, USD Billion, 2021 - 2033)
- Healthcare Providers
- Research Institutions
- Homecare Settings
- Fitness and Sports Centers
- Regional Outlook (Revenue, USD Billion, 2021 - 2033)
- North America
- U.S.
- Canada
- Mexico
- Europe
- UK
- Germany
- France
- Italy
- Spain
- Denmark
- Sweden
- Norway
- Asia Pacific
- Japan
- China
- India
- Thailand
- South Korea
- Australia
- Latin America
- Brazil
- Argentina
- Middle East & Africa
- South Africa
- Saudi Arabia
- UAE
- Kuwait
- North America
Frequently Asked Questions About This Report
The North America region dominated the global actigraphy device market, accounting for approximately 35.0% of revenue in 2025.
Key players in the market include Ametris (formerly ActiGraph, LLC.), Fibion Inc., Koninklijke Philips N.V., CamNtech Ltd, Empatica Inc., ActivInsights Ltd, and Neurocare Group AG, among others.
The sleep disorders segment accounted for the largest revenue share, over 50.0%, in 2025.
The global actigraphy device market size was valued at USD 3.3 billion in 2025 and is estimated at USD 4.2 billion in 2026.
The global actigraphy device market is expected to grow at a CAGR of 24.6% from 2026 to 2033, reaching USD 19.7 billion.
About the Author(s)
Medical Devices Research Team
Healthcare · Medical DevicesThis report was authored by the medical devices research team at Grand View Research - comprising two research analysts, one senior research analyst, and one industry expert - with specialized expertise in the medical devices segment of the healthcare industry. All findings are based on proprietary healthcare databases, executive interviews, and regulatory analysis, subject to internal peer review prior to publication.
Last Updated:
Speak to Analyst

Customize this report to your needs - add regions, segments, or data points, with 20% free customization.
Or view our licence options:


ISO 9001:2015 & 27001:2022 Certified
We are GDPR and CCPA compliant! Your transaction & personal information is safe and secure. For more details, please read our privacy policy.


