
- Home
- »
- Pharmaceuticals
- »
-
Acute Myeloid Leukemia Treatment Market Size Report 2033GVR Report cover

Acute Myeloid Leukemia Treatment Market (2026 - 2033)
Size, Share & Trends Analysis Report By Disease, By Treatment, By Route of Administration (Parenteral, Oral), By End Use, By Region, And Segment Forecasts
Market Size, 2025
$3.8BMarket Estimate, 2026
$4.2BMarket Forecast, 2033
$8.7BCAGR, 2026–2033
11.2%Acute Myeloid Leukemia Treatment Market Summary
The global acute myeloid leukemia treatment market size was valued at USD 3.8 billion in 2025 and is projected to grow from USD 4.2 billion in 2026 to USD 8.7 billion by 2033, at a CAGR of 11.2% from 2026 to 2033. North America dominated the market, accounting for a revenue share of 40.0% in 2025. The market is driven by the rising incidence of AML among the aging population and significant unmet treatment needs, particularly among elderly and relapsed/refractory patients, alongside the increasing adoption of targeted therapies, advances in molecular diagnostics, expanding clinical research, and continued approvals of novel therapies.
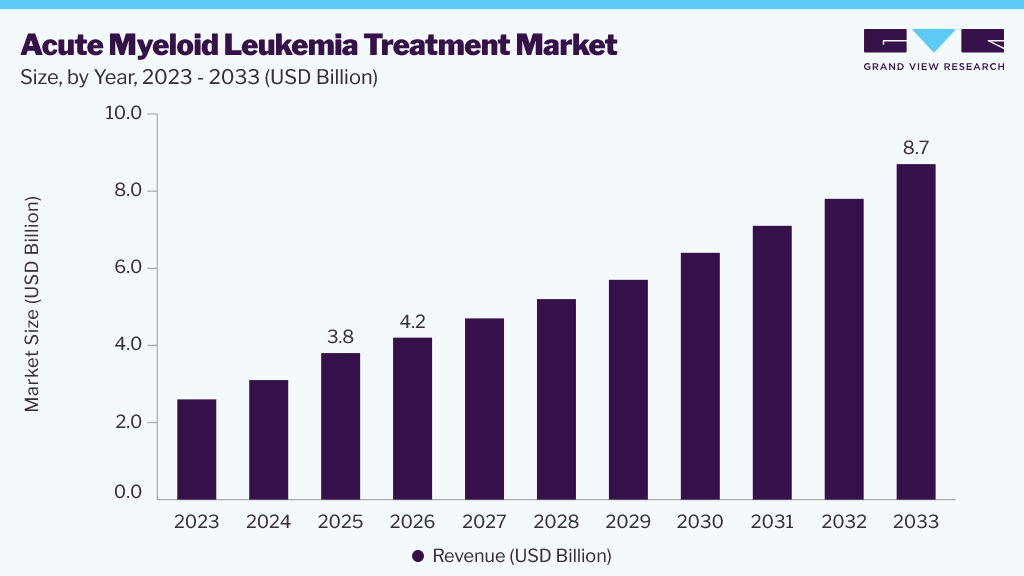 Source: Grand View Research, IR Documents, Primary Interviews, Paid DatabasesTo learn more about this report,
 Download Free Sample Report
Key Market Trends & Insights
- By disease: Myeloblastic leukemia segment accounted for the largest share of around 45.0% in 2025.
- By treatment: Chemotherapy segment accounted for the largest share of around 50.0% in 2025.
- By route of administration: Parenteral route segment accounted for the largest share of over 60.0% in 2025.
- By end use, Hospitals and clinics segment accounted for the largest share of around 50.0% in 2025.
Regional Highlights
- Largest regional market: North America (40.0% revenue share, 2025)
- Fastest-growing regional market: Asia Pacific (highest CAGR, 2026-2033)
Market Size & Forecast
- Market size in 2025: USD 3.8 Billion
- Estimated market size in 2026: USD 4.2 Billion
- Projected market size by 2033: USD 8.7 Billion
- CAGR (2026-2033): 11.2%
Prism AI by Grand View Research Free to tryAsk a question about the acute myeloid leukemia treatment marketTry asking✓Every figure cited from GVR research Prefer the report? Download free sample →
The rising incidence of acute myeloid leukemia (AML), driven by genetic mutations, aging, unhealthy lifestyles, and exposure to hazardous chemicals such as benzene and radiation, is increasing the demand for advanced treatment options. According to the American Cancer Society, approximately 22,010 new AML cases are expected to be diagnosed in the U.S. in 2025, highlighting the growing clinical need.Advances in targeted therapies have significantly transformed AML treatment, particularly therapies targeting BCL2, FLT3, IDH, and menin pathways, enabling more personalized treatment approaches. In October 2025, the U.S. FDA approved Revuforj (revumenib) from Syndax Pharmaceuticals for relapsed or refractory AML with susceptible NPM1 mutations, expanding precision treatment options. Similarly, in June 2025, the FDA accepted the NDA for ziftomenib from Kura Oncology and Kyowa Kirin and granted Priority Review for the treatment of relapsed or refractory NPM1-mutant AML.
Combination regimens, including venetoclax with hypomethylating agents, continue to improve patient outcomes, while emerging immunotherapies, such as CAR T-cell therapies, are expanding treatment options for high-risk patients. Continued R&D investments, strategic collaborations, and a growing precision medicine pipeline are expected to accelerate market growth over the forecast period further.
Analyst Perspective
The global acute myeloid leukemia treatment market is expected to grow steadily, driven by the rising incidence of hematologic malignancies, increasing adoption of targeted therapies, and ongoing advancements in precision oncology. The growing availability of molecular diagnostics, personalized treatment approaches, and novel immunotherapies is accelerating market expansion by improving treatment outcomes and supporting earlier therapeutic intervention. Furthermore, ongoing clinical trials, expanding regulatory approvals for innovative drugs, and increasing investment in oncology research are creating new opportunities for market growth. However, the high cost of advanced therapies, the risk of drug resistance, and the complexity of treatment management may hinder market growth.
Disease Insights
The myeloblastic leukemia segment accounted for the largest market share, at around 45.0% in 2025, driven by the disease type’s high incidence and prevalence, which drive significant demand for effective treatments. The robust size of this market segment is also supported by the continuous development of new therapies and the improvement of existing treatments. For instance, in October 2024, the National Institutes of Health launched a precision medicine clinical trial in the U.S. to evaluate targeted treatment combinations for acute myeloid leukemia and myelodysplastic syndromes based on patients’ genetic profiles. Further investment in research is evident with significant funding. For instance, in February 2025, Auron Therapeutics announced that the FDA granted Fast Track designation to AUTX-703 for relapsed or refractory acute myelogenous leukemia, underscoring the urgent need for innovative treatments for patients in the U.S. facing poor outcomes.
Promyelocytic leukemia is expected to grow at the fastest CAGR over the forecast period, driven by advancements in targeted therapies and a deeper understanding of the disease’s molecular basis, leading to more effective, tailored approaches. Innovations such as arsenic trioxide and all-trans retinoic acid (ATRA) revolutionized the treatment paradigm, significantly improving survival rates and reducing long-term side effects associated with traditional chemotherapy. Focused research on molecular and genetic therapies has further stimulated the rapid development and adoption of new treatments in this market segment.
Treatment Insights
The chemotherapy segment accounted for the largest market share, at around 50.0%, in 2025. Chemotherapy has maintained its status as a primary treatment modality for AML due to its broad application across various subtypes and proven efficacy in achieving remission, especially during induction therapy. For instance, in December 2024, the 66th American Society of Hematology Annual Meeting witnessed 3 studies that offered new insights into acute myelogenous leukemia treatment, enhancing understanding of CPX-351 efficacy, oral maintenance therapy outcomes, and long-term data on midostaurin for high-risk patients. Moreover, the strategic integration of chemotherapy with newer agents, such as low-dose cytarabine and glasdegib, has further improved outcomes for older patients and those with significant comorbidities, ensuring chemotherapy’s continued relevance and substantial market share in AML treatment strategies.
The immunotherapy segment is expected to grow at the fastest CAGR over the forecast period, fueled by breakthroughs in targeted therapies and monoclonal antibodies that enhance the immune system’s capacity to fight leukemia cells. Segment growth has been fueled by clinical successes and accelerated FDA approvals of treatments that specifically target pathways crucial for cancer cell survival. For instance, in July 2024, new findings from Therapeutic Advances in Hematology highlighted advances in CAR therapy for AML in China, focusing on targeting specific surface markers to enhance treatment efficacy. Immunotherapy’s potential to provide durable remissions with fewer side effects than conventional chemotherapy, along with ongoing clinical trials combining it with other therapies, underscores its emerging importance in AML treatment strategies. Significant research investments by major pharmaceutical companies further support its anticipated accelerated growth.
Route of Administration Insights
The parenteral route segment dominated the market, accounting for around 65.0% of revenue in 2025, primarily due to intravenous administration of the most effective chemotherapies, including cytarabine and anthracycline-based drugs. This method enables rapid absorption into the bloodstream, allowing for controlled dosing that effectively targets cancer cells. Given the urgent nature of AML, parenteral administration is vital for initial treatment phases aimed at achieving remission. The FDA’s approval of new drug combinations in 2023 further emphasized this segment’s critical role in effective AML management.
The oral segment is expected to grow at the fastest CAGR over the forecast period. The approval of new oral medications, such as IDH inhibitors (e.g., ivosidenib) and BCL-2 inhibitors (e.g., venetoclax), marked a significant advancement in AML treatment, offering ease of administration and the potential for outpatient care. For instance, in December 2024, findings from the ASH Annual Meeting indicated that the revumenib-based combination therapy showed significant remission rates in patients with relapsed/refractory acute myeloid leukemia. Oral therapies have effectively targeted specific AML subtypes, reflecting a shift towards less invasive treatments that improve patient convenience, reduce hospital stays, lower costs, and enhance compliance and satisfaction.
End Use Insights
The hospitals and clinics segment accounted for the largest market share, at around 50.0%, in 2025. This is primarily due to the complex nature of AML, which requires sophisticated diagnostic tools, specialized healthcare professionals, and advanced facilities to manage treatment effectively. Hospitals and clinics are equipped to provide comprehensive care, including high-dose chemotherapy and stem cell transplants, which are often necessary in AML treatment protocols.
Hospital infrastructure enables the integration of multidisciplinary teams needed for AML management, including hematologists, oncologists, nurses, and support staff, ensuring a coordinated treatment approach. In 2023, reliance on hospitals for AML treatment was further emphasized by the introduction of advanced therapies requiring controlled administration and monitoring, underscoring hospitals' critical role in delivering intensive care.
Homecare setting is expected to grow at the fastest CAGR over the forecast period. This growth is driven by the increasing availability of oral chemotherapeutics and targeted therapies, which can be safely administered at home. The shift towards home care is facilitated by advancements in telehealth and remote monitoring technologies, allowing healthcare providers to offer continuous support and management of AML patients from a distance.
In 2024, the expansion of homecare services was influenced by healthcare policies aimed at reducing hospital readmissions and the burden on healthcare facilities, while also improving patients' quality of life by allowing them to receive treatment in the comfort of their homes. The adoption of homecare settings is further supported by the development of patient education programs and home health services, ensuring that patients receive safe and effective treatment outside of hospital settings.
Regional Insights
North America acute myeloid leukemia treatment market dominated the global market with a revenue share of around 40.0% in 2025. Targeted therapies and immunotherapies have shown promising results in clinical trials, transforming AML treatment in North America. A significant emphasis on precision medicine aims to tailor therapies to individual genetic profiles, with emerging treatments such as BiTE antibodies and CAR-T cell therapy offering hope for refractory cases. A 2024 study by the Alliance for Leukemias in Mexico revealed considerable disparities in access to leukemia care. Only 29.5% of the physicians surveyed reported having a dedicated leukemia clinic, while 64.2% identified access to diagnostic tests as a major treatment barrier. For instance, the PRONAII Childhood Leukemia Project advanced leukemia care in Mexico by enhancing diagnostic capabilities, fostering collaboration, standardizing processes, and addressing disparities in the states of Oaxaca, Puebla, and Tlaxcala, ultimately seeking to reduce early mortality rates among children with leukemia. Recent initiatives to improve leukemia care in Mexico have significantly contributed to market growth.
To learn more about this report, Download Free Sample Report U.S. Acute Myeloid Leukemia Treatment Market Trends
The acute myeloid leukemia treatment market in the U.S. dominated North America in 2025. Market growth in the country is influenced by the stringent regulatory environment governing drug approvals and clinical trials. The FDA is crucial in evaluating and approving new AML therapies, ensuring patient safety and efficacy standards are met. Furthermore, the high healthcare expenditure in the U.S. enables patients to access advanced treatments, contributing to the rapid adoption of novel therapies in the market. For instance, in September 2024, ImCheck Therapeutics received FDA Fast Track designation in the U.S. for ICT01, combined with azacitidine and venetoclax, to treat AML patients unfit for intensive chemotherapy.
Asia Pacific Acute Myeloid Leukemia Treatment Market Trends
The Asia Pacific acute myeloid leukemia treatment market is expected to register the fastest CAGR during the forecast period. The region presents distinct trends in AML treatment driven by economic factors, regulatory landscapes, and cultural nuances. In countries such as China and Japan, there is a growing demand for innovative therapies due to the rising prevalence of AML and improved healthcare infrastructure. Regulatory bodies in the Asia-Pacific region are working to streamline drug approval processes to expedite patient access to advanced treatments.
The acute myeloid leukemia treatment market in Japan is projected to grow at the fastest CAGR in the APAC market over the forecast period. The aging population has led to a higher incidence of AML among older adults; moreover, advancements in diagnostic techniques have enabled earlier detection of the disease. Recent regulatory approvals of targeted therapies, such as quizartinib, further expanded treatment options, while global collaboration continues to advance AML management research and practices. For instance, in May 2024, Nippon Shinyaku launched Vyxeos Combination for IV injection in Japan, following marketing approval from the Ministry of Health, Labor and Welfare for the treatment of high-risk AML.
Key Acute Myeloid Leukemia Treatment Market Company Insights
The acute myeloid leukemia treatment market is characterized by global, regional, and niche solution providers competing through technological innovation, strategic partnerships, acquisitions, and product portfolio expansion.
Key Acute Myeloid Leukemia Treatment Companies
The following key companies have been profiled for this study on the acute myeloid leukemia treatment market:
-
Astellas Pharma Inc.
-
Bristol-Myers Squibb Company
-
DAIICHI SANKYO COMPANY, LIMITED
-
Jazz Pharmaceuticals plc
-
Merck KGaA
-
Novartis AG
-
Otsuka Pharmaceuticals Co., Ltd.
-
Pfizer Inc.
-
Rigel Pharmaceuticals, Inc.
-
Sanofi
Recent Developments
-
In December 2024, the QuANTUM-Wild Phase 3 trial began in Japan and the U.S., assessing VANFLYTA’s efficacy combined with chemotherapy for patients with newly diagnosed FLT3-ITD negative acute myeloid leukemia.
-
In September 2024, Rigel expanded its partnership with Kissei, granting them exclusive rights to develop and commercialize REZLIDHIA in Japan, Korea, and Taiwan, receiving an upfront payment of USD 10 million.
-
In April 2024, Actinium revealed the results of the Phase 3 SIERRA trial for Iomab-B, showing a survival advantage in patients with high-risk relapsed or refractory acute myeloid leukemia who have TP53 mutations. These findings were accepted for oral presentation at the 50th European Bone Marrow Transplant Annual Meeting.
Acute Myeloid Leukemia Treatment Market Report Scope
Report Attribute
Details
Market size in 2025
USD 3.8 billion
Estimated market size in 2026
USD 4.2 billion
Projected market size by 2033
USD 8.7 billion
Growth rate
CAGR of 11.2% from 2026 to 2033
Base year for estimation
2025
Historical data
2021 - 2024
Forecast period
2026 - 2033
Quantitative units
Revenue in USD billion, and CAGR from 2026 to 2033
Report coverage
Revenue forecast, company ranking, competitive landscape, growth factors, and trends
Segments covered
Disease, treatment, route of administration, end use, region
Regional Scope
North America; Europe; Asia Pacific; Latin America; Middle East & Africa
Country Scope
U.S.; Canada; Mexico; UK; Germany; France; Italy; Spain; Denmark; Sweden; Norway; China; Japan; India; Australia; South Korea; Thailand; Brazil; Argentina; South Africa; Saudi Arabia; UAE; Kuwait
Key companies profiled
Astellas Pharma Inc.; Bristol-Myers Squibb Company; DAIICHI SANKYO COMPANY, LIMITED; Jazz Pharmaceuticals plc; Novartis AG; Otsuka Pharmaceuticals Co., Ltd.; Pfizer Inc.; Rigel Pharmaceuticals, Inc.; Merck KGaA; Sanofi
Customization scope
Free report customization (equivalent to 8 analyst working days) with purchase. Addition or alteration to country, regional & segment scope.
Pricing and purchase options
Avail of customized purchase options to meet your exact research needs. Explore purchase options
Global Acute Myeloid Leukemia Treatment Market Report Segmentation
This report forecasts revenue growth at the global, regional, and country levels and provides an analysis of the latest industry trends and opportunities across each sub-segment from 2021 to 2033. For this study, Grand View Research has segmented the global acute myeloid leukemia treatment market report based on disease, treatment, route of administration, end use, and region:
- Disease Outlook (Revenue, USD Billion, 2021 - 2033)
- Myeloblastic Leukemia
- Myelomonocytic Leukemia
- Promyelocytic Leukemia
- Monocytic Leukemia
- Other Diseases
- Treatment Outlook (Revenue, USD Billion, 2021 - 2033)
- Chemotherapy
- Anti-metabolites
- Alkylating Agents
- Anthracycline Drugs
- Others
- Targeted Therapy
- FLT3 Inhibitors
- Rydapt
- Vanflyta
- Xospata
- IDH Inhibitors
- Tibsovo
- Rezlidhia
- Idhifa
- Mylotarg
- BCL-2 Inhibitor
- Hedgehog Pathway Inhibitor
- FLT3 Inhibitors
- Immunotherapy
- Bispecific Antibodies
- Antibody-drug Conjugates
- Immune Checkpoint Inhibitors
- Chimeric Antigen Receptor (CAR) T-cell Therapy
- Other Treatments
- Chemotherapy
- Route of Administration Outlook (Revenue, USD Billion, 2021 - 2033)
- Parenteral
- Oral
- End Use Outlook (Revenue, USD Billion, 2021 - 2033)
- Hospitals and Clinics
- Specialty Centers
- Homecare Setting
- Ambulatory Care Centers
- Regional Outlook (Revenue, USD Billion, 2021 - 2033)
- North America
- U.S.
- Canada
- Mexico
- Europe
- UK
- Germany
- France
- Italy
- Spain
- Denmark
- Sweden
- Norway
- Asia Pacific
- Japan
- China
- India
- Australia
- South Korea
- Thailand
- Latin America
- Brazil
- Argentina
- Middle East & Africa
- South Africa
- Saudi Arabia
- UAE
- Kuwait
- North America
Frequently Asked Questions About This Report
The global acute myeloid leukemia treatment market is expected to grow at a CAGR of 11.2% from 2026 to 2033, reaching USD 8.7 billion in 2033.
The global acute myeloid leukemia treatment market size was valued at USD 3.8 billion in 2025 and is estimated at USD 4.2 billion in 2026.
North America dominated with an approximately 40.0% revenue share in 2025.
Key players in the market include Astellas Pharma Inc., Bristol-Myers Squibb Company, Daiichi Sankyo Company, Limited, Jazz Pharmaceuticals, plc, Novartis AG, Otsuka Pharmaceuticals Co., Ltd., Pfizer, Inc., Rigel Pharmaceuticals, Inc., Merck KGaA, and Sanofi, among others.
The myeloblastic leukemia segment accounted for the largest revenue share in 2025, at around 45.0%.
About the Author(s)
Pharmaceuticals Research Team
Healthcare · PharmaceuticalsThis report was authored by the pharmaceuticals research team at Grand View Research - comprising two research analysts, one senior research analyst, and one industry expert - with specialized expertise in the pharmaceuticals segment of the healthcare industry. All findings are based on proprietary healthcare databases, executive interviews, and regulatory analysis, subject to internal peer review prior to publication.
Last Updated:
Speak to Analyst

Customize this report to your needs - add regions, segments, or data points, with 20% free customization.
Or view our licence options:


ISO 9001:2015 & 27001:2022 Certified
We are GDPR and CCPA compliant! Your transaction & personal information is safe and secure. For more details, please read our privacy policy.


