
- Home
- »
- Advanced Interior Materials
- »
-
Aerospace Parts Manufacturing Market Report, 2026-2033GVR Report cover

Aerospace Parts Manufacturing Market (2026 - 2033)
Size, Share & Trends Analysis Report By Product (Engine, Aerostructure, Avionics, Insulation Components, Equipment, System, & Support), By End Use (Commercial, Business, Military), By Region And Segment Forecasts
Market Size, 2025
$1,003.0BMarket Estimate, 2026
$1,042.8BMarket Forecast, 2033
$1,426.9BCAGR, 2026–2033
5.4%Aerospace Parts Manufacturing Market Summary
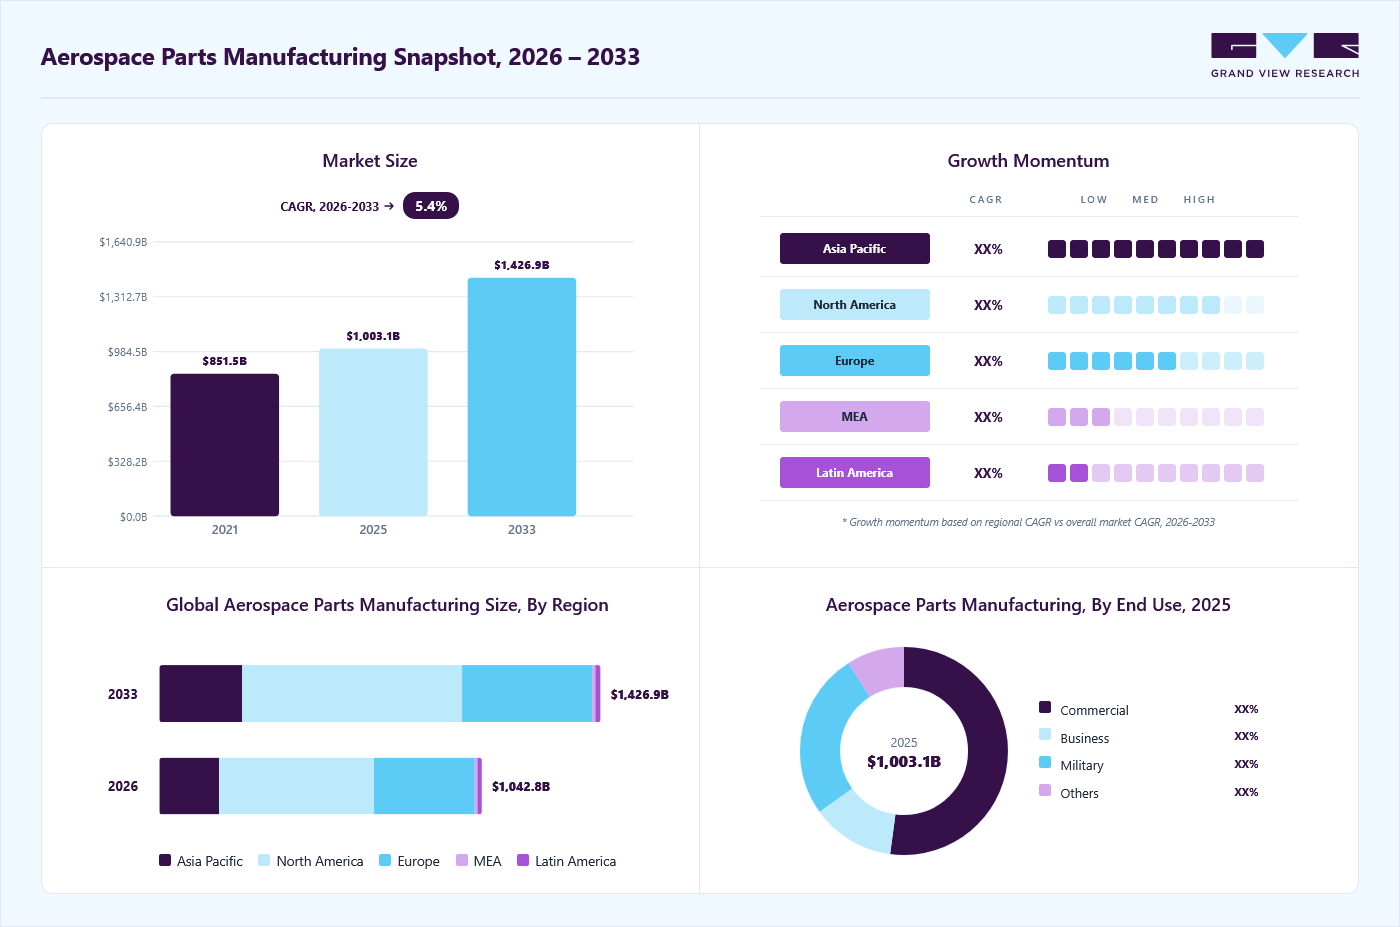
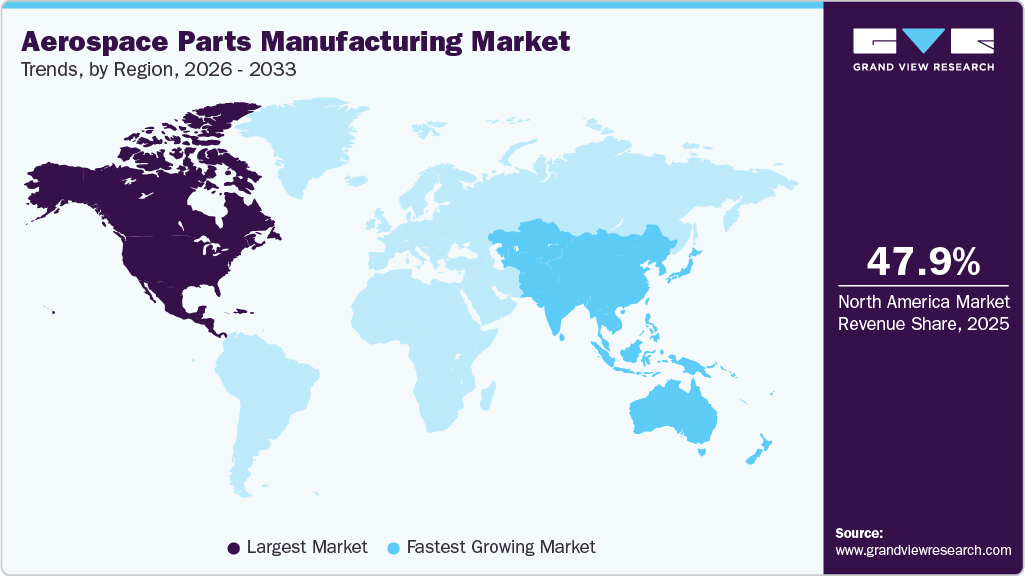
The global aerospace parts manufacturing market size was valued at USD 1,003.0 billion in 2025 and is projected to grow from USD 1,042.8 billion in 2026 to USD 1,426.9 billion by 2033, at a CAGR of 5.4% from 2026 to 2033. The market in North America dominated with a revenue share of 47.9% in 2025. The market is growing due to the significant backlog of orders for next-generation commercial aircraft.
 Source: Grand View Research, IR Documents, Primary Interviews, Paid DatabasesTo learn more about this report,
 Download Free Sample Report
Key Market Trends & Insights
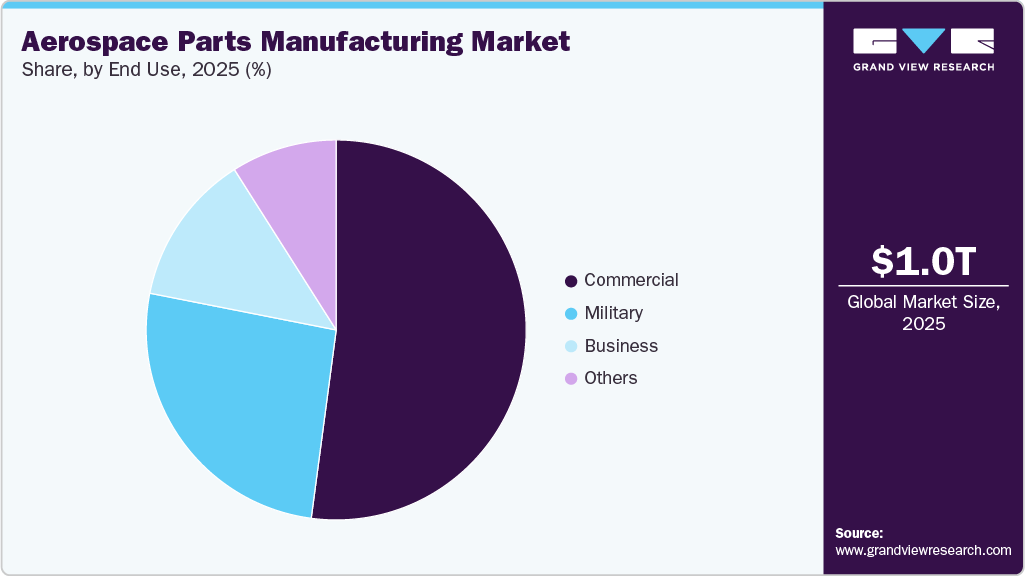
- By end use: Commercial segment held the largest market share of 52.1% in 2025.
- By product: Aerostructure segment held the largest market share of 50.5% in 2025.
Regional Highlights
- Largest regional market: North America (47.9% revenue share, 2025)
- Fastest-growing regional market: Asia Pacific (highest CAGR, 2026-2033)
- By country: The U.S. held the largest market share in 2025
Market Size & Forecast
- Market size in 2025: USD 1,003.0 Billion
- Estimated market size in 2026: USD 1,042.8 Billion
- Projected market size by 2033: USD 1,426.9 Billion
- CAGR (2026-2033): 5.4%
Three ways to get this report
Buy it, customize it, or ask a question.Ask an Analyst
Analyst response in 1 business day
- AccessReport author, directly
- Reply timeWithin 1 working day
- No sales callDirect answer only
- FormatEmail reply
- CostFree, no cost
Get the Full Report
What the study covers
- FormatsPDF · Excel · Dashboard
- Timeline2026–2033 annual, 2025 base
- Coverage20+ countries, 5 regions
- Companies10+ key players profiled
Customize the Report
20% free customization
- IncludeCountries, segments, points
- TailorTo your product definition
- ExtendDeeper competitor detail
- OrA fully bespoke study
- Turnaround5–10 working days
With global passenger air traffic recovering and surpassing pre-pandemic levels, airlines are increasingly focused on fleet modernization to enhance fuel efficiency and reduce operating costs. This sustained demand for new narrow-body and wide-body aircraft is generating a stable, long-term requirement for high-precision components and assemblies across the manufacturing supply chain.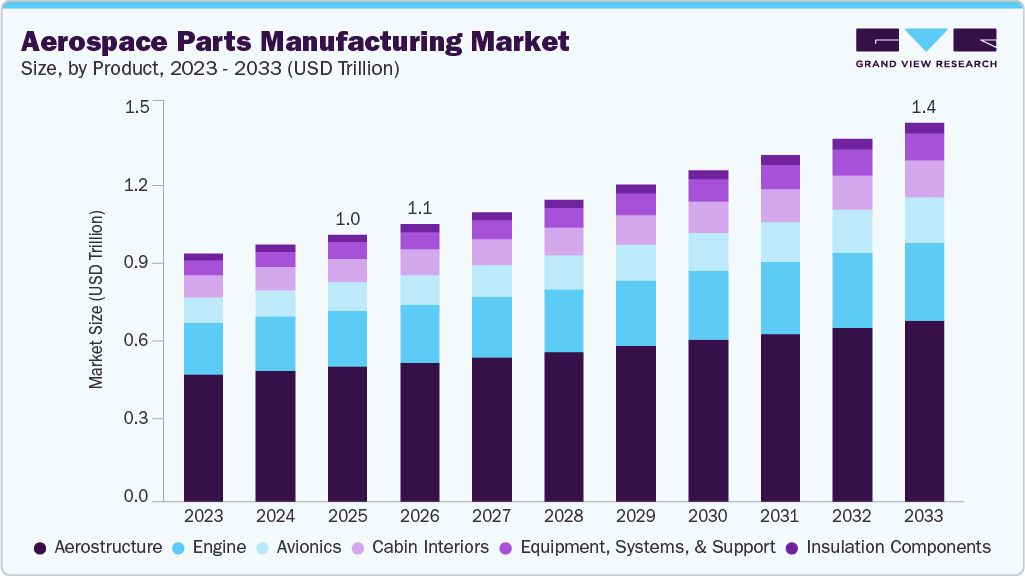 To learn more about this report, Download Free Sample Report
Moreover, increasing global defense budgets and a robust Maintenance, Repair, and Overhaul (MRO) sector are also contributing toward market growth. Geopolitical tensions have prompted nations to invest heavily in advanced fighter jets, UAVs (Unmanned Aerial Vehicles), and military transport, necessitating specialized aerospace-grade parts. Concurrently, the aging of existing global fleets drives a continuous need for replacement components, ensuring a steady revenue stream for manufacturers.
Market Concentration & Characteristics
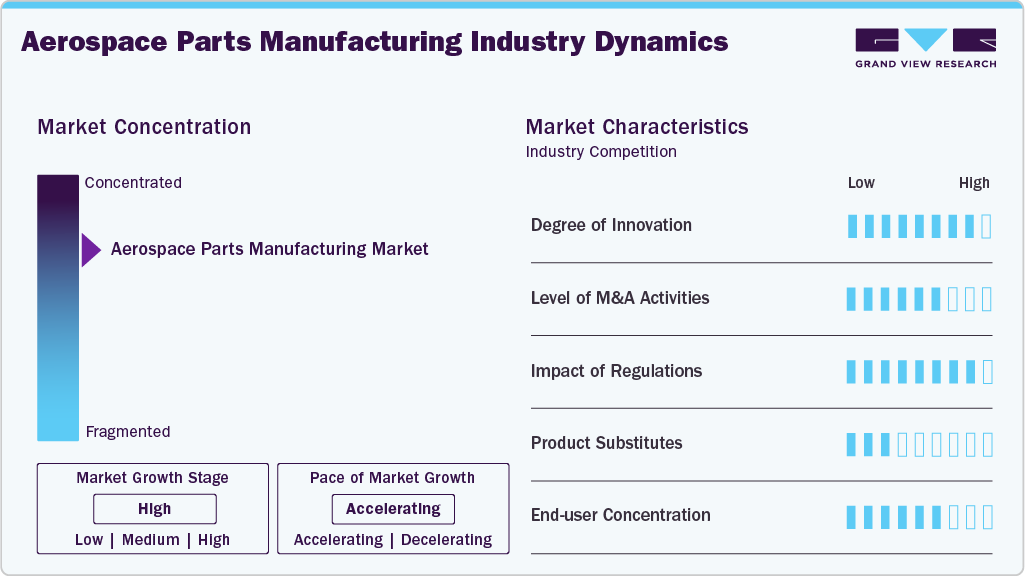
The aerospace parts manufacturing industry is structurally highly concentrated, characterized by a limited number of Tier-1 OEMs and specialized suppliers due to high capital intensity, certification barriers, and technological complexity. Major aircraft manufacturers such as Boeing and Airbus dominate demand, while a relatively small pool of approved suppliers competes for long-term contracts.
Regulation is a defining force shaping industry structure and economics. Stringent certification regimes enforced by bodies such as the Directorate General of Civil Aviation and global aviation authorities impose rigorous standards on materials, design, testing, and traceability. These requirements significantly raise entry barriers, elongate product development cycles, and increase costs, but also reinforce incumbency advantages and ensure high reliability. At the same time, environmental regulations, emissions reduction, for instance, are pushing manufacturers toward fuel-efficient designs and sustainable materials, indirectly accelerating innovation while tightening compliance burdens.
 To learn more about this report, Download Free Sample Report
Technology is a significant competitive aspect, with advancements in composite materials, additive manufacturing (3D printing), IoT-enabled smart components, and automation/Industry 4.0 reshaping production and product design. These technologies improve weight efficiency, predictive maintenance, and cost structures, while enabling new entrants in niche areas. Leading players are responding through vertical integration, strategic partnerships, and heavy R&D investment, including joint ventures and supply chain consolidation to manage risk and secure contracts.
Drivers, Opportunities & Restraints
The market growth is driven by a combination of increasing fleet renewal activities, rising defense expenditures, and ongoing technological advancements. The adoption of additive manufacturing (three-dimensional printing) and advanced composite materials is enabling the production of lighter and more durable components. In addition, the focus on sustainable aviation is creating opportunities for electric and hybrid propulsion-related parts. These factors collectively support higher production rates and a shift toward more complex, high-value manufacturing.
The primary opportunity for growth lies in the rapid adoption of advanced manufacturing technologies, specifically additive manufacturing (3D printing) and digital twin modeling. These technologies enable the production of complex, lightweight components that reduce fuel consumption and material waste, aligning with the industry's shift toward sustainable aviation. Emerging markets in the Asia Pacific and the Middle East are also contributing to new growth prospects, supported by rising air traffic and investments in domestic aerospace manufacturing capabilities.
The market is significantly constrained by high capital expenditure and the cyclical nature of the industry. Establishing aerospace-grade production facilities requires substantial investments, creating high barriers to entry. In addition, rigorous regulatory and certification requirements can account for a considerable proportion of development budgets and delay product launches. Supply chain vulnerabilities, including the volatility of raw material prices for titanium and specialized alloys, further impact production stability and profit margins for manufacturers.
Product Insights
Aerostructure was the largest segment in 2025 in terms of revenue. This segment includes the production and assembly of the airframe, particularly the fuselage, wings, and flight control surfaces. The segment’s growth is driven by the increasing adoption of advanced composite materials and titanium alloys, due to a growing need for reducing aircraft weight to enhance fuel efficiency and minimize structural fatigue. This segment is essential for both large-scale commercial production and highly customized business jet configurations.
Equipment, system, and support is expected to accelerate at a rapid CAGR over the forecast period. The segment encompasses a broad range of components and services that enable aircraft functionality, integration, and lifecycle performance. This includes onboard equipment, integrated systems such as hydraulic, fuel, and electrical systems, as well as support elements related to installation, maintenance, and operational reliability. Demand for this segment is driven by increasing aircraft production, ongoing fleet modernization, and the growing complexity of aircraft architectures, particularly with the shift toward more electric and digitally integrated platforms.
End Use Insights
The commercial segment accounted for the largest market share in 2025, driven by sustained growth in passenger air traffic and a significant multi-year backlog of orders for narrow-body and wide-body aircraft from original equipment manufacturers (OEMs). Airlines, including both full-service carriers and low-cost operators, are actively expanding and modernizing their fleets to improve fuel efficiency and operational economics. Consequently, manufacturing within this segment is characterized by a strong emphasis on scalability, cost efficiency, and high-volume production to meet consistent global demand.
 To learn more about this report, Download Free Sample Report
The business segment represents a smaller but stable share of the market, driven by demand for corporate travel, private aviation, and specialized mission aircraft. Growth in this segment is supported by rising adoption among high-net-worth individuals and enterprises seeking flexibility, time efficiency, and enhanced connectivity. Manufacturing in the business aircraft segment places greater emphasis on customization, premium materials, and advanced cabin systems compared to commercial aircraft.
Regional Insights
North America was the largest regional market in 2025 and is characterized by high levels of government defense spending and a robust infrastructure for commercial aircraft production. Manufacturers are increasingly focused on digital integration and automated production lines to maintain technological superiority and market share. A significant driver is the large-scale modernization of aging commercial fleets, which sustains demand for fuel-efficient next-generation parts.
 To learn more about this report, Download Free Sample Report
U.S. Aerospace Parts Manufacturing Market Trends
The aerospace parts manufacturing market in the U.S. is characterized by advanced technological capabilities, a well-established supply chain, and strong demand from both commercial and defense aviation. The U.S. market is driven by massive commercial backlogs and the world’s largest defense budget. The market scenario is characterized by a transition toward Industry 4.0, with heavy investment in automated assembly lines and digital twin technology to accelerate production rates.
Europe Aerospace Parts Manufacturing Market Trends
The aerospace parts manufacturing market in Europe is driven by a strong focus on sustainability and the development of next-generation aircraft in compliance with European Union Aviation Safety Agency (EASA) standards. Key growth factors include the expansion of the Space 2.0 ecosystem and a notable increase in regional defense budgets amid evolving geopolitical dynamics. Manufacturers in the region are at the forefront of adopting advanced composite materials and additive manufacturing (three-dimensional printing) technologies to meet stringent emissions and noise regulations, while also enhancing performance and efficiency.
The UK aerospace parts manufacturing market holds a strong position in aircraft components, particularly in engines, aerostructures, and advanced systems. The market is a global center for aerospace engines and wing technology, largely due to the presence of Rolls-Royce and Airbus operations. The country also emphasizes research and development in lightweight materials and advanced manufacturing processes, strengthening its role as a high-value component supplier.
The aerospace parts manufacturing market in Germany is supported by a robust industrial base, strong engineering expertise, and its integration within the broader European aerospace ecosystem. The market benefits from collaborations with major aircraft manufacturers and suppliers, alongside a focus on precision manufacturing and advanced materials. Growth is further driven by investments in defense modernization, increasing aircraft production rates, and the adoption of Industry 4.0 technologies to improve efficiency and production quality.
Asia Pacific Aerospace Parts Manufacturing Market Trends
The aerospace parts manufacturing market in the Asia Pacific is the fastest-growing regional market, primarily driven by the rapid growth of low-cost carriers (LCCs) and the massive surge in domestic air passenger traffic in China and India. Government initiatives to localize aerospace production and establish domestic supply chains are key strategic drivers. The region is also becoming a global hub for Maintenance, Repair, and Overhaul (MRO) services.
Japan aerospace parts manufacturing market is primarily driven by government policy, with the government committed to increasing defense spending to 2.0% of GDP by 2027. Complementing this defense growth is Japan’s established role as a Tier 1 supplier for global commercial platforms, where its specialization in advanced carbon-fiber composites and precision titanium machining plays a significant role in the production of fuel-efficient narrow and wide-body aircraft.
The aerospace parts manufacturing market in China is expanding rapidly, supported by strong government backing and increasing domestic aircraft production. The market’s growth is driven by the localization of commercial aviation, particularly the increase in production of the COMAC C919 program aimed at competing with foreign competition. Government initiatives such as Made in China 2025 are providing substantial support for the development of domestic capabilities in avionics and engine manufacturing, reducing reliance on imports.
Latin America Aerospace Parts Manufacturing Market Trends
The aerospace parts manufacturing market in Latin America is expected to witness steady growth, supported by increasing regional aircraft maintenance, repair, and overhaul (MRO) activities, gradual expansion of domestic aerospace manufacturing capabilities, and rising defense investments in key countries such as Brazil and Argentina. Moreover, growing air passenger traffic, fleet modernization initiatives, and growing participation in global aerospace supply chains contribute to market growth.
Brazil aerospace parts manufacturing market is supported by a well-established ecosystem, anchored by companies such as Embraer, a prominent aircraft manufacturer with headquarters and operations in the country. Growth is driven by increasing nearshoring trends, as North American companies seek to diversify supply chains closer to home, along with the country’s strengths in aerostructures and integrated systems manufacturing. However, market expansion is moderated by economic volatility and a relatively high tax burden on imported specialized machinery required for capacity upgrades and technological advancement.
Middle East & Africa Aerospace Parts Manufacturing Market Trends
The aerospace parts manufacturing market in the MEA is supported by increasing air passenger traffic, the expansion of major aviation hubs in the Gulf countries, and ongoing fleet modernization initiatives led by national carriers. In addition, rising defense spending and investments in domestic aerospace capabilities are contributing to steady demand for aircraft components.
Saudi Arabia aerospace parts manufacturing market is developing steadily, supported by increasing defense spending and government initiatives aimed at localizing aerospace manufacturing under national diversification strategies. The country is investing in building domestic capabilities across maintenance, manufacturing, and supply chain integration through partnerships with global aerospace companies.
Key Aerospace Parts Manufacturing Company Insights
Some of the key players operating in the market include Safran Group and Rolls-Royce plc, among others.
-
Safran Group is an international group operating across three primary segments: Aerospace Propulsion, Equipment & Defense, and Aircraft Interiors. The company has a strong presence in narrow-body aircraft engines through the CFM International joint venture, which delivered 1,802 LEAP engines in 2025. Moreover, Safran is a Tier 1 manufacturer of high-value components, including carbon brakes, landing gear, and nacelles, with a growing focus on integrating flight control and actuation businesses acquired from Collins Aerospace to enhance its vertical manufacturing capabilities.
-
Rolls-Royce plc is a British multinational power systems company, structured into four core divisions: Civil Aerospace, Defense, Power Systems, and Small Modular Reactors (SMR). Its aerospace parts manufacturing business focuses on large-engine wide-body platforms, particularly the Trent engine series, where the company is currently executing a strategic program to double component durability by 2027. Rolls-Royce maintains a significant manufacturing footprint in precision-engineered turbine blades and high-pressure components, while simultaneously expanding its defense manufacturing capacity to support next-generation combat and transport engine programs in the U.S. and UK.
Key Aerospace Parts Manufacturing Companies:
The following key companies have been profiled for this study on the aerospace parts manufacturing market.
- Rolls-Royce plc
- Safran Group
- GE Aviation
- Pratt & Whitney
- Honeywell International, Inc.
- MTU Aero Engines AG
- Spirit AeroSystems, Inc.
- Liebherr International AG
- Parker-Hannifin Corporation
- Thales S.A.
- Hexcel Corporation
- Mitsubishi Heavy Industries Ltd.
- Kawasaki Heavy Industries Ltd.
- Triumph Group
- Collins Aerospace (RTX Corporation)
- Eaton Corporation plc
- Woodward, Inc
- IHI Corporation
- Curtiss-Wright Corporation
- Magellan Aerospace
Recent Developments
-
In July 2025, Safran completed the acquisition of Collins Aerospace’s flight control and actuation business, a USD 1.8 billion transaction that adds a high-value, mission-critical systems portfolio to its operations. The acquired unit, which generated around USD 1.55 billion in revenue in 2024 and employs approximately 4,000 people across global facilities, will be integrated into Safran’s Electronics & Defense division. Strategically, the acquisition strengthens Safran’s position in flight control and actuation systems, enabling it to offer a more comprehensive portfolio.
-
In May 2025, Collins Aerospace announced an investment of over £16 billion (~USD 18.01 billion) in a research and development (R&D) project at its Kilkeel facility in Northern Ireland, focused on developing next-generation passenger seating for wide-body and twin-aisle aircraft. The initiative aims to design and manufacture highly innovative and complex seating systems, improving comfort, durability, and production efficiency, while supporting the company’s export growth.
Aerospace Parts Manufacturing Market Report Scope
Report Attribute
Details
Market size in 2025
USD 1,003.0 billion
Estimated market size in 2026
USD 1,042.8 billion
Projected market size by 2033
USD 1,426.9 billion
Growth rate
CAGR of 5.4% from 2026 to 2033
Historical data
2021 - 2025
Forecast period
2026 - 2033
Quantitative units
Revenue in USD billion/million and CAGR from 2026 to 2033
Report coverage
Revenue forecast, company market position analysis, competitive landscape, growth factors, and trends
Segments covered
Product, end use, region
Regional scope
North America; Europe; Asia Pacific; Latin America; MEA
Country Scope
U.S.; Canada; Mexico; UK; Germany; France; Italy; Netherlands; Poland; China; Indonesia; Japan; Philippines; Malaysia; Australia; Brazil; South Africa; Saudi Arabia; UAE
Key companies profiled
Rolls-Royce plc; Safran Group; GE Aviation; Pratt & Whitney; Honeywell International, Inc.; MTU Aero Engines AG; Spirit AeroSystems, Inc.; Liebherr International AG; Parker-Hannifin Corporation; Thales S.A.; Hexcel Corporation; Mitsubishi Heavy Industries Ltd.; Kawasaki Heavy Industries Ltd.; Triumph Group; Collins Aerospace (RTX Corporation); Eaton Corporation plc; Woodward, Inc; IHI Corporation; Curtiss-Wright Corporation; Magellan Aerospace
Customization scope
Free report customization (equivalent up to 8 analysts working days) with purchase. Addition or alteration to country, regional & segment scope.
Pricing and purchase options
Avail customized purchase options to meet your exact research needs. Explore purchase options
Global Aerospace Parts Manufacturing Market Report Segmentation
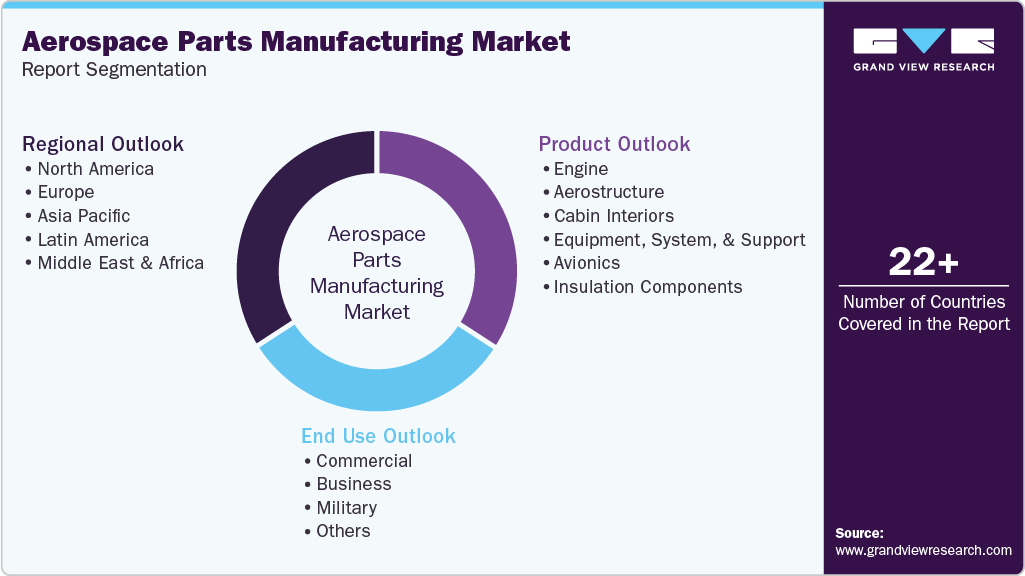
This report forecasts revenue growth at global, regional & country levels and provides an analysis of the industry trends in each of the sub-segments from 2021 to 2033. For this study, Grand View Research has segmented the global aerospace parts manufacturing market based on product, end use, and region:
 To learn more about this report, Download Free Sample Report
-
Product Outlook (Revenue, USD Billion, 2021 - 2033)
-
Engine
-
Aerostructure
-
Cabin Interiors
-
Equipment, System, and Support
-
Avionics
-
Insulation Components
-
-
End Use Outlook (Revenue, USD Billion, 2021 - 2033)
-
Commercial
-
Business
-
Military
-
Others
-
-
Regional Outlook (Revenue, USD Billion, 2021 - 2033)
-
North America
-
U.S.
-
Canada
-
Mexico
-
-
Europe
-
UK
-
Germany
-
France
-
Italy
-
Netherlands
-
Poland
-
-
Asia Pacific
-
China
-
India
-
Japan
-
Indonesia
-
Malaysia
-
Philippines
-
-
Latin America
-
Brazil
-
Argentina
-
-
Middle East & Africa
-
South Africa
-
Saudi Arabia
-
UAE
-
-
Frequently Asked Questions About This Report
The global aerospace parts manufacturing market size was valued at USD 1,003.0 billion in 2025 and is estimated at USD 1,042.8 billion for 2026.
The global aerospace parts manufacturing market is expected to grow at a CAGR of 5.4% from 2026 to 2033, reaching USD 1,426.9 billion by 2033.
The North America aerospace parts manufacturing market dominated the global revenue share in 2025 accounting for 47.9% of the share, driven by record defense spending, a massive commercial aircraft backlog from major OEMs, and the rapid integration of AI-driven automation.
Key players include Rolls-Royce plc; Safran Group; GE Aviation; Pratt & Whitney; Honeywell International, Inc.; MTU Aero Engines AG; Spirit AeroSystems, Inc.; Liebherr International AG; Parker-Hannifin Corporation; Thales S.A.; Hexcel Corporation; Mitsubishi Heavy Industries Ltd.; Kawasaki Heavy Industries Ltd.; Triumph Group; Collins Aerospace (RTX Corporation); Eaton Corporation plc; Woodward, Inc; IHI Corporation; Curtiss-Wright Corporation; Magellan Aerospace.
Asia Pacific is the fastest-growing region over the forecast period.
The aerostructure segment led with a 50.5% revenue share in 2025.
The commercial segment accounted for the largest revenue share of 52.1% in 2025.
The market is primarily driven by surging global air traffic necessitating fleet expansion, increased defense spending, and a transition toward lightweight composite materials to enhance fuel efficiency.
About the Author(s)
Advanced Interior Materials Research Team
Advanced Materials · Advanced Interior MaterialsThis report was authored by the advanced interior materials research team at Grand View Research - comprising two research analysts, one senior research analyst, and one industry expert - with specialized expertise in the advanced interior materials segment of the advanced materials industry. All findings are based on proprietary advanced materials databases, executive interviews, and regulatory analysis, subject to internal peer review prior to publication.
Last Updated:
Speak to Analyst

Customize this report to your needs - add regions, segments, or data points, with 20% free customization.
Or view our licence options:


ISO 9001:2015 & 27001:2022 Certified
We are GDPR and CCPA compliant! Your transaction & personal information is safe and secure. For more details, please read our privacy policy.


