
- Home
- »
- Pharmaceuticals
- »
-
Allergy Immunotherapy Market Size, Share Report 2026-2033GVR Report cover
![Allergy Immunotherapy Market (2026 - 2033)Report]()
Allergy Immunotherapy Market (2026 - 2033)
Size, Share & Trends Analysis Report Product Type (Inhalant Allergen Immunotherapy, Venom Allergen Immunotherapy), By Route of Administration, By Indication, By Patient Group, By Distribution Channel, By Region, And Segment Forecasts
Market Size, 2025
$2.1BMarket Estimate, 2026
$2.3BMarket Forecast, 2033
$4.1BCAGR, 2026–2033
8.9%Allergy Immunotherapy Market Summary
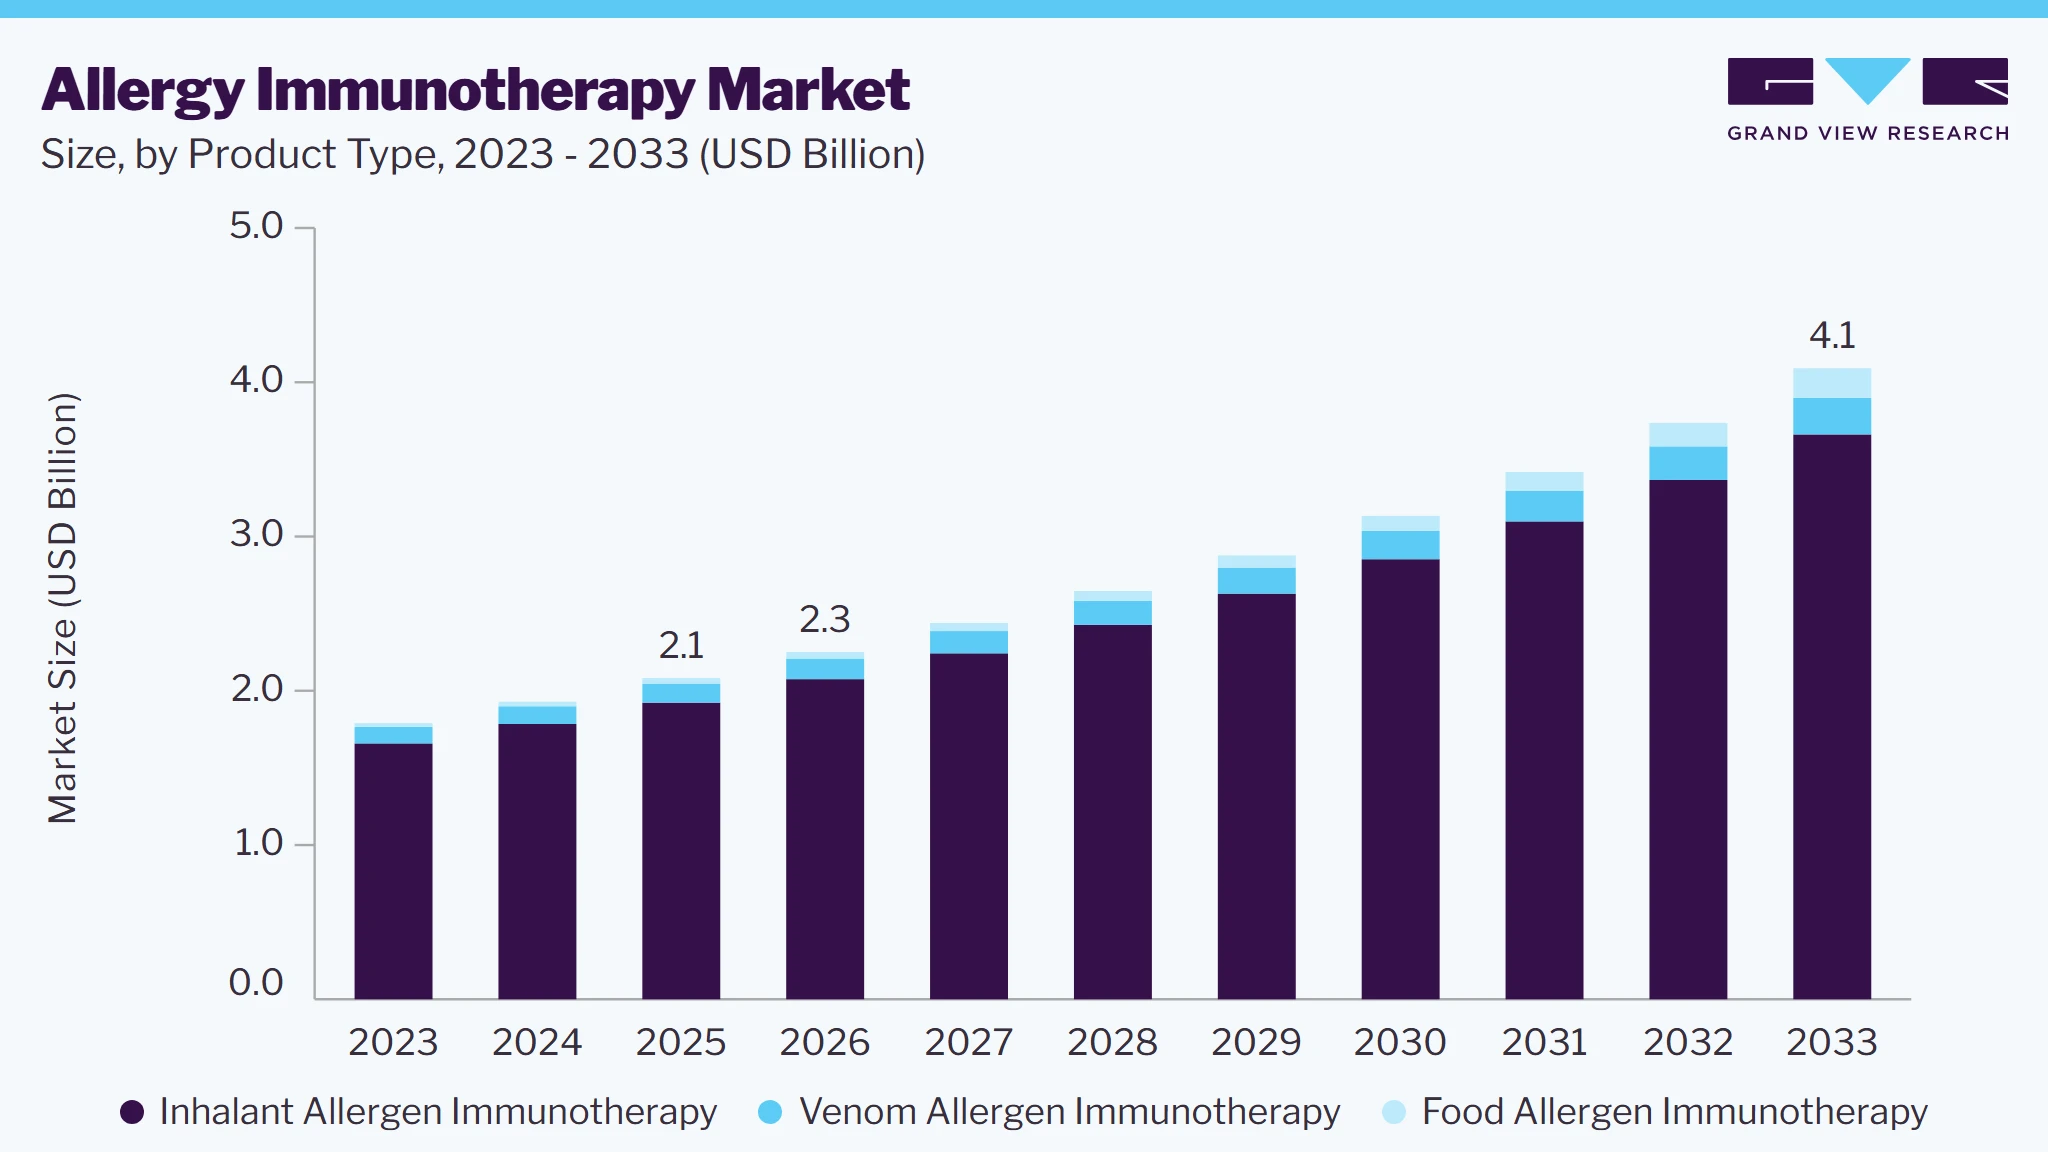
The global allergy immunotherapy market size was valued at USD 2.1 billion in 2025 and is projected to grow from USD 2.3 billion in 2026 to USD 4.1 billion by 2033, at a CAGR of 8.9% from 2026 to 2033. Europe dominated the market, accounting for the largest revenue share of 61.6% in 2025. The market is driven by the increasing prevalence of allergic diseases, improvements in allergy diagnosis, and growing adoption of allergen immunotherapy..

Key Market Trends & Insights
- By product type: Inhalant allergen immunotherapy held the largest revenue share of 92.4% in 2025
- By route of administration: Subcutaneous immunotherapy held the largest revenue share of 58.6% in 2025
- By indication: Allergic rhinitis held the largest revenue share of 72.8% in 2025
- By patient group: Adult segment held the largest revenue share of 69.8% in 2025
- By distribution channel: Hospital pharmacies held the largest revenue share of 48.6% in 2025
Regional Highlights
- Largest regional market: Europe (61.6% revenue share, 2025)
- Fastest-growing regional market: Asia Pacific (highest CAGR, 2026-2033)
- By country: Germany held the largest revenue share of Europe in 2025
Market Size & Forecast
- Market Size in 2025: USD 2.1 Billion
- Estimated Market Size in 2026: USD 2.3 Billion
- Projected Market Size by 2033: USD 4.1 Billion
- CAGR (2026-2033): 8.9%
Market Dynamics
The rising prevalence of allergic diseases is a key factor driving the growth of the allergy immunotherapy market. Increasing exposure to environmental allergens, urbanization, air pollution, changing climatic conditions, and lifestyle-related factors have contributed to a growing number of patients with allergic rhinitis, allergic asthma, food allergies, and insect venom allergies. This increasing disease burden has raised demand for specialist consultations, allergy diagnostics, and long-term treatment options that address the underlying immune response. Improvements in diagnostic methods, including skin prick testing and allergen-specific immunoglobulin E (IgE) testing, have enabled more accurate patient identification and appropriate selection for allergen immunotherapy, supporting wider clinical adoption. In addition, the expansion of specialist allergy services and the adoption of standardized clinical guidelines have encouraged healthcare providers to incorporate allergen immunotherapy into routine practice for eligible patients. Patients are increasingly seeking long-term disease-modifying therapies that reduce symptom recurrence and improve quality of life, further supporting treatment adoption. The growing patient population has also encouraged pharmaceutical companies to invest in allergy research, clinical development, and standardized immunotherapy products, while healthcare institutions continue to strengthen allergy care services. Together, these factors are expanding the eligible treatment population and supporting the continued market growth across developed and emerging healthcare systems.
The high cost of allergy immunotherapy is a key factor limiting market growth, as treatment requires long-term administration, specialist consultations, allergy diagnostic testing, regular follow-up visits, and continued use of immunotherapy products. Compared with symptomatic medications, the cumulative treatment cost can discourage patients from initiating or completing therapy, particularly in healthcare systems with high out-of-pocket expenses. In addition, reimbursement coverage for allergy immunotherapy varies across countries and is often subject to eligibility criteria, prior authorization requirements, or indication-specific restrictions, limiting patient access to treatment. The requirement for three to five years of therapy further affects long-term patient adherence, as regular clinic visits, ongoing treatment costs, and treatment commitment may reduce persistence. These factors can limit clinical outcomes and the overall utilization of allergen immunotherapy. Although reimbursement policies are gradually improving in some countries, differences in healthcare coverage continue to influence treatment accessibility. For instance, in July 2025, the Dutch National Health Care Institute recommended extending reimbursement for ALK's Acarizax to children aged 5-11 years with persistent house dust mite-induced allergic rhinitis, and the recommendation was implemented by the Ministry of Health, Welfare and Sport in August 2025, expanding reimbursement eligibility for pediatric patients.
Next-generation immunotherapy technologies are creating opportunities for the growth of the allergy immunotherapy market by improving treatment safety, effectiveness, and patient convenience. Manufacturers are investing in recombinant allergens, modified allergen extracts, peptide-based immunotherapy, and advanced adjuvant technologies to provide more targeted immune responses, reduce treatment-related reactions, improve dosing consistency, and shorten treatment duration. These advancements are expected to expand treatment options for patients with respiratory, food, and venom allergies while supporting more individualized therapy. Ongoing clinical research and collaboration among pharmaceutical companies, academic institutions, and healthcare organizations are generating evidence to support the development and regulatory approval of these technologies. Continued investment in innovative immunotherapy platforms is also strengthening product pipelines and creating opportunities for future product launches. For instance, in February 2025, Allergy Therapeutics reported positive Phase III results for Grass MATA MPL, a short-course grass pollen immunotherapy candidate that combines modified allergoids with the MPL adjuvant platform. The study demonstrated clinically meaningful symptom reduction using a six-injection treatment regimen, supporting the development of next-generation allergen immunotherapy technologies.
Market Concentration & Characteristics
The allergy immunotherapy market demonstrates a high degree of innovation, driven by biologic-assisted immunotherapy, precision diagnostics, and novel desensitization approaches. Companies are focusing on improving treatment efficacy, reducing adverse events, and expanding treatment for patients with multiple allergies. For instance, in March 2025, Roche announced positive Phase III OUtMATCH study results demonstrating that Xolair (omalizumab) achieved better treatment success with fewer adverse events than multi-allergen oral immunotherapy in patients with food allergies, reinforcing innovation in biologic-supported allergy immunotherapy.
The allergy immunotherapy market exhibits a medium level of M&A activity, with companies preferring strategic collaborations, licensing agreements, and portfolio expansion over large-scale acquisitions. These partnerships help strengthen product portfolios, expand geographic reach, and accelerate the commercialization of allergy therapies.
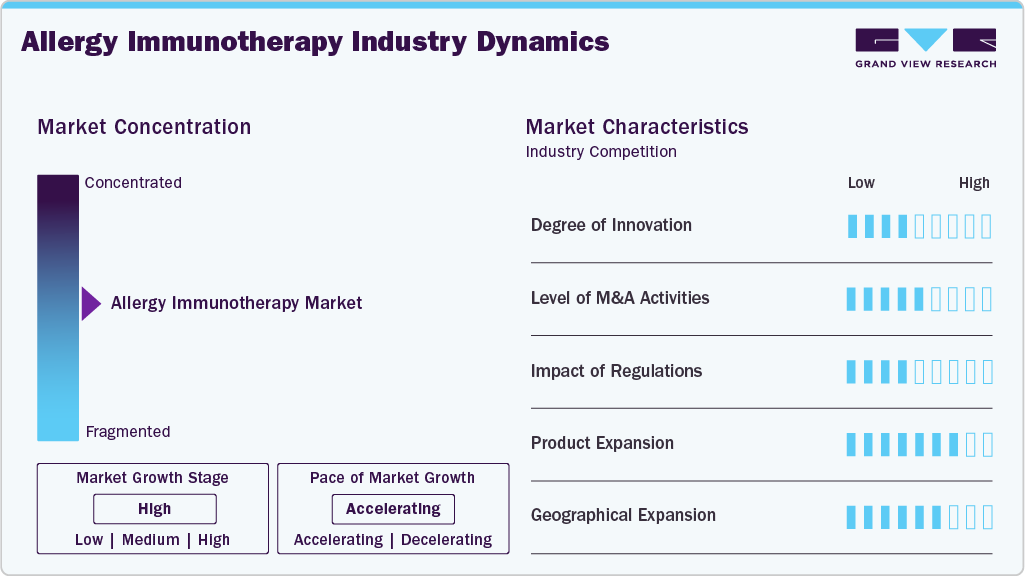
Regulatory agencies play a significant role in shaping the allergy immunotherapy industry by requiring comprehensive evidence for safety, efficacy, and manufacturing quality. These standards improve product reliability while increasing development timelines. For instance, in March 2025, the U.S. FDA approved Celltrion's OMLYCLO (omalizumab-igec) as the first interchangeable biosimilar to Xolair for allergic asthma, chronic rhinosinusitis with nasal polyps, IgE-mediated food allergy, and chronic spontaneous urticaria, expanding treatment access while maintaining stringent regulatory standards.
Product expansion remains high as manufacturers broaden allergy treatment portfolios beyond traditional allergen immunotherapy through biologics, biosimilars, and therapies targeting multiple allergic conditions. Companies are also expanding patient access through additional formulations and indications.
Regional expansion is medium to high, supported by increasing commercialization activities across Europe and other international markets, as well as rising allergy diagnosis rates and healthcare investment. Companies are strengthening distribution networks to improve patient access.
Analyst Perspective
The allergy immunotherapy market is shifting from symptom relief to disease-modifying treatments, driven by the rising prevalence of allergic diseases and improved diagnosis. Growth is supported by expanding allergen immunotherapy portfolios, increased adoption of sublingual therapies, and advancements in food allergy treatments. Regulatory approvals, pediatric label expansions, and stronger clinical evidence are enhancing physician confidence and patient access. Emerging markets are improving allergy diagnostics and specialist care, while industry collaborations continue to accelerate product development. These factors are expected to support steady market growth throughout the forecast period.
Product Type Insights
The inhalant allergen immunotherapy segment dominated the market with the largest share of 92.4% in 2025, driven by the high prevalence of respiratory allergic diseases, including allergic rhinitis and allergic asthma, associated with allergens such as house dust mites, grass pollen, tree pollen, and ragweed. The segment benefits from the widespread availability of both subcutaneous and sublingual immunotherapy products that have demonstrated long-term clinical efficacy and disease-modifying benefits. Strong recommendations from international allergy management guidelines and increasing physician confidence have supported the adoption of these therapies in routine clinical practice. Growing awareness of early diagnosis and the need for long-term management of allergic diseases has further increased treatment utilization. For instance, in February 2025, ALK received U.S. FDA approval to expand the indication of ODACTRA to children aged 5-11 years with house dust mite-induced allergic rhinitis, broadening the eligible patient population and supporting continued growth of the inhalant allergen immunotherapy.
The food allergen immunotherapy segment is projected to grow at the fastest CAGR of 23.9% during the forecast period, driven by the rising global prevalence of food allergies, particularly among children and adolescents. Increasing cases of peanut, milk, egg, tree nut, and shellfish allergies have created a significant unmet need for long-term disease-modifying treatments beyond strict allergen avoidance. Continuous advancements in oral immunotherapy (OIT) and epicutaneous immunotherapy (EPIT), along with the integration of biologic therapies such as anti-IgE antibodies to improve treatment safety and efficacy, are expanding the clinical adoption of food allergen immunotherapy. Additionally, a growing number of late-stage clinical trials, increasing regulatory support for innovative therapies, and rising awareness among healthcare professionals and caregivers are accelerating market growth. Improved diagnosis rates, expanding pediatric allergy care infrastructure, and favorable reimbursement initiatives in developed markets are further expected to support the rapid expansion of this segment through 2033.
Route of Administration Insights
The subcutaneous immunotherapy (SCIT) segment dominated the allergy immunotherapy industry with the largest share of 58.6% in 2025, supported by its established clinical efficacy in treating allergic rhinitis, allergic asthma, and venom allergies. SCIT remains the preferred immunotherapy approach for many patients because it provides long-term disease modification by addressing the underlying allergic response rather than only controlling symptoms. Its broad allergen coverage enables treatment for multiple inhalant allergens, making it particularly suitable for polysensitized patients. Well-established treatment protocols, extensive clinical evidence, and decades of physician experience have contributed to its widespread adoption in allergy clinics and hospitals. In addition, strong recommendations from international allergy management guidelines continue to reinforce its use as a standard treatment option for eligible patients. Increasing diagnosis of allergic diseases, expanding access to specialist allergy services, and growing awareness of disease-modifying therapies continue to support the sustained growth of the SCIT segment.
The sublingual immunotherapy (SLIT) segment is projected to grow at the fastest CAGR of 10.3% during the forecast period, driven by the growing preference for convenient, non-invasive allergy treatments that can be self-administered at home. Unlike subcutaneous immunotherapy (SCIT), SLIT eliminates the need for frequent clinic visits and injections, improving patient comfort, treatment adherence, and long-term compliance. Increasing adoption among pediatric and adult patients, coupled with favorable safety profiles and a lower risk of systemic allergic reactions, is further supporting market growth. Expanding regulatory approvals and product launches are also strengthening the segment's outlook. For instance, in May 2025, Health Canada approved ALK's ITULATEK for children and adolescents aged 5-17 years with seasonal allergic rhinitis, broadening access to pediatric SLIT.
Indication Insights
The allergic rhinitis segment dominated the allergy immunotherapy market with the largest share of 72.8% in 2025, driven by the high global prevalence of the condition and the established role of allergen immunotherapy as the only disease-modifying treatment capable of providing sustained symptom relief while reducing disease progression. Widespread availability of subcutaneous and sublingual immunotherapy products targeting pollen and house dust mite allergies has supported strong clinical adoption across major healthcare markets. Long-term clinical evidence, favorable treatment outcomes, and recommendations from international allergy management guidelines have further strengthened physician confidence in prescribing allergen immunotherapy for allergic rhinitis. Increasing awareness of early diagnosis and long-term disease management has also contributed to higher treatment uptake. For instance, in January 2025, the UK's National Institute for Health and Care Excellence (NICE) recommended ALK's ACARIZAX for persistent moderate-to-severe house dust mite allergic rhinitis in adults and adolescents, expanding access to sublingual allergen immunotherapy through routine NHS use.
The food allergy segment is projected to grow at the fastest CAGR of 22.8% during the forecast period, driven by the increasing prevalence of food allergies worldwide and the growing need for long-term disease-modifying therapies. Rising cases of peanut, milk, egg, tree nut, and shellfish allergies, particularly among children, are increasing demand for treatments that provide sustained immune tolerance rather than temporary symptom relief. Significant advancements in oral immunotherapy (OIT) and epicutaneous immunotherapy (EPIT), combined with ongoing clinical research into safer and more effective treatment approaches, are expanding the therapeutic landscape. Growing investment by pharmaceutical and biotechnology companies, increasing regulatory support, and a robust pipeline of innovative therapies are further accelerating market growth.
Patient Group Insights
The adult segment dominated the market with the largest share of 69.8% in 2025, driven by the high prevalence of allergic rhinitis and allergic asthma, higher diagnosis rates, and greater utilization of allergen immunotherapy in specialty allergy clinics. Adults are more likely to complete the recommended long-term treatment course, supporting sustained demand for both subcutaneous and sublingual immunotherapy. Increasing awareness of disease-modifying therapies, improved access to allergy specialists, and established clinical guidelines have further strengthened treatment adoption among the adult population. The availability of multiple immunotherapy options and long-term clinical evidence demonstrating sustained symptom control have encouraged physicians to recommend allergen immunotherapy for eligible patients. In addition, expanding allergy diagnostic services and increasing patient awareness regarding the long-term benefits of immunotherapy continue to support treatment uptake, reinforcing the adult segment's leading position in the market.
The pediatric segment of the allergy immunotherapy industry is projected to grow at the fastest CAGR of 9.8% during the forecast period, supported by the rising prevalence of allergic diseases among children and increasing emphasis on early intervention. Expanding pediatric approvals, broader age-label indications, and growing availability of child-specific immunotherapy products are improving access and supporting wider adoption among younger patients.
Distribution Channel Insights
The hospital pharmacies segment dominated the market with the largest share of 48.6% in 2025, driven by the administration requirements of allergen immunotherapy, particularly subcutaneous immunotherapy (SCIT), which requires physician supervision, post-injection patient monitoring, and immediate access to emergency care for potential systemic allergic reactions. Hospital and specialty clinic pharmacies play an important role in the appropriate storage, preparation, and dispensing of allergen extracts while ensuring compliance with established treatment protocols. Their integration with allergy specialists enables coordinated patient management, regular follow-up, and monitoring throughout the treatment course, improving long-term adherence and clinical outcomes. In addition, the increasing number of specialized allergy centers, expanding availability of immunotherapy services in hospitals, and growing patient preference for supervised treatment have reinforced the position of hospital pharmacies as the primary distribution channel for allergen immunotherapy products across major healthcare markets.
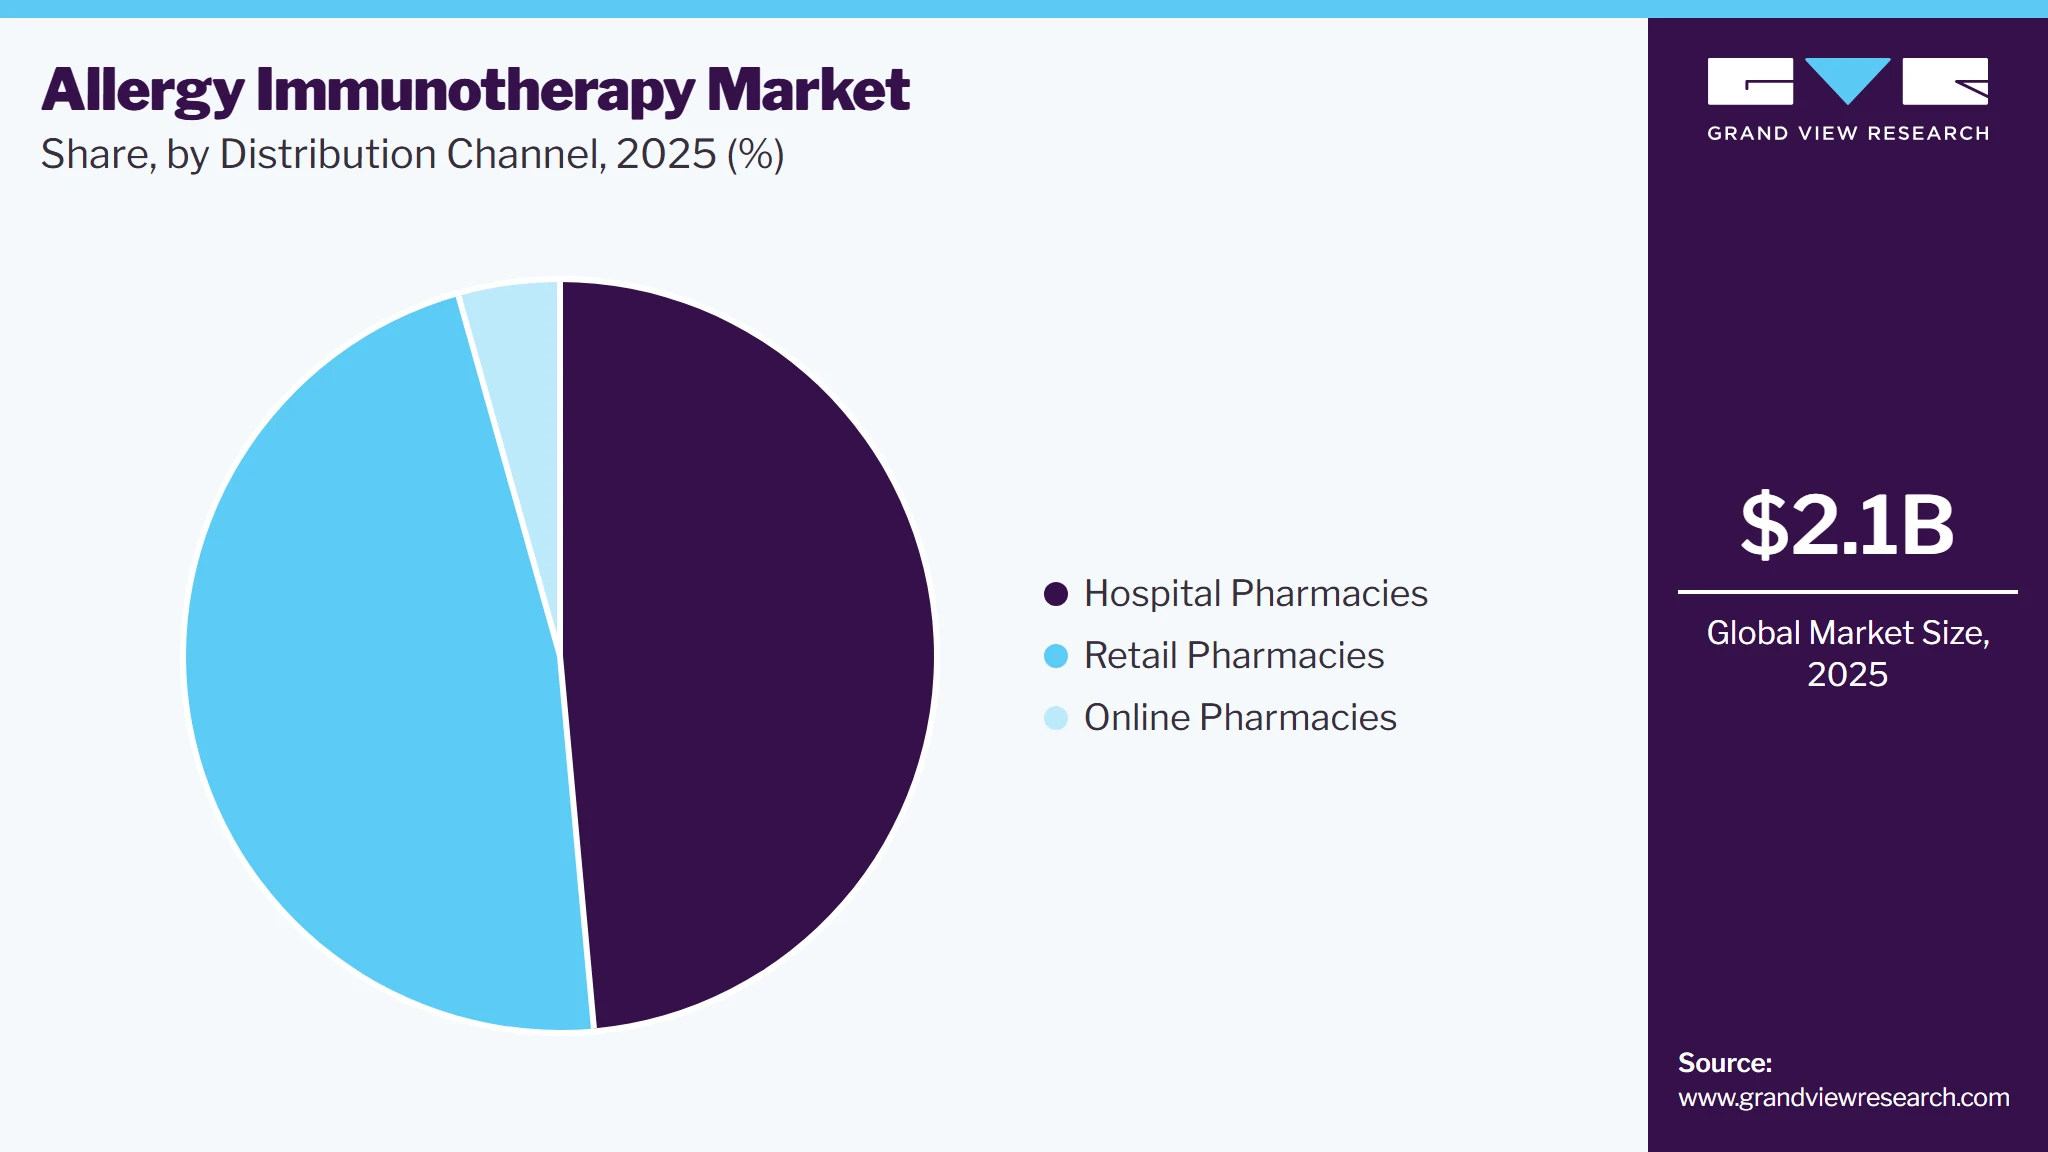
The online pharmacies segment is projected to grow at the fastest CAGR of 11.4% during the forecast period, driven by the rapid expansion of digital healthcare platforms and increasing consumer preference for convenient medicine purchasing. Growing adoption of self-administered sublingual immunotherapy (SLIT) enables patients to refill prescriptions online without frequent hospital visits, supporting the shift toward e-pharmacy services. The integration of digital prescription management, telemedicine consultations, automated refill systems, and home delivery services is improving treatment continuity and patient adherence, particularly for individuals requiring long-term allergy management. Expanding specialty pharmacy networks are also enhancing access to temperature-controlled biologics and personalized patient support programs.
Regional Insights
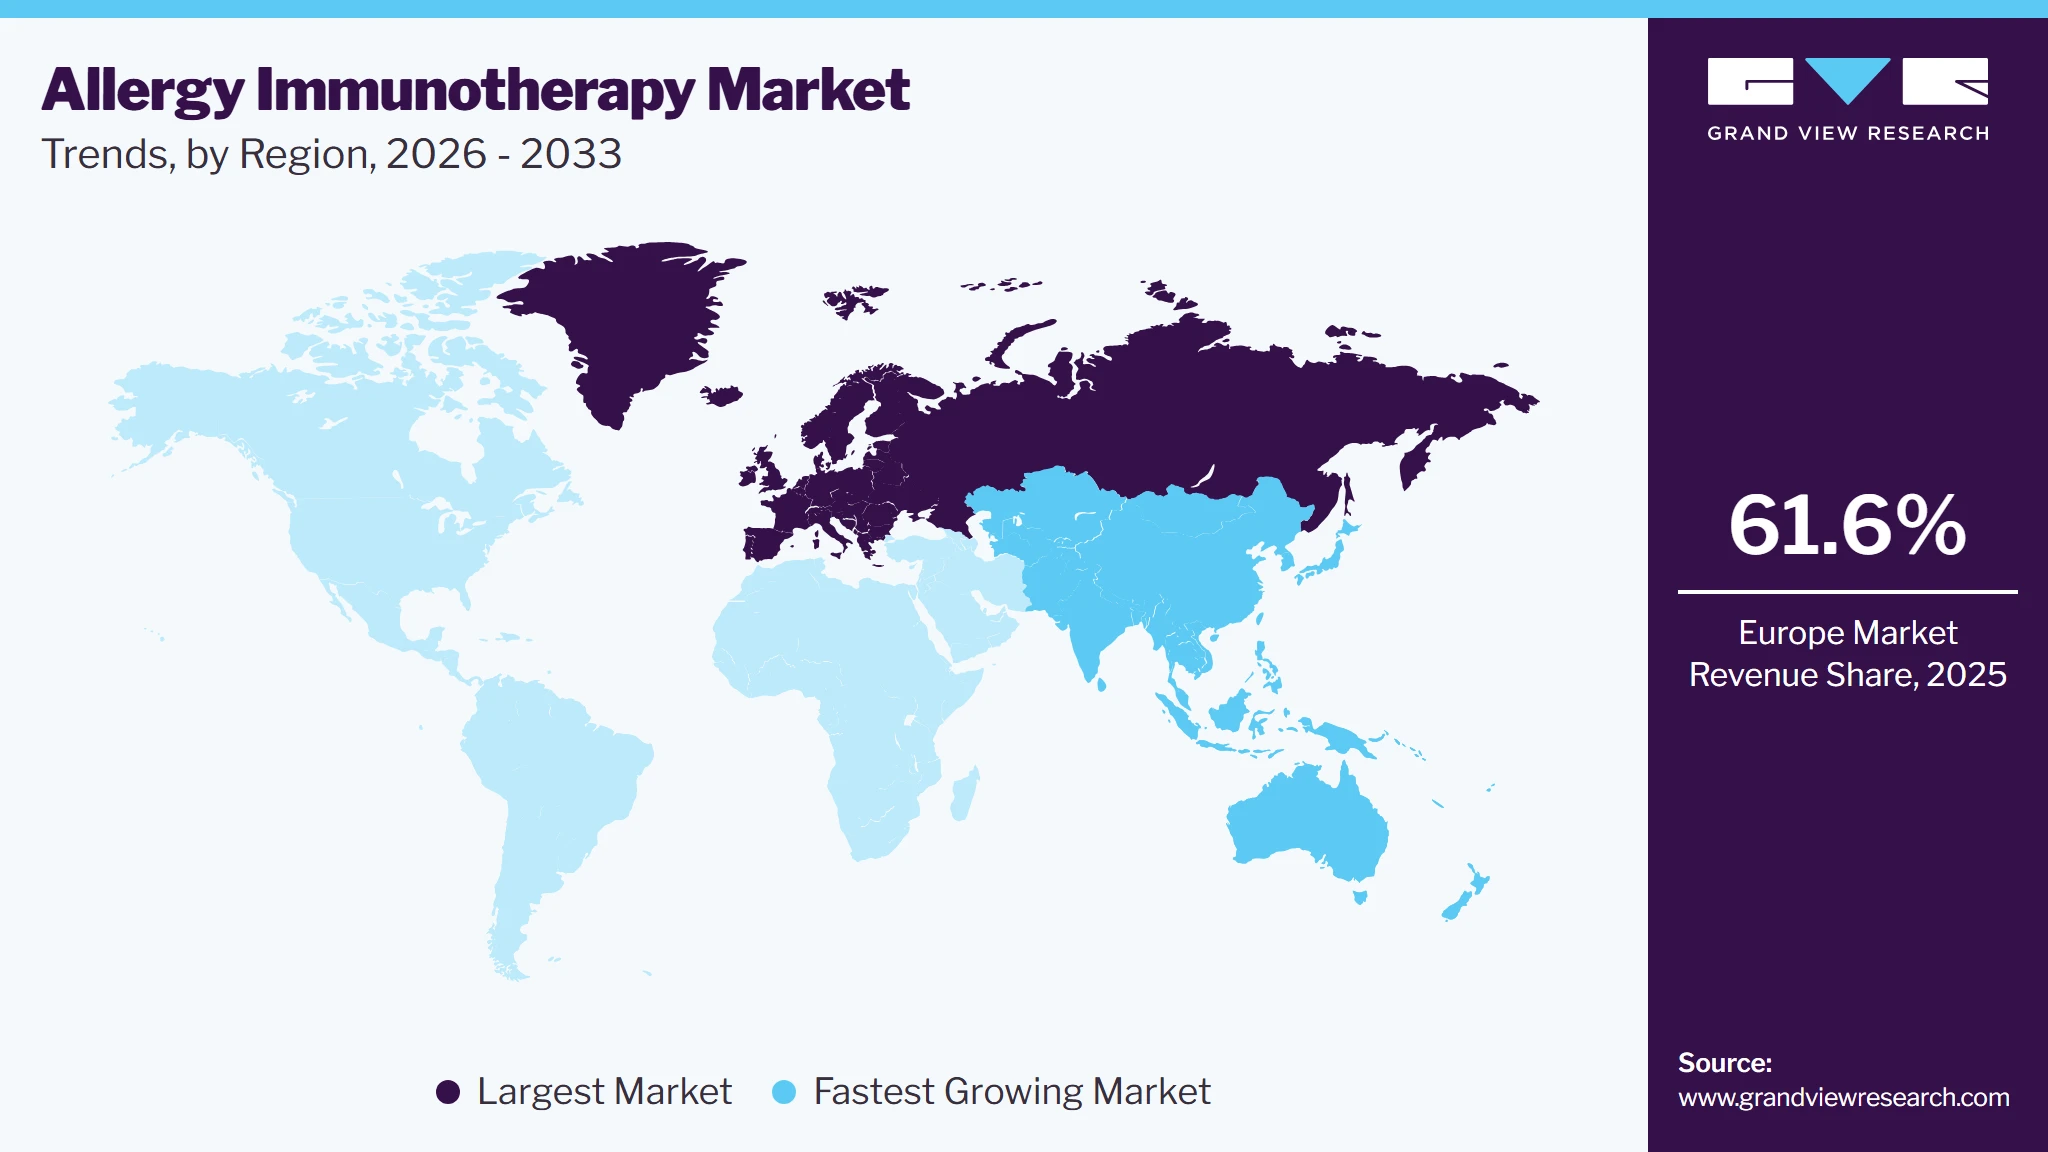
The Europe allergy immunotherapy market accounted for the largest revenue share of 61.6% in 2025. The market is driven by the increasing adoption of allergen immunotherapy as a long-term treatment for allergic diseases and the growing emphasis on disease-modifying therapies. Market growth is supported by the presence of manufacturers investing in product development, manufacturing capabilities, and clinical research, improving the availability of immunotherapy products across the region. The increasing adoption of standardized, evidence-based clinical guidelines has increased physician confidence and expanded the use of allergen immunotherapy among eligible patients. In addition, the growing number of specialized allergy treatment centers and continued collaboration among research institutes, healthcare providers, and pharmaceutical companies are advancing innovation, improving patient access, and supporting the continued market growth.
UK Allergy Immunotherapy Market Trends
The UK allergy immunotherapy market is driven by the increasing demand for long-term disease-modifying therapies that reduce dependence on symptomatic medications for allergic conditions. Market growth is supported by the expansion of allergy care services, improved patient referral pathways, and increasing access to dedicated allergy clinics, enabling earlier diagnosis and treatment. The growing adoption of evidence-based clinical guidelines has increased physician confidence and supported the integration of allergen immunotherapy into routine clinical practice. In addition, advancements in allergy diagnostics, the availability of standardized immunotherapy products, and continued investment in allergy research have expanded treatment options and supported the continued market growth.
The allergy immunotherapy market in Germany is driven by the increasing use of allergen immunotherapy in routine clinical practice for the long-term management of allergic diseases. Market growth is supported by the country's network of allergy specialists, university hospitals, and dedicated allergy centers, improving patient access to diagnosis and treatment. Continued investment by pharmaceutical companies in allergen immunotherapy products, clinical research, and product development has expanded treatment availability. In addition, collaboration among healthcare providers, research institutions, and industry participants, together with advances in allergy diagnostics and physician education, has supported appropriate patient selection and the continued adoption of allergy immunotherapy across Germany.
North America Allergy Immunotherapy Market Trends
The North America allergy immunotherapy industry is driven by the increasing prevalence of allergic rhinitis, allergic asthma, food allergies, and insect venom allergies, creating sustained demand for therapies that provide long-term disease modification. Growth is supported by the region's advanced healthcare infrastructure, well-established allergy care network, specialized clinics, and standardized diagnostic services that enable early diagnosis and appropriate treatment. Continuous advancements in allergy research, standardized allergen-extract manufacturing, and optimized treatment protocols have strengthened physicians' confidence and expanded clinical adoption. In addition, increasing environmental exposure to seasonal and perennial allergens, prolonged pollen seasons, and growing awareness of the long-term benefits of allergen immunotherapy continue to support market growth across North America.
The U.S. allergy immunotherapy industry is driven by the increasing prevalence of allergic rhinitis, allergic asthma, food allergies, and other allergic conditions, creating sustained demand for long-term disease-modifying therapies. Environmental changes, urbanization, and prolonged exposure to indoor and outdoor allergens continue to increase the number of patients requiring specialist allergy care. Market growth is further supported by improvements in allergy diagnosis, standardized patient assessment, and the wider use of allergen-specific testing, enabling earlier identification of eligible patients for immunotherapy. The continued expansion of commercially available immunotherapy products, supported by regulatory approvals, lifecycle management strategies, and ongoing clinical research, has strengthened physician confidence and broadened treatment options. In addition, the country's well-established allergy care infrastructure, extensive network of allergy specialists and clinics, and improved referral pathways between primary care physicians and specialists continue to enhance patient access, supporting the sustained market growth.
Asia Pacific Allergy Immunotherapy Market Trends
The Asia Pacific allergy immunotherapy industry is projected to grow at a CAGR of 10.9% over the forecast period. The market is driven by the increasing availability of allergen immunotherapy products through multinational and domestic manufacturers, improving access to standardized treatment options across the region. Market growth is driven by the increasing use of allergen-specific diagnostic testing, which enables appropriate patient selection and treatment planning. Continued investment by regional pharmaceutical companies in allergy research, product development, and clinical studies has expanded treatment availability. In addition, improvements in specialist allergy services, increasing adoption of allergen immunotherapy in clinical practice, and the large population of untreated patients continue to support the market growth.
The Japan allergy immunotherapy market is driven by the increasing prevalence of seasonal and environmental allergies, creating demand for long-term disease-modifying therapies. Market growth is supported by the increasing use of allergy immunotherapy in routine clinical practice and the growing focus on long-term disease management. Continued investment by pharmaceutical companies in product development and improved treatment formulations has expanded the availability of allergy immunotherapy products. In addition, increasing patient awareness of long-term allergy management, improved access to allergy care services, and ongoing investment in allergy research continue to support the adoption of allergy immunotherapy and the growth of the market in Japan.
The allergy immunotherapy market in China is driven by the rising prevalence of allergic diseases linked to urbanization, environmental changes, and exposure to airborne pollutants, thereby creating demand for long-term disease-modifying therapies. Market growth is supported by improvements in healthcare infrastructure, the expansion of allergy diagnostic services, and increased access to specialist care across the country. Continued investment by domestic pharmaceutical companies in allergy therapeutics, manufacturing, and clinical research has improved product availability. In addition, rising healthcare expenditure, increasing awareness of long-term allergy management, and ongoing healthcare reforms continue to support the adoption of allergy immunotherapy and the growth of the market in China.
Latin America Allergy Immunotherapy Market Trends
The Latin America allergy immunotherapy industry is driven by the increasing prevalence of allergic diseases associated with environmental changes, urbanization, and exposure to airborne allergens, creating demand for long-term disease-modifying therapies. Market growth is supported by the increasing adoption of standardized allergy management practices and allergen-specific diagnostic testing, enabling appropriate patient selection for immunotherapy. Continued commercial expansion by multinational and domestic pharmaceutical companies has improved the availability of standardized immunotherapy products across the region. In addition, the expansion of specialist allergy services, increasing referrals to allergy specialists, and improved access to allergy diagnosis continue to support the adoption of allergy immunotherapy across Latin America.
The Brazil allergy immunotherapy market is driven by the increasing prevalence of environmental allergies associated with year-round exposure to airborne allergens, creating demand for long-term disease-modifying therapies. Market growth is supported by the increasing adoption of allergy immunotherapy in specialist clinical practice and the use of standardized treatment protocols for appropriately diagnosed patients. Continued expansion of pharmaceutical companies has improved the availability and distribution of standardized allergen immunotherapy products across the country. In addition, expanding access to specialist consultations, allergy diagnostics, and immunotherapy services through the private healthcare sector continues to support the adoption of allergy immunotherapy and market growth in Brazil.
MEA Allergy Immunotherapy Market Trends
The Middle East & Africa allergy immunotherapy industry is driven by the rising prevalence of allergic diseases linked to environmental changes, increased exposure to airborne allergens, and urbanization, thereby creating demand for long-term disease-modifying therapies. Market growth is supported by the expansion of allergy and clinical immunology services, improving access to specialist consultations, allergy diagnostics, and immunotherapy treatment. Continued participation by multinational pharmaceutical companies through product registrations and distribution agreements has improved the availability of standardized allergen immunotherapy products. In addition, the increasing adoption of standardized allergy management practices and appropriate patient selection continues to support the use of allergy immunotherapy across the Middle East & Africa.
Key Allergy Immunotherapy Company Insights
The allergy immunotherapy market is characterized by the presence of established manufacturers with broad allergen immunotherapy portfolios, and companies focused on developing therapies for food allergies and new treatment platforms. Key participants, including ALK-Abelló, Stallergenes Greer, Allergy Therapeutics, HAL Allergy, LETI Pharma, Allergopharma, Immunotek, Torii Pharmaceutical Co., Ltd., HollisterStier Allergy (Jubilant HollisterStier LLC), Diater, Roxall, Probelte, and Lofarma, compete through product portfolio expansion, clinical research, manufacturing capacity, regulatory approvals, and geographic expansion. Aimmune Therapeutics and DBV Technologies continue to focus on food allergy immunotherapy by advancing oral and epicutaneous treatment approaches. Companies are also investing in standardized allergen extracts, subcutaneous and sublingual immunotherapy products, lifecycle management, and clinical studies to support product adoption. Strategic collaborations, licensing agreements, and investments in new allergen formulations continue to shape competition and support the development of the allergy immunotherapy industry.
Key Allergy Immunotherapy Companies
The following key companies have been profiled for this study of the allergy immunotherapy market.
-
ALK-Abello
-
Stallergenes Greer
-
Allergy Therapeutics
-
HAL Allergy.
-
Leti Pharma
-
Aimmune Therapeutics.
-
DBV Technologies
-
HollisterStier Allergy (Jubilant HollisterStier LLC)
-
Immunotek
-
Allergopharma.
-
Diater
-
Roxall
-
Probelte
-
Lofarma
Competitive Benchmarking
Operating Strategies
Competitive Edge
Weaknesses
Mature Players: ALK-Abelló
- Focus on expanding approved SCIT and SLIT portfolios, strengthening manufacturing capacity, increasing geographic presence, generating long-term clinical evidence, and pursuing regulatory approvals for new indications.
- Mature companies also invest in digital patient support, supply chain optimization, and strategic commercial partnerships to reinforce market leadership.
- Benefit from extensive commercial infrastructure, broad product portfolios, established manufacturing capabilities, strong physician relationships, proven regulatory expertise, and global distribution networks.
- Their long-standing market presence supports high customer confidence, broad reimbursement coverage, and sustained competitive positioning.
- Face higher operating costs, complex manufacturing processes, and stringent regulatory compliance requirements across global markets.
- Maintaining sustained growth also requires continuous investment in innovation, manufacturing expansion, and product differentiation within an increasingly competitive allergy immunotherapy market.
Emerging Players: Allergy Therapeutics
- Concentrate on developing next-generation allergy immunotherapies, including novel allergen formulations, epicutaneous and oral immunotherapy platforms, and personalized treatment approaches.
- Their strategies emphasize clinical trials, pipeline expansion, scientific collaborations, regional market entry, and licensing agreements to accelerate commercialization.
- Possess greater flexibility in innovation, enabling rapid development of novel immunotherapy platforms and differentiated treatment approaches.
- Their focused R&D strategies, specialized clinical programs, and collaborative partnerships allow them to address unmet needs and emerging allergy indications efficiently.
- Operate with smaller commercial footprints, limited manufacturing scale, narrower geographic reach, and fewer marketed products.
- Dependence on successful clinical outcomes, regulatory approvals, external funding, and commercialization partnerships may delay broader market adoption and revenue growth.
Recent Developments
-
In June 2026, DBV Technologies announced the screening of the first participant in the THRIVE Phase II study evaluating the VIASKIN Peanut Patch in infants aged 6 to 12 months. The study advances the clinical development of epicutaneous immunotherapy for peanut allergy and supports the expansion of treatment options for pediatric patients.
-
In January 2026, Stallergenes Greer announced an agreement to acquire ENTOMON S.R.L., an Italian manufacturer of certified Hymenoptera venom extracts used for venom immunotherapy (VIT) and allergy diagnostics. The acquisition expands the company's manufacturing capabilities and strengthens its venom immunotherapy portfolio.
-
In May 2025, ALK-Abelló entered into a four-year U.S. co-promotion agreement with ARS Pharmaceuticals for neffy, an epinephrine nasal spray for the emergency treatment of Type I allergic reactions, including anaphylaxis. The agreement strengthens ALK-Abelló's allergy specialist commercial network in the U.S. and expands its allergy care portfolio alongside its established allergy immunotherapy business.
Allergy Immunotherapy Market Report Scope
Report Attribute
Details
Market size value in 2025
USD 2.1 billion
Market size value in 2026
USD 2.3 billion
Revenue forecast in 2033
USD 4.1 billion
Growth rate
CAGR of 8.9% from 2026 to 2033
Base year for estimation
2025
Historical data
2021 - 2024
Forecast period
2026 - 2033
Quantitative units
Revenue in USD million/billion and CAGR from 2026 to 2033
Report coverage
Revenue forecast, company ranking, competitive landscape, growth factors, and trends
Segments covered
Product type, route of administration, indication, patient group, distribution channel, region
Regional scope
North America; Europe; Asia Pacific; Latin America; MEA
Country scope
U.S.; Canada; Mexico; Germany; UK; France; Italy; Spain; Denmark; Sweden; Norway; China; Japan; India; Australia; Thailand; South Korea; Brazil; Argentina; South Africa; Saudi Arabia; UAE; Kuwait
Key companies profiled
ALK-Abello; Stallergenes Greer; Allergy Therapeutics; HAL Allergy.; Leti Pharma; Aimmune Therapeutics.; DBV Technologies; HollisterStier Allergy (Jubilant HollisterStier LLC); Immunotek; Allergopharma.; Diater; Roxall; Probelte; Lofarma
Customization scope
Free report customization (equivalent up to 8 analyst’s working days) with purchase. Addition or alteration to country, regional & segment scope.
Pricing and purchase options
Avail customized purchase options to meet your exact research needs. Explore purchase options
Global Allergy Immunotherapy Market Report Segmentation
This report forecasts revenue growth at the global, regional, and country levels and provides an analysis of the latest industry trends in each of the sub-segments from 2021 to 2033. For this study, Grand View Research has segmented the global allergy immunotherapy market report based on product type, route of administration, indication, patient group, distribution channel, and region:
-
Product Type Outlook (Revenue, USD Million/Billion, 2021 - 2033)
-
Inhalant Allergen Immunotherapy
-
Grass Pollen Immunotherapy
-
Tree Pollen Immunotherapy
-
Weed Pollen Immunotherapy
-
House Dust Mite Immunotherapy
-
Animal Dander Immunotherapy
-
Mold (Fungal) Immunotherapy
-
-
Venom Allergen Immunotherapy
-
Bee Venom Immunotherapy
-
Wasp Venom Immunotherapy
-
Ant Venom Immunotherapy
-
-
Food Allergen Immunotherapy
-
Peanut Allergy Immunotherapy
-
Milk Allergy Immunotherapy
-
Egg Allergy Immunotherapy
-
Others
-
-
-
Route of Administration Outlook (Revenue, USD Million/Billion, 2021 - 2033)
-
Subcutaneous Immunotherapy (SCIT)
-
Sublingual Immunotherapy (SLIT)
-
-
Indication Outlook (Revenue, USD Million/Billion, 2021 - 2033)
-
Allergic Rhinitis
-
Allergic Asthma
-
Insect Sting Allergy
-
Food Allergy
-
Atopic Dermatitis
-
-
Patient Group Outlook (Revenue, USD Million/Billion, 2021 - 2033)
-
Pediatric
-
Adult
-
-
Distribution Channel Outlook (Revenue, USD Million/Billion, 2021 - 2033)
-
Hospital Pharmacies
-
Retail Pharmacies
-
Online Pharmacies
-
-
Regional Outlook (Revenue, USD Million/Billion, 2021 - 2033)
-
North America
-
U.S.
-
Canada
-
Mexico
-
-
Europe
-
Germany
-
UK
-
France
-
Italy
-
Spain
-
Denmark
-
Sweden
-
Norway
-
-
Asia Pacific
-
Japan
-
China
-
India
-
Australia
-
South Korea
-
Thailand
-
-
Latin America
-
Brazil
-
Argentina
-
-
Middle East and Africa (MEA)
-
South Africa
-
Saudi Arabia
-
UAE
-
Kuwait
-
-
Research Methodology
The allergy immunotherapy market figures in this report are based on a proven research process that combines executive interviews with secondary research from proprietary databases, company filings, and recognized regulatory and institutional sources. Market size is built through value-chain sizing—reconciling supply-side and demand-side estimates—and triangulated with bottom-up and top-down approaches. Every estimate passes multiple levels of expert validation before publication, with each allergy immunotherapy segment quantified using the revenue-capture definitions in the table below.
Segment definition
Segment - Product Type
Revenue capture definition
Inhalant Allergen Immunotherapy
Comprises allergen immunotherapy products developed for the treatment of allergies caused by airborne allergens, including pollens, house dust mites, animal dander, and molds, using standardized allergen extracts to induce long-term immune tolerance and reduce allergic responses.
Venom Allergen Immunotherapy
Comprises allergen immunotherapy products formulated from purified insect venom extracts for individuals with hypersensitivity to bee, wasp, ant, and other venomous insect stings, providing long-term protection against systemic allergic reactions following subsequent stings.
Food Allergen Immunotherapy
Comprises allergen immunotherapy products intended to desensitize individuals with clinically confirmed food allergies through controlled exposure to specific food allergens, improving immune tolerance and reducing the severity of allergic reactions following accidental allergen exposure.
Segment - Route of Administration
Revenue capture definition
Subcutaneous Immunotherapy (SCIT)
Comprises allergen immunotherapy products administered through subcutaneous injections under healthcare professional supervision using scheduled build-up and maintenance regimens to achieve long-term immune tolerance against specific allergens.
Sublingual Immunotherapy (SLIT)
Comprises allergen immunotherapy products administered beneath the tongue as tablets or liquid drops, allowing allergen absorption through the oral mucosa for long-term desensitization against clinically relevant allergens.
Segment - Indication
Revenue capture definition
Allergic Rhinitis
Comprises allergen immunotherapy products prescribed for patients with clinically confirmed allergic rhinitis caused by seasonal or perennial allergens to reduce symptoms and modify the underlying allergic immune response over time.
Allergic Asthma
Comprises allergen immunotherapy products indicated for patients with allergen-induced asthma and confirmed allergen sensitization, supporting long-term management by reducing immune-mediated respiratory responses associated with allergen exposure.
Insect Sting Allergy
Comprises allergen immunotherapy products indicated for individuals with hypersensitivity to insect venom, reducing the risk of systemic allergic reactions following future stings through allergen-specific immune desensitization.
Food Allergy
Comprises allergen immunotherapy products indicated for patients with clinically confirmed food allergies requiring allergen-specific treatment to improve immune tolerance and reduce allergic reactions associated with accidental food allergen exposure.
Atopic Dermatitis
Comprises allergen immunotherapy products used in selected patients with atopic dermatitis associated with clinically confirmed allergen sensitization, where allergen-specific treatment forms part of an individualized allergy management strategy.
Segment - Patient Group
Revenue capture definition
Pediatric
Comprises allergen immunotherapy products administered to patients younger than 18 years who meet approved clinical criteria for allergen-specific treatment based on physician evaluation and confirmed allergen sensitization.
Adult
Comprises allergen immunotherapy products administered to individuals aged 18 years and above for the long-term management of allergic diseases requiring allergen-specific immune desensitization according to approved clinical recommendations.
Distribution Channel
Revenue capture definition
Hospital Pharmacies
Comprises allergen immunotherapy products supplied through hospital pharmacies for administration or dispensing within hospital-based healthcare facilities, supporting treatment initiation, maintenance therapy, and specialist allergy care services.
Retail Pharmacies
Comprises allergen immunotherapy products dispensed through community and chain retail pharmacies to patients with valid prescriptions, supporting continued access to maintenance therapy outside hospital-based healthcare facilities.
Online Pharmacies
Comprises allergen immunotherapy products distributed through licensed online pharmacy platforms that process valid prescriptions and deliver approved immunotherapy products directly to eligible patients through regulated digital dispensing services.
Estimation Model
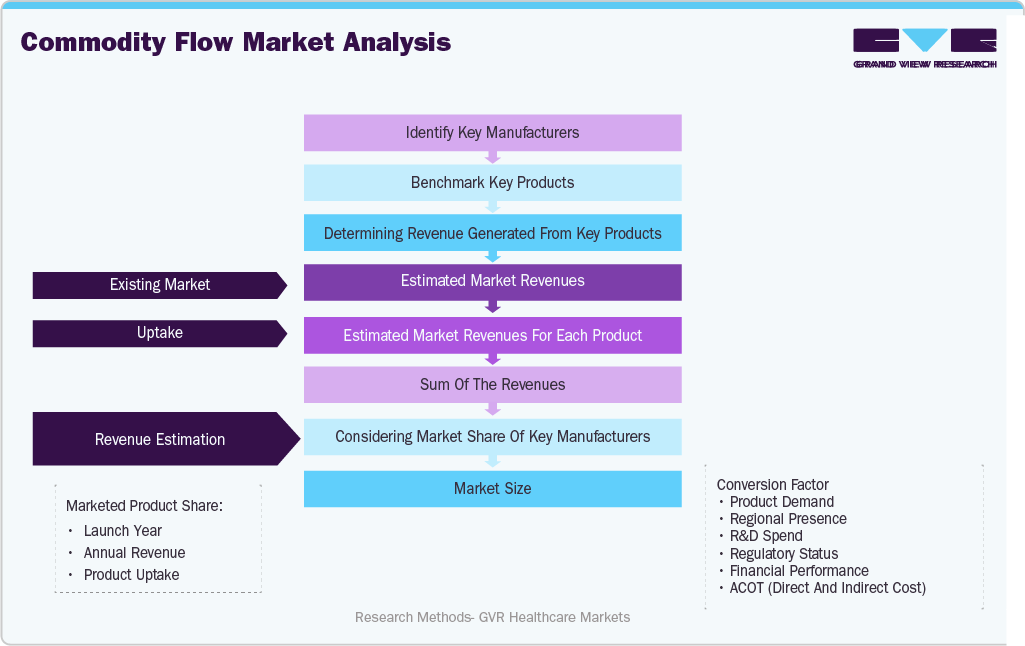
The allergy immunotherapy market was estimated using a commodity flow and revenue-based approach. Key manufacturers offering subcutaneous immunotherapy (SCIT), sublingual immunotherapy (SLIT), venom immunotherapy, and food allergy immunotherapy products were identified, followed by benchmarking their commercial portfolios across major regions. Revenue generated from leading allergy immunotherapy products was evaluated using annual reports, investor presentations, financial filings, company websites, regulatory databases, and publicly available commercial information. Product pricing, regional availability, regulatory approvals, distribution channels, and treatment adoption were assessed to estimate product-level revenues. The revenues generated from individual products were aggregated and validated by considering the market presence of leading manufacturers and competitive positioning across regions. The final market estimates were verified through primary interviews with industry participants and secondary research, ensuring consistency with product commercialization trends, treatment utilization, and the competitive structure of the global allergy immunotherapy market.
Delivered Customizations
This report has been delivered with the following In-depth customizations
CLIENT REQUEST
CUSTOMIZATION DELIVERED
VALUE ADDS
Allergy Immunotherapy Commercialization Strategy Assessment
Developed a customized strategic assessment of the allergy immunotherapy market focusing on commercial opportunities across respiratory and food allergies. The study evaluated competitive benchmarking, regulatory positioning, pricing dynamics, reimbursement frameworks, physician adoption, distribution channels, and market access strategies across major global markets to determine commercial expansion opportunities for immunotherapy products.
Enables pharmaceutical companies and investors to evaluate competitive positioning, identify attractive commercialization opportunities, optimize regional market entry strategies, and support long-term portfolio expansion within the allergy immunotherapy market.
Allergy Diagnosis, Patient Identification & Treatment Adoption Analysis
Delivered a detailed assessment of the allergy care pathway influencing immunotherapy adoption, including allergy prevalence, diagnostic testing utilization, patient identification pathways, allergist referral patterns, treatment eligibility, patient adherence, healthcare infrastructure, and integration of precision diagnostics across specialty allergy clinics and hospitals.
Provides actionable insights for optimizing patient access strategies, improving physician engagement, identifying underserved patient populations, strengthening treatment adoption, and aligning commercial planning with evolving allergy diagnosis and management practices.
Pipeline Benchmarking & Next-generation Immunotherapy Opportunity Assessment
Conducted a focused assessment of the allergy immunotherapy pipeline, including recombinant allergens, peptide immunotherapy, oral and epicutaneous immunotherapy platforms, biologic combination approaches, and novel allergen delivery technologies. The analysis included clinical development benchmarking, partnership activity, licensing opportunities, regulatory progress, and evaluation of future competitive dynamics across seasonal, perennial, food, and venom allergy segments.
Supports strategic portfolio planning, partnership and licensing evaluation, pipeline prioritization, and investment decision-making by identifying innovation trends, unmet clinical needs, and future growth opportunities within the allergy immunotherapy market.
Frequently Asked Questions About This Report
The global allergy immunotherapy market size was valued at USD 2.1 billion in 2025 and is estimated at USD 2.3 billion for 2026.
The global allergy immunotherapy market is expected to grow at a CAGR of 8.9% from 2026 to 2033, reaching USD 4.1 billion by 2033.
Subcutaneous Immunotherapy (SCIT) held the largest revenue share of 58.6% in 2025, while Sublingual Immunotherapy (SLIT) is projected to be the fastest-growing route of administration with a 10.3% CAGR through 2033.
Key players include ALK-Abelló, Stallergenes Greer, Allergy Therapeutics, HAL Allergy, LETI Pharma, Aimmune Therapeutics, DBV Technologies, HollisterStier Allergy (Jubilant HollisterStier LLC), Immunotek, Allergopharma, Diater, Roxall, Probelte, and Lofarma
Key factors include the rising prevalence of allergic diseases, increasing adoption of disease-modifying therapies, improvements in allergy diagnostics, expansion of specialist allergy services, growing investment in next-generation immunotherapy technologies, and increasing regulatory approvals for innovative allergen immunotherapy products.
Europe dominated the allergy immunotherapy market with a 61.6% revenue share in 2025, supported by strong clinical adoption, established manufacturers, and well-developed allergy care infrastructure.
The inhalant allergen immunotherapy segment led the market with a 92.4% revenue share in 2025, while Food Allergen Immunotherapy is expected to be the fastest-growing segment with a 23.9% CAGR during the forecast period.
Allergic rhinitis accounted for the largest revenue share of 72.8% in 2025, while Food Allergy is projected to be the fastest-growing indication with a 22.8% CAGR over the forecast period.
Asia Pacific is the fastest-growing regional market and is projected to expand at a CAGR of 10.9% during the forecast period.
About the Author(s)
Pharmaceuticals Research Team
Healthcare · PharmaceuticalsThis report was authored by the pharmaceuticals research team at Grand View Research - comprising two research analysts, one senior research analyst, and one industry expert - with specialized expertise in the pharmaceuticals segment of the healthcare industry. All findings are based on proprietary healthcare databases, executive interviews, and regulatory analysis, subject to internal peer review prior to publication.
Last Updated:
Speak to Analyst


Customize this report to your needs — add regions, segments, or data points, with 20% free customization.
Or view our licence options:


ISO 9001:2015 & 27001:2022 Certified
We are GDPR and CCPA compliant! Your transaction & personal information is safe and secure. For more details, please read our privacy policy.


