
- Home
- »
- Medical Devices
- »
-
Ambulatory Blood Pressure Monitoring Devices Market Report, 2033GVR Report cover

Ambulatory Blood Pressure Monitoring Devices Market (2026-2033)
Size, Share & Trends Analysis Report By Product (Ambulatory Blood Pressure Monitors, Instrument & Accessories), By End Use (Hospitals, Ambulatory Surgical Centers & Clinics, Homecare), By Region, And Segment Forecasts
Market Size, 2025
$1.6BMarket Estimate, 2026
$1.7BMarket Forecast, 2033
$3.8BCAGR, 2026–2033
11.6%Ambulatory Blood Pressure Monitoring Devices Market Summary
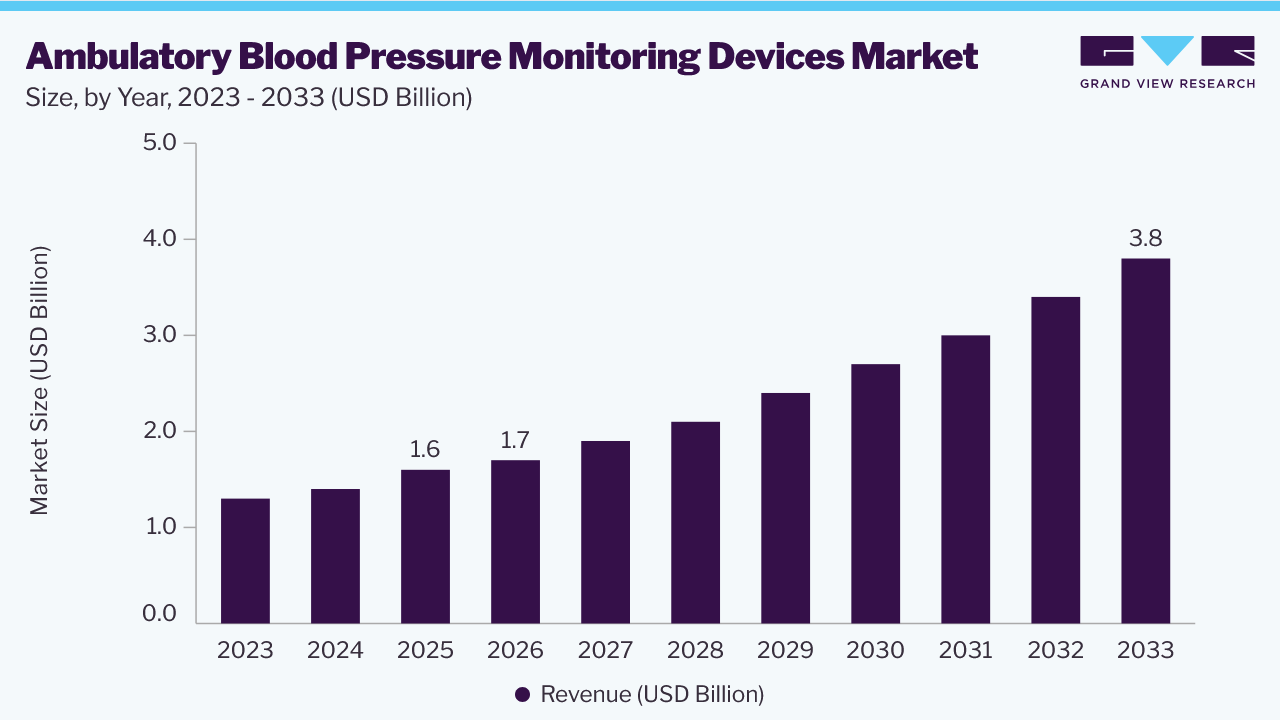
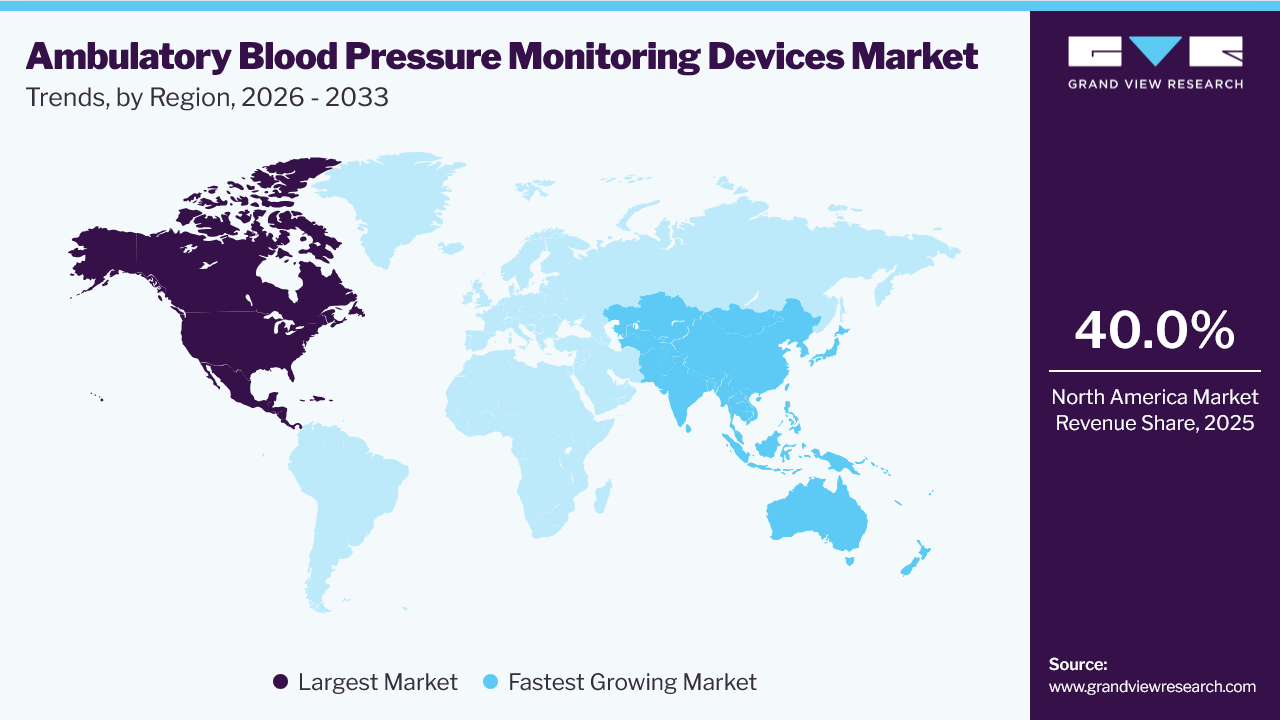
The global ambulatory blood pressure monitoring devices market size was valued at USD 1.6 billion in 2025 and is projected to grow from USD 1.7 billion in 2026 to USD 3.8 billion by 2033, at a CAGR of 11.6% from 2026 to 2033. North America dominated the global market, accounting for the largest revenue share of 40.0% in 2025. The market is primarily driven by the growing geriatric population, increasing prevalence of chronic diseases such as hypertension, and ongoing technological advancements in blood pressure monitoring solutions. According to the World Health Organization (WHO) Hypertension Fact Sheet updated in 2025, an estimated 1.4 billion adults aged 30–79 years worldwide were living with hypertension in 2024. Hypertension remains one of the leading causes of premature mortality globally and contributes significantly to the burden of cardiovascular diseases, including heart attack, stroke, and kidney disorders.
Furthermore, WHO reports that nearly two-thirds of individuals with hypertension reside in low- and middle-income countries, where diagnosis and disease management remain major healthcare challenges. These factors are increasing the need for reliable blood pressure screening and continuous monitoring solutions, thereby driving demand for ambulatory blood pressure monitoring devices worldwide.
Key Market Trends & Insights
- By end use: The hospitals segment held the largest market share of over 65.0% in 2025.
- By product: The ambulatory blood pressure monitors segment held the largest market share of around 66.0% in 2025.
Regional Highlights
- Largest regional market: North America (40.0% revenue share, 2025)
- Fastest-growing regional market: Asia Pacific (highest CAGR, 2026-2033)
Market Size & Forecast
- Market size in 2025: USD 1.6 Billion
- Estimated market size in 2026: USD 1.7 Billion
- Projected market size by 2033: USD 3.8 Billion
- CAGR (2026-2033): 11.6%
Prism AI by Grand View Research Free to tryAsk a question about the ambulatory blood pressure monitoring devices marketTry asking✓Every figure cited from GVR research Prefer the report? Download free sample →The growing geriatric population is a key factor driving demand for ambulatory blood pressure monitoring (ABPM) devices. According to the United Nations International Day of Older Persons update published in 2025, the global population aged 60 years and above reached approximately 1.2 billion in 2025 and is projected to increase to 2.1 billion by 2050. As older adults are more susceptible to hypertension, cardiovascular diseases, and other age-related health conditions, the expanding elderly population is expected to drive sustained demand for continuous, accurate, and non-invasive blood pressure monitoring technologies.
 Source: Grand View Research, IR Documents, Primary Interviews, Paid DatabasesTo learn more about this report,
 Download Free Sample Report
Furthermore, ongoing technological advancements in ABPM devices are expected to support market growth throughout the forecast period. The increasing adoption of digital, connected, and mobile-enabled blood pressure monitoring technologies is enhancing patient convenience, data accessibility, and remote care capabilities. For instance, in April 2026, OMRON Healthcare announced its support for May Measurement Month 2026 through the donation of 3,000 advanced blood pressure monitors capable of detecting probable atrial fibrillation, highlighting the industry's growing focus on early disease detection and remote cardiovascular monitoring. Such developments are expected to accelerate the adoption of advanced blood pressure monitoring solutions and strengthen the broader market for ambulatory monitoring technologies worldwide.
Analyst Perspective
The global ambulatory blood pressure monitoring devices market is evolving toward connected, wearable, and continuous monitoring solutions. Growth is driven by the rising prevalence of hypertension, an aging population, and increasing adoption of home healthcare and telemedicine. Innovations such as cuffless devices, AI-enabled analytics, and mobile connectivity are improving convenience and patient engagement. Despite challenges related to device costs, reimbursement, and clinical validation, continued innovation and investments in digital health are expected to support market growth.
End Use Insights
The hospitals segment accounted for the largest market share, exceeding 65.0% in 2025. This dominance is primarily driven by the need for high clinical accuracy, improved patient outcomes, technological advancements, and regulatory compliance. Hospitals operate under stringent requirements to maintain patient safety and quality of care, creating strong demand for precise monitoring solutions. In addition, healthcare providers rely on ambulatory blood pressure monitoring devices to support the diagnosis and management of hypertension and other cardiovascular conditions. By providing continuous blood pressure measurements over a 24-hour period, ABPM devices offer a more comprehensive assessment of blood pressure variability and patterns than conventional in-office readings, supporting informed clinical decision-making.
The home care segment is anticipated to register the fastest CAGR from 2026 to 2033, and this trend is expected to continue throughout the forecast period. Growth is primarily driven by the increasing preference for home-based disease management, greater convenience, and rising demand for cost-effective healthcare solutions. Furthermore, advancements in device connectivity, portability, and digital health technologies have made continuous blood pressure monitoring increasingly practical in home settings. The expanding adoption of telehealth services and remote patient monitoring platforms is further supporting the use of home-based blood pressure monitoring solutions. Growing consumer awareness regarding preventive healthcare and the importance of continuous blood pressure management is also contributing to segment growth.
Product Insights
The ambulatory blood pressure monitors segment held the largest market share, accounting for approximately 66.0% in 2025. Segment growth is driven by the increasing prevalence of hypertension and cardiovascular diseases, which continue to create demand for accurate and continuous blood pressure monitoring solutions. Rising awareness regarding early diagnosis and disease prevention is further supporting the adoption of ambulatory blood pressure monitors. These devices provide a complete 24-hour blood pressure profile, enabling healthcare professionals to evaluate fluctuations throughout the day and make more informed treatment decisions based on comprehensive patient data.
The instruments and accessories segment accounted for a significant share of the ambulatory blood pressure monitoring devices market in 2025. Growth in this segment is supported by ongoing innovations in wearable technologies, mobile health applications, and sensor-based monitoring systems, which enhance user convenience and monitoring capabilities. In addition, increasing demand for replacement components and accessories is contributing to segment expansion. Technologically advanced cuffs, sensors, batteries, and connectivity modules are improving device performance while extending product life cycles. Moreover, the growing installed base of ambulatory blood pressure monitoring devices worldwide is generating steady demand for accessories and replacement parts, supporting continued market growth.
The blood pressure cuff sub-segment within the instruments and accessories segment accounted for the largest market share of approximately 57.0% in 2025. The sub-segment benefits from the proven accuracy, reliability, and versatility of cuff-based monitoring systems, which continue to support widespread adoption among healthcare providers and patients. Blood pressure cuffs are available in multiple sizes and configurations to accommodate diverse patient populations, with both disposable and reusable variants widely used in healthcare settings. Ongoing product innovation is further strengthening segment growth. For instance, in March 2026, Garmin announced the availability of its Index BPM smart blood pressure monitor in Canada, enabling users to measure and track blood pressure readings through the Garmin Connect ecosystem and supporting the broader adoption of connected blood pressure monitoring technologies.
Regional Insights
The North America ambulatory blood pressure monitoring devices industry dominated with a revenue share of approximately 40.0% in 2025. Growth in the region is driven by increased product launches by key companies, rising overall healthcare expenditure, and more regulatory approvals. Moreover, the region has a high number of health-conscious consumers, which is likely to drive market growth.
U.S. Ambulatory Blood Pressure Monitoring Devices Market Trends
 To learn more about this report, Download Free Sample Report
The ambulatory blood pressure monitoring devices industry in the U.S. accounted for approximately 88.0% of the North American market in 2025. The high prevalence of cardiovascular disease and hypertension continues to drive demand for advanced blood pressure monitoring technologies. In response to the growing disease burden, manufacturers are introducing innovative monitoring solutions that enable continuous, remote patient management. For instance, in January 2026, Kestra Medical Technologies announced a strategic collaboration with Biobeat Technologies to integrate FDA-cleared cuffless, patch-based blood pressure monitoring technology into its cardiac recovery platform, expanding access to continuous cardiovascular monitoring across the United States.
The Mexico ambulatory blood pressure monitoring devices industry is expected to experience significant market growth due to ongoing healthcare reforms, increasing demand for home-based care, and the rising burden of hypertension and cardiovascular diseases. The country's growing focus on preventive healthcare and digital monitoring solutions is expected to accelerate the adoption of advanced blood pressure monitoring technologies, particularly connected and home-based systems.
Europe Ambulatory Blood Pressure Monitoring Devices Market Trends
The ambulatory blood pressure monitoring devices industry in Europe was the second-largest market in 2025. Market growth is primarily driven by the region’s expanding geriatric population, which is at a higher risk of developing hypertension and other cardiovascular disorders. Increasing awareness among healthcare professionals regarding the clinical benefits of 24-hour ambulatory blood pressure monitoring compared with conventional in-clinic measurements is expected to further support market expansion. In addition, the growing emphasis on early diagnosis and effective management of hypertension is accelerating the adoption of ambulatory blood pressure monitoring devices across the region.
The UK ambulatory blood pressure monitoring devices industry is anticipated to witness strong growth from 2026 to 2033, on account of the increasing elderly population and rising prevalence of chronic conditions, including hypertension and cardiovascular diseases. Furthermore, the expansion of digital health initiatives, the growing adoption of home-based healthcare services, and increasing awareness of the benefits of continuous blood pressure monitoring are expected to drive market demand. The country's strong focus on preventive healthcare and remote patient management is also contributing to the adoption of advanced monitoring technologies.
The ambulatory blood pressure monitoring devices industry in Germany is expected to grow at a CAGR of 10.0% from 2026 to 2033. The market is supported by ongoing technological advancements, a well-established healthcare infrastructure, and increasing adoption of connected medical devices. Germany remains one of Europe's largest medical technology markets, benefiting from high healthcare expenditure and growing demand for home-based monitoring solutions. In addition, increasing emphasis on the early detection and management of cardiovascular diseases is expected to support market growth throughout the forecast period.
The France ambulatory blood pressure monitoring devices industry held the second-largest share of the European market in 2025. The country's growing geriatric population and increasing focus on preventive healthcare are expected to positively influence market growth. Rising demand for home-based healthcare services and continuous monitoring solutions is further supporting adoption. Moreover, increasing awareness regarding hypertension management and improved access to digital healthcare technologies are expected to contribute to market expansion over the forecast period.
Asia Pacific Ambulatory Blood Pressure Monitoring Devices Market Trends
The ambulatory blood pressure monitoring devices industry in the Asia Pacific is projected to register the fastest growth during the forecast period. Growth is primarily driven by favorable government initiatives promoting the adoption of advanced medical technologies, rising healthcare expenditure, and the rapidly expanding elderly population. In addition, increasing pressure on healthcare systems to improve outcomes while reducing overall treatment costs is expected to accelerate demand for ambulatory blood pressure monitoring devices across the region.
The China ambulatory blood pressure monitoring devices industry is projected to experience the fastest growth in the Asia Pacific market from 2026 to 2033. The country's strong manufacturing capabilities, particularly in electronic components and medical devices, support the development and affordability of blood pressure monitoring technologies. Moreover, cost-effective manufacturing, an extensive supply chain ecosystem, and increasing healthcare investments are expected to continue attracting market participants and supporting industry growth.
The ambulatory blood pressure monitoring devices industry in India is projected to expand significantly over the forecast period. Rising prevalence of hypertension and cardiovascular diseases, growing healthcare awareness, and increasing access to digital health technologies are key factors driving market growth. Furthermore, government initiatives promoting preventive healthcare and the expanding adoption of remote patient monitoring solutions are expected to support demand for ambulatory blood pressure monitoring devices.
The Japan ambulatory blood pressure monitoring devices industry is anticipated to witness steady growth from 2026 to 2033, supported by the country's aging population and high prevalence of hypertension. Japan's universal healthcare system provides broad access to medical services and reimbursement mechanisms for various healthcare technologies. In addition, the presence of leading industry participants, including Omron Healthcare and Nihon Kohden, coupled with the increasing adoption of advanced monitoring technologies, is expected to drive market growth.
Latin America Ambulatory Blood Pressure Monitoring Devices Market Trends
The ambulatory blood pressure monitoring devices industry in Latin America is expected to grow steadily over the forecast period. Increasing prevalence of chronic diseases and cardiovascular disorders, coupled with demographic shifts toward an aging population, are creating greater demand for continuous blood pressure monitoring solutions. Furthermore, rising healthcare awareness and expanding access to digital health services are expected to support market development across the region.
The ambulatory blood pressure monitoring devices industry in Brazil is projected to grow at a CAGR of 9.0% during the forecast period. Growth is driven by increasing healthcare awareness, improved access to monitoring technologies, and rising demand for connected and technologically advanced blood pressure monitoring solutions. In addition, the growing adoption of remote patient monitoring and home healthcare services is expected to further support market expansion.
Key Ambulatory Blood Pressure Monitoring Devices Company Insights
Leading companies operating in the ambulatory blood pressure monitoring devices market are focused on strengthening their market positions through strategic initiatives, including mergers and acquisitions, partnerships, product launches, and geographic expansion. Continuous innovation and technological advancement remain key competitive strategies, enabling market participants to enhance product capabilities, expand their customer base, and address the growing demand for accurate, connected, and patient-centric blood pressure monitoring solutions.
Key Ambulatory Blood Pressure Monitoring Devices Companies
The following key companies have been profiled for this study on the Ambulatory Blood Pressure Monitoring Devices market:
-
OMRON Healthcare Co., Ltd.
-
Welch Allyn, Inc. (a Baxter company)
-
A&D Medical Co., Ltd.
-
Microlife Corporation
-
Rossmax International Ltd.
-
Spacelabs Healthcare, LLC
-
BOSCH + SOHN GmbH u. Co. KG
-
SunTech Medical, Inc.
-
SCHILLER AG
-
Biobeat Technologies Ltd.
-
Aktiia SA
-
HINGMED Medical Technology Co., Ltd.
Recent Developments
- In September 2025, Sky Labs launched CART BP, a ring-type cuffless blood pressure monitoring device designed for everyday use. The solution enables continuous 24-hour blood pressure monitoring, including nighttime, providing users and clinicians with a more comprehensive assessment of blood pressure patterns. The launch highlights the growing adoption of wearable, non-invasive monitoring technologies and supports the advancement of next-generation ambulatory blood pressure monitoring solutions.
- In July 2025, Aktiia SA announced that its G0 Blood Pressure Monitoring System, marketed as the Hilo Band, received U.S. FDA 510(k) clearance for over-the-counter use. The approval made the Hilo Band the first FDA-cleared cuffless blood pressure monitoring device available without a prescription, expanding access to continuous blood pressure monitoring and accelerating the adoption of wearable ambulatory blood pressure monitoring technologies.
Ambulatory Blood Pressure Monitoring Devices Market Report Scope
Report Attribute
Details
Market size in 2025
USD 1.6 billion
Estimated market size in 2026
USD 1.7 billion
Projected market size by 2033
USD 3.8 billion
Growth rate
CAGR of 11.6% from 2026 to 2033
Base year for estimation
2025
Historical data
2021 – 2024
Forecast period
2026 – 2033
Quantitative units
Revenue in USD billion and CAGR from 2026 to 2033
Report coverage
Revenue forecast, company ranking, competitive landscape, growth factors, and trends
Segments covered
Product, end use, region
Regional Scope
North America; Europe; Asia Pacific; Central & South America; Middle East & Africa
Country Scope
U.S.; Canada; Mexico; UK; Germany; France; Italy; Spain; Denmark; Sweden; Norway; China; India; Japan; Australia ; South Korea; Thailand; Brazil; Argentina; South Africa; UAE; Saudi Arabia; Kuwait
Key companies profiled
OMRON Healthcare Co., Ltd.; Welch Allyn, Inc. (a Baxter company); A&D Medical Co., Ltd.; Microlife Corporation; Rossmax International Ltd.; Spacelabs Healthcare, LLC; BOSCH + SOHN GmbH u. Co. KG; SunTech Medical, Inc.; SCHILLER AG; Biobeat Technologies Ltd.; Aktiia SA; HINGMED Medical Technology Co., Ltd.
Customization scope
Free report customization (equivalent up to 8 analysts working days) with purchase. Addition or alteration to country, regional & segment scope.
Pricing and purchase options
Avail of customized purchase options to meet your exact research needs. Explore purchase options
Global Ambulatory Blood Pressure Monitoring Devices Market Report Segmentation
This report forecasts revenue growth at global, regional, and country levels and provides an analysis of the latest industry trends and opportunities in each of the sub-segments from 2021 to 2033. For this study, Grand View Research has segmented the global ambulatory blood pressure monitoring devices market report based on product, end use, and region:
-
Product Outlook (Revenue, USD B illion, 2021 - 2033)
-
Ambulatory Blood Pressure Monitors
-
Instrument & Accessories
-
Blood Pressure Cuffs
-
Others Type
-
-
-
End Use Outlook (Revenue, USD B illion, 2021 - 2033)
-
Hospitals
-
Ambulatory Surgical Centers & Clinics
-
Homecare
-
-
Regional Outlook (Revenue, USD B illion , 2021 - 2033)
-
North America
-
U.S.
-
Canada
-
Mexico
-
-
Europe
-
UK
-
Germany
-
France
-
Italy
-
Spain
-
Denmark
-
Sweden
-
Norway
-
-
Asia Pacific
-
Japan
-
China
-
India
-
South Korea
-
Australia
-
Thailand
-
-
Latin America
-
Brazil
-
Argentina
-
-
Middle East and Africa (MEA)
-
South Africa
-
Saudi Arabia
-
UAE
-
Kuwait
-
-
Frequently Asked Questions About This Report
The global ambulatory blood pressure monitoring devices market size was valued at USD 1.6 billion in 2025 and is estimated at USD 1.7 billion in 2026.
The global ambulatory blood pressure monitoring devices market is expected to grow at a CAGR of 11.6% from 2026 to 2033, reaching USD 3.8 billion in 2033.
Based on the product, instruments & accessories dominated the market and accounted for 66.0% of global revenue in 2025.
North America dominated with approximately 40.0% revenue share in 2025.
The key companies operating in the global ambulatory blood pressure monitoring devices market include Baxter International Inc., Bosch Sohn GmbH Co KG, BPL Ltd, Contec Medical Systems Co., Ltd, GE Healthcare, Halma Plc, Omron Corporation, OSI Systems Inc. (Spacelabs Healthcare Inc.), Schiller AG, and Vaso Corporation.
About the Author(s)
Medical Devices Research Team
Healthcare · Medical DevicesThis report was authored by the medical devices research team at Grand View Research - comprising two research analysts, one senior research analyst, and one industry expert - with specialized expertise in the medical devices segment of the healthcare industry. All findings are based on proprietary healthcare databases, executive interviews, and regulatory analysis, subject to internal peer review prior to publication.
Last Updated:
Speak to Analyst

Customize this report to your needs - add regions, segments, or data points, with 20% free customization.
Or view our licence options:


ISO 9001:2015 & 27001:2022 Certified
We are GDPR and CCPA compliant! Your transaction & personal information is safe and secure. For more details, please read our privacy policy.


