
- Home
- »
- Pharmaceuticals
- »
-
Amyloidosis Treatment Market Size Report, 2026-2033GVR Report cover

Amyloidosis Treatment Market (2026 - 2033)
Size, Share & Trends Analysis Report By Treatment (Chemotherapy, Immunosuppressive Drugs, Transplantation, Supportive Care, Surgery), By End Use (Hospitals & Clinics), By Region, And Segment Forecasts
Market Size, 2025
$6.2BMarket Estimate, 2026
$6.6BMarket Forecast, 2033
$10.9BCAGR, 2026–2033
7.4%Amyloidosis Treatment Market Summary
The global amyloidosis treatment market size was valued at USD 6.2 billion in 2025 and is projected to grow from USD 6.6 billion in 2026 to USD 10.9 billion by 2033, at a CAGR of 7.4% from 2026 to 2033. North America dominated the market, accounting for a revenue share of 39.3% in 2025. The industry is experiencing growth due to rising awareness of the disease, advancements in diagnostic methods, and an increasing number of patients being identified at earlier stages with accurate diagnoses.
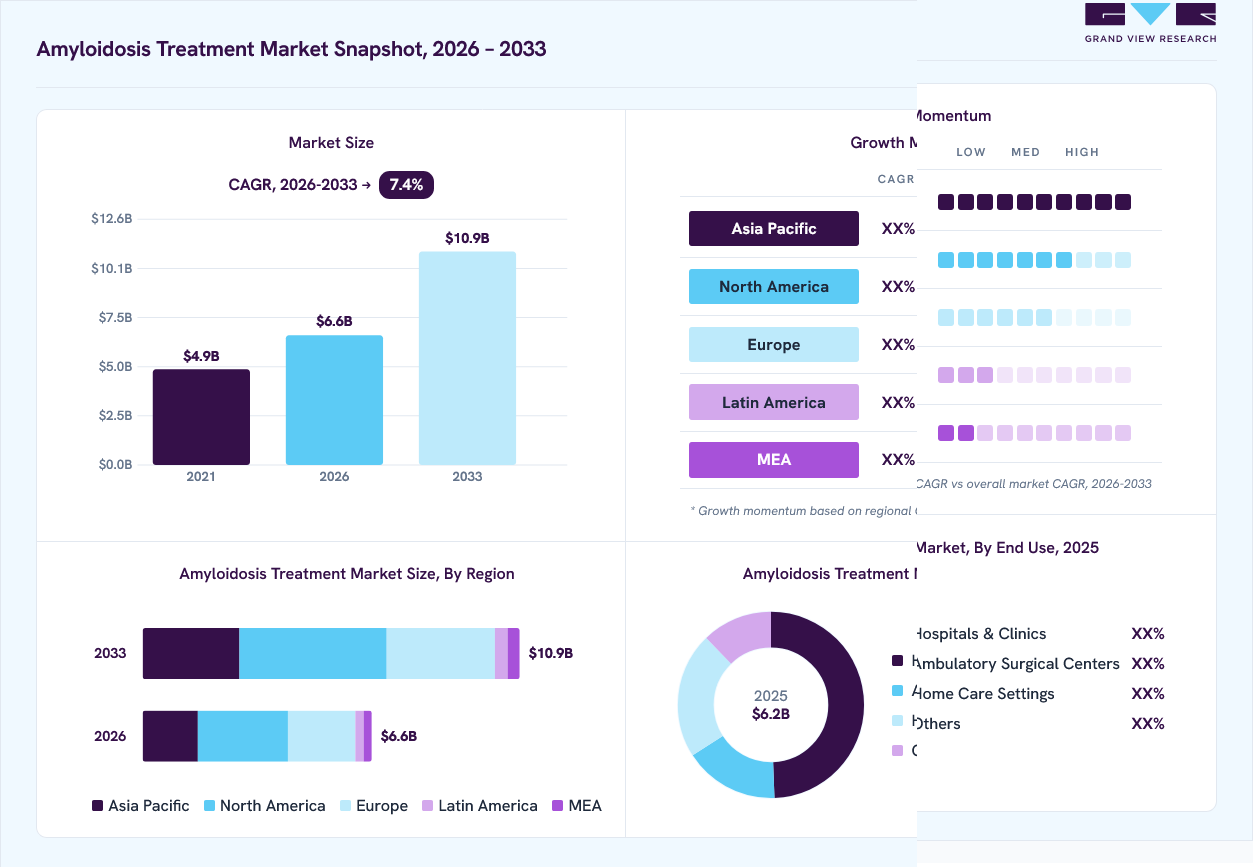 Source: Grand View Research, IR Documents, Primary Interviews, Paid DatabasesTo learn more about this report,
 Download Free Sample Report
Key Market Trends & Insights
- By treatment: Chemotherapy segment led the market with the largest revenue share of 26.5% in 2025.
- By end use: Hospitals & clinics segment led the market with the largest revenue share of 49.3% in 2025.
Regional Highlights
- Largest regional market: North America (39.3% revenue share, 2025)
- By country: The U.S. held the largest market share in 2025.
Market Size & Forecast
- Market size in 2025: USD 6.2 Billion
- Estimated market size in 2026: USD 6.6 Billion
- Projected market size by 2033: USD 10.9 Billion
- CAGR (2026-2033): 7.4%
Three ways to get this report
Buy it, customize it, or ask a question.Ask an Analyst
Analyst response in 1 business day
- AccessReport author, directly
- Reply timeWithin 1 working day
- No sales callDirect answer only
- FormatEmail reply
- CostFree, no cost
Get the Full Report
What the study covers
- FormatsPDF · Excel · Dashboard
- Timeline2026–2033 annual, 2025 base
- Coverage20+ countries, 5 regions
- Companies10+ key players profiled
Customize the Report
20% free customization
- IncludeCountries, segments, points
- TailorTo your product definition
- ExtendDeeper competitor detail
- OrA fully bespoke study
- Turnaround5–10 working days
Innovations such as advanced imaging, mass spectrometry, and genetic testing are allowing healthcare providers to better distinguish between amyloidosis subtypes, supporting more precise and effective treatment approaches. The establishment of specialized care centers and the availability of trained medical experts are further enhancing access to comprehensive care. Additionally, the growing incidence of age-related transthyretin amyloidosis, particularly among older populations, is driving demand for long-term therapeutic solutions. These factors are prompting pharmaceutical companies to expand their research pipelines, while the recognition of amyloidosis as a condition that can be effectively managed with timely treatment is transforming global patient care practices.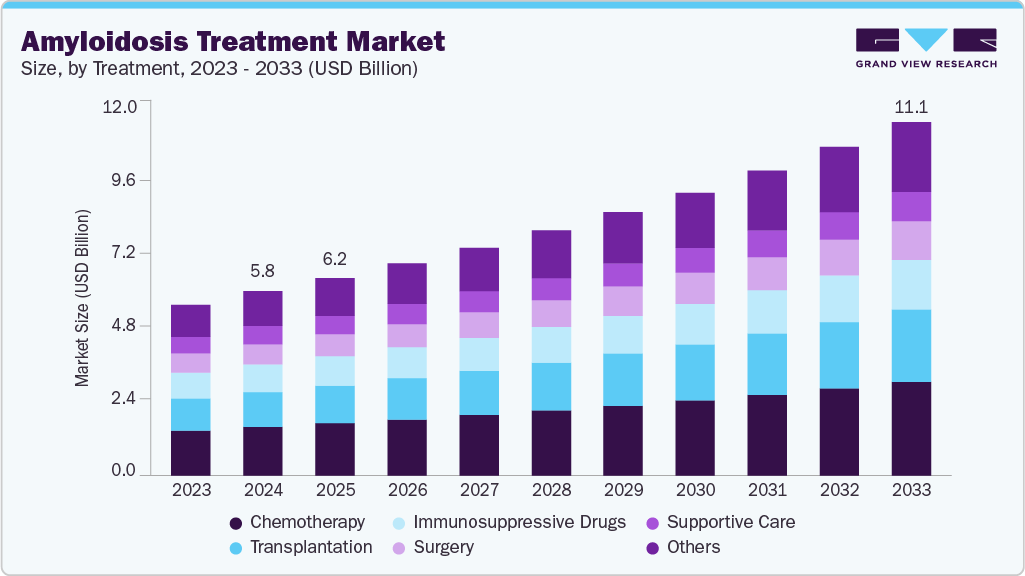 To learn more about this report, Download Free Sample Report
One of the key drivers fueling the amyloidosis treatment market is the regulatory advancement of gene-silencing therapies for transthyretin amyloidosis. For instance, in March 2025, the U.S. FDA approved Amvuttra (vutrisiran) as the first gene-silencing therapy for transthyretin amyloid cardiomyopathy (ATTR-CM). The approval was backed by Phase III HELIOS-B trial results showing a 28% reduction in all-cause mortality and cardiovascular events. Patients also experienced notable improvements in functional capacity and quality of life. This advancement offers a new treatment pathway directly reducing TTR protein production with only four annual injections. The approval is expected to boost early diagnosis, expand RNA-based therapy adoption, and intensify competition in the ATTR-CM market.
The regulatory approval of highly effective small-molecule stabilizers targeting transthyretin amyloidosis is a major development boosting the amyloidosis treatment market. For instance , in December 2024, the U.S. FDA approved Attruby (acoramidis), a near-complete transthyretin (TTR) stabilizer developed by BridgeBio Pharma, for the treatment of transthyretin amyloid cardiomyopathy (ATTR-CM) (BridgeBio). Acoramidis demonstrated over 90% stabilization of TTR and significantly reduced cardiovascular death and hospitalizations in the pivotal ATTRibute-CM trial. The approval introduces a convenient oral alternative that expands treatment options beyond RNAi-based therapies and meets the needs of a broader patient base. It is expected to intensify market competition and accelerate innovation in ATTR-CM therapeutics. With improved efficacy, tolerability, and ease of administration, acoramidis is positioned to reshape treatment paradigms for newly diagnosed and long-term ATTR-CM patients.
 To learn more about this report, Download Free Sample Report
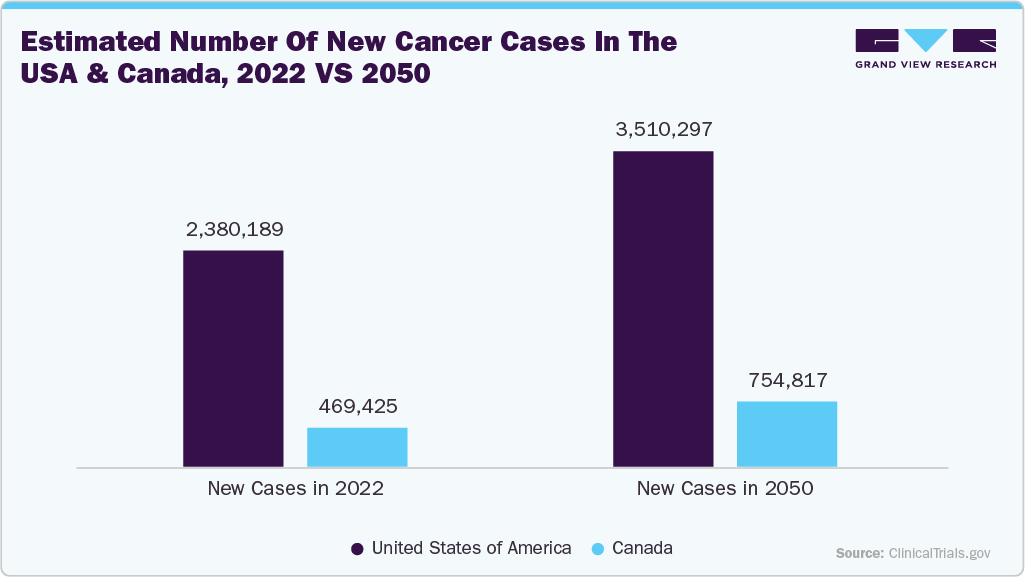
The projected surge in cancer cases, with the United States expected to see a 47.5% increase and Canada a 60.7% increase by 2050, the rising prevalence of chronic and complex diseases. This trend emphasizes the growing strain on healthcare systems, which in turn accelerates demand for advanced diagnostics and treatment solutions. Given that cancer and amyloidosis share overlapping clinical challenges such as organ dysfunction, protein misfolding, and systemic inflammation, the increase in cancer incidence indirectly raises awareness and identification of related conditions like amyloidosis. This linkage is likely to enhance patient screening, expand healthcare investments, and strengthen treatment infrastructure.
Consequently, the industry is expected to benefit from these dynamics as rising cancer prevalence fuels both clinical awareness and therapeutic innovation. With heightened demand for precision therapies, there will be an increased focus on monoclonal antibodies, targeted treatments, and supportive care solutions that address disease progression more effectively. Moreover, pharmaceutical companies and healthcare providers are likely to increase research funding and collaborations, leveraging advancements in oncology to accelerate drug development for amyloidosis. This synergy will position the amyloidosis market for significant growth in the coming decades.
Market Dynamics
The amyloidosis treatment market is witnessing steady expansion, driven by increasing disease awareness, improved diagnosis rates, and the growing availability of targeted therapies for transthyretin amyloidosis (ATTR) and light chain amyloidosis (AL). The market is transitioning from conventional chemotherapy and supportive care toward disease modifying treatments, including transthyretin stabilizers and RNA silencing therapies, reflecting the industry's focus on improving long term patient outcomes. Growing investments in rare disease research, expanding clinical pipelines, and favorable regulatory support are further contributing to market growth. In addition, increasing physician awareness and advancements in genetic testing are enabling earlier identification of eligible patients, supporting treatment adoption. A notable industry development reflects this trend. For instance, in March 2025, Alnylam Pharmaceuticals received U.S. FDA approval for Amvuttra (vutrisiran) for the treatment of transthyretin amyloidosis with cardiomyopathy (ATTR-CM). The approval expanded disease modifying treatment options and accelerated the market shift toward RNA interference based therapies, supporting continued innovation and commercial growth within the amyloidosis treatment landscape.
The amyloidosis treatment market is being driven by the increasing adoption of targeted therapies that address the underlying mechanisms of disease progression rather than providing symptomatic relief. Earlier, treatment options for amyloidosis, particularly ATTR amyloidosis, were limited and focused on managing complications associated with organ damage. However, the introduction of transthyretin stabilizers, RNA silencing therapies, and monoclonal antibody-based approaches has expanded the treatment landscape and improved disease management. These therapies have encouraged physicians to diagnose patients earlier and initiate treatment before irreversible organ impairment occurs. The growing clinical evidence supporting disease modifying therapies is also contributing to greater acceptance among healthcare providers and payers. In addition, increasing awareness among cardiologists, neurologists, and hematologists has improved referral pathways and treatment uptake. The market is further benefiting from continued investments in rare disease drug development, resulting in a broader pipeline of novel therapies. For instance, in 2025, Bayer expanded the commercialization of Beyonttra (acoramidis) across multiple European markets following regulatory approvals, increasing the availability of targeted therapies for transthyretin amyloidosis with cardiomyopathy (ATTR-CM) and supporting the wider adoption of disease modifying treatment approaches globally. Such developments are contributing to increased treatment adoption and expanding commercial opportunities within the amyloidosis treatment market.
The amyloidosis treatment market faces challenges due to delayed diagnosis and the underidentification of eligible patients. Amyloidosis often presents with symptoms that are similar to those of more common cardiovascular, neurological, and hematological disorders, making accurate diagnosis difficult in the early stages of the disease. As a result, patients frequently consult multiple specialists before receiving a confirmed diagnosis, which delays treatment initiation and reduces the number of patients receiving approved therapies. The challenge is particularly evident in transthyretin amyloidosis with cardiomyopathy (ATTR-CM), where symptoms are often mistaken for conventional heart failure and other age related conditions. In addition, diagnosis typically requires access to specialized imaging technologies, genetic testing, and experienced treatment centers, which may not be readily available across all healthcare settings. Limited disease awareness among healthcare providers in some regions further contributes to missed or delayed diagnoses. These factors continue to restrict patient identification, reduce treatment uptake, and limit the full commercial potential of approved therapies within the amyloidosis treatment market.
Opportunity - Expansion of RNA-Based and Gene-Silencing Therapies
The growing development of RNA interference, antisense oligonucleotide, and gene silencing therapies presents a significant opportunity for the amyloidosis treatment market. These therapies are designed to reduce the production of disease causing proteins and address the underlying pathology of amyloidosis, supporting a shift toward disease modifying treatment approaches. Increasing clinical validation, favorable regulatory support, and continued investment in rare disease research are encouraging the development of next generation therapies across multiple amyloidosis subtypes. As manufacturers expand their pipelines and pursue approvals across major markets, the availability of targeted treatment options is expected to increase. For instance, in March 2025, Ionis Pharmaceuticals and AstraZeneca announced that WAINZUA (eplontersen) received European Commission approval for the treatment of hereditary transthyretin-mediated amyloidosis (hATTR) in adult patients with stage 1 or stage 2 polyneuropathy. The approval expanded the commercial availability of RNA targeted therapies and strengthened the treatment landscape for ATTR amyloidosis across the European market. Such developments are supporting portfolio expansion, increasing treatment options for patients, and creating opportunities for sustained market growth over the forecast period.
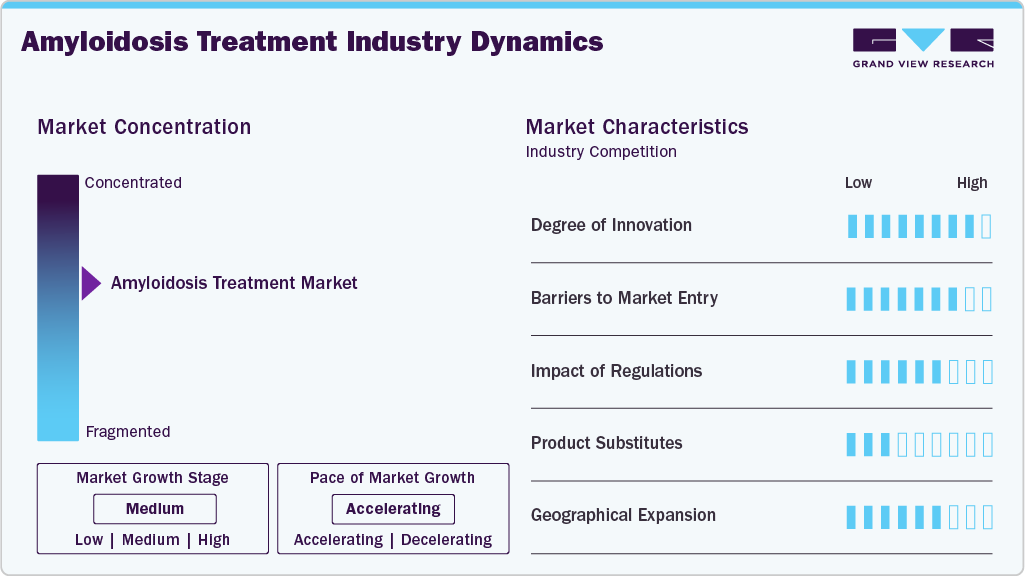
Market Concentration & Characteristics
The industry demonstrates high innovation, particularly with RNA-based therapeutics, monoclonal antibodies, and gene silencing techniques. Companies are prioritizing the development of disease-modifying drugs over traditional symptom management. Advances in diagnostics, including biomarker testing and AI-enhanced imaging, support personalized treatment strategies. Patents and orphan drug designations have further accelerated innovation across niche subtypes. Continued pipeline activity highlights a strong commitment to novel, targeted approaches.
Barriers to entry are significant due to high R&D costs, strict regulatory requirements, and the specialized nature of amyloidosis. Orphan drug development requires long clinical timelines and substantial financial resources. The dominance of key players with strong IP portfolios limits opportunities for new entrants. Disease rarity often constricts access to patient populations for clinical trials. Additionally, expertise in rare disease commercialization is necessary for sustained success.
 To learn more about this report, Download Free Sample Report
Regulations have a mixed impact, offering incentives and hurdles in the market. Orphan drug frameworks provide market exclusivity, tax benefits, and expedited review pathways for eligible products. However, regulatory bodies impose rigorous safety and efficacy standards given the complexity of the condition. Global discrepancies in approval timelines and reimbursement policies can slow market access. Post-approval monitoring remains critical due to the long-term nature of treatment outcomes.
Product substitutes are limited, but supportive therapies such as corticosteroids, diuretics, or off-label use of multiple myeloma drugs may serve temporary roles. For specific subtypes, such as ATTR amyloidosis, tafamidis and siRNA-based treatments dominate with few close alternatives. Bone marrow transplantation can serve as a substitute for pharmacologic therapy in AL amyloidosis, though it is suitable only for select patients. Alternative medicine plays a negligible role due to disease severity. The low interchangeability between treatments strengthens brand loyalty for approved therapies.
Geographical expansion remains a key growth lever as companies target underdiagnosed regions in Asia, Latin America, and the Middle East. North America and Europe lead in diagnosis rates and drug access, driven by advanced healthcare systems. Emerging markets show untapped potential, but face limitations in diagnostics, specialist care, and affordability. Multinational firms are forming partnerships to expand distribution and clinical outreach in underserved areas. Regional awareness campaigns and infrastructure investments are gradually improving detection and treatment availability.
Analyst Perspective
The amyloidosis treatment market is being shaped by the growing adoption of targeted therapies, particularly for ATTR amyloidosis, and increasing investment in rare disease treatment development. Regulatory approvals, expanding clinical evidence, and broader physician awareness are supporting the uptake of disease modifying therapies across key markets. Large pharmaceutical companies continue to strengthen their positions through portfolio expansion and commercialization initiatives, while specialized biotechnology companies are contributing innovation through RNA based and other targeted treatment approaches. Despite these developments, delayed diagnosis and patient identification remain key challenges that affect treatment uptake. Over the forecast period, market competition is expected to be driven by clinical differentiation, market access strategies, and efforts to improve early diagnosis and patient identification.
Treatment Insights
Based on treatment, the chemotherapy segment led the market with the largest revenue share of 26.5% in 2025, driven by chemotherapy, which remained a primary treatment option in 2024 due to its established role in managing AL amyloidosis. It is widely used to target underlying plasma cell dyscrasias, offering effective disease control for eligible patients. For instance, in March 2024, Fred Hutchinson Cancer Center described that chemotherapy remained the cornerstone treatment for AL amyloidosis, with physicians administering agents such as bortezomib (Velcade), cyclophosphamide, and dexamethasone either intravenously, subcutaneously, or orally to destroy abnormal plasma cells.
The transplantation segment is projected to grow at the fastest CAGR of 8.5% over the forecast period, fueled by the anticipated rise in autologous stem cell transplantation, supported by improving patient selection and advancements in procedural safety. Greater access to transplant centers and experienced hematology teams has expanded the eligible patient pool. Long-term survival benefits and deep hematologic responses associated with transplantation are driving demand. Enhanced pre-transplant risk assessment tools have reduced complication rates and improved treatment outcomes. For instance, in April 2025, the American Journal of Hematology reported that optimized autologous stem cell transplantation protocols using full-dose melphalan and high CD34⁺ cell counts significantly improved survival in 1,704 AL amyloidosis patients. Rising awareness among specialists about its curative potential is influencing referral patterns, and as more patients are diagnosed early, transplantation adoption is expected to increase steadily across developed regions.
End Use Insights
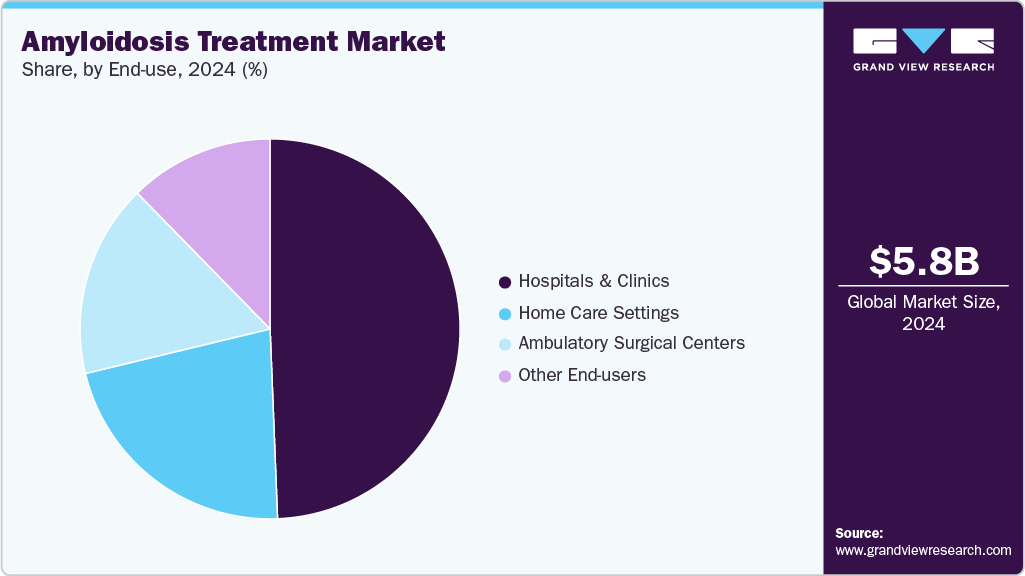
Based on end use, the hospitals & clinics segment led the market with the largest revenue share of 49.3% in 2025, which can be attributed to hospitals and clinics serving as the primary hubs for diagnosis, treatment, and follow-up care for amyloidosis patients. These facilities are equipped with advanced diagnostic tools, specialized care teams, and supportive infrastructure for complex treatment protocols. Multidisciplinary care coordination, including hematology, cardiology, and nephrology, is centralized within hospital settings. For instance, in May 2025, Mayo Clinic reported that its Cardiac Amyloidosis Clinic operating across Arizona, Florida, and Minnesota managed over 2,500 amyloidosis patients annually, utilizing mass spectrometry-based proteomics, cardiac MRI, and integrated care teams across key specialties. Access to infusion therapies, transplantation services, and clinical trials is largely hospital-based. Reimbursement structures also favor treatment administration in hospital environments for rare diseases. This comprehensive care delivery model underpins the dominant revenue contribution of hospitals and clinics.
 To learn more about this report, Download Free Sample Report
The home care settings segment is projected to grow at a fastest CAGR of 8.7% over the forecast period, as home care settings are gaining traction with the increasing availability of oral therapies and subcutaneous formulations for chronic management. Patients prefer at-home treatment options for comfort, convenience, and reduced risk of hospital-acquired infections. Digital health monitoring tools and remote consultation services support the shift toward decentralized care. Improvements in caregiver training and home-based nursing support have enhanced treatment adherence. As payers emphasize value-based care, home-based models are integrated into long-term management plans. This trend is expected to accelerate, particularly in regions with aging populations and rising chronic disease burdens.
Regional Insights
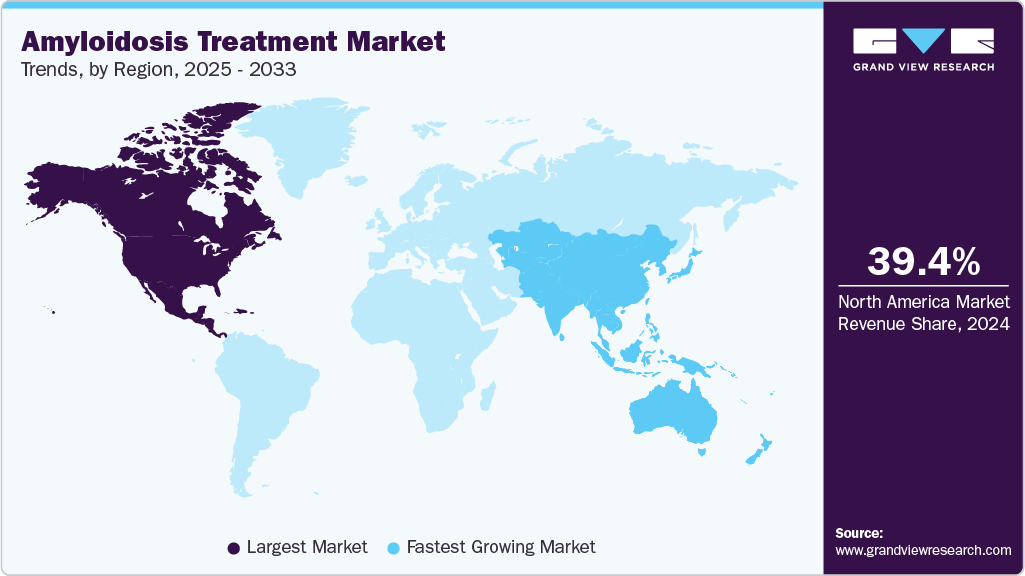
North America dominated the amyloidosis treatment market with the largest revenue share of 39.3% in 2025, due to advanced diagnostic capabilities and access to specialized care centers. The high prevalence of systemic and light-chain amyloidosis is accelerating early diagnosis and long-term management. Pharmaceutical companies in the region are actively investing in precision therapies and conducting multiple late-stage clinical trials. Improved patient awareness and high insurance coverage rates support wider adoption of advanced treatment options. Market players are benefiting from streamlined regulatory pathways, allowing faster drug approvals. Ongoing expansion of RNA-based and monoclonal antibody therapies further enhances the market landscape.
 To learn more about this report, Download Free Sample Report
U.S. Amyloidosis Treatment Market Trends
The amyloidosis treatment market in the U.S. held the largest share in the North America region in 2025, owing to its robust healthcare infrastructure and significant patient pool affected by hereditary and acquired forms of amyloidosis. The presence of major pharmaceutical firms such as Pfizer, Johnson & Johnson, and Alnylam enables faster commercial launch and patient outreach. Increasing clinical trial participation and academic collaboration encourage more rapid innovation in therapeutic approaches. Access to tertiary care centers and the use of advanced biomarkers contribute to early disease recognition. High treatment affordability due to widespread insurance coverage is improving access to novel therapies. Emerging RNA interference drugs are rapidly gaining traction in specialized care settings.
Europe Amyloidosis Treatment Market Trends
The amyloidosis treatment market in Europe is supported by rising clinical research and a growing base of treatment centers. Countries across the region are witnessing increased uptake of biologics and targeted agents for treating light-chain and transthyretin amyloidosis. Expanding diagnostic programs enables earlier identification of disease subtypes, leading to more precise interventions. The pharmaceutical ecosystem is strengthened by active participation in international clinical trials. Partnerships between regional hospitals and biotech firms accelerate access to advanced treatment protocols. Focusing on quality of life and outcome-based therapies guides long-term adoption trends.
The UK amyloidosis treatment market is driven by strong academic involvement and national health initiatives for rare disease management. Clinical experts are increasingly employing genetic testing and cardiac imaging for more accurate diagnosis of hereditary and wild-type ATTR. Local research centers like the National Amyloidosis Centre collaborate with global firms to support evidence-based treatment protocols. The growing adoption of tafamidis and RNA-targeted therapies is expanding patient therapeutic options. A well-organized referral system ensures timely specialist intervention and disease monitoring. Patient engagement initiatives are boosting trial enrollment and improving clinical awareness.
Germany is a key contributor to the European amyloidosis treatment market due to its advanced diagnostic infrastructure and strong focus on precision medicine. Regional hospitals are adopting integrated care models involving cardiologists, hematologists, and genetic counselors for better disease management. Pharmaceutical firms are introducing novel therapies through local partnerships and educational programs for clinicians. Rising awareness among primary care physicians enhances early-stage referrals and reduces diagnostic delays. The reimbursement environment supports the use of high-cost biologics and gene-silencing therapies. Innovation in imaging and laboratory testing facilitates broader disease stratification and treatment optimization.
The amyloidosis treatment market in France is witnessing steady growth as national research institutes and hospitals lead efforts in clinical innovation. Increasing diagnosis of transthyretin amyloidosis among older people is shaping demand for long-term therapy solutions. Collaboration with biotech companies is improving access to RNA-based and antibody-based therapeutics. Regional health networks are enhancing disease surveillance and expanding referral pathways for quicker patient onboarding. The development of multidisciplinary care centers is streamlining care delivery across regions. Focused physician education contributes to recognizing subtle disease symptoms in the early stages.
Asia Pacific Amyloidosis Treatment Market Trends
The amyloidosis treatment market in Asia Pacific is expected to register the fastest CAGR of 8.2% over the forecast period, due to growing healthcare infrastructure and a rising pool of undiagnosed patients. Expanding access to diagnostic tools such as mass spectrometry and cardiac MRI is increasing disease detection rates. Governments and private providers are enhancing specialty care access in urban and semi-urban areas. Local and international pharmaceutical firms are introducing therapies targeting both hereditary and age-related forms. Medical tourism is accelerating demand for advanced treatments among international patients. Educational programs raise awareness among primary care professionals about amyloidosis symptoms and treatment options.
Japan amyloidosis treatment market is growing as its aging population faces a higher incidence of wild-type ATTR and cardiac involvement. Healthcare institutions offer genetic counseling and biomarker testing to facilitate targeted therapy use. Domestic pharmaceutical companies are developing and marketing RNA-interference drugs and stabilizers with proven efficacy. Hospital networks are integrating care pathways for cardiology and neurology to manage complex cases efficiently. Clinical societies are setting diagnostic and treatment guidelines that align with international best practices. Government-certified centers of excellence are promoting consistency in diagnosis and long-term patient follow-up.
The amyloidosis treatment market in China is driven by higher disease awareness and healthcare modernization. Hospitals are adopting advanced pathology techniques and molecular diagnostics to improve case identification. Local biotech companies invest in innovative treatments and partner with global firms. Increasing access to tertiary care in metropolitan areas is facilitating specialized intervention. Clinical research is gaining momentum, supported by funding from private and academic sources. Demand for therapies targeting hereditary ATTR in regions with high genetic prevalence is rising.
Latin America Amyloidosis Treatment Market Trends
The amyloidosis treatment market in Latin America is growing due to expanding diagnostic capabilities and improved referral systems. Awareness campaigns and professional education are increasing the early identification of systemic amyloidosis subtypes. International collaborations are allowing faster entry of new therapies and diagnostics. Urban hospitals are starting to offer advanced care through integrated specialty clinics. Limited access in rural areas remains challenging, though mobile outreach and telemedicine are bridging gaps. Insurance penetration growth contributes to greater access to high-cost therapies across select urban markets.
Brazil amyloidosis treatment market is growing due to rising investments in rare disease research and a growing number of specialized clinics. The expansion of public-private collaborations facilitates early detection programs and patient registries. Physicians are increasingly trained in identifying multisystemic symptoms of amyloidosis, improving diagnosis accuracy. Novel therapies are entering the market through local distributors and clinical trial networks. Urban healthcare systems are leading the way in delivering complex treatment protocols involving monoclonal antibodies and gene therapies. Regional innovation hubs are supporting the development of local diagnostics and therapeutic solutions.
Middle East & Africa Amyloidosis Treatment Market Trends
The amyloidosis treatment market in the MEA region is fueled by increased investment in diagnostic capabilities and tertiary care. Countries are adopting teleconsultation platforms and centralized referral networks to support patient navigation. Multinational pharmaceutical firms are expanding operations in high-potential markets with unmet needs. Limited awareness is being addressed through targeted training programs for healthcare providers. Research centers in key regions are beginning to collaborate on rare disease identification and therapeutic innovation. Rising private healthcare expenditure is enabling more patients to access novel amyloidosis therapies.
Saudi Arabia amyloidosis treatment market is making notable progress by establishing rare disease programs in major hospitals. Advances in cardiac imaging and biopsy-based diagnostics enhance the detection of ATTR and AL amyloidosis. The country focuses on workforce training to build expertise in managing multisystemic disorders. Partnerships with global firms are facilitating access to innovative therapies and clinical trial opportunities. Demand is increasing for RNA-based therapies supported by rising diagnostic accuracy and patient education. Regional centers in the GCC region are evolving into referral hubs for amyloidosis care.
Key Amyloidosis Treatment Companies Insights
Key players operating in the amyloidosis treatment market are undertaking various initiatives to strengthen their presence and increase the reach of their products and services. Strategies such as expansion activities and partnerships are key in propelling the market growth.
Key Amyloidosis Treatment Companies:
The following are the leading companies in the amyloidosis treatment market.
- Johnson & Johnson Services, Inc.
- GSK plc
- Takeda Pharmaceutical Company Limited
- Amgen Inc.
- Bristol-Myers Squibb Company
- Novartis AG
- F. Hoffmann-La Roche Ltd
- Merck KGaA
- Sanofi
- Alnylam Pharmaceuticals, Inc.
Competitive Benchmarking
Category
Operating Strategies
Competitive Edge
Weakness
Established Players (Pfizer Inc., Johnson & Johnson Services, Inc., Takeda Pharmaceutical Company Limited, Bristol-Myers Squibb Company, Novartis AG, F. Hoffmann-La Roche Ltd, Merck KGaA, Sanofi)
- Focus on expanding rare disease and hematology portfolios through strategic acquisitions, clinical development programs, lifecycle management, and global commercialization initiatives. Invest in advanced biologics, targeted therapies, and combination treatment approaches for amyloidosis and related disorders. Strengthen partnerships with healthcare providers, research institutions, and patient advocacy groups to improve disease awareness and treatment access.
- Strong global presence with extensive commercial infrastructure, established regulatory expertise, and significant research and development capabilities. Broad therapeutic portfolios and established relationships with healthcare systems enable rapid market access and large scale commercialization.
- High research and development costs associated with rare disease drug development and long clinical trial timelines. Large organizational structures can limit operational flexibility and slow decision making compared with specialized biotechnology companies.
Specialized Rare Disease and Innovation Focused Players (Alnylam Pharmaceuticals, Inc., Amgen Inc., GSK plc)
- Focus on developing targeted therapies based on RNA interference, biologics, and precision medicine approaches to address underlying disease mechanisms. Emphasize pipeline expansion through clinical research, strategic collaborations, and investment in next generation therapeutic platforms. Target high unmet need patient populations through specialized treatment offerings and disease awareness initiatives.
- Strong scientific expertise in innovative therapeutic modalities and ability to develop differentiated treatments addressing specific amyloidosis subtypes. Agile development strategies and focused research programs support faster innovation in niche disease segments.
- Dependence on a limited number of commercial products and pipeline assets increases exposure to clinical, regulatory, and commercialization risks. Smaller commercial footprints in certain regions may limit market penetration compared with diversified pharmaceutical companies.
Recent Developments
-
In June 2025, Alnylam Pharmaceuticals secured European Commission approval for AMVUTTRA (vutrisiran) for the treatment of adult patients with both hereditary and wild-type ATTR amyloidosis with cardiomyopathy. This decision followed results from the HELIOS-B Phase 3 study, which demonstrated notable reductions in overall mortality and repeated cardiovascular complications.
-
In May 2025, Johnson & Johnson reported that JNJ‑79635322 achieved an 86.1% overall response rate in a Phase 1 trial (NCT05652335) among 36 heavily pretreated patients, including 100% ORR in BCMA/GPRC5D‑naïve cases. The trispecific antibody showed a manageable safety profile with no Grade 3+ cytokine release or oral toxicities at the recommended dose.
-
In January 2024, Ultromics partnered with Pfizer to accelerate the development and FDA clearance of EchoGo Amyloidosis, an AI tool that uses a single echocardiogram view to detect cardiac amyloidosis early. The algorithm, granted Breakthrough Device Designation, aims to support faster diagnosis and earlier treatment initiation in clinical practice.
Amyloidosis Treatment Market Report Scope
Report Attribute
Details
Market size in 2025
USD 6.2 billion
Estimated market size in 2026
USD 6.6 billion
Projected market size by 2033
USD 10.9 billion
Growth rate
CAGR of 7.4% from 2026 to 2033
Historical data
2021 - 2024
Forecast period
2026 - 2033
Quantitative units
Revenue in USD million/billion and CAGR from 2026 to 2033
Report coverage
Revenue forecast, company ranking, competitive landscape, growth factors, and trends
Segments covered
Treatment, end use, region
Regional scope
North America; Europe; Asia Pacific; Latin America; MEA
Country scope
U.S.; Canada; Mexico; UK; Germany; France; Italy; Spain; Denmark; Norway; Sweden; Japan; China; India; South Korea; Australia; Thailand; Brazil; Argentina; South Africa; Saudi Arabia; UAE; Kuwait.
Key companies profiled
Pfizer Inc.; Johnson & Johnson Services, Inc.; GSK plc; Takeda Pharmaceutical Company Limited; Amgen Inc.; Bristol-Myers Squibb Company; Novartis AG; F. Hoffmann-La Roche Ltd; Merck KGaA; Sanofi; Alnylam Pharmaceuticals, Inc.
Customization scope
Free report customization (equivalent up to 8 analysts' working days) with purchase. Addition or alteration to country, regional & segment scope.
Pricing and purchase options
Avail customized purchase options to meet your exact research needs. Explore purchase options
Global Amyloidosis Treatment Market Report Segmentation
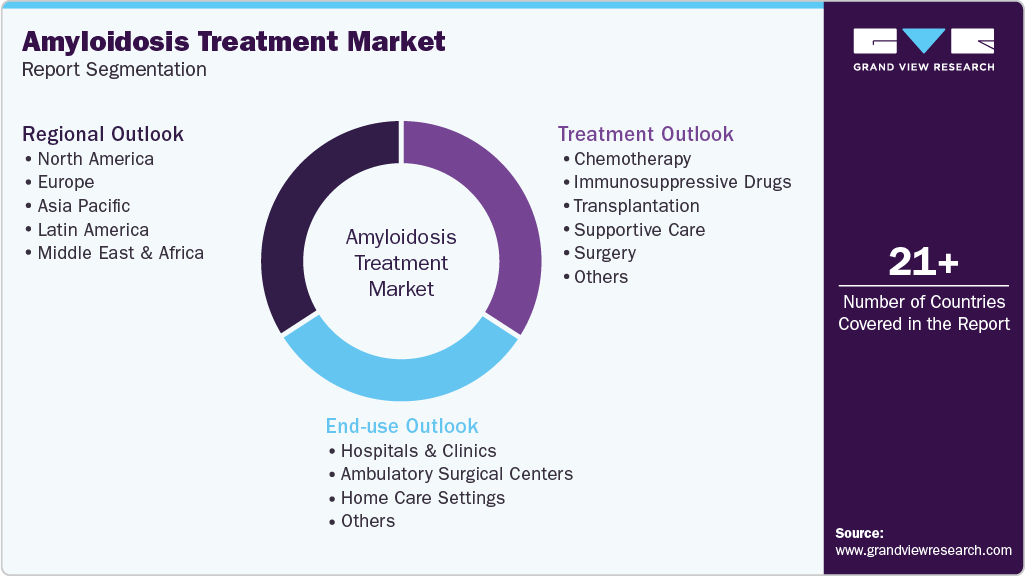
This report forecasts revenue growth at global, regional, and country levels and provides an analysis of the latest industry trends in each of the sub-segments from 2021 to 2033. For this study, Grand View Research has segmented the global amyloidosis treatment market report based on treatment, end-use, and region:
 To learn more about this report, Download Free Sample Report
-
Treatment Outlook (Revenue, USD Million, 2021 - 2033)
-
Chemotherapy
-
Immunosuppressive Drugs
-
Transplantation
-
Supportive Care
-
Surgery
-
Others
-
-
End Use Outlook (Revenue, USD Million, 2021 - 2033)
-
Hospitals & Clinics
-
Ambulatory Surgical Centers
-
Home Care Settings
-
Others
-
-
Regional Outlook (Revenue, USD Million, 2021 - 2033)
-
North America
-
U.S.
-
Canada
-
Mexico
-
-
Europe
-
UK
-
Germany
-
France
-
Italy
-
Spain
-
Denmark
-
Sweden
-
Norway
-
-
Asia Pacific
-
Japan
-
China
-
India
-
Australia
-
South Korea
-
Thailand
-
-
Latin America
-
Brazil
-
Argentina
-
-
Middle East & Africa
-
South Africa
-
Saudi Arabia
-
UAE
-
Kuwait
-
-
Research Methodology
The amyloidosis treatment market figures in this report are based on a proven research process that combines executive interviews with secondary research from proprietary databases, company filings, and recognized regulatory and institutional sources. Market size is built through value-chain sizing - reconciling supply-side and demand-side estimates - and triangulated with bottom-up and top-down approaches. Every estimate passes multiple levels of expert validation before publication, with each amyloidosis treatment segment quantified using the revenue-capture definitions in the table below.
Segment Definition
Segment - Treatment
Revenue capture definition
Chemotherapy
Includes drug therapies used to suppress or eliminate abnormal plasma cells responsible for producing amyloid forming light chains, primarily in AL amyloidosis. This segment covers alkylating agents, proteasome inhibitors, immunomodulatory drugs, corticosteroid based regimens, and combination chemotherapy protocols. Revenue is derived from the sale and administration of chemotherapy drugs only and excludes immunosuppressive therapies, transplantation procedures, supportive care medications, and surgical interventions.
Immunosuppressive Drugs
Includes pharmacological therapies used to control underlying inflammatory or autoimmune conditions associated with secondary amyloidosis (AA amyloidosis). This segment covers biologics, anti-inflammatory agents, disease modifying therapies, and immunosuppressive medications intended to reduce the production of amyloid precursor proteins. Revenue is generated from the sale of immunosuppressive agents and excludes chemotherapy drugs, transplantation procedures, supportive care therapies, and surgical treatments.
Transplantation
Includes therapeutic procedures involving organ transplantation or autologous stem cell transplantation performed to treat advanced amyloidosis or restore organ function affected by amyloid deposition. This segment covers liver, kidney, heart, and stem cell transplantation related treatment revenue. It excludes pharmaceutical therapies, supportive care management, and non transplant surgical procedures.
Supportive Care
Includes treatments aimed at managing symptoms and complications associated with amyloidosis without directly targeting the underlying disease process. This segment covers cardiovascular medications, diuretics, pain management therapies, nutritional support, renal management therapies, and other symptom control interventions. Revenue is generated from supportive care products and services and excludes disease modifying therapies, transplantation, and surgery.
Surgery
Includes operative procedures performed to manage localized amyloid deposits or disease related complications that do not involve organ transplantation. This segment covers procedures such as carpal tunnel release, gastrointestinal surgeries, orthopedic interventions, and other corrective surgical treatments. Revenue includes procedure related services and excludes transplantation and pharmaceutical therapies.
Others
Includes disease modifying therapies that do not fall under chemotherapy or immunosuppressive drugs. This segment primarily covers transthyretin stabilizers, RNA interference therapies, antisense oligonucleotide therapies, monoclonal antibodies, gene based therapies, and other emerging targeted treatments used for ATTR amyloidosis and other amyloid disorders. Revenue is generated from the sale and administration of these therapies and excludes products accounted for in other treatment segments.
Segment – End Use
Revenue capture definition
Hospitals & Clinics
Includes healthcare facilities that provide diagnosis, treatment administration, transplantation procedures, inpatient care, outpatient care, and long term management of amyloidosis patients. Revenue is attributed to therapies and services delivered within hospitals, specialty clinics, and physician practices.
Ambulatory Surgical Centers
Includes outpatient facilities that perform surgical and procedural interventions related to amyloidosis treatment without requiring extended hospitalization. Revenue includes procedure related treatment services provided in ambulatory care settings.
Home Care Settings
Includes treatment administration, monitoring, and supportive care delivered in patients' homes. This segment covers home infusion services, home nursing care, remote monitoring, and self administered therapies supplied for home use.
Others
Includes all remaining treatment settings not classified under hospitals and clinics, ambulatory surgical centers, or home care settings. This segment may include rehabilitation centers, long term care facilities, research institutions, and specialty treatment centers.
Estimation Model
Based on the patient pool methodology shown in the image, the Amyloidosis Treatment Market can be estimated by first identifying the country-wise population and determining the prevalence and incidence of amyloidosis, including major subtypes such as transthyretin amyloidosis (ATTR) and light-chain (AL) amyloidosis. The total patient pool is then narrowed down to the diagnosed patient population using diagnosis rates obtained from epidemiological studies, healthcare databases, and expert opinions. Existing treatment penetration and patient uptake rates are analyzed to estimate the number of patients receiving therapy across hospitals, specialty clinics, and treatment centers in each region.
The market size is subsequently calculated by multiplying the treated patient pool by the average annual cost of amyloidosis treatment, including drug costs, monitoring expenses, and supportive care costs. Revenue estimates are generated at the country level and aggregated to regional and global levels. The final market valuation is validated through primary interviews with hematologists, cardiologists, healthcare providers, and pharmaceutical industry experts, while data triangulation and sensitivity analyses ensure the accuracy of the market estimates and forecasts.
Delivered Customizations
This report has been delivered with the following In-depth customizations
Client Request
Customization Delivered
Value Adds
ATTR Amyloidosis Treatment Adoption Analysis
Assessment of prescribing and utilization trends across transthyretin stabilizers, RNA interference therapies, antisense oligonucleotides, and emerging disease modifying treatments for ATTR amyloidosis across different patient populations and healthcare settings.
Helps identify treatment adoption patterns, prescribing preferences, and opportunities for market expansion across approved and emerging therapies.
AL Amyloidosis Treatment and Unmet Needs Assessment
Analysis of treatment pathways, disease burden, diagnostic delays, and unmet clinical needs among patients with AL amyloidosis, including the use of chemotherapy, stem cell transplantation, and emerging targeted therapies.
Supports identification of treatment gaps, underserved patient populations, and areas for future therapeutic development.
Emerging Therapy and Pipeline Assessment
Evaluation of pipeline candidates, novel therapeutic approaches, clinical development progress, regulatory milestones, and potential impact on existing amyloidosis treatment classes.
Provides insights into future treatment trends, competitive dynamics, and potential areas of market growth.
Patient Identification and Disease Management Analysis
Assessment of diagnosis pathways, referral patterns, screening practices, and treatment management approaches across ATTR and AL amyloidosis patient populations.
Helps identify barriers to diagnosis, opportunities for earlier patient identification, and strategies to improve treatment uptake.
Competitive Benchmarking and Portfolio Analysis
Comparative assessment of approved products, pipeline assets, clinical evidence, commercialization activities, strategic partnerships, and market positioning of leading amyloidosis treatment companies.
Supports competitive intelligence, portfolio evaluation, partnership assessment, and market positioning decisions.
Frequently Asked Questions About This Report
Some key players operating in the amyloidosis treatment market include Pfizer Inc., Johnson & Johnson, Services, Inc., GSK plc, Takeda Pharmaceutical Company Limited, Amgen Inc., Bristol-Myers Squibb Company, Novartis AG, F. Hoffmann-La Roche Ltd, Merck KGaA, Sanofi, Alnylam Pharmaceuticals, Inc.
Key factors that are driving market growth include innovations such as advanced imaging, mass spectrometry, and genetic testing allowing healthcare providers to better distinguish between amyloidosis subtypes, supporting more precise and effective treatment approaches.
North America dominated the amyloidosis treatment market with the largest revenue share of 39.3% in 2025.
Based on end use, the hospitals & clinics segment led the market with the largest revenue share of 49.3% in 2025.
Asia Pacific is the fastest-growing region over the forecast period.
The global amyloidosis treatment market is projected to grow at a CAGR of 7.4% from 2026 to 2033 to reach USD 10.9 billion by 2033.
Based on treatment, the chemotherapy segment led the market with the largest revenue share of 26.5% in 2025.
The global amyloidosis treatment market size was estimated at USD 6.2 billion in 2025 and is projected to grow to USD 6.6 billion in 2026.
About the Author(s)
Pharmaceuticals Research Team
Healthcare · PharmaceuticalsThis report was authored by the pharmaceuticals research team at Grand View Research - comprising two research analysts, one senior research analyst, and one industry expert - with specialized expertise in the pharmaceuticals segment of the healthcare industry. All findings are based on proprietary healthcare databases, executive interviews, and regulatory analysis, subject to internal peer review prior to publication.
Last Updated:
Speak to Analyst

Customize this report to your needs - add regions, segments, or data points, with 20% free customization.
Or view our licence options:


ISO 9001:2015 & 27001:2022 Certified
We are GDPR and CCPA compliant! Your transaction & personal information is safe and secure. For more details, please read our privacy policy.


