
- Home
- »
- Animal Health
- »
-
Animal Ultrasound Market Size, Share & Trends Report 2033GVR Report cover

Animal Ultrasound Market (2026 - 2033)
Size, Share & Trends Analysis Report By Solution (Equipment, Accessories/Consumables, PACS), By Animal (Small, Large), By Type, By Technology, By Application, By End-use, By Region, And Segment Forecasts
Market Size, 2025
$539.4MMarket Estimate, 2026
$575.7MMarket Forecast, 2033
$998.8MCAGR, 2026–2033
8.2%Animal Ultrasound Market Summary
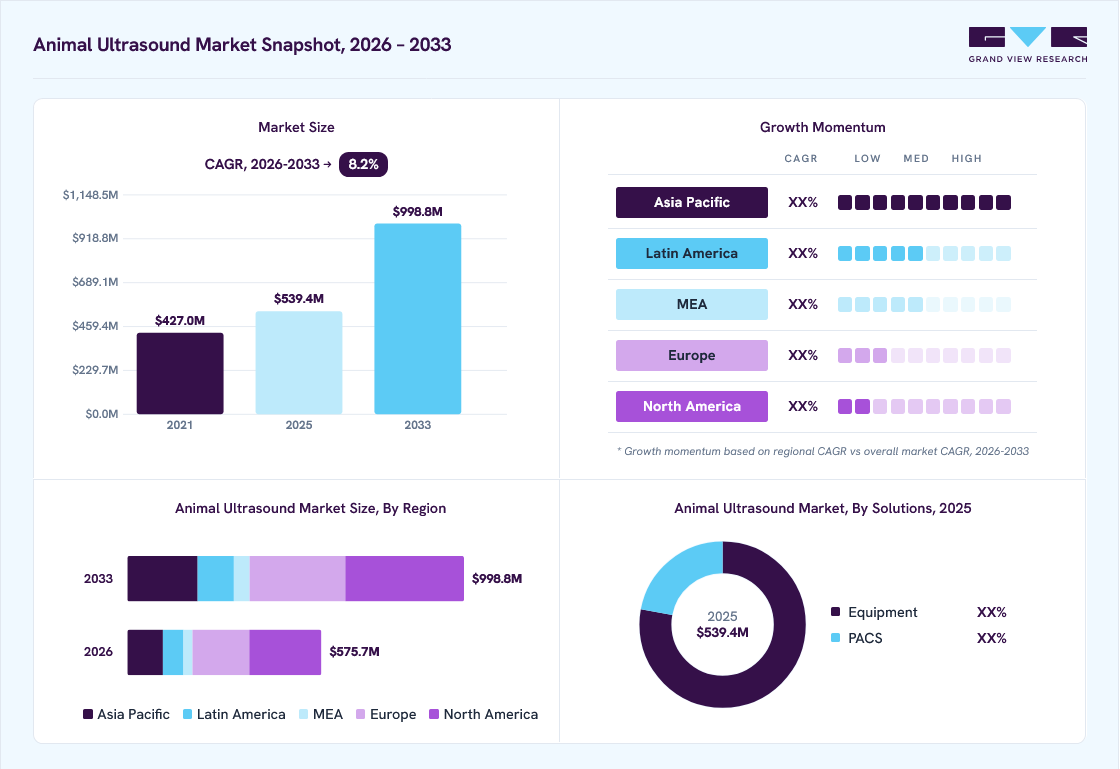
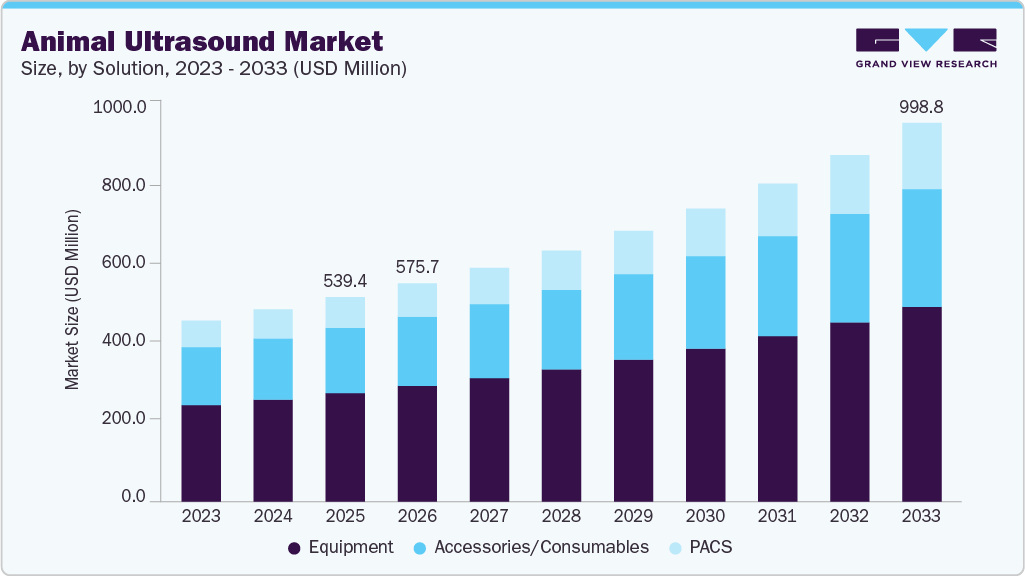
The global animal ultrasound market size was valued at USD 539.4 million in 2025 and is projected to grow from USD 575.7 million in 2026 to USD 998.8 million by 2033, at a CAGR of 8.2% from 2026 to 2033. North America dominated the market, accounting for a revenue share of 37.3% in 2025. Some of the key factors driving market growth are growing research initiatives & breakthroughs, expanding applications of ultrasound in the veterinary sector, rising adoption of pet insurance, and increasing critical collaboration in the industry.
 Source: Grand View Research, IR Documents, Primary Interviews, Paid DatabasesTo learn more about this report,
 Download Free Sample Report
Key Market Trends & Insights
- By animal: Small animals held the largest share of 61.5% of the market in 2025.
- By solution: Equipment segment held the largest share in 2025.
- By type: 2-D ultrasound imaging segment led the market with the largest revenue share of 50.7% in 2025.
- By technology: Digital imaging segment led the market with the largest revenue share of 69.2% in 2025.
- By application: Abdominal segment led the market with the largest revenue share of 30.3% in 2025.
- By end use: Veterinary hospitals & clinics segment led the market with the largest revenue share of 65.1% in 2025.
Regional Highlights
- Largest regional market: North America (37.3% revenue share, 2025)
- Fastest-growing regional market: Asia Pacific (highest CAGR, 2026-2033)
- By country: The U.S. held the largest market share in 2025.
Market Size & Forecast
- Market size in 2025: USD 539.4 Million
- Estimated market size in 2026: USD 575.7 Million
- Projected market size by 2033: USD 998.8 Million
- CAGR (2026-2033): 8.2%
Prism AI by Grand View Research Free to tryAsk a question about the animal ultrasound marketTry asking✓Every figure cited from GVR research Prefer the report? Download free sample →Growing research initiatives and technological breakthroughs are significantly accelerating the market by enhancing diagnostic precision, expanding therapeutic applications, and supporting wider clinical adoption. Increasing R&D investment by universities, veterinary institutes, and animal health companies is leading to innovations that make ultrasound systems more accurate, portable, and cost-efficient. A major advancement is the rapid adoption of focused ultrasound (FUS), which extends ultrasound use beyond diagnostics into noninvasive therapeutic procedures. FUS shows strong potential in oncology, pain management, soft-tissue repair, neuromodulation, and metabolic diseases, driving demand for advanced systems capable of high-energy, image-guided interventions. As research transitions into routine practice, veterinary hospitals increasingly invest in upgraded ultrasound platforms, training, and workflow integration.
 To learn more about this report, Download Free Sample Report
In addition, the expanding use of ultrasound across all tiers of veterinary practice is a major growth catalyst, signaling its transition from a specialized tool to a standard diagnostic modality. More than half of clinics now own ultrasound systems, and routine use for abdominal pain, respiratory issues, reproductive monitoring, and emergency triage is rising steadily. This shift drives recurring demand for upgraded hardware, software enhancements, and practitioner training. Clinical applications are diversifying beyond abdominal and thoracic imaging into cardiology, oncology, musculoskeletal injuries, and point-of-care emergency diagnostics. As ultrasound becomes integral to general practice and specialty care workflows, it boosts recurring revenue from device purchases, service contracts, consumables, and education programs, expanding long-term market adoption.
Moreover, rising pet insurance adoption is reducing the financial barriers associated with advanced diagnostics, significantly increasing the utilization of ultrasound in veterinary practices. For instance, the North American Pet Health Insurance Association, Inc. reported in April 2025 that an estimated 7.03 million pets in North America were insured in 2024, demonstrating strong growth in policy enrollment and reflecting a broader willingness among owners to financially safeguard their animals’ health. Some of the providers such as Embrace and Wagmo routinely cover medically necessary imaging, enabling earlier diagnosis of chronic and acute conditions. This trend supports preventative care, improves treatment decision-making, and expands demand for high-quality ultrasound systems across general practices, specialty centers, and emergency hospitals.
 To learn more about this report, Download Free Sample Report
Furthermore, growing collaboration among veterinary hospitals, research institutions, and imaging technology manufacturers is strengthening innovation and accelerating clinical adoption within the veterinary ultrasound market. For instance, in August 2025, Probo Veterinary collaborated with Improve Veterinary Education and Mindray Animal Medical to support veterinarians seeking advanced ultrasound training by providing Mindray Vetus Ultrasound Systems for Improve Veterinary Education’s renowned imaging courses. Similarly, in August 2025, Esaote North America and Epica International partnered to collaboratively broaden their imaging portfolios in both human and veterinary healthcare, spanning MRI, ultrasound, and CT technologies. These collaborations support joint product development, accelerate technology dissemination, and reinforce market competitiveness, ultimately increasing demand for sophisticated imaging platforms and strengthening overall ultrasound adoption across veterinary settings.
Market Dynamics
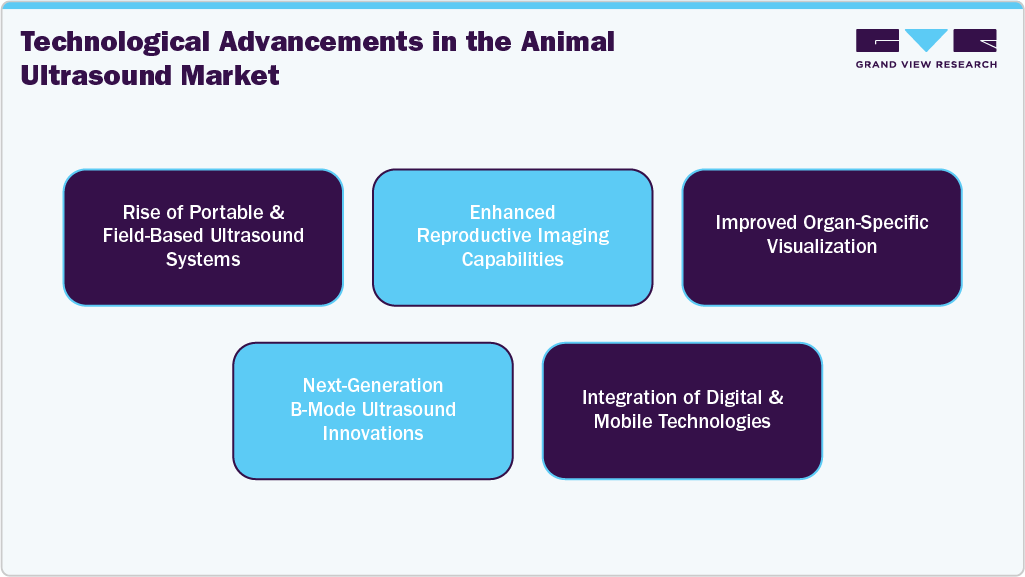
The animal ultrasound market is experiencing steady growth, driven by increasing research initiatives and technological breakthroughs that continue to improve imaging quality, portability, and diagnostic accuracy. A major advancement is the rapid adoption of focused ultrasound (FUS), which extends ultrasound use beyond diagnostics into noninvasive therapeutic procedures. FUS shows strong potential in oncology, pain management, soft-tissue repair, neuromodulation, and metabolic diseases, driving demand for advanced systems capable of high-energy, image-guided interventions. In addition, expanding applications of ultrasound across companion animals, livestock, equine practice, reproduction management, cardiology, abdominal imaging, musculoskeletal assessment, and emergency care are key factors accelerating the market demand.
The market is also witnessing rising pet ownership and expenditure on animal healthcare that encourage veterinarians to adopt advanced, non-invasive diagnostic technologies for faster and more accurate clinical decision-making. In addition, increasing adoption of pet insurance is improving owners' ability to afford advanced diagnostic procedures, supporting greater utilization of ultrasound services. Furthermore, strategic collaborations among ultrasound manufacturers, veterinary hospitals, research institutions, universities, and technology companies are fostering innovation, accelerating product development, and expanding commercial reach. The growing availability of portable and point-of-care ultrasound systems, combined with increasing awareness of preventive animal healthcare and early disease detection, is expected to further strengthen market growth throughout the forecast period.
The increasing utilization of ultrasound across all tiers of veterinary practice is a major contributor to market growth as it demonstrates that imaging is becoming a standard of care rather than a specialized or optional service. For instance, according to an article published by GE HealthCare in February 2025, more than half of veterinary clinics are now equipped with ultrasound systems, and 45.0% conduct at least five exams weekly. This indicates that adoption is transitioning from early-use phases to widespread clinical integration. As general practitioners, emergency veterinarians, and specialty clinicians rely on ultrasound for routine diagnosis, the need for upgraded systems, software enhancements, and ongoing training increases, driving sustained demand. High-frequency use in everyday cases, such as abdominal pain, respiratory distress, and reproductive monitoring, encourages clinics to invest in both cart-based and portable/handheld devices, thereby expanding revenue opportunities for manufacturers and service providers. Furthermore, integration with artificial intelligence and cloud-based imaging platforms enhances diagnostic accuracy, workflow efficiency, and remote consultation capabilities, encouraging broader adoption across both companion animal and production animal healthcare settings.
Regulatory complexities can substantially hinder the expansion of the animal ultrasound industry, as they often lead to prolonged product approval timelines, higher compliance expenses, and restricted entry for emerging technologies. Across many countries, veterinary ultrasound systems must comply with rigorous safety, performance, and quality standards before they are permitted for clinical use. When approval pathways are lengthy, unclear, or differ widely between regions, manufacturers may delay or reconsider launching innovative ultrasound solutions such as portable, AI-enabled, or advanced Doppler systems, especially in markets with fragmented regulatory oversight. In several Latin American jurisdictions, for instance, obtaining certification for veterinary imaging equipment may take many months or even years, which slows the availability of improved diagnostic tools despite growing clinical needs in small-animal and livestock healthcare.
The growing adoption of ultrasonography (USG) across diverse animal species, including domestic animals, livestock, exotic species, and wildlife, is creating significant growth opportunities in the veterinary ultrasound industry. As highlighted by the Veterinary Officer Department of Wildlife Protection, Kashmir, India, ultrasonography is a non-invasive and radiation-free imaging modality that enables accurate detection of soft-tissue abnormalities, foreign bodies, reproductive disorders, tumors, glaucoma, and organ-related conditions. Its increasing use in veterinary hospitals, wildlife rehabilitation centers, and zoological facilities is driven by its ability to support safe and effective diagnosis while also guiding minimally invasive procedures such as biopsies and fluid aspiration. Furthermore, the rising demand for advanced diagnostic imaging in wildlife healthcare, where complex injuries and radiolucent foreign bodies are frequently encountered, is accelerating the need for portable and field-deployable ultrasound systems.
Increasing operational expenses and inflationary pressures are significantly influencing pet owners’ perception of veterinary care costs. While the veterinary industry has witnessed substantial advancements in diagnostic technologies, including advanced imaging systems and highly accurate laboratory testing, the adoption of these innovations involves considerable capital investment, ongoing maintenance costs, and specialized workforce training. As veterinary clinics continue to integrate these technologies to enhance clinical outcomes and maintain competitive positioning, the overall cost of services has increased. However, several pet owners remain hesitant to accept higher treatment and diagnostic expenses, often examining the value proposition of advanced veterinary procedures. This growing affordability concern may limit the adoption of recommended diagnostics and impact market growth.
Market Concentration & Characteristics
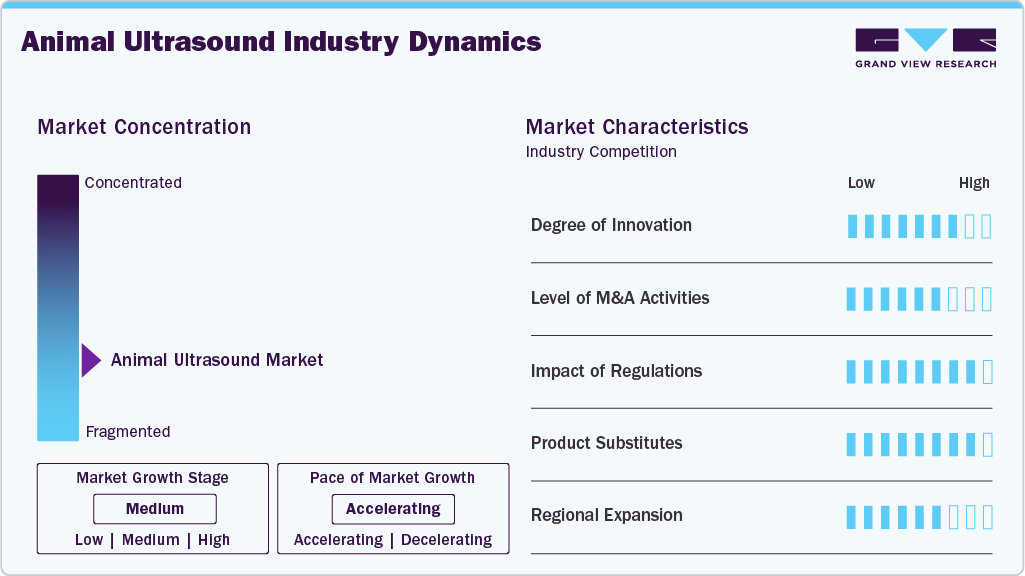
The industry is at a moderate growth stage, and the pace is accelerating. The market is dominated by established players such as Fujifilm American Holdings Corporation, Mindray, Esaote, and IMV Imaging. These companies control advanced technology, global distribution, and training networks. However, rising demand for portable and affordable systems is enabling new entrants to gain traction, gradually increasing competitive diversity.
The market is driven by rapid innovation, particularly in portable, wireless, and AI-enhanced imaging technologies. Some of the advancements such as high-resolution probes, 3D/4D imaging, focused ultrasound therapeutics, and cloud-based diagnostics are transforming veterinary workflows. For instance, in October 2025, Butterfly launched the next-generation iQ3 Vet, built on P4.3 Ultrasound-on-Chip technology with faster data transfer, enhanced imaging, and ergonomic design, expanding advanced POCUS capabilities in the U.S. and Canada.
 To learn more about this report, Download Free Sample Report
The market is experiencing moderate but steadily increasing mergers and acquisitions as leading imaging companies seek to expand their veterinary portfolios. Acquisitions and strategic partnerships such as collaborations between ultrasound manufacturers, veterinary hospital groups, and training institutions help accelerate technology integration, expand product lines, and strengthen regional presence. For instance, in March 2024, Mars completed acquiring Cerba HealthCare’s stakes in Cerba Vet and ANTAGENE, strengthening its Science & Diagnostics division with expanded veterinary diagnostic and genetic testing capabilities across the French market.
Regulations impact the veterinary ultrasound industry primarily through device safety standards, veterinary practice guidelines, and import/export controls. Compliance with FDA, CE, and regional veterinary regulations ensures product quality and clinical reliability.
Product substitutes in the market include X-ray, CT, and MRI serve as diagnostic alternatives but ultrasound remains uniquely positioned due to its noninvasive nature, affordability, portability, and real-time imaging capabilities. Substitution risk is low in routine diagnostics and reproductive care but moderate in advanced orthopedic or neurological cases where CT/MRI may be preferred.
Regional expansion is accelerating as rising pet ownership, livestock health investments, and improving veterinary infrastructure boost demand for diagnostic imaging. North America and Europe remain mature markets, while Asia Pacific, Latin America, and the Middle East show significant growth potential.
Analyst Perspective
The animal ultrasound market is witnessing robust growth, fueled by rising pet ownership, growing livestock health management needs, and increasing awareness of early disease detection in veterinary care. In addition, ultrasound imaging has become indispensable for diagnosing pregnancy, abdominal disorders, cardiac conditions, and musculoskeletal injuries in companion animals, livestock, and equine species, owing to its non-invasive nature and real-time diagnostic capability. In addition, technological advancements, including portable and handheld ultrasound devices, wireless connectivity, and AI-integrated imaging software, are enhancing point-of-care diagnostics, particularly benefiting large-animal practitioners and field veterinarians working in remote or rural settings.
Furthermore, growing investments in animal healthcare infrastructure, expanding veterinary clinics, and increasing disposable income supporting elective diagnostic procedures are propelling market expansion. In addition, rising incidence of zoonotic diseases and stringent food safety regulations are boosting ultrasound adoption in livestock monitoring and breeding programs. Key players are focusing on product miniaturization, improved image resolution, and affordability to penetrate emerging markets, while strategic collaborations and acquisitions continue to intensify competition, driving innovation across this evolving veterinary diagnostic imaging segment.
Solution Insights
Based on solution, the equipment segment led the market with the largest revenue share of 53.0% in 2025. Console/cart-based ultrasound and portable/handheld ultrasound solutions are included in this segment. The segment is driven by its universal use across companion animals, livestock, and exotic species. Its noninvasive, cost-effective, and versatile capabilities enable real-time imaging for abdominal, cardiac, reproductive, and emergency diagnostics, making it standard in clinics, hospitals, and field settings. Continuous use in small-animal practices and livestock breeding further sustains demand. Some of the technological advancements also support growth. For instance, in December 2024, Allambie Vet introduced an advanced ultrasound system offering clearer imaging and faster diagnostics, whereas in May 2024, Esaote North America launched the MyLab FOX, featuring next-generation probes and enhanced connectivity to improve productivity across varied veterinary environments.
The PACS segment is projected to grow at the fastest CAGR from 2026 to 2033. The market’s growth is boosted as veterinary practices shift to fully digital imaging workflows. PACS software allows seamless storage, retrieval, and sharing of ultrasound images across devices, enabling instant access, comparison with past scans, and efficient collaboration through teleradiology. In addition, demand is rising as modern systems such as Butterfly iQ3 Vet, Clarius HD3 Vet, and Esaote MyLab FOX generate large, high-resolution files that require secure, centralized storage. Furthermore, cloud-based PACS lets veterinarians upload images directly from devices and review them anywhere. IMV Imaging further supports this shift by integrating specialized PACS with its equine and companion-animal ultrasound platforms for streamlined image management.
Animal Insights
Based on animal, the small animals segment led the market with the largest revenue share of 61.5% in 2025 and are expected to grow at the fastest rate over the forecast period. The market is advancing due to rising pet ownership, growing insurance uptake, and increased veterinary spending. For instance, according to the American Pet Products Association's 2024-2025 National Pet Owners Survey, 66% of American homes, or about 94 million families, own a pet. Small-animal ultrasound has become a daily diagnostic tool, with a 2024 survey of 1,216 veterinarians showing 84% have an ultrasound unit and most use it several times weekly. Besides this, common applications such as cystocentesis, pregnancy checks, and abdominal or thoracic scans are considered essential in general and emergency care. In addition, clinics are widely adopting devices from handheld Butterfly iQ+ Vet to advanced GE Logiq S8 systems, fueling the segment’s leading market share.
The large animals segment is expected to show significant growth during the forecast period, driven by rising demand for advanced, portable imaging in equine sports medicine and livestock fertility management. In addition, performance horses rely on high-resolution musculoskeletal ultrasound for tendon and ligament assessment, supported by technologies like Samsung’s MV-Flow and S-Shearwave Imaging. Moreover, livestock growth and herd-health pressures are boosting the adoption of ultrasound for early disease detection and reproductive monitoring. Innovation is accelerating this shift; for example, IMV Technologies’ BovIntel software, launched in 2024, automates bovine reproductive imaging and improves fertility precision, expanding usage of systems like Easi-Scan: Go and strengthening technology-driven herd management.
Type Insights
Based on type, the 2-D ultrasound imaging segment led the market with the largest revenue share of 50.7% in 2025, as it provides clear, real-time grayscale imaging for pregnancy checks, abdominal and thoracic evaluations, cardiac exams, biopsies, and musculoskeletal assessments across companion animals, livestock, and equine patients. Its affordability, reliability, and universal applicability make it the default tool in clinics and field settings. The market is witnessing continuous improvements in imaging, such as higher spatial resolution, harmonic imaging, speckle reduction, and AI-based optimization that further enhance diagnostic quality, keeping systems simple to use. Most leading platforms, from GE Logiq consoles to Butterfly iQ3 Vet and IMV Easi-Scan, are built around advanced 2-D capabilities, reinforcing its dominant market position.
3-D/4-D ultrasound imaging is projected to grow at the fastest CAGR during the forecast period. These systems use high-density volumetric transducers, far more expensive than standard probes, making them suitable mainly for academic or research settings. Current veterinary use focuses on specialized applications such as fetal morphology assessment, viability evaluation, and structural characterization. Although studies like Hildebrandt et al. (2009) show potential benefits, 3-D imaging requires several seconds of motion-free acquisition, often unrealistic without sedation. Moreover, high cost, longer scan times, and workflow constraints continue to limit widespread adoption in everyday veterinary practice.
Technology Insights
Based on technology, the digital imaging segment led the market with the largest revenue share of 69.2% in 2025, as it offers superior resolution, faster processing, and seamless data management compared to analog systems. Fully digital platforms provide enhanced clarity through harmonic imaging, speckle reduction, and automated optimization, improving diagnostic accuracy in cardiology, abdominal scans, reproduction, and musculoskeletal assessments. These systems also support advanced features such as color doppler, elastography, and 3-D/4-D imaging, making them essential across small-animal, equine, and livestock care. Furthermore, modern systems such as GE LOGIQ V2 Vet and Mindray Vetus series use digital beamforming to deliver sharper visualization of fine structures. Innovation continues to fuel adoption, for instance, Butterfly Network’s iQ3 Vet, launched in October 2025, delivers cart-level digital imaging in a handheld probe, reinforcing the shift toward portable, chip-based ultrasound solutions.
The contrast imaging segment is expanding rapidly as veterinary professionals adopt contrast-enhanced ultrasound (CEUS) for early, accurate diagnosis of complex conditions in small animals. CEUS uses microbubble agents to improve visualization of tissue perfusion and vascularity, allowing detection of lesions that are often missed on standard B-mode or Doppler scans. In addition, CEUS helps differentiate benign and malignant masses without requiring CT or MRI, reducing cost and anesthesia risks. Its growing use in abdominal imaging, cardiology, oncology, and emergency care, along with improved CEUS-enabled systems and contrast agents, is accelerating clinical adoption and market growth.
Application Insights
Based on application, the abdominal segment led the market with the largest revenue share of 30.3% in 2025, because abdominal diseases are among the most frequent and clinically significant issues in pets. Conditions such as vomiting, diarrhea, urinary problems, and weight loss commonly require abdominal imaging to identify causes like GI obstructions, liver and kidney disease, pancreatitis, or bladder stones. Since many abnormalities cannot be detected through exams or X-rays alone, ultrasound provides essential real-time clarity. Its broad utility across species and age groups, detecting tumors, blockages, congenital issues, and organ dysfunction, strengthens its dominance. Veterinary clinics, such as Crystal Creek Animal Hospital, rely on abdominal ultrasound daily to assess key organs, underscoring its importance in routine diagnostics.
The oncology segment is growing steadily due to the rising incidence of cancer in companion animals and the essential role of ultrasound in early detection. Cancer is affecting millions of pets annually, one in four dogs and one in five cats. Veterinarians rely on ultrasound to identify internal tumors, cysts, metastases, and organ abnormalities. It provides a noninvasive, real-time view of the liver, spleen, kidneys, lymph nodes, and abdominal cavity, where many cancers originate or spread. Ultrasound is often the first tool to detect conditions such as splenic hemangiosarcoma or unexplained weight loss and vomiting, helping guide biopsies, staging, and treatment decisions. Its accuracy and accessibility make it indispensable in veterinary oncology.
End Use Insights
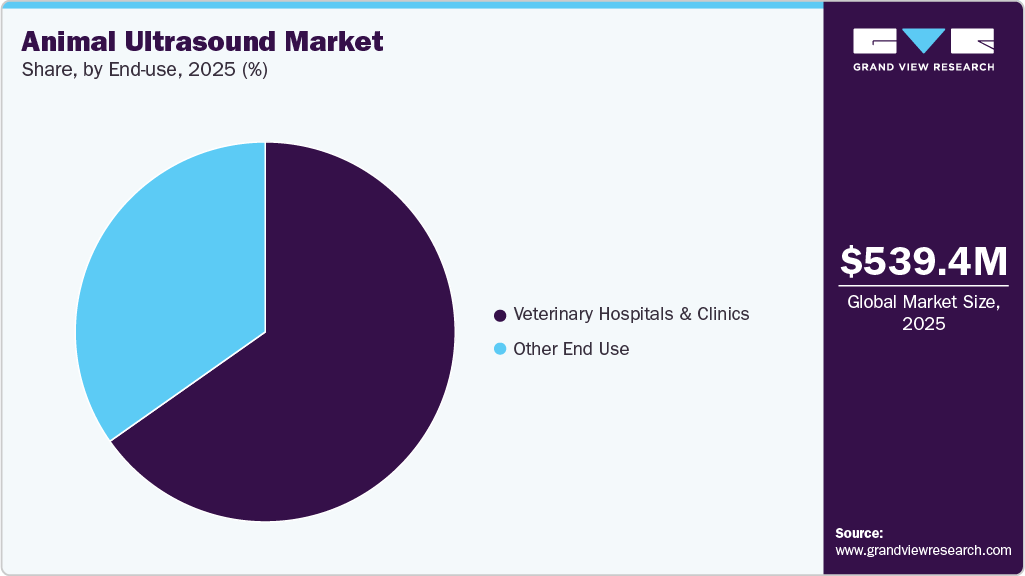
Based on end use, the veterinary hospitals & clinics segment led the market with the largest revenue share of 65.1% in 2025 driven primarily by its capacity to deliver rapid diagnostics and immediate treatment to patients. These facilities typically invest in advanced ultrasound equipment because they handle a higher caseload and more complex cases, allowing them to maximize system utilization and clinical value. For instance, a study from the University of North Carolina conducted in 2018, showed that over 50% of veterinary practices now use some form of ultrasound equipment, and about 45% conduct five or more ultrasound examinations each week in U.S. Thus, the increasing caseloads in clinics and hospitals, fueled by rising pet ownership and greater willingness to spend on preventive diagnostics are contributing to usage intensity. Moreover, technological innovations, especially portable handheld ultrasound machines and cloud-based image management systems have made it increasingly cost-effective for clinics to adopt ultrasound for point-of-care use.
 To learn more about this report, Download Free Sample Report
The other end use segment, including veterinary diagnostic laboratories, academic institutions, and research centers, is projected to grow at the fastest CAGR from 2025 to 2033 due to rising adoption of ultrasound for advanced, non-clinical applications. Diagnostic laboratories use high-resolution ultrasound and PACS to support smaller clinics that lack in-house imaging capabilities, creating scalable demand. In addition, academic and research institutes also rely on ultrasound for studies in physiology, reproduction, and disease modeling, and drive the uptake of portable and high-precision systems. Furthermore, growth is further supported by rising pet insurance coverage, which boosts diagnostic testing volumes. In 2024, North America recorded 7.03 million insured pets, up 12.2% from 2023, reflecting expanding use of diagnostic imaging across veterinary facilities.
Regional Insights
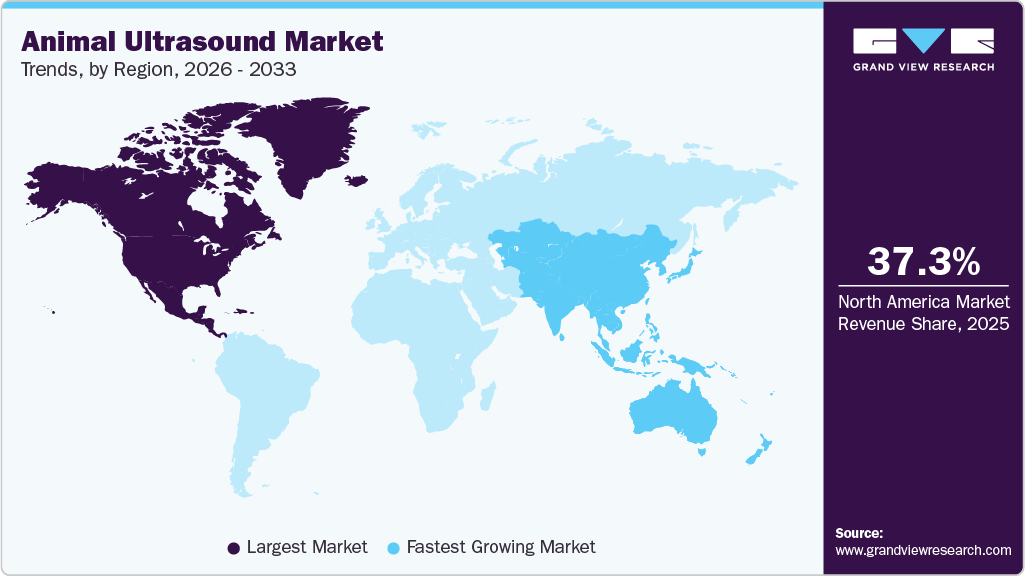
North America dominated the animal ultrasound market with the largest revenue share of 37.3% in 2025. The market is driven by rising pet healthcare spending, growing demand for advanced diagnostic imaging, and increased adoption of portable, point-of-care systems in veterinary clinics. Ultrasound is widely used for cardiac, abdominal, and reproductive assessments in companion animals, whereas durable handheld devices enable on-site diagnostics for livestock and equine patients. In addition, continuous technological advancements and new product launches are further driving adoption across general and specialty practices.
 To learn more about this report, Download Free Sample Report
Besides this, strategic initiatives, such as partnerships and expanded distribution agreements, are enhancing access to advanced imaging. For instance, in May 2024, Esaote North America’s collaboration with Epica International and the launch of the portable MyLab Omega eXP VET with AI-enhanced imaging are accelerating market penetration, improving workflow efficiency, and raising diagnostic standards across North American veterinary facilities.
U.S. Animal Ultrasound Market Trends
The animal ultrasound market in the U.S. held the largest share in the North America region in 2025. The animal ultrasound market in the U.S. accounted for the highest sharein the North American region, owing to rising pet healthcare spending, demand for early diagnostics, and adoption of portable imaging systems in veterinary clinics. Small-animal practices utilize ultrasound for cardiology, abdominal scans, and emergencies, while large-animal veterinarians rely on handheld devices for equine and livestock care. Market growth is driven by innovation, AI-enhanced systems, and expanding product portfolios. Some of the key players, such as Esaote, IDEXX, and Butterfly Network, compete by offering advanced imaging, versatile probes, and workflow-optimizing technologies.
Canada animal ultrasound market is expected to grow at a significant CAGR during the forecast period. The region is transforming due to increasing adoption of veterinary ultrasonography, hands-on training, and educational programs such as miEducation’s Veterinary Ultrasound Bootcamp. Innovations like MRI-guided High-Intensity Focused Ultrasound (HIFU) for canine osteosarcoma expand ultrasound use into therapeutic applications. In addition, companies such as Animages provide teleradiology, mobile ultrasound, and multimodal imaging services, enhancing access and expertise. These initiatives and technological advancements are driving broader adoption of high-performance ultrasound systems across veterinary hospitals, specialty clinics, and research centers in Canada.
Europe Animal Ultrasound Market Trends
The animal ultrasound market in Europe is expanding rapidly, supported by regional initiatives promoting standardized, safe veterinary imaging. Some of the organizations such as the Animal Ultrasound Association (AU) provide structured guidelines, enhancing diagnostic accuracy and encouraging adoption across companion animal, mixed-practice, and livestock clinics. In addition, collaborations between manufacturers and education providers, such as Probo Veterinary, Improve Veterinary Education, and Mindray Animal Medical, equip courses with advanced Vetus systems, improving clinician skills and confidence. As hands-on training expands and adherence to guidelines rises, ultrasound is becoming an essential diagnostic tool, boosting equipment adoption, service utilization, and overall market growth across small-animal, equine, and production-animal segments in Europe.
The UK animal ultrasound market is expected to grow significantly over the forecast period. The market is expanding rapidly, driven by growing adoption of advanced imaging technologies and AI-enabled systems that enhance diagnostic precision in companion animals. In addition, strategic partnerships, such as Vetology with VetIT and Probo Veterinary with AltinVet, are expanding access to portable, AI-assisted, and cloud-compatible ultrasound solutions, improving workflow and diagnostic confidence. For instance, in June 2025, Vetology entered into a partnership with UK-based VetIT to expand access to AI-powered diagnostic imaging and teleradiology across the UK and Europe, enabling veterinary clinics to integrate advanced, cloud-compatible radiology tools with local support and streamlined workflows.
The animal ultrasound market in Germany held a significant share in 2025. The market is expanding rapidly, supported by strong demand from small-animal clinics, equine specialists, and livestock operations. Veterinarians rely on portable, battery-powered units for fieldwork and high-resolution consoles in referral centers for cardiology, reproductive, musculoskeletal, and abdominal imaging. Professional development programs by organizations such as the German Veterinary Medical Society enhance clinician proficiency, supporting the adoption of AI-assisted imaging, cloud teleradiology, and advanced measurement tools.
Asia Pacific Animal Ultrasound Market Trends
The animal ultrasound market in Asia Pacific is expected to grow at the fastest CAGR over the forecast period. The region's market is expanding due to growing pet ownership, modernization of livestock management, and rising demand for advanced veterinary diagnostics. In addition, increased awareness of preventive care and early disease detection is boosting the adoption of portable, high-resolution ultrasound systems in countries such as China, India, Japan, and Australia for cardiac, abdominal, musculoskeletal, and reproductive assessments. Innovative applications in wildlife conservation are emerging. For instance, EC Technologies in May 2024 utilized ultrasound to non-invasively monitor reproductive health and detect complications in endangered species, supporting conservation efforts and expanding the clinical and ecological role of veterinary ultrasound across the region.
Japan animal ultrasound market held a significant revenue shareandis witnessing new growth opportunities due to increasing demand for advanced diagnostic care. Early detection and preventive care are fueling the adoption of high-resolution ultrasound systems for cardiac, renal, and musculoskeletal evaluations for more than 15 million companion animals. Besides this, clinics are upgrading to technologically advanced platforms, such as the Vetus 8 Premium, enhancing imaging precision and workflow. Modernized veterinary facilities integrating these systems are raising diagnostic standards, improving client trust, and supporting proactive, high-quality care.
The market for animal ultrasound in India is emerging, supported by a vast livestock population and a focus on reproductive efficiency. Some of the programs, such as the Rashtriya Gokul Mission and ABIP, promote pregnancy detection, IVF, and embryo transfer using portable ultrasound systems, supported by subsidies and regulatory clarity. In addition, technological advancements and institutional upgrades, such as GADVASU’s new diagnostic unit, further accelerate adoption.
Latin America Animal Ultrasound Market Trends
The animal ultrasound market in Latin America is poised by rising pet ownership and increased spending on preventive veterinary care. Clinics in Brazil and Argentina are adopting portable, digital, and AI-integrated ultrasound systems for rapid, non-invasive diagnostics in abdominal, cardiac, and reproductive applications. Furthermore, technological innovations from companies like Mindray, Esaote, and Canon Medical enhance workflow and accuracy, while partnerships with local distributors expand market reach.
Brazil animal ultrasound market is gaining momentum, due to its large livestock and cattle industry, with a 2025 calf crop of 47.8 million head. Farmers use portable, field-ready ultrasound systems for reproductive monitoring, disease detection, and calf health assessment to optimize breeding outcomes. In addition, beef and dairy production demands, along with international export standards, further boost adoption. Some of the technological advancements, including AI-assisted and high-resolution portable devices, enable real-time, non-invasive imaging, enhancing herd health management, productivity, and preventive care.
Middle East & Africa Animal Ultrasound Market Trends
The animal ultrasound market in the Middle East & Africa is driven by the growing adoption of advanced reproductive technologies in livestock, rising demand for improved herd productivity, and government-backed initiatives to modernize veterinary practices. For instance, in March 2025, Rwanda is deploying veterinary ultrasound technology through the RwanNovIA project to improve artificial insemination (AI) success rates in cattle. Early trials increased AI conception from 33% to up to 95% in some districts, enabling early pregnancy detection, reproductive health monitoring, and better herd management, with support from IMV Technologies, JS AFRICA, and the French government. Projects like Rwanda’s RwanNovIA demonstrate the impact of ultrasound in enhancing AI success, early pregnancy detection, and reproductive health management in cattle.
South Africa animal ultrasound market held the largest regional revenue share and is fueled by rising demand for advanced diagnostics in companion animals, livestock, and wildlife. Portable, high-resolution systems like BXL enable pregnancy detection, cardiac and organ assessments, musculoskeletal imaging, and wildlife care, enhancing veterinary efficiency and animal welfare. Innovations such as underwater ultrasound for marine species, exemplified by the first thorntail ray embryo scan at uShaka Marine World in 2024, highlighted non-invasive monitoring.
The animal ultrasound market in Kuwait is growing due to increased adoption of advanced imaging technologies in companion animal and livestock care. The market is driven by rising pet-owner awareness of preventive healthcare drives clinics to use portable, high-resolution, and 3D/Doppler-enabled ultrasound systems for diagnostics, reproductive monitoring, and cardiac assessments. Simultaneously, modernization in livestock management, supported by government animal health initiatives, encourages ultrasound use for reproductive efficiency in cattle and camels.
Key Animal Ultrasound Company Insights
Key players operating in the animal ultrasound market are undertaking various initiatives to strengthen their presence and increase the reach of their products and services. Strategies such as expansion activities and partnerships are key in propelling the market growth.
Key Animal Ultrasound Companies
The following key companies have been profiled for this study on the animal ultrasound market.
-
IDEXX
-
Esaote SpA
-
Mars Inc. (Sound & Heska)
-
FUJIFILM Holdings America Corporation
-
Shenzhen Mindray Bio-Medical Electronics
-
Siemens Healthcare Limited (PLH Medical Ltd.)
-
Samsung Healthcare
-
ASUSTeK Computer Inc.
-
IMV Imaging
-
CHISON Medical Technologies Co., Ltd.
-
BenQ Medical Technology Corp.
-
Avante Animal Health
-
Contec Medical Systems Co. Ltd.
-
Wuhan Zoncare Bio-medical Electronics Co., Ltd
-
Butterfly Network, Inc.
Competitive Benchmarking
Category
Operating Strategies
Competitive Edge
Weakness
Established Players (EIDEX, Esaote SpA and others)
Mature players strengthen their market position by investing in advanced ultrasound technologies, including AI‑assisted imaging, portable and wireless systems, cloud‑based image management, and high‑resolution diagnostics. They expand product portfolios, strengthen distributor networks with after‑sales support. Strategic collaborations with veterinary hospitals, universities, and research institutes, alongside acquisitions and continuous product upgrades, help improve customer retention, expand geographic presence, and sustain long‑term revenue growth.
Mature companies benefit from strong brand recognition, extensive product portfolios, established distribution channels, and long‑standing relationships with veterinary hospitals and clinics. Their significant investments in research and development, regulatory compliance, and strong marketing performance. Comprehensive training programs, reliable after‑sales support, and financial strength allow them to respond quickly to evolving customer needs while maintaining premium pricing and high customer loyalty.
Mature players often face challenges related to premium product pricing, complex organizational structures, and slower decision‑making processes. Large research and development expenditures, and stringent regulatory compliance requirements increase operational expenses.
Emerging Players (Conte Medical Systems Co. Ltd., Wuhan Zoncare Biomedical Electronics Co., Ltd and other players)
Emerging players focus on developing portable, handheld, and AI‑enabled ultrasound systems that improve diagnostic accuracy and workflow efficiency. They emphasize strategic partnerships with veterinary hospitals, distributors, and academic institutions to expand market reach. Investments in cloud connectivity, well‑structured capabilities, software upgrades, and user‑friendly interfaces help differentiate products. Companies also target underserved emerging markets, offer flexible pricing, product training, and after‑sales support to encourage adoption among general practitioners and specialty veterinary clinics.
Emerging companies gain a competitive advantage through innovative imaging technologies such as wireless ultrasound devices, AI‑assisted image interpretation, telemedicine, and software integration for veterinary applications. Faster product innovation cycles, customizable software, cloud‑based data management systems, and strong distributor networks expand market penetration. Their ability to address the growing demand for point‑of‑care imaging, mobile diagnostics, and telemedicine among providers offers greater flexibility compared with many established manufacturers offering conventional systems.
Emerging players often face limited brand recognition, smaller distribution networks, and constrained financial resources compared to established companies. Limited global regulatory experience, lower manufacturing scale, and fewer long‑term clinical validation studies may affect customer confidence
Recent Developments
-
In September 2025, Mindray launched Project 2030, expanding ultrasound education, global outreach, and academic partnerships to enhance imaging accessibility, training, and clinical competence in veterinary and human healthcare settings.
-
In August 2025, Siemens Healthineers signed an eight-year partnership to replace 29 ultrasound units in Germany, modernizing systems and enhancing imaging reliability with direct benefits extending to veterinary workflows.
-
In June 2025, Fujifilm VisualSonics launched the Vevo F2 LAZR-X20, a multimodal photoacoustic imaging platform offering high-powered laser technology, advanced tissue characterization, and expanded research capabilities for preclinical animal oncology, cardiovascular, neurobiology and molecular biology applications.
Animal Ultrasound Market Report Scope
Report Attribute
Details
Market size in 2025
USD 539.4 million
Estimated market size in 2026
USD 575.7 million
Projected market size by 2033
USD 998.8 million
Growth rate
CAGR of 8.2% from 2026 to 2033
Historical data
2021 - 2025
Forecast period
2026 - 2033
Quantitative units
Revenue in USD million/billion and CAGR from 2026 to 2033
Report coverage
Revenue forecast, company ranking, competitive landscape, growth factors, and trends
Segments covered
Animal, solution, type, technology, application, end use, region
Regional scope
North America; Europe; Asia Pacific; Latin America; MEA
Country scope
U.S.; Canada; Mexico; Germany; UK; France; Italy; Spain; Norway; Denmark; Sweden; China; Japan; India; South Korea; Australia; Thailand; Brazil; Argentina; Saudi Arabia; South Africa; UAE; Kuwait; Oman; Qatar.
Key companies profiled
IDEXX; Esaote SpA; Mars Inc. (Sound & Heska); FUJIFILM Holdings America Corporation; Shenzhen Mindray Bio-Medical Electronics; Siemens Healthcare Limited (PLH Medical Ltd.); Samsung Healthcare; ASUSTeK Computer Inc.; IMV Imaging; CHISON Medical Technologies Co., Ltd.; BenQ Medical Technology Corp.; Avante Animal Health; Contec Medical Systems Co. Ltd.; Wuhan Zoncare Bio-medical Electronics Co., Ltd; Butterfly Network, Inc.
Customization scope
Free report customization (equivalent up to 8 analysts' working days) with purchase. Addition or alteration to country, regional & segment scope.
Pricing and purchase options
Avail customized purchase options to meet your exact research needs. Explore purchase options
Global Animal Ultrasound Market Report Segmentation
This report forecasts revenue growth at global, regional, and country levels and provides an analysis of the latest industry trends in each of the sub-segments from 2021 to 2033. For this study, Grand View Research has segmented the global animal ultrasound market report based on animal, solution, type, technology, application, end use, and region:
-
Animal Outlook (Revenue, USD Million, 2021 - 2033)
-
Small Animals
-
Large Animals
-
-
Solution Outlook (Revenue, USD Million, 2021 - 2033)
-
Equipment
-
Console/Cart-Based Ultrasound
-
Portable/Handheld Ultrasound
-
-
Accessories/Consumables
-
PACS
-
-
Type Outlook (Revenue, USD Million, 2021 - 2033)
-
2-D Ultrasound Imaging
-
3-D/4-D Ultrasound Imaging
-
Doppler Imaging
-
-
Technology Outlook (Revenue, USD Million, 2021 - 2033)
-
Digital Imaging
-
Contrast Imaging
-
-
Application Outlook (Revenue, USD Million, 2021 - 2033)
-
Orthopedics
-
Cardiology
-
Oncology
-
Abdominal
-
Other Applications
-
-
End Use Outlook (Revenue, USD Million, 2021 - 2033)
-
Veterinary Hospitals & Clinics
-
Other End-Use
-
-
Regional Outlook (Revenue, USD Million, 2021 - 2033)
-
North America
-
U.S.
-
Canada
-
Mexico
-
-
Europe
-
UK
-
Germany
-
France
-
Italy
-
Spain
-
Denmark
-
Sweden
-
Norway
-
-
Asia Pacific
-
Japan
-
China
-
India
-
Australia
-
Thailand
-
South Korea
-
-
Latin America
-
Brazil
-
Argentina
-
-
Middle East & Africa
-
South Africa
-
UAE
-
Saudi Arabia
-
Kuwait
-
Qatar
-
Oman
-
-
Research Methodology
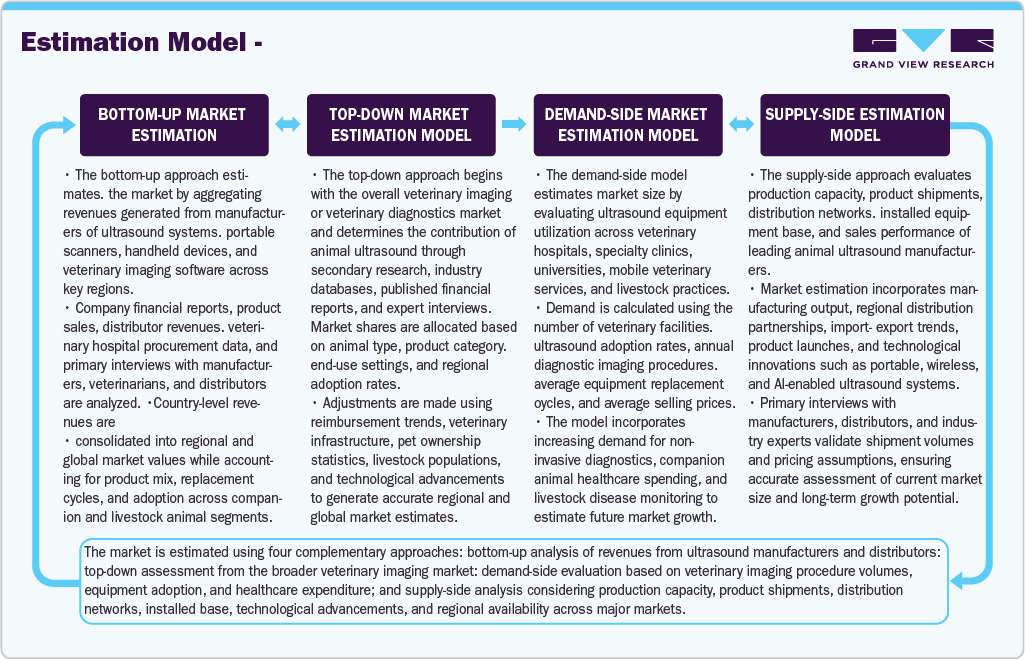
The animal ultrasound market figures in this report are based on a proven research process that combines executive interviews with secondary research from proprietary databases, company filings, and recognized regulatory and institutional sources. Market size is built through value-chain sizing - reconciling supply-side and demand-side estimates - and triangulated with bottom-up and top-down approaches. Every estimate passes multiple levels of expert validation before publication, with each animal ultrasound segment quantified using the revenue-capture definitions in the table below.
Segment Definition
Segment - Animal
Revenue Capture Definition
Large Animals
The market size reflects the total revenue derived from all ultrasound-based diagnostic procedures performed across large animal species, including swine, cattle, sheep, goats, horses, and other livestock.
Small Animals
The market size reflects the total revenue derived from all ultrasound-based diagnostic procedures performed across small species including dogs, cats, small mammals, and other small animals.
Segment - Solution
Revenue Capture Definition
Equipment
The market size represents total revenue generated from the sale, leasing, and integration of ultrasound devices used for diagnostic ultrasound examinations.
Console/Cart-Based Ultrasound
The console/cart-based ultrasound segment represents the total revenue generated from the sale, deployment, and use of stationery or trolley-mounted ultrasound systems for diagnostic imaging in large animals, including livestock species.
Portable/Handheld Ultrasound
The portable/handheld ultrasound segment represents the total revenue generated from compact and mobile ultrasound devices used for diagnostic imaging in large animals, including swine, cattle, sheep, goats, horses, and other livestock.
Accessories/Consumables
The market size indicates total revenue generated from supplemental components and single-use or regularly replaced products required to support and optimize ultrasound diagnostic procedures, including gels, probe covers, biopsy guides, replacement transducers, and ancillary supplies.
PACS
The PACS segment represents the total revenue generated from digital imaging software platforms designed for the storage, retrieval, distribution, and management of ultrasound diagnostic data for large animals, including swine, cattle, sheep, goats, horses, and other livestock.
Segment - Type
Revenue Capture Definition
2-D Ultrasound Imaging
The 2-D ultrasound imaging segment represents the total revenue generated from two-dimensional diagnostic imaging procedures and related system utilization in large animals, including swine, cattle, sheep, goats, horses, and other livestock.
3-D/4-D Ultrasound Imaging
The 3-D/4-D ultrasound imaging segment represents the total revenue generated from advanced diagnostic imaging procedures and related system utilization in large animals, improving anatomical visualization and clinical precision.
Doppler Imaging
The Doppler imaging segment represents the total revenue generated from ultrasound procedures used to assess blood flow, vascular conditions, and cardiac function in large animals, including livestock and equine species.
Segment - Technology
Revenue Capture Definition
Digital Imaging
The digital imaging segment represents the total revenue generated from ultrasound diagnostic examinations captured, processed, and stored in digital formats for large animals, including swine, cattle, sheep, goats, horses, and other livestock species.
Contrast Imaging
The contrast imaging segment represents the total revenue generated from ultrasound diagnostic examinations that utilize contrast agents to enhance visualization of blood flow, tissue perfusion, and internal anatomical structures in livestock animals.
Segment- Application
Revenue Capture Definition
Orthopedics
The market size represents the total revenue generated from ultrasound-based diagnostic interventions utilized exclusively for detecting, assessing, and monitoring orthopedic conditions in animals.
Cardiology
The market size reflects the overall revenue derived from the use of ultrasound diagnostic procedures specifically performed on animals suffering from cardiac disease.
Oncology
The market size represents the total monetary value generated from ultrasound-based diagnostic interventions utilized exclusively for identifying, evaluating, and monitoring cancerous conditions in animals.
Abdominal
The market size represents the total revenue generated from ultrasound-based diagnostic interventions conducted exclusively on animals presenting with abdominal health complications, including urinary, reproductive, and obstetric disorders.
Other Applications
The market size represents the total revenue generated from ultrasound-based diagnostic interventions conducted exclusively for veterinary cases involving ophthalmic, neurological, and dental disorders in animals.
Segment - End Use
Revenue Capture Definition
Veterinary Hospitals & Clinics
The market size reflects the total revenue generated by veterinary hospitals and clinics conducting ultrasound-based diagnostic procedures for both small companion animals and large livestock species.
Other End Use
The market size reflects the total revenue generated by academic and research institutions, as well as veterinary diagnostic laboratories, conducting ultrasound-based diagnostic procedures for both small companion animals and livestock species.
Estimation Model
 To learn more about this report, Download Free Sample Report
Delivered Customizations
This report has been delivered with the following In-depth customizations
Client Request
Customization Delivered
Value Adds
Technology & Innovation Assessment
Detailed evaluation of emerging technologies in the market, including AI-assisted image interpretation, wireless and handheld ultrasound systems, portable point-of-care devices, cloud-based image management, tele-ultrasound solutions, advanced Doppler imaging, and high-frequency transducers. The assessment also covers commercialization trends, product innovation pipelines, regulatory developments, adoption rates, and future technological advancements across companion and livestock animal diagnostics.
This helps stakeholders identify high-growth technologies, optimize R&D investments, accelerate product development, assess commercialization potential, and align innovation strategies with evolving veterinary imaging requirements, improving competitive positioning and long-term business growth.
Market Opportunity Analysis
Customized assessment of emerging applications, high-growth animal segments, underserved regional markets, investment opportunities, product demand forecasts, regulatory developments, reimbursement landscape, and future market potential. The analysis incorporates scenario-based forecasting models, veterinary infrastructure assessment, primary expert interviews, and technology adoption trends to identify new revenue opportunities across the global market.
This supports strategic decision-making, investment prioritization, market expansion planning, product portfolio optimization, and risk mitigation while identifying sustainable growth opportunities, attractive customer segments, and long-term revenue potential across regional veterinary imaging markets.
Competitive Benchmarking
Comprehensive benchmarking of leading ultrasound manufacturers, veterinary imaging companies, and emerging technology providers based on product portfolio, pricing strategies, AI capabilities, imaging performance, distribution networks, geographic presence, partnerships, manufacturing capacity, innovation pipeline, customer support, and recent strategic developments. The analysis also includes SWOT assessment, competitive positioning, and market share comparisons to identify growth opportunities and competitive advantages.
This enables companies to evaluate competitive positioning, identify technology gaps, benchmark product performance, strengthen distribution strategies, establish strategic partnerships, improve product differentiation, and develop sustainable competitive advantages within the rapidly evolving animal ultrasound Market.
Frequently Asked Questions About This Report
The global animal ultrasound market is expected to grow at a CAGR of 8.2% from 2025 to 2033, reaching USD 998.8 million by 2033.
North America animal ultrasound market held the largest share of 37.3% of the global market in 2025.
Some key players operating in the global veterinary ultrasound market include IDEXX; Esaote SpA; Mars Inc. (Sound & Heska); FUJIFILM Holdings America Corporation; Shenzhen Mindray Bio-Medical Electronics; Siemens Healthcare Limited (PLH Medical Ltd.); Samsung Healthcare; ASUSTeK Computer Inc.; IMV Imaging; CHISON Medical Technologies Co., Ltd.; BenQ Medical Technology Corp.; Avante Animal Health; Contec Medical Systems Co. Ltd.; Wuhan Zoncare Bio-medical Electronics Co., Ltd; Butterfly Network, Inc.
Based on solution, the equipment segment led the market with the largest revenue share of 53.0% in 2025.
The global animal ultrasound market size was valued at USD 539.4 million in 2025 and is estimated at USD 575.7 million for 2026.
Asia Pacific is the fastest-growing region over the forecast period of 2026-2033.
Based on type, the 2-D ultrasound imaging segment led the market with the largest revenue share of 50.7% in 2025.
Based on technology, the digital imaging segment led the market with the largest revenue share of 69.2% in 2025.
Some of the key factors driving market growth are growing research initiatives & breakthroughs, expanding applications of ultrasound in the veterinary sector, rising adoption of pet insurance and increasing critical collaboration in the industry.
About the Author(s)
Animal Health Research Team
Healthcare · Animal HealthThis report was authored by the animal health research team at Grand View Research - comprising two research analysts, one senior research analyst, and one industry expert - with specialized expertise in the animal health segment of the healthcare industry. All findings are based on proprietary healthcare databases, executive interviews, and regulatory analysis, subject to internal peer review prior to publication.
Last Updated:
Speak to Analyst

Customize this report to your needs - add regions, segments, or data points, with 20% free customization.
Or view our licence options:


ISO 9001:2015 & 27001:2022 Certified
We are GDPR and CCPA compliant! Your transaction & personal information is safe and secure. For more details, please read our privacy policy.


