
- Home
- »
- Next Generation Technologies
- »
-
Anti-money Laundering Market Size & Share Report, 2033GVR Report cover

Anti-money Laundering Market (2026 - 2033)
Size, Share, & Trends Analysis Report By Component (Software, Services) , By Deployment (Cloud, On-premise), By Product (Compliance Management, Currency Transaction Reporting), By Enterprise Size, By End Use, By Region, And Segment Forecasts
Market Size, 2025
$2.0BMarket Estimate, 2026
$2.3BMarket Forecast, 2033
$6.8BCAGR, 2026–2033
16.6%Anti-money Laundering Market Summary
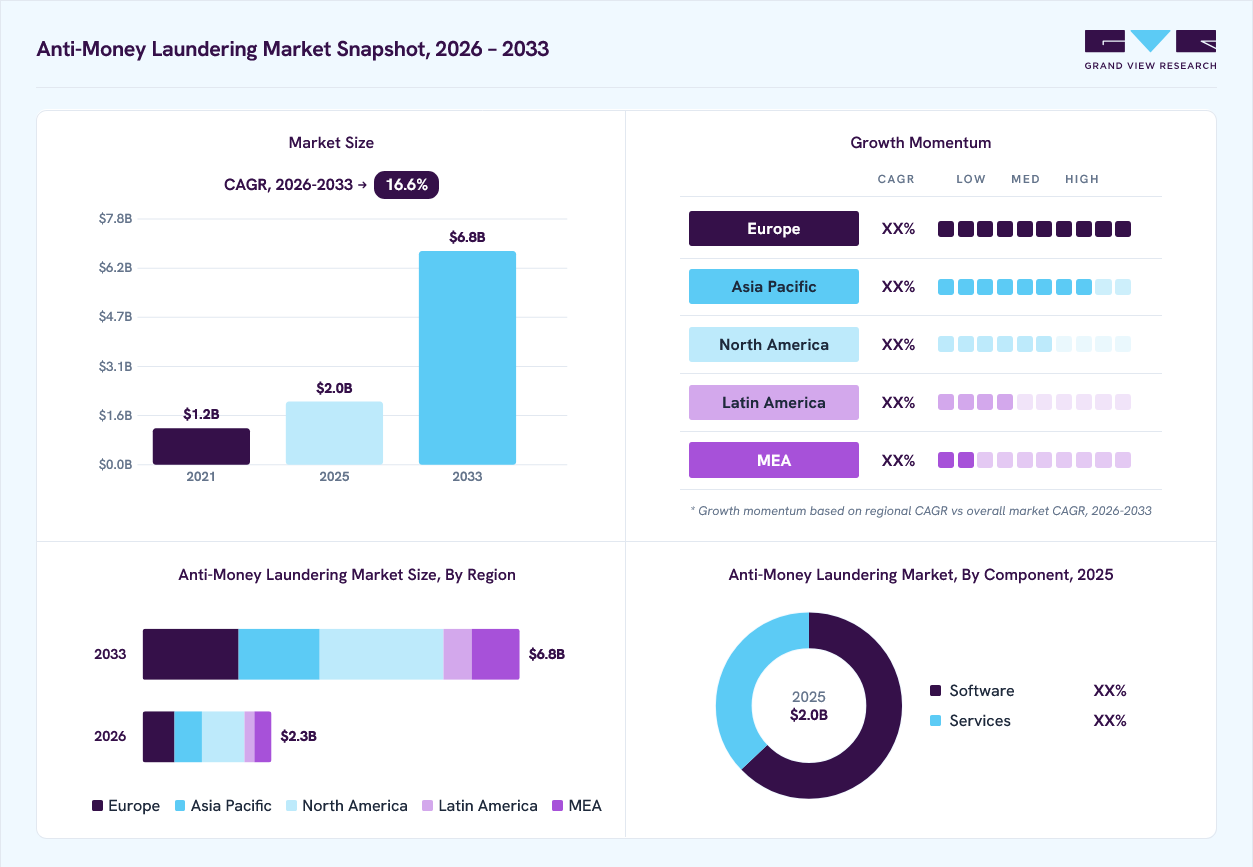
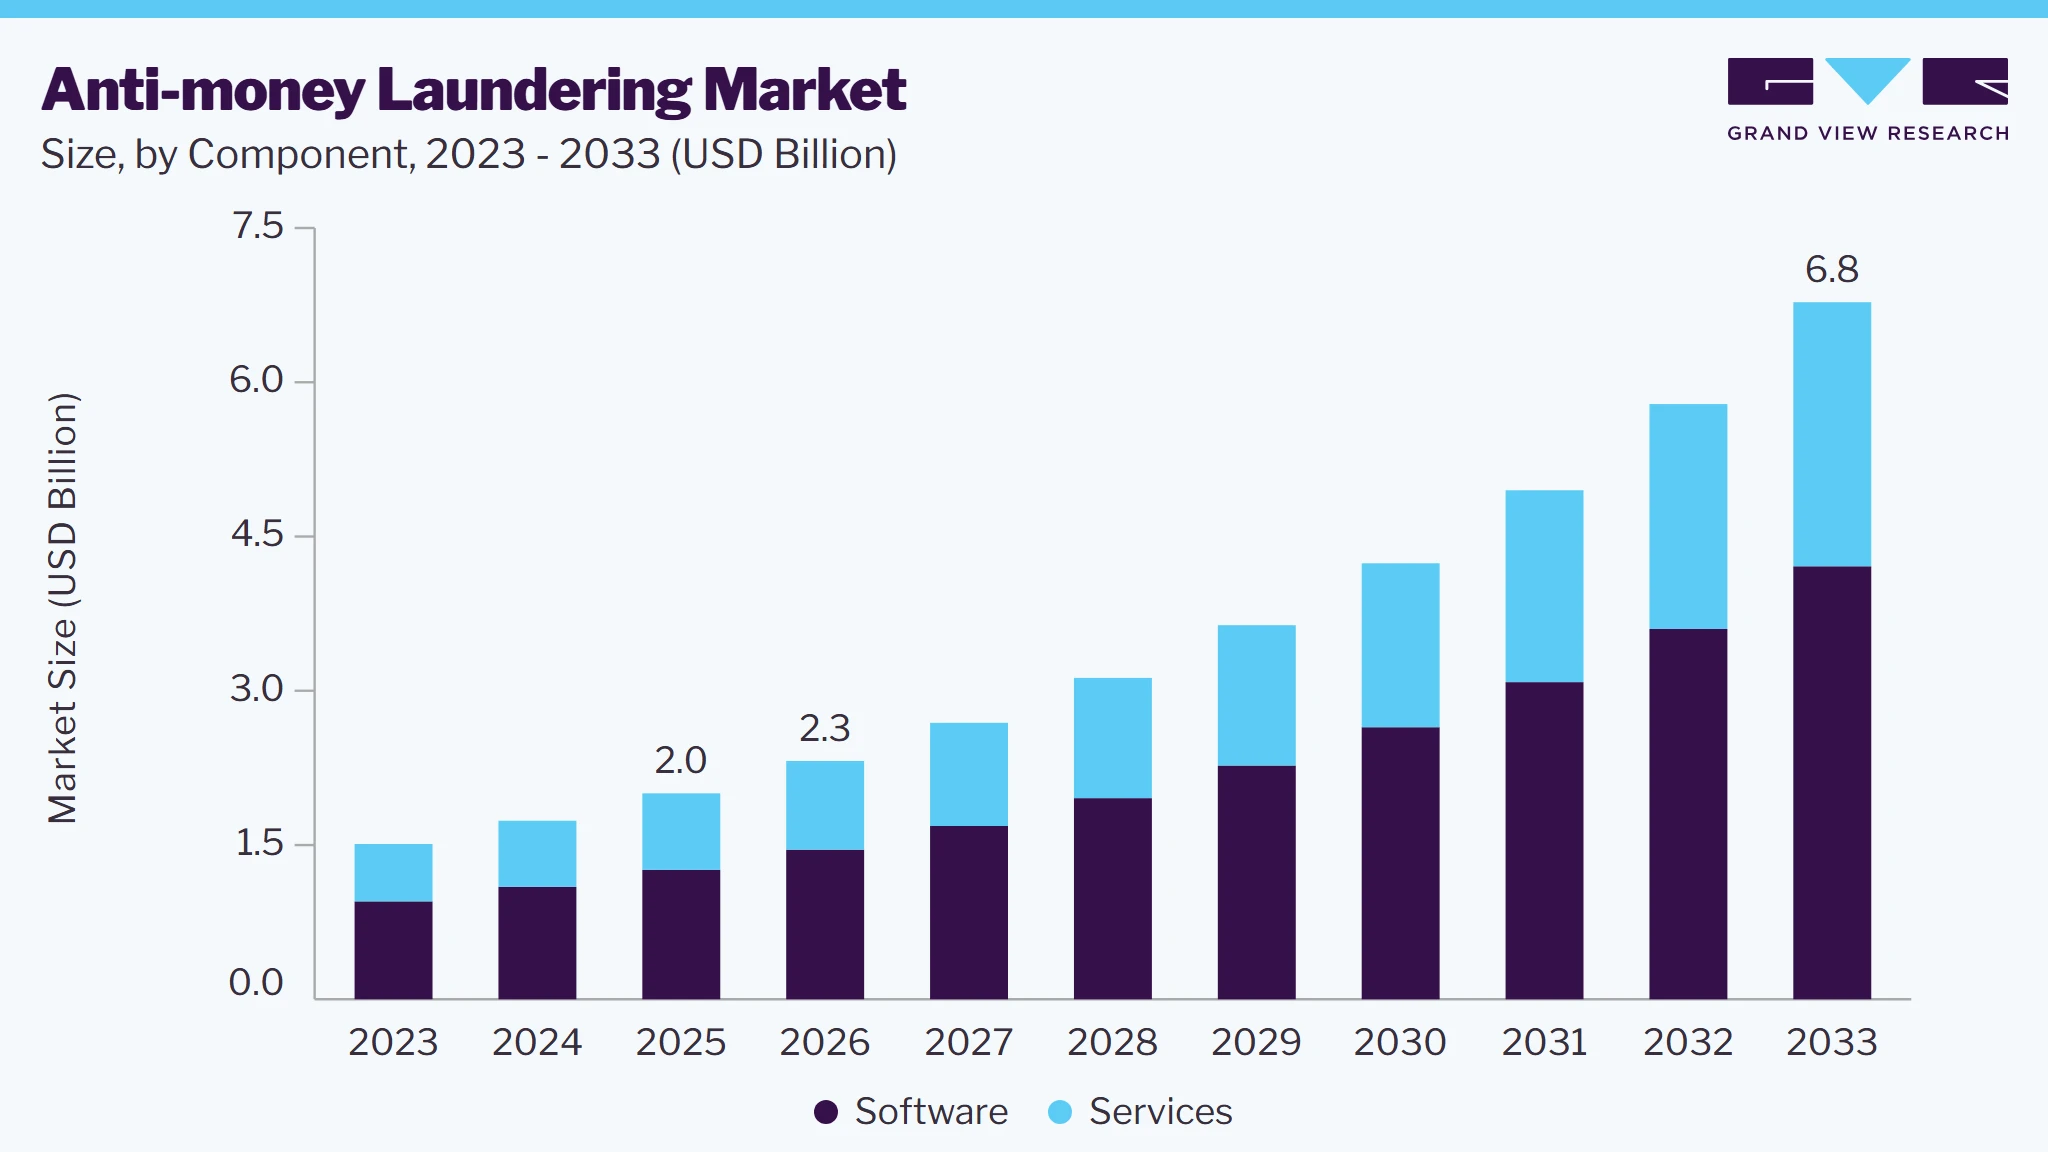
The global anti-money laundering market size was valued at USD 2.0 billion in 2025 and is projected to grow from USD 2.3 billion in 2026 to USD 6.8 billion by 2033, at a CAGR of 16.6% from 2026 to 2033. North America dominated the anti-money laundering (AML) market, accounting for a revenue share of 33.0% in 2025. The growth of the market is driven by increasingly stringent regulations and the need for financial institutions to comply with global standards.
 Source: Grand View Research, IR Documents, Primary Interviews, Paid DatabasesTo learn more about this report,
 Download Free Sample Report
Key Market Trends & Insights
- By component: Software segment dominated the market, with a revenue share of 62.9% in 2025
- By product: Compliance management segment held the largest market share of 28.1% in 2025
- By deployment: On-Premise segment accounted for the largest revenue share of 54.7% in 2025
- By enterprise size: Large enterprises segment accounted for the largest revenue share in 2025
- By end use: BFSI segment accounted for the largest revenue share in 2025
Regional Highlights
- Largest regional market: North America (33.0% revenue share, 2025)
- Fastest-growing regional market: Europe (highest CAGR, 2026-2033)
- By country: The U.S. held the largest market share in 2025.
Market Size & Forecast
- Market size in 2025: USD 2.0 Billion
- Estimated market size in 2026: USD 2.3 Billion
- Projected market size by 2033: USD 6.8 Billion
- CAGR (2026-2033): 16.6%
Three ways to get this report
Buy it, customize it, or ask a question.Ask an Analyst
Analyst response in 1 business day
- AccessReport author, directly
- Reply timeWithin 1 working day
- No sales callDirect answer only
- FormatEmail reply
- CostFree, no cost
Get the Full Report
What the study covers
- FormatsPDF · Excel · Dashboard
- Timeline2026–2033 annual, 2025 base
- Coverage20+ countries, 5 regions
- Companies10+ key players profiled
Customize the Report
20% free customization
- IncludeCountries, segments, points
- TailorTo your product definition
- ExtendDeeper competitor detail
- OrA fully bespoke study
- Turnaround5–10 working days
Regulatory bodies around the world, such as the Financial Action Task Force (FATF), have been intensifying efforts to combat money laundering and terrorist financing. This regulatory pressure compels financial institutions to adopt advanced anti-money laundering solutions to ensure compliance and avoid substantial penalties. As a result, the demand for robust anti-money laundering solutions has surged, leading to the continuous development and enhancement of technology-driven solutions in this sector. The growing complexity of financial crimes further emphasizes the need for sophisticated tools that can effectively monitor and analyze financial transactions.The significant growth in online businesses and electronic transactions in recent years has become a major driver of the anti-money laundering market. The rapid expansion of online marketplaces is largely due to the convenience they provide to consumers. Additionally, more financial institutions are introducing innovative online banking services and digital transaction options, which further propel the growth of online commerce. Factors such as digital advancements and the rising popularity of mobile payments are expected to accelerate the adoption of online transactions. Utilizing non-cash transactions helps organizations maintain transparency and effectively monitor any suspicious activities.
 To learn more about this report, Download Free Sample Report
Technological advancements are playing a pivotal role in transforming the anti-money laundering landscape. The integration of Artificial Intelligence (AI), machine learning, and big data analytics into anti-money laundering solutions has enhanced the ability of organizations to detect suspicious activities with greater accuracy. These technologies enable financial institutions to analyze large volumes of data in real time, identify patterns, and predict potential risks more effectively. Additionally, automation of routine compliance tasks has reduced operational costs and the occurrence of human errors. This technological shift is driving the adoption of advanced anti-money laundering solutions across various industries, making them more efficient in combating financial crimes.
Digital transformation within the financial services sector has also contributed to the growing importance of anti-money laundering systems. For instance, as per the insights of Worldmetrics.org. in 2024, 67% of financial institutions consider digital transformation essential for their survival. As more transactions move online, the volume and complexity of financial activities have increased, creating new challenges for detecting and preventing money laundering. Additionally, the rise of digital banking, mobile payments, and cryptocurrencies has expanded the landscape in which financial crimes can occur. This evolution necessitates advanced anti-money laundering systems that can monitor and analyze digital transactions across multiple platforms and jurisdictions. Consequently, financial institutions are increasingly investing in cutting-edge AML technologies to stay ahead of evolving threats in the digital era.
Globalization and the rise in cross-border transactions have made the fight against money laundering even more complex. Financial activities that span multiple countries often involve different regulatory environments, making it challenging to maintain consistent compliance. Anti-money laundering solutions must now be capable of handling the intricacies of cross-border financial flows while ensuring adherence to diverse regulatory frameworks. This need for comprehensive and versatile anti-money laundering systems is driving innovation in the market, as providers seek to offer solutions that can effectively address the demands of global finance, thereby contributing to the growth of the market.
Market Dynamics
The anti-money laundering (AML) market is shaped by intensifying regulatory scrutiny, rising sophistication of financial crimes, and accelerated digitization across global financial systems. Governments and regulators continue to expand AML mandates in response to cross-border illicit financial flows, cyber-enabled fraud, and terrorism financing risks. Simultaneously, financial institutions are modernizing compliance infrastructure through automation, advanced analytics, and cloud deployment models. The market is increasingly influenced by artificial intelligence, driven transaction monitoring, real-time risk scoring, and integration of AML platforms with broader governance, risk, and compliance ecosystems, positioning AML solutions as a core component of enterprise risk management strategies.
The primary driver of the AML market is the escalating enforcement of global and regional financial regulations, combined with the growing complexity of money laundering techniques. Regulatory bodies such as financial intelligence units and central banks are tightening compliance requirements related to customer due diligence, suspicious activity reporting, and transaction transparency. Financial institutions face significant penalties, reputational damage, and operational restrictions for non-compliance, compelling organizations to strengthen AML frameworks. The rise in digital payments, cross-border remittances, and virtual assets has further expanded the attack surface for illicit financial activities.
Anti-money laundering solutions directly address this driver by enabling automated compliance workflows, continuous transaction surveillance, and real-time detection of suspicious patterns. Advanced AML platforms leverage machine learning and behavioral analytics to reduce false positives and improve detection accuracy across high-volume transaction environments. These capabilities allow regulated entities to meet evolving regulatory expectations while managing compliance costs, thereby accelerating adoption across BFSI, fintech, and payment service providers. As enforcement actions increase globally, AML solutions are becoming mission-critical investments rather than discretionary compliance tools.
A key restraint on AML market growth is the high cost and complexity of implementing and maintaining AML systems. Comprehensive AML deployments often require integration with legacy core banking systems, data normalization across multiple sources, and ongoing model calibration. Smaller financial institutions and non-financial regulated entities frequently lack the internal expertise and budget required to manage sophisticated AML platforms, leading to delayed adoption or reliance on manual processes.
This restraint disproportionately impacts small and medium enterprises and institutions in emerging markets, where regulatory pressure is rising, but technology budgets remain constrained. On-premise deployments amplify these challenges due to infrastructure costs and longer deployment timelines. As a result, adoption rates are uneven across regions, slowing overall market expansion despite strong regulatory drivers. Vendors must increasingly address usability, scalability, and total cost of ownership to mitigate this restraint.
A major opportunity in the AML market is the rapid shift toward cloud-based, AI-enabled compliance solutions. Advances in cloud infrastructure, data security frameworks, and regulatory acceptance of cloud deployments are enabling financial institutions to modernize AML operations with greater agility. Cloud platforms enable scalable transaction monitoring, faster updates in response to regulatory changes, and improved collaboration among compliance teams.
This opportunity presents significant growth potential for vendors offering modular, cloud-native AML solutions tailored to mid-tier banks, fintechs, and non-traditional financial entities. Segments such as transaction monitoring and customer identity management are particularly well positioned to benefit from AI-driven analytics and automation. Vendors with strong cloud capabilities and domain-specific AML expertise are expected to capture increased market share as institutions prioritize flexible, cost-efficient compliance architectures.
Analyst Perspective
The anti-money laundering market is transitioning from rule-based compliance systems to intelligence driven risk management platforms. Regulatory pressure and rising sophistication in financial crime continue to drive demand, while artificial intelligence and cloud adoption are reshaping solution architectures. Vendors are increasingly focusing on modular, interoperable AML platforms that integrate seamlessly with enterprise data ecosystems. Investment is expected to focus on transaction monitoring automation, identity verification, and cloud-native deployments. Competitive differentiation is shifting toward analytics accuracy, scalability, and regulatory adaptability rather than standalone compliance functionality.
Component Insights
Based on component, the software segment led the market with the largest revenue share of 62.9% in 2025. The segment growth can be attributed to an increase in demand for anti-money laundering software among banks and payment solution providers. The software detect suspicious activities and reduce the number of genuine transaction declines. Advanced technologies such as artificial intelligence, machine learning, and big data analytics are being integrated into anti-money laundering software, enabling real-time analysis of vast amounts of data. These innovations are not only improving the effectiveness of anti-money laundering programs but also reducing the operational costs associated with manual compliance efforts.
The services segment is expected to register significant growth from 2026 to 2033. The services segment in the anti-money laundering market is gaining traction as financial institutions seek expert guidance and support to navigate the complexities of AML compliance. Several companies across the globe are focusing on developing and launching AI-powered anti-money laundering services to help banks eliminate anti-money laundering risks. For instance, in April 2024, Oracle launched an AI-powered cloud service, the Oracle Financial Services Compliance Agent, designed to help banks eliminate anti-money laundering (AML) risks more efficiently. The service enables banks to conduct scenario testing, identify suspicious activities, and optimize their transaction monitoring systems. This tool leverages artificial intelligence and machine learning to enhance the effectiveness of AML programs, reducing costs and improving decision-making.
Product Insights
Based on product, the compliance management segment led the market with the largest revenue share of 28.1% in 2025. The growth attributed to the rising financial crimes, which necessitates advanced monitoring systems capable of analyzing vast volumes of transactions in real-time. Regulatory pressure from global and regional authorities is also pushing financial institutions to adopt more robust transaction monitoring tools to ensure compliance and avoid hefty fines. At the same, companies across the globe are developing AML solutions to focus and prevent high-risk activities. For instance, in October 2023, WorkFusion launched a new AI solution, Isaac, designed to enhance AML transaction monitoring by automating the first-level alert review process. Isaac utilizes machine learning to assess alerts, auto-escalate those requiring further investigation, and close non-suspicious alerts with supporting documentation. This innovation reduced the burden on AML analysts, allowing them to focus on higher-risk activities.
The customer identity management segment is expected to grow significantly from 2026 to 2033. The growth of the segment can be attributed to the rising importance of robust Know Your Customer (KYC) processes in the fight against money laundering. Financial institutions are increasingly adopting customer identity management solutions to verify the identities of their clients, ensuring that they are not inadvertently facilitating illicit activities. The surge in digital banking and online transactions has heightened the need for accurate and efficient identity verification processes. Advanced technologies, such as biometric authentication and AI-driven identity verification, are being integrated into these solutions to enhance their accuracy and reliability.
Deployment Insights
Based on deployment, the on-premise miles segment led the market with the largest revenue share of 54.7% in 2025. The on-premise segment of the anti-money laundering market remains crucial for organizations that prioritize control and security over their compliance systems. Many institutions prefer on-premise solutions due to their ability to customize and integrate with existing IT infrastructure, providing greater control over data security and regulatory compliance. On-premise anti-money laundering systems offer the advantage of being tailored to specific organizational needs, allowing for more rigorous and specialized compliance processes.
The cloud segment is expected to grow significantly from 2026 to 2033. The cloud segment of the anti-money laundering market is experiencing rapid growth due to its flexibility, scalability, and cost-effectiveness. Cloud-based anti-money laundering solutions offer organizations the advantage of easier updates and integrations, reducing the burden of maintaining and upgrading on-premise systems. These solutions enable financial institutions to access advanced features and technologies, such as artificial intelligence and real-time data analytics, without the need for extensive infrastructure investments. The rise of remote work and the increasing adoption of digital banking services have further accelerated the shift towards cloud-based AML solutions.
Enterprise Size Insights
Based on enterprise size, the large enterprises segments led the market with the largest revenue share of 68.0% in 2025. Large enterprises are increasingly prioritizing anti-money laundering (AML) measures due to the heightened regulatory scrutiny they face globally. With vast and complex operations, these organizations are vulnerable to sophisticated money laundering schemes, making robust AML systems essential. The adoption of advanced technologies such as AI and machine learning is becoming common among large enterprises to detect and prevent illicit activities more efficiently.
The small & medium enterprises segment is expected to grow significantly from 2026 to 2033. Although small & medium enterprises often have fewer resources compared to large enterprises, they are adopting cost-effective and scalable AML solutions to address their unique challenges. The rise of cloud-based AML platforms is particularly beneficial for SMEs, enabling them to implement sophisticated monitoring systems without the need for substantial infrastructure investments. Additionally, small & medium enterprises are becoming more aware of the reputational risks associated with non-compliance, driving them to prioritize anti-money laundering measures.
End Use Insights
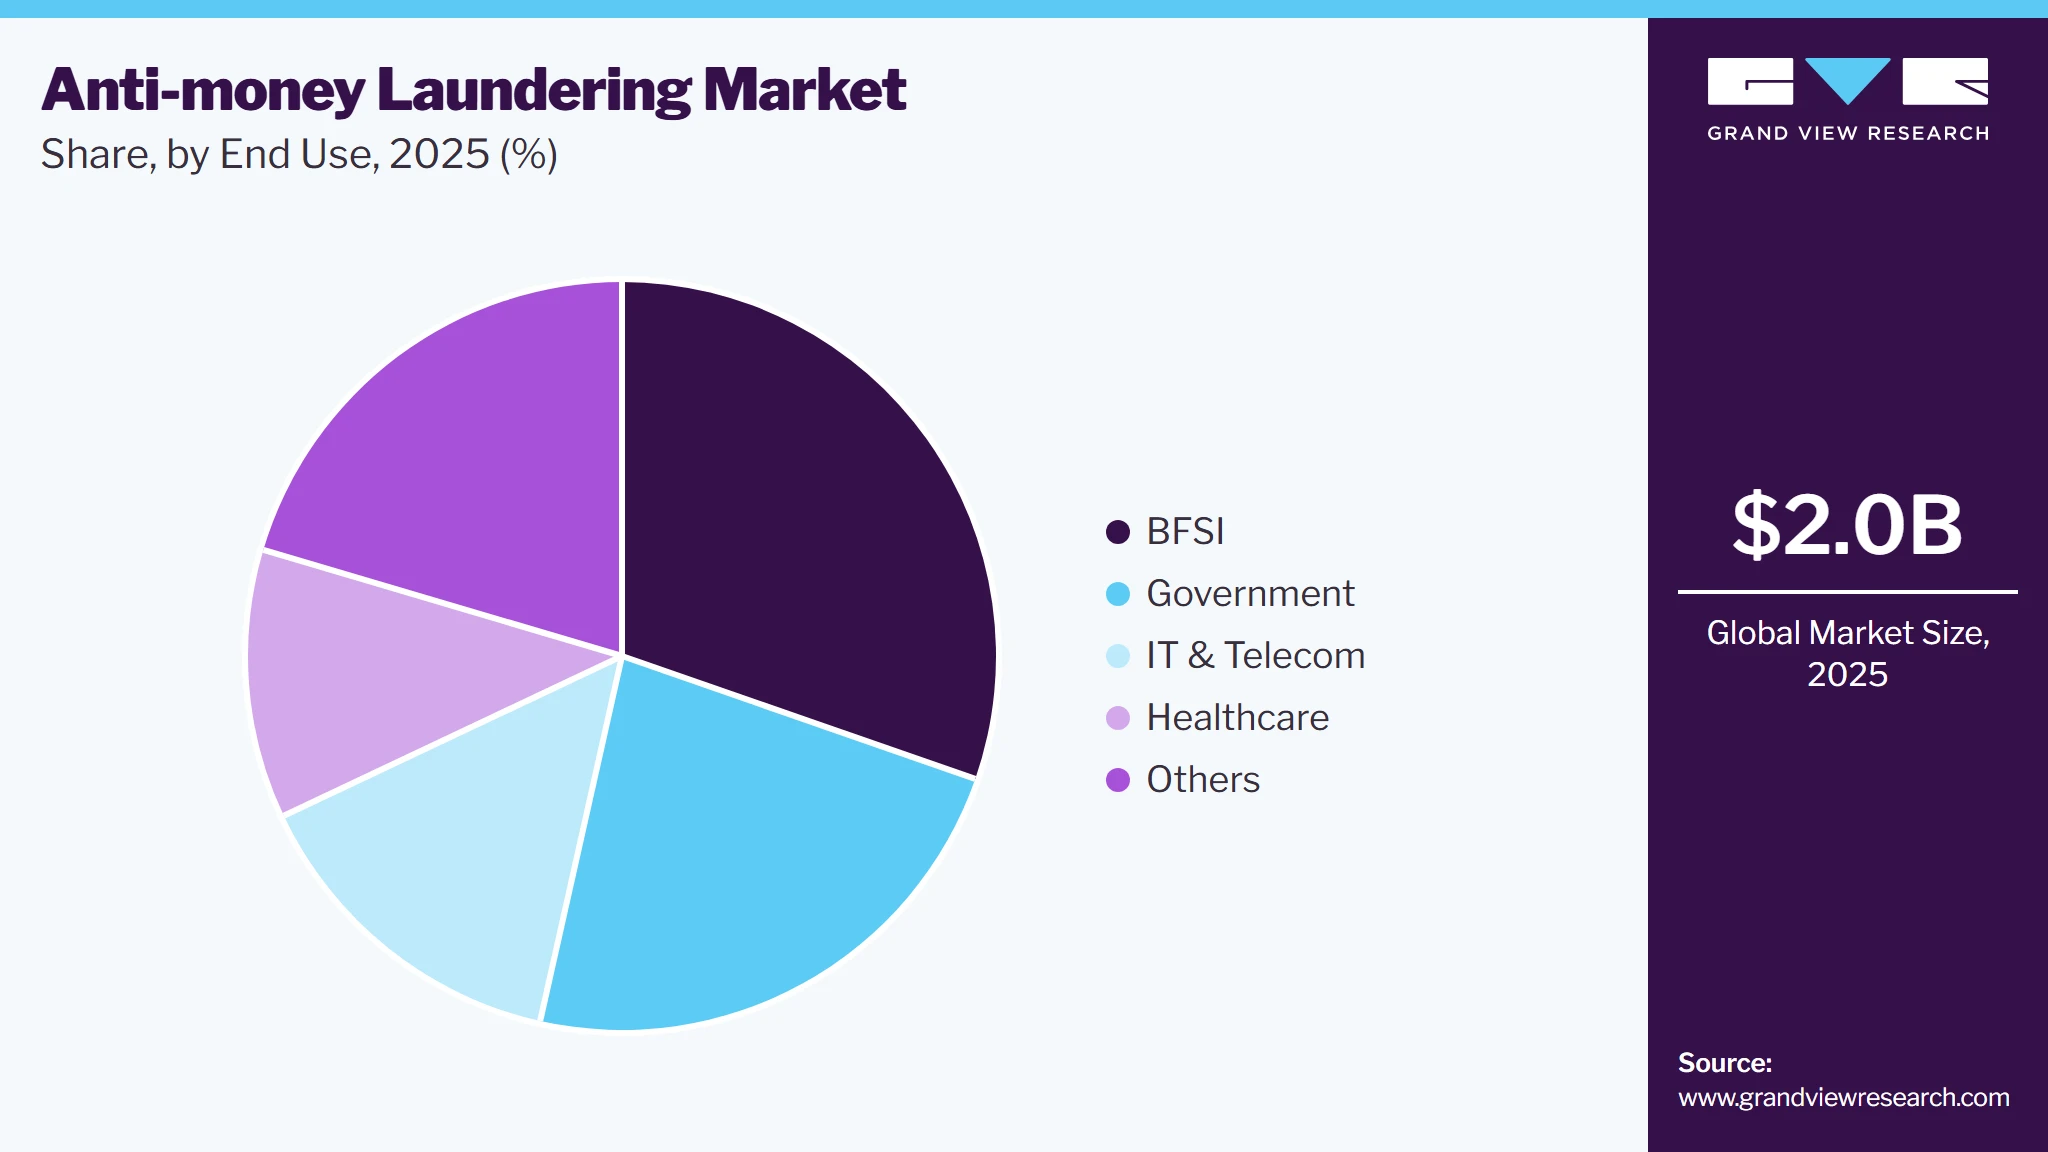
Based on end use, the BFSI segments led the market with the largest revenue share of 30.3% in 2025. High fines imposed on banks for violating anti-money laundering laws are expected to drive the growth of the segment. With these penalties being potentially crippling, banks are now placing a greater emphasis on investing in advanced technologies and systems that can better detect and prevent money laundering activities. The risk of significant financial loss and damage to reputation is driving banks to improve their compliance strategies, making this a priority in their operations. This shift is anticipated to fuel growth in the anti-money laundering market, as banks around the world seek to upgrade their systems to prevent regulatory breaches.
 To learn more about this report, Download Free Sample Report
The government segment is expected to grow significantly from 2026 to 2033. Anti-money laundering software is widely used by government bodies to reduce tax abuses, corruption, cybercrimes, foreign and domestic terrorist financing, human trafficking, and other crimes. Anti-money laundering solutions enable government agencies to detect, monitor, and investigate suspicious financial transactions, thereby reducing the risk of these activities occurring within the public sector. By implementing robust anti-money laundering frameworks, governments can enhance transparency and trust in public institutions, ensuring that taxpayer funds are used appropriately and that the financial system is protected from abuse.
Regional Insights
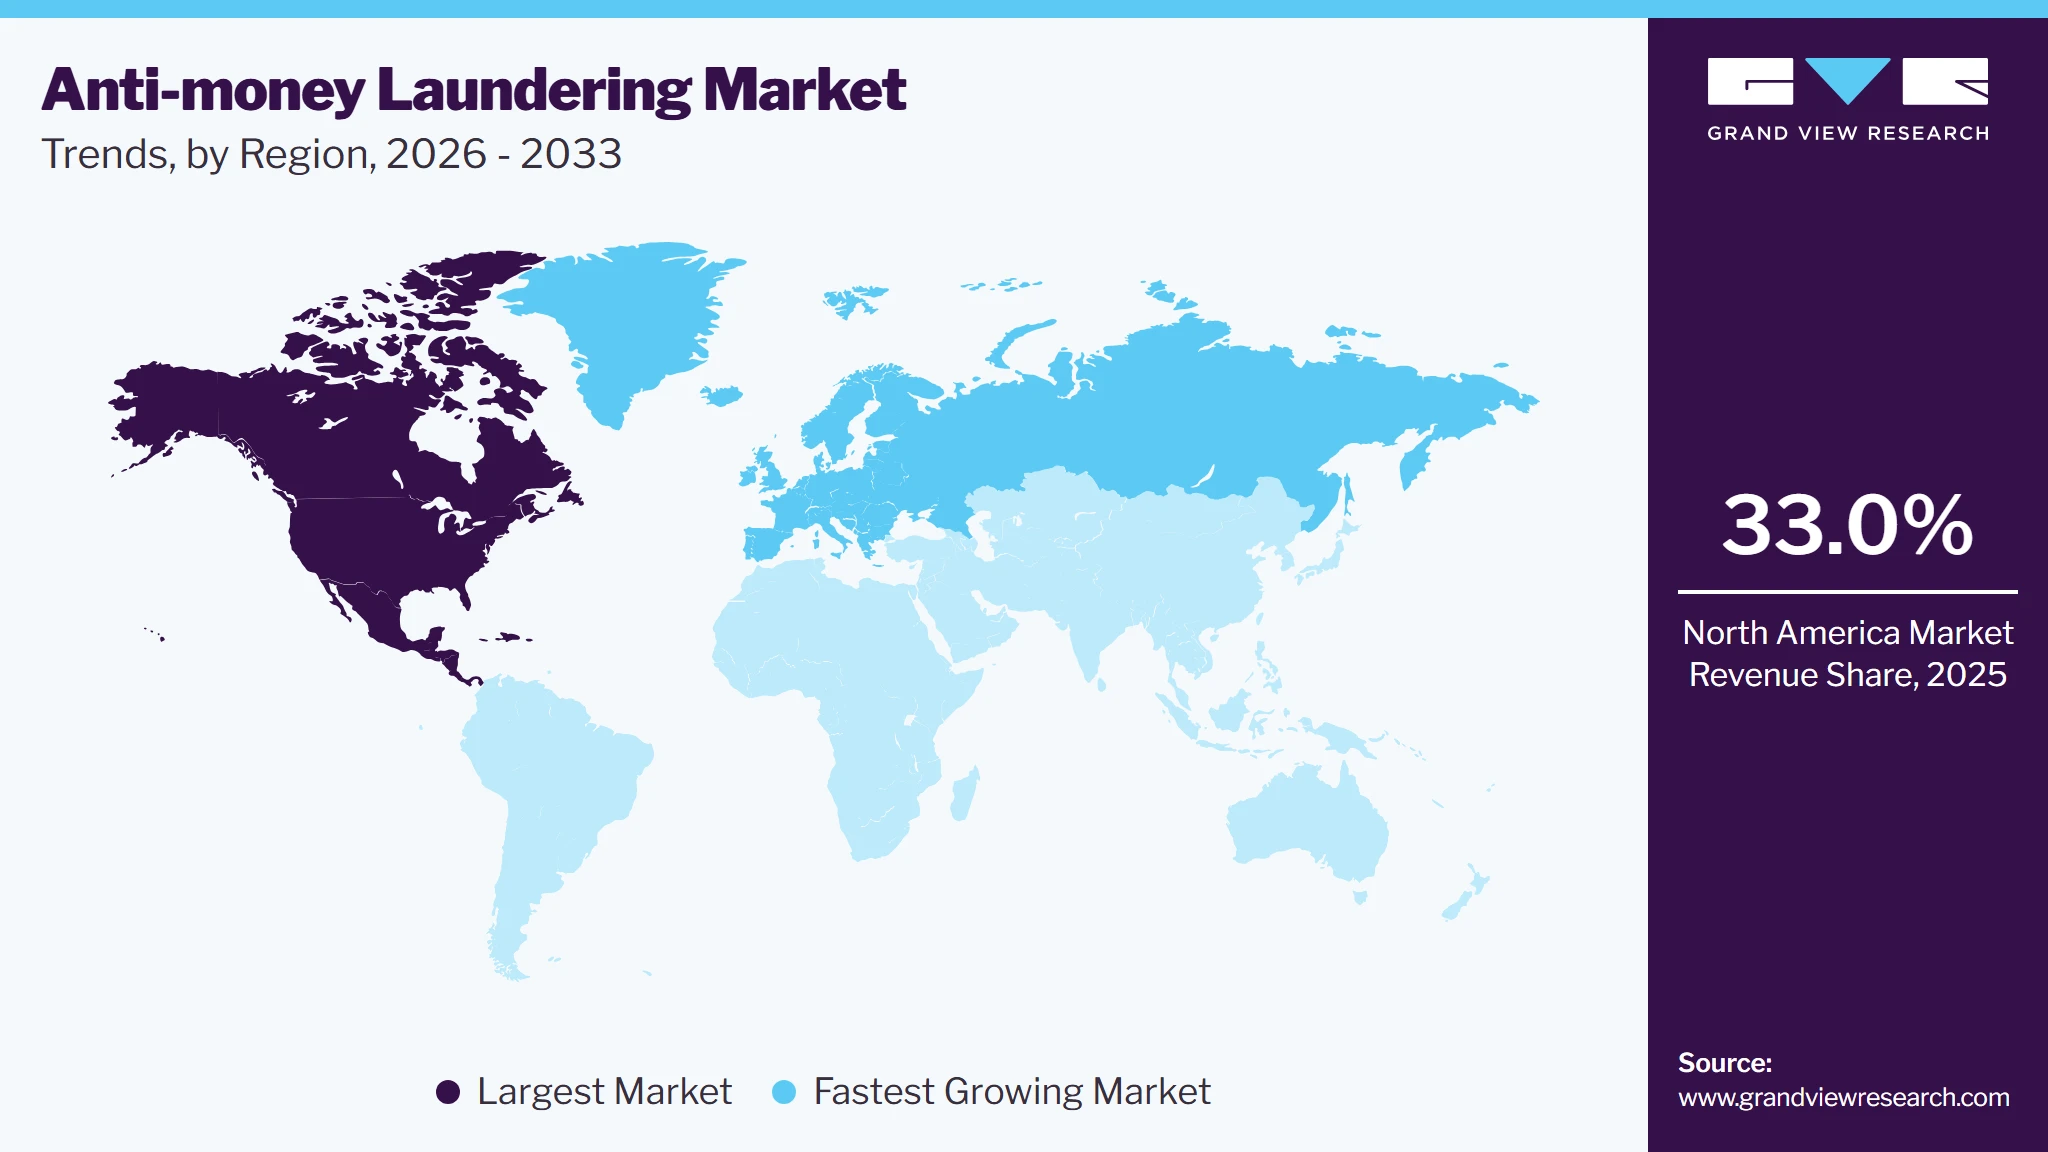
North America anti-money laundering market dominated the global market and accounted for 33.0% in 2024. North America holds the largest share in the anti-money laundering (AML) market due to its stringent regulatory environment and the strong enforcement of anti-money laundering laws. The region is home to major financial institutions that are required to comply with complex regulations, driving demand for advanced anti-money laundering solutions. Additionally, North America invests highly in cutting-edge technologies, such as AI and machine learning, which are integral to modern anti-money laundering systems. The presence of well-established financial hubs, along with the increasing volume of financial transactions, further contributes to the region's dominant position in the anti-money laundering market.
 To learn more about this report, Download Free Sample Report
U.S. Anti-Money Laundering Industry Trends
The anti-money laundering market in the U.S. held the largest share in the North America region in 2025. According to the 2024 Money Laundering and Financial Crime Report, the U.S. recorded a total of 11,472 anti-money laundering events, highlighting the growing need for robust anti-money laundering solutions. This surge in anti-money laundering incidents underscores the importance of implementing sophisticated systems to effectively address and mitigate financial crimes across the country.
Asia Pacific Anti-Money Laundering Industry Trends
The Asia Pacific anti-money laundering industryis anticipated to register significant growth from 2026 to 2033. The expansion of financial services and the rise in cross-border transactions in Asia Pacific are further fueling the demand for advanced AML solutions. Additionally, the region's rapid economic growth and the modernization of its financial systems are contributing to the increased focus on AML compliance. As regulatory oversight intensifies, Asia Pacific's AML market is expected to experience substantial growth in the coming years.
The Japan anti-money laundering industry is expected to grow steadily in the coming years, driven by heightened regulatory scrutiny and advancements in financial technology. The Japanese government, through agencies such as the Financial Services Agency (FSA), is strengthening anti-money laundering measures to align with global standards set by the Financial Action Task Force (FATF). Japan's stringent compliance requirements, coupled with its increasing reliance on digital banking and payment systems, are propelling demand for robust AML solutions.
Anti-money laundering market in China holds a substantial share in the Asia-Pacific region, fueled by the country’s strong commitment to combating financial crimes and fostering a stable financial ecosystem. The People’s Bank of China (PBOC) has been at the forefront of enforcing AML regulations and promoting compliance across financial institutions and non-banking entities.
Europe Anti-money Laundering Market Trends
The European anti-money laundering market is poised for significant growth from 2026 to 2033. The European Union has implemented stringent directives, such as the Anti-Money Laundering Directive (AMLD), which mandates comprehensive anti-money laundering measures across member states. European financial institutions are investing in advanced anti-money laundering solutions to meet these regulatory demands and avoid substantial penalties. Additionally, the region’s diverse and interconnected financial landscape requires robust systems to monitor cross-border transactions effectively. As a result, Europe's commitment to maintaining financial integrity and transparency is driving the growth of its anti-money laundering market.
The UK anti-money laundering market is poised for substantial growth, driven by its status as a global financial hub and the increasing complexity of financial crimes. The U.K.'s robust regulatory framework, governed by the Financial Conduct Authority (FCA) and the National Crime Agency (NCA), mandates stringent compliance measures for financial institutions. The implementation of the Fifth and Sixth Anti-Money Laundering Directives (5AMLD and 6AMLD) has further heightened the focus on combating financial crime.
Anti-money laundering market in Germany is growing rapidly, underpinned by the country’s strong regulatory landscape and its role as a key financial center in the European Union. Germany’s Federal Financial Supervisory Authority (BaFin) has intensified its efforts to combat money laundering, particularly in response to increasing risks associated with its robust banking, real estate, and automotive industries.
Key Anti-Money Laundering Company Insights
Key players operating in the anti-money laundering market are NICE Actimize, Cognizant Technology Solutions Corporation, SAS Institute, Inc., and others. Businesses are primarily focusing on offering on-premise software solutions to enterprises owing to security-related benefits. Moreover, the on-premise anti-money laundering solutions help businesses enhance their security level and thereby improve the satisfaction level of their customers.
-
NICE Actimize is a prominent company in financial crime, risk, and compliance solutions, offering advanced anti-money laundering (AML) software tailored for financial institutions. The company’s portfolio includes solutions like Suspicious Activity Monitoring (SAM), Customer Due Diligence (CDD), and Watchlist Filtering. NICE Actimize employs artificial intelligence and machine learning to enhance the detection of illicit activities, reduce false positives, and improve regulatory compliance efficiency.
-
SAS Institute, Inc. is a global analytics leader offering a comprehensive suite of anti-money laundering solutions designed to help financial institutions meet compliance requirements and mitigate financial crime risks. The company's AML software combines advanced analytics, machine learning, and big data capabilities to deliver real-time transaction monitoring, automated alert management, and efficient customer due diligence processes.
Key Anti-Money Laundering Companies:
The following key companies have been profiled for this study on the anti-money laundering market.
- NICE Actimize
- Tata Consultancy Services Limited
- Cognizant Technology Solutions Corporation
- ACI Worldwide, Inc.
- SAS Institute, Inc.
- Fiserv, Inc.
- Oracle Corporation
- BAE Systems
- Accenture
- Open Text Corporation
- Experian Information Solutions, Inc.
Competitive Benchmarking
Category
Operating Strategies
Competitive Edge
Weakness
Established Players (NICE Actimize, SAS Institute, Inc., Oracle Corporation, Accenture)
- These players are focused on end-to-end AML platforms, deep regulatory alignment, and enterprise-scale deployments
- These players have strong analytics capabilities, global client base, and regulatory credibility.
- High cost of ownership and complex implementations
Emerging Players (ACI Worldwide, Inc., Fiserv, Inc., Open Text Corporation)
- These players are focused on emphasis on modular solutions, cloud integration, and targeted AML offerings.
- These players have agility, strong integration with payment and data platforms.
- Limited breadth compared to full-suite AML leaders
Recent Developments
-
In September 2024, Tech Mahindra Limited, a global leader in technology consulting, has partnered with Discai, a BankTech subsidiary of the KBC Group, to deliver an advanced AI-powered Anti-Money Laundering (AML) solution. The collaboration combines Tech Mahindra’s IT integration expertise with Discai’s AI-driven and rule-based AML technology to enhance transaction monitoring and ensure regulatory compliance. The solution, known as KYT AML (Know Your Transaction Anti-Money Laundering), is designed to effectively detect and prevent financial crimes. By leveraging AI and rule-based methodologies, it helps financial institutions streamline compliance processes and adhere to stringent regulatory frameworks.
-
In June 2023, Google Cloud launched an AI-powered Anti Money Laundering (AML) product designed to help financial institutions detect money laundering efficiently. The AML AI system utilized machine learning to enhance risk detection, reduce operational costs, and improve compliance by minimizing false positives. HSBC, one of the early adopters, reported detecting 2-4 times more suspicious activities while reducing alert volumes by over 60%. The product was implemented across various global jurisdictions, offering benefits such as increased accuracy and reduced investigation time.
Anti-Money Laundering Market Report Scope
Report Attribute
Details
Market size in 2025
USD 2.0 billion
Estimated Market size in 2026
USD 2.3 billion
Projected Market size by 2033
USD 6.8 billion
Growth rate
CAGR of 16.6% from 2026 to 2033
Base year for estimation
2025
Historical data
2021 - 2024
Forecast period
2026 - 2033
Quantitative units
Revenue in USD million and CAGR from 2026 to 2033
Report coverage
Revenue forecast, company market share, competitive landscape, growth factors, and trends
Segments covered
Component, product, deployment, enterprise size, end use, region
Regional scope
North America; Europe; Asia Pacific; Latin America; MEA
Country scope
U.S.; Canada; Mexico; Germany; U.K.; France; China; Japan; India; South Korea; Australia; Brazil; Saudi Arabia; UAE; and South Africa
Key companies profiled
NICE Actimize; Tata Consultancy Services Limited; Cognizant Technology Solutions Corporation; ACI Worldwide Inc.; SAS Institute Inc.; Fiserv, Inc.; Oracle Corporation; BAE Systems; Accenture; and Open Text Corporation
Customization scope
Free report customization (equivalent up to 8 analysts' working days) with purchase. Addition or alteration to country, regional & segment scope.
Pricing and purchase options
Avail customized purchase options to meet your exact research needs. Explore purchase options
Global Anti-Money Laundering Market Report Segmentation
The report forecasts revenue growth at global, regional, and country levels and provides an analysis of the latest industry trends in each of the sub-segments from 2021 to 2033. For this study, Grand View Research has segmented the anti-money laundering market based on component, product, deployment, enterprise size, end use, and region.
-
Component Outlook (Revenue, USD Million, 2021 - 2033)
-
Software
-
Services
-
-
Product Outlook (Revenue, USD Million, 2021 - 2033)
-
Compliance Management
-
Currency Transaction Reporting
-
Customer Identity Management
-
Transaction Monitoring
-
-
Deployment Outlook (Revenue, USD Million, 2021 - 2033)
-
Cloud
-
On-premise
-
-
Enterprise Size Outlook (Revenue, USD Million, 2021 - 2033)
-
Large Enterprises
-
Small & Medium Enterprises
-
-
End Use Outlook (Revenue, USD Million, 2021 - 2033)
-
BFSI
-
Government
-
Healthcare
-
IT & Telecom
-
Others
-
-
Regional Outlook (Revenue, USD Million, 2021 - 2033)
-
North America
-
U.S.
-
Canada
-
Mexico
-
-
Europe
-
UK
-
Germany
-
France
-
-
Asia Pacific
-
China
-
India
-
Japan
-
South Korea
-
Australia
-
-
Latin America
-
Brazil
-
-
Middle East & Africa (MEA)
-
Kingdom of Saudi Arabia (KSA)
-
UAE
-
South Africa
-
-
Research Methodology
The anti-money laundering market figures in this report are based on a proven research process that combines executive interviews with secondary research from proprietary databases, company filings, and recognized regulatory and institutional sources. Market size is built through value-chain sizing - reconciling supply-side and demand-side estimates - and triangulated with bottom-up and top-down approaches. Every estimate passes multiple levels of expert validation before publication, with each anti-money laundering segment quantified using the revenue-capture definitions in the table below.
Segment Definition
Component
Revenue capture definition
Software
Revenue generated from licensing or subscription of AML platforms, including transaction monitoring engines, case management systems, analytics modules, reporting tools, and AI/ML-based risk scoring software.
Services
Revenue derived from implementation, system integration, consulting, regulatory advisory, model tuning, training, managed services, and ongoing technical support related to AML solutions.
Product
Revenue capture definition
Compliance Management
Revenue generated from licensing, subscriptions, and maintenance fees for software that manages AML policies, regulatory rule updates, audit workflows, case management, and regulatory reporting compliance.
Currency Transaction Reporting
Revenue generated from solutions that automate detection, aggregation, and regulatory filing of cash transactions above mandated thresholds, including software licenses, reporting modules, and compliance update services.
Customer Identity Management
Revenue generated from identity verification, KYC onboarding tools, customer risk profiling, screening against sanctions/PEP lists, biometric verification, and ongoing customer due diligence platforms.
Transaction Monitoring
Revenue generated from real-time and batch transaction monitoring software that detects suspicious patterns, generates alerts, supports investigations, and enables suspicious activity reporting.
Deployment
Revenue capture definition
Cloud
Revenue generated from subscription-based AML platforms delivered through cloud infrastructure, including SaaS licensing, usage-based pricing, upgrades, remote access features, and cloud security services.
On-Premise
Revenue generated from perpetual software licenses, infrastructure-dependent deployments, system customization, integration services, internal maintenance contracts, and compliance-specific upgrades.
Enterprise Size
Revenue capture definition
Large Enterprises
Revenue generated from enterprise-scale AML deployments covering high transaction volumes, multi-entity operations, advanced analytics, customization, integration with core systems, and long-term support contracts.
Small & Medium Enterprises
Revenue is generated from cost-effective AML solutions such as cloud subscriptions, simplified monitoring tools, basic compliance modules, and managed AML services tailored to regulatory requirements.
End Use
Revenue capture definition
BFSI
Revenue generated from AML software and services used by banks, insurers, fintechs, and financial institutions for customer due diligence, transaction monitoring, fraud detection, and regulatory compliance.
Government
Revenue generated from AML platforms deployed by regulatory bodies, financial intelligence units, tax authorities, and law enforcement agencies for monitoring illicit financial flows and compliance enforcement.
Healthcare
Revenue generated from AML and fraud detection tools is used to monitor billing, insurance claims, payment flows, and misuse of healthcare funds.
IT & Telecom
Revenue generated from AML and transaction monitoring solutions is used to manage digital payments, subscription billing, mobile money, and large-scale customer transaction data.
Others
Revenue is generated from AML solutions adopted by industries such as retail, real estate, gaming, energy, and e-commerce to monitor high-value transactions and meet sector-specific compliance requirements.
Estimation Model
Layer Name
Key Question
Description
Regulatory Exposure Layer
Which industries are mandated to adopt AML solutions?
This layer identifies sectors subject to AML regulations, including BFSI, fintech, and government entities. It evaluates regulatory scope, reporting obligations, and enforcement intensity across regions. Regulatory exposure determines the addressable market baseline.
Technology Adoption Layer
What AML technologies are being implemented?
This layer analyzes adoption of transaction monitoring, identity management, analytics, and reporting tools. It differentiates between legacy systems and next-generation AI-driven platforms. Deployment preferences such as cloud versus on-premise are also assessed.
Spending & Deployment Layer
How much is spent on AML software and services?
This layer evaluates organizational spending patterns across software licenses, subscriptions, and professional services. It accounts for enterprise size, transaction volumes, and maturity compliance. Spending intensity varies significantly across developed and emerging markets.
Revenue Realization Layer
How is vendor revenue generated and scaled?
This layer aggregates vendor revenues based on software, services, renewals, and upgrades. It captures recurring revenue models and long-term contracts. Competitive positioning and customer retention influence revenue scalability.
Delivered Customizations
This report has been delivered with the following In-depth customizations
Client Request
Customization Delivered
Value Adds
Regional Anti-money Laundering Market Opportunity Assessment
- Country/region-wise market sizing and forecasts
- Analysis of demand, adoption trends, and regulatory landscape
- Identification of high-growth regions and investment hotspots
- Identified region-specific growth opportunities
- Supported expansion and go-to-market strategy
- Enabled informed regional investment decisions
Cross-Segmentation Analysis for the Anti-money Laundering Market
- Criss-cross market analysis by component, product, deployment, enterprise size, end use
- Demand and adoption assessment across key segments
- Segment attractiveness and growth potential benchmarking
- Identified high-potential market segments
- Supported targeted product positioning and marketing strategy
- Improved customer and segment prioritization
Competitive Benchmarking and Strategic Positioning in the Anti-money Laundering Market
- Benchmarking of key competitors across products, pricing, partnerships, and innovation
- Comparative assessment of market share, capabilities, and strategies
- Analysis of competitive strengths, gaps, and differentiation areas
- Identified competitive white spaces and growth gaps
- Supported strategic positioning and differentiation
- Enabled data-driven competitive strategy development
Frequently Asked Questions About This Report
The global anti-money laundering market size was estimated at USD 2.0 billion in 2025 and is expected to reach USD 2.3 billion in 2026.
The global anti-money laundering market is expected to grow at a compound annual growth rate of 16.6% from 2026 to 2033, reaching USD 6.8 billion by 2033.
Software segment dominated the market, with a revenue share of 62.9% in 2025. The segment growth can be attributed to an increase in demand for anti-money laundering software among banks and payment solution providers.
Some key players operating in the anti-money laundering market include NICE Actimize, Tata Consultancy Services Limited, Cognizant Technology Solutions Corporation, ACI Worldwide, Inc., SAS Institute, Inc., Fiserv, Inc., Oracle Corporation, BAE Systems, Accenture, Open Text Corporation, and Experian Information Solutions, Inc.
The growth of the market is driven by increasingly stringent regulations and the need for financial institutions to comply with global standards.
North America dominated the global market with the largest revenue share of 33.0% in 2025. North America holds the largest share in the anti-money laundering (AML) market due to its stringent regulatory environment and the strong enforcement of anti-money laundering laws.
Compliance Management segment held the largest market share of 28.1% in 2025, while customer identity management is the fastest-growing segment over the forecast period.
On-Premise segment accounted for the largest revenue share of 54.7% in 2025, while cloud is the fastest-growing segment over the forecast period.
Large Enterprises segment accounted for the largest revenue share of 68.0% in 2025, while small & medium enterprises is the fastest-growing segment over the forecast period.
About the Author(s)
Next Generation Technologies Research Team
Technology · Next Generation TechnologiesThis report was authored by the next generation technologies research team at Grand View Research - comprising two research analysts, one senior research analyst, and one industry expert - with specialized expertise in the next generation technologies segment of the technology industry. All findings are based on proprietary technology databases, executive interviews, and regulatory analysis, subject to internal peer review prior to publication.
Last Updated:
Speak to Analyst

Customize this report to your needs - add regions, segments, or data points, with 20% free customization.
Or view our licence options:


ISO 9001:2015 & 27001:2022 Certified
We are GDPR and CCPA compliant! Your transaction & personal information is safe and secure. For more details, please read our privacy policy.


