
- Home
- »
- Pharmaceuticals
- »
-
Anti-vascular Endothelial Growth Factor Therapeutics Market Report, 2026-2033GVR Report cover

Anti-vascular Endothelial Growth Factor Therapeutics Market (2026 - 2033)
Size, Share & Trends Analysis Report By Product (Eylea, Lucentis, Beovu), By Disease (Macular Edema, Diabetic Retinopathy, Retinal Vein Occlusion), By Region, And Segment Forecasts
Market Size, 2025
$14.5BMarket Estimate, 2026
$14.3BMarket Forecast, 2033
$11.8BCAGR, 2026–2033
-2.7%Anti-vascular Endothelial Growth Factor Therapeutics Market Summary
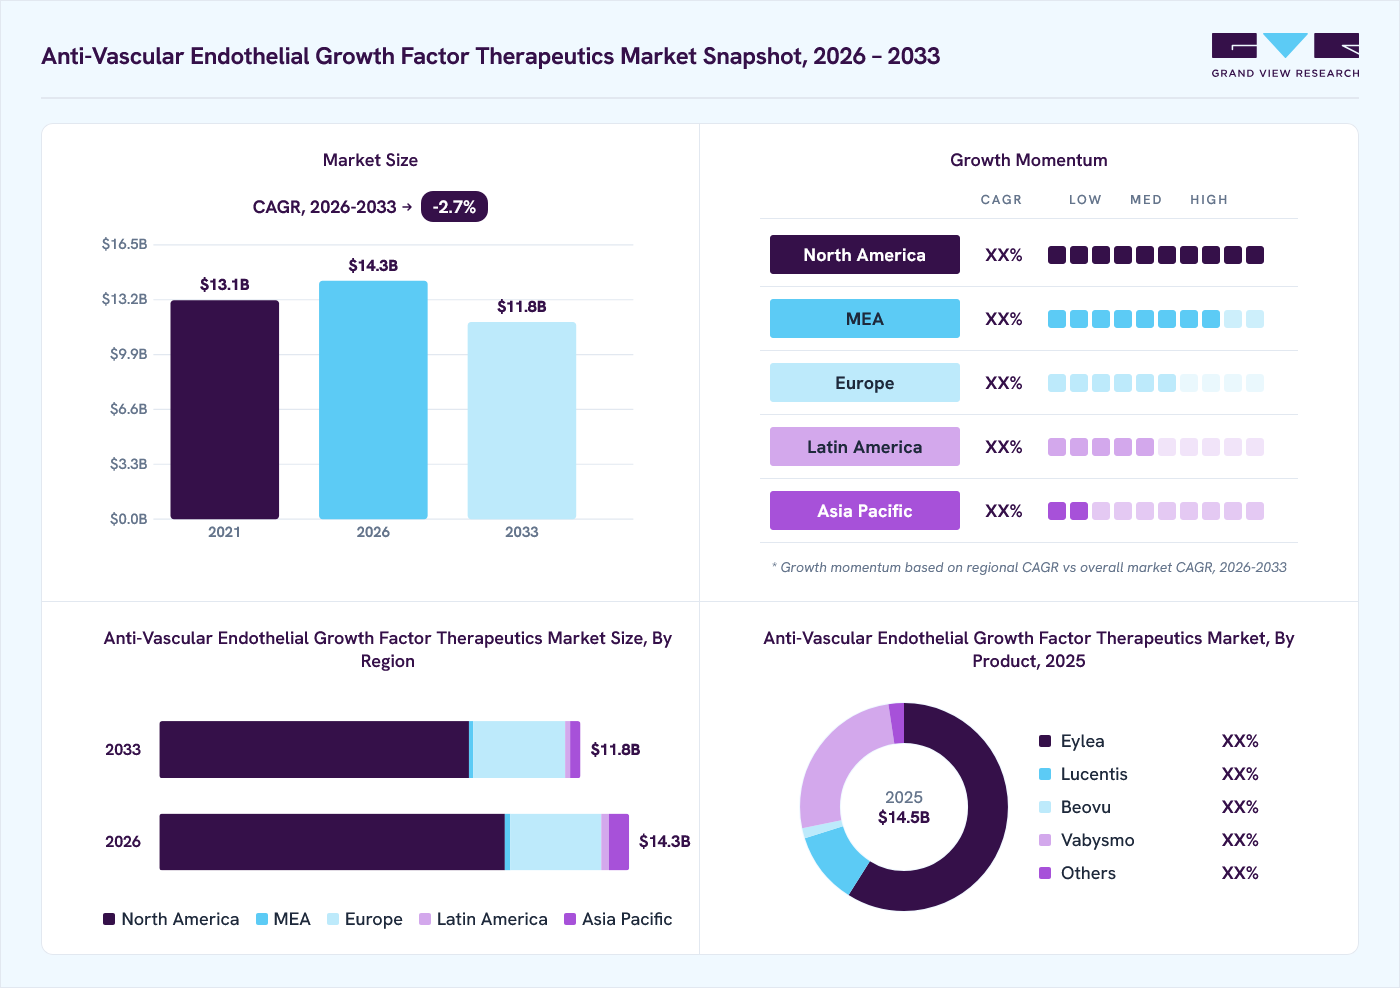
The global anti-vascular endothelial growth factor therapeutics market size was valued at USD 14.5 billion in 2025 and is projected to grow from USD 14.3 billion in 2026 to USD 11.8 billion by 2033, at a CAGR of -2.7% from 2026 to 2033. The market in North America dominated with a revenue share of 66.7% in 2025. The emergence of biosimilars in the market is contributing to a significant decline in revenue.
 Source: Grand View Research, IR Documents, Primary Interviews, Paid DatabasesTo learn more about this report,
 Download Free Sample Report
Key Market Trends & Insights
- By product: Eylea segment held the largest market share of 58.9% in 2025.
- By disease: Age-related macular degeneration segment held the largest market share of 52.8% in 2025.
Regional Highlights
- Largest regional market: North America (66.7% revenue share, 2025)
- By country: The U.S. held the largest market share in 2025
Market Size & Forecast
- Market size in 2025: USD 14.5 Billion
- Estimated market size in 2026: USD 14.3 Billion
- Projected market size by 2033: USD 11.8 Billion
- CAGR (2026-2033): -2.7%
Prism AI by Grand View Research Free to tryAsk a question about the anti-vascular endothelial growth factor therapeutics marketTry asking✓Every figure cited from GVR research Prefer the report? Download free sample →
As these lower-cost alternatives gain approval, they enhance competition, prompting healthcare providers to favor them over branded therapies. This shift is exacerbated by the increasing pipeline of biosimilars targeting established anti-vascular endothelial growth factor (anti-VEGF) treatments, which pressures pricing and reduces market share for original products. Consequently, the presence of biosimilars is reducing the overall value of the anti-VEGF therapeutics market as patient access expands, while profitability for traditional therapies diminishes.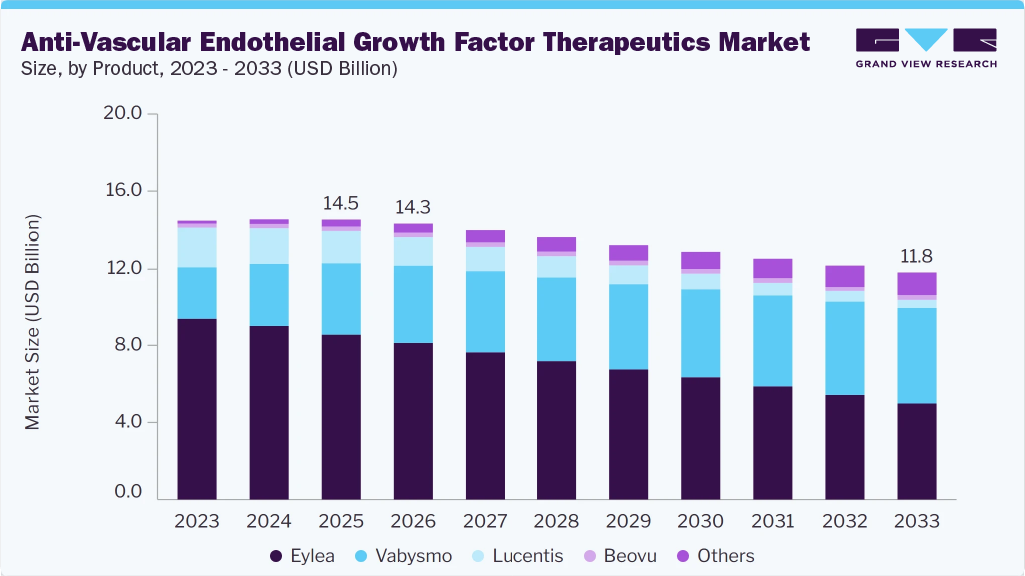 To learn more about this report, Download Free Sample Report
The anti-VEGF therapeutics industry has witnessed considerable advancements in drug delivery and development, driven by the need to improve efficacy, safety, and patient compliance. The core objective of anti-VEGF therapy is to inhibit angiogenesis, a process that plays a pivotal role in conditions such as age-related macular degeneration (AMD), diabetic retinopathy, and certain cancers. The recent innovations in this market are not only enhancing treatment outcomes but also revolutionizing how these therapies are administered, offering significant implications for healthcare providers and pharmaceutical companies.
Awareness campaigns initiated by healthcare organizations, patient advocacy groups, and educational institutions have played a critical role in highlighting the importance of regular eye examinations and prompt intervention. In July 2024, the Mary Tyler Moore Vision Initiative launched its inaugural public service announcement (PSA) campaign, featuring narration by Academy Award-winning actor Kevin Kline. The campaign also includes contributions from notable figures such as Oprah Winfrey, Julia Louis-Dreyfus, and Reese Witherspoon. Such initiatives aim to raise awareness about the importance of funding medical research focused on finding a cure for diabetic retinal disease, a condition that impacted Moore during the later years of her life. This shift in focus has not only facilitated earlier detection but also improved treatment outcomes, thereby fostering greater demand for anti-VEGF therapies.
However, despite the therapeutic benefits, these anti-VEGF agents are associated with a range of potential side effects and safety concerns that warrant careful consideration by healthcare providers and patients, including blurred vision, eye pain, increased intraocular pressure, and other severe allergic reactions. Moreover, the potential for adverse events increases with the duration of therapy. Long-term use of anti-VEGF agents may lead to cumulative toxicities, raising concerns about their safety in chronic conditions that require extended treatment periods, which is anticipated to negatively impact the market growth in the forecast period.
Market Dynamics
The Anti-Vascular Endothelial Growth Factor Therapeutics Market is experiencing gradual contraction due to increasing biosimilar penetration, pricing pressures, and the maturity of established anti-VEGF products across key markets. While the prevalence of retinal disorders such as age-related macular degeneration, diabetic retinopathy, diabetic macular edema, and retinal vein occlusion continues to sustain treatment demand, revenue growth is being constrained by intensified competition from lower-cost alternatives and reimbursement optimization initiatives. Healthcare providers are increasingly adopting biosimilar and cost-effective treatment strategies, particularly in developed markets where anti-VEGF therapies have achieved broad penetration. The market continues to benefit from the clinical effectiveness of anti-VEGF agents in preserving vision and managing disease progression, while innovations in longer-acting formulations help improve patient convenience and treatment adherence. However, patent expirations, limited pricing flexibility, and slower uptake in certain emerging markets continue to pressure overall market revenues. Despite the anticipated market decline, ongoing product enhancements, expanded access to retinal care, and the development of next-generation therapies are expected to support stable demand and maintain competitive activity throughout the forecast period.
The anti-vascular endothelial growth factor therapeutics market is primarily driven by the rising prevalence of retinal disorders and the growing adoption of anti-VEGF therapies as standard treatment options. The rising incidence of age-related macular degeneration, diabetic macular edema, diabetic retinopathy, and retinal vein occlusion is creating sustained demand for effective vision-preserving therapies. Growth in the elderly population and the global increase in diabetes cases are further contributing to the expanding patient pool requiring long-term retinal care. Anti-VEGF therapies have demonstrated strong clinical effectiveness in controlling disease progression and maintaining visual acuity, thereby strengthening physicians' confidence and treatment adoption. In addition, advancements in formulation technology are enabling longer dosing intervals, reducing treatment burden, and improving patient adherence. Regulatory approvals of enhanced anti-VEGF products are also supporting wider market penetration and expanding treatment accessibility across healthcare systems. As healthcare providers continue to prioritize early diagnosis and intervention for retinal diseases, demand for anti-VEGF therapeutics is expected to remain strong. For instance, in January 2024, Santen Pharmaceutical Co., Ltd. and Bayer Yakuhin announced that Japan’s Ministry of Health, Labor and Welfare had approved Eylea 8 mg for the treatment of neovascular age-related macular degeneration and diabetic macular edema. The approval was supported by the PULSAR and PHOTON clinical trials, which demonstrated non-inferior visual acuity outcomes with dosing intervals of 12 weeks or 16 weeks compared with the 8-week regimen used for Eylea 2 mg.
Pricing pressure and growing biosimilar competition continue to act as significant restraints on the Anti-Vascular Endothelial Growth Factor Therapeutics Market. While anti-VEGF therapies provide substantial clinical benefits, their relatively high treatment costs place pressure on healthcare budgets and reimbursement systems. Many healthcare providers and payers are increasingly seeking cost-effective treatment alternatives to address rising expenditures associated with chronic retinal disease. The entry of biosimilars has intensified market competition by offering comparable efficacy and safety profiles at lower prices. As a result, original product manufacturers face challenges in maintaining pricing power and market share. Patent expirations and regulatory approvals of biosimilar products are accelerating this competitive shift, particularly in mature pharmaceutical markets. Although companies are pursuing lifecycle management strategies through new formulations and expanded indications, the growing availability of lower-cost alternatives continues to influence purchasing decisions and reimbursement policies. This competitive environment may limit revenue growth opportunities for established brands. For instance, in June 2024, Formycon AG and Klinge Biopharma GmbH announced that the U.S. Food and Drug Administration had approved FYB203/AHZANTIVE, an aflibercept biosimilar, for neovascular age-related macular degeneration, diabetic macular edema, diabetic retinopathy, and macular edema following retinal vein occlusion.
The development of long-acting and next-generation anti-VEGF therapies represents a significant opportunity for market expansion. One of the major challenges associated with current anti-VEGF treatment regimens is the need for frequent intravitreal injections, which can affect patient adherence and increase the burden on healthcare facilities. Pharmaceutical companies are therefore investing heavily in innovative formulations designed to extend treatment durability while maintaining clinical effectiveness. Higher-dose products, advanced biologics, and therapies targeting multiple disease pathways are gaining attention for the potential to reduce injection frequency and improve patient convenience. These innovations can enhance treatment outcomes and strengthen physicians' preference for newer therapeutic options. Growing demand for more efficient disease management solutions among aging populations is also creating favorable conditions for product adoption. As healthcare systems increasingly emphasize value-based care, therapies capable of delivering sustained efficacy with fewer administrations are expected to gain significant commercial traction. For instance, in April 2026, Regeneron Pharmaceuticals announced that the U.S. Food and Drug Administration had approved EYLEA HD with dosing intervals of up to 20 weeks for wet age-related macular degeneration and diabetic macular edema. The approval was supported by 96-week clinical data and enabled eligible patients to receive treatment only 2 to 3 times annually, highlighting the market potential of long-acting anti-VEGF therapies.
Analyst Perspective
The Anti Vascular Endothelial Growth Factor Therapeutics Market continues to evolve through product innovation, longer dosing intervals, and increasing adoption of advanced retinal disease therapies. Market growth is supported by the rising prevalence of age-related macular degeneration, diabetic retinopathy, and retinal vein occlusion, particularly among aging and diabetic populations. Leading companies are focusing on high dose formulations and durable treatment options that reduce injection frequency and improve patient adherence. The competitive landscape is becoming more dynamic with the entry of biosimilars and next generation biologics, creating pricing pressure while expanding patient access. Continued investment in retinal disease research and global commercialization strategies is expected to support sustained market expansion over the forecast period.
Product Insights
Based on Product, the Eylea segment led the market with the largest revenue share of 58.9% in 2025. Eylea (aflibercept), developed by Regeneron Pharmaceuticals in collaboration with Bayer, has been a foremost anti-VEGF therapy for treating retinal diseases such as wet age-related macular degeneration (AMD), diabetic macular edema (DME), and retinal vein occlusion (RVO). Its proven effectiveness in stabilizing vision has notably driven its market traction. For instance, in October 2024, Regeneron Pharmaceuticals, Inc. expanded the availability of Eylea (aflibercept), with approval in the U.S. for a higher dose regimen that offers more convenient dosing intervals. However, as the anti-VEGF therapeutics market becomes increasingly competitive, EYLEA’s growth is anticipated to face challenges due to rising competition and market saturation.
The others segment, which includes biosimilars and pipeline therapies, is expected to grow at a significant CAGR of 14.7% over the forecast period. Biosimilars are increasingly used to treat conditions such as neovascular age-related macular degeneration (nAMD) and diabetic macular edema (DME), which are the leading causes of vision loss worldwide. The rise in biosimilar adoption is driven by cost-effectiveness and expanded patient access across regions, notably in emerging markets, where cost constraints often limit access to innovative biologics. Recent trends indicate steady market expansion for biosimilars as healthcare providers and systems seek alternative, affordable treatment options.
Disease Insights
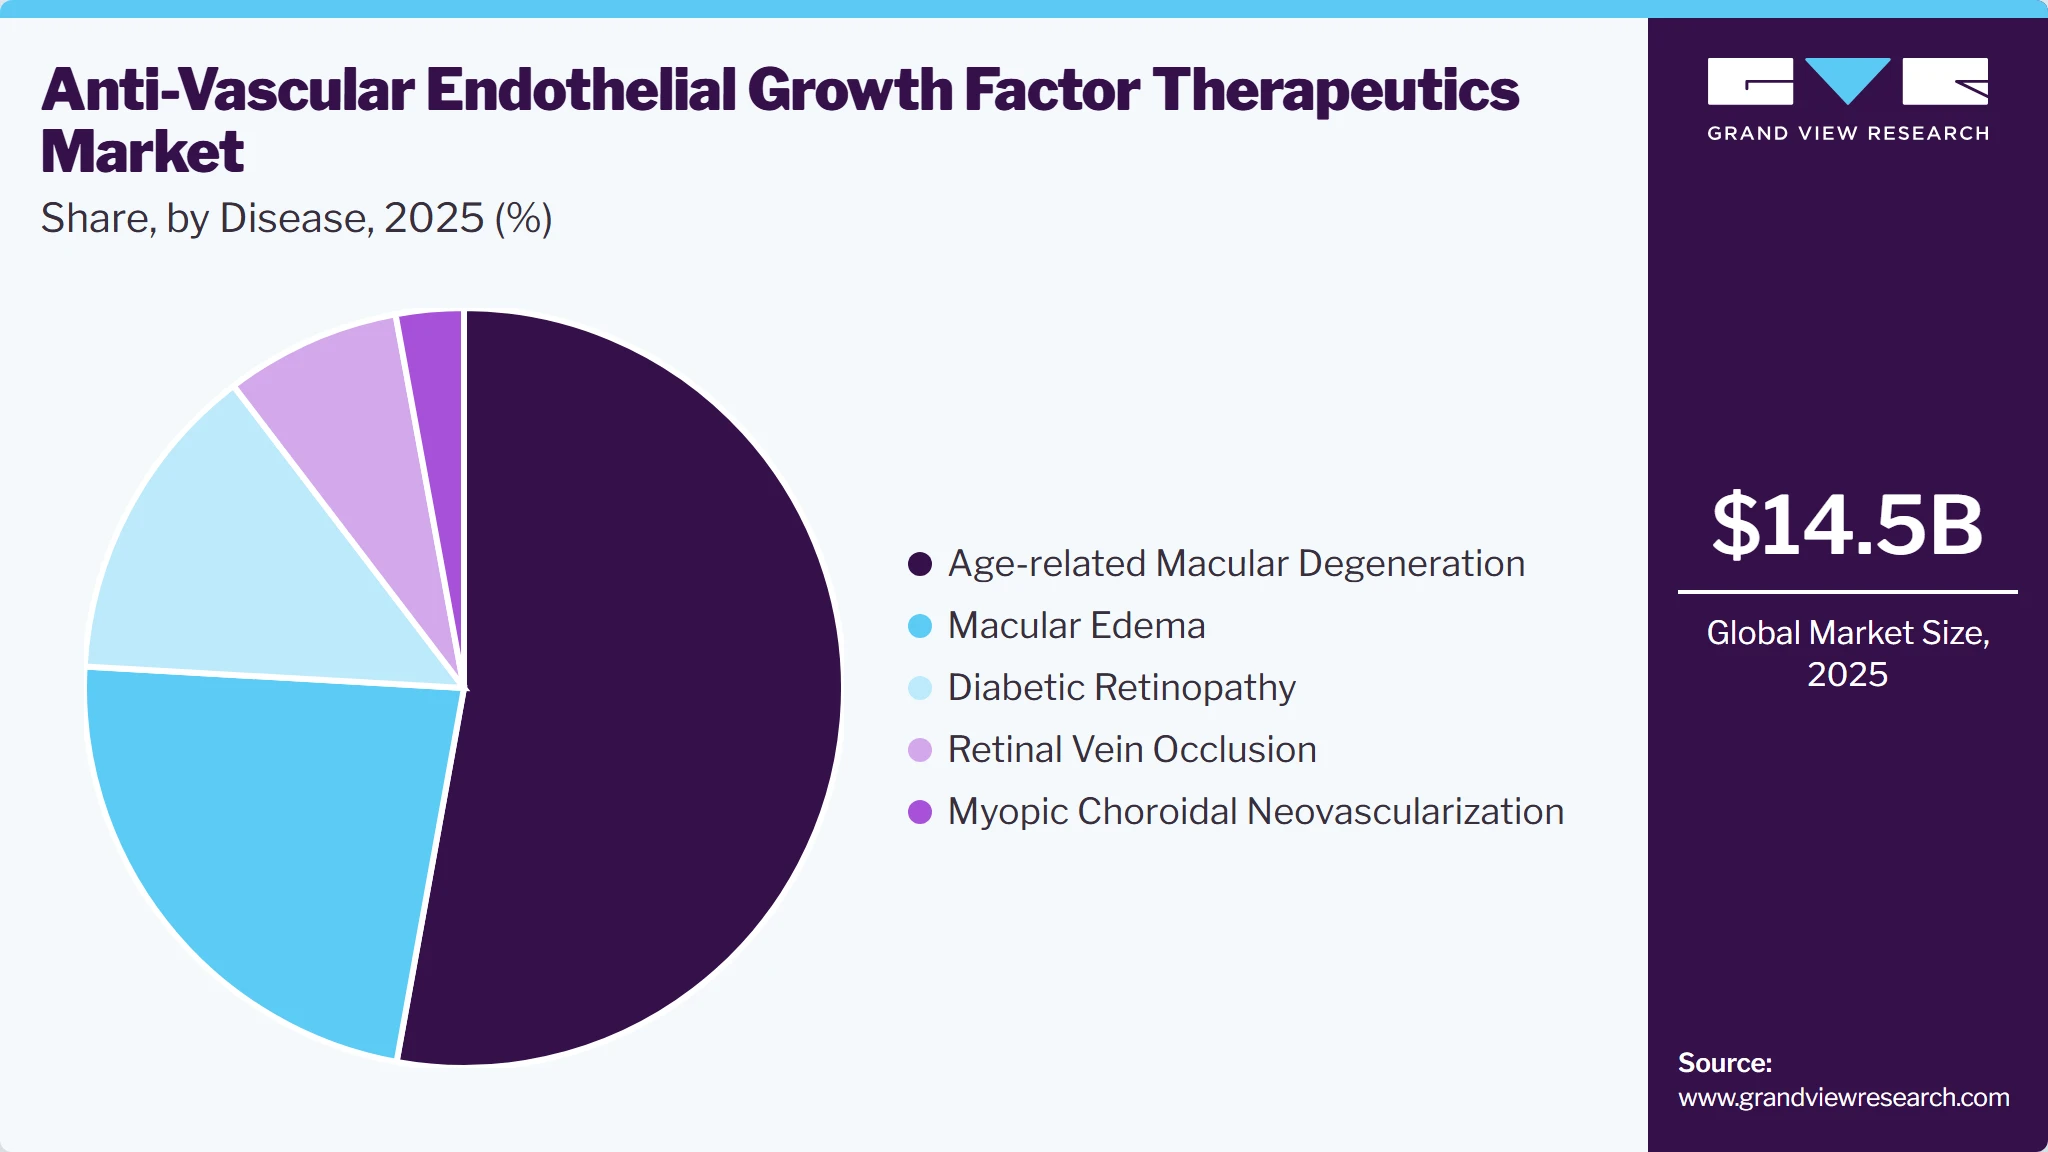
Based on Disease, the age-related macular degeneration segment led the market with the largest revenue share of 52.8% in 2025, driven by rising disease prevalence, advancements in drug formulations, and expanding access to healthcare. AMD is one of the primary causes of vision loss in older adults, marked by the degeneration of the macula, which is essential for central vision. This disease affects millions globally, with the prevalence estimated at approximately 8.7% in adults aged 45 and older and significantly higher rates in those over 75. According to the study titled "Age-Related Macular Degeneration: Epidemiology, Pathophysiology, Diagnosis, and Treatment," published in Cureus in September 2022, it is projected that nearly 5.4 million Americans will have AMD by 2050. The study also stated that AMD affects approximately 200 million people worldwide, with projections reaching nearly 300 million by 2040. Thus, the increasing prevalence of AMD is a major driver for the segment’s growth.
 To learn more about this report, Download Free Sample Report
Macular Edema held the second-largest share in 2025. The segment for anti-VEGF therapeutics in macular edema is witnessing an upward trajectory as cases of DME and RVO increase globally. The growing incidence of diabetes and related complications drives demand for effective treatments. Anti-VEGF agents are instrumental in delaying disease progression, improving vision quality, and lowering the long-term care burden. Notable companies capitalize on this growth potential with product launches, approvals, and M&A activities. Regeneron Pharmaceuticals, Inc. (October 2024), for instance, expanded the availability of Eylea (aflibercept), an anti-VEGF therapy, with approval in the U.S. for a higher dose regimen that offers more convenient dosing intervals
Regional Insights
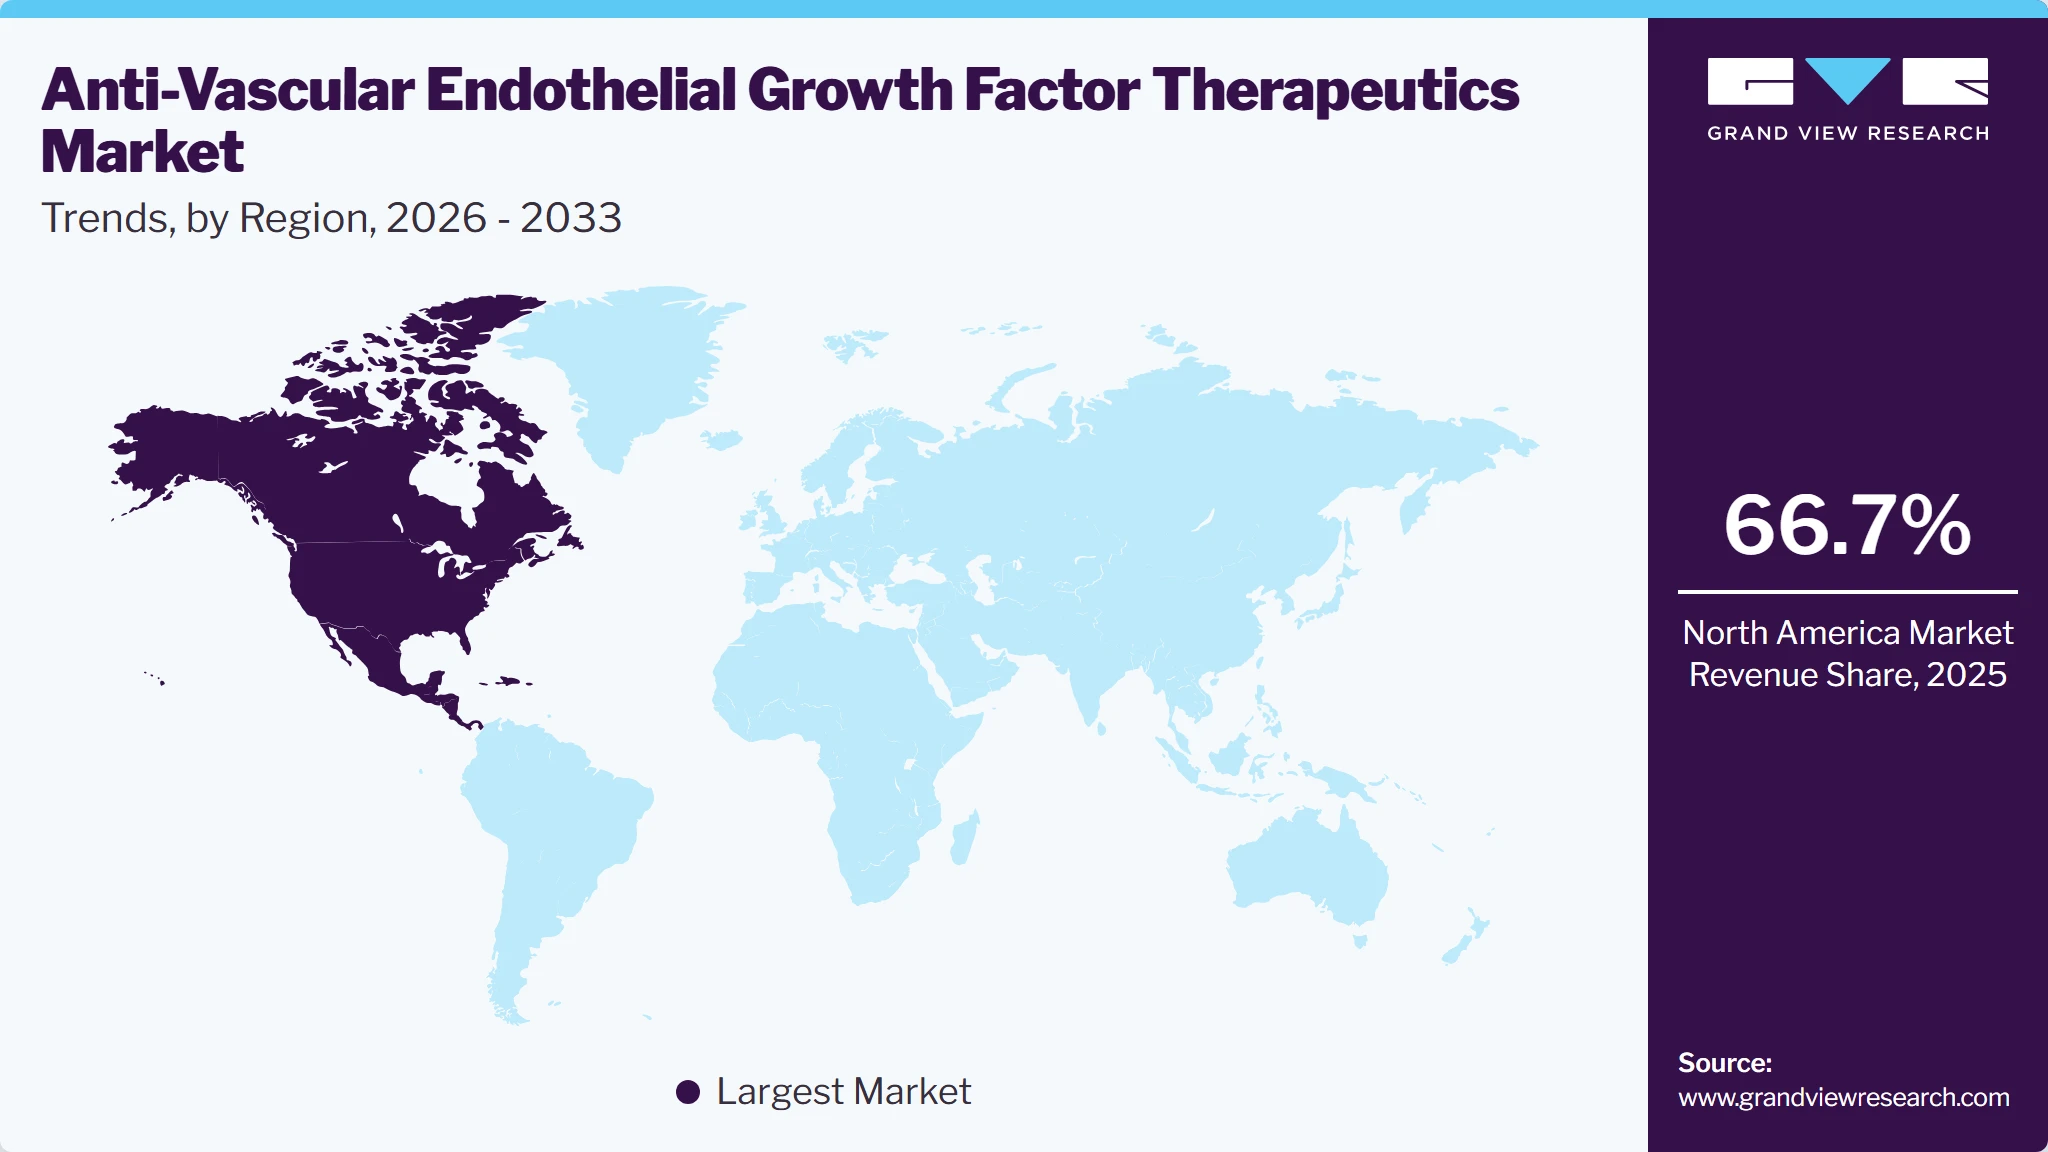
North America dominated the anti-vascular endothelial growth factor therapeutics market with the largest revenue share of 66.7% in 2025, which can be attributed to the increasing prevalence of eye-related conditions such as age-related macular degeneration (AMD), diabetic retinopathy, retinal vein occlusion, and macular edema. Key companies in the region are engaged in strategic collaborations and product enhancements to address evolving patient needs and maintain their competitive positions. For instance, in August 2023, the U.S. FDA approved Eylea HD (aflibercept), a high-dose version of the original Eylea developed by Regeneron Pharmaceuticals and Bayer AG. Additionally, increased healthcare spending and investments in the biotechnology sector are attributed to the emergence of biosimilars to offer more affordable options in anti-VEGF therapies.
 To learn more about this report, Download Free Sample Report
U.S. Anti-vascular Endothelial Growth Factor Therapeutics Market Trends
The anti-vascular endothelial growth factor therapeutics market in the U.S. held the largest share in the North America region in 2025, driven by advancements in research and development by players such as Biogen, Amgen, and F. Hoffmann-La Roche. Moreover, partnerships and acquisitions among major players, such as Pfizer, Inc., Bausch Health Companies, Inc., and Viatris, Inc., are reshaping the competitive landscape as companies seek to expand their product portfolios and gain a foothold in this high-value market. For instance, in January 2023, Coherus BioSciences announced an agreement to acquire exclusive U.S. commercial rights to FYB203, a biosimilar candidate for Eylea (aflibercept) from Klinge Biopharma.
Europe Anti-vascular Endothelial Growth Factor Therapeutics Market Trends
The anti-vascular endothelial growth factor therapeutics market in Europe is driven by an aging population and increasing prevalence of vision-related diseases such as age-related macular degeneration (AMD), diabetic retinopathy, macular edema, and retinal vein occlusion. Advancements in drug delivery systems, such as longer-acting injectables and sustained-release implants, are expected to boost the regional market. For instance, in September 2024, Regeneron Pharmaceuticals, Inc. shared new analyses of EYLEA HD (aflibercept) and EYLEA (aflibercept) injections of 8mg and 2 mg at the Annual Meeting of the European Society of Retina Specialists (EURETINA), held in Barcelona from September 19-22, 2024.
The UK anti-vascular endothelial growth factor therapeutics market is driven by an increasing prevalence of ocular conditions such as age-related macular degeneration (AMD), diabetic retinopathy, macular edema, and retinal vein occlusion. In addition, regulatory approvals in the region help deliver new treatments to patients more quickly and contribute to revenue generation. For instance, in January 2024, the UK Medicines and Healthcare Products Regulatory Agency (MHRA) approved Bayer's Eylea 8mg (aflibercept) for the treatment of neovascular (wet) age-related macular degeneration (nAMD) and visual impairment associated with diabetic macular edema (DMO).
The anti-vascular endothelial growth factor therapeutics market in Germany is influenced by developments in the treatment of eye diseases, such as diabetic macular edema (DME). For instance, a study published in the SAGE Journal highlights that in 2022, the prevalence of clinically significant DME in Germany ranged from 1% to 1.4%, with an estimated 160,000 patients newly diagnosed with diabetic eye disease each year.
Asia Pacific Anti-vascular Endothelial Growth Factor Therapeutics Market Trends
The anti-vascular endothelial growth factor therapeutics market in the Asia Pacific is influenced by the growing healthcare reforms in the region, aided by improved healthcare infrastructure, a growing population, and an increase in the number of companies entering the market. Age-related diseases, especially age-related macular degeneration (AMD), diabetic retinopathy (DR), macular edema, and retinal vein occlusion (RVO), are growing concerns as the population ages and diabetes prevalence increases in this region.
Japan anti-vascular endothelial growth factor therapeutics market is influenced by the rapidly aging population. A scientific report published in Japan in November 2023 noted that 10 million people in the country are affected by diabetes mellitus (DM), with 3 million experiencing diabetic retinopathy (DR). DR is the third leading cause of visual impairment, accounting for 12.8% of visual disorders. Japan, being the hub for the highest proportion of the elderly population in the world, significantly impacts the market.
Latin America Anti-vascular Endothelial Growth Factor Therapeutics Market Trends
The anti-vascular endothelial growth factor therapeutics market in Latin America exhibits high growth potential due to the expanding healthcare infrastructure and increased awareness of chronic eye conditions among aging populations.
The Brazil anti-vascular endothelial growth factor therapeutics industry exhibits a growing demand for advanced ophthalmic solutions, particularly for diseases such as diabetic macular edema and retinal vein occlusion. The increasing prevalence of ophthalmic diseases fuels the demand for such treatments and further contributes to market growth. For instance, a study published in BMC Ophthalmology in December 2021 found that age-related macular degeneration (AMD) prevalence in Brazil rises significantly with age: from 1.5% to 16.7% in individuals aged 50 and older, reaching 15.1% in those over 60, and climbing to 31.5% among those 80 and older.
Middle East And Africa Anti-vascular Endothelial Growth Factor Therapeutics Market Trends
The anti-vascular endothelial growth factor therapeutics market in the Middle East and Africa is driven by the increasing prevalence of retinal conditions such as diabetic retinopathy (DR) and age-related macular degeneration (AMD), especially in urban areas with rising diabetes rates. According to the World Health Organization (WHO), an estimated 26.3 million people in the African Region experience some level of visual loss. Among them, approximately 20.4 million have low vision, while about 5.9 million are blind. Africa is home to around 15.3% of the global population living with blindness.
Saudi Arabia anti-vascular endothelial growth factor therapeutics market is largely supported by the government’s steady commitment to healthcare modernization under Vision 2030. With a rising burden of age-related and diabetes-induced retinal disorders, Saudi Arabia has seen significant demand for anti-VEGF drugs. A 2023 study published by NCBI reported that in Saudi Arabia, diabetic retinopathy (DR) affects between 28.1% and 45.7% of individuals with diabetes. Among these, vision-threatening DR is present in approximately 4.5% to 17.5% of diabetic patients, which increases the need for effective anti-VEGF therapies.
Key Anti-vascular Endothelial Growth Factor Therapeutics Company Insights
The market is highly competitive due to several strategic initiatives, such as new product launches, mergers and acquisitions, and regional expansion, undertaken by key market players to increase their global footprints. Companies are diversifying their product portfolios to address a broader range of applications.
Key Anti-vascular Endothelial Growth Factor Therapeutics Companies:
The following key companies have been profiled for this study on the anti-vascular endothelial growth factor therapeutics market.
-
Regeneron Pharmaceuticals, Inc.
-
Bayer AG
-
Novartis AG
-
F. Hoffmann-La Roche Ltd.
-
Biogen
-
Pfizer, Inc.
-
Coherus BioSciences, Inc.
-
Amgen, Inc.
-
Bausch Health Companies, Inc.
-
Viatris, Inc.
Competitive Benchmarking
Category
Operating Strategies
Competitive Edge
Weakness
Large Integrated Pharmaceutical Companies (Regeneron Pharmaceuticals, Inc., Bayer AG, Novartis AG, F. Hoffmann-La Roche Ltd., Pfizer, Inc., Amgen, Inc.)
- Expand anti-VEGF portfolios through indication expansions, lifecycle management initiatives, development of high-dose and long-acting formulations, and global commercialization strategies. Invest in next-generation retinal therapies, combination approaches, and clinical studies to reduce treatment burden. Strengthen market position through strategic collaborations, licensing agreements, and geographic expansion across established and emerging ophthalmology markets.
- Strong global commercial networks, extensive regulatory and clinical development expertise, established relationships with ophthalmologists and healthcare institutions, and advanced biologics manufacturing capabilities. Broad financial resources enable large-scale research investments, rapid market access initiatives, and sustained portfolio expansion across multiple therapeutic areas.
- High research, development, and manufacturing costs are associated with biologic therapies. Exposure to pricing pressures, reimbursement challenges, biosimilar competition, and evolving regulatory requirements across multiple regions. Large organizational structures may reduce operational flexibility and slow strategic decision-making in niche market segments.
Ophthalmology and Specialty Biopharmaceutical Companies (Biogen, Bausch Health Companies, Inc., Coherus BioSciences, Inc., Viatris, Inc.)
- Focus on strengthening ophthalmology portfolios through biosimilar development, targeted retinal disease therapies, strategic licensing agreements, and commercialization partnerships. Emphasize cost-competitive treatment options, regional market expansion, and differentiated product positioning to increase market penetration. Pursue selective investments in retinal disease innovation and specialty care channels.
- Specialized expertise in ophthalmology and retinal disease management, greater organizational agility, focused commercial strategies, and the ability to address underserved market opportunities. Competitive positioning in biosimilars and specialty products supports access to cost-sensitive healthcare systems and emerging markets.
- More limited financial resources, research capabilities, and commercial reach compared with multinational pharmaceutical companies. Greater dependence on a smaller number of products and partnerships increases exposure to competitive, regulatory, and market access risks. Limited manufacturing scale and global distribution capabilities may restrict long-term growth potential.
Recent Developments
-
In January 2026, the European Commission approved Eylea 8 mg (aflibercept) for visual impairment caused by macular edema following retinal vein occlusion, including branch, central, and hemiretinal vein occlusion. The approval expanded the product's European indications and provided a longer-acting treatment option for patients with RVO-associated macular edema.
-
In November 2025, the U.S. FDA approved EYLEA HD (aflibercept 8 mg) for macular edema following retinal vein occlusion (RVO), with dosing intervals of up to eight weeks after an initial monthly dosing period. The FDA also approved a monthly dosing option for selected patients across its approved indications.
-
In July 2024, Genentech, a member of the Roche Group, announced promising two-year Phase III data for Susvimo (ranibizumab injection), presented at the ASRS 2024 Annual Meeting. The results demonstrate Susvimo's sustained efficacy in treating diabetic macular edema (DME) and diabetic retinopathy (DR).
-
In March 2024, Roche Pharma India launched Vabysmo (faricimab) in India for the treatment of neovascular age-related macular degeneration and diabetic macular edema. Vabysmo targets both angiopoietin-2 and vascular endothelial growth factor A, thereby restoring vascular stability.
Anti-vascular Endothelial Growth Factor Therapeutics Market Report Scope
Report Attribute
Details
Market size in 2025
USD 14.5 billion
Estimated market size in 2026
USD 14.3 billion
Projected market size by 2033
USD 11.8 billion
Growth rate
CAGR of -2.7% from 2026 to 2033
Historical data
2021 - 2024
Forecast period
2026 - 2033
Quantitative units
Revenue in USD million/billion and CAGR from 2026 to 2033
Report coverage
Revenue forecast, company ranking, competitive landscape, growth factors, and trends
Segments covered
Product, disease, and region
Regional scope
North America; Europe; Asia Pacific; Latin America; MEA
Country scope
U.S.; Canada; Mexico; Germany; UK; France; Italy; Spain; Norway; Denmark; Sweden; China; Japan; India; South Korea; Australia; Thailand; Brazil; Argentina; Saudi Arabia; South Africa; UAE; Kuwait
Key companies profiled
Regeneron Pharmaceuticals, Inc., Bayer AG, Novartis AG, F. Hoffmann-La Roche Ltd., Biogen, Pfizer, Inc., Coherus BioSciences, Inc., Amgen, Inc., Bausch Health Companies, Inc., Viatris, Inc.
Customization scope
Free report customization (equivalent to 8 analyst working days) with purchase. Addition or alteration to country, regional & segment scope.
Pricing and purchase options
Avail customized purchase options to meet your exact research needs. Explore purchase options
Global Anti-vascular Endothelial Growth Factor Therapeutics Market Report Segmentation
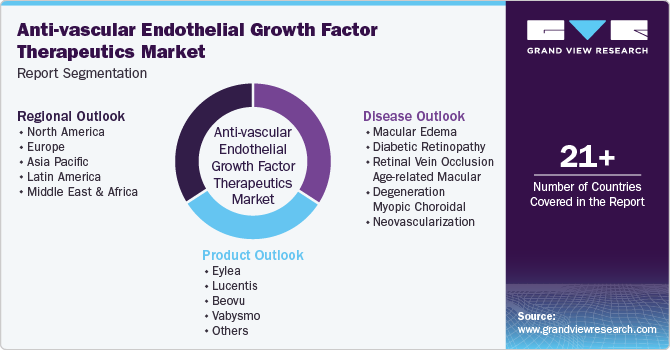
This report forecasts revenue growth at the global, regional, and country levels and provides an analysis of the latest trends in each of the sub-segments from 2021 to 2033. For this study, Grand View Research has segmented the global anti-vascular endothelial growth factor therapeutics market report on the basis of product, disease, and regions:
 To learn more about this report, Download Free Sample Report
-
Product Outlook (Revenue, USD Million, 2021 - 2033)
-
Eylea
-
Lucentis
-
Beovu
-
Vabysmo
-
Others
-
-
Disease Outlook (Revenue, USD Million, 2021 - 2033)
-
Macular Edema
-
Diabetic Retinopathy
-
Retinal Vein Occlusion
-
Age-related Macular Degeneration
-
Myopic Choroidal Neovascularization
-
-
Regional Outlook (Revenue, USD Million, 2021 - 2033)
-
North America
-
U.S.
-
Canada
-
Mexico
-
-
Europe
-
UK
-
Germany
-
France
-
Italy
-
Spain
-
Denmark
-
Sweden
-
Norway
-
-
Asia Pacific
-
Japan
-
China
-
India
-
Australia
-
South Korea
-
Thailand
-
-
Latin America
-
Brazil
-
Argentina
-
-
Middle East and Africa (MEA)
-
South Africa
-
Saudi Arabia
-
UAE
-
Kuwait
-
-
Research Methodology
The anti-vascular endothelial growth factor therapeutics market figures in this report are based on a proven research process that combines executive interviews with secondary research from proprietary databases, company filings, and recognized regulatory and institutional sources. Market size is built through value-chain sizing - reconciling supply-side and demand-side estimates - and triangulated with bottom-up and top-down approaches. Every estimate passes multiple levels of expert validation before publication, with each anti-vascular endothelial growth factor therapeutics segment quantified using the revenue-capture definitions in the table below.
Segment Definition
Segment - Product
Revenue capture definition
Eylea
Revenue generated from Eylea (aflibercept), an anti-VEGF therapy approved for the treatment of retinal diseases, including age-related macular degeneration, diabetic retinopathy, diabetic macular edema, retinal vein occlusion, and myopic choroidal neovascularization, where applicable. This segment includes all revenue derived from Eylea across approved indications and future label expansions. Revenue attributable to Eylea is reported exclusively within this segment.
Lucentis
Revenue generated from Lucentis (ranibizumab), an anti-VEGF monoclonal antibody fragment used for the treatment of retinal vascular disorders. This segment includes all sales associated with Lucentis across approved indications, including age-related macular degeneration, diabetic retinopathy, diabetic macular edema, retinal vein occlusion, and myopic choroidal neovascularization. Revenue from Lucentis is classified solely within this category.
Beovu
Revenue generated from Beovu (brolucizumab), an anti-VEGF therapy indicated for retinal diseases, including neovascular age-related macular degeneration and other approved retinal conditions. This segment encompasses all commercial sales of Beovu, regardless of geographic market, treatment setting, or approved indication. Revenue is attributed exclusively to this segment.
Vabysmo
Revenue generated from Vabysmo (faricimab), a bispecific angiopoietin 2 and VEGF inhibitor approved for multiple retinal diseases. This segment includes revenue generated from Vabysmo across all approved indications, including age-related macular degeneration, diabetic macular edema, diabetic retinopathy, and retinal vein occlusion. All Vabysmo-related sales are classified solely within this segment.
Others
Revenue generated from all anti-VEGF therapeutics not separately identified above. This includes products such as Avastin (bevacizumab), biosimilar anti-VEGF products, regional brands, pipeline products commercialized during the forecast period, and future market entrants. Revenue is allocated to this segment only when it does not belong to the individually reported product categories above.
Segment - Disease
Revenue capture definition
Macular Edema
Revenue generated from anti-VEGF therapies prescribed to treat the macular edema, including diabetic macular edema and macular edema associated with other retinal vascular disorders, was categorized under macular edema treatment pathways. Revenue associated with these indications is assigned exclusively to this segment.
Diabetic Retinopathy
Revenue generated from anti-VEGF therapies used in the management of diabetic retinopathy, including both proliferative and non proliferative forms of the disease. This segment captures all sales associated with diabetic retinopathy treatment regardless of product type, treatment duration, or geographic market. Revenue is classified solely within this category.
Retinal Vein Occlusion
Revenue generated from anti-VEGF therapies prescribed for retinal vein occlusion, including branch retinal vein occlusion and central retinal vein occlusion. All revenue associated with the treatment of retinal vein occlusion-related complications is reported exclusively in this segment, regardless of the therapeutic product used.
Age-Related Macular Degeneration
Revenue generated from anti-VEGF therapies used for the treatment of age-related macular degeneration, particularly neovascular or wet age-related macular degeneration. This segment includes all revenue derived from approved anti-VEGF products prescribed for this indication. Revenue attributable to age-related macular degeneration is classified solely within this segment.
Myopic Choroidal Neovascularization
Revenue generated from anti-VEGF therapies used in the treatment of myopic choroidal neovascularization associated with pathological myopia. This segment encompasses all sales associated with anti-VEGF treatment for myopic choroidal neovascularization and is reported exclusively within this category, regardless of product brand or treatment setting.
Estimation Model
The Anti-VEGF Therapeutics Market size is calculated using a combination of secondary research, primary research, and data triangulation techniques. The process begins with identifying all commercially available Anti-VEGF therapies, including Eylea, Lucentis, Beovu, Vabysmo, Avastin, biosimilars, and other regional products. Secondary research is conducted through company annual reports, SEC filings, investor presentations, regulatory agency publications, clinical trial databases, scientific journals, healthcare databases, and government healthcare statistics to gather information on product revenues, treatment adoption rates, approved indications, pricing trends, and patient populations.
A bottom-up approach is used to estimate market revenues by analyzing product-level sales across major regions and indications, including age-related macular degeneration, diabetic retinopathy, diabetic macular edema, retinal vein occlusion, and myopic choroidal neovascularization. Revenue contributions are assessed by country through prescription volume analysis, treatment frequency, average selling prices, reimbursement coverage, and healthcare utilization patterns. Market segmentation is then developed by product, disease indication, distribution channel, and geography. A top-down assessment is performed by evaluating ophthalmology therapeutics expenditure, retinal disease treatment spending, biologics market penetration, and healthcare infrastructure trends to validate overall market estimates.
Primary research includes interviews with ophthalmologists, retina specialists, hospital procurement managers, specialty pharmacy representatives, healthcare payers, distributors, and executives from Anti-VEGF manufacturers. Insights obtained through these interviews are used to validate market assumptions, pricing structures, treatment trends, and future demand projections. Final market estimates are derived through data triangulation, where supply-side revenues, demand-side utilization data, and macro healthcare indicators are reconciled to ensure consistency and accuracy. Forecasting incorporates factors such as disease prevalence growth, aging demographics, biosimilar adoption, regulatory approvals, product innovation, reimbursement developments, and expansion of retinal disease treatment programs across global markets.
Delivered Customizations
This report has been delivered with the following In-depth customizations
Client Request
Customization Delivered
Value Adds
Anti-VEGF Competitive Landscape & Product Portfolio Assessment
Conducted a comprehensive assessment of the global anti-VEGF therapeutics landscape, evaluating marketed products, biosimilars, late-stage pipeline candidates, clinical development activity, and competitive positioning. The study analyzed key market participants, including Regeneron Pharmaceuticals, Bayer AG, Novartis AG, F. Hoffmann-La Roche Ltd., Biogen, Pfizer, Amgen, and other emerging developers. The assessment reviewed product differentiation, dosing durability, indication coverage, regulatory approvals, commercialization strategies, and innovation trends across retinal disease indications.
Helped the client identify competitive threats, evaluate product positioning strategies, benchmark clinical and commercial performance, and prioritize partnership, licensing, and investment opportunities within the evolving anti-VEGF therapeutics market.
Anti-VEGF Technology & Innovation Benchmarking Study
Delivered a detailed benchmarking analysis of anti-VEGF technologies, focusing on molecular design, biologic platforms, extended duration formulations, bispecific antibodies, biosimilar development, and next-generation retinal therapies. The assessment compared commercial and pipeline products based on clinical efficacy, safety profile, treatment durability, patient adherence benefits, and innovation potential. The study also evaluated intellectual property positioning and future technology adoption trends across the ophthalmology sector.
Enabled the client to assess technology competitiveness, identify innovation gaps, benchmark product differentiation strategies, and prioritize investments in next-generation retinal disease treatment platforms and advanced biologic technologies.
Anti-VEGF Manufacturing, Supply Chain & Commercialization Feasibility Assessment
Conducted a strategic assessment of the Anti-VEGF manufacturing and supply chain ecosystem, evaluating biologics production capabilities, fill finish infrastructure, regulatory compliance requirements, cold chain logistics, distribution networks, and commercialization readiness. The study analyzed manufacturing organizations, supply continuity risks, regional production capabilities, and scalability considerations that support the global commercial supply of anti-VEGF therapeutics and biosimilars.
Supported strategic manufacturing and commercialization planning by identifying qualified production partners, evaluating supply chain resilience, mitigating operational risks, and strengthening long-term market access and commercial expansion strategies across global ophthalmology markets.
Frequently Asked Questions About This Report
The global anti-VEGF therapeutics market is expected to witness a compound annual growth rate of -2.7% from 2026 to 2033 to reach USD 11.8 billion by 2033.
Key players in the market for global anti-vascular endothelial growth factor therapeutics include Regeneron Pharmaceuticals, Inc.; Bayer AG; and Novartis AG. Other key companies operating in anti-VEGF therapeutics market are F. Hoffmann-La Roche Ltd; Biogen; Pfizer, Inc.; Coherus BioSciences; Amgen, Inc.; Bausch Health Companies, Inc.; and Viatris, Inc.
Key factors responsible for market decline include the emergence of biosimilars. As these lower-cost alternatives gain approval, they enhance competition, prompting healthcare providers to favor them over branded therapies.
The age-related macular degeneration segment led the market with the largest revenue share of 52.8% in 2025.
North America dominated the anti-vascular endothelial growth factor therapeutics market with the largest revenue share of 66.7% in 2025.
The Eylea segment led the market with the largest revenue share of 58.9% in 2025.
The global anti-vascular endothelial growth factor therapeutics market size was estimated at USD 14.5 billion in 2025 and is projected to reach USD 14.3 billion in 2026.
About the Author(s)
Pharmaceuticals Research Team
Healthcare · PharmaceuticalsThis report was authored by the pharmaceuticals research team at Grand View Research - comprising two research analysts, one senior research analyst, and one industry expert - with specialized expertise in the pharmaceuticals segment of the healthcare industry. All findings are based on proprietary healthcare databases, executive interviews, and regulatory analysis, subject to internal peer review prior to publication.
Last Updated:
Speak to Analyst

Customize this report to your needs - add regions, segments, or data points, with 20% free customization.
Or view our licence options:


ISO 9001:2015 & 27001:2022 Certified
We are GDPR and CCPA compliant! Your transaction & personal information is safe and secure. For more details, please read our privacy policy.


