
- Home
- »
- Pharmaceuticals
- »
-
Antibiotic Resistance Market Size And Share Report, 2033GVR Report cover

Antibiotic Resistance Market (2026 - 2033) Size, Share & Trends Analysis Report By Disease (cUTI, cIAI, ABSSSI, HABP, CABP, BSI), By Pathogen (E.coli), By Drug Class (Oxazolidinones), By Mechanism Of Action, By Distribution Channel, By Region, And Segment Forecasts
Market Size, 2025
$9.7BMarket Estimate, 2026
$10.2BMarket Forecast, 2033
$14.3BCAGR, 2026–2033
4.9%Antibiotic Resistance Market Summary
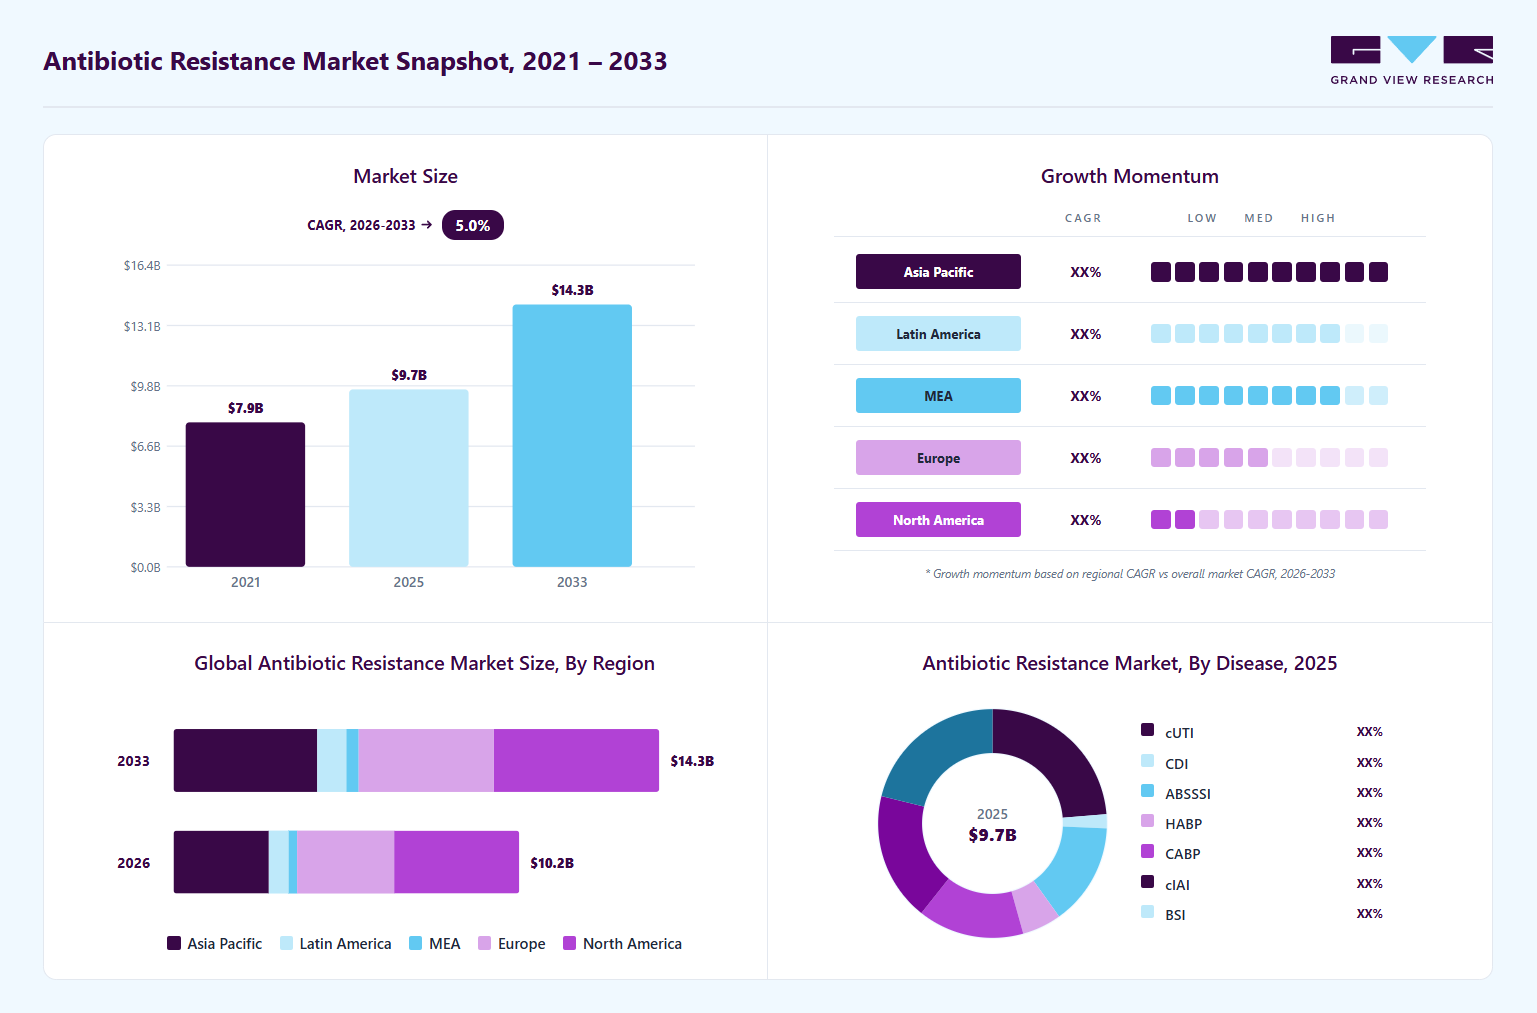
The global antibiotic resistance market size was valued at USD 9.7 billion in 2025 and is projected to grow from USD 10.2 billion in 2026 to USD 14.3 billion by 2033, at a CAGR of 4.9% from 2026 to 2033. The market in North America dominated with a revenue share of 36.5% in 2025. Increasing resistance among pathogens such as Escherichia coli, Klebsiella pneumoniae, Staphylococcus aureus, and Acinetobacter baumannii is creating significant pressure on healthcare systems worldwide.
 Source: Grand View Research, IR Documents, Primary Interviews, Paid DatabasesTo learn more about this report,
 Download Free Sample Report
Key Market Trends & Insights
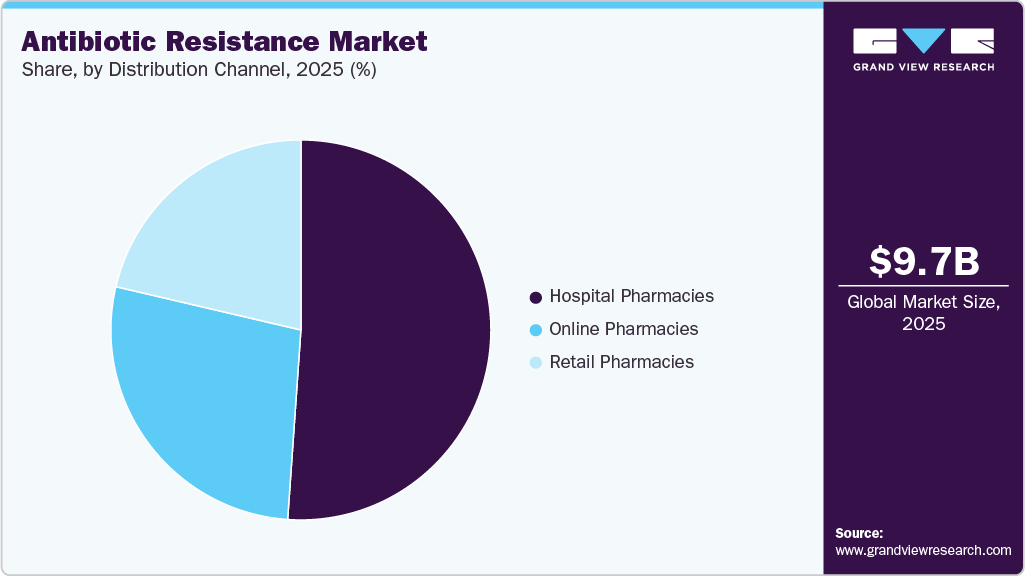
- By distribution channel: Hospital pharmacies segment held the largest market share of 51.1% in 2025.
- By mechanism of action: Cell wall synthesis inhibitors segment held the largest market share of 50.9% in 2025.
- By disease: cUTI segment held the largest market share of 23.7% in 2025.
- By pathogen: K. pneumoniae segment held the largest market share of 20.6% in 2025.
- By drug class: oxazolidinones segment held the largest market share of 14.5% in 2025.
Regional Highlights
- Largest regional market: North America (36.5% revenue share, 2025)
- Fastest-growing regional market: Asia Pacific (highest CAGR, 2026-2033)
- By country: The U.S. held the largest market share in 2025
Market Size & Forecast
- Market size in 2025: USD 9.7 Billion
- Estimated market size in 2026: USD 10.2 Billion
- Projected market size by 2033: USD 14.3 Billion
- CAGR (2026-2033): 4.9%
GVR research-powered AIAsk Prism AI about the antibiotic resistance marketGet cited answers from GVR research on market growth, segments, regulations and forecasts.Start with✓ Source-linked answers ✓ Market-specific context ✓ Traceable figuresExplore Prism AI ↗
The growing incidence of hospital-acquired, bloodstream, urinary tract, and respiratory infections is accelerating the need for advanced antibacterial therapies and rapid diagnostic technologies. Additionally, rising mortality rates from resistant infections and the expanding clinical burden in intensive care settings are driving demand for novel antimicrobial agents.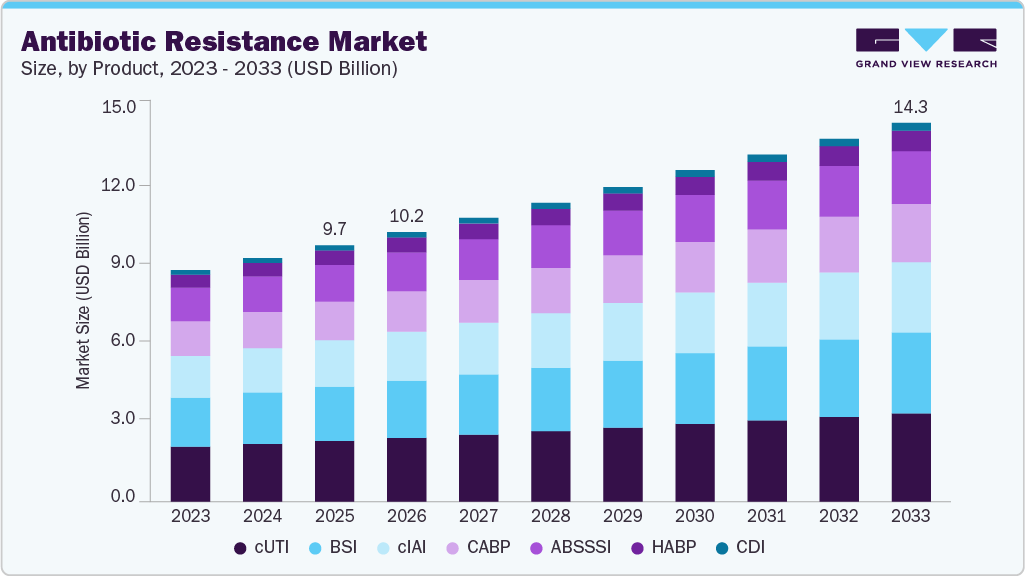 To learn more about this report, Download Free Sample Report
The growth of the antibiotic resistance industry is also driven by increasing investments in antibiotic innovation, non-traditional antibacterial therapies, and precision diagnostic platforms. Pharmaceutical companies, biotechnology firms, and academic institutions are increasingly focusing on the development of next-generation antibiotics, bacteriophage therapies, microbiome-based therapeutics, monoclonal antibodies, and AI-assisted drug discovery platforms to combat resistant pathogens. For instance, in October 2025, the World Health Organization highlighted that the global antibacterial pipeline remains insufficient despite ongoing innovation efforts, emphasizing the urgent requirement for new chemical classes and improved oral treatment options. Furthermore, the growing integration of artificial intelligence into antimicrobial drug discovery is accelerating compound screening and the development of pathogen-targeted therapies. Rising funding support for small and mid-sized biotechnology companies engaged in antibacterial R&D is further contributing to technological advancements and strengthening long-term market growth opportunities.
Strategic collaborations, international funding initiatives, and public-private partnerships are increasingly shaping the competitive landscape of the antibiotic resistance market. Governments, regulatory agencies, and healthcare organizations are strengthening global coordination to improve antibiotic accessibility, surveillance systems, and antimicrobial research infrastructure. The growing focus on One Health initiatives integrating human, animal, and environmental health is also contributing to broader antimicrobial resistance management strategies. Additionally, increased investments in diagnostics, surveillance programs, and antibacterial development targeting WHO priority pathogens are supporting market growth. Healthcare authorities across North America, Europe, and Asia Pacific are expanding funding for antimicrobial innovation programs to address the rising socioeconomic burden of resistant infections. These initiatives are expected to accelerate the commercialization of novel therapies and enhance long-term market sustainability in the global antibiotic resistance treatment landscape.
Market Dynamics
Pathogenic infections of major concern in developed and developing nations alike include Gram-negative and Gram-positive infections that are resistant to broad-spectrum antibiotics conventionally used for treatment. Enterobacteriaceae, P. aeruginosa, and K. pneumoniae pathogens that are carbapenem resistant record a high resistance rate of an average 40% in developed nations, which is even higher in developing nations. WHO and CDC have identified these pathogens as high priority, under critical or urgent category, due to their high incidence that account for a major share of healthcare-associated infections.
Invasive infections stemming from these pathogens record approximately 0.25 million cases in the U.S. and 0.5 million cases in Europe. In developing regions, excessive use of broad-spectrum antibiotics is driving resistance rates, which poses a threat globally due to growing cross-border tourism. Treatment of antibiotic-resistant Gram-negative infections is a major challenge as these pathogens are no longer susceptible to last-resort carbapenems, and resistance mechanisms in these pathogens confer additional resistance to other drug classes such as cephalosporins.
Among Gram-positive pathogens, drug-resistant S. pneumoniae, CDI, and MRSA account for the majority of the cases. MRSA infections impose a significant cost burden due to high resistance rates of an average 25% in developed regions and more than 40% in developing regions. Based on the several antibiotics that have received QIDP designation in the recent decade, the MRSA segment has been of commercial interest to manufacturers in this space, with more therapies currently in the pipeline. With the continual increase in drug resistance rates to current treatment options and increasing shift toward step-down oral therapy, demand for new generation antibiotics remains high in the Gram-positive pathogens segment.
Treatment of infections characterized by antibiotic resistance imposes a high financial burden on hospitals and patients. According to a study published by WHO, antibiotic-resistant infections account for a minimum of USD 20 billion in addition to direct healthcare costs and around USD 35 billion in productivity lost due to prolonged hospitalization each year. Treatment costs for diseases associated with high priority pathogens increase with the use of new generation antibiotics and due to long treatment durations.
For instance, as per CDC records, infections due to antibiotic-resistant C. difficile currently cost around USD 1.0 billion in excess medical costs per year. In addition, according to the Center for Infectious Disease and Research Policy, the average incremental treatment cost of a bacterial drug-resistant infection involves an additional USD 1,400. Patented therapies entering the antibiotic resistance market are priced high due to long development timelines and high clinical development costs.
Direct treatment costs for pathogenic infections with antibiotic resistance escalate with additional expenses due to diagnostic procedures and prolonged hospital stays. In developing regions, these incremental costs contribute to high out-of-pocket costs for patients. On the other hand, in developed regions, reimbursement approval for recently developed antibiotic therapies through the New Technology Add-on Payment (NTAP) provision is gradually enabling access to reimbursement. Despite these measures, coverage is still restricted for treatment of severe infections that account for significant out-of-pocket expenditure.
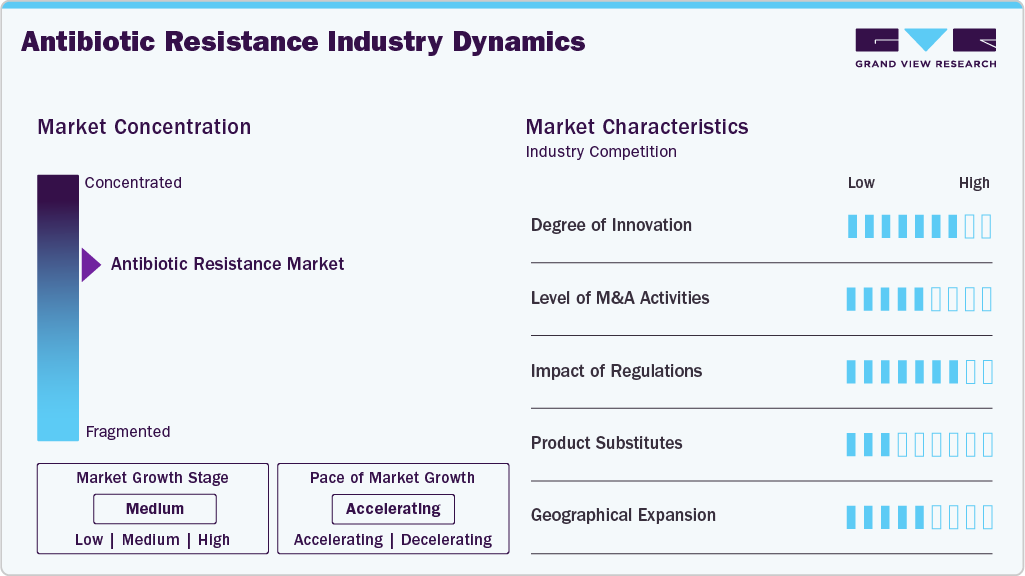
Market Characteristics
The antibiotic resistance market demonstrates a high degree of innovation driven by the increasing prevalence of multidrug-resistant bacterial infections and the declining effectiveness of conventional antibiotics. Pharmaceutical and biotechnology companies are actively investing in the development of next-generation antibiotics, bacteriophage therapies, monoclonal antibodies, antimicrobial peptides, and microbiome-based therapeutics targeting priority resistant pathogens. The market is also witnessing increasing adoption of artificial intelligence, genomic sequencing, and bioinformatics tools to accelerate antibacterial drug discovery, resistance prediction, and pathogen identification. In addition, advancements in rapid molecular diagnostics and antimicrobial susceptibility testing platforms are improving early detection and supporting targeted antimicrobial treatment approaches across healthcare settings. Growing regulatory support, public-private partnerships, and global antimicrobial resistance funding initiatives are further accelerating innovation activity and strengthening the long-term development pipeline within the antibiotic resistance industry.
The market faces significant barriers to entry due to the high costs and extended timelines associated with antibacterial drug discovery, clinical development, and regulatory approval. The development of novel antibiotics and antimicrobial therapies targeting resistant pathogens requires substantial investment in advanced microbiological research, resistance surveillance, and specialized clinical trials that meet strict efficacy and safety standards. In addition, limited commercial returns for newly approved antibiotics, largely influenced by antimicrobial stewardship practices and controlled prescribing patterns, continue to discourage new market participants and private investment. Regulatory agencies also require comprehensive resistance data, pharmacovigilance monitoring, and pathogen-specific clinical evidence for antibacterial approvals, increasing development complexity. Furthermore, the market remains highly specialized and innovation-intensive, with established pharmaceutical companies, biotechnology firms, and government-supported research programs maintaining strong intellectual property positions and advanced antimicrobial development capabilities.
 To learn more about this report, Download Free Sample Report
Regulations have a significant impact on the antibiotic resistance market by influencing antibacterial drug development, approval pathways, antimicrobial stewardship practices, and post-marketing surveillance requirements. Regulatory agencies such as the World Health Organization, the U.S. Food and Drug Administration, and the European Medicines Agency are increasingly implementing policies to control antimicrobial resistance through stricter antibiotic-use guidelines, surveillance frameworks, and expedited regulatory pathways for innovative antibacterial therapies. The market is also influenced by growing adoption of antimicrobial stewardship regulations and infection prevention standards across healthcare systems globally. In addition, regulatory incentives, public funding programs, and subscription-based reimbursement models are supporting investment in novel antibiotics and rapid diagnostic technologies. However, stringent clinical evidence requirements, pharmacovigilance obligations, and evolving compliance standards continue to increase development complexity and operational costs for market participants.
The antibiotic resistance industry faces moderate competition from alternative and preventive healthcare approaches aimed at reducing reliance on conventional antibiotics. The increasing adoption of vaccines, rapid diagnostic technologies, antimicrobial stewardship programs, and hospital infection prevention measures is helping reduce inappropriate antibiotic usage and lower infection rates across healthcare settings. In addition, growing research into bacteriophage therapies, microbiome-based therapeutics, monoclonal antibodies, immunotherapies, and other non-traditional antibacterial approaches is expanding the range of potential treatment alternatives for resistant bacterial infections. However, despite the development of these substitutes, antibiotics continue to remain the primary and most widely used treatment option for severe bacterial infections, sustaining long-term demand for novel antibacterial therapies in the global market.
The market is witnessing increasing geographical expansion driven by the rising global burden of antimicrobial-resistant infections and growing investments in healthcare infrastructure across emerging economies. Pharmaceutical companies and biotechnology firms are expanding their presence in Asia Pacific, Latin America, the Middle East, and parts of Africa due to rising antibiotic consumption, improved diagnostic capabilities, and greater awareness of antimicrobial resistance. Governments and international health organizations are also strengthening regional surveillance programs, antimicrobial stewardship initiatives, and infection control frameworks to address the growing public health impact of resistant pathogens. In addition, expanding regulatory support and funding for antibacterial research in countries such as China, India, and Brazil are encouraging clinical development and commercialization activities within these regions. The growing demand for advanced antibiotics, rapid diagnostics, and hospital-based infection management solutions is further supporting the global market expansion.
Disease Insights
The cUTI segment dominated the antibiotic resistance market, accounting for the largest revenue share of 23.70% in 2025, due to the increasing prevalence of multidrug-resistant urinary tract infections caused by pathogens such as E. coli, Klebsiella pneumoniae, and Pseudomonas aeruginosa. Rising hospitalization rates, catheter-associated infections, and recurrent treatment failures are continuing to increase demand for advanced antimicrobial therapies targeting resistant infections. The market is witnessing stronger adoption of broad-spectrum antibiotics, β-lactam/β-lactamase inhibitor combinations, and carbapenem-based therapies for the management of severe cUTI. For instance, in May 2025, GSK and Spero Therapeutics reported positive late-stage trial results for tebipenem HBr, an investigational oral carbapenem antibiotic for cUTIs, highlighting ongoing innovation within the segment. The development of oral therapies for resistant cUTIs is expected to support outpatient treatment and reduce reliance on prolonged intravenous antibiotic administration. Increasing antimicrobial resistance surveillance programs and growing investment in next-generation anti-infective drugs are further supporting the expansion of the cUTI segment globally.
The CDI segment is projected to grow at a CAGR of 5.35% over the forecast period, driven by the increasing prevalence of hospital-acquired and recurrent Clostridioides difficile infections among elderly, immunocompromised, and long-term hospitalized patient populations. Rising recurrence rates, prolonged antibiotic exposure, and growing concerns about antimicrobial resistance are driving demand for targeted anti-infective therapies and microbiome-based treatment approaches. The market is experiencing increasing adoption of narrow-spectrum antibiotics, live biotherapeutic products, and microbiota restoration therapies aimed at reducing infection recurrence while preserving healthy gut microbiota and improving long-term clinical outcomes. Healthcare providers are increasingly emphasizing therapies that can minimize repeat hospitalizations, reduce reliance on repeated antibiotic cycles, and support better disease management in patients with recurrent CDI. For instance, in May 2025, Ferring Pharmaceuticals presented new Phase IIIb CDI-SCOPE study data for REBYOTA, demonstrating safety, effectiveness, and microbiome restoration benefits in recurrent CDI patients, highlighting continued innovation and growing clinical confidence in microbiome-based therapeutics within the segment. Furthermore, increasing antimicrobial stewardship initiatives, hospital infection surveillance programs, supportive regulatory advancements, and growing investments in next-generation microbiome therapeutics are contributing to the continued expansion of the CDI segment globally.
Pathogen Insights
The K. pneumoniae segment dominated the antibiotic resistance industry, accounting for the largest revenue share of 20.59% in 2025, due to the rising prevalence of multidrug-resistant and carbapenem-resistant strains across healthcare settings. The segment is experiencing strong growth driven by increasing cases of hospital-acquired pneumonia, bloodstream infections, urinary tract infections, ventilator-associated infections, and sepsis associated with gram-negative bacteria. Growing resistance to commonly used antibiotics such as cephalosporins and carbapenems is significantly limiting treatment options and increasing dependence on advanced combination therapies. The market is witnessing rising adoption of β-lactam/β-lactamase inhibitor combinations, siderophore cephalosporins, and other next-generation anti-infective agents targeting resistant K. pneumoniae.
Additionally, increasing hospital infection control measures, rapid diagnostic testing, and antimicrobial stewardship programs are supporting better management of carbapenem-resistant infections globally. For instance, in October 2025, the WHO released its Global Antibiotic Resistance Surveillance Report 2025, highlighting Klebsiella pneumoniae as one of the leading drug-resistant gram-negative pathogens globally. The report stated that more than 55% of K. pneumoniae infections worldwide were resistant to third-generation cephalosporins, while carbapenem resistance is also increasing, significantly limiting available treatment options for severe bloodstream and hospital-acquired infections. The WHO further emphasized that resistant K. pneumoniae infections are becoming a major global health threat due to rising mortality risk, increasing sepsis burden, and limited access to effective last-line antibiotics in several regions.
The CDI segment is projected to grow at a CAGR of 5.39% over the forecast period, driven by the persistent burden of healthcare-associated infections and the increasing impact of broad-spectrum antibiotic use in clinical settings. CDI remains closely linked to antimicrobial exposure, particularly in hospitalized and elderly populations, where disruption of gut microbiota increases infection risk and recurrence rates. This has made CDI a recurring clinical challenge, supporting sustained demand for both standard and advanced therapeutic options. At the same time, growing antimicrobial resistance pressures across healthcare systems are reinforcing antibiotic stewardship programs, which aim to optimize prescribing practices and reduce CDI incidence. Overall, the CDI segment continues to grow as a structurally important part of the antibiotic resistance market, supported by high recurrence burden, hospital-centric infection dynamics, and increasing focus on prevention and microbiome-preserving treatment strategies.
Drug Class Insights
The oxazolidinones segment dominated the market, accounting for a significant revenue share in 2025, driven by the rising prevalence of multidrug-resistant Gram-positive bacterial infections. The oxazolidinones segment plays a critical role in the market. This class, which includes agents such as linezolid, functions by inhibiting bacterial protein synthesis through binding to the 50S ribosomal subunit, thereby preventing formation of the initiation complex. It is particularly important in treating infections caused by methicillin-resistant Staphylococcus aureus (MRSA) and vancomycin-resistant Enterococcus (VRE), where conventional antibiotic options are often limited. The segment is widely utilized in hospital settings for conditions such as complicated skin and soft tissue infections and hospital-acquired pneumonia. Its clinical relevance has increased in parallel with the global rise in resistance to beta-lactams and glycopeptides, thereby reducing the effectiveness of first-line therapies. Overall, oxazolidinones are considered a vital last-resort therapeutic option in managing severe resistant Gram-positive infections, especially in critical care environments.
The combination therapies segment is projected to grow at a CAGR of 6.46% over the forecast period, driven by the increasing prevalence of multidrug-resistant bacterial infections. The combination therapies segment is gaining strong importance in the market. This approach involves the use of two or more antibiotics with complementary mechanisms of action to improve treatment efficacy and broaden antimicrobial coverage. It is especially relevant in managing severe infections caused by resistant Gram-negative pathogens such as carbapenem-resistant Klebsiella pneumoniae and Pseudomonas aeruginosa, where single-agent therapy may be insufficient. Commonly used combinations, including beta-lactam/beta-lactamase inhibitor regimens, are widely adopted in intensive care units and for hospital-acquired infections. The segment is further supported by the limited availability of new antibiotic classes, increasing dependence on established combination strategies. Overall, combination therapies remain a key clinical approach for improving outcomes in complex resistant infections in hospital settings.
Mechanism of Action Insights
The cell wall synthesis inhibitors segment dominated the antibiotic resistance industry with the largest revenue share of 50.96% in 2025, driven by the persistent global burden of bacterial infections and the rising prevalence of antimicrobial resistance. The cell wall synthesis inhibitors continues to remain a foundational therapeutic class. These agents, including β-lactams and glycopeptides, act by inhibiting peptidoglycan formation, thereby compromising bacterial cell wall integrity and leading to cell death. However, their effectiveness is increasingly challenged by resistance mechanisms such as β-lactamase production and altered penicillin-binding proteins, which reduce drug susceptibility across multiple pathogens. In response, the market is witnessing a gradual shift toward combination therapies, including β-lactam/β-lactamase inhibitor combinations, designed to restore antimicrobial activity against resistant strains. Additionally, ongoing antimicrobial resistance pressures are encouraging the development of next-generation cell wall-targeting agents with enhanced stability and broader spectrum coverage. Overall, the segment remains a critical pillar of the antibiotic resistance market, supported by its central role in first-line therapy and continuous innovation to overcome evolving bacterial resistance mechanisms.
The RNA synthesis inhibitors segment is projected to grow at a CAGR of 6.00% over the forecast period, driven by the growing need for effective therapies against multidrug-resistant bacterial infections. The segment is gaining steady traction. These agents primarily act by targeting bacterial RNA polymerase, thereby disrupting transcription and inhibiting essential protein synthesis. Drugs such as rifamycins and fidaxomicin are commonly used in this class, particularly for the management of persistent and difficult-to-treat infections. The rising incidence of resistant tuberculosis and Clostridioides difficile infections is supporting the clinical relevance of this mechanism of action. The segment benefits from greater focus on pathogen-specific treatment approaches that minimize collateral damage to beneficial microbiota. Overall, the ongoing demand for novel anti-infective strategies continues to reinforce the adoption of RNA synthesis inhibitors in the resistance management pathway.
Distribution Channel Insights
The hospital pharmacies segment dominated the antibiotic resistance market with the largest revenue share of 51.11% in 2025, driven by the high burden of severe and multidrug-resistant infections requiring controlled clinical management. The hospital pharmacies segment plays a central role in the market. These pharmacies serve as the primary distribution channel for reserve and last-line antibiotics used in inpatient care, particularly in intensive care units and surgical wards. They ensure the regulated dispensing of critical antimicrobial agents, such as carbapenems, glycopeptides, and oxazolidinones, under strict hospital formulary guidelines. The segment is strongly supported by antimicrobial stewardship programs, which promote rational antibiotic use and help curb inappropriate prescribing within hospital settings. The increasing incidence of hospital-acquired infections has further reinforced the reliance on institutional pharmacy systems for timely and accurate drug administration. Overall, hospital pharmacies remain a key access point for advanced anti-infective therapies in the management of complex, resistant infections.
 To learn more about this report, Download Free Sample Report
The retail pharmacies segment is projected to grow at a CAGR of 5.48% over the forecast period, driven by the growing burden of community-acquired bacterial infections and increasing outpatient healthcare utilization. The segment holds a significant position in the market. This channel primarily facilitates the dispensing of physician-prescribed antibiotics for mild-to-moderate infections managed outside hospital settings. Expanding pharmacy infrastructure and improved access to medicines in urban and semi-urban regions are supporting the timely availability of antimicrobial therapies. However, stricter prescription enforcement and antimicrobial stewardship programs are increasingly regulating antibiotic dispensing practices through retail outlets. Rising awareness regarding antimicrobial resistance is also influencing patient behavior, encouraging more consultation-based and controlled antibiotic use. Overall, the segment reflects the balance between improving access to essential antibiotics and strengthening regulatory oversight to reduce inappropriate consumption.
Regional Insights
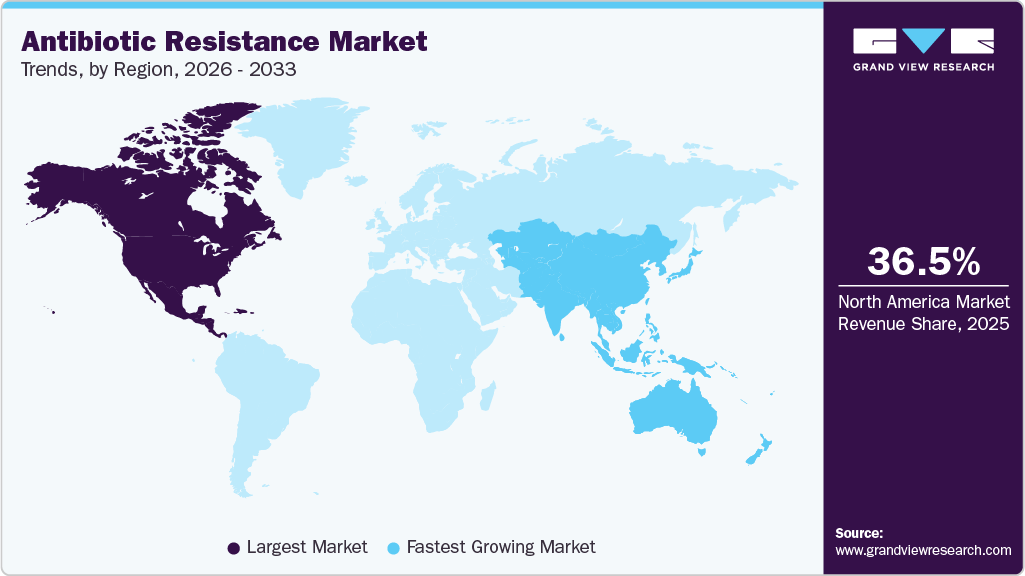
The North America antibiotic resistance market held the largest share of 36.47% in 2025, driven by the high burden of antimicrobial-resistant infections and advanced healthcare infrastructure. The region holds a leading revenue position in the global market, supported by significant R&D investments and government-led antimicrobial stewardship initiatives. The market is further reinforced by the rising prevalence of resistant pathogens and hospital-acquired infections, which continue to increase demand for novel and combination therapies. The U.S. represents the dominant country-level contributor within the region, reflecting strong diagnostic capabilities and widespread insurance coverage for infection management. Growth is also supported by the ongoing development of advanced antibiotics targeting resistant strains, especially in high-burden disease areas like cUTI and CDI. Overall, North America remains a key hub for innovation and commercialization in the antibiotic resistance landscape, with steady expansion anticipated over the forecast period.
 To learn more about this report, Download Free Sample Report
U.S. Antibiotic Resistance Market Trends
The U.S. antibiotic resistance industry dominates North America, driven by the rising burden of drug-resistant infections and the growing need for advanced therapeutic options. The country continues to report a high incidence of antimicrobial-resistant pathogens across both hospital and community settings, creating sustained demand for novel antibiotics and combination therapies. Increasing cases of difficult-to-treat infections such as cUTI, CDI, and bloodstream infections are reinforcing the clinical importance of next-generation anti-infective drugs. The market is further supported by robust surveillance systems, strong healthcare infrastructure, and ongoing investment in antimicrobial stewardship programs to slow the development of resistance. In addition, the presence of leading pharmaceutical and biotechnology companies actively engaged in antibiotic R&D strengthens the innovation pipeline. Overall, the U.S. remains a key market in the global antibiotic resistance landscape, with persistent growth driven by unmet clinical needs and evolving resistance patterns.
Europe Antibiotic Resistance Market Trends
The Europe antibiotic resistance industry showcases steady growth, driven by the rising burden of multidrug-resistant bacterial infections and increasing hospital-acquired infection rates across the region. Strong surveillance frameworks established by agencies such as the European Centre for Disease Prevention and Control (ECDC) are accelerating demand for advanced antimicrobial solutions and diagnostics. The growing emphasis on antimicrobial stewardship programs across European healthcare systems is also shaping prescribing practices and supporting controlled antibiotic use. At the same time, the aging population in Europe is contributing to higher susceptibility to infections, further sustaining treatment demand. Increasing resistance among key pathogens such as E. coli and Klebsiella pneumoniae is limiting the effectiveness of conventional therapies and driving the need for novel antibiotics. Overall, the market is characterized by a balance between rising clinical need and strict regulatory efforts aimed at preserving antibiotic efficacy.
The UK antibiotic resistance market is expanding due to the increasing prevalence of drug-resistant infections across both hospital and community settings. Rising cases of healthcare-associated infections, particularly in intensive care units, are driving greater demand for advanced antimicrobial therapies and rapid diagnostic tools. Strong national initiatives, such as the UK Antimicrobial Resistance Strategy, are reinforcing surveillance, prevention, and responsible antibiotic use across healthcare systems. The growing incidence of resistant pathogens, such as Escherichia coli and Staphylococcus aureus, further limits treatment effectiveness and increases clinical complexity. Continuous investment in research and development of novel antibiotics and alternative therapies is also supporting market growth. Overall, the market is shaped by a combination of rising infection burden and structured public health efforts to contain resistance.
The antibiotic resistance market in Germany is growing due to the increasing incidence of multidrug-resistant bacterial infections within both inpatient and outpatient care settings. A high volume of surgical procedures and intensive medical interventions is contributing to elevated risks of postoperative and hospital-acquired infections. Germany’s robust diagnostic infrastructure is enabling earlier detection of resistant strains, driving demand for targeted antimicrobial therapies. The presence of robust antimicrobial stewardship programs is also influencing prescribing behavior and encouraging more controlled antibiotic use. Rising resistance among Gram-negative pathogens, including Pseudomonas aeruginosa, is further complicating treatment pathways and supporting the need for novel solutions. Overall, the market is evolving under the combined influence of clinical complexity, advanced healthcare systems, and growing therapeutic gaps.
The France antibiotic resistance market is growing due to the rising burden of antimicrobial-resistant infections across both hospital and community healthcare settings. The increasing prevalence of difficult-to-treat infections caused by resistant pathogens such as Escherichia coli and Klebsiella pneumoniae is driving demand for advanced therapeutic options. The country’s strong public health surveillance systems and “One Health” approach are supporting coordinated monitoring of resistance across humans, animals, and the environment. Expanding hospital infection control measures and antimicrobial stewardship programs are also shaping antibiotic usage patterns and improving diagnostic-driven treatment decisions. Continuous research efforts and public funding for novel antibacterial agents are further strengthening the innovation pipeline. Overall, the market is progressing under the combined influence of growing clinical need and structured national containment strategies.
Asia Pacific Antibiotic Resistance Market Trends
The Asia Pacific antibiotic resistance industry is expected to grow at the fastest CAGR of 6.07% over the forecast period, driven by the high burden of infectious diseases combined with rapid population growth and increasing healthcare utilization across emerging economies. Overcrowded healthcare facilities and inconsistent infection prevention practices in certain regions are contributing to faster transmission of multidrug-resistant organisms. Rising antibiotic consumption, driven by improved healthcare access and large-scale use in densely populated countries such as India and China, is further intensifying resistance pressure. Limited availability of advanced diagnostic infrastructure in many low- and middle-income settings often leads to empirical and inappropriate antibiotic use, worsening resistance trends. In response, governments across the region are strengthening antimicrobial stewardship frameworks and investing in surveillance systems to monitor resistant pathogens more effectively. Overall, the market is shaped by a complex mix of high disease prevalence, evolving healthcare systems, and growing policy focus on containment strategies.
The Japan antibiotic resistance market is expanding due to the growing burden of infections associated with a rapidly aging population and increased hospitalization rates. Despite strong infection control standards, healthcare-associated resistant infections continue to pose clinical challenges in complex care settings. Japan’s well-developed national surveillance systems are enhancing the detection and tracking of antimicrobial resistance trends across healthcare facilities. Rising resistance among common pathogens such as Escherichia coli and Staphylococcus aureus is contributing to treatment complexity. Increasing integration of advanced diagnostics is supporting more precise antibiotic selection and improved antimicrobial stewardship practices. Overall, the market is shaped by demographic pressures, high healthcare standards, and sustained focus on resistance monitoring and control.
The antibiotic resistance market in China is expanding due to a high burden of multidrug-resistant infections driven by extensive healthcare utilization and historically high antibiotic consumption across hospital and community settings. Strong national initiatives such as the China Antimicrobial Resistance Surveillance System (CARSS) and CHINET are enabling large-scale monitoring of resistance patterns across clinical institutions, strengthening data-driven treatment strategies. Major domestic pharmaceutical players, including Shanghai Fosun Pharmaceutical and Hengrui Medicine, are increasingly involved in developing and supplying next-generation anti-infective agents to address rising therapeutic gaps. Resistance levels among critical pathogens, such as carbapenem-resistant Klebsiella pneumoniae and Acinetobacter baumannii, remain a key clinical concern, driving demand for advanced hospital-based therapies. The government’s National Action Plan for AMR containment further reinforces stewardship programs and accelerates R&D on novel antibiotics and diagnostics. Overall, the market is shaped by a combination of high resistance burden, structured surveillance infrastructure, and strong domestic pharmaceutical innovation efforts.
Latin America Antibiotic Resistance Market Trends
The Latin America market is growing steadily due to the growing burden of multidrug-resistant infections, particularly in hospital environments across Brazil, Mexico, and Argentina, where healthcare system capacity and diagnostic access vary significantly. Regional surveillance initiatives such as PAHO’s ReLAVRA 2.0 network are strengthening standardized monitoring of antimicrobial resistance and improving cross-country data comparability for key pathogens. Public and private hospital systems are increasingly reporting resistance in Gram-negative bacteria such as carbapenem-resistant Klebsiella pneumoniae and Acinetobacter baumannii, driving demand for last-line treatment options. In response to these challenges, companies including Pfizer Inc., Bayer AG, and AbbVie Inc. maintain active anti-infective portfolios supporting hospital formulary needs across major Latin American markets. Local pharmaceutical players such as EMS S.A. (Brazil) and Laboratorios Roemmers (Argentina) also contribute to antibiotic supply and the availability of generic anti-infectives in the region. Overall, the market is shaped by rising infection complexity, evolving surveillance infrastructure, and a mixed ecosystem of multinational and regional pharmaceutical participation.
The Brazil antibiotic resistance market dominates Latin America, due to its large healthcare infrastructure, high patient inflow, and significant burden of resistant infections across both public and private hospital systems. The country reports elevated resistance levels among priority pathogens, including carbapenem-resistant Klebsiella pneumoniae and Acinetobacter baumannii, particularly in intensive care and surgical units. The National Regulatory Authority, ANVISA, has strengthened antimicrobial surveillance and infection control frameworks in collaboration with the ReLAVRA 2.0 network, thereby improving resistance monitoring across regions. High antibiotic utilization in outpatient care, along with inconsistent stewardship adherence across healthcare facilities, continues to contribute to selection pressure for resistant strains. Local pharmaceutical companies such as EMS S.A. and Eurofarma play an important role in supplying affordable generic antibiotics, thereby expanding access to treatment. Overall, the market is driven by high disease burden, structured regulatory oversight, and strong domestic manufacturing participation supporting antimicrobial availability.
Middle East & Africa Antibiotic Resistance Market Trends
The MEA antibiotic resistance industry is expanding due to the rising prevalence of multidrug-resistant infections across both hospital and community healthcare settings. In several countries within the region, high rates of healthcare-associated infections and limited infection control infrastructure are contributing to the faster spread of resistant pathogens. Resistance in Gram-negative bacteria such as Klebsiella pneumoniae and Acinetobacter baumannii is increasingly reported in intensive care units, creating significant treatment challenges. Strengthening national surveillance programs in countries such as Saudi Arabia, South Africa, and the UAE is improving the monitoring of antimicrobial resistance trends. Growing investments in healthcare infrastructure and increasing access to diagnostic technologies are gradually supporting more targeted antibiotic use. Overall, the market is shaped by a combination of high infectious disease burden, evolving healthcare systems, and expanding antimicrobial stewardship efforts across the region.
The Saudi Arabia antibiotic resistance market is growing rapidly due to the increasing burden of multidrug-resistant infections in both hospital and community healthcare settings. High rates of hospital-acquired infections, particularly in intensive care units and post-surgical care, are contributing to greater clinical reliance on advanced antimicrobial therapies. The country’s strong healthcare modernization under Vision 2030 is driving investments in infection control systems, diagnostic infrastructure, and antimicrobial stewardship programs. National surveillance initiatives led by the Saudi Center for Disease Prevention and Control (Weqaya) are improving tracking of resistant pathogens and guiding treatment protocols. Rising resistance among Gram-negative organisms such as Klebsiella pneumoniae and Pseudomonas aeruginosa is further increasing demand for last-line antibiotics and combination therapies. Overall, the market is shaped by healthcare system expansion, structured regulatory oversight, and a growing focus on controlling antimicrobial resistance within tertiary care networks.
Key Antibiotic Resistance Company Insights
Melinta Therapeutics, Basilea Pharmaceutica Ltd., and Paratek Pharmaceuticals, Inc. are strengthening their anti-infective portfolios by advancing novel antibacterial agents targeting multidrug-resistant Gram-negative and Gram-positive pathogens. Tetraphase Pharmaceuticals and WOCKHARDT are focused on developing next-generation antibiotics and reformulated therapies designed to address resistance mechanisms such as efflux pumps and enzymatic degradation. Seres Therapeutics is expanding microbiome-based approaches aimed at restoring microbial balance and reducing recurrence of resistant infections. Entasis Therapeutics is enhancing its pipelines with precision antibacterials and pathogen-specific drug candidates targeting critical resistance pathways. Theravance Biopharma continues to advance differentiated anti-infective assets focused on difficult-to-treat infections in niche clinical settings. AbbVie is supporting the market through broad-spectrum anti-infective research and combination strategies addressing evolving resistance patterns. Overall, the market reflects intensifying competition driven by novel mechanism development, pathogen-specific targeting, and expanding clinical adoption of resistance-guided therapies.
Key Antibiotic Resistance Companies
The following key companies have been profiled for this study on the antibiotic resistance market.
-
Melinta Therapeutics
-
Basilea Pharmaceutica Ltd.
-
Tetraphase Pharmaceuticals
-
Theravance Biopharma
-
WOCKHARDT
-
Paratek Pharmaceuticals, Inc.
-
Seres Therapeutics
-
ACHAOGEN, INC.
-
Entasis Therapeutics
-
AbbVie
Recent Developments
-
In August 2025, Melinta Therapeutics entered a definitive acquisition agreement with CorMedix Inc. in a transaction valued at approximately $300 million. The deal expanded CorMedix’s infectious disease portfolio by adding hospital-focused antibiotics, including VABOMERE and BAXDELA, thereby strengthening its presence in the treatment of resistant infections.
-
In November 2025, Basilea Pharmaceutica announced a strategic partnership with Phare Bio to develop a next-generation broad-spectrum antibiotic using AI-driven discovery platforms. The collaboration targets high-priority gram-negative resistant pathogens, combining AI molecule design with Basilea’s clinical development capabilities.
Antibiotic Resistance Market Report Scope
Report Attribute
Details
Market size in 2025
USD 9.7 billion
Estimated market size in 2026
USD 10.2 billion
Projected market size by 2033
USD 14.3 billion
Growth rate
CAGR of 4.9% from 2026 to 2033
Base year for estimation
2025
Historical data
2021 - 2024
Forecast period
2026 - 2033
Quantitative units
Revenue in USD million/billion and CAGR from 2026 to 2033
Report coverage
Revenue forecast, company ranking, competitive landscape, growth factors, trends
Segments covered
Disease, pathogen, drug class, mechanism of action, distribution channel, and region
Regional scope
North America; Europe; Asia Pacific; Latin America; Middle East & Africa
Country scope
U.S.; Canada; Mexico; UK; Germany; France; Italy; Spain; Denmark; Sweden; Norway; China; Japan; India; Australia; South Korea; Thailand; Brazil; Argentina; South Africa; Saudi Arabia; UAE; Kuwait
Key company profiled
Melinta Therapeutics; Basilea Pharmaceutica Ltd.; Tetraphase Pharmaceuticals; Theravance Biopharma; WOCKHARDT; Paratek Pharmaceuticals, Inc.; Seres Therapeutics; ACHAOGEN, INC.; Entasis Therapeutics; AbbVie
Customization scope
Free report customization (equivalent up to 8 analysts working days) with purchase. Addition or alteration to country, regional & segment scope.
Pricing and purchase options
Avail customized purchase options to meet your exact research needs. Explore purchase options
Global Antibiotic Resistance Market Report Segmentation
This report forecasts revenue growth at the global, regional, and country levels and provides an analysis of the latest industry trends in each of the sub-segments from 2021 to 2033. For this study, Grand View Research has segmented the global antibiotic resistance market report based on disease, pathogen, mechanism of action, drug class, distribution channel, and region:
-
Disease Outlook (Revenue, USD Million, 2021 - 2033)
-
cUTI (Complicated Urinary Tract Infections)
-
CDI (Clostridioides difficile Infection)
-
ABSSSI (Acute bacterial skin and skin structure infections)
-
HABP (Hospital-acquired bacterial pneumonia)
-
CABP
-
cIAI
-
BSI
-
-
Pathogen Outlook (Revenue, USD Million, 2021 - 2033)
-
E. coli
-
klebsiella pneumoniae
-
P. aeruginosa
-
S. aureus
-
A. baumannii
-
Strep. pneumoniae
-
H. influenzae
-
CDI
-
Enterococcus faecium
-
-
Drug Class Outlook (Revenue, USD Million, 2021 - 2033)
-
Oxazolidinones
-
Lipoglycopeptides
-
Tetracyclines
-
Combination therapies
-
Cephalosporins
-
Others
-
-
Mechanism of Action Outlook (Revenue, USD Million, 2021 - 2033)
-
Protein Synthesis Inhibitors
-
Cell Wall Synthesis Inhibitors
-
RNA Synthesis Inhibitors
-
DNA Synthesis Inhibitors
-
Others
-
-
Distribution Channel Outlook (Revenue, USD Million, 2021 - 2033)
-
Hospital Pharmacies
-
Retail Pharmacies
-
Online Pharmacies
-
-
Regional Outlook (Revenue, USD Million, 2021 - 2033)
-
North America
-
U.S.
-
Canada
-
Mexico
-
-
Europe
-
UK
-
Germany
-
France
-
Italy
-
Spain
-
Denmark
-
Sweden
-
Norway
-
-
Asia Pacific
-
China
-
Japan
-
India
-
Australia
-
Thailand
-
South Korea
-
-
Latin America
-
Brazil
-
Argentina
-
-
Middle East & Africa
-
South Africa
-
Saudi Arabia
-
UAE
-
Kuwait
-
-
Frequently Asked Questions About This Report
The global antibiotic resistance market size was valued at USD 9.7 billion in 2025 and is estimated at USD 10.2 billion for 2026.
The global antibiotic resistance market is expected to grow at a CAGR of 4.9% from 2026 to 2033, reaching USD 14.3 billion.
Key factors include increasing prevalence of multidrug-resistant bacterial infections, rising hospital-acquired infections, growing antimicrobial resistance among major pathogens, and increasing demand for novel antibacterial therapies and rapid diagnostic technologies. Advancements in AI-assisted drug discovery, bacteriophage therapies, microbiome-based therapeutics, and antimicrobial stewardship initiatives are further supporting market expansion.
Key players include Melinta Therapeutics; Basilea Pharmaceutica Ltd.; Tetraphase Pharmaceuticals; Theravance Biopharma; WOCKHARDT; Paratek Pharmaceuticals, Inc.; Seres Therapeutics; ACHAOGEN, INC.; Entasis Therapeutics; AbbVie.
Asia Pacific is the fastest-growing region over the forecast period.
cUTI segment led with a 23.7% revenue share in 2025, while CDI segment to grow at a CAGR of 5.35% over the forecast period.
The K. pneumoniae segment held the largest share (over 20.0%) in 2025.
Oxazolidinones held the largest revenue share of 14.5% in 2025, while combination therapies to grow with 5.35% CAGR over the forecast period.
The hospital pharmacies held the largest share (over 51.0%) in 2025.
North America dominated with a 36.5% revenue share in 2025.
About the Author(s)
Pharmaceuticals Research Team
Healthcare · PharmaceuticalsThis report was authored by the pharmaceuticals research team at Grand View Research - comprising two research analysts, one senior research analyst, and one industry expert - with specialized expertise in the pharmaceuticals segment of the healthcare industry. All findings are based on proprietary healthcare databases, executive interviews, and regulatory analysis, subject to internal peer review prior to publication.
Last Updated:
Speak to Analyst

Customize this report to your needs - add regions, segments, or data points, with 20% free customization.
Or view our licence options:


ISO 9001:2015 & 27001:2022 Certified
We are GDPR and CCPA compliant! Your transaction & personal information is safe and secure. For more details, please read our privacy policy.


