
- Home
- »
- Pharmaceuticals
- »
-
Antidiabetics Market Size, Share & Trends Report 2026-2033GVR Report cover

Antidiabetics Market (2026 - 2033)
Size, Share & Trends Analysis Report By Drug Class (GLP-1 Receptor Agonists, Insulin), By Diabetes Type (Type 1, 2), By Route Of Administration (Oral, Intravenous), By Distribution Channel, By Region, And Segment Forecasts
Market Size, 2025
$104.0BMarket Estimate, 2026
$117.5BMarket Forecast, 2033
$235.4BCAGR, 2026–2033
10.4%Antidiabetics Market Summary
The global antidiabetics market size was valued at USD 104.0 billion in 2025 and is projected to grow from USD 117.5 billion in 2026 to USD 235.4 billion by 2033, at a CAGR of 10.4% from 2026 to 2033. North America dominated the market, accounting for a revenue share of 41.5% in 2025. The antidiabetics industry is driven by rising diabetes prevalence, advancements in GLP-1 receptor agonists and SGLT2 inhibitors, and increasing adoption of combination therapies.
 Source: Grand View Research, IR Documents, Primary Interviews, Paid DatabasesTo learn more about this report,
 Download Free Sample Report
Key Market Trends & Insights
- By drug class: GLP-1 receptor agonists segment dominated the market, with a revenue share of 46.8 % in 2025.
- By diabetes type: Type 2 segment held the largest market share of 79.4% in 2025.
- By route of administration: Intravenous segment held the largest revenue share of 41.8% in 2025.
- By distribution channel: Hospital pharmacy segment accounted for the largest revenue share of 47.2% in 2025.
Regional Highlights
- Largest regional market: North America (41.5% revenue share, 2025)
- Fastest-growing regional market: Asia Pacific (highest CAGR, 2026-2033)
- By country: The U.S. held the largest market share in 2025.
Market Size & Forecast
- Market size in 2025: USD 104.0 Billion
- Estimated market size in 2026: USD 117.5 Billion
- Projected market size by 2033: USD 235.4 Billion
- CAGR (2026-2033): 10.4%
Three ways to get this report
Buy it, customize it, or ask a question.Ask an Analyst
Analyst response in 1 business day
- AccessReport author, directly
- Reply timeWithin 1 working day
- No sales callDirect answer only
- FormatEmail reply
- CostFree, no cost
Get the Full Report
What the study covers
- FormatsPDF · Excel · Dashboard
- Timeline2026–2033 annual, 2025 base
- Coverage20+ countries, 5 regions
- Companies10+ key players profiled
Customize the Report
20% free customization
- IncludeCountries, segments, points
- TailorTo your product definition
- ExtendDeeper competitor detail
- OrA fully bespoke study
- Turnaround5–10 working days
Regulatory approvals, biosimilar insulin expansion, and cardiovascular benefits enhance market growth. Innovations in drug delivery, personalized medicine, and AI-driven R&D accelerate development. Favorable reimbursement policies and healthcare expansion in emerging markets further drive adoption, strengthening pharmaceutical investments in diabetes treatment.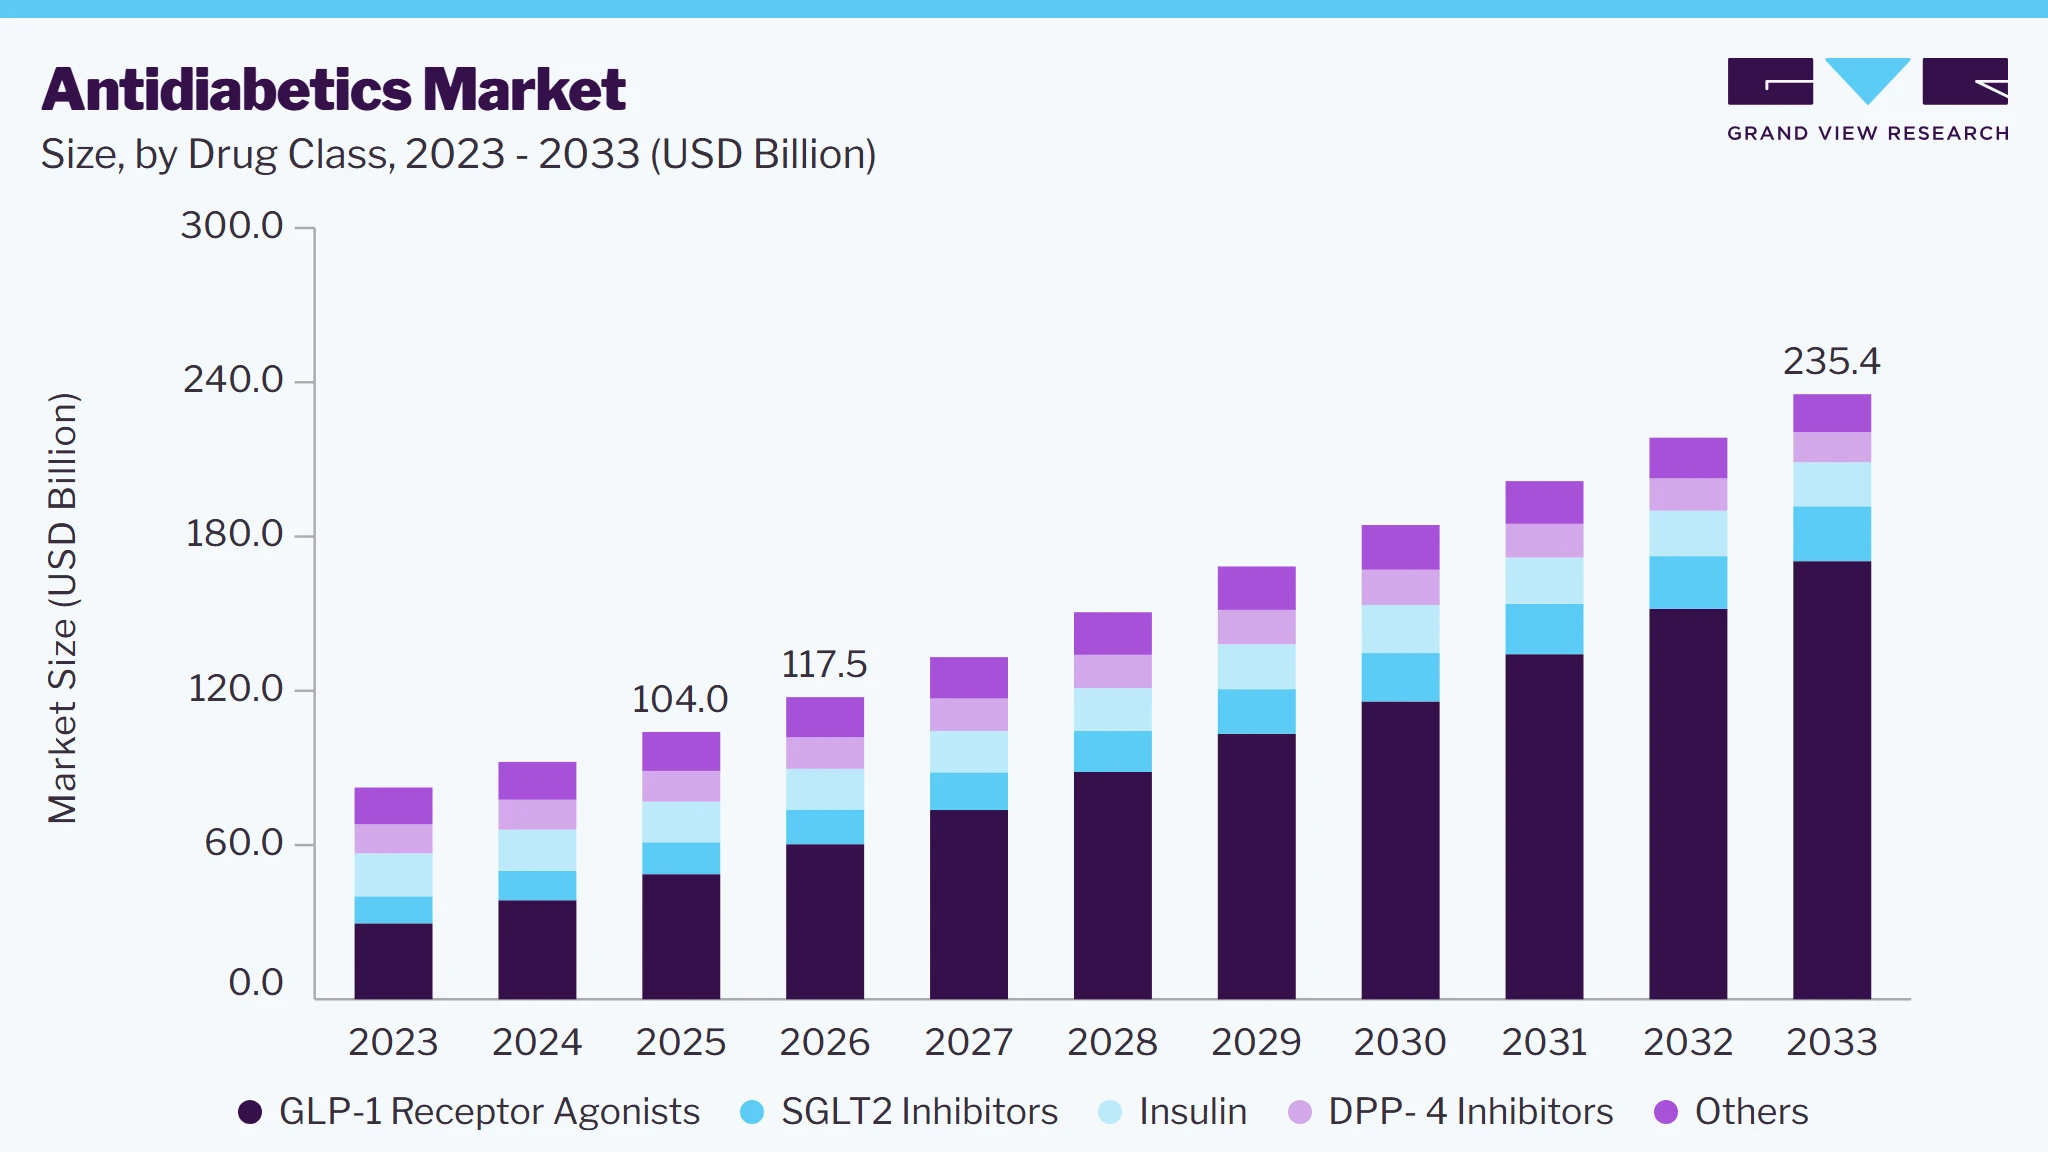 To learn more about this report, Download Free Sample Report
The industry is driven by the rising global diabetes prevalence, projected to increase from 536.6 million in 2021 to 783.7 million by 2045 (IDF Diabetes Atlas, 10th edition). The growing burden of undiagnosed diabetes (44.7% in 2021) further supports the demand for diagnostics and early intervention therapies. The increasing incidence of impaired glucose tolerance (541 million in 2021) and impaired fasting glucose (319 million in 2021) highlights the need for preventive and therapeutic solutions. Additionally, diabetes-related health expenditures reached $966 billion in 2021, reflecting a growing economic burden and investment in advanced treatment options. Expanding healthcare access, regulatory approvals, and innovative drug classes such as GLP-1 receptor agonists further accelerate market growth.
The expanded approval of a leading GLP-1 receptor agonist is expected to drive market growth by broadening its use across cardiometabolic conditions, enhancing its clinical utility and reinforcing demand within the antidiabetic therapeutics segment. For instance, in January 2025, Novo Nordisk announced FDA approval of Ozempic (semaglutide) to reduce the risk of kidney disease worsening, kidney failure, and cardiovascular death in adults with type 2 diabetes and chronic kidney disease (CKD). This approval follows the FLOW phase 3b trial, which demonstrated a 24% relative risk reduction. Ozempic is now the most broadly indicated GLP-1 RA. CKD affects 37 million U.S. adults, with 40% of type 2 diabetes patients experiencing CKD. The approval expands Ozempic’s cardiometabolic benefits.
Pipeline Analysis
The antidiabetic therapeutics market demonstrates a strong and evolving pipeline, reflecting ongoing innovation and competitive activity. Multiple candidates are progressing through Phase 2 to Phase 4 trials, with semaglutide-based combinations playing a central role. Key sponsors such as Novo Nordisk, Eli Lilly, and other emerging players are exploring mono- and combination therapies targeting glycemic control and weight reduction. The presence of novel agents like retatrutide, cagrilintide, and orforglipron indicates a shift toward multi-target approaches. Given the robust clinical activity and diversification in mechanisms of action, the market is positioned for sustained growth over the forecast period.
Interventions
Sponsor
Phases
DRUG: semaglutide|DRUG: oral glucose-lowering medications (commercially available)
Novo Nordisk A/S
PHASE4
DRUG: Oral semaglutide|DRUG: Placebo (semaglutide)
Novo Nordisk A/S
PHASE3
DRUG: Antidiabetics|DRUG: Placebo (semaglutide)
Novo Nordisk A/S
PHASE3
DRUG: GZR18|DRUG: Antidiabetics
Gan and Lee Pharmaceuticals, USA
PHASE2
DRUG: HEC88473, Placebo, Dulaglutide
Dongguan HEC Biopharmaceutical R&D Co., Ltd.
PHASE2
DRUG: Orforglipron|DRUG: Placebo
Eli Lilly and Company
PHASE3
DRUG: Retatrutide|DRUG: Antidiabetics
Eli Lilly and Company
PHASE3
DRUG: Cagrilintide|DRUG: Antidiabetics|DRUG: Tirzepatide
Novo Nordisk A/S
PHASE3
DRUG: HRS9531 Injection|DRUG: Antidiabetics Injection
Fujian Shengdi Pharmaceutical Co., Ltd.
PHASE3
DRUG: Cagrilintide|DRUG: Antidiabetics|DRUG: Tirzepatide
Novo Nordisk A/S
PHASE3
DRUG: Cagrilintide|DRUG: Antidiabetics|DRUG: Placebo cagrilintide|DRUG: Placebo semaglutide
Novo Nordisk A/S
PHASE3
DRUG: Retatrutide|DRUG: Placebo
Eli Lilly and Company
PHASE3
DRUG: Pioglitazone + Alogliptin|DRUG: Alogliptin|DRUG: Metformin|DRUG: Dapagliflozin
Celltrion Pharm, Inc.
PHASE4
Source: Clinicaltrial.gov
Expanded Clinical Utility of SGLT2 Inhibitors
As per the study titled "SGLT2 inhibitors and clinical outcomes in patients with heart failure: a systematic review and meta-analysis" published in 2024 in The Lancet, several findings may act as drivers for the antidiabetic market. The study highlights that SGLT2 inhibitors demonstrate consistent benefits in reducing cardiovascular death and worsening heart failure across diverse patient populations-including those without diabetes. These findings support the use of SGLT2 inhibitors beyond glycemic control, indicating their potential role in managing multimorbidity involving diabetes, heart failure, and chronic kidney disease. As the study shows efficacy independent of diabetic status, it could promote broader clinical adoption and inclusion in treatment guidelines. Such expanded indications and cross-specialty utility align with current healthcare trends favoring integrated chronic disease management, which may support increased prescribing, improved reimbursement scenarios, and ultimately drive growth in the antidiabetic market.
In addition, the 2025 study titled "Sodium-Glucose Cotransporter-2 (SGLT-2) Inhibitors: Antidiabetic Medications for Treating Diabetes" highlights the role of SGLT-2 inhibitors in managing type 2 diabetes by promoting urinary glucose excretion. Beyond glycemic control, the study emphasizes cardiovascular and renal benefits, particularly with agents like dapagliflozin. It also discusses newer drugs such as enavogliflozin and henagliflozin, offering improved selectivity and efficacy. The evolution from natural compounds like phlorizin to modern SGLT-2 inhibitors reflects advancements in diabetes therapy. Overall, the study positions SGLT-2 inhibitors as key contributors to both glycemic management and broader clinical outcomes in type 2 diabetes treatment.
Market Dynamics
The antidiabetics market is driven by the increasing prevalence of type 1 and type 2 diabetes, rising obesity rates, and growing demand for therapies that provide effective glycemic control while addressing associated metabolic conditions. The market has witnessed a shift toward GLP 1 receptor agonists, SGLT2 inhibitors, and combination therapies due to their demonstrated clinical benefits in blood glucose management, weight reduction, and cardiovascular risk management. Continuous advancements in insulin formulations, including long acting and once weekly candidates, are expanding treatment options and supporting patient adherence. In addition, increasing adoption of continuous glucose monitoring systems and digital health platforms is improving disease management and enabling more personalized treatment approaches. Government initiatives focused on diabetes screening and early diagnosis are contributing to greater treatment penetration across several regions. Furthermore, ongoing investments in research and development, growing availability of biosimilar insulin products, and expanding access to healthcare services continue to support the demand for antidiabetic therapies worldwide.
The increasing prevalence of diabetes, coupled with growing demand for therapies that improve glycemic control and treatment adherence, continues to drive the antidiabetics market. Rising obesity rates, aging populations, and broader diabetes screening programs are contributing to a larger diagnosed patient population requiring long term treatment. Healthcare providers are increasingly adopting therapies that offer additional cardiovascular and renal benefits, supporting the utilization of GLP 1 receptor agonists and SGLT2 inhibitors. The market is also benefiting from technological advancements in insulin delivery and glucose monitoring systems that enable improved disease management. Pharmaceutical companies are focusing on therapies that reduce dosing frequency and simplify treatment regimens, which can improve adherence among patients requiring lifelong care. For instance, in March 2026, Novo Nordisk received U.S. FDA approval for Awiqli (insulin icodec-abae), the first once weekly basal insulin for adults with type 2 diabetes. The approval was supported by the ONWARDS Phase 3 clinical program involving approximately 2,680 adults with type 2 diabetes and reduced insulin administration from 7 injections per week to 1 injection per week, supporting treatment convenience and broader adoption of insulin therapy.
Regulatory requirements and safety concerns continue to restrain the growth of the antidiabetics market. New therapies and extended duration insulin products require comprehensive clinical evaluation to establish safety and efficacy across different patient populations. Concerns related to hypoglycemia, gastrointestinal adverse events, cardiovascular outcomes, and long term treatment effects often result in extensive regulatory review processes. These requirements can increase development costs, delay product approvals, and limit the speed of market entry for innovative therapies. In addition, reimbursement restrictions and pricing pressures across several healthcare systems may affect patient access to newly introduced treatments. Regulatory agencies are placing increasing emphasis on post marketing surveillance and real world evidence to support long term safety assessments. For instance, in July 2024, Novo Nordisk announced that the U.S. FDA had issued a Complete Response Letter for once weekly insulin icodec for type 1 diabetes and requested additional information during the review process. Clinical data showed 50% to 80% higher rates of clinically significant or severe hypoglycemia compared with daily insulin degludec in type 1 diabetes patients, resulting in additional regulatory scrutiny before approval.
The growing availability of biosimilar insulin products presents a significant opportunity for the antidiabetics market. Rising healthcare expenditure associated with diabetes management has increased the focus on affordable treatment alternatives that can maintain clinical effectiveness while improving patient access. Biosimilar products can support wider treatment adoption by reducing therapy costs and increasing competition within the insulin segment. This opportunity is particularly relevant in emerging economies where diabetes prevalence continues to rise and affordability remains a key consideration for long term disease management. Pharmaceutical companies are increasing investments in biosimilar development to expand their diabetes portfolios and address unmet treatment needs. For instance, in February 2025, Sanofi received U.S. FDA approval for Merilog (insulin aspart-szjj), the first rapid acting insulin biosimilar to NovoLog for adults and pediatric patients with diabetes mellitus. The approval included both a 3 mL prefilled pen and a 10 mL multiple dose vial, expanding the availability of lower cost insulin treatment options and creating opportunities for broader patient access to diabetes care.
Market Concentration & Characteristics
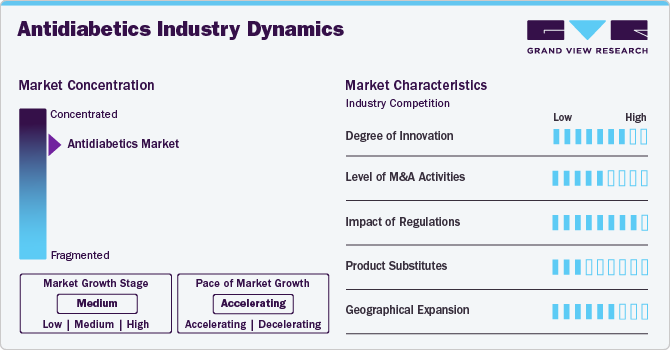
The industry demonstrates continuous innovation in therapeutic classes, drug delivery mechanisms, and digital health integration. Developments include long-acting insulin analogs, GLP-1 receptor agonists, SGLT2 inhibitors, and fixed-dose combinations. Increasing focus on precision medicine, smart insulin pens, and adjunct digital platforms supports individualized disease management. Innovations aim to improve glycemic control, reduce cardiovascular risks, and enhance adherence through less frequent dosing and fewer side effects.
M&A activities in the antidiabetic market are driven by the pursuit of advanced therapies and pipeline diversification. Companies acquire or partner with biotech firms to gain access to novel drug candidates, such as oral insulin formulations and next-generation GLP-1 drugs. Strategic collaborations also target integrated digital solutions and biosimilar insulin development. These transactions aim to strengthen competitive positioning, especially in addressing rising global prevalence and demand for cost-effective therapies.
 To learn more about this report, Download Free Sample Report
The antidiabetic drug market is regulated by agencies such as the FDA and EMA, with stringent approval pathways for new molecular entities and biosimilars. Clinical efficacy, safety in long-term use, and cardiovascular outcome trials are critical regulatory benchmarks. Pricing and reimbursement decisions are influenced by comparative effectiveness and economic evaluations. In emerging regions, regulatory harmonization efforts aim to expedite access to essential diabetes medications.
While lifestyle interventions such as diet, exercise, and behavioral therapy remain essential in diabetes care, pharmacologic treatments dominate moderate-to-severe cases. Substitution pressures also arise from alternative therapies, including bariatric surgery for type 2 diabetes remission and emerging cell-based treatments. However, established antidiabetic drugs maintain demand due to guideline inclusion, scalable use, and real-world effectiveness.
Growth in the antidiabetic market is accelerating in emerging economies across Asia-Pacific, Africa, and Latin America, driven by urbanization, dietary shifts, and rising obesity rates. Multinational firms expand local production and patient access programs to meet growing needs. Developed regions, notably North America and Europe, sustain revenue through the uptake of innovative therapies, value-based care models, and increasing use of combination and personalized treatments.
Analyst Perspective
The antidiabetics market continues to advance toward therapies that provide effective glycemic control while addressing associated cardiovascular, renal, and metabolic complications. GLP 1 receptor agonists, SGLT2 inhibitors, and next generation insulin products are becoming increasingly important components of diabetes management due to their demonstrated clinical benefits and ability to improve treatment adherence. Biosimilar insulin products are expanding patient access by offering cost effective treatment alternatives, while pharmaceutical companies are focusing on product differentiation, label expansions, and combination therapies to strengthen their market positions. Although pricing pressures, regulatory requirements, and long term safety monitoring remain important challenges, continued innovation in oral and injectable therapies supports market growth. The market is expected to maintain steady expansion as the global diabetes burden increases and healthcare systems prioritize early diagnosis, long term disease management, and improved patient outcomes.
Drug Class Insights
Based on drug class, the glp-1 receptor agonists segment led the market with the largest revenue share of46.8 % in 2025 due to their dual benefits in glycemic control and weight reduction, which are critical for managing type 2 diabetes. These agents, including liraglutide and semaglutide, enhance insulin secretion, suppress glucagon, and slow gastric emptying. Their cardiovascular benefits, demonstrated in major clinical trials, have further strengthened their adoption. Additionally, the introduction of once-weekly formulations and combination therapies has improved patient compliance. Rising global diabetes prevalence and increasing preference for effective, multi-functional therapies continue to drive growth in this segment across major pharmaceutical markets.
SGLT2 inhibitors are experiencing significant growth in the antidiabetic market due to their unique mechanism of reducing glucose reabsorption in the kidneys, promoting glycemic control and weight loss. Their added cardiovascular and renal protective effects, supported by clinical evidence, have expanded their usage beyond diabetes to heart failure and chronic kidney disease management. Increasing physician preference, favorable clinical outcomes, and expanding label approvals contribute to the segment’s rising demand globally. Leading molecules such as dapagliflozin and empagliflozin continue to drive growth, supported by strategic launches and ongoing clinical research.
Diabetes Type Insights
Based on diabetes type, the type 2 segment led the market with the largest revenue share of 79.4% in 2025. This growth be attributed to the increasing prevalence of this chronic condition globally. According to the IMHE report June 2023, the global diabetes cases to soar from 529 million to 1.3 billion by 2050 As more individuals are diagnosed with type 2 diabetes, the demand for effective management and treatment options grows, leading to the segment's substantial market share. The increasing awareness about diabetes prevention management and the development of innovative therapies and technologies are projected to drive this growth.
The Type 1 diabetes segment is witnessing significant growth in the antidiabetic market, driven by advancements in insulin delivery systems, continuous glucose monitoring technologies, and increased awareness of early diagnosis and disease management. Improved access to treatment and innovations in insulin analogs are enhancing patient outcomes and adherence. Additionally, growing research into adjunct therapies, including SGLT2 inhibitors for Type 1 diabetes, is expanding therapeutic options. The rising global prevalence of Type 1 diabetes, particularly among younger populations, is further contributing to the segment’s expanding market share across both developed and developing regions.
Route of Administration Insights
Based onroute of administration, theintravenous segment led the market with the largest revenue share of 41.8% in 2025 due to its critical role in managing acute complications such as diabetic ketoacidosis and severe hyperglycemia. Hospitals and emergency care settings widely adopted intravenous administration for rapid therapeutic effect, especially in patients requiring immediate glycemic control. The segment’s growth was further supported by increasing hospitalization rates linked to diabetes-related complications and enhanced access to healthcare infrastructure in developing regions. Additionally, intravenous routes remained essential for administering insulin in intensive care units, contributing to its continued market dominance.
The subcutaneous segment is estimated to grow at the fastest rate during the forecast period. This method of administering diabetes medication is more convenient for patients, allowing for self-injection or the use of less invasive devices, thereby reducing the need for frequent doctor visits or hospital stays. Subcutaneous diabetic drugs also act quickly, helping to manage blood glucose levels more effectively-an essential factor in diabetes care. Several prominent companies are partnering with technology firms to develop smart insulin pens that connect to mobile apps, enabling better tracking of blood sugar levels and dosage recommendations. This reflects the ongoing transformation and advancement in diabetes care. For instance, in August 2023, Insulet launched the Omnipod 5 Automated Insulin Delivery System in Germany, marking a significant step forward in diabetes treatment. The growing adoption of such innovative delivery solutions is expected to drive the segment’s growth.
Distribution Channel Insights
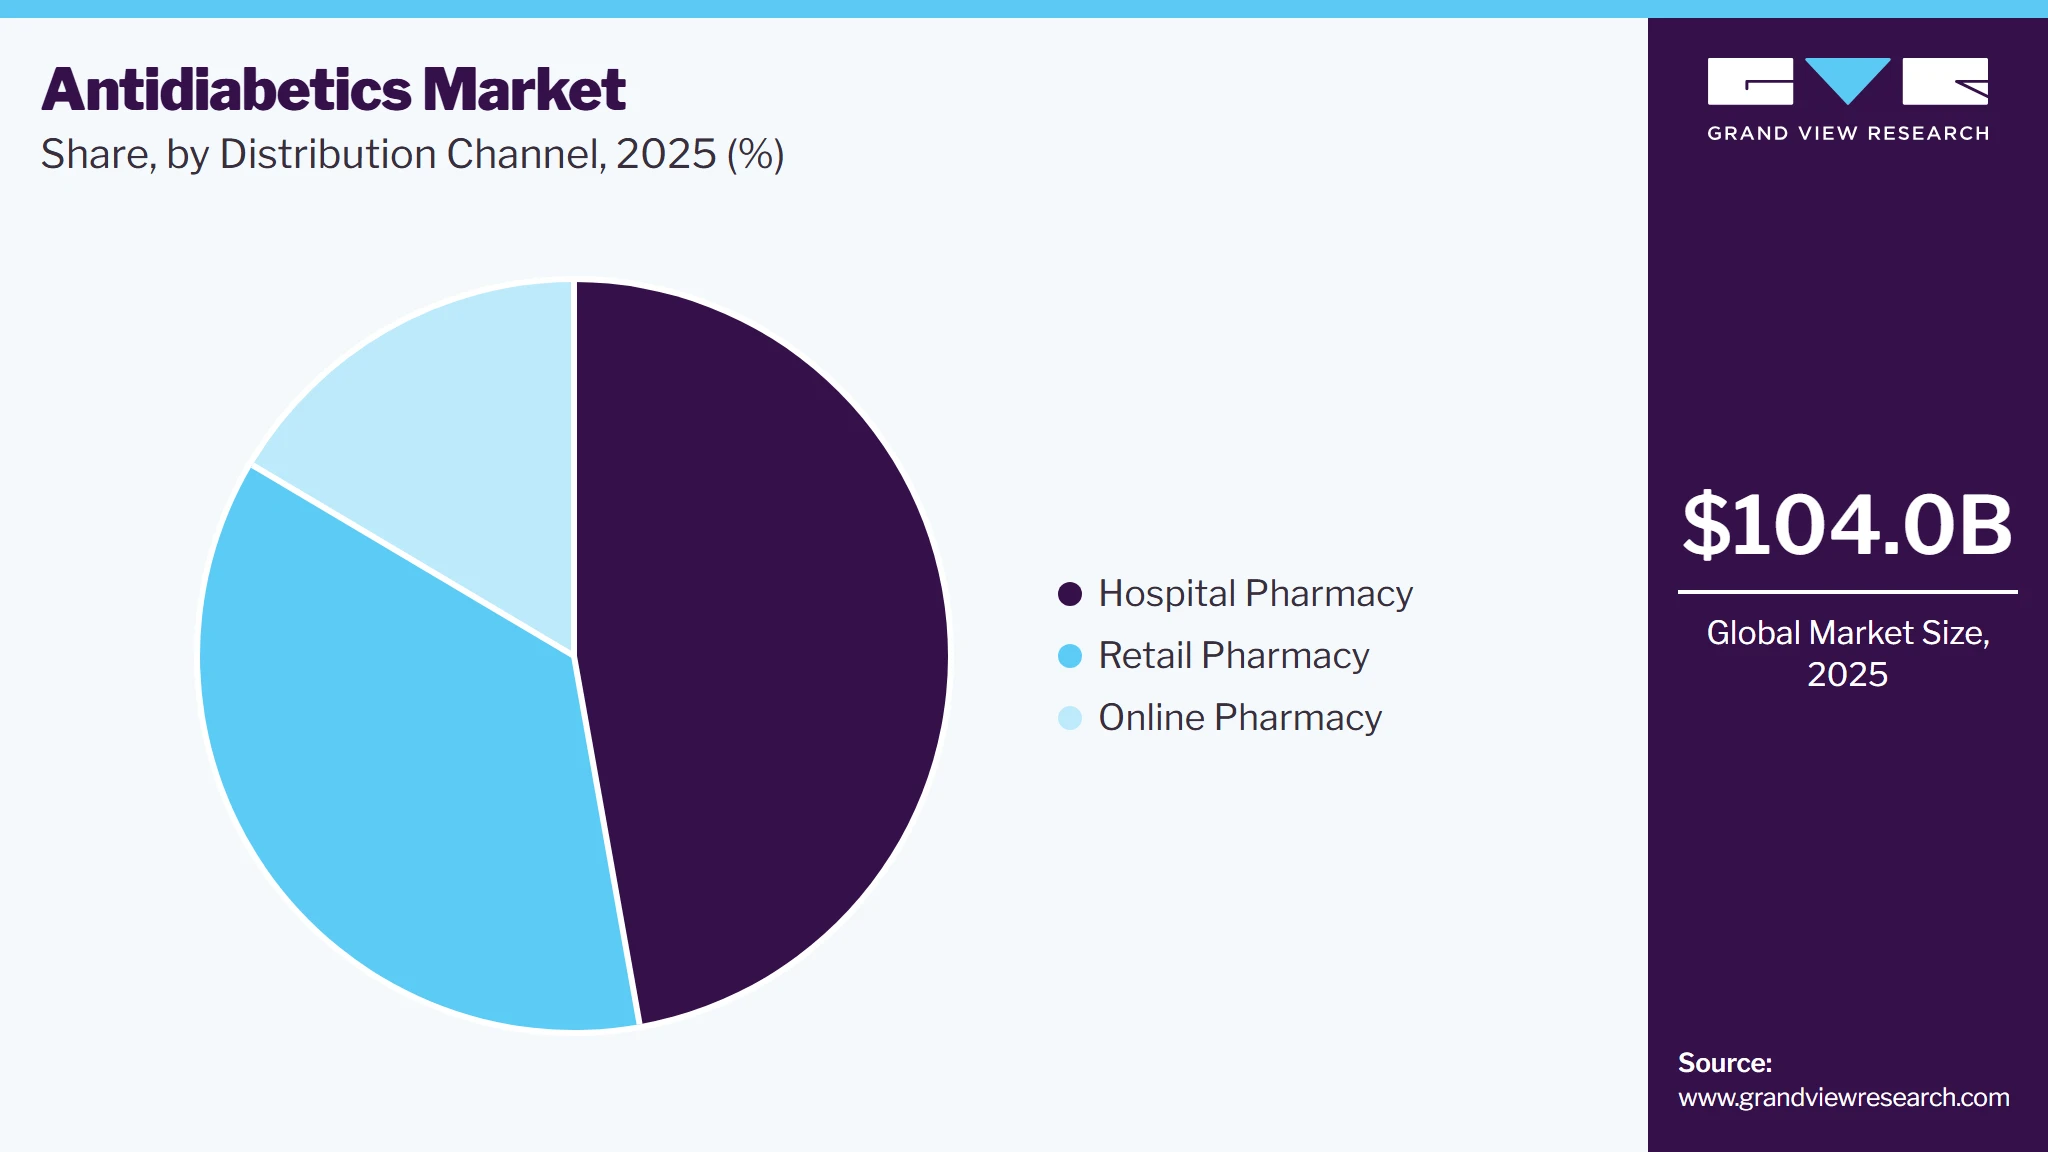
Based on distribution channel, the hospital pharmacy segment led the market with the largest revenue share of 47.2% in 2025. This dominance is attributed to the high volume of prescriptions filled and administered within hospital settings, especially for patients requiring intensive diabetes management or combination therapies. Hospitals are also the primary points of care for newly diagnosed cases and for those with severe complications, leading to increased dispensing of antidiabetic drugs. Additionally, hospitals often stock a broad range of medications, including newer and injectable therapies, further contributing to the segment's leading position in the market.
 To learn more about this report, Download Free Sample Report
The online pharmacies segment is estimated to grow at the fastest growth rate during the forecast period. This growth is driven by increasing internet penetration, rising preference for doorstep delivery, and improved access to medications in remote areas. The convenience of online ordering, availability of discounts, and ease of comparing product options contribute to higher consumer adoption. Additionally, the growing use of mobile health platforms and e-prescriptions is streamlining the purchase process for chronic disease treatments like diabetes, supporting the segment's rapid expansion.
Regional Insights
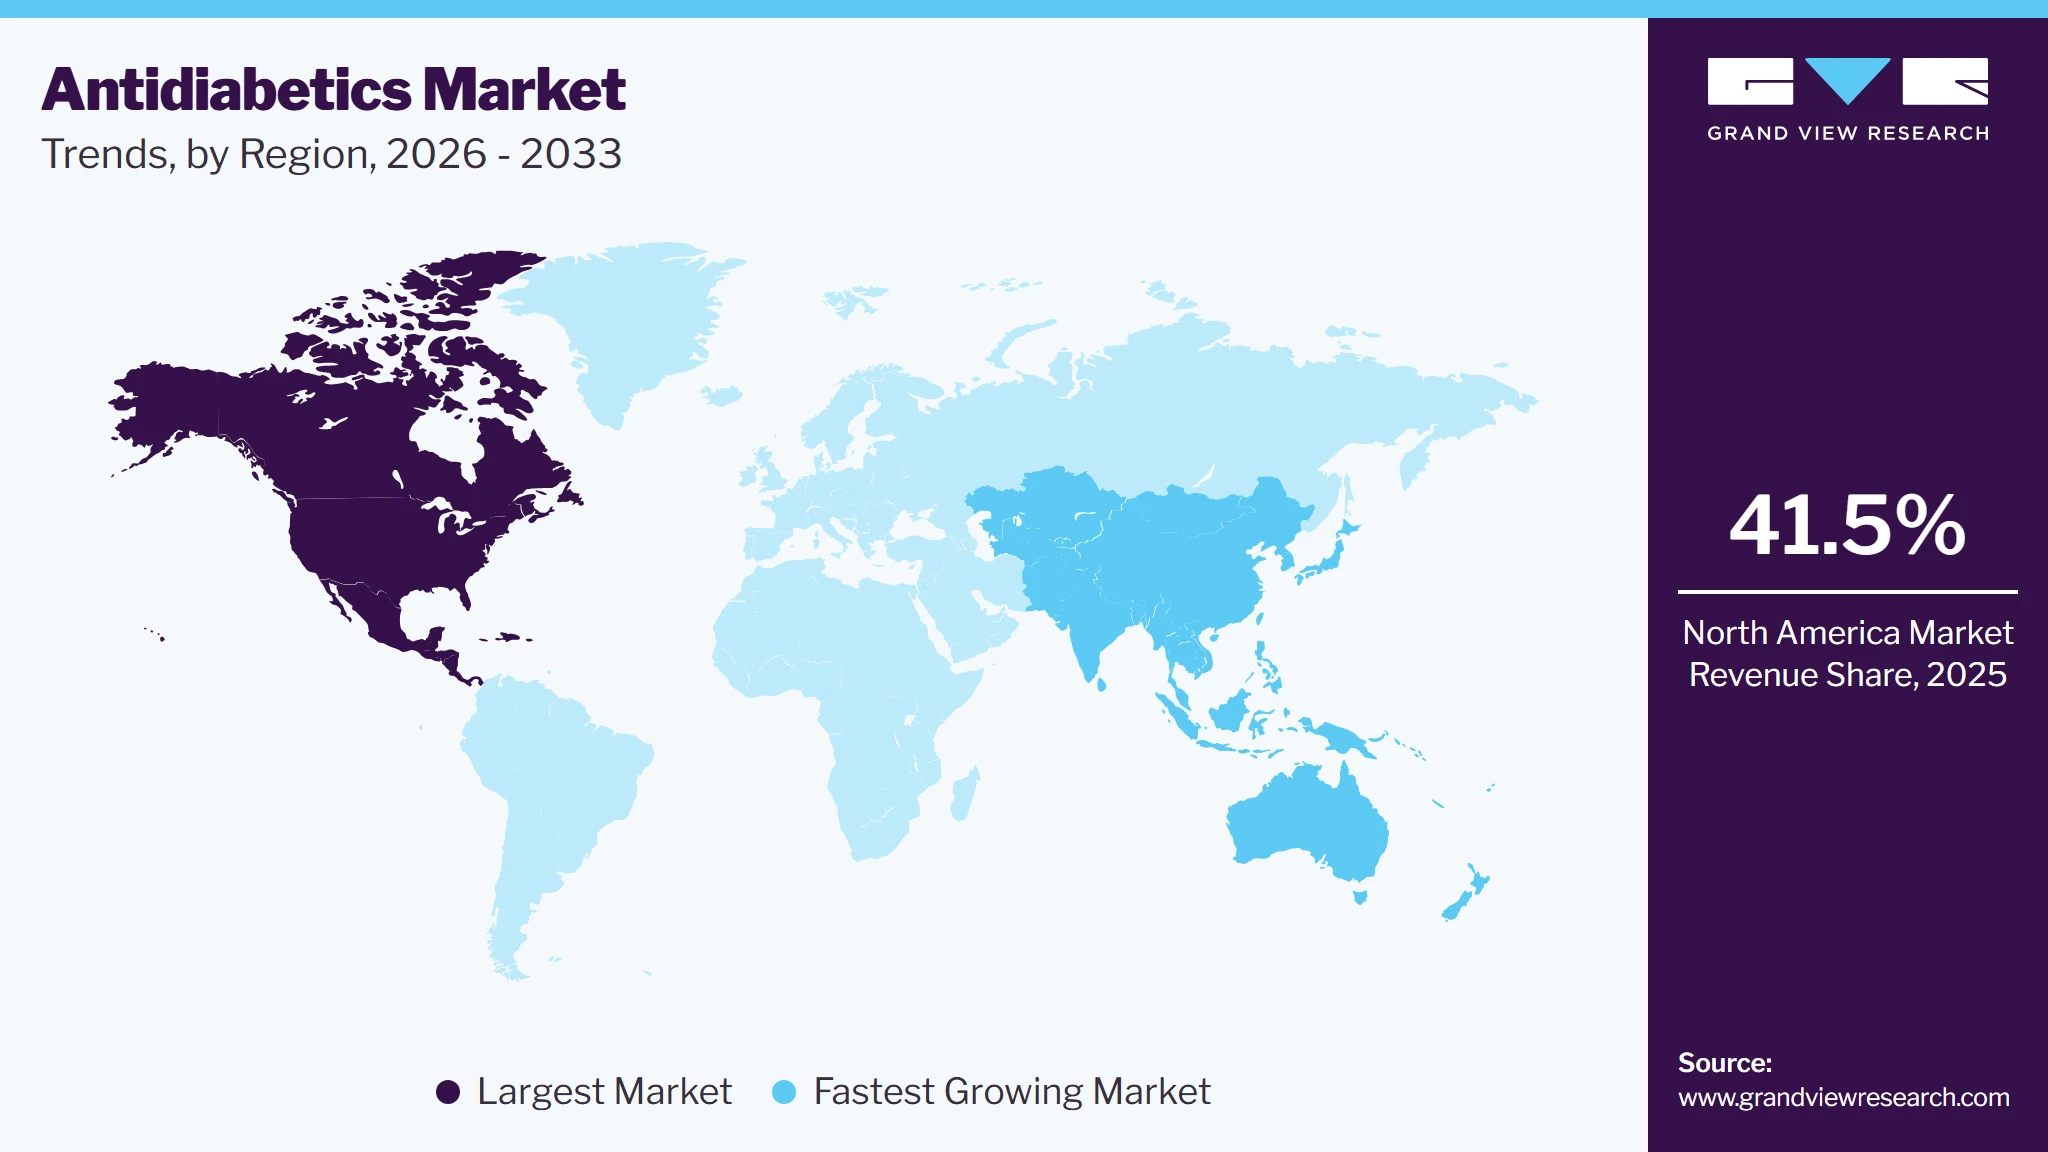
North America dominated the antidiabetics market with the largest revenue share of 41.5% in 2025. The region has a notably high prevalence of diabetes, primarily type 2, which is increasing due to lifestyle changes and an aging population. Moreover, the presence of a well-established healthcare infrastructure and high healthcare spending facilitates widespread access to treatment and disease management solutions. The region is home to several leading pharmaceutical firms and research institutes that consistently develop and introduce innovative antidiabetic drugs and technologies, fueling overall market growth.
 To learn more about this report, Download Free Sample Report
U.S. Antidiabetics Market Trends
The antidiabetics market in the U.S. held the largest share in the North America region in 2025. This is attributed to advancements in clinical research, an increasing number of FDA-approved drugs, and a robust pipeline of ongoing R&D. The increasing focus on personalized diabetic therapy and improved access to newer drug classes is also supporting market growth. As of mid-2022, nearly 100 antihyperglycemic agents were under evaluation for type 2 diabetes, and over 60 had already received approval, underscoring the dynamic development landscape.
Europe Antidiabetics Market Trends
The antidiabetics market in Europe is expanding, driven by the high prevalence and financial burden of diabetes. It remains a leading cause of mortality across the region. However, prevalence and mortality rates differ among countries. The market is witnessing strong growth due to increased disease awareness, supportive health policies, and the rising adoption of modern therapeutic options. The surge in the use of DPP-4 inhibitors and GLP-1 receptor agonists also reflects a shift toward more effective drug regimens, contributing to the regional market’s expansion.
The UK antidiabetics market is supported by rising prescription volumes and the growing adoption of innovative treatment options. There is increasing demand for newer classes of antidiabetic drugs as public health authorities focus on enhancing disease management outcomes. Ongoing national initiatives to reduce diabetes-related health complications are creating a favorable environment for market growth, particularly in terms of drug availability, reimbursement, and physician engagement.
The antidiabetics market in France is expected to grow steadily over the coming years. Rising public awareness around disease management and increasing screening activities are contributing to the demand for early and effective interventions. DPP-4 inhibitors and GLP-1 receptor agonists remain the most prescribed drug classes in the country, reflecting physicians' preference for well-tolerated and effective therapies. Government programs focusing on chronic disease management are also expected to support long-term market development.
Germany antidiabetics market is projected to grow at a lucrative rate over the forecast period. Market growth is driven by ongoing advancements from both public and private organizations and a rising elderly population. Several companies headquartered in Germany are engaged in extensive R&D activities, which are contributing to the commercialization of novel antidiabetic therapies. These developments are fostering enhanced treatment outcomes and expanding therapeutic options, thereby boosting market performance.
Asia Pacific Antidiabetics Market Trends
The antidiabetics market in Asia Pacific is estimated to register the fastest growth during the forecast period. The surge in type 2 diabetes cases is fueled by changes in lifestyle, urbanization, and dietary habits. The region’s large and aging population base makes it a critical market for diabetes therapeutics. Additionally, the rapid expansion of telemedicine and digital health platforms is improving access to diabetes care. The integration of technology into diabetes management is expected to further accelerate market penetration in the region.
China antidiabetics market is expected to witness substantial growth in the near future. China has one of the highest numbers of diabetes patients globally, with nearly 114 million individuals currently affected. This massive disease burden is spurring increased demand for antidiabetic therapies. The government and healthcare providers are focusing on improving early diagnosis and access to modern treatment options, which is expected to drive the expansion of the therapeutic landscape in the country.
The antidiabetics market in Japan is forecasted to grow consistently due to the presence of a strong healthcare infrastructure. Over 7.4 million individuals were living with diabetes in 2020, and the number continues to rise due to a westernized lifestyle, unhealthy eating patterns, lack of physical activity, and an aging demographic. Japan’s emphasis on early intervention, continuous patient monitoring, and adoption of advanced treatment options is expected to drive the overall market growth.
Latin America Antidiabetics Market Trends
The antidiabetics market in Latin America is gaining traction, with the region recognized as a promising area for industry expansion. A significant portion of the population is entering older age groups, which is associated with a higher risk of diabetes. Increasing healthcare expenditure, coupled with efforts to improve access to chronic disease treatments, supports regional market growth. Local governments are working on strengthening health systems and expanding access to antidiabetic drugs and services.
Brazil antidiabetics market is expected to expand during the forecast period. Several reforms have been introduced to diversify financing, develop new service organizations, and increase the distribution of medical professionals. Additionally, quality improvement programs and policy frameworks aimed at reducing diabetes-related complications are shaping a more favorable market. These efforts also reflect a growing interest in integrating comprehensive diabetes therapy and management strategies at the national level.
Middle East and Africa (MEA) Antidiabetics Market Trends
The antidiabetics market in the Middle East and Africa is advancing, supported by increased government focus on addressing the growing diabetes epidemic. Lifestyle and dietary changes have led to rising obesity rates, which in turn elevate diabetes risk. Efforts by national authorities to raise awareness and invest in chronic disease programs are expected to foster long-term market development. The shift towards structured care models and integrated disease management solutions is expected to support the consistent adoption of diabetic medications.
Saudi Arabia antidiabetics market is showing strong momentum, attributed to considerable government investment in pharmaceutical infrastructure and education. Public health organizations, including the Saudi Diabetes & Endocrine Association, are actively engaged in awareness campaigns aimed at early diagnosis and treatment. At the same time, investments in R&D and the adoption of modern drug delivery systems are expected to enhance patient compliance and improve outcomes, further contributing to the market’s growth trajectory.
Key Antidiabetics Company Insights
The antidiabetics market is experiencing notable growth driven by the prevalence of diabetes globally, coupled with advancements in drug research and technology leading to more effective and targeted treatment options. This presents significant opportunities for major players to capitalize. Key market participants are proactively pursuing strategic initiatives such as mergers, acquisitions, and collaborations to enhance their market share and cater to the rising demand for antidiabetic products and services.
Key Antidiabetics Companies:
The following key companies have been profiled for this study on the antidiabetics market.
-
Novo Nordisk
-
Eli Lilly and Company
-
Sanofi
-
Merck & Co., Inc.
-
AstraZeneca plc
-
Johnson & Johnson Services Inc.
-
Boehringer Ingelheim
-
Novartis AG
-
Takeda Pharmaceutical Company
-
Bayer AG
Competitive Benchmarking
Category
Operating Strategies
Competitive Edge
Weakness
Established Players (Eli Lilly and Company, AstraZeneca plc, Boehringer Ingelheim, Merck & Co., Inc., Bayer AG)
- Focus on expanding diabetes portfolios through investments in GLP 1 receptor agonists, SGLT2 inhibitors, and combination therapies. Strengthen market presence through large scale clinical programs, label expansions, strategic collaborations, and geographic expansion across developed and emerging markets. Emphasize cardiovascular and renal outcome data to support broader utilization of diabetes therapies.
- Strong global brand presence, extensive clinical evidence, and established relationships with healthcare providers and payers. Broad commercial infrastructure, diversified product portfolios, and significant research and development capabilities support sustained market positioning and product adoption.
- Exposure to pricing pressures, patent expirations, and increasing competition from biosimilars and generic products. Large organizational structures may extend product development timelines and delay responses to rapidly changing market requirements.
Emerging and Diversifying Players (Takeda Pharmaceutical Company Limited, Bristol-Myers Squibb, Pfizer, Inc., Johnson & Johnson Services, Inc., Novartis AG)
- Focus on selective participation in diabetes care through strategic partnerships, pipeline development, and expansion into metabolic disease segments. Leverage existing therapeutic expertise and commercial infrastructure to evaluate opportunities in diabetes and related chronic disease management. Explore innovative treatment approaches through collaborations and targeted research programs.
- Strong financial resources, established pharmaceutical capabilities, and broad healthcare networks. Ability to leverage expertise across multiple therapeutic areas and access large patient populations through global commercial operations.
- Comparatively smaller presence in the current diabetes therapeutics market compared with category leaders. Limited product concentration in core antidiabetic segments may reduce competitive positioning against companies with dedicated diabetes portfolios and established market presence.
Recent Developments
-
In February 2025, the U.S. FDA approved Merilog (insulin-aspart-szjj), the first rapid-acting insulin biosimilar to Novolog, for adults and children with diabetes. Approved in 3ml prefilled pen and 10ml vial forms, Merilog aims to improve mealtime glycemic control. Manufactured by Sanofi-Aventis U.S. LLC, it is the third insulin biosimilar approved in the U.S. This milestone supports the FDA’s goal to expand access to cost-effective insulin therapies and foster a competitive biosimilar market for diabetes treatment.
-
In May 2024, Soliqua (Insulin Glargine 100IU + Lixisenatide 33mcg/ml) is indicated for adults with type 2 diabetes inadequately controlled on basal insulin or GLP-1 receptor agonist alone. Each 3ml prefilled pen is priced at ₹1,850 (approximately 22.30 USD). Manufactured by Sanofi India, Soliqua combines basal insulin and a GLP-1 RA for glycemic control. It is administered subcutaneously once daily, with the dosage adjusted individually based on prior therapy, metabolic needs, and glycemic response.
-
In January 2024, Glenmark launched the first biosimilar of Liraglutide in India. Liraglutide is a popular drug used to treat type 2 diabetes mellitus in adults. The drug will be marketed under the brand name Lirafit for USD 1.20 and will be available only under prescription. The biosimilar launch will make the drug more accessible to patients in India as the cost will lower by up to 70%.
-
In June 2023, the FDA approved Jardiance (empagliflozin) and Synjardy (empagliflozin with metformin) for treating type 2 diabetes in children aged 10 and older. These drugs, previously used in adults, now offer pediatric patients new options beyond metformin. A clinical trial showed empagliflozin significantly reduced HbA1C levels. Common side effects include low blood sugar, urinary tract infections, and gastrointestinal issues. These medications are not recommended for type 1 diabetes or patients with severe kidney problems.
Antidiabetics Market Report Scope
Report Attribute
Details
Market size in 2025
USD 104.0 billion
Estimated market size in 2026
USD 117.5 billion
Projected market size by 2033
USD 235.4 billion
Growth rate
CAGR of 10.4% from 2026 to 2033
Historical data
2021 - 2024
Forecast period
2026 - 2033
Quantitative units
Revenue in USD million/billion and CAGR from 2026 to 2033
Report coverage
Revenue forecast, company ranking, competitive landscape, growth factors, and trends
Segments covered
Drug class, diabetes type, route of administration, distribution channel, region
Regional scope
North America; Europe; Asia Pacific; Latin America; MEA
Country scope
U.S.; Canada; Mexico; UK; Germany; France; Italy; Spain; Denmark; Norway; Sweden; Japan; China; India; South Korea; Australia; Thailand; Brazil; Argentina; South Africa; Saudi Arabia; UAE; Kuwait.
Key companies profiled
AstraZeneca plc; Bayer AG; Takeda Pharmaceutical Company Limited; Eli Lilly and Company; Boehringer Ingelheim; Bristol-Myers Squibb; Pfizer, Inc.; Johnson & Johnson Services Inc.; Merck & Co. Inc ; Novartis AG.
Customization scope
Free report customization (equivalent up to 8 analysts' working days) with purchase. Addition or alteration to country, regional & segment scope.
Pricing and purchase options
Avail customized purchase options to meet your exact research needs. Explore purchase options
Global Antidiabetics Market Report Segmentation
This report forecasts revenue growth at the global, regional, and country levels and provides an analysis of the latest trends in each of the sub-segments from 2021 to 2033. For this study, Grand View Research has segmented the global antidiabetics market report on the basis of drug type, diabetics type, route of administration, distribution channel, and region:
-
Drug Class Outlook (Revenue, USD Million, 2021 - 2033)
-
Insulin
-
Insulin By Type
-
Long-acting insulin
-
Premix insulin
-
Fast-acting insulin
-
Human insulin
-
-
-
GLP-1 Receptor Agonists
-
DPP- 4 Inhibitors
-
SGLT2 Inhibitors
-
Others
-
-
Diabetes Type Outlook (Revenue, USD Million, 2021 - 2033)
-
Type 1
-
Type 2
-
-
Route of Administration Outlook (Revenue, USD Million, 2021 - 2033)
-
Oral
-
Subcutaneous
-
Intravenous
-
-
Distribution Channel Outlook (Revenue, USD Million, 2021 - 2033)
-
Online pharmacies
-
Hospital Pharmacies
-
Retail pharmacies
-
-
Regional Outlook (Revenue, USD Million, 2021 - 2033)
-
North America
-
U.S.
-
Canada
-
Mexico
-
-
Europe
-
UK
-
Germany
-
France
-
Italy
-
Spain
-
Denmark
-
Sweden
-
Norway
-
-
Asia Pacific
-
Japan
-
China
-
India
-
Australia
-
Thailand
-
South Korea
-
-
Latin America
-
Brazil
-
Argentina
-
-
Middle East & Africa
-
South Africa
-
Saudi Arabia
-
UAE
-
Kuwait
-
-
Research Methodology
The antidiabetics market figures in this report are based on a proven research process that combines executive interviews with secondary research from proprietary databases, company filings, and recognized regulatory and institutional sources. Market size is built through value-chain sizing - reconciling supply-side and demand-side estimates - and triangulated with bottom-up and top-down approaches. Every estimate passes multiple levels of expert validation before publication, with each antidiabetics segment quantified using the revenue-capture definitions in the table below.
Segment Definition
Segment - Drug Class
Revenue capture definition
Insulin
Revenue generated from insulin products prescribed for the management of type 1 diabetes, type 2 diabetes, and other insulin dependent conditions. This segment includes rapid acting, short acting, intermediate acting, long acting, ultra long acting, premixed insulins, and insulin biosimilars. All sales associated with insulin based therapies are included exclusively within this segment.
GLP-1 Receptor Agonists
Revenue generated from glucagon like peptide 1 receptor agonists used for glycemic control in patients with type 2 diabetes. This segment includes injectable and oral GLP 1 receptor agonists prescribed as monotherapy or in combination with other antidiabetic agents. All sales associated with GLP 1 receptor agonist therapies are classified solely within this segment.
DPP-4 Inhibitors
Revenue generated from dipeptidyl peptidase 4 inhibitor therapies indicated for the treatment of type 2 diabetes. This segment includes standalone DPP 4 inhibitors and fixed dose combinations containing a DPP 4 inhibitor component. All sales associated with DPP 4 inhibitor based treatments are included exclusively within this segment.
SGLT2 Inhibitors
Revenue generated from sodium glucose cotransporter 2 inhibitor therapies prescribed for type 2 diabetes and related metabolic conditions. This segment includes standalone SGLT2 inhibitors and combination products containing an SGLT2 inhibitor as an active component. Revenue from all SGLT2 inhibitor based therapies is classified solely within this segment.
Others
Revenue generated from antidiabetic drug classes not included under insulin, GLP 1 receptor agonists, DPP 4 inhibitors, or SGLT2 inhibitors. This segment includes sulfonylureas, biguanides, thiazolidinediones, meglitinides, alpha glucosidase inhibitors, amylin analogs, and other antidiabetic therapies. All sales associated with these products are included exclusively within this segment.
Segment - Diabetes Type
Revenue capture definition
Type 1
Revenue generated from antidiabetic therapies prescribed for the treatment and management of type 1 diabetes. This segment includes insulin products and adjunct therapies specifically used to control blood glucose levels in patients with autoimmune mediated insulin deficiency. All sales associated with type 1 diabetes treatment are included exclusively within this segment.
Type 2
Revenue generated from antidiabetic therapies prescribed for the treatment and management of type 2 diabetes. This segment includes insulin, GLP 1 receptor agonists, DPP 4 inhibitors, SGLT2 inhibitors, and other glucose lowering therapies used either alone or in combination. All sales associated with type 2 diabetes indications are classified solely within this segment.
Segment - Route of Administration
Revenue capture definition
Oral
Revenue generated from antidiabetic therapies administered orally for the management of diabetes. This segment includes tablets, capsules, and oral formulations of glucose lowering drugs such as DPP 4 inhibitors, SGLT2 inhibitors, biguanides, sulfonylureas, and oral GLP 1 receptor agonists. All sales associated with orally administered antidiabetic therapies are included exclusively within this segment.
Subcutaneous
Revenue generated from antidiabetic therapies administered through subcutaneous injection. This segment includes insulin products, GLP 1 receptor agonists, dual agonists, and other injectable diabetes therapies intended for self administration or healthcare provider administration. All sales associated with subcutaneous antidiabetic therapies are classified solely within this segment.
Intravenous
Revenue generated from antidiabetic therapies administered through the intravenous route, primarily within hospital and acute care environments. This segment includes intravenous insulin formulations and other diabetes related therapies delivered directly into the bloodstream for intensive glucose management. All sales associated with intravenous administration are included exclusively within this segment.
Segment - Distribution Channel
Revenue capture definition
Hospital Pharmacy
Revenue generated from antidiabetic drugs dispensed through hospital pharmacies for inpatient and outpatient diabetes management. This segment includes products supplied directly by hospitals, specialty diabetes clinics, and affiliated healthcare institutions. All sales through hospital based dispensing channels are included exclusively within this segment.
Retail Pharmacy
Revenue generated from antidiabetic drugs dispensed through community pharmacies, chain pharmacies, independent pharmacies, and drug stores. This segment includes prescription refills and over the counter diabetes related medications distributed through physical retail pharmacy networks. All sales through retail pharmacy channels are classified solely within this segment.
Online Pharmacy
Revenue generated from antidiabetic drugs distributed through licensed digital pharmacy platforms and e commerce based pharmacy providers. This segment includes prescription fulfillment, home delivery services, and online medication ordering for diabetes therapies. All sales through online pharmacy channels are included exclusively within this segment.
Estimation Model
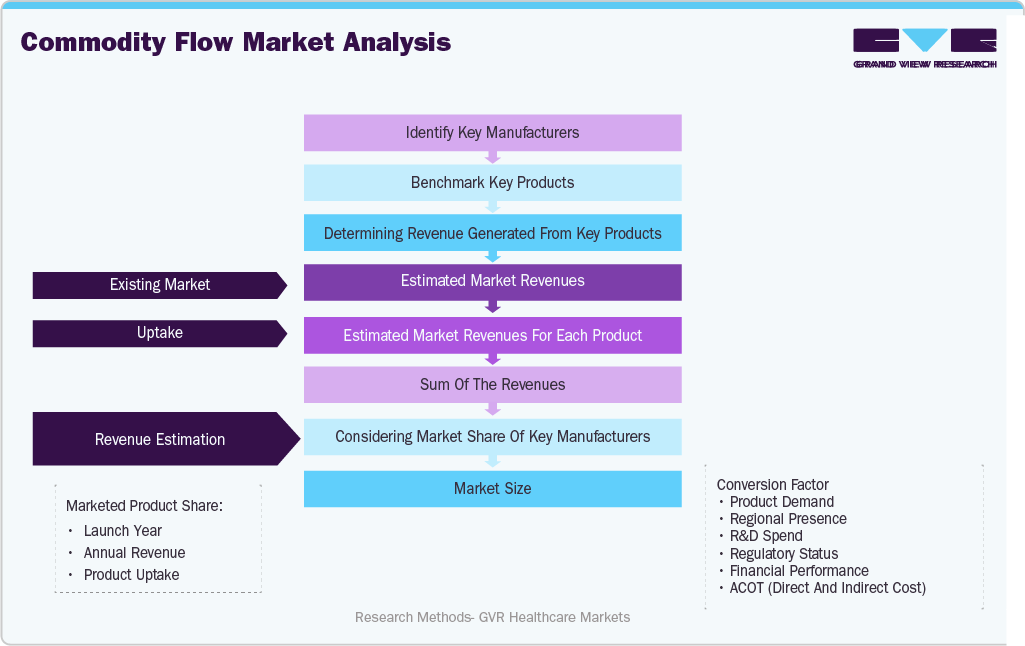 To learn more about this report, Download Free Sample Report
The antidiabetics market was estimated using a commodity flow and revenue based market analysis approach. The methodology began with the identification of key manufacturers and commercially available antidiabetic therapies across major drug classes, including insulin, GLP 1 receptor agonists, SGLT2 inhibitors, DPP 4 inhibitors, and other glucose lowering agents. Key products were benchmarked based on approved indications, launch year, geographic availability, and treatment utilization patterns. Product level revenues were assessed through company annual reports, investor presentations, regulatory filings, prescription databases, and healthcare industry publications. Existing market demand was evaluated by analyzing diabetes prevalence, treatment rates, prescribing trends, and adoption patterns across major countries. The contribution of established therapies and recently introduced products was incorporated to estimate product specific revenue generation within the overall market.
The overall market size was derived by aggregating revenue estimates generated from individual antidiabetic products across all regions and therapeutic categories. Market share analysis of leading manufacturers was conducted to validate revenue allocation and assess competitive positioning. Additional factors such as product demand, regional presence, pricing trends, reimbursement coverage, research and development investments, regulatory approvals, and healthcare expenditure on diabetes management were incorporated into the analysis. The assessment also considered the growing utilization of GLP 1 receptor agonists, SGLT2 inhibitors, biosimilar insulin products, and emerging diabetes therapies. Final market estimates were validated through data triangulation using company reported sales, product level performance, epidemiology data, prescription volume trends, and expert industry insights to ensure accurate calculation of the Antidiabetics Market size and future growth projections.
Delivered Customizations
This report has been delivered with the following In-depth customizations
CUB/THER Subject
Customization Delivered
Value Adds
Advanced Therapy Adoption Analysis Assessment of adoption trends across insulin, GLP1 receptor agonists, SGLT2 inhibitors, DPP4 inhibitors, and emerging diabetes therapies, including prescribing patterns, treatment sequencing, and utilization across major healthcare markets.
Helps identify high-growth therapeutic segments, treatment transition trends, and expansion opportunities across the antidiabetics market.
Treatment Pathway and Patient Journey Assessment Analysis of patient progression from diagnosis through lifestyle intervention, oral antidiabetic therapy, injectable therapy, and advanced diabetes management stages, including treatment switching patterns and factors influencing therapy selection.
Supports identification of unmet needs, patient retention opportunities, adherence drivers, and market expansion opportunities across different stages of diabetes management.
Diagnostic and Early Detection Landscape Evaluation Evaluation of diabetes screening programs, diagnostic testing trends, continuous glucose monitoring adoption, referral pathways, and early disease identification initiatives influencing diabetes diagnosis and treatment initiation.
Tracks opportunities related to earlier patient identification, improved treatment penetration, expansion of the diagnosed patient population, and preventive care initiatives.
Pipeline and Innovation Landscape Assessment Assessment of emerging antidiabetic therapies, novel mechanisms of action, oral peptide development, once-weekly insulin programs, combination therapies, biosimilar competition, and advancements in metabolic disease research relevant to diabetes treatment.
Identifies future growth opportunities, competitive differentiation factors, innovation-driven segments, and pipeline developments expected to influence market growth.
Competitive Benchmarking and Portfolio Analysis Comparative assessment of approved antidiabetic therapies, clinical evidence, market positioning, pricing strategies, reimbursement access, lifecycle management initiatives, and strategic developments of leading market participants.
Supports competitive intelligence, partnership evaluation, portfolio optimization, product repositioning, and strategic decision-making within the antidiabetics market.
Frequently Asked Questions About This Report
The antidiabetics market is driven by rising diabetes prevalence, advancements in GLP-1 receptor agonists and SGLT2 inhibitors, and increasing adoption of combination therapies.
Some key players operating in the antidiabetics market include AstraZeneca plc, Bayer AG, Takeda Pharmaceutical Company Limited, Eli Lilly and Company, Boehringer Ingelheim, Bristol-Myers Squibb, Pfizer, Inc., Johnson & Johnson Services Inc., Merck & Co. Inc , Novartis AG
Based on diabetes type, the type 2 segment led the market with the largest revenue share of 79.4% in 2025.
Based on route of administration, the intravenous segment led the market with the largest revenue share of 41.8% in 2025.
North America dominated the antidiabetics market with the largest revenue share of 41.5% in 2025.
The global antidiabetics market is expected to grow at a compound annual growth rate of 10.4% from 2026 to 2033 to reach USD 235.4 billion by 2033.
Based on drug class, the glp-1 receptor agonists segment led the market with the largest revenue share of 46.8 % in 2025.
Based on distribution channel, the hospital pharmacy segment led the market with the largest revenue share of 47.2% in 2025.
The global antidiabetics market size was estimated at USD 104.0 billion in 2025 and is projected to grow to USD 117.5 billion in 2026.
About the Author(s)
Pharmaceuticals Research Team
Healthcare · PharmaceuticalsThis report was authored by the pharmaceuticals research team at Grand View Research - comprising two research analysts, one senior research analyst, and one industry expert - with specialized expertise in the pharmaceuticals segment of the healthcare industry. All findings are based on proprietary healthcare databases, executive interviews, and regulatory analysis, subject to internal peer review prior to publication.
Last Updated:
Speak to Analyst

Customize this report to your needs - add regions, segments, or data points, with 20% free customization.
Or view our licence options:


ISO 9001:2015 & 27001:2022 Certified
We are GDPR and CCPA compliant! Your transaction & personal information is safe and secure. For more details, please read our privacy policy.


