
- Home
- »
- Network Security
- »
-
Application Delivery Controller Market Size Report, 2033GVR Report cover

Application Delivery Controller Market (2026 - 2033)
Size, Share & Trends Analysis Report By Deployment (Hardware-based ADCs, Virtual ADCs), By Enterprise Size (Small & Medium Enterprise, Large Enterprise), By End-use, By Region, And Segment Forecasts
Market Size, 2025
$4.6BMarket Estimate, 2026
$5.0BMarket Forecast, 2033
$14.7BCAGR, 2026–2033
16.8%Application Delivery Controller Market Summary
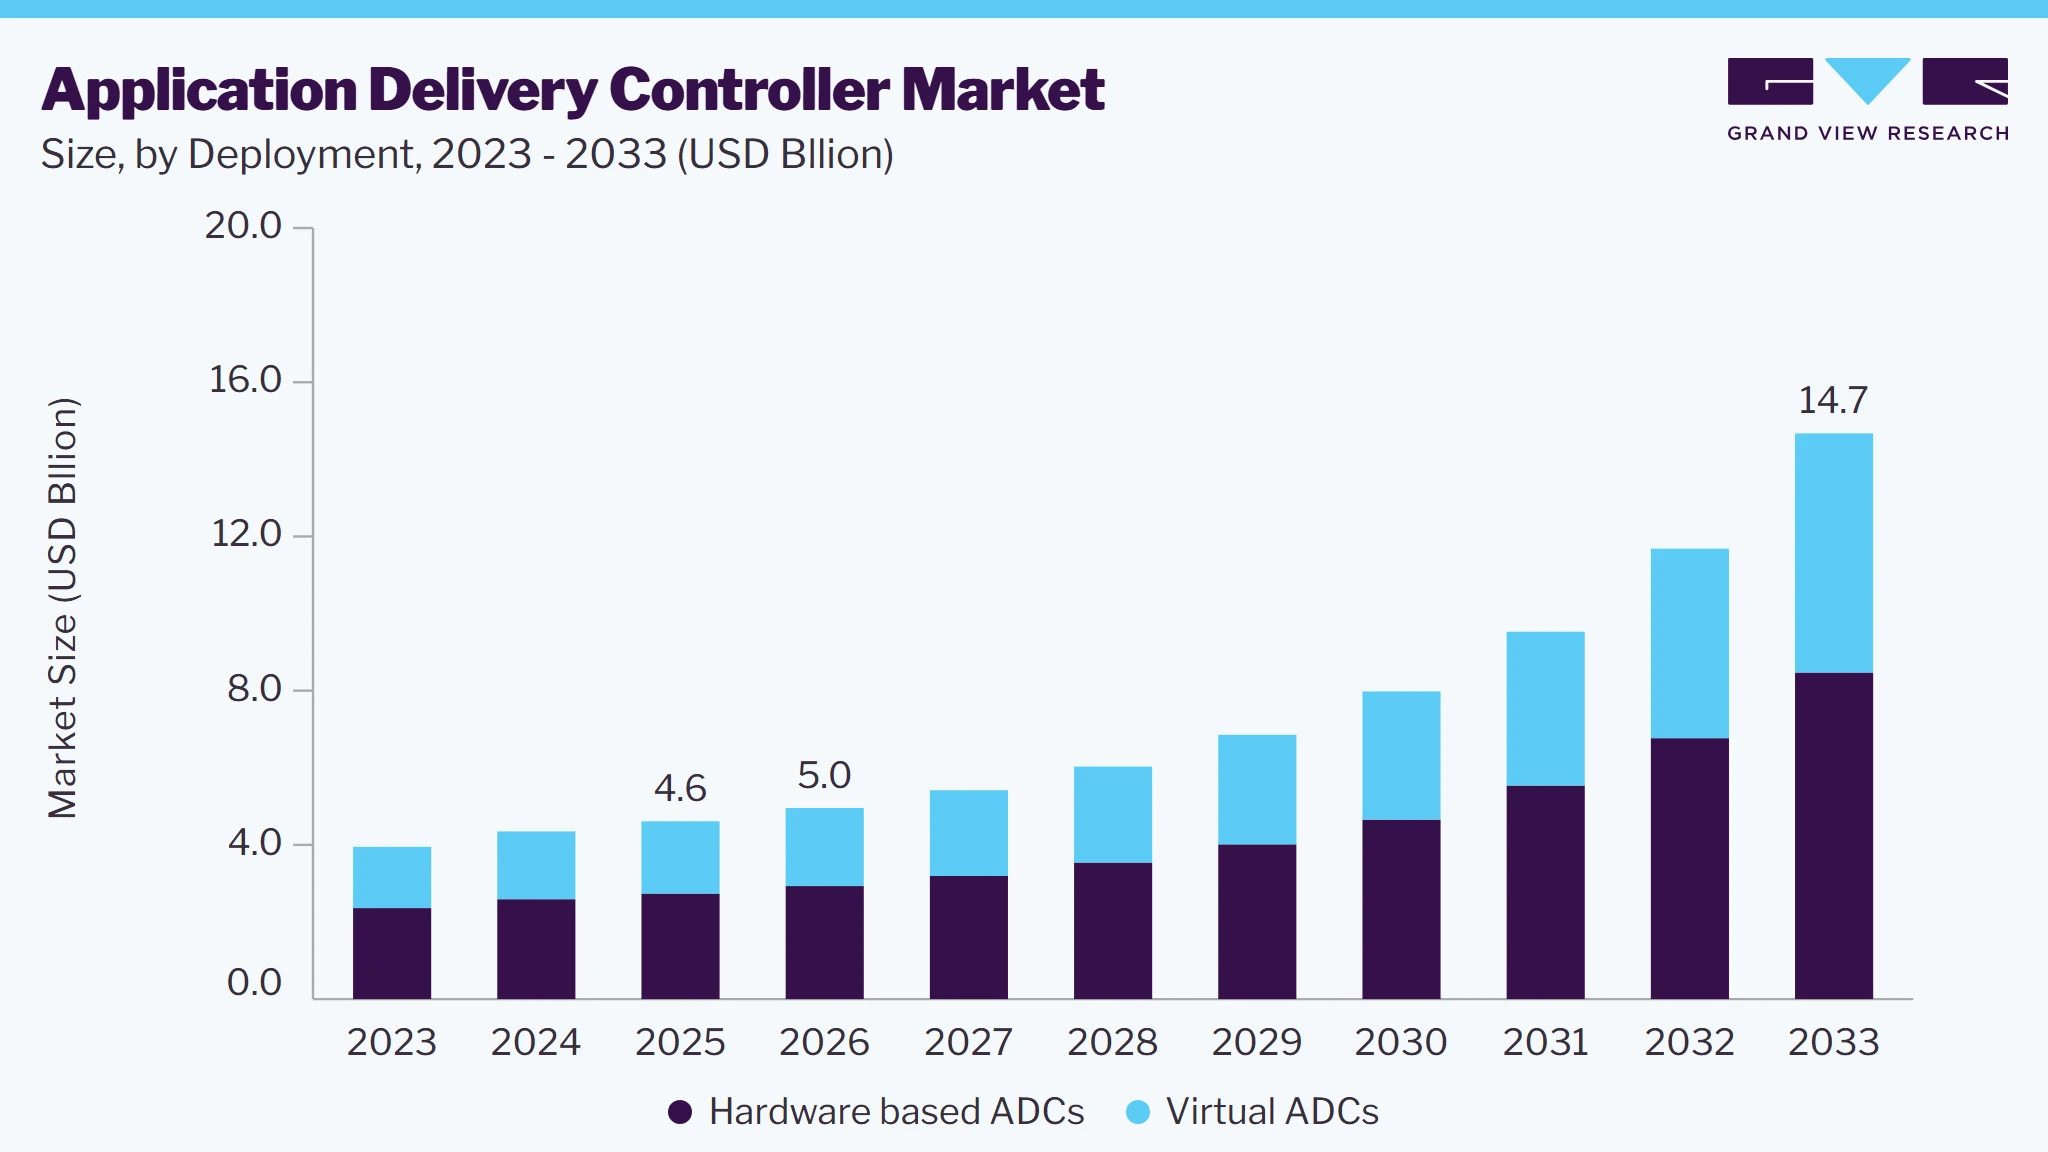
The global application delivery controller market size was valued at USD 4.6 billion in 2025 and is projected to grow from USD 5.0 billion in 2026 to USD 14.7 billion in 2033 at a CAGR of 16.8% from 2026 to 2033. North America market dominated, with a revenue share of 34.7% in 2025. Application delivery controllers (ADC) manage and optimize the delivery of applications across complex environments, ensuring high availability, security, and performance.
 Source: Grand View Research, IR Documents, Primary Interviews, Paid DatabasesTo learn more about this report,
 Download Free Sample Report
Key Market Trends & Insights
- By deployment mode: Hardware based ADCs segment dominated the market, with a revenue share of 59.4% in 2025.
- By enterprise size: Large enterprise segment held the largest market share of 56.8% in 2025.
- By end use: BFSI segment held the largest revenue share of 25.0% in 2025.
Regional Highlights
- Largest regional market: North America (34.7% revenue share, 2025)
- Fastest-growing regional market: Asia Pacific (highest CAGR, 2026-2033)
- By country: The U.S. held the largest market share in 2025.
Market Size & Forecast
- Market size in 2025: USD 4.6 Billion
- Estimated market size in 2026: USD 5.0 Billion
- Projected market size by 2033: USD 14.7 Billion
- CAGR (2026-2033): 16.8%
Three ways to get this report
Buy it, customize it, or ask a question.Ask an Analyst
Analyst response in 1 business day
- AccessReport author, directly
- Reply timeWithin 1 working day
- No sales callDirect answer only
- FormatEmail reply
- CostFree, no cost
Get the Full Report
What the study covers
- FormatsPDF · Excel · Dashboard
- Timeline2026–2033 annual, 2025 base
- Coverage20+ countries, 5 regions
- Companies10+ key players profiled
Customize the Report
20% free customization
- IncludeCountries, segments, points
- TailorTo your product definition
- ExtendDeeper competitor detail
- OrA fully bespoke study
- Turnaround5–10 working days
North American enterprises are increasingly adopting hybrid and multi-cloud strategies to improve scalability, resilience, and operational flexibility. As applications are distributed across private data centers, public clouds, and edge environments, organizations require advanced ADCs to provide intelligent load balancing, application availability, traffic optimization, and centralized policy management. The growing use of cloud-native applications and Kubernetes further accelerates demand for software-based and cloud-native ADC solutions.ADCs equipped with security features like DDoS protection, web application firewalls, and intrusion prevention systems help organizations safeguard their applications from potential attacks. The growing demand for mobile applications and the impending rollout of 5G networks are further fueling the market, as ADCs can optimize performance and reduce latency for mobile users. Additionally, the rise of IoT devices and edge computing necessitates efficient traffic management, which ADCs can provide, enabling real-time data processing and analytics. Collectively, these factors position ADCs as essential components in modern IT infrastructures, driving their adoption and market growth.
 To learn more about this report, Download Free Sample Report
As the number of connected devices continues to rise with the expansion of the IoT ecosystem, ADCs will play a critical role in managing the influx of data and ensuring seamless application delivery. The integration of edge computing will also drive the demand for ADCs that can operate efficiently in distributed environments, enabling low-latency application access for end-users. Overall, the ADC market is set to witness significant advancements and growth, driven by these trends and the ongoing need for secure, high-performance application delivery in an increasingly digital world.
As organizations continue to embrace digital transformation initiatives, the demand for efficient and secure application delivery solutions will only intensify. The ongoing evolution of cloud technologies, coupled with the increasing need for scalability and flexibility, will drive the adoption of cloud-native ADCs designed to cater to dynamic workloads and multi-cloud environments. Furthermore, the growing emphasis on application performance and user experience will compel businesses to invest in advanced ADC solutions that leverage artificial intelligence (AI) and machine learning (ML) for predictive analytics and automation. These technologies will enhance the ability of ADCs to adapt to changing traffic patterns and optimize resource allocation in real time.
Market Dynamics
The application delivery controller market is experiencing strong growth as organizations increasingly prioritize application performance, cybersecurity, and seamless digital user experiences in response to accelerating cloud adoption, AI-driven workloads, and evolving hybrid IT environments. The widespread deployment of hybrid and multi-cloud infrastructures is driving demand for ADC solutions that provide intelligent load balancing, traffic management, SSL/TLS offloading, application acceleration, and high availability across distributed applications and data centers. Growing investments in digital transformation, cloud-native application development, and edge computing are accelerating the adoption of software-based and cloud-native ADCs that integrate seamlessly with Kubernetes, containers, microservices, and DevOps workflows. The rapid advancement of artificial intelligence (AI), machine learning (ML), and automation is enabling next-generation ADCs to deliver predictive traffic optimization, automated scaling, anomaly detection, and AI-driven application performance management. Organizations are increasingly leveraging ADC platforms integrated with Web Application Firewalls (WAF), API security, bot management, DDoS mitigation, and Zero Trust security frameworks to protect critical applications from increasingly sophisticated cyber threats. The growing emphasis on API-first architectures, digital banking, e-commerce, video streaming, SaaS applications, and mission-critical enterprise workloads is further driving demand for intelligent application delivery solutions that ensure low latency, scalability, resilience, and uninterrupted service availability. In addition, rising investments in hyperscale data centers, 5G infrastructure, edge computing, and secure application delivery across industries such as BFSI, IT & telecommunications, healthcare, government, retail, manufacturing, and media & entertainment are expanding the adoption of advanced ADC platforms worldwide.
The growing adoption of hybrid and multi-cloud environments is a major driver of the application delivery controller market. Organizations are deploying business-critical applications across private data centers, public clouds, and edge environments, creating a need for intelligent traffic management, load balancing, and application optimization. ADCs enable seamless application availability, automated workload distribution, SSL/TLS offloading, and application acceleration across distributed infrastructures. As enterprises accelerate cloud migration, containerization, Kubernetes adoption, and microservices architectures, investments in software-based and cloud-native ADCs continue to increase. These solutions ensure consistent application performance, scalability, and resilience while simplifying application delivery across increasingly complex IT ecosystems.
The complexity of managing ADC deployments across hybrid and multi-cloud environments remains a significant restraint for the application delivery controller market. Organizations often operate diverse infrastructures comprising on-premises data centers, multiple public cloud providers, containers, and legacy applications, making integration and policy management challenging. Additionally, enterprise-grade ADC solutions require substantial investments in hardware, software licensing, implementation, and skilled network administrators. Migration from traditional hardware appliances to cloud-native ADC platforms can further increase deployment complexity and operational costs, particularly for small and medium-sized enterprises (SMEs) with limited IT budgets and technical expertise.
The rapid expansion of AI-powered applications, edge computing, and API-driven digital services presents significant opportunities for the application delivery controller market. Organizations are increasingly investing in next-generation ADCs that integrate artificial intelligence, machine learning, and automation to optimize traffic routing, predict application demand, automate scaling, and improve application resilience. Simultaneously, growing adoption of Web Application Firewalls (WAF), API security, bot mitigation, DDoS protection, and Zero Trust architectures is driving demand for security-integrated ADC platforms. As enterprises expand edge deployments, 5G networks, hyperscale data centers, and latency-sensitive applications, the demand for intelligent, cloud-native, and AI-enabled ADC solutions is expected to grow substantially.
Analyst Perspective
The application delivery controller market is becoming a strategic component of modern digital infrastructure as organizations increasingly prioritize application availability, cybersecurity, low-latency performance, and seamless user experiences across hybrid and multi-cloud environments. The rapid adoption of cloud-native applications, microservices, Kubernetes, edge computing, and AI-driven workloads is accelerating demand for intelligent ADC platforms that deliver advanced load balancing, application acceleration, traffic management, SSL/TLS offloading, and integrated security capabilities. Organizations are increasingly deploying ADCs alongside Web Application Firewalls (WAF), API security, DDoS protection, Zero Trust architectures, and cloud security platforms to ensure resilient and secure application delivery across distributed IT ecosystems. The primary competitive advantage will belong to vendors that can deliver intelligent, AI-driven, and highly integrated application delivery platforms by combining predictive traffic optimization, automated workload scaling, real-time application analytics, API protection, bot mitigation, and cloud-native orchestration within a unified platform. As enterprises continue to modernize legacy applications, expand edge deployments, and invest in hyperscale data centers, vendors capable of providing scalable, software-defined, cloud-native, and security-centric ADC solutions with seamless integration across on-premises, cloud, and edge environments will be best positioned to capture long-term market opportunities.
Deployment Insights
Based on deployment, the hardware based ADCs segment led the market with the largest revenue share of 59.4% in 2025 and is expected to grow at the significant CAGR over the forecast period. Hardware-based ADCs are engineered to deliver superior performance compared to software-based solutions. By leveraging dedicated hardware components, such as Application-Specific Integrated Circuits (ASICs), these devices optimize data processing and traffic management. This specialized architecture enables faster packet processing, resulting in lower latency and higher throughput. As a result, hardware-based ADCs are particularly suited for organizations that experience high traffic loads and require reliable performance for mission-critical applications. With the increasing reliance on real-time applications-such as video conferencing, online transactions, and cloud services-businesses need solutions that can handle intensive workloads without compromising efficiency. Consequently, the demand for high-performance hardware-based ADCs is on the rise, as organizations seek to ensure seamless application delivery, maintain high user satisfaction, and support the growing complexities of their IT environments.
Virtual ADCs are expected to grow steadily over the forecast period. The rapid migration of businesses to cloud environments has significantly boosted the adoption of Virtual Application Delivery Controllers (ADCs). Virtual ADCs seamlessly integrate with cloud-based infrastructures, allowing organizations to deploy them quickly and efficiently without the constraints of physical hardware. This capability enables businesses to scale their application delivery resources dynamically, adapting to fluctuating workloads and ensuring optimal performance. As organizations increasingly embrace hybrid and multi-cloud architectures, the need for effective application delivery solutions across diverse platforms becomes critical. Virtual ADCs provide the flexibility required to manage applications spread across various cloud environments while maintaining consistent performance and security. Their ability to optimize traffic, accelerate application delivery, and enhance user experience further drives their adoption. Consequently, virtual ADCs have emerged as essential components in modern IT strategies, helping organizations meet the demands of a rapidly evolving digital landscape while maximizing the benefits of cloud services.
Enterprise Size Insights
Based on enterprise size, the large enterprise segment led the market with the largest revenue share of 56.8% in 2025. Large enterprises often manage intricate IT environments that encompass a combination of on-premises, cloud, and hybrid architectures. This complexity creates significant challenges in application delivery, traffic management, and security, necessitating advanced solutions that can adapt to varied infrastructures. ADCs are specifically designed to navigate these multifaceted setups, providing centralized control over application traffic and ensuring seamless integration across different platforms. ADCs enhance operational efficiency by simplifying the management of diverse applications, allowing organizations to monitor and optimize performance from a single point of control. Their ability to balance traffic, ensure high availability, and implement security measures across multiple environments is crucial for large enterprises. As these organizations strive to maintain performance and reliability amidst growing complexities, the demand for ADCs continues to rise, solidifying their role as essential tools for effective application delivery in modern IT landscapes.
The SME segment is expected to grow steadily over the forecast period. As small and medium enterprises (SMEs) seek to improve operational efficiency and enhance customer engagement, many are embarking on digital transformation initiatives. This transition often involves integrating cloud services, which enable SMEs to access resources and applications more flexibly and cost-effectively. ADCs are instrumental in this digital shift, as they ensure reliable access to applications while optimizing performance across various platforms. By managing traffic efficiently, ADCs minimize latency and downtime, significantly improving the user experience for both employees and customers. As SMEs increasingly recognize the importance of digital strategies to stay competitive, the demand for ADC solutions has grown. These tools not only facilitate seamless application delivery but also support the rapid scaling and adaptability needed in today’s dynamic business environment. Consequently, ADCs are becoming essential for SMEs as they navigate their digital transformation journeys and strive to meet evolving market demands.
End Use Insights
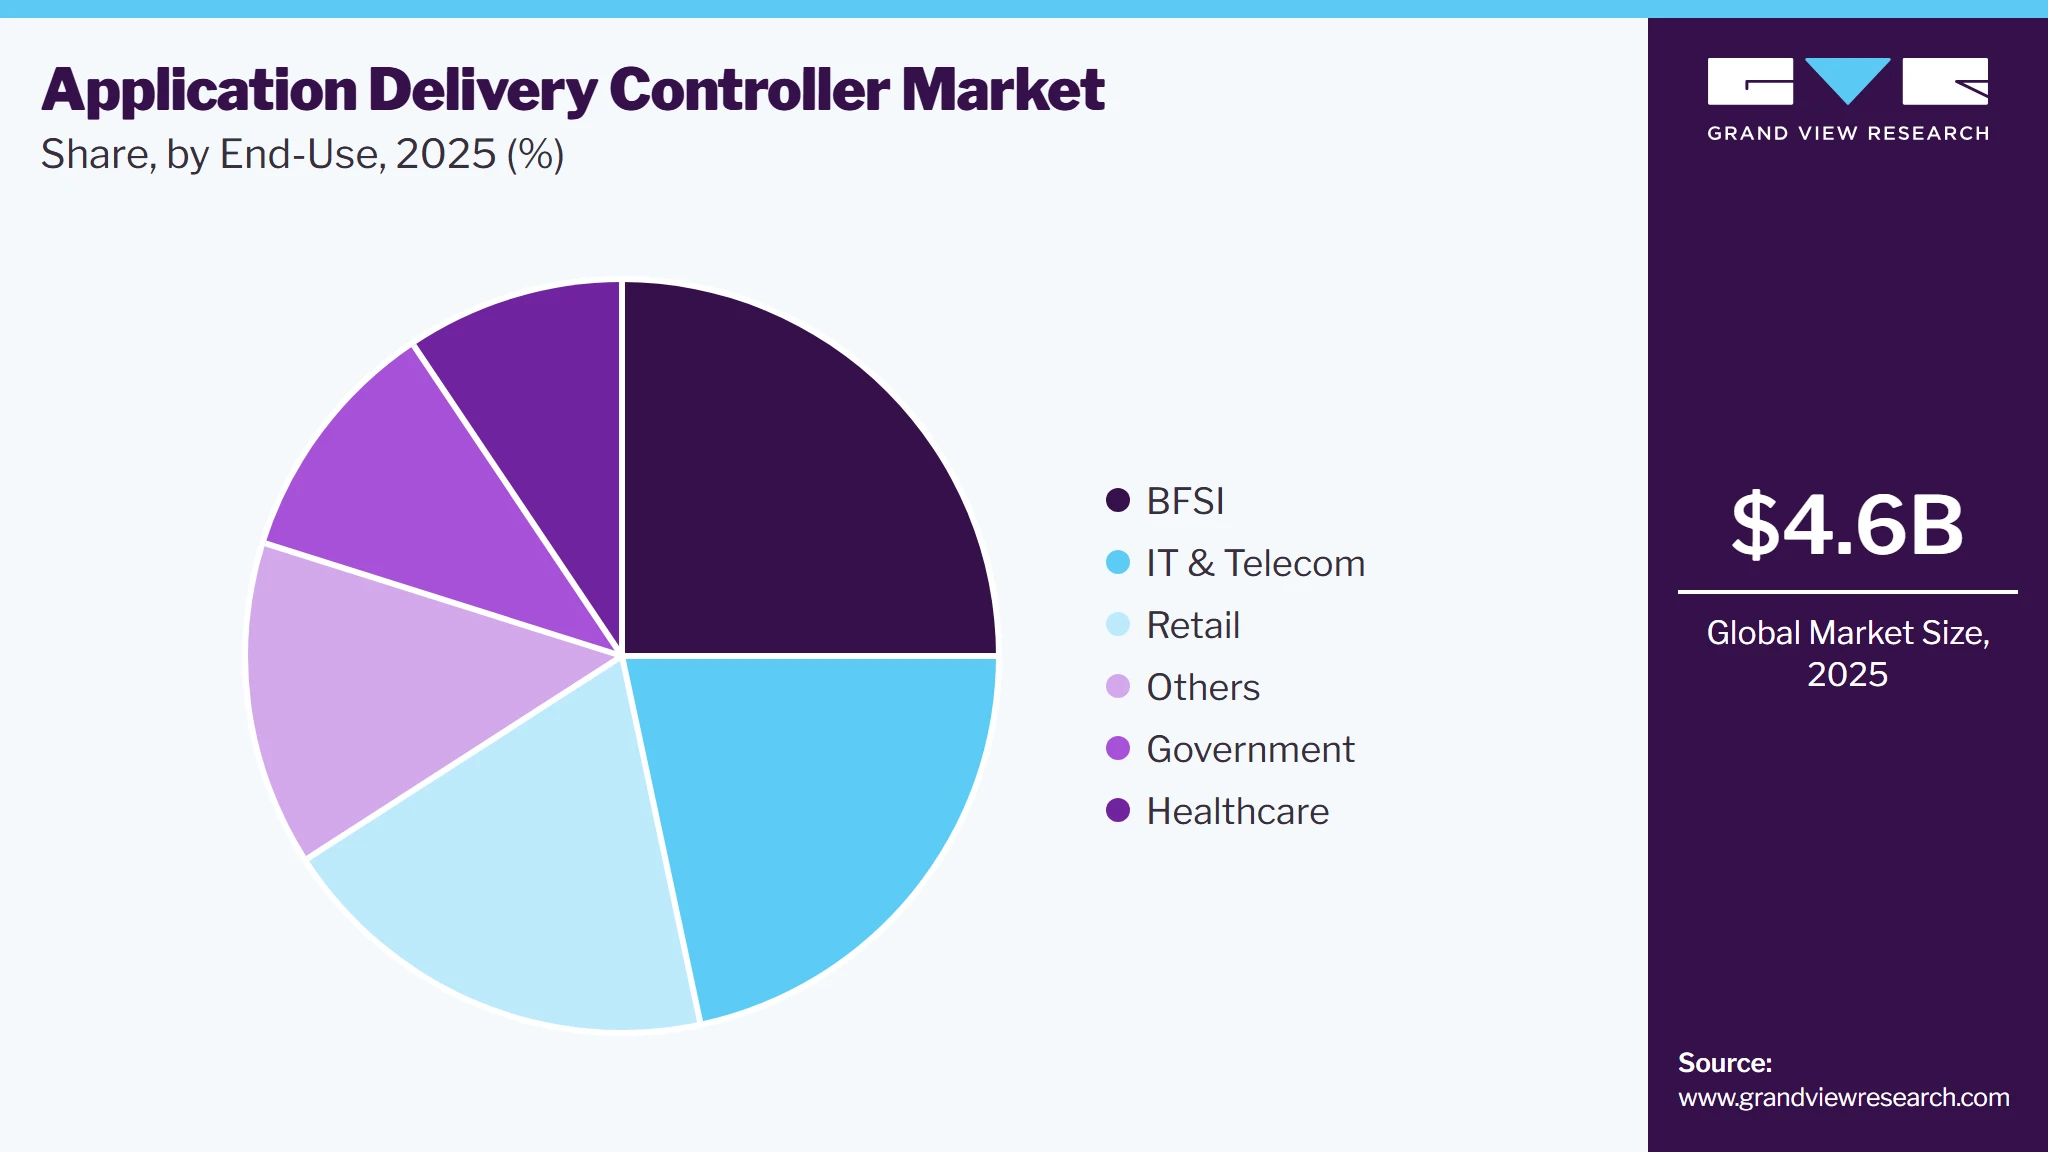
Based on end-use, the BFSI segment led the market with the largest revenue share of 25.0% in 2025. The BFSI sector is experiencing significant growth, leading to an increase in transaction volumes that financial institutions must manage effectively. This surge in activity necessitates scalable solutions capable of adjusting to fluctuating demands. ADCs play a crucial role in this context, as they provide the flexibility to scale resources up or down in real time. During peak traffic periods, such as month-end closings or promotional campaigns, ADCs ensure that applications can handle the increased load without sacrificing performance. By efficiently distributing traffic and optimizing resource utilization, ADCs maintain high availability and responsiveness, which is crucial for customer satisfaction in a competitive financial landscape. As organizations strive to accommodate growth and meet rising customer expectations, the scalability offered by ADCs becomes essential. This capability not only supports the current operational needs but also positions financial institutions for future expansion and digital transformation initiatives.
 To learn more about this report, Download Free Sample Report
The retail segment is expected to grow steadily over the forecast period. The explosive growth of e-commerce has fundamentally reshaped the retail landscape, driving a significant increase in online transactions and customer interactions. Retailers are now prioritizing digital platforms to establish a strong online presence, catering to the rising demand for convenient and accessible shopping experiences. Application Delivery Controllers (ADCs) play a pivotal role in this transformation by optimizing application performance, which is crucial for maintaining fast load times and reliable access to websites. As consumers expect quick and seamless interactions, ADCs help mitigate latency issues, manage traffic effectively, and ensure high availability, thereby enhancing the overall user experience. This optimization is vital for customer retention, as slow or unreliable websites can lead to lost sales and diminished brand loyalty. By investing in ADC solutions, retailers can better meet customer expectations, maximize engagement, and ultimately thrive in an increasingly competitive e-commerce environment.
Regional Insights
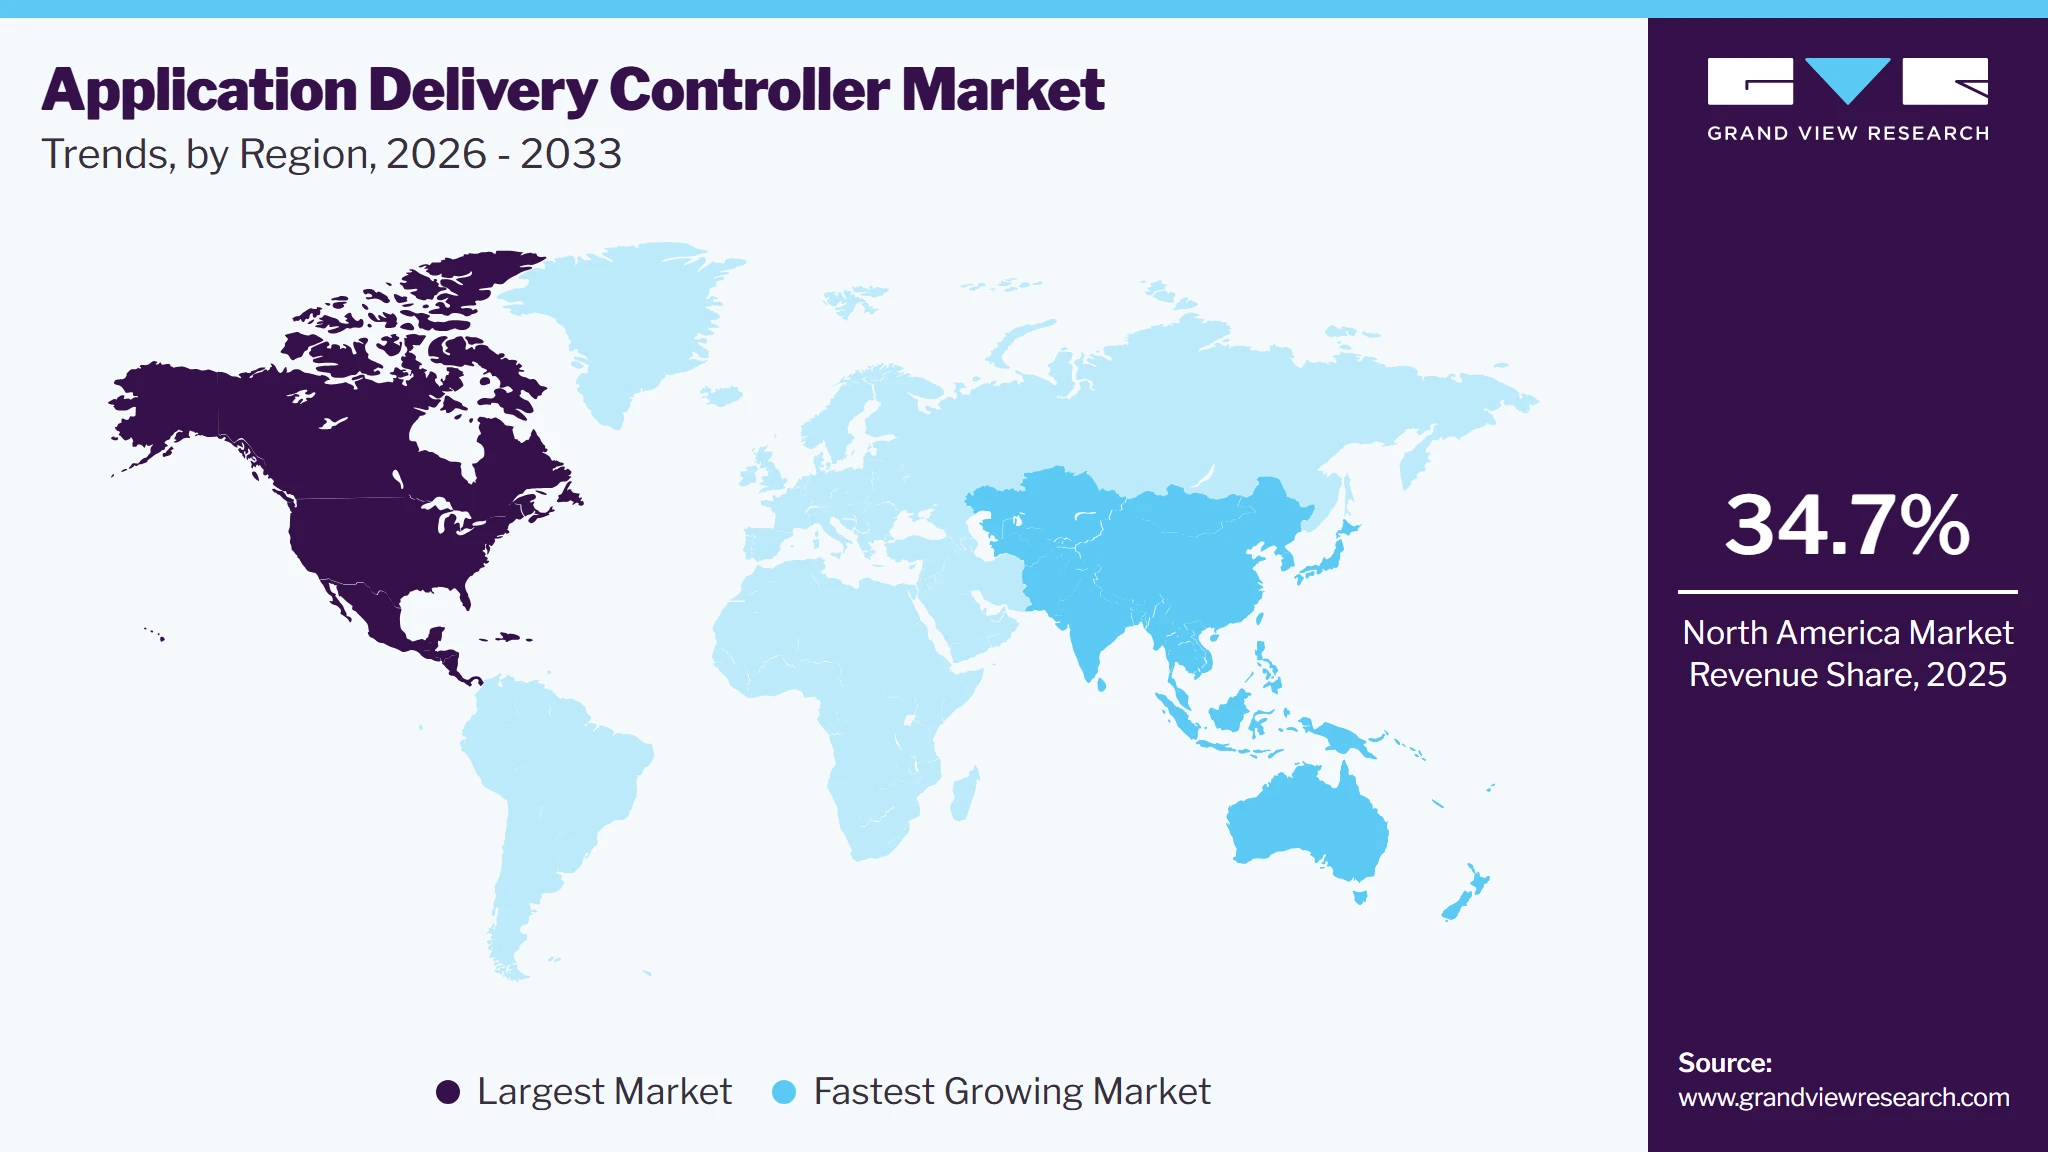
North America dominated the application delivery controller market with the largest revenue share of 34.7% in 2025. North American enterprises, especially in the U.S. and Canada, are leading the way in cloud adoption and digital transformation. As businesses increasingly migrate to hybrid and multi-cloud environments, the need for Application Delivery Controllers (ADCs) has grown substantially. ADCs are essential in ensuring seamless application delivery, providing scalability, and securing the flow of data across various infrastructures. In cloud environments, ADCs play a critical role in optimizing the performance of cloud-based applications, balancing traffic loads, and reducing latency. As organizations rely more on cloud services to enhance operational efficiency, the demand for ADC solutions that can integrate effectively across multiple platforms continues to rise. This trend supports North America's position as a key growth market for ADC providers, as companies seek solutions that enable them to handle dynamic workloads while maintaining high levels of security and performance during their digital transformation efforts.
 To learn more about this report, Download Free Sample Report
U.S. Application Delivery Controller Market Trends
The application delivery controller market in the U.S. held the largest share in the North America region in 2025. The U.S. has experienced significant growth in e-commerce and digital services, particularly in sectors like retail and financial services. As online platforms face increasing traffic volumes, the need for efficient application performance becomes critical. Application Delivery Controllers (ADCs) play a key role by optimizing performance, minimizing latency, and ensuring the scalability needed to handle peak traffic periods. During high-demand events, such as sales or market fluctuations, ADCs help maintain reliable access and smooth user experiences. This growing dependence on digital platforms has fueled the demand for ADC solutions, driving market growth in the region.
Asia Pacific Application Delivery Controller Market Trends
The application delivery controller market in Asia Pacific is expected to grow significantly at a CAGR of 14.2% from 2025 to 2030. In the Asia Pacific region, small and medium-sized enterprises (SMEs) are rapidly embracing digital technologies and cloud services to enhance their operations. As these businesses expand their digital presence, the demand for scalable and cost-effective Application Delivery Controllers (ADCs) is rising. ADCs help SMEs ensure reliable application performance, improve user experience, and manage traffic efficiently, even as their workloads grow. This shift towards digitalization, supported by the flexibility and affordability of virtual ADCs, is driving market growth in the region, enabling SMEs to compete effectively in the digital economy while maintaining high performance and security standards.
Japan application delivery controller market is expected to grow rapidly in the coming years. Japan’s focus on advanced technologies like AI and IoT is increasing the demand for Application Delivery Controllers (ADCs). These technologies require the efficient management of complex application environments, and ADCs help ensure optimal performance, scalability, and seamless integration across multiple platforms.
The application delivery controller market in China held a substantial market share in 2024. China’s accelerated digital transformation, particularly in key sectors like manufacturing, finance, and healthcare, is boosting the demand for Application Delivery Controllers (ADCs). These sectors rely on ADCs to optimize application performance, streamline operations, and ensure reliable, seamless delivery of services in increasingly digitalized and complex environments.
Europe Application Delivery Controller Market Trends
The application delivery controller market in Europe is growing as the rising cybersecurity threats in Europe are compelling organizations to invest in Application Delivery Controllers (ADCs) that enhance security features and safeguard sensitive data. By integrating advanced threat protection, ADCs help mitigate risks, ensuring secure application performance and compliance with regulatory standards in a complex digital landscape.
The UK application delivery controller market is expected to grow rapidly in the coming years as organizations increasingly adopt cloud services the demand for Application Delivery Controllers (ADCs) grows to effectively manage hybrid and multi-cloud environments. ADCs facilitate seamless integration and communication between applications, ensuring optimal performance and reliability across diverse cloud platforms.
The application delivery controller market in Germany is expected to hold a significant market share in the coming years. Germany's strong manufacturing and IT sectors are pivotal in increasing the demand for Application Delivery Controllers (ADCs). These industries require optimized application delivery and performance to enhance operational efficiency, manage complex IT environments, and ensure seamless communication across diverse applications and platforms.
Key Application Delivery Controller Company Insights
Some of the key companies in the application delivery controller market include F5 Networks, A10 Networks, Citrix Systems, Barracuda Networks, and others. Organizations are focusing on increasing customer base to gain a competitive edge in the industry. Therefore, key players are taking several strategic initiatives, such as mergers and acquisitions, and partnerships with other major companies.
-
F5 Networks is known for its advanced solutions that optimize the performance, security, and scalability of applications across multi-cloud and on-premises environments. F5's ADCs are designed to enhance application availability, ensure secure traffic management, and provide flexible load balancing. With the rise of cloud computing, F5's innovations in ADC technology, including integration with security features like Web Application Firewalls (WAF), make it a critical component for businesses undergoing digital transformation.
-
Citrix Systems is a significant player in the Application Delivery Controller (ADC) market. Citrix's ADCs are designed to enhance the performance, security, and scalability of applications across cloud and on-premises environments. NetScaler ADCs are known for their robust load balancing, application acceleration, and security features, making them a popular choice for enterprises looking to improve application delivery.
Key Application Delivery Controller Companies
The following key companies have been profiled for this study on the application delivery controller market.
-
F5 Networks
-
A10 Networks
-
Citrix Systems
-
Radware
-
Array Networks
-
Kemp Technologies
-
Fortinet, Inc.
-
Cisco Systems
-
Barracuda Networks
-
ZEVENET
Competitive Benchmarking
Category
Operating Strategies
Competitive Edge
Weakness
Established Players (F5, Citrix (NetScaler), A10 Networks, Fortinet, Radware, Progress (Kemp), Cloudflare, Akamai Technologies)
- Established vendors focus on delivering comprehensive application delivery and security platforms that combine load balancing, application acceleration, SSL/TLS offloading, Web Application Firewall (WAF), DDoS protection, API security, Global Server Load Balancing (GSLB), and traffic management. Their strategies emphasize continuous innovation in AI-driven traffic optimization, cloud-native ADCs, Kubernetes ingress solutions, Zero Trust security, strategic acquisitions, and partnerships with hyperscale cloud providers, telecom operators, cybersecurity vendors, and system integrators.
- These companies benefit from extensive enterprise customer bases, strong global channel networks, proven deployment experience, and comprehensive application security portfolios. Their integrated platforms provide end-to-end application delivery, security, and performance management across on-premises, hybrid, multi-cloud, and edge environments. Significant R&D investments, mature support ecosystems, and strong relationships with cloud providers enable them to serve large enterprises while maintaining high customer retention and continuous product innovation.
- Established vendors face increasing pressure to modernize legacy hardware-centric portfolios for cloud-native environments while balancing innovation with existing customer requirements. High product development costs, complex enterprise deployments, premium pricing, migration challenges from legacy infrastructure, and intense competition from cloud-native and hyperscaler-native load balancing services can impact growth, particularly among SMEs and cloud-first organizations.
Emerging Players (HAProxy Technologies, Array Networks, NGINX, Avi Networks (VMware), Edgenexus, Loadbalancer.org)
- Emerging vendors primarily focus on software-based, virtual, and cloud-native ADC solutions optimized for Kubernetes, containers, microservices, DevOps, API management, and edge computing. Their strategies emphasize lightweight architectures, open-source technologies, automation, Infrastructure-as-Code (IaC), AI-assisted traffic management, flexible licensing, SaaS delivery models, and seamless integration with CI/CD pipelines and cloud platforms.
- Emerging companies offer agile, scalable, and cost-effective ADC solutions with faster deployment, simplified management, and strong compatibility with modern application architectures. Their focus on automation, API-driven configuration, cloud-native deployments, and DevSecOps integration enables organizations to rapidly deploy and scale applications while reducing infrastructure complexity and operational costs. Their flexible subscription models and continuous innovation make them attractive for digital-native businesses and SMEs.
- Emerging vendors generally have limited global market presence, smaller sales and support organizations, and lower brand recognition than established ADC providers. Their product portfolios may lack the breadth of advanced security, enterprise-grade support, and global service capabilities required by large multinational organizations. Dependence on partner ecosystems, increasing competition from established networking and cybersecurity vendors, and rapid technology evolution in cloud-native application delivery present challenges to long-term market expansion and profitability.
Recent Developments
-
In August 2024, Broadcom Inc. unveiled VMware Tanzu Platform 10, designed to accelerate cloud-native application delivery by enhancing governance and operational efficiency for platform engineering teams. It reduces complexity for developers and introduces Tanzu AI Solutions to enable rapid, secure deployment of GenAI-powered applications.
-
In April 2023, A10 Networks launched an integrated cloud-native Thunder Application Delivery Controller (ADC) with Fastly's next-gen Web Application Firewall (WAF), enhancing cloud defense capabilities. This solution provides improved security, performance, and scalability for businesses by combining Fastly’s advanced threat detection with A10's application delivery expertise, addressing evolving cloud threats effectively.
Application Delivery Controller Market Report Scope
Report Attribute
Details
Market size in 2025
USD 4.6 billion
Estimated market size in 2026
USD 5.0 billion
Projected market size by 2033
USD 14.7 billion
Growth rate
CAGR of 16.8% from 2026 to 2033
Base year for estimation
2025
Historical data
2021 - 2024
Forecast period
2026 - 2033
Quantitative units
Revenue in USD billion and CAGR from 2026 to 2033
Report coverage
Revenue forecast, company ranking, competitive landscape, growth factors, and trends
Segments covered
Deployment, enterprise size, end-use, region
Regional scope
North America; Europe; Asia Pacific; Latin America; MEA
Country scope
U.S.; Canada; Mexico; Germany; UK; France; China; Japan; India; South Korea; Australia; Brazil; Saudi Arabia; South Africa; UAE
Key companies profiled
A10 Networks; Array Networks; Barracuda Networks; Cisco Systems; Citrix Systems; F5 Networks; Fortinet, Inc.; Kemp Technologies; Radware; ZEVENET
Customization scope
Free report customization (equivalent up to 8 analysts' working days) with purchase. Addition or alteration to country, regional & segment scope.
Pricing and purchase options
Avail customized purchase options to meet your exact research needs. Explore purchase options
Global Application Delivery Controller Market Report Segmentation
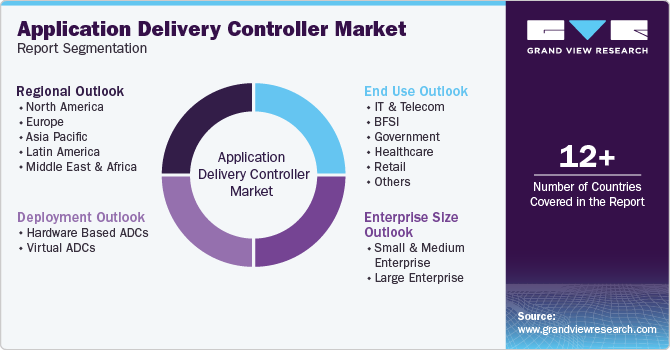
This report forecasts revenue growth at the global, regional, and country levels and provides an analysis of the latest industry trends in each of the sub-segments from 2021 to 2033. For this study, Grand View Research has segmented the global application delivery controller market report based on deployment, enterprise size, end use and region:
 To learn more about this report, Download Free Sample Report
-
Deployment Outlook (Revenue, USD Billion, 2021 - 2033)
-
Hardware based ADCs
-
Virtual ADCs
-
-
Enterprise Size Outlook (Revenue, USD Billion, 2021 - 2033)
-
Small & Medium Enterprise
-
Large Enterprise
-
-
End Use Outlook (Revenue, USD Billion, 2021 - 2033)
-
IT & Telecom
-
BFSI
-
Government
-
Healthcare
-
Retail
-
Others
-
-
Regional Outlook (Revenue, USD Billion, 2021 - 2033)
-
North America
-
U.S.
-
Canada
-
Mexico
-
-
Europe
-
UK
-
Germany
-
France
-
-
Asia Pacific
-
China
-
India
-
Japan
-
Australia
-
South Korea
-
-
Latin America
-
Brazil
-
-
Middle East & Africa (MEA)
-
UAE
-
Saudi Arabia
-
South Africa
-
-
Research Methodology
The application delivery controller market figures in this report are based on a proven research process that combines executive interviews with secondary research from proprietary databases, company filings, and recognized regulatory and institutional sources. Market size is built through value-chain sizing-reconciling supply-side and demand-side estimates-and triangulated with bottom-up and top-down approaches. Every estimate passes multiple levels of expert validation before publication, with each application delivery controller segment quantified using the revenue-capture definitions in the table below.
Segment Definition
Segment - Deployment
Revenue capture definition
Hardware-based ADCs
Hardware-based Application Delivery Controllers are dedicated physical appliances deployed within enterprise data centers or private cloud environments to manage application traffic, optimize performance, and enhance security. These solutions provide high throughput, low latency, advanced load balancing, SSL/TLS offloading, Web Application Firewall (WAF), DDoS protection, and traffic management capabilities. Hardware ADCs are widely adopted by large enterprises and organizations with mission-critical applications requiring maximum performance, reliability, and control.
Virtual ADCs
Virtual ADCs are software-based application delivery solutions deployed as virtual machines or cloud-native instances within private, public, or hybrid cloud environments. They offer the same core functionalities as hardware ADCs, including load balancing, application acceleration, traffic optimization, and security services, while providing greater scalability, flexibility, and cost efficiency. Virtual ADCs are extensively used in cloud-native architectures, Kubernetes environments, and multi-cloud deployments.
Segment - Enterprise Size
Revenue capture definition
Large Enterprise
The Large enterprises segment, with respect to the number of employees, typically comprises organizations employing more than 1,000 employees for multinational corporations.
Small & Medium-sized Enterprises (SMEs)
The SMEs segment, with respect to the number of employees, generally includes organizations employing between 10 and 999 employees.
Segment - End Use
Revenue capture definition
IT & Telecommunications
The IT & telecommunications sector utilizes ADCs to optimize application delivery, manage network traffic, support cloud services, enhance customer experience, and ensure high availability for enterprise applications, SaaS platforms, and telecommunications services. ADCs also provide security for APIs, web applications, and digital service platforms.
BFSI
Banks, financial institutions, and insurance companies deploy ADCs to ensure secure, high-performance delivery of online banking, payment processing, mobile banking, trading platforms, and financial applications. ADCs enhance application availability while integrating security features such as SSL offloading, WAF, DDoS mitigation, and API protection to safeguard sensitive financial transactions.
Government
Government agencies use ADCs to secure citizen service portals, e-governance applications, defense networks, and critical public-sector infrastructure. These solutions provide application availability, secure remote access, traffic optimization, and protection against cyber threats while supporting regulatory compliance and business continuity.
Healthcare
Healthcare organizations deploy ADCs to ensure reliable and secure access to electronic health records (EHRs), telemedicine platforms, patient portals, medical imaging systems, and healthcare applications. ADCs help maintain application performance, data security, regulatory compliance, and uninterrupted access to critical healthcare services.
Retail
Retail organizations use ADCs to optimize e-commerce platforms, point-of-sale (POS) systems, inventory management applications, and customer engagement platforms. ADCs improve website responsiveness, manage peak shopping traffic, enhance transaction security, and ensure consistent digital shopping experiences across online and omnichannel retail environments.
Others
This segment includes manufacturing, education, media & entertainment, energy & utilities, transportation & logistics, hospitality, and other industries that utilize ADCs to improve application performance, ensure business continuity, optimize traffic management, and secure enterprise applications supporting digital transformation initiatives.
Estimation Model
Layer
Question
Analysis
Application Infrastructure & Digital Transformation Demand Layer
Who can benefit from Application Delivery Controller (ADC) solutions?
Identify organizations operating business-critical applications that require high availability, low latency, secure access, and traffic optimization. Include large enterprises, SMEs, cloud service providers, telecom operators, hyperscale data center operators, financial institutions, healthcare providers, government agencies, retailers, manufacturing companies, and digital-native enterprises. Assess cloud adoption, digital transformation maturity, application modernization initiatives, AI workload growth, API adoption, and business-critical application deployments to define the total addressable market.
Cloud, Data Center & Network Modernization Layer
Where is the demand for ADCs generated?
Evaluate growth in hybrid and multi-cloud environments, enterprise data centers, hyperscale facilities, edge computing infrastructure, Kubernetes adoption, containerized applications, and microservices deployments. Assess investments in cloud migration, application modernization, software-defined networking (SDN), Zero Trust security, and digital infrastructure expansion to determine the operationally reachable market.
ADC Adoption & Deployment Layer
Who actively adopts ADC solutions?
Analyze adoption across large enterprises, SMEs, cloud providers, telecom operators, BFSI institutions, healthcare organizations, government agencies, retail & e-commerce companies, manufacturing firms, and media organizations. Evaluate demand for hardware-based ADCs, virtual ADCs, cloud-native ADCs, integrated Web Application Firewall (WAF), API security, SSL offloading, global server load balancing (GSLB), and DDoS protection to identify primary deployment opportunities and buyer segments.
Revenue Generation Layer
How is revenue generated?
Assess revenue generated through hardware ADC appliance sales, perpetual and subscription software licensing, SaaS-based ADC services, cloud marketplace deployments, implementation and integration services, consulting, managed services, technical support, maintenance contracts, software upgrades, security subscriptions (WAF, bot management, API protection), and recurring licensing and renewal revenues.
Delivered Customizations
This report has been delivered with the following In-depth customizations
Client Request
Customization Delivered
Value Adds
Application Delivery Controller Vendor Competitive Benchmarking
Assessed leading ADC vendors based on product portfolio, hardware and virtual ADC offerings, cloud-native capabilities, load balancing, application acceleration, Web Application Firewall (WAF), API security, DDoS protection, SSL/TLS offloading, Kubernetes support, deployment model, pricing strategies, partnerships, geographic presence, innovation roadmap, and market share.
Enables stakeholders to benchmark competitors, identify technology leaders, evaluate product differentiation, assess cloud-native and security capabilities, and formulate competitive product development and go-to-market strategies.
Regional Market Opportunity Assessment
Evaluated market opportunities across Asia Pacific, Latin America, and the Middle East & Africa based on cloud adoption, hyperscale data center investments, AI infrastructure expansion, regulatory environment, enterprise digitalization, and cybersecurity spending.
Enables organizations to prioritize regional expansion, identify investment hotspots, optimize market entry strategies, and align sales initiatives with regional technology adoption trends.
Technology & Innovation Benchmarking
Analyzed emerging technologies including Kubernetes Ingress Controllers, container-native ADCs, service mesh integration, edge computing, AI-powered automation, API-first architectures, and Secure Access Service Edge (SASE) compatibility across major vendors.
Helps stakeholders understand technology evolution, identify innovation gaps, evaluate future-ready platforms, and develop long-term product roadmaps aligned with evolving enterprise application delivery requirements.
Frequently Asked Questions About This Report
The global application delivery controller market is expected to grow at a CAGR of 16.8% from 2026 to 2033, reaching USD 14.7 billion by 2033.
Some key players operating in the application delivery controllers market include F5 Networks, A10 Networks, Citrix Systems, Radware, Array Networks, Kemp Technologies, Fortinet, Inc., Cisco Systems, Barracuda Networks, and ZEVENET. .
The growing demand for mobile applications and the impending rollout of 5G networks are further fueling the market, as ADCs can optimize performance and reduce latency for mobile users. Additionally, the rise of IoT devices and edge computing necessitates efficient traffic management, which ADCs can provide, enabling real-time data processing and analytics.
North America dominated with 34.7% revenue share in 2025.
Asia Pacific is the fastest-growing region over the forecast period.
The global application delivery controller market size was valued at USD 4.6 billion in 2025 and is estimated at USD 5.0 billion in 2026.
Large enterprise segment held the largest market share of 56.8% in 2025.
BFSI segment held the largest revenue share of 25.0% in 2025.
About the Author(s)
Network Security Research Team
Technology · Network SecurityThis report was authored by the network security research team at Grand View Research - comprising two research analysts, one senior research analyst, and one industry expert - with specialized expertise in the network security segment of the technology industry. All findings are based on proprietary technology databases, executive interviews, and regulatory analysis, subject to internal peer review prior to publication.
Last Updated:
Speak to Analyst

Customize this report to your needs - add regions, segments, or data points, with 20% free customization.
Or view our licence options:


ISO 9001:2015 & 27001:2022 Certified
We are GDPR and CCPA compliant! Your transaction & personal information is safe and secure. For more details, please read our privacy policy.


