
- Home
- »
- Next Generation Technologies
- »
-
Artificial Intelligence In Manufacturing Market Report, 2033GVR Report cover

Artificial Intelligence In Manufacturing Market (2026 - 2033)
Size, Share & Trends Analysis Report By Component (Hardware, Software, Services), By Technology, By Application, By End Use, By Region, And Segment Forecasts
Market Size, 2025
$7.1BMarket Estimate, 2026
$9.7BMarket Forecast, 2033
$172.4BCAGR, 2026–2033
50.8%Artificial Intelligence In Manufacturing Market Summary
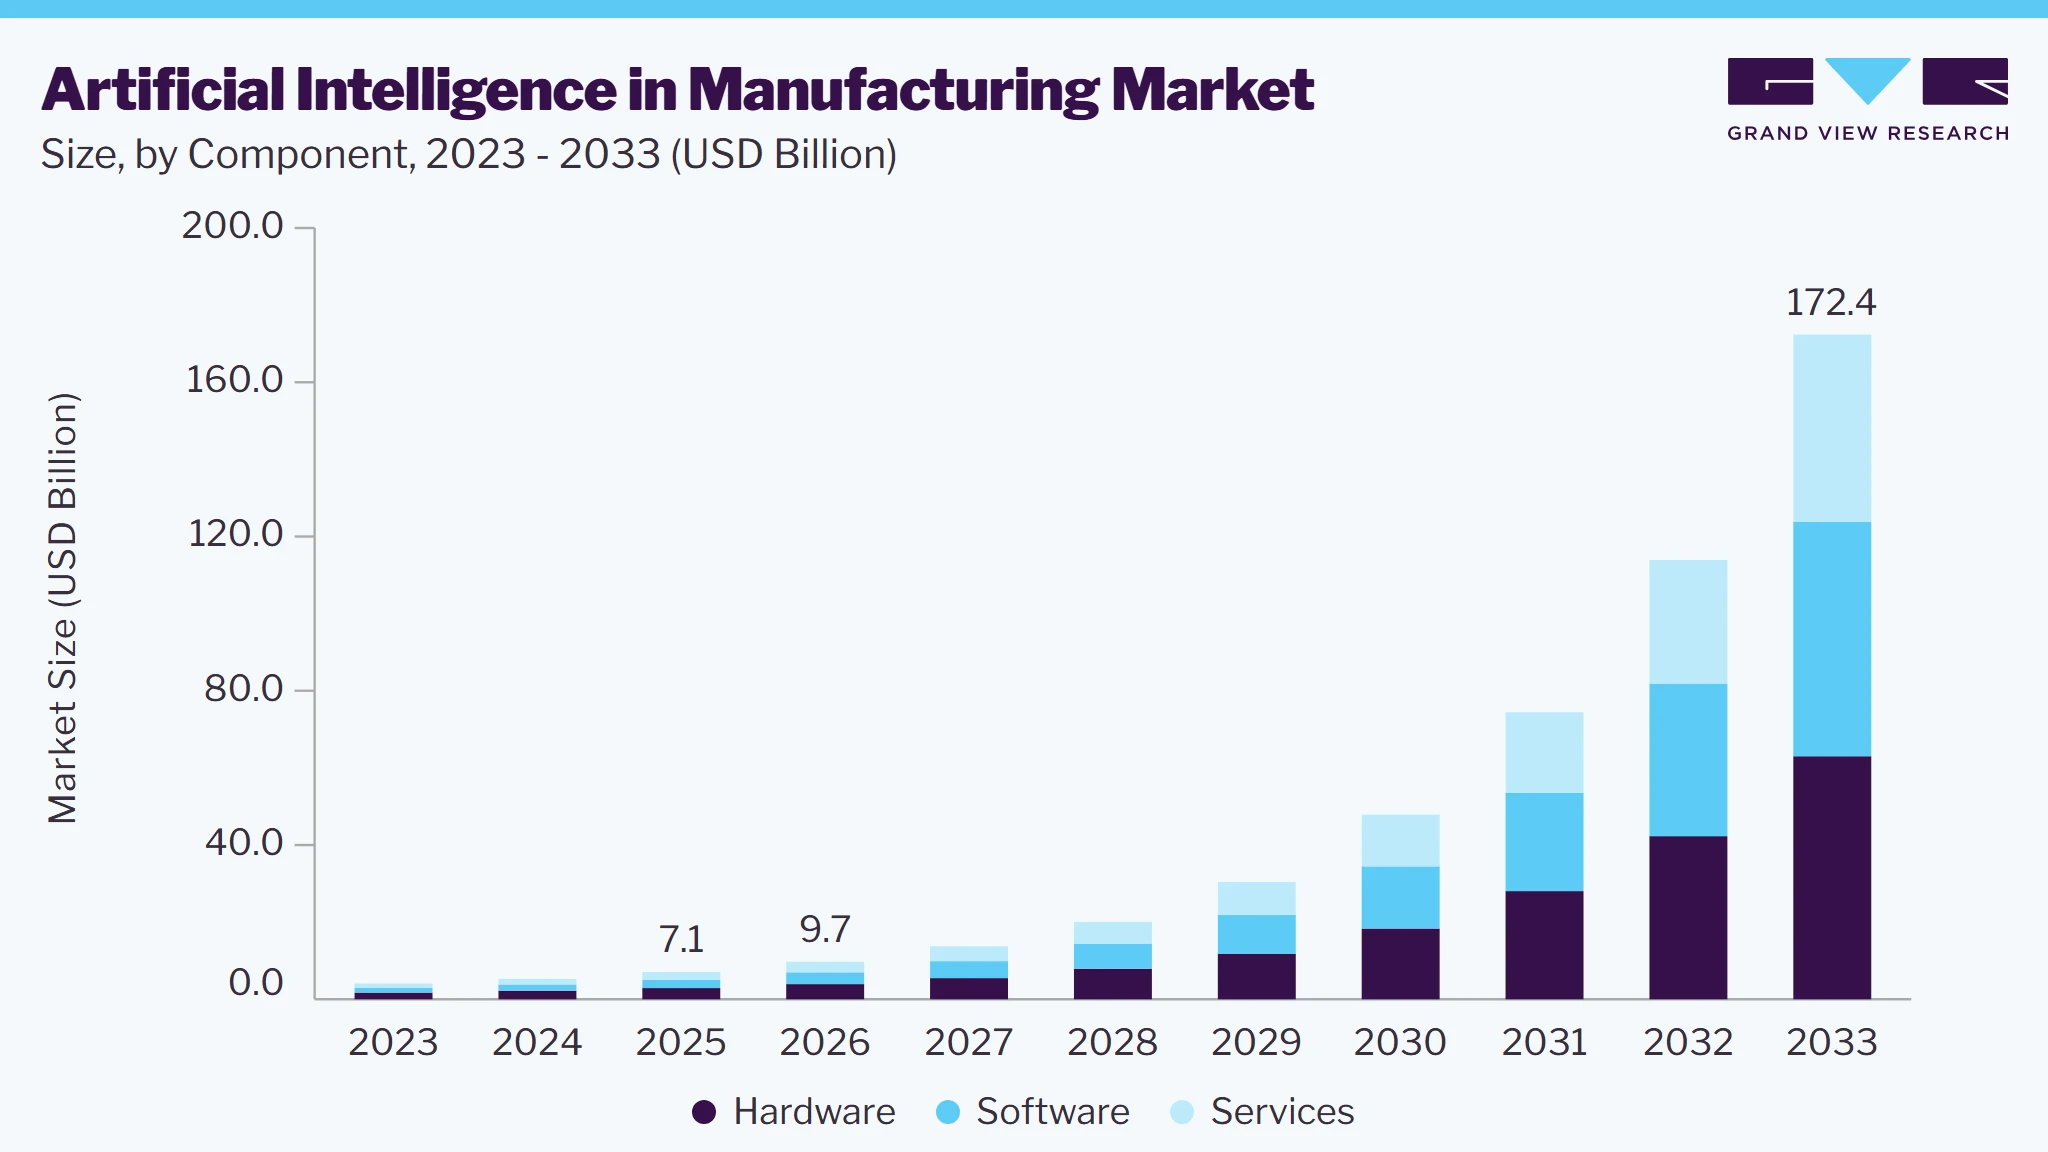
The global artificial intelligence in manufacturing market size was estimated at USD 7.1 billion in 2025 and is projected to grow from USD 9.7 billion in 2026 to USD 172.4 billion by 2033, growing at a CAGR of 50.8% from 2026 to 2033. North America dominated the AI in Manufacturing market with the largest revenue share of over 32% in 2025. The market is driven by increasing adoption of AI-powered predictive maintenance, rising deployment of industrial automation and smart manufacturing solutions, growing integration of machine learning and computer vision in production processes, expanding use of digital twins and industrial IoT, increasing demand for quality inspection and process optimization, and continuous investments in AI-enabled manufacturing technologies.
 Source: Grand View Research, IR Documents, Primary Interviews, Paid DatabasesTo learn more about this report,
 Download Free Sample Report
Key Market Trends & Insights
- By component: Hardware segment dominated the market, with a revenue share of 41% in 2025.
- By technology: Computer vision segment dominated the market, with a revenue share of over 29% in 2025.
- By application: Production planning segment held the largest revenue share in 2025.
- By end use: Automobile segment held the largest revenue share in 2025.
Regional Highlights
- Largest regional market: North America (over 32% revenue share, 2025)
- Fastest growing regional market: Asia Pacific (highest CAGR, 2026-2033)
- By country: The U.S. held the largest market share in 2025.
Market Size & Forecast
- Market size in 2025: USD 7.1 Billion
- Estimated market size in 2026: USD 9.7 Billion
- Projected market size by 2033: USD 172.4 Billion
- CAGR (2026-2033): 50.8%
Three ways to get this report
Buy it, customize it, or ask a question.Ask an Analyst
Analyst response in 1 business day
- AccessReport author, directly
- Reply timeWithin 1 working day
- No sales callDirect answer only
- FormatEmail reply
- CostFree, no cost
Get the Full Report
What the study covers
- FormatsPDF · Excel · Dashboard
- Timeline2026–2033 annual, 2025 base
- Coverage20+ countries, 5 regions
- Companies10+ key players profiled
Customize the Report
20% free customization
- IncludeCountries, segments, points
- TailorTo your product definition
- ExtendDeeper competitor detail
- OrA fully bespoke study
- Turnaround5–10 working days
This growth is driven by artificial intelligences (AI) numerous benefits in the construction sector, such as preventing cost overruns by predicting budgets based on historical data and assisting in creating predictive models according to timelines. These include analytics, augmented reality, virtual reality, smart packaging, and additive manufacturing. Digital transformation initiatives across various sectors contributed to this valuation by laying the groundwork for future AI-driven services.
 To learn more about this report, Download Free Sample Report
The fourth industrial revolution, Industry 4.0, is centered on the application of cyber-physical models and digital integration across the linked value chain. This fundamental change has accelerated the development of advanced technological capabilities and the widespread proliferation of digital ecosystems, particularly in the industrial sector. The growing digital revolution in manufacturing not only creates new opportunities in a variety of fields but also increases efficiency by tapping pre-existing values more efficiently. This transition correlates with the adoption of artificial intelligence in the Manufacturing sector, enabling innovation and efficiency benefits throughout production processes.
The advancement of automation within the manufacturing sector and the increasing demand for integrating big data are driving the expansion of AI in the manufacturing market. In addition, the extensive utilization of machine vision cameras in various manufacturing applications such as machinery inspection, material movement, field service, and quality control are a significant driver propelling the growth of artificial intelligence in manufacturing. Furthermore, major market players are implementing diverse strategies, such as introducing new products and fostering innovation, to broaden their product portfolios and uphold competitiveness in the rapidly evolving market. For instance, in February 2025, Tata Consultancy Services (TCS) collaborated with Salesforce to empower businesses in the manufacturing and semiconductor sectors to leverage AI and cloud computing effectively. This partnership aims to unlock data-driven insights, enhancing sales processes and field service operations through initiatives such as the Semiconductor Sales Accelerator, Seller for the Future, and Digital Field Service.
Market Dynamics
The AI in manufacturing market is experiencing rapid growth driven by the increasing adoption of artificial intelligence technologies to enhance production efficiency, operational intelligence, and manufacturing agility across industrial facilities. Manufacturers are integrating machine learning, computer vision, generative AI, industrial robotics, and predictive analytics into smart manufacturing environments to optimize production planning, automate quality inspection, and reduce equipment downtime. The expanding deployment of Industrial Internet of Things (IIoT), digital twins, edge AI, and cloud-based manufacturing execution systems is enabling real-time data-driven decision-making and improving overall factory performance. Growing investments in Industry 4.0 initiatives, autonomous production systems, and AI-enabled supply chain optimization are further strengthening the adoption of AI-powered manufacturing solutions across discrete and process industries. Additionally, continuous advancements in AI software platforms, industrial data analytics, and intelligent process automation are creating new opportunities for technology providers while accelerating the digital transformation of global manufacturing operations.
Drivers: Increasing Adoption of AI-Powered Automation, Predictive Analytics, and Smart Manufacturing
Manufacturers across industries such as automotive, electronics, aerospace, pharmaceuticals, and food processing are increasingly deploying artificial intelligence to automate complex production tasks, improve process accuracy, and enhance operational efficiency. AI technologies, including machine learning, computer vision, and deep learning, are used to analyze large volumes of data generated by industrial IoT sensors, robots, and connected machinery. These systems enable predictive maintenance by identifying early signs of equipment wear and potential failures, thereby reducing unplanned downtime and maintenance costs. AI-powered computer vision solutions enhance quality control by detecting defects, dimensional variations, and assembly errors with greater precision than traditional inspection methods. In addition, AI-driven production planning and scheduling tools optimize resource allocation, energy consumption, and inventory management to improve throughput and reduce waste. Furthermore, the growing adoption of smart manufacturing and Industry 4.0 initiatives, supported by increasing investments in factory digitization and automation, is significantly accelerating the demand for artificial intelligence solutions in manufacturing environments.
Overall, artificial intelligence in manufacturing market is poised for significant growth, driven by increasing investments in smart manufacturing, rising demand for real-time data-driven decision-making, and the ongoing digital transformation of industrial operations.
Despite its substantial growth potential, the artificial intelligence in manufacturing market faces several challenges. Implementing AI solutions often requires significant investments in software platforms, advanced sensors, edge computing infrastructure, and workforce training. Small and medium-sized manufacturers may find these upfront costs prohibitive, limiting adoption.
Another major restraint is the complexity of integrating AI systems with legacy manufacturing equipment and enterprise software such as manufacturing execution systems (MES) and enterprise resource planning (ERP) platforms. Poor data quality, siloed information, and a lack of standardized industrial data formats can reduce the effectiveness of AI models.
Cybersecurity and data privacy also present challenges, as connected factories generate large volumes of sensitive operational and intellectual property data. In addition, the shortage of skilled professionals with expertise in artificial intelligence, industrial automation, and data science can delay deployment and limit scalability across manufacturing facilities.
The rapid advancement of generative AI, digital twin technology, and autonomous robotics is creating substantial opportunities for artificial intelligence in manufacturing market. Generative AI enables manufacturers to optimize product designs, create production scenarios, and generate actionable insights from large volumes of operational data.
Digital twins provide virtual replicas of machines, production lines, and entire factories, allowing companies to simulate performance, identify bottlenecks, and improve efficiency before making physical changes. Autonomous robots and AI-driven cobots are also expanding opportunities by enabling flexible automation and collaboration with human workers. The increasing adoption of cloud-based AI platforms from companies such as Microsoft, Google Cloud, Amazon Web Services (AWS), and IBM is making advanced analytics more accessible to manufacturers of all sizes. Furthermore, growing investments in sustainable manufacturing, energy optimization, and resilient supply chains are expected to unlock significant long-term opportunities for the global artificial intelligence in manufacturing market.
Market Concentration & Characteristics
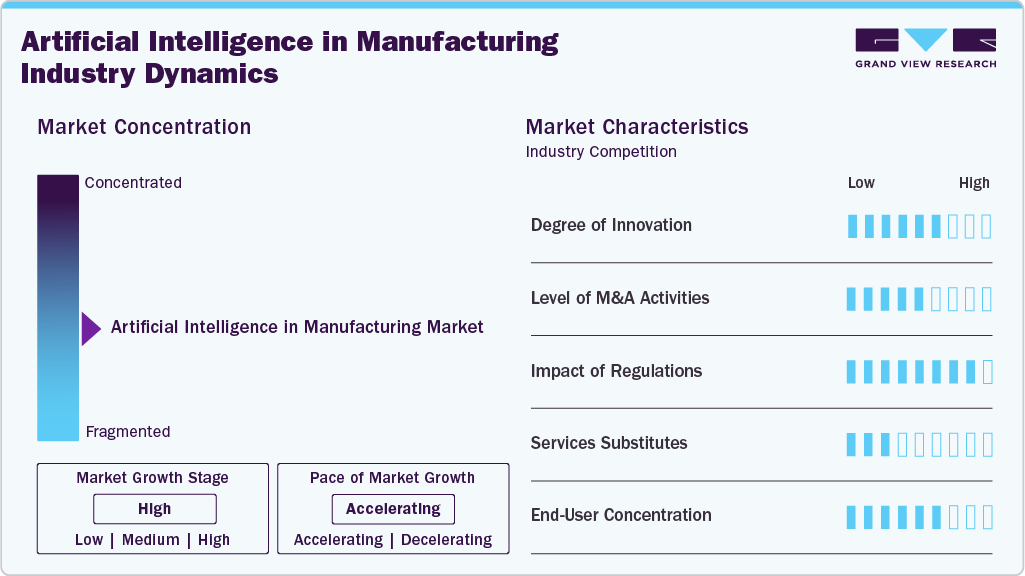
The Artificial Intelligence in manufacturing market is highly fragmented, with numerous global technology companies, industrial automation providers, cloud platform vendors, semiconductor manufacturers, and specialized AI startups competing across predictive maintenance, quality inspection, production planning, robotics, and supply chain optimization applications. The market includes large multinational corporations that leverage broad software portfolios, advanced analytics capabilities, and extensive industrial customer networks, alongside a growing number of niche solution providers focused on specific use cases such as computer vision-based defect detection, digital twins, and autonomous robotics.
 To learn more about this report, Download Free Sample Report
Overall, the artificial intelligence in manufacturing market faces competition from alternative automation and analytics technologies, including conventional industrial automation systems, rule-based software, and traditional quality control solutions. This competitive pressure encourages AI solution providers to demonstrate clear returns on investment through improved productivity, reduced downtime, enhanced product quality, and greater operational efficiency in order to accelerate adoption across manufacturing environments.
Analyst Perspective
The AI in manufacturing market is expected to witness sustained long-term expansion as manufacturers increasingly prioritize intelligent factories, connected production environments, and data-centric industrial operations to improve competitiveness. The convergence of generative AI, industrial automation, advanced analytics, industrial edge computing, and cyber-physical systems is transforming conventional manufacturing into highly adaptive and autonomous production environments. Increasing investments in industrial AI platforms, intelligent process orchestration, collaborative robotics, and real-time operational intelligence will continue to reshape manufacturing value chains across both discrete and process industries. Furthermore, the growing emphasis on sustainable manufacturing, energy-efficient production, industrial cybersecurity, and resilient supply networks is expanding the strategic role of AI across enterprise-wide manufacturing operations. As technology maturity advances and industrial AI adoption accelerates globally, solution providers capable of delivering scalable, interoperable, and industry-specific AI capabilities are expected to strengthen their competitive positioning and unlock significant market opportunities.
Component Insights
Based on Component, the hardware segment led the market with the largest revenue share of 41% in 2025 . Developments in dedicated AI chips and processors played a crucial role in the AI in manufacturing industry. These hardware advancements were tailored to meet the specific computational requirements of AI algorithms, resulting in quicker and more effective processing of complicated datasets. Businesses were allocating resources to create specialized hardware specifically optimized for tasks related to machine learning, which consequently improved efficiency and allowed for the implementation of more advanced AI applications within manufacturing settings. These specialized chips were instrumental in managing complex neural network computations, thus facilitating the progression of AI-centric operations across the industry.
The software segment is expected to grow at the highest CAGR during the forecast period. Software solutions offer extensive applicability across a diverse spectrum of production processes owing to their exceptional versatility and adaptability. Given its innate flexibility, software stands out as the optimal choice for a sector characterized by varied requirements. The swift development, testing, and deployment capabilities inherent in software enable rapid implementation—a crucial advantage in the manufacturing landscape. This adaptability proves indispensable in an industry that necessitates prompt responses to fluctuations in AI in the manufacturing market and technological advancements. Furthermore, software integration into existing industrial machinery and workflows is notably straightforward and seamless.
Technology Insights
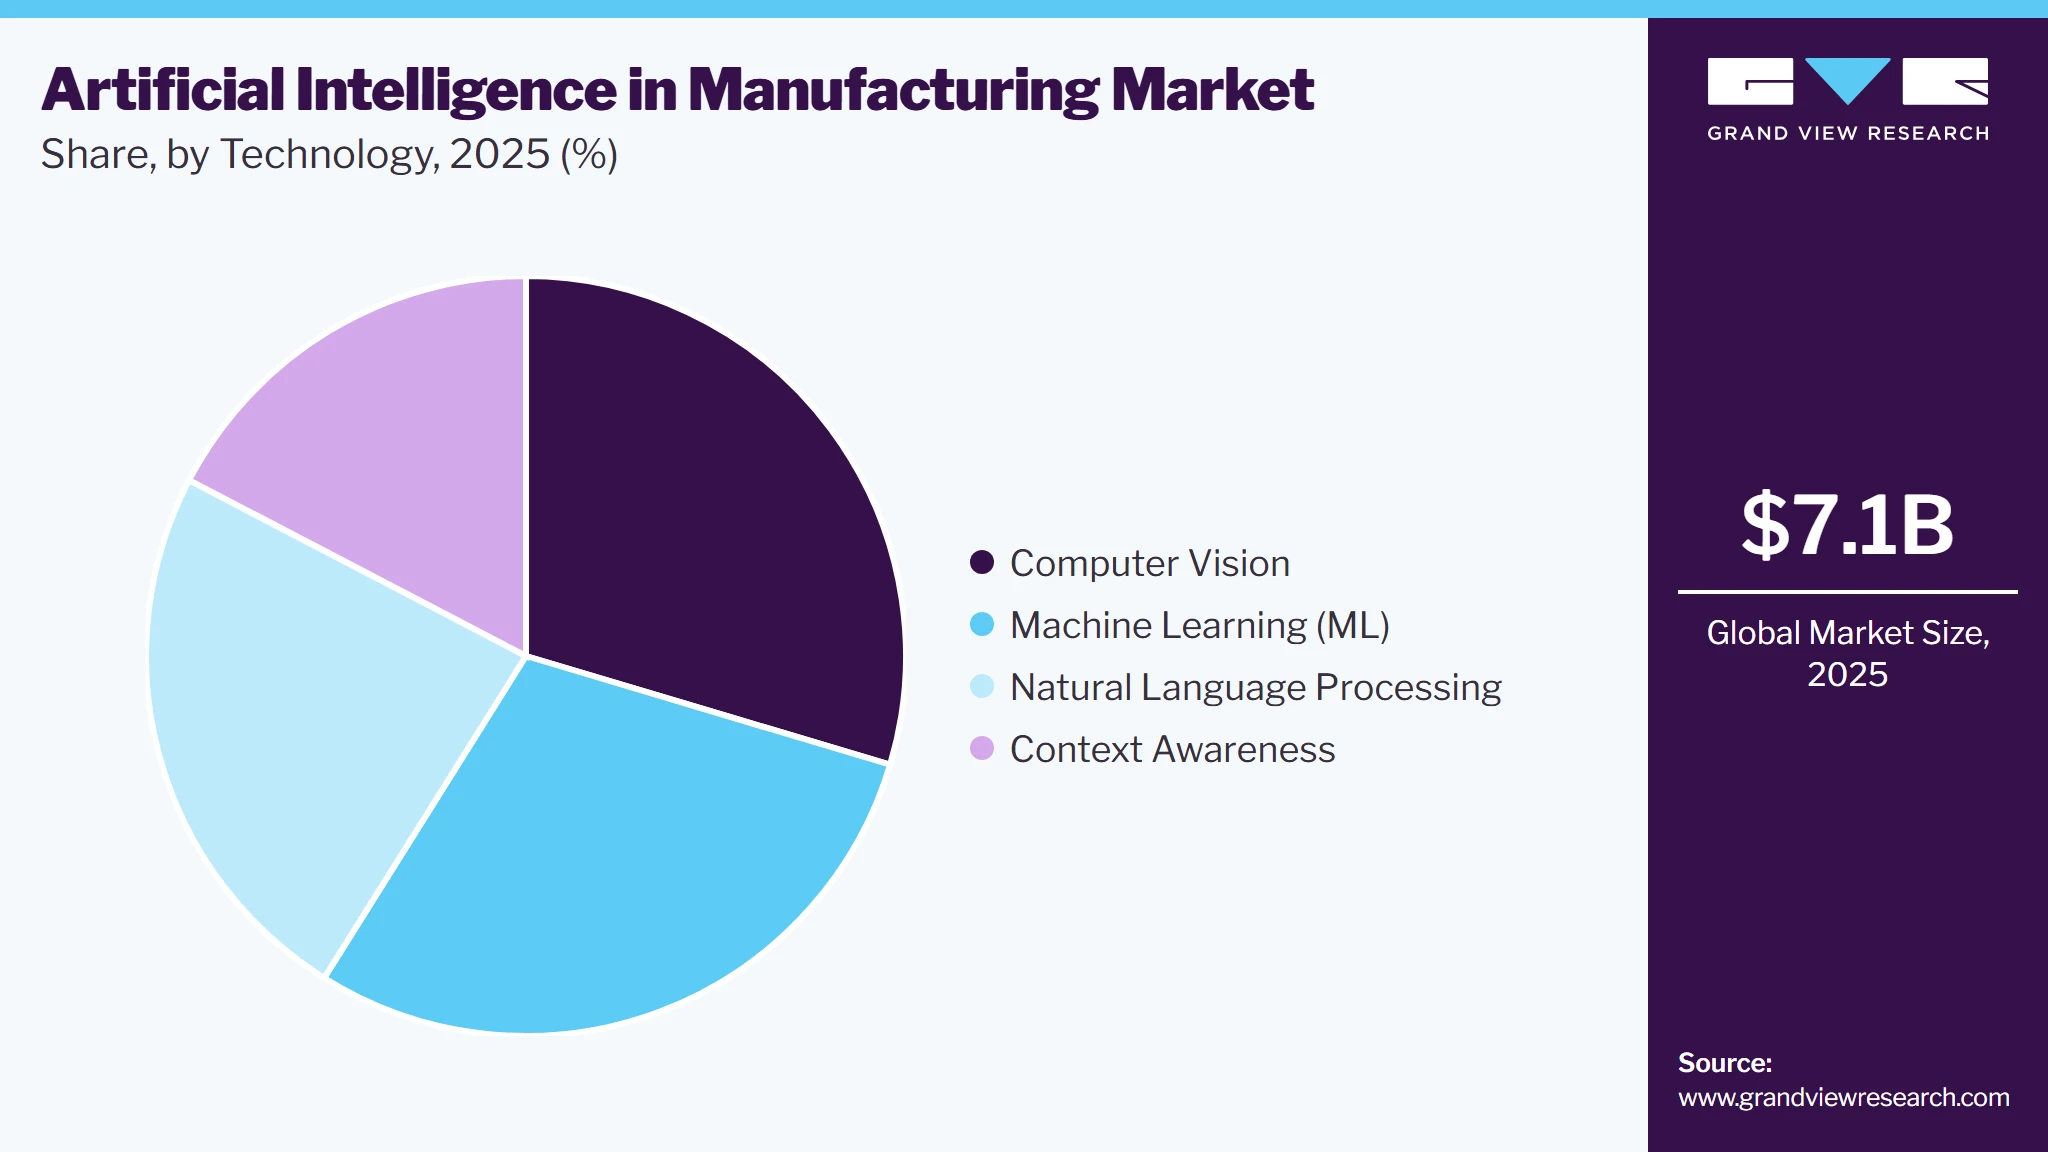
Based on Technology, the computer vision segment led the market with the largest revenue share of over 29% in 2025, due to its demonstrable effectiveness in enhancing operational efficiency and reducing downtime. The analysis of past equipment data by Machine Learning algorithms enables the prediction of potential machinery failures before they occur. This foresight allows manufacturers to proactively schedule maintenance activities. This shift from reactive to proactive maintenance empowers manufacturers to optimize their resources, minimizing unexpected downtimes and maximizing overall operational dependability. The reduction of costs coupled with dependable operations made machine learning the front-runner in artificial intelligence in manufacturing industry.
The computer vision segment is expected to register the fastest CAGR during the forecast period. Artificial intelligence integrated with computer vision techniques enhances task efficiency. Through computer vision, robots gain improved understanding of their surroundings within factory premises, enabling safer navigation around humans. In smart manufacturing environments, AI-driven computer vision aids in detecting faults and flaws in product outcomes, subsequently streamlining factory workflows. For instance, Micron Technology Inc. specializes in crafting precise memory technology on silicon wafers, a process prone to imperceptible defects. To address this challenge, the company has implemented AI-based computer vision methods in its manufacturing facilities, effectively identifying defects and significantly enhancing manufacturing efficiency and effectiveness.
Application Insights
Based on application, the production planning segment led the market with the largest revenue share of over 24% in 2025. AI-powered production planning systems were transforming demand prediction by incorporating sophisticated predictive analytics. These systems employed machine learning algorithms to scrutinize historical data, market trends, and diverse influential variables for generating precise forecasts of demand. Leveraging these insights, manufacturers optimized inventory levels, refined production schedules, and allocated resources with greater effectiveness, culminating in cost reductions and heightened operational efficiency.
The predictive maintenance & machinery inspection segment is expected to register the fastest CAGR during the forecast period. AI-powered predictive maintenance systems placed a growing emphasis on remote monitoring and diagnostics. Employing AI algorithms, manufacturers were able to remotely observe equipment status, identify irregularities, and promptly diagnose potential problems in live scenarios. For instance, General Motors utilizes AI driven predictive analytics to optimize vehicle production by analyzing historical performance and real-time data from its robotics and conveyor systems. The AI model identifies anomalous patterns that may indicate potential malfunctions, enabling early detection and swift intervention. This emerging trend facilitated proactive decision-making, enabling timely maintenance or repairs to be conducted without the necessity for physical inspection, thereby mitigating disruptions in production operations.
End Use Insights
Based on end use, the automobile segment led the market with the largest revenue share of over 22% in 2025. AI holds significant potential in medical device manufacturing due to its technology, encompassing quality control, yield optimization, and predictive maintenance, among other functionalities. Implementing machine learning and computing enhances engineers' roles by enabling learning from errors and improving precision. Medical device manufacturers can employ AI in diverse ways, including ensuring device quality and predictive maintenance based on data analysis.
 To learn more about this report, Download Free Sample Report
The automobile sector is projected to witness the highest growth rate over the forecast period, driven by the integration of AI technology with advanced connectivity elements. This integration has enhanced Vehicle-to-Vehicle (V2V) and Vehicle-to-Infrastructure (V2I) communication, introducing sophisticated AI assistants that provide real-time traffic updates and predictive navigation, improving driving experience and safety. For instance, in October 2024, Elon Musk introduced Tesla's Cybercab robotaxi, marking a significant step towards autonomous vehicles and AI-driven transportation solutions, aligning with Tesla's broader strategy to transform the transportation sector with efficient and safe mobility solutions.
Regional Insights
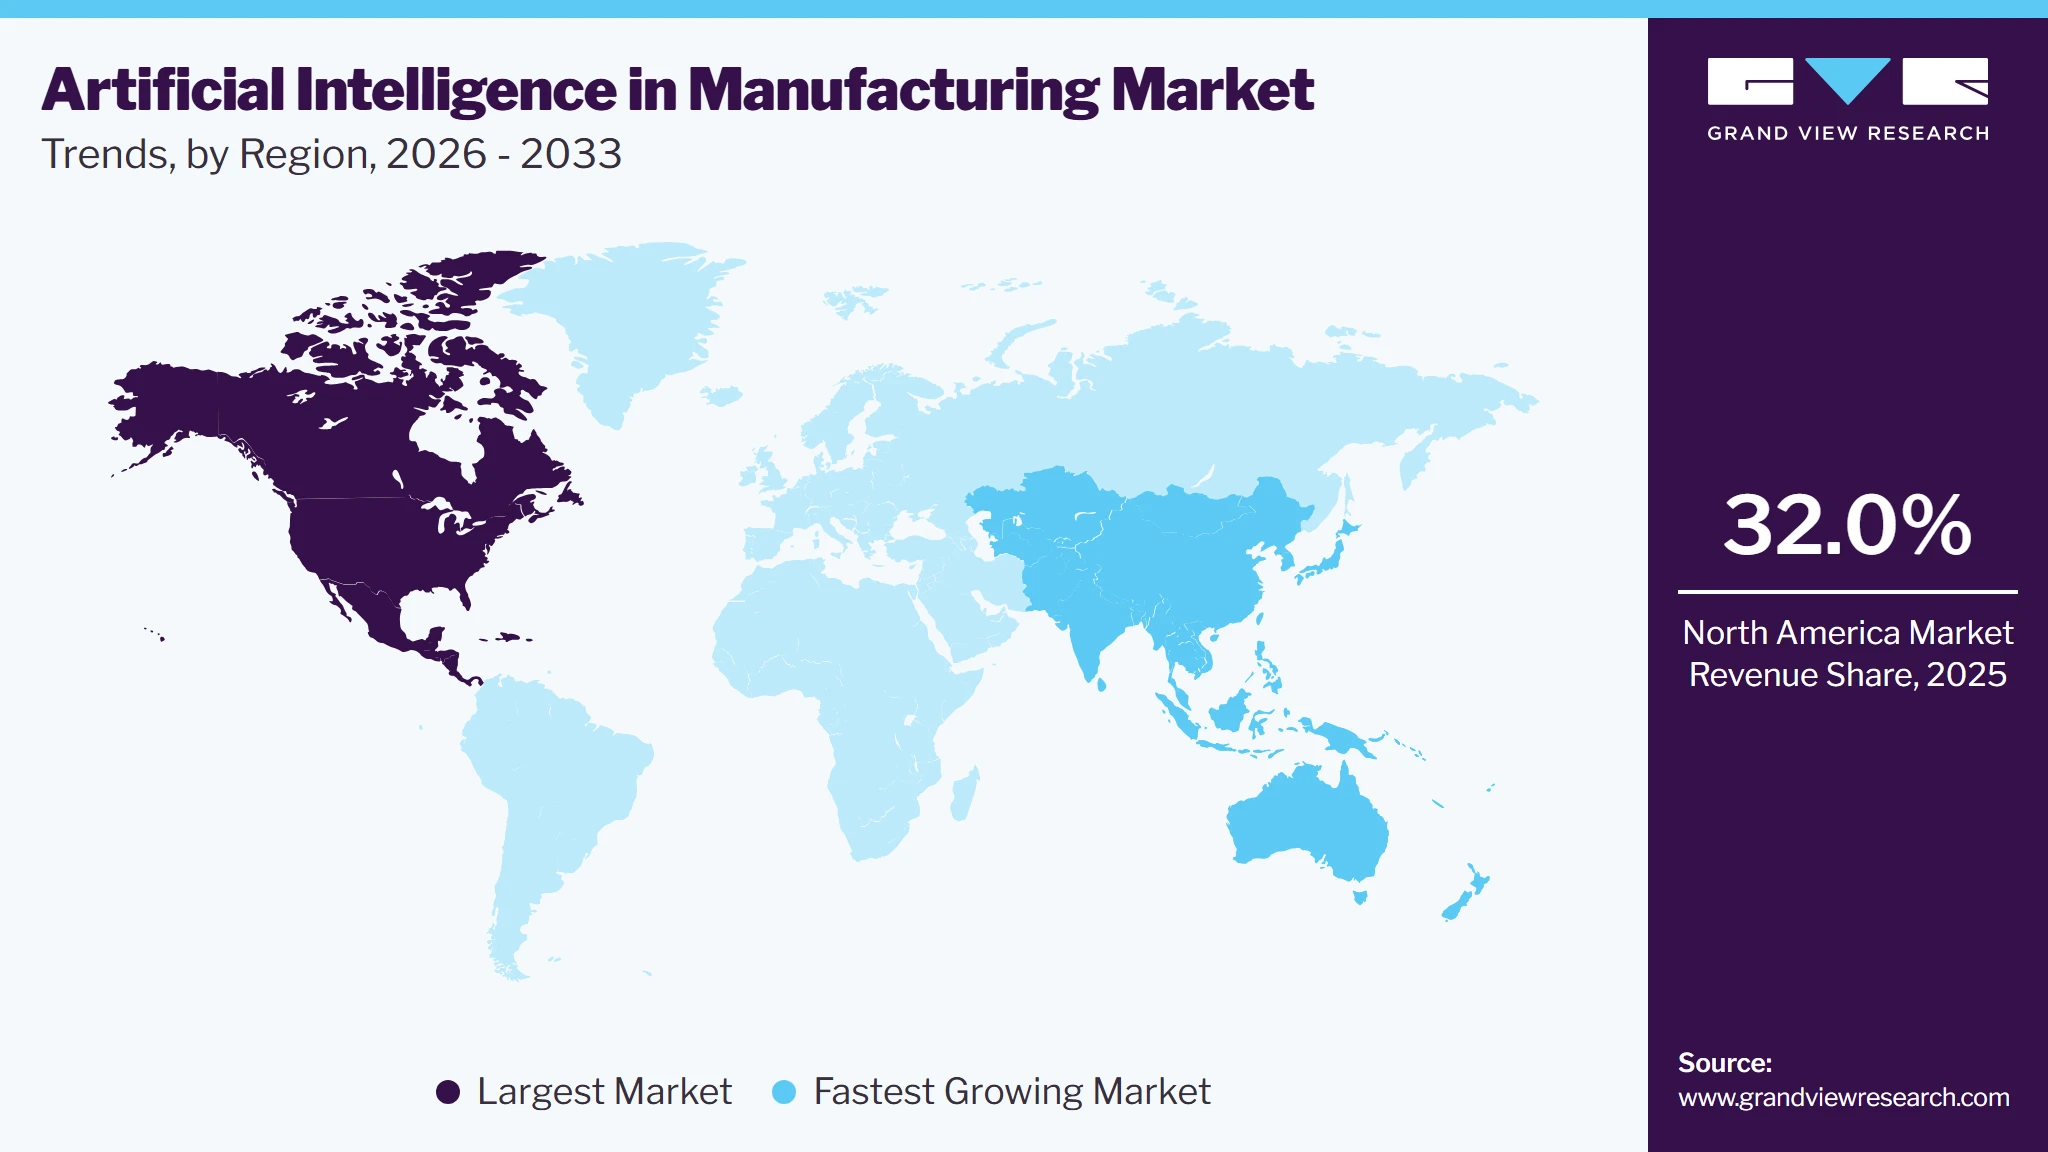
North America dominated the AI in Manufacturing market with the largest revenue share of over 32% in 2025. The regional market's revenue growth is propelled by the presence of top-tier companies producing high-performance hardware components essential for running advanced AI models. The U.S. government's National Strategy for Advanced Manufacturing serves as a strategic blueprint outlining initiatives to revitalize the manufacturing sector, fortify national supply chains, bolster national security, and encourage investments in research and development. This strategy prioritizes research endeavors encompassing machine learning, data privacy, encryption, and risk assessment, aiming to facilitate the integration of AI within manufacturing processes. Moreover, it seeks to institute industry-wide standards, best practices, and software solutions to foster innovative business models that harness production data while ensuring data security and safeguarding intellectual property rights.
 To learn more about this report, Download Free Sample Report
U.S. Artificial Intelligence in Manufacturing Market Trends
The AI in Manufacturing market in the U.S. held the largest share in the North America region in 2025 due to its pioneering role in AI innovation. This stems from a robust ecosystem of major technology firms and startups, coupled with considerable government funding that accelerates the development and deployment of AI solutions. This emphasis on research and development, combined with a skilled workforce, allows for rapid advancements and widespread adoption of AI across diverse manufacturing sectors
Europe Artificial Intelligence in Manufacturing Market Trends
Europe artificial intelligence in manufacturing market is expected to grow at a significant CAGR during the forecast period, driven by increased investments in AI research and development, particularly in countries such as Germany, France, and the UK. Key sectors such as healthcare, automotive, and manufacturing are increasingly adopting AI, contributing to market expansion. Supportive government policies and initiatives designed to foster AI innovation are also expected to stimulate market growth, alongside Europe's commitment to ethical AI development and data privacy
Asia Pacific Artificial Intelligence in Manufacturing Market Trends
Asia Pacific is anticipated to witness the highest CAGR in the artificial intelligence in manufacturing market during the forecast period 2025 - 2033. The Asia Pacific region made significant strides in advancing smart manufacturing in line with Industry 4.0 principles. The countries such as China, Japan, India in this region focused on leveraging AI-driven technologies to digitalize and enhance production procedures. With a strong emphasis on integrating IoT devices, AI analytics, and cyber-physical systems, the objective was to establish sophisticated factories capable of adaptive manufacturing, predictive analysis, and immediate data-informed decision-making. This strategic move positioned the region as a leader in technological innovation within the manufacturing sector.
China artificial intelligence in manufacturing market dominated the regional market in 2024 fueled by significant investments in AI research and development from both governmental and private entities. China's expansive population and abundant data resources provide a strong foundation for training and refining AI models. Strong governmental support for AI innovation, combined with a rapidly expanding technology sector, has further accelerated growth within artificial intelligence in manufacturing industry, with widespread adoption of AI across industries such as e-commerce, finance, and transportation
Key Artificial Intelligence in Manufacturing Company Insights
Some of the key players operating in the market include Microsoft Corporation, IBM Corporation, Amazon.com, Inc., and Google LLC (Alphabet Inc.)
-
Microsoft Corporation offers a wide range of AI capabilities and solutions, such as industrial Internet of Things, cloud computing, AI, and other smart manufacturing technologies. It also offers Azure Time Series Insights and Azure Digital Twins & Simulation, which helps in generating data representations of products, assets, and factories and helps in improving the process.
-
The IBM Maximo Application Suite uses AI algorithms to evaluate equipment performance and forecast maintenance requirements in industrial environments. The primary objective of the AI applications in this suite is to study correlations between asset reliability and various maintenance procedures to improve equipment uptime, reduce breakdowns, and increase overall operational productivity.
Spark Cognition Inc., General Vision Inc., and Sight Machine are some of the emerging market participants in the artificial intelligence in manufacturing industry.
- Spark Cognition specializes in AI-driven predictive analytics, focusing on various industries. They provide AI-powered predictive maintenance solutions that utilize machine learning algorithms to forecast equipment failure and optimize operations in manufacturing plants. This helps in reducing downtime, enhance productivity, and improve safety by analyzing data from sensors and other sources to predict potential issues before they occur.
- General Vision Inc. offers machine vision systems that use AI algorithms for quality control, defect detection, and automated inspection processes in manufacturing facilities. Their technology enables high-speed and precise inspection, improving product quality and production efficiency in various manufacturing sectors.
Key Artificial Intelligence In Manufacturing Companies
The following are the leading companies in the artificial intelligence in manufacturing market.
-
AIBrain Inc.
-
Amazon Web Services
-
Aquant Inc.
-
Cisco Systems Inc
-
General Electric Company
-
General Vision Inc.
-
Google LLC (Alphabet Inc.)
-
IBM Corporation
-
Intel Corporation
-
Micron Technology Inc.
-
Microsoft Corporation
-
Mitsubishi Electric Corporation
-
NVIDIA Corporation
-
Oracle Corporation
-
Rethink Robotics
-
Rockwell Automation Inc
-
SAP SE
-
Siemens AG
-
Sight Machine
-
Spark Cognition Inc.
Competitive Benchmarking
Operating Strategies
Competitive Edge
Weaknesses
Mature Players: Amazon Web Services (AWS); Cisco Systems; IBM Corporation; NVIDIA Corporation; Rockwell Automation
- Expand AI capabilities through acquisitions, partnerships, and industry-specific manufacturing solutions
- Invest in machine learning, industrial IoT, edge computing, and cloud analytics to deliver scalable smart manufacturing solutions
- Strong global presence, extensive industrial customer networks, and broad AI and automation portfolios support market leadership
- Ability to deliver scalable AI solutions across cloud, edge, industrial IoT, and factory automation platforms strengthens competitiveness
- Dependence on legacy systems and large enterprise customer bases can slow the adoption of new AI technologies and deployment models
- Complex organizational structures may reduce agility and delay innovation compared to specialized industrial AI startups
Emerging Players: AIBrain Inc.; General Vision Inc; SparkCognition Inc.
- Develop specialized and cost-effective AI solutions targeting niche manufacturing applications
- Focus on agility, customization, and rapid innovation to address evolving smart manufacturing requirements and industry-specific operational challenges.
- Faster development cycles enable quick adoption of emerging AI technologies and evolving manufacturing requirements.
- Flexible and customer-centric approaches help differentiate solutions in niche industrial AI applications.
- Limited financial resources and smaller market presence can restrict large-scale expansion and global commercialization
- Lower brand recognition and a smaller industrial customer base compared to established technology and automation companies
Recent Developments
-
In February 2025, Ikigai Capital, an investment group, declared a USD 1 million investment in Ariprus Digicon, an AI technology company specializing in industrial digitization. This funding aims to support the development of adaptable AI agents that can replicate the expertise of domain specialists, thereby improving automation and efficiency in manufacturing processes.
-
In February 2025, Stellantis announced an expanded partnership with Mistral AI to integrate artificial intelligence (AI) into its operations. This collaboration leverages Mistral AI’s expertise in large language models (LLMs) and AI-driven automation to enhance projects spanning manufacturing, engineering, fleet data analysis, and internal car sales.
-
In October 2023, Google Cloud introduced specialized Generative AI solutions tailored for healthcare and manufacturing industries, with the objective of improving efficiency and facilitating digital transformation. This initiative signifies a significant stride in harnessing artificial intelligence in manufacturing industry-specific progress.
-
In April 2023, Siemens collaborated with Microsoft to enhance industrial AI, transforming the management of product lifecycles. The integration of Siemens' Teamcenter software with Microsoft Teams and Azure OpenAI Service's language models aims to boost innovation and effectiveness. This collaboration facilitates smooth cross-departmental cooperation, propelling progress in design, engineering, manufacturing, and product operations, representing a substantial advancement in integrating industrial technologies.
Artificial Intelligence in Manufacturing Market Report Scope
Report Attribute
Details
Market size in 2025
USD 7.1 billion
Estimated market size in 2026
USD 9.7 billion
Projected market size by 2033
USD 172.4 billion
Growth rate
CAGR of 50.8% from 2026 to 2033
Base year for estimation
2025
Historical data
2021 - 2024
Forecast period
2026 - 2033
Quantitative units
Revenue in USD million/billion and CAGR from 2026 to 2033
Report coverage
Revenue forecast, company ranking, competitive landscape, growth factors, and trends
Segments covered
Component, technology, application, end use, region
Regional scope
North America; Europe; Asia Pacific; Latin America; MEA
Country scope
U.S.; Canada; Mexico; Germany; UK; France; China; Japan; India; South Korea; Australia; Brazil; Saudi Arabia; South Africa; UAE
Key companies profiled
Amazon Web Services; Cisco Systems Inc; General Electric Company; Google LLC (Alphabet Inc.; IBM Corporation; Intel Corporation; Microsoft Corporation; Mitsubishi Electric Corporation; NVIDIA Corporation; Oracle Corporation; Rethink Robotics; Rockwell Automation Inc; SAP SE; Siemens AG
Customization scope
Free report customization (equivalent up to 8 analysts' working days) with purchase. Addition or alteration to country, regional & segment scope.
Pricing and purchase options
Avail customized purchase options to meet your exact research needs. Explore purchase options
Global Artificial Intelligence in Manufacturing Market Report Segmentation
This report forecasts revenue growth at global, regional, and country levels and provides an analysis of the latest industry trends in each of the sub-segments from 2021 to 2033. For this study, Grand View Research has segmented the global artificial intelligence in manufacturing market report based on component, technology, application, end use, and region.
-
Component Outlook (Revenue, USD Million, 2021 - 2033)
-
Hardware
-
Software
-
Services
-
-
Technology Outlook (Revenue, USD Million, 2021 - 2033)
-
Machine Learning (ML)
-
Computer Vision
-
Context Awareness
-
Natural Language Processing
-
-
Application Outlook (Revenue, USD Million, 2021 - 2033)
-
Material Movement
-
Predictive Maintenance & Machinery Inspection
-
Production Planning
-
Field Services
-
Quality Control & Reclamation
-
Others
-
-
End Use Outlook (Revenue, USD Million, 2021 - 2033)
-
Semiconductor & Electronics
-
Energy & Power
-
Medical devices
-
Automobile
-
Heavy Metal & Machine Manufacturing
-
Others
-
-
Regional Outlook (Revenue, USD Million, 2021 - 2033)
-
North America
-
U.S.
-
Canada
-
-
Europe
-
Germany
-
UK
-
France
-
-
Asia Pacific
-
China
-
Japan
-
India
-
South Korea
-
Australia
-
-
Latin America
-
Brazil
-
Mexico
-
-
Middle East and Africa (MEA)
-
KSA
-
UAE
-
South Africa
-
-
Research Methodology
The artificial intelligence in manufacturing Market figures in this report are based on a proven research process that combines executive interviews with secondary research from proprietary databases, company filings, and recognized regulatory and institutional sources. Market size is built through value-chain sizing - reconciling supply-side and demand-side estimates - and triangulated with bottom-up and top-down approaches. Every estimate passes multiple levels of expert validation before publication, with each artificial intelligence in manufacturing Market segment quantified using the revenue-capture definitions in the table below.
Segment Definition
Segment - Component
Revenue capture definition
Hardware
The hardware segment comprises AI-enabled computing infrastructure, industrial sensors, edge devices, GPUs, processors, robotics, cameras, and other physical equipment that support AI deployment in manufacturing environments. It enables real-time data acquisition, intelligent automation, and high-performance processing for production and operational applications.
Software
This segment includes AI software platforms, machine learning frameworks, computer vision applications, predictive analytics tools, and manufacturing intelligence solutions used to optimize industrial operations. These solutions facilitate data analysis, process automation, quality management, and production decision-making across manufacturing facilities.
Services
The services segment consists of consulting, implementation, system integration, customization, maintenance, and managed services associated with AI in manufacturing deployments. Service providers support manufacturers in designing, integrating, optimizing, and scaling AI solutions to achieve operational efficiency and business objectives.
Segment - Technology
Revenue capture definition
Machine Learning (ML)
The machine learning (ML) segment encompasses AI algorithms that analyze manufacturing data to identify patterns, generate predictions, and continuously improve operational performance. It supports applications such as predictive maintenance, production optimization, process automation, and intelligent decision-making.
Computer Vision
The computer vision segment includes AI technologies that process and interpret visual data captured through industrial cameras and imaging systems. It is widely utilized for automated inspection, defect detection, product measurement, and quality assurance across manufacturing processes.
Context Awareness
The segment focuses on AI technologies capable of interpreting environmental, operational, and equipment conditions to support adaptive manufacturing decisions. These solutions enhance production efficiency by responding intelligently to real-time changes within industrial environments.
Natural Language Processing
Natural Language Processing (NLP) comprises AI technologies that enable machines to understand, interpret, and generate human language within manufacturing operations. It supports applications including intelligent documentation, virtual assistants, maintenance support, and knowledge management.
Segment - Application
Revenue capture definition
Material Movement
The material movement segment covers AI solutions used to automate, optimize, and monitor the transportation of raw materials, components, and finished products within manufacturing facilities. These solutions improve warehouse efficiency, inventory flow, and production logistics through intelligent automation.
Predictive Maintenance &
Machinery InspectionThis segment includes AI applications that continuously monitor equipment performance to predict failures and optimize maintenance schedules before breakdowns occur. It enhances equipment reliability, reduces unplanned downtime, and extends the operational lifespan of industrial assets.
Production Planning
Production planning refers to AI-driven solutions that optimize manufacturing schedules, resource allocation, capacity utilization, and workflow management. These technologies improve production efficiency by enabling data-driven planning and adaptive manufacturing operations.
Field Services
The field services segment comprises AI applications that support maintenance technicians, equipment servicing, remote diagnostics, and on-site operational assistance. AI enhances service efficiency by improving issue identification, maintenance planning, and workforce productivity.
Quality Control & Reclamation
The quality control & reclamation segment includes AI-powered inspection and defect detection solutions that ensure products meet manufacturing quality standards while minimizing waste. These technologies also support material recovery, rework optimization, and continuous quality improvement throughout production.
Others
The others segment includes emerging AI applications such as energy optimization, supply chain intelligence, workforce safety, sustainability management, and industrial cybersecurity. These applications extend AI adoption beyond core manufacturing operations to improve overall operational performance.
Segment - End Use
Revenue capture definition
Semiconductor & Electronics
The semiconductor & electronics segment utilizes AI in manufacturing to enhance precision production, wafer inspection, yield optimization, and automated quality control. AI technologies support high-volume manufacturing while improving process consistency and reducing production defects.
Energy & Power
The energy & power segment applies AI technologies to optimize equipment performance, asset monitoring, predictive maintenance, and plant operations. AI supports efficient energy production by improving operational reliability, resource utilization, and infrastructure management.
Medical devices
Medical devices include manufacturers utilizing AI to improve precision manufacturing, product traceability, quality assurance, and regulatory compliance. AI solutions enhance production accuracy while supporting stringent quality and safety requirements.
Automobile
The automobile segment incorporates AI across vehicle manufacturing processes, including robotics, predictive maintenance, intelligent assembly, quality inspection, and supply chain optimization. These technologies improve manufacturing efficiency, production flexibility, and product consistency.
Heavy Metal & Machine Manufacturing
Heavy metal & machine manufacturing covers AI-enabled production environments focused on large-scale industrial equipment, fabricated metals, and machinery manufacturing. AI supports process optimization, equipment monitoring, automated inspection, and operational efficiency within complex manufacturing operations.
Others
The others segment includes industries such as aerospace, chemicals, food & beverages, textiles, packaging, and consumer goods that leverage AI to improve manufacturing performance and operational intelligence. AI adoption across these industries supports automation, quality enhancement, and production optimization according to industry-specific requirements.
Estimation Model
Layer Name
Key Questions
Description
Manufacturing AI Demand Layer
Who creates demand for AI in Manufacturing?
Identify demand generated by automotive, semiconductor & electronics, energy & power, medical devices, heavy metal & machinery manufacturing, and other industrial sectors. This layer evaluates manufacturing output, factory automation initiatives, Industry 4.0 adoption, operational efficiency requirements, workforce productivity goals, and digital transformation investments driving AI adoption.
AI Technology & Infrastructure Layer
Who develops AI in Manufacturing solutions?
Assess AI software vendors, industrial automation providers, cloud service providers, semiconductor companies, robotics manufacturers, computer vision developers, and edge AI solution providers. This layer measures investments in machine learning, computer vision, predictive analytics, generative AI, Industrial IoT (IIoT), digital twins, and intelligent manufacturing infrastructure.
AI Deployment & Industrial Adoption Layer
Who adopts AI in Manufacturing solutions?
Evaluate AI implementation across production planning, predictive maintenance, quality control, material movement, field services, supply chain optimization, and smart factory operations. This layer captures enterprise adoption by deployment model, component, technology, application, organization size, and manufacturing industry.
Market Revenue Realization Layer
How much revenue is generated through AI in Manufacturing?
Estimate market revenue generated from AI hardware, software platforms, cloud-based AI solutions, edge AI infrastructure, implementation services, consulting, maintenance, and managed services. This layer quantifies revenue across technology providers, system integrators, industrial automation companies, cloud vendors, and manufacturing enterprises.
Regional Investment & Expansion Layer
Where is future market growth expected?
Assess regional investments in smart manufacturing, AI infrastructure, government-led Industry 4.0 initiatives, industrial automation spending, and manufacturing digitalization across North America, Europe, Asia Pacific, Latin America, and the Middle East & Africa. This layer identifies regional growth opportunities, investment trends, and expansion potential influencing the future AI in manufacturing market.
Delivered Customizations
This report has been delivered with the following In-depth customizations
Client Request
Customization Delivered
Value Adds
AI-Powered Predictive Maintenance Opportunity Assessment for an Industrial Technology Provider
- Analysis of demand for predictive maintenance solutions across automotive, electronics, aerospace, and heavy industries
- Benchmarking of leading vendors, pricing models, and go-to-market strategies
- Identified high-growth industry verticals and priority use cases
- Supported product positioning and commercialization planning
Smart Manufacturing AI Market Entry and Expansion Strategy for a Software or Automation Company
- Assessment of regional adoption trends for AI in quality inspection, production optimization, and supply chain analytics
- Analysis of customer requirements, technology preferences, and deployment models (cloud, edge, and on-premise)
• Identified attractive regional markets and customer segments for expansion
• Optimized solution development and pricing strategies
About the Author(s)
Next Generation Technologies Research Team
Technology · Next Generation TechnologiesThis report was authored by the next generation technologies research team at Grand View Research - comprising two research analysts, one senior research analyst, and one industry expert - with specialized expertise in the next generation technologies segment of the technology industry. All findings are based on proprietary technology databases, executive interviews, and regulatory analysis, subject to internal peer review prior to publication.
Last Updated:
Speak to Analyst

Customize this report to your needs - add regions, segments, or data points, with 20% free customization.
Or view our licence options:


ISO 9001:2015 & 27001:2022 Certified
We are GDPR and CCPA compliant! Your transaction & personal information is safe and secure. For more details, please read our privacy policy.


