
- Home
- »
- HVAC & Construction
- »
-
Asia Pacific Air Conditioning Systems Market Size, Growth Report, 2026-2033GVR Report cover

Asia Pacific Air Conditioning Systems Market (2026 - 2033)
Size, Share & Trends Analysis Report By Product Type (Window ACs, Split ACs, Multi-split ACs, Portable ACs, Centralized ACs), By System Type, By Technology, By Distribution Channel, By End Use, By Region, And Segment Forecasts
Market Size, 2025
$60.9BMarket Estimate, 2026
$66.0BMarket Forecast, 2033
$113.9BCAGR, 2026–2033
8.1%Asia Pacific Air Conditioning Systems Market Summary
The Asia Pacific air conditioning systems market size was estimated at USD 60.9 billion in 2025 and is projected to grow from USD 66.0 billion in 2026 to USD 113.9 billion by 2033, growing at a CAGR of 8.1% from 2026 to 2033. China dominated the APAC air-conditioning systems market, accounting for approximately 45.0% of revenue in 2025. Market growth is primarily driven by rising temperatures, rapid urbanization, expanding construction activities, and increasing demand for energy-efficient indoor cooling and comfort solutions across residential, commercial, and industrial sectors.
Key Market Trends & Insights
- By product type: The ductless mini-split systems segment dominated the Asia Pacific air conditioning systems market and accounted for the largest revenue share of 50.1% in 2025.
- By technology: The inverter segment dominated the Asia Pacific air conditioning systems market and accounted for the largest revenue share of 71.3% in 2025.
- By distribution channel: The offline ACs segment dominated the Asia Pacific air conditioning systems market and accounted for the largest revenue share of 78.5% in 2025.
- By end use: The residential segment dominated the Asia Pacific air conditioning systems market and accounted for the largest revenue share of 47.1% in 2025.
Regional Insights
- Largest regional market: China (Approximately 45.0% revenue share, 2025)
- Fastest-growing regional market: India (highest CAGR, 2026-2033)
Market Size & Forecast
- Market size in 2025: USD 60.9 Billion
- Estimated market size in 2026: USD 66.0 Billion
- Projected market size by 2033: USD 113.9 Billion
- CAGR (2026-2033): 8.1%
Prism AI by Grand View Research Free to tryAsk a question about the asia pacific air conditioning systems marketTry asking✓Every figure cited from GVR research Prefer the report? Download free sample →
In addition, the expansion of smart cities and improving living standards across China, India, and Southeast Asian economies are driving the adoption of air conditioning systems. Increasing urbanization and higher disposable incomes are encouraging consumers to invest in advanced cooling solutions that offer greater comfort and energy efficiency. As electricity costs continue to rise, demand is shifting toward inverter-based air conditioning systems that deliver superior cooling performance while reducing power consumption. According to a study published in Applied Energy, smart city initiatives in China have improved energy efficiency through technological innovation and optimized resource utilization. The expansion of smart infrastructure and digitally connected buildings is increasing the demand for advanced HVAC systems capable of delivering automated climate control, efficient cooling, and intelligent energy management. This trend reflects the industry's growing emphasis on sustainable and energy-efficient cooling technologies.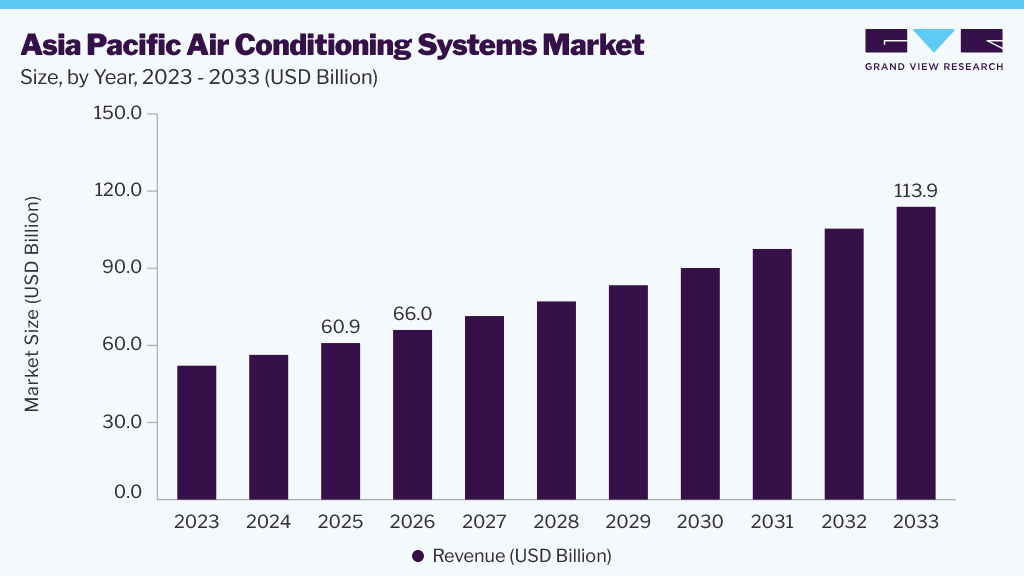 Source: Grand View Research, IR Documents, Primary Interviews, Paid DatabasesTo learn more about this report,
 Download Free Sample Report
Moreover, the adoption of smart and connected air conditioning systems is emerging as a key trend in the Asia Pacific market. Consumers and businesses are increasingly seeking intelligent climate control solutions that provide enhanced convenience, operational efficiency, and lower energy consumption. To address this demand, manufacturers are integrating technologies such as artificial intelligence, Internet of Things (IoT), and smart sensors to enable remote monitoring, personalized temperature control, and improved energy management. These advanced systems are gaining popularity in modern homes, offices, hotels, and commercial buildings as users seek convenient, cost-effective cooling solutions. These advanced solutions are gaining widespread adoption across residential buildings, offices, hotels, and commercial facilities. For instance, LG has introduced its AI DUALCOOL air conditioning series with AI-based optimization features, including AI Logic, AI sensors, and smart energy management capabilities that automatically optimize cooling performance based on environmental conditions and room occupancy, helping improve user comfort while reducing electricity consumption. This highlights the growing shift toward intelligent, digitally connected air conditioning systems across the region.
Sustainability and environmental regulations are also shaping the development of air conditioning systems across the Asia Pacific. Governments and industries are focusing on reducing energy consumption and greenhouse gas emissions, encouraging manufacturers to introduce systems that use low-global-warming-potential refrigerants and improved-efficiency technologies. The growing demand for green buildings and energy-efficient infrastructure is further supporting the adoption of advanced HVAC solutions. Additionally, the expansion of commercial infrastructure, data centers, healthcare facilities, and industrial facilities is increasing demand for high-capacity and centralized air conditioning systems, creating new growth opportunities for market participants.
Analyst Perspective
The Asia Pacific air conditioning systems market is witnessing steady growth owing to rising temperatures, rapid urbanization, increasing construction activities, and growing demand for indoor comfort solutions across residential, commercial, and industrial sectors. The market is witnessing growing adoption of energy-efficient inverter systems, smart air conditioners, IoT-enabled HVAC solutions, and AI-based cooling technologies as consumers and businesses focus on reducing energy consumption while improving cooling performance. Although challenges such as high installation costs, increasing energy-efficiency requirements, and the need for regular maintenance persist, advancements in smart sensors, connected HVAC platforms, and eco-friendly refrigerant technologies continue to create new opportunities. Companies that adopt innovative, energy-efficient, and digitally connected air conditioning solutions are expected to benefit from the market’s long-term growth by addressing rising cooling demand and supporting sustainable infrastructure development across the Asia Pacific.
Product Type Insights
Ductless mini-split systems dominated the Asia Pacific air conditioning systems market, accounting for 50.1% of the revenue share in 2025. The segment's dominance is primarily attributed to the region's high concentration of residential apartments, rapid urbanization, and the increasing preference for energy-efficient cooling solutions across China, Japan, South Korea, India, and Southeast Asia. Unlike centralized systems, ductless mini-split units are well-suited to high-rise residential buildings and small commercial establishments, where installing extensive ductwork is often impractical or cost-prohibitive. Their ability to provide independent zone cooling, lower installation costs, and improved energy efficiency has made them the preferred choice for both new construction and retrofit projects. In addition, the increasing penetration of smart homes is driving demand for connected mini-split systems equipped with AI-powered temperature optimization, occupancy sensing, Wi-Fi connectivity, and remote monitoring capabilities. For instance, LG's AI DUALCOOL series and Daikin's inverter split air conditioners integrate intelligent energy management and smart control features to optimize cooling performance. Such innovations are accelerating consumer adoption of ductless mini-split systems, thereby reinforcing the segment's market leadership.
Package air conditioners are expected to register the fastest growth in the Asia Pacific air conditioning systems market during the forecast period, driven by the rapid expansion of commercial infrastructure and rising investments in institutional facilities across the region. Growing construction of retail outlets, educational institutions, healthcare facilities, hotels, warehouses, and industrial facilities in countries such as China, India, Indonesia, Vietnam, and Thailand is increasing demand for cost-effective, high-capacity cooling solutions. Package air conditioners offer an integrated design that combines major system components into a single unit, enabling faster installation, lower maintenance requirements, and reduced installation costs compared with conventional centralized systems. The segment is also benefiting from the expansion of smart commercial buildings and the modernization of existing infrastructure, as building owners increasingly replace aging cooling equipment with energy-efficient packaged systems. The manufacturers, such as Daikin, Carrier, Trane Technologies, and Johnson Controls, continue to introduce high-efficiency packaged rooftop and packaged air-conditioning solutions with advanced controls and low-global-warming-potential refrigerants to address the evolving cooling requirements of commercial and institutional customers across the Asia-Pacific region.
Technology Insights
The inverter technology segment dominated the Asia Pacific air conditioning systems market, accounting for the largest revenue share of 71.3% in 2025. The segment growth is driven by increasing consumer awareness regarding energy savings, rising electricity costs, and government initiatives promoting efficient appliances. Inverter-based systems provide better temperature control, lower power consumption, and improved operational efficiency compared with conventional systems, supporting widespread adoption across residential and commercial applications. The increasing focus on reducing carbon emissions and the adoption of smart home technologies are encouraging consumers and businesses to shift toward inverter-based air conditioning systems. Manufacturers are continuously introducing advanced inverter models with IoT connectivity and AI-based energy optimization features, further supporting market growth. For instance, LG’s Dual Inverter AC technology has gained prominence for its ability to adjust the compressor speed based on cooling requirements, thereby improving energy efficiency, providing faster cooling, and maintaining consistent indoor temperatures.
The non-inverter technology segment is expected to experience steady demand in the Asia Pacific due to its lower upfront cost, simple operation, and strong appeal among price-sensitive consumers. These systems continue to be widely adopted across developing economies, particularly in the residential sector, where purchase affordability remains a key consideration. Non-inverter air conditioners provide reliable cooling performance, lower initial investment, and are widely available through established distribution networks. Although energy-efficiency concerns are encouraging a gradual shift toward inverter models, non-inverter systems continue to maintain a stable market presence due to their cost-effectiveness, easier maintenance, and adoption in regions where consumers prioritize affordable cooling over advanced energy-saving features.
Distribution Channel Insights
The offline channels segment dominated the Asia Pacific air conditioning systems market, accounting for the largest revenue share of 78.5% in 2025. Consumers continue to prefer offline stores due to the availability of product demonstrations, professional consultation, installation support, and reliable after-sales services. Given the high-value nature of air conditioning systems, many buyers prefer to evaluate product features, cooling performance, and energy efficiency in person before making a purchase. Brand-authorized dealers and retail networks remain important channels for purchasing air conditioning systems, particularly for residential and commercial customers who seek end-to-end installation and maintenance support.
The online channels segment is anticipated to register the fastest CAGR from 2026 to 2033. The growth is driven by increasing e-commerce penetration, evolving digital purchasing behavior, attractive promotional offers, and the expanding availability of professional installation services. Consumers are increasingly comparing models online and purchasing through digital platforms due to instant price comparisons across competitors and wider product choices. Another factor driving this segment is the doorstep deliveries offered by almost every AC brand today, which supports the at-home-shopping convenience for customers.
End Use Insights
The residential segment dominated the Asia Pacific air conditioning systems market, accounting for the largest revenue share of 47.1% in 2025. Growth in the segment is primarily driven by rising disposable incomes, rapid urbanization, expanding residential construction, and increasing demand for indoor comfort solutions. Rising temperatures, improving living standards, and the growing adoption of energy-efficient air conditioning systems are further supporting residential demand across the region. Countries such as China and India continue to witness strong adoption of air conditioners, fueled by large-scale housing developments, increasing household electrification, and a growing middle-class population.
The commercial segment is anticipated to register strong growth during the forecast period of 2026 to 2033. The growth is attributed to the expansion of offices, shopping malls, hotels, healthcare facilities, and data centers across the Asia Pacific. Increasing investments in green buildings, smart commercial infrastructure, and energy-efficient HVAC systems are further accelerating demand for advanced commercial air conditioning solutions. Manufacturers are responding by introducing high-efficiency systems that reduce energy consumption while meeting increasingly stringent environmental regulations. For instance, in January 2026, Mitsubishi Electric launched its City Multi R32 YXM VRF air conditioning range, designed specifically to provide sustainable heating and cooling solutions for commercial buildings. This development reflects the growing adoption of high-efficiency VRF systems in commercial infrastructure as businesses prioritize energy management, sustainability, and flexible climate control.
Regional Insights
China Air Conditioning Systems Market Trends
The China air conditioning systems market dominated the Asia Pacific market, accounting for the largest revenue share of 45.0% in 2025. The country’s dominance is supported by large-scale residential and commercial construction, a strong manufacturing base, and consistent demand for cooling solutions. As one of the world's largest producers and consumers of air conditioning systems, China benefits from a well-established supply chain, extensive production capacity, and continuous investments in energy-efficient technologies. Furthermore, government initiatives promoting sustainable development and stricter energy-efficiency regulations are accelerating the adoption of advanced air conditioning systems. For instance, in September 2025, the China Household Electrical Appliances Association (CHEAA) introduced new energy-efficiency and carbon-footprint standards for room air conditioners, including the T/CHEAA standards for carbon-footprint accounting of household air conditioners. This reflects the growing focus on energy-efficient air conditioning solutions in China and supports the expansion of advanced cooling systems across residential and commercial applications.
India Air Conditioning Systems Market Trends
The India market is anticipated to register the fastest CAGR during the forecast period of 2026 to 2033. Growth is driven by rising temperatures, rising disposable income, rapid urban development, and relatively low air conditioner penetration compared with other major Asia-Pacific markets. Government initiatives promoting energy efficiency, domestic manufacturing, and infrastructure development are further supporting market expansion. For instance, the U.S. Department of Commerce has highlighted that government initiatives such as Make in India, Atmanirbhar Bharat, and Production Linked Incentive (PLI) schemes are supporting the development of an energy-efficient HVAC ecosystem in the country.
Key Asia Pacific Air Conditioning Systems Company Insights
The major players operating across the Asia Pacific air conditioning systems market are focused on the adoption of inorganic strategic initiatives such as mergers, partnerships, acquisitions, etc.
Key Asia Pacific Air Conditioning Systems Companies
-
DAIKIN INDUSTRIES Ltd.
-
Carrier Global Corporation
-
Midea Group Co., Ltd.
-
Mitsubishi Electric Corporation
-
LG Electronics Inc.
-
Panasonic Holdings Corporation
-
Samsung Electronics Co., Ltd.
-
Haier Smart Home Co., Ltd.
-
Johnson Controls International plc
-
Trane Technologies plc
Recent Developments
-
In June 2026, Daikin launched the VKM-JM decentralized fresh air unit as part of its expanding R-32 VRV portfolio for commercial applications. The new system combines fresh-air treatment, humidity control, heat recovery, and filtration in a single solution designed for offices, retail spaces, and hospitality buildings. The launch addresses the growing demand for energy-efficient HVAC systems that enhance indoor air quality while reducing the cooling load and operating costs of commercial air conditioning systems.
-
In February 2026, Daikin introduced its Vertical DX Air Handling Unit designed for large indoor spaces such as warehouses, logistics centers, sports facilities, and multipurpose halls. The system is compatible with Daikin VRV and ERA condensing units and focuses on improving comfort, energy efficiency, and flexible installation for large-scale commercial applications. The product launch reflects the increasing adoption of advanced centralized and VRF-based cooling solutions across commercial and industrial infrastructure.
-
In May 2025, Daikin introduced a new VRV 5 floor-standing unit featuring R-32 refrigerant technology for commercial buildings. The product was developed to support lower-carbon HVAC solutions and provides flexible installation options for smaller commercial spaces while maintaining energy efficiency and compliance with updated refrigerant standards. This launch reflects the industry shift toward sustainable refrigerant technologies and high-efficiency commercial air conditioning systems.
-
In March 2025, LG Electronics unveiled the ARTCOOL AI Air residential air conditioner, combining AI-driven comfort features with premium design elements. The product focuses on personalized cooling, improved energy efficiency, and enhanced user convenience through intelligent control technologies, supporting the rising consumer demand for smart home air conditioning solutions.
-
In January 2025, LG Electronics introduced the DUALCOOL AI Air conditioner with enhanced AI-based cooling technologies. The system uses AI algorithms, temperature sensing, and user pattern analysis through the ThinQ platform to optimize airflow direction, cooling performance, and energy efficiency. This launch demonstrates the growing integration of artificial intelligence, smart sensors, and IoT-enabled connectivity into residential air conditioning systems across the Asia-Pacific region.
Asia Pacific Air Conditioning Systems Market Report Scope
Report Attribute
Details
Market size in 2025
USD 60.9 billion
Estimated market size in 2026
USD 66.0 billion
Projected market size by 2033
USD 113.9 billion
Growth rate
CAGR of 8.1% from 2026 to 2033
Base year for estimation
2025
Actual data
2021 - 2024
Forecast period
2026 - 2033
Quantitative units
Revenue in USD billion, and CAGR from 2026 to 2033
Report coverage
Revenue forecast, company ranking, competitive landscape, growth factors, and trends
Segments covered
Product type, system type, technology, distribution channel, end use, and region
Country Scope
China; India; Japan; Australia; South Korea
Key companies profiled
DAIKIN INDUSTRIES, Ltd.; Carrier Global Corporation; Midea Group Co., Ltd.; Mitsubishi Electric Corporation; LG Electronics Inc.; Panasonic Holdings Corporation; Samsung Electronics Co., Ltd.; Haier Smart Home Co., Ltd.; Johnson Controls International plc; Trane Technologies plc
Customization scope
Free report customization (equivalent up to 8 analysts working days) with purchase. Addition or alteration to country, regional & segment scope.
Pricing and purchase options
Avail of customized purchase options to meet your exact research needs. Explore purchase options
Asia Pacific Air Conditioning Systems Market Report Segmentation
This report forecasts revenue growth at regional and country levels and provides an analysis of the latest industry trends in each of the sub-segments from 2021 to 2033. For the purpose of this study, Grand View Research has segmented the Asia Pacific air conditioning systems market report on the basis of product type, system type, technology, distribution channel, end use, and region:
-
Product Type Outlook (Revenue, USD Billion, 2021 - 2033)
-
Package Air Conditioners
-
Split Air Conditioning Systems
-
Ductless Mini-Split Systems
-
-
Technology Outlook (Revenue, USD Billion, 2021 - 2033)
-
Inverter
-
Non-inverter
-
-
Distribution Channel Outlook (Revenue, USD Billion, 2021 - 2033)
-
Online
-
Offline
-
-
End Use Outlook (Revenue, USD Billion, 2021 - 2033)
-
Residential
-
Commercial
-
Industrial
-
-
Regional Outlook (Revenue, USD Million, 2021 - 2033)
-
Asia Pacific
-
Japan
-
China
-
India
-
Australia
-
South Korea
-
-
Frequently Asked Questions About This Report
The Asia Pacific air conditioning systems market size was valued at USD 60.9 billion in 2025 and is estimated at USD 66.0 billion in 2026.
The Asia Pacific air conditioning systems market is expected to grow at a CAGR of 8.1% from 2026 to 2033, reaching USD 113.9 billion in 2033
Key players in the market include DAIKIN INDUSTRIES, Ltd.; Carrier Global Corporation; Midea Group Co., Ltd.; Mitsubishi Electric Corporation; LG Electronics Inc.; Panasonic Holdings Corporation; Samsung Electronics Co., Ltd.; Haier Smart Home Co., Ltd.; Johnson Controls International plc; Trane Technologies plc, and others
China dominated with an approximately 45.0% revenue share in 2025.
The ductless mini-split systems segment accounted for the largest revenue share of 50.1% in 2025
About the Author(s)
HVAC & Construction Research Team
Technology · HVAC & ConstructionThis report was authored by the hvac & construction research team at Grand View Research - comprising two research analysts, one senior research analyst, and one industry expert - with specialized expertise in the hvac & construction segment of the technology industry. All findings are based on proprietary technology databases, executive interviews, and regulatory analysis, subject to internal peer review prior to publication.
Last Updated:
Speak to Analyst

Customize this report to your needs - add regions, segments, or data points, with 20% free customization.
Or view our licence options:


ISO 9001:2015 & 27001:2022 Certified
We are GDPR and CCPA compliant! Your transaction & personal information is safe and secure. For more details, please read our privacy policy.


