
- Home
- »
- Pharmaceuticals
- »
-
Atopic Dermatitis Drugs Market Size And Share Report, 2033GVR Report cover

Atopic Dermatitis Drugs Market (2026 - 2033)
Size, Share & Trends Analysis Report By Drug Class (Corticosteroids. Biologics), By Route Of Administration (Topical, Parenteral), By Distribution Channel, By Region, And Segment Forecasts
Market Size, 2025
$19.4BMarket Estimate, 2026
$21.3BMarket Forecast, 2033
$37.3BCAGR, 2026–2033
8.3%Atopic Dermatitis Drugs Market Summary
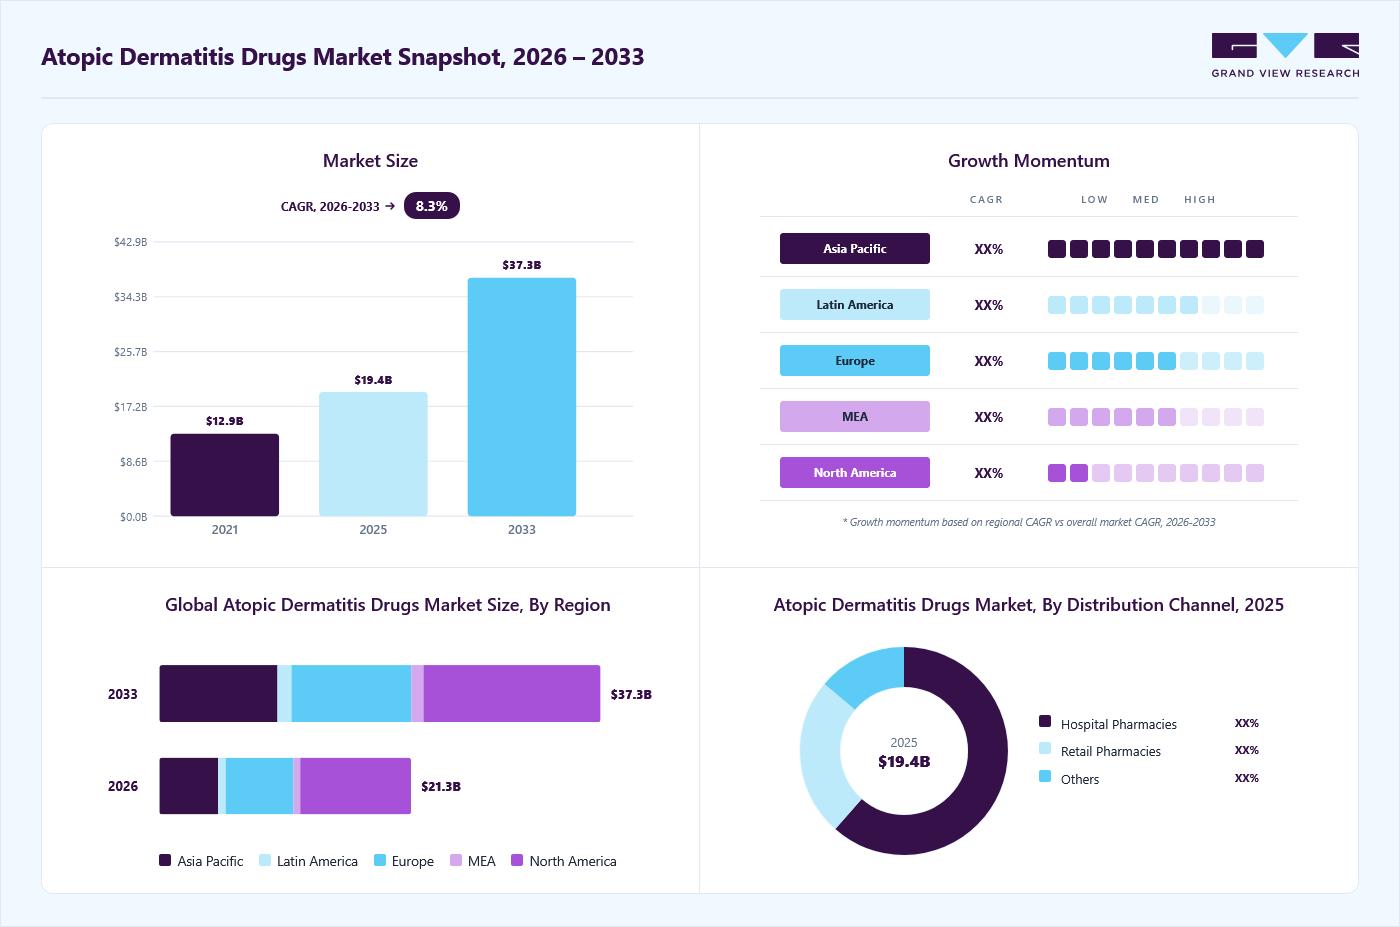
The global atopic dermatitis drugs market size was valued at USD 19.4 billion in 2025 and is projected to grow from USD 21.3 billion in 2026 to USD 37.3 billion by 2033, growing at a CAGR of 8.3% from 2026 to 2033. The market in North America dominated with a revenue share of 44.6% in 2025. This growth can be attributed to the prevalence of atopic dermatitis, especially in children and adults, which is on the rise globally.
 Source: Grand View Research, IR Documents, Primary Interviews, Paid DatabasesTo learn more about this report,
 Download Free Sample Report
Key Market Trends & Insights
- By drug class: Biologics segment held the largest market share of 40.9% in 2025.
- By route of administration: Topical segment held the largest market share of 38.9% in 2025.
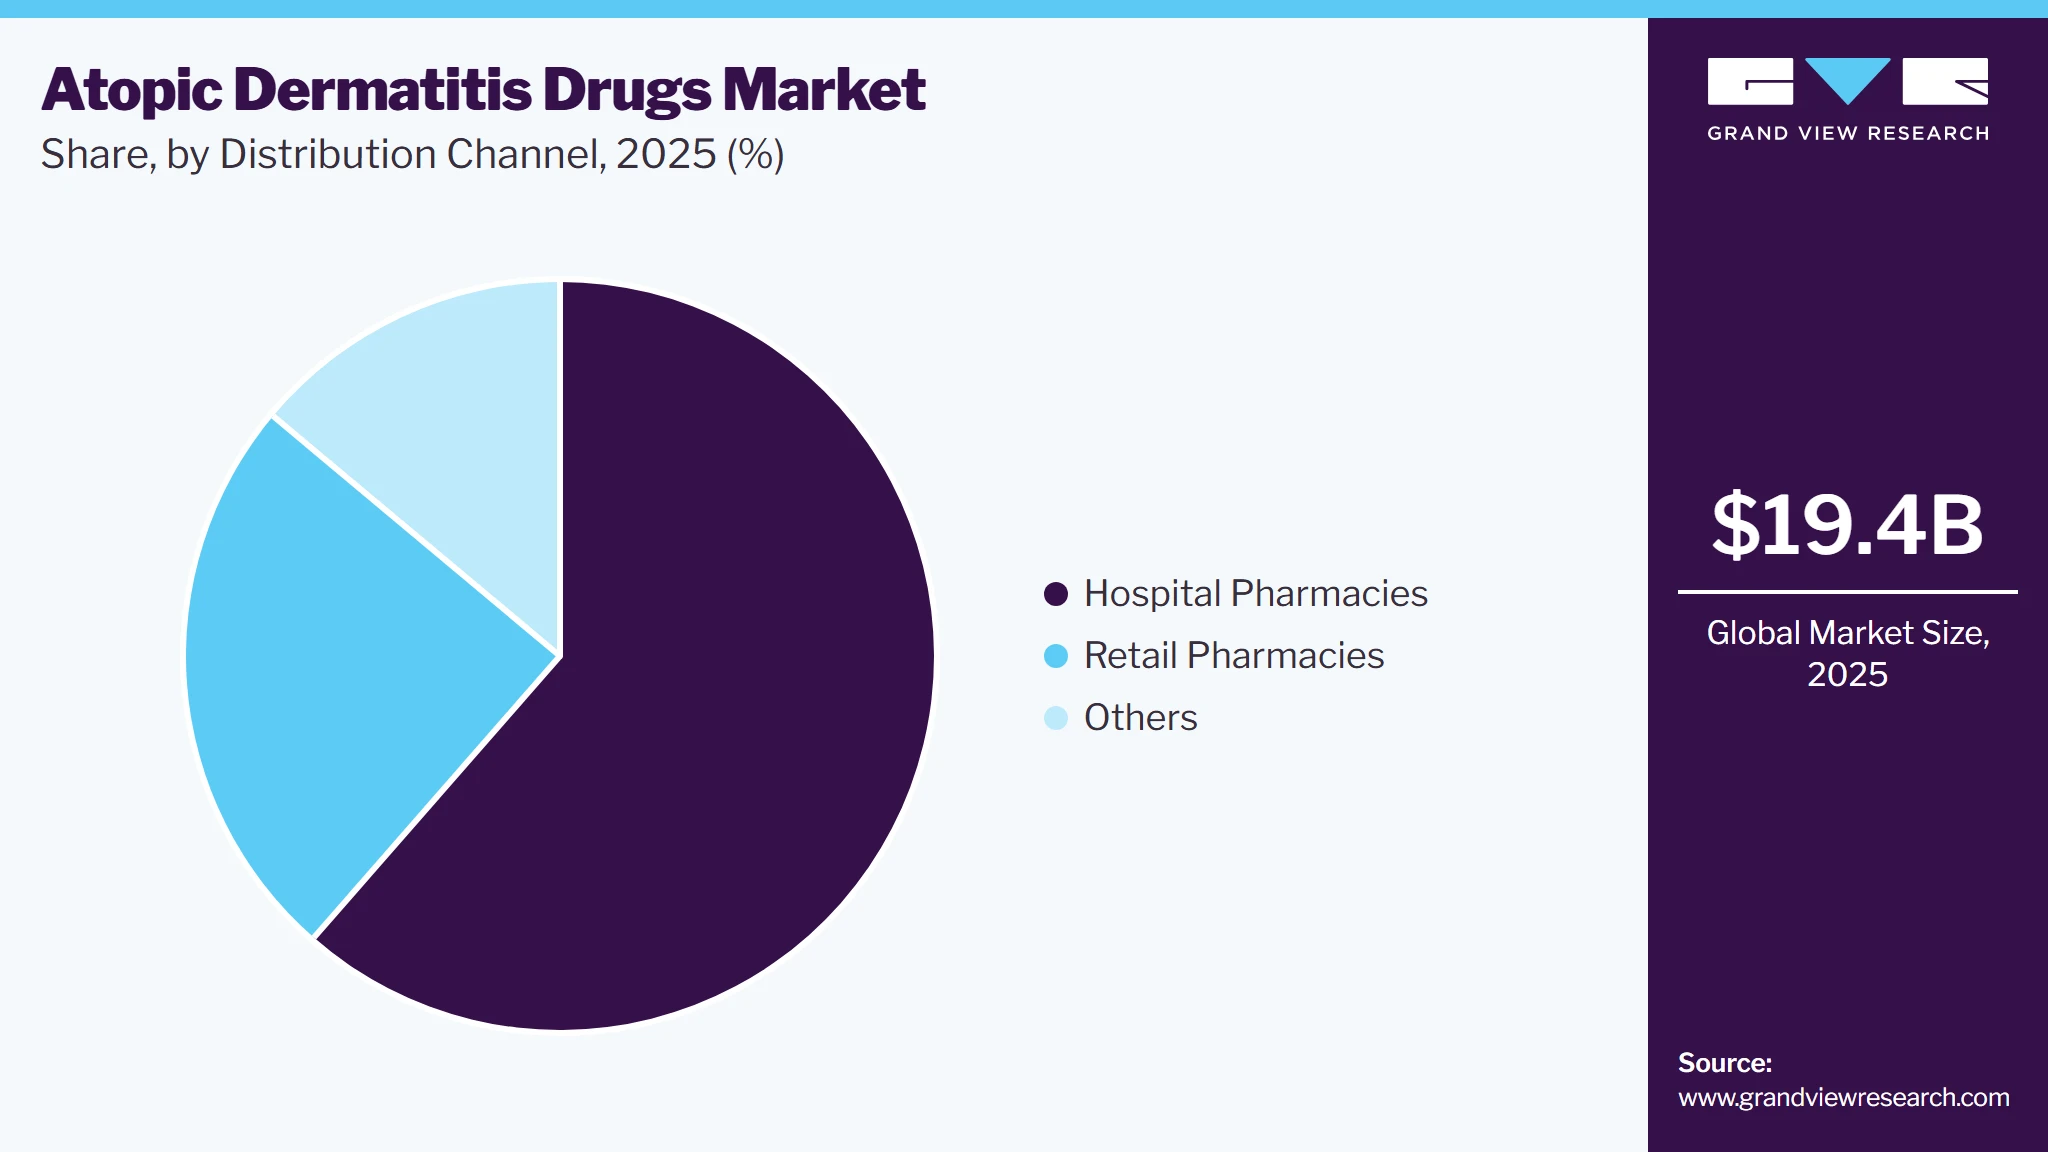
- By distribution channel: Hospital pharmacies held the largest market share of 61.4% in 2025.
Regional Highlights
- Largest regional market: North America (44.6% revenue share, 2025)
- Fastest-growing regional market: Asia Pacific (highest CAGR, 2026-2033)
- The atopic dermatitis drugs industry in the U.S. held the largest revenue share in 2025.
Market Size & Forecast
- Market size in 2025: USD 19.4 Billion
- Estimated market size in 2026: USD 21.3 Billion
- Projected market size by 2033: USD 37.3 Billion
- CAGR (2026-2033): 8.3%
Three ways to get this report
Buy it, customize it, or ask a question.Ask an Analyst
Analyst response in 1 business day
- AccessReport author, directly
- Reply timeWithin 1 working day
- No sales callDirect answer only
- FormatEmail reply
- CostFree, no cost
Get the Full Report
What the study covers
- FormatsPDF · Excel · Dashboard
- Timeline2026–2033 annual, 2025 base
- Coverage20+ countries, 5 regions
- Companies10+ key players profiled
Customize the Report
20% free customization
- IncludeCountries, segments, points
- TailorTo your product definition
- ExtendDeeper competitor detail
- OrA fully bespoke study
- Turnaround5–10 working days
Factors like environmental changes, pollution, and urban lifestyles contribute to this increase, leading to higher demand for effective treatments. Atopic dermatitis is a chronic condition that often requires long-term management, creating a consistent demand for therapeutic solutions. Atopic dermatitis, a persistent inflammatory skin disorder, is estimated to affect over 200 million people globally, including around 20% of children and 10% of adults, according to the American Academy of Dermatology's 2023 data. While it predominantly occurs in childhood and can extend into adulthood, approximately 25% of adult cases are identified as adult onset. This trend is likely to drive the development of innovative therapeutic options, including biologics and targeted therapies, as existing treatments may not fully address the needs of all patient segments.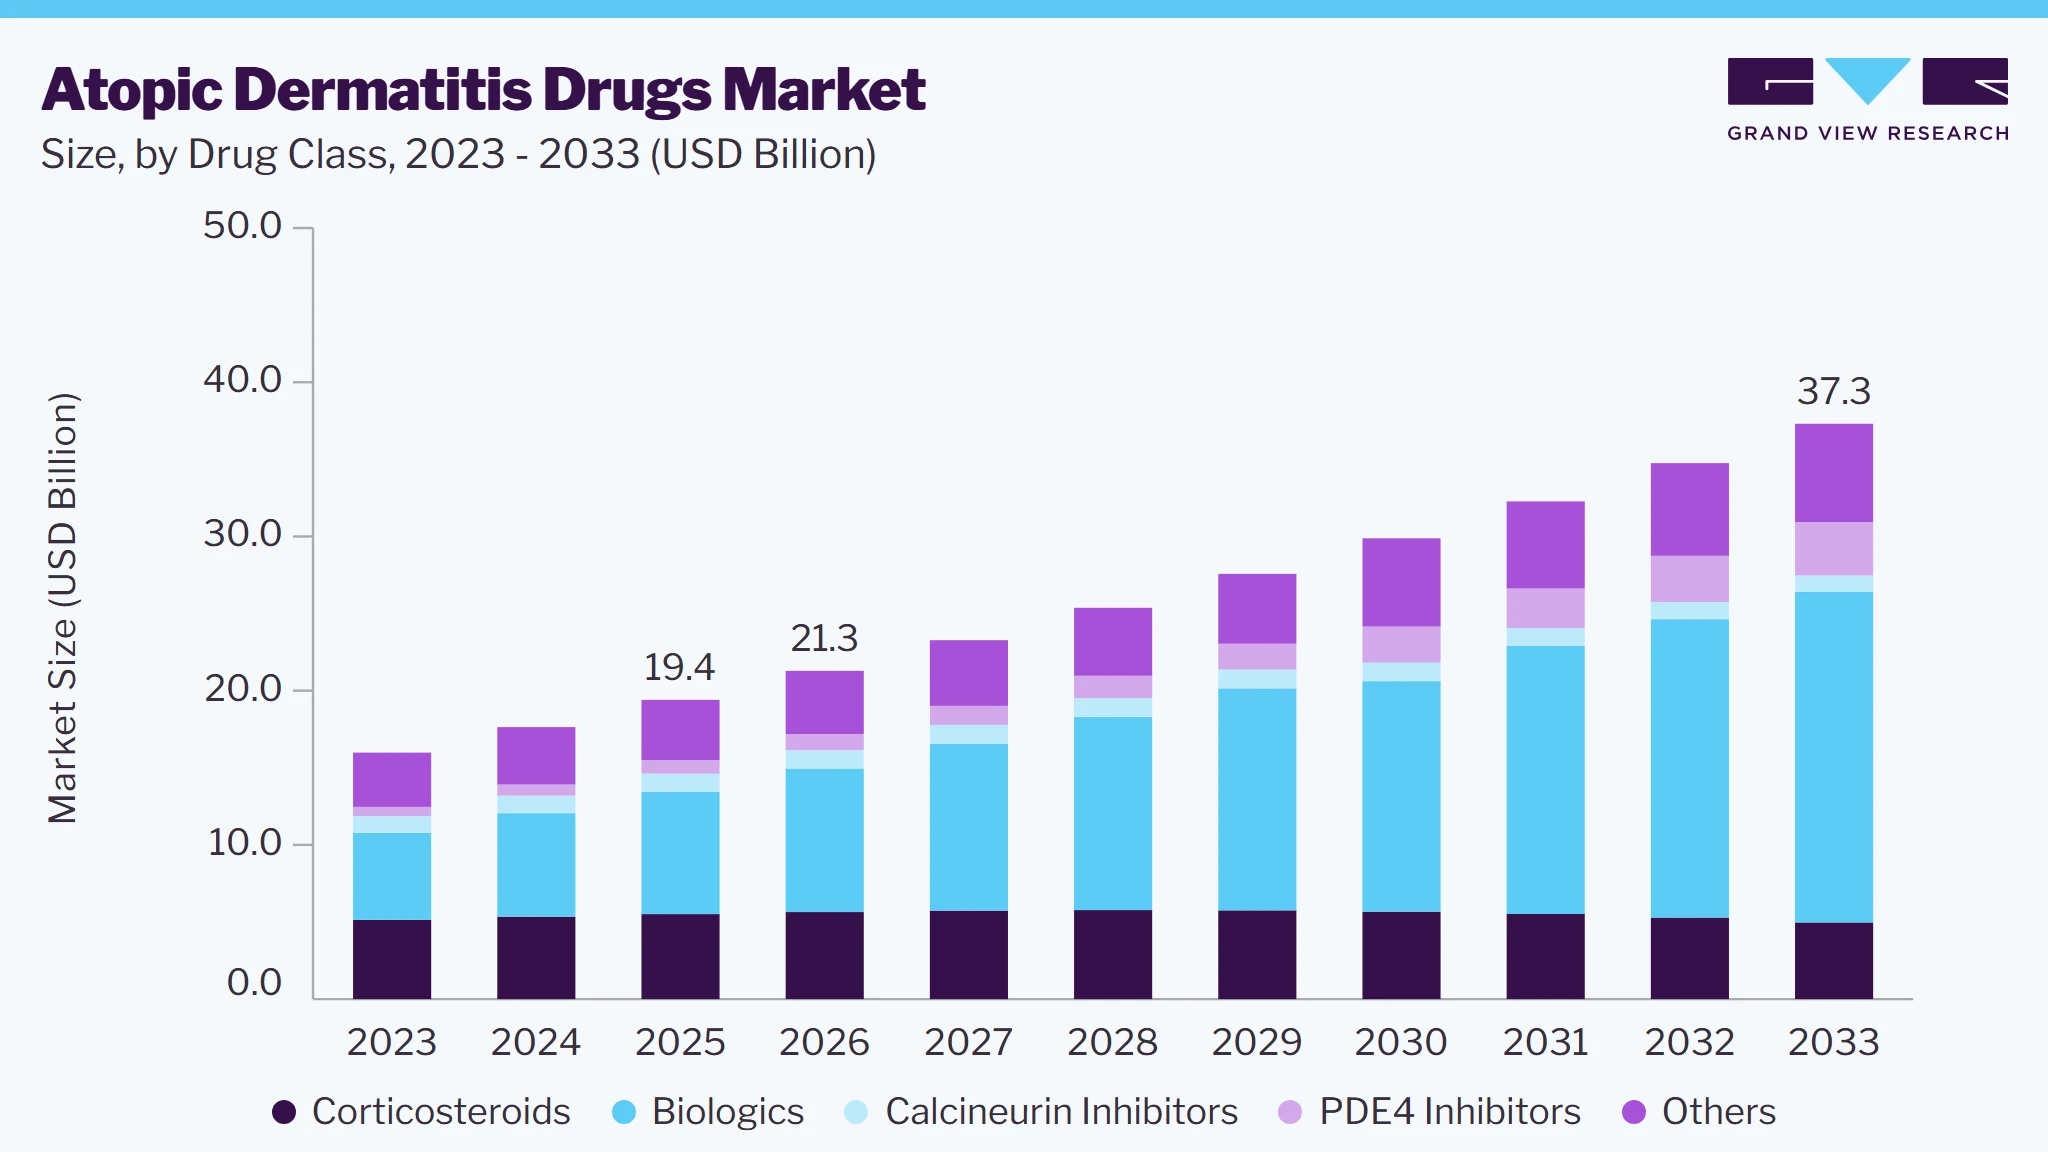 To learn more about this report, Download Free Sample Report
In addition, according to the European Academy of Dermatology & Venereology 2023 estimate, it affected roughly 10-15% of children and 3-5% of adults in Europe, although prevalence rates can differ across regions. It tends to be more common in urban and industrialized areas than in rural locations, likely due to environmental and lifestyle influences. However, the exact causes are still not fully understood. This could expand treatment pipelines, including non-steroidal options and therapies targeting the underlying immune mechanisms. This would position the atopic dermatitis treatment market for significant growth in the coming years.
Atopic dermatitis (AD) is typically managed with a combination of emollients and topical anti-inflammatory treatments, which are effective for most patients. However, severe cases often require systemic therapies for better disease control. For instance, Cyclosporin A, a fast-acting immunosuppressive drug, is approved in several European countries and is often used for more severe cases. In contrast, slower-acting immunosuppressive agents such as Methotrexate, Azathioprine, and Mycophenolate are reserved for more complex cases and are typically prescribed by specialists. Furthermore, Dupilumab, a biologic recently approved in the EU, represents a novel treatment approach. It specifically targets the overactive parts of the immune system in AD patients, offering a more targeted and potentially safer option for disease management.
Market Dynamics
The atopic dermatitis market is experiencing steady growth driven by the increasing prevalence of chronic inflammatory skin conditions, greater disease awareness, and improved access to diagnosis and treatment. Demand for advanced therapies is rising as healthcare providers increasingly adopt biologics and targeted immunomodulators that offer better disease control than conventional treatment approaches. The market is also benefiting from expanding treatment eligibility across pediatric and adult patient populations. Regulatory approvals and product label expansions continue to enhance treatment availability and strengthen competition among manufacturers. For instance, in 2025, ongoing commercialization and market expansion activities for newly approved targeted therapies, including biologics addressing key inflammatory pathways associated with atopic dermatitis, contributed to broader patient access and treatment adoption across major healthcare markets. Furthermore, continued investment in research and development is supporting the advancement of novel therapies focused on reducing inflammation and persistent itch symptoms. While treatment costs and long term safety monitoring remain important considerations, favorable reimbursement trends and increasing physician confidence in targeted therapies are supporting sustained market growth.
The increasing adoption of targeted biologic therapies is a major driver of growth in the atopic dermatitis market. Traditional treatment approaches such as topical corticosteroids and immunosuppressants often provide limited long term disease control for patients with moderate to severe atopic dermatitis. As understanding of the underlying immune pathways has improved, biologic therapies targeting specific cytokines involved in inflammation have become an important part of treatment strategies. These therapies offer improved efficacy, reduced disease flare frequency, and better quality of life outcomes, leading to greater acceptance among healthcare professionals and patients. Expanding regulatory approvals across pediatric and adult populations are further increasing the eligible treatment population. In addition, growing physician familiarity with biologics and increasing inclusion in clinical treatment guidelines are supporting market expansion. Healthcare systems in developed markets are also improving reimbursement pathways for advanced therapies, encouraging broader adoption. For instance, in 2025, the continued global expansion of Dupixent for multiple atopic dermatitis patient groups strengthened the role of biologics as a standard treatment option for moderate to severe disease. The success of biologics has encouraged further investment in immunology research and development, creating a favorable environment for sustained market growth and innovation across the atopic dermatitis treatment landscape.
Safety concerns associated with advanced systemic therapies remain a significant restraint for the atopic dermatitis market. While biologics and Janus kinase inhibitors have demonstrated meaningful clinical benefits, long term safety considerations continue to influence treatment decisions among physicians, patients, and regulatory authorities. The requirement for ongoing patient monitoring can increase treatment complexity and healthcare costs. Concerns regarding infections, cardiovascular events, thrombotic complications, and other adverse effects have resulted in stricter prescribing practices for certain therapies. These factors can limit treatment uptake, particularly among patients with existing comorbidities or those considered at higher risk for adverse events. Furthermore, healthcare providers often evaluate the benefit risk profile carefully before initiating advanced systemic treatments, which may delay therapy adoption. Regulatory agencies continue to emphasize safety surveillance and post marketing monitoring requirements for immunomodulatory therapies. For instance, regulatory warnings associated with JAK inhibitor therapies have led clinicians to apply more selective prescribing criteria and enhanced patient monitoring protocols. Such measures, while important for patient safety, can create barriers to wider adoption and may encourage some physicians to favor established treatment options before progressing to newer therapies. Consequently, safety related considerations remain an important factor affecting market expansion and treatment utilization.
The development of novel therapies targeting specific inflammatory and itch related pathways presents a significant opportunity in the atopic dermatitis market. Despite recent advances, a substantial proportion of patients continue to experience persistent symptoms, inadequate treatment responses, or recurrent disease flares. This creates demand for therapies with differentiated mechanisms of action capable of addressing unmet clinical needs. Pharmaceutical companies are increasingly focusing on pathways associated with inflammation, skin barrier dysfunction, and chronic pruritus, which is one of the most burdensome symptoms of the disease. Growing investment in precision medicine and biomarker driven treatment approaches is also supporting innovation. In addition, expanding awareness of disease burden among healthcare providers and patients is improving diagnosis rates and encouraging earlier intervention. For instance, in 2025, the commercialization and market expansion of nemolizumab, a therapy targeting the IL 31 pathway associated with itch signaling, highlighted the industry's focus on addressing symptoms that are not fully controlled by existing treatments. Continued advancement of such therapies is expected to broaden treatment options and create new revenue opportunities. As clinical evidence accumulates and access improves, these innovative therapies have the potential to reshape treatment paradigms and support long term market growth.
Analyst Perspective
The atopic dermatitis market is undergoing a transition from conventional anti inflammatory therapies toward targeted biologics and advanced immunomodulators that offer improved disease control and patient outcomes. Increasing diagnosis rates, growing awareness of chronic inflammatory skin disorders, and expanding access to innovative therapies are supporting market growth. Pharmaceutical companies are actively investing in biologics, JAK inhibitors, and novel pathway specific treatments to address unmet clinical needs, particularly in moderate to severe disease. Continued regulatory approvals, pediatric label expansions, and broader reimbursement coverage are expected to enhance treatment adoption. However, pricing pressures, long term safety considerations, and competitive intensity will remain important factors influencing future market dynamics.
Drug Class Insights
Based on drug class, the biologics segment led the market with the largest revenue share of 40.9% in 2025. The growth of the biologics segment is augmented by rising demand for biologics due to high efficacy, rising product approvals, and availability of a robust pipeline of biologic drugs for atopic dermatitis. Biologics has a significant clinical advantage over conventional topical treatments, as they target the inflammatory mechanisms fostering the disease rather than just addressing the symptoms. The high specificity of these drugs gives them a competitive edge. For instance, in February 2024, Galderma announced that the U.S. FDA had accepted its Biologics License Applications (BLA) for nemolizumab, a first-in-class investigational monoclonal antibody. Nemolizumab inhibits IL-31 signaling, providing safe and rapid relief from itch, the most distressing symptom of both prurigo nodularis and moderate to severe atopic dermatitis (AD) in adolescents and adults. Accepting BLA licenses for products is anticipated to open new avenues in the market.
The PDE4 segment is expected to register significant market growth during the forecast period owing to growing research and development in PDE4 drugs for treating atopic dermatitis. For instance, in September 2024, Arcutis Biotherapeutics, Inc. announced that JAMA Dermatology Journal published positive Phase 3 trial results from INTEGUMENT-1 and INTEGUMENT-2, showing that ZORYVE (roflumilast) cream significantly improved outcomes for mild to moderate atopic dermatitis (AD), including a statistically significant improvement in IGA Success. These results validate the efficacy and safety of ZORYVE in treating mild to moderate atopic dermatitis (AD), potentially increasing its adoption among dermatologists and boosting drug sales.
Route Of Administration Insights
Based on route of administration, the topical segment led the market with the largest revenue share of 38.9% in 2025. The high prescription rates and affordability of medications, combined with the safety and efficacy of topical treatments, contribute significantly to their widespread use. According to a study published in the Dermatology and Therapy Journal in June 2022, there were 176,458 pediatric patients diagnosed with atopic dermatitis (AD). Among these patients, 99.2% were treated with topical corticosteroids, while 5.1% were prescribed topical calcineurin inhibitors. In addition, 37.1% received potent topical corticosteroids, and 2.1% were administered systemic corticosteroids. These statistics highlight the dominance of topical corticosteroids in the treatment landscape for AD, underscoring their critical role in managing this condition effectively.
The parenteral segment is projected to experience the fastest growth in the atopic dermatitis drugs industry during the forecast period. This can be attributed to the increasing adoption of biologics, particularly for patients with severe disease, and the growing need for effective treatments in moderate to severe cases. In March 2024, Chugai Pharmaceutical Co., Ltd. announced that Maruho Co., Ltd. received regulatory approval from the Ministry of Health, Labour and Welfare (MHLW) for Mitchga (Nemolizumab) Subcutaneous Injection 30 mg. This humanized monoclonal antibody is indicated for treating pruritus associated with atopic dermatitis in children aged 6 to under 13 years and prurigo nodularis in adults and children aged 13 years and older, specifically when existing treatments are insufficiently effective in Japan. Thus, the approval of new parenteral administration drugs of AD is expected to boost the atopic dermatitis drugs industry growth.
Distribution Channel Insights
Based on distribution channel, the hospital pharmacies segment led the market with the largest revenue share of 61.4% in 2025. Many patients with moderate to severe atopic dermatitis require prescription medications, which are often more readily available through hospital pharmacies. This includes systemic treatments and newer biologics that retail pharmacies may not stock. Furthermore, patients with chronic conditions such as atopic dermatitis often seek specialized care, which is more readily available in hospitals and specialized clinics. Thus, patients with severe symptoms are more likely to be treated in hospitals, leading to increased usage of hospital pharmacies.
 To learn more about this report, Download Free Sample Report
The other pharmacies segment is projected to witness a significant growth rate over the forecast period. Other pharmacies such as online pharmacies boost the adoption of drugs by increasing accessibility to essential medications, such as topical and oral AD drugs, particularly for families in remote or underserved areas. They offer convenience, discreet delivery, and often lower costs, making it easier for parents to obtain and manage their AD care consistently. In addition, the integration of telemedicine has made it easier for patients to consult healthcare providers and receive prescriptions online, further driving the growth of other pharmacies.
Regional Insights
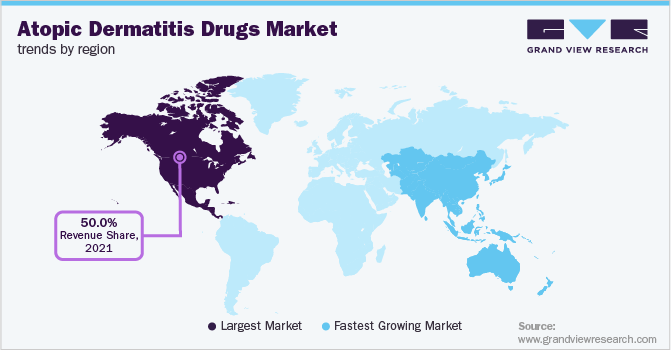
North America dominated the atopic dermatitis drugs market with the largest revenue share of 44.6% in 2025. This can be attributed to the high adoption rates of biologics and topical treatments. The region's leadership in this sector is primarily attributed to the comprehensive healthcare system, extensive research and development initiatives, and the introduction of personalized medicine approaches. However, challenges such as rising drug costs and insurance coverage limitations may impede growth.
 To learn more about this report, Download Free Sample Report
U.S. Atopic Dermatitis Drugs Market Trends
The atopic dermatitis drugs market in the U.S. held the largest share in the North America region in 2025, fueled by a high incidence of atopic dermatitis among both adults and children. Increasing utilization of monoclonal antibodies and newer therapies, such as Janus kinase (JAK) inhibitors, are transforming treatment paradigms. Nevertheless, the market faces hurdles, including disparities in access to advanced therapies and the need for more healthcare provider education on emerging treatments.
Europe Atopic Dermatitis Drugs Market Trends
Europe atopic dermatitis drugs market was identified as a lucrative region in this industry. Growth is fueled by increased awareness and diagnosis rates related to atopic dermatitis. The region is seeing an uptick in clinical trials for innovative treatments and a rise in the adoption of combination therapies that enhance treatment efficacy. Furthermore, increasing regulatory support for novel AD drugs and improved patient access contribute to regional expansion.
The atopic dermatitis drugs market in UK accounted for the largest share of the due to technological advancements in treatment options, particularly the introduction of systemic therapies and innovative topical formulations. Furthermore, increased patient access to specialty pharmacies and dermatology clinics has improved treatment adherence and outcomes for pediatric and adult populations alike.
The atopic dermatitis drugs market in Germany is anticipated to witness high growth in Europe in 2024. The growing incidence of moderate to severe AD has led to increased demand for biologics and corticosteroid drugs, which are essential in managing the AD disease.
The atopic dermatitis drugs market in France is set to expand, and it is supported by public health initiatives to increase awareness and treatment of chronic skin diseases. Enhanced reimbursement policies for new therapies and the promotion of dermatological care in primary healthcare settings are expected to bolster market growth.
Asia Pacific Atopic Dermatitis Drugs Market Trends
The Asia Pacific atopic dermatitis drugs market is expected to experience the fastest growth in the global market. This growth is driven by an increasing prevalence of skin conditions and rising disposable incomes. The adoption of advanced therapies and growing awareness of skincare are key factors propelling this market segment.
The atopic dermatitis drugs market in China is experiencing significant growth in the atopic dermatitis sector, supported by a rising focus on skincare products and dermatological treatments. The government’s initiatives to improve healthcare access and investment in research and development are expected to stimulate market growth further.
The atopic dermatitis drugs market in Japan held a notable revenue share in 2024, driven by innovative biologics and personalized medicine research. Increased emphasis on patient education and adherence programs is fostering better management of the disease among both adults and children.
Latin America Atopic Dermatitis Drugs Market Trends
Latin America atopic dermatitis drugs market is identified as a lucrative region, with growing investments in dermatological research and increasing patient awareness. The market benefits from a rise in disposable incomes and the introduction of new treatments targeting various patient demographics.
The atopic dermatitis drugs market in Brazil led the global market in Latin America in 2024, where an increasing number of dermatological clinics and pharmacies are improving access to treatments. Innovative healthcare initiatives addressing skin conditions among children are driving growth in this segment.
MEA Atopic Dermatitis Drugs Market Trends
The MEA atopic dermatitis drugs market is expected to grow due to increased government funding for healthcare improvements and enhanced treatment access. The demand for effective therapies is rising due to a growing awareness of skin conditions and the prevalence of atopic dermatitis.
The atopic dermatitis drugs market in Saudi Arabia is projected to be one of the fastest-growing markets in the coming years. This can be attributed to the growing population and increased healthcare expenditure. Enhanced focus on chronic disease management and patient education initiatives supports market development. As the healthcare system evolves, the availability of modern therapies is expected to improve significantly in Saudi Arabia.
Key Atopic Dermatitis Drugs Company Insights
Some of the key players such as Pfizer Inc., AbbVie Inc., Sanofi, Galderma Laboratories, L.P., Eli Lilly and Company (Dermira), Regeneron Pharmaceuticals Inc., LEO Pharma Inc., Otsuka Pharmaceutical Co., Ltd, Novartis AG, and Incyte Corporation hold significant positions in market. These companies are undertaking various strategies such as new product development, collaborations, acquisitions, mergers, and regional expansion for serving the unmet needs of their customers.
Key Atopic Dermatitis Drugs Companies:
The following key companies have been profiled for this study on the atopic dermatitis drugs market.
-
Pfizer Inc.
-
Sanofi
-
AbbVie Inc.
-
Galderma Laboratories, L.P.
-
Eli Lilly and Company (Dermira)
-
Regeneron Pharmaceuticals Inc.
-
LEO Pharma Inc.
-
Otsuka Pharmaceutical Co., Ltd.
-
Novartis AG
-
Incyte Corporation
Competitive Benchmarking
Operating Strategies
Competitive Edge
Weaknesses
Large Integrated Pharmaceutical Companies (Pfizer Inc., Sanofi, AbbVie Inc., Eli Lilly and Company, Novartis AG, Otsuka Pharmaceutical Co., Ltd.)
- Expand dermatology and immunology portfolios through biologics, JAK inhibitors, and next generation targeted therapies for moderate to severe atopic dermatitis.
- Focus on label expansions across pediatric and adult populations, lifecycle management initiatives, and global commercialization.
- Invest in clinical research, combination treatment approaches, and strategic partnerships to strengthen long term market positioning.
- Strong global commercial infrastructure, extensive regulatory expertise, broad healthcare provider networks, and substantial research and development capabilities.
- Ability to conduct large scale clinical trials, secure favorable reimbursement coverage, and leverage diversified immunology portfolios to support market expansion and product adoption.
- High research, development, and commercialization costs associated with advanced immunology therapies.
- Exposure to pricing pressures, reimbursement negotiations, and increasing competition from emerging targeted treatments.
- Large organizational structures may reduce operational flexibility and delay response to rapidly evolving market opportunities.
Dermatology and Immunology Focused Specialists (Galderma Laboratories, L.P., Regeneron Pharmaceuticals Inc., LEO Pharma Inc., Incyte Corporation)
- Focus on developing innovative therapies targeting key inflammatory and itch related pathways involved in atopic dermatitis.
- Prioritize clinical differentiation through novel mechanisms of action, patient focused treatment outcomes, and expanded dermatology portfolios.
- Pursue strategic collaborations, licensing agreements, and regional commercialization partnerships to enhance market reach and maximize product value.
- Deep expertise in dermatology and immunology, specialized clinical development capabilities, and strong focus on unmet patient needs.
- Greater agility in advancing innovative therapies and responding to emerging scientific developments.
- Ability to build differentiated positions through targeted treatment approaches and focused commercial strategies.
- More limited commercial scale and financial resources compared with multinational pharmaceutical companies.
- Higher dependence on a smaller number of products and clinical programs, increasing exposure to regulatory, competitive, and commercialization risks.
- Reliance on partnerships in certain regions may limit independent market expansion and long term revenue diversification.
Recent Developments
-
In September 2024, the U.S. FDA approved EBGLYSS (lebrikizumab-lbkz) developed by Eli Lilly and Company for the treatment of moderate to severe atopic dermatitis (eczema) adult and children aged 12 years and above who weigh at least 40kg that is not well manage by topical treatment. This approval is expected to boost market growth.
-
In August 2023, Lynk Pharmaceuticals Co., Ltd. announced positive topline results from its Phase II clinical trial of LNK01001 for adults with atopic dermatitis (AD). After 12 weeks of treatment, preliminary data indicated that patients in both the low-dose and high-dose groups demonstrated significant improvements in Eczema Area and Severity Index (EASI) scores compared to the placebo group. The successful completion of clinical trial and approval of product is anticipated to drive market growth.
-
In June 2022, the U.S. FDA approved Dupixent (dupilumab) developed by Sanofi for the treatment of moderate to severe atopic dermatitis (eczema) children aged 6 months to 5 years whose disease not controlled with treatment of topical drugs. This approval is anticipated to drive market growth.
Atopic Dermatitis Drugs Market Report Scope
Report Attribute
Details
Market size in 2025
USD 19.4 billion
Estimated market size in 2026
USD 21.3 billion
Projected market size by 2033
USD 37.3 billion
Growth rate
CAGR of 8.3% from 2026 to 2033
Historical data
2021 - 2025
Forecast period
2026 - 2033
Quantitative units
Revenue in USD million/billion and CAGR from 2026 to 2033
Report coverage
Revenue forecast, company ranking, competitive landscape, growth factors, and trends
Segments covered
Drug Class, Route of Administration, Distribution Channel and Region
Regional scope
North America; Europe; Asia Pacific; Latin America; MEA
Country scope
U.S.; Canada; Mexico; Germany; UK; France; Italy; Spain; Norway; Denmark; Sweden; China; Japan; India; South Korea; Australia; Thailand; Brazil; Argentina; Saudi Arabia; South Africa; UAE; Kuwait
Key companies profiled
Pfizer Inc., Sanofi, AbbVie Inc., Galderma Laboratories, L.P., Eli Lilly and Company (Dermira), Regeneron Pharmaceuticals Inc., LEO Pharma Inc., Otsuka Pharmaceutical Co., Ltd., Novartis AG, Incyte Corporation
Customization scope
Free report customization (equivalent up to 8 analysts' working days) with purchase. Addition or alteration to country, regional & segment scope.
Pricing and purchase options
Avail customized purchase options to meet your exact research needs. Explore purchase options
Global Atopic Dermatitis Drugs Market Report Segmentation
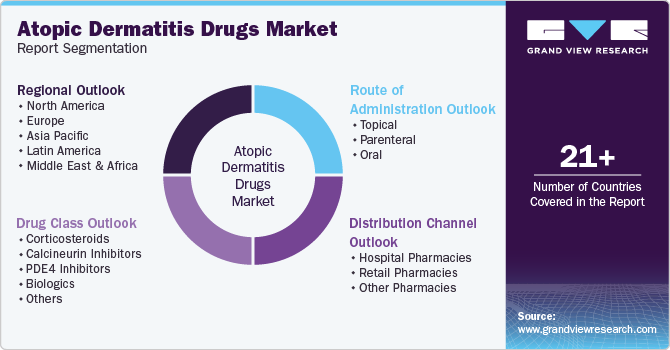
This report forecasts revenue growth at global, regional, and country levels and provides an analysis of the latest industry trends in each of the sub-segments from 2021 to 2033. For this study, Grand View Research has segmented the global atopic dermatitis drugs market report based on drug class, route of administration, distribution channel, and region:
 To learn more about this report, Download Free Sample Report
-
Drug Class Outlook (Revenue, USD Million, 2021 - 2033)
-
Corticosteroids
-
Calcineurin Inhibitors
-
PDE4 Inhibitors
-
Biologics
-
Others
-
-
Route of Administration Outlook (Revenue, USD Million, 2021 - 2033)
-
Topical
-
Parenteral
-
Oral
-
-
Distribution Channel Outlook (Revenue, USD Million, 2021 - 2033)
-
Hospital Pharmacies
-
Retail Pharmacies
-
Other Pharmacies
-
-
Regional Outlook (Revenue, USD Million, 2021 - 2033)
-
North America
-
U.S.
-
Canada
-
Mexico
-
-
Europe
-
Germany
-
UK
-
France
-
Italy
-
Spain
-
Denmark
-
Sweden
-
Norway
-
-
Asia Pacific
-
China
-
Japan
-
India
-
South Korea
-
Australia
-
Thailand
-
-
Latin America
-
Brazil
-
Argentina
-
-
Middle East and Africa (MEA)
-
South Africa
-
Saudi Arabia
-
Kuwait
-
UAE
-
-
Research Methodology
Segment Definition
Segment - Drug Class
Revenue capture definition
Corticosteroids
Revenue generated from corticosteroid therapies prescribed for the treatment of atopic dermatitis. This segment includes topical, oral, and injectable corticosteroids used to reduce inflammation, itching, and skin lesions associated with the disease. Revenue from all corticosteroid products utilized in atopic dermatitis management is attributed exclusively to this segment.
Calcineurin Inhibitors
Revenue generated from calcineurin inhibitor therapies used in the treatment of atopic dermatitis, including products containing tacrolimus and pimecrolimus. These therapies act by suppressing immune responses and reducing skin inflammation. All revenue associated with calcineurin inhibitors prescribed for atopic dermatitis is classified solely within this segment.
PDE4 Inhibitors
Revenue generated from phosphodiesterase 4 inhibitor therapies indicated for atopic dermatitis treatment. This segment includes topical and systemic PDE4 inhibitors that reduce inflammatory signaling pathways involved in disease progression. Revenue from all PDE4 inhibitor products prescribed for atopic dermatitis is assigned exclusively to this category.
Biologics
Revenue generated from biologic therapies approved or prescribed for atopic dermatitis, including monoclonal antibodies targeting specific inflammatory pathways such as IL-4, IL-13, IL-31, and related cytokines. Revenue from all biologic products used in atopic dermatitis treatment is reported exclusively within this segment regardless of patient age group or treatment setting.
Others
Revenue generated from all other drug classes used in the management of atopic dermatitis that are not included under Corticosteroids, Calcineurin Inhibitors, PDE4 Inhibitors, or Biologics. This includes JAK inhibitors, antihistamines, immunosuppressants, emerging targeted therapies, and future treatment classes. Revenue is allocated to this segment only when it does not belong to the predefined categories above.
Segment - Route of Administration
Revenue capture definition
Topical
Revenue generated from atopic dermatitis therapies administered directly to the skin through creams, ointments, gels, lotions, foams, and other topical formulations. This segment includes corticosteroids, calcineurin inhibitors, PDE4 inhibitors, and other topical therapies. Revenue is attributed to this segment when the product is delivered via the topical route.
Parenteral
Revenue generated from atopic dermatitis therapies administered through injectable routes, including subcutaneous and intravenous administration. This segment primarily includes biologic therapies and other injectable immunomodulatory treatments. Revenue is assigned to this segment when the product is administered through a parenteral route.
Oral
Revenue generated from atopic dermatitis therapies administered orally in the form of tablets, capsules, or liquid formulations. This includes oral JAK inhibitors, corticosteroids, immunosuppressants, and other systemic therapies prescribed for disease management. Revenue is classified within this segment when the therapy is delivered through oral administration.
Segment - Distribution Channel
Revenue capture definition
Hospital Pharmacies
Revenue generated from atopic dermatitis therapies dispensed, administered, and billed through hospital based pharmacies and hospital affiliated dermatology or specialty care departments. This segment includes products procured and managed by hospitals for inpatient and outpatient treatment settings. Revenue is attributed to this segment when the therapy is distributed through a hospital pharmacy channel.
Retail Pharmacies
Revenue generated from atopic dermatitis therapies distributed through retail pharmacy networks, including chain pharmacies, independent pharmacies, community pharmacies, and drug stores. This segment covers prescription and over the counter products obtained by patients through retail dispensing channels. Revenue is assigned to this segment when the product is supplied through a retail pharmacy.
Others
Revenue generated from all remaining distribution channels not included under Hospital Pharmacies or Retail Pharmacies. This includes online pharmacies, specialty pharmacies, mail order pharmacies, dermatology clinics, government procurement programs, and other alternative distribution pathways. Revenue is allocated to this segment only when it is not attributable to the predefined channels above.
Estimation Model
The study incorporates a combination of primary and secondary research methodologies to estimate and validate the global Atopic Dermatitis Market size. Secondary research involves an extensive review of company annual reports, investor presentations, SEC filings, product labels, regulatory databases, clinical trial registries, scientific publications, dermatology association reports, government healthcare statistics, and peer reviewed journals. Revenue analysis of key marketed products, treatment adoption trends, prescription volumes, pricing benchmarks, and epidemiology data are also evaluated.
Primary research includes interviews with dermatologists, immunologists, hospital pharmacists, key opinion leaders, healthcare providers, pharmaceutical executives, distributors, and reimbursement specialists across major regions. Insights obtained from these interviews are used to validate market assumptions, treatment utilization patterns, pricing dynamics, competitive positioning, and future growth trends.
Market size estimation is conducted using both top down and bottom-up approaches. The bottom-up approach analyzes revenues generated by approved atopic dermatitis therapies across different drug classes, routes of administration, distribution channels, and geographic regions. The top-down approach evaluates overall dermatology and immunology market trends and allocates revenues based on disease prevalence, treatment rates, and therapy penetration. Data triangulation and market breakdown procedures are applied to ensure accuracy and consistency of the final market estimates and forecasts.
Delivered Customizations
This report has been delivered with the following In-depth customizations
Client Request
Customization Delivered
Value Adds
Atopic Dermatitis Competitive Landscape & Pipeline Assessment
Conducted a targeted assessment of the global atopic dermatitis landscape, evaluating approved therapies, late-stage pipeline candidates, mechanisms of action, clinical development progress, regulatory milestones, and competitive positioning. The study analyzed key players including Sanofi, Regeneron Pharmaceuticals, AbbVie, Eli Lilly, Galderma, Pfizer, Incyte, Novartis, LEO Pharma, and Otsuka Pharmaceutical, along with emerging therapeutic approaches targeting inflammatory and itch related pathways.
Helped the client identify high potential therapeutic targets, assess competitive threats, benchmark pipeline differentiation, evaluate market entry opportunities, and prioritize licensing, acquisition, and partnership strategies within the evolving atopic dermatitis treatment market.
Atopic Dermatitis Therapy Benchmarking & Innovation Assessment
Delivered a comprehensive benchmarking analysis of atopic dermatitis therapies, focusing on biologics, JAK inhibitors, PDE4 inhibitors, corticosteroids, and emerging targeted treatments. The assessment compared efficacy outcomes, safety profiles, treatment convenience, regulatory status, patient population coverage, and commercial positioning across leading products and pipeline assets.
Enabled the client to assess therapy competitiveness, identify innovation gaps, benchmark product differentiation strategies, evaluate emerging treatment trends, and prioritize investments in next generation dermatology and immunology development programs.
Atopic Dermatitis Market Access & Commercialization Feasibility Assessment
Conducted a strategic assessment of the atopic dermatitis commercialization ecosystem, evaluating reimbursement environments, payer coverage trends, distribution networks, physician adoption patterns, patient access programs, and regional regulatory frameworks. The study analyzed market barriers, pricing dynamics, treatment accessibility, and commercial readiness across major global markets.
Supported strategic commercialization planning by identifying reimbursement opportunities, evaluating market access challenges, mitigating launch risks, assessing regional growth potential, and strengthening long term market expansion strategies for atopic dermatitis therapies across global healthcare systems.
Frequently Asked Questions About This Report
Some of the key players operating in the market are Bayer AG, Regeneron Pharmaceuticals, Inc., Pfizer Inc., LEO Pharma A/S, Viatris Inc., and Sanofi among others.
Launch of novel & effective biologics & small molecules, premium-priced drugs replacing generic first-line and second-line therapeutics, growing incidence of AD, and improved diagnostics are estimated to stoke the growth of the market.
North America dominated the Atopic Dermatitis Drugs market with the largest revenue share of 44.6% in 2025.
Asia Pacific is the fastest-growing region over the forecast period.
Based on route of administration, the topical segment led the market with the largest revenue share of 38.9% in 2025.
Based on distribution channel, the hospital pharmacies segment led the market with the largest revenue share of 61.4% in 2025.
The global atopic dermatitis drugs market is expected to grow at a compound annual growth rate of 8.3% from 2026 to 2033 and is expected to reach USD 37.3 billion by 2033.
Based on drug class, the biologics segment led the market with the largest revenue share of 40.9% in 2025.
The global Atopic Dermatitis Drugs market size was estimated at USD 19.4 billion in 2025 and is projected to grow from USD 21.3 billion in 2026
About the Author(s)
Pharmaceuticals Research Team
Healthcare · PharmaceuticalsThis report was authored by the pharmaceuticals research team at Grand View Research - comprising two research analysts, one senior research analyst, and one industry expert - with specialized expertise in the pharmaceuticals segment of the healthcare industry. All findings are based on proprietary healthcare databases, executive interviews, and regulatory analysis, subject to internal peer review prior to publication.
Last Updated:
Speak to Analyst

Customize this report to your needs - add regions, segments, or data points, with 20% free customization.
Or view our licence options:


ISO 9001:2015 & 27001:2022 Certified
We are GDPR and CCPA compliant! Your transaction & personal information is safe and secure. For more details, please read our privacy policy.


