
- Home
- »
- Medical Devices
- »
-
Audiology Devices Market Size & Share Report, 2026-2033GVR Report cover

Audiology Devices Market (2026 - 2033)
Size, Share & Trends Analysis Report By Technology (Digital, Analog), By Age Group, By Product (Cochlear Implants, Hearing Aids), By Sales Channel, By Region, And Segment Forecasts
Market Size, 2025
$15.6BMarket Estimate, 2026
$16.6BMarket Forecast, 2033
$25.1BCAGR, 2026–2033
6.1%Audiology Devices Market Summary
The global audiology devices market size was valued at USD 15.6 billion in 2025 and is projected to grow from USD 16.6 billion in 2026 to USD 25.1 billion in 2033, at a CAGR of 6.1% from 2026 to 2033. Europe dominated the market, accounting for a revenue share of 35.0% in 2025. This global market growth can be attributed to factors such as an aging population, the rising prevalence of hearing disorders, and supportive government initiatives that facilitate access to hearing aids.
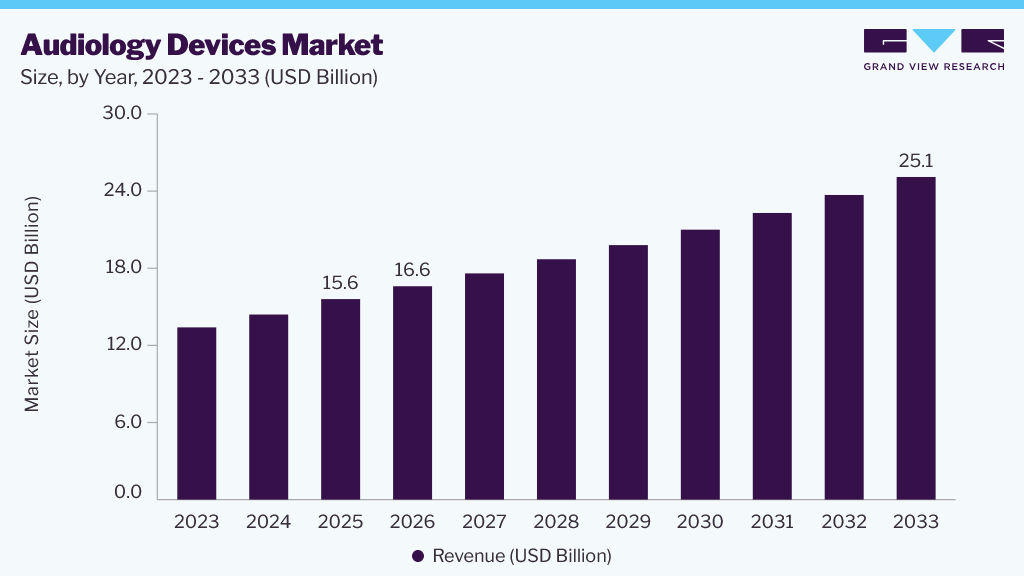 Source: Grand View Research, IR Documents, Primary Interviews, Paid DatabasesTo learn more about this report,
 Download Free Sample Report
Key Market Trends & Insights
- By product: The hearing aids segment held the largest market share of around 75.0% in 2025.
- By technology: The digital segment held the largest market share of around 95.0% in 2025.
- By age group: The adult segment held the largest market share of over 90.0% in 2025.
- By sales channel: The retail sales segment held the largest market share of around 65.0% in 2025.
Regional Highlights
- Largest regional market: Europe (35.0% revenue share, 2025)
- Fastest-growing regional market: Asia Pacific (highest CAGR, 2026-2033)
Market Size & Forecast
- Market size in 2025: USD 15.6 Billion
- Estimated market size in 2026: USD 16.6 Billion
- Projected market size by 2033: USD 25.1 Billion
- CAGR (2026-2033): 6.1%
Three ways to get this report
Buy it, customize it, or ask a question.Ask an Analyst
Analyst response in 1 business day
- AccessReport author, directly
- Reply timeWithin 1 working day
- No sales callDirect answer only
- FormatEmail reply
- CostFree, no cost
Get the Full Report
What the study covers
- FormatsPDF · Excel · Dashboard
- Timeline2026–2033 annual, 2025 base
- Coverage20+ countries, 5 regions
- Companies10+ key players profiled
Customize the Report
20% free customization
- IncludeCountries, segments, points
- TailorTo your product definition
- ExtendDeeper competitor detail
- OrA fully bespoke study
- Turnaround5–10 working days
According to a WHO factsheet published in February 2024, approximately 5% of the global population requires rehabilitation for hearing loss. The number of people experiencing hearing loss is expected to reach nearly 2.5 billion by 2050, with around 700 million requiring hearing rehabilitation. Rising life expectancy, age-related hearing impairment, and increasing exposure to occupational and environmental noise are therefore expected to sustain demand for audiology devices and hearing care solutions.Technological advancements are further reshaping the audiology devices industry, with manufacturers focusing on solutions that offer improved speech clarity, connectivity, convenience, and personalization compared with conventional hearing aids. Rechargeable devices, compact designs, wireless connectivity, and AI-enabled noise management are gaining traction. For instance, in August 2024, Sonova launched the Phonak Audéo Sphere Infinio, featuring dual-chip AI technology that distinguishes speech from background noise in real time and improves speech understanding in challenging listening environments.
The market is also witnessing increased strategic activity as leading companies seek to strengthen their product portfolios and expand their global presence. In 2025, Demant completed its acquisition of KIND, expanding its international hearing care network while continuing to introduce AI-enabled hearing solutions. GN also launched the ReSound Vivia, incorporating AI-based technology to enhance speech understanding. These product innovations and strategic expansions highlight the industry's continued focus on improving hearing outcomes and accelerating the adoption of next-generation audiology devices.
Market Concentration & Characteristics
Key players invest in technological advancements, such as intelligent hearing devices. Smart hearing aids are advanced devices that enhance hearing using digital technology and automatically adjust sound settings based on the environment. They often feature wireless connectivity, allowing users to stream audio directly from smartphones and other devices. For instance, in February 2024, Widex launched the SmartRIC hearing aid, designed to improve natural hearing quality. The L-shaped device strategically places microphones to enhance speech capture and align with the user’s auditory focus. As Widex’s most durable rechargeable Receiver-in-Canal (RIC) model, the SmartRIC provides up to 37 hours of functionality on a single charge. It has microphone inlets that minimize wind & handling noise and has Widex’s portable charging option.
Partnerships and collaborations are thriving in the industry as companies seek to improve patient outcomes by integrating advanced technologies. These alliances leverage combined clinical expertise and tech innovation to enhance products, expand market access, and accelerate development through shared R&D investments. For instance, in March 2025, Cochlear Ltd. and GN expanded their long-standing Smart Hearing Alliance through an enhanced R&D partnership to accelerate the development of integrated hearing solutions. The collaboration focuses on artificial intelligence (AI), Deep Neural Networks (DNN), advanced wireless connectivity, and seamless integration between cochlear implants and hearing aids to improve patient outcomes and listening experiences.
Government initiatives aimed at raising awareness of hearing screenings among infants and older adults are fostering industry growth. Strong government support for improving accessibility is expected to drive demand. The FDA shapes the regulatory framework of the U.S. audiology market, overseeing the safety and efficacy of audiology devices. In addition to the growing demand driven by the aging population, there is an increasing focus on the accessibility and affordability of audiology devices, which drives the market in the U.S. Recent legislative and regulatory changes have made hearing aids more accessible, especially for those with mild to moderate hearing loss.
The audiology devices industry experiences moderate regional expansion due to several challenges. These include stringent regulatory barriers across regions; disparities in healthcare infrastructure between developed and developing countries; high prices, particularly for advanced hearing aids and cochlear implants, which create a significant barrier, especially in low- and middle-income countries; and a shortage of trained healthcare professionals in low- and middle-income countries.
Analyst Perspective
The audiology devices market is expanding as hearing loss becomes increasingly common among aging populations and younger individuals exposed to prolonged noise. Growing awareness of hearing health, improved screening programs, and improved access to audiological care are supporting demand for hearing aids, cochlear implants, and diagnostic devices. Technological advances such as wireless connectivity, artificial intelligence, rechargeable systems, and smaller device designs are improving convenience and user experience. The growing availability of over-the-counter hearing solutions is also making hearing care more accessible to consumers. Companies with strong product portfolios, advanced technology capabilities, and established distribution networks are likely to strengthen their market position.
Product Insights
The hearing aids segment led the market with the largest revenue share of around 75.0% in 2025 and is expected to witness the fastest CAGR during the forecast period, owing to the significant demand for invisible-in-canal and complete-in-canal hearing aids. This can be attributed to the rising awareness of cochlear implants as noninvasive procedures and new products launched by key companies. For instance, in July 2025, Cochlear Ltd. received U.S. FDA approval for the Cochlear Nucleus Nexa System, the world's first smart cochlear implant system featuring upgradeable implant firmware, internal memory, and the new Nucleus 8 Nexa and Kanso 3 Nexa sound processors. The launch significantly advanced hearing technology by improving connectivity, patient outcomes, and long-term access to future innovations in audiology devices.
The surgical devices segment is anticipated to grow at a significant CAGR over the forecast period, driven by advancements reflecting a growing trend in audiology towards personalized solutions that leverage technology to enhance patient outcomes in hearing rehabilitation. For instance, in October 2024, Olympus Corporation received U.S. FDA 510(k) clearance for the VISERA S Surgical Visualization Platform, enhancing visualization and workflow efficiency across ENT and other minimally invasive surgical procedures. The platform supports improved precision and decision-making during otologic and head & neck surgeries.
Technology Insights
The digital segment led the market with the largest revenue share of around 95.0% in 2025. This is attributed to the quick adaptability of these devices. Many manufacturers offer digital hearing aids with Bluetooth connectivity integrated with In-The-Ear (ITE) and Behind-The-Ear (BTE) models. The Open hearing aid range by Oticon can be connected to iPhone, iPad, and iPod touch devices, allowing users to stream audio directly into their hearing aids.
The analog segment is anticipated to grow at a significant CAGR over the forecast period. Analog hearing aids offer a traditional, straightforward approach to hearing assistance by processing sound waves into continuous electrical signals and amplifying all sounds uniformly. Known for their simplicity, they provide a consistent listening experience without advanced features, making them suitable for those who prefer ease of use. These devices are valued for their durability and reliability, as they contain fewer electronic components, resulting in lower maintenance needs and longer lifespans. Analog hearing aids operate without needing a battery, making them ideal for individuals who may forget to charge their devices or prefer to avoid managing battery replacements. This is expected to boost the demand for analog hearing aids in the market.
Sales Channel Insights
The retail sales segment accounted for the largest market revenue share of around 65.0% in 2025 and is projected to register the fastest CAGR over the forecast period, owing to the presence of large retail chains such as CVS, Walgreens, Walmart, and Amazon. These retail stores are entering the healthcare retail sector. Furthermore, rising government initiatives for audiology care products and remote care are expected to drive the growth of the retail sales segment during the forecast period.
The e-commerce segment is anticipated to grow at a significant CAGR over the forecast period, driven by the increasing preference for online shopping and its convenience. E-commerce platforms provide an accessible channel for customers to research, compare, and purchase hearing aids and related devices from the comfort of their homes. With a growing number of consumers opting for online shopping, particularly in regions with limited access to physical stores, e-commerce plays a crucial role in expanding the reach of audiology products to a broader audience.
Age Group Insights
The adult segment accounted for the largest share of market revenue, over 90.0%, in 2025. The increasing geriatric population and growing awareness of available hearing implants & devices are major factors driving segment growth. According to the National Institute on Deafness and Other Communication Disorders (NIDCD), around 5% of adults between the ages of 45 and 54 experience disabling hearing loss. This percentage rises to 10% for adults aged 55-64, 22% for those aged 65-74, and 55% for individuals aged 75 and older.
The pediatrics segment is projected to witness a remarkable CAGR during the forecast period, due to the rising number of infants born with sensorineural hearing loss and the effectiveness of cochlear implants in treating these hearing abnormalities in children. According to the NIDCD, in the U.S., approximately 2 to 3 per 1,000 newborns are born with hearing loss in one or both ears. This growing recognition among parents and healthcare professionals led to a surge in demand for pediatric hearing aids and related devices.
Regional Insights
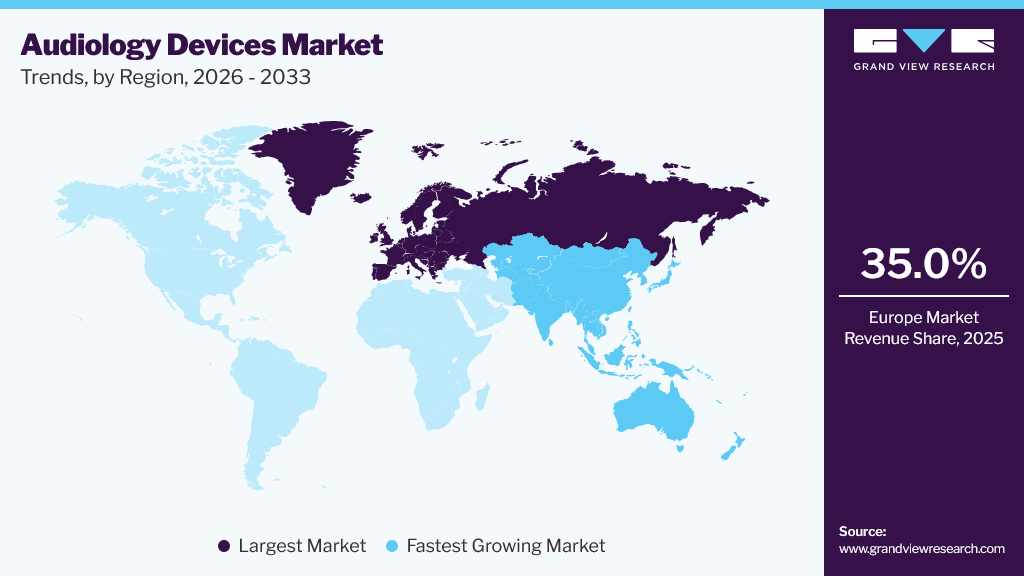
The audiology devices industry in Europe dominated the global market, with a revenue share of around 35.0% in 2025. Key factors contributing to the growth of this region are an aging population and the rising prevalence of hearing loss. Moreover, increasing government support through approvals and reimbursement, coupled with growing awareness, is driving market growth. Furthermore, the presence of several key players is positively impacting market growth as these players tend to engage in strategic initiatives.
 To learn more about this report, Download Free Sample Report
The audiology devices industry in the UK accounted for a significant share of the European market in 2025, owing to the rising prevalence of hearing disabilities, a growing geriatric population, and technological advancements. Moreover, new initiatives in the country are expected to drive the hearing aids market, with a growing focus on enhancing accessibility, affordability, and innovation in hearing healthcare solutions.
The Germany audiology devices industry held the largest market share in the European region in 2025. Germany is one of Europe's largest and most mature audiology device industries, driven by factors such as an aging population, high healthcare expenditure, and advancements in hearing aid technologies. For instance, according to a 2025 study published in HNO (Springer Nature), Germany continues to face significant challenges in accessing hearing healthcare, particularly for individuals with permanent hearing loss who require hearing technologies such as hearing aids and cochlear implants. The study highlights the importance of improving access to advanced audiology devices and hearing care services to enhance patient outcomes. This group faces barriers to accessing urgent medical care, as communication options and sign language interpreters are scarce. This factor drives the country's demand for hearing aids.
Asia Pacific Audiology Devices Market Trends
The audiology devices industry in the Asia Pacific region is expected to grow significantly over the forecast period, owing to an aging population and the rising prevalence of age-related hearing problems. Asian countries, such as India and China, have large geriatric populations, resulting in lucrative market growth.
China’s audiology devices industry accounted for the largest share of the Asia Pacific market in 2025. The China audiology devices industry is experiencing growth driven by an aging population, increased healthcare awareness, and expanding government support. The Chinese government implemented several initiatives to improve healthcare accessibility, including support for hearing rehabilitation services. These factors, along with growing awareness of hearing loss and the benefits of early intervention, fuel demand for audiology devices in the region.
The audiology devices industry in India is expected to grow significantly over the forecast period. The government is investing in improving the country’s healthcare infrastructure to provide better diagnostics and treatments for hearing disorders. Rising public awareness and an increasing literacy rate are expected to drive market growth in the country.
Key Audiology Devices Company Insights
The audiology devices industry is characterized by global, regional, and niche solution providers competing through technological innovation, strategic partnerships, acquisitions, and product portfolio expansion.
Key Audiology Devices Companies
The following key companies have been profiled for this study on the audiology devices market:
-
Demant A/S
-
GN Store Nord A/S
-
Sonova
-
Starkey Laboratories, Inc.
-
MED-EL Medical Electronics
-
Cochlear Ltd.
-
WS Audiology A/S
-
MAICO Diagnostics GmbH
-
Oticon Medical
-
INVENTIS srl
-
Tech Innovations and M&A trends
Recent Developments
-
In March 2026, Sonova Holding AG announced its intention to divest its Consumer Hearing business following a strategic portfolio review, allowing the company to focus investments on its core Hearing Instruments and Cochlear Implants businesses.
-
In August 2024, Sonova launched two new hearing aid platforms, including the first real-time AI-enabled device to dive into critical hearing loss challenges.
-
In March 2024, WSAudiology introduced Rexton ReCharge, an affordable range of rechargeable hearing solutions designed to meet global hearing needs.
Audiology Devices Market Report Scope
Report Attribute
Details
Market size in 2025
USD 15.6 billion
Estimated market size in 2026
USD 16.6 billion
Projected market size by 2033
USD 25.1 billion
Growth rate
CAGR of 6.1% from 2026 to 2033
Base year for estimation
2025
Historical data
2021 - 2024
Forecast period
2026 - 2033
Quantitative units
Revenue in USD billion and CAGR from 2026 to 2033
Report coverage
Revenue forecast, company ranking, competitive landscape, growth factors, and trends
Segments covered
Product, technology, age group, sales channel, region
Regional Scope
North America; Europe; Asia Pacific; Latin America; MEA
Country Scope
U.S.; Canada; Mexico; UK; Germany; France; Italy; Spain; Norway; Denmark; Sweden; China; Japan; India; South Korea; Australia; Thailand; Brazil; Argentina; Saudi Arabia; South Africa; UAE; Kuwait
Key companies profiled
Demant A/S; GN Store Nord A/S; Sonova; Starkey Laboratories, Inc.; MED-EL Medical Electronics; Cochlear Ltd.; WS Audiology A/S; MAICO Diagnostics GmbH; Oticon Medical; INVENTIS srl; Tech Innovations and M&A trends
Customization scope
Free report customization (equivalent to 8 analyst working days) with purchase. Addition or alteration to country, regional & segment scope.
Pricing and purchase options
Avail of customized purchase options to meet your exact research needs. Explore purchase options
Global Audiology Devices Market Report Segmentation
This report forecasts revenue growth at the global, regional, and country levels and provides an analysis of the latest industry trends and opportunities across each sub-segment from 2021 to 2033. For this study, Grand View Research has segmented the global audiology devices market report based on product, sales channel, technology, age group, and region:
- Product Outlook (Revenue, USD Billion, 2021 - 2033)
- Hearing Aids
- Cochlear Implants
- BAHA/BAHS
- Diagnostic Devices
- Surgical Devices
- Technology Outlook (Revenue, USD Billion, 2021 - 2033)
- Digital
- Analog
- Sales channel Outlook (Revenue, USD Billion, 2021 - 2033)
- Retail Sales
- E-commerce
- Government Purchases
- Age Group Outlook (Revenue, USD Billion, 2021 - 2033)
- Adults
- Pediatrics
- Regional Outlook (Revenue, USD Billion, 2021 - 2033)
- North America
- U.S.
- Canada
- Mexico
- Europe
- UK
- Germany
- France
- Italy
- Spain
- Norway
- Denmark
- Sweden
- Asia Pacific
- Japan
- China
- India
- Australia
- South Korea
- Thailand
- Latin America
- Brazil
- Argentina
- Middle East and Africa (MEA)
- South Africa
- Saudi Arabia
- UAE
- Kuwait
- North America
Frequently Asked Questions About This Report
The global audiology devices market size was valued at USD 15.6 billion in 2025 and is estimated at USD 16.6 billion in 2026.
The global audiology devices market is expected to grow at a CAGR of 6.1% from 2026 to 2033, reaching USD 25.1 billion.
The Europe region dominated the global audiology devices market, accounting for approximately 35.0% of revenue in 2025.
Key players in the market include Demant A/S; GN Store Nord A/S; Sonova; Starkey Laboratories, Inc.; MED-EL Medical Electronics; Cochlear Ltd.; WS Audiology A/S; MAICO Diagnostics GmbH; Oticon Medical; and INVENTIS srl.
The hearing aids segment accounted for the largest revenue share, at around 75.0%, in 2025.
About the Author(s)
Medical Devices Research Team
Healthcare · Medical DevicesThis report was authored by the medical devices research team at Grand View Research - comprising two research analysts, one senior research analyst, and one industry expert - with specialized expertise in the medical devices segment of the healthcare industry. All findings are based on proprietary healthcare databases, executive interviews, and regulatory analysis, subject to internal peer review prior to publication.
Last Updated:
Speak to Analyst

Customize this report to your needs - add regions, segments, or data points, with 20% free customization.
Or view our licence options:


ISO 9001:2015 & 27001:2022 Certified
We are GDPR and CCPA compliant! Your transaction & personal information is safe and secure. For more details, please read our privacy policy.


