
- Home
- »
- Advanced Interior Materials
- »
-
Automotive Bushing Market Size And Share Report, 2033GVR Report cover

Automotive Bushing Market (2026 - 2033)
Size, Share & Trends Analysis Report By Vehicle Type (HCV, LCV, Passenger), By Application (Suspension, Engine, Chassis, Interior, Exhaust, Transmission), By Region, And Segment Forecasts
Market Size, 2025
$170.0BMarket Estimate, 2026
$178.1BMarket Forecast, 2033
$251.3BCAGR, 2026–2033
5.0%Automotive Bushing Market Summary
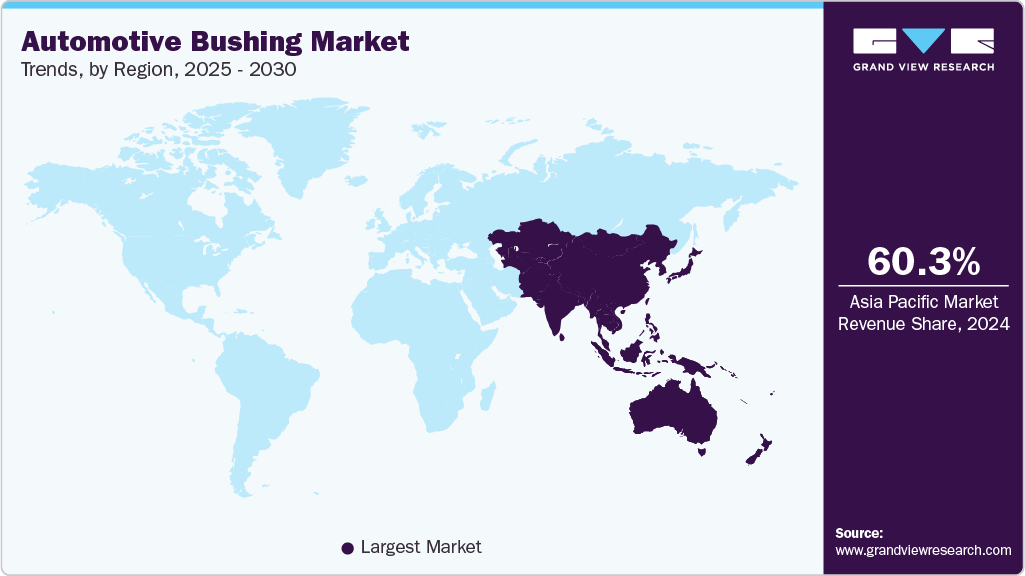
The global automotive bushing market size was valued at USD 170.0 billion in 2025 and is projected to grow from USD 178.1 billion in 2026 to USD 251.3 billion by 2033, at a CAGR of 5.0% from 2026 to 2033. Asia Pacific dominated the market, accounting for a revenue share of 60.3% in 2025. Increasing focus on vehicle safety and performance is a key driving factor that is encouraging the growth of the automotive bushings industry worldwide.
 Source: Grand View Research, IR Documents, Primary Interviews, Paid DatabasesTo learn more about this report,
 Download Free Sample Report
Key Market Trends & Insights
- By vehicle type: Heavy commercial vehicle segment led the market with the largest revenue share of 41.2% in 2025.
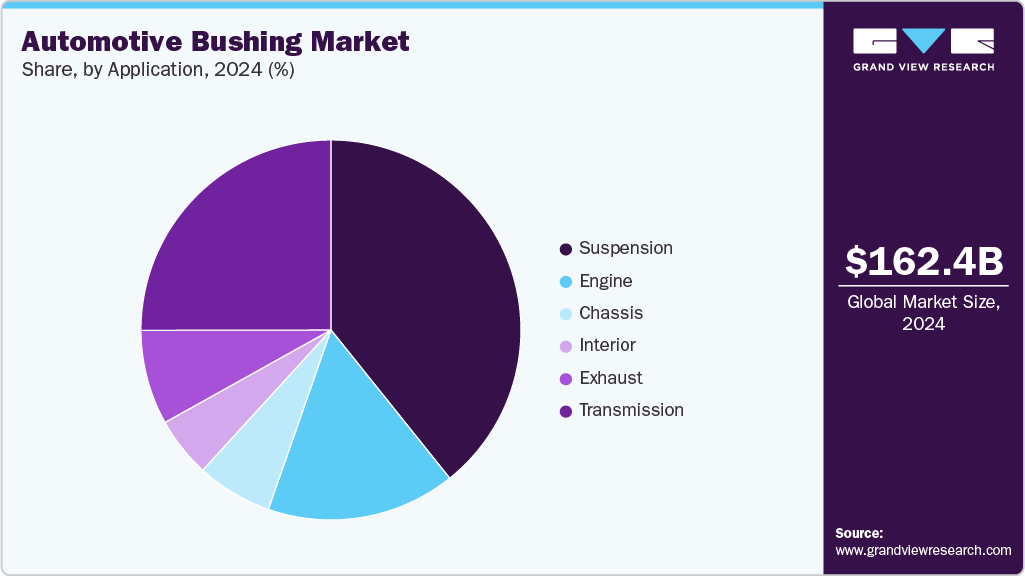
- By application: Suspension segment led the market with the largest revenue share of 39.1% in 2025
Regional Highlights
- Largest regional market: Asia Pacific (60.3% revenue share, 2025)
- Fastest-growing regional market: North America (highest CAGR, 2026-2033)
- By country: China held the largest market share in 2025.
Market Size & Forecast
- Market size in 2025: USD 170.0 Billion
- Estimated market size in 2026: USD 178.1 Billion
- Projected market size by 2033: USD 251.3 Billion
- CAGR (2026-2033): 5.0%
Three ways to get this report
Buy it, customize it, or ask a question.Ask an Analyst
Analyst response in 1 business day
- AccessReport author, directly
- Reply timeWithin 1 working day
- No sales callDirect answer only
- FormatEmail reply
- CostFree, no cost
Get the Full Report
What the study covers
- FormatsPDF · Excel · Dashboard
- Timeline2026–2033 annual, 2025 base
- Coverage20+ countries, 5 regions
- Companies10+ key players profiled
Customize the Report
20% free customization
- IncludeCountries, segments, points
- TailorTo your product definition
- ExtendDeeper competitor detail
- OrA fully bespoke study
- Turnaround5–10 working days
Automotive manufacturers and consumers emphasize enhanced vehicle handling, ride comfort, and safety features. This has propelled the demand for high-quality bushings-essential components across different automotive systems that help absorb shocks and reduce vibrations. Besides, improvements in the traditional bush designs and materials have further contributed to smoother driving experience and overall vehicle stability, leading to higher demand for advanced bushing solutions.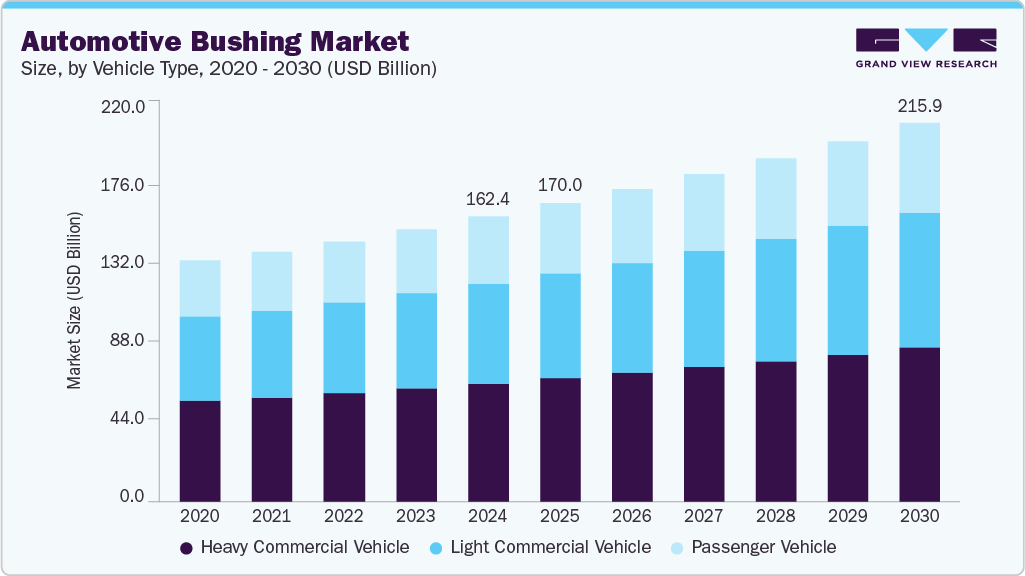 To learn more about this report, Download Free Sample Report
Automotive bushings serve as critical components in a vehicle's suspension system, designed to reduce vibration, noise, and impact between metal parts. These bushings are typically made from a combination of rubber and metal, providing a cushion that absorbs shocks and minimizes the transmission of road imperfections to the vehicle's frame. By isolating different parts of the suspension system, bushings help maintain smooth and controlled handling, ensuring the ride remains comfortable and stable. The types of bushings can vary, including control arm bushings, sway bar bushings, and engine mount bushings, each serving a specific function within the vehicle's architecture.
Advancements in material science and increasing consumer demand for enhanced vehicle performance and comfort are major driving factors influencing the development and use of automotive bushings. As high-strength composites and synthetic elastomers become more prevalent, the use of bushings that offer improved durability, reduced noise, and better performance under various driving conditions is gaining traction. In addition, consumer expectations for a smooth, quiet, and responsive ride drive manufacturers to continually innovate and refine bushing technology to meet high standards of comfort and handling. Besides, the continuously growing vehicle manufacturing across different vehicle types and the growing significance of electric vehicles (EVs) are further encouraging the growth of certain bushings. For instance, the 9.6% growth in India’s automotive production (28 million units in FY 2023-24) boosts demand for automotive bushings, as every vehicle requires multiple bushings for suspension, engine mounts, and chassis systems. Similarly, growing vehicle production
However, one significant restraining factor is the cost of advanced bushing materials and manufacturing processes. While high-performance bushings can provide substantial benefits, their production can be more expensive than traditional rubber bushings. This increased cost can impact the vehicle's overall price, making it a consideration for manufacturers and consumers. Balancing performance and cost remains a challenge, as manufacturers must weigh the benefits of advanced bushings against their impact on vehicle affordability and market competitiveness.
Market Dynamics
The automotive bushing market is influenced by increasing vehicle production, continuous advancements in suspension and chassis systems, and growing demand for enhanced ride comfort, noise reduction, and vibration control. Manufacturers are focusing on developing lightweight, high-performance bushings using advanced rubber, polyurethane, and composite materials to improve durability while supporting vehicle weight reduction and fuel efficiency goals. The expanding production of electric and hybrid vehicles is creating opportunities for specialized bushings designed to withstand unique load characteristics and reduce cabin noise. At the same time, the aftermarket continues to benefit from periodic replacement requirements as bushings are wear-prone components. However, fluctuations in raw material prices, pricing pressure from OEMs, and the increasing complexity of automotive component validation present challenges for manufacturers operating in this market.
Automakers are increasingly adopting lightweight materials and advanced suspension technologies to improve fuel efficiency, vehicle handling, and overall driving comfort. This has accelerated the use of durable automotive bushings that offer improved vibration isolation, longer service life, and compatibility with modern vehicle architectures. The integration of advanced suspension systems in passenger cars and commercial vehicles is further strengthening demand for precision-engineered bushings. Growing consumer preference for improved vehicle stability, reduced cabin noise, and enhanced driving performance is also encouraging broader adoption across vehicle platforms.
Fluctuating prices of rubber, polyurethane, synthetic elastomers, and metal components create cost uncertainties for bushing manufacturers. At the same time, strong pricing pressure from automotive OEMs limits margin expansion and increases the need for cost-efficient manufacturing processes. Manufacturers also face challenges in maintaining consistent product quality while meeting stringent automotive performance and durability standards. Intense competition from regional suppliers further constrains profitability, particularly in price-sensitive markets.
The rapid adoption of electric and hybrid vehicles is creating demand for specialized bushings designed to minimize noise, absorb higher torque loads, and support lightweight chassis designs. Continuous innovation in material engineering and suspension systems is opening new growth opportunities for manufacturers developing application-specific bushing solutions. Increasing investments in next-generation mobility platforms and premium vehicle segments are accelerating the adoption of advanced bushing technologies. Furthermore, the growing replacement demand in the automotive aftermarket presents additional opportunities for manufacturers to expand their product offerings and geographic presence.
Market Concentration & Characteristics
The market growth stage is low, and the pace of growth is accelerating. The automotive bushing market is experiencing moderate innovation, driven by the demand for lightweight and durable materials such as polyurethane and advanced composites, and the shift toward EVs requiring superior noise and vibration damping. However, innovations face challenges due to high R&D costs and slow adoption in budget vehicles, where cost sensitivity limits the integration of advanced solutions.
The automotive bushing industry is also characterized by moderate merger and acquisition (M&A) activity by the leading players. Suppliers are increasingly targeting emerging markets, including India and China, to capitalize on growing regional demand and cost-efficient manufacturing bases. For instance, in April 2025, NOVOSENSE and Continental expanded their partnership to include system-based chips and low-side switches. This collaboration aims to improve vehicle safety, efficiency, and reliability while strengthening their global supply chains.
 To learn more about this report, Download Free Sample Report
The impact of regulations in the automotive bushing industry is moderate to high, driven by tightening global standards on noise, vibration, and harshness (NVH) control, emissions reduction, and material sustainability. Environmental and safety standards, such as emissions regulations and vehicle safety requirements, indirectly influence bushing design and materials. Regulations promoting lightweight vehicles and sustainability push manufacturers to innovate with eco-friendly materials.
The threat of substitutes is relatively moderate. Automotive bushings perform a specialized function in isolating vibrations and reducing noise between vehicle components. While alternative technologies like active suspension systems exist, they do not fully replace the need for bushing. Thus, substitutes pose a minimal immediate threat but could increase with future advancements in vehicle suspension technology.
The global automotive bushing market is moderately concentrated, with a few major companies leading the industry. These companies benefit from a strong brand reputation, wide distribution networks, and significant investments in research and development. Large automotive manufacturers and tier-1 suppliers are the main buyers, which increases the market’s concentration. To grow, companies focus on expanding their presence in different regions, especially in emerging markets like Asia-Pacific. They do this by forming partnerships, acquiring local businesses, and adapting their products to meet local regulations and customer needs.
Major Tier-1 suppliers, such as ContiTech Deutschland GmbH, Schaeffler AG, and many more, act as intermediaries between original equipment manufacturers (OEM) and bushing manufacturers, concentrating demand among fewer high-volume customers and leading to moderate end-use concentration.
Analyst Perspective
The automotive bushing market is expanding steadily as vehicle manufacturers continue to focus on improving ride comfort, noise and vibration reduction, and overall vehicle durability. Demand for high-performance bushings is increasing across suspension, engine, chassis, transmission, and exhaust systems as OEMs prioritize enhanced driving dynamics and component reliability. The transition toward lightweight vehicle platforms and electric vehicles is also encouraging the adoption of advanced elastomer, polyurethane, and composite bushing materials that offer improved durability while reducing vehicle weight. Furthermore, increasing global vehicle production and continuous investments in automotive manufacturing and platform development are supporting market expansion. Manufacturers that offer durable, lightweight, and application-specific bushing solutions with superior vibration isolation and longer service life are well positioned to capitalize on long-term growth opportunities.
Vehicle Type Insights
Based on vehicle type, the heavy commercial vehicle segment led the market with the largest revenue share of 41.2% in 2025 and is expected to grow significantly over the forecast period. Heavy commercial vehicles, including large trucks and buses, utilize automotive bushings in a more demanding context where durability and performance are of utmost importance. Bushings for such category vehicles are subjected to extreme loads and harsh driving conditions, including rough roads and high-speed travel. As a result, bushings for heavy commercial vehicles are designed to be exceptionally durable and resistant to wear and tear. They must also effectively manage vibrations and noise to enhance the driver’s comfort and vehicle stability. Innovations in bushing materials and designs, such as high-strength composites and advanced elastomers, are critical in addressing the unique challenges faced by heavy commercial vehicles, ensuring they can operate efficiently and reliably under severe conditions.
Light commercial vehicle type held the fastest growth in the automotive bushing market, registering a CAGR of 6.2% over the forecast period. In light commercial vehicles, such as delivery vans and small trucks, automotive bushings are essential for balancing load-bearing capacity with ride comfort. These vehicles often experience dynamic levels of stress and wear due to frequent stops, varying loads, and urban driving conditions. Consequently, bushings in light commercial vehicles need to be more robust to withstand the diverse demands of use while still providing adequate vibration damping and noise reduction. In 2024, the OICA correspondents' survey reported a global production of 20.90 million light commercial vehicles (LCV) units. This significant production volume further fuels the demand for automotive bushings, as light commercial vehicles require a wide range of bushings for suspension, steering, and engine components, contributing to market growth worldwide.
Application Insights
Based on application, the market is segmented into suspension, engine, chassis, interior, exhaust, and transmission.The suspension segment led the market with the largest revenue share of 39.1% in 2025. In the automobile suspension system, automotive bushings are crucial for managing the interface between various components, including control arms, sway bars, and struts. These bushings provide a buffer that absorbs shocks and vibrations from the road, enhancing ride comfort and vehicle handling. By reducing the transfer of road imperfections and minimizing noise, bushings in the suspension system contribute significantly to the vehicle's overall stability and smoothness. In modern vehicles, advanced bushing materials and designs improve performance and durability, addressing the need for comfort and responsive handling in increasingly sophisticated suspension systems. Additionally, the growing demand for EVs has also contributed to the growing demand for suspension bushings.
 To learn more about this report, Download Free Sample Report
The engine segment held the fastest growth in the automotive bushing market over the forecast period. Automotive bushings are used primarily in engine mounts to isolate engine vibrations and reduce the transfer of engine noise to the vehicle’s cabin. Engine mounts with high-quality bushings ensure the engine remains securely positioned while absorbing the vibrations and stresses generated during operation. This contributes to a quieter, more refined driving experience while protecting other vehicle components from undue stress. As automotive technology advances, including the introduction of electric and hybrid powertrains, the role of engine bushings is evolving. For instance, electric vehicles with different vibration characteristics than traditional internal combustion engines require specialized bushings to manage their powertrains' unique demands effectively.
Regional Insights
The automotive bushing market in North America is projected to grow at the fastest rate, with a CAGR of 5.4% during the forecast period. In North America, the consumption of automotive bushings is influenced by a strong focus on vehicle performance and consumer comfort. The U.S. automotive market, with its diverse range of vehicles from heavy-duty trucks to luxury sedans, drives demand for high-quality bushings that offer durability and enhanced ride quality. The popularity of pickup trucks and SUVs in North America has led to increased use of robust bushing designed to handle larger loads and off-road conditions. For example, the American automotive aftermarket industry frequently upgrades bushings to improve handling and comfort in performance vehicles and trucks, reflecting a consumer preference for high-performance enhancements and long-term durability.
U.S. Automotive Bushing Market Trends
In the North American automotive bushing market, the U.S. is projected to grow at the fastest rate over the forecast period. It also accounted for the largest regional revenue share in 2024. In the U.S., specific trends within the automotive bushing market focus on performance and customization. A strong aftermarket sector characterizes the U.S. automotive market. Consumers often seek to enhance their vehicles with upgraded bushings that improve handling, reduce noise, and extend component lifespan. This trend is evident in the popularity of aftermarket performance bushings for sports cars and trucks, designed to provide better control and comfort. Moreover, the rise of electric vehicles (EVs) in the U.S. market is driving demand for specialized bushings that address the unique characteristics of electric powertrains. Companies are developing advanced bushings to cater to the growing segment of EVs and hybrid vehicles, ensuring that they meet the specific needs of these new technologies.
Europe Automotive Bushing Market Trends
The automotive bushing market in Europe is expected to grow significantly over the forecast period. Europe, known for its emphasis on automotive engineering and environmental standards, is witnessing trends toward high-performance and eco-friendly automotive bushings. The production of 17.23 million units of motor vehicles in Europe in 2024, according to the OICA survey, directly impacts the automotive bushing market by driving demand for bushings used in various vehicle components, particularly in suspension and engine applications. The European market strongly emphasizes reducing vehicle emissions and improving fuel efficiency, leading to increased demand for lightweight and durable bushings. In addition, stringent noise and vibration regulations drive the adoption of advanced bushing materials that enhance comfort and compliance with environmental standards. Besides, the presence of key industry players including Continental AG and ZF Group also helps the market to perform significantly in the region.
Asia Pacific Automotive Bushing Market Trends
Asia Pacific dominated the automotive bushing market with the largest revenue share of 60.3% in 2025 and is further expected to grow significantly over the forecast period. In the Asia Pacific region, the consumption of automotive bushings is experiencing significant growth due to the burgeoning automotive industry and increasing vehicle production rates. Countries such as China and India are the major drivers of this trend, with robust automotive manufacturing sectors and rising vehicle ownership. Expanding passenger and commercial vehicle segments in these markets have increased demand for advanced bushing technologies that improve riding comfort and vehicle performance.
 To learn more about this report, Download Free Sample Report
The automotive bushing market in China held the largest share in the Asia Pacific region in 2025. China's rising vehicle production, especially in electric vehicles (EVs), directly boosts demand for high-performance bushings critical for noise, vibration, and harshness (NVH) control. For example, in April 2024, according to the publication of the U.S. International Trade Commission, Chinese EV exports increased 1,016% from 2018 to 2023, to nearly 1.6 million EVs exported in 2023, boosting demand for automotive bushings, essential for vehicle suspension and vibration control. Increased EV production drives growth and innovation in the bushing market, as EVs require specialized, high-performance components. This export surge directly supports the expansion of China’s automotive bushing industry.
Key Companies & Market Share Insights
Some of the key players operating in the market are ContiTech Deutschland GmbH, Schaeffler AG, Powerflex USA, MEYLE AG, Vogelsang Fastener Solutions, Teknorot and others. Global companies focus on capacity expansion, signing partnership agreements with distributors, and various other operational strategies to gain an edge in the competitive market.
-
ContiTech Deutschland GmbH, a division of Continental AG, excels in the automotive sector with a diverse range of high-quality automotive bushing products. Specializing in vibration control and noise reduction, ContiTech’s bushings are designed to enhance vehicle performance and comfort. Their portfolio includes engine mountings, transmission mounts, and suspension bushings, all engineered to meet stringent OEM standards. Leveraging advanced materials and innovative technologies, ContiTech’s automotive bushings offer superior durability and performance, contributing to smoother rides and extended vehicle life.
-
Schaeffler AG is a global supplier of automotive components, including a comprehensive range of automotive bushings integral to their product lineup. Their automotive bushing portfolio encompasses engine, transmission, and suspension systems solutions, focusing on optimizing vehicle dynamics and reducing NVH (Noise, Vibration, and Harshness). With a strong emphasis on precision engineering, Schaeffler's products are designed to meet the demanding requirements of modern vehicles while enhancing overall driving comfort.
Key Automotive Bushing Companies:
The following key companies have been profiled for this study on the automotive bushing market.
-
Powerflex USA
-
GYCX Factory
-
MEYLE AG
-
ContiTech Deutschland GmbH
-
Vogelsang Fastener Solutions
-
Schaeffler AG
-
Teknorot
-
Kesaria Rubber Industries Pvt. Ltd.
-
Continental AG (Germany)
-
Vibracoustic
Competitive Benchmarking
Category
Operating Strategies
Competitive Edge
Weakness
Established Players (e.g., Continental AG, ContiTech Deutschland GmbH, Vibracoustic, Sumitomo Riko Co., Ltd., Schaeffler AG, MEYLE AG)
- Strengthen OEM partnerships and expand global manufacturing capabilities.
- Invest in advanced rubber-metal technologies, lightweight materials, and NVH-focused product innovation.
- Strong global presence with diversified product portfolios and established OEM relationships.
- Advanced R&D capabilities, high manufacturing standards, and extensive distribution networks.
- Higher manufacturing and operational costs compared to regional competitors.
- Exposure to OEM pricing pressure and fluctuations in global automotive production.
Emerging & Regional Players (e.g., eknorot, Powerflex USA, Kesaria Rubber Industries Pvt. Ltd., GYCX Factory)
- Focus on cost-efficient manufacturing and expansion in regional aftermarket channels.
- Develop customized products and strengthen regional distribution partnerships.
- Competitive pricing with greater flexibility to meet regional customer requirements.
- Strong presence in aftermarket applications and faster product customization.
- Limited global brand recognition and relatively lower R&D investments.
- Smaller international footprint and limited participation in global OEM supply chains.
Recent Developments
-
In September 2024, Continental AG introduced a new generation of hydraulic wheelset guiding bushings for train bogies, offering significantly improved pressure adaptation compared to conventional models.
-
In January 2024, Rheinmetall AG secured a significant new contract for engine components from a prominent, internationally operating vehicle manufacturer. The order comprises rocker arm bushings for various engine variants within the heavy transport sector.
-
In January 2024, Jiangyin Fangchen Auto Parts Co., Ltd. introduced its latest Suspension Bushing Sets designed for Mercedes-Benz, BMW, and Audi series vehicles.
Automotive Bushing Market Report Scope
Report Attribute
Details
Market size in 2025
USD 170.0 billion
Estimated market size in 2026
USD 178.1 billion
Projected market size by 2033
USD 251.3 billion
Growth rate
CAGR of 5.0% from 2026 to 2033
Base year for estimation
2025
Historical data
2021 - 2024
Forecast period
2026 - 2033
Quantitative units
Revenue in USD billion and CAGR from 2026 to 2033
Report coverage
Revenue forecast, company ranking, competitive landscape, growth factors, and trends
Segments covered
Vehicle type, application, region
Regional scope
North America; Europe; Asia Pacific; Latin America; Middle East & Africa
Country scope
U.S., Canada, Mexico, Germany, UK, France, Italy, Spain, China, Japan, India, South Korea, Brazil, Argentina, Saudi Arabia, South Africa
Key companies profiled
Continental AG; ContiTech Deutschland GmbH; Vibracoustic; Sumitomo Riko Co., Ltd.; Schaeffler AG; MEYLE AG; Teknorot; Powerflex USA; Kesaria Rubber Industries Pvt. Ltd.; GYCX Factory
Customization scope
Free report customization (equivalent up to 8 analysts' working days) with purchase. Addition or alteration to country, regional & segment scope.
Pricing and purchase options
Avail customized purchase options to meet your exact research needs. Explore purchase options
Global Automotive Bushing Market Report Segmentation
This report forecasts revenue growth at global, regional, and country levels and provides an analysis of the latest industry trends in each of the sub-segments from 2021 to 2033. For this study, Grand View Research has segmented the global automotive bushing market report based on vehicle type, application, and region:
 To learn more about this report, Download Free Sample Report
-
Vehicle Type Outlook (Revenue, USD Million, 2021 - 2033)
-
Heavy Commercial Vehicle
-
Light Commercial Vehicle
-
Passenger Vehicle
-
-
Application Outlook (Revenue, USD Million, 2021 - 2033)
-
Suspension
-
Engine
-
Chassis
-
Interior
-
Exhaust
-
Transmission
-
-
Regional Outlook (Revenue, USD Million, 2021 - 2033)
-
North America
-
U.S.
-
Canada
-
Mexico
-
-
Europe
-
Germany
-
UK
-
France
-
Italy
-
Spain
-
-
Asia Pacific
-
China
-
Japan
-
India
-
South Korea
-
-
Latin America
-
Brazil
-
Argentina
-
-
Middle East and Africa (MEA)
-
Saudi Arabia
-
South Africa
-
-
Research Methodology
The automotive bushing market figures in this report are based on a proven research process that combines executive interviews with secondary research from proprietary databases, company filings, and recognized regulatory and institutional sources. Market size is built through value-chain sizing - reconciling supply-side and demand-side estimates - and triangulated with bottom-up and top-down approaches. Every estimate passes multiple levels of expert validation before publication, with each automotive bushing segment quantified using the revenue-capture definitions in the table below.
Segment Definition
Segment - Vehicle Type
Revenue Capture Definition
Heavy Commercial Vehicle
Revenue is generated from the sale of automotive bushings used in heavy commercial vehicles, including trucks, buses, and construction equipment, for suspension, chassis, engine, and drivetrain applications.
Light Commercial Vehicle
Revenue is generated from the sale of automotive bushings installed in light commercial vehicles such as vans and pickup trucks to improve ride stability, vibration isolation, and component durability.
Passenger Vehicle
Revenue generated from the sale of automotive bushings used in passenger cars, including hatchbacks, sedans, SUVs, crossovers, and luxury vehicles, across suspension, engine, steering, and chassis systems.
Segment - Application
Revenue Capture Definition
Suspension
Revenue generated from the sale of automotive bushings used in suspension components such as control arms, stabilizer bars, and shock absorbers to improve ride comfort and vehicle stability.
Engine
Revenue generated from the sale of engine bushings and engine mount bushings designed to isolate engine vibration, reduce noise, and provide secure engine support.
Chassis
Revenue generated from the sale of automotive bushings installed in chassis assemblies, including subframes and structural mounting points, to enhance durability and vibration damping.
Interior
Revenue is generated from the sale of bushings used in interior vehicle components such as seats, dashboards, steering columns, and pedals to minimize noise and vibration.
Exhaust
Revenue generated from the sale of bushings and isolators used in exhaust mounting systems to reduce vibration transfer and support exhaust assemblies.
Transmission
Revenue is generated from the sale of transmission bushings used in transmission mounts, shift linkages, and drivetrain assemblies to improve alignment, stability, and vibration control.
Estimation Model
Layer Name
Key Question
Description
Vehicle Production & Component Demand Layer
Where are automotive bushing required?
Analyze demand across passenger vehicles, light commercial vehicles, and heavy commercial vehicles. Assess vehicle production volumes, suspension, engine, chassis, transmission, exhaust, and interior system requirements to establish the addressable demand for automotive bushings in OEM vehicle manufacturing.
Automotive Manufacturing & Platform Development Layer
Where is new product demand being created?
Evaluate investments in automotive manufacturing, production capacity expansion, new vehicle platforms, and electrification initiatives across major automotive markets. Assess OEM production plans, localization strategies, and model launches that drive procurement of new automotive bushings.
Product Adoption Layer
Which automotive bushing technologies are being deployed?
Segment demand by material type, vehicle type, application, and sales channel. Apply adoption rates based on vehicle architecture, load-bearing requirements, vibration and noise reduction, durability, and performance specifications.
Revenue Generation Layer
How much market revenue is generated?
Estimate annual shipments of automotive bushings by material, vehicle type, application, and region. Quantify revenues generated exclusively from the sale of new automotive bushings supplied to OEMs and Tier-1 automotive component manufacturers.
Delivered Customizations
This report has been delivered with the following In-depth customizations
CLIENT REQUEST
CUSTOMIZATION DELIVERED
VALUE ADDS
Competitive Benchmarking
A comprehensive competitive benchmarking analysis was conducted by assessing automotive bushing manufacturers based on product portfolio, material expertise, manufacturing capabilities, geographic presence, innovation initiatives, strategic partnerships, and competitive positioning within the automotive bushing market.
Enabled stakeholders to evaluate competitive positioning, identify product and material differentiation opportunities, benchmark industry best practices, and develop effective market positioning and growth strategies.
Regional Segmentation
A detailed regional assessment was conducted across major markets, evaluating vehicle production trends, automotive manufacturing hubs, regulatory standards, supply chain dynamics, aftermarket demand, and regional growth factors influencing the automotive bushing market. The analysis also examined the contribution of major countries to regional market performance.
Helped stakeholders identify high-growth regional markets, optimize expansion strategies, strengthen supply chain planning, and align product portfolios with regional automotive manufacturing and replacement demand.
Opportunity Assessment
A detailed opportunity assessment was conducted by analyzing advancements in lightweight materials, electric vehicle adoption, suspension system innovations, aftermarket replacement demand, and evolving OEM requirements across the automotive bushing market. The study identified high-potential growth areas across vehicle segments, applications, and emerging mobility platforms.
Enabled stakeholders to identify attractive investment opportunities, align product development with evolving automotive requirements, strengthen innovation strategies, and capitalize on growth across electric vehicles, advanced suspension systems, and the expanding aftermarket sector.
Frequently Asked Questions About This Report
The suspension segment accounted for the largest revenue share of 39.1% in 2025.
The global automotive bushing market size was estimated at USD 170.0 billion in 2025 and is expected to be USD 178.1 billion in 2026.
The global automotive bushing market, in terms of revenue is expected to grow at a compound annual growth rate of 5.0% from 2026 to 2033 to reach USD 251.3 billion by 2033.
Asia Pacific dominated the automotive bushing market with the largest revenue share of 60.3% in 2025.
Some key players operating in the automotive bushing market include Continental AG, ContiTech Deutschland GmbH, Vibracoustic, Sumitomo Riko Co., Ltd., Schaeffler AG, MEYLE AG, Teknorot, Powerflex USA, Kesaria Rubber Industries Pvt. Ltd., and GYCX Factory
The heavy commercial vehicle segment led the market with the largest revenue share of 41.2% in 2025.
Key factors include increasing global vehicle production, growing demand for enhanced ride comfort and vibration isolation, rising adoption of lightweight suspension components, expanding commercial vehicle fleets, and advancements in rubber-metal composite materials that improve durability and vehicle performance.
About the Author(s)
Advanced Interior Materials Research Team
Advanced Materials · Advanced Interior MaterialsThis report was authored by the advanced interior materials research team at Grand View Research - comprising two research analysts, one senior research analyst, and one industry expert - with specialized expertise in the advanced interior materials segment of the advanced materials industry. All findings are based on proprietary advanced materials databases, executive interviews, and regulatory analysis, subject to internal peer review prior to publication.
Last Updated:
Speak to Analyst

Customize this report to your needs - add regions, segments, or data points, with 20% free customization.
Or view our licence options:


ISO 9001:2015 & 27001:2022 Certified
We are GDPR and CCPA compliant! Your transaction & personal information is safe and secure. For more details, please read our privacy policy.


