
- Home
- »
- Automotive & Transportation
- »
-
Automotive Digital Cockpit Market Size Report, 2026-2033GVR Report cover

Automotive Digital Cockpit Market (2026 - 2033)
Size, Share & Trends Analysis Report By Equipment (Digital Instrument Cluster, Driving Monitoring System, Head-up Display (HUD)), By Display Technology (LCD, TFT-LCD, OLED), By Vehicle Type, By Region, And Segment Forecasts
Market Size, 2025
$26.8BMarket Estimate, 2026
$29.4BMarket Forecast, 2033
$69.8BCAGR, 2026–2033
13.2%Automotive Digital Cockpit Market Summary
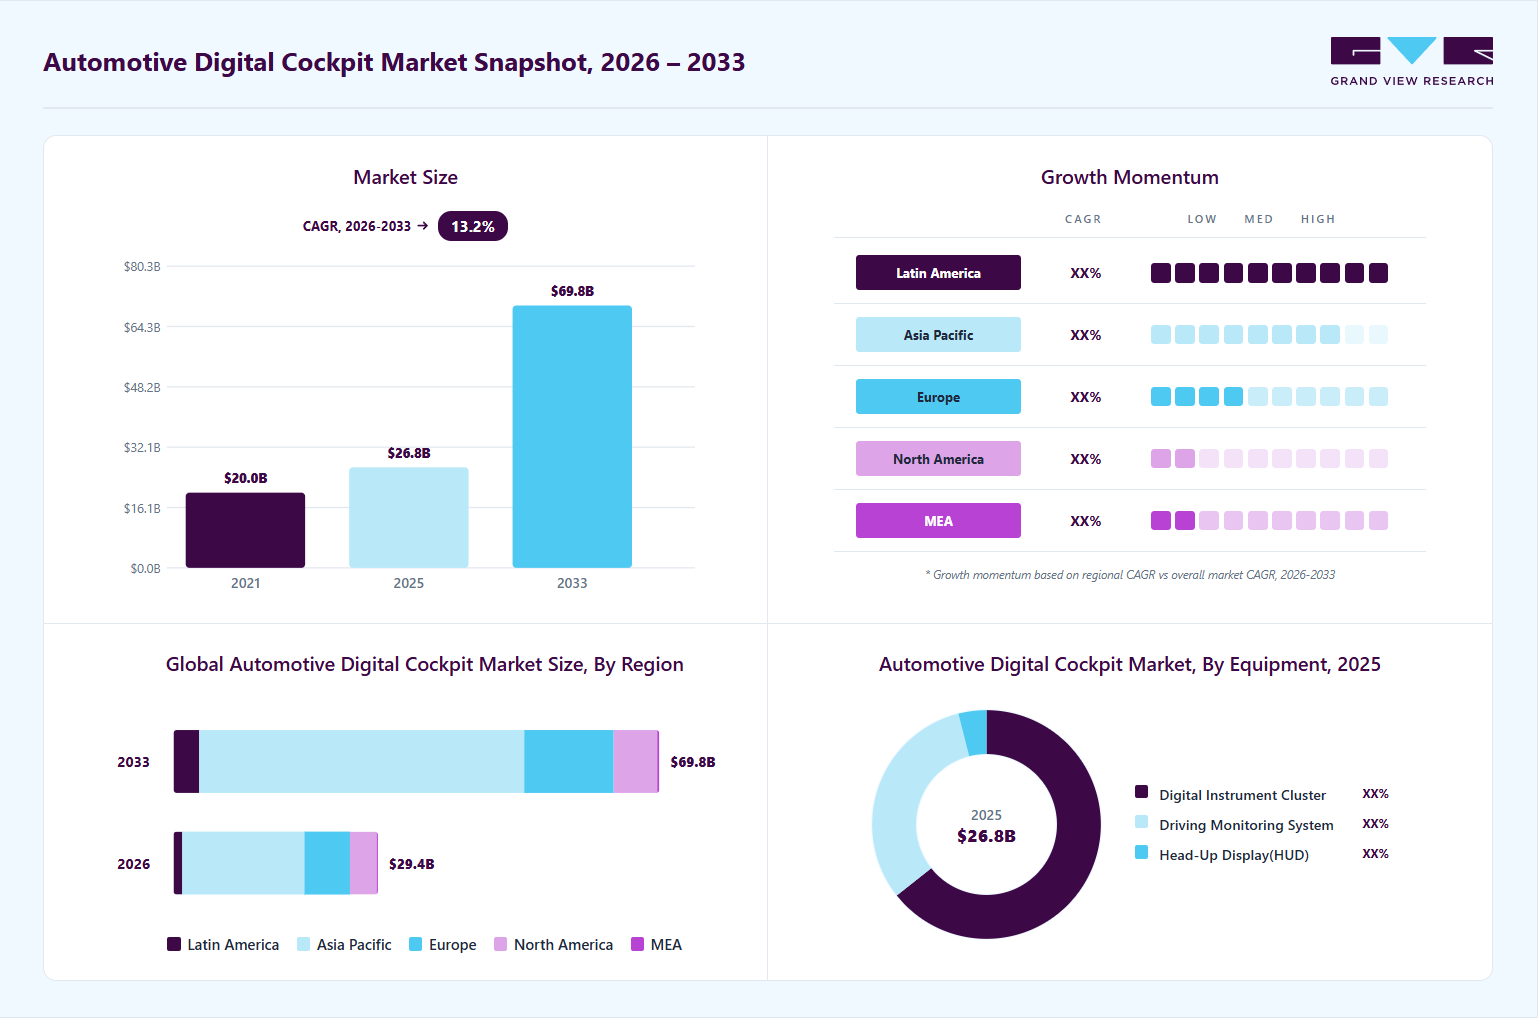
The global automotive digital cockpit market size was valued at USD 26.8 billion in 2025 and is projected to grow from USD 29.4 billion in 2026 to USD 69.8 billion by 2033, at a CAGR of 13.2% from 2026 to 2033. Asia Pacific dominated the global market with the largest revenue share of 59.2% in 2025. Due to the increasing pace of urbanization and rising disposable income levels, growing sales of passenger cars and commercial vehicles have compelled manufacturers to launch vehicle models that integrate advanced digital cockpit solutions.
 Source: Grand View Research, IR Documents, Primary Interviews, Paid DatabasesTo learn more about this report,
 Download Free Sample Report
Key Market Trends & Insights
- By equipment: Digital Instrument Cluster segment dominated the market, with a revenue share of 64.3% in 2025.
- By display technology: TFT-LCD segment held the largest market share of 54.2% in 2025.
- By vehicle type: Passenger Cars segment held the largest revenue share in 2025.
Regional Highlights
- Largest regional market: Asia Pacific (59.2% revenue share, 2025)
- Fastest-growing regional market: Latin America (highest CAGR, 2026-2033)
- By country: The Brazil is the fastest growing country in 2025.
Market Size & Forecast
- Market size in 2025: USD 26.8 Billion
- Estimated market size in 2026: USD 29.4 Billion
- Projected market size by 2033: USD 69.8 Billion
- CAGR (2026-2033): 13.2%
Three ways to get this report
Buy it, customize it, or ask a question.Ask an Analyst
Analyst response in 1 business day
- AccessReport author, directly
- Reply timeWithin 1 working day
- No sales callDirect answer only
- FormatEmail reply
- CostFree, no cost
Get the Full Report
What the study covers
- FormatsPDF · Excel · Dashboard
- Timeline2026–2033 annual, 2025 base
- Coverage20+ countries, 5 regions
- Companies10+ key players profiled
Customize the Report
20% free customization
- IncludeCountries, segments, points
- TailorTo your product definition
- ExtendDeeper competitor detail
- OrA fully bespoke study
- Turnaround5–10 working days
According to data from the International Organization of Motor Vehicle Manufacturers (OICA), total sales of passenger cars and commercial vehicles globally crossed 92.7 million in 2023, which was a sharp increase from the sales figure of around 82.9 million in 2022. Increasing awareness and popularity of electric vehicles in developed markets is another notable factor that has driven the adoption of these systems in vehicles. Using a digital cockpit enables multiple displays to be seamlessly connected, with each display accessing data from a centralized source that enables synchronization. This ensures that information regarding various functions can be easily obtained, which helps optimize the driving experience.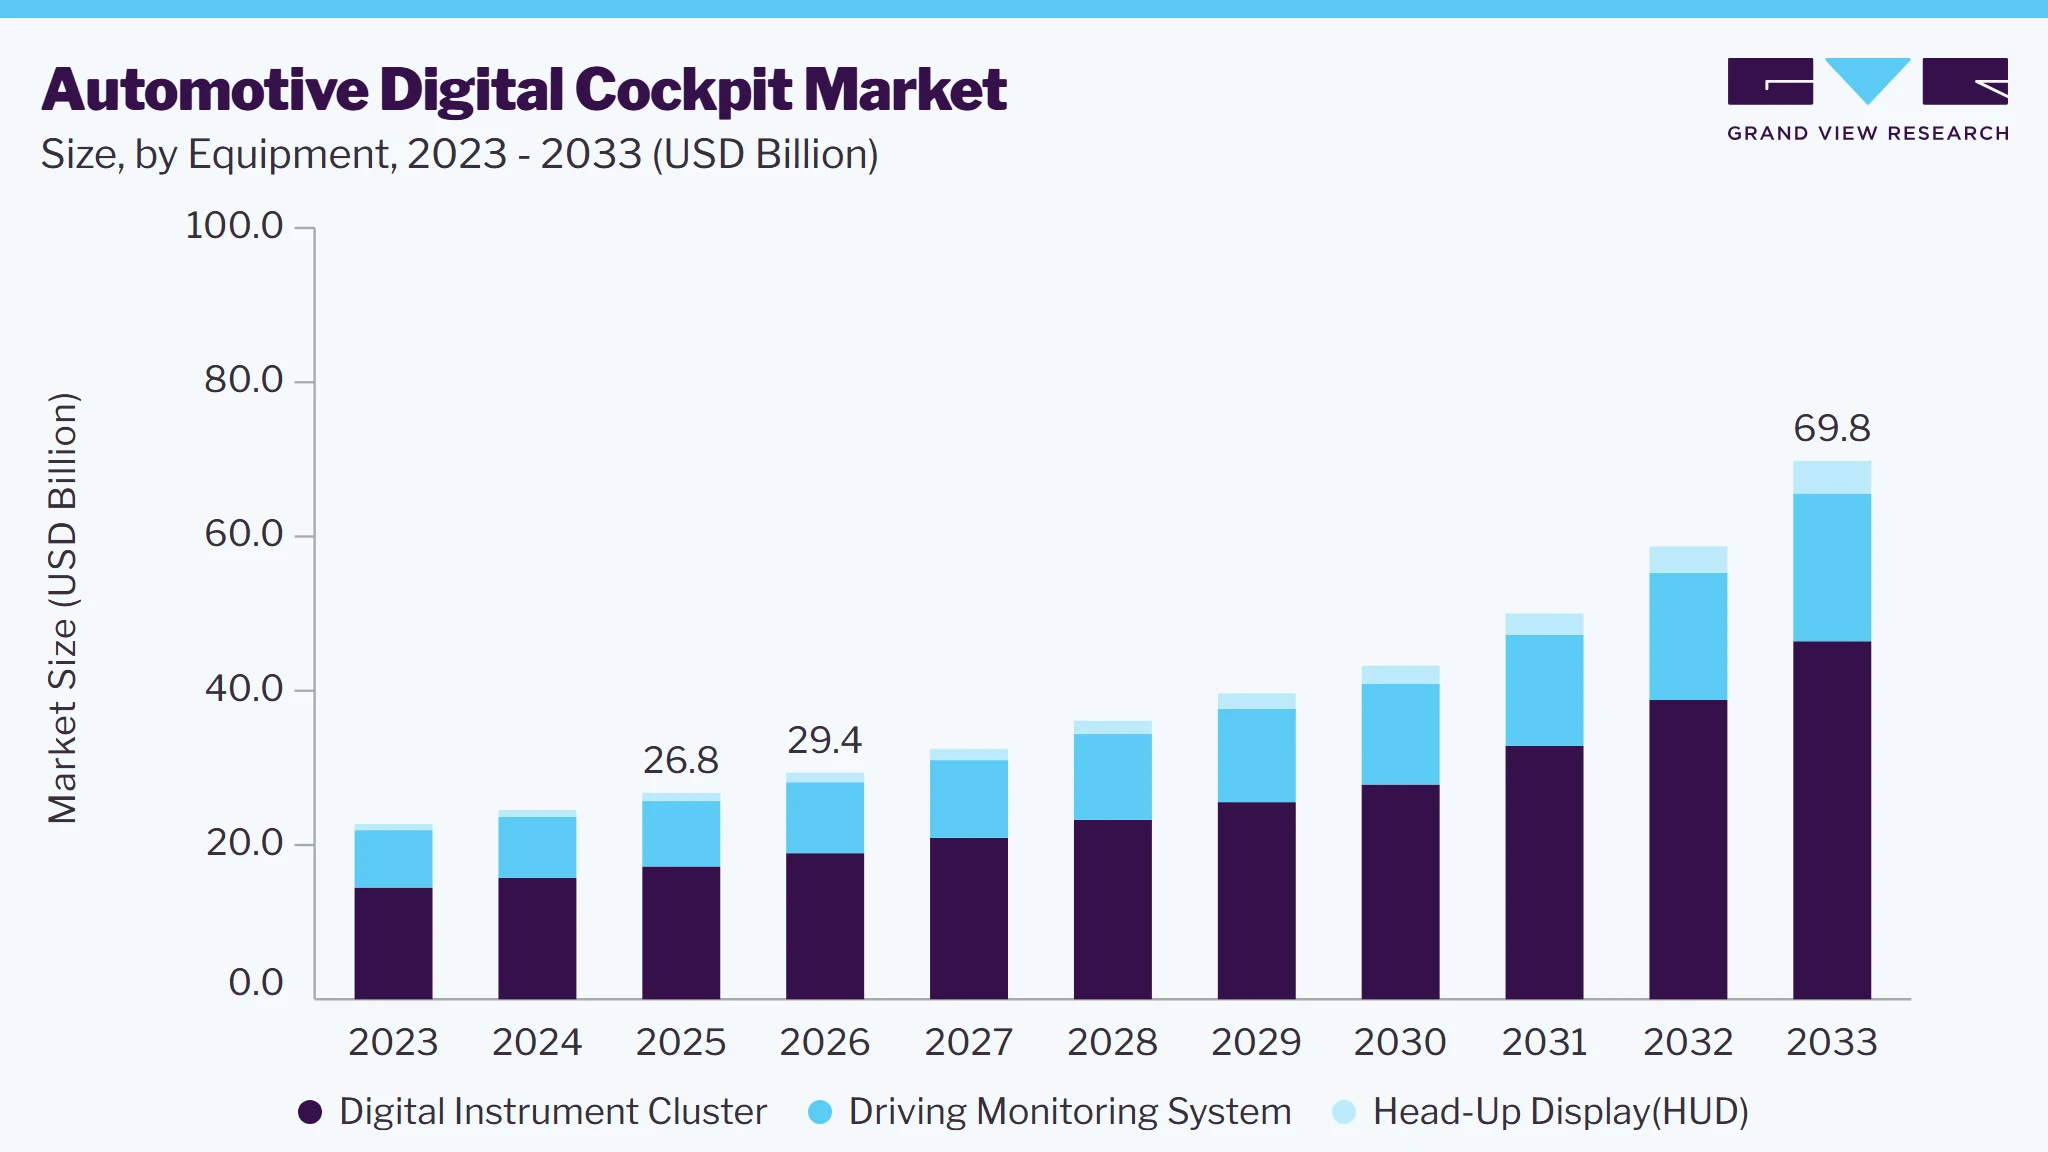 To learn more about this report, Download Free Sample Report
Rising smartphone penetration and widespread proliferation of the Internet have resulted in the extensive adoption of vehicles with digital cockpit systems, as they enable drivers to utilize various smartphone features without taking their hands off the wheel. Smartphone integration features such as Android Auto and Apple CarPlay allow users to access applications such as phone, music, and calendar via the car’s dashboard in a safe manner that does not divert their focus from driving. Furthermore, the integration of AI within automotive software to offer personalized experiences is expected to shape market growth during the forecast period, as automakers leverage this technology to customize the driving experience by understanding driver preferences and accordingly adjusting the cockpit display. For instance, Mercedes Benz, through its Mercedes-Benz User Experience (MBUX) infotainment system, integrates Advanced Driver Assistance Systems (ADAS), intelligent voice control, and a range of display solutions that help enhance interactions between the driver and the cockpit.
Innovations in display technology, artificial intelligence, and human-machine interfaces (HMIs) enable the development of more sophisticated and responsive digital cockpits, driving demand from both manufacturers and consumers. Constant developments in the AI space and the emergence of Generative AI are expected to boost market expansion in the coming years, with tech-based organizations looking to build upon the use cases of these technologies. For instance, in October 2024, Qualcomm announced a multi-year strategic partnership with Google to develop Generative AI-based digital cockpit solutions and software-defined vehicles (SDV). This collaboration would leverage the Snapdragon Digital Chassis and multiple in-vehicle technologies by Google, including Android Automotive OS and Google Cloud, to establish a standardized reference framework, enabling the creation of Gen AI-enabled in-car experiences.
Market Dynamics
Advancements in display technologies, cockpit domain controllers, human-machine interfaces (HMI), connected vehicle platforms, AI-powered voice assistants, and augmented reality (AR) applications are significantly enhancing the functionality, personalization, user experience, and safety of automotive digital cockpits across passenger and commercial vehicles. The integration of high-resolution displays, digital instrument clusters, infotainment systems, cloud connectivity, and over-the-air (OTA) updates further improves real-time information delivery, seamless connectivity, and software-driven feature enhancements. However, high development and integration costs, increasing software complexity, cybersecurity concerns, and stringent automotive safety and regulatory requirements elevate overall system costs and create challenges for manufacturers and OEMs. Meanwhile, growing consumer demand for connected and premium in-vehicle experiences, increasing adoption of electric and autonomous vehicles, advancements in vehicle digitalization, and the expansion of software-defined vehicle architectures are creating opportunities for market participants to develop intelligent, customizable, AI-enabled, and next-generation digital cockpit solutions.
The rapid evolution of digital display technologies, cockpit domain controllers, and advanced human-machine interface (HMI) systems has significantly enhanced the functionality, connectivity, and user experience of automotive digital cockpits. Modern digital cockpit platforms integrate high-resolution instrument clusters, infotainment systems, head-up displays (HUDs), augmented reality (AR) navigation, and intelligent voice assistants into a unified ecosystem, enabling seamless access to vehicle information, entertainment, and connected services. These next-generation solutions offer improved driver engagement, enhanced situational awareness, and personalized in-vehicle experiences, making them increasingly important across passenger vehicles, electric vehicles (EVs), and premium automotive segments.
The market is also witnessing growing integration of artificial intelligence, cloud computing, and connected vehicle technologies. AI-powered digital assistants enable natural language interactions, predictive recommendations, driver behavior analysis, and personalized content delivery, helping OEMs enhance customer experience and vehicle functionality. Furthermore, cloud-based platforms and over-the-air (OTA) software updates allow continuous feature upgrades, remote diagnostics, and cybersecurity enhancements, reducing maintenance requirements while improving vehicle lifecycle value.
Despite significant advancements in digital cockpit technologies, the high cost associated with hardware integration, software development, and system validation remains a major challenge for market growth. Modern automotive digital cockpits incorporate multiple high-resolution displays, advanced infotainment systems, cockpit domain controllers, head-up displays (HUDs), connectivity modules, and AI-powered applications, requiring substantial investments in research, development, testing, and vehicle integration. These costs are particularly challenging for mass-market vehicle segments, where affordability remains a key purchasing criterion.
The increasing complexity of software-defined vehicle architectures further adds to development and maintenance expenses. Automotive manufacturers must ensure seamless interoperability between instrument clusters, infotainment systems, advanced driver assistance systems (ADAS), telematics platforms, and cloud-based services while complying with stringent automotive safety and regulatory standards. The need for frequent software updates, cybersecurity management, and functional safety validation increases both operational complexity and time-to-market.
The increasing transition toward software-defined vehicles (SDVs), connected mobility platforms, and next-generation electric and autonomous vehicles is creating substantial growth opportunities for the automotive digital cockpit market. As consumers increasingly demand seamless connectivity, personalized in-vehicle experiences, and intelligent vehicle interactions, automotive manufacturers are investing heavily in advanced digital cockpit platforms that integrate infotainment, navigation, communication, and vehicle control functions into a unified ecosystem. This shift is accelerating the adoption of multi-display systems, AI-powered voice assistants, augmented reality (AR) interfaces, and cloud-connected cockpit solutions across both premium and mass-market vehicle segments.
The rapid expansion of electric vehicle (EV) production is further driving demand for advanced digital cockpit technologies. EV manufacturers are increasingly leveraging digital cockpit systems to provide real-time battery monitoring, energy management insights, charging station navigation, and personalized user interfaces that enhance the overall driving experience. At the same time, the growing deployment of advanced driver assistance systems (ADAS) and autonomous driving technologies is increasing the need for sophisticated human-machine interfaces (HMIs) capable of delivering critical vehicle information in an intuitive and safe manner.
Analyst Perspective
The growing demand for connected vehicles, enhanced in-vehicle user experiences, electric vehicles, and software-defined vehicle architectures is driving strong growth in the automotive digital cockpit market. Automotive manufacturers are increasingly deploying digital cockpit solutions to deliver seamless connectivity, advanced infotainment, real-time vehicle information, personalized user experiences, and improved driver safety. Advances in display technologies, cockpit domain controllers, artificial intelligence, augmented reality (AR), driver monitoring systems, and cloud connectivity are enhancing functionality, responsiveness, and user engagement across a wide range of vehicle segments. Ongoing innovation in human-machine interfaces (HMI), over-the-air (OTA) software updates, voice assistants, and connected mobility platforms is expanding the adoption of digital cockpits in passenger cars, electric vehicles, luxury vehicles, and commercial vehicles. However, high development and integration costs, increasing software complexity, cybersecurity concerns, and stringent automotive safety requirements remain significant challenges, particularly for cost-sensitive vehicle segments and emerging manufacturers. The market is expected to grow steadily as automotive OEMs continue to invest in vehicle digitalization, connected mobility ecosystems, autonomous driving technologies, and next-generation intelligent cockpit platforms that enhance both driver and passenger experiences.
Equipment Insights
Based on equipment, the digital instrument cluster segment led the market with the largest revenue share of 64.3% in 2025 and is expected to maintain its leading position in the coming years. These systems are a collection of gauges and displays that provide drivers with real-time information about their vehicles. They have attained substantial popularity due to their ability to display information in a clear and concise manner, which helps enhance the overall driving experience. Digital instrument clusters offer a range of features that have driven their market demand. These include customizable displays that allow users to tailor the layout and information shown, such as speed, navigation, and multimedia controls, to their preferences. They also allow integration of various functions, including navigation, vehicle diagnostics, and driver assistance alerts, into a single display for convenience. Recent advancements have made it possible to support voice commands and touch interaction, enhancing usability while minimizing distractions.
The head-up display (HUD) segment is anticipated to advance at the fastest CAGR from 2025 to 2030. This component of the digital cockpit displays useful information directly in the line of sight of the driver, enabling them to monitor speed, understand routes, and be aware of warning signals that may otherwise be missed on secondary displays. A number of innovations have resulted in the substantial growth of this segment. For instance, modern HUDs increasingly utilize augmented reality (AR) to overlay navigation directions, speed limits, and hazard alerts onto the real-world view, making it easier for drivers to comprehend information without diverting their attention. Moreover, some HUDs offer 3D visuals that can enhance depth perception for navigation cues and other critical information, improving situational awareness. Another advancement has been the incorporation of eye tracking technologies, which can accurately detect where the driver is looking, adjusting displayed information accordingly to ensure that it remains relevant and in focus. In January 2022, at the CES 2022 event, Panasonic introduced its Augmented Reality HUD (AR HUD) 2.0 solution, which includes a patented eye tracking system (ETS). This technology identifies a driver’s height and head movement while driving and dynamically adjusts the images in the “eyebox,” enabling drivers to solely view clear and accurately positioned high-resolution icons and overlays.
Display Technology Insights
Based on display technology, the TFT-LCD segment led the market with the largest revenue share of 54.2% in 2025, owing to the extensive usage of this display type in digital cockpits due to their versatility and performance. TFT (Thin-Film Transistor) LCDs can provide high-resolution displays, enabling crisp and clear visuals for information such as speed, navigation, and multimedia content. They offer excellent viewing angles, allowing drivers and passengers to see the display clearly from different positions in the vehicle. The technology further allows for quick response times, reducing motion blur and ensuring that dynamic information, such as navigation changes, is displayed smoothly. They can be easily integrated with various vehicle systems, including infotainment, navigation, and driver assistance technologies, providing a cohesive user experience. Thus, benefits such as improved safety, enhanced user experience, and support for modern aesthetics are important factors enabling segment expansion.
The OLED segment is anticipated to expand at the fastest CAGR during the forecast period, as this technology has gained significant traction in recent years due to its advantages over conventional LCDs. OLEDs provide deeper blacks and higher contrast ratios, enhancing visibility and readability of information in various lighting conditions. Additionally, OLED displays can produce a wide color gamut, resulting in vibrant colors that improve the overall aesthetic of the digital cockpit. These panels are generally thinner and lighter than LCDs, allowing for more flexible design options and reduced weight in the vehicle. Furthermore, the technology allows for flexible displays, enabling innovative designs such as curved screens that can enhance the cockpit's layout. Many display technology companies are developing OLED solutions and partnering with leading automakers to incorporate these products in newer vehicle models. For instance, in April 2023, Samsung Display signed an agreement with Ferrari at the former’s Asan campus in Korea to develop an OLED display that would be implemented in Ferrari’s next-generation models.
Vehicle Type Insights
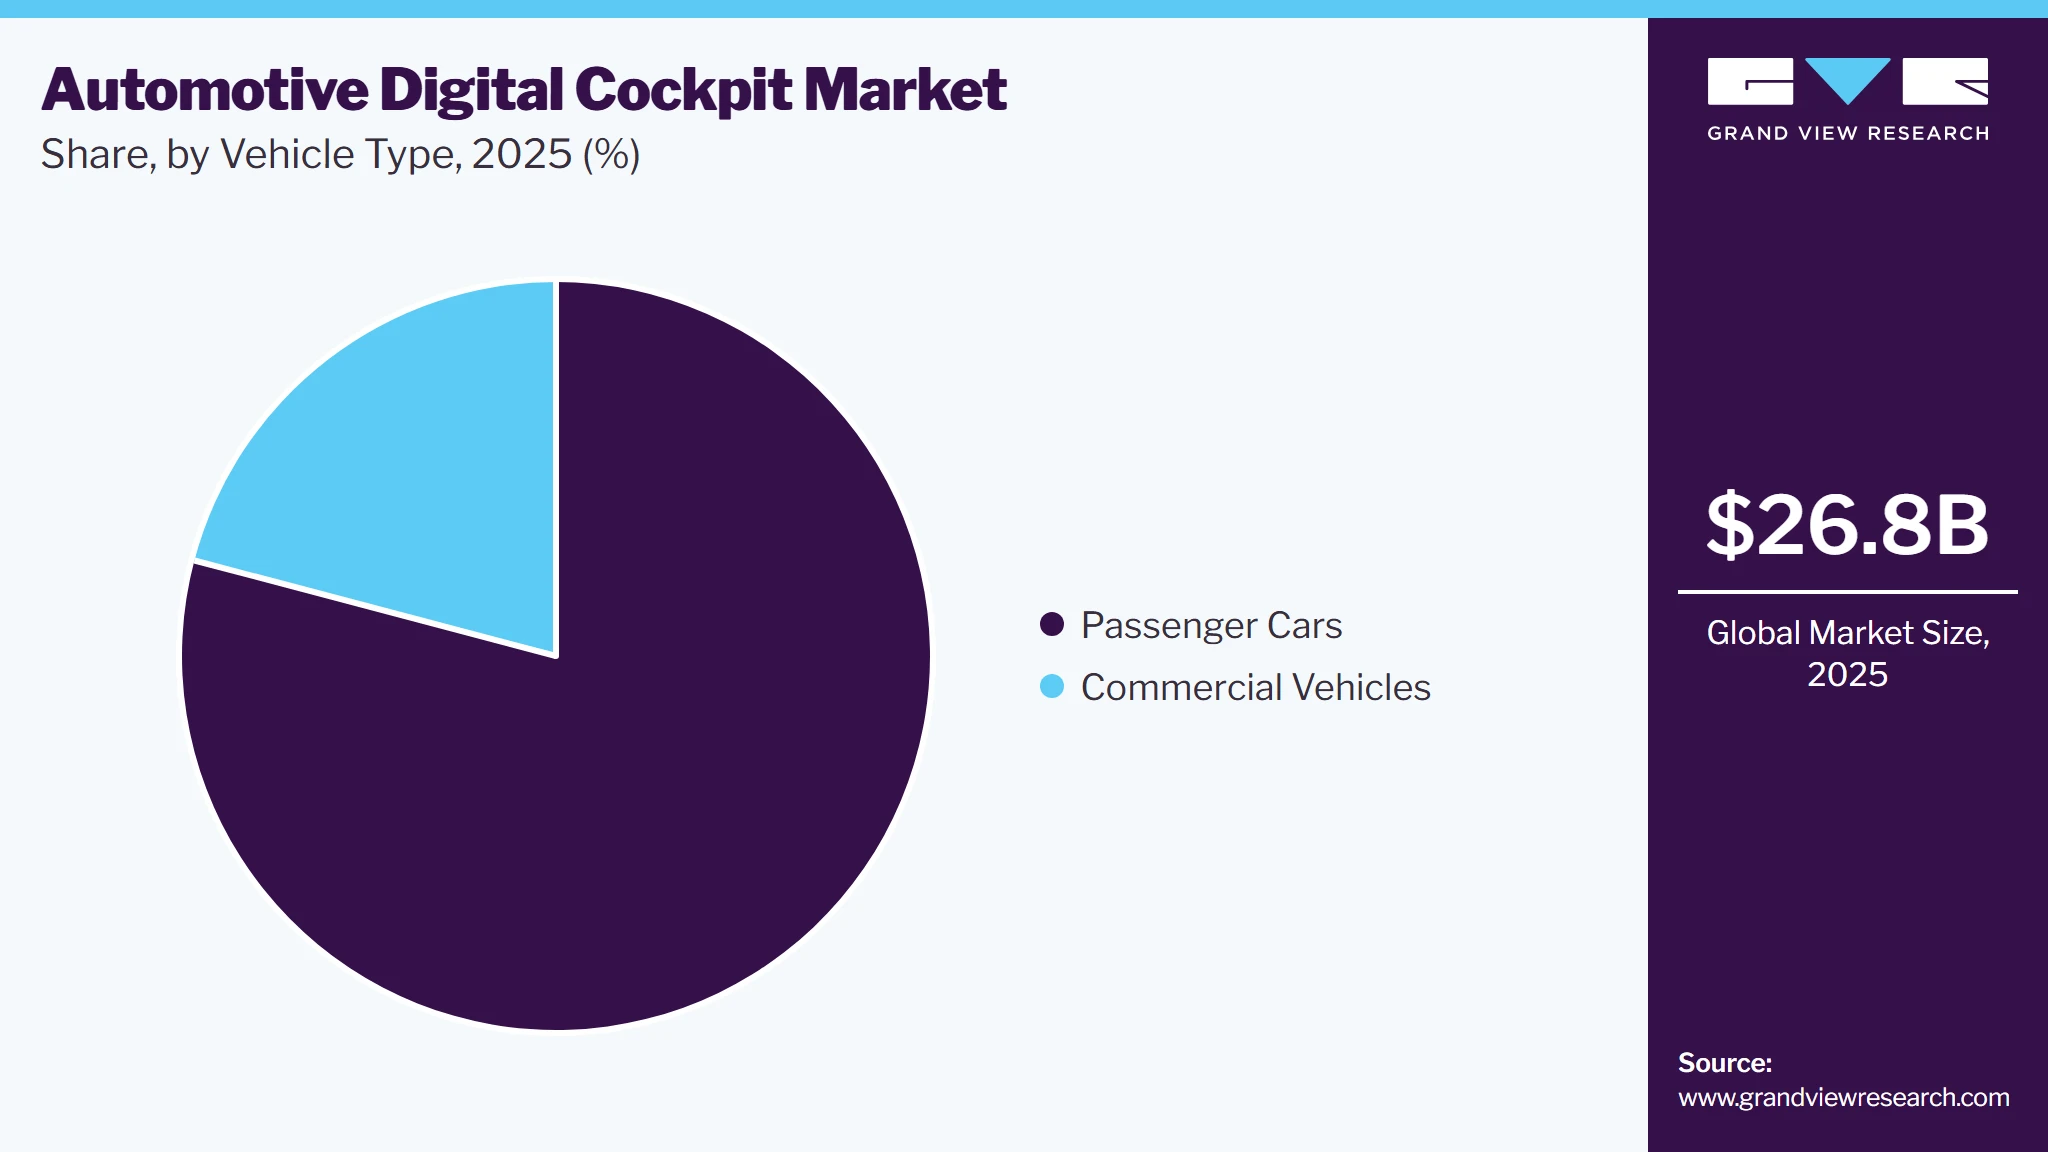
Based on vehicle type, the passenger cars segment led the market with the largest revenue share of 79.1% in 2025, on account of the increasing sales of these vehicles and a steadily rising demand for digital cockpit systems by consumers. As per the OICA, more than 70% of global vehicle sales in 2023 came from passenger vehicles, aided by higher living standards and growing disposable income levels. Rapid emergence and developments in the autonomous vehicles space and the incorporation of connected features by leading manufacturers are expected to maintain this segment’s position as the leading end-user of digital cockpits in the coming years.
 To learn more about this report, Download Free Sample Report
The commercial vehicles segment is expected to advance at a faster CAGR from 2025 to 2030, owing to the increasing integration of vehicle-to-vehicle communications technologies for fleet management. Digital cockpits in commercial vehicles transform how drivers interact with their vehicles, enhancing safety, efficiency, and overall usability. Digital displays provide real-time data on vehicle performance, fuel efficiency, navigation, and diagnostics, helping drivers make informed decisions. Many digital cockpits offer connectivity features that allow fleet managers to monitor vehicle performance, location, and driver behavior through integrated telematics. Moreover, integrating advanced driver-assistance systems enhances safety with features including lane departure warnings, adaptive cruise control, and collision avoidance alerts. Inbuilt communication systems enable drivers to stay connected with dispatchers, receive job updates, and manage logistics efficiently. These features ensure increased productivity and efficiency and smooth and seamless operations.
Regional Insights
Asia Pacific Automotive Digital Cockpit Market Trends
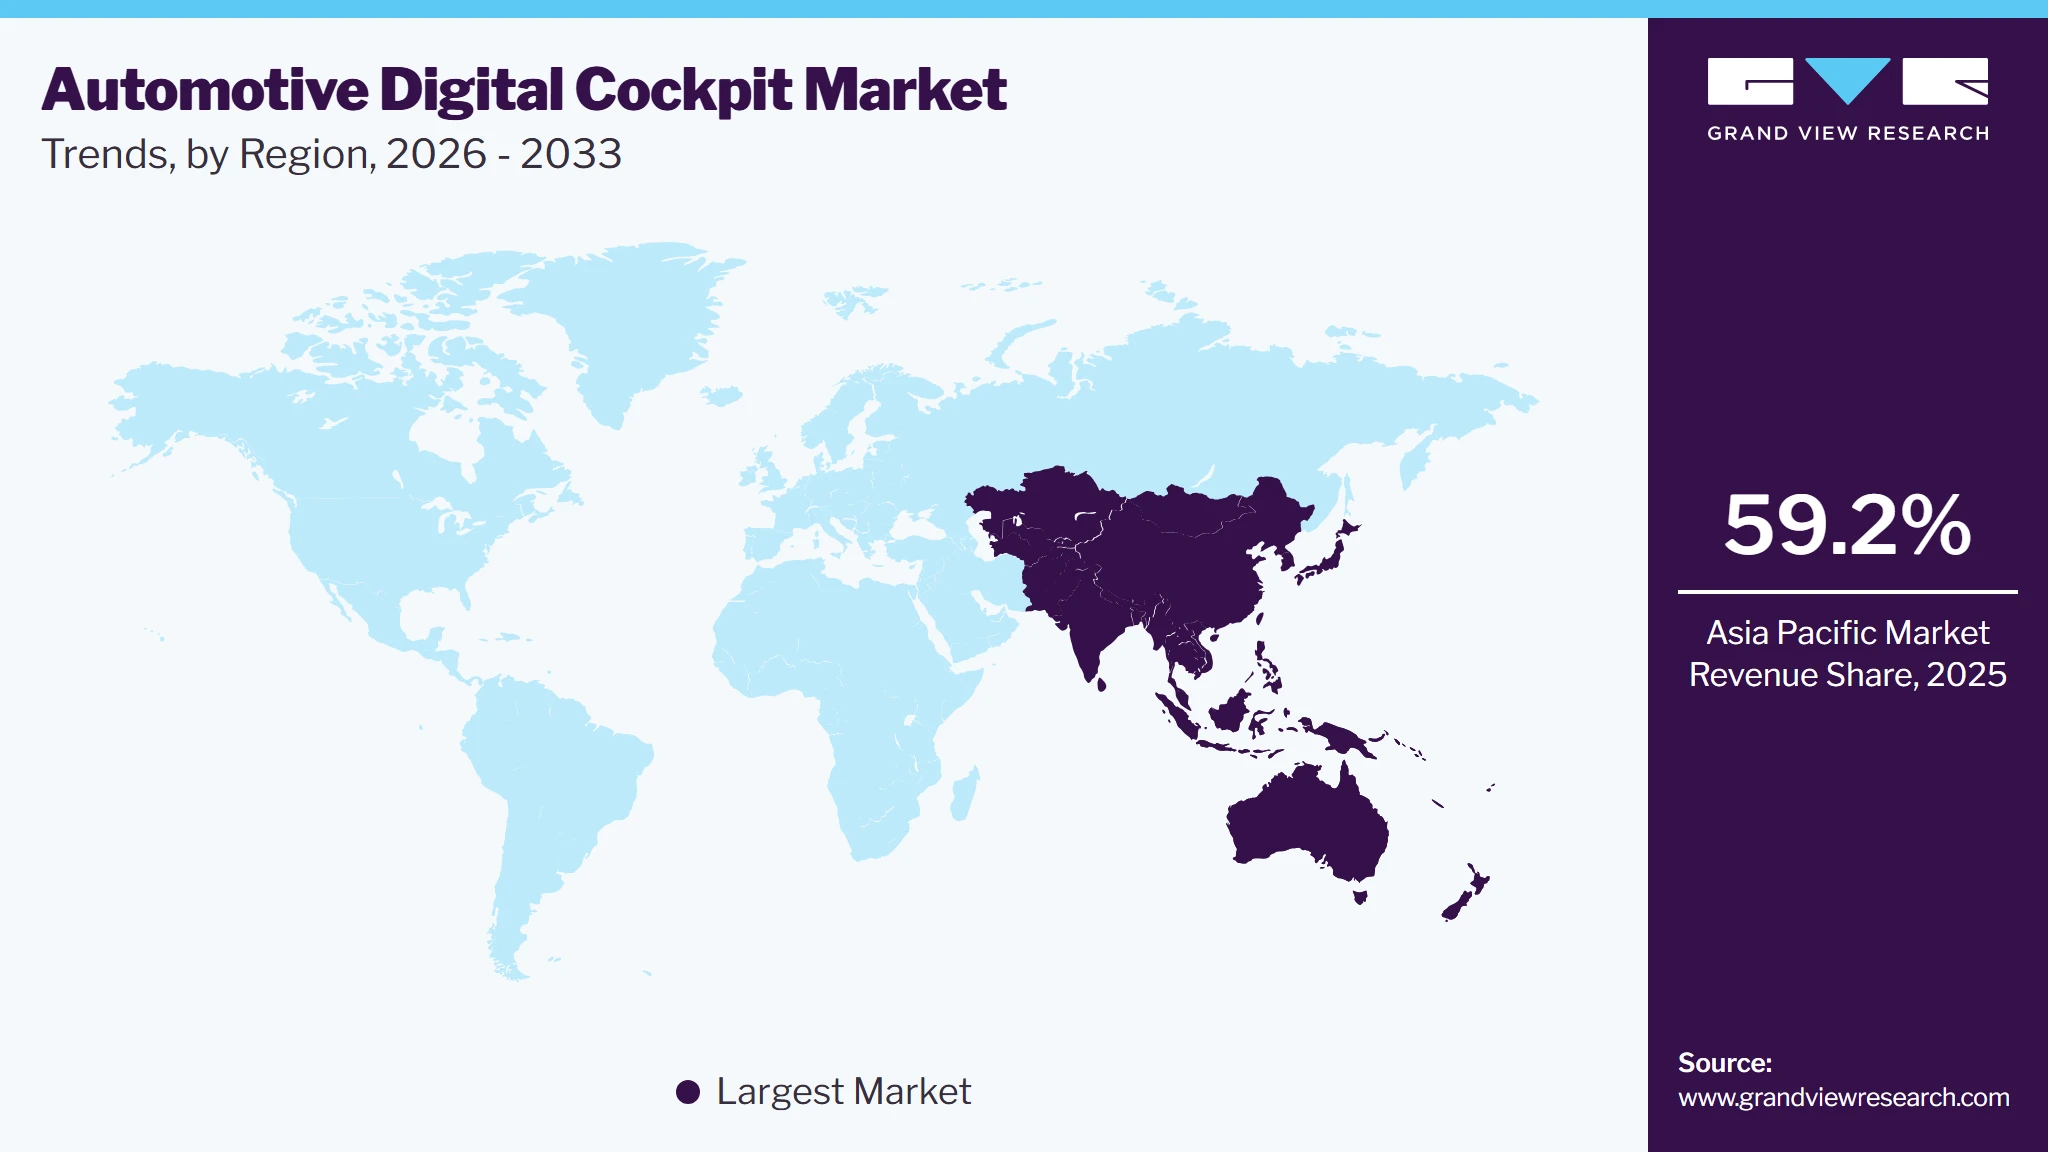
Asia Pacific dominated the global automotive digital cockpit market with the largest revenue share of 59.2% in 2025. India is the fastest growing country in the Aisa Pacific automotive digital cockpit market. The increasing pace of vehicle sales in the region and the need for advanced vehicular technologies to improve passenger experience has compelled manufacturers to launch innovative solutions in this industry. Furthermore, the rapidly growing popularity of electric vehicles, particularly in economies such as India and China, has propelled market expansion in recent years. Rising consumer expectations for connectivity, personalization, and seamless integration with smartphones and other devices are pushing manufacturers to adopt digital cockpit systems. Additionally, intensifying competition among regional automakers to provide premium features in their vehicle models has compelled them to partner with organizations such as DENSO, Panasonic, and HYUNDAI MOBIS, all of which have a notable regional presence.
 To learn more about this report, Download Free Sample Report
China accounted for a leading revenue share in the regional market in 2024. The fast pace of urbanization in the economy has significantly improved the living standards of citizens, leading to the rising demand for automobiles. Moreover, with the consistent push toward electric mobility by the Chinese government, there has been substantial growth in sales of EVs that incorporate head-up displays, voice assistants, and infotainment systems. According to a report by Canalys published in July 2024 , the proliferation rate of digital cockpits has increased steadily in the country, rising to 66% in 2023. This number is expected to reach 80% by 2025, enabled by a strong focus on software ecosystems and intelligent hardware integration. Artificial intelligence (AI) is also expected to play a vital role in this market, aiding constant advancements in driver monitoring and environmental feedback.
Europe Automotive Digital Cockpit Market Trends
Europe is anticipated to advance at a substantial CAGR during the forecast period because of the well-established automotive industry in regional economies such as Germany, the UK, and Spain. Moreover, ongoing technological advancements, rapidly evolving consumer preferences, and the shift toward electric and autonomous vehicles are expected to drive market advancements in the coming years. European manufacturers are integrating advanced technologies such as touchscreen displays, augmented reality, and voice recognition into digital cockpits, enhancing driver experience and functionality. Governments and technological leaders aim to accelerate the transformation of automotive AI and maintain the competitiveness of this sector in this region. Stricter regulations regarding safety and emissions in Europe are pushing automakers to innovate, with digital cockpits considered to be useful in providing essential information and controls that support compliance with these regulations.
Latin America Automotive Digital Cockpit Market Trends
The Latin America region is anticipated to advance at the fastest CAGR from 2025 to 2030. Economies such as Brazil and Mexico have seen large-scale development activities that have increased passenger and commercial vehicle sales. Consumer preferences in this region are rapidly shifting towards the adoption of connected vehicles owing to the increasing accessibility of advanced technologies and the growing presence of major digital cockpit solution providers. As a result, automotive manufacturers are introducing advanced models equipped with such systems. For instance, in November 2023, Citroën announced the launch of the C3 Aircross in Brazil, specifically developing the model for the South American market. It features a novel seven-seat configuration that offers convenience and flexibility, three driving modes, and specially tuned suspensions to ensure a smooth ride. The SUV includes a customizable 7-inch TFT digital dashboard and the Citroën Connect infotainment system with a 10-inch touchscreen equipped with Apple CarPlay and Android Auto.
Key Automotive Digital Cockpit Company Insights
Some of the major companies involved in the global automotive digital cockpit market include HYUNDAI MOBIS, Robert Bosch, and DENSO CORPORATION, among others.
-
HYUNDAI MOBIS, a subsidiary of the Hyundai Motor Group, is a South Korean automotive parts company primarily engaged in manufacturing automotive components and modules. It produces a wide range of automotive parts, including chassis, safety systems, and electronic parts and is also involved in the development of integrated modules, such as front-end modules and cockpit modules. The company invests heavily in developing technologies related to electric vehicles (EVs), autonomous driving, and connected car solutions. Much of its investment is directed towards research and development, particularly in areas including vehicle electrification and advanced driver-assistance systems (ADAS). HYUNDAI MOBIS has manufacturing plants and R&D centers globally, including locations in South Korea, the U.S., Europe, and China.
-
DENSO CORPORATION is a Japan-based global automotive parts manufacturer that develops and produces various products, including climate control systems, airbag systems, and spark plugs. DENSO also produces non-automotive components such as household heating equipment and industrial robots.
Key Automotive Digital Cockpit Companies:
The following key companies have been profiled for this study on the automotive digital cockpit market.
-
HYUNDAI MOBIS
-
Robert Bosch GmbH
-
Visteon Corporation
-
Continental AG
-
DENSO CORPORATION
-
Panasonic Holdings Corporation
-
Pioneer Corporation
-
SAMSUNG
-
FORVIA
-
Garmin Ltd.
Competitive Benchmarking
Category
Operating Strategies
Competitive Edge
Weakness
Established Players (Robert Bosch GmbH, Continental AG, DENSO Corporation, Visteon Corporatio)
• Focus on integrated digital cockpit platforms, cockpit domain controllers, AI-powered HMI solutions, connected infotainment systems, and advanced display technologies.
• Continuous investment in software-defined vehicle architectures, cloud connectivity, driver monitoring systems, augmented reality (AR) displays, and next-generation cockpit ecosystems.
• Strong global OEM relationships, extensive automotive electronics expertise, and comprehensive product portfolios covering instrument clusters, infotainment systems, HUDs, and cockpit controllers.
• Significant R&D capabilities, large-scale manufacturing infrastructure, strong brand recognition, and the ability to deliver integrated hardware-software solutions.
• High product development and integration costs associated with advanced cockpit platforms.
• Complex validation and qualification processes resulting in longer development cycles.
Emerging Players FORVIA
(Garmin Ltd.)
• Focus on specialized software platforms, AI-enabled voice assistants, digital HMI solutions, cloud-connected services, cockpit personalization, and software-defined vehicle technologies.
• Strong expertise in software development, AI technologies, cloud integration, and user-centric digital experiences.
• Limited manufacturing capabilities and smaller global footprint compared to established automotive suppliers.
Recent Developments
-
In October 2024, HYUNDAI MOBIS announced the signing of a Business Cooperation Agreement with the German optoelectronics company ZEISS. This partnership would oversee the development of the ‘Holographic Windshield Display' at the former’s technical research centre located in Yongin, Gyeonggi-do. The Holographic HUD technology leverages the windshield as a transparent display to monitor a range of driving information and can also utilize infotainment features such as videos, music, and games simultaneously. The companies aim to begin mass production of this technology in 2027.
-
In September 2024, Garmin introduced the Garmin Dash Cam X series, which includes four models of high-quality dash cameras. The product range comprises the Garmin Dash Cam X110, X210, Mini 3, and the X310. These compact systems offer video resolutions of up to 4K Ultra High Definition (UHD) that can act as proof in cases of unexpected traffic incidents. The dashcam series is integrated with the ‘Garmin Clarity’ polarizer lens enhancement to reduce windshield glare, along with Garmin Clarity HDR optics that enable sharp details to be captured in both low light and very bright conditions.
Automotive Digital Cockpit Market Report Scope
Report Attribute
Details
Market size value in 2025
USD 26.8 billion
Estimated market size in 2026
USD 29.4 billion
Projected market size by 2033
USD 69.8 billion
Growth rate
CAGR of 13.2% from 2026 to 2033
Base year for estimation
2025
Historical data
2021 - 2024
Forecast period
2026 - 2033
Quantitative units
Revenue in USD million/billion and CAGR from 2026 to 2033
Report coverage
Revenue forecast, company ranking, competitive landscape, growth factors, and trends
Segments covered
Equipment, display technology, vehicle type, region
Regional scope
North America; Europe; Asia Pacific; Latin America; MEA
Country scope
U.S.; Canada; Mexico; U.K.; Germany; France; Italy China; Japan; India; Australia; South Korea; Australia; Brazil; Kingdom of Kingdom of Saudi Arabia (KSA); UAE; South Africa
Key companies profiled
HYUNDAI MOBIS, Robert Bosch GmbH, Visteon Corporation, Continental AG, DENSO CORPORATION, Panasonic Holdings Corporation, Pioneer Corporation, SAMSUNG, FORVIA, and Garmin Ltd.
Customization scope
Free report customization (equivalent up to 8 analysts' working days) with purchase. Addition or alteration to country, regional & segment scope.
Pricing and purchase options
Avail customized purchase options to meet your exact research needs. Explore purchase options
Global Automotive Digital Cockpit Market Report Segmentation
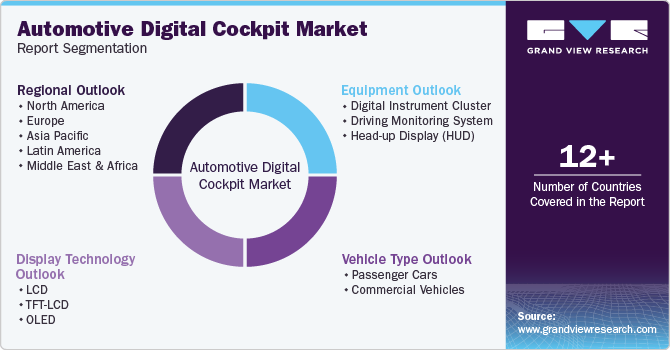
This report forecasts revenue and volume growth at the global, regional, and country levels and provides an analysis of the latest industry trends in each of the sub-segments from 2021 to 2033. For this study, Grand View Research has segmented the global automotive digital cockpit market report based on equipment, display technology, vehicle type, and region:
 To learn more about this report, Download Free Sample Report
-
Equipment Outlook (Volume, Units, Revenue, USD Billion, 2021 - 2033)
-
Digital Instrument Cluster
-
Driving Monitoring System
-
Head-up Display (HUD)
-
-
Display Technology Outlook (Volume, Units; Revenue, USD Billion, 2021 - 2033)
-
LCD
-
TFT-LCD
-
OLED
-
-
Vehicle Type Outlook (Volume, Units; Revenue, USD Billion, 2021 - 2033)
-
Passenger Cars
-
Commercial Vehicles
-
-
Regional Outlook (Volume, Units; Revenue, USD Billion, 2021 - 2033)
-
North America
-
U.S.
-
Canada
-
-
Europe
-
Germany
-
U.K.
-
Spain
-
-
Asia Pacific
-
China
-
Japan
-
India
-
-
Latin America
-
Brazil
-
Mexico
-
-
Middle East & Africa
-
Research Methodology
The automotive digital cockpit market figures in this report are based on a proven research process that combines executive interviews with secondary research from proprietary databases, company filings, and recognized regulatory and institutional sources. Market size is built through value-chain sizing - reconciling supply-side and demand-side estimates - and triangulated with bottom-up and top-down approaches. Every estimate passes multiple levels of expert validation before publication, with each automotive digital cockpit segment quantified using the revenue-capture definitions in the table below.
Segment Definition
Segment- Equipment
Revenue Capture Definition
Digital Instrument Cluster
This segment captures revenue generated from digital instrument cluster systems that replace traditional analog gauges with configurable digital displays. These systems provide real-time vehicle information such as speed, fuel level, battery status, navigation data, ADAS alerts, and vehicle diagnostics, enhancing driver awareness and user experience across passenger and commercial vehicles.
Driver Monitoring System (DMS)
This segment includes revenue derived from driver monitoring systems that utilize cameras, sensors, artificial intelligence, and computer vision technologies to monitor driver behavior, attention levels, fatigue, distraction, and overall driving conditions. These systems are increasingly adopted to improve vehicle safety, support ADAS functionalities, and comply with evolving safety regulations.
Head-Up Display (HUD)
This segment captures revenue generated from head-up display systems that project critical driving information directly onto the windshield or a dedicated transparent display within the driver’s line of sight. HUD solutions provide navigation guidance, vehicle speed, safety warnings, and ADAS notifications while minimizing driver distraction and improving situational awareness.
Segment- Display Technology
Revenue Capture Definition
LCD
This segment captures revenue generated from automotive digital cockpit displays based on liquid crystal display (LCD) technology. These displays are widely used in instrument clusters, infotainment systems, and rear-seat entertainment systems due to their cost-effectiveness, reliability, and established manufacturing ecosystem.
TFT-LCD
This segment includes revenue derived from thin-film transistor liquid crystal display (TFT-LCD) technology used in automotive digital cockpit applications. TFT-LCD displays offer enhanced image quality, brightness, color reproduction, and response times, making them suitable for advanced instrument clusters, center information displays, and infotainment systems.
OLED
This segment captures revenue generated from organic light-emitting diode (OLED) displays integrated into automotive digital cockpit systems. OLED technology provides superior contrast ratios, deeper blacks, wider viewing angles, faster response times, and flexible display designs, enabling premium and next-generation in-vehicle user experiences.
Segment- Vehicle Type
Revenue Capture Definition
Passenger Cars
This segment captures revenue generated from automotive digital cockpit solutions installed in passenger vehicles, including hatchbacks, sedans, SUVs, crossovers, luxury vehicles, and electric vehicles. Digital cockpit systems in this segment focus on enhancing connectivity, infotainment, navigation, driver assistance, and personalized user experiences.
Commercial Vehicles
This segment includes revenue derived from automotive digital cockpit systems deployed in commercial vehicles such as light commercial vehicles (LCVs), medium-duty trucks, heavy-duty trucks, buses, coaches, and specialized fleet vehicles. These solutions support fleet management, route optimization, vehicle diagnostics, driver monitoring, safety compliance, and operational efficiency requirements.
Estimation Model
Layer Name
Key Question
Description
Vehicle Production & Installation Base Layer
Where are automotive digital cockits deployed and what drives demand?
Establish the total potential demand base by identifying digital cockpit deployment across passenger cars, commercial vehicles, electric vehicles, luxury vehicles, and connected vehicles. Demand is driven by vehicle production volumes, increasing digitalization, rising consumer preference for connected experiences, and the growing integration of advanced HMI and infotainment technologies.
Addressable Market Layer
Which vehicle segments can realistically adopt automotive digital cockpit solutions?
Refine the total vehicle production base into the realistically serviceable market by considering factors such as vehicle segment positioning, OEM technology adoption strategies, consumer affordability, regulatory requirements, connectivity infrastructure, software-defined vehicle development, and regional automotive production trends.
Digital Cockpit Procurement Layer
Who is actively purchasing and integrating automotive digital cockpit solutions?
Estimate annual demand generation by analyzing OEM vehicle production volumes, digital cockpit penetration rates, adoption of digital instrument clusters, head-up displays (HUDs), driver monitoring systems, infotainment platforms, electric vehicle production, premium vehicle demand, and investments in connected and autonomous vehicle technologies.
Revenue Layer
How is revenue generated from automotive digital cockpit sales?
Revenue is generated through the sale and integration of automotive digital cockpit components and platforms, including digital instrument clusters, driver monitoring systems, head-up displays, cockpit domain controllers, and display technologies. Market revenue is calculated by considering units installed, product mix, display technology adoption (LCD, TFT-LCD, OLED), vehicle segment penetration, software and connectivity features, regional pricing variations, and value chain margins across component suppliers, system integrators, and OEMs.
Delivered Customizations
This report has been delivered with the following In-depth customizations
Client Request
Customization Delivered
Value Adds
Automotive Digital Cockpit Market Assessment
Structured evaluation of market dynamics including key drivers, restraints, opportunities, and industry trends across the automotive digital cockpit value chain.
Assessment of technology evolution across digital instrument clusters, cockpit domain controllers, head-up displays (HUDs), driver monitoring systems, AI-powered HMIs, and connected vehicle platforms.
Clear visibility into market growth drivers and adoption barriers.
Strategic input for market entry, expansion planning, and investment decisions.
End-Use and Application Insights
Analysis of demand distribution across passenger cars, commercial vehicles, electric vehicles, luxury vehicles, and connected vehicle platforms.
Identification of high-growth and high-value vehicle segments.
Support for targeted product development and go-to-market strategies.
Technology and Competitive Landscape Review
Benchmarking of key automotive digital cockpit technologies including digital instrument clusters, head-up displays (HUDs), driver monitoring systems, cockpit domain controllers, LCD/TFT-LCD/OLED displays, AI-enabled voice assistants, and augmented reality interfaces.
Analysis of major players' innovation strategies, product differentiation, software capabilities, display technologies, OEM partnerships, and regional market presence.
Competitive intelligence for technology positioning and portfolio optimization.
Guidance for R&D prioritization, partnership evaluation, and long-term growth planning.
Frequently Asked Questions About This Report
The global automotive digital cockpit market size was valued at USD 26.7 billion in 2025 and is expected to reach USD 29.4 billion in 2026.
Some key players operating in the automotive digital cockpit market include Continental AG, Harman International, Faurecia, Hyundai Mobis, Denso Corporation, Robert Bosch GmbH, and Visteon Corporation.
Key factors that are driving the market growth include increased adoption of in-vehicle telematics, infotainment system, safety and pollution sensors, navigation, and the internet of things is a prominent factor driving the demand for automotive digital cockpit solutions.
The global automotive digital cockpit market is expected to grow at a compound annual growth rate of 13.2% from 2026 to 2033 to reach USD 69.8 billion by 2033.
The Asia Pacific region dominated the market and accounted for the largest revenue share of 59.2% in 2025.
The digital instrument cluster segment dominated the market for the automotive digital cockpit and accounted for the largest share of 64.3% in 2025, in terms of value.
The TFT-LCD display segment dominated the market for the automotive digital cockpit and accounted for the largest revenue share of over 54.2% in 2025.
The passenger cars segment dominated the market for the automotive digital cockpit and accounted for the largest revenue share of more than 79.1% in 2025.
About the Author(s)
Automotive & Transportation Research Team
Technology · Automotive & TransportationThis report was authored by the automotive & transportation research team at Grand View Research - comprising two research analysts, one senior research analyst, and one industry expert - with specialized expertise in the automotive & transportation segment of the technology industry. All findings are based on proprietary technology databases, executive interviews, and regulatory analysis, subject to internal peer review prior to publication.
Last Updated:
Speak to Analyst

Customize this report to your needs - add regions, segments, or data points, with 20% free customization.
Or view our licence options:


ISO 9001:2015 & 27001:2022 Certified
We are GDPR and CCPA compliant! Your transaction & personal information is safe and secure. For more details, please read our privacy policy.


