
- Home
- »
- Automotive & Transportation
- »
-
Automotive eCall Market Size & Share Report, 2026-2033GVR Report cover

Automotive eCall Market (2026 - 2033)
Size, Share & Trends Analysis Report By Propulsion Type (ICE, Electric Motor), By Trigger Type (Manually Initiated eCall, Automatically Initiated eCall), By Vehicle Type (Passenger Cars, Commercial Vehicles), By Region, And Segment Forecasts
Market Size, 2025
$3.0BMarket Estimate, 2026
$3.3BMarket Forecast, 2033
$8.7BCAGR, 2026–2033
14.9%Automotive eCall Market Summary
The global automotive eCall market size was valued at USD 3.0 billion in 2025 and is projected to grow from USD 3.3 billion in 2026 to USD 8.7 billion by 2033, at a CAGR of 14.9% from 2026 to 2033. Europe dominated the global market, accounting for the largest revenue share of 39.54% in 2025. Strict government safety regulations are driving growth in the automotive eCall market, especially in regions such as Europe, where eCall systems are required in all new vehicles.
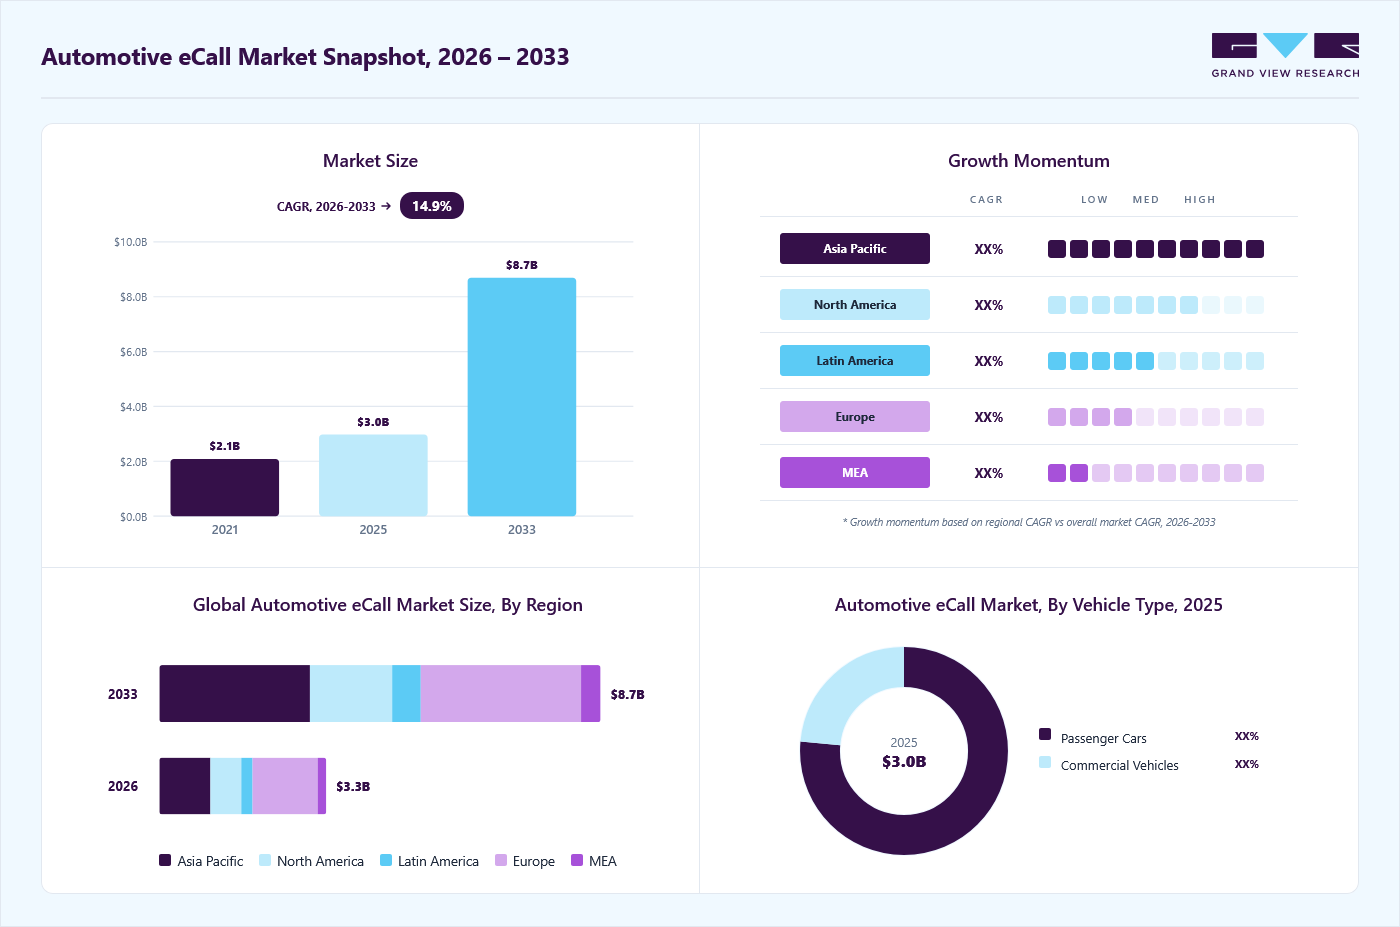 Source: Grand View Research, IR Documents, Primary Interviews, Paid DatabasesTo learn more about this report,
 Download Free Sample Report
Key Market Trends & Insights
- By propulsion type: ICE segment dominated the market, with a revenue share of 68.1% in 2025.
- By trigger type: Automatically initiated eCall (AIeC) segment held the largest market share of 67.4% in 2025.
- By vehicle type: Passenger cars material segment held the largest revenue share in 2025.
Regional Highlights
- Largest regional market: Europe (39.54% revenue share, 2025)
- Fastest-growing regional market: Asia Pacific (highest CAGR, 2026-2033)
- By country: The Germany held the largest market share in 2025.
Market Size & Forecast
- Market size in 2025: USD 3.0 Billion
- Estimated market size in 2026: USD 3.3 Billion
- Projected market size by 2033: USD 8.7 Billion
- CAGR (2026-2033): 14.9%
Three ways to get this report
Buy it, customize it, or ask a question.Ask an Analyst
Analyst response in 1 business day
- AccessReport author, directly
- Reply timeWithin 1 working day
- No sales callDirect answer only
- FormatEmail reply
- CostFree, no cost
Get the Full Report
What the study covers
- FormatsPDF · Excel · Dashboard
- Timeline2026–2033 annual, 2025 base
- Coverage20+ countries, 5 regions
- Companies10+ key players profiled
Customize the Report
20% free customization
- IncludeCountries, segments, points
- TailorTo your product definition
- ExtendDeeper competitor detail
- OrA fully bespoke study
- Turnaround5–10 working days
These mandates prompt automakers to adopt automatic emergency response technologies to improve road safety and reduce fatalities. In addition, increased regulatory attention to connected vehicle infrastructure and emergency response efficiency continues to support market expansion. The market growth can be attributed to the increasing adoption of connected and smart vehicles, as automakers continue to integrate advanced telematics, IoT, and real-time communication technologies into modern vehicle platforms. Rising consumer demand for enhanced safety and connectivity features is prompting manufacturers to deploy automated emergency response systems as standard components of connected vehicle ecosystems. In addition, the expansion of intelligent transportation infrastructure and next-generation mobility solutions is further supporting the integration of eCall technologies across passenger and commercial vehicles.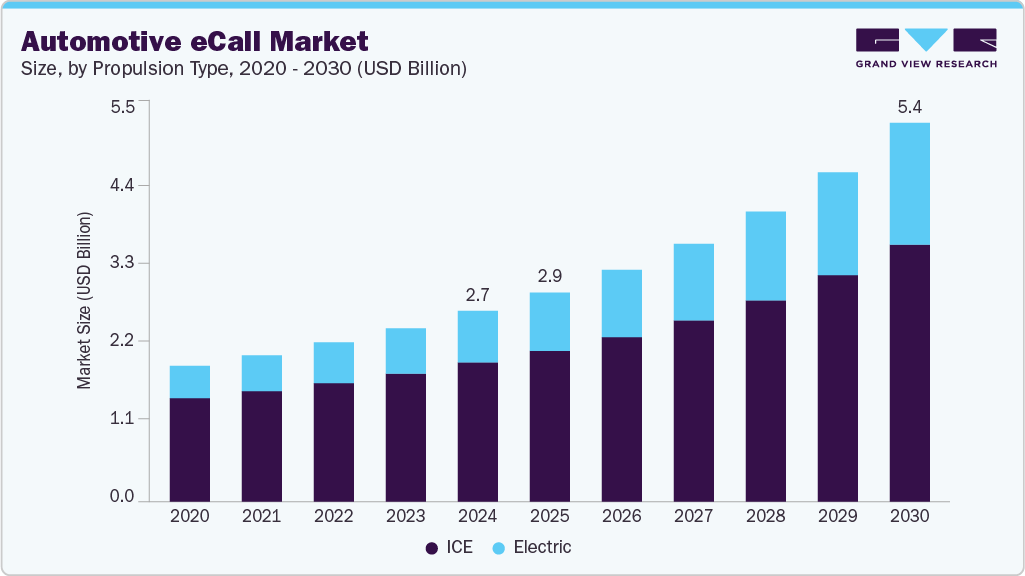 To learn more about this report, Download Free Sample Report
The automotive eCall market is expanding rapidly due to rising adoption of connected vehicle technologies, increased regulatory focus on road safety, and the growing integration of telematics and real-time emergency communication systems in modern vehicles. Automotive manufacturers and connectivity solution providers are expanding their eCall services across new geographic markets to strengthen vehicle safety capabilities and improve emergency response efficiency. For instance, in March 2025, Intelematics, an Australian technology company, expanded its eCall service into New Zealand to help automotive manufacturers improve road safety and comply with ANCAP’s updated safety assessment protocols, which include eCall capabilities. The company introduced services such as eCall, Stolen Vehicle Tracking, iCall, and bCall as part of its connected vehicle safety and security portfolio.
The insurance industry is further supporting the growth of the automotive eCall market by recognizing the role of eCall systems in reducing accident-related losses and improving claims verification processes. Telematics-enabled safety systems, including eCall, provide insurers with faster access to accident data and emergency response information, helping enhance risk assessment and fraud prevention capabilities. Thus, many insurance providers are offering incentives and premium discounts for vehicles equipped with eCall technology, encouraging wider adoption, particularly in price-sensitive, cost-conscious consumer markets.
Despite strong growth prospects, the automotive eCall market faces several restraints that could hinder its widespread adoption and scalability. One of the primary challenges is the high cost of system integration, especially for manufacturers producing low-cost or economy vehicles. While premium and mid-range vehicles can absorb the additional cost of telematics hardware and connectivity services, budget models often operate on thinner profit margins, making it difficult for automakers to include eCall systems without impacting vehicle affordability.
The growing focus on road safety, faster emergency response times, and the adoption of connected vehicle technologies are driving the global automotive eCall market. Regulatory mandates for advanced vehicle safety systems are prompting automakers to integrate eCall solutions in both passenger and commercial vehicles. Advances in telematics, GPS, and wireless communication are enhancing the effectiveness of emergency response. However, strict compliance requirements and certification processes for evolving communication standards remain challenging. Despite these obstacles, the expansion of 5G connectivity and intelligent transportation infrastructure is creating new growth opportunities.
Market Dynamics
The increasing focus on road safety and faster emergency response is significantly driving the growth of the automotive eCall market. Automotive eCall systems enable the automatic transmission of critical information, such as vehicle location, crash severity, and identification details, to emergency response centers immediately after an accident occurs. This helps reduce emergency response times, improves access to timely medical assistance, and improves overall passenger safety during road accidents.
The increasing number of road accidents and growing awareness regarding vehicle safety are further encouraging governments and automakers to invest in advanced emergency communication technologies. In addition, the implementation of stricter vehicle safety regulations and the expansion of connected transportation infrastructure are accelerating the integration of eCall systems across passenger and commercial vehicles worldwide.
Automotive manufacturers supplying vehicles with eCall and next-generation eCall (NG-eCall) systems in Europe must meet strict EU and UN safety regulations, as well as requirements for 2G, 3G, 4G, and 5G mobile communication technologies. To secure type approval, manufacturers increasingly rely on certification-authority-approved testing solutions during development to validate system performance, communication reliability, and regulatory compliance. Inadequate attention to compliance during verification can result in failed type-approval tests, higher troubleshooting costs, and vehicle launch delays. Although Hybrid eCall systems are not yet subject to mandatory type-approval, growing industry interest is prompting automakers and certification authorities to invest in technical validation and dedicated testing environments to support future reliability and standardization.
The integration of next-generation connected vehicle technologies is creating significant opportunities in the automotive eCall market. As the industry moves toward connected, autonomous, and software-defined vehicles, demand for advanced emergency communication and telematics solutions is expected to increase. The expansion of 5G connectivity, cloud-based platforms, and intelligent transportation infrastructure supports the development of next-generation eCall systems with improved data transmission, location accuracy, and emergency response times. In addition, the rise of electric and autonomous vehicles offers new opportunities for automakers and technology providers to incorporate advanced eCall features within broader connected mobility ecosystems.
Market Concentration & Characteristics
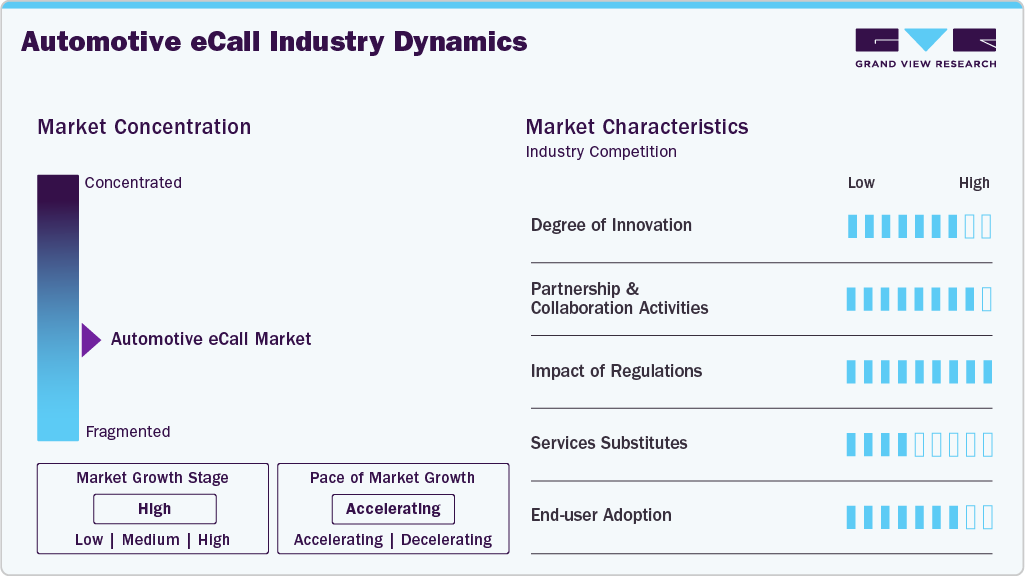
The automotive eCall market is moderately fragmented, with participants including automotive OEMs, Tier-1 suppliers, telematics service providers, and telecom operators. Established companies such as Robert Bosch GmbH, Continental AG, and Denso Corporation maintain strong positions through long-term OEM contracts and integrated safety systems. However, many regional and specialized firms focus on specific areas of the value chain, such as connectivity modules, software platforms, and emergency response integration.
 To learn more about this report, Download Free Sample Report
The market is highly ecosystem-driven and regulation-led, where compliance requirements (especially in Europe) significantly shape adoption patterns and system design. Competitive intensity is moderate, as differentiation is constrained by standardized safety functions, prompting companies to compete more on reliability, integration capabilities, and partnerships with automakers and telecom providers. Thus, success in the market depends less on standalone product innovation and more on the ability to integrate seamlessly across vehicles, networks, and emergency infrastructure.
Analyst’s Perspective
Stricter regulations, increased safety awareness, and wider adoption of connected vehicle technologies are driving growth in the global automotive eCall market. Automakers are integrating eCall systems to meet safety requirements and improve emergency response. Advances in telematics, GPS, and cellular communications are enhancing the reliability and effectiveness of these solutions. The market is further supported by the rise of electric and autonomous vehicles, which demand advanced connectivity and safety features. In addition, the emergence of 5G-enabled mobility ecosystems is expected to create new opportunities for next-generation eCall systems.
Propulsion Type Insights
The ICE segment dominated the market, accounting for the largest revenue share of 68.11% in 2025. Segment growth is mainly driven by the larger global base of ICE vehicles compared to electric vehicles, particularly in developing regions where EV adoption remains limited due to infrastructure and cost challenges. This extensive vehicle base has led to greater integration of eCall systems in ICE models. In addition, the segment’s dominance is reinforced by the early introduction of regulatory mandates such as the European Union’s 218 eCall requirement, which came into effect when ICE vehicles represented the majority of production and on-road fleets. Thus, automakers prioritized embedding eCall systems in ICE platforms to ensure compliance in their highest-volume categories, maintaining their lead as electrification advances.
The electric segment is expected to grow at the fastest CAGR during the forecast period. The segment growth is supported by the rapid global adoption of EVs and increasing regulatory emphasis on advanced safety and connectivity features. As governments across regions such as Europe, China, and North America implement stricter emissions norms and offer incentives to accelerate electrification, EV production and adoption are expanding rapidly. This expanding EV fleet is simultaneously driving higher demand for integrated in-vehicle safety systems, including eCall, as manufacturers increasingly embed connected emergency response capabilities as standard features in next-generation electric platforms.
Trigger Type Insights
The automatically initiated eCall (AIeC) segment dominated the automotive eCall market in 2025. The segment's growth is driven by enhanced safety benefits and strong regulatory support. Unlike manually initiated systems, AIeC automatically triggers an emergency call to rescue services in the event of a severe collision, even if vehicle occupants are unconscious or unable to respond, thereby significantly improving emergency response outcomes. This life-saving capability has made AIeC the preferred configuration in modern vehicles, particularly in regions such as the European Union, where automatic activation is mandated for new vehicles under eCall regulations. Furthermore, the segment’s dominance is reinforced by the growing global emphasis on reducing road fatalities and improving crash response times through faster and more reliable emergency communication systems.
The manually initiated eCall (MIeC) segment is expected to witness the highest growth over the forecast period, driven by demand for user-controlled safety features and adoption in regions where automatic eCall is not yet required. Unlike AIeC, MIeC allows occupants to manually trigger emergency calls in a wider range of situations, including medical emergencies, roadside breakdowns, or personal safety concerns. This flexibility and user autonomy make MIeC appealing to vehicles that prioritize user experience and customizable safety. In emerging markets with developing regulations for automatic eCall, MIeC adoption is further supported by lower implementation costs and less reliance on advanced crash-detection technology.
Vehicle Type Insights
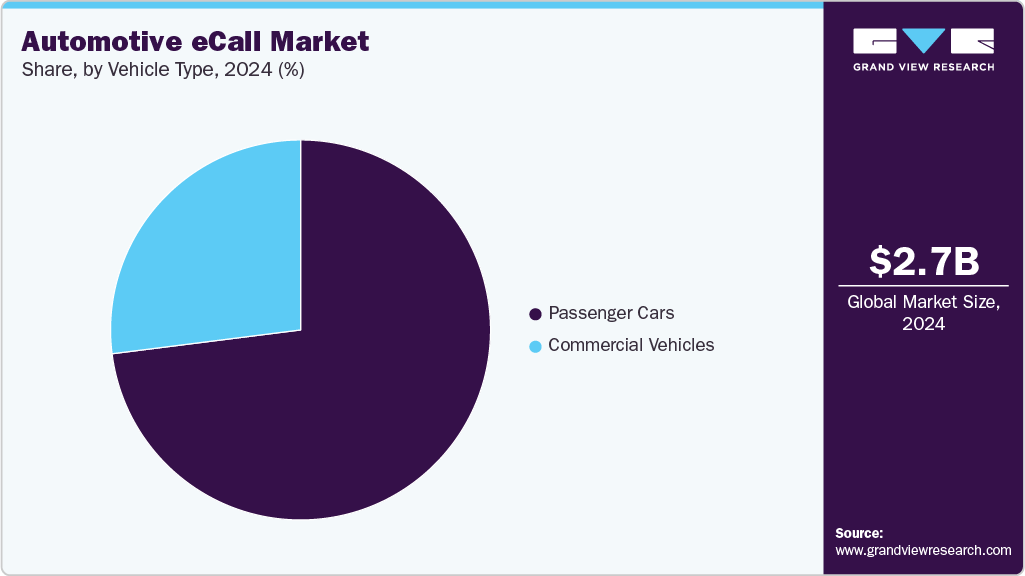
The passenger cars segment accounted for the largest market share in 2025. The dominance is attributed to the high global production and sales volumes of passenger vehicles compared to other vehicle types. This growth is further supported by regulatory mandates, particularly in regions such as the European Union, where all new passenger cars must be equipped with eCall functionality, ensuring widespread integration across this segment. In addition, increasing consumer awareness regarding vehicle safety, along with rising demand for connected in-car features, has encouraged automakers to deploy eCall systems across a broad range of passenger car models, further reinforcing the segment’s leading position.
 To learn more about this report, Download Free Sample Report
The commercial vehicle segment is expected to witness the fastest growth over the forecast period. As commercial vehicles, including trucks, buses, and delivery vehicles, are increasingly being integrated with advanced safety and telematics systems, the demand for eCall technology is growing rapidly in this segment. Fleet management and operational efficiency are becoming key priorities for businesses in logistics, transportation, and public services. The integration of eCall technology offers safety benefits and operational advantages, such as improved fleet tracking, real-time monitoring, and optimized emergency response times. This capability is essential for businesses that depend on their vehicles for critical operations, such as long-haul freight transportation and passenger transit.
Regional Insights
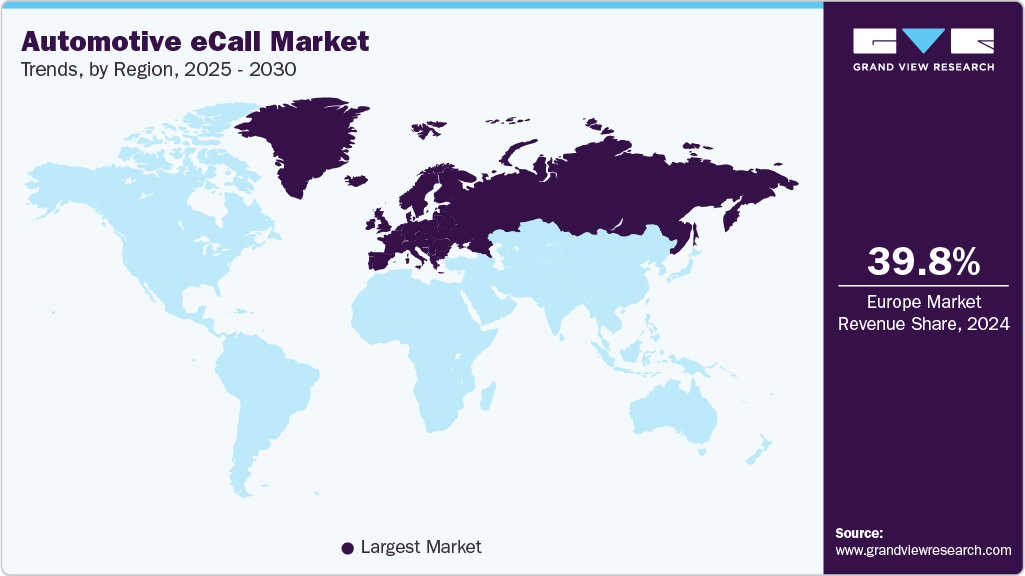
Europe automotive eCall market dominated the global market and accounted for a share of 39.39% in 2025, largely due to stringent regulatory mandates and widespread adoption of connected vehicle technologies. The region’s well-established telecommunications infrastructure and seamless integration between eCall systems and emergency services (such as 112-based PSAPs-Public Safety Answering Points) have also contributed to its dominance. Countries like Germany, France, and the UK are key markets, with automakers and technology providers continuously enhancing eCall functionalities, including Next-Generation eCall (NG eCall), which supports richer data transmission.
 To learn more about this report, Download Free Sample Report
Germany Automotive eCall Market Trends
The Germany automotive eCall market held a significant market share in 2025 in the Europe region. The country’s robust automotive manufacturing base and early adoption of advanced vehicle safety technologies drive market growth. As home to several leading automobile manufacturers, Germany leads in integrating connected car and telematics solutions to meet European Union safety regulations. The country’s commitment to road safety, technological innovation, and premium vehicle production has also accelerated the deployment of advanced eCall systems in both passenger and commercial vehicles.
The UK automotive eCall market is expected to witness the fastest CAGR during the forecast period. The country’s growth is driven by increased adoption of connected vehicle technologies and a stronger focus on vehicle safety and emergency response. Investments in smart mobility infrastructure and rising demand for advanced in-vehicle communication systems are further supporting this growth. In addition, the growing presence of electric and connected vehicles is enabling wider integration of eCall systems in next-generation vehicle platforms.
Asia Pacific Automotive eCall Market Trends
The Asia Pacific automotive eCall market is expected to grow at the fastest CAGR during the forecast period. Rising vehicle production and automotive sales in countries such as China, India, and Japan are contributing to the increased demand for advanced safety technologies, including eCall systems. In addition, growing consumer awareness of vehicle safety in the Asia Pacific region is a key factor influencing market growth. As consumers seek more advanced safety features, automakers are incorporating eCall systems into their vehicles to meet these demands.
The China automotive eCall market held a significant market share in 2025 in the Asia Pacific region. China's automotive sector is at the forefront of integrating advanced technologies such as electric vehicles (EVs) and autonomous driving systems. The adoption of eCall systems is increasingly seen as a critical component of these innovations, ensuring that vehicles are equipped with the necessary infrastructure to support emergency communication and enhance overall safety.
The India automotive eCall market is expected to grow at the fastest growth rate during the forecast period. India's expanding automotive industry, characterized by rising vehicle production and sales, is contributing to the demand for advanced safety technologies. As the market grows, automakers are increasingly focusing on integrating eCall systems to enhance vehicle safety and meet consumer expectations. In addition, the development of next-generation telematics protocols and the increasing adoption of connected vehicle technologies are facilitating the integration of eCall systems. These advancements enable real-time communication between vehicles and emergency services, improving response times and overall road safety.
North America Automotive eCall Market Trends
The North American automotive eCall market was identified as a lucrative region in 2025. Insurance incentives and safety benefits are majorly driving the market growth. Insurance companies are offering discounts to consumers who choose vehicles equipped with advanced safety technologies, such as eCall systems. This is due to the role eCall plays in reducing accident response times and, consequently, the severity of claims. Thus, many consumers are opting for vehicles with these systems to take advantage of the potential cost savings, thus boosting the demand for eCall-equipped cars.
The U.S. automotive eCall market held a substantial market share in 2025. As autonomous vehicle technology advances in the U.S., the integration of eCall systems is becoming crucial. Autonomous vehicles rely heavily on connected technologies, and eCall serves as an essential component to ensure emergency communication in case of an incident. This growing trend toward autonomous driving increases demand for advanced safety technologies, including eCall.
Key Automotive ECall Company Insights
Some of the key players operating in the automotive eCall market include Continental AG, Telit Cinterion, Thales, Robert Bosch GmbH, DENSO CORPORATION, Infineon Technologies AG, among others. These companies are actively investing in research and development (R&D) to improve the performance, reliability, and responsiveness of automotive eCall systems. Key areas of innovation include enhancing system integration with telematics and vehicle connectivity platforms, as well as leveraging advanced technologies such as cloud-based communication and precise geolocation services. In addition, these players are expanding their global manufacturing footprint and forming strategic partnerships to support the growing demand for eCall solutions across diverse regional automotive markets.
-
Continental AG is a global automotive parts manufacturer offering products such as tires, braking systems, vehicle electronics, and powertrain components. The company develops systems that enable vehicles to contact emergency services after a crash by transmitting data like location and crash severity to facilitate prompt assistance. Continental integrates eCall functionality into its telematics control units, supporting both automatic and manual call activation. To meet growing global demand for vehicle safety systems, Continental is expanding its production infrastructure and forming industry partnerships.
-
Visteon Corporation is a U.S.-based automotive electronics supplier specializing in digital cockpit and connectivity solutions. The company develops telematics control units (TCUs) that enable emergency call functions and support both dedicated short-range communications (DSRC) and cellular vehicle-to-everything (C-V2X) standards. TCUs integrate with various vehicle networks and operating systems, offering features such as over-the-air software updates and high-precision positioning. These capabilities improve the reliability and responsiveness of eCall systems.
Key Automotive ECall Companies
The following key companies have been profiled for this study on the automotive eCall market.
-
Continental AG
-
Robert Bosch GmbH
-
Telit Cinterion
-
Thales
-
DENSO CORPORATION
-
Infineon Technologies AG
-
Valeo
-
STMicroelectronics
-
u-blox
-
Visteon Corporation
Competitive Benchmarking
Operating Strategies
Competitive Edge
Weaknesses
Mature Players: Continental AG; Robert Bosch GmbH; DENSO CORPORATION; Valeo; STMicroelectronics
- Invest in ADAS, telematics, and connected vehicle technologies to strengthen automotive safety portfolios
- Expand global OEM partnerships and strategic collaborations
- Strong automotive supply chains and long-term OEM relationships
- Extensive expertise in automotive electronics and embedded safety systems
- Managing broad product portfolios and rapidly evolving technologies
- High dependence on automotive production cycles may impact profitability
Emerging Players: Telit Cinterion; Thales; Infineon Technologies AG; u-blox; Visteon Corporation
- Focus on innovation in connectivity modules, GNSS, IoT telematics, and cybersecurity solutions
- Collaborate with telecom providers and OEMs to strengthen connected mobility ecosystems
- Strong specialization in communication technologies and automotive semiconductors
- Flexible product development helps address evolving connected vehicle requirements
- Limited manufacturing scale and smaller distribution networks restrict broader market penetration
- High R&D and compliance costs create challenges in competing with established Tier-1 suppliers
Recent Developments
-
In December 2025, ANRITSU CORPORATION announced the launch of an advanced acoustic evaluation solution for next-generation automotive emergency call systems (NG eCall), developed in collaboration with HEAD acoustics. The solution, which complied with ITU-T Recommendation P.1140, was designed to enable precise assessment of voice communication quality between vehicle occupants and Public Safety Answering Points (PSAPs), thereby supporting faster and more effective emergency response operations.
-
In March 2025, Telit Cinterion introduced the LE310 LTE Cat. 1 bis and SL871K2 GNSS modules for compact, low-power IoT applications, including asset tracking, telematics, and wearables. The LE310 provides global LTE Cat. 1 bis connectivity in a 15 x 18 mm form factor, optimized for space-constrained, battery-powered devices, and is available in both regional and global versions. The SL871K2 GNSS module supports multiple satellite constellations (GPS, QZSS, GLONASS, BeiDou, and Galileo), enabling concurrent tracking and advanced features such as Assisted GNSS, 1PPS output, and TRAIM.
Automotive eCall Market Report Scope
Report Attribute
Details
Market size value in 2025
USD 3.0 billion
Market size value in 2026
USD 3.3 billion
Revenue forecast in 2033
USD 8.7 billion
Growth rate
CAGR of 14.9% from 2026 to 2033
Base year for estimation
2025
Historical data
2021 - 2025
Forecast period
2026 - 2033
Quantitative units
Revenue in USD billion and CAGR from 2026 to 2033
Report coverage
Revenue forecast, company ranking, competitive landscape, growth factors, and trends
Segments covered
Propulsion type, trigger type, vehicle type, region
Regional scope
North America; Europe; Asia Pacific; Latin America; MEA
Country scope
U.S.; Canada; Mexico; Germany; UK; France; China; Japan; India; South Korea; Australia; Brazil; KSA; UAE; South Africa
Key companies profiled
Continental AG; Robert Bosch GmbH; Telit Cinterion; Thales; DENSO CORPORATION; Infineon Technologies AG; Valeo; STMicroelectronics; u-blox; Visteon Corporation
Customization scope
Free report customization (equivalent up to 8 analysts working days) with purchase. Addition or alteration to country, regional & segment scope.
Pricing and purchase options
Avail customized purchase options to meet your exact research needs. Explore purchase options
Global Automotive eCall Market Report Segmentation
This report forecasts revenue growth at regional and country levels and provides an analysis on the industry trends in each of the sub-segments from 2021 to 2033. For the purpose of this study, Grand View Research has segmented the automotive eCall market report based on propulsion type, trigger type, vehicle type, and region.
 To learn more about this report, Download Free Sample Report
-
Propulsion Type Outlook (Revenue, USD Million, 2021 - 2033)
-
ICE
-
Electric Motor
-
-
Trigger Type Outlook (Revenue, USD Million, 2021 - 2033)
-
Manually Initiated eCall (MIeC)
-
Automatically Initiated eCall (AIeC)
-
-
Vehicle Type Outlook (Revenue, USD Million, 2021 - 2033)
-
Passenger Cars
-
Commercial Vehicles
-
-
Region Outlook (Revenue, USD Million, 2021 - 2033)
-
North America
-
U.S.
-
Canada
-
Mexico
-
-
Europe
-
UK
-
Germany
-
France
-
-
Asia Pacific
-
China
-
India
-
Japan
-
South Korea
-
Australia
-
-
Latin America
-
Brazil
-
-
Middle East & Africa
-
KSA
-
UAE
-
South Africa
-
-
Research Methodology
(a) Segment Definition
Segment - Propulsion Type
Revenue capture definition
ICE
This segment includes passenger and commercial vehicles powered by conventional gasoline, diesel, or hybrid internal combustion engines equipped with eCall systems. These vehicles utilize embedded telematics and communication modules to automatically transmit emergency information in the event of an accident.
Electric
This segment comprises battery-electric vehicles (BEVs) and plug-in hybrid electric vehicles (PHEVs) equipped with automotive eCall systems. The growing adoption of connected EV platforms is driving the implementation of advanced eCall solutions that support enhanced emergency communication and vehicle diagnostics.
Segment - Trigger Type
Revenue capture definition
Manually Initiated eCall (MIeC)
Manually initiated eCall (MIeC) systems are the eCall systems that are activated by vehicle occupants through a dedicated emergency button when assistance is required. These systems enable drivers or passengers to directly contact emergency response centers during accidents, medical emergencies, or other critical situations.
Automatically Initiated eCall (AIeC)
Automatically initiated eCall (AIeC) systems are the eCall systems that are activated automatically when onboard sensors detect a serious collision or accident. These systems transmit critical information such as vehicle location, identification details, and crash data to emergency services without requiring manual intervention.
Segment - Vehicle Type
Revenue capture definition
Passenger Cars
This segment includes all passenger vehicles equipped with automotive eCall systems, such as hatchbacks, sedans, SUVs, crossovers, and luxury vehicles. Revenue is generated from the integration of eCall hardware, telematics control units (TCUs), communication modules, software platforms, and related services installed in passenger cars.
Commercial Vehicles
This segment includes light commercial vehicles (LCVs), medium commercial vehicles (MCVs), heavy commercial vehicles (HCVs), buses, and coaches equipped with eCall systems. Revenue is derived from eCall hardware, connectivity solutions, fleet telematics integration, emergency communication systems, software, and associated maintenance and support services deployed in commercial vehicles.
(b) Estimation Model
Layer Name
Key Question
Description
Global Vehicle Production & Parc Layer
What is the total addressable vehicle base for eCall systems?
Evaluate global production and sales of passenger cars and commercial vehicles across major regions to determine the vehicle population eligible for eCall system integration.
eCall Penetration Layer
What proportion of vehicles are equipped with eCall systems?
Assess the adoption of eCall technologies across vehicle categories, considering regulatory mandates, vehicle safety requirements, OEM integration rates, and connected vehicle penetration.
Technology & Vehicle Mix Layer
Which eCall technologies and vehicle segments generate demand?
Analyze adoption across manually initiated eCall (MIeC), automatically initiated eCall (AIeC), and next-generation eCall systems, segmented by passenger cars, commercial vehicles, ICE vehicles, and electric vehicles.
Revenue Monetization Layer
How is market value generated?
Estimate market revenue from eCall hardware components, telematics control units (TCUs), GNSS/GPS modules, in-vehicle communication systems, software platforms, connectivity services, installation, maintenance, and related support services across the automotive value chain.
Delivered Customizations
This report has been delivered with the following In-depth customizations
Client Request
Customization Delivered
Value Adds
Automotive eCall Market Analysis
Regional automotive eCall demand assessment
Connected vehicle and telematics adoption analysis
Identified high-growth regional markets
Supported strategic market expansion planning
Vehicle Safety & Consumer Adoption Study
Analysis of passenger and commercial vehicle safety trends
Consumer preference assessment for connected safety systems
Automatic crash notification adoption analysis
Improved customer targeting strategy
Supported product positioning and feature prioritization
Competitive Landscape Assessment
Benchmarking of leading automotive telematics providers
OEM partnership and product portfolio comparison
Embedded connectivity and ADAS integration analysis
Supported competitive intelligence
Identified market differentiation opportunities
Frequently Asked Questions About This Report
The global automotive eCall market size was estimated at USD 3.0 billion in 2025 and is expected to reach USD 3.3 billion in 2026 .
Some key players operating in the automotive eCall market include Continental AG; Robert Bosch GmbH; Telit Cinterion; Thales; DENSO CORPORATION; Infineon Technologies AG; Valeo; STMicroelectronics; u-blox; and Visteon Corporation
Strict government safety regulations are driving growth in the automotive eCall market, especially in regions such as Europe, where eCall systems are required in all new vehicles. In addition, increased regulatory attention to connected vehicle infrastructure and emergency response efficiency continues to support market expansion.
Asia Pacific is the fastest growing region over the forecast period.
The global automotive eCall market is expected to grow at a compound annual growth rate of 14.9% from 2026 to 2033 to reach USD 8.7 billion by 2033.
Europe dominated with a 39.4% revenue share in 2025.
The ICE segment led with a 68.1% revenue share in 2025, while electric is the fastest growing segment.
The automatically initiated eCall (AIeC) segment led with a 67.4% revenue share in 2025, while manually initiated eCall (MIeC) is the fastest growing segment.
The passenger cars segment led with a 76.4% revenue share in 2025, while commercial vehicle is the fastest growing segment.
About the Author(s)
Automotive & Transportation Research Team
Technology · Automotive & TransportationThis report was authored by the automotive & transportation research team at Grand View Research - comprising two research analysts, one senior research analyst, and one industry expert - with specialized expertise in the automotive & transportation segment of the technology industry. All findings are based on proprietary technology databases, executive interviews, and regulatory analysis, subject to internal peer review prior to publication.
Last Updated:
Speak to Analyst

Customize this report to your needs - add regions, segments, or data points, with 20% free customization.
Or view our licence options:


ISO 9001:2015 & 27001:2022 Certified
We are GDPR and CCPA compliant! Your transaction & personal information is safe and secure. For more details, please read our privacy policy.


