
- Home
- »
- Advanced Interior Materials
- »
-
Automotive Metals Market Size & Share Report, 2026-2033GVR Report cover

Automotive Metals Market (2026 - 2033)
Size, Share & Trends Analysis Report By Product (Aluminum, Steel, Magnesium), By Application (Body Structure, Power Train, Suspension), By Vehicle Type (Passenger Cars), By Region, And Segment Forecasts
Market Size, 2025
$411.4BMarket Estimate, 2026
$439.4BMarket Forecast, 2033
$740.0BCAGR, 2026–2033
7.7%Automotive Metals Market Summary
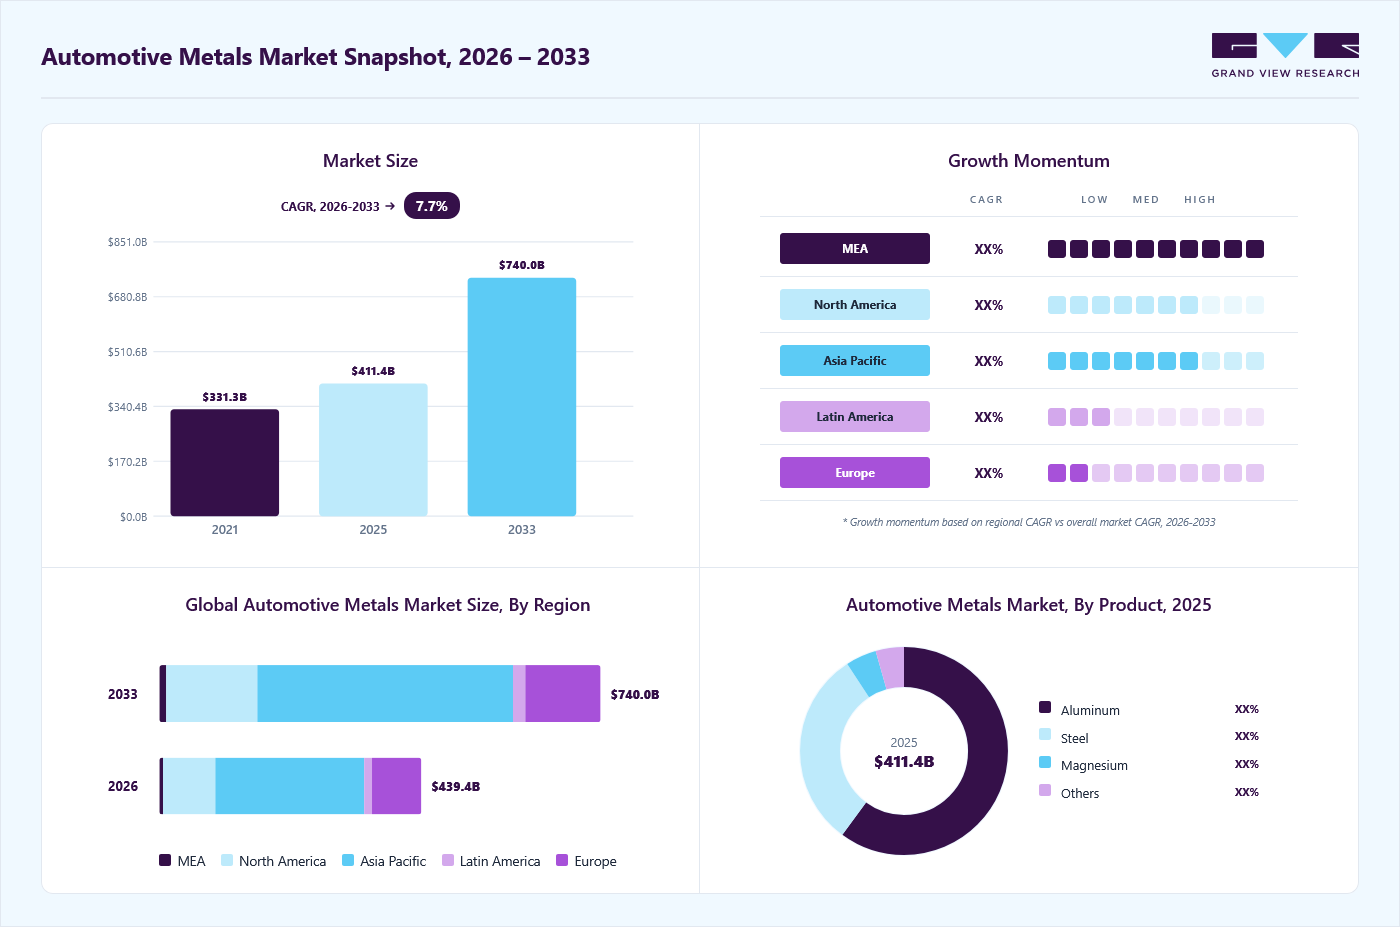
The global automotive metals market size was valued at USD 411.4 billion in 2025 and is projected to grow from USD 439.4 billion in 2026 to USD 740.0 billion by 2033, at a CAGR of 7.7% from 2026 to 2033. The market in Asia Pacific dominated with a revenue share of 56.0% in 2025. Automotive metals refer to the key metallic materials used in vehicle manufacturing to build structural parts, body panels, engines, and safety components.
 Source: Grand View Research, IR Documents, Primary Interviews, Paid DatabasesTo learn more about this report,
 Download Free Sample Report
Key Market Trends & Insights
- By product: Aluminum segment held the largest market share of 60.0% in 2025.
- By application: Body structure segment held the largest market share in 2025.
- By vehicle type: Passenger cars segment held the largest market share in 2025.
Regional Highlights
- Largest regional market: Asia Pacific (56.0% revenue share, 2025)
- By country: The U.S. held the largest market share in 2025
Market Size & Forecast
- Market size in 2025: USD 411.4 Billion
- Estimated market size in 2026: USD 439.4 Billion
- Projected market size by 2033: USD 740.0 Billion
- CAGR (2026-2033): 7.7%
Three ways to get this report
Buy it, customize it, or ask a question.Ask an Analyst
Analyst response in 1 business day
- AccessReport author, directly
- Reply timeWithin 1 working day
- No sales callDirect answer only
- FormatEmail reply
- CostFree, no cost
Get the Full Report
What the study covers
- FormatsPDF · Excel · Dashboard
- Timeline2026–2033 annual, 2025 base
- Coverage20+ countries, 5 regions
- Companies10+ key players profiled
Customize the Report
20% free customization
- IncludeCountries, segments, points
- TailorTo your product definition
- ExtendDeeper competitor detail
- OrA fully bespoke study
- Turnaround5–10 working days
They mainly include steel, aluminum, magnesium, and other alloys, chosen for their strength, lightweight properties, and durability. Electric vehicle (EV) adoption is one of the strongest growth drivers for the market, as EVs require significantly higher metal intensity compared to conventional internal combustion engine vehicles. The increased use of aluminum for lightweight body structures, copper for wiring and motors, and nickel-based metals for battery-related components is accelerating overall demand. As global EV production continues to rise, automakers are expanding their procurement of high-performance metals to improve driving range, thermal management, and vehicle durability.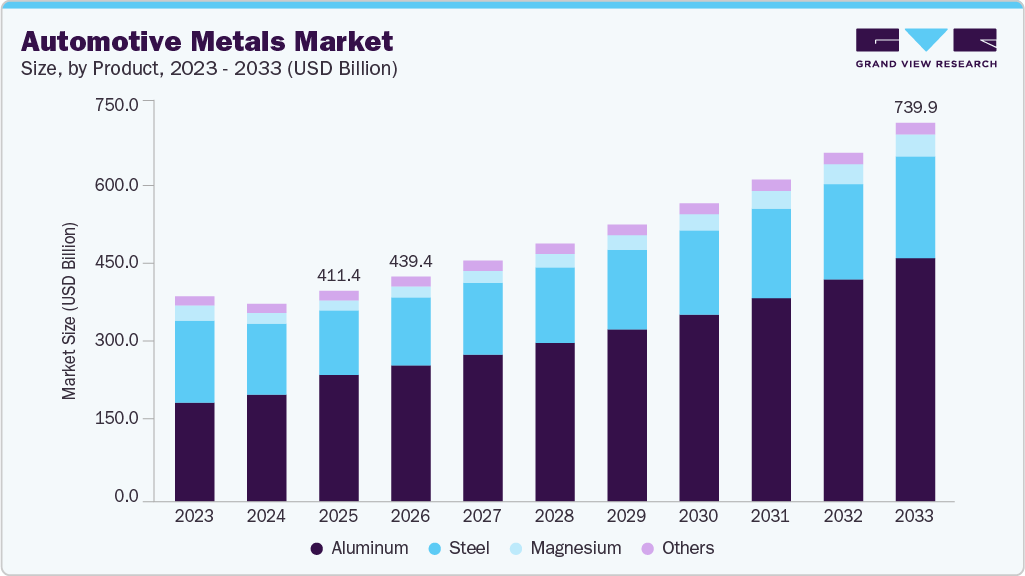 To learn more about this report, Download Free Sample Report
Stringent emissions regulations and fuel-efficiency mandates across major regions such as North America, Europe, and Asia are driving automakers to focus heavily on light weighting. To reduce vehicle weight without compromising safety, manufacturers are increasing the use of advanced high-strength steel (AHSS), aluminum alloys, and magnesium. This shift toward lighter yet stronger materials is expanding demand for engineered metals across structural, chassis, and powertrain components.
Another major driver is the growing demand for vehicle safety, comfort, and premium features, which is increasing the use of metals across both interior and exterior systems. The integration of advanced driver assistance systems (ADAS), infotainment electronics, enhanced braking systems, and reinforced crash structures is contributing to higher consumption of steel, aluminum, and copper-based alloys. As consumers demand more technologically advanced vehicles, metal content per vehicle continues to rise.
Rising global automotive production, especially in emerging markets such as India, Southeast Asia, Latin America, and parts of the Middle East, is further supporting demand growth. Expanding urbanization, rising disposable incomes, and government-led infrastructure development are boosting vehicle sales, thereby increasing the consumption of automotive metals. Additionally, growing commercial vehicle fleets for logistics and construction are driving higher demand for steel and aluminum components.
Lastly, sustainability trends and the push for recycling are creating long-term momentum in the market. Automakers are increasingly shifting toward recycled aluminum and steel to reduce carbon footprints and comply with environmental targets. This is encouraging investments in green steel production, secondary aluminum supply chains, and closed-loop recycling systems, strengthening the long-term growth outlook for automotive metals globally.
Drivers, Opportunities & Restraints
The market is primarily driven by rising global vehicle production and the growing shift toward lightweight materials to improve fuel efficiency and reduce emissions. Automakers are increasingly adopting advanced high-strength steel (AHSS), aluminum, and magnesium to reduce vehicle weight while maintaining structural integrity and crash safety. Additionally, the rapid expansion of electric vehicle manufacturing is significantly boosting demand for aluminum for battery enclosures and body structures, as well as for copper and specialty alloys for electrical systems and drivetrain components.
A major opportunity lies in the accelerating transition toward electric and hybrid vehicles, which require higher metal intensity per vehicle compared to conventional cars. The rising focus on sustainability is also driving strong demand for recycled aluminum, green steel, and low-carbon metal supply chains, encouraging investments in circular-economy models. Further, innovation in metal processing technologies such as high-pressure die casting, hot stamping, and advanced alloy development is enabling automakers to adopt new materials, opening growth potential for specialized and high-performance automotive metal suppliers.
The market faces restraints from volatility in raw material prices, especially for aluminum, copper, nickel, and steel, which creates cost uncertainty for manufacturers and suppliers. Supply chain disruptions, trade restrictions, and dependence on imports for key metals can also impact production stability and profit margins.
Product Insights
The aluminum segment of the automotive metals market is primarily driven by the global push for light weighting to improve fuel efficiency and extend the driving range of electric vehicles (EVs). Automakers are increasingly substituting conventional steel components with aluminum in body structures, closures (hoods, doors, trunk lids), chassis parts, and crash management systems due to its high strength-to-weight ratio and corrosion resistance. This shift is strongly supported by tightening emission regulations across major regions such as Europe, North America, and China, where OEMs are under constant pressure to reduce fleet-average CO₂ emissions.
Magnesium is expected to grow at a CAGR of 10.3% over the forecast period. Magnesium is about 30% lighter than aluminum and nearly 75% lighter than steel, making it highly attractive to automakers seeking to improve fuel economy and extend EV driving range. As global emission norms become stricter and EV penetration rises, OEMs are increasingly focusing on lightweighting strategies to offset the heavy weight of battery packs. This is accelerating the adoption of magnesium in applications such as steering wheels, seat frames, transmission cases, instrument panel structures, and inner body components, where weight savings deliver direct performance benefits.
Application Insights
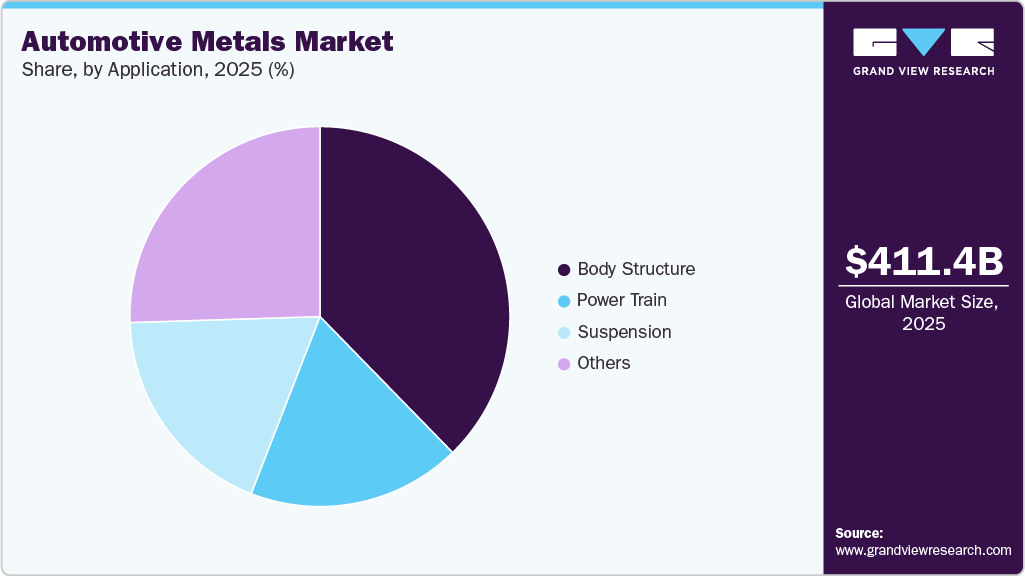
The body structure segment is strongly driven by the growing focus on lightweight vehicle architectures to meet stricter fuel-economy and emissions regulations across major automotive regions. Automakers are increasingly adopting advanced high-strength steel (AHSS), aluminum, and selective magnesium components in body-in-white structures to reduce overall vehicle weight while maintaining crash safety and structural rigidity.
 To learn more about this report, Download Free Sample Report
The suspension segment is primarily driven by the increasing demand for enhanced vehicle performance, ride comfort, and durability across both passenger and commercial vehicles. Suspension systems require high-strength materials to withstand continuous dynamic loads, road shocks, and long-term fatigue, which sustains strong demand for steel and advanced alloys in components such as control arms, knuckles, springs, stabilizer bars, and subframes. As vehicle production continues to rise globally, particularly in SUVs and light trucks, suspension systems are becoming heavier-duty, leading to higher metal consumption per vehicle.
Vehicle Type Insights
The passenger cars benefit from robust global vehicle production, which reached an estimated 75.5 million units in 2024 according to OICA, with Asia, especially China and India, driving much of the growth. Passenger car output alone accounts for a substantial portion of this total, reflecting broad demand and model refresh cycles across global markets. Production in China itself surpassed 27 million cars in 2024, while India’s passenger car output grew by nearly 9%, underscoring the expanding manufacturing bases in emerging economies.
The light commercial vehicles segment is expected to grow at a CAGR of 7.2% over the forecast period supported by strong global demand tied to expanding logistics and delivery services, particularly in urban and e-commerce sectors where vans and light trucks are critical for last-mile transportation. In 2024, light commercial vehicles accounted for a significant portion of light truck registrations worldwide, with approximately 9.8 million units recorded, reflecting firm underlying demand for these vehicle types.
Regional Insights
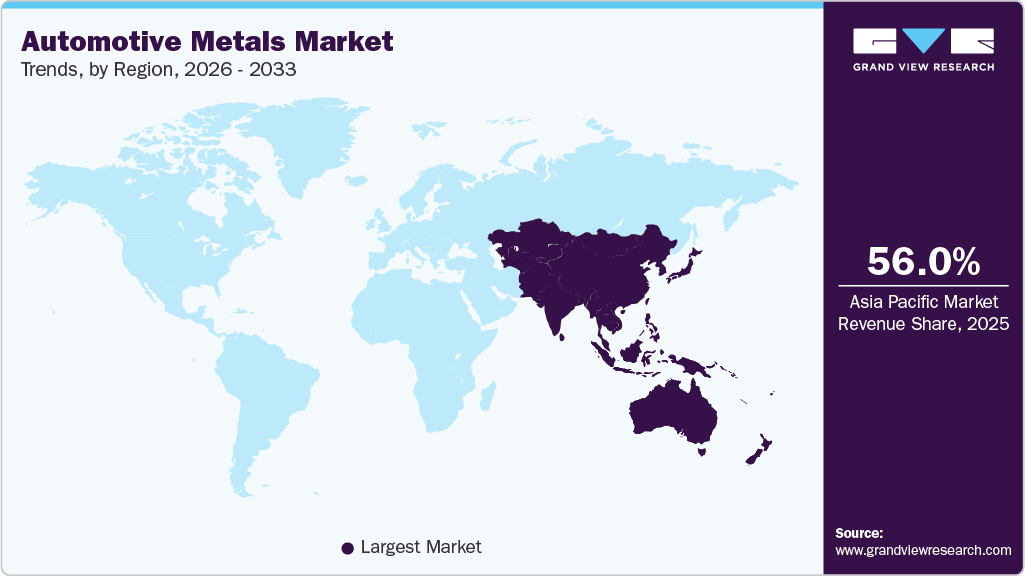
Asia Pacific dominated the automotive metals market with the largest revenue share of 56% in 2025. Asia Pacific accounts for the largest share of global automotive manufacturing, supported by high domestic sales and export-based production hubs in China, Japan, South Korea, Thailand, and Indonesia. Higher vehicle output directly increases consumption of steel, aluminum, and alloy metals across body-in-white, powertrain, suspension, and safety components, making production scale one of the strongest contributors to market expansion.
 To learn more about this report, Download Free Sample Report
North America Automotive Metals Market Trends
North America has a high preference for larger vehicles, which require significant volumes of steel and aluminum for body structures, chassis, and suspension systems. To comply with fuel efficiency regulations and reduce emissions, OEMs are increasingly shifting from conventional steel to AHSS and aluminum-intensive designs, particularly in full-size pickups, where weight reduction directly improves performance and fuel economy.
U.S. Automotive Metals Market Trends
The U.S. automotive metals market is being shaped by a distinct set of drivers compared to Europe, defined less by carbon regulation and more by trade policy realignment, industrial protectionism, and a volatile pivot toward domestic battery production. The USMCA’s mandatory rules of origin, requiring 70% of a vehicle’s steel and aluminum to originate in North America, serve as the primary structural driver for regional metal demand. However, this mechanism is under intense strain due to a surge in Chinese foreign direct investment in Mexican automotive manufacturing, which critics argue allows non-North American content to circumvent tariffs.
Europe Automotive Metals Market Trends
Electrification is one of the strongest growth drivers for the automotive metals market in Europe. As battery electric vehicle (BEV) adoption rises across Germany, France, the UK, and the Nordics, automakers are increasing their use of lightweight and high-performance metals to offset the heavy battery pack weight. This directly supports higher demand for aluminum in body structures, battery enclosures, and thermal management systems, while AHSS continues to remain critical for safety-focused vehicle designs.
Middle East & Africa Automotive Metals Market Trends
Vehicle assembly expansion and industrial diversification are major growth drivers for the automotive metals market in the Middle East and Africa. Countries such as Saudi Arabia, UAE, Egypt, Morocco, and South Africa are strengthening their automotive manufacturing and assembly ecosystems to reduce import dependency and support local industrial development. As local vehicle production increases, demand rises for automotive-grade steel, aluminum, and alloy-based components used in body structures, chassis, and suspension systems.
Key Automotive Metals Company Insights
Some of the key players operating in the market include Thyssenkrupp AG., Tata Steel, and others.
-
Tata Steel is one of the world’s leading integrated steel producers, headquartered in India, with a strong global manufacturing footprint across Asia and Europe. The company has a well-established presence in automotive-grade steel, supplying high-performance flat steel products to major OEMs and tier suppliers. In the automotive metals space, Tata Steel offers a broad portfolio including AHSS, UHSS, galvanized and galvannealed steel, hot-rolled and cold-rolled steel sheets, and specialized coated steel solutions.
-
Thyssenkrupp AG is a major German industrial conglomerate with a strong legacy in steel manufacturing and engineering solutions, serving automotive, construction, and industrial end-use sectors globally. Through its steel division, the company is a key supplier of premium flat steel products for the automotive industry, particularly in Europe. Thyssenkrupp’s automotive metals offerings include high-strength and advanced high-strength steel grades, cold-rolled and hot-rolled steel, galvanized steel sheets, electrical steel, and tailored blanks designed for lightweight vehicle structures and enhanced crash performance.
Key Automotive Metals Companies:
The following key companies have been profiled for this study on the automotive metals market.
- ArcelorMittal
- Essar Steel
- Hyundai Steel
- Nippon Steel & Sumitomo Metal Corporation
- Novelis
- POSCO
- Tata Steel
- Thyssenkrupp AG
- United Steel Corporation
- Voestalpine Group
Recent Developments
-
In February 2026, Hyundai Steel started mass production of low-emission steel sheets that reduce carbon emissions by around 20% compared to conventional blast furnace products. These products are manufactured using a pioneering hybrid steelmaking process combining molten metal from electric arc furnaces and blast furnaces, first tested at the company's Dangjin plant from April 2023.
Automotive Metals Market Report Scope
Report Attribute
Details
Market definition
The automotive metals market size represents the total value of metal materials consumed in vehicle manufacturing during a particular year.
Market size in 2025
USD 411.4 billion
Estimated market size in 2026
USD 439.4 billion
Projected market size by 2033
USD 740.0 billion
Growth rate
CAGR of 7.7% from 2026 to 2033
Base year for estimation
2025
Historical data
2021 - 2024
Forecast period
2026 - 2033
Quantitative Units
Volume in kilotons, revenue in USD million/billion, and CAGR from 2026 to 2033
Report coverage
Volume forecast, revenue forecast, competitive landscape, growth factors, and trends
Segments covered
Product, Application, Vehicle Type, Region
Regional scope
North America; Europe; Asia Pacific; Latin America; Middle East & Africa
Country scope
U.S.; Canada; Mexico; Germany; France; Italy; Russia; China; Japan; India; Brazil; Saudi Arabia; UAE
Key companies profiled
ArcelorMittal; Tata Steel; Hyundai Steel; Essar Steel; Thyssenkrupp AG; Novelis; POSCO; Voestalpine Group; Nippon Steel & Sumitomo Metal Corporation; United Steel Corporation
Customization scope
Free report customization (equivalent up to 8 analysts working days) with purchase. Addition or alteration to country, regional & segment scope.
Pricing and purchase options
Avail customized purchase options to meet your exact research needs. Explore purchase options
Global Automotive Metals Market Report Segmentation
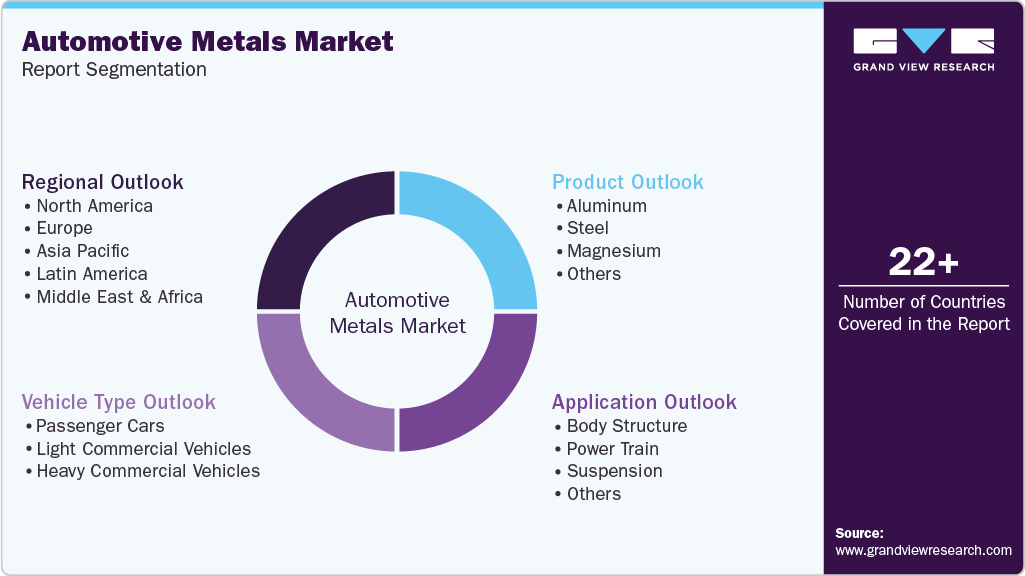
This report forecasts revenue and volume growth at global, regional, and country levels and provides an analysis of the latest industry trends in each of the sub-segments from 2021 to 2033. For the purpose of this study, Grand View Research has segmented the global automotive metals market report on the basis of product, application, vehicle type, and region:
 To learn more about this report, Download Free Sample Report
-
Product Outlook (Volume, Kil0tons; Revenue, USD Million; 2021 - 2033)
-
Aluminum
-
Steel
-
Magnesium
-
Others
-
-
Application Outlook (Volume, Kil0tons; Revenue, USD Million; 2021 - 2033)
-
Body Structure
-
Power Train
-
Suspension
-
Others
-
-
Vehicle Type Outlook (Volume, Kil0tons; Revenue, USD Million; 2021 - 2033)
-
Passenger Cars
-
Light Commercial Vehicles
-
Heavy Commercial Vehicles
-
-
Regional Outlook (Volume, Kil0tons; Revenue, USD Million; 2021 - 2033)
-
North America
-
U.S.
-
Canada
-
Mexico
-
-
Europe
-
Germany
-
France
-
Italy
-
Russia
-
-
Asia Pacific
-
China
-
Japan
-
India
-
-
Latin America
-
Brazil
-
-
Middle East & Africa
-
Saudi Arabia
-
UAE
-
-
Frequently Asked Questions About This Report
The global automotive metals market is expected to grow at a compound annual growth rate of 7.7% from 2026 to 2033 to reach USD 740.0 billion by 2033.
The global automotive metals market size was estimated at USD 411.4 billion in 2025 and is expected to reach USD 439.4 billion in 2026.
Body structure held the largest revenue share of more than 37.7% in 2025.
The key factors driving the global automotive metals market are the rising production of passenger and commercial vehicles, increasing demand for lightweight materials to improve fuel efficiency and reduce emissions, rapid growth of electric vehicles (EVs), stricter government regulations on carbon emissions, and the increasing use of advanced high-strength steel, aluminum, and magnesium in modern vehicle manufacturing.
Some of the key vendors of the global automotive metals market are ArcelorMittal, Tata Steel, Hyundai Steel, Essar Steel, Thyssenkrupp AG, Novelis, POSCO, Voestalpine Group, Nippon Steel & Sumitomo Metal Corporation, United Steel Corporation, among others
The aluminum segment led with a 60.0% revenue share in 2025, while magnesium is the fastest-growing segment.
Passenger cars held the largest shar in 2025.
Asia Pacific dominated with a 56.0% revenue share in 2025.
About the Author(s)
Advanced Interior Materials Research Team
Advanced Materials · Advanced Interior MaterialsThis report was authored by the advanced interior materials research team at Grand View Research - comprising two research analysts, one senior research analyst, and one industry expert - with specialized expertise in the advanced interior materials segment of the advanced materials industry. All findings are based on proprietary advanced materials databases, executive interviews, and regulatory analysis, subject to internal peer review prior to publication.
Last Updated:
Speak to Analyst

Customize this report to your needs - add regions, segments, or data points, with 20% free customization.
Or view our licence options:


ISO 9001:2015 & 27001:2022 Certified
We are GDPR and CCPA compliant! Your transaction & personal information is safe and secure. For more details, please read our privacy policy.


