
- Home
- »
- Advanced Interior Materials
- »
-
Automotive Steel Market Size And Share Report, 2026-2033GVR Report cover

Automotive Steel Market (2026 - 2033)
Size, Share & Trends Analysis Report By Vehicle Type (Passenger Vehicle, LCVs, HCVs), By Application (Body Structure, Power Train, Suspension), By Region, And Segment Forecasts
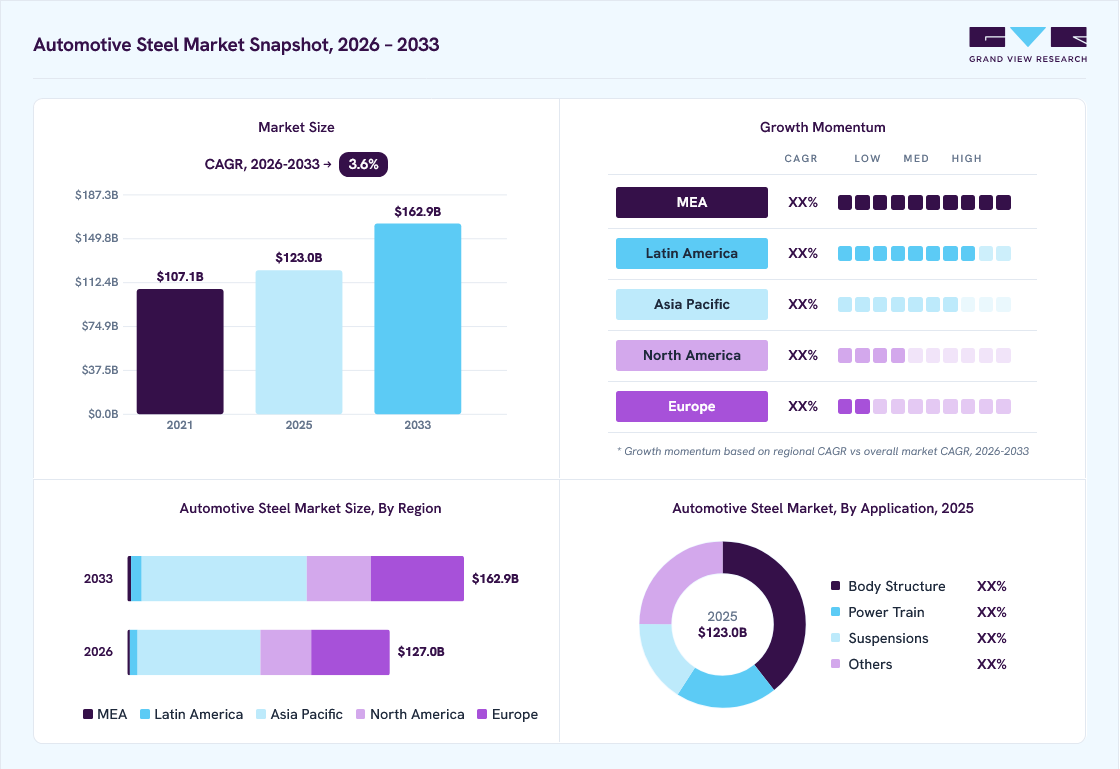
Market Size, 2025
$123.0BMarket Estimate, 2026
$127.0BMarket Forecast, 2033
$162.9BCAGR, 2026–2033
3.6%Automotive Steel Market Summary
The automotive steel market size was valued at USD 123.0 billion in 2025 and is projected to grow from USD 127.0 billion in 2026 to USD 162.9 billion by 2033, at a CAGR of 3.6% from 2026 to 2033. Asia Pacific dominated the market, accounting for a revenue share of 46.4% in 2025. The market growth can be attributed to the increasing vehicle production and sales and rising concerns about weight and fuel efficiency.
 Source: Grand View Research, IR Documents, Primary Interviews, Paid DatabasesTo learn more about this report,
 Download Free Sample Report
Key Market Trends & Insights
- By vehicle type: Passenger cars segment led the market with the largest revenue share of 54.1% in 2025.
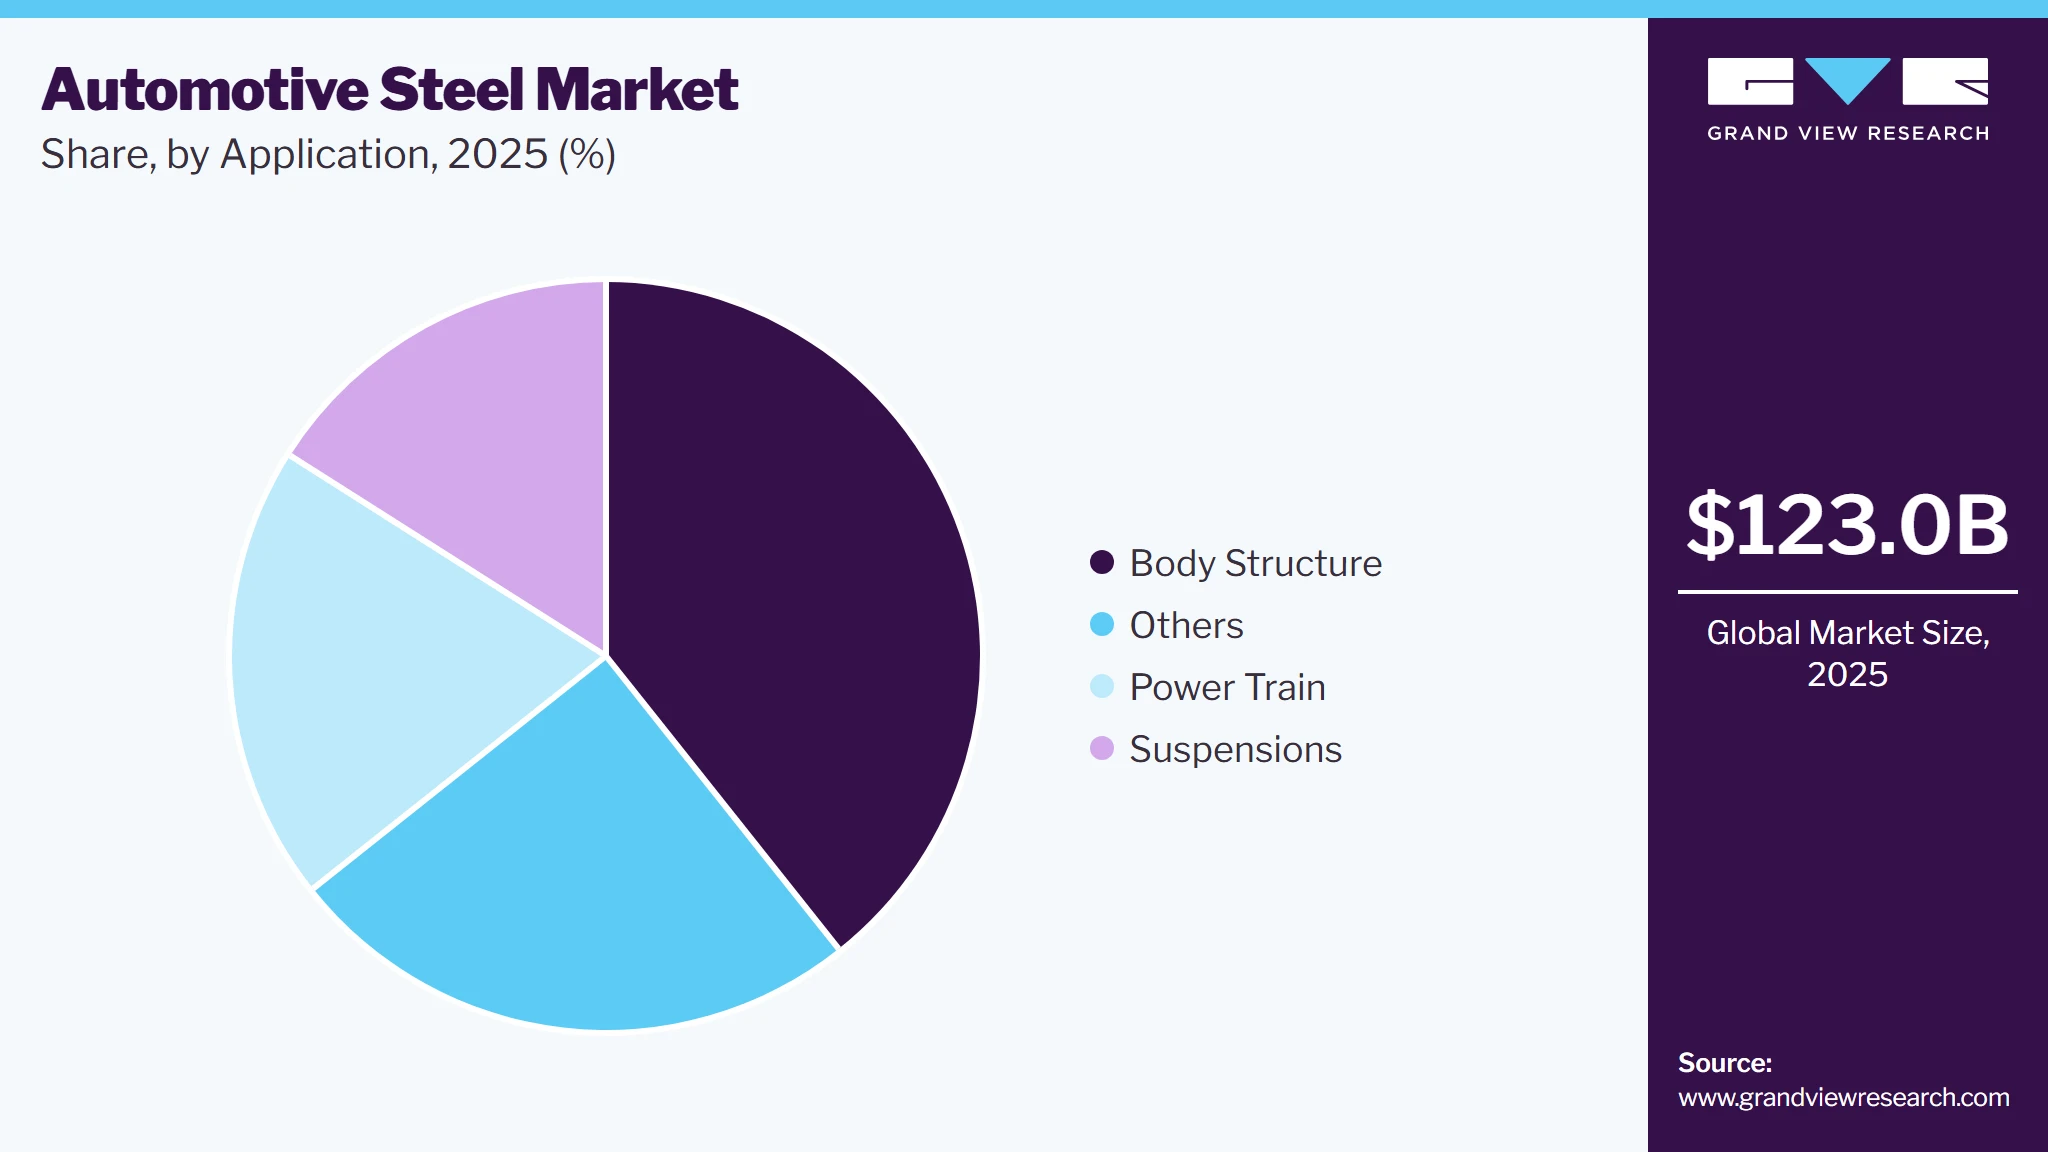
- By application: Body structure segment led the market with the largest revenue share of 39.3% in 2025.
Regional Highlights
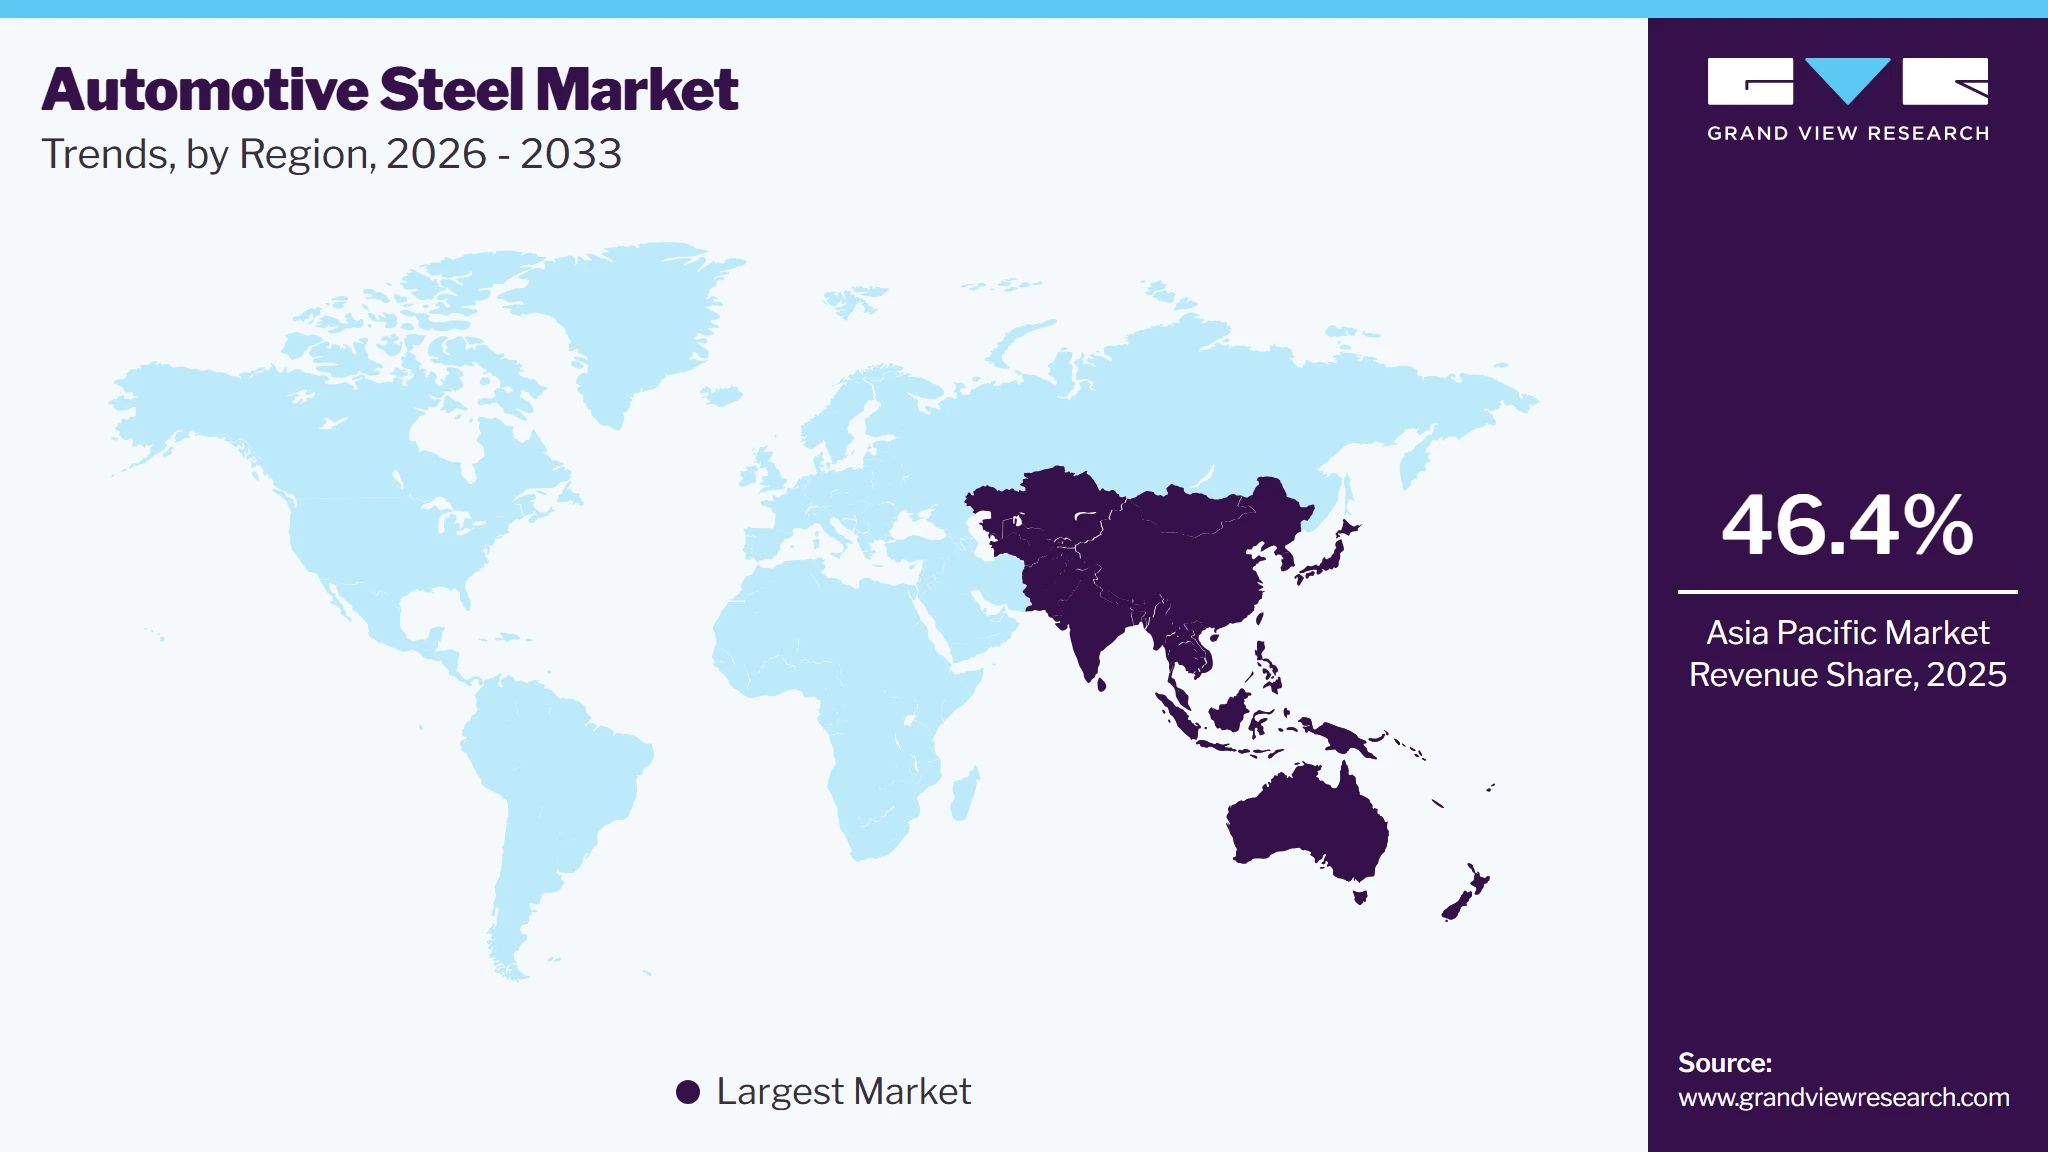
- Largest regional market: Asia Pacific (46.4% revenue share, 2025)
- By country: China held the largest market share in 2025.
Market Size & Forecast
- Market size in 2025: USD 123.0 Billion
- Estimated market size in 2026: USD 127.0 Billion
- Projected market size by 2033: USD 162.9 Billion
- CAGR (2026-2033): 3.6%
Three ways to get this report
Buy it, customize it, or ask a question.Ask an Analyst
Analyst response in 1 business day
- AccessReport author, directly
- Reply timeWithin 1 working day
- No sales callDirect answer only
- FormatEmail reply
- CostFree, no cost
Get the Full Report
What the study covers
- FormatsPDF · Excel · Dashboard
- Timeline2026–2033 annual, 2025 base
- Coverage20+ countries, 5 regions
- Companies10+ key players profiled
Customize the Report
20% free customization
- IncludeCountries, segments, points
- TailorTo your product definition
- ExtendDeeper competitor detail
- OrA fully bespoke study
- Turnaround5–10 working days
In addition, stringent safety regulations and the demand for cost-effective materials enhance the appeal of automotive steel. Furthermore, the shift towards electric vehicles and innovations in steel alloys further propel this sector as manufacturers seek to reduce carbon emissions while improving vehicle performance and sustainability.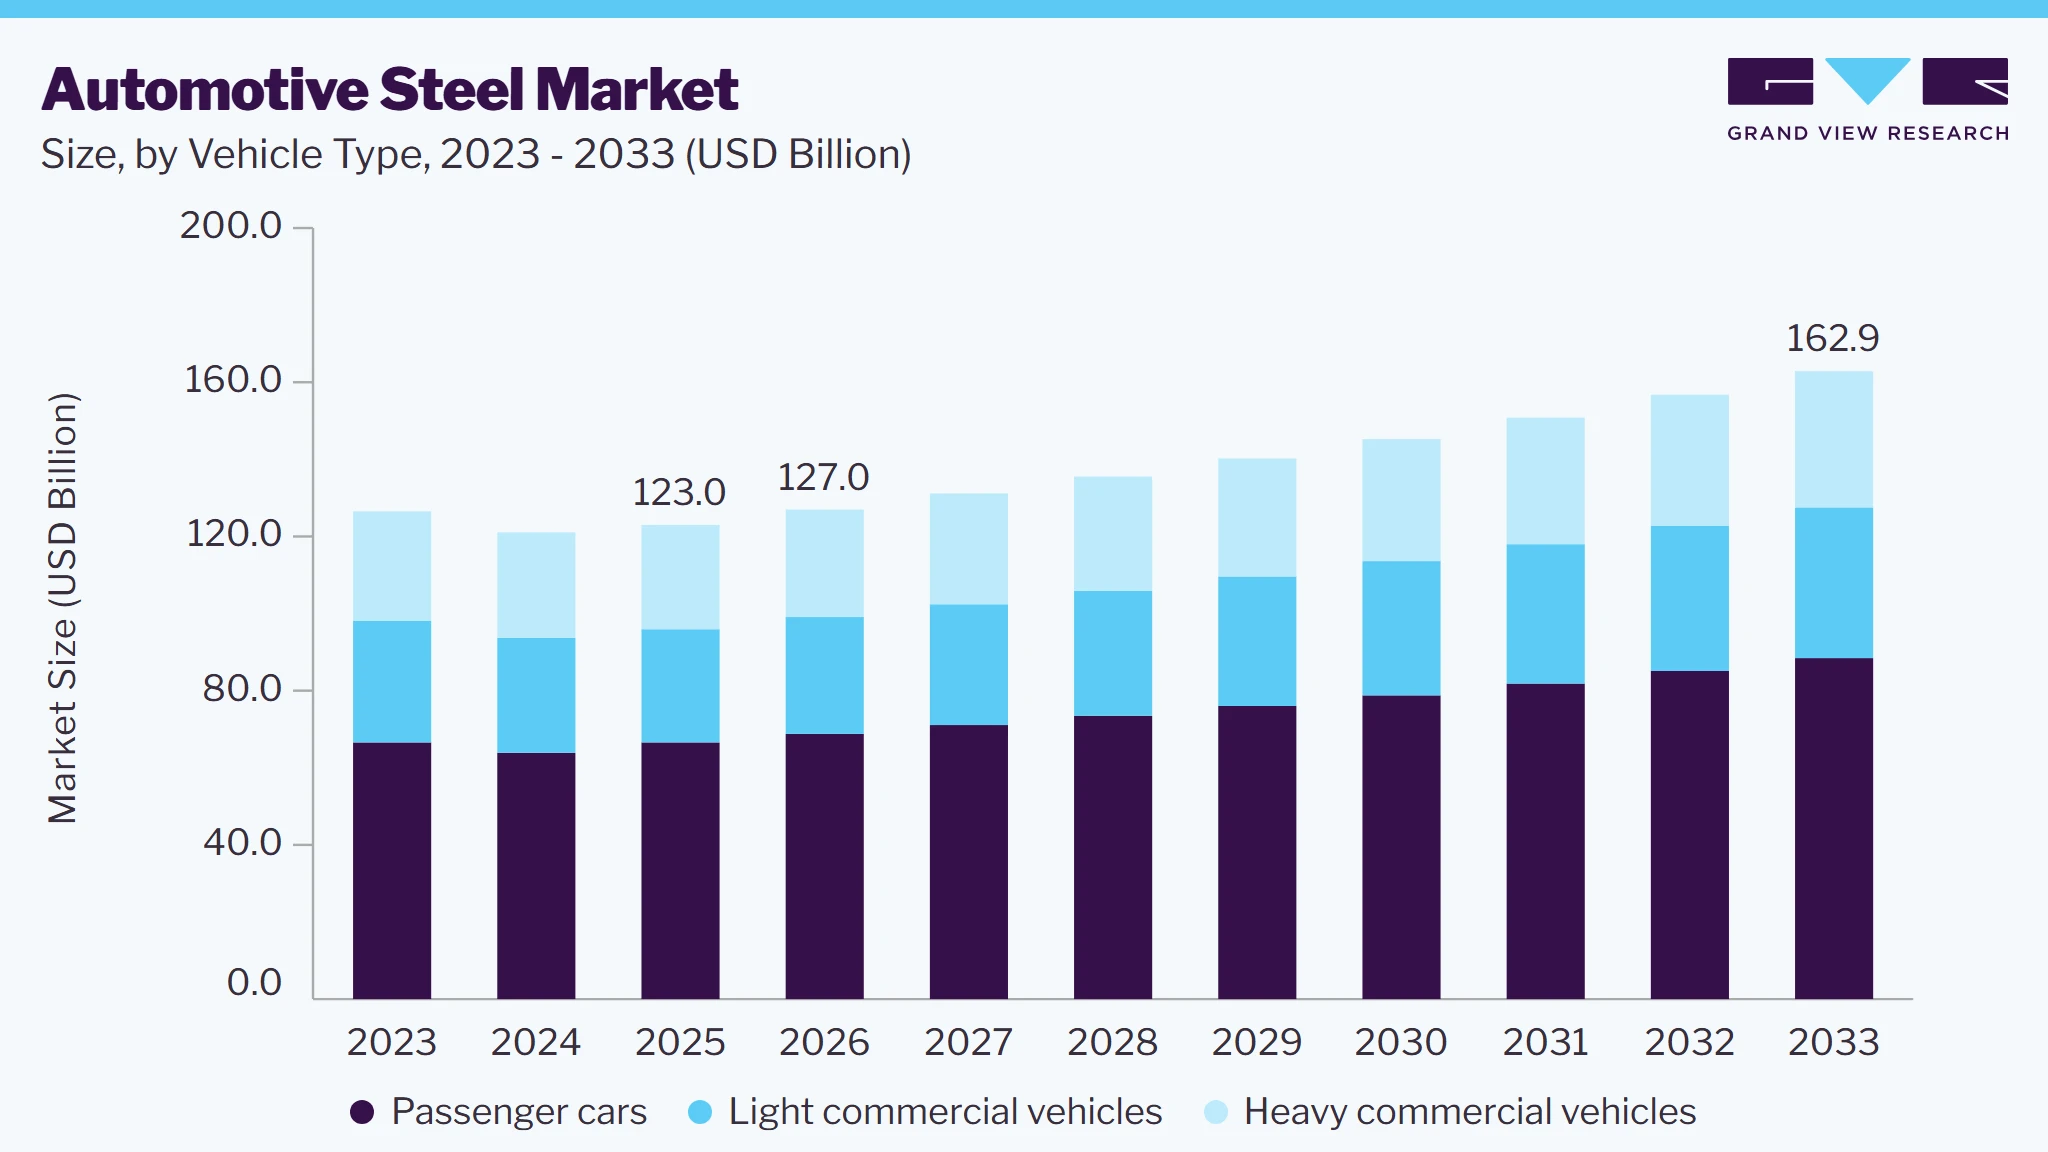 To learn more about this report, Download Free Sample Report
Automotive steel refers to the specialized steel used in the manufacturing of vehicles, designed to meet specific safety, performance, and weight requirements. The growing demand for high-strength steel (HSS) and advanced high-strength steel (AHSS) is a primary factor driving the automotive steel market. Manufacturers increasingly focus on lightweight vehicle designs that enhance fuel efficiency while ensuring safety. HSS and AHSS provide the necessary strength and rigidity, allowing for reduced vehicle weight without compromising structural integrity.
In addition, advancements in steel production technologies have improved the properties of automotive steel, making it suitable for various applications. Innovations such as hot stamping and laser welding enable the production of stronger, more formable, and corrosion-resistant steel grades. The introduction of third-generation AHSS combines high tensile strength with enhanced ductility, offering manufacturers greater design flexibility for complex geometries that improve passenger protection.
Furthermore, the rise of electric vehicles (EVs) further fuels the demand for automotive steel as manufacturers seek materials that offer durability and cost-effectiveness while reducing weight. Steel remains a preferred choice for chassis and safety components due to its high strength-to-weight ratio and recyclability. Moreover, sustainability considerations are increasingly influencing material selection in the automotive industry. Steel's recyclability positions it as a competitive option, aligning with manufacturers' goals to reduce environmental impact and promote circular economy principles through eco-friendly production processes.
Market Dynamics
The growth of the automotive steel market is primarily driven by the steady expansion of global vehicle production, particularly in emerging economies across Asia Pacific, Latin America, and parts of Eastern Europe. Rising disposable incomes, rapid urbanization, and increasing demand for passenger cars, light commercial vehicles, and heavy trucks continue to drive steel consumption across the automotive manufacturing sector. In parallel, stringent fuel-efficiency and vehicle-safety regulations are encouraging automakers to adopt advanced high-strength steel (AHSS) and ultra-high-strength steel (UHSS), which deliver higher strength and lower weight while maintaining crash performance. These materials enable manufacturers to reduce vehicle mass, improve fuel economy, and meet increasingly strict emission standards without significantly increasing production costs.
The increasing production of passenger cars, light commercial vehicles, and heavy trucks remains one of the primary growth drivers for the automotive steel market. Rising urbanization, population growth, expanding industrial activities, and improving household incomes are contributing to higher vehicle ownership across both developed and emerging economies. As automotive manufacturers expand production capacities to meet growing domestic and export demand, the consumption of automotive steel continues to increase across body structures, chassis, suspension systems, powertrain components, and safety assemblies. This trend is particularly evident in the Asia Pacific, where countries such as China and India continue to account for a significant share of global vehicle manufacturing.
In addition, the recovery of automotive production following supply chain disruptions, coupled with investments in new manufacturing facilities and localized vehicle production, is strengthening demand for advanced automotive materials. Original equipment manufacturers are increasing production of conventional, hybrid, and electric vehicles to address evolving consumer preferences and regulatory requirements, further expanding steel consumption. Since steel remains one of the most cost-effective, durable, and recyclable materials used in vehicle manufacturing, rising automotive production directly supports sustained demand for automotive steel across all vehicle categories.
The increasing adoption of lightweight materials such as aluminum, magnesium, carbon fiber composites, and high-performance engineering plastics presents a significant restraint for the automotive steel market. Automakers are incorporating these materials into body panels, closures, structural components, and interior parts to reduce vehicle weight, improve fuel efficiency, and extend the driving range of electric vehicles. While advanced high-strength steel continues to offer an effective balance of strength, safety, and cost, certain applications are increasingly shifting toward alternative lightweight materials due to their superior weight reduction potential. This gradual substitution of materials is limiting the growth of conventional automotive steel in selected vehicle segments and intensifying competition among material suppliers.
The growing demand for low carbon and green steel presents a significant opportunity for the automotive steel market as vehicle manufacturers accelerate their decarbonization strategies and work toward net zero emission targets. Automotive original equipment manufacturers are increasingly seeking steel produced through low emission processes, including electric arc furnaces, hydrogen based direct reduced iron, and greater use of recycled scrap, to reduce the carbon footprint of their vehicles. This shift is encouraging steel producers to invest in cleaner production technologies and develop certified low carbon steel products that meet stringent environmental standards. As sustainability becomes a key purchasing criterion across the automotive value chain, suppliers offering green steel solutions are expected to secure long term supply agreements and strengthen their competitive position in the global automotive steel market.
Analyst Perspective
The automotive steel market is steadily evolving as automakers seek materials that balance strength, safety, cost efficiency, and sustainability. Although lightweight alternatives such as aluminum and composites are gaining traction in selected vehicle components, advanced high-strength steel and ultra-high-strength steel continue to play a vital role in modern vehicle manufacturing due to their excellent crash performance, durability, recyclability, and cost-effectiveness. Rising production of passenger cars, commercial vehicles, and electric vehicles is supporting long-term demand, while increasing adoption of low-carbon and green steel is creating new opportunities for steel producers to align with automotive decarbonization goals.
Vehicle Type Insights
Passenger cars segment led the market with the largest revenue share of 54.1% in 2025. This growth can be attributed to the increasing demand for lightweight materials that enhance fuel efficiency and meet stringent safety standards. In addition, consumers prioritize eco-friendly vehicles, so manufacturers turn to advanced high-strength steel (AHSS) to reduce vehicle weight without compromising structural integrity. Furthermore, this shift aligns with regulatory pressures to reduce carbon emissions and supports the development of modern vehicle designs that cater to consumer preferences for performance and sustainability.
The heavy commercial vehicle segment is expected to grow at a CAGR of 7.6% over the forecast period, owing to the rising logistics and transportation industries, which require robust and durable materials. In addition, the demand for heavy-duty vehicles is increasing due to urbanization and the expansion of e-commerce, necessitating efficient transportation solutions. Furthermore, government initiatives promoting eco-friendly vehicles, including electric commercial vehicle incentives, encourage manufacturers to adopt advanced steel solutions. These developments aim to enhance vehicle performance while adhering to environmental regulations, driving this sector's demand for high-strength automotive steel.
Application Insights
Based on application, body structure segment led the market with the largest revenue share of 39.3% in 2025, primarily driven by the increasing demand for advanced high-strength steel (AHSS). This material allows manufacturers to create lighter, more fuel-efficient vehicles while ensuring safety and structural integrity. In addition, stringent safety regulations further necessitate using robust materials that can effectively absorb crash energy. Furthermore, steel's high recyclability enhances its appeal, aligning with the automotive industry's shift toward sustainable practices.
 To learn more about this report, Download Free Sample Report
The suspension application segment is expected to grow at a CAGR of 7.0% from 2025 to 2033, owing to the demand for automotive steel being propelled by the need for high-strength and rigidity components. Suspension systems are subjected to significant stress and vibrations, requiring materials that can withstand these conditions without compromising performance. Furthermore, as vehicle manufacturers focus on improving ride quality and handling, using advanced steel grades in suspension components is becoming increasingly prevalent. This trend supports the overall growth of the automotive steel market, as robust suspension systems are essential for vehicle safety and durability.
Regional Insights
Asia Pacific dominated the automotive steel market with the largest revenue share of 46.4% in 2025. This growth can be attributed to the rising demand for electric and lightweight vehicles. As countries such as China and India ramp up automotive production, manufacturers are increasingly adopting advanced high-strength steel (AHSS) to enhance fuel efficiency and meet stringent safety standards. Furthermore, government initiatives to reduce carbon emissions further encourage the use of sustainable materials, making automotive steel a key component in the transition towards greener transportation solutions.
 To learn more about this report, Download Free Sample Report
The automotive steel market in the China held the largest share in the Asia Pacific region in 2025, driven by the rapid expansion of the electric vehicle (EV) sector. The government's strong support for EV production and increasing consumer preference for environmentally friendly vehicles drive demand for high-strength steel. In addition, advancements in steel manufacturing technologies enable the production of lighter and more durable materials, which are essential for improving vehicle performance and safety. This combination of factors positions China as a leader in the automotive steel market.
Europe Automotive Steel Market Trends
Europe automotive steel market is expected to grow at a CAGR of 7.8% over the forecast period, owing to stringent regulations to reduce carbon emissions and promote sustainability. In addition, the push for electric vehicles and lightweight materials has led manufacturers to adopt advanced high-strength steel solutions. Furthermore, government incentives and subsidies for EV production encourage automakers to invest in innovative steel technologies that enhance vehicle efficiency. This regulatory environment fosters a competitive landscape that propels the demand for automotive steel across European countries.
The automotive steel market in Germany dominated the European market and accounted for the largest revenue share in 2024, primarily driven by a strong focus on engineering excellence and innovation in vehicle design. As one of Europe's largest automotive producers, Germany emphasizes using advanced high-strength steel to create lightweight vehicles that meet rigorous safety standards while improving fuel efficiency. The country's commitment to sustainability and environmental responsibility further drives demand for innovative steel solutions, positioning Germany at the forefront of European automotive steel advancements.
North America Automotive Steel Market Trends
The North America automotive steel market is expected to grow significantly over the forecast period, driven by increasing investments in electric vehicle infrastructure and production. In addition, government policies promoting fuel efficiency and stricter emissions regulations compel manufacturers to utilize advanced high-strength steel in their designs. Furthermore, the rising consumer demand for lightweight vehicles with better performance and lower environmental impact also contributes to this trend.
The automotive steel market in the U.S. is expected to be driven by technological advancements and government initiatives aimed at promoting electric vehicles. In addition, the increasing focus on reducing greenhouse gas emissions drives manufacturers to explore lightweight materials such as advanced high-strength steel. Furthermore, substantial investments in EV infrastructure signal a shift towards sustainable transportation solutions, further enhancing the demand for automotive steel products that meet evolving consumer preferences and regulatory requirements. This dynamic landscape positions the U.S. as a key global automotive steel market player.
Key Automotive Steel Company Insights
Key companies in the global automotive steel industry include JSW, Nippon Steel Corporation, Nucor, and others. These companies adopt various strategies to enhance their competitive edge. These include investing in research and development to innovate advanced steel grades, improving production processes, and developing lightweight solutions. In addition, collaborations and partnerships with automotive manufacturers are also emphasized to create tailored steel products that meet specific vehicle requirements. Furthermore, companies focus on sustainability initiatives, such as enhancing recycling processes and reducing carbon emissions, aligning their operations with global environmental standards and consumer expectations for greener products.
-
Hyundai Steel manufactures hot and cold-rolled steel sheets, coated steel, and structural components designed to enhance vehicle performance and safety. Operating primarily in the automotive segment, the company focuses on developing innovative materials that meet the evolving demands of the automotive industry, particularly in lightweight vehicle manufacturing and sustainability.
-
JFE Steel Corporation produces high-strength steel, cold-rolled sheets, and coated steel, catering to the needs of automotive manufacturers seeking to improve fuel efficiency and safety. The company operates within the automotive segment, emphasizing the development of advanced materials that support lightweight construction and meet stringent safety standards, thereby contributing to the overall advancement of the automotive industry.
Key Automotive Steel Companies
The following key companies have been profiled for this study on the automotive steel market.
-
ArcelorMittal
-
China BaoWu Steel Group Corporation Limited
-
Hyundai Steel
-
JFE Steel Corporation
-
JSW
-
Nippon Steel Corporation
-
Nucor
-
POSCO
-
Tata Steel
-
United States Steel Corporation
Market Participant Categorization
Operating Strategies
Competitive Edge
Weakness
Established Players (e.g. ArcelorMittal S.A., Thyssenkrupp AG)
- Mature participants in the automotive steel market primarily focus on large scale integrated steel production, continuous product innovation, and long term partnerships with automotive OEMs and Tier 1 suppliers.
- These companies operate advanced steelmaking, rolling, galvanizing, and finishing facilities capable of producing a wide range of automotive grades, including advanced high strength steel (AHSS), ultra high strength steel (UHSS), galvanized steel, and electrical steel.
- Established players possess significant competitive advantages through their integrated manufacturing infrastructure, extensive research capabilities, and large scale production capacities.
- Their ability to produce high quality automotive steel with consistent mechanical properties enables them to meet the demanding specifications of global automotive manufacturers.
- Despite their strong market positions, mature players face challenges associated with high capital intensity and rising production costs.
- Automotive steel manufacturing requires continuous investment in blast furnaces, rolling mills, galvanizing lines, coating technologies, and environmental compliance systems.
Emerging & Regional Players (e.g., SSAB AB, United States Steel Corporation)
- Emerging participants in the automotive steel market generally focus on specialized steel grades, regional manufacturing capabilities, and flexible production models.
- Rather than competing directly with established integrated producers on production scale, these companies target niche opportunities in high strength steels, coated automotive steel, and customized products for electric vehicles and lightweight vehicle platforms.
- Emerging companies benefit from operational flexibility and the ability to adopt modern steelmaking technologies without extensive legacy infrastructure.
- Their facilities often incorporate advanced automation, digital quality control, and energy efficient production systems, enabling improved operational performance and lower environmental impacts.
- Emerging participants face significant challenges related to limited production capacity, lower economies of scale, and restricted financial resources.
- Competing with established global steel manufacturers that possess integrated supply chains, extensive research capabilities, and long standing OEM relationships can be difficult.
Recent Developments
-
In June 2024, Tata Steel Nederland introduced Zeremis Recycled, a new automotive steel featuring 30% recycled content aimed at helping customers meet their circularity goals. This initiative aimed at the rising demand for sustainable steel in the automotive, packaging, and construction industries. As part of its Green Steel Plan, Tata Steel aimed for significant CO2 reductions and enhanced sustainability, supporting immediate environmental benefits for its clients.
-
In September 2023, LISI AUTOMOTIVE partnered with ArcelorMittal to advance sustainability in the automotive industry through the development of XCarb recycled and renewably produced low-carbon-emissions automotive steel. This collaboration aimed to significantly reduce carbon footprints and improve product quality by integrating innovative steel solutions into manufacturing processes.
Automotive Steel Market Report Scope
Report Attribute
Details
Market definition
The market size represents the value of annual consumption of steel utilized in the production of automobiles.
Market size in 2025
USD 123.0 billion
Estimated market size in 2026
USD 127.0 billion
Projected market size by 2033
USD 162.9 billion
Growth rate
CAGR of 3.6% from 2026 to 2033
Base year for estimation
2025
Historical data
2021 - 2024
Forecast period
2026 - 2033
Quantitative units
Revenue in USD million, volume in kilotons, and CAGR from 2026 to 2033
Report coverage
Revenue forecast, volume forecast, company ranking, competitive landscape, growth factors, and trends
Segments covered
Application, vehicle type, region.
Regional scope
North America; Europe; Asia Pacific; Latin America; Middle East & Africa
Country scope
U.S., Canada, Mexico, Germany, UK, France, India, China, Japan, Brazil
Key companies profiled
ArcelorMittal S.A., Thyssenkrupp AG, Nippon Steel Corporation, Hyundai Steel, POSCO, Tata Steel, Baosteel Group Corporation, JFE Steel Corporation, United States Steel Corporation
Customization scope
Free report customization (equivalent up to 8 analysts' working days) with purchase. Addition or alteration to country, regional & segment scope.
Pricing and purchase options
Avail customized purchase options to meet your exact research needs. Explore purchase options
Global Automotive Steel Market Report Segmentation
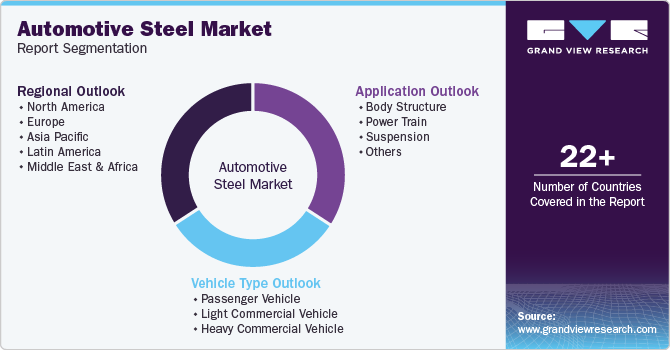
This report forecasts revenue growth at global, regional, and country levels and analyzes the latest industry trends in each sub-segment from 2021 to 2033. For this study, Grand View Research has segmented the automotive steel market report based on vehicle type, application, and region:
 To learn more about this report, Download Free Sample Report
-
Vehicle Type Outlook (Volume, Kilotons; Revenue, USD Million, 2021 - 2033)
-
Passenger Vehicle
-
Light Commercial Vehicle
-
Heavy Commercial Vehicle
-
-
Application Outlook (Volume, Kilotons; Revenue, USD Million, 2021 - 2033)
-
Body Structure
-
Power Train
-
Suspension
-
Others
-
-
Regional Outlook (Volume, Kilotons; Revenue, USD Million, 2021 - 2033)
-
North America
-
U.S.
-
Canada
-
Mexico
-
-
Europe
-
Germany
-
France
-
Italy
-
-
Asia Pacific
-
China
-
India
-
Japan
-
South Korea
-
-
Latin America
-
Brazil
-
Argentina
-
-
Middle East and Africa
-
Research Methodology
The automotive steel market figures in this report are based on a proven research process that combines executive interviews with secondary research from proprietary databases, company filings, and recognized regulatory and institutional sources. Market size is built through value-chain sizing-reconciling supply-side and demand-side estimates-and triangulated with bottom-up and top-down approaches. Every estimate passes multiple levels of expert validation before publication, with each automotive steel segment quantified using the revenue-capture definitions in the table below.
Segment Definition
Vehicle Type
Revenue Capture Definition
Passenger Cars
Revenue from passenger cars includes automotive steel used in the production of sedans, hatchbacks, SUVs, crossovers, and multi purpose vehicles. Market revenue is generated through the use of steel for body structures, chassis, closures, powertrain components, and safety systems.
Light Commercial Vehicles
Revenue from light commercial vehicles includes automotive steel supplied for vans, pickup trucks, and light duty cargo vehicles used for commercial transportation and logistics. Revenue is captured from steel utilized in frames, body panels, suspension systems, cargo structures, and structural reinforcements.
Heavy Commercial Vehicles
Revenue from heavy commercial vehicles includes automotive steel used in the manufacturing of heavy duty trucks, buses, trailers, and specialized commercial vehicles. Market revenue is derived from steel used for chassis, cabins, axles, load bearing structures, drivetrain components, and heavy duty safety applications.
Application
Revenue Capture Definition
Body Structure
Revenue from body structure includes automotive steel used in vehicle bodies, frames, pillars, roofs, doors, floor panels, and crash management components. Market revenue is generated from steel supplied to enhance structural strength, occupant safety, and vehicle durability.
Power Train
Revenue from the powertrain segment includes automotive steel utilized in engines, transmissions, drive shafts, gears, axles, and related drivetrain components. Revenue is captured through the supply of high strength and wear resistant steel that improves performance, efficiency, and reliability.
Suspensions
Revenue from suspensions includes automotive steel used in springs, control arms, stabilizer bars, suspension links, and other load bearing components. Market revenue is derived from steel supplied to improve ride comfort, handling, fatigue resistance, and vehicle stability.
Others
Revenue from the others segment includes automotive steel used in exhaust systems, steering components, seating structures, wheels, fasteners, fuel systems, and various interior and exterior parts. Revenue is generated from steel supplied for supporting applications that contribute to vehicle functionality, safety, and overall performance.
Estimation Model
Layer Name
Key Question
Description
Vehicle Production Demand Base Layer
What forms the demand base?
Identify global vehicle production across passenger cars, light commercial vehicles, and heavy commercial vehicles. Assess demand from OEM manufacturing and replacement requirements in the automotive aftermarket. Evaluate automotive production trends, vehicle parc growth, and regional manufacturing capacity to establish the total addressable demand for automotive steel.
Automotive Steel Penetration Layer
Where is automotive steel utilized?
Estimate the penetration of automotive steel across key vehicle applications including body structure, chassis, powertrain, suspension, wheels, exhaust systems, and safety components. Analyze the adoption of advanced high strength steel (AHSS), ultra high strength steel (UHSS), galvanized steel, hot stamped steel, and conventional steel across different vehicle segments and regions.
Steel Consumption Intensity Layer
How much automotive steel is consumed?
Analyze automotive steel consumption intensity based on vehicle type, vehicle weight, structural design, crash safety requirements, and lightweighting strategies. Evaluate average steel content per passenger car, light commercial vehicle, and heavy commercial vehicle while considering the increasing use of high strength steel grades to improve fuel efficiency and vehicle performance. Consumption intensity varies according to vehicle architecture, production technology, and regulatory standards.
Revenue Layer
How is market revenue generated?
Market revenue is quantified through the sale of automotive steel products including hot rolled, cold rolled, galvanized, advanced high strength, and ultra high strength steel supplied to OEMs and automotive component manufacturers. Revenue generation is driven by global vehicle production, replacement demand, value added steel grades, and regional automotive manufacturing activity. Market value is influenced by steel prices, raw material costs, product mix, lightweighting trends, and automotive production volumes.
Delivered Customizations
This report has been delivered with the following In-depth customizations
Client Request
Customization Delivered
Value Adds
Regional Segmentation
Detailed regional analysis of the automotive steel market across North America, Europe, Asia Pacific, Latin America, and Middle East & Africa. Included evaluation of passenger vehicle and commercial vehicle production, EV manufacturing capacity, automotive steel consumption trends, OEM investments, government fuel efficiency regulations, lightweight vehicle initiatives, and steel demand by vehicle manufacturing clusters.
Identified high growth automotive manufacturing hubs and emerging steel demand centers. Enabled strategic expansion planning based on vehicle production forecasts, EV adoption, and regional automotive investments. Supported demand forecasting and supply chain optimization.
Competitive Benchmarking
Benchmarking analysis of leading automotive steel manufacturers based on production capacity, automotive grade steel portfolio, advanced high strength steel capabilities, geographic footprint, OEM relationships, research and development investments, sustainability initiatives, manufacturing efficiency, and strategic partnerships. Included comparison of global steel producers supplying automotive OEMs and Tier 1 suppliers.
Assisted in evaluating competitive positioning, technological strengths, and market leadership opportunities. Supported partnership assessments, competitive intelligence, and strategic differentiation initiatives.
Opportunity Assessment
Identification of high growth opportunities across electric vehicles, advanced high strength steel adoption, lightweight vehicle platforms, battery electric vehicle structures, crash resistant body components, sustainable steel production, and low carbon automotive materials.
Enabled prioritization of high return growth segments and emerging regional opportunities. Supported long term investment planning, product innovation, capacity expansion decisions, and strategic business development initiatives aligned with the future of automotive manufacturing.
Frequently Asked Questions About This Report
The automotive steel market size was estimated at USD 123.0 billion in 2025 and is expected to reach USD 127.0 billion in 2026.
Asia Pacific dominated the market with revenue share of 46.4% in 2025.
China dominated the Asia Pacific market with revenue share in 2025.
The key factor that is driving the growth of the global automotive steel market is the growing demand for lightweight, fuel efficient, and electric vehicles, which require advanced high strength steel to improve safety, reduce vehicle weight, and enhance overall performance while meeting stringent emission regulations.
Body structure accounted for largest revenue share of 39.3% in 2025.
The automotive steel market is expected to grow at a compound annual growth rate of 3.6% from 2026 to 2033 to reach USD 162.9 billion by 2033.
Based on vehicle type, passenger cars segment accounted for a market revenue share of 54.1% in 2025.
The key players operating in the automotive steel market are ArcelorMittal S.A., Thyssenkrupp AG, Nippon Steel Corporation, Hyundai Steel, POSCO, Tata Steel, Baosteel Group Corporation, JFE Steel Corporation, United States Steel Corporation, SSAB AB.
About the Author(s)
Advanced Interior Materials Research Team
Advanced Materials · Advanced Interior MaterialsThis report was authored by the advanced interior materials research team at Grand View Research - comprising two research analysts, one senior research analyst, and one industry expert - with specialized expertise in the advanced interior materials segment of the advanced materials industry. All findings are based on proprietary advanced materials databases, executive interviews, and regulatory analysis, subject to internal peer review prior to publication.
Last Updated:
Speak to Analyst

Customize this report to your needs - add regions, segments, or data points, with 20% free customization.
Or view our licence options:


ISO 9001:2015 & 27001:2022 Certified
We are GDPR and CCPA compliant! Your transaction & personal information is safe and secure. For more details, please read our privacy policy.


