
- Home
- »
- Automotive & Transportation
- »
-
Autonomous Tractors Market Size, Share Report, 2026-2033GVR Report cover

Autonomous Tractors Market (2026 - 2033)
Size, Share & Trends Analysis Report By Power Output, By Automation, By Application, By Farming Type (Field Farming, Horticulture, Dairy Farming & Livestock Management), By Region, And Segment Forecasts
Market Size, 2025
$2.4BMarket Estimate, 2026
$2.8BMarket Forecast, 2033
$9.0BCAGR, 2026–2033
18.4%Autonomous Tractors Market Summary
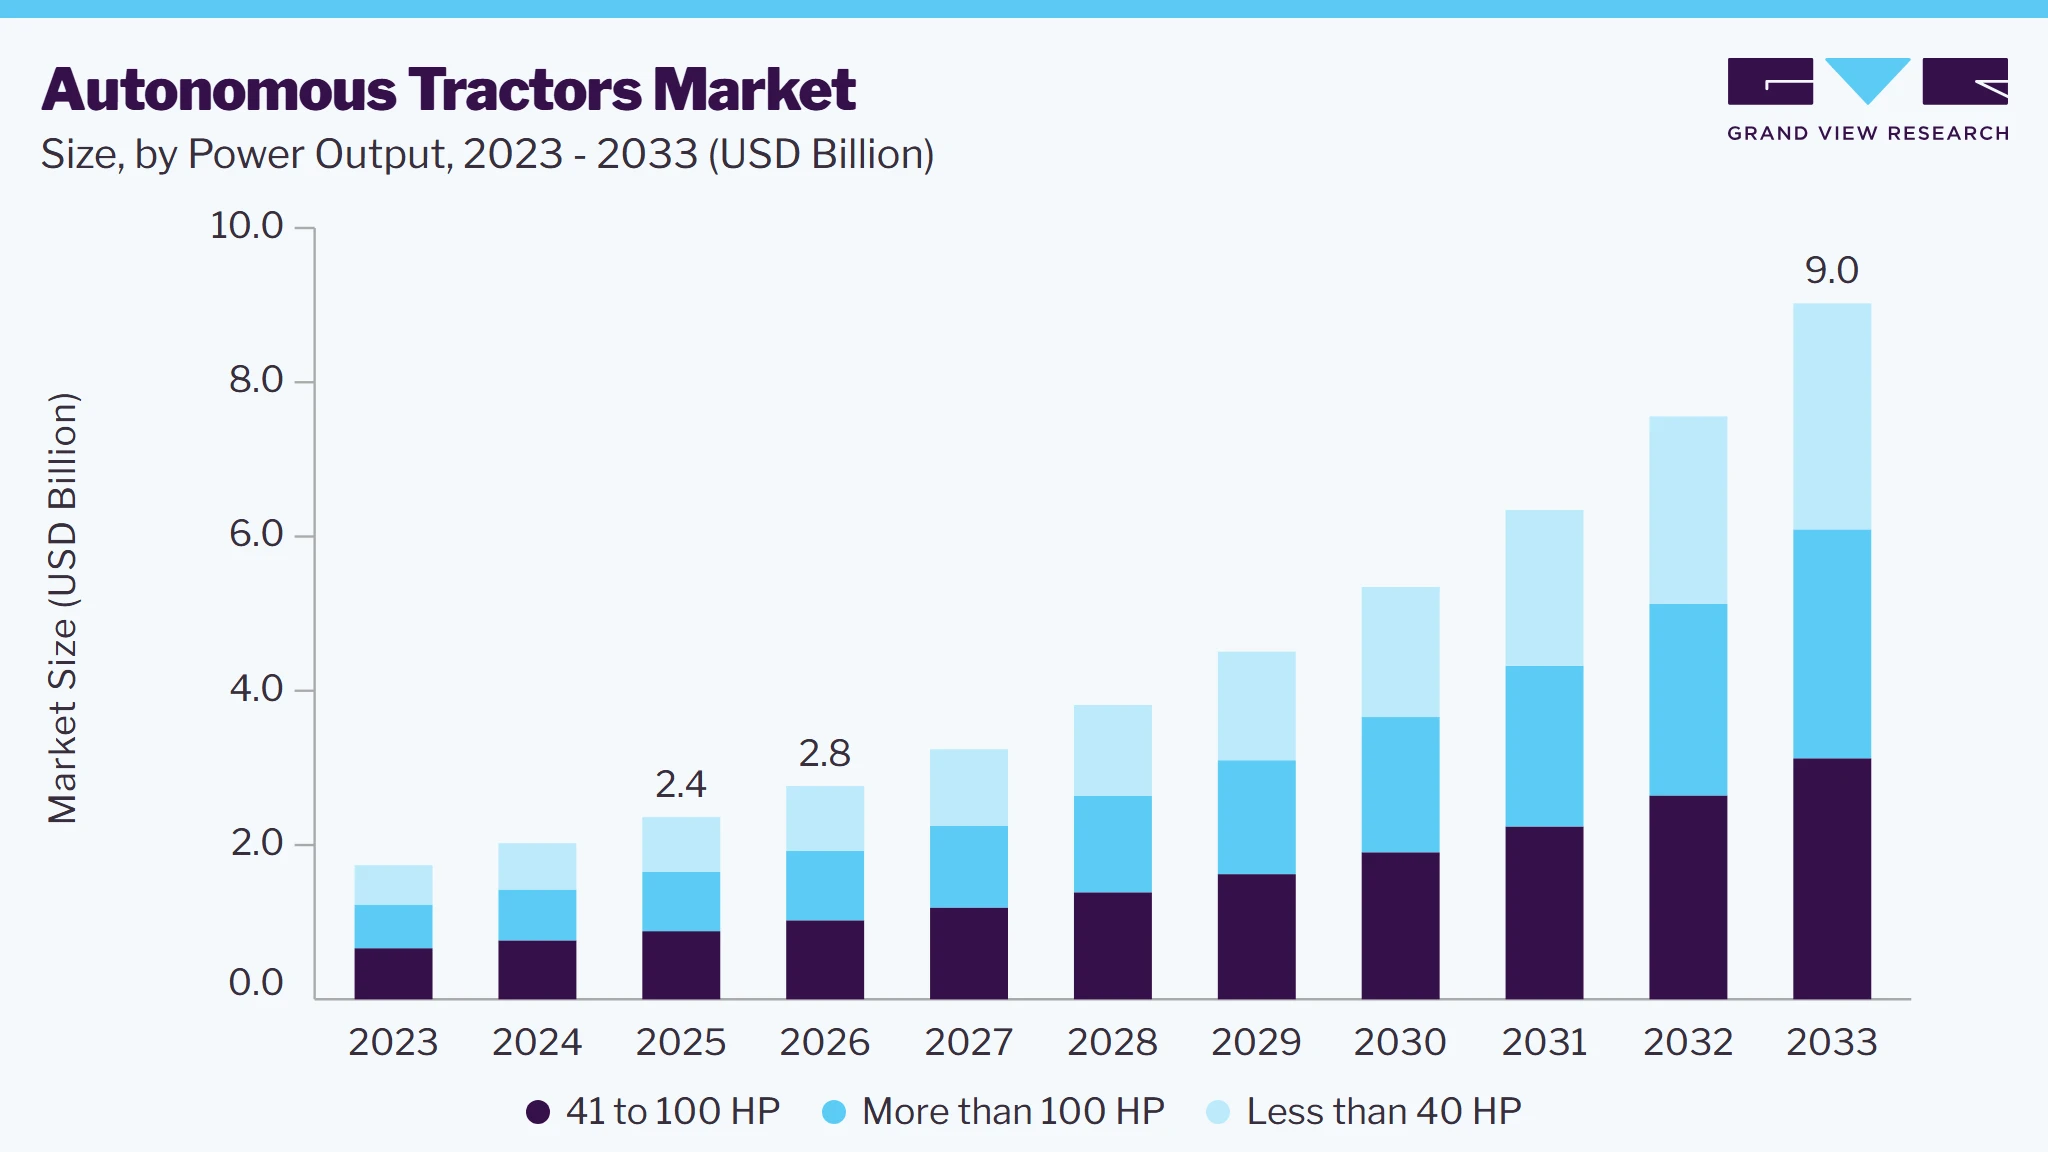
The global autonomous tractors market size was valued at USD 2.4 billion in 2025 and is projected to grow from USD 2.8 billion in 2026 to USD 9.0 billion by 2033, at a CAGR of 18.4% from 2026 to 2033. North America dominated the market, accounting for a revenue share of 37.2% in 2025. This growth is driven by increasing deployment of connected farm machinery.
 Source: Grand View Research, IR Documents, Primary Interviews, Paid DatabasesTo learn more about this report,
 Download Free Sample Report
Key Market Trends & Insights
- By power output: 41 to 100 hp segment dominated the market, with a revenue share of 37.4% in 2025.
- By automation: Partially- autonomous segment dominated the market, with a revenue share of 61.3% in 2025.
- By application: Harvesting segment dominated the market, with a revenue share of 36.4% in 2025.
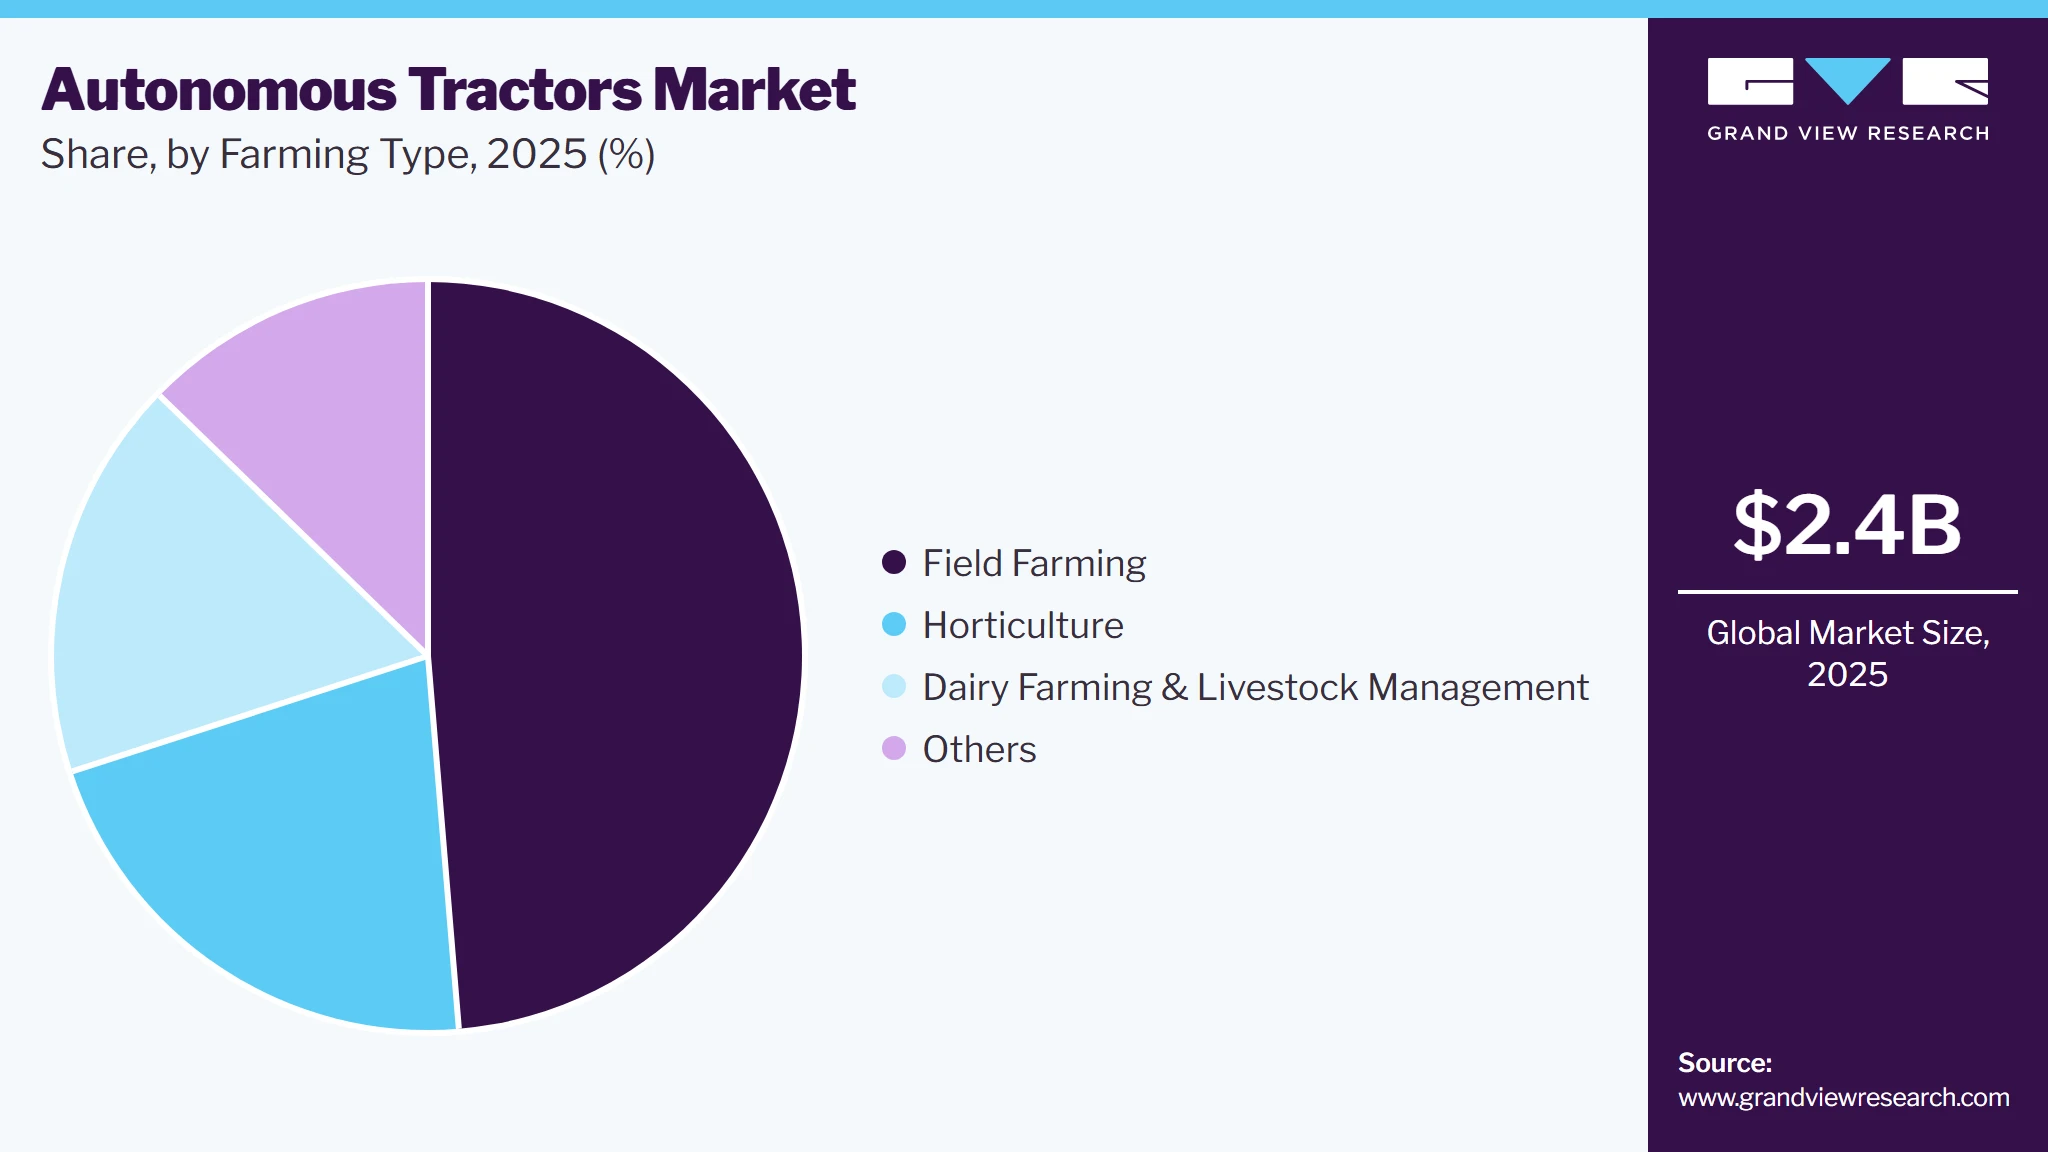
- By farming type: Field farming segment held the largest revenue share of 48.7% in 2025.
Regional Highlights
- Largest regional market: North America (37.2% revenue share, 2025)
- Fastest-growing regional market: Asia Pacific (highest CAGR, 2026-2033)
- By country: The U.S. held the largest market share in 2025.
Market Size & Forecast
- Market size in 2025: USD 2.4 Billion
- Estimated market size in 2026: USD 2.8 Billion
- Projected market size by 2033: USD 9.0 Billion
- CAGR (2026-2033): 18.4%
Prism AI by Grand View Research Free to tryAsk a question about the autonomous tractors marketTry asking✓Every figure cited from GVR research Prefer the report? Download free sample →The market for autonomous tractors is experiencing significant growth driven by a convergence of technological advancements, agricultural trends, economic factors, and environmental considerations. One of the primary drivers of autonomous tractor adoption is the global shortage of skilled agricultural labor. Many farming regions are facing difficulties in finding and retaining qualified workers. Autonomous tractors offer a solution by reducing the reliance on human operators, thereby mitigating the impact of labor scarcity. These machines can operate autonomously for extended periods, performing tasks with precision and consistency, which not only addresses labor shortages but also enhances overall farm productivity.
In addition, the trend towards larger farm sizes is another factor driving the demand for autonomous tractors. As agricultural operations scale up to meet growing food demand, there is a need for machinery that can efficiently cover expansive areas. Autonomous tractors excel in this regard, as they can operate continuously without human fatigue and manage large-scale operations effectively. This scalability enhances productivity and allows farmers to maximize their yields while minimizing operational costs over vast agricultural lands.
 To learn more about this report, Download Free Sample Report
Technological advancements play a crucial role in the development and adoption of autonomous tractors. Recent innovations in artificial intelligence, machine learning, GPS technology, and sensors have significantly enhanced the capabilities of these machines. AI algorithms enable autonomous tractors to navigate fields, detect obstacles, and make real-time adjustments in operations. GPS systems provide precise positioning data, allowing for accurate field mapping and targeted application of inputs such as fertilizers and pesticides. Such technological sophistication improves operational efficiency, reduces input wastage, and optimizes resource management on farms.
However, the target market faces several significant restraints that could slow down its widespread adoption and integration into agricultural practices worldwide. One of the foremost challenges is the high initial costs associated with autonomous tractor technology. Implementing autonomous systems requires substantial investment in advanced sensors, GPS equipment, artificial intelligence software, and integration with existing farm management systems. For many farmers, especially those operating smaller or medium-sized farms, these upfront costs can be prohibitive. The return on investment (ROI) must be carefully assessed against potential long-term savings in labor, efficiency gains, and reduced input costs to justify such expenditures.
Market Dynamics
The autonomous tractors market is experiencing rapid growth as agricultural producers increasingly adopt self-driving machinery to address labor shortages, improve field efficiency, and enhance precision across farming operations. Autonomous tractors equipped with GPS guidance, machine vision, artificial intelligence, sensors, and telematics can perform tasks such as plowing, planting, spraying, tillage, and hauling with minimal human intervention. Rising demand for precision agriculture, increasing farm consolidation, and the need to optimize fuel consumption, input usage, and equipment utilization are accelerating the deployment of autonomous tractor systems. Additionally, advancements in autonomous navigation technologies, connectivity infrastructure, and remote fleet management platforms are making autonomous tractors more commercially viable across a broader range of agricultural applications.
Drivers: Increasing adoption of telematics and remote equipment monitoring are driving market growth
The increasing adoption of telematics and remote equipment monitoring is driving market growth in the autonomous tractors market by enabling continuous visibility into tractor performance, operational efficiency, and field activity across large agricultural operations. Modern autonomous tractors increasingly generate extensive real-time data on engine performance, battery status, hydraulic systems, fuel consumption, equipment utilization, field coverage, and navigation accuracy, which can be transmitted directly to centralized management platforms. Farmers and agricultural enterprises increasingly require machinery capable of providing remote operational visibility without requiring constant physical supervision of field equipment. Telematics-enabled autonomous tractors allow operators to coordinate multiple machines across different fields while maintaining centralized oversight of operational conditions and equipment status throughout the farming cycle. The continued expansion of connected agricultural machinery is propelling demand for autonomous tractor platforms equipped with advanced telematics capabilities.
The high purchase cost of autonomous tractors is restraining growth in the autonomous tractor market, as many farmers and agricultural enterprises find the initial capital investment significantly higher than that of conventional tractor purchases. Autonomous tractors integrate advanced sensors, GPS/GNSS navigation systems, machine vision cameras, LiDAR or radar technologies, telematics platforms, onboard computing hardware, connectivity modules, and autonomous control software, all of which substantially increase equipment pricing. Small and medium-sized farms often operate on limited capital budgets and prioritize investments that provide immediate production capacity over long-term automation capabilities. Agricultural operators frequently postpone purchases of autonomous equipment until existing machinery reaches the end of its operational life or until larger expansion projects justify new investment.
The growing adoption of electric autonomous tractors is creating substantial opportunities in the autonomous tractors market by expanding demand for machinery that combines automation with low-emission power systems. Agricultural producers increasingly seek equipment capable of performing field operations with minimal operator intervention while reducing fuel dependency, engine maintenance requirements, and operational complexity. Electric autonomous tractors provide a platform that aligns with long-term farm electrification strategies and precision agriculture technologies, allowing manufacturers to develop fully integrated intelligent farming systems. Equipment providers can introduce modular electric tractor platforms that support autonomous navigation, remote fleet management, automated charging coordination, and software-based performance optimization across multiple agricultural applications. The ongoing transition toward electric, autonomous field equipment is creating opportunities for new product development and advanced agricultural machinery ecosystems.
Analyst Perspective
The autonomous tractors market is evolving from an advanced machinery segment into a foundational automation platform for future farming operations. Unlike conventional tractors, autonomous systems create value by reducing labor dependency, extending operating hours, improving operational consistency, and enabling coordinated fleet management across large agricultural fields. Competitive differentiation is increasingly determined by the reliability of autonomous navigation, obstacle detection, remote supervision capabilities, and integration with broader precision farming ecosystems rather than horsepower alone. As regulatory frameworks mature and farmers gain confidence in autonomous field operations, tractors are expected to become increasingly software-defined agricultural assets that support continuous, data-driven, and highly automated farm management.
Power Output Insights
Based on power output, the 41 to 100 hp segment led the market with the largest revenue share of 37.4% in 2025. Autonomous tractors in the 41 to 100 hp range have gained prominence in the agriculture sector primarily due to their practicality and cost-effectiveness. These tractors offer a versatile solution for a variety of tasks essential to dairy operations, such as feeding, manure management, and field maintenance, such as planting and spraying. Their medium-sized horsepower makes them suitable for navigating the terrain typically found on dairy farms, including smaller fields and pasture lands. This adaptability allows farmers to efficiently manage their operations throughout the year without the need for multiple specialized machines.
The less than 40 hp segment registered the highest CAGR of 16.0% over the forecast period. Their compact size, technological advancements, and suitability for diverse farm sizes and tasks contribute to their growing popularity and market growth over the forecast period. Smaller autonomous tractors are increasingly favored for their agility and maneuverability in smaller fields and confined spaces, which are common in diverse agricultural settings. Their compact size allows them to navigate more efficiently through narrow rows and tighter spaces compared to larger machinery.
Automation Insights
Based on automation, the partially- autonomous output segment led the market with the largest revenue share of 61.3% in 2025. Partially autonomous tractors have gained broader acceptance among users, such as farmers and agricultural businesses, due to their perceived reliability and familiarity. Users might find comfort in the ability to intervene when necessary, maintaining control over operations. In addition, partial autonomy represents a more cost-effective option for buyers compared to fully autonomous systems. These tractors may offer significant operational benefits at a lower initial investment or ongoing maintenance cost, aligning better with budget constraints.
The fully autonomous segment is anticipated to register the highest CAGR of 15.9% over the forecast period in the target market. Advances in technology, such as improvements in artificial intelligence, sensor technology, and connectivity, are likely driving the growth of fully autonomous tractors. These innovations enable tractors to perform complex tasks autonomously, reducing the need for human intervention. Fully autonomous tractors leverage AI algorithms and machine learning models to interpret data from various sensors (such as cameras, LiDAR, and radar) and make real-time decisions. These technologies enable tractors to perceive their environment, identify obstacles, and adjust their actions accordingly without human intervention.
Application Insights
Based on the application, the autonomous tractors market is segmented into tillage, harvesting, planting & seeding, and others. The harvesting segment led the market with the largest revenue share of 36.4% in 2025. Harvesting is a critical phase in agriculture that occurs within a relatively short window of time. During this period, there is typically high demand for efficient and timely harvesting to maximize crop yield and quality. Autonomous tractors equipped for harvesting tasks can operate continuously, if needed, without fatigue or human limitations, ensuring that harvesting operations are completed within optimal timeframes.
The planting & seeding segment registered the highest CAGR of 16.9% over the forecast period. There is a growing trend towards precision agriculture practices, where farmers aim to optimize inputs such as seeds, fertilizers, and pesticides based on specific field conditions. Autonomous planting and seeding equipment can precisely control and adjust these inputs according to real-time data and analytics, thereby improving crop yield, quality, and resource utilization. This capability has driven increased adoption of autonomous solutions in the planting & seeding segment.
Farming Type Insights
Based on farming type, the field farming segment led the market with the largest revenue share of 48.7% in 2025. Field farming encompasses a wide range of agricultural activities such as plowing, tillage, cultivation, and general field maintenance. These tasks are fundamental to crop production and cover large areas of agricultural land, making them crucial targets for automation to enhance efficiency and productivity. In additionn, autonomous tractors bring substantial improvements in operational efficiency to field farming tasks. They can operate continuously for extended periods without fatigue, maintaining consistent speeds and precision in tasks such as seedbed preparation, weed control, and soil management. This consistency and efficiency translate into time savings and better utilization of resources for farmers.
 To learn more about this report, Download Free Sample Report
The others segments, including forestry and controlled environment farms, registered the highest CAGR of 14.8% over the forecast period. Forestry and controlled environment farms have unique operational requirements that benefit significantly from autonomous technology. In forestry, autonomous tractors are used for tasks such as tree planting, thinning, and harvesting, where precision and environmental considerations are crucial. Controlled environment farms, including greenhouse and indoor vertical farming operations, utilize autonomous tractors for tasks such as seedling management, crop maintenance, and harvesting in controlled environments. Moreover, autonomous tractors offer enhanced efficiency and precision in forestry and controlled environment farming operations. In forestry, for example, autonomous systems can navigate rugged terrain and perform tasks with minimal environmental impact, improving productivity and sustainability. In controlled environment farms, autonomous tractors can operate in confined spaces with precision, optimizing resource use and maximizing crop yields.
Regional Insights
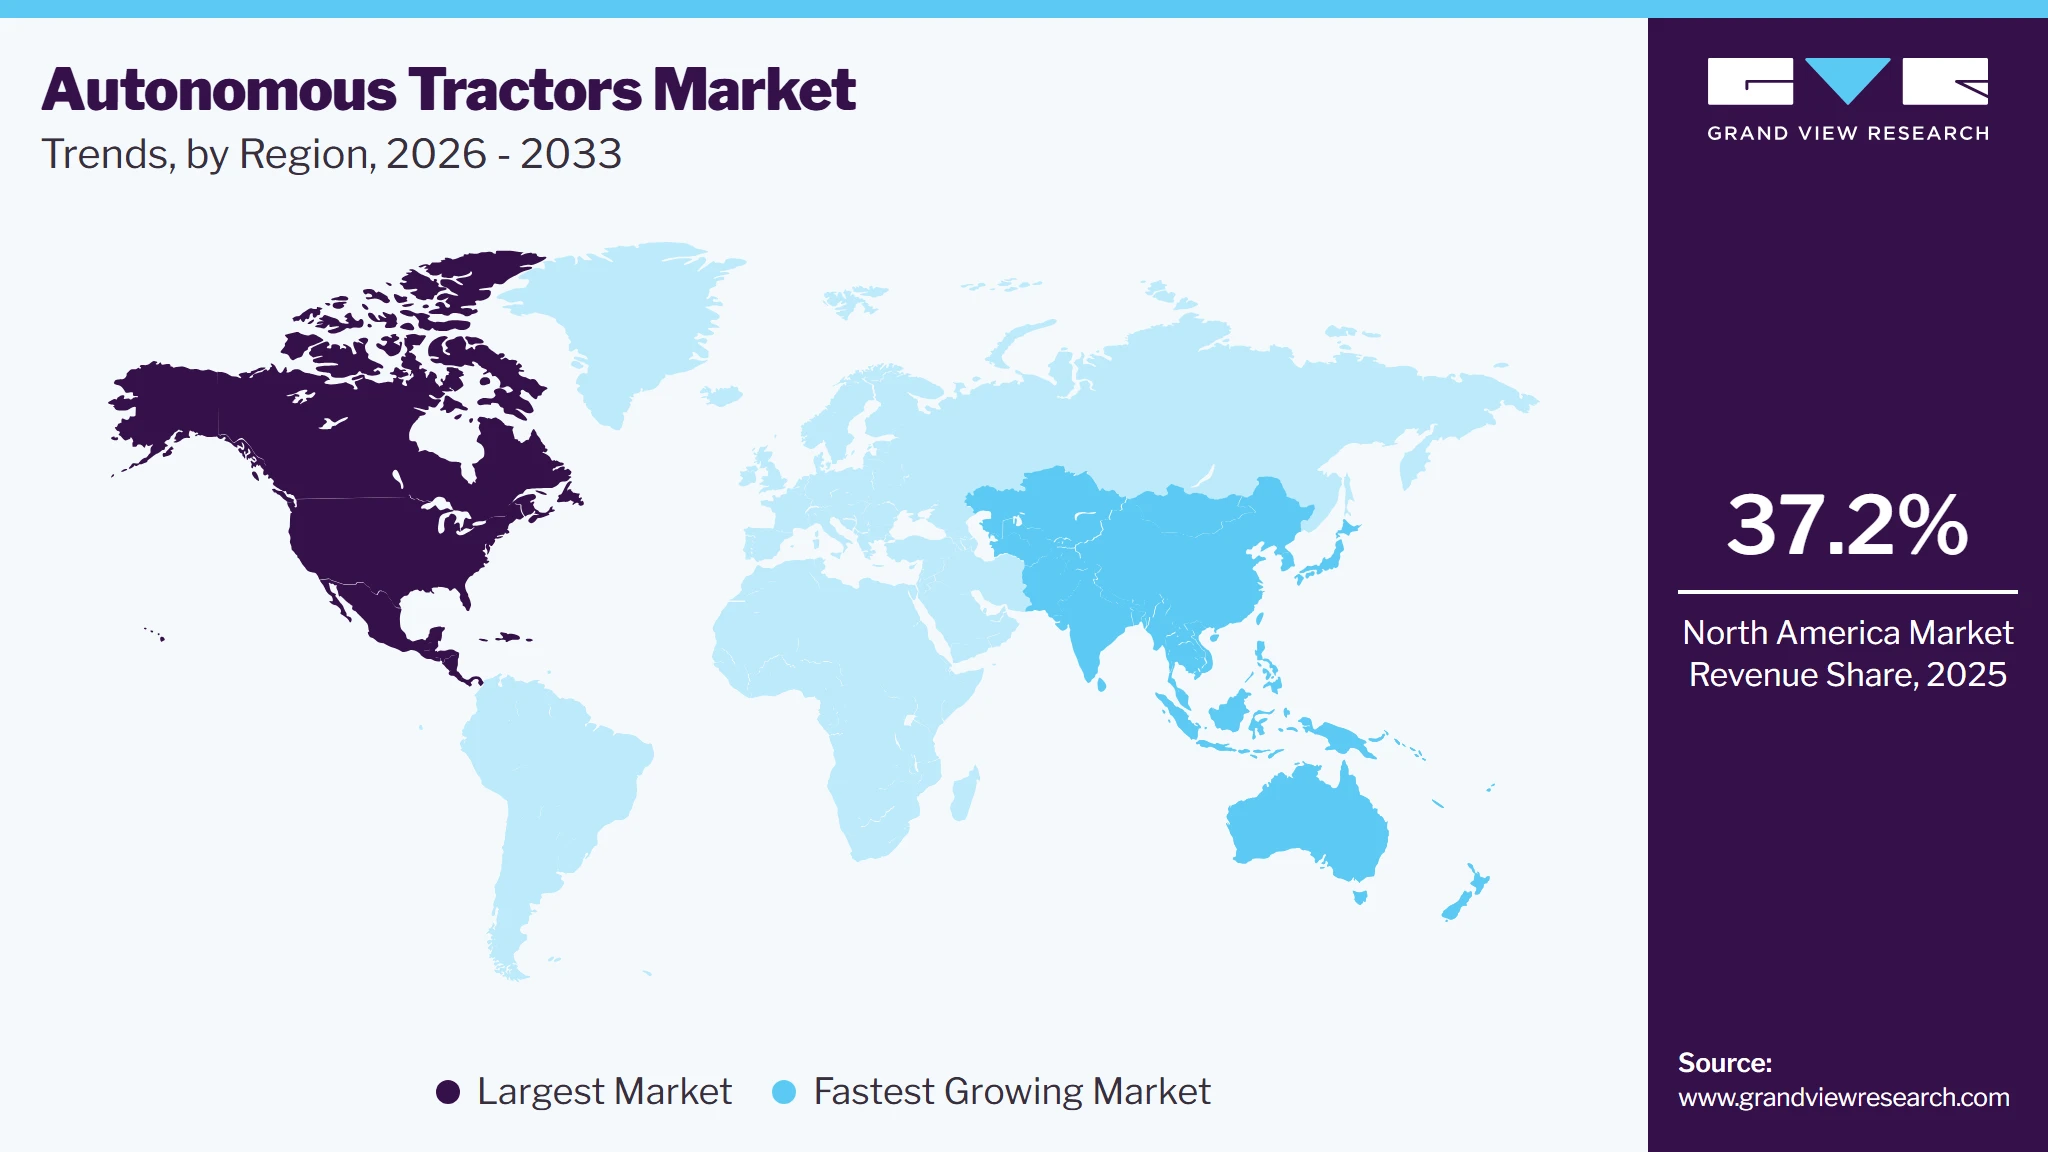
North America dominated the global autonomous tractors market with the largest revenue share of 37.2% in 2025 and is expected to continue its dominance over the forecast period. North America has been an early adopter and leader in the development and deployment of precision agriculture technologies, including autonomous tractors. This early adoption has created a mature ecosystem of technology providers, service providers, and supportive industries that contribute to the growth and dominance of the autonomous tractors market in the region. In addition, the agricultural landscape in North America is characterized by extensive, large-scale farms that benefit significantly from the adoption of autonomous tractors. These farms cover vast areas of land, making efficiency and labor optimization crucial factors in farm management. Autonomous tractors enable farmers in North America to operate more efficiently, cover larger areas of land, and reduce the dependency on manual labor, which is increasingly scarce and costly.
 To learn more about this report, Download Free Sample Report
U.S. Autonomous Tractors Market Trends
The autonomous tractors market in the U.S. held the largest share in the North America region in 2025. The U.S. is home to some of the world's leading agricultural machinery manufacturers and technology companies. These companies have been at the forefront of developing and advancing autonomous tractor technologies. Investments in research and development (R&D) have led to the creation of sophisticated autonomous systems that can navigate fields, perform precise operations, and integrate with farm management software. This technological prowess has given companies in the U.S. a competitive edge in the global autonomous tractors market.
Asia Pacific Autonomous Tractors Market Trends
The autonomous tractors industry in the Asia Pacific is anticipated to grow at the fastest CAGR from 2026 to 2033. The Asia-Pacific region is experiencing a rising demand for autonomous tractors in agriculture, driven by several key factors that are shaping the agricultural landscape and technological adoption in the region. Many countries in the Asia Pacific, including China, Japan, Australia, and India, are witnessing a rapid transition towards mechanized farming practices. This shift is driven by the need to improve productivity, reduce labor dependency, and address challenges related to an aging agricultural workforce. Autonomous tractors represent a significant advancement in farm mechanization by offering capabilities to operate autonomously, thereby enhancing efficiency and scalability in agricultural operations.
Europe Autonomous Tractors Market Trends
Europe has a well-established regulatory framework that supports innovation and technology adoption in agriculture. Regulations related to agricultural machinery safety, emissions standards, and data privacy are well-defined, providing clarity and assurance to farmers and manufacturers investing in autonomous tractors. Regulatory support and incentives from national governments and the European Union encourage the adoption of autonomous technologies as part of efforts to modernize agriculture and achieve sustainability goals. In addition, European countries have ambitious environmental sustainability goals, including reducing greenhouse gas emissions, improving soil health, and promoting biodiversity in agriculture. Autonomous tractors contribute to these goals by enabling precision farming practices that minimize the use of agrochemicals, optimize water and energy efficiency, and promote sustainable land management practices. This alignment with sustainability objectives reinforces the demand for autonomous tractors among European farmers and policymakers.
Key Autonomous Tractors Company Insights
Some of the key companies operating in the autonomous tractors market include Deere & Company, AGCO Corporation, among others.
-
Deere & Company is one of the leading U.S.-based companies that specializes in manufacturing agricultural machinery, drivetrains, heavy equipment, diesel engines, forestry machinery, and lawn care equipment. The company operates through four business segments, namely, production & precision farming, small agriculture & turf, construction & forestry, and financial services. The production & precision farming segment focuses on developing and manufacturing advanced agricultural machinery, including tractors, combines, harvesters, tillage equipment, soil preparation, seeding, crop care, and more with precision technologies. This segment integrates GPS, telematics, and data analytics to optimize farming operations such as planting, seeding, spraying, and harvesting. The company serves its customers in over 100 countries with administrative and sales offices in Argentina, Australia, Brazil, Canada, China, France, Germany, India, Italy, Mexico, Poland, Singapore, Sweden, South Africa, Spain, Ukraine, the UK, and the U.S.
Monarch Tractor and YANMAR HOLDINGS CO., LTD. are some of the emerging market companies in the target market.
-
Monarch Tractor is a company that specializes in manufacturing electric autonomous tractors designed for sustainable agriculture. These tractors are equipped with advanced technologies such as AI, machine learning, and sensor fusion to enhance precision farming practices. Monarch Tractor aims to reduce the environmental impact of agriculture by offering zero-emission, quiet operation alternatives to traditional diesel-powered tractors. It targets both small and large-scale farms, focusing on innovation and sustainability in the agricultural machinery sector. The company has secured licensing agreements with tractor manufacturer Case New Holland and others to expand its technology to various regions and crops.
Key Autonomous Tractors Companies
The following key companies have been profiled for this study on the autonomous tractors market.
-
John Deere (Deere & Company)
-
CNH Industrial
-
AGCO Corporation
-
Kubota Corporation
-
Claas KGaA mbH
-
Yanmar Co., Ltd.
-
Mahindra & Mahindra
-
SDF Group
-
TYM Corporation
-
Monarch Tractor
Competitive Benchmarking
Category
Operating Strategies
Competitive Edge
Weakness
Established Players (John Deere; CNH Industrial; AGCO Corporation; Kubota Corporation; Yanmar Holdings)
Established players focus on integrating autonomous capabilities into existing tractor platforms through GPS guidance, AI-based navigation, telematics, and precision farming software. They also expand partnerships with technology providers and agricultural enterprises to improve large-scale commercial deployment and service support.
These companies benefit from extensive manufacturing capacity, strong dealer networks, and long-standing relationships with commercial farming customers. Their ability to combine autonomous technologies with existing machinery ecosystems supports reliable deployment across diverse agricultural operations.
High development costs and complex integration requirements can increase product pricing and deployment timelines. Regulatory approvals, safety validation, and varying field conditions may also slow broader market adoption.
Emerging Players (Monarch Tractor; AutoNxt Automation; Solectrac; Cellestial E-Mobility; Sabanto)
Emerging players focus on electric autonomous tractors, retrofit automation systems, and software-driven autonomous farming platforms designed for precision agriculture and sustainable farming. They emphasize flexible deployment models, cloud connectivity, and rapid product innovation to address labor shortages and operational efficiency challenges.
These companies offer specialized automation technologies, faster innovation cycles, and strong capabilities in electric propulsion and digital farm connectivity. Their focused solutions can provide greater flexibility for targeted agricultural applications and emerging sustainable farming initiatives.
Limited manufacturing scale and smaller service networks can restrict commercial expansion. Building customer confidence and expanding infrastructure for autonomous and electric farming technologies remain significant growth challenges.
Recent Developments
-
In February 2024, Deere & Company introduced its latest range of four-track tractors with high hp, which includes a top model boasting 830 horsepower. The 2025 lineup features new models, including the 9RX 710, the 9RX 770, and the 9RX 830, equipped with upgraded engines, hydraulic systems, and technology packages, along with updated cabs. To support farmers in preparing their equipment and farms for autonomous operations, the MY25 8 Series and 9 Series tractors will offer an autonomous-ready option. This feature enables farmers to transition to fully autonomous operation seamlessly, aligning with their farm's specific readiness.
-
In October 2023, Monarch Tractor expanded its operations into Europe, marking a significant milestone in its global growth strategy. This move signifies Monarch Tractor's commitment to global growth and its confidence in meeting farmers' evolving needs for sustainable and efficient agricultural solutions. It positions Monarch Tractor as an emerging player in the European agricultural technology sector and sets the stage for further expansion and innovation in the future.
Autonomous Tractors Market Report Scope
Report Attribute
Details
Market size in 2025
USD 2.4 billion
Estimated market size in 2026
USD 2.8 billion
Projected market size by 2033
USD 9.0 billion
Growth rate
CAGR of 18.4% from 2026 to 2033
Base year for estimation
2025
Historical data
2021 - 2024
Forecast period
2026 - 2033
Quantitative units
Revenue in USD million/billion and CAGR from 2026 to 2033
Report coverage
Revenue forecast, company market share analysis, competitive landscape, growth factors, and trends
Segments covered
Power output, automation, application, farming type, region
Regional scope
North America; Europe; Asia Pacific; Latin America; MEA
Country scope
U.S.; Canada; Mexico; Germany; UK; France; China; Japan; India; South Korea; Australia; Brazil; Saudi Arabia; South Africa; UAE
Key companies profiled
Deere & Company; CNH Industrial; AGCO Corporation; Kubota Corporation; Claas KGaA mbH; Yanmar Co., Ltd.; Mahindra & Mahindra; SDF Group; TYM Corporation; Monarch Tractor
Customization scope
Free report customization (equivalent up to 8 analysts' working days) with purchase. Addition or alteration to country, regional & segment scope.
Pricing and purchase options
Avail customized purchase options to meet your exact research needs. Explore purchase options
Global Autonomous Tractors Market Report Segmentation
This report forecasts revenue growth at global, regional, and country levels and provides an analysis of the latest industry trends in each of the sub-segments from 2021 to 2033. For this study, Grand View Research has segmented the global autonomous tractors market report based on power output, automation, application, farming type, and region:
-
Power Output Outlook (Revenue, USD Million, 2021 - 2033)
-
Less than 40 HP
-
41 to 100 HP
-
More than 100 HP
-
-
Automation Outlook (Revenue, USD Million, 2021 - 2033)
-
Partially Autonomous
-
Fully Autonomous
-
-
Application Outlook (Revenue, USD Million, 2021 - 2033)
-
Tillage
-
Harvesting
-
Planting & Seeding
-
Others
-
-
Farming Type Outlook (Revenue, USD Million, 2021 - 2033)
-
Field Farming
-
Horticulture
-
Dairy Farming & Livestock Management
-
Others
-
-
Regional Outlook (Revenue, USD Million, 2021 - 2033)
-
North America
-
U.S.
-
Canada
-
Mexico
-
-
Europe
-
UK
-
Germany
-
France
-
-
Asia Pacific
-
China
-
Japan
-
India
-
South Korea
-
Australia
-
-
Latin America
-
Brazil
-
-
Middle East and Africa (MEA)
-
KSA
-
UAE
-
South Africa
-
-
Research Methodology
The autonomous tractors Market figures in this report are based on a proven research process that combines executive interviews with secondary research from proprietary databases, company filings, and recognized regulatory and institutional sources. Market size is built through value-chain sizing - reconciling supply-side and demand-side estimates - and triangulated with bottom-up and top-down approaches. Every estimate passes multiple levels of expert validation before publication, with each Autonomous Tractors Market segment quantified using the revenue-capture definitions in the table below.
Segment Definition
Segment - Power Output
Revenue capture definition
Less than 40 HP
Market value is driven by autonomous compact tractors designed for orchards, vineyards, greenhouses, specialty crops, and small-scale farming operations where maneuverability is essential. Manufacturers benefit from growing demand for labor-saving automation among high-value crop producers and precision horticulture applications.
41 to 100 HP
The largest power segment, capturing investment in versatile autonomous tractors capable of performing tillage, planting, spraying, hauling, and general farm operations across medium and large farms. Buyers increasingly prioritize autonomous functionality in this range because it delivers a strong balance between operational flexibility, productivity gains, and capital efficiency.
More than 100 HP
Commercial opportunities are concentrated in large-scale row-crop farming, plantation agriculture, and commercial farming enterprises requiring high-horsepower autonomous equipment for intensive field operations. Premium pricing is supported by advanced GPS guidance, AI-based navigation, implemented automation, fleet coordination, and the ability to operate continuously with minimal human supervision.
Segment - Automation
Revenue capture definition
Partially- Autonomous
The dominant automation segment is generating value through tractors equipped with autonomous steering, guidance systems, automated implement control, obstacle detection, and operator-assistance technologies. Farmers adopt these systems to reduce labor requirements and improve field accuracy while maintaining human oversight for critical operational decisions.
Fully Autonomous
The fastest-growing segment is driven by tractors capable of performing agricultural operations without onboard operators using AI, machine vision, GPS/GNSS, LiDAR, and remote fleet management technologies. Investment is accelerating as commercial farms seek continuous operation, labor optimization, and highly precise autonomous field execution.
Segment - Application
Revenue capture definition
Tillage
The largest application segment, capturing demand for autonomous tractors performing plowing, cultivation, harrowing, and seedbed preparation with high positional accuracy and optimized field coverage. Autonomous tillage reduces operator fatigue, improves fuel efficiency, and enables longer operating hours during critical land preparation periods.
Harvesting
Commercial demand is supported by autonomous tractor deployment for hauling, grain cart operations, harvesting support logistics, and coordination with harvesting equipment. Farmers invest in automation to improve harvest efficiency, reduce labor bottlenecks, and optimize machinery utilization during narrow harvest windows.
Planting & Seeding
Market value is created through autonomous planting operations that enable precise seed placement, spacing control, variable-rate seeding, and optimized field navigation. Advanced automation improves the consistency of crop establishment while reducing seed waste and input variability across large agricultural fields.
Others
This category includes spraying, fertilizer application, mowing, transport, irrigation support, orchard operations, and specialized agricultural tasks. Expanding precision agriculture and robotic farming initiatives continue to create new opportunities for autonomous tractor deployment beyond traditional field operations.
Segment - Farming Type
Revenue capture definition
Field Farming
The largest end-use segment is driven by extensive row-crop and grain farming operations that require autonomous tractors for large-area tillage, planting, spraying, and transport. Commercial adoption is strongest among farms seeking higher productivity, reduced labor dependence, and optimized machinery utilization across extensive acreage.
Horticulture
Market activity centers on autonomous tractors designed for orchards, vineyards, fruit farms, vegetable production, and other specialty-crop environments that require precise navigation and compact maneuverability. Growers invest in autonomous solutions to improve efficiency in labor-intensive horticultural operations while minimizing crop damage.
Dairy Farming and Livestock
Management
Value is generated through autonomous tractors used for feed transportation, manure handling, forage operations, mowing, and other repetitive farm tasks within dairy and livestock operations. Automation helps livestock producers reduce labor costs and maintain consistent operational routines throughout the production cycle.
Others
This segment includes plantation agriculture, forestry operations, greenhouse farming, municipal agriculture, agricultural research, and mixed farming systems. Growing investment in agricultural automation and robotics continues to expand autonomous tractor adoption across diverse farming environments.
Estimation Model
Layer
Question
Analysis
Autonomous Field Operations Layer
Which agricultural tasks can autonomous tractors perform independently?
Identify field operations that can be executed with minimal or no human intervention, including plowing, tillage, planting, seeding, spraying, fertilizing, mowing, and hauling. This layer defines market demand based on the ability of autonomous tractors to operate continuously, improve precision, and address labor shortages across row crops, specialty crops, orchards, and large-scale commercial farming operations.
Autonomy Enablement Layer
What technologies allow tractors to operate autonomously?
Assess the integration of GPS guidance, RTK positioning, machine vision, LiDAR, radar, onboard sensors, AI-based navigation, edge computing, and connectivity platforms that enable autonomous decision-making. Successful deployment depends on navigation accuracy, obstacle detection, field mapping capability, equipment interoperability, cybersecurity, and the reliability of autonomous control systems under varying agricultural conditions.
Fleet Coordination Layer
How are autonomous tractors integrated into modern farm machinery ecosystems?
Analyze how autonomous tractors operate alongside implements, harvesters, drones, irrigation systems, farm management software, and telematics platforms. Farmers increasingly utilize coordinated fleets of connected machines for synchronized field operations, remote supervision, route optimization, predictive maintenance, and real-time operational monitoring across large agricultural enterprises.
Autonomy-as-a-Productivity Platform Layer
How is commercial value generated within the autonomous tractor ecosystem?
Evaluate revenue streams from autonomous tractor sales, retrofit autonomy kits, software subscriptions, fleet management platforms, remote monitoring services, AI-driven operational analytics, maintenance contracts, and autonomy upgrades. Additional value is created through lower labor costs, higher field productivity, reduced fuel and input consumption, extended operating hours, and recurring revenues from digital services that support autonomous agricultural operations throughout the equipment lifecycle.
Delivered Customizations
This report has been delivered with the following In-depth customizations
Client Request
Customization Delivered
Value Adds
Autonomous Field Operations & Driverless Farming Trends
Conducted a focused analysis of autonomous tractor deployment across row crop farming, grain production, and large-scale commercial agriculture, covering driverless field operations, autonomous plowing, seeding, spraying, and harvesting support activities.
Helps stakeholders identify high-value autonomous farming applications, evaluate driverless machinery adoption trends, and assess commercialization opportunities in next-generation farm automation.
Fleet Coordination, Autonomous Navigation & Remote Farm Management Trends
Evaluated adoption trends for GPS and RTK-guided tractors, machine-to-machine coordination, remote operation centers, obstacle detection systems, and autonomous implement control across precision agriculture environments.
Provides insights into operational efficiency improvements, labor optimization opportunities, and commercially attractive autonomous fleet management capabilities that enhance field productivity.
AI-Enabled Farm Automation Ecosystem & Autonomous Mobility Opportunity Assessment
Assessed demand for AI-based decision engines, sensor fusion technologies, autonomous mission planning software, cloud-connected tractor platforms, and predictive maintenance systems, along with challenges related to rural connectivity, regulatory frameworks, safety validation, and equipment interoperability.
Supports investment and expansion strategies by identifying emerging autonomous farming opportunities, evaluating technology readiness, and strengthening long-term growth potential in intelligent and fully automated agricultural machinery ecosystems.
Frequently Asked Questions About This Report
The global autonomous tractors market size was valued at USD 2.4 billion in 2025 and is estimated at USD 2.8 billion for 2026.
The global autonomous tractors market is expected to grow at a CAGR of 18.4% from 2026 to 2033, reaching USD 9.0 billion by 2033.
Partially- autonomous segment dominated the market, with a revenue share of 61.3% in 2025 while fully autonomous segment is expected to be the fastest-growing market.
Some of the prominent players in the autonomous tractors market are Deere & Company, CNH Industrial, AGCO Corporation, Kubota Corporation, Claas KGaA mbH, Yanmar Co., Ltd., Mahindra & Mahindra, SDF Group, TYM Corporation, Monarch Tractor.
The agricultural autonomous tractors market is primarily driven by increasing demand for sustainable and efficient farming practices, as well as the need to address labor shortages in agriculture. Additionally, technological advancements in areas like GPS, computer vision, and artificial intelligence are enabling more capable autonomous tractors that can boost farm productivity and profits while reducing costs.
The harvesting segment led the market with the largest revenue share of 36.4% in 2025. Harvesting is a critical phase in agriculture that occurs within a relatively short window of time.
41 to 100 hp segment dominated the market, with a revenue share of 37.4% in 2025.
North America dominated with a 37.2% revenue share in 2025.
Asia Pacific is the fastest-growing region over the forecast period.
About the Author(s)
Automotive & Transportation Research Team
Technology · Automotive & TransportationThis report was authored by the automotive & transportation research team at Grand View Research - comprising two research analysts, one senior research analyst, and one industry expert - with specialized expertise in the automotive & transportation segment of the technology industry. All findings are based on proprietary technology databases, executive interviews, and regulatory analysis, subject to internal peer review prior to publication.
Last Updated:
Speak to Analyst

Customize this report to your needs - add regions, segments, or data points, with 20% free customization.
Or view our licence options:


ISO 9001:2015 & 27001:2022 Certified
We are GDPR and CCPA compliant! Your transaction & personal information is safe and secure. For more details, please read our privacy policy.


