
- Home
- »
- Beauty & Personal Care
- »
-
Baby Toiletries Market Size And Share Report, 2026-2033GVR Report cover

Baby Toiletries Market (2026 - 2033)
Size, Share & Trends Analysis Report By Product (Skin Care Products, Diapers, Hair Care Products, Wipes, Bathing Products ), By Distribution Channel (Hypermarkets, Chemist And Pharmacy Stores, E-commerce ), By Region, And Segment Forecasts
Market Size, 2025
$119.8BMarket Estimate, 2026
$126.7BMarket Forecast, 2033
$191.8BCAGR, 2026–2033
6.1%Baby Toiletries Market Summary
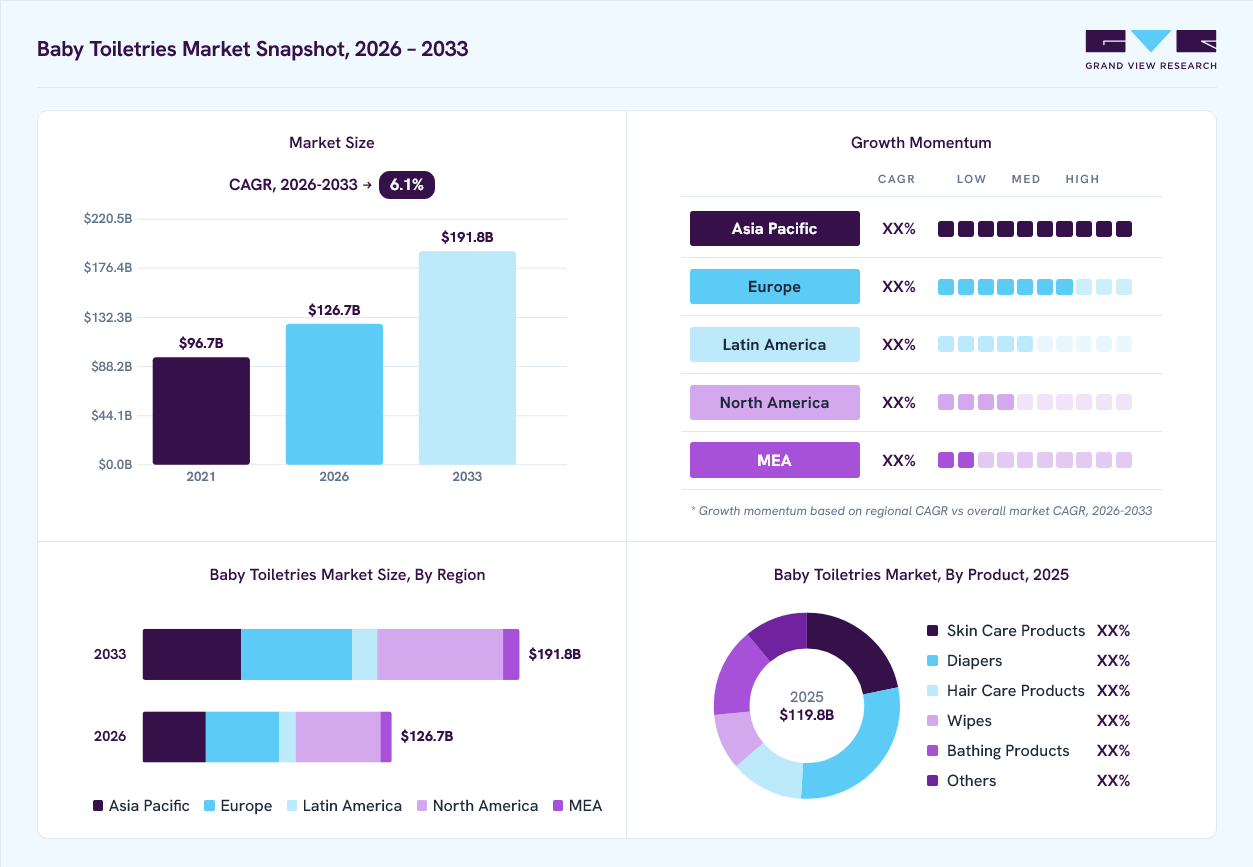
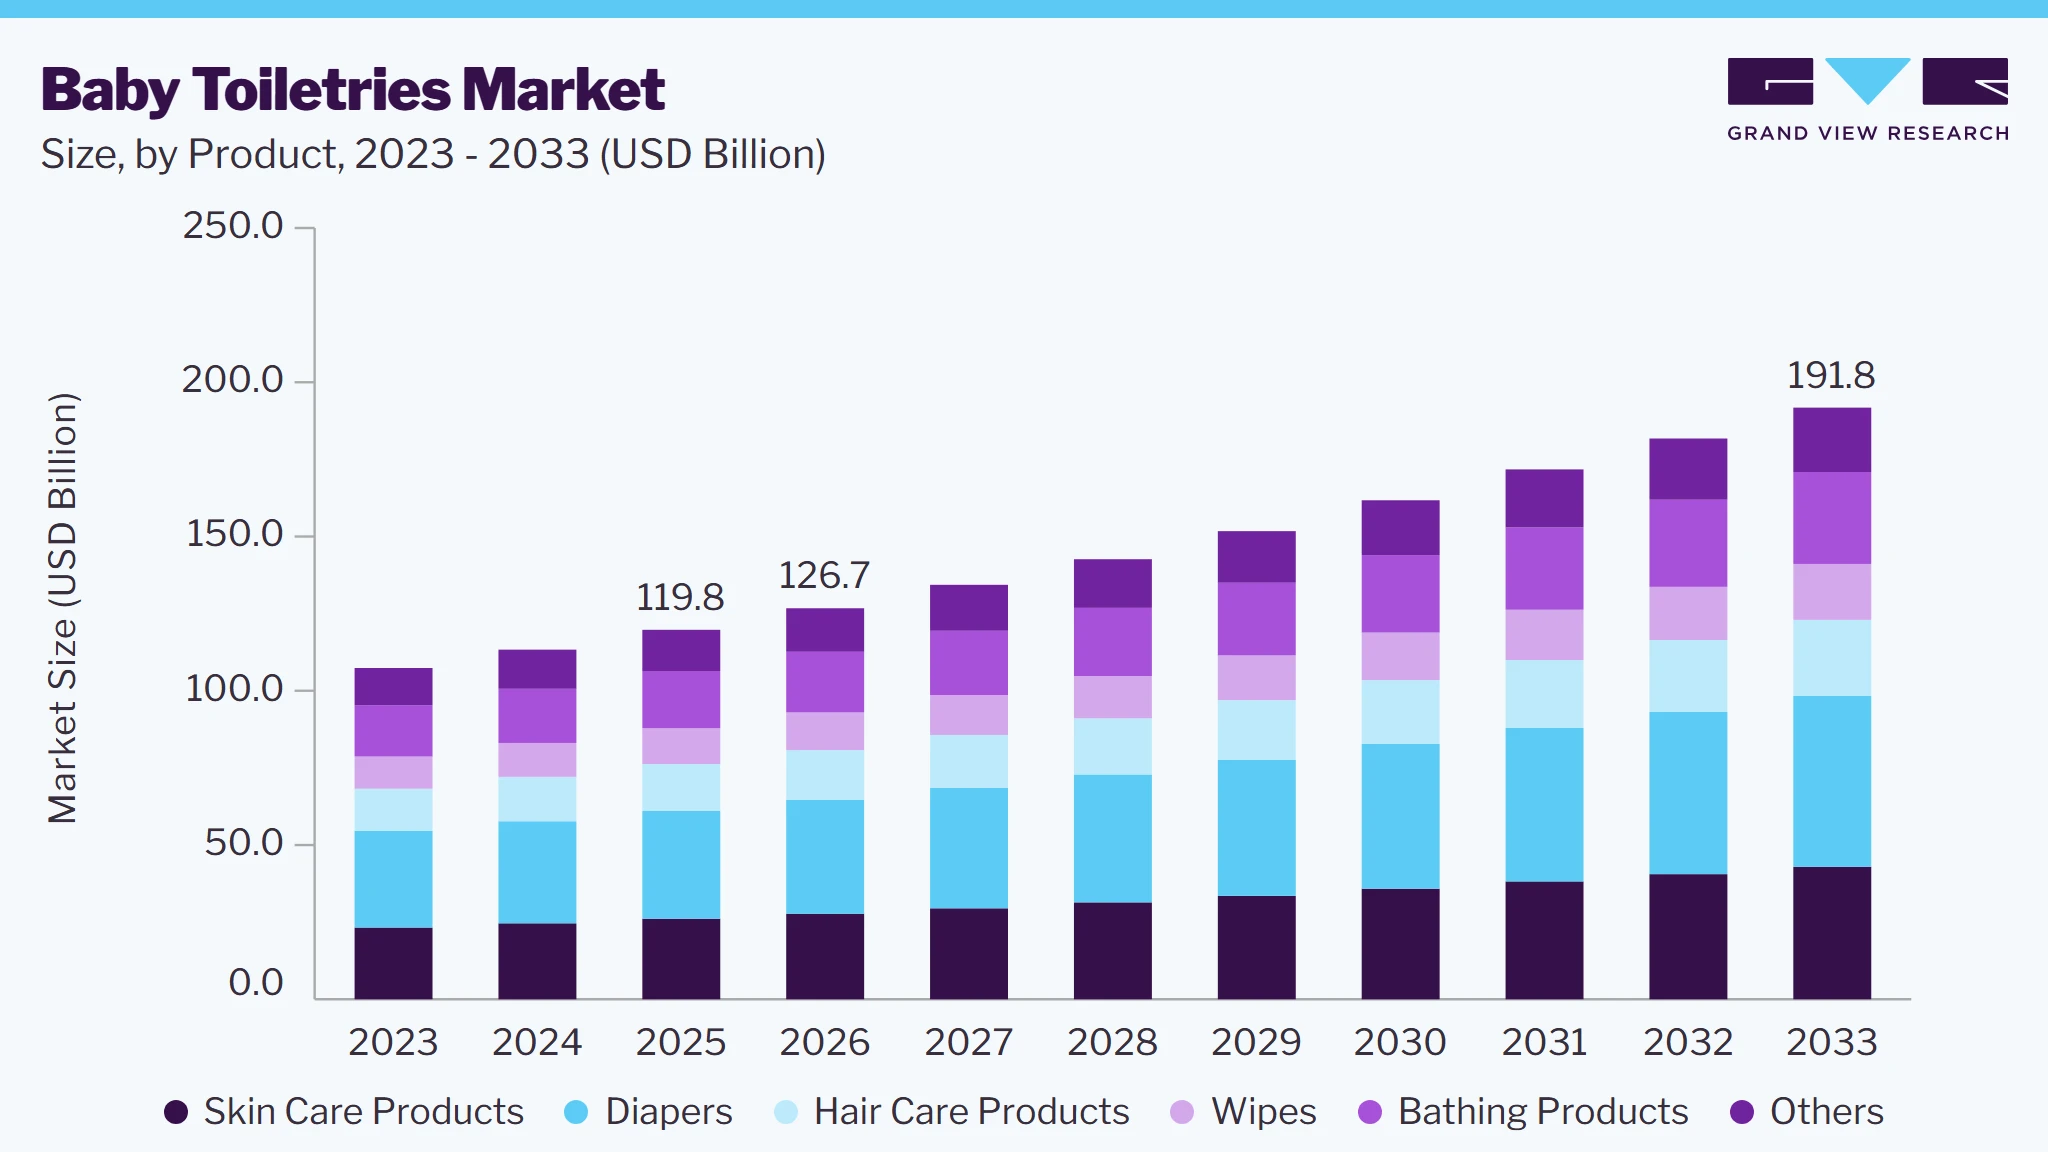
The global baby toiletries market size was valued at USD 119.8 billion in 2025 and is projected to grow from USD 126.7 billion in 2026 to USD 191.8 billion by 2033, at a CAGR of 6.1% from 2026 to 2033. North America dominated the market, accounting for a revenue share of 34.1% in 2025. The baby toiletries industry is witnessing remarkable growth, driven by rising awareness among parents about the importance of hygiene and health for their children.
 Source: Grand View Research, IR Documents, Primary Interviews, Paid DatabasesTo learn more about this report,
 Download Free Sample Report
Key Market Trends & Insights
- By product: Diaper segment dominated the market, with a revenue share of 29.2% in 2025.
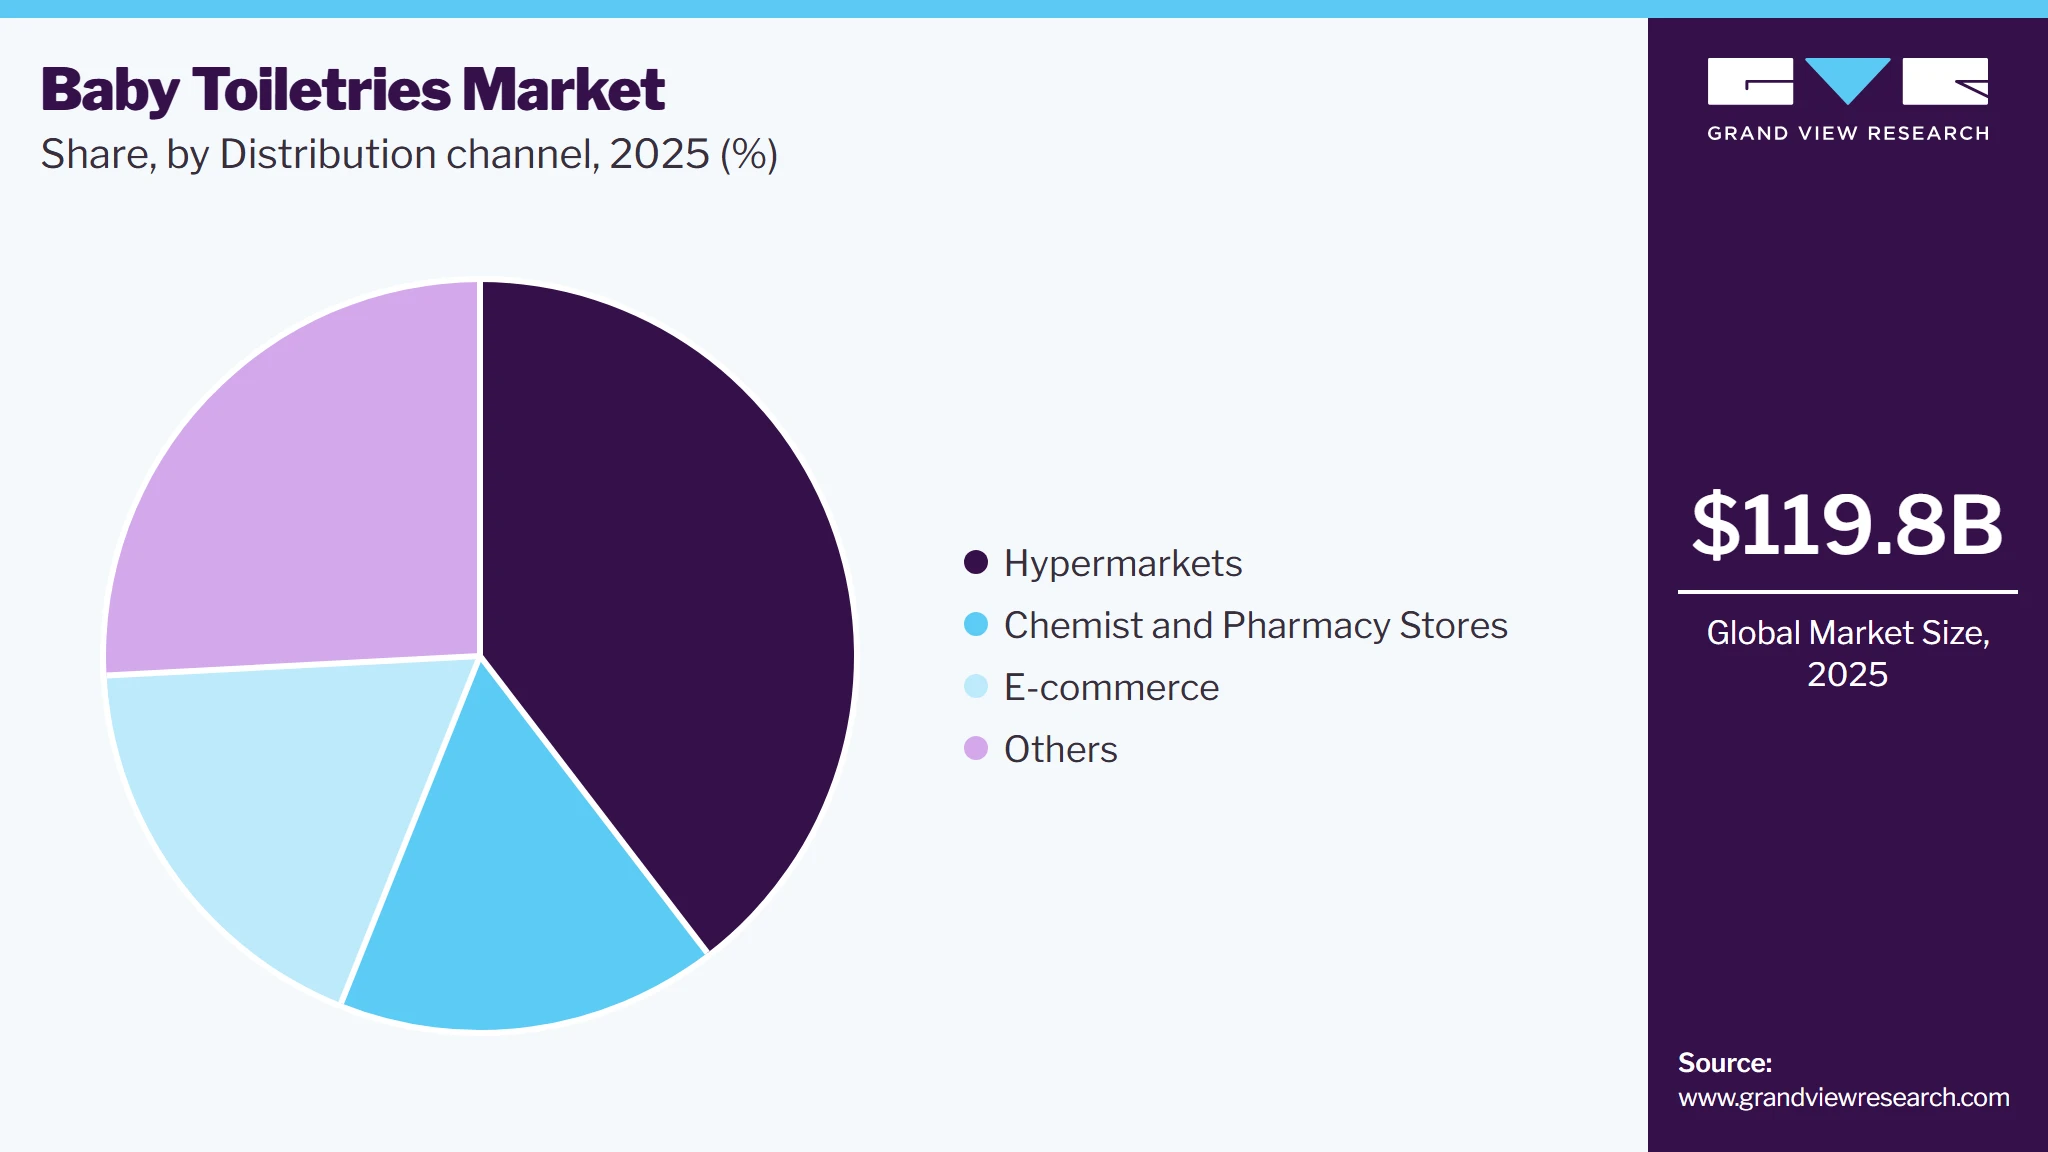
- By distribution channel: Hypermarkets segment held the largest market share of 39.6% in 2025.
Regional Highlights
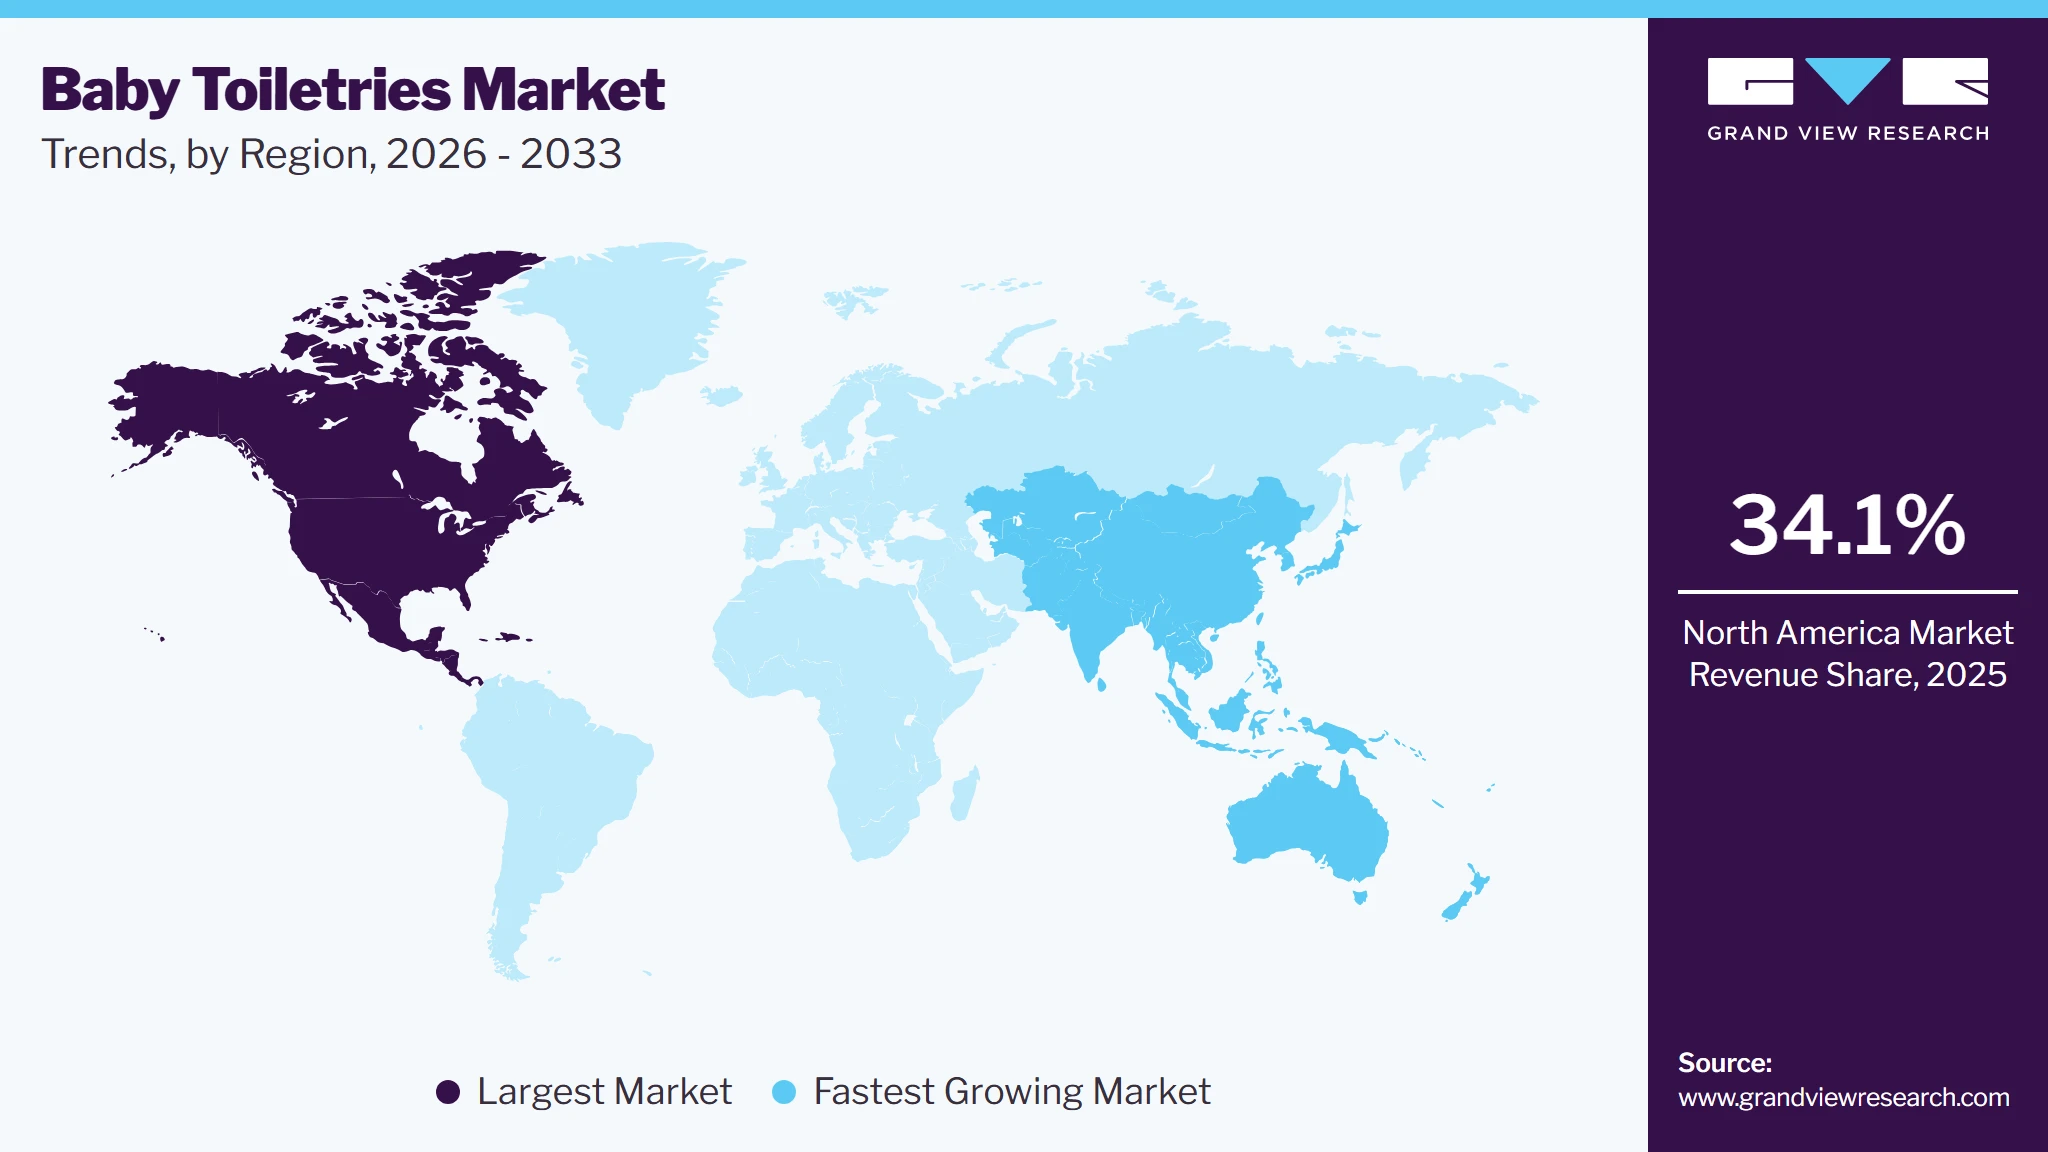
- Largest regional market: North America (34.1% revenue share, 2025)
- Fastest-growing regional market: Asia Pacific (highest CAGR, 2026-2033)
- By country: The U.S. held the largest market share in 2025.
Market Size & Forecast
- Market size in 2025: USD 119.8 Billion
- Estimated market size in 2026: USD 126.7 Billion
- Projected market size by 2033: USD 191.8 Billion
- CAGR (2026-2033): 6.1%
Three ways to get this report
Buy it, customize it, or ask a question.Ask an Analyst
Analyst response in 1 business day
- AccessReport author, directly
- Reply timeWithin 1 working day
- No sales callDirect answer only
- FormatEmail reply
- CostFree, no cost
Get the Full Report
What the study covers
- FormatsPDF · Excel · Dashboard
- Timeline2026–2033 annual, 2025 base
- Coverage20+ countries, 5 regions
- Companies10+ key players profiled
Customize the Report
20% free customization
- IncludeCountries, segments, points
- TailorTo your product definition
- ExtendDeeper competitor detail
- OrA fully bespoke study
- Turnaround5–10 working days
Parents are increasingly opting for specialized products that cater to their baby’s delicate and sensitive skin. This trend, combined with growing birth rates in various regions and higher disposable incomes, has expanded the market significantly. As families prioritize high-quality options, the baby toiletries industry continues to benefit from their willingness to invest in superior toiletries.The growing e-commerce sector has also played a crucial role in propelling the baby toiletries industry forward. With online platforms making products more accessible to a wider audience, parents can easily explore and purchase premium products from the comfort of their homes. Social media and celebrity endorsements further amplify this trend, encouraging parents to try high-end baby care items. These factors have collectively contributed to the increasing popularity of premium products within the baby care industry.
 To learn more about this report, Download Free Sample Report
Ongoing product innovation and the introduction of eco-friendly options have attracted environmentally conscious parents, adding momentum to the baby products industry. In December 2024, R for Rabbit, a leading brand in premium baby care products, launched its ‘Feather Diapers’ campaign with a focus on ‘Next-Gen Parenting.’ The innovative diapers featured advanced wetness detection technology and ultra-soft materials, catering to the needs of modern parents.
Similarly, in February 2025, Ontex Group NV launched its Dreamshields technology for baby diapers across Europe, further driving innovation in the market. With features like a unique channel design for enhanced absorption, SeconDRY technology for instant dryness, and sustainable materials, these diapers provide parents with superior comfort and leakage protection for their babies. Such innovations highlight the evolving preferences in the baby products industry, where convenience, sustainability, and advanced functionality are at the forefront of consumer demand.
Market Dynamics
The baby toiletries market is experiencing sustained growth driven by rising birth rates in developing economies, increasing parental awareness regarding infant hygiene and skin health, and growing demand for specialized baby care products. Parents are becoming increasingly cautious about product ingredients and are actively seeking toiletries formulated specifically for infants’ delicate skin. The market is further benefiting from premiumization trends, rising disposable incomes, and expanding availability of baby care products through organized retail and e-commerce channels. Additionally, increasing awareness regarding early childhood health and hygiene practices is encouraging consistent usage of baby shampoos, body washes, lotions, diaper rash creams, oils, and wipes, supporting long-term market expansion.
Growing awareness regarding infant skin sensitivity and the potential impact of harsh chemicals is a key factor driving the baby toiletries market. Babies possess a thinner and more permeable skin barrier compared to adults, making them more susceptible to irritation, dryness, allergies, and dermatological conditions. As a result, parents are increasingly prioritizing products specifically formulated for newborns and infants that contain mild, hypoallergenic, dermatologically tested, and pH-balanced ingredients.
The demand for sulfate-free shampoos, alcohol-free wipes, tear-free cleansers, and fragrance-free skincare products has increased significantly as parents become more informed through healthcare professionals, parenting communities, and digital platforms. Furthermore, rising concerns regarding eczema, diaper dermatitis, and skin allergies among infants are encouraging greater adoption of specialized baby toiletries designed to protect and maintain skin health. This heightened focus on safety and efficacy continues to support premium product adoption and market growth.
The baby toiletries market faces significant challenges due to stringent regulatory standards and increasing scrutiny of product ingredients. Manufacturers are required to comply with rigorous safety, quality, labeling, and testing requirements to ensure suitability for infant use. Regulatory authorities and consumer advocacy groups closely monitor ingredients commonly used in baby care products, including preservatives, fragrances, parabens, phthalates, and certain surfactants.
Product recalls, contamination concerns, or negative publicity surrounding ingredient safety can quickly erode consumer trust and impact brand reputation. Additionally, obtaining certifications related to dermatological testing, hypoallergenic claims, organic ingredients, and safety standards often increases product development costs and extends time-to-market. These regulatory and compliance challenges can create barriers for new entrants and limit innovation speed within the industry.
The increasing preference for clean-label and naturally derived baby care products presents a substantial growth opportunity for the baby toiletries market. Parents are increasingly seeking products formulated with plant-based ingredients, organic extracts, natural oils, and minimal synthetic additives to reduce potential exposure to harsh chemicals during infancy. This trend is particularly strong among millennial and Gen Z parents, who actively evaluate ingredient transparency and sustainability credentials before making purchasing decisions.
In addition, premium baby toiletries featuring organic certifications, environmentally friendly packaging, and sustainably sourced ingredients are gaining traction across both developed and emerging markets. The expansion of e-commerce platforms is further enabling niche and premium brands to reach a broader consumer base while educating parents about product benefits. As consumer preference shifts toward safer, environmentally conscious, and scientifically validated baby care solutions, manufacturers have significant opportunities to develop differentiated offerings that address evolving parental expectations.
Analyst Perspective
The baby toiletries market is witnessing a pronounced shift toward ingredient transparency and pediatrician-endorsed formulations as parents become increasingly cautious about product safety. Demand growth is strongest in premium skin care, wipes, and bathing products formulated without parabens, sulfates, artificial fragrances, and other perceived irritants. Manufacturers are expanding portfolios with plant-based, hypoallergenic, and dermatologically tested products to address concerns around infant skin sensitivity. E-commerce is accelerating product discovery and brand penetration, particularly for niche and premium offerings. In emerging markets, rising disposable incomes and increasing awareness of infant hygiene are expanding category adoption, while established players continue to leverage trust, safety credentials, and specialized product innovation to maintain market leadership.
Consumer Survey & Insights
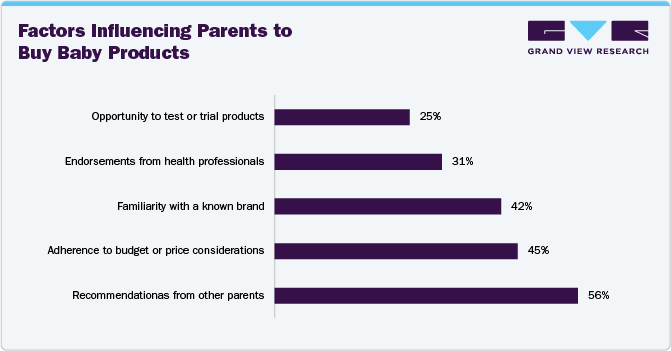
An insights project conducted by ParentsandBrands in 2021 involved an online survey and a panel discussion with 18 parents, resulting in 164 responses related to their purchasing decisions for baby toiletries. Key factors influencing these decisions included recommendations from other parents (56%), adherence to budget or price considerations (45%), familiarity with a known brand (42%), endorsements from health professionals (31%), and the opportunity to test or trial products (25%). This data highlights the significance of social validation and personal experience in the decision-making process.
 To learn more about this report, Download Free Sample Report
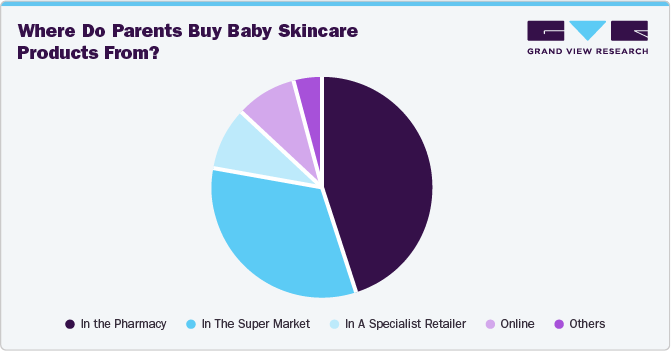
Additionally, according to this insight, 45% of respondents prefer purchasing from a pharmacy, while 33% shop at supermarkets. Additionally, 9% choose specialist retailers, another 9% opt for online shopping, and 4% explore other avenues.
 To learn more about this report, Download Free Sample Report
Product Insights
Based on product, the diaper segment led the market with the largest revenue share of 29.2% in 2025 and is expected to grow at the fastest CAGR over the forecast period, owing to their essential role in maintaining infant skin health and preventing common conditions such as dryness, rashes, irritation, and diaper-related skin issues. Parents are increasingly prioritizing products formulated with mild, hypoallergenic, dermatologically tested, and emical-free ingredients to ensure safety for sensitive baby skin. Growing awareness regarding infant hygiene, rising disposable incomes, and increasing demand for premium and organic baby care products have further strengthened segment growth. In addition, continuous product innovation featuring natural ingredients, fragrance-free formulations, and pediatrician-recommended solutions is driving consumer preference, supporting the segment’s dominant market position and expected rapid growth during the forecast period.
Demand for baby skin care products is expected to grow at a CAGR of 6.5% from 2025 to 2033. Increasing awareness among parents about the importance of maintaining their baby's skin health is a significant driver. Parents are becoming more cautious and selective about the products they use on their baby's delicate skin, favoring gentle care and protection. Additionally, the growing trend towards using natural and organic skin care products propels the demand for such items in the market. The availability of a wide range of specialized skin care products, including lotions, creams, oils, and powders, also contributes to this segment's growth. Furthermore, product formulations and packaging advancements are enhancing the appeal of baby skin care products, making them more attractive to consumers.
Distribution Channel Insights
Based on distribution channel, the hypermarkets segment led the market with the largest revenue share of 39.6% in 2025. Hypermarkets remain the leading distribution channel in the baby toiletries market due to their extensive product assortment, competitive pricing, and ability to offer consumers a convenient one-stop shopping experience. Parents often prefer purchasing baby toiletries from hypermarkets because they can compare multiple brands, product variants, and pricing options in a single location while benefiting from promotional discounts and bulk purchase offers. The strong presence of organized retail chains, particularly in urban and suburban areas, has further contributed to the segment's dominance. Additionally, the availability of trusted international and domestic baby care brands, combined with increasing consumer confidence in organized retail outlets, continues to support the hypermarket segment’s leading share in the global baby toiletries market.
 To learn more about this report, Download Free Sample Report
Sales of baby toiletries through e-commerce are set to grow at a CAGR of 7.6% from 2025 to 2033. The convenience and ease of online shopping are major drivers, allowing parents to purchase baby toiletries from the comfort of their homes. Additionally, e-commerce platforms often offer a wider variety of products compared to physical stores, giving consumers more choices. The ability to easily compare prices and read reviews also plays a crucial role in the growing popularity of e-commerce. Furthermore, the increasing penetration of smartphones and the internet, especially in emerging markets, is expanding the reach of online retail. Many e-commerce platforms also provide attractive discounts and subscription services, making them a cost-effective option for parents.
Regional Insights
North America dominated the baby toiletries market with the largest revenue share of 34.1% in 2025, due to high consumer spending on premium infant care products, strong awareness regarding baby hygiene, and widespread availability of specialized baby care brands. Parents in the region increasingly prioritize products formulated with gentle, hypoallergenic, organic, and dermatologically tested ingredients, driving demand for premium baby shampoos, lotions, wipes, powders, and bath products. The presence of established manufacturers, robust retail distribution networks, and growing preference for natural and chemical-free formulations further support market growth. Additionally, rising focus on infant health and wellness, coupled with increasing adoption of premium baby care routines among millennial and Gen Z parents, continues to strengthen the region’s market leadership.
 To learn more about this report, Download Free Sample Report
U.S. Baby Toiletries Market Trends
The baby toiletries market in the U.S. held the largest share of about 81.0% in the North America region in 2025, supported by high purchasing power, strong brand penetration, and growing demand for premium infant personal care products. Parents are increasingly seeking safe, clinically tested, and environmentally sustainable baby toiletries, leading to higher adoption of organic, plant-based, fragrance-free, and eco-friendly formulations. The expansion of e-commerce platforms and subscription-based baby care services has improved product accessibility and encouraged repeat purchases. Furthermore, growing consumer awareness regarding ingredient transparency, skin sensitivity concerns among infants, and the rising popularity of clean-label baby products continue to drive demand across the U.S. baby toiletries market.
Europe Baby Toiletries Market Trends
The baby toiletries market in Europe accounted for a revenue share of over 29% in 2024. European parents are highly conscious of product ingredients and sustainability, leading to a strong preference for organic and eco-friendly baby toiletries. The increasing trend of dual-income households results in higher disposable incomes, allowing parents to invest in premium baby care products. Additionally, the region's advanced retail infrastructure, including the widespread availability of products in supermarkets, pharmacies, and specialized baby stores, facilitates easy access to various baby toiletries. The presence of leading and local brands and extensive marketing campaigns further stimulate demand. Moreover, the influence of social media and parenting blogs in promoting specific baby care products plays a significant role in shaping consumer preferences in Europe.
Asia Pacific Baby Toiletries Market Trends
The baby toiletries market in Asia Pacific is set to grow at a CAGR of 6.6% from 2025 to 2033. The increasing birth rate in many countries within the region, particularly in India and China, provides a large consumer base for baby toiletries. Additionally, the rising disposable income among middle-class families is enabling parents to spend more on high-quality baby care products. The growing awareness about baby hygiene and health, coupled with the influence of Western parenting practices, is also propelling the demand for baby toiletries in the region.
Key Baby Toiletries Company Insights
Some key companies in the baby toiletries industry are Johnson & Johnson Services, Inc., KCWW, Procter & Gamble, Hengan International Group Company Ltd, and others.
-
Hengan International Group Company Ltdis one of the largest manufacturers of maternal & child hygiene products. The company produces sanitary napkins, baby diapers, adult diapers, and other personal hygiene products. Hengan International has a significant market presence in China and exports its products to over 63 countries. The company is known for its continuous innovation and commitment to sustainable development, having received several awards for its low-carbon and green initiatives.
Key Baby Toiletries Companies
The following key companies have been profiled for this study on the baby toiletries market.
-
Johnson & Johnson Services, Inc.
-
KCWW
-
Procter & Gamble
-
Hengan International Group Company Ltd.
-
Beiersdorf
-
Dabur
-
Unilever
-
Avon Healthcare
-
Himalaya Wellness Company
Competitive Benchmarking
Operating Strategies
Competitive Edge
Weaknesses
Established Players (Johnson & Johnson Services, Inc.; Procter & Gamble; Unilever; Beiersdorf; Hengan International Group Company Ltd.)
- Expand baby care portfolios across baby shampoos, lotions, oils, powders, wipes, diaper care products, and bath essentials while emphasizing safety, dermatological testing, and hypoallergenic formulations.
- Strengthen omnichannel distribution through supermarkets, pharmacies, hospitals, maternity care networks, and e-commerce platforms while investing in premium, natural, and organic product lines to address evolving parental preferences.
- Strong brand trust built around infant safety, extensive global distribution networks, and significant marketing and R&D capabilities.
- Ability to leverage large-scale manufacturing, regulatory expertise, and diversified personal care portfolios to maintain leadership across both developed and emerging markets.
- Higher operating and compliance costs due to stringent infant product safety standards and quality assurance requirements.
- Greater exposure to product recalls, ingredient scrutiny, and changing consumer preferences toward niche, organic, and clean-label baby care brands.
Emerging & Regional Players (Dabur; Himalaya Wellness Company; Avon Healthcare; KCWW)
- Focus on herbal, natural, Ayurvedic, and chemical-free baby toiletries targeting health-conscious parents seeking gentle and plant-based formulations.
- Utilize regional distribution strength, digital marketing, pediatrician recommendations, and value-oriented pricing strategies to increase penetration in emerging markets and underserved consumer segments.
- Strong positioning in natural and wellness-oriented baby care categories with growing consumer preference for clean-label products.
- Greater agility in responding to regional consumer needs, ingredient trends, and demand for specialized baby skincare and hygiene solutions.
- Limited international presence and lower marketing budgets compared to multinational consumer goods companies.
- Challenges in scaling distribution, building global brand recognition, and competing with established players that possess stronger retailer relationships and broader product portfolios.
Recent Developments
-
In January 2025, CITTA, a premium baby bath and skincare brand based in Pune, launched an innovative baby care range featuring humus extract to enhance skin health and immunity. Their 'Protection Range' includes Protecting Body Lotion and Protecting Sunscreen, designed to nourish delicate skin and support its microbiome. These products merging cultural wisdom with scientific research to provide safe and effective skincare solutions for infants.
-
In September 2024, Dove unveiled its Baby Dove Eczema Care range, specifically designed for the delicate needs of eczema-prone baby skin. This new line includes the Baby Dove Eczema Care Soothing Bath Treatment and Eczema Care Cream, both formulated to nourish and protect sensitive skin. Free from phthalates, dyes, parabens, steroids, and fragrances, the products enriched with 100% natural nutrients and are approved by the National Eczema Association, ensuring effective relief from symptoms of eczema while maintaining skin’s natural moisture barrier.
-
In June 2024, Johnson’s Baby launched a new Coconut and Honeysuckle Skin Nourish line, featuring pediatrician- and dermatologist-tested products designed to relieve dry skin and provide 24-hour moisture. This new line includes Johnson’s Baby Skin Nourish Creamy Oil with Coconut & Honeysuckle scents, Baby Lotion with Coconut & Honeysuckle, and Johnson’s Baby Coconut & Honeysuckle Skin Nourish Moisture Wash. All products are hypoallergenic.
Baby Toiletries Market Report Scope
Report Attribute
Details
Market size in 2025
USD 119.8 billion
Estimated market size in 2026
USD 126.7 billion
Projected market size by 2033
USD 191.8 billion
Growth rate
CAGR of 6.1% from 2026 to 2033
Base year for estimation
2025
Historical data
2021 - 2024
Forecast period
2026 - 2033
Quantitative units
Revenue in USD million/billion and CAGR from 2026 to 2033
Report coverage
Revenue forecast, company ranking, competitive landscape, growth factors, and trends
Segments covered
Product, distribution channel, region
Regional scope
North America; Europe; Asia Pacific; Latin America; Middle East & Africa
Country scope
U.S.; Canada; Mexico; Germany; UK; France; Italy; Spain; China; Japan; India; South Korea; Brazil; Argentina; South Africa; Saudi Arabia
Key companies profiled
Johnson & Johnson Services, Inc.; KCWW; Procter & Gamble; Hengan International Group Company Ltd.; Beiersdorf; Dabur; Unilever; Avon Healthcare; Himalaya Wellness Company
Customization scope
Free report customization (equivalent up to 8 analysts' working days) with purchase. Addition or alteration to country, regional & segment scope.
Pricing and purchase options
Avail customized purchase options to meet your exact research needs. Explore purchase options
Global Baby Toiletries Market Report Segmentation
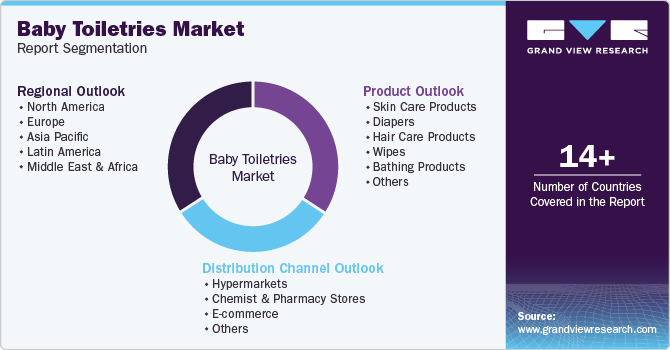
This report forecasts revenue growth at regional and country levels and provides an analysis of the latest industry trends in each of the sub-segments from 2021 to 2033. For this study, Grand View Research has segmented the global baby toiletries market report based on product, distribution channel, and region:
 To learn more about this report, Download Free Sample Report
-
Product Outlook (Revenue, USD Million; 2021 - 2033)
-
Skin Care Products
-
Diapers
-
Hair Care Products
-
Wipes
-
Bathing Products
-
Others
-
-
Distribution Channel Outlook (Revenue, USD Million; 2021 - 2033)
-
Hypermarkets
-
Chemist and Pharmacy Stores
-
E-commerce
-
Others
-
-
Regional Outlook (Revenue, USD Million; 2021 - 2033)
-
North America
-
U.S.
-
Canada
-
Mexico
-
-
Europe
-
UK
-
Germany
-
France
-
Italy
-
Spain
-
-
Asia Pacific
-
Japan
-
China
-
India
-
South Korea
-
-
Latin America
-
Brazil
-
Argentina
-
-
Middle East and Africa (MEA)
-
South Africa
-
Saudi Arabia
-
-
Research Methodology
The baby toiletries market figures in this report are based on a proven research process that combines executive interviews with secondary research from proprietary databases, company filings, and recognized regulatory and institutional sources. Market size is built through value-chain sizing-reconciling supply-side and demand-side estimates-and triangulated with bottom-up and top-down approaches. Every estimate passes multiple levels of expert validation before publication, with each baby toiletries segment quantified using the revenue-capture definitions in the table below.
Segment Definition
Segment –Product
Revenue capture definition
Skin Care Products
Covers baby-specific skincare products including lotions, creams, moisturizers, oils, powders, diaper rash creams, sunscreens, and protective ointments formulated for infant and toddler skin. The scope includes both daily-use and therapeutic skincare toiletries sold through retail and online channels for babies and young children.
Diapers
Covers disposable diapers, training pants, swim diapers, overnight diapers, and related absorbent hygiene products designed for infants and toddlers. The study includes diaper variants differentiated by size, absorbency, age group, and usage occasion, marketed through organized and unorganized retail distribution networks.
Hair Care Products
Includes baby shampoos, hair oils, conditioners, detangling sprays, scalp care formulations, and other hair hygiene products specifically developed for infants and young children. The scope covers products addressing cleansing, nourishment, scalp maintenance, and hair management requirements within the baby toiletries category.
Wipes
Covers baby wipes used for diaper changing, hand and face cleaning, personal hygiene, and general infant care. The segment includes scented and unscented wipes, biodegradable wipes, antibacterial wipes, and sensitive-skin variants available in multiple packaging formats and distribution channels.
Bathing Products
Includes baby soaps, body washes, bubble baths, cleansing bars, bath additives, and wash-and-shampoo combinations formulated for infants and toddlers. The scope encompasses products intended for routine bathing, skin cleansing, and hygiene maintenance, including products designed for sensitive and delicate baby skin.
Others
Covers miscellaneous baby toiletry products not classified under core categories, including baby fragrances, oral care products, grooming accessories, cotton products, cleansing solutions, and specialty hygiene products. The scope includes emerging and niche toiletries developed for infant personal care and hygiene applications.
Segment – Distribution Channel
Revenue capture definition
Hypermarkets
Covers sales of baby toiletries through large-format retail stores, supermarkets, warehouse clubs, and mass merchandisers offering dedicated baby care sections. The scope includes both branded and private-label products sold through organized retail environments with broad product assortments and promotional offerings.
Chemist and Pharmacy Stores
Includes sales of baby toiletries through pharmacies, drugstores, medical stores, and healthcare retail outlets. The scope covers products purchased through prescription-independent healthcare channels, including dermatologist-recommended, pediatrician-endorsed, and specialized infant hygiene and skincare product ranges.
E-commerce
Covers online sales of baby toiletries through brand-owned websites, online marketplaces, retailer platforms, and mobile commerce applications. The scope includes direct-to-consumer sales, subscription models, bundled product offerings, and digital retail transactions across domestic and cross-border online channels.
Others
Includes baby toiletry sales through convenience stores, specialty baby stores, department stores, wholesalers, institutional channels, and independent retailers. The scope covers all remaining distribution formats involved in the sale of infant hygiene and personal care products outside the primary retail channel classifications.
Estimation Model
Layer Title
Guiding Question
Description
Infant & Toddler Population Layer
Who requires baby toiletry products?
Begin with the global population of infants and toddlers (typically ages 0–3 years). Apply birth rates, population statistics, and age-cohort data to determine the total number of children requiring daily hygiene and personal care products. This forms the foundational consumer pool for baby toiletries.
Purchasing Household Layer
Which households actively purchase commercial baby care products?
Filter the infant population using disposable income levels, urbanization rates, working-parent demographics, retail accessibility, and hygiene awareness indicators. This derives households that regularly purchase packaged baby toiletries rather than relying solely on traditional or homemade alternatives.
Category Adoption & Consumption Layer
Who actively consumes baby toiletries across product categories?
Apply penetration and consumption rates across diapers, wipes, skin care products, bathing products, and hair care products. Account for usage intensity, premium product adoption, repeat purchases, and frequency of consumption to estimate annual product demand. Diapers and wipes typically generate the highest recurring demand due to frequent usage.
Monetisation Layer
How much revenue is generated?
Multiply annual category-level consumption volumes by average selling prices across diapers, wipes, skin care, hair care, and bathing products. Further adjust for premiumization trends, organic formulations, dermatologist-tested products, and e-commerce-driven product mix shifts to estimate total market revenue.
Delivered Customizations
This report has been delivered with the following In-depth customizations
Client Request
Customization Delivered
Value Adds
Parent Purchase Journey & Product Category Conversion Analysis
Comprehensive analysis of how parents allocate spending across diapers, skin care products, wipes, bathing products, and hair care products throughout different child-development stages. The study maps purchasing frequency, basket composition, premiumization trends, and category migration patterns across first-time parents versus experienced parents.
Identifies which product categories serve as entry points for brand acquisition and which categories drive long-term customer retention. Helps manufacturers develop cross-selling strategies and maximize lifetime customer value across the baby care portfolio. Diapers remain the largest category, while skin care products are among the faster-growing segments.
Clean Label, Natural & Sensitive-Skin Product Opportunity Assessment
Detailed evaluation of demand for chemical-free, dermatologist-tested, hypoallergenic, organic, and plant-based baby toiletries across key regions. The analysis benchmarks product claims, ingredient positioning, certification trends, and consumer willingness to pay for safety-focused formulations.
Helps clients identify premium growth pockets where parents increasingly prioritize ingredient transparency, toxin-free formulations, and skin-safety credentials. Particularly valuable for new product development and premium brand positioning strategies. Market growth is increasingly supported by demand for gentle and specialized products for sensitive baby skin.
Regional Premiumization & Affordability Mapping
Country-level comparison of premium, mid-tier, and value baby toiletries across North America, Europe, Asia Pacific, Latin America, and MEA. The study evaluates pricing structures, disposable income impact, urbanization trends, and regional brand preferences.
Helps companies prioritize markets where premium baby care adoption is accelerating versus regions where affordability remains the primary purchase driver. Supports market-entry, pricing, and portfolio localization strategies.
Frequently Asked Questions About This Report
The global baby toiletries market size was valued at USD 119.8 billion in 2025 and is estimated at USD 126.7 billion in 2026.
North America dominated the market with a 34.1% revenue share in 2025.
Asia Pacific is the fastest-growing regional market.
The hypermarkets segment held the largest revenue share of 39.6% in 2025, benefiting from broad product assortments, competitive pricing, and strong consumer preference for one-stop shopping destinations.
The global baby toiletries market is expected to grow at a CAGR of 6.1% from 2025 to 2033, reaching USD 191.8 billion by 2033.
The diapers segment led the market with a 29.2% revenue share in 2025, owing to its essential nature and recurring purchase frequency.
Key players include Johnson & Johnson, Procter & Gamble, Kimberly-Clark Corporation, Unilever PLC, Beiersdorf AG, The Himalaya Drug Company, Burt's Bees Baby, Chicco, Pigeon Corporation, and Mustela.
Key factors include increasing parental awareness regarding infant hygiene and skin health, rising demand for premium and organic baby care products, growing birth rates in developing economies, expanding penetration of specialized baby care brands, and increasing availability of baby toiletries through online retail channels.
About the Author(s)
Beauty & Personal Care Research Team
Consumer Goods · Beauty & Personal CareThis report was authored by the beauty & personal care research team at Grand View Research - comprising two research analysts, one senior research analyst, and one industry expert - with specialized expertise in the beauty & personal care segment of the consumer goods industry. All findings are based on proprietary consumer goods databases, executive interviews, and regulatory analysis, subject to internal peer review prior to publication.
Last Updated:
Speak to Analyst

Customize this report to your needs - add regions, segments, or data points, with 20% free customization.
Or view our licence options:


ISO 9001:2015 & 27001:2022 Certified
We are GDPR and CCPA compliant! Your transaction & personal information is safe and secure. For more details, please read our privacy policy.


