
- Home
- »
- Pharmaceuticals
- »
-
BCG Vaccine Market Size, Share & Trends Report, 2033GVR Report cover

BCG Vaccine Market (2026 - 2033)
Size, Share & Trends Analysis Report By Product (Immune BCG Vaccine, Therapeutic BCG Vaccine), By Distribution Channel (Public Sector, Private Sector), By Region (North America, Europe, Asia Pacific), And Segment Forecasts
Market Size, 2025
$181.8MMarket Estimate, 2026
$190.3MMarket Forecast, 2033
$275.5MCAGR, 2026–2033
5.4%BCG Vaccine Market Summary
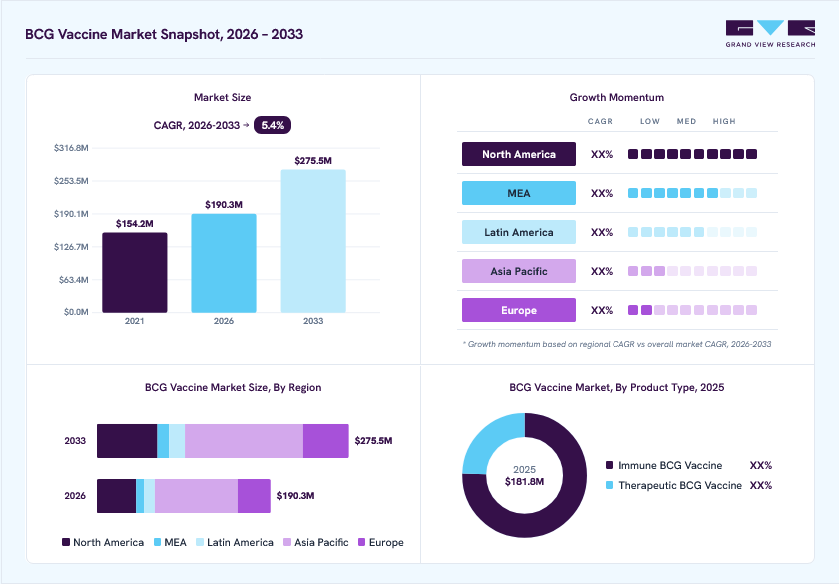
The global BCG vaccine market size was valued at USD 181.8 million in 2025 and is projected to grow from USD 190.3 million in 2026 to USD 275.5 million by 2033, at a CAGR of 5.4% from 2026 to 2033. Asia Pacific dominated the market, accounting for the largest share of 47.8% in 2025. The industry is supported by the continued use of the Bacillus Calmette-Guérin (BCG) vaccine for tuberculosis (TB) prevention and the treatment of non-muscle invasive bladder cancer.
 Source: Grand View Research, IR Documents, Primary Interviews, Paid DatabasesTo learn more about this report,
 Download Free Sample Report
Key Market Trends & Insights
- By product: Immune BCG vaccine segment held the highest market share of 75.3% in 2025.
- By distribution channel: Public sector held the highest market share of 77.9% in 2025.
Regional Highlights
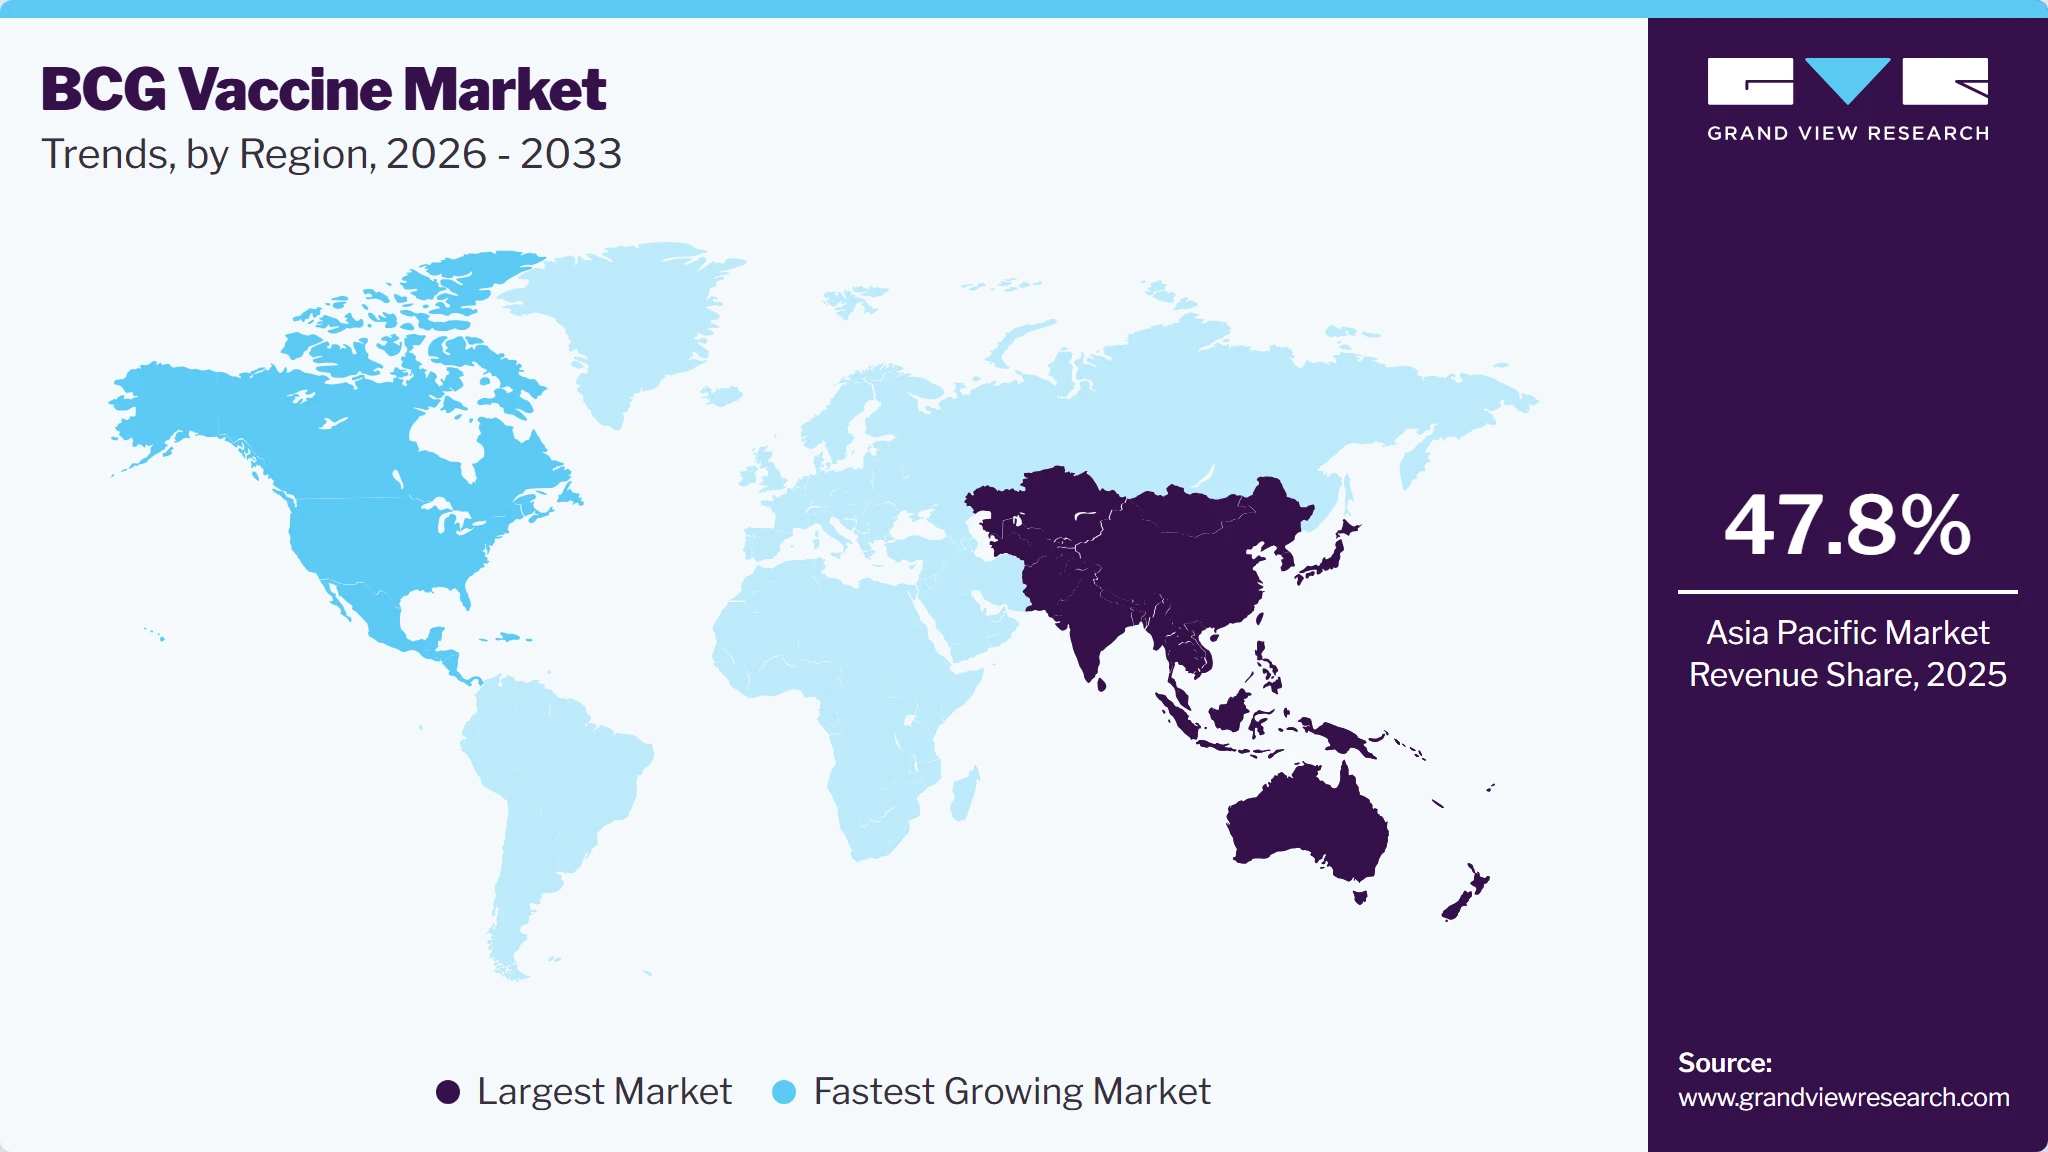
- Largest Market: Asia Pacific (47.8% market share in 2025)
- Fastest Growing Market: North America (highest CAGR, 2026-2033)
- By country: China held the largest market share in 2025.
Market Size & Forecast
- Market size in 2025: USD 181.8 Million
- Estimated market size in 2026: USD 190.3 Million
- Projected market size by 2033: USD 275.5 Million
- CAGR (2026-2033): 5.4%
Three ways to get this report
Buy it, customize it, or ask a question.Ask an Analyst
Analyst response in 1 business day
- AccessReport author, directly
- Reply timeWithin 1 working day
- No sales callDirect answer only
- FormatEmail reply
- CostFree, no cost
Get the Full Report
What the study covers
- FormatsPDF · Excel · Dashboard
- Timeline2026–2033 annual, 2025 base
- Coverage20+ countries, 5 regions
- Companies10+ key players profiled
Customize the Report
20% free customization
- IncludeCountries, segments, points
- TailorTo your product definition
- ExtendDeeper competitor detail
- OrA fully bespoke study
- Turnaround5–10 working days
The vaccine is included in national immunization programs in many countries with a moderate to high TB burden, especially across Asia Pacific, Africa, and parts of Latin America. Government vaccination programs and procurement by public health agencies continue to support market demand. The market has a limited number of manufacturers, making supply dependent on production capacity, regulatory compliance, and quality standards. Manufacturers are investing in production upgrades and capacity expansion to improve product availability. Research on new therapeutic uses of BCG is ongoing, but its primary use remains TB prevention and bladder cancer treatment. Support from global health organizations, continued focus on tuberculosis control, and stable demand from public healthcare systems continue to maintain the market across developed and developing countries.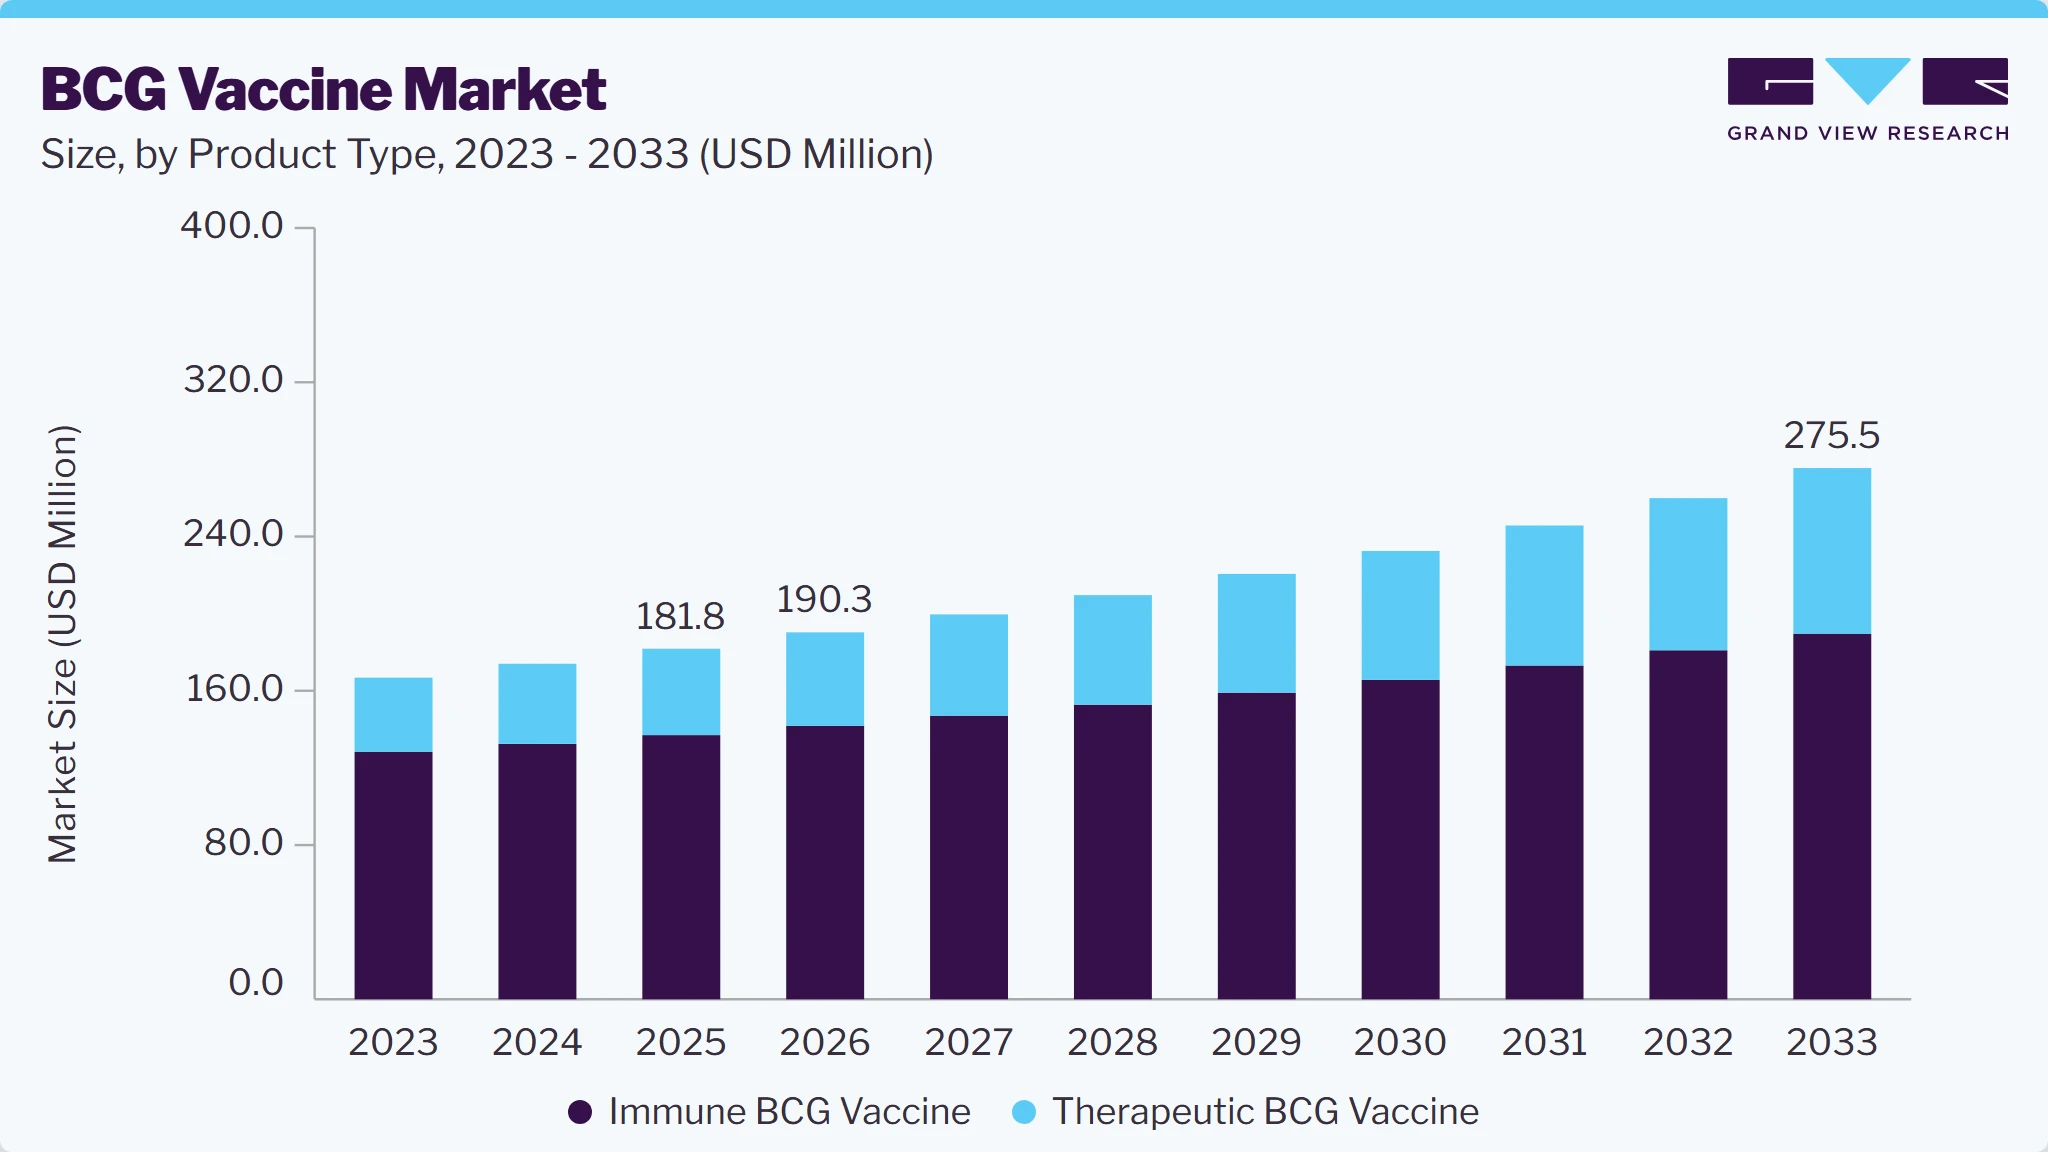 To learn more about this report, Download Free Sample Report
Market Dynamics
The market is driven by the continued use of the vaccine in national immunization programs for newborns and infants, particularly in countries with a moderate to high tuberculosis (TB) burden. Many governments include BCG vaccination in routine childhood immunization schedules to reduce the risk of severe forms of TB during early life. Public procurement through national healthcare systems supports consistent demand, while organizations such as the World Health Organization (WHO), UNICEF, and Gavi continue to support TB prevention initiatives and vaccine access in low- and middle-income countries. In addition to its role in TB prevention, the vaccine is widely used for the treatment of non-muscle invasive bladder cancer, creating demand from hospitals and cancer care centers. Manufacturers are also investing in production improvements to maintain product availability and meet regulatory requirements. These factors continue to support demand across both public health and oncology applications. For instance, in January 2025, Pfizer announced positive Phase III results for sasanlimab in combination with the BCG vaccine for the treatment of high-risk non-muscle invasive bladder cancer, supporting the continued clinical use of BCG in cancer therapy.
The industry faces challenges due to the limited number of manufacturers producing the vaccine globally. Manufacturing BCG requires specialized production facilities, strict quality control, and compliance with regulatory standards, making capacity expansion a lengthy process. Any production issue, maintenance activity, or regulatory inspection can affect product availability and lead to supply shortages. Since many countries depend on government procurement for routine immunization programs, interruptions in supply can affect vaccine distribution and immunization planning. The bladder cancer treatment segment is also affected because hospitals rely on a stable supply of BCG for patient care. Manufacturers continue to improve production facilities and quality systems, but balancing global demand with available supply remains an ongoing challenge. Maintaining stable manufacturing operations and increasing production capacity are important for improving product availability across both tuberculosis prevention and oncology use. For instance, in 2025, UNICEF reported that the global BCG vaccine market continued to depend on a limited number of manufacturers while efforts were underway to strengthen supply availability through production improvements.
The industry offers opportunities through investments in manufacturing capacity and improvements in vaccine supply. Governments continue to strengthen routine immunization programs, creating long-term demand through public procurement. Manufacturers are also focusing on expanding production capacity, improving manufacturing efficiency, and meeting regulatory quality requirements to reduce supply constraints. In addition, continued research on tuberculosis vaccines and immunotherapy is increasing scientific interest in BCG-based technologies. Although BCG remains the standard vaccine for tuberculosis prevention, ongoing investments in vaccine development and manufacturing infrastructure can support stable product availability and improve access in countries with a high tuberculosis burden. These factors provide opportunities for manufacturers to strengthen supply, expand partnerships with public health agencies, and support long-term vaccination programs.
Market Concentration & Characteristics
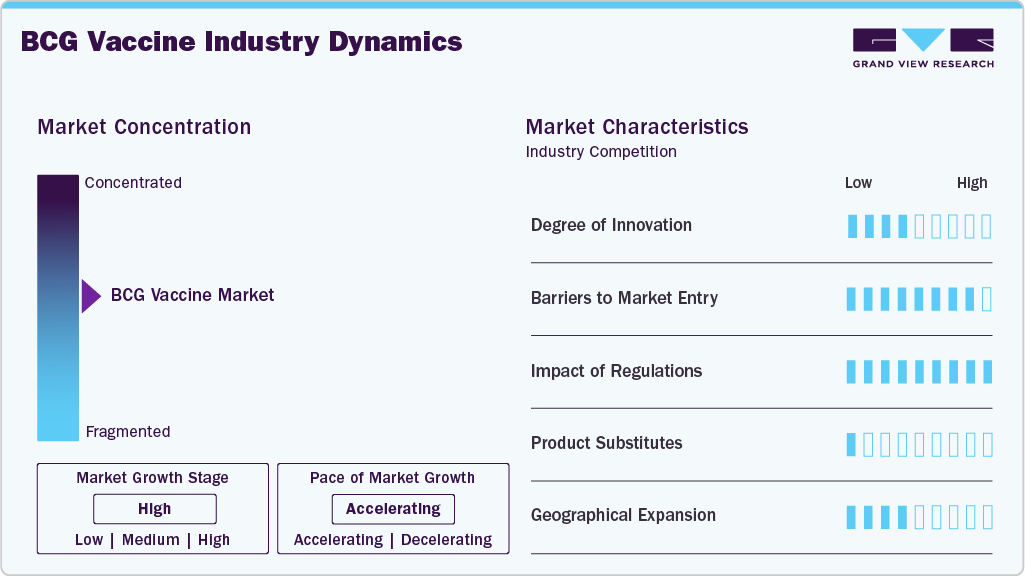
The degree of innovation is moderate in the BCG vaccine industry. Most research is focused on improving manufacturing processes, increasing production capacity, and evaluating BCG in combination with immunotherapies for bladder cancer. The vaccine itself has remained largely unchanged for tuberculosis prevention, with manufacturers concentrating on product quality, supply stability, and process improvements rather than introducing new vaccine formulations.
The barriers to entry are high in this industry because manufacturing the BCG vaccine requires specialized biological production facilities, skilled technical expertise, and compliance with strict regulatory and quality standards. New manufacturers must complete detailed validation processes and obtain approvals from regulatory authorities before commercial production, making market entry both time-consuming and capital-intensive.
 To learn more about this report, Download Free Sample Report
The impact of regulations is high in the industry. Manufacturers must comply with national regulatory requirements, Good Manufacturing Practices (GMP), and World Health Organization guidelines to ensure product quality, safety, and consistency. Regular inspections, quality testing, and batch release requirements directly affect production timelines and vaccine supply.
The availability of product substitutes is low because BCG remains the only widely used vaccine for routine tuberculosis prevention in newborns and infants in countries where vaccination is recommended. Although several tuberculosis vaccine candidates are under clinical development, none have replaced BCG in national immunization programs or routine public health practice.
The level of geographical expansion is moderate as manufacturers continue to strengthen vaccine supply in countries with a moderate to high tuberculosis burden. Demand is supported by national immunization programs across Asia Pacific, Africa, and parts of Latin America. Companies are also investing in manufacturing capacity and working with public health agencies to improve vaccine availability in underserved regions.
Analyst Perspective
The BCG vaccine industry is supported by its continued use in tuberculosis prevention and the treatment of non-muscle invasive bladder cancer. Routine childhood immunization programs provide stable demand across many countries. Market performance depends on production capacity, product availability, and compliance with quality standards. Ongoing research may support additional clinical applications of BCG in cancer treatment. Manufacturers that maintain a reliable supply, improve production efficiency, and meet regulatory requirements are expected to strengthen their position in the market.Product Insights
The immune BCG vaccine segment accounted for the largest market share of 75.3% in 2025. The segment dominates the market because it is included in routine childhood immunization programs across many countries with a moderate to high tuberculosis burden. Government procurement through national immunization programs ensures consistent demand and supports large-scale vaccine distribution. Recommendations from the World Health Organization and national health authorities continue to strengthen their adoption in public vaccination schedules. The vaccine is administered shortly after birth in many countries, resulting in stable procurement volumes every year. Its established safety profile, long history of clinical use, and widespread availability through public healthcare systems further support demand.
The therapeutic BCG vaccine segment is projected to register the fastest CAGR of 8.5% during the forecast period. Growth is driven by the increasing use of BCG in the treatment of non-muscle invasive bladder cancer and the rising number of patients requiring intravesical therapy. Continued adoption by hospitals and urology centers supports demand, while ongoing clinical research is evaluating BCG in combination with newer immunotherapies to improve treatment outcomes. Increasing awareness of early bladder cancer diagnosis, expanding access to specialized cancer care, and growing investment in oncology services are also contributing to segment growth. In addition, manufacturers are focusing on improving product availability to address supply challenges and meet clinical demand.
Distribution Channel Insights
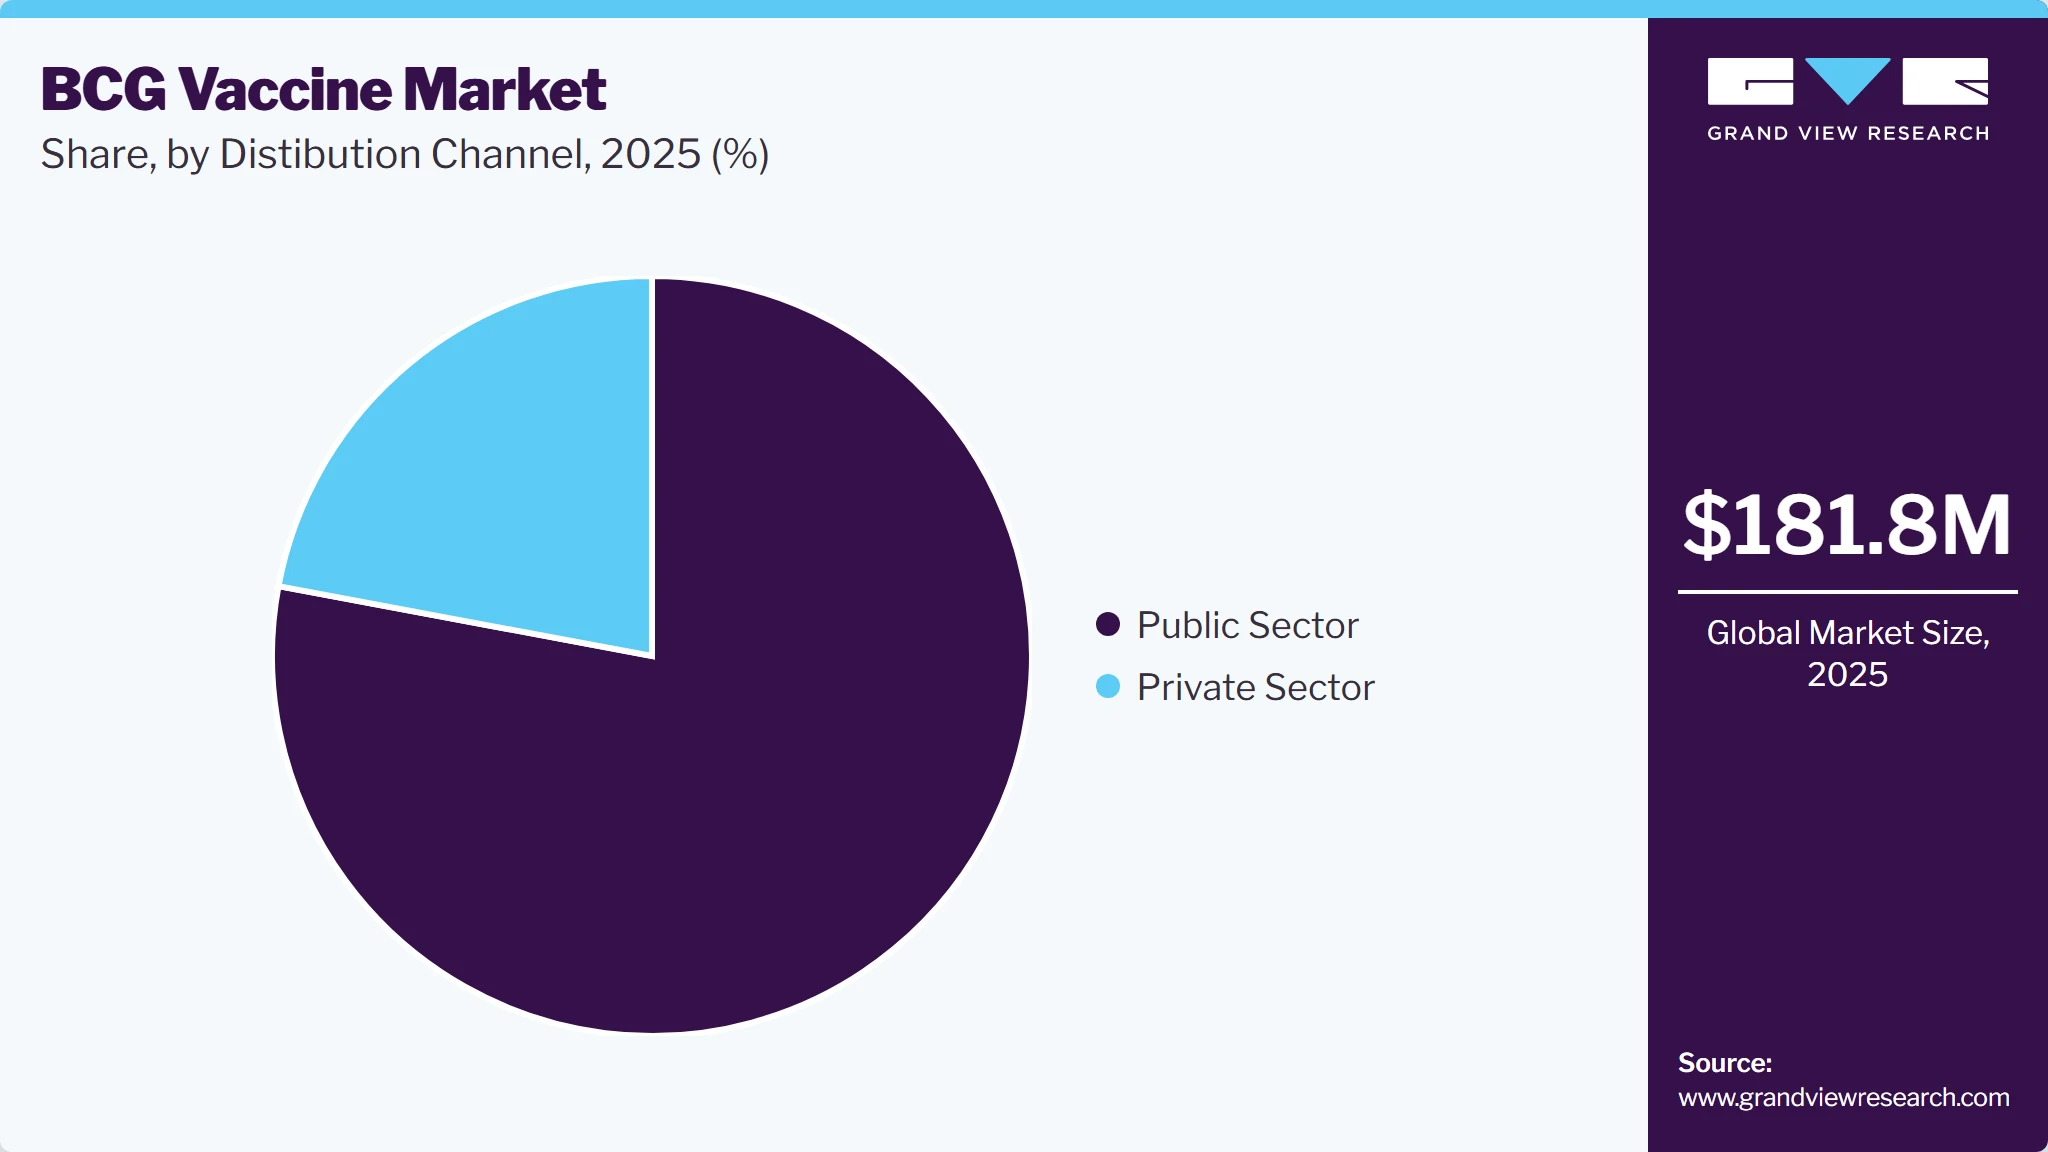
The public sector accounted for the largest share of 77.9% in 2025. The segment dominates because BCG vaccination is primarily delivered through government-funded immunization programs in countries with a moderate to high tuberculosis burden. National health authorities procure vaccines in large volumes to support routine childhood vaccination, ensuring stable demand. Support from international organizations such as UNICEF and Gavi further strengthens vaccine procurement and distribution in low- and middle-income countries. Public healthcare facilities provide broad access to newborn vaccination, while centralized procurement helps maintain consistent vaccine availability. In addition, government investments in tuberculosis control programs and established public health infrastructure continue to support large-scale vaccine administration.
 To learn more about this report, Download Free Sample Report
The private sector is projected to register the fastest CAGR of 10.0% during the forecast period. Growth is supported by the increasing role of private hospitals, specialty clinics, and diagnostic centers in providing vaccination and bladder cancer treatment services. Rising healthcare spending, expansion of private healthcare infrastructure, and greater access to specialized medical services are contributing to segment growth. In several countries, individuals are also choosing private healthcare facilities because of shorter waiting times and broader access to medical specialists. The growing use of BCG for the treatment of non-muscle invasive bladder cancer in private hospitals is further supporting demand. In addition, continued investment in private healthcare networks and expanding oncology services are expected to strengthen the role of the private sector, resulting in faster growth during the forecast period.
Regional Insights
The BCG vaccine market in Asia Pacific accounted for the largest share of 47.8% in 2025. The region has a large birth population, resulting in sustained demand for BCG vaccines through routine childhood immunization programs. A higher tuberculosis burden across several countries continues to support widespread BCG vaccination during infancy. The presence of leading vaccine manufacturers and established production facilities contributes to consistent product availability across the region. Increasing healthcare access and improving vaccination coverage continue to strengthen vaccine demand in both urban and rural areas.
 To learn more about this report, Download Free Sample Report
Japan BCG Vaccine Market Trends
The Japan BCG vaccine market is supported by routine childhood BCG vaccination and an established vaccine manufacturing industry. The country maintains consistent demand through regular infant immunization practices and a well-developed healthcare system. Domestic manufacturers continue to focus on maintaining production quality and a stable vaccine supply. The use of BCG in bladder cancer treatment also supports demand from hospitals and specialized urology centers. Continuous improvements in healthcare services and patient access contribute to stable product utilization.
The BCG vaccine market in China represents a significant market due to its large infant population and continued focus on tuberculosis prevention. Routine childhood vaccination creates a steady demand for BCG vaccines across the country. The presence of domestic vaccine manufacturers supports local production and product availability. Expanding healthcare infrastructure has improved access to vaccination and specialized medical services in many regions. The increasing diagnosis of bladder cancer is also supporting the use of therapeutic BCG in hospitals.
North America BCG Vaccine Market Trends
The North America BCG vaccine market is projected to register the fastest growth of 6.4% during the forecast period. Growth is supported by the increasing use of BCG in the treatment of non-muscle invasive bladder cancer across hospitals and specialized cancer centers. Rising bladder cancer incidence continues to increase the demand for intravesical BCG therapy in clinical practice. Ongoing clinical research evaluating BCG in combination with immunotherapies is expanding treatment options for eligible patients. Healthcare providers are strengthening access to specialized urology and oncology services, supporting higher treatment volumes. Continued efforts by manufacturers to improve product availability are further contributing to market growth across the region.
The BCG vaccine market in the U.S. is primarily driven by the established use of BCG as a standard treatment for non-muscle invasive bladder cancer in hospitals and cancer centers. A large patient population requiring bladder cancer treatment supports consistent product demand. The presence of advanced healthcare infrastructure enables wider access to specialized urology services and follow-up care. Continuous clinical research involving BCG-based treatment approaches is contributing to broader clinical adoption. Investments in oncology care and increasing awareness of early cancer diagnosis continue to support market expansion in the country.
Europe BCG Vaccine Market Trends
The BCG vaccine market in Europe is supported by routine tuberculosis vaccination in selected countries and the continued use of BCG for bladder cancer treatment. Demand remains stable through established healthcare systems and clinical practice guidelines for eligible patients. The presence of experienced vaccine manufacturers and contract manufacturing organizations supports product availability across the region. Healthcare providers continue to expand access to specialized oncology and urology services, increasing treatment volumes. Research institutions are actively evaluating BCG in cancer immunotherapy, contributing to scientific development. These factors continue to support the regional market across both infectious disease prevention and oncology applications.
The UK BCG vaccine market is supported by targeted tuberculosis vaccination programs for high-risk populations and continued clinical use in bladder cancer treatment. Healthcare providers follow established clinical guidelines for intravesical BCG therapy in eligible patients with non-muscle invasive bladder cancer. The country's developed oncology infrastructure supports access to specialized diagnosis, treatment, and follow-up services. Research organizations continue to evaluate new treatment combinations involving BCG for bladder cancer management. Strong collaboration between hospitals and academic institutions supports clinical research activities. These factors contribute to steady demand for BCG vaccines across preventive and therapeutic applications.
The BCG vaccine market in Germany is driven by an established healthcare infrastructure and extensive oncology services. Demand is supported by the continued use of BCG as a standard treatment for non-muscle invasive bladder cancer in hospitals and specialized urology centers. The presence of experienced healthcare professionals enables consistent adoption of guideline-based treatment. Clinical research activities focusing on immunotherapy combinations continue to increase scientific interest in BCG-based therapies. Strong diagnostic capabilities support early identification of bladder cancer patients requiring treatment.
The France BCG vaccine market is supported by the continued use of BCG in the treatment of non-muscle invasive bladder cancer and the country's established clinical oncology network. Hospitals and specialized urology centers continue to use intravesical BCG as a standard treatment for eligible patients. Rising awareness of early bladder cancer diagnosis is increasing the number of patients receiving timely treatment. The presence of experienced healthcare professionals supports the consistent use of guideline-based therapies. Ongoing clinical studies related to cancer immunotherapy continue to strengthen the role of BCG in oncology. These factors contribute to stable demand for BCG vaccines across therapeutic applications in France.
Latin America BCG Vaccine Market Trends
The BCG vaccine market in Latin America is supported by the continued use of BCG in routine childhood vaccination and increasing attention to tuberculosis prevention. Many healthcare providers continue to administer the vaccine at birth, resulting in stable annual demand. Expanding healthcare infrastructure has improved access to vaccination services across several parts of the region. The growing availability of diagnostic services is supporting earlier detection and treatment of bladder cancer, increasing the use of therapeutic BCG. Regional manufacturers and international suppliers continue to maintain vaccine availability through established distribution networks.
Brazil BCG vaccine market is driven by its large birth population and continued use of BCG in routine infant vaccination. Consistent demand for tuberculosis prevention supports stable vaccine procurement across healthcare facilities. The country also has an established clinical practice for using BCG in the treatment of non-muscle invasive bladder cancer. Improvements in healthcare access have increased the availability of vaccination and specialized oncology services. Growing awareness of early disease diagnosis is supporting timely treatment and patient management.
Middle East & Africa BCG Vaccine Market Trends
The BCG vaccine market in the Middle East & Africa is supported by the continued need for tuberculosis prevention across several countries with moderate to high disease burden. Routine infant vaccination remains an important contributor to vaccine demand throughout the region. Improvements in healthcare infrastructure are increasing access to immunization services and strengthening vaccine coverage. The expansion of hospital networks and specialized medical facilities is also supporting the use of BCG in bladder cancer treatment. Manufacturers continue to improve product availability through regional supply partnerships and distribution channels.
The Saudi Arabia BCG vaccine market is supported by routine newborn vaccination and the country's expanding healthcare infrastructure. Healthcare providers continue to administer BCG as part of standard infant immunization practices, supporting consistent vaccine demand. The presence of advanced hospitals and specialized oncology centers has increased the use of BCG for non-muscle invasive bladder cancer treatment. Greater access to diagnostic services is contributing to earlier disease detection and improved patient management. Ongoing investments in hospital capacity and specialized medical services continue to strengthen vaccine utilization across preventive and therapeutic applications.
Key BCG Vaccine Company Insights
The BCG vaccine market is moderately concentrated, with a limited number of manufacturers supplying vaccines for tuberculosis prevention and bladder cancer treatment. Competition is based on manufacturing capacity, product quality, regulatory compliance, supply reliability, and participation in public procurement programs. Companies are focused on maintaining consistent production, expanding manufacturing capabilities, and meeting international quality standards to strengthen their market position. Public-sector vaccine institutes and regional manufacturers play an important role in supplying domestic and international markets, while established pharmaceutical companies continue to support oncology applications of BCG. Long-term supply agreements established distribution networks, and compliance with global regulatory requirements remain important factor for maintaining competitiveness.
Key BCG Vaccine Companies
The following key companies have been profiled for this study on the BCG vaccine market.
-
Merck & Co., Inc.
-
Serum Institute of India Pvt. Ltd.
-
Japan BCG Laboratory
-
AJ Vaccines A/S
-
China National Biotec Group (CNBG)
-
GreenSignal Bio Pharma Ltd.
-
InterVax Ltd.
-
BioFarma
-
Biomed-Lublin S.A.
-
BB-NCIPD Ltd.
Recent Developments
-
In July 2026, Serum Institute of India Pvt. Ltd. partnered with Gates Medical Research Institute to manufacture the investigational M72/AS01E tuberculosis vaccine and expand future TB vaccine manufacturing capacity.
-
In May 2026, Japan BCG Laboratory entered into an exclusive development and supply agreement with ImmunityBio to manufacture and supply the Tokyo-172 strain of BCG for development and commercialization in the U.S. for bladder cancer treatment.
BCG Vaccine Market Report Scope
Report Attribute
Details
Market size value in 2025
USD 181.8 million
Market size value in 2026
USD 190.3 million
Revenue forecast in 2033
USD 275.5 million
Growth rate
CAGR of 5.4% from 2026 to 2033
Base year for estimation
2025
Historical data
2021 - 2024
Forecast period
2026 - 2033
Quantitative units
Revenue in USD million/billion and CAGR from 2026 to 2033
Report coverage
Revenue forecast, company ranking, competitive landscape, growth factors, trends
Segments covered
Product, distribution channel, region
Regional scope
North America; Europe; Asia Pacific; Latin America; Middle East & Africa
Country scope
U.S.; Canada; Mexico; UK; Germany; France; Italy; Spain; Denmark; Sweden; Norway; China; Japan; India; Australia; South Korea; Thailand; Brazil; Argentina; South Africa; Saudi Arabia; UAE; Kuwait
Key company profiled
Merck & Co., Inc.; Serum Institute of India Pvt. Ltd.; Japan BCG Laboratory; AJ Vaccines A/S; China National Biotec Group (CNBG); GreenSignal Bio Pharma Ltd.; InterVax Ltd.; BioFarma; Biomed-Lublin S.A.; BB-NCIPD Ltd.
Customization scope
Free report customization (equivalent up to 8 analysts working days) with purchase. Addition or alteration to country, regional & segment scope.
Pricing and purchase options
Avail customized purchase options to meet your exact research needs. Explore purchase options
Global BCG Vaccine Market Report Segmentation
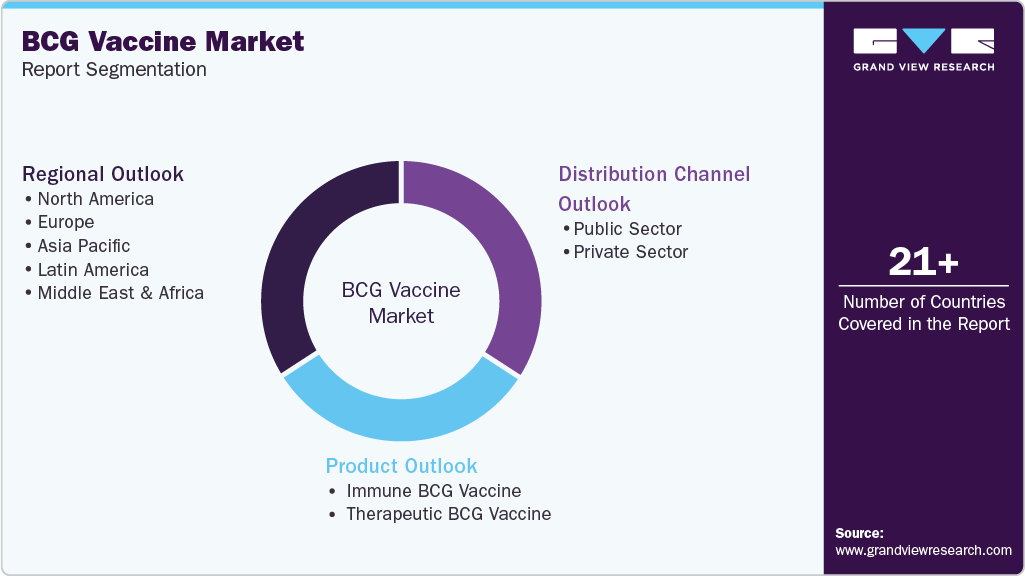
This report forecasts revenue growth at global, regional, and country levels and provides an analysis of the latest industry trends in each of the sub-segments from 2021 to 2033. For this study, Grand View Research has segmented the global BCG vaccine market report based on product, distribution channel, and region:
 To learn more about this report, Download Free Sample Report
-
Product Outlook (Revenue, USD Million, 2021 - 2033)
-
Immune BCG Vaccine
-
Therapeutic BCG Vaccine
-
-
Distribution Channel Outlook (Revenue, USD Million, 2021 - 2033)
-
Public Sector
-
Private Sector
-
-
Regional Outlook (Revenue, USD Million, 2021 - 2033)
-
North America
-
U.S.
-
Canada
-
Mexico
-
-
Europe
-
UK
-
Germany
-
France
-
Italy
-
Spain
-
Denmark
-
Sweden
-
Norway
-
-
Asia Pacific
-
Japan
-
China
-
India
-
Australia
-
South Korea
-
Thailand
-
-
Latin America
-
Brazil
-
Argentina
-
-
Middle East & Africa
-
South Africa
-
Saudi Arabia
-
UAE
-
Kuwait
-
-
Research Methodology
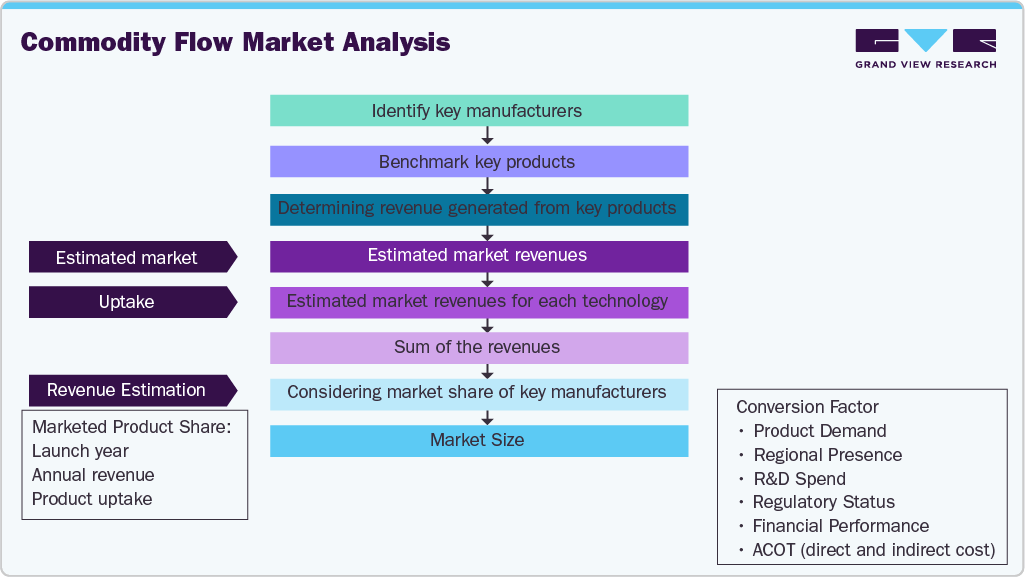
The BCG vaccine market was estimated using a commodity flow and revenue-based approach. The study identified key manufacturers producing BCG vaccines for tuberculosis immunization and bladder cancer treatment and benchmarked their product portfolios, manufacturing capacity, pricing, geographic presence, and distribution channels. Revenue generated from key BCG vaccine products was assessed using company annual reports, regulatory filings, investor presentations, procurement records, government immunization data, UNICEF and PAHO supply information, and public health publications. Product-level revenues were aggregated to estimate the existing market and validated by analyzing procurement volumes, vaccination coverage, bladder cancer treatment demand, manufacturing output, and regional supply trends. Market estimates were further verified through primary interviews with vaccine manufacturers, distributors, healthcare professionals, procurement agencies, and industry experts. Data triangulation and regional validation were applied to produce consistent market size estimates across major countries and regions.
Segment Definition
Segment - Product Type
Revenue capture definition
Immune BCG Vaccine
Includes BCG vaccine products used for the prevention of tuberculosis through active immunization. The segment covers vaccines supplied for routine immunization programs and other approved preventive vaccination initiatives across public and private healthcare systems.
Therapeutic BCG Vaccine
Includes BCG vaccine products used as intravesical immunotherapy for the treatment of non-muscle invasive bladder cancer. The segment covers approved therapeutic BCG formulations administered as part of bladder cancer management in healthcare facilities.
Segment - Distribution Channel
Revenue capture definition
Public Sector
Includes BCG vaccines procured and distributed through government health departments, national immunization programs, public hospitals, and international procurement agencies. The segment covers vaccines supplied under publicly funded healthcare initiatives for disease prevention and approved therapeutic use.
Private Sector
Includes BCG vaccines supplied through private hospitals, private clinics, specialty cancer centers, and private healthcare providers. The segment covers vaccines purchased directly by private healthcare institutions or patients for approved preventive or therapeutic indications outside government procurement programs.
 To learn more about this report, Download Free Sample Report
Delivered Customizations
This report has been delivered with the following In-depth customizations
Client Request
Customization Delivered
Value Adds
Global BCG Vaccine Market Opportunity Assessment (North America, Europe, Asia Pacific & Emerging Markets)
Conducted a detailed assessment of BCG vaccine demand across major and emerging markets, covering tuberculosis immunization programs, bladder cancer treatment, vaccination coverage, manufacturing capacity, procurement models, regulatory framework, pricing trends, and distribution channels. The study also evaluated country-level supply dynamics, public health initiatives, and manufacturer presence to identify growth opportunities across different regions.
Helped the client identify priority markets for expansion, assess procurement opportunities, evaluate manufacturing capacity requirements, and understand regional demand patterns. The study supported production planning, market entry decisions, supply chain optimization, and long-term investment strategies across public immunization and oncology segments.
BCG Vaccine Manufacturing & Competitive Benchmarking Study
Delivered a comprehensive benchmarking assessment of global BCG vaccine manufacturers, covering production capacity, manufacturing technologies, product portfolio, regulatory approvals, supply agreements, distribution networks, pricing strategies, and competitive positioning. The analysis also reviewed manufacturing constraints, capacity expansion plans, and procurement participation across key regions.
Enabled the client to compare competitor capabilities, identify manufacturing gaps, evaluate partnership opportunities, and understand supplier positioning. The study supported manufacturing expansion planning, sourcing decisions, competitive intelligence, and long-term business strategy in the BCG vaccine market.
Emerging Market BCG Vaccine Supply Chain & Procurement Assessment
Conducted a country-level assessment of BCG vaccine procurement and supply chain dynamics across Asia, Latin America, the Middle East, and Africa. The study analyzed government procurement practices, distribution infrastructure, healthcare access, cold chain capabilities, import dependency, local manufacturing, and regulatory requirements affecting vaccine availability.
Supported strategic planning by identifying supply chain gaps, procurement opportunities, regional manufacturing potential, and distribution challenges. The assessment helped improve market prioritization, strengthen supply planning, support regional expansion strategies, and optimize vaccine availability across developing healthcare markets.
Frequently Asked Questions About This Report
The global BCG vaccine market size was valued at USD 181.8 million in 2025 and is estimated at USD 190.3 million for 2026.
The global BCG vaccine market is expected to grow at a CAGR of 5.4% from 2026 to 2033, reaching USD 275.5 million by 2033.
Key factors include continued government immunization programs for tuberculosis prevention, increasing use of BCG in the treatment of non-muscle invasive bladder cancer, support from organizations such as WHO, UNICEF, and Gavi, expanding manufacturing capacity, and ongoing research into BCG-based oncology applications.
Asia Pacific dominated the global BCG vaccine market with a 47.8% revenue share in 2025, supported by a large birth population, high tuberculosis burden, routine childhood immunization programs, and the presence of leading vaccine manufacturers.
North America is projected to be the fastest-growing regional market over the forecast period.
Key players include Merck & Co., Inc., Serum Institute of India Pvt. Ltd., Japan BCG Laboratory, AJ Vaccines A/S, China National Biotec Group (CNBG), GreenSignal Bio Pharma Ltd., InterVax Ltd., BioFarma, Biomed-Lublin S.A., and BB-NCIPD Ltd.
The immune BCG vaccine segment led the market with a 75.3% revenue share in 2025, while the therapeutic BCG vaccine segment is expected to register the fastest growth during the forecast period.
The public sector accounted for the largest share of 77.9% in 2025, while the private sector is projected to be the fastest-growing distribution channel through 2033.
About the Author(s)
Pharmaceuticals Research Team
Healthcare · PharmaceuticalsThis report was authored by the pharmaceuticals research team at Grand View Research - comprising two research analysts, one senior research analyst, and one industry expert - with specialized expertise in the pharmaceuticals segment of the healthcare industry. All findings are based on proprietary healthcare databases, executive interviews, and regulatory analysis, subject to internal peer review prior to publication.
Last Updated:
Speak to Analyst

Customize this report to your needs - add regions, segments, or data points, with 20% free customization.
Or view our licence options:


ISO 9001:2015 & 27001:2022 Certified
We are GDPR and CCPA compliant! Your transaction & personal information is safe and secure. For more details, please read our privacy policy.


