
- Home
- »
- Clinical Diagnostics
- »
-
Blood Culture Test Market Size & Share Report, 2026-2033GVR Report cover

Blood Culture Test Market (2026 - 2033)
Size, Share & Trends Analysis Report By Product (Consumables, Instruments, Software & Services), By Technique (Conventional, Automated), By Application (Fungal Infections), By Technology, By End-use, By Region, And Segment Forecasts
Market Size, 2025
$7.3BMarket Estimate, 2026
$8.2BMarket Forecast, 2033
$19.4BCAGR, 2026–2033
13.0%Blood Culture Test Market Size & Trends
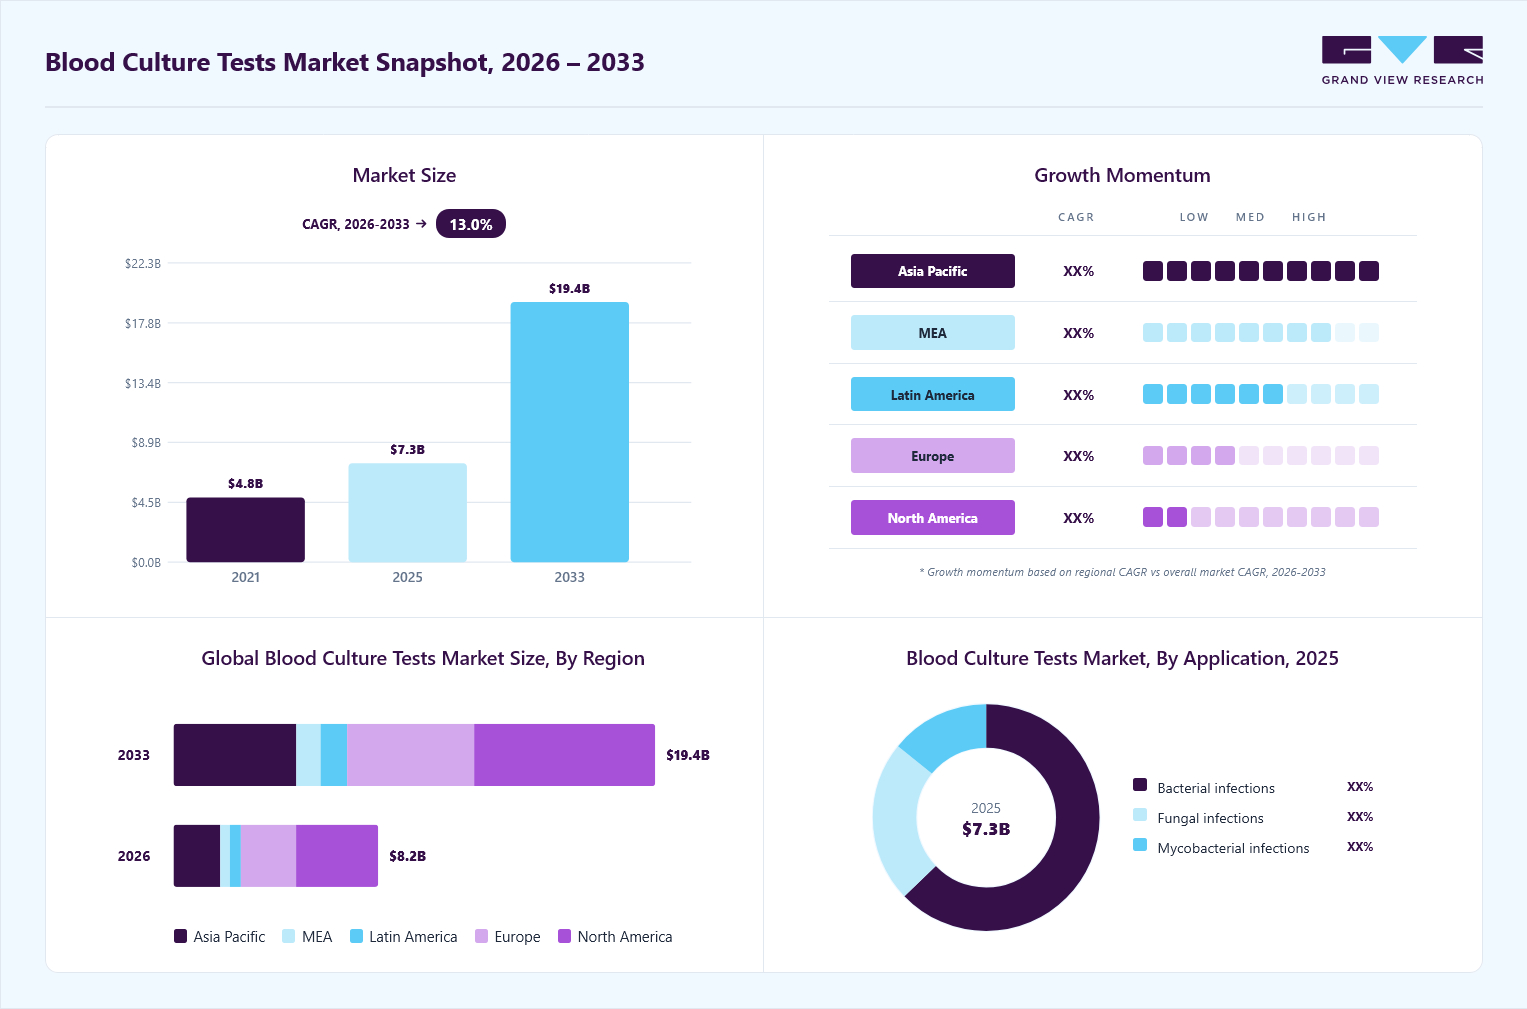
The global blood culture test market size was valued at USD 7.3 billion in 2025 and is projected to grow from USD 8.2 billion in 2026 to USD 19.4 billion by 2033, at a CAGR of 13.0% from 2026 to 2033. North America dominated the market with the largest revenue share of 40.5% in 2025. Increasing approval of novel products by regulatory bodies for bloodstream infection (BSI) diagnosis and increasing prevalence of BSIs are some of the major factors expected to drive market growth.
 Source: Grand View Research, IR Documents, Primary Interviews, Paid DatabasesTo learn more about this report,
 Download Free Sample Report
Key Market Trends & Insights
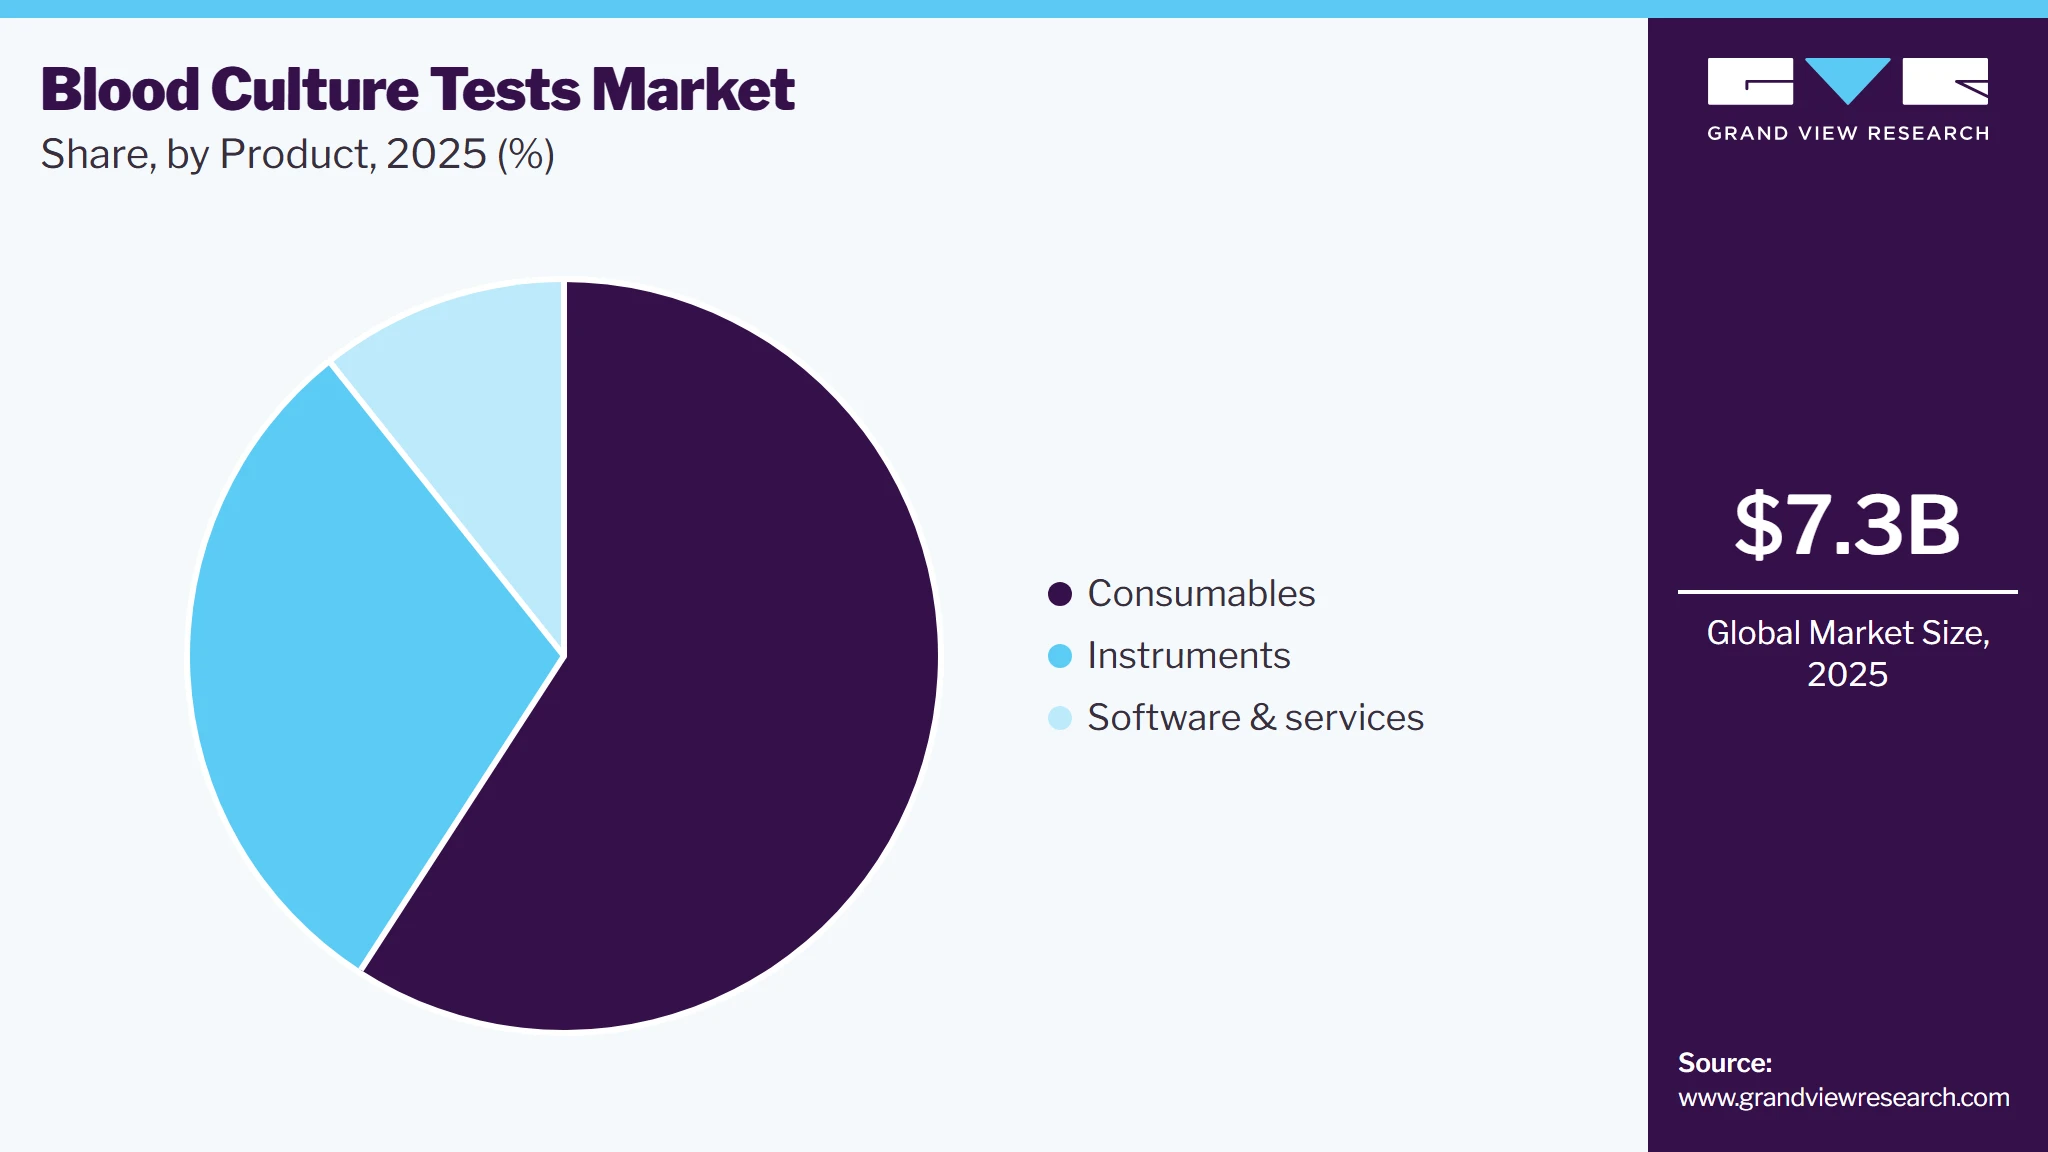
- By product: Consumables segment held the largest share of 59.1% in 2025.
- By technique: Conventional blood culture technique segment held the largest share of 63.9% in 2025.
- By technology: Culture-based technology segment dominated the market with a share of 67.1% in 2025.
- By application: Bacterial infections application segment held the largest share of 69.6% in 2025.
- By end-use: Hospitals and diagnostic laboratories segment led the market with the largest revenue share of 70.2% in 2025.
Regional Highlights
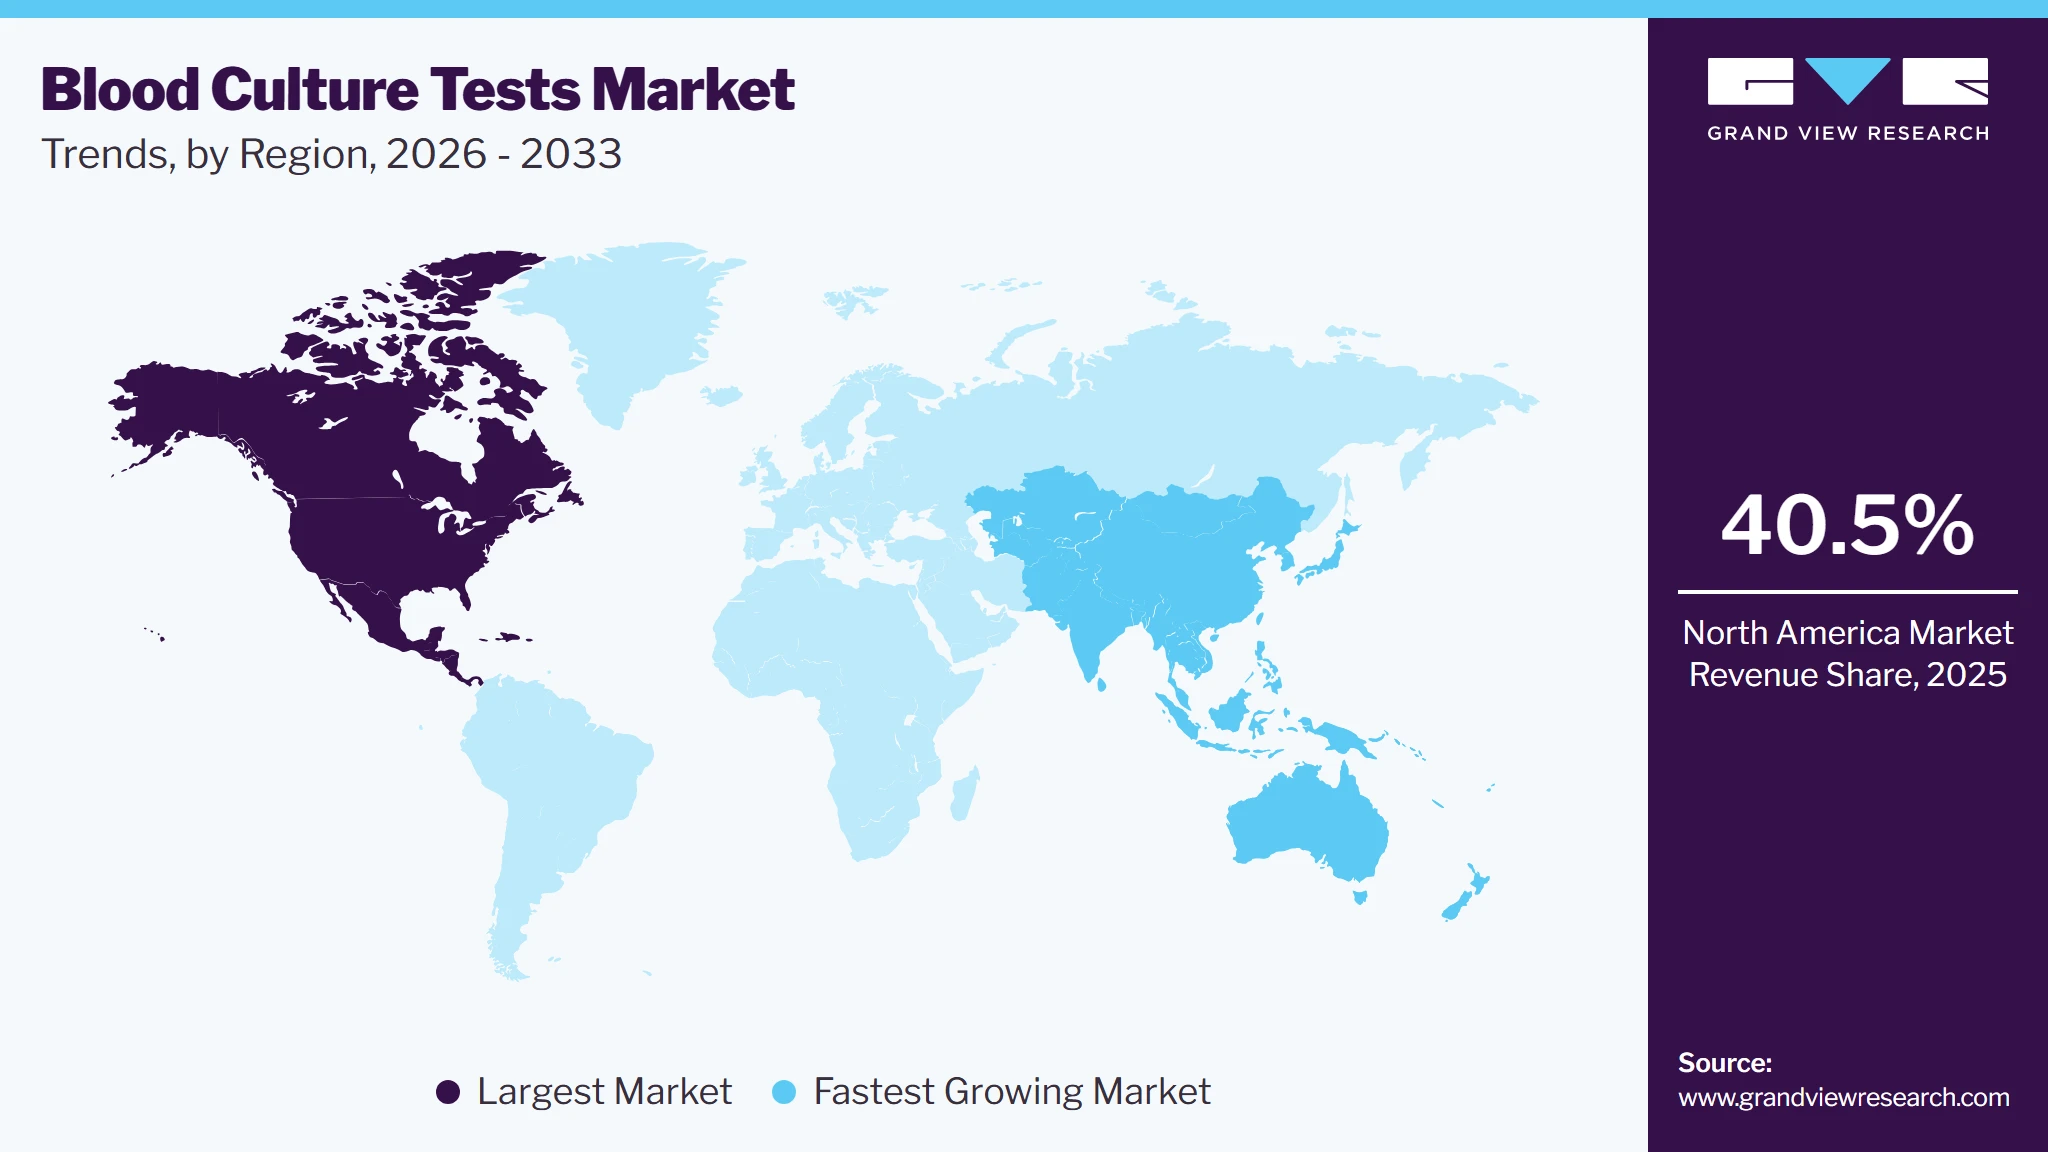
- Largest regional market: North America (40.5% revenue share, 2025)
- Fastest-growing regional market: Asia Pacific (highest CAGR, 2026-2033)
- By country: The blood culture test market in the U.S. held the largest share in the North America region in 2025.
Market Size & Forecast
- Market Size in 2025: USD 7.3 Billion
- Estimated Market Size in 2026: USD 8.2 Billion
- Projected Market Size by 2033: USD 19.4 Billion
- CAGR (2026-2033): 13.0%
Three ways to get this report
Buy it, customize it, or ask a question.Ask an Analyst
Analyst response in 1 business day
- AccessReport author, directly
- Reply timeWithin 1 working day
- No sales callDirect answer only
- FormatEmail reply
- CostFree, no cost
Get the Full Report
What the study covers
- FormatsPDF · Excel · Dashboard
- Timeline2026–2033 annual, 2025 base
- Coverage20+ countries, 5 regions
- Companies10+ key players profiled
Customize the Report
20% free customization
- IncludeCountries, segments, points
- TailorTo your product definition
- ExtendDeeper competitor detail
- OrA fully bespoke study
- Turnaround5–10 working days
Sepsis is a type of BSI and according to a study published by NIH in 2023, around 1.7 million people in the U.S. sufferfrom sepsis each year. Moreover, according to the World Health Organization, around 250,000 cases of BSI occur in the U.S. each year. As a result, advanced products for detecting mycobacterial infections, fungal, and bacterial are in high demand in hospitals and clinical diagnostics laboratories. Furthermore, according to data published by the World Health Organization in 2023, globally, 1 out of 6 people suffering from bacterial meningitis die each year. In addition, occurrence of bacterial meningitis is substantial in sub-Saharan Africa. A recent outbreak of COVID-19 witnessed massive demand for blood culture tests to analyze specimens. As the percentage of COVID-19 infections in 2021 and 2022 rose worldwide, government agencies actively engaged to procure blood culture tests. These factors positively impacted the blood culture tests market growth during the pandemic.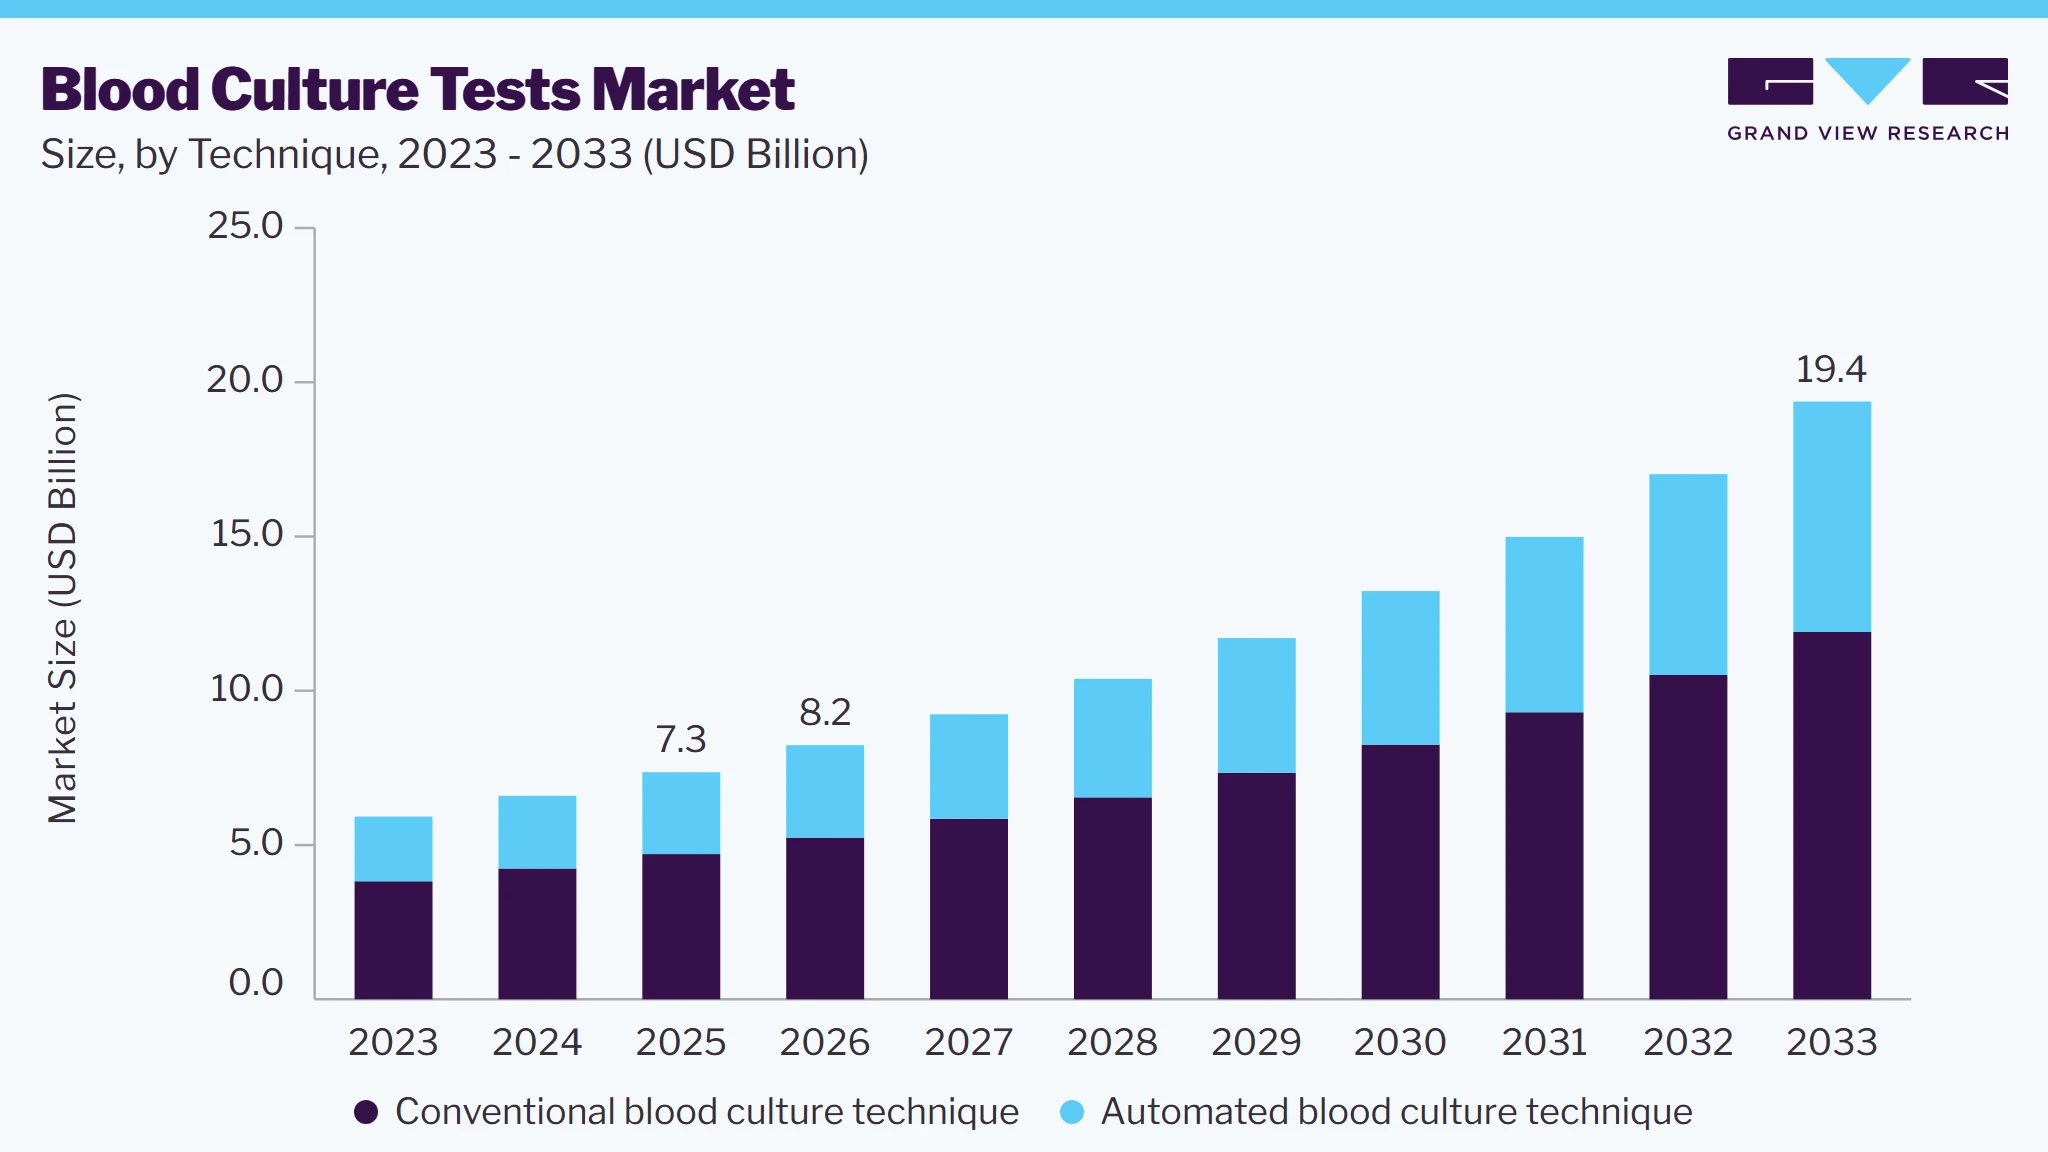 To learn more about this report, Download Free Sample Report
In addition, new product launches and collaborations among market players also played a major role in market growth. For instance, in September 2023, BD collaborated with Navigate BioPharma Services, Inc. This collaboration is expected to allow both companies to develop and commercialize new blood culture tests more quickly. A considerable number of market players are focusing on R&D investments to advance their product capabilities. Vendors' investment in R&D for development of novel products is a critical strategy for long-term growth of their businesses.
Healthcare-associated infections are increasing, and it is a key driver for the bloodstream infection market. COVID-19 had a positive impact on the bloodstream infection market in North America. Due to the pandemic, there is increased demand for self-care options. BD and Abbott are key players operating in the bloodstream infection market. Intellectual property protection and FDA regulations are major barriers for new and emerging players in the bloodstream infection market of North America. Development of technology is a current trend taking place in this market. More accurate results are the scope for improvement for bloodstream infection products available in the market. Bloodstream infection diseases can be claimed in insurance, but it depends on insurance policy norms and company
Market Dynamics
The blood culture test market is experiencing steady expansion driven by the increasing burden of bloodstream infections, sepsis, hospital acquired infections, and antimicrobial resistance worldwide. Rising emphasis on early and accurate pathogen identification is driving the adoption of blood culture testing across hospitals, diagnostic laboratories, and critical care settings, as timely diagnosis supports appropriate treatment decisions and improves patient outcomes. The market is also benefiting from the growing adoption of automated blood culture systems that enhance laboratory productivity, improve detection efficiency, and reduce turnaround times. A notable industry development highlights the ongoing focus on technological advancement and workflow optimization. For instance, in 2025, bioMérieux continued expanding the utilization of its BACT/ALERT automated blood culture platform, while industry participants increased investments in automation technologies and rapid microbial detection solutions to strengthen sepsis management capabilities. Furthermore, expanding healthcare infrastructure, increasing infection surveillance initiatives, and growing investments in diagnostic services across emerging economies are supporting market expansion, although contamination concerns and reimbursement limitations continue to influence market adoption.
The rising prevalence of sepsis and bloodstream infections is a significant factor driving growth in the blood culture test market. Blood culture testing remains a critical diagnostic tool for identifying causative pathogens and supporting targeted antimicrobial therapy, making it an essential component of infection management protocols. Increasing hospital admissions, intensive care utilization, surgical procedures, and the growing population of immunocompromised patients have heightened the demand for accurate and timely diagnostic testing. The clinical burden of sepsis continues to create substantial demand for blood culture testing. According to the report published by U.S. Centers for Disease Control and Prevention in March 2026, at least 1.7 million adults in the United States develop sepsis annually, and more than 350,000 patients die during hospitalization or are discharged to hospice care due to the condition. The World Health Organization reports that sepsis affects approximately 49 million people and causes 11 million deaths each year. Furthermore, industry innovation continues to enhance diagnostic capabilities. For instance, in January 2025, bioMerieux received U.S. FDA clearance for its VITEK REVEAL rapid antimicrobial susceptibility testing solution, supporting faster clinical decision making for bloodstream infections. Growing emphasis on early diagnosis, infection surveillance, and antimicrobial stewardship is expected to support continued market expansion.
Blood culture contamination and the time required to obtain definitive results remain significant challenges affecting the growth of the blood culture test market. Contaminated blood culture samples can result in false positive outcomes, leading to unnecessary antibiotic use, additional diagnostic investigations, prolonged hospital stays, and increased healthcare expenditures. Variability in specimen collection techniques, inadequate skin antisepsis practices, and inconsistencies in laboratory protocols continue to contribute to contamination rates across healthcare settings. Furthermore, conventional blood culture methods typically require extended incubation periods before pathogen identification and antimicrobial susceptibility results become available, potentially delaying appropriate treatment decisions for critically ill patients. These limitations can affect clinical workflow efficiency and increase the burden on healthcare resources. Although advancements in automation and laboratory standardization are improving diagnostic performance, contamination concerns and prolonged turnaround times remain persistent operational challenges. As healthcare providers increasingly focus on cost containment and rapid clinical decision making, these factors continue to influence the adoption and utilization of blood culture testing across various healthcare environments.
The increasing adoption of automated blood culture systems and rapid microbial identification technologies is creating significant growth opportunities for the blood culture test market. Healthcare providers are investing in laboratory automation to enhance operational efficiency, streamline microbiology workflows, and reduce diagnostic turnaround times. The integration of advanced diagnostic technologies enables earlier pathogen detection, supporting timely clinical decision making and more effective antimicrobial therapy selection. Demand for rapid diagnostic solutions is particularly increasing in critical care settings where prompt identification of bloodstream infections is essential for effective sepsis management and improved patient outcomes. In addition, expanding healthcare infrastructure and laboratory modernization initiatives across emerging economies are supporting the adoption of advanced blood culture testing platforms. Recent industry developments further underscore this opportunity. For instance, in May 2025, bioMérieux received U.S. FDA clearance for the VITEK REVEAL Rapid Antimicrobial Susceptibility Testing system, enabling laboratories to deliver antimicrobial susceptibility results directly from positive blood cultures in significantly less time than conventional methods. advancements are strengthening sepsis management programs, improving laboratory efficiency, and supporting the broader adoption of automated blood culture testing workflows across healthcare facilities.
Analyst Perspective
The blood culture testing market is expected to witness steady growth, driven by the rising prevalence of bloodstream infections, sepsis, hospital-acquired infections, and antimicrobial resistance globally. Increasing demand for rapid and accurate pathogen identification is accelerating the adoption of automated blood culture systems, molecular diagnostics, and workflow-integrated laboratory solutions. Market participants are increasingly focusing on technological advancements to improve diagnostic accuracy, reduce turnaround time, and minimize false positives. In addition, growing healthcare expenditure, expansion of clinical laboratory infrastructure, and increasing awareness regarding early infection diagnosis are expected to support long-term market expansion.
Product Insights
Based on product, the consumables segment led the market with the largest revenue share of 59.1% in 2025. Growing number of blood culture tests, rising incidence of infectious diseases, and growing awareness about the benefits of the procedure are major factors responsible for market dominance. Technological advancements and existing product enhancements are anticipated to offer a favorable environment for segment growth. For instance, in February 2022, Kurin, Inc. announced launch of its proprietarypush-button needle system for advanced safety.
 To learn more about this report, Download Free Sample Report
Software systems are developed to eliminate any false positives during the process, which ultimately results in wrong diagnosis. Incorrect diagnosis substantially increases healthcare costs and may result in fatalities due to wrongly prescribed medications. These are also used to determine the degree of relatedness between various strains analyzed, providing highly reproducible and discriminatory data. Thus, software systems have become an integral part of automated blood culture systems, expected to witness lucrative growth over the forecast period.
Technique Insights
Based on technique, the conventional blood culture technique segment led the market with the largest revenue share of 63.9% in 2025. The conventional blood culture technique segment held the largest share of 64.78% in 2023 of the blood culture tests market due to its extensive use in hospitals, pathology laboratories, and clinical laboratories. Furthermore, an increasing number of research & development activities to develop efficient blood culture tests is expected to drive market growth. For instance, in December 2022, a collaborative research work conducted by the Great Ormond Street Institute of Child Health (GOSH) and Wyss Institute for Biologically announced successful results of their reengineered procedures for identification of pathogens associated with pediatric sepsis.
The automated blood culture technique segment is estimated to register the fastest growth rate during the forecast period. Key companies majorly focus on the launch of advanced instruments and consumables to provide highly efficient and reliable tests to their customers. For instance, in January 2023, QIAGEN launched the EZ2 Connect MDx platform. This platform is designed for automated sample processing in diagnostic labs, making the whole process more efficient.
Technology Insights
Based on technology, the culture-based technology segment led the market with the largest revenue share of 67.1% in 2025, attributable to enhanced capabilities of this technology for pathogen detection. In addition, increasing prevalence of infectious diseases and growing research & development investments in developing countries are expected to boost the segment growth. High usage of this technology in various end-use locations, such as hospitals, physician office laboratories, reference, and, pathology is further expected to drive segment growth.
The molecular technology segment is expected to register the highest CAGR during the forecast period. Molecular technologies such as blood cultures and nucleic acid amplification & probe tests have significantly improved the accuracy and speed of results and turnaround time in BSIs. Novel paradigms for rapid BSI diagnosis such as automated AST from positive blood culture bottles manufactured by Accelerate Diagnostics and direct from peripheral blood pathogen detection manufactured by T2 Biosystems with an expected turnaround time of less than 6 hours. The approval of these tests is expected to produce more informative, cheaper, and faster results to help manage BSI.
Application Insights
Based on applications, the bacterial infections segment led the market with the largest revenue share of 69.6% in 2025 and is estimated to grow at a highest CAGR over the forecast period majorly attributed to increasing cases of bacterial infections, globally. Strategic partnerships among market players to launch new products & technologies are also projected to accelerate segment growth. For instance, in April 2023, bioMerieux partnered with Oxford Nanopore Technologies plc. The partnership is expected to develop new faster, more accurate, and easier-to-use blood culture tests, which improve the diagnosis and treatment of infectious diseases.
The fungal infections segment is anticipated to witness significant growth over the coming years due to prevalence of BSIs and rising number of sepsis cases worldwide. For instance, Candida species are predominant agents of fungal sepsis, which accounts for around 10% to 15% of healthcare-related infections.
End-use Insights
Based on end-use, the hospitals and diagnostic laboratories segment led the market with the largest revenue share of 70.2% in 2025 owing to an increasing rate of hospitalizations and growing cases of Hospital-acquired Infections (HAIs). According to an article published by WHO in 2022, 7 patients and 15 patients out of every 100 patients in an acute-care hospital setting in high-income and low & middle-income countries respectively, will acquire at least one HAI at the time of their stay in hospital. Typically, in such settings, prompt detection allows the physicians to plan a proper treatment regimen for the patient. In underdeveloped and developing countries, which lack access to rapid diagnostic tests, hospitals serve as primary testing facilities.
The reference laboratory segment is anticipated to witness the fastest CAGR during the forecast period. Reference laboratories are often listed by insurance companies for specific tests, requiring patients to provide samples for testing. With an increase in incidence of infectious diseases, volume of blood culture tests has also increased causing a spur in the growth of reference laboratories segment.These laboratories operate privately and are engaged in a high volume of routine and specialty testing. These facilities have several advantages, such as they provide fast results (approximately 3-4 hours); are highly sensitive, specific, scalable, & cost-efficient; and facilitate the testing of many sample types.
Regional Insights
North America dominated the blood culture test market with the largest revenue share of 40.5% in 2025 attributable to a well-established clinical diagnostics industry, presence of several key players, availability of government-funded programs, reimbursement structure, awareness initiatives, and new product launches. For instance, in February 2023, BARDA received FDA Approval for the Selux NGP System in partnership with Selux Diagnostics, Inc. The system is designed to allow testing directly from positive blood cultures, which helps to reduce the total test time from 36 hours to 16 hours from whole blood collection.
 To learn more about this report, Download Free Sample Report
U.S. Blood Culture Test Market Trends
The blood culture test market in the U.S. held the largest share in the North America region in 2025.
Asia Pacific Blood Culture Test Market Trends
Asia Pacific is anticipated to witness the highest CAGR during the forecast period owing to an increase in number of hospitalizations, and rising cases of various diseases such as urinary tract infections, bloodstream infections, & ventilator-associated pneumonia. Several key players are geographically expanding into Asian countries such as China and India due to high unmet needs, growing opportunities to gain a higher share in the market, and the presence of the target population.
Key Blood Culture Test Company Insights
Key players in the blood culture tests market are focusing on various strategies to consolidate their position in the market and gain a higher share,
-
In March 2023, T2 Biosystems, Inc. announced its plan to add Candida Auris detection technology to its existing T2Candida panel. The company has already received FDA and CE approval for its T2Candida panel.
-
In April 2023, Bruker Corporation introduced MALDI Biotyper IVD Software. The new software provides a high sample throughput for microbial identification. The software is used in a variety of clinical settings, including hospitals, clinics, and reference laboratories.
Key Blood Culture Test Companies
-
BD
-
Terumo Corporation
-
Bruker Corporation
-
bioMerieux
-
T2 Biosystems Inc.
-
Luminex Corporation
-
Abbott Laboratories
-
Siemens Healthineers AG
-
Danaher Corporation
-
F. Hoffmann-La Roche Ltd.
Competitive Benchmarking
Operating Strategies
Competitive Edge
Weaknesses
Established Players (BD, Terumo Corporation, Bruker Corporation, bioMérieux, Luminex Corporation)
- Focus on expanding automated blood culture systems, molecular diagnostics, and rapid microbial identification technologies.
- Invest in strategic collaborations, acquisitions, FDA approvals, and AI-enabled laboratory automation.
- Strengthen global distribution networks and high-throughput diagnostic capabilities
- Strong brand presence and established relationships with hospitals and diagnostic laboratories.
- Advanced R&D capabilities and broad infectious disease diagnostic portfolios.
- Ability to provide integrated, automated, and rapid testing solutions globally
- High capital investment and operational costs associated with advanced diagnostic technologies.
- Complex regulatory approval processes and reimbursement challenges.
- Dependence on continuous technological innovation to maintain market leadership
Emerging and Specialized Players (T2 Biosystems Inc.)
- Focus on niche molecular diagnostics, rapid sepsis detection, and cost-effective testing technologies.
- Develop innovative microbial identification platforms and portable diagnostic solutions.
- Expand market presence through partnerships with hospitals, laboratories, and research institutions
- Faster adoption of emerging technologies and operational flexibility.
- Ability to target underserved healthcare settings with specialized solutions.
- Competitive pricing and innovation-driven product development strategies
- Limited global distribution and lower brand recognition.
- Restricted financial resources for large-scale expansion and R&D investments.
- Challenges related to regulatory approvals, scalability, and commercialization
Recent Developments
-
In April 2026, Waters Corporation announced the CE marking of the BD BACTEC™ FXI Culture System, a next-generation, fully automated blood culture system designed for bloodstream infection diagnosis. The system delivers approximately three hours faster time to detection compared with the previous-generation BD BACTEC FX system and incorporates automated blood-volume measurement, vial loading, unloading, incubation, and detection capabilities.
Blood Culture Test Market Report Scope
Report Attribute
Details
Market size value in 2025
USD 7.3 billion
Estimated Market Size in 2026
USD 8.2 billion
Projected Market Size by 2033
USD 19.4 billion
Growth rate
CAGR of 13.0% from 2026 to 2033
Historical data
2021 - 2024
Forecast period
2026 - 2033
Quantitative units
Revenue in USD million/billion and CAGR from 2026 to 2033
Report coverage
Revenue forecast, company ranking, competitive landscape, growth factors, and trends
Segments covered
Product, application, technique, technology, end-use, region
Regional scope
North America; Europe; Asia Pacific; Latin America; MEA
Country scope
U.S.; Canada; Mexico; Germany; UK; France; Italy; Spain; Norway; Denmark; Sweden; Rest of Europe; China; Japan; India; South Korea; Australia; Thailand; Rest of Asia Pacific; Brazil; Argentina; Rest of LATAM; Saudi Arabia; South Africa; UAE; Kuwait; Rest of MEA
Key companies profiled
BD; Terumo Corp.; bioMerieux; Bruker Corp.; T2 Biosystems Inc.; Abbott Laboratories; Luminex Corp.; Siemens Healthineers AG; F. Hoffmann-La Roche Ltd.; Danaher Corp.
Customization scope
Free report customization (equivalent up to 8 analysts' working days) with purchase. Addition or alteration to country, regional & segment scope.
Pricing and purchase options
Avail customized purchase options to meet your exact research needs. Explore purchase options
Global Blood Culture Test Market Report Segmentation
This report forecasts revenue growth at global, regional, and country levels and provides an analysis of the latest trends in each of the sub-segments from 2021 to 2033. For this study, Grand View Research has segmented the global blood culture test market report based on product, technique, technology, application, end-user, and region:
-
Product Outlook (Revenue, USD Billion, 2021 - 2033)
-
Consumables
-
By Type
-
Bacterial Infections
-
Fungal Infections
-
Mycobacterial Infections
-
-
By Components
-
Blood Culture Media
-
Aerobic
-
Anaerobic
-
Fungi/Yeast
-
Others
-
-
Assay, Kits, and Reagents
-
Blood Culture Accessories
-
-
-
Instruments
-
By Type
-
Bacterial Infections
-
Fungal Infections
-
Mycobacterial Infections
-
-
By Components
-
Laboratory Equipment
-
Incubators
-
Colony Counters
-
Microscopes
-
Gram Stainers
-
-
Automated Blood Culture Systems
-
-
-
Software & Services
-
Bacterial Infections
-
Fungal Infections
-
Mycobacterial Infections
-
-
-
Technique Outlook (Revenue, USD Billion, 2021 - 2033)
-
Conventional
-
Automated
-
-
Technology Outlook (Revenue, USD Billion, 2021 - 2033)
-
Culture-based Technology
-
Molecular Technology
-
PCR
-
Microarray
-
PNA-FISH
-
-
Proteomic Technology
-
-
Application Outlook (Revenue, USD Billion, 2021 - 2033)
-
Bacterial Infections
-
Fungal Infections
-
Mycobacterial Infections
-
-
End-use Outlook (Revenue, USD Billion, 2021 - 2033)
-
Hospital Laboratories
-
Reference Laboratories
-
Others
-
-
Regional Outlook (Revenue, USD Billion, 2021 - 2033)
-
North America
-
U.S.
-
Canada
-
Mexico
-
-
Europe
-
Germany
-
UK
-
France
-
Italy
-
Spain
-
Sweden
-
Denmark
-
Norway
-
Rest of Europe
-
-
Asia Pacific
-
Japan
-
China
-
India
-
South Korea
-
Australia
-
Thailand
-
Rest of Asia Pacific
-
-
Latin America
-
Brazil
-
Argentina
-
Rest of LATAM
-
-
MEA
-
South Africa
-
Saudi Arabia
-
UAE
-
Kuwait
-
Rest of MEA
-
-
Research Methodology
(a) Segment Definition
Segment - Techniques
Revenue capture definition
Conventional Blood Culture Technique
Revenue is generated from manual blood culture procedures, including culture media, consumables, incubators, manual microbial detection, laboratory processing, and associated diagnostic testing in hospitals and laboratories.
Automated Blood Culture Technique
Automated Blood Culture Technique:
Revenue is captured from automated blood culture instruments, culture bottles, reagents, software integration, maintenance services, and rapid microbial detection solutions used in clinical laboratories and hospitals.
Segment - Product
Revenue capture definition
Consumables
Revenue is generated from recurring purchases of blood culture media, assay kits, reagents, culture bottles, test kits, and laboratory accessories used for routine blood culture testing.
Instruments
Revenue is captured from sales of automated blood culture systems, incubators, analyzers, microbial detection platforms, and laboratory equipment used for bloodstream infection diagnosis.
Software & Services
Revenue is derived from laboratory software, workflow management systems, data analytics platforms, maintenance contracts, technical support, training, and diagnostic integration services.
Segment Technology
Revenue capture definition
Culture-based Technology
Revenue is generated from conventional and automated blood culture systems, culture media, consumables, and laboratory processes used for microbial growth detection and pathogen identification.
Molecular Technology
Revenue is captured from PCR-based assays, syndromic panels, nucleic acid amplification tests, reagents, and molecular diagnostic platforms for rapid pathogen and resistance marker detection.
Proteomic Technology Revenue is derived from proteomic platforms, including MALDI-TOF systems, reagents, software, and microbial identification solutions used for protein-based pathogen characterization following blood culture testing.
Segment Application
Revenue capture definition
Bacterial Infections
Revenue is generated from blood culture tests, consumables, and diagnostic solutions used for detecting bacterial pathogens responsible for bloodstream infections, sepsis, and hospital-acquired infections.
Fungal Infections
Revenue is captured from specialized blood culture media, diagnostic assays, and testing solutions used for identifying fungal and yeast-related bloodstream infections, particularly in immunocompromised patients.
Mycobacterial Infections
Revenue is derived from dedicated culture media, molecular assays, and diagnostic systems used for detecting mycobacterial bloodstream infections, including tuberculosis and non-tuberculous mycobacteria
Segment End Use
Revenue capture definition
Hospital Laboratories
Revenue is generated from blood culture testing performed in hospital-based laboratories through the use of diagnostic instruments, consumables, reagents, and microbiology services for infection diagnosis.
Reference Laboratories
Revenue is captured from outsourced blood culture testing, advanced diagnostic services, high-throughput sample processing, and specialized pathogen identification conducted by independent laboratories.
Others
Revenue is derived from blood culture testing conducted in academic research institutes, specialty clinics, ambulatory care centers, and public health laboratories for diagnostic and research purposes.
Delivered Customizations
This report has been delivered with the following In-depth customizations
Client Request
Customization Delivered
Value Adds
Sepsis & Hospital Infection Burden Analysis
Assessment of sepsis prevalence, bloodstream infection rates, ICU admissions, and antimicrobial resistance trends across key regions.
Helps identify high-demand testing areas and supports market opportunity assessment.
Blood Culture Utilization & Testing Volume Analysis
Evaluation of blood culture testing volumes by hospitals, ICUs, emergency departments, and diagnostic laboratories including repeat testing patterns..
Supports demand forecasting and laboratory capacity planning.
Automation & Rapid Pathogen Detection Assessment
Analysis of automated blood culture systems, rapid microbial identification technologies, AST integration, and laboratory workflow modernization trends.
Tracks adoption of faster and more efficient infectious disease diagnostic solutions.
Antimicrobial Resistance (AMR) & Innovation Landscape
Assessment of AMR-focused diagnostics, molecular blood culture technologies, AI-assisted detection systems, and next-generation sepsis testing platforms.
Highlights emerging technologies and growing opportunities linked to global AMR management initiatives.
Frequently Asked Questions About This Report
The global blood culture test market size was estimated at USD 7.3 billion in 2025 and is expected to reach USD 8.2 billion in 2026.
The global blood culture test market is expected to grow at a compound annual growth rate of 13.0% from 2026 to 2033 to reach USD 19.4 billion by 2033.
Consumables dominated the blood culture test market with a share of 59.1% in 2025.
Key factors that are driving the market growth include increasing prevalence of infectious diseases and growing approval rates for new products, such as instruments and consumables for Bloodstream Infections (BSI) diagnosis.
Some key players operating in the blood culture test market include BD; Terumo Corp.; bioMerieux; Bruker Corp.; T2 Biosystems Inc.; Abbott Laboratories; Luminex Corp.; Siemens Healthineers AG; F. Hoffmann-La Roche Ltd.; Danaher Corp.
Asia Pacific is the fastest-growing region over the forecast period
Conventional blood culture technique segment led the market with the largest revenue share of 63.9% in 2025
North America dominated the blood culture test market with a share of 40.5% in 2025, owing to its advanced healthcare infrastructure, high adoption of automated blood culture systems, strong presence of leading diagnostic companies, and increasing incidence of bloodstream infections and sepsis.
Culture-based technology segment dominated the market with a share of 67.1% in 2025.
About the Author(s)
Clinical Diagnostics Research Team
Healthcare · Clinical DiagnosticsThis report was authored by the clinical diagnostics research team at Grand View Research - comprising two research analysts, one senior research analyst, and one industry expert - with specialized expertise in the clinical diagnostics segment of the healthcare industry. All findings are based on proprietary healthcare databases, executive interviews, and regulatory analysis, subject to internal peer review prior to publication.
Last Updated:
Speak to Analyst

Customize this report to your needs - add regions, segments, or data points, with 20% free customization.
Or view our licence options:


ISO 9001:2015 & 27001:2022 Certified
We are GDPR and CCPA compliant! Your transaction & personal information is safe and secure. For more details, please read our privacy policy.


