
- Home
- »
- Specialty Glass, Ceramic & Fiber
- »
-
Carbon Fiber Market Size, Growth Report, 2026-2033GVR Report cover

Carbon Fiber Market (2026 - 2033)
Size, Share & Trends Analysis Report By Raw Material (PAN-Based, Pitch-Based), By Tow Size (Small Tow, Large Tow), By Application (Automotive, Aerospace & Defence, Wind Turbines), By Region, And Segment Forecasts
Market Size, 2025
$6.4BMarket Estimate, 2026
$7.1BMarket Forecast, 2033
$14.6BCAGR, 2026–2033
10.9%Carbon Fiber Market Summary
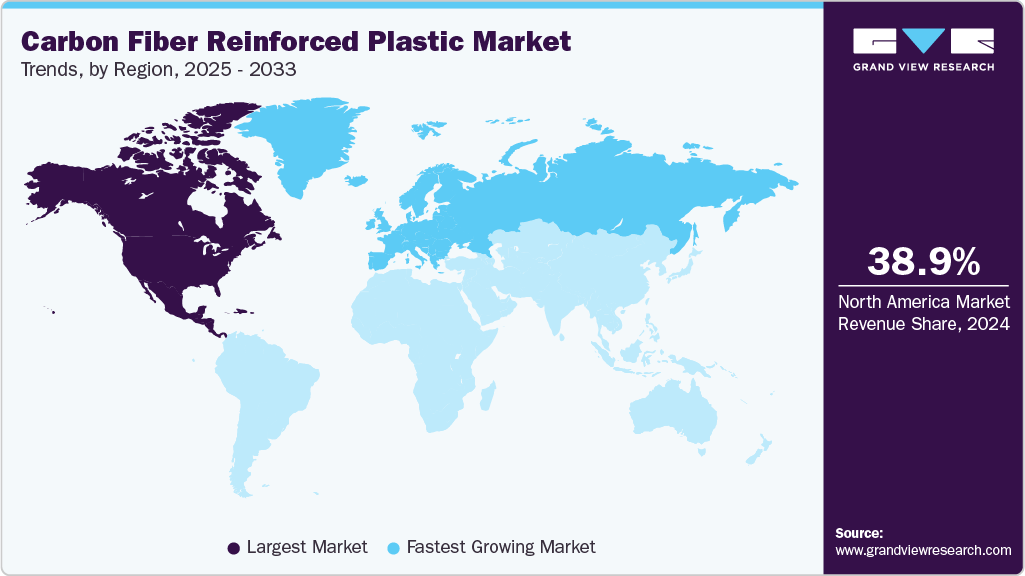
The global Carbon Fiber market size was valued at USD 6.4 billion in 2025 and is projected to grow from USD 7.1 billion in 2026 to USD 14.6 billion by 2033, at a CAGR of 10.9% from 2026 to 2033. Europe dominated the global market, accounting for the largest revenue share of 32.0% in 2025. This growth can be attributed to the rising use of carbon fiber in wind energy applications, driven by the global shift toward renewable energy.
 Source: Grand View Research, IR Documents, Primary Interviews, Paid DatabasesTo learn more about this report,
 Download Free Sample Report
Key Market Trends & Insights
- By raw material: Polyacrylonitrile (PAN) segment accounted for the fastest and largest revenue share of 96.5% in 2025.
- By application: Aerospace & defense segment accounted for the largest revenue share of 32.4% in 2025.
- By tow size: Small tow segment is expected to grow at a CAGR of 11.1% over the forecast period.
Regional Highlights
- Largest regional market: Europe (32% revenue share, 2025)
- By country: The Germany Carbon Fiber industry is a major contributor to the global market.
Market Size & Forecast
- Market size in 2025: USD 6.4 Billion
- Estimated market size in 2026: USD 7.1 Billion
- Projected market size by 2033: USD 14.6 Billion
- CAGR (2026-2033): 10.9%
Three ways to get this report
Buy it, customize it, or ask a question.Ask an Analyst
Analyst response in 1 business day
- AccessReport author, directly
- Reply timeWithin 1 working day
- No sales callDirect answer only
- FormatEmail reply
- CostFree, no cost
Get the Full Report
What the study covers
- FormatsPDF · Excel · Dashboard
- Timeline2026–2033 annual, 2025 base
- Coverage20+ countries, 5 regions
- Companies10+ key players profiled
Customize the Report
20% free customization
- IncludeCountries, segments, points
- TailorTo your product definition
- ExtendDeeper competitor detail
- OrA fully bespoke study
- Turnaround5–10 working days
As countries aim to reduce their dependence on fossil fuels, the demand for wind turbines is increasing, and carbon fiber's strength and durability make it ideal for turbine blades. Carbon fiber allows for longer and more efficient blades that capture more wind energy, thus improving the efficiency of wind farms.Furthermore, the construction and infrastructure industries are recognizing carbon fiber's potential for enhancing the longevity and resilience of structures. In civil engineering, carbon fiber is increasingly used for strengthening and retrofitting bridges, buildings, and other infrastructure, where its corrosion resistance and lightweight nature offer distinct advantages over traditional materials.
 To learn more about this report, Download Free Sample Report
The carbon fiber industry is driven by the material's advantageous properties and strong demand across diverse sectors. One significant driver is the growing need for lightweight and high-strength materials in the automotive and aerospace industries. Carbon fiber is renowned for its high strength-to-weight ratio, which makes it ideal for manufacturing lighter vehicles and aircraft. This results in increased fuel efficiency and reduced emissions, aligning with global efforts to meet sustainability goals and reduce environmental impact. In aerospace, the use of carbon fiber components contributes to reduced fuel consumption and enhanced aircraft performance, making it highly valued for modern aircraft and spacecraft design.
The electronics and sports equipment sectors are also significant contributors to carbon fiber demand. Electronics manufacturers are incorporating carbon fiber into devices to achieve durability while keeping devices lightweight, appealing to consumer preferences for portable and robust products. In sports, carbon fiber is widely used in equipment such as bicycles, tennis rackets, and golf clubs due to its superior strength and flexibility, which enhances performance. Lastly, government incentives and subsidies supporting research and development in advanced materials are fueling innovations in carbon fiber production, helping reduce costs, and improving manufacturing efficiencies. With technological advancements, carbon fiber has become more accessible and affordable, which further drives its adoption across multiple industries.
Raw Material Insights
The PAN segment led the market and accounted for the fastest and largest revenue share of 96.5% in 2025. The automotive industry’s increasing shift toward electric vehicles (EVs) is driving the demand for PAN-based carbon fiber. Manufacturers are using these fibers in vehicle body structures, battery enclosures, and interior components to make EVs lighter and improve battery efficiency, thereby enhancing overall range. This aligns with the broader sustainability goals and regulatory mandates for lower emissions, which many automakers are actively pursuing.
The pitch segment is expected to grow significantly at a 6.9% CAGR in terms of revenue over the forecast period. The industrial sector, including electronics and construction, contributes to the rising demand for pitch-based carbon fiber. In electronics, pitch-based fibers are utilized for heat dissipation in devices where maintaining stable temperatures is critical to performance. Similarly, in the construction industry, these fibers are applied in high-stress environments, such as in reinforced concrete for bridges and buildings. Their strength, rigidity, and resilience to environmental stressors make pitch-based carbon fiber highly sought after for extending infrastructure lifespan.
Application Insights
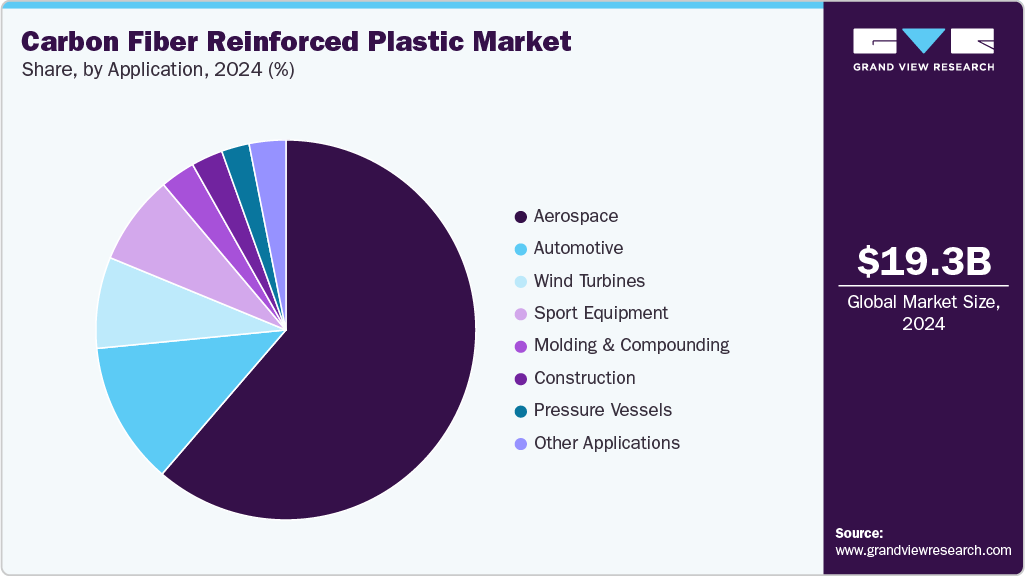
The aerospace & defense segment led the market and accounted for the largest revenue share of 32.4% in 2024. The increased investment in next-generation aircraft and space exploration is driving the demand for carbon fiber in aerospace. As the industry develops advanced aircraft, satellites, and spacecraft, carbon fiber’s properties become essential for achieving the structural integrity and lightness required for long-term missions and extreme environmental conditions. The rise of commercial space ventures, as well as government-led space missions, further strengthens the demand for carbon fiber.
Wind turbine application is expected to grow at the fastest CAGR of 12.3% in terms of revenue over the forecast period. The increasing global emphasis on renewable energy sources to combat climate change and reduce carbon emissions is driving demand for wind energy infrastructure. Carbon fiber is an ideal material for wind turbine blades, offering high strength and lightweight properties that allow for longer, more efficient blades capable of capturing more wind energy.
Tow Size Insights
The small tow led the market and accounted for the largest revenue share of 78% in 2025. Rising adoption in the automotive industry, particularly in luxury and high-performance vehicles where weight reduction and mechanical strength are paramount, is driving the market growth. Small tow carbon fiber is preferred in manufacturing body panels, roof structures, and other parts that benefit from its precise structural properties, ultimately enhancing vehicle speed, fuel economy, and stability. This aligns with the automotive sector's emphasis on sustainability and efficiency, with small tow carbon fiber allowing for significant weight reductions without compromising strength or safety.
 To learn more about this report, Download Free Sample Report
Large tow’s revenue is expected to grow at 10.2% CAGR over the forecast period. The wind energy sector is a major driver for the large tow segment, where the material’s strength and cost-efficiency play a vital role in the production of longer, more durable turbine blades. Large tow carbon fiber enables the manufacturing of these blades at a lower cost per unit, making it more feasible to build and maintain wind farms on a larger scale. Given the global shift toward renewable energy sources, demand for large tow carbon fiber in this sector is expected to continue rising as wind power infrastructure expands globally.
Regional Insights
Europe carbon fiber dominated the market and accounted for 32% of global revenue in 2025. The aerospace industry in Europe also plays a crucial role in boosting the demand for carbon fiber. With the presence of prominent aircraft manufacturers such as Airbus, there is a growing need for high-strength, lightweight materials to improve fuel efficiency and enhance performance. Carbon fiber’s strength-to-weight ratio is particularly valuable for aircraft, enabling longer flight ranges and lower operational costs. Europe’s aerospace sector is heavily invested in research and development, aiming to leverage advanced composites like carbon fiber for next-generation aircraft.
 To learn more about this report, Download Free Sample Report
The carbon fiber industry in Germany is bolstered by the consumer demand for high-quality, durable, and aesthetically appealing products in sports and electronics. In sporting goods, carbon fiber is valued for its lightweight yet robust nature, enhancing performance in products like bicycles, golf clubs, and racquets. In consumer electronics, carbon fiber’s sleek look and strength make it a popular choice for premium device casings and components. As these sectors continue to grow, the demand for carbon fiber is likely to increase alongside them.
The carbon fiber industry in UK is witnessing growth through increased focus on automating manufacturing processes, particularly in industries such as robotics, where carbon fiber’s lightweight and durable nature improves efficiency and productivity. Robots that incorporate carbon fiber components are more agile, reducing energy consumption and increasing precision. As the UK industrial sector continues to invest in automation and robotics, the demand for carbon fiber in these applications is expected to grow.
Asia Pacific Carbon Fiber Market Trends
The Asia Pacific carbon fiber industry is driven by the automotive industry, which acts a major driver of growth, particularly in countries such as Japan, China, and South Korea. As these countries focus on producing lighter and more fuel-efficient vehicles, carbon fiber is becoming a key material in automotive manufacturing. This is especially true for electric vehicles (EVs) where reducing the weight of the vehicle directly impacts range and performance. With the shift towards more sustainable transportation solutions, the automotive sector’s adoption of carbon fiber is increasing rapidly across the region, driven by both government regulations and consumer demand for greener, more energy-efficient vehicles.
The China carbon fiber industry is driven by the pivotal role played by Chinese government in driving the growth. National policies that focus on industrial upgrading, the promotion of sustainable energy, and the support for advanced manufacturing are creating a favorable environment for the use of carbon fiber. In addition, China’s commitment to reducing carbon emissions and improving energy efficiency across industries has encouraged the adoption of carbon fiber in sectors such as automotive, aerospace, and energy. Government subsidies, funding for R&D, and policies aimed at boosting the green economy are all contributing to the growing demand for carbon fiber in the country.
North America Carbon Fiber Market Trends
The carbon fiber industry in North America is anticipated to grow over the forecast period. The automotive sector, particularly in the United States, is undergoing a transformation with a rapid shift toward electric vehicles (EVs) and more fuel-efficient vehicles. Carbon fiber is a critical material in EVs due to its lightweight nature, which helps improve energy efficiency and extends the driving range of electric vehicles. With major automakers like General Motors, Ford, and Tesla leading the way in EV production, the demand for carbon fiber in automotive manufacturing is rising. Furthermore, government policies aimed at reducing carbon emissions and promoting electric transportation are accelerating the adoption of lightweight materials like carbon fiber in vehicle design.
Central and South America Carbon Fiber Market Trends
Central and South America carbon fiber industry is expected to grow at the fastest CAGR of 10.4% over the forecast period. The automotive industry, particularly in countries like Brazil and Mexico, is a key driver of carbon fiber adoption. The demand for lightweight, durable materials in vehicle manufacturing is increasing as automakers work to meet stricter fuel efficiency standards and reduce emissions. Carbon fiber is being used to improve vehicle performance and safety while reducing weight. As the region continues to adopt electric vehicles (EVs) and hybrid vehicles, carbon fiber plays an important role in enhancing the energy efficiency and driving range of these vehicles. Local manufacturers and international automotive giants with plants in the region are likely to drive the growth of carbon fiber used in automotive applications.
Key Carbon Fiber Company Insights
Some of the key players operating in the market include Formosa Plastics Corporation, Jiangsu Hengshen Co. Ltd, and Mitsubishi Chemical Corporation. These companies compete on the basis of fiber performance, production scale, and vertically integrated offerings that span precursor materials, fibers, and prepregs for aerospace, automotive, wind energy, and sporting goods applications. Key strategies include capacity expansions, long-term supply agreements with aerospace OEMs, and investment in lower-cost, recyclable carbon fiber to broaden adoption in high-volume industries.
Key Carbon Fiber Companies:
The following key companies have been profiled for this study on the carbon fiber market.
- A&P Technology Inc.
- Anshan Sinocarb Carbon Fiber Co. Ltd
- DowAksa USA LLC
- Formosa Plastics Corporation
- Hexcel Corporation
- Hyosung Advanced Materials
- Jiangsu Hengshen Co. Ltd
- Mitsubishi Chemical Corporation
- Nippon Graphite Fiber Co. Ltd
- SGL Carbon
- Solvay
- Teijin Limited
- Toray Industries Inc.
- Zhongfu Shenying Carbon Fiber Co. Ltd.
Recent Developments:
- In July 2026, Hexcel Corporation completed NCAMP qualification of its HexPly M91 carbon fiber-reinforced epoxy prepreg system in unidirectional tape and plain-weave fabric forms, supporting its use in primary aerospace structures and other structural applications.
- In December 2025, Mitsubishi Chemical Group announced plans to approximately double its high-performance carbon fiber production capacity through upgrades at its Tokai Plant in Japan and Sacramento Plant in the U.S., with phased enhancements planned for 2025–2027 to address demand from aerospace, sports and leisure, hypercars, and other high-end applications.
Carbon Fiber Market Report Scope
Report Attribute
Details
Market size in 2025
USD 6.4 billion
Estimated Market size in 2026
USD 7.1 billion
Projected Market size by 2033
USD 14.6 billion
Growth rate
CAGR of 10.9% from 2026 to 2033
Base year for estimation
2025
Historical data
2021 - 2024
Forecast period
2026 - 2033
Quantitative units
Volume in Tons, Revenue in USD billion/million, and CAGR from 2026 to 2033
Report coverage
Revenue forecast, company ranking, competitive landscape, growth factors, and trends
Regional Scope
North America; Europe; Asia Pacific; Central & South America; Middle East & Africa
Country scope
U.S.; Canada; Mexico; Germany; UK; France; China; Japan; Taiwan; Brazil
Segments covered
Raw material, tow size, application, region
Key companies profiled
A&P Technology Inc.; Anshan Sinocarb Carbon Fiber Co. Ltd; DowAksa USA LLC; Formosa Plastics Corporation; Hexcel Corporation; Hyosung Advanced Materials; Jiangsu Hengshen Co. Ltd; Mitsubishi Chemical Corporation; Nippon Graphite Fiber Co. Ltd; SGL Carbon; Solvay; Teijin Limited; Toray Industries Inc.; Zhongfu Shenying Carbon Fiber Co. Ltd
Customization scope
Free report customization (equivalent up to 8 analysts working days) with purchase. Addition or alteration to country, regional & segment scope.
Pricing and purchase options
Avail customized purchase options to meet your exact research needs. Explore purchase options
Global Carbon Fiber Market Report Segmentation
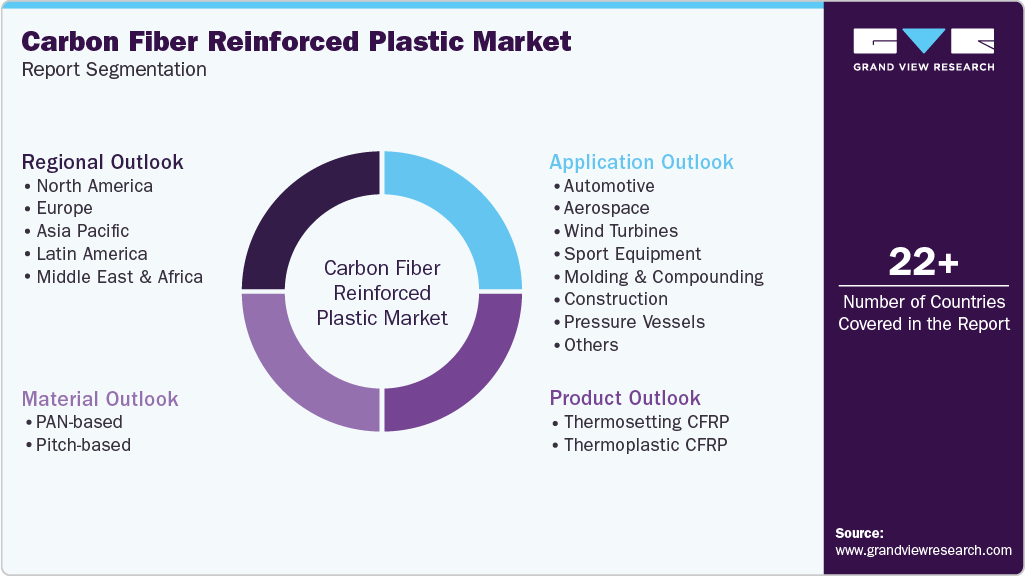
This report forecasts revenue growth at country levels and provides an analysis of the industry trends in each of the sub-segments from 2021 to 2033. For this study, Grand View Research has segmented the global carbon fiber market report based on raw material, tow size, application, and region:
 To learn more about this report, Download Free Sample Report
-
Raw Material Outlook (Volume, Tons; Revenue, USD Million, 2021 - 2033)
-
PAN Based
-
Pitch Based
-
-
Tow Size Outlook (Volume, Tons; Revenue, USD Million, 2021 - 2033)
-
Small Tow
-
Large Tow
-
-
Application Outlook (Volume, Tons; Revenue, USD Million, 2021 - 2033)
-
Automotive
-
Aerospace & Defense
-
Wind Turbines
-
Sports/Leisure
-
Molding & Compounding
-
Construction
-
Pressure Vessels
-
Others
-
-
Regional Outlook (Volume, Tons; Revenue, USD Million, 2021 - 2033)
-
North America
-
U.S.
-
Canada
-
Mexico
-
-
Europe
-
Germany
-
UK
-
France
-
-
Asia Pacific
-
China
-
Japan
-
Taiwan
-
-
Central & South America
-
Brazil
-
-
Middle East & Africa
-
Frequently Asked Questions About This Report
The global carbon fiber market size was valued at USD 6.4 billion in 2025 and is estimated at USD 7.1 billion for 2026.
The global carbon fiber market is expected to grow at a CAGR of 10.9% from 2026 to 2033, reaching USD 14.6 billion by 2033.
The aerospace & defense market accounted for the largest revenue share of 32.4% in 2025 and this is attributed to the growing use of carbon fiber in the industry to cater to growing demand for commercial aircrafts across the world.
The growing automotive development and aerospace & defense sector is propelling the growth for carbon fiber in the market. This is due to the light weightiness of carbon fiber in comparison to its conventional alternatives such as metals and its alloys.
Europe dominated with a 32.0% revenue share in 2025.
The polyacrylonitrile (PAN) segment led with a 96.5% revenue share in 2025.
The small tow segment accounted for the largest revenue share of 78.0% in 2025.
Key players include A&P Technology Inc.; Anshan Sinocarb Carbon Fiber Co. Ltd; DowAksa USA LLC; Formosa Plastics Corporation; Hexcel Corporation; Holding company Composite; Hyosung Advanced Materials; Jiangsu Hengshen Co. Ltd; Mitsubishi Chemical Corporation; Nippon Graphite Fiber Co. Ltd; SGL Carbon; Solvay; Teijin Limited; Toray Industries Inc.; Zhongfu Shenying Carbon Fiber Co. Ltd.
About the Author(s)
Specialty Glass, Ceramic & Fiber Research Team
Advanced Materials · Specialty Glass, Ceramic & FiberThis report was authored by the specialty glass, ceramic & fiber research team at Grand View Research - comprising two research analysts, one senior research analyst, and one industry expert - with specialized expertise in the specialty glass, ceramic & fiber segment of the advanced materials industry. All findings are based on proprietary advanced materials databases, executive interviews, and regulatory analysis, subject to internal peer review prior to publication.
Last Updated:
Speak to Analyst

Customize this report to your needs - add regions, segments, or data points, with 20% free customization.
Or view our licence options:


ISO 9001:2015 & 27001:2022 Certified
We are GDPR and CCPA compliant! Your transaction & personal information is safe and secure. For more details, please read our privacy policy.


