
- Home
- »
- Medical Devices
- »
-
Cleanroom Robots In Healthcare Market Report, 2026-2033GVR Report cover

Cleanroom Robots In Healthcare Market (2026 - 2033)
Size, Share & Trends Analysis Report By Type (Traditional Industrial Robots, Collaborative Robots, Controllers, Sensors, Power Supply), By Component, By End-use, By Region, And Segment Forecasts
Market Size, 2025
$789.1MMarket Estimate, 2026
$982.5MMarket Forecast, 2033
$4,430.7MCAGR, 2026–2033
24.0%Cleanroom Robots in Healthcare Market Summary
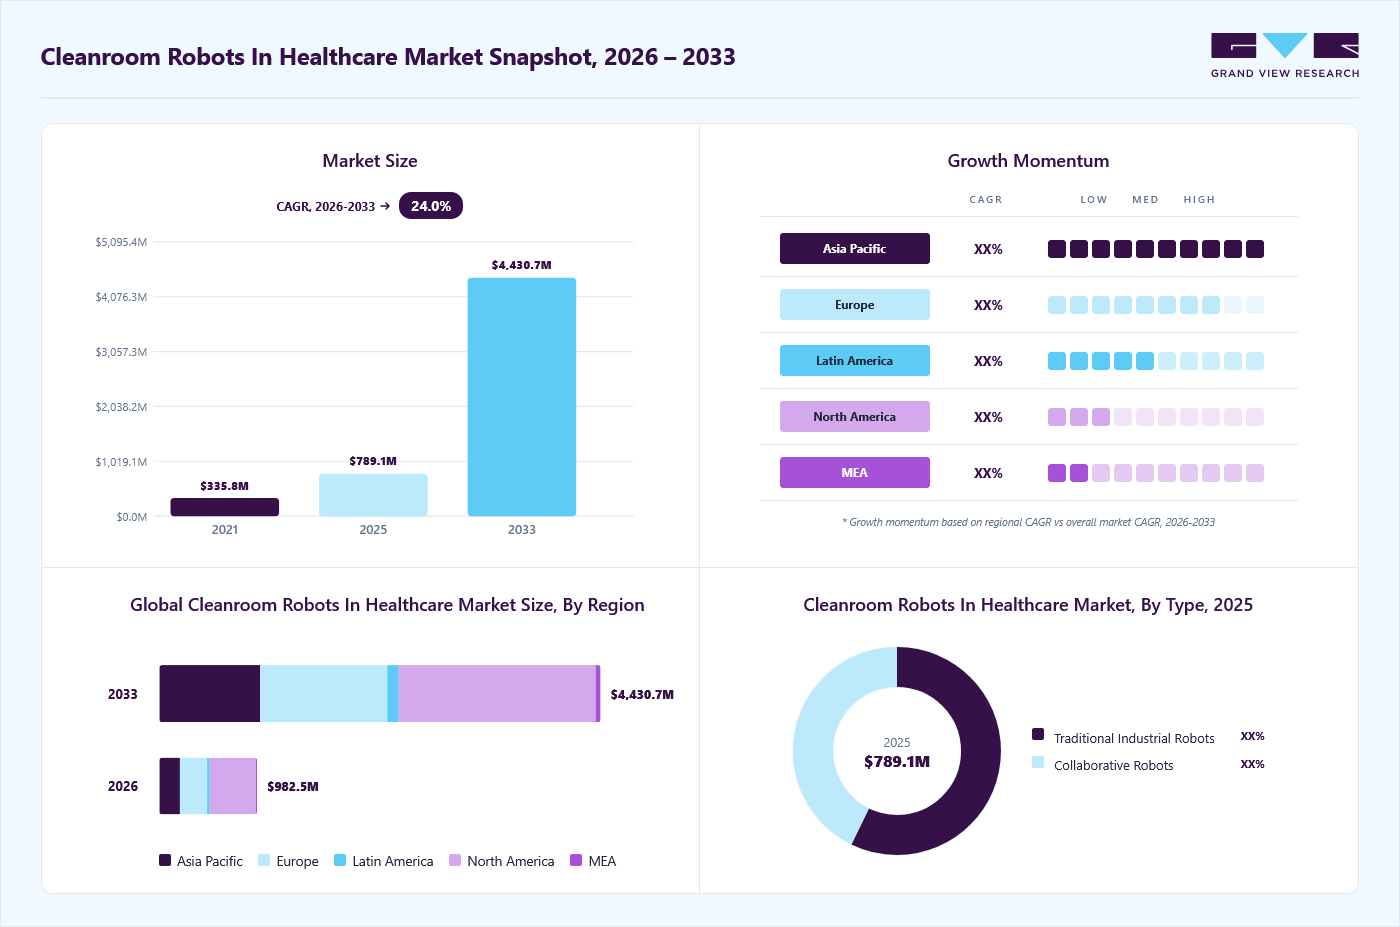
The global cleanroom robots in healthcare market size was valued at USD 789.1 million in 2025 and is projected to grow from USD 982.5 million in 2026 to USD 4430.7 million by 2033, at a CAGR of 24.0% from 2026 to 2033, due to the increasing demand for sterile and contamination-free environments in healthcare facilities, the rise of minimally invasive surgical procedures, the need for efficient cleaning and disinfection protocols, and the increasing adoption of robotic technology in healthcare. North America dominated the market, accounting for the largest share of 78.9% in 2025.
 Source: Grand View Research, IR Documents, Primary Interviews, Paid DatabasesTo learn more about this report,
 Download Free Sample Report
Key Market Trends & Insights
- By type: Traditional industrial robots segment held the largest share of 57.2% in 2025.
- By component: Robotic arms segment held the largest share of 44.7% in 2025.
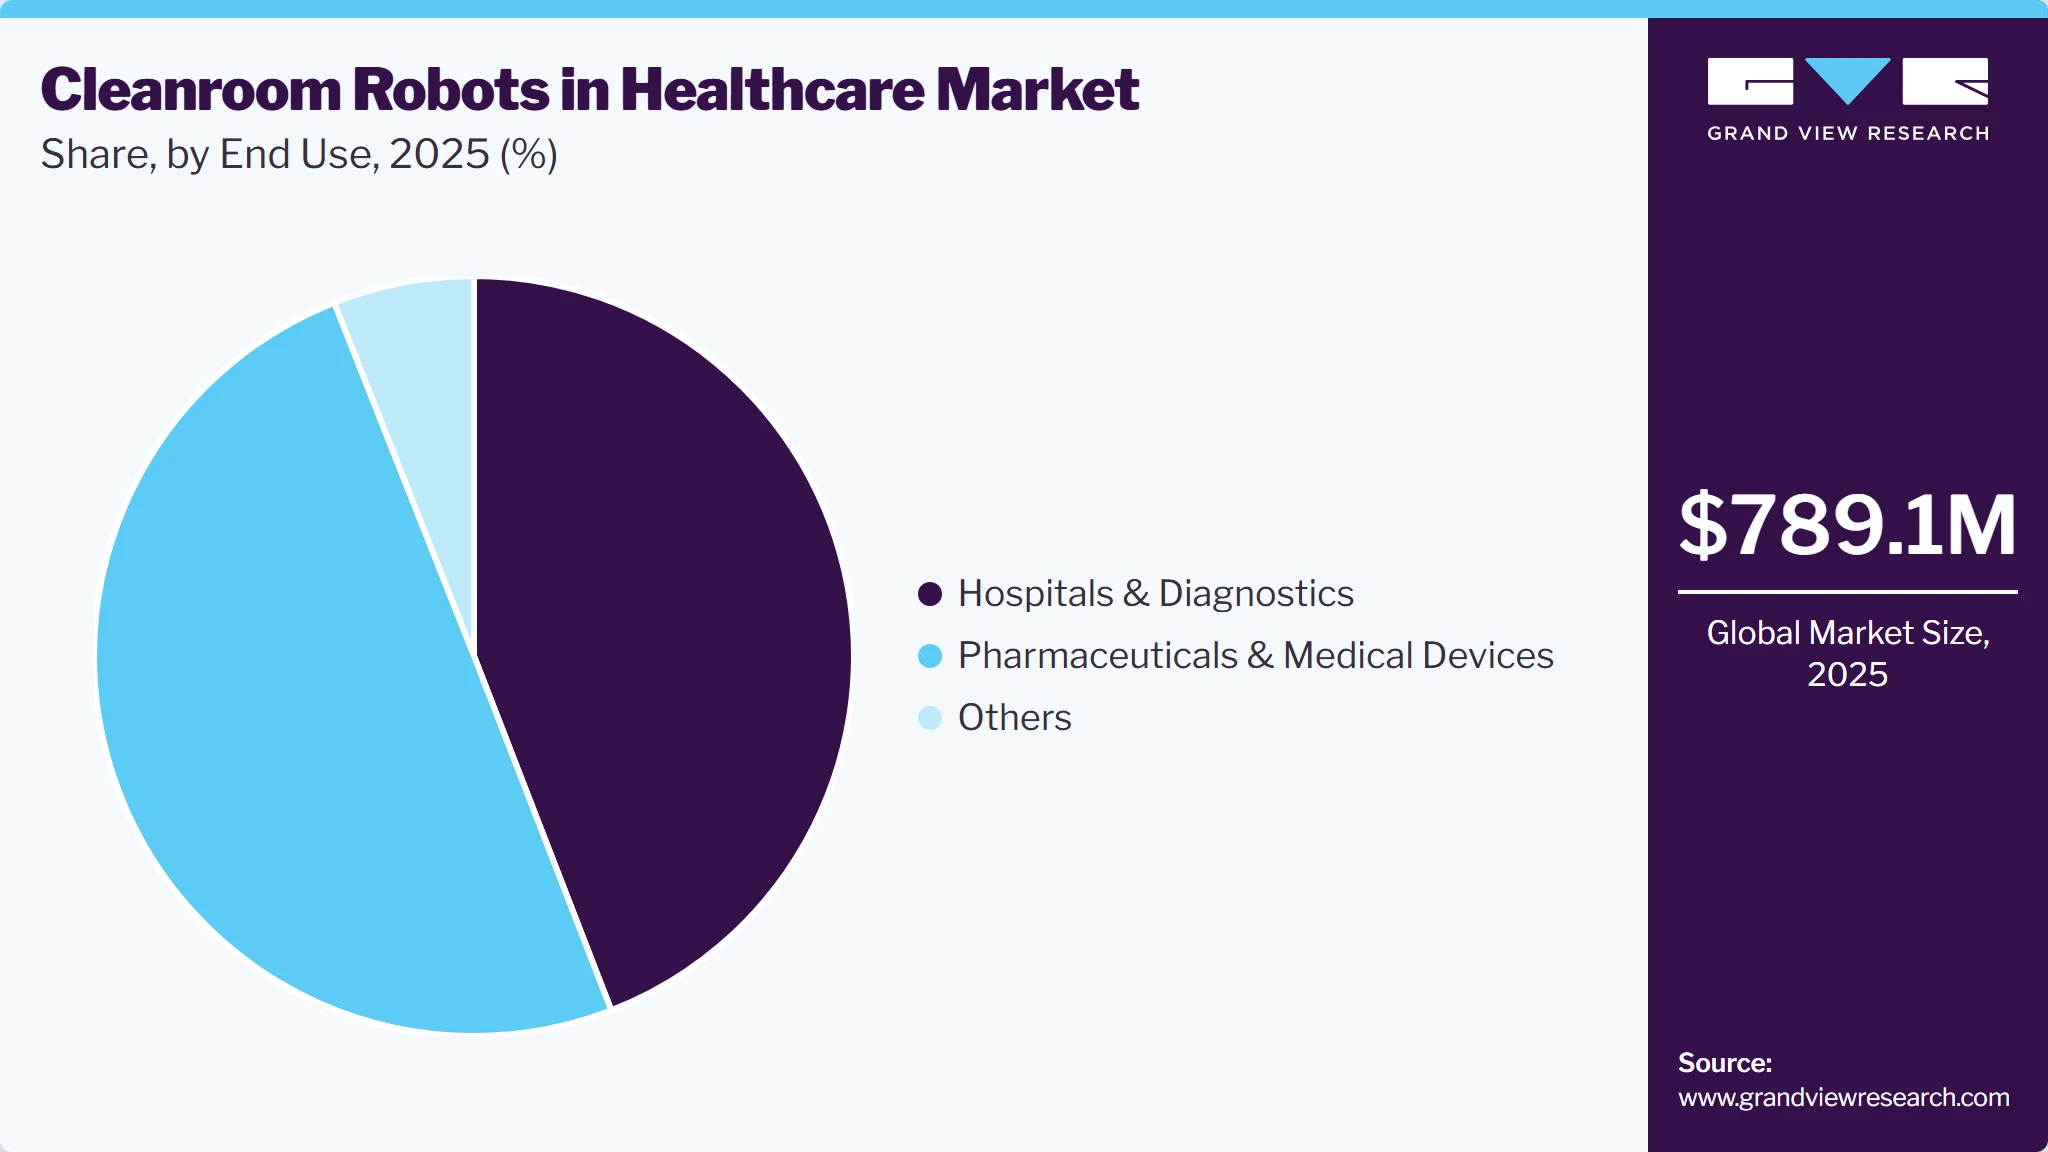
- By end use: Pharmaceutical & medical device companies segment held the largest market share of 49.9% in 2025.
Regional Highlights
- Largest regional market: North America (78.9% revenue share, 2025)
- By country: The U.S. held the largest revenue share of North America in 2025.
Market Size & Forecast
- Market size in 2025: USD 789.1 Million
- Estimated market size in 2026: USD 982.5 Million
- Projected market size by 2033: USD 4430.7 Million
- CAGR (2026-2033): 24.0%
Three ways to get this report
Buy it, customize it, or ask a question.Ask an Analyst
Analyst response in 1 business day
- AccessReport author, directly
- Reply timeWithin 1 working day
- No sales callDirect answer only
- FormatEmail reply
- CostFree, no cost
Get the Full Report
What the study covers
- FormatsPDF · Excel · Dashboard
- Timeline2026–2033 annual, 2025 base
- Coverage20+ countries, 5 regions
- Companies10+ key players profiled
Customize the Report
20% free customization
- IncludeCountries, segments, points
- TailorTo your product definition
- ExtendDeeper competitor detail
- OrA fully bespoke study
- Turnaround5–10 working days
The global cleanroom robots in healthcare market size was estimated at USD 673.87 million in 2024 and is projected to grow at a CAGR of 25.68% from 2025 to 2030, due to the increasing demand for sterile and contamination-free environments in healthcare facilities, the rise of minimally invasive surgical procedures, the need for efficient cleaning and disinfection protocols, and the increasing adoption of robotic technology in healthcare. For instance, in February 2023, the OMRON, an electronics company, introduced its new i4H SCARA robots, designed specifically for electrostatic discharge ESD and cleanroom environments. These robots are optimized for use in industries such as healthcare, digital and automotive sectors, including semiconductor manufacturing.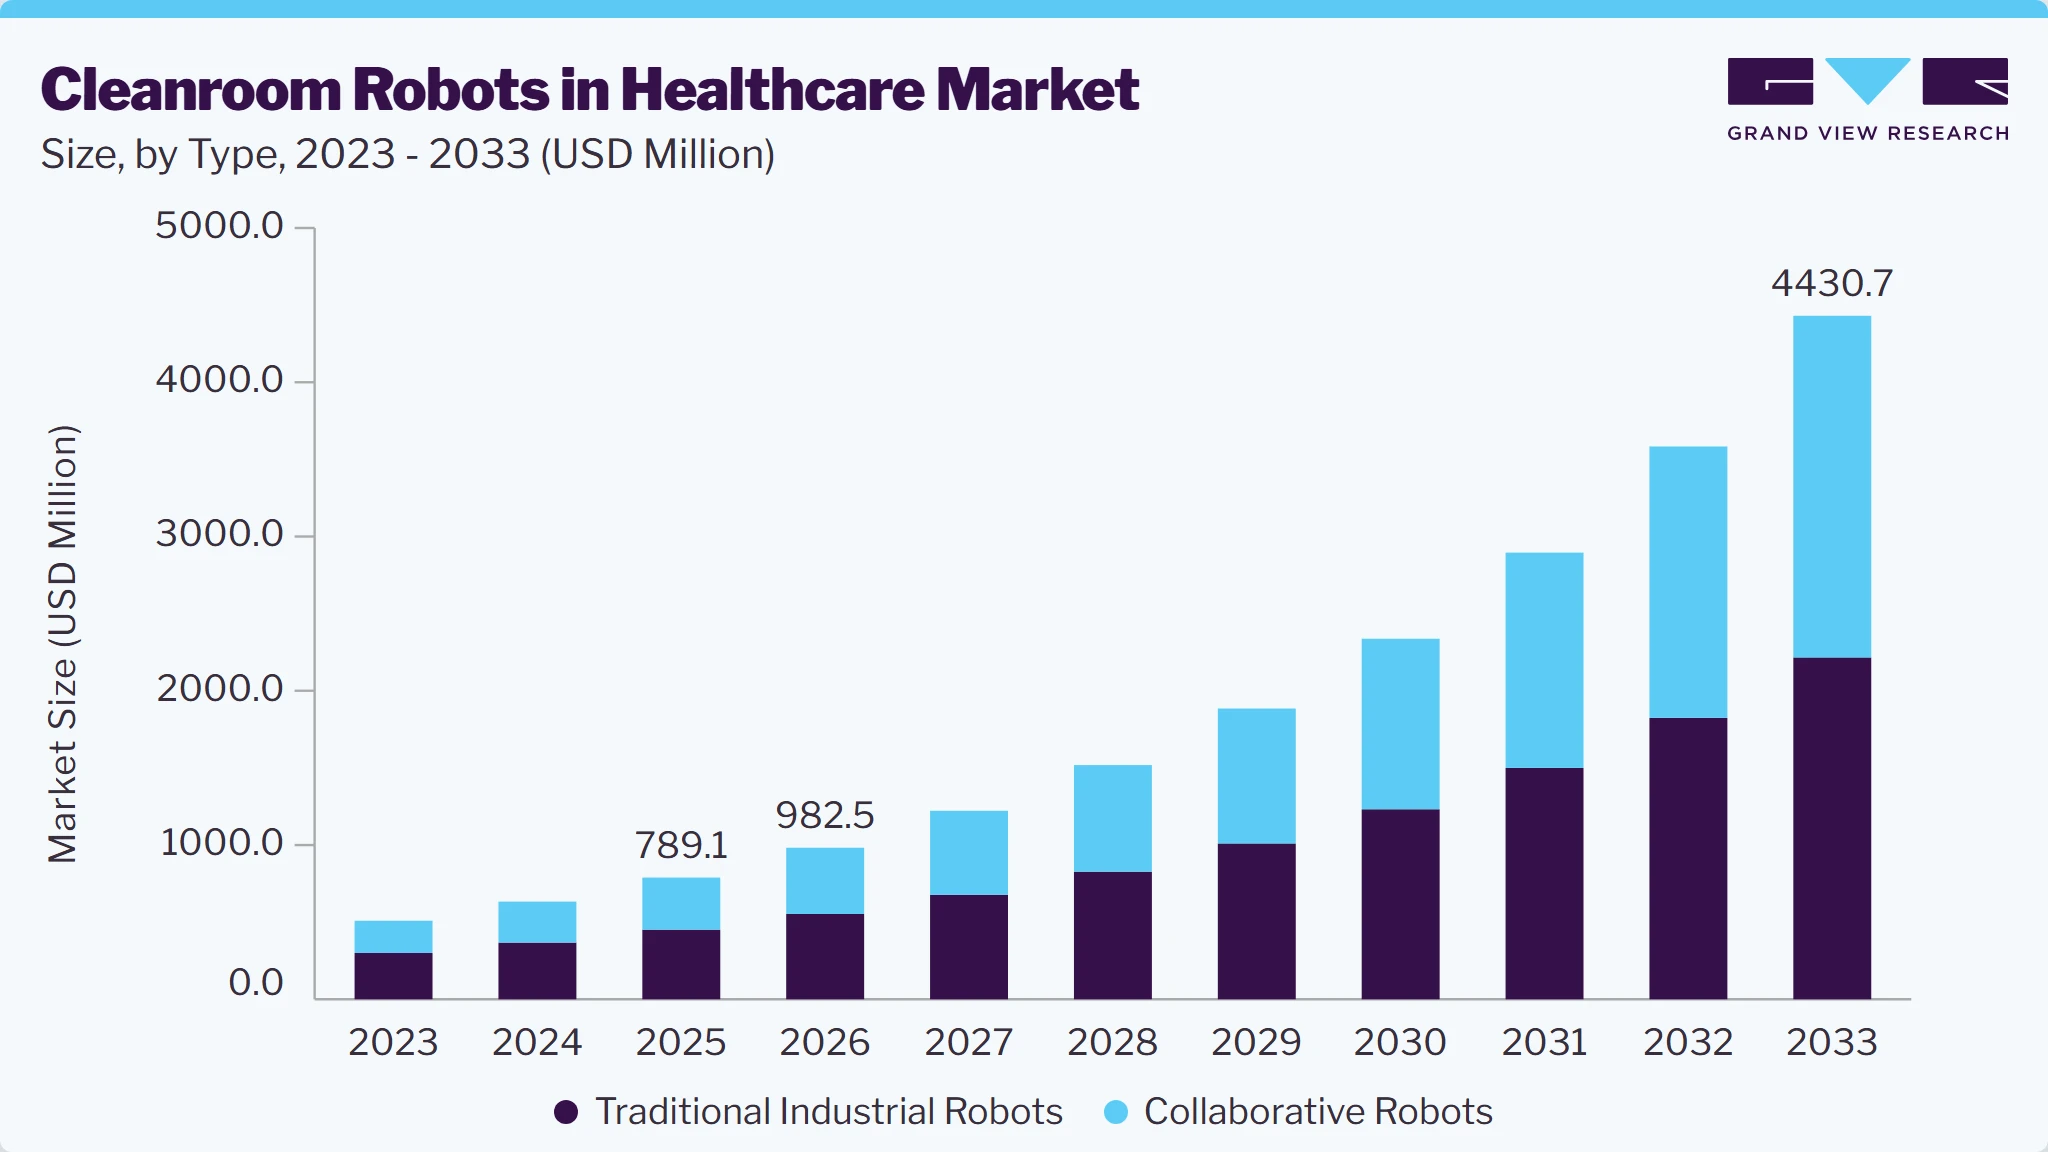 To learn more about this report, Download Free Sample Report
The increasing need for high precision and consistency in medical and pharmaceutical processes drives the adoption of cleanroom robots. These robots play a critical role in ensuring contamination-free handling of products, which is essential for maintaining patient safety and the effectiveness of medical treatments. By minimizing human intervention, cleanroom robots reduce the risk of contamination and ensure a sterile environment, providing the high standards required in the healthcare and pharmaceutical industries. Their ability to consistently perform delicate and precise tasks makes them important in these settings, contributing to the quality and reliability of medical and pharmaceutical products.
In addition, advancements in robotics technology have significantly expanded the capabilities of cleanroom robots. Innovations such as enhanced sensor capabilities, improved dexterity, and AI integration have enabled these robots to perform complex tasks with greater accuracy and efficiency. Enhanced sensors allow for precise detection and manipulation of objects, while improved dexterity ensures the robots can handle delicate tasks without compromising the sterile environment. AI integration further enhances their functionality by enabling adaptive learning and decision-making processes, making these robots more versatile and reliable. For instance, in June 2022, FANUC America expanded its lineup by introducing three SCARA robot models. These new models are designed to assist companies in automating their assembly, packaging, pick and place, and inspection processes.
Furthermore, stringent regulatory requirements from global health authorities mandate the use of cleanroom environments for producing pharmaceuticals and medical devices. Cleanroom robots are crucial in maintaining these environments by minimizing human intervention, thereby reducing the risk of contamination. For instance, in September 2022, Swiss tech company SEED Biosciences announced that its pipetting robot, DISPENCELL, has received approval for use in cleanrooms and sterile environments. This adherence to regulations ensures that the highest standards of cleanliness and safety are met, which is essential for the integrity and effectiveness of medical products.
Market Dynamics
The global cleanroom robots in healthcare market growth is due to the increasing demand for sterile and contamination-free environments in healthcare facilities, the rise of minimally invasive surgical procedures, the need for efficient cleaning and disinfection protocols, and the increasing adoption of robotic technology in healthcare.
Stringent regulatory requirements and the need for contamination-free environments are driving the adoption of cleanroom robots in healthcare and pharmaceutical settings. These robots operate in controlled environments to perform tasks such as material handling, inspection, and packaging with high precision and minimal human intervention. This reduces contamination risks and ensures compliance with GMP and ISO cleanroom standards.
Cleanroom robots are equipped with advanced sensors, vision systems, and sealed designs to operate in sterile environments. They are increasingly used in biologics manufacturing, semiconductor-based medical device production, and laboratory automation. Automation in cleanrooms improves process consistency, reduces error rates, and enhances overall operational efficiency. The growing demand for high-quality, contamination-free products is accelerating adoption. For instance, in March 2025, Stäubli Robotics collaborated with Novo Nordisk to develop Sterimove, a first Grade A/B/C/D-compatible mobile robot for pharmaceutical cleanrooms. Its hygienic design eliminates retention areas, uses H2O2-compatible materials, preserves laminar airflow, and offers modular flexibility with a compact footprint for automated material transport in aseptic production.
Moreover, the increasing complexity of drug manufacturing, particularly biologics and advanced therapies, is driving the adoption of pharma robots. These systems ensure high precision, reproducibility, and compliance with stringent regulatory standards such as GMP. Automation reduces human intervention in critical processes such as compounding, dispensing, and packaging, minimizing contamination risks and improving product quality. This is essential as pharmaceutical companies scale production to meet global demand. For instance, in January 2026, Multiply Labs partnered with NVIDIA to integrate Isaac Sim, GR00T foundation models, and perception AI into robotic biomanufacturing systems to scale production of cell and gene therapies.
Pharma and cleanroom robots require specialized designs, validation processes, and compliance with stringent regulatory standards, increasing initial expenditure. These costs are particularly challenging for small- and mid-sized hospitals, contract manufacturers, and facilities in emerging markets, where budget constraints limit investment in advanced automation technologies. As a result, adoption remains concentrated in large healthcare institutions and well-funded pharmaceutical companies.
Table 1 Price ranges of medical & healthcare robots (USD)
Robot Model
Manufacturer
Price in USD
Cleanroom Robots - ISO-certified robots for sterile environments in healthcare, medical device & biotech
IRB 910SC
Compact SCARA cleanroomABB (Switzerland)
~USD 30,000 - USD 60,000
i4H SCARA Robot
ESD & cleanroom, 2023OMRON (Japan)
~USD 25,000 - USD 45,000
TX2-60 CR / SCR
ISO Class 2 (SCR) / Class 4 (CR)Stäubli (Switzerland)
~USD 60,000 - USD 120,000
Motoman HC Series (Cleanroom)
Collaborative cleanroom cobotYaskawa Electric (Japan)
~USD 40,000 - USD 60,000
Source: Secondary Research, Grand View Research Analysis.
Case Study: Autonomous UV Disinfection Robots for Reducing Healthcare-Associated Infections
Problem
Healthcare-associated infections (HAIs) remain a major challenge for healthcare systems globally, contributing to approximately 37,000 deaths annually in Europe and nearly 100,000 deaths annually in the U.S. In addition to the clinical burden, HAIs are estimated to result in annual treatment costs of approximately USD 6.5 billion in the U.S. Traditional manual cleaning processes may be subject to variability in execution, labor shortages, and limited ability to consistently disinfect high-touch surfaces.
Solution
Healthcare facilities have adopted autonomous UV-C disinfection robots to supplement conventional environmental cleaning practices. The UVD Robot developed by Blue Ocean Robotics autonomously navigates hospital environments using LiDAR-based mapping and emits concentrated UV-C light capable of eliminating up to 99.99% of bacteria and viruses under controlled conditions. The system can disinfect a standard patient room in approximately 10 minutes and automatically suspends UV exposure when human movement is detected to ensure operational safety.
Outcome
The deployment of UV disinfection robots has enabled healthcare facilities to enhance environmental hygiene protocols, improve consistency in room disinfection, and reduce reliance on manual cleaning processes. During the COVID-19 pandemic, adoption expanded beyond hospitals to airports, hotels, public transportation hubs, and other high-traffic facilities seeking to strengthen infection control measures. The growing use of autonomous cleaning technologies has also supported efforts to optimize workforce utilization and maintain higher sanitation standards.
Industry Implication
The increasing integration of autonomous disinfection systems highlights a broader shift toward smart hospital infrastructure and technology-enabled infection prevention strategies. As healthcare providers continue to prioritize patient safety, operational efficiency, and antimicrobial resistance mitigation, autonomous cleaning robots are expected to become an increasingly important component of modern environmental services programs.
Market Concentration & Characteristics
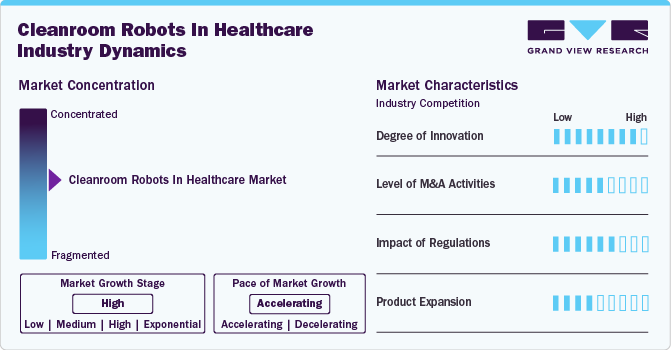
The global cleanroom robots in the healthcare industry is characterized by a high degree of innovation. Technological advancements such as AI integration, enhanced sensor technologies, and improved dexterity are revolutionizing these robots' capabilities. These innovations enable cleanroom robots to perform complex and precise tasks with greater efficiency and reliability, minimizing human intervention and contamination risks. This continual technological progress is essential for maintaining stringent sterility standards in healthcare and pharmaceutical applications. For instance, in July 2024, ChargePoint Technology, a liquid and powder transfer specialist, introduced a new robotic material handling solution to enhance safety and efficiency in manufacturing solid dosage drugs. This solution addresses risks linked to manual intervention by mitigating ergonomic and manual handling issues while reducing the likelihood of cross-contamination from personnel.
Mergers and acquisitions (M&A) activities in the cleanroom robots in the healthcare market are currently robust. Companies are strategically acquiring or merging with others to enhance their technological capabilities, expand market reach, and integrate specialized expertise in sterile automation solutions. For instance, in October 2022, igus acquired Commonplace Robotics, a company that specializes in intuitive control systems, software, and power electronics for robotics, catering to both industrial and educational sectors. This trend reflects the sector's dynamic growth and the importance of innovation in healthcare robotics.
 To learn more about this report, Download Free Sample Report
Regulations significantly impact the market by mandating strict sterility and contamination control standards. Compliance with these regulations drives the adoption of cleanroom robots, as they effectively minimize human intervention and contamination risks, ensuring the production of safe and high-quality medical and pharmaceutical products.
Product expansion in the market involves the introduction of advanced robotic systems tailored for sterile environments. For instance, in July 2022, Comau launched its latest six-axis articulated robot, the Racer-5SE, designed specifically for industries such as healthcare. It is certified with IP67 for ingress protection and meets high standards for cleanroom environments with ISO 5 classification (ISO 14644-1). Companies are developing robots with enhanced precision, improved contamination control features, and integration of AI for autonomous operation.
Analyst Perspective
The cleanroom robots in healthcare market is expected to grow steadily as pharmaceutical companies, medical device manufacturers, hospitals, and diagnostic laboratories increase investment in sterile and automated workflows. Pharmaceuticals and medical devices are expected to remain the largest end-use segment, supported by contamination-free production, precise assembly, sterile packaging, and consistent quality requirements.
Adoption across hospitals and diagnostic laboratories is also expected to increase for sample handling, specimen preparation, laboratory testing, and material transfer, further supporting market growth. Traditional industrial robots, including articulated, SCARA, Cartesian, and parallel robots, are expected to continue supporting high-volume operations, while collaborative robots are expected to gain demand due to their flexibility and suitability for smaller cleanroom and laboratory spaces.
Type Insights
By type, the traditional industrial robots segment held the largest share of 57.2% in 2025. However, the collaborative robots segment is expected to witness growth at the fastest CAGR over the forecast period. These companies are innovating by integrating advanced technologies such as cleanroom-compatible materials, enhanced contamination control features, and precision motion control systems. For instance, in March 2024, igus is introducing a new energy supply system tailored for SCARA robots operating in cleanroom environments. Constructed from tribologically optimized high-performance plastics, this system operates with minimal particle emission, meeting ISO Class 2 standards even during high-speed operations. These innovations cater specifically to the stringent cleanliness standards required in pharmaceutical and medical device manufacturing. Traditional industrial robots are increasingly deployed for tasks such as assembly, packaging, and handling of sensitive materials, supporting the industry's demand for reliable and efficient automation solutions in sterile environments.
The collaborative robots segment is expected to witness significant CAGR growth over the forecast period. These robots are designed to work alongside humans in sterile environments, enhancing flexibility and efficiency in medical and pharmaceutical settings. Their advanced safety features and ease of integration allow for seamless interaction with healthcare professionals, contributing to increased productivity and operational flexibility within cleanroom environments. This trend underscores the growing adoption of collaborative robotics to meet evolving healthcare industry demands.
Component Insights
By component, the robotic arms segment held the largest share of 44.7% in 2025. However, the motors segment is expected to witness significant CAGR growth over the forecast period. These companies are driving innovation by integrating advanced features such as cleanroom-compatible materials, precision motion control, and enhanced sterilization capabilities. For instance, in April 2024, Roborock revealed the upcoming launch of its highly anticipated robotic cleaner, the S8 MaxV Ultra. Previously acclaimed at CES 2024, this advanced model has captured attention for its intelligent features. Robotic arms are increasingly utilized for critical tasks in pharmaceutical and medical device manufacturing, including precise assembly, packaging, and handling of sensitive materials. This segment's growth is fueled by the rising demand for automation solutions that ensure stringent cleanliness standards and operational efficiency in healthcare environments.
The motors segment is expected to witness significant CAGR growth over the forecast period, owing to advancements in technology. Innovations such as brushless DC motors, precision servo motors, and compact, high-efficiency designs are enhancing the performance and reliability of cleanroom robots. These advanced motors provide superior control, reduced maintenance, and lower contamination risks, which are crucial for sterile environments. Key players such as Maxon Motors and Faulhaber are leading this segment by developing motors that meet the stringent requirements of healthcare applications.
End-use Insights
By end use, the pharmaceutical & medical device companies segment held the largest market share of 49.9% in 2025. However, Hospitals & diagnostics segment is expected to grow at a fastest rate over the forecast period. This surge in funding drives the demand for automation to enhance precision, efficiency, and sterility in production processes. Cleanroom robots are essential for maintaining contamination-free environments, ensuring high-quality manufacturing standards. Consequently, key players are focusing on innovative robotic solutions to meet the stringent requirements of this expanding sector.
 To learn more about this report, Download Free Sample Report
Hospitals & diagnostics segment is expected to grow at a fastest rate over the forecast period. This expansion is driven by the increasing need for sterile environments and precise diagnostic procedures. Cleanroom robots are crucial in hospitals for tasks such as automated medication dispensing, surgical assistance, and laboratory automation, reducing human error and contamination risks. As healthcare facilities invest in advanced technologies to improve patient care and operational efficiency, the demand for cleanroom robots in this segment continues to rise, propelling market growth.
Regional Insights
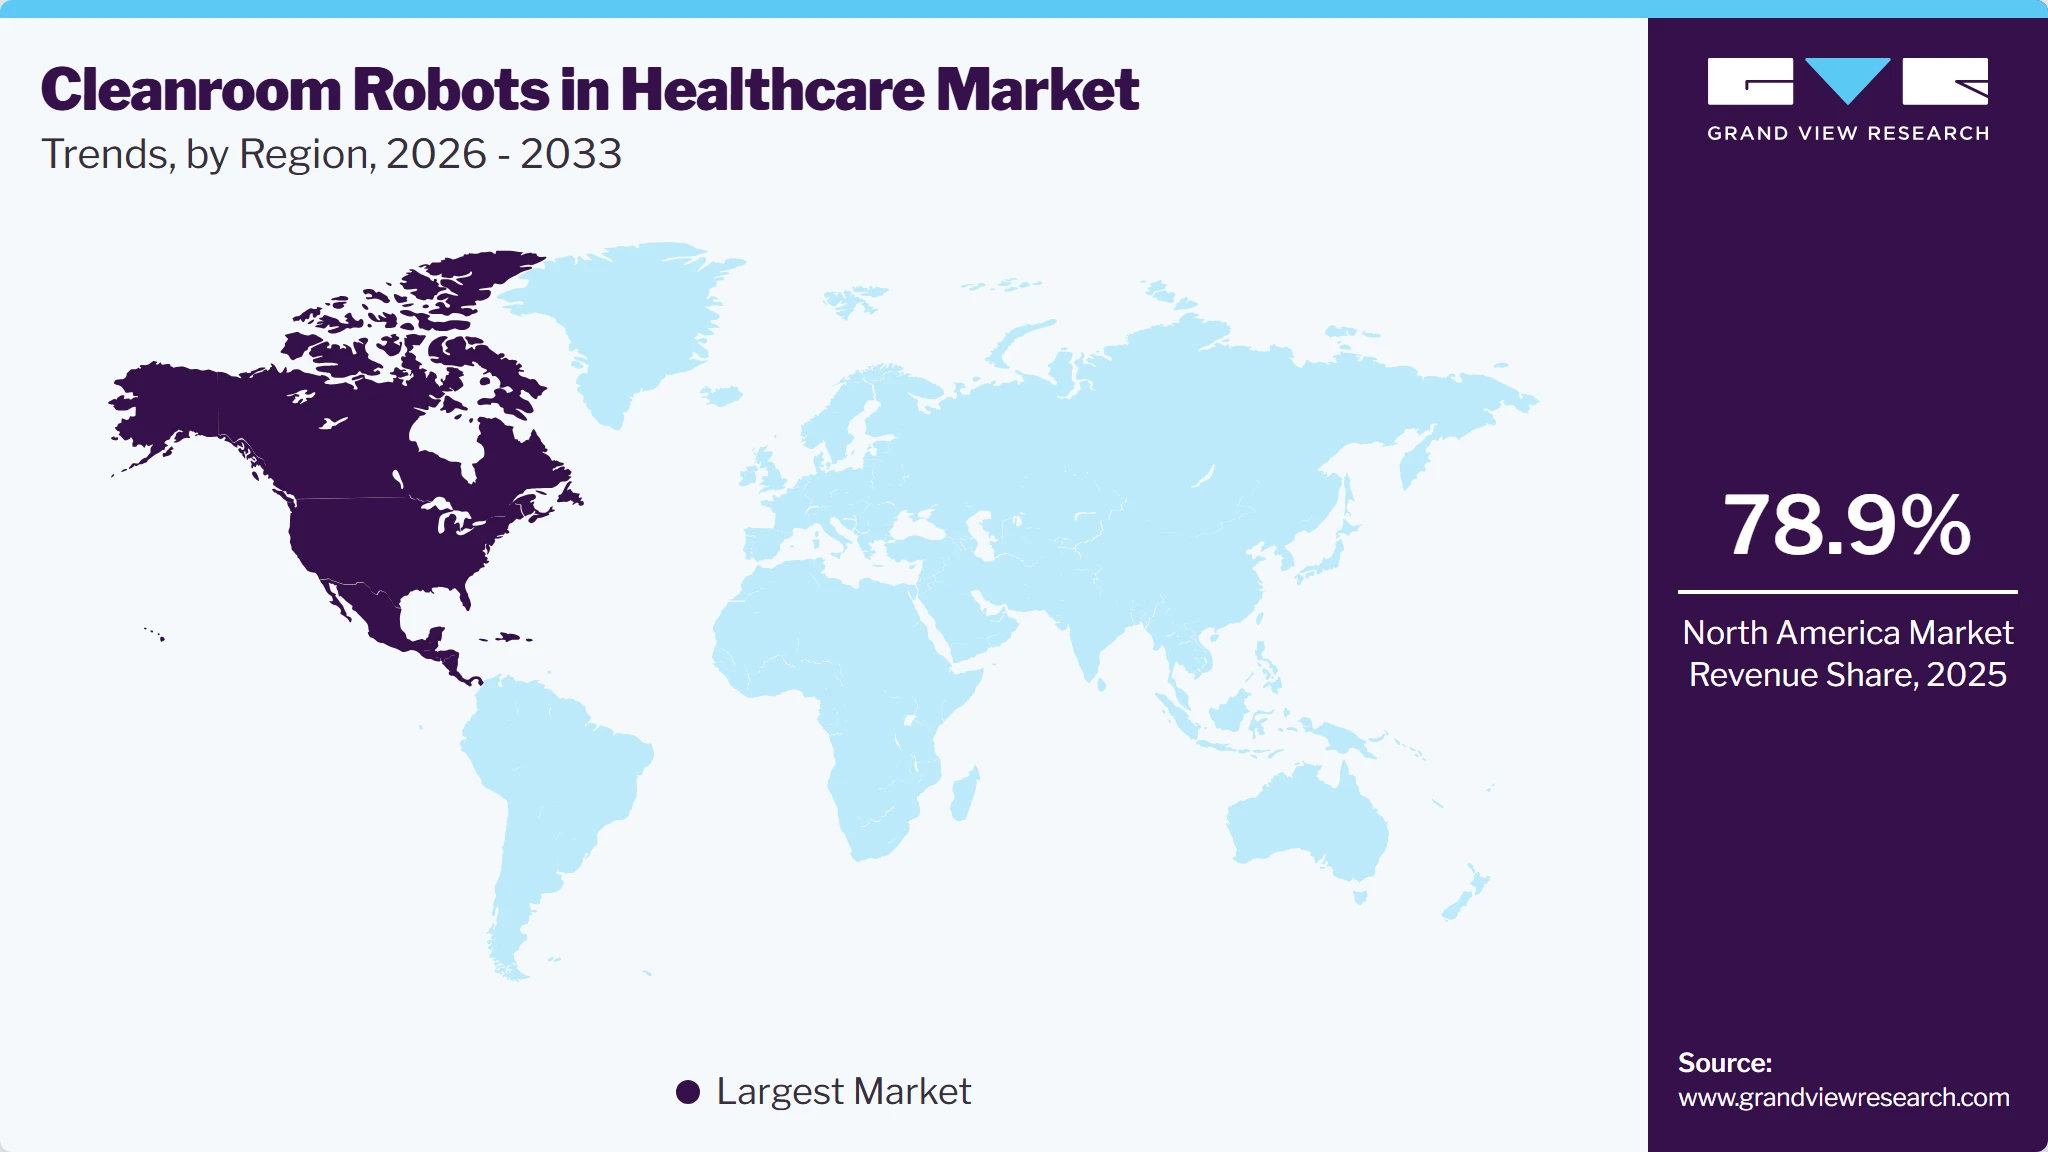
North America dominated the cleanroom robots in healthcare market with the largest revenue share of 78.9% in 2025. Strategic partnerships are pivotal in this region, as companies collaborate to enhance technological capabilities and market reach. For instance, in September 2022, iRobot Corp. launched the Roomba Combo j7+, an advanced robot vacuum and mop, accompanied by the iRobot OS 5.0 updates. This model is ideal for health centers with a mix of carpets, rugs, and hard floors, offering the convenience of both vacuuming and mopping in a single session. These alliances focus on integrating advanced robotics with healthcare processes to meet stringent regulatory standards, improve efficiency, and ensure contamination-free environments, thereby boosting the adoption of cleanroom robots in the healthcare sector.
 To learn more about this report, Download Free Sample Report
U.S. Cleanroom Robots In Healthcare Market Trends
The cleanroom robots in healthcare market in the U.S. held the largest share in the North America region in 2025, driven by increasing investments in healthcare automation and stringent regulatory standards. The demand for precision and contamination-free environments in medical and pharmaceutical industries significantly boosts market expansion.
Europe Cleanroom Robots In Healthcare Market Trends
The Europe cleanroom robots in healthcare market is experiencing significant growth, propelled by advancements in technology. Innovations such as AI integration, enhanced sensors, and precision control systems are improving the efficiency and reliability of cleanroom robots. These technological advancements ensure stringent contamination control, meeting the high standards required in pharmaceutical and medical device manufacturing. European companies are increasingly adopting these advanced robotic solutions to enhance productivity and maintain sterility in healthcare environments.
The UK cleanroom robots in healthcare market is one of the major markets in the European region, is experiencing considerable growth. Furthermore, rise in launches of new products, and growing adoption of these robots by healthcare and pharmaceutical organization. For instance, in August 2023, UK-based startup United Robots introduced a fleet of AI-powered industrial cleaning robots designed for large, crowded spaces. This London-based company launched its new autonomous robots to enhance the efficiency and effectiveness of industrial cleaning in expansive and busy environments. These companies leverage AI and advanced technology to enhance robotic precision, efficiency, and contamination control. Innovations include AI-driven diagnostics, real-time monitoring, and adaptive learning capabilities. These advancements ensure high standards of sterility and operational efficiency, making cleanroom robots essential in the UK's pharmaceutical and medical device industries.
Asia Pacific Cleanroom Robots In Healthcare Market Trends
The Asia Pacific cleanroom robots in healthcare market is experiencing significant growth is driven by technological advancements and substantial government initiatives. Significant investments are being made to integrate advanced robotics in healthcare settings, enhancing precision and efficiency. Moreover, the Chinese government's support for automation and smart manufacturing, along with increased funding for healthcare innovation, is driving market in this region.
The Japan cleanroom robots in healthcare market is characterized by continuous innovation. Key advancements include the integration of advanced robotics with AI for enhanced precision and efficiency in sterile environments. In addition, government initiatives aimed at promoting healthcare technology adoption, along with growing investments in AI and robotics, are further fueling market growth.
Latin America Cleanroom Robots In Healthcare Market Trends
The Latin Americacleanroom robots in healthcare marketis experiencing growing demand due to increasing requirements for sterile manufacturing environments in pharmaceutical and medical device sectors. This trend is driving adoption of cleanroom robots to ensure high standards of cleanliness and operational efficiency. Moreover, the growing recognition of robotics as a tool to address healthcare challenges is escalating the expansion of cleanroom robots in the healthcare industry.
The Brazil cleanroom robots in healthcare market is expanding with significant investments in healthcare infrastructure and shortages of healthcare resources and high demand for services are supplementing market growth. Government initiatives and funding to support the development and deployment of AI-driven healthcare technologies are further driving growth.
MEA Cleanroom Robots In Healthcare Market Trends
The cleanroom robots in healthcare market in MEA is experiencing growth. There is increasing adoption of cleanroom robots to maintain sterile environments essential for pharmaceutical and medical device manufacturing, ensuring high standards of safety and quality. In the Middle East, countries such as the UAE, Saudi Arabia, and Qatar are making substantial investments in healthcare infrastructure and technological advancements, including robotics, to improve healthcare delivery and patient care.
The Saudi Arabia cleanroom robots in healthcare market is expanding rapidly due to growing demand within the healthcare sector and increased healthcare investments. The adoption of cleanroom robots is crucial for maintaining sterile conditions in pharmaceutical and medical device manufacturing. This growth reflects the country's commitment to enhancing healthcare infrastructure and meeting stringent regulatory requirements for cleanliness and safety in healthcare settings.
Key Cleanroom Robots In Healthcare Company Insights
Key participants in the cleanroom robots in healthcare market focus on developing innovative business growth strategies through mergers and acquisitions, partnerships and collaborations, product portfolio expansions, and business footprint expansions:
Key Cleanroom Robots In Healthcare Companies:
The following key companies have been profiled for this study on the cleanroom robots in healthcare market.
-
ABB Ltd.
-
Denso Corporation
-
FANUC Corporation
-
Kawasaki Heavy Industries, Ltd.
-
Yaskawa Electric Corporation
-
Aerotech, Inc.
-
Nachi Fujikoshi Corporation
-
Avidbots Corp.
-
LionsBot International Pte Ltd.
Competitive Benchmarking
Category
Operating Strategies
Competitive Edge
Weakness
Established Players (ABB Ltd.; Denso Corporation FANUC Corporation)
- Mature players focus on advanced automation systems for semiconductor, pharmaceutical, and electronics cleanroom environments. They strengthen market presence through AI-enabled robotics, precision motion control, and strategic partnerships with manufacturing companies.
- Strong global distribution networks and established industrial automation expertise support large-scale deployment. Advanced contamination-control technologies and integrated automation platforms strengthen competitive positioning.
- High installation and maintenance costs increase adoption barriers for small manufacturers. Complex integration with existing cleanroom infrastructure and operational systems may limit deployment flexibility.
Emerging & Specialized Players (Kawasaki Heavy Industries, Ltd.; Yaskawa Electric Corporation; Nachi Fujikoshi Corporation; Stäubli International AG.)
- Emerging players focus on collaborative cleanroom robots, compact automation systems, and flexible robotic solutions for precision manufacturing. They emphasize niche applications, agile innovation, and cost-efficient deployment strategies to gain traction.
- Flexible product portfolios and rapid innovation cycles support adoption across specialized cleanroom applications. Collaborative robot technologies improve operational efficiency and simplify automation workflows.
- Limited global presence and smaller distribution networks may restrict market expansion. Lower R&D budgets and limited manufacturing scale may affect long-term competitiveness against established automation providers.
Recent Developments
-
In April 2024, LionsBot International, a Singapore-based company specializing in robotic cleaning solutions, inaugurated its state-of-the-art robot factory. This facility, the largest of its kind in Southeast Asia dedicated to manufacturing and research and development of advanced cleaning robotics technology, represents a major achievement for Singapore in positioning itself as a global leader in this sector.
-
In April 2024, Avidbots, a company based in Ontario specializing in robotics, introduced Kas, a fully autonomous floor scrubber designed to cater to the retail, healthcare, and education sectors.
-
In November 2023, Syrius Technology announced a strategic partnership with SoftBank Robotics and IRIS OHYAMA to introduce a new commercial cleaning robot. This collaboration aims to enhance cleaning services with improved efficiency, convenience, eco-friendliness, and high-quality results for the public.
Cleanroom Robots In Healthcare Market Report Scope
Report Attribute
Details
Market size value in 2025
USD 789.1 million
Market size value in 2026
USD 982.5 million
Revenue forecast in 2033
USD 4430.7 million
Growth rate
CAGR of 24.0% from 2026 to 2033
Historical data
2021 - 2024
Forecast period
2026 - 2033
Quantitative units
Revenue in USD million/billion and CAGR from 2026 to 2033
Report coverage
Revenue forecast, company ranking, competitive landscape, growth factors, and trends
Segments covered
Type, Component, End Use, and Region
Regional scope
North America; Europe; Asia Pacific; Latin America; MEA
Country scope
U.S.; Canada; Mexico; U.K.; Germany; Spain; France; Italy; Spain; Denmark; Sweden; Norway; China; Japan; India; Australia; South Korea; Thailand; Brazil; Argentina; South Africa; Saudi Arabia; UAE; Kuwait
Key companies profiled
ABB Ltd.; Denso Corporation; FANUC Corporation; Kawasaki Heavy Industries, Ltd.; Yaskawa Electric Corporation; Nachi Fujikoshi Corporation; Stäubli International AG.
Customization scope
Free report customization (equivalent up to 8 analysts' working days) with purchase. Addition or alteration to country, regional & segment scope.
Pricing and purchase options
Avail customized purchase options to meet your exact research needs. Explore purchase options
Global Cleanroom Robots In Healthcare Market Segmentation
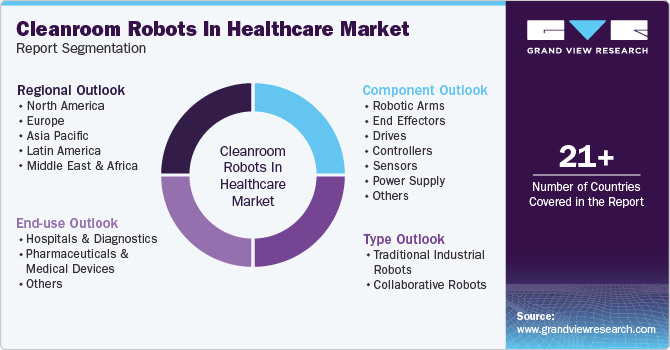
This report forecasts revenue growth at country levels and provides an analysis on the latest industry trends and opportunities in each of the sub-segments from 2021 to 2033. For the purpose of this study, Grand View Research has segmented the cleanroom robots in healthcare market report on the basis of type, component, end-use and region.
 To learn more about this report, Download Free Sample Report
-
Type Outlook (Revenue, USD Million, 2021 - 2033)
-
Traditional Industrial Robots
-
Articulated Robots
-
SCARA Robots
-
Parallel Robots
-
Cartesian Robots
-
-
Collaborative Robots
-
-
Component Outlook (Revenue, USD Million, 2021 - 2033)
-
Robotic Arms
-
End Effectors
-
Drives
-
Controllers
-
Sensors
-
Power Supply
-
Motors
-
Others
-
-
End-use Outlook (Revenue, USD Million, 2021 - 2033)
-
Hospitals & Diagnostics
-
Pharmaceuticals & Medical Devices
-
Others
-
-
Regional Outlook (Revenue, USD Million, 2021 - 2033)
-
North America
-
U.S.
-
Canada
-
Mexico
-
-
Europe
-
UK
-
Germany
-
France
-
Italy
-
Spain
-
Norway
-
Denmark
-
Sweden
-
-
Asia Pacific
-
Japan
-
China
-
India
-
Australia
-
South Korea
-
Thailand
-
-
Latin America
-
Brazil
-
Argentina
-
-
Middle East & Africa
-
South Africa
-
Saudi Arabia
-
UAE
-
Kuwait
-
-
Research Methodology
The cleanroom robots in healthcare market figures in this report are based on a proven research process that combines executive interviews with secondary research from proprietary databases, company filings, and recognized regulatory and institutional sources. Market size is built through value-chain sizing - reconciling supply-side and demand-side estimates - and triangulated with bottom-up and top-down approaches. Every estimate passes multiple levels of expert validation before publication, with each cleanroom robots in healthcare segment quantified using the revenue-capture definitions in the table below.
Segment Definition
Segment - Type
Revenue capture definition
Traditional Industrial Robots
Automated robotic systems designed to perform repetitive, high-precision tasks within controlled healthcare cleanroom environments. These robots are commonly used in pharmaceutical manufacturing, medical device production, laboratory automation, and sterile material handling processes.
Articulated Robots
Multi-jointed robotic arms with rotary axes that provide a high degree of flexibility and movement. In healthcare cleanrooms, they are used for assembly, packaging, inspection, dispensing, and material handling applications requiring complex motion paths.
SCARA Robots
Selective Compliance Assembly Robot Arm (SCARA) systems designed for high-speed pick-and-place, assembly, and packaging operations. These robots offer excellent precision and are widely used in pharmaceutical filling, laboratory automation, and medical device manufacturing.
Parallel Robots
High-speed robotic systems consisting of multiple arms connected to a common platform. Also known as delta robots, they are commonly used for rapid sorting, packaging, sample handling, and precision manufacturing tasks in healthcare cleanroom settings.
Cartesian Robots
Robots that operate along linear X, Y, and Z axes using a rectangular coordinate system. These systems are utilized for material transfer, automated dispensing, inspection, and precision positioning applications within cleanroom environments.
Collaborative Robots (Cobots)
Robots designed to safely operate alongside human workers without extensive physical barriers. In healthcare cleanrooms, cobots assist with laboratory workflows, pharmaceutical production, packaging, inspection, and repetitive tasks while enhancing productivity and workforce efficiency.
Segment - Component
Revenue capture definition
Robotic Arms
The primary mechanical structures of robots that perform movement, positioning, handling, assembly, and manipulation tasks. Robotic arms provide the flexibility and precision required for healthcare cleanroom operations.
End Effectors
Devices attached to the end of robotic arms that interact directly with objects or materials. Examples include grippers, vacuum suction tools, dispensing systems, and specialized handling tools used for sterile products and laboratory samples.
Drives
Mechanical and electronic systems that convert control signals into motion. Drives regulate robot speed, positioning, torque, and movement accuracy during cleanroom operations.
Controllers
The central processing units that manage robot functions, motion control, task execution, communication, and system integration. Controllers ensure accurate and reliable robotic performance in regulated healthcare environments.
Sensors
Devices that collect information regarding position, force, motion, temperature, proximity, vision, and environmental conditions. Sensors enable real-time monitoring, process control, and enhanced robotic precision.
Power Supply
Electrical systems that provide the energy required to operate robotic components, controllers, motors, and peripheral devices within cleanroom facilities.
Motors
Electromechanical devices responsible for generating movement in robotic joints and axes. Motors facilitate precise positioning, speed control, and repeatable robotic operations.
Others
Includes gearboxes, communication modules, machine vision systems, cables, software interfaces, safety systems, mounting structures, and other supporting robotic components.
Segment - End Use
Revenue capture definition
Hospitals & Diagnostics
Healthcare facilities, clinical laboratories, and diagnostic centers that utilize cleanroom robots for laboratory automation, specimen handling, diagnostic testing, sterile material transport, pharmaceutical preparation, and infection-control-sensitive applications.
Pharmaceutical & Medical Device Companies
Pharmaceutical manufacturers, biotechnology companies, and medical device producers that deploy cleanroom robots for aseptic processing, drug manufacturing, packaging, quality inspection, material handling, and precision assembly in controlled environments.
Others
Includes contract manufacturing organizations (CMOs), contract development and manufacturing organizations (CDMOs), academic research laboratories, biotechnology research facilities, tissue engineering centers, and other healthcare-related organizations utilizing cleanroom robotic systems.
Estimation Model
Market Estimation Process:
Market-specific Research Models:
Consensus-Based Estimates & Forecasting
The cleanroom robots in healthcare market presents emerging dominant opportunities, featuring global key players such as ABB Ltd.; Denso Corporation; FANUC Corporation; Kawasaki Heavy Industries, Ltd.; Yaskawa Electric Corporation; Nachi Fujikoshi Corporation; and Stäubli International AG. To ensure a holistic approach, the GVR research team adopted a comprehensive methodology, considering multiple companies worldwide and utilizing various variables for data accuracy.
Our methodology included:
Model 1: Commodity Flow Analysis - For public players, annual reports were referenced. For private players, premium paid data sources such as S&P Global, Crunchbase, ZoomInfo, RocketReach, etc., were used for the latest revenue insights.
Model 2: Parent Market Analysis
Model 3: Country-level Multivariate Analysis Assumptions
Model 4: Segment-level Multivariate Analysis Assumptions
Model 5: Cleanroom Robots in Healthcare Market CAGR Calculations
Model 1: Commodity Flow Analysis
Commodity flow analysis was employed to track the movement of cleanroom robots in healthcare through the value chain, from technology providers to end users. This analysis provided insights into demand generation points, intermediary roles, and ultimate consumption patterns.
Delivered Customizations
This report has been delivered with the following In-depth customizations
Client Request
Customization Delivered
Value Adds
Cleanroom Robot Adoption & Automation Analysis
Developed a tailored analysis of the cleanroom robots market focused on adoption of autonomous material handling robots, robotic arms, and mobile cleanroom automation systems across pharmaceutical, semiconductor, and biotechnology facilities. The study covered automation trends, contamination-control requirements, labor optimization initiatives, and deployment of robotic systems across sterile and controlled manufacturing environments.
Enables stakeholders to understand evolving cleanroom automation ecosystems, identify high-growth robotic applications and end-user segments, assess operational efficiency improvements, and evaluate the impact of automation on contamination reduction, productivity enhancement, and long-term manufacturing scalability.
Autonomous Mobile Robot (AMR) Adoption & Facility Utilization Trends
Delivered a customized evaluation of healthcare and semiconductor facility adoption trends for AMRs and robotic transport systems operating in ISO-classified cleanrooms. The study assessed workflow optimization requirements, integration with cleanroom logistics, and automation-driven productivity improvements across manufacturing and research facilities.
Provides actionable insights into changing facility automation preferences, demand for robotic material transfer solutions, and emerging opportunities linked to contamination-free production environments, operational efficiency, and labor cost optimization trends.
Cleanroom Infrastructure & Robotic Workflow Optimization Assessment
Conducted a focused assessment of cleanroom robotic infrastructure, including robotic integration platforms, AI-enabled monitoring systems, and automated workflow management solutions. The analysis evaluated deployment challenges, operational costs, integration with existing cleanroom systems, and automation efficiency improvements across pharmaceutical and electronics manufacturing facilities.
Supports strategic planning for robotic automation investments, identifies opportunities for workflow modernization and contamination-control optimization, and helps companies align with next-generation cleanroom manufacturing and process automation requirements.
Frequently Asked Questions About This Report
Key factors that are driving the cleanroom robots in healthcare market growth include the increasing demand for sterile and contamination-free environments in healthcare facilities, the rise of minimally invasive surgical procedures, the need for efficient cleaning and disinfection protocols, and the increasing adoption of robotic technology in healthcare.
The global cleanroom robots in healthcare market size was estimated at USD 789.1 million in 2025 and is expected to reach USD 982.5 million in 2025.
The global cleanroom robots in healthcare market is expected to grow at a compound annual growth rate of 24.0% from 2026 to 2033 to reach USD 4430.7 billion by 2033.
North America dominated with a 47.6% revenue share in 2025.
Asia Pacific is the fastest-growing region over the forecast period.
The robotic arms segment led with a 44.7% revenue share in 2025, while motors is the fastest-growing segment.
The pharmaceuticals & medical devices segment led with a 49.9% revenue share in 2025, while hospitals & diagnostics is the fastest-growing segment.
The traditional industrial robots segment dominated the cleanroom robots in healthcare market with a share of 57.2% in 2025.
Some key players operating in the cleanroom robots in healthcare market include ABB Ltd.; Denso Corporation; FANUC Corporation; Kawasaki Heavy Industries, Ltd.; Yaskawa Electric Corporation; Nachi Fujikoshi Corporation; Stäubli International AG.
About the Author(s)
Medical Devices Research Team
Healthcare · Medical DevicesThis report was authored by the medical devices research team at Grand View Research - comprising two research analysts, one senior research analyst, and one industry expert - with specialized expertise in the medical devices segment of the healthcare industry. All findings are based on proprietary healthcare databases, executive interviews, and regulatory analysis, subject to internal peer review prior to publication.
Last Updated:
Speak to Analyst

Customize this report to your needs - add regions, segments, or data points, with 20% free customization.
Or view our licence options:


ISO 9001:2015 & 27001:2022 Certified
We are GDPR and CCPA compliant! Your transaction & personal information is safe and secure. For more details, please read our privacy policy.


